Endeavour International — EnerCom's 2008 Oil & Services Conference VII
30 slides from Endeavour International's conference presentation, Feb 19, 2009
Slide 1: EnerCom's 2008 Oil & Services Conference VII
Exhibit 99.1 EnerCom’s 2008 +/- Oil & Services Conference™ VII 18 February 2009
Slide 2: Forward-looking statements and SEC reserves cautionary note
This is an oral presentation which is accompanied by slides. Investors are urged to review our SEC filings. This presentation contains certain forward-looking statements regarding various oil and gas discoveries, oil and gas exploration, development and production activities, anticipated and potenti
Slide 3: Endeavour at a Glance
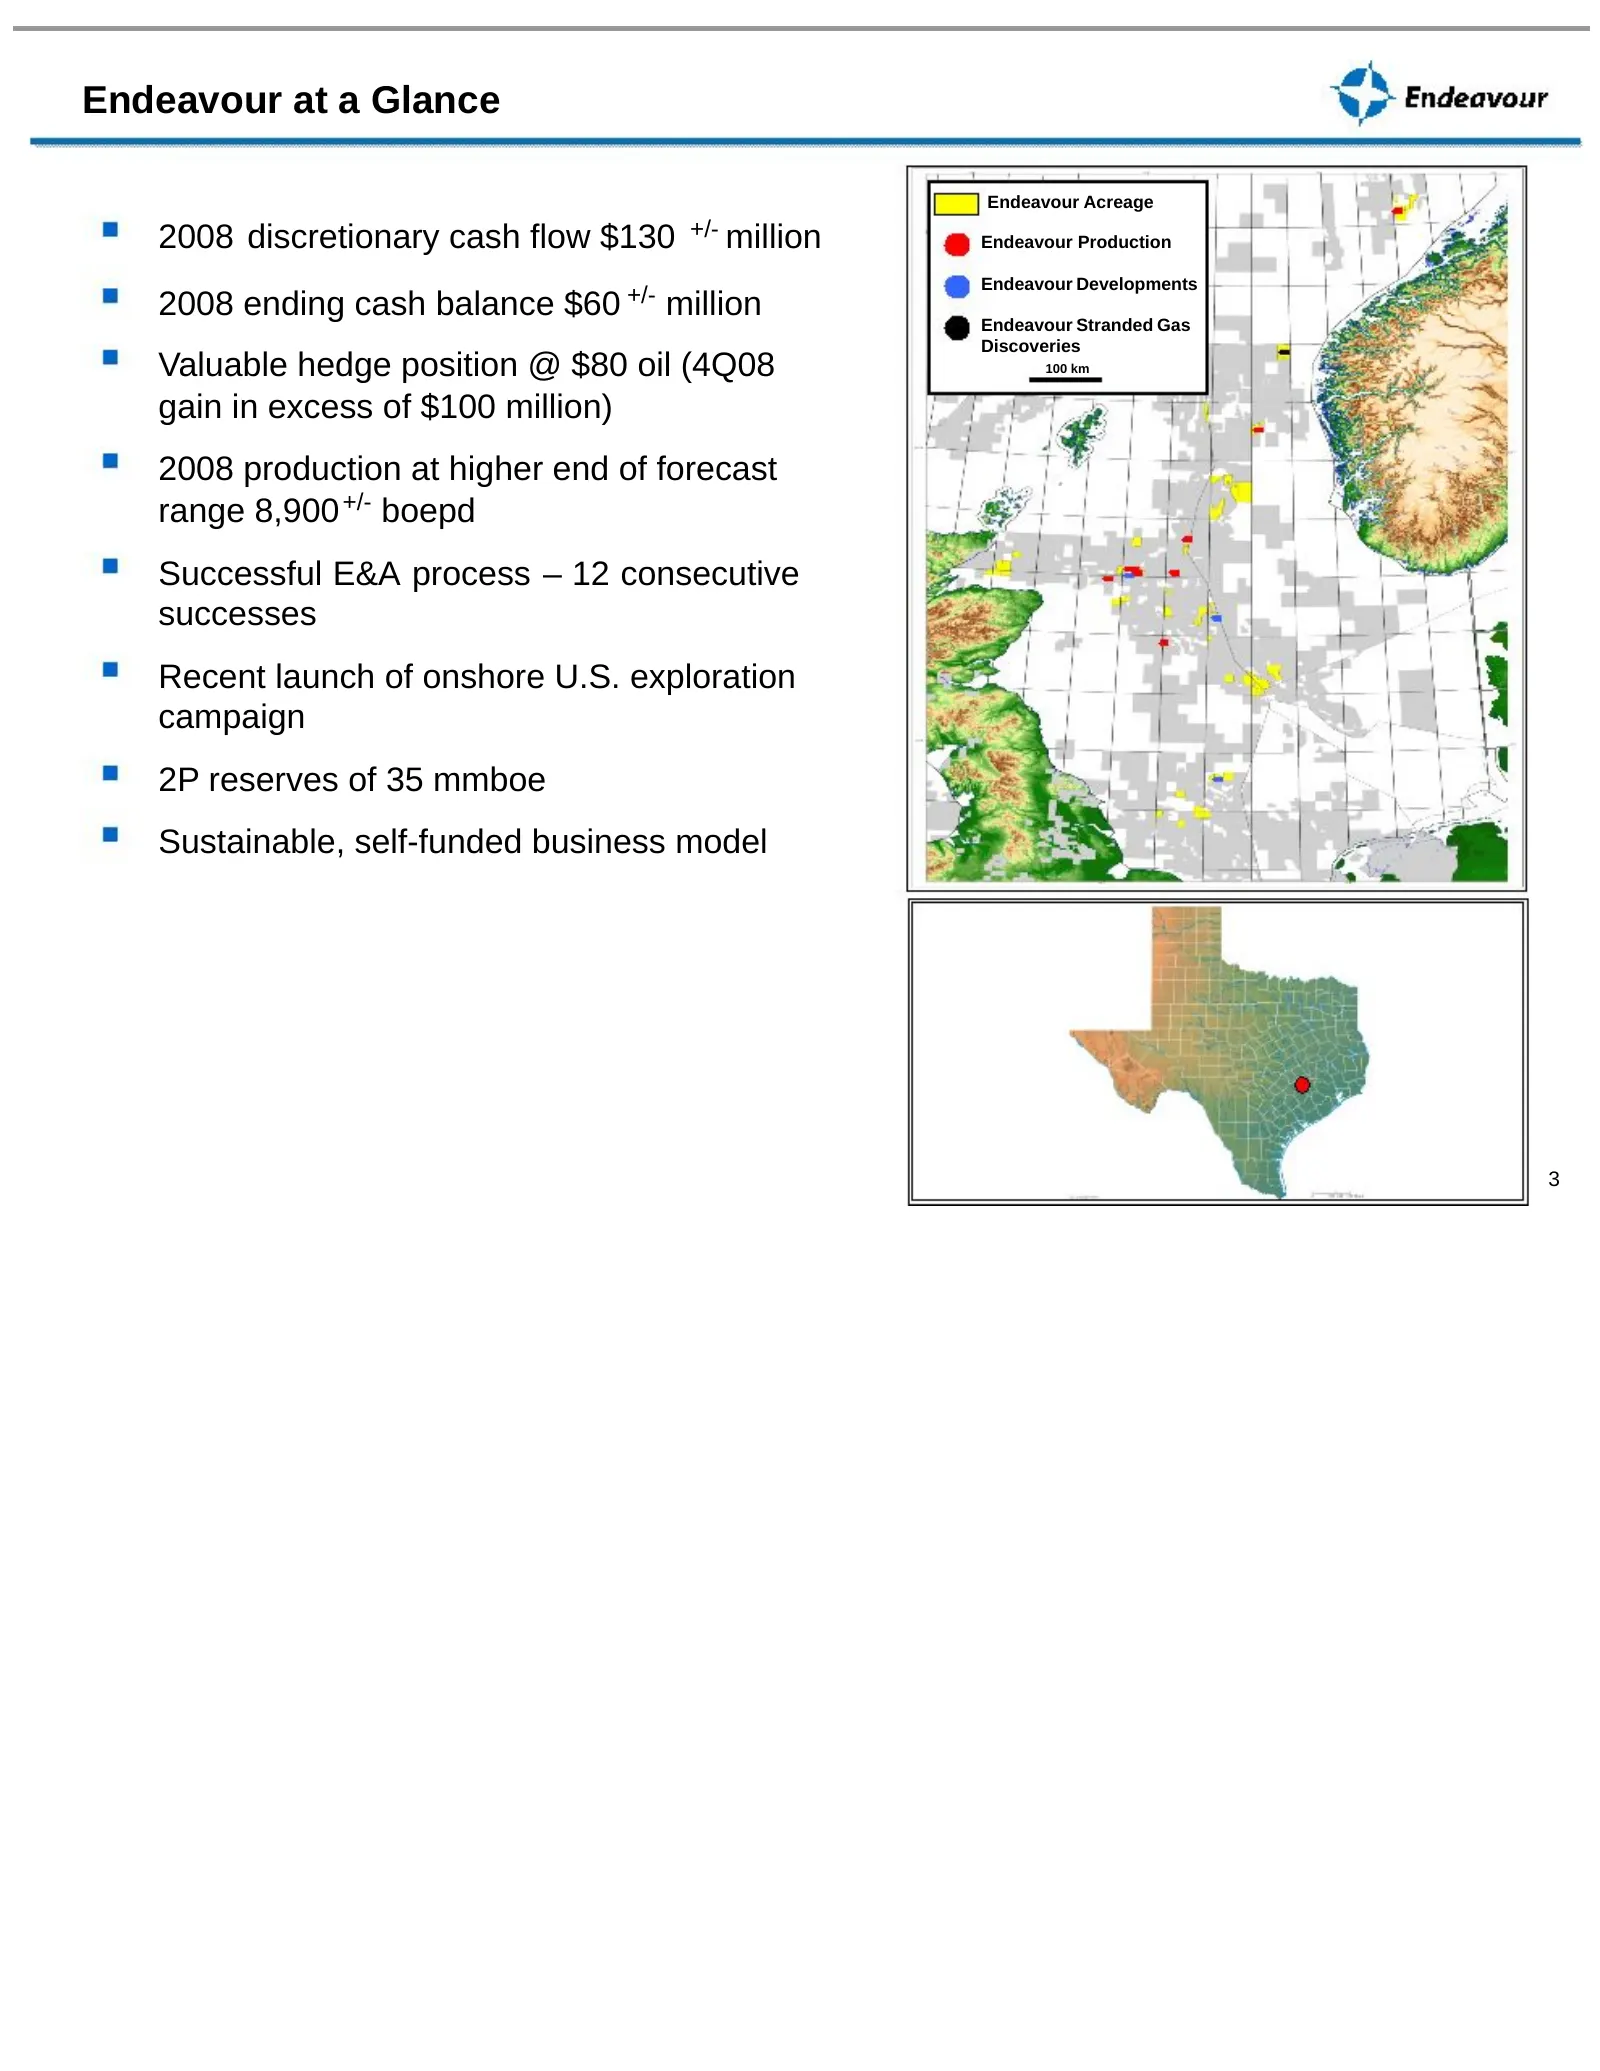
Endeavour at a Glance Endeavour Acreage 2008 discretionary cash flow $130 +/- million Endeavour Production Endeavour Developments 2008 ending cash balance $60 +/- million Endeavour Stranded Gas Discoveries Valuable hedge position @ $80 oil (4Q08 100 km gain in excess of $100 million) 2008 production
Slide 4: Potential Production Growth
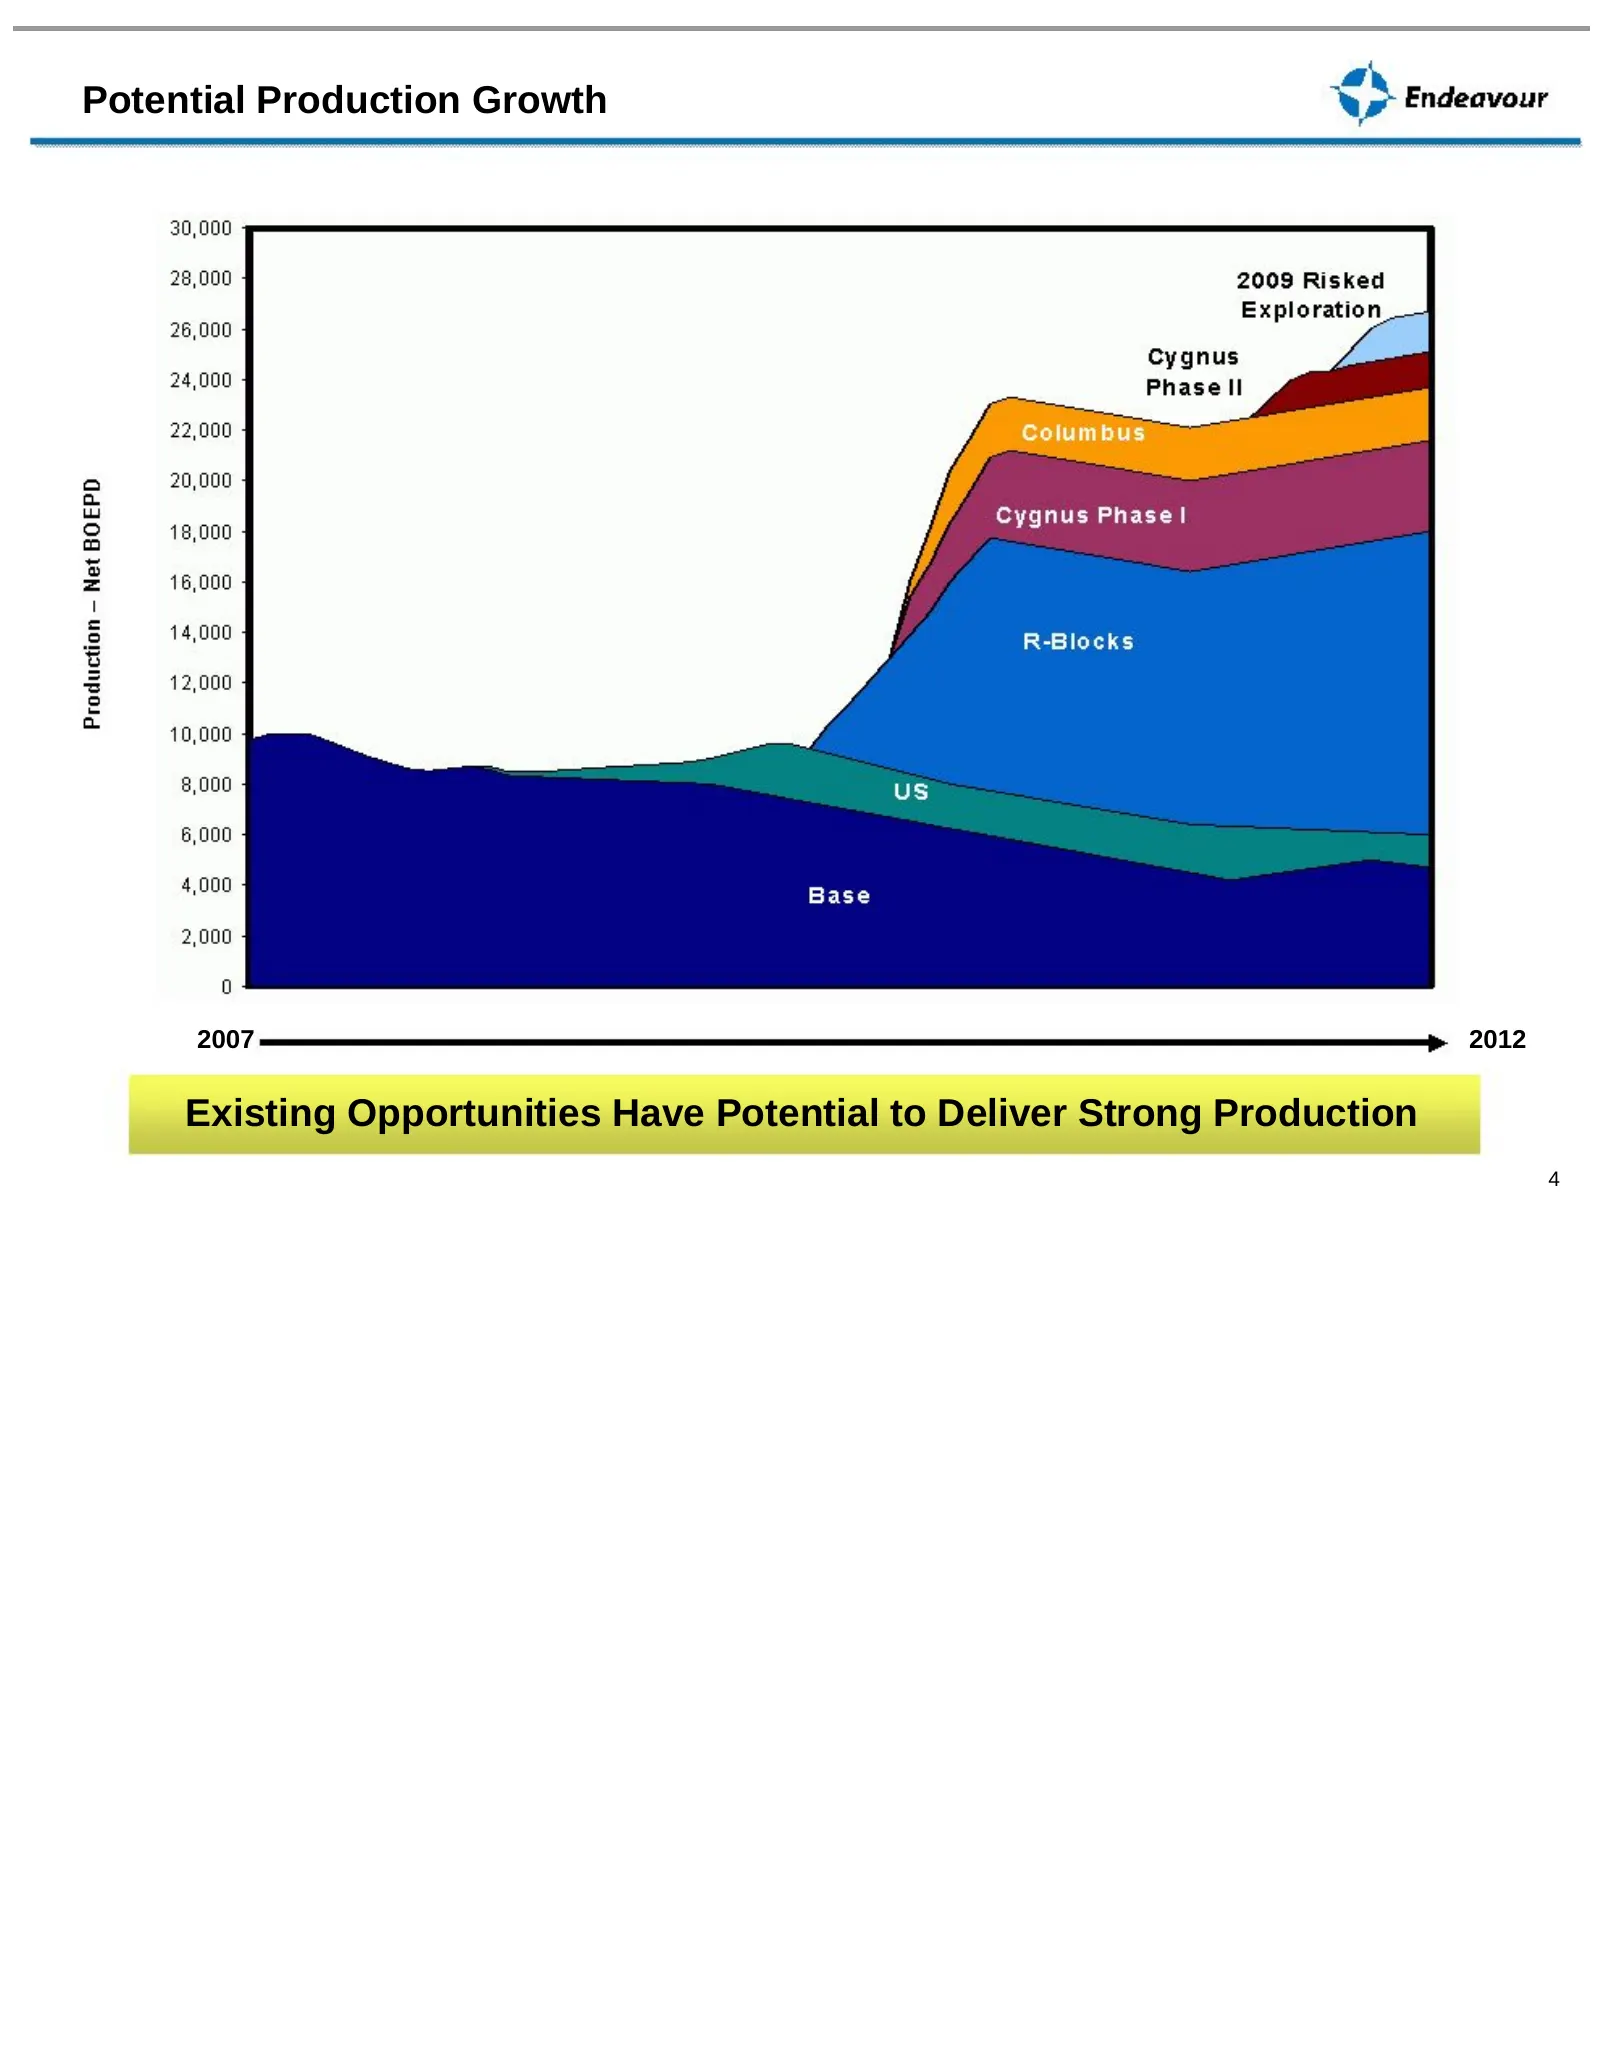
Potential Production Growth 2007 2012 Existing Opportunities Have Potential to Deliver Strong Production 4
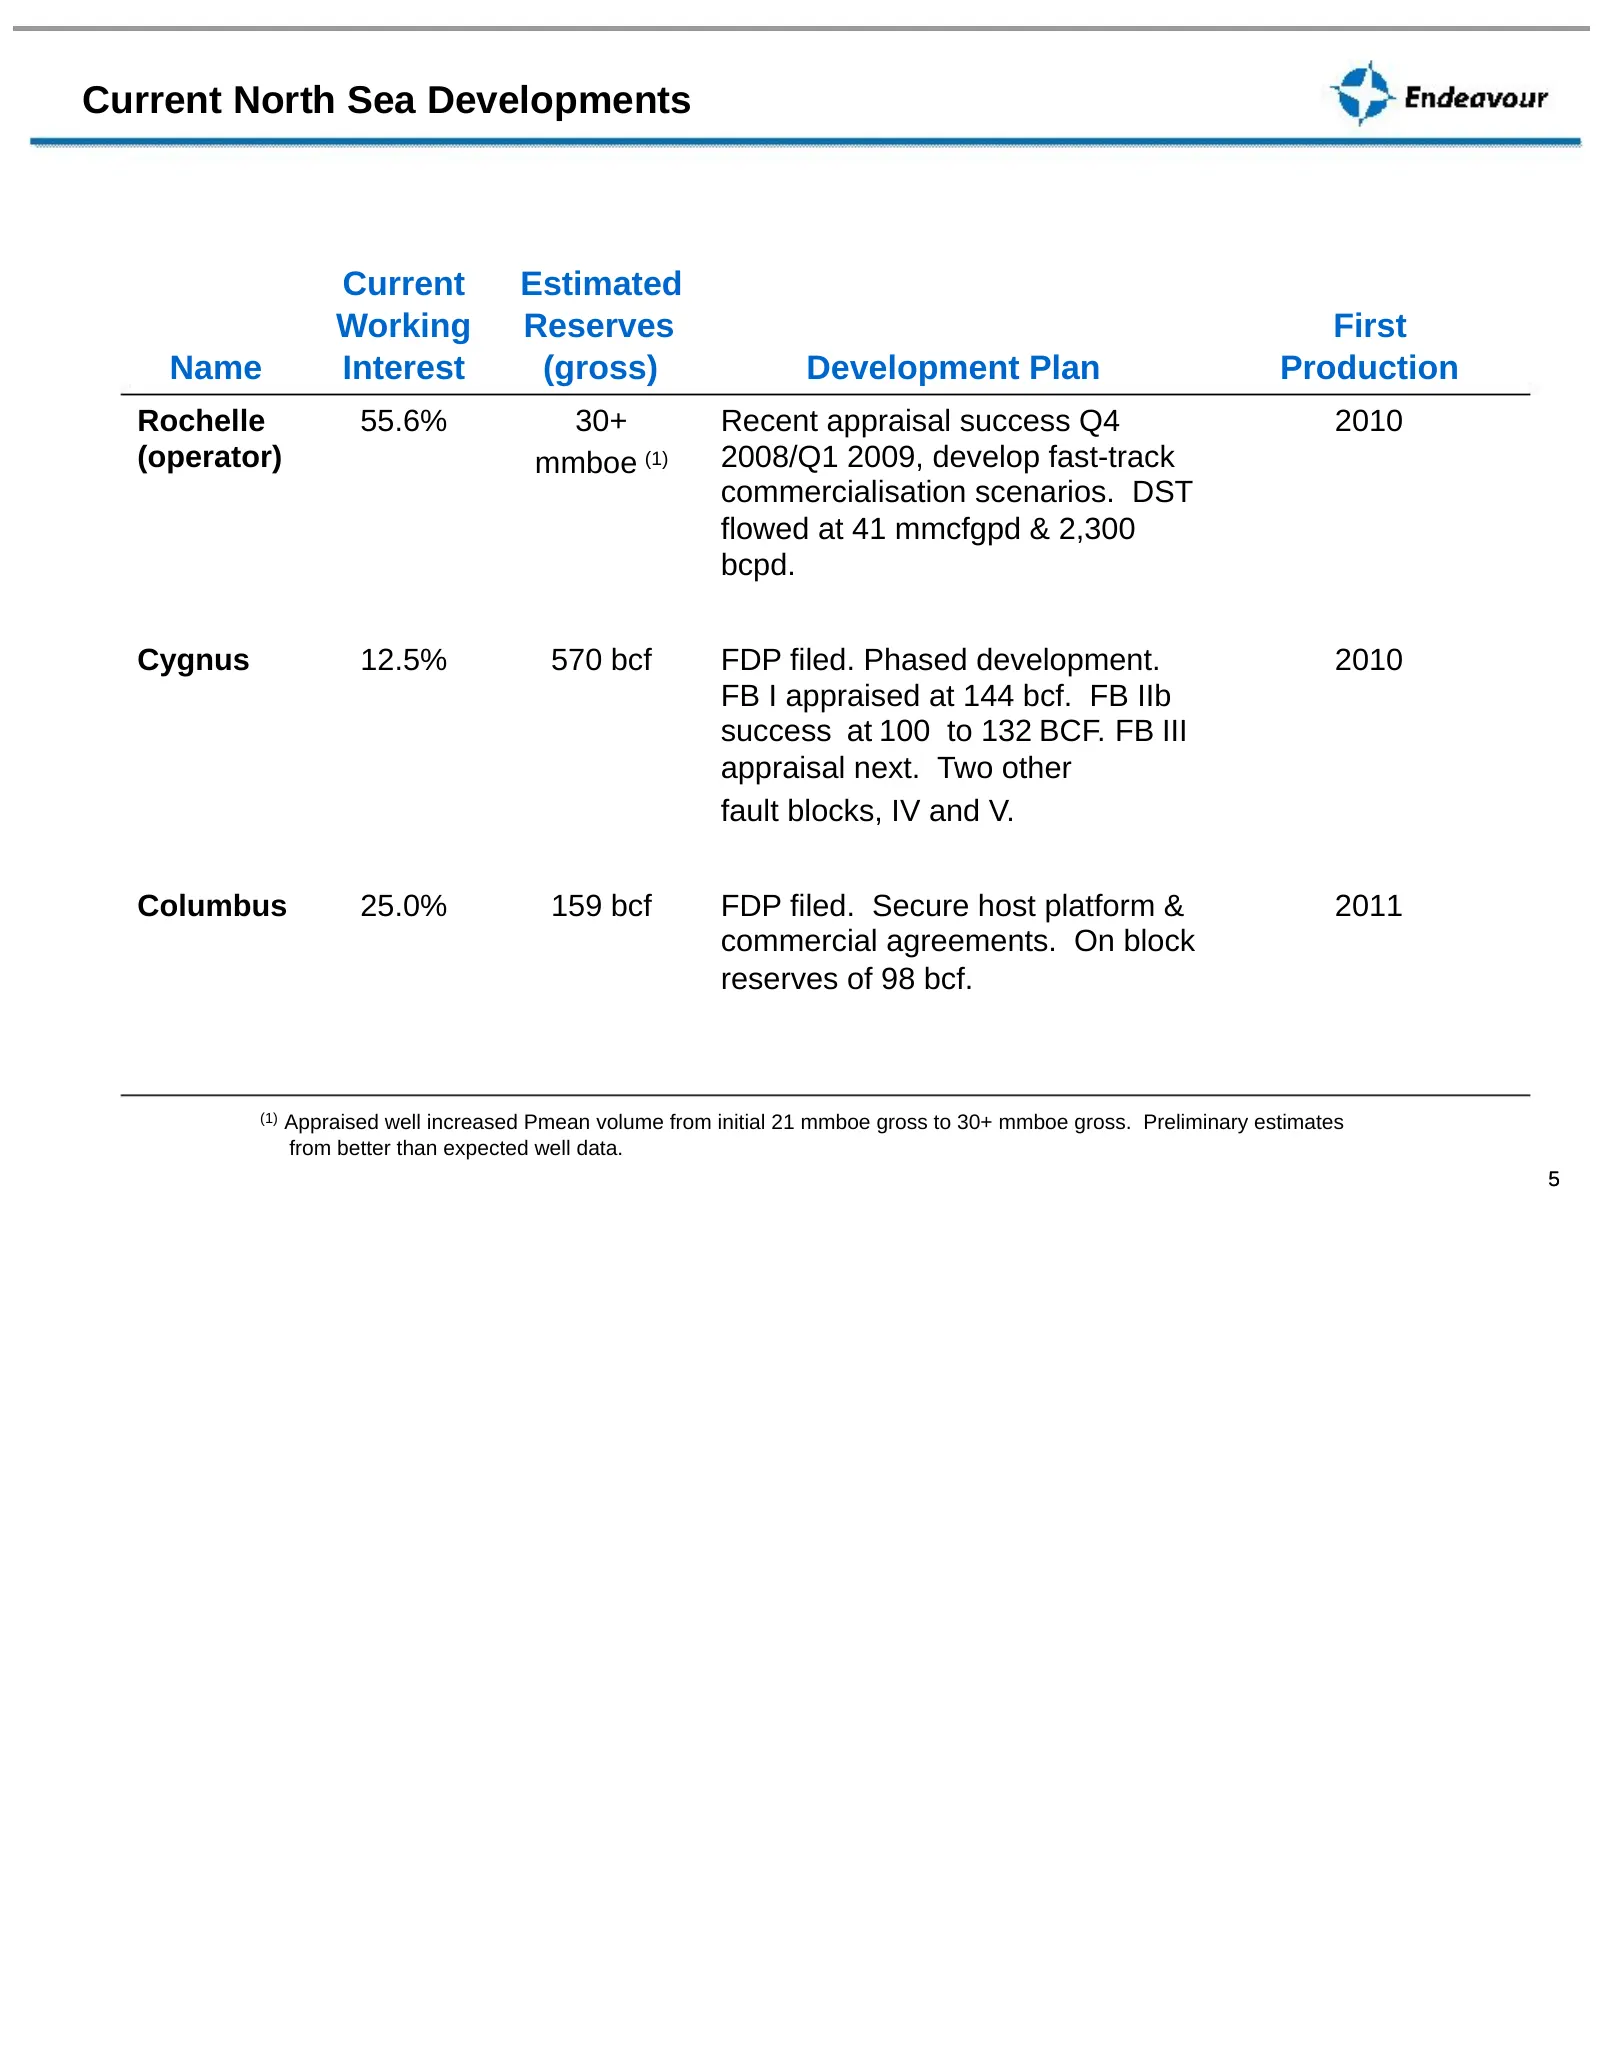
Slide 5: Current North Sea Developments
Current North Sea Developments Current Estimated Working Reserves First Name Interest (gross) Development Plan Production Rochelle 55.6% 30+ Recent appraisal success Q4 2010 (operator) mmboe (1) 2008/Q1 2009, develop fast-track commercialisation scenarios. DST flowed at 41 mmcfgpd & 2,300 bcpd. Cygn
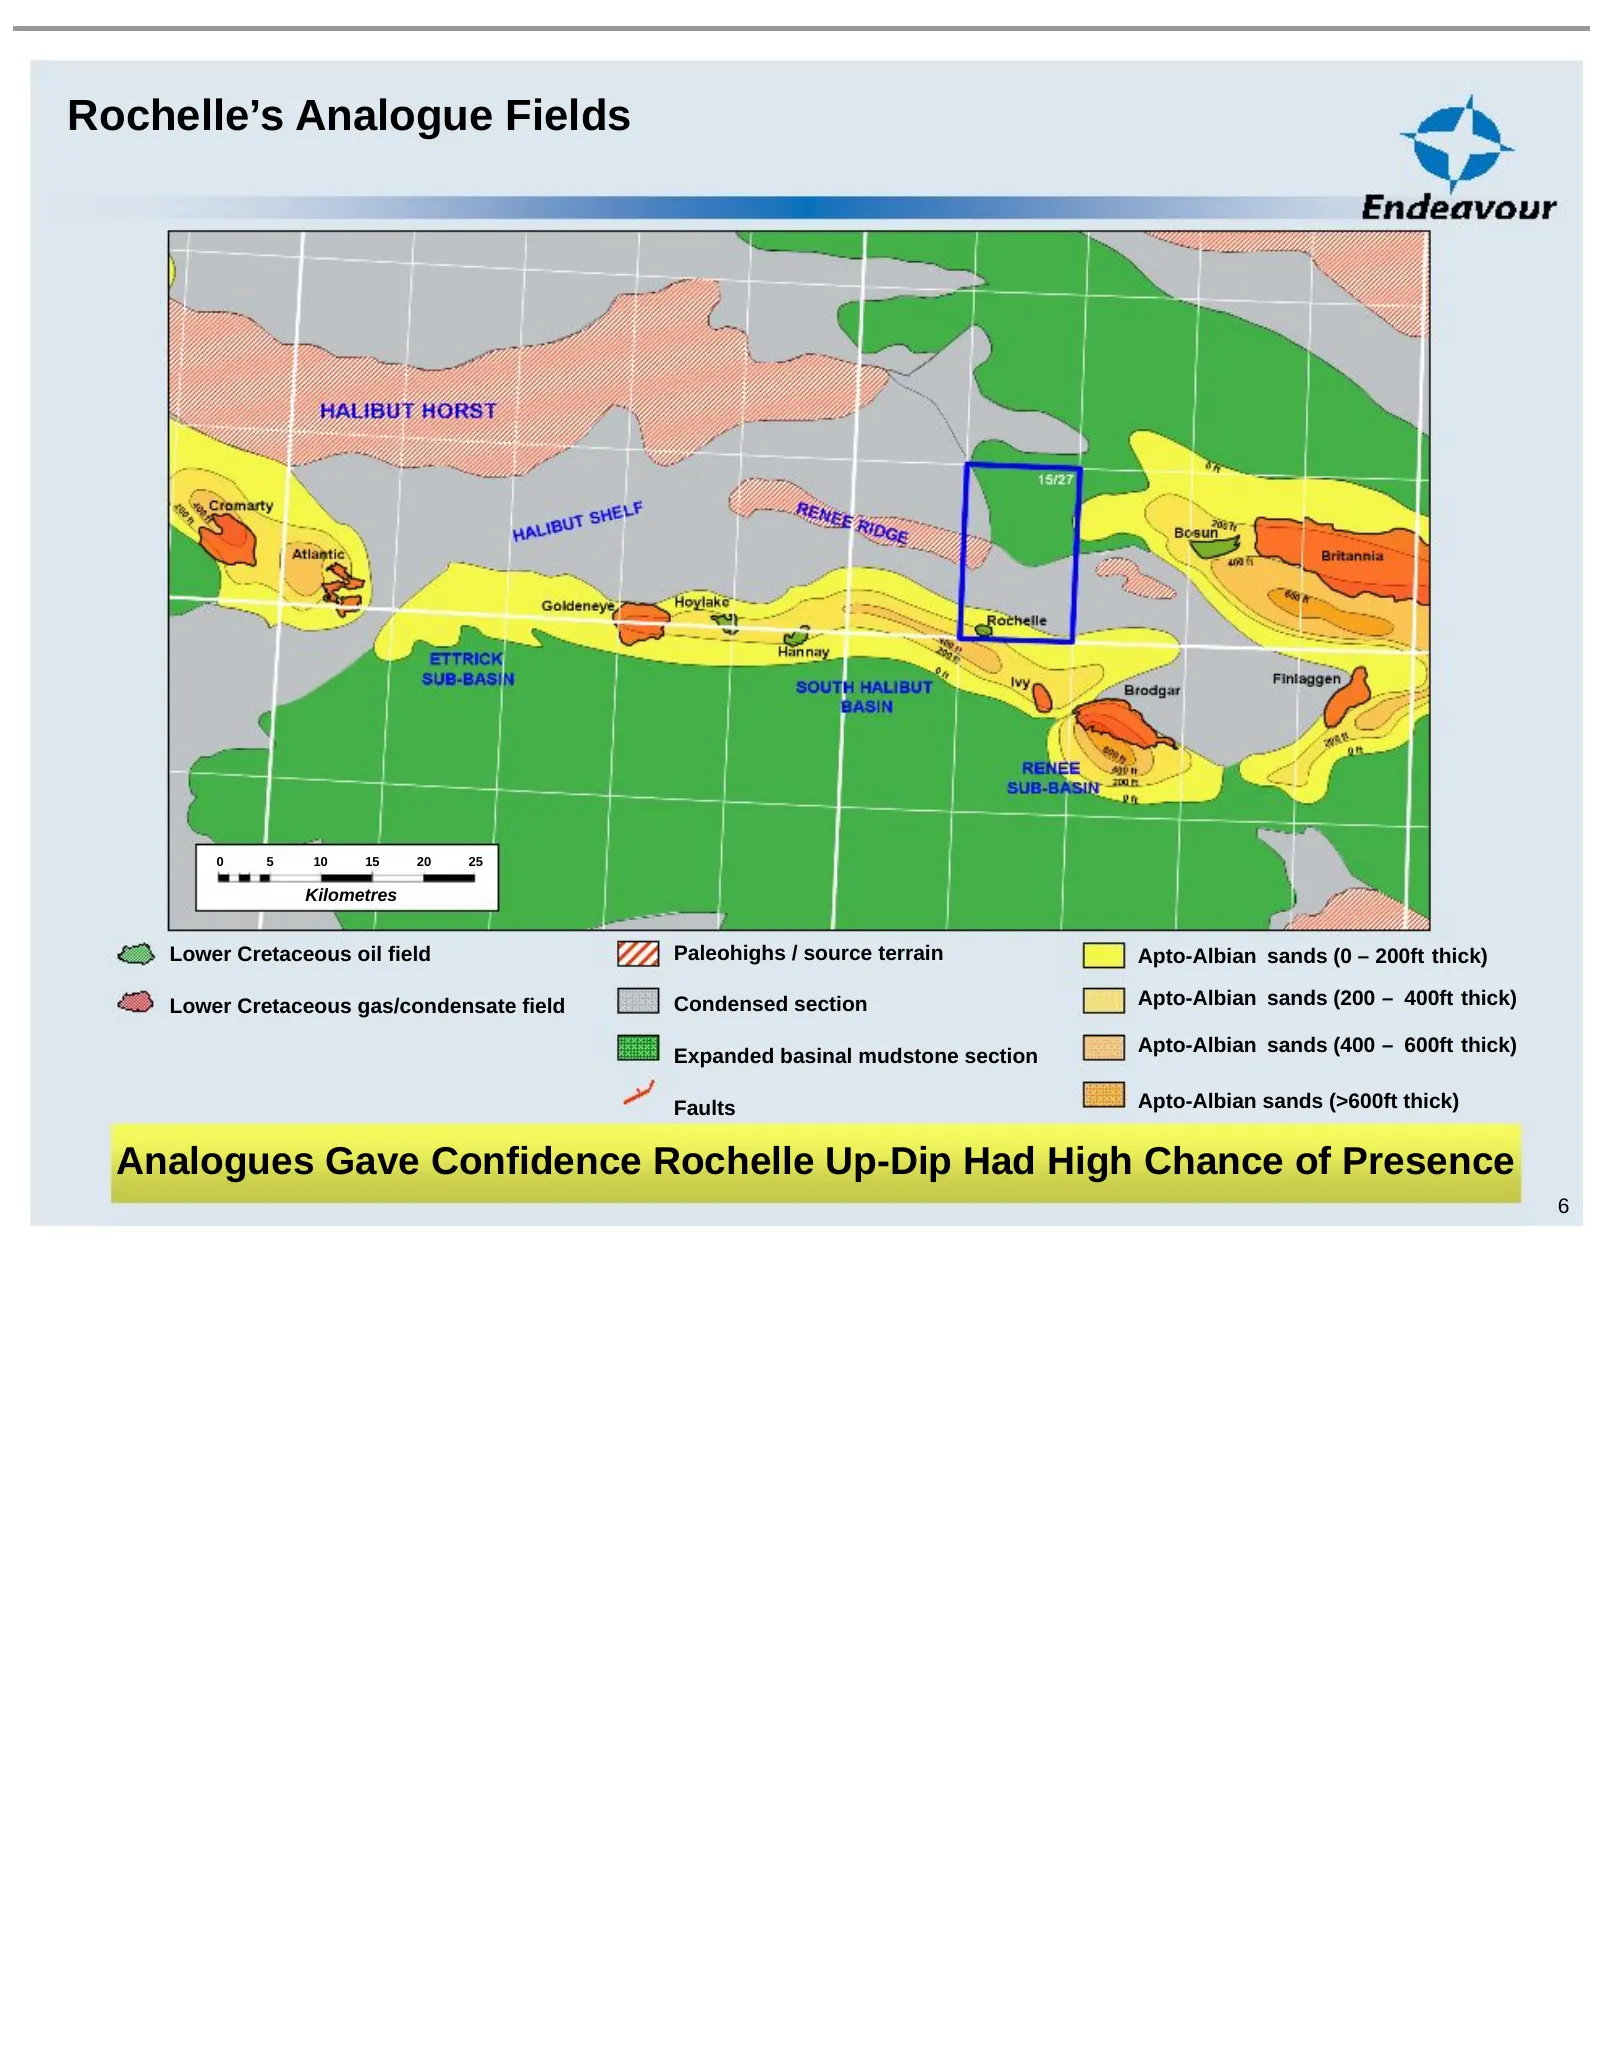
Slide 6: Rochelle's Analogue Fields
Rochelle’s Analogue Fields 0 5 10 15 20 25 Kilometres Lower Cretaceous oil field Paleohighs / source terrain Apto-Albian sands (0 – 200ft thick) Lower Cretaceous gas/condensate field Condensed section Apto-Albian sands (200 – 400ft thick) Apto-Albian sands (400 – 600ft thick) Expanded basinal mudsto
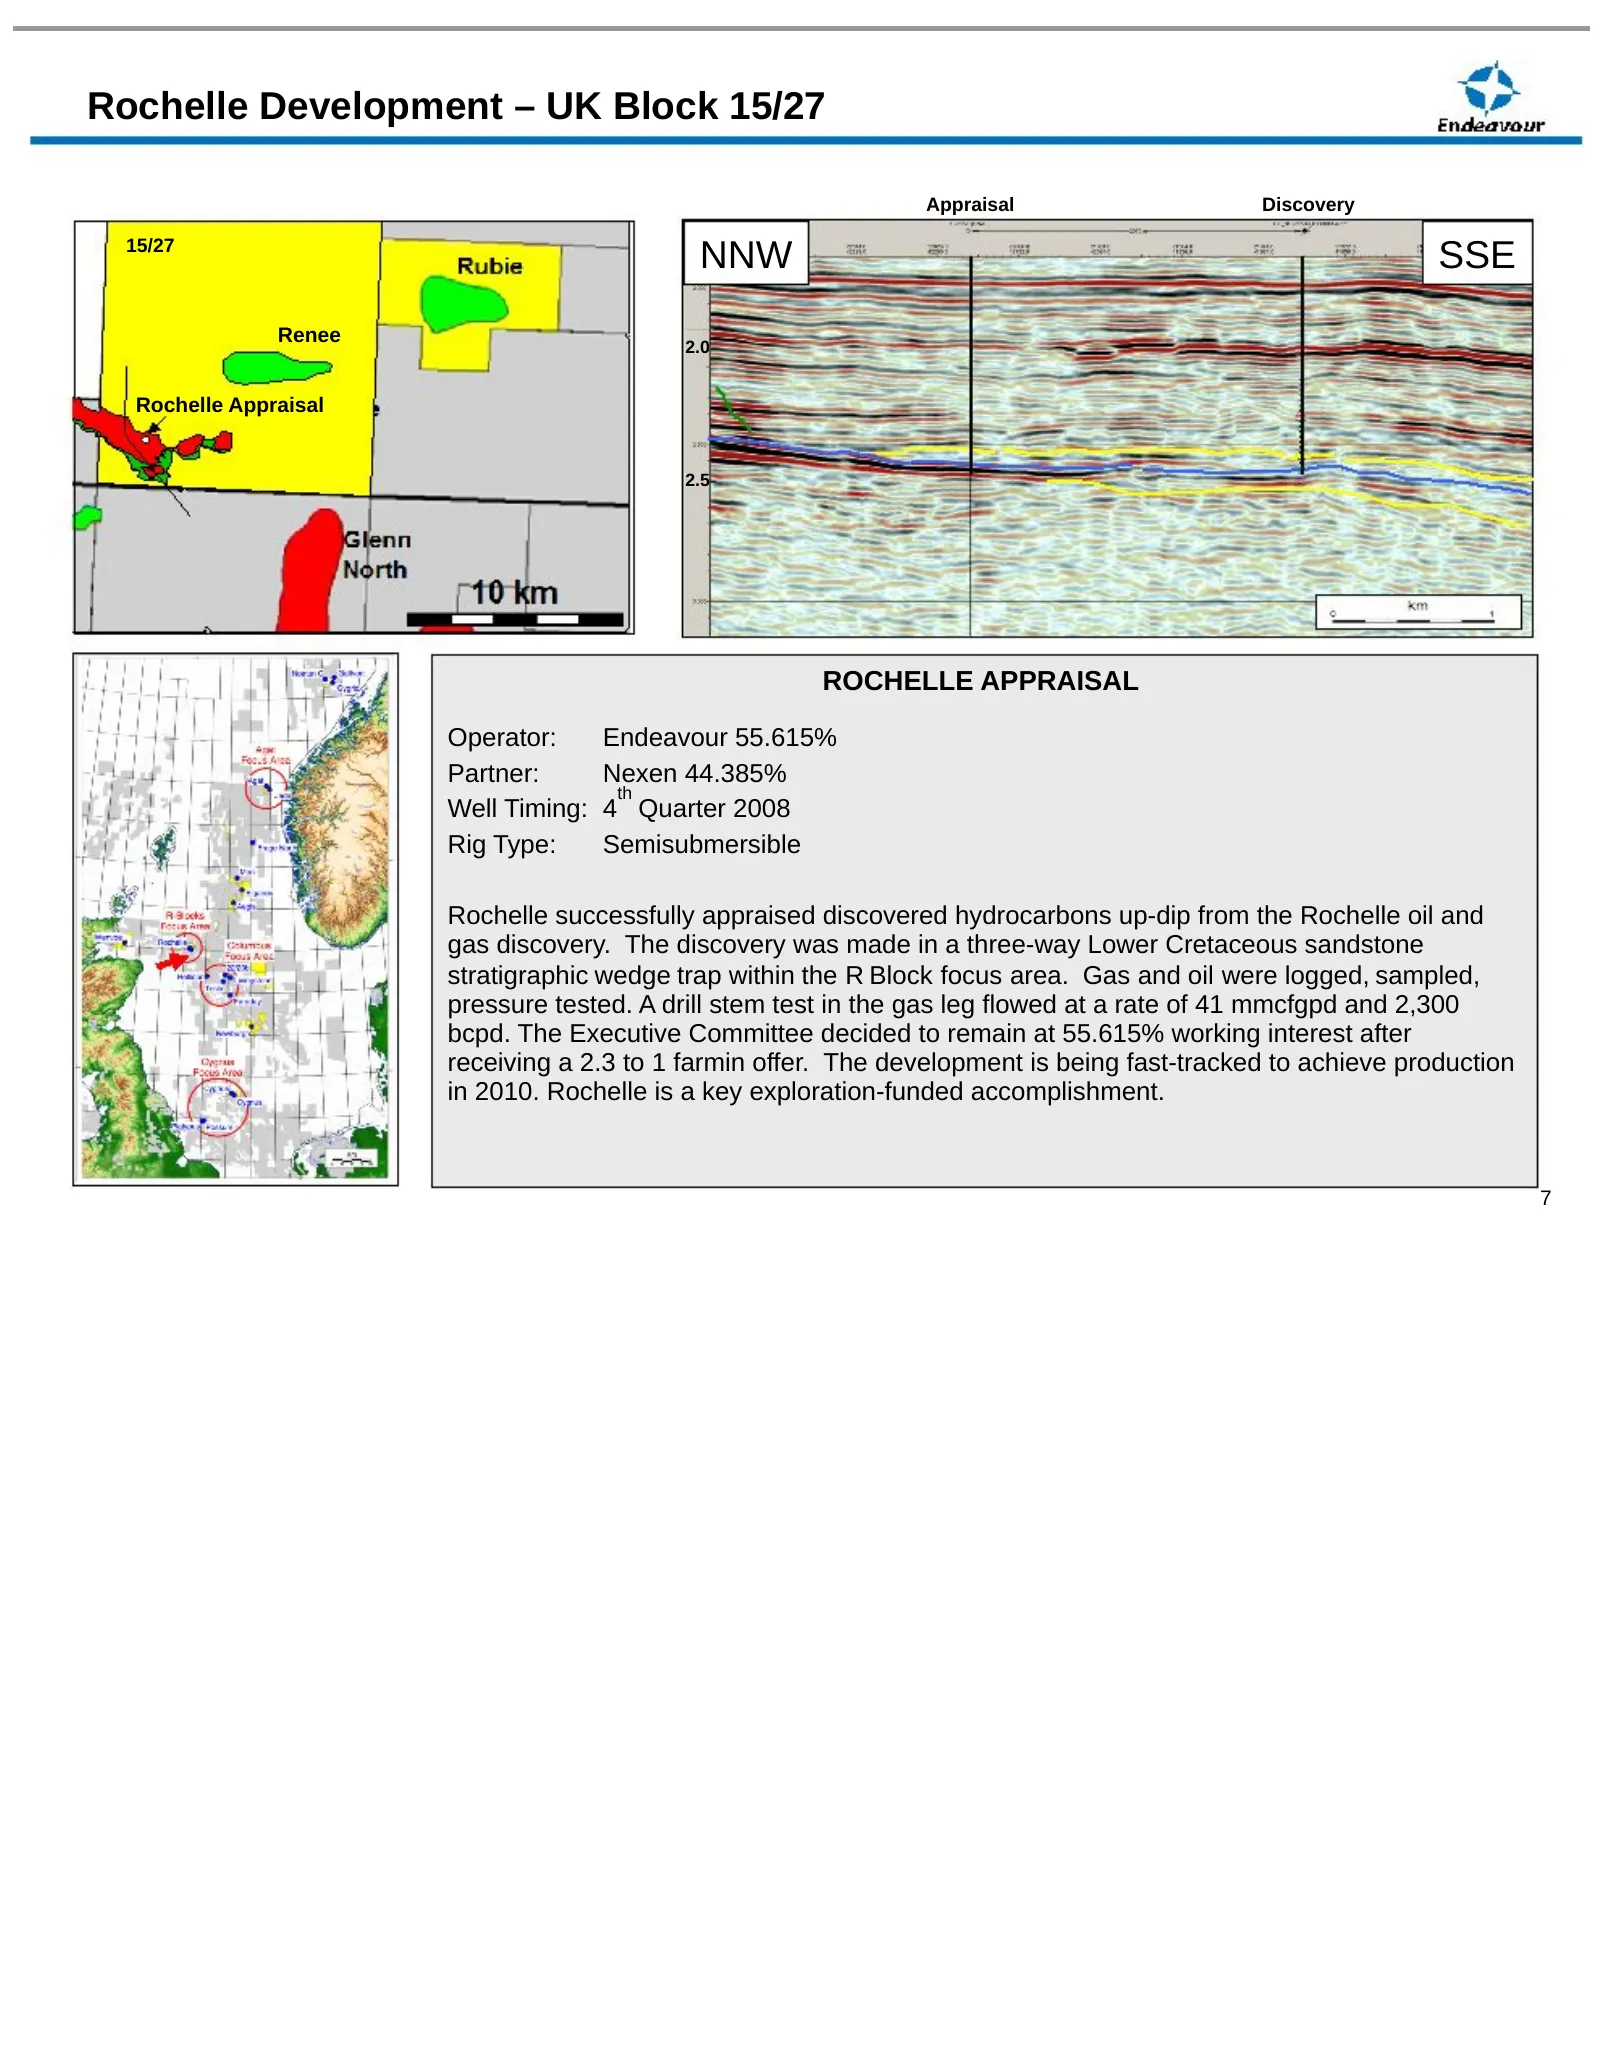
Slide 7: Rochelle Development – UK Block 15/27
Rochelle Development – UK Block 15/27 Appraisal Discovery N SE 15/27 NNW SSE Renee 2.0 Rochelle Appraisal 2.5 ROCHELLE APPRAISAL Operator: Endeavour 55.615% Partner: Nexen 44.385% th Well Timing: 4 Quarter 2008 Rig Type: Semisubmersible Rochelle successfully appraised discovered hydrocarbons up-dip
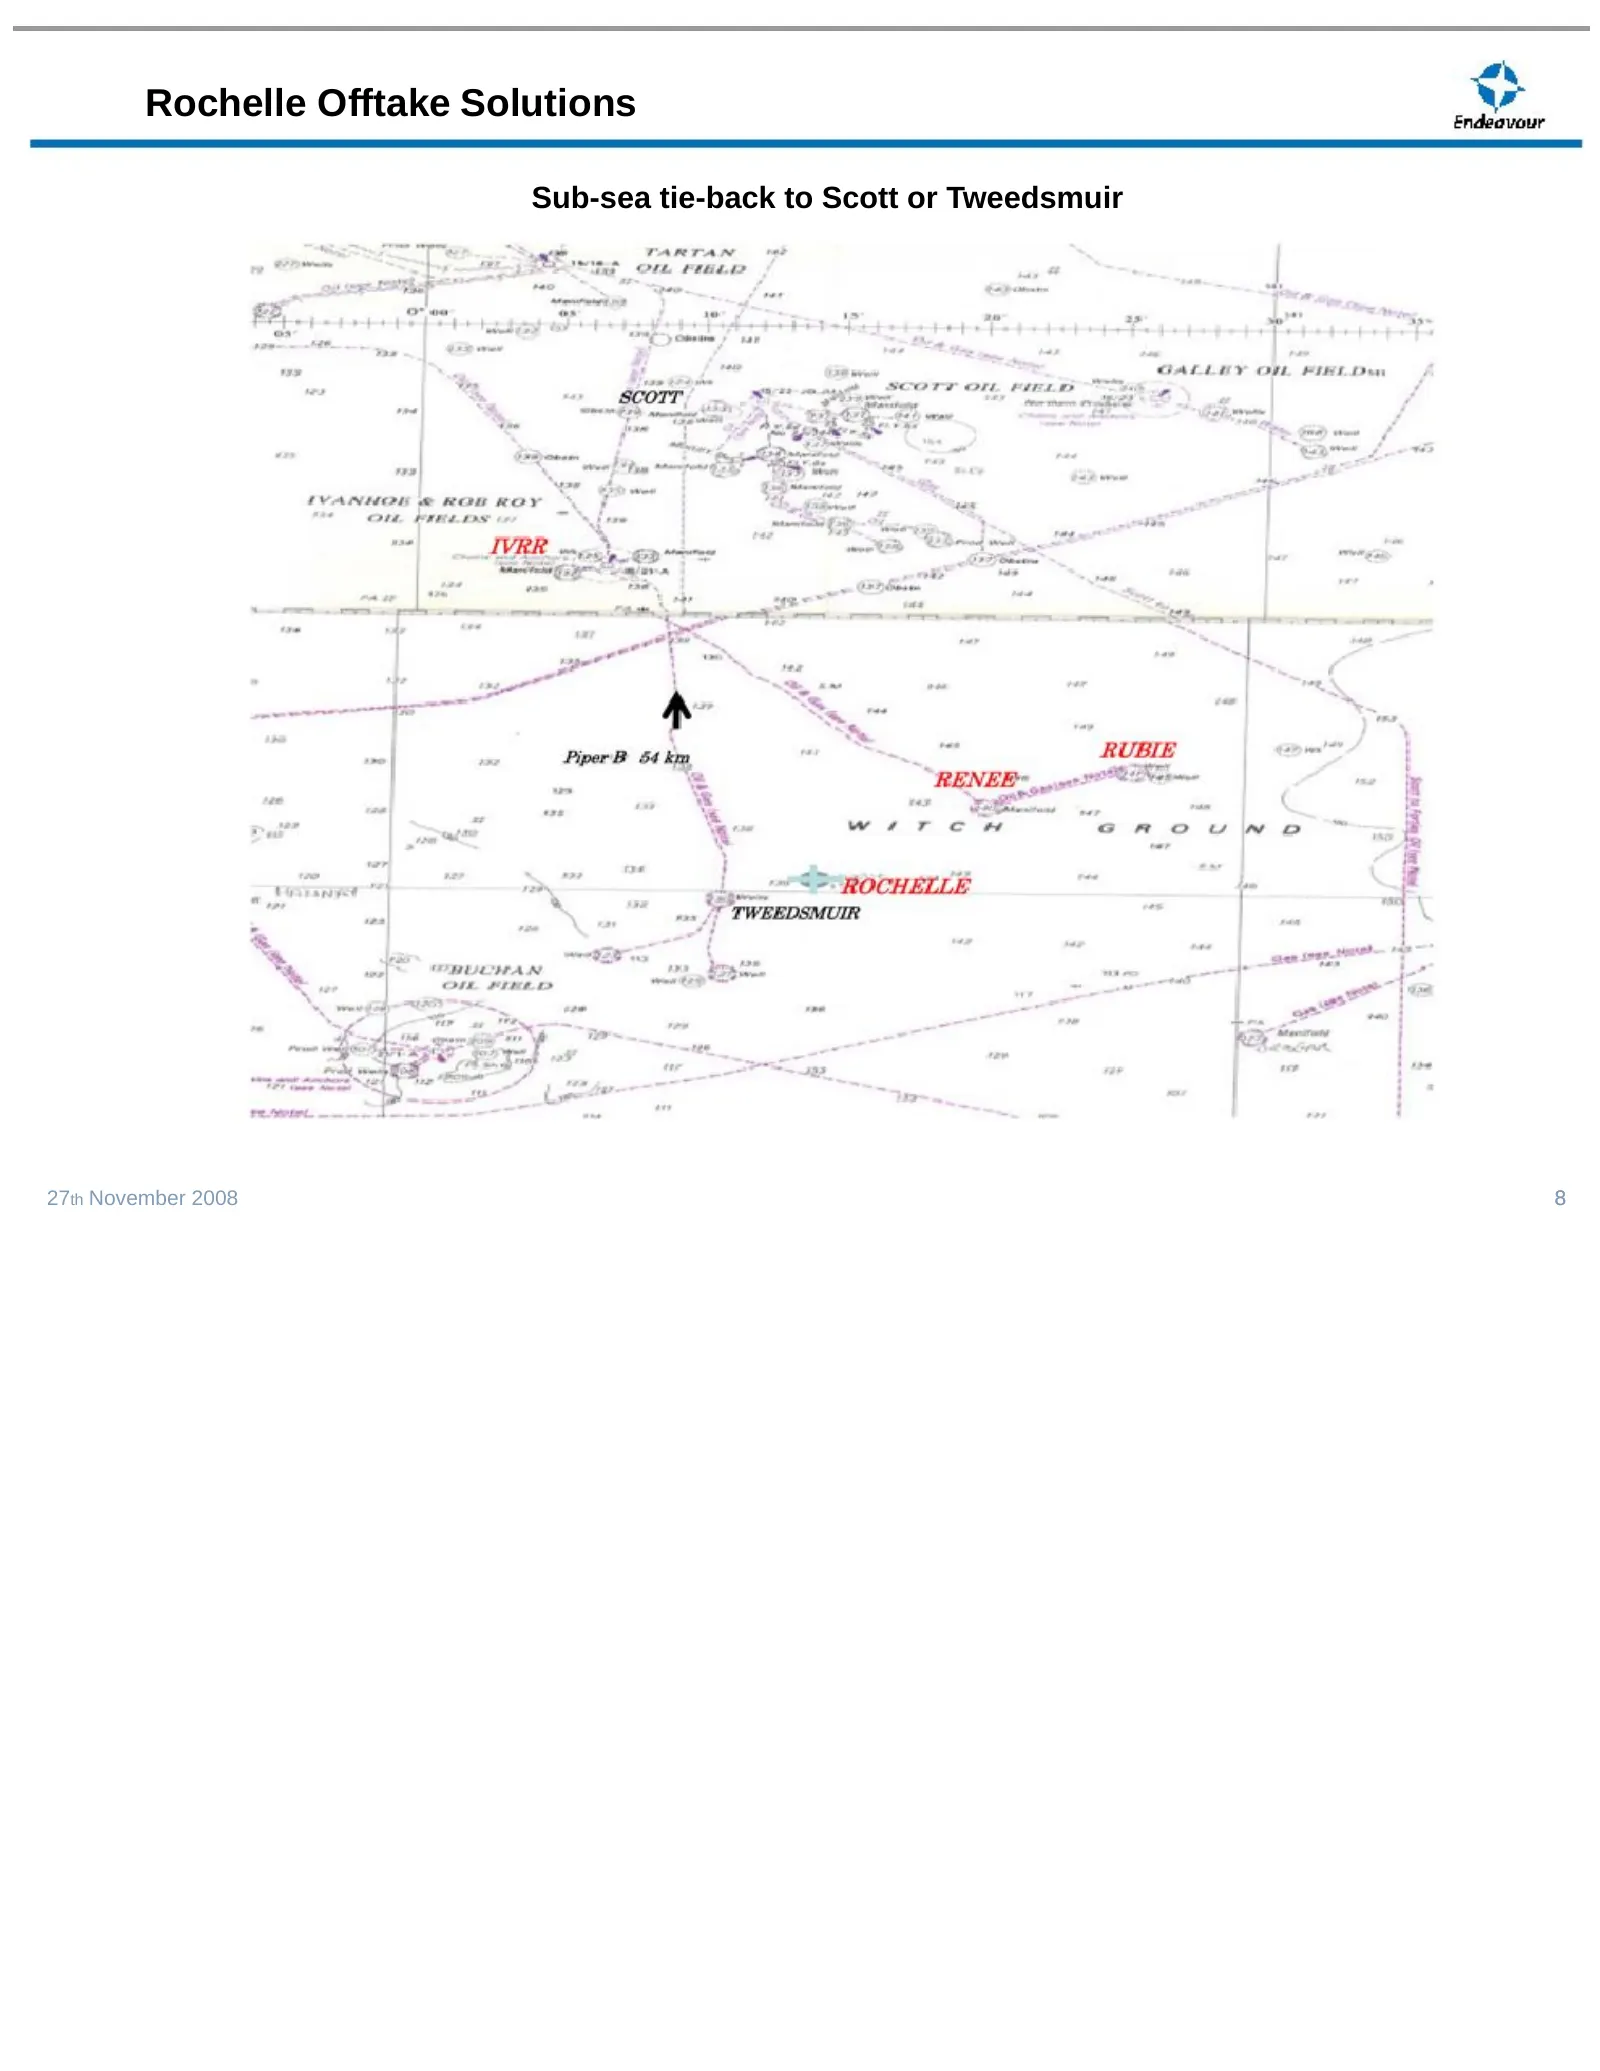
Slide 8: Rochelle Offtake Solutions
Rochelle Offtake Solutions Sub-sea tie-back to Scott or Tweedsmuir 27th November 2008 8
Slide 9: Cygnus Fault Block II & III – UK Block 44/12a
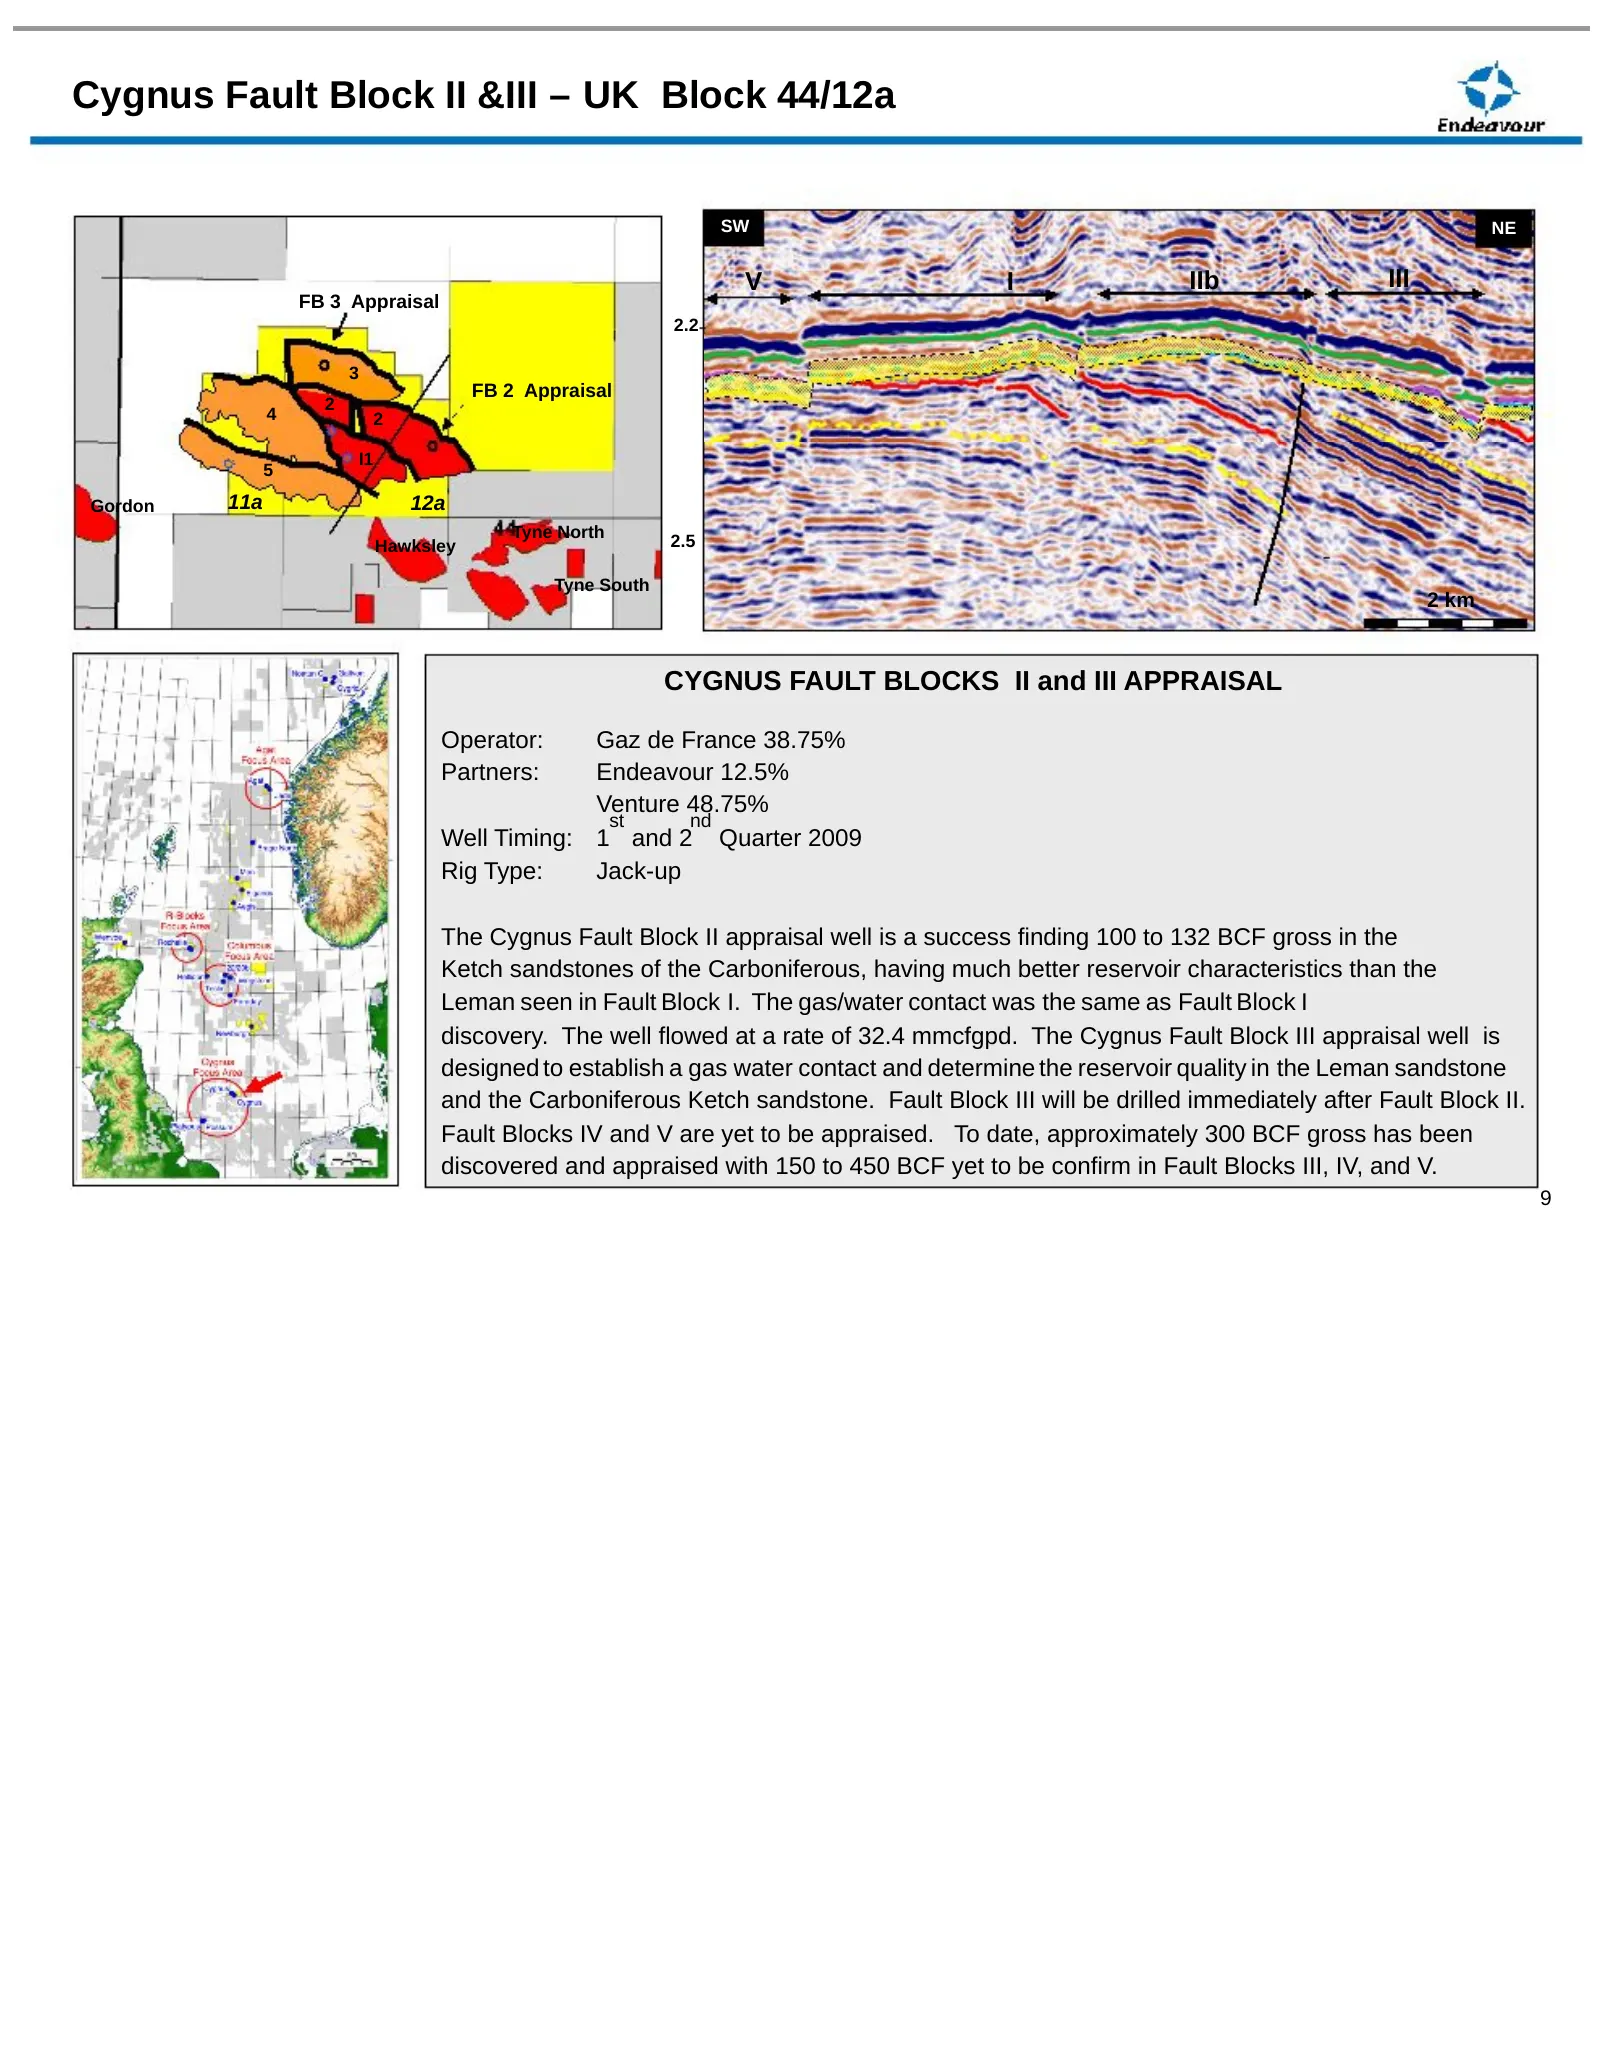
Cygnus Fault Block II &III – UK Block 44/12a SW NE V I IIb III FB 3 Appraisal 2.2 3 FB 2 Appraisal 2 4 2 I1 5 Gordon 11a 12a Tyne North Hawksley 2.5 Tyne South 2 km CYGNUS FAULT BLOCKS II and III APPRAISAL Operator: Gaz de France 38.75% Partners: Endeavour 12.5% Venture 48.75% st nd Well Timing: 1 a
Slide 10: Cygnus Location Area Map
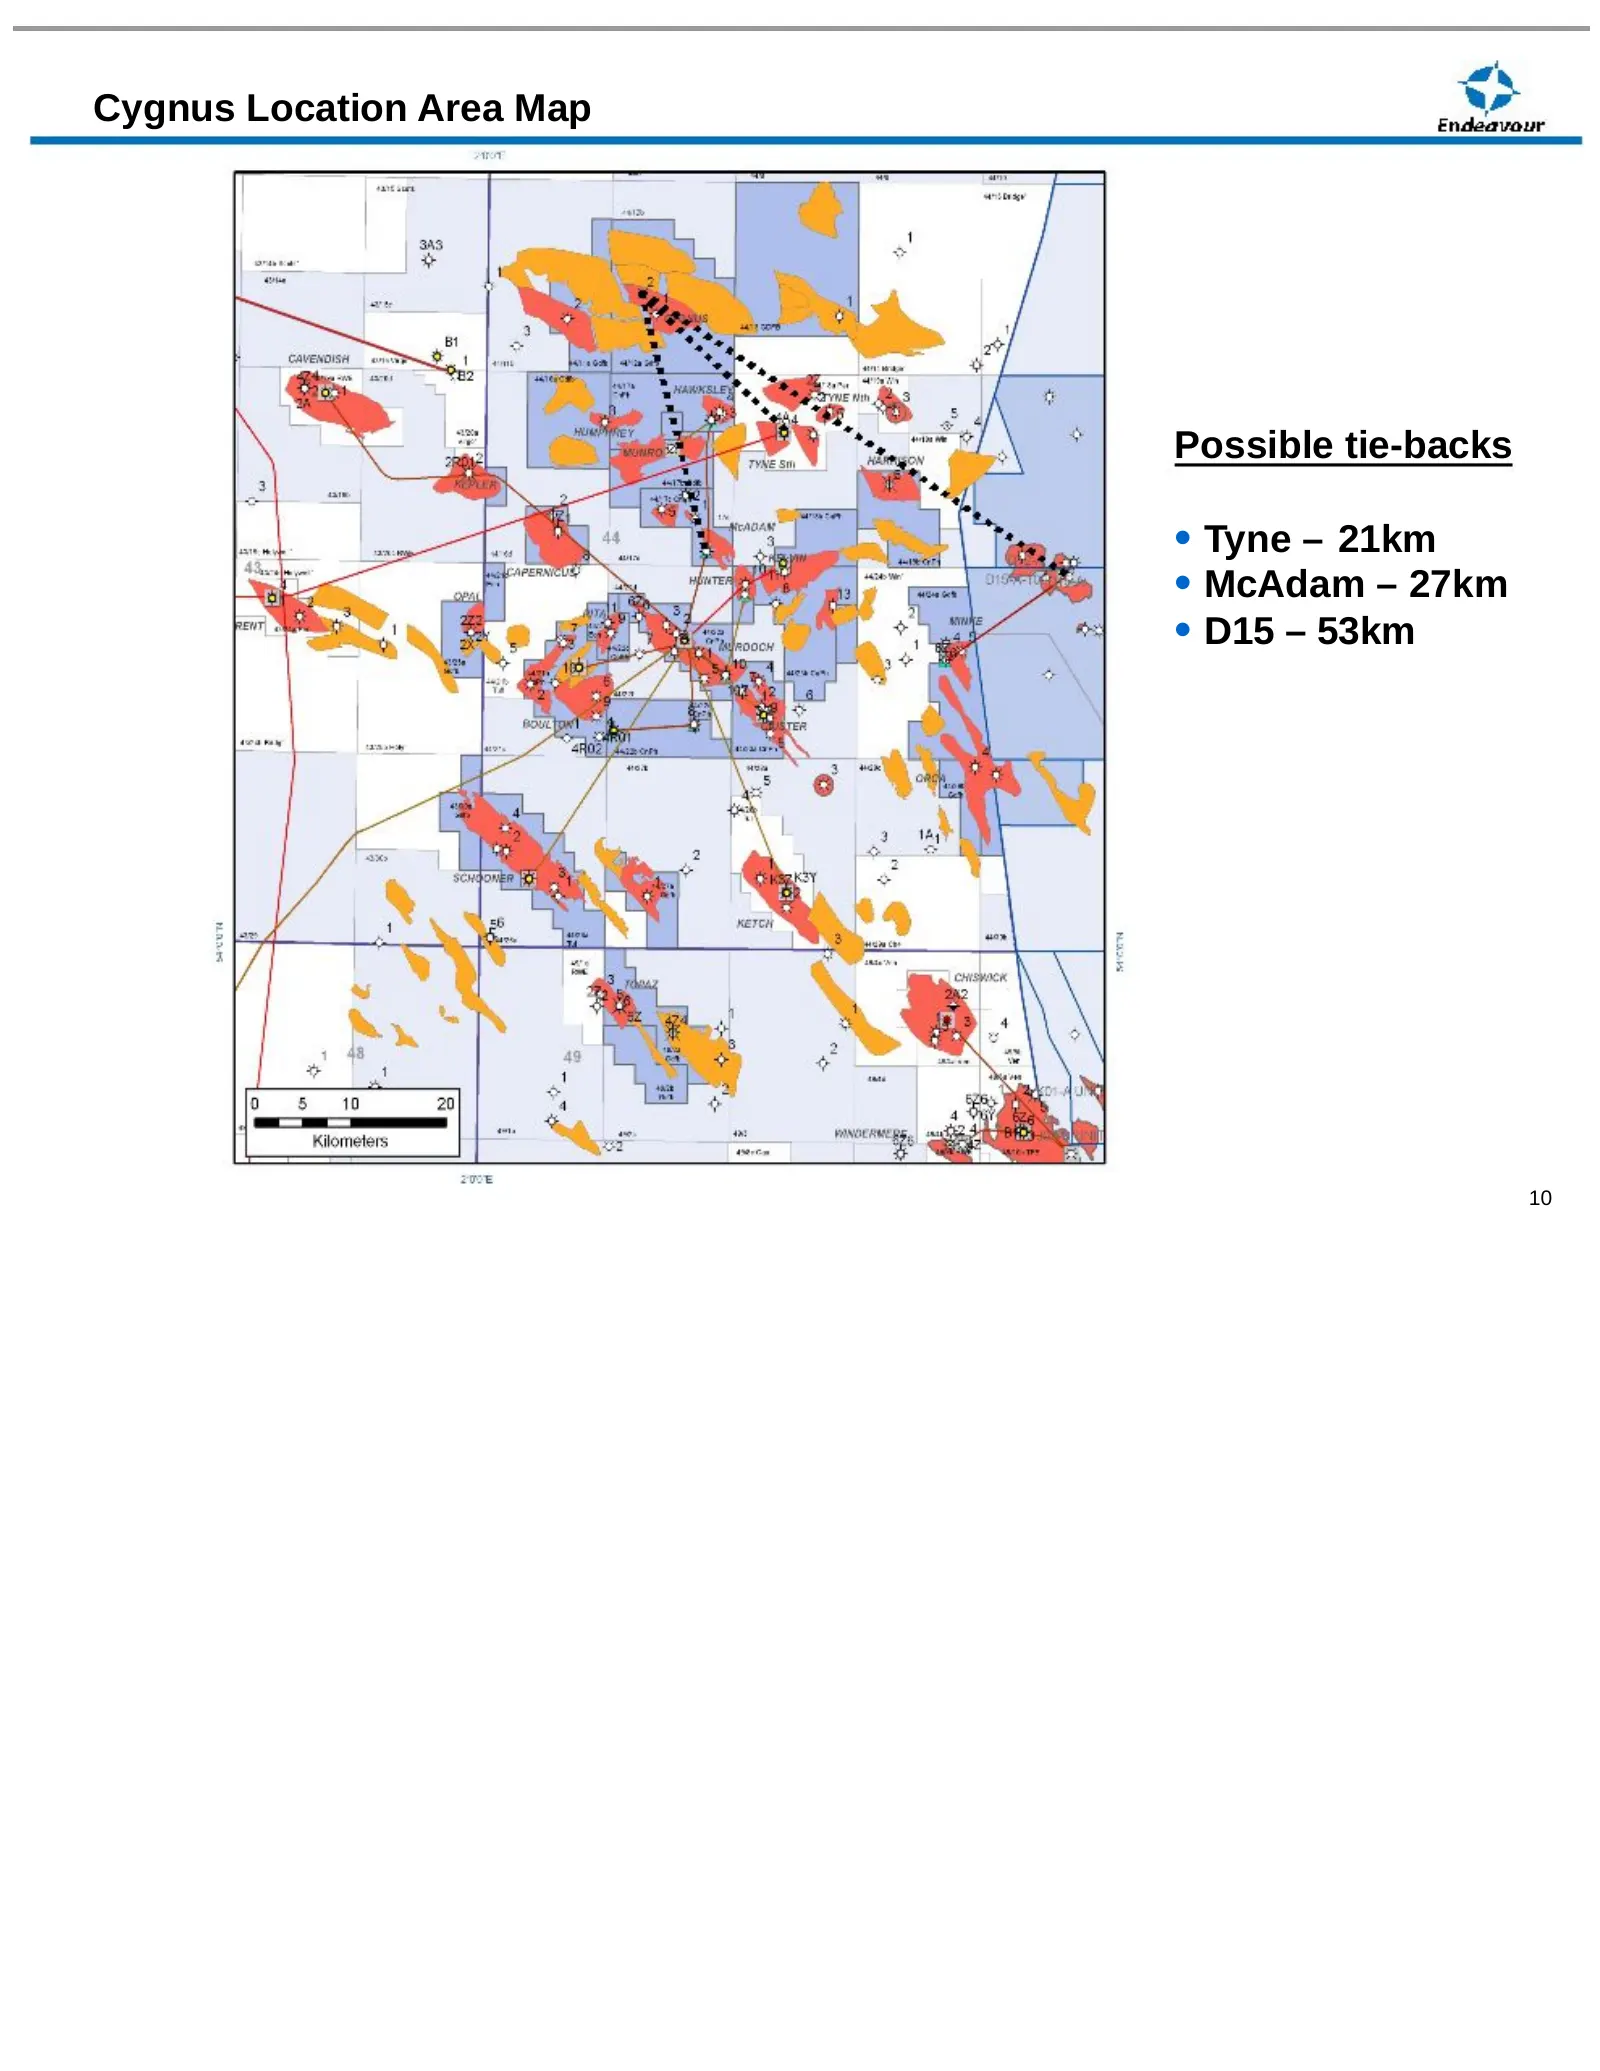
Cygnus Location Area Map Possible tie-backs • Tyne – 21km • McAdam – 27km • D15 – 53km 10
Slide 11: Columbus Development
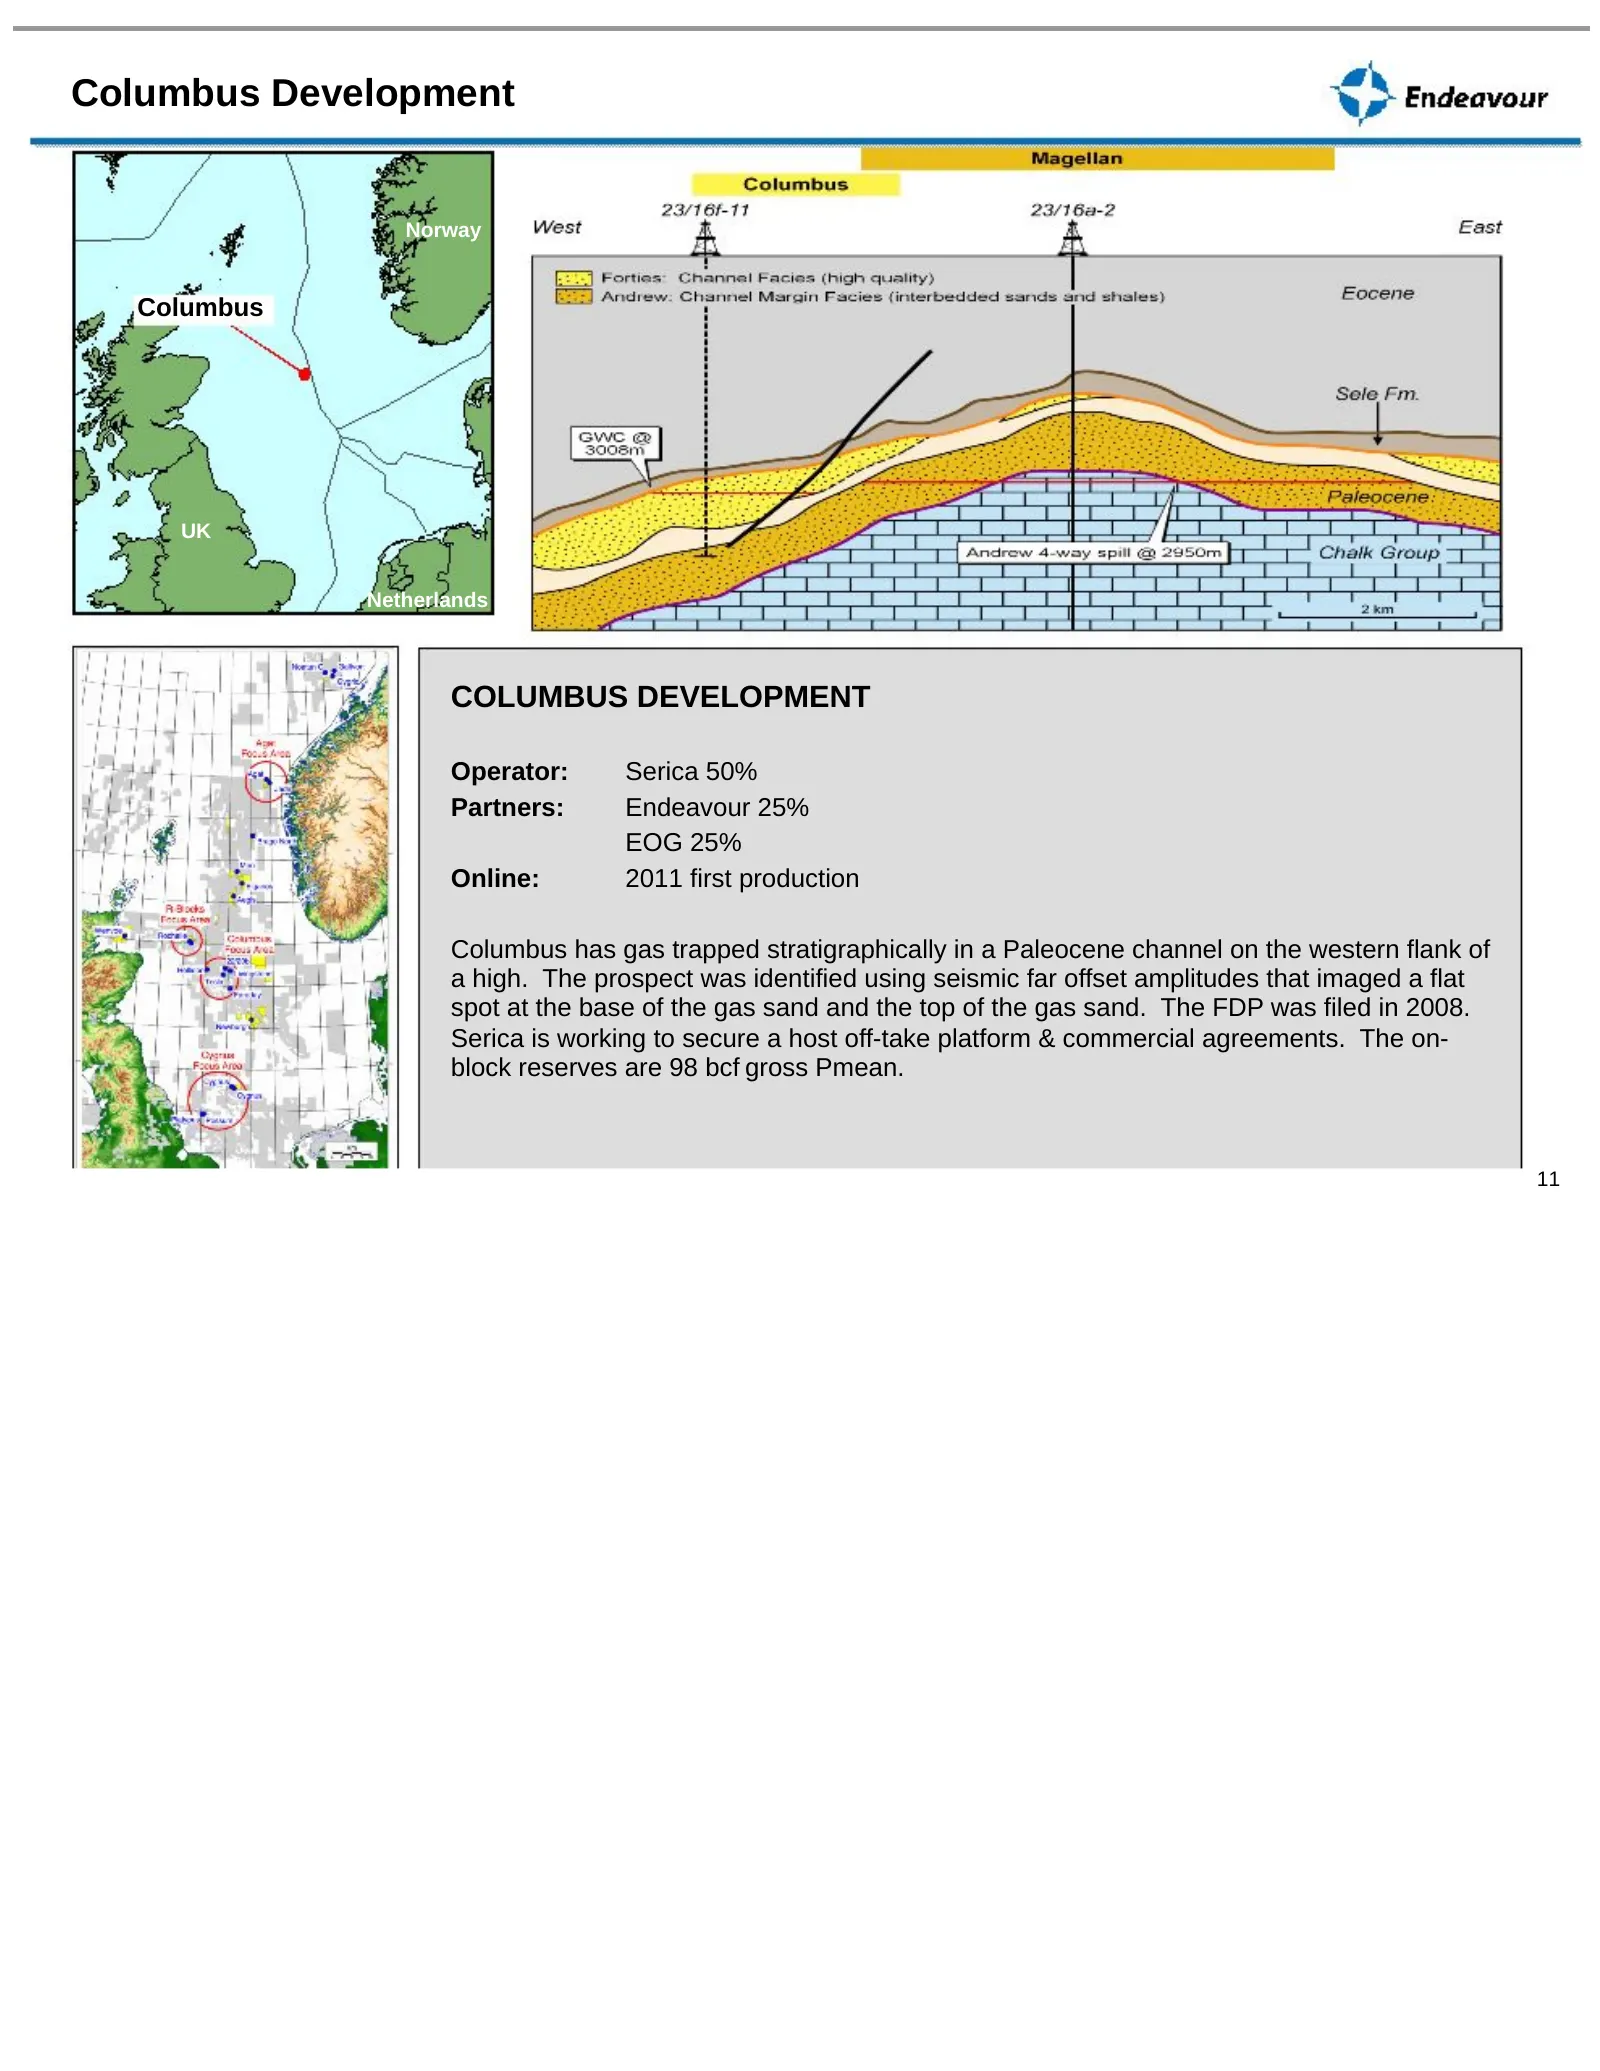
Columbus Development Norway Columbus UK Netherlands COLUMBUS DEVELOPMENT Operator: Serica 50% Partners: Endeavour 25% EOG 25% Online: 2011 first production Columbus has gas trapped stratigraphically in a Paleocene channel on the western flank of a high. The prospect was identified using seismic far
Slide 12: Columbus Tie-in Options
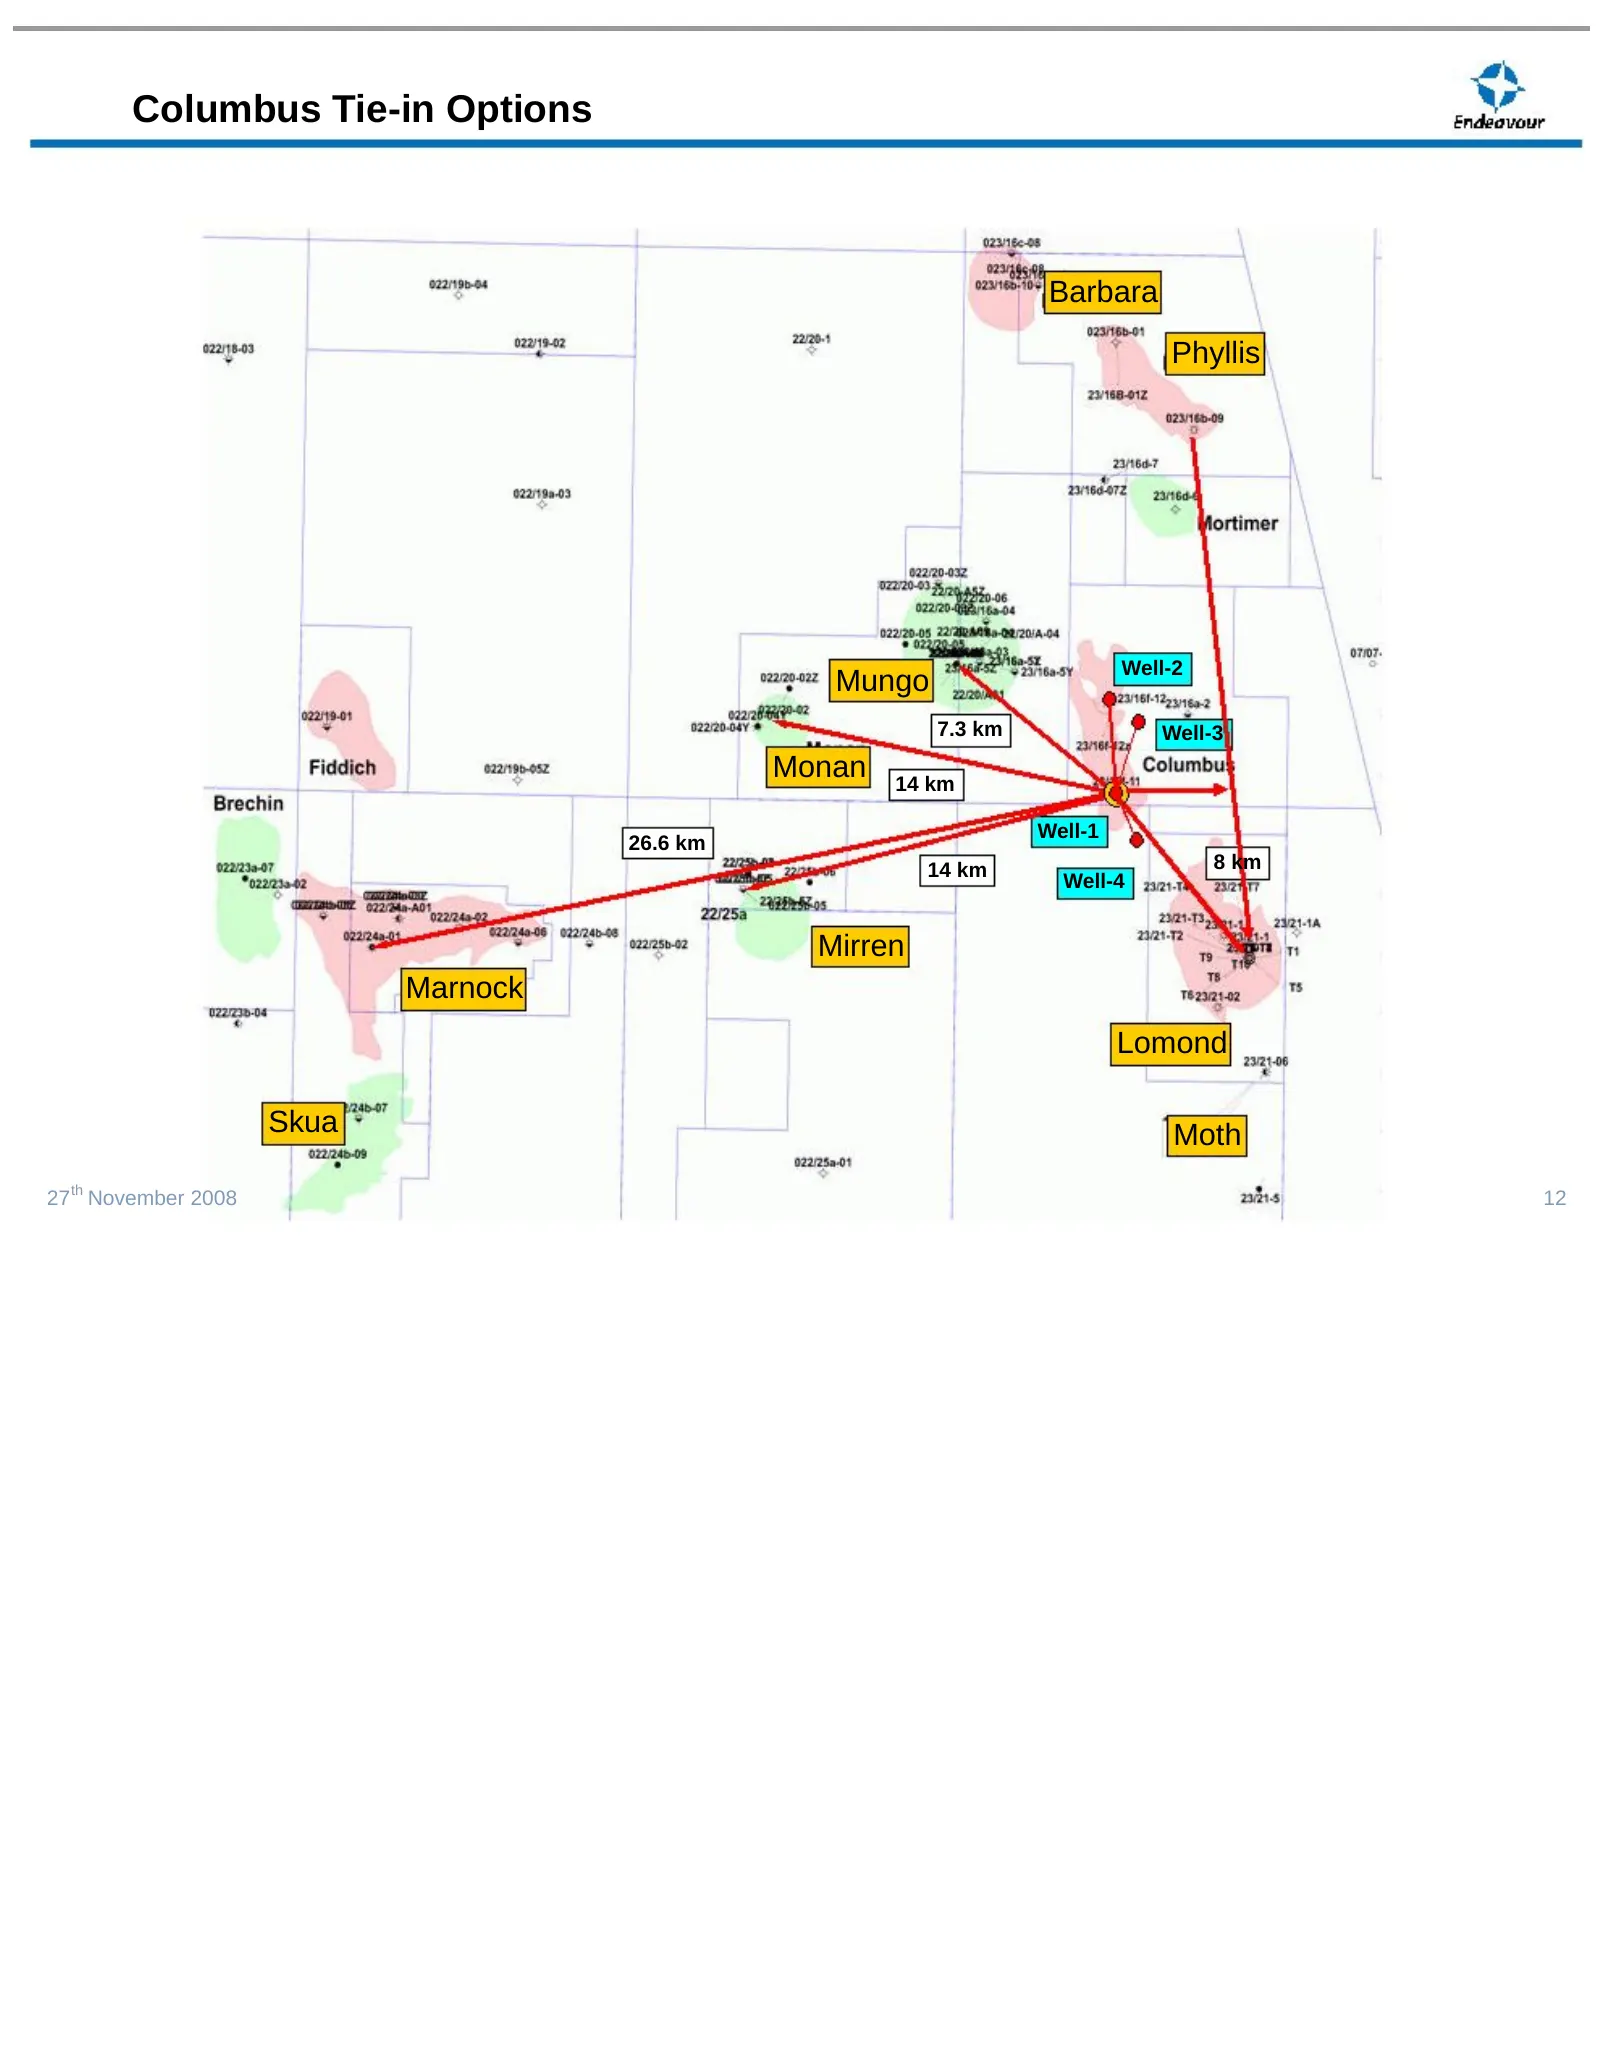
Columbus Tie-in Options Barbara Phyllis Well-2 Mungo 7.3 km Well-3 Monan 14 km Well-1 26.6 km 14 km 8 km Well-4 Mirren Marnock Lomond Skua Moth 27 th November 2008 12
Slide 13: US Growth Strategy
US Growth Strategy Initial entrance in onshore Texas to participate in several onshore prospects • Lower finding cost • Higher pre-drill reserve potential • Lower tax rate and NOLs • Shorter cycle time from discovery to production than a similar type prospect in the North Sea Recent downturn in the
Slide 14: 2008 Exploration and Appraisal Wells
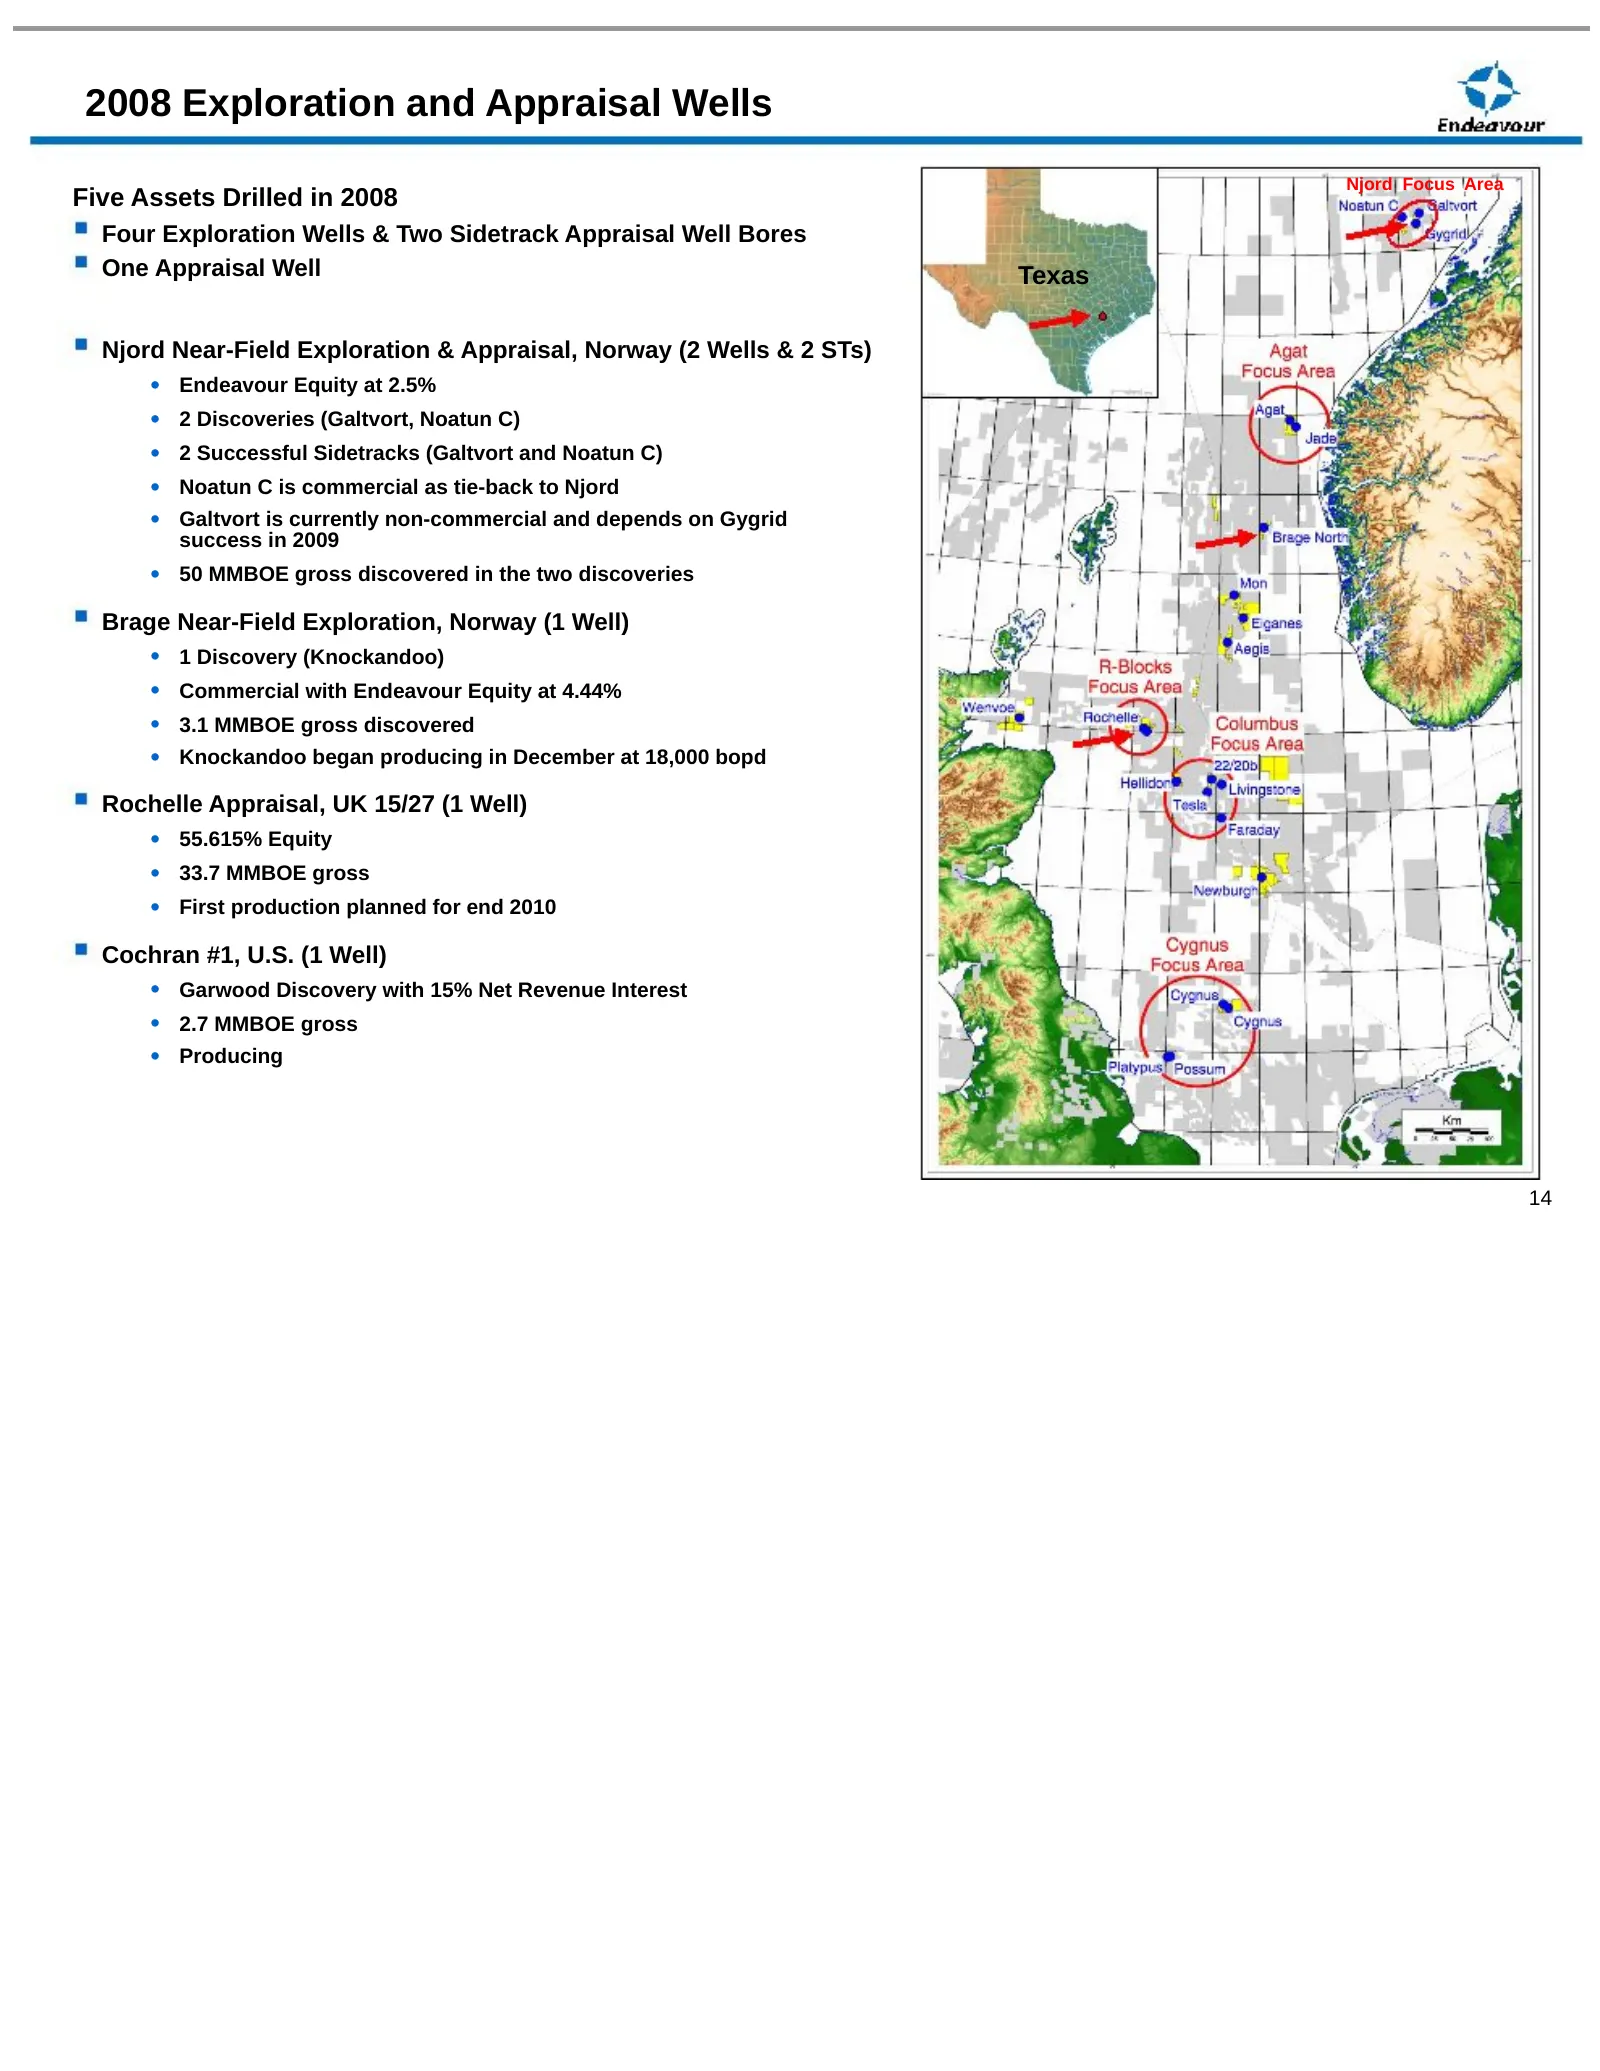
2008 Exploration and Appraisal Wells Njord Focus Area Five Assets Drilled in 2008 Four Exploration Wells & Two Sidetrack Appraisal Well Bores One Appraisal Well Texas Njord Near-Field Exploration & Appraisal, Norway (2 Wells & 2 STs) • Endeavour Equity at 2.5% • 2 Discoveries (Galtvort, Noatun C) •
Slide 15: Njord Focus Area
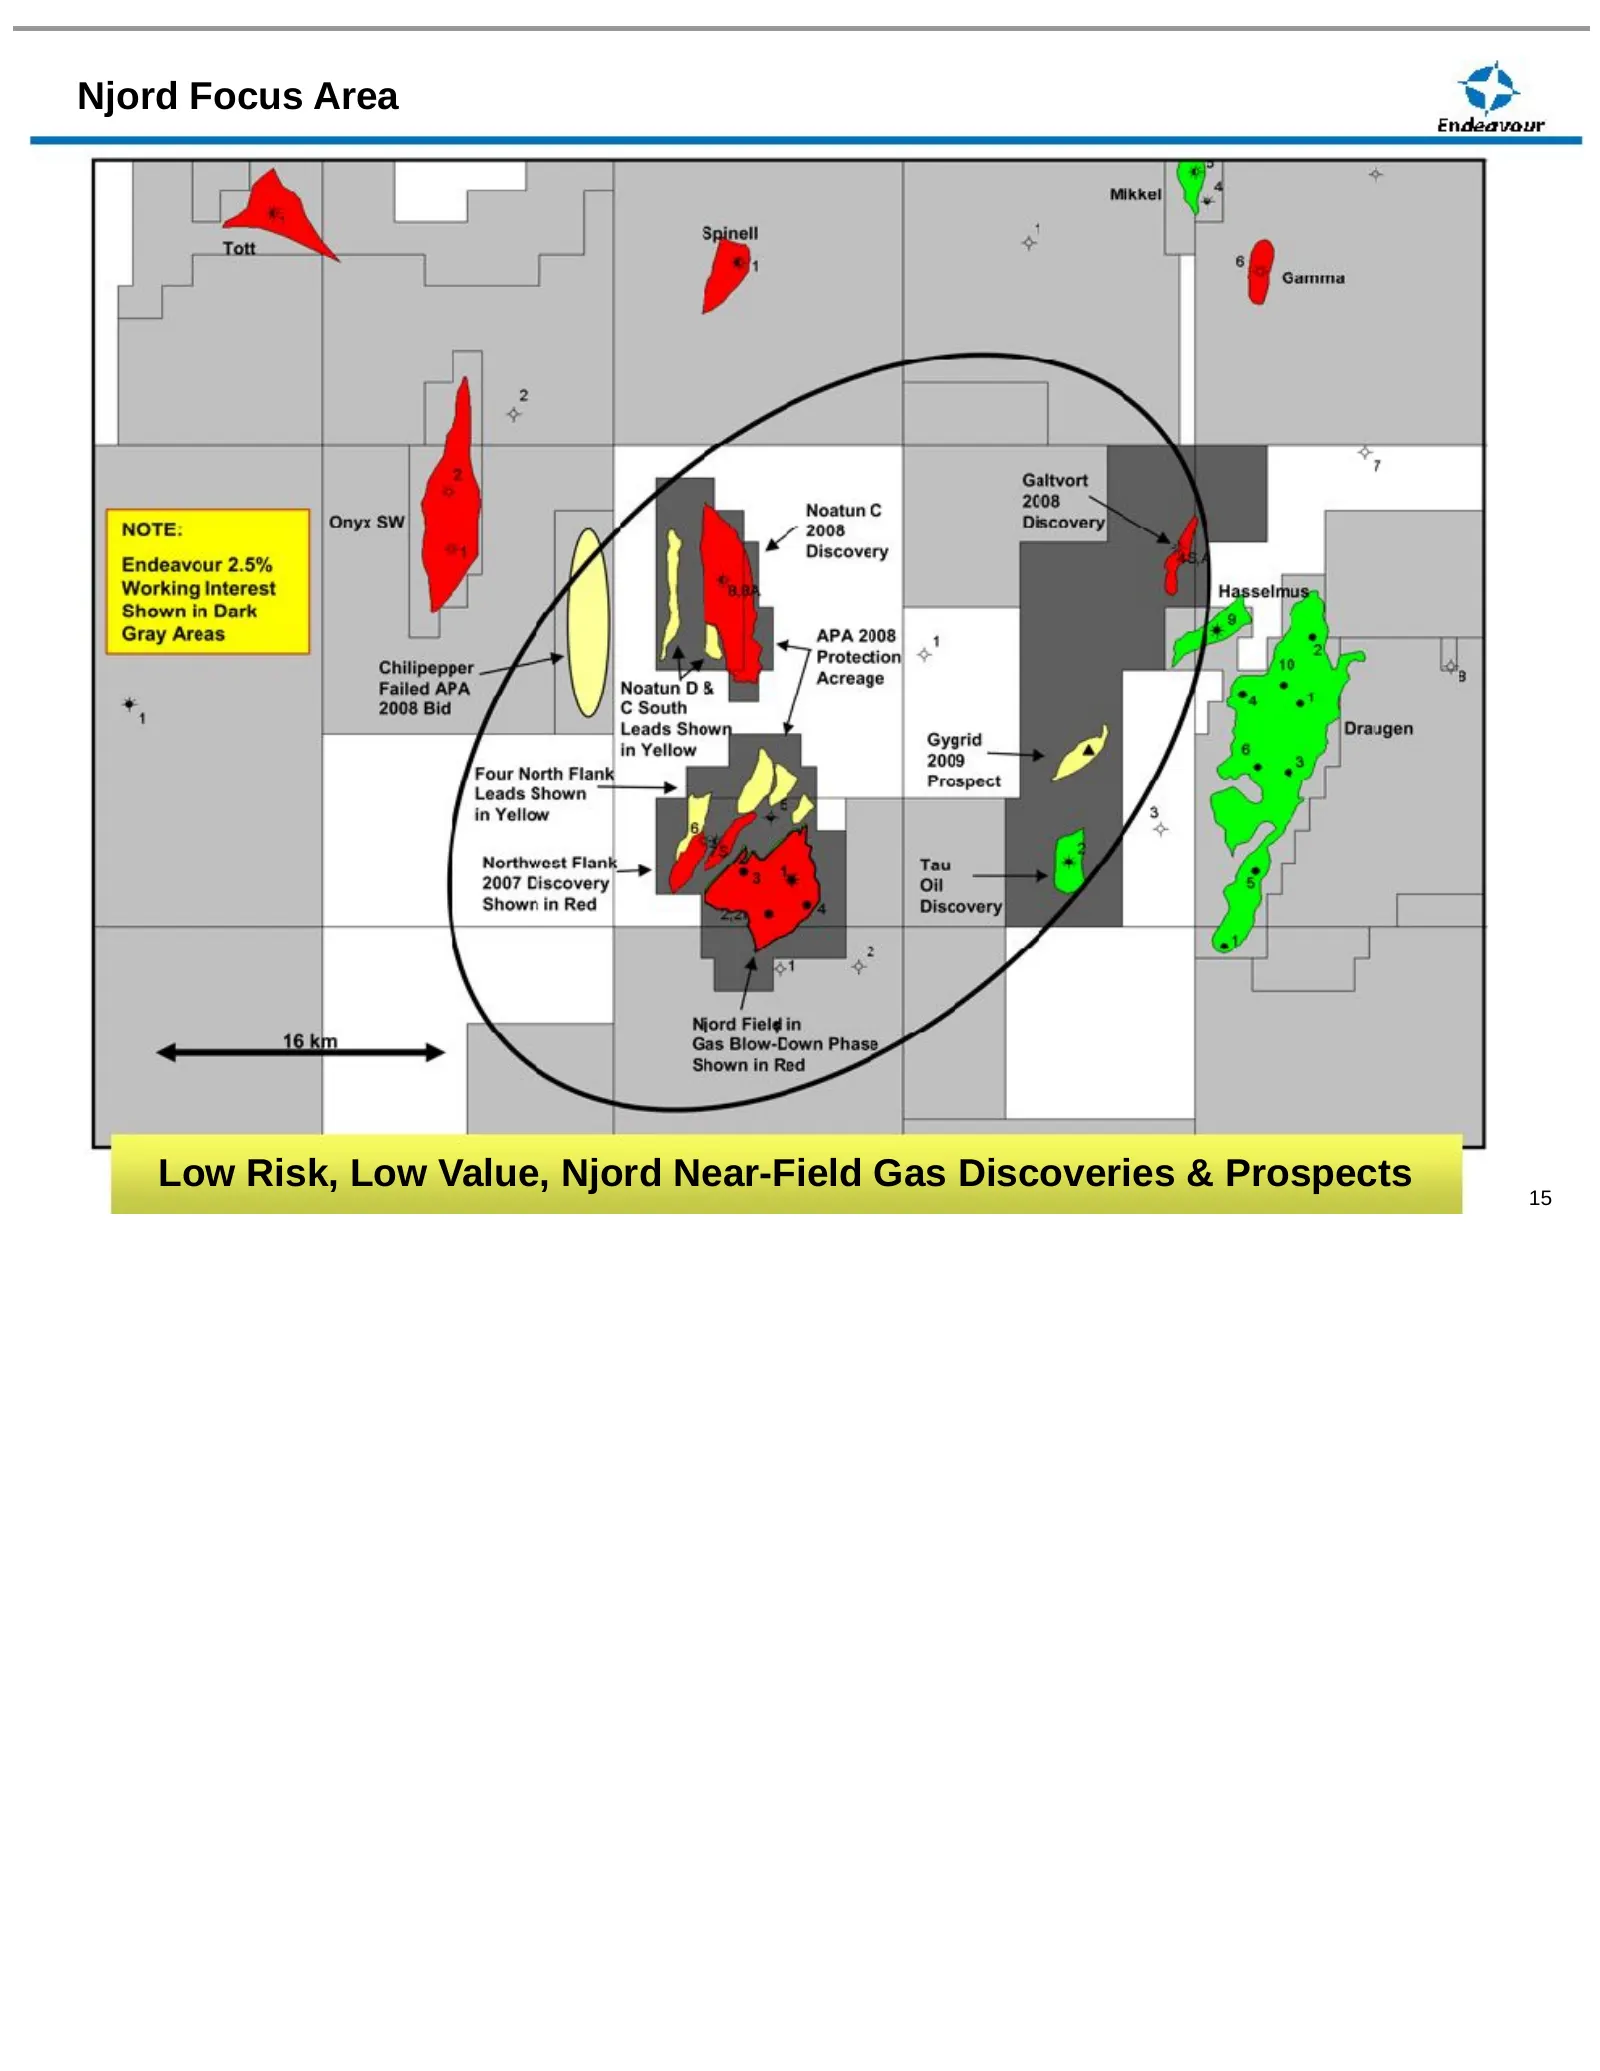
Njord Focus Area Low Risk, Low Value, Njord Near-Field Gas Discoveries & Prospects 15
Slide 16: Brage Knockandoo - Norway Block 31/4
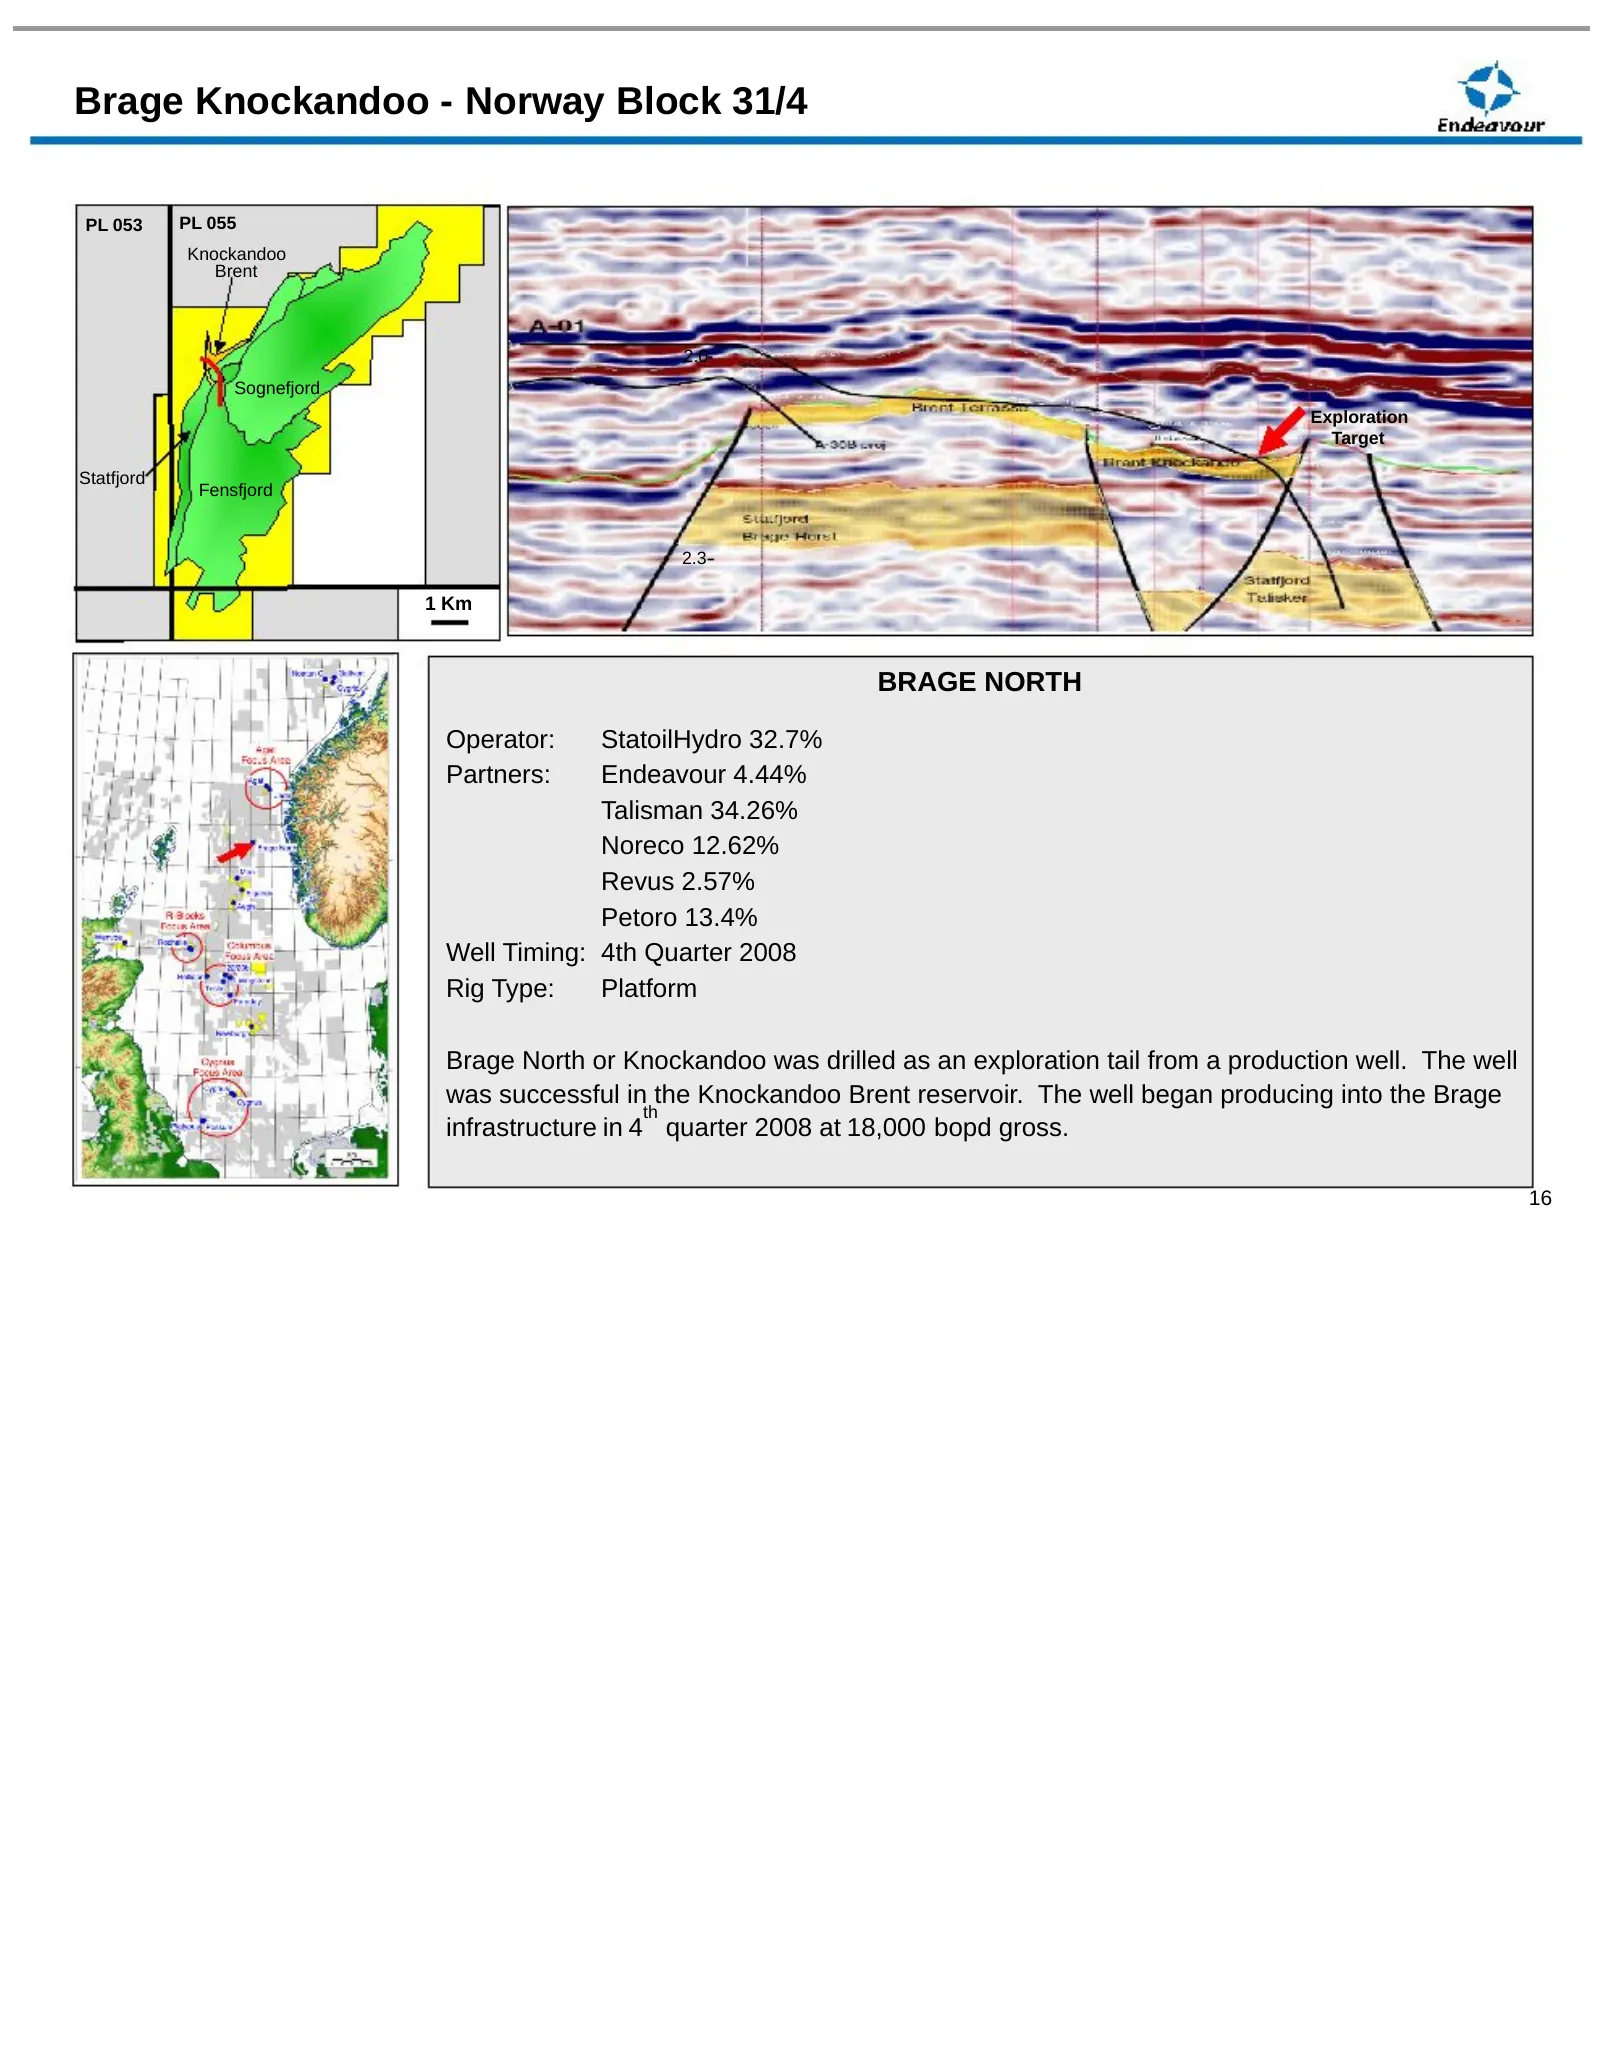
Brage Knockandoo - Norway Block 31/4 PL 053 PL 055 Knockandoo Brent 2.0 Sognefjord Exploration Target Statfjord Fensfjord 2.3 1 Km BRAGE NORTH Operator: StatoilHydro 32.7% Partners: Endeavour 4.44% Talisman 34.26% Noreco 12.62% Revus 2.57% Petoro 13.4% Well Timing: 4th Quarter 2008 Rig Type: Platfor
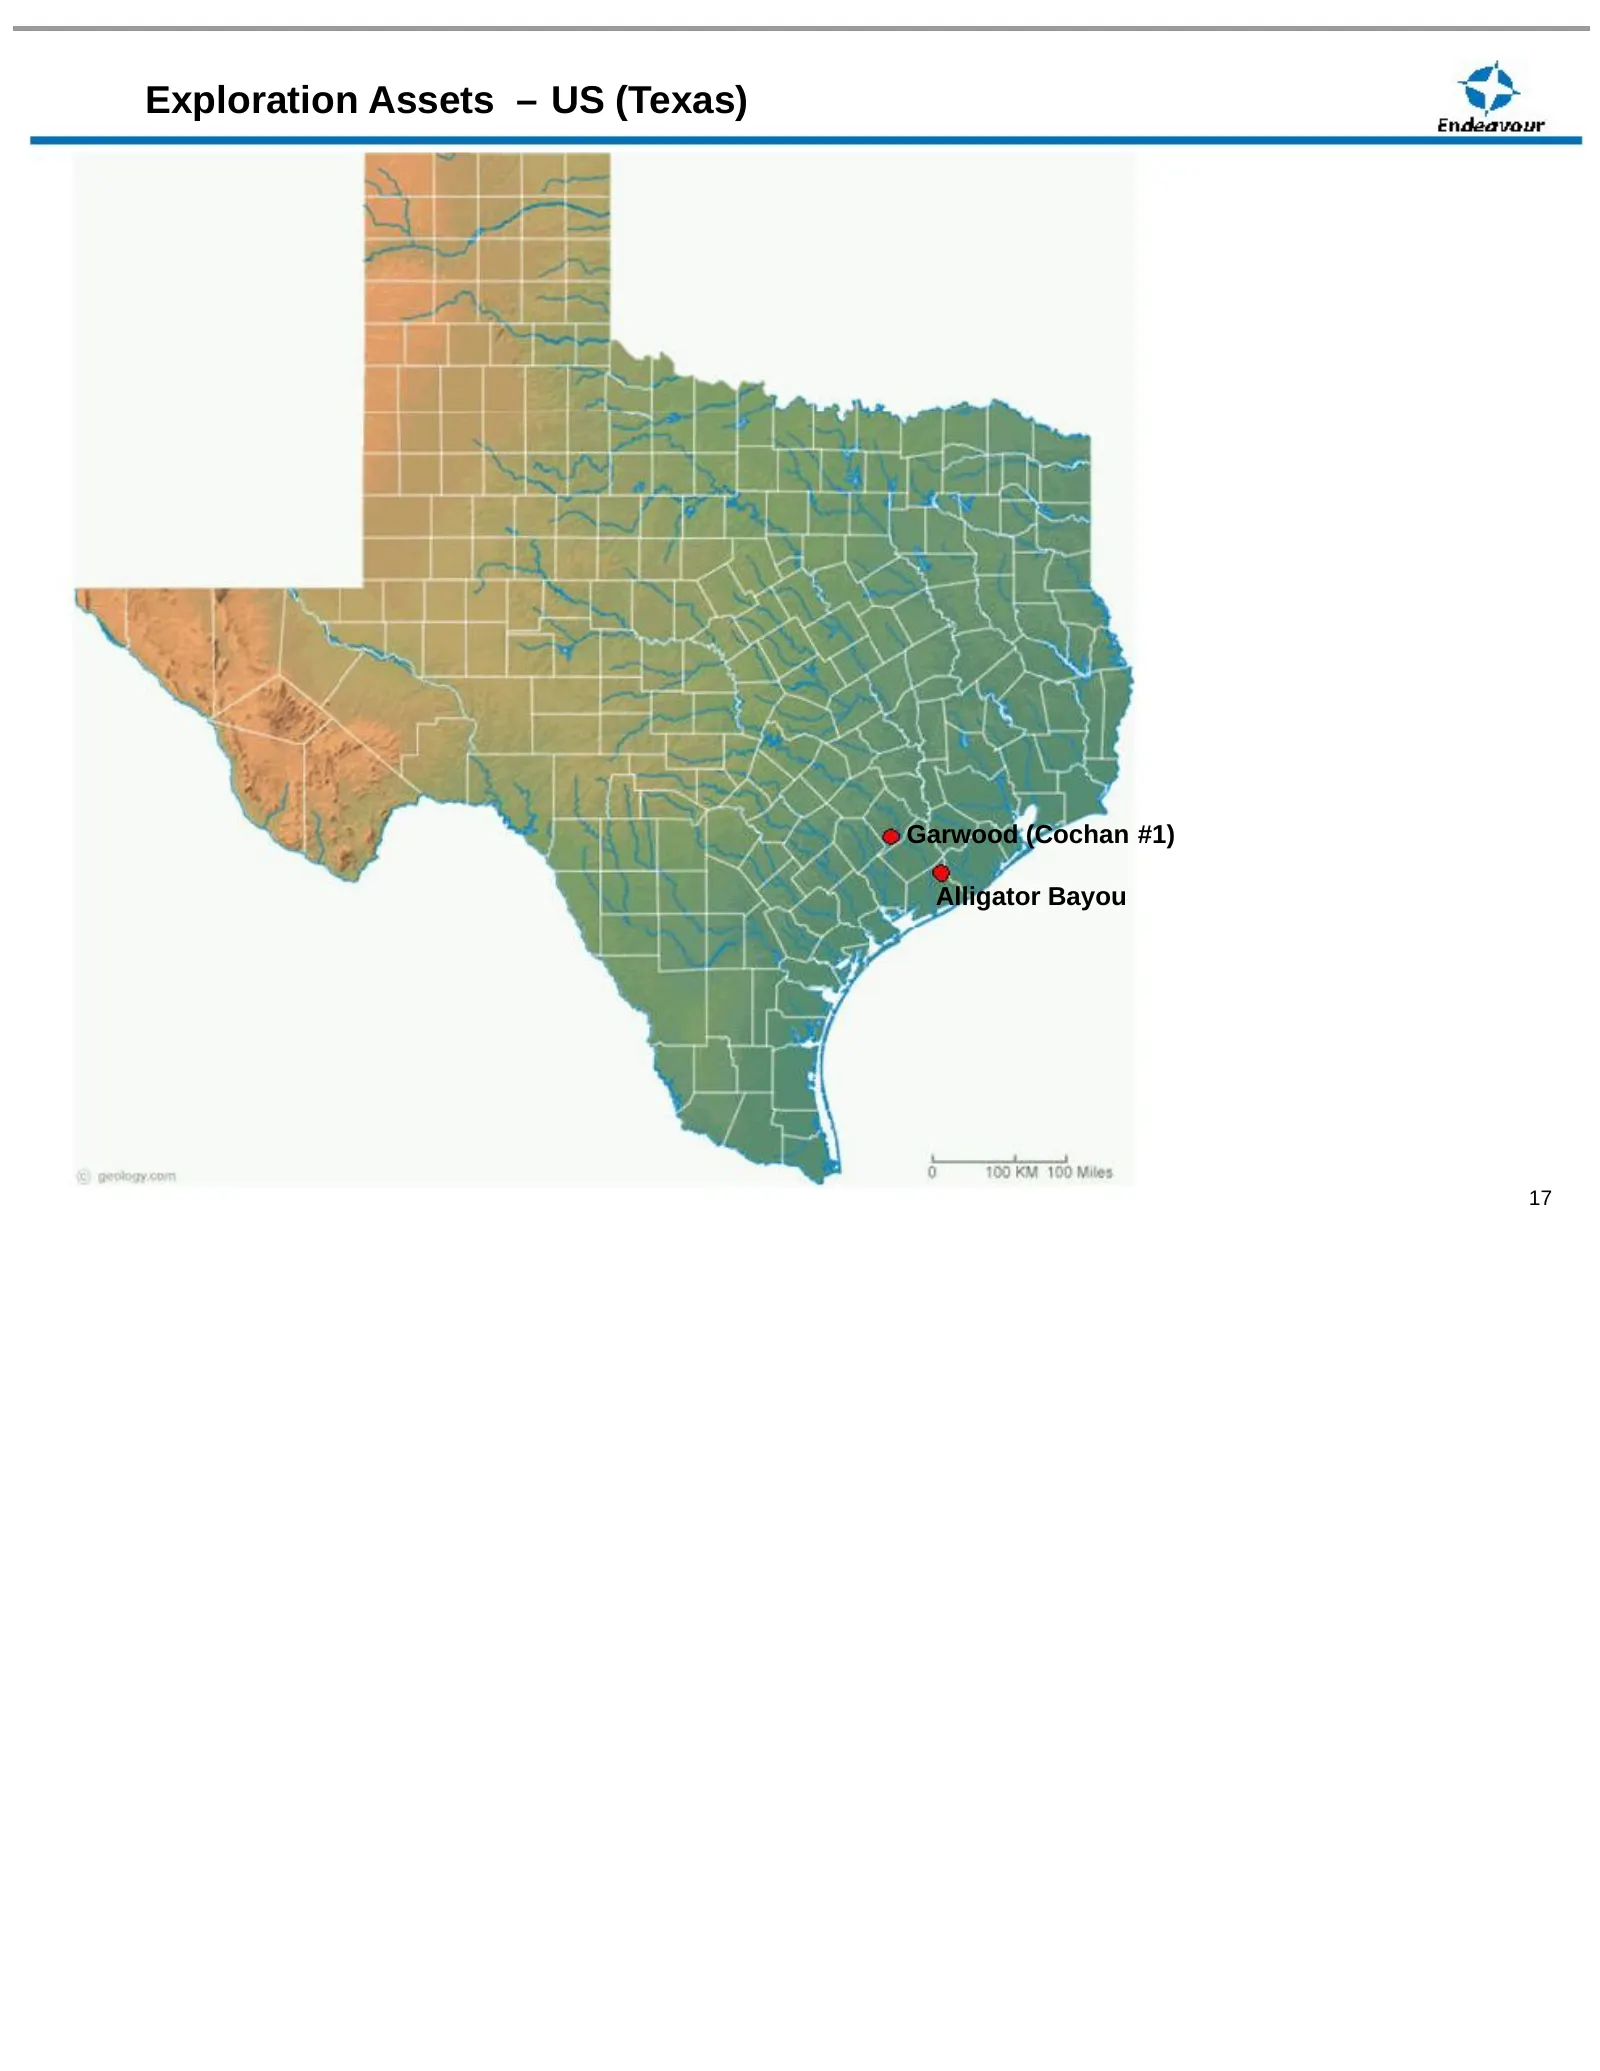
Slide 17: Exploration Assets – US (Texas)
Exploration Assets – US (Texas) Garwood (Cochan #1) Alligator Bayou 17
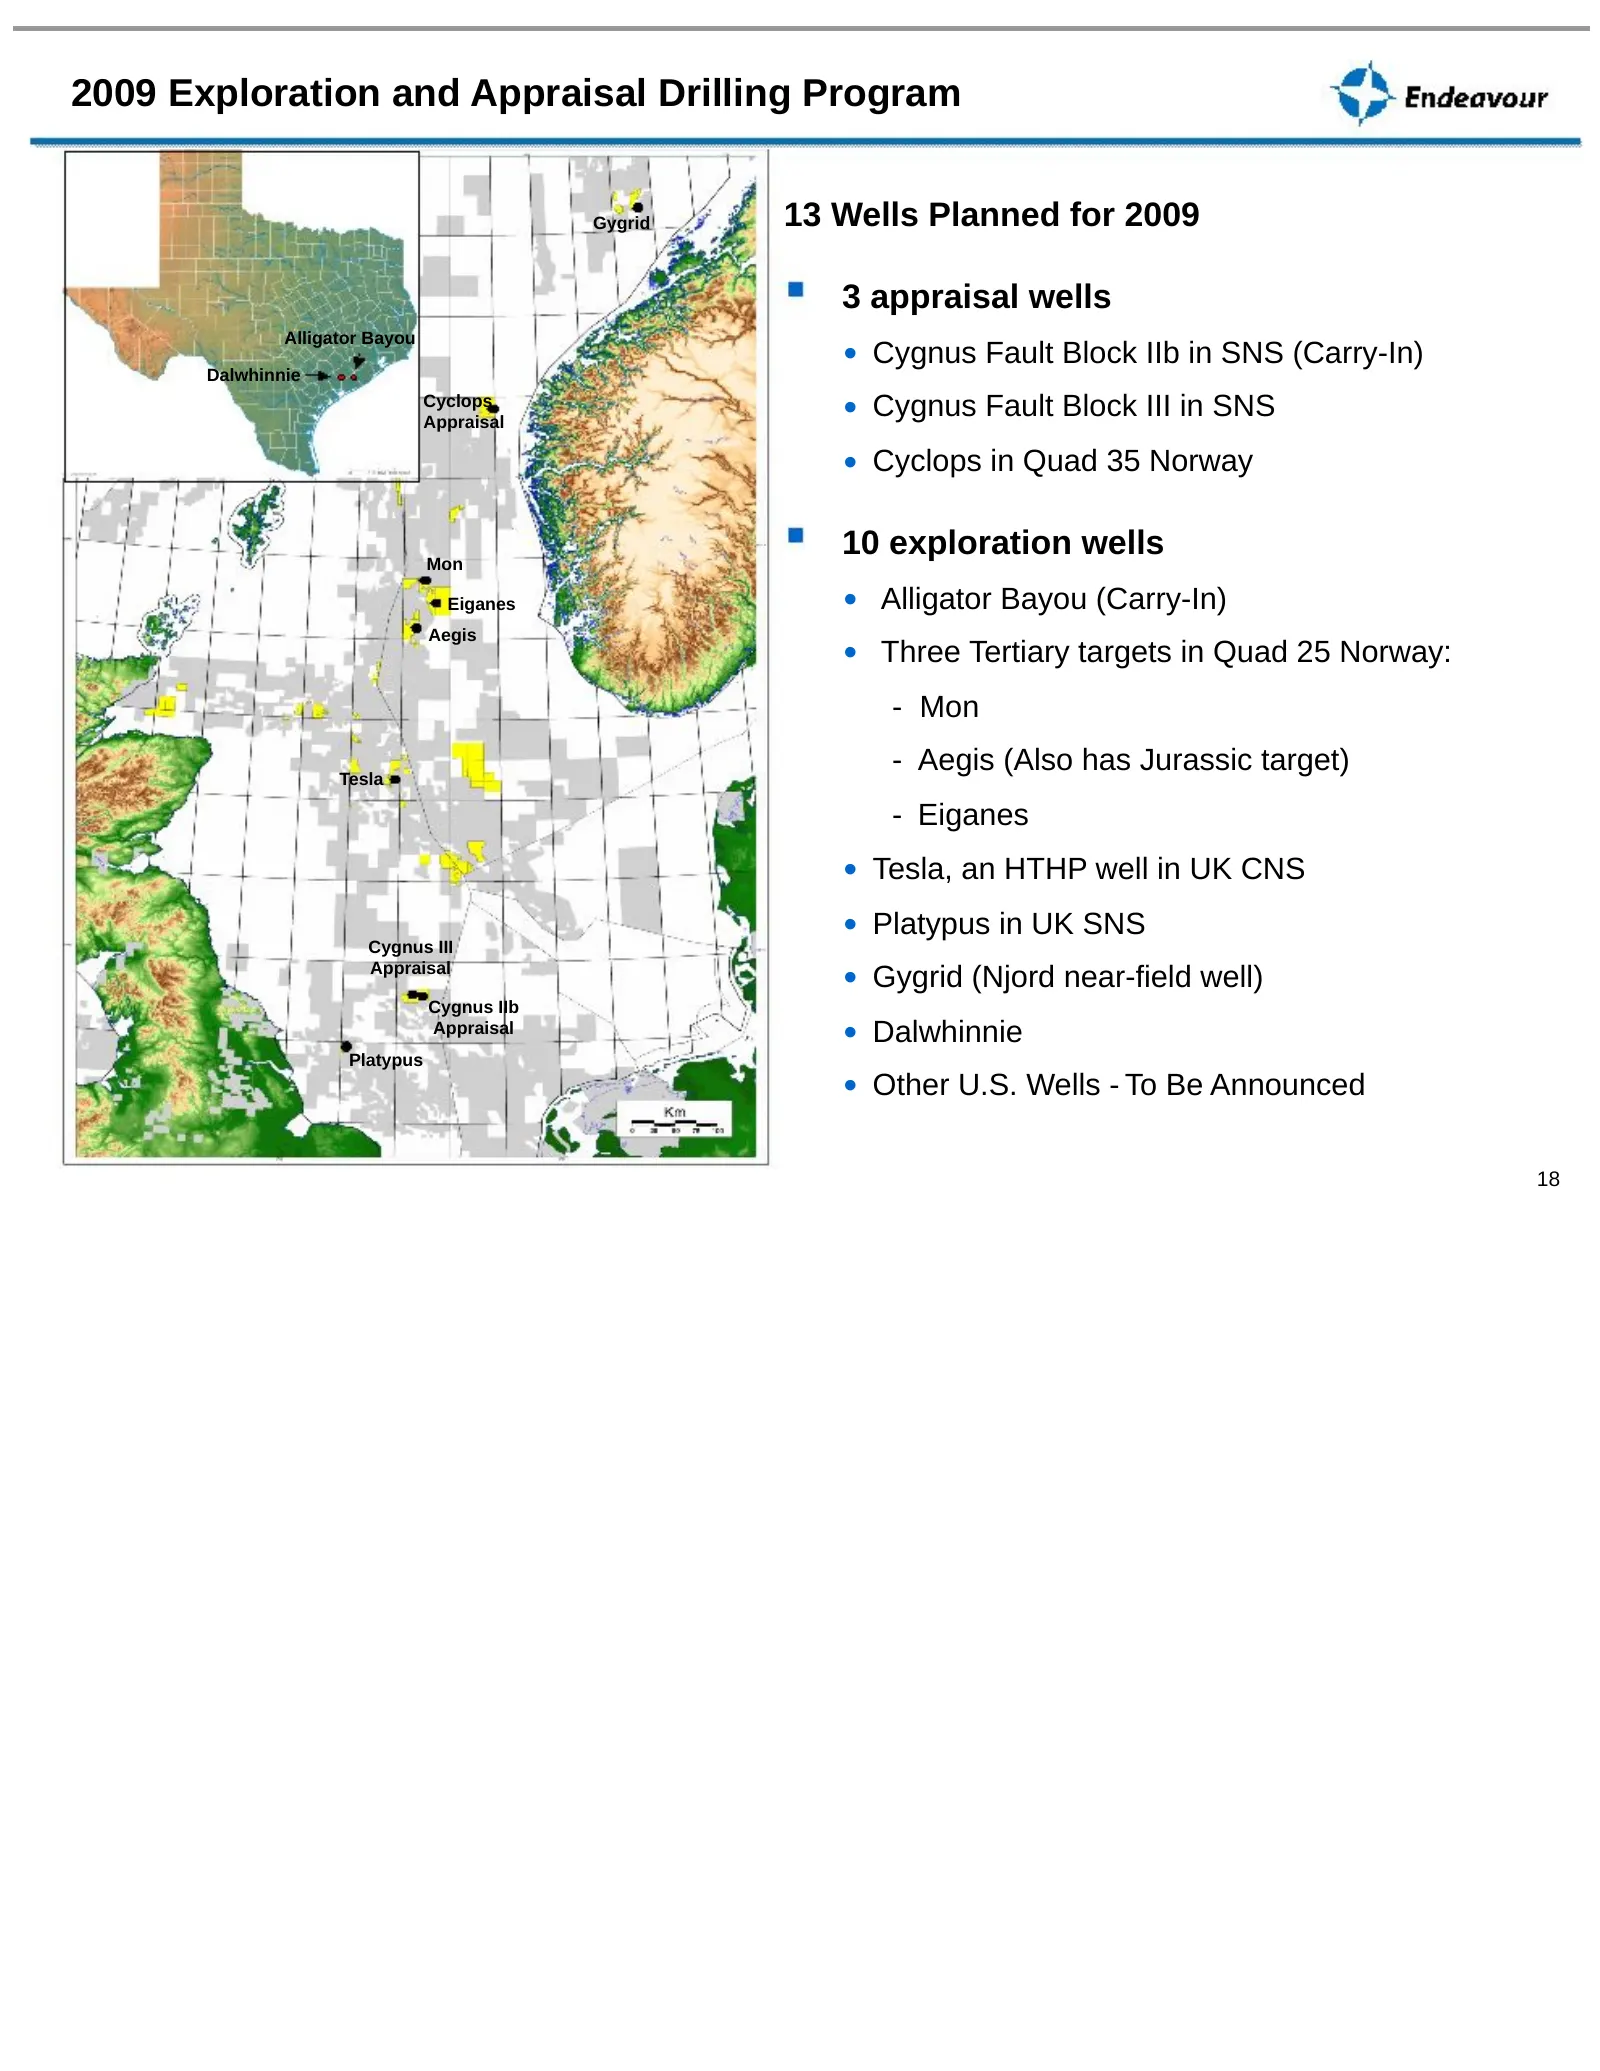
Slide 18: 2009 Exploration and Appraisal Drilling Program
2009 Exploration and Appraisal Drilling Program Gygrid 13 Wells Planned for 2009 3 appraisal wells Alligator Bayou Dalwhinnie • Cygnus Fault Block IIb in SNS (Carry-In) Cyclops Appraisal • Cygnus Fault Block III in SNS • Cyclops in Quad 35 Norway Mon 10 exploration wells Eiganes • Alligator Bayou (C
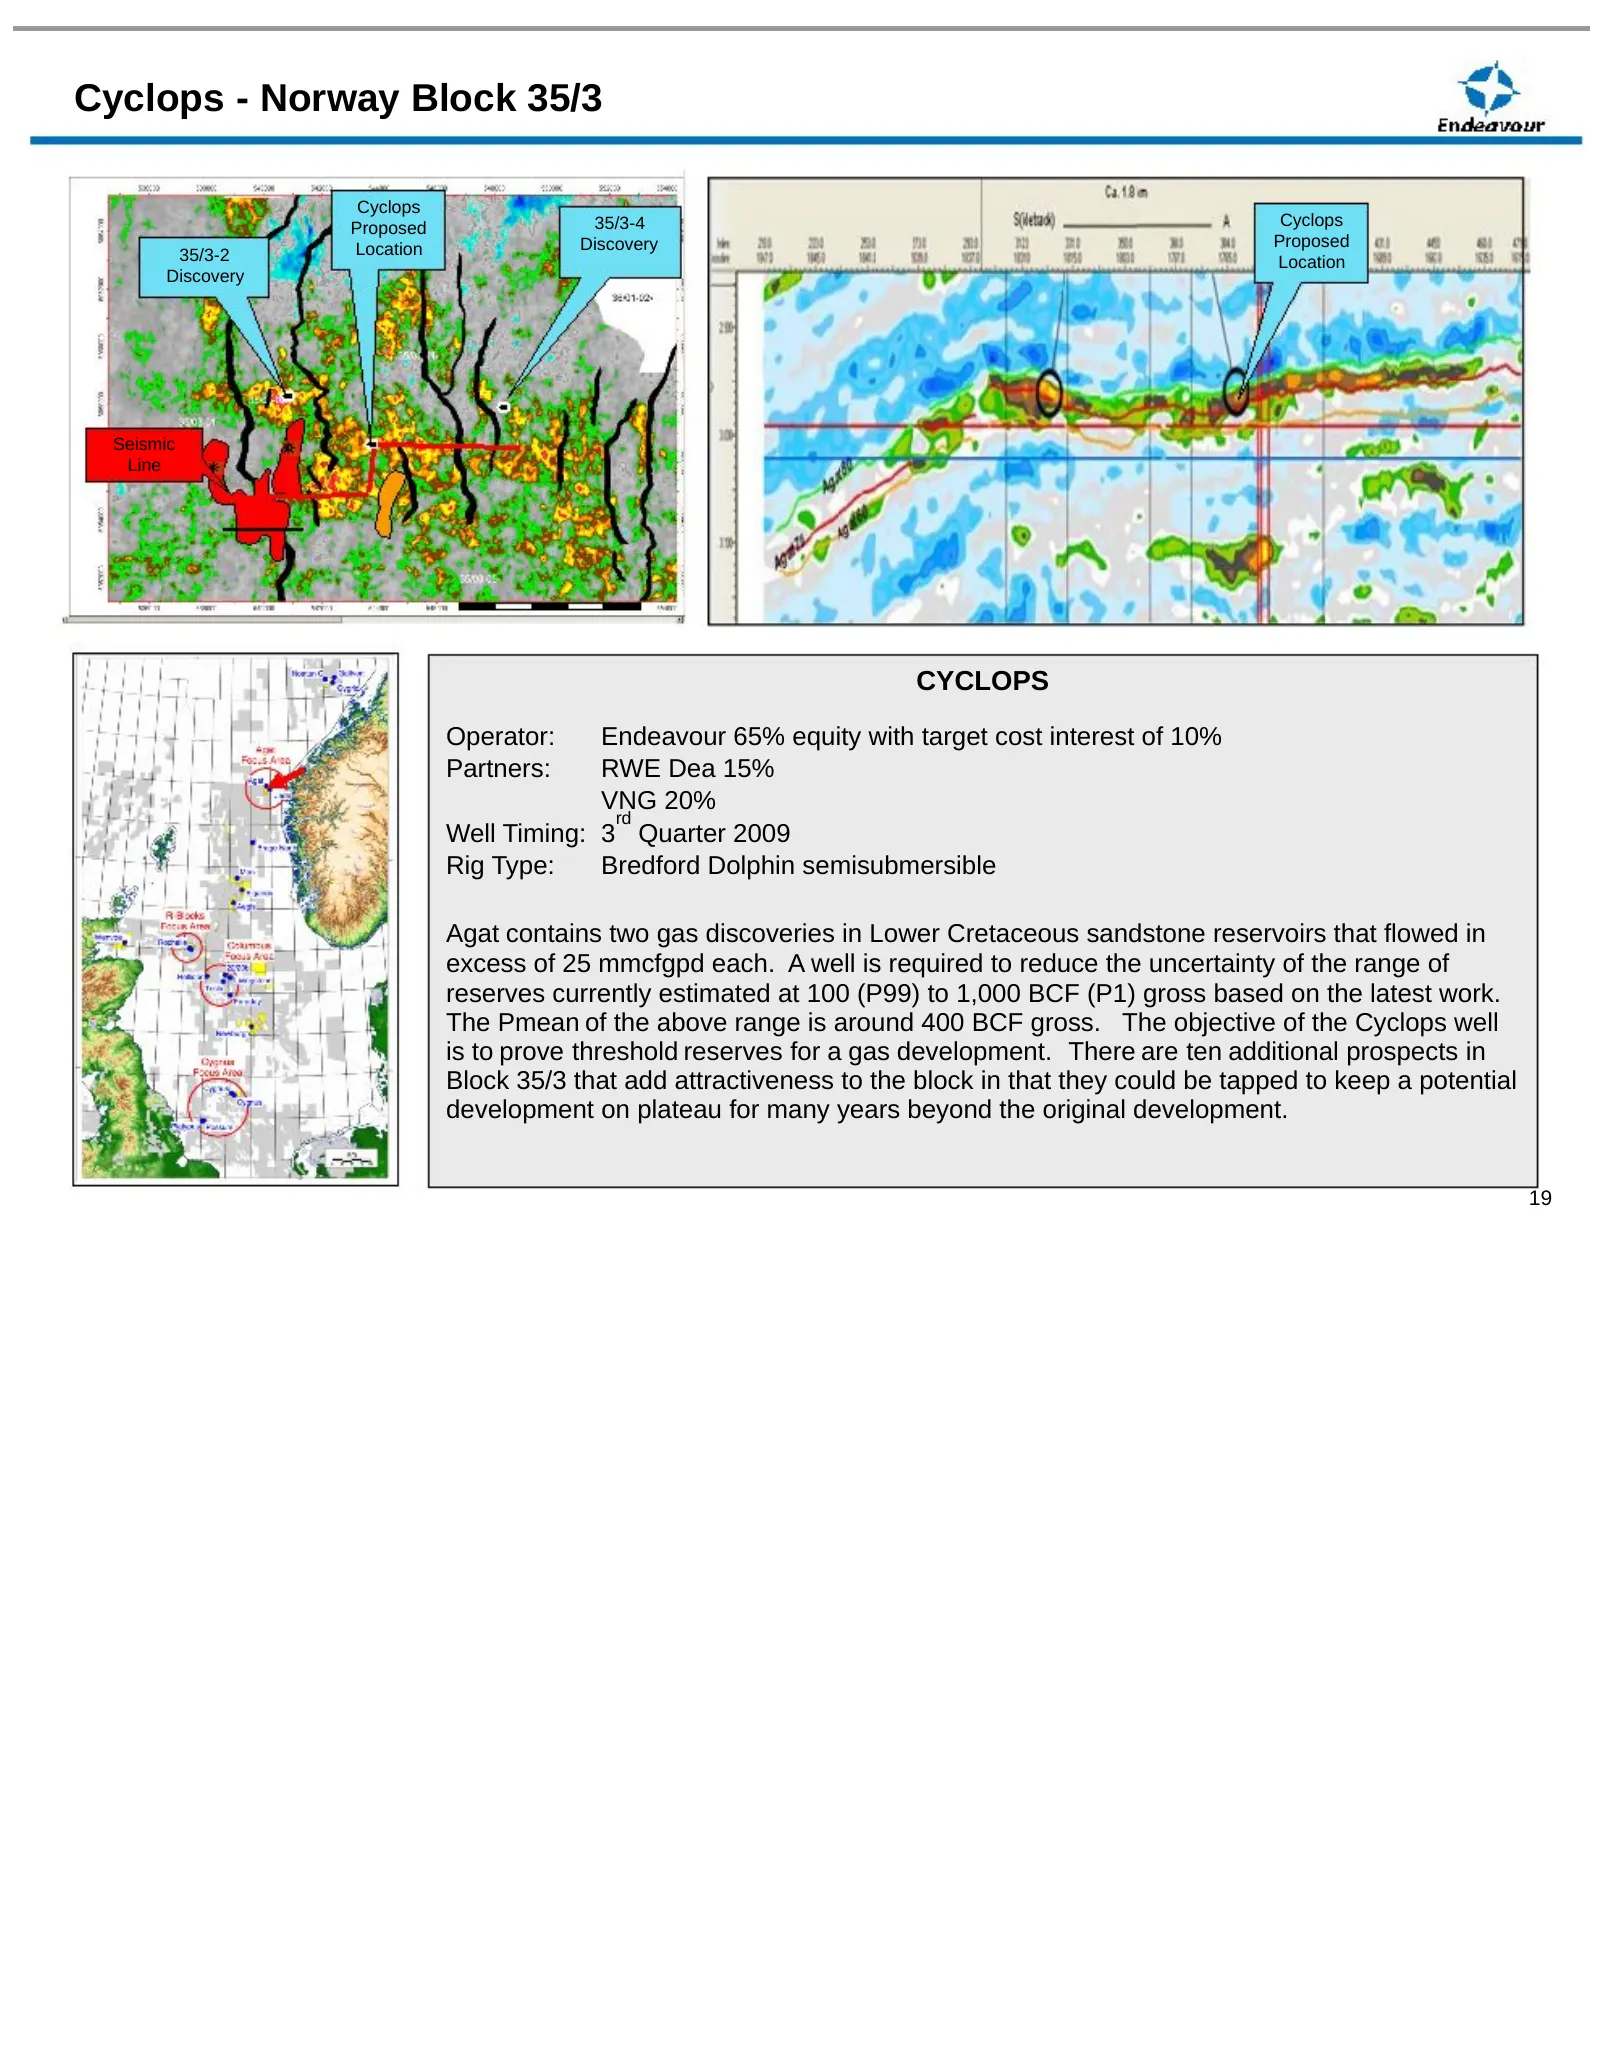
Slide 19: Cyclops - Norway Block 35/3
Cyclops - Norway Block 35/3 Cyclops Proposed 35/3-4 Cyclops Location Discovery Proposed 35/3-2 Location Discovery Seismic Line CYCLOPS Operator: Endeavour 65% equity with target cost interest of 10% Partners: RWE Dea 15% VNG 20% rd Well Timing: 3 Quarter 2009 Rig Type: Bredford Dolphin semisubmersib
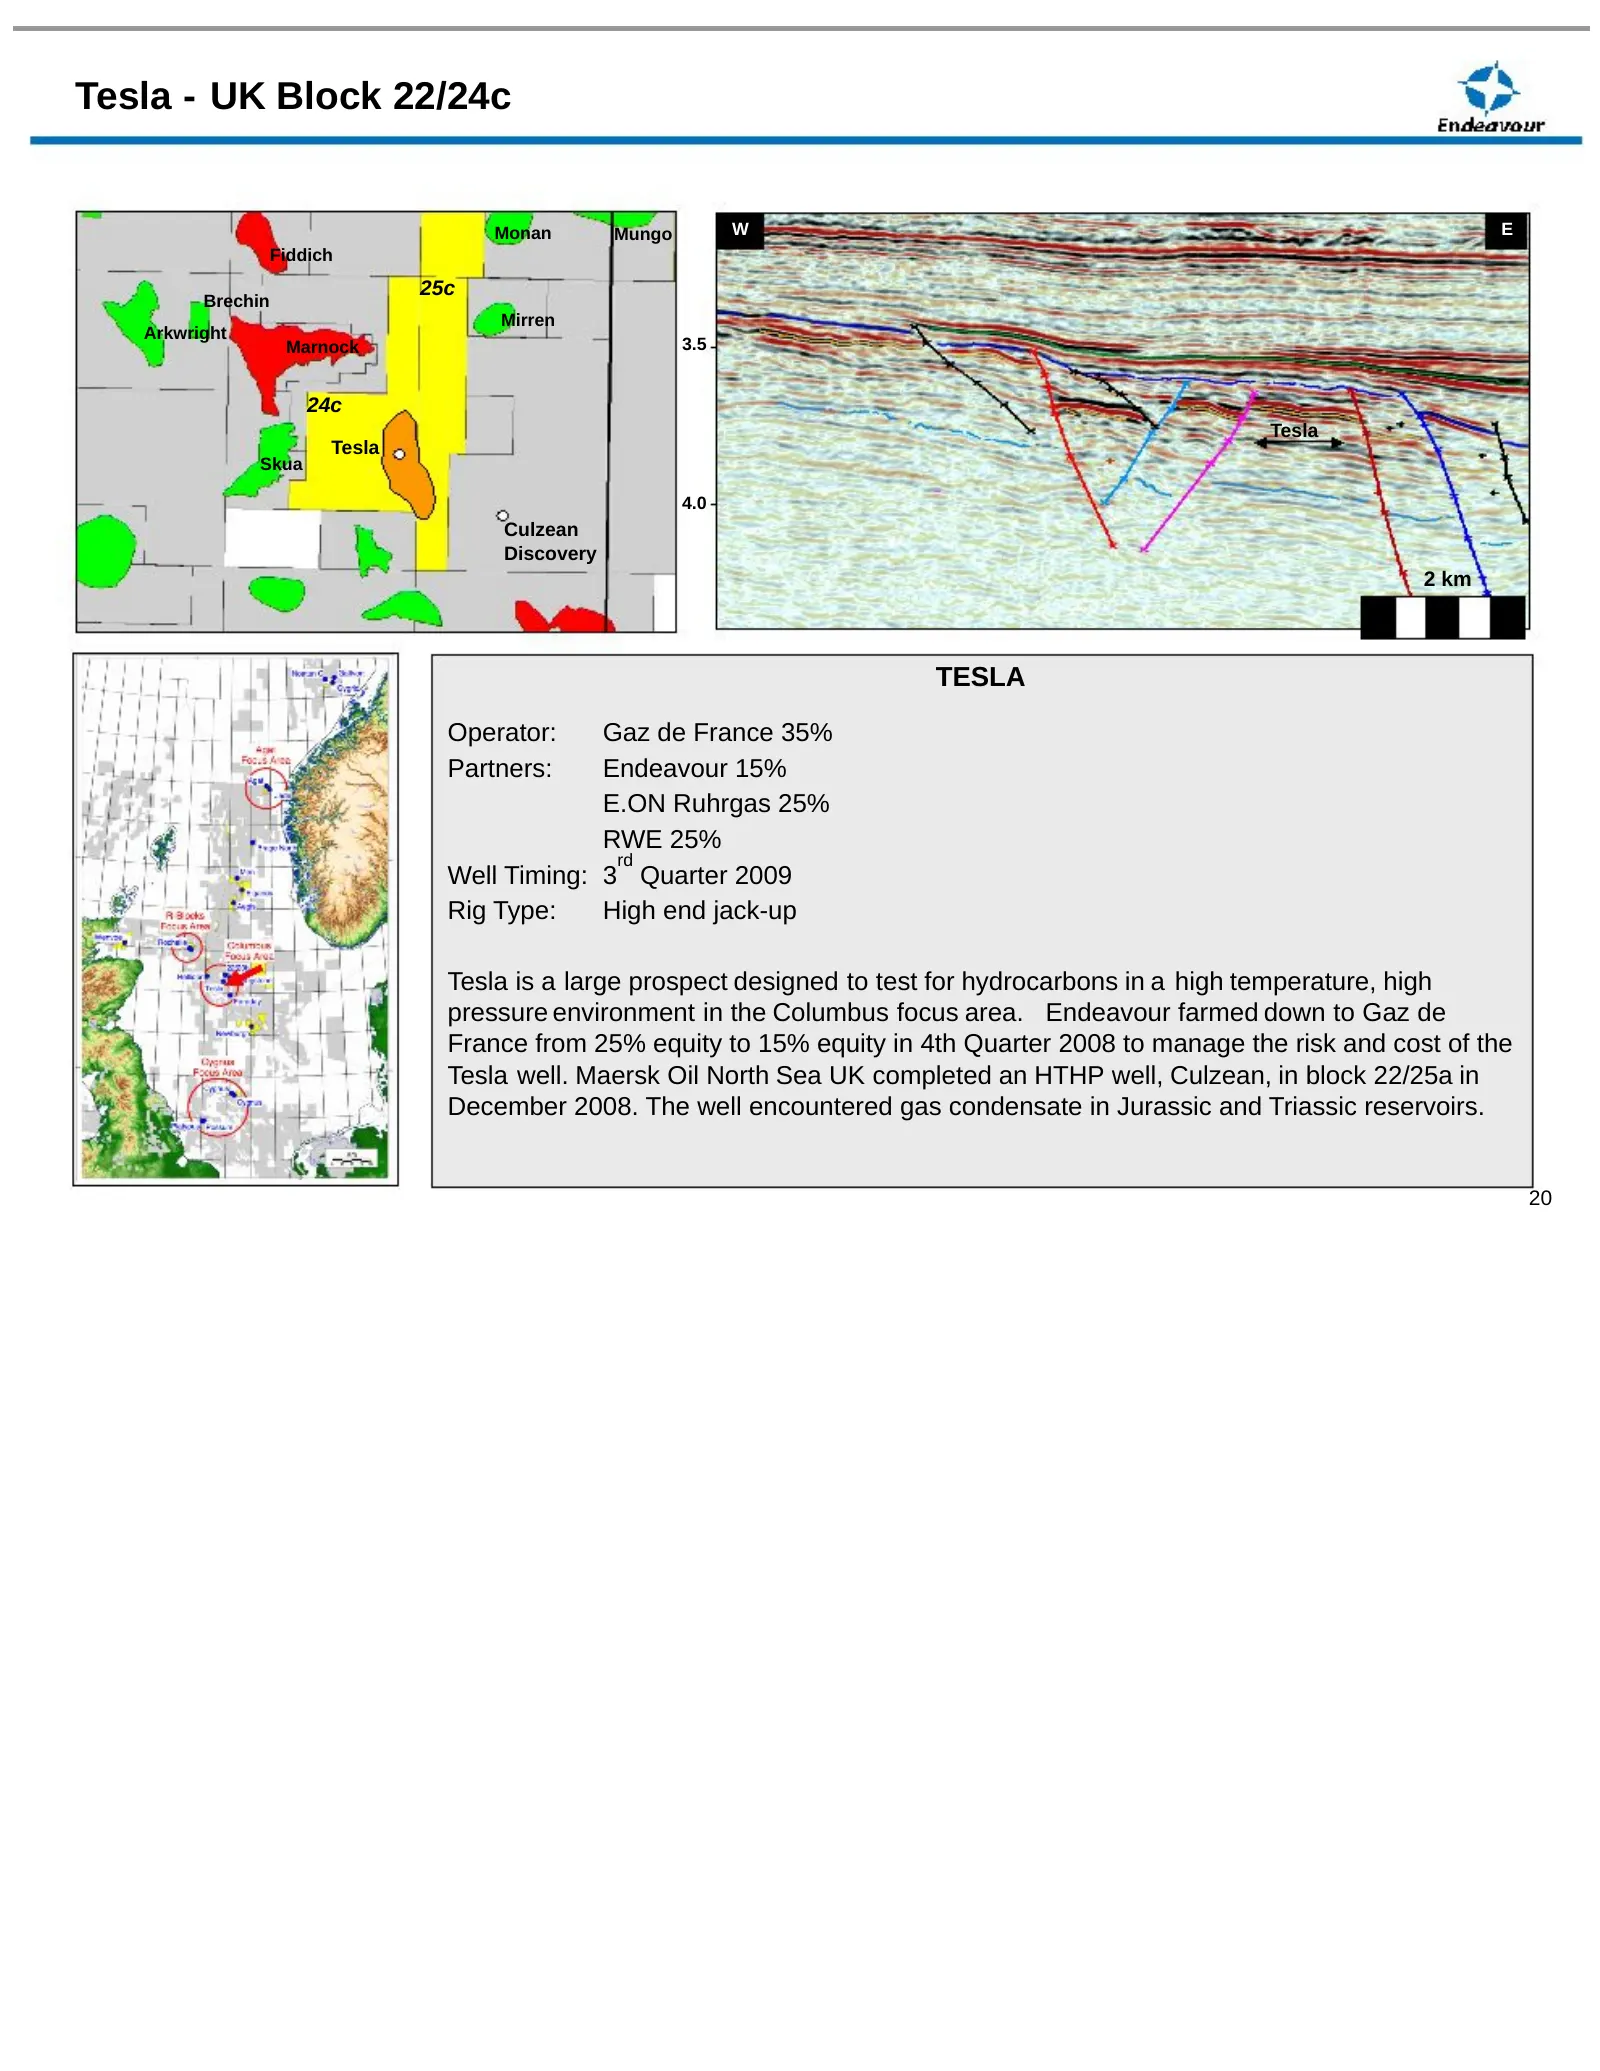
Slide 20: Tesla - UK Block 22/24c
Tesla - UK Block 22/24c Monan Mungo W E Fiddich 25c Brechin Mirren Arkwright Marnock 3.5 24c Tesla Tesla Skua 4.0 Culzean Discovery 2 km TESLA Operator: Gaz de France 35% Partners: Endeavour 15% E.ON Ruhrgas 25% RWE 25% rd Well Timing: 3 Quarter 2009 Rig Type: High end jack-up Tesla is a large prosp
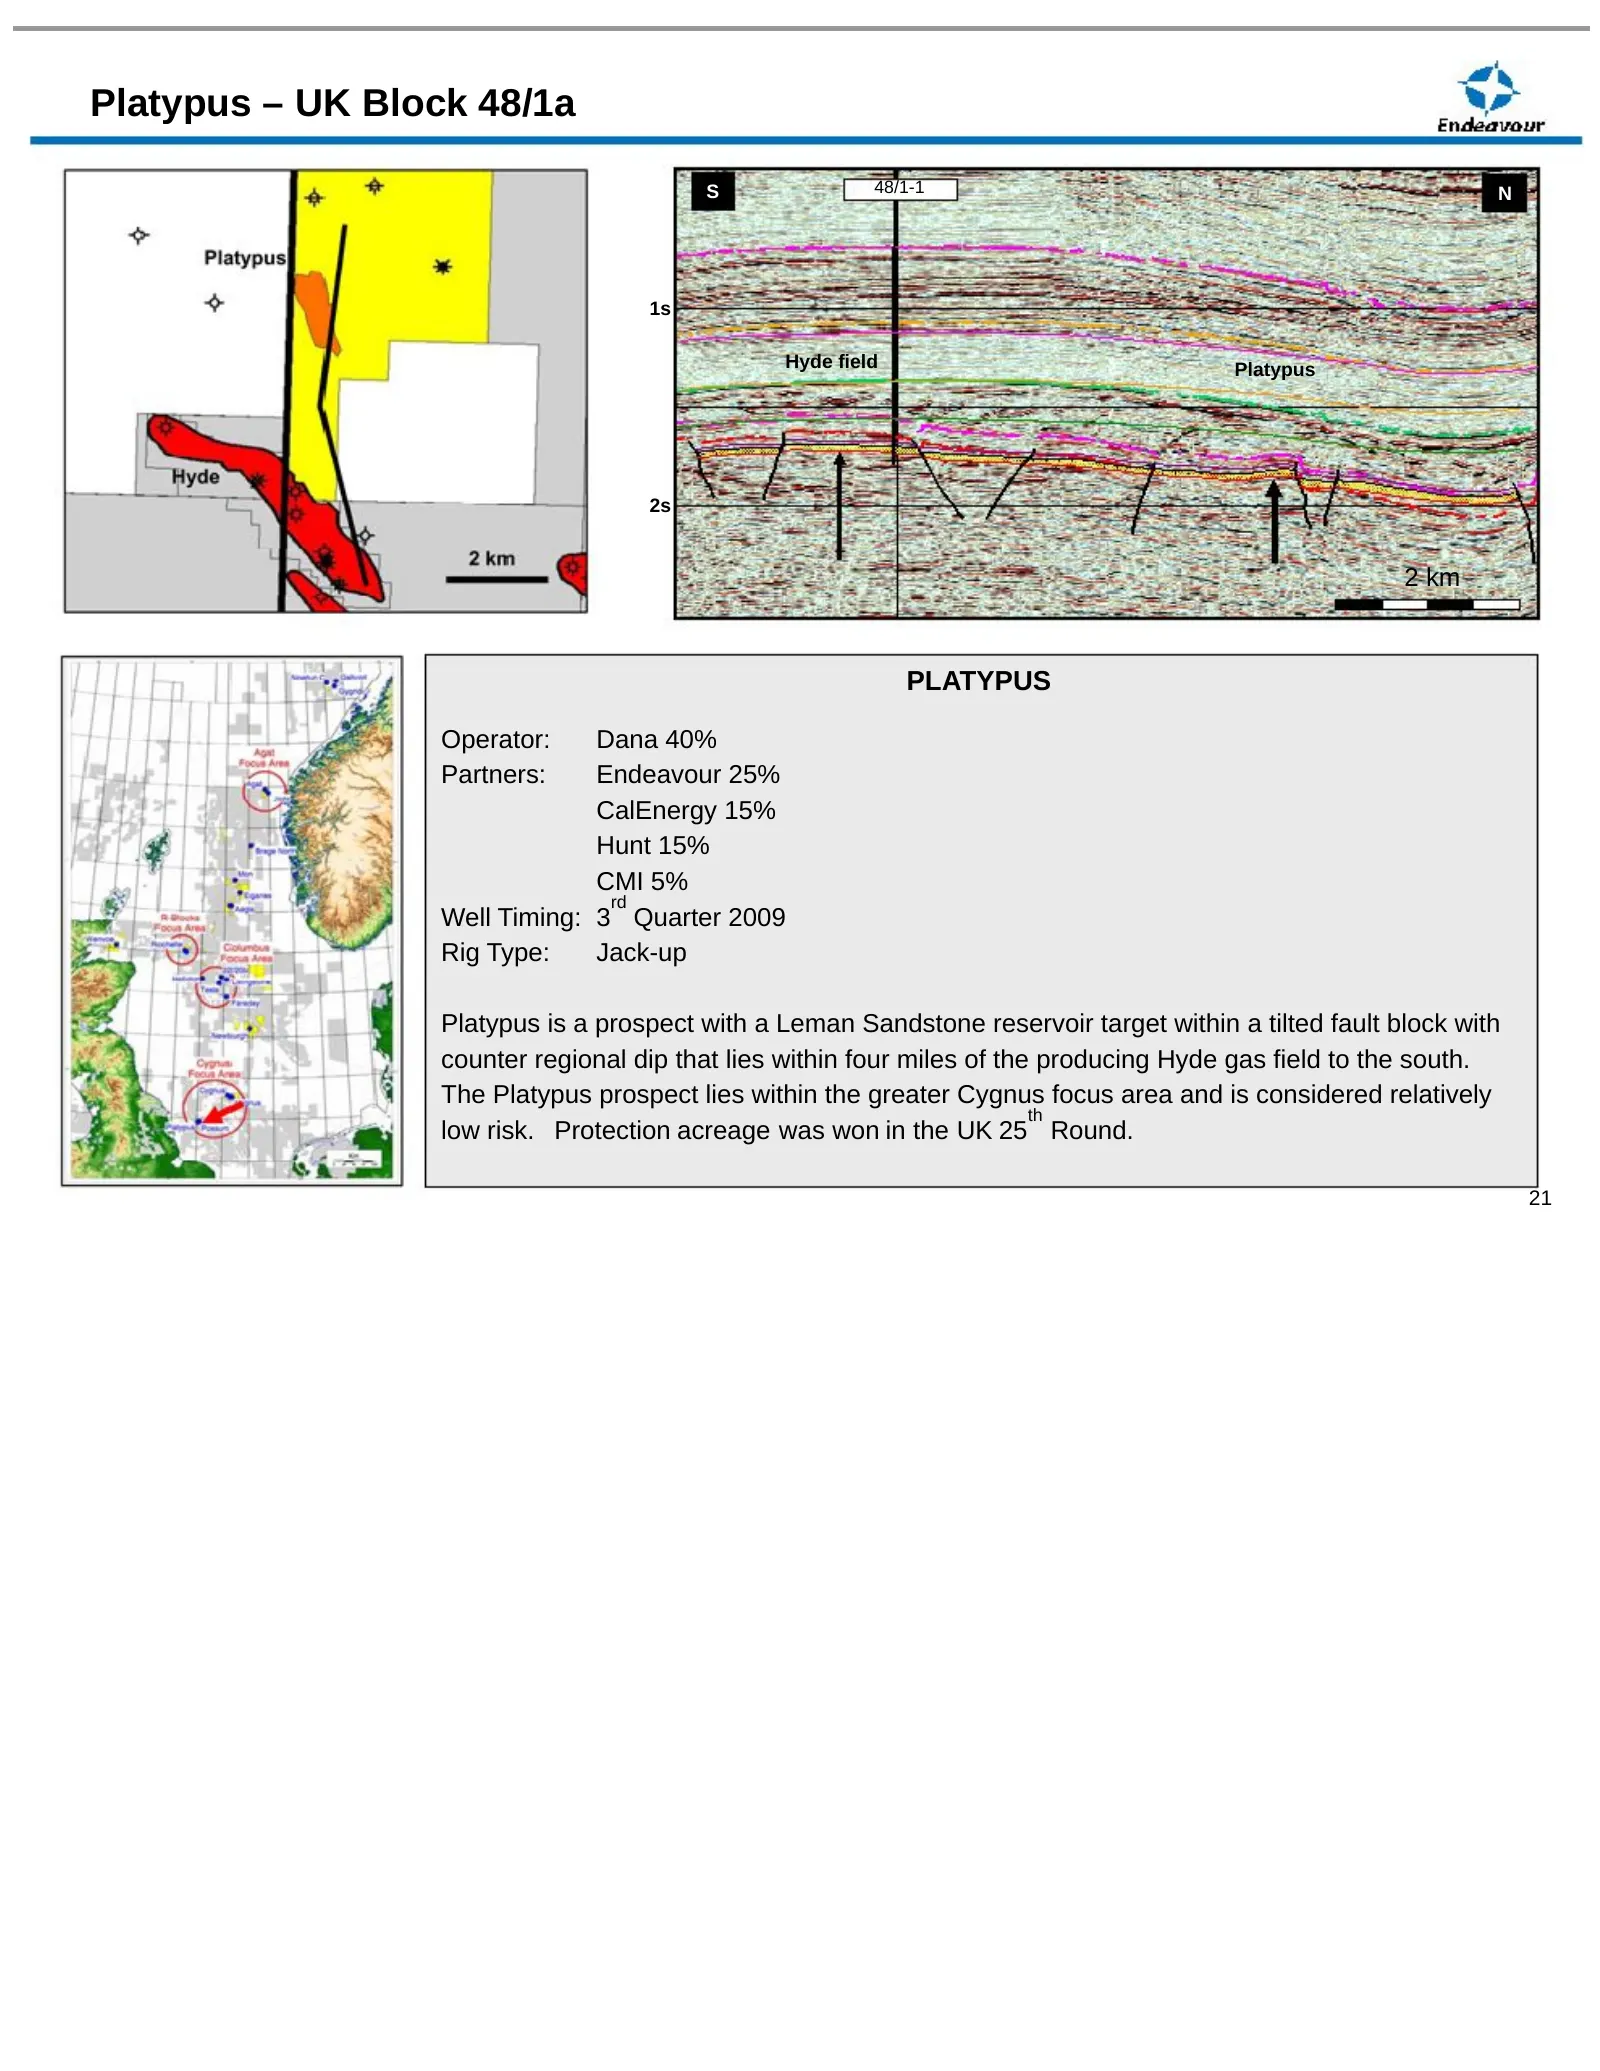
Slide 21: Platypus – UK Block 48/1a
Platypus – UK Block 48/1a S 48/1-1 N 1s Hyde field Platypus 2s 2 km PLATYPUS Operator: Dana 40% Partners: Endeavour 25% CalEnergy 15% Hunt 15% CMI 5% rd Well Timing: 3 Quarter 2009 Rig Type: Jack-up Platypus is a prospect with a Leman Sandstone reservoir target within a tilted fault block with count
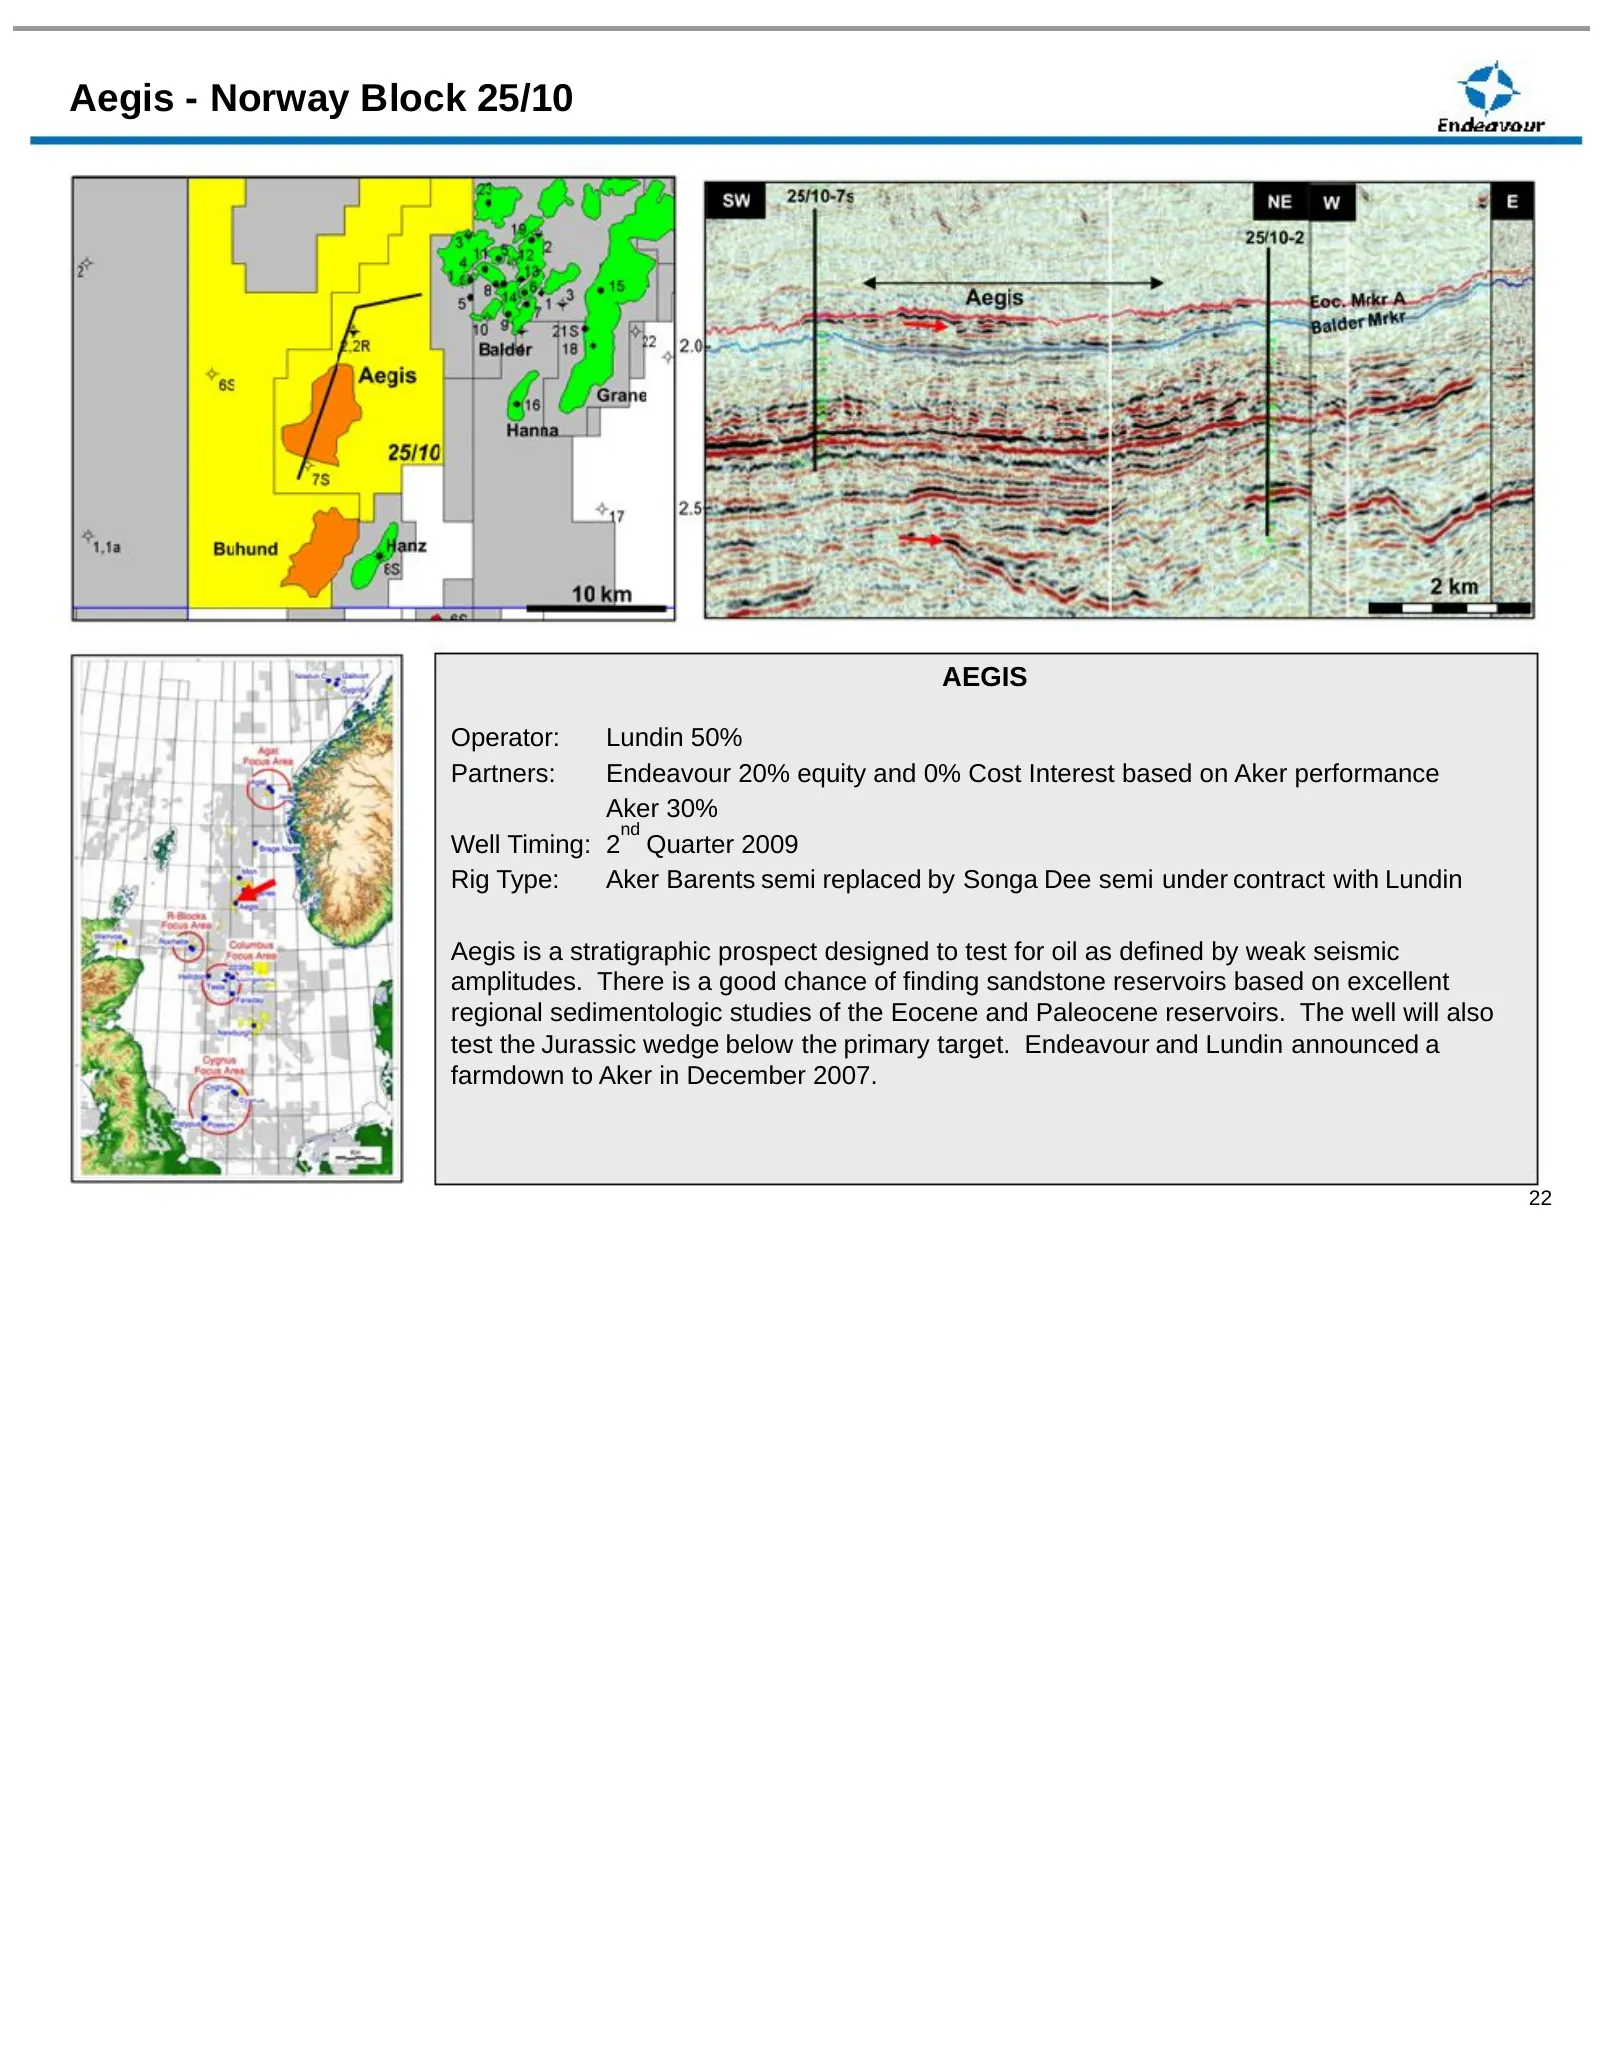
Slide 22: Aegis - Norway Block 25/10
Aegis - Norway Block 25/10 AEGIS Operator: Lundin 50% Partners: Endeavour 20% equity and 0% Cost Interest based on Aker performance Aker 30% nd Well Timing: 2 Quarter 2009 Rig Type: Aker Barents semi replaced by Songa Dee semi under contract with Lundin Aegis is a stratigraphic prospect designed to
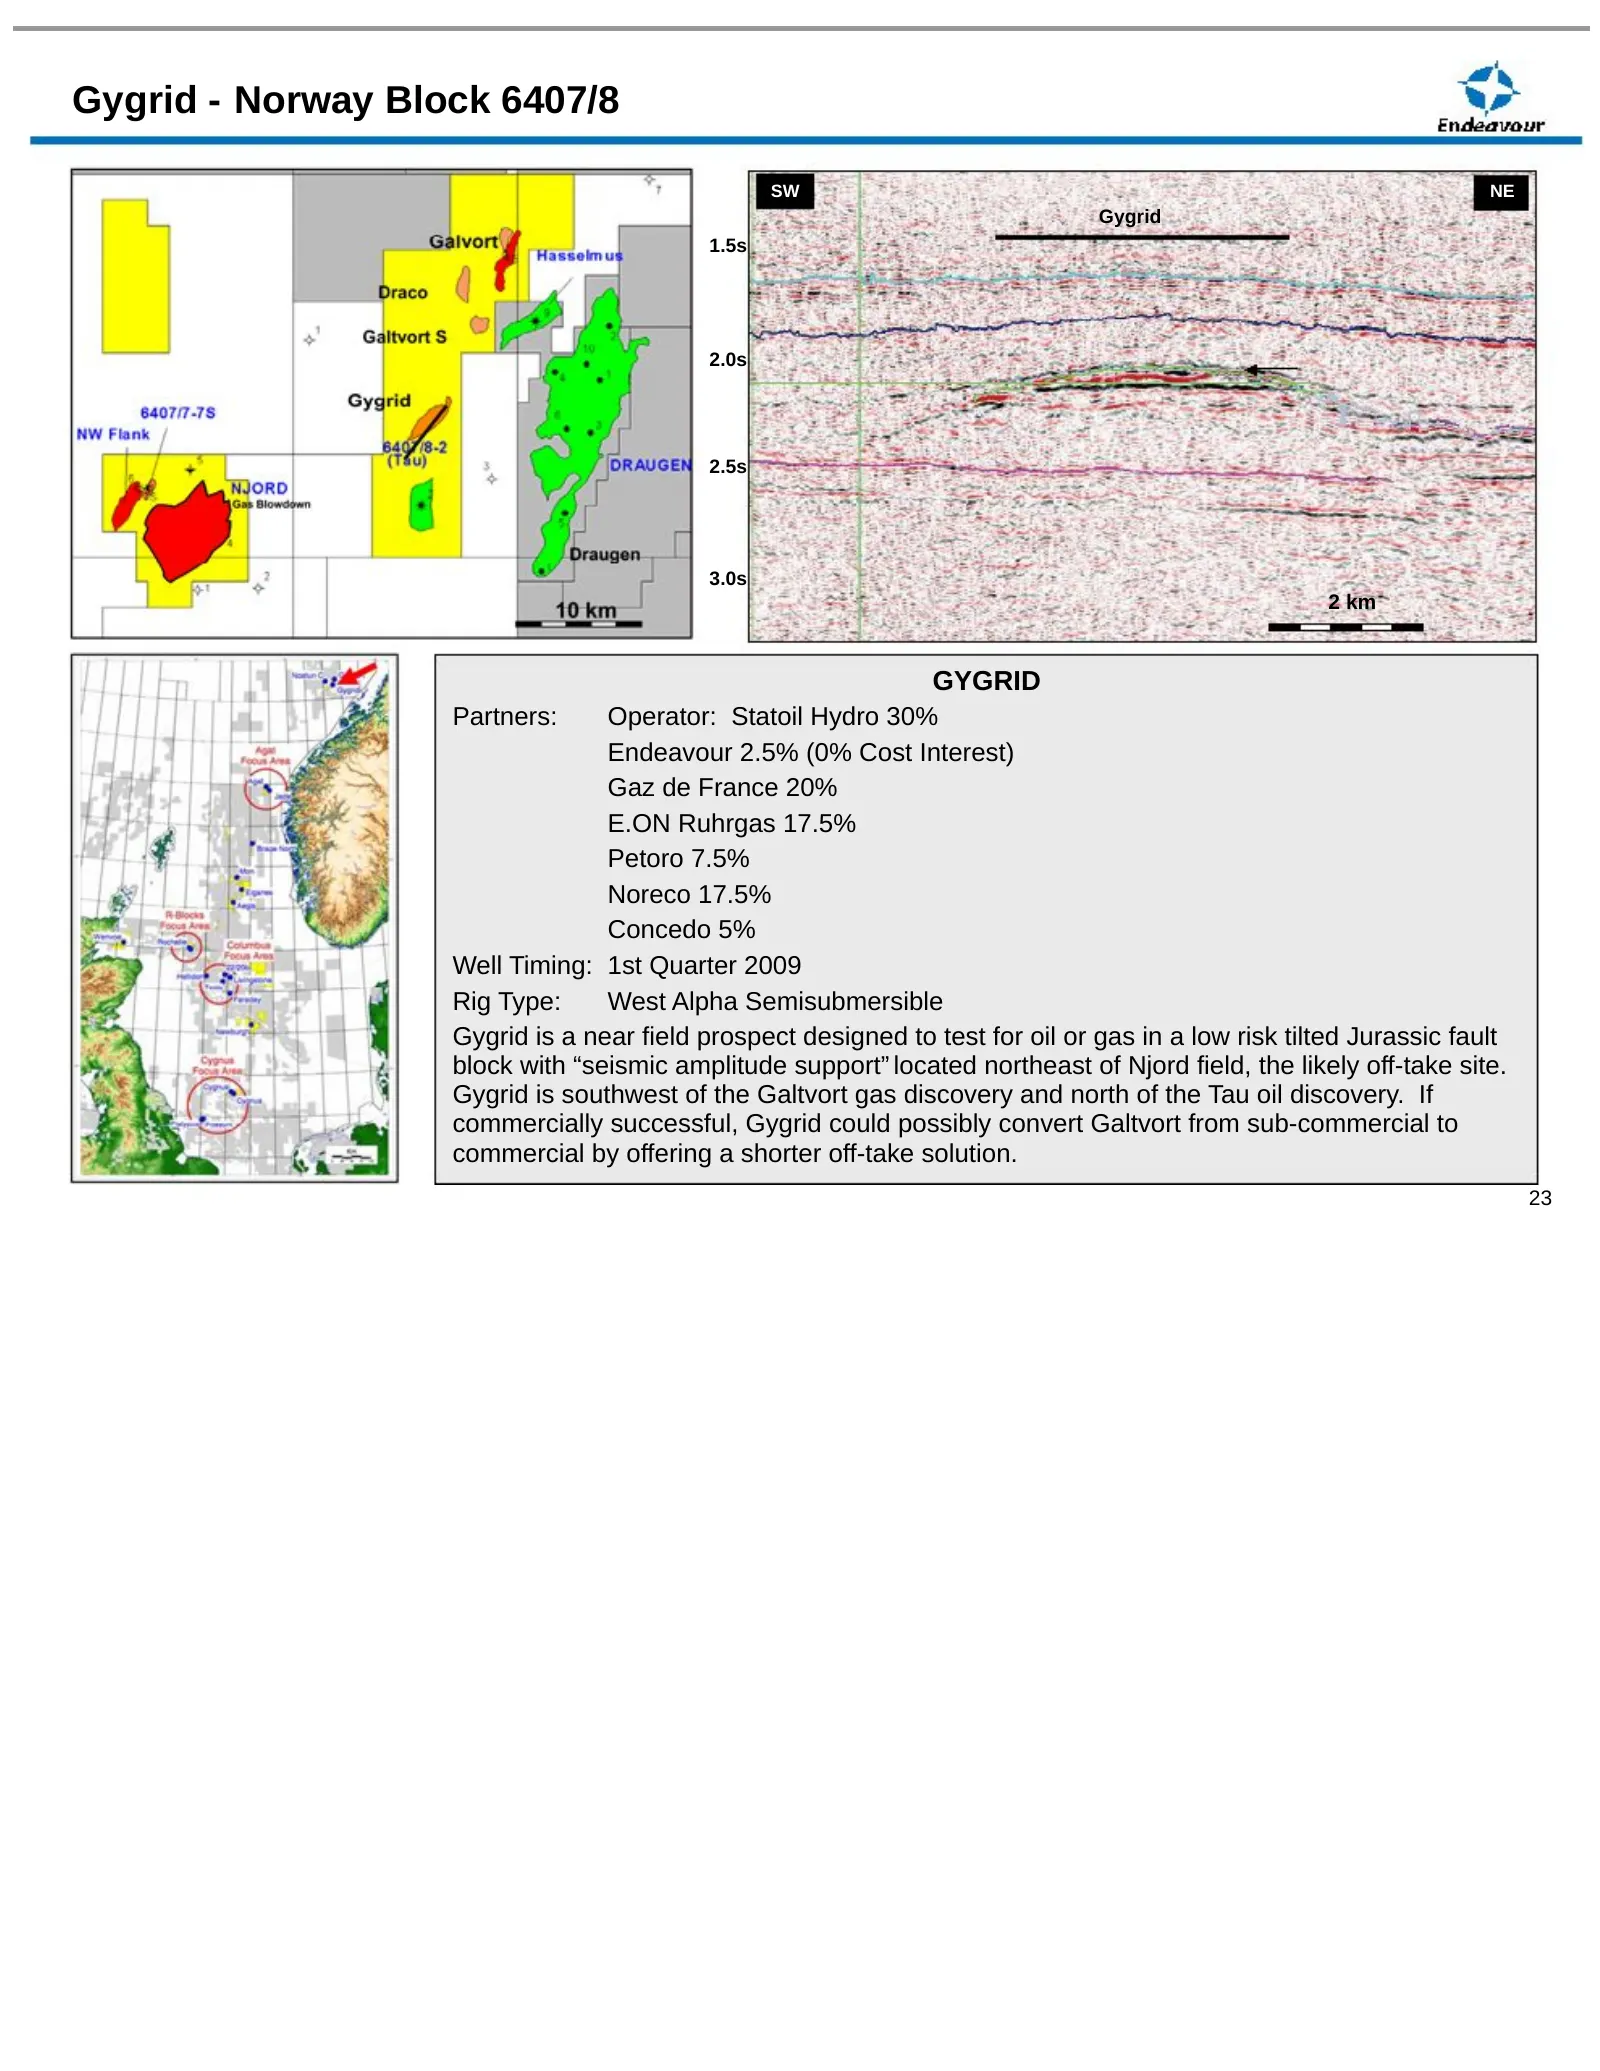
Slide 23: Gygrid - Norway Block 6407/8
Gygrid - Norway Block 6407/8 SW NE Gygrid 1.5s 2.0s 2.5s 3.0s 2 km GYGRID Partners: Operator: Statoil Hydro 30% Endeavour 2.5% (0% Cost Interest) Gaz de France 20% E.ON Ruhrgas 17.5% Petoro 7.5% Noreco 17.5% Concedo 5% Well Timing: 1st Quarter 2009 Rig Type: West Alpha Semisubmersible Gygrid is a ne
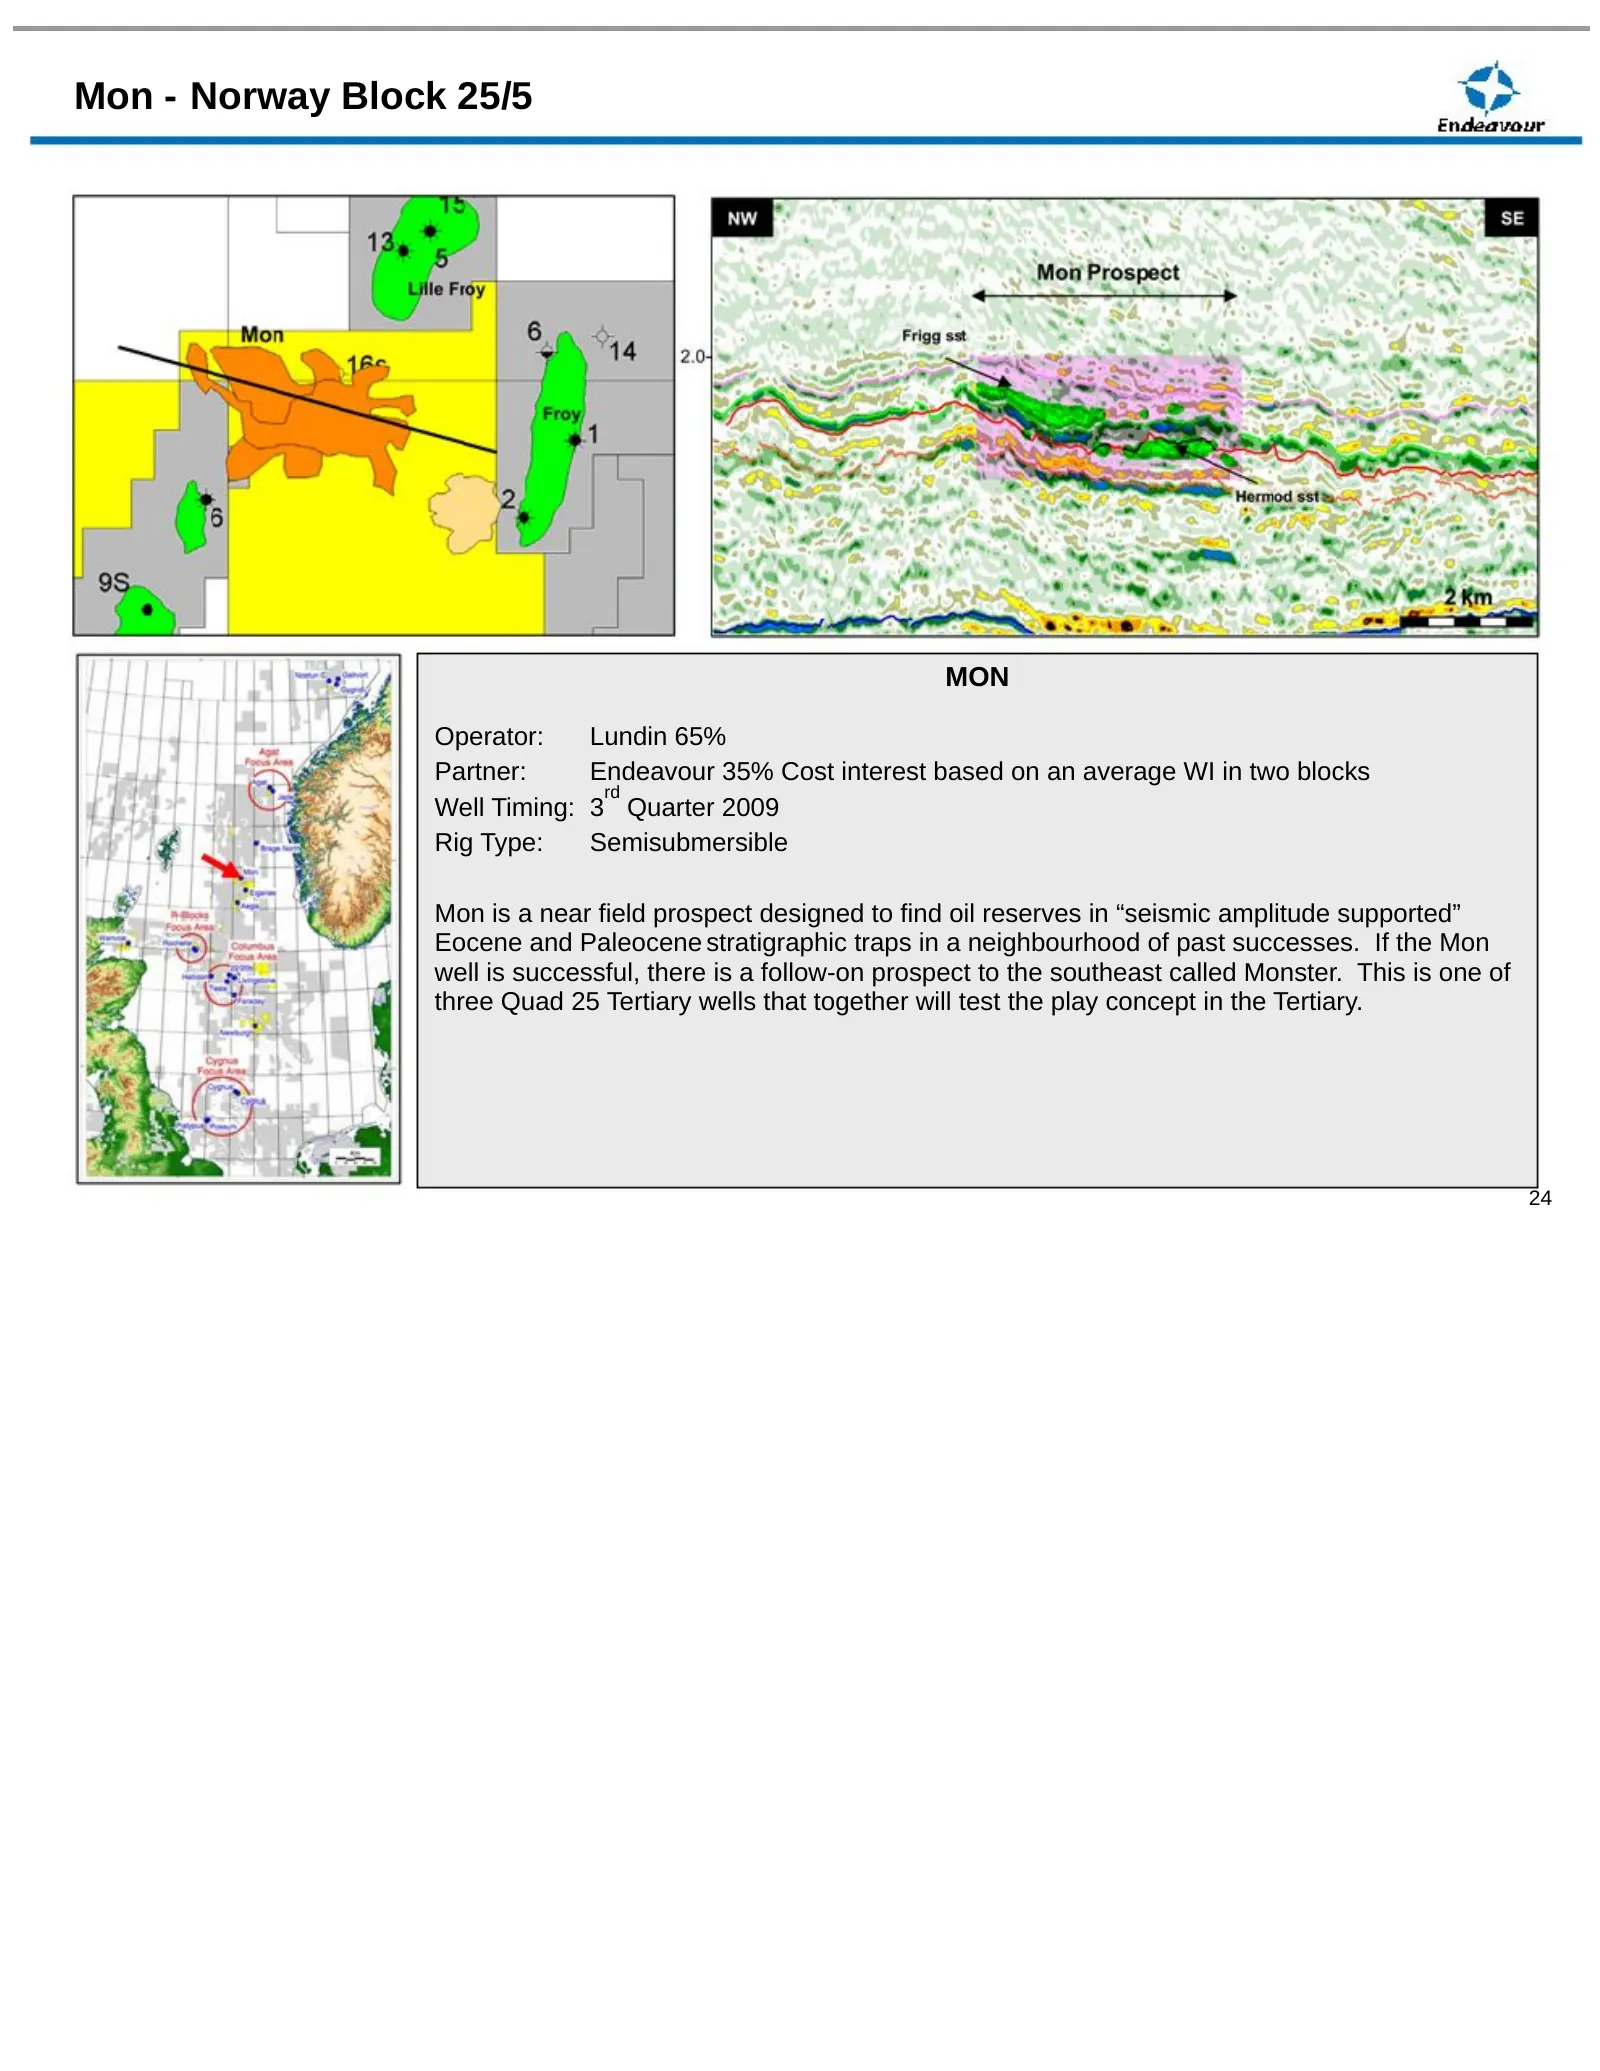
Slide 24: Mon - Norway Block 25/5
Mon - Norway Block 25/5 MON Operator: Lundin 65% Partner: Endeavour 35% Cost interest based on an average WI in two blocks rd Well Timing: 3 Quarter 2009 Rig Type: Semisubmersible Mon is a near field prospect designed to find oil reserves in “seismic amplitude supported” Eocene and Paleocene stratig
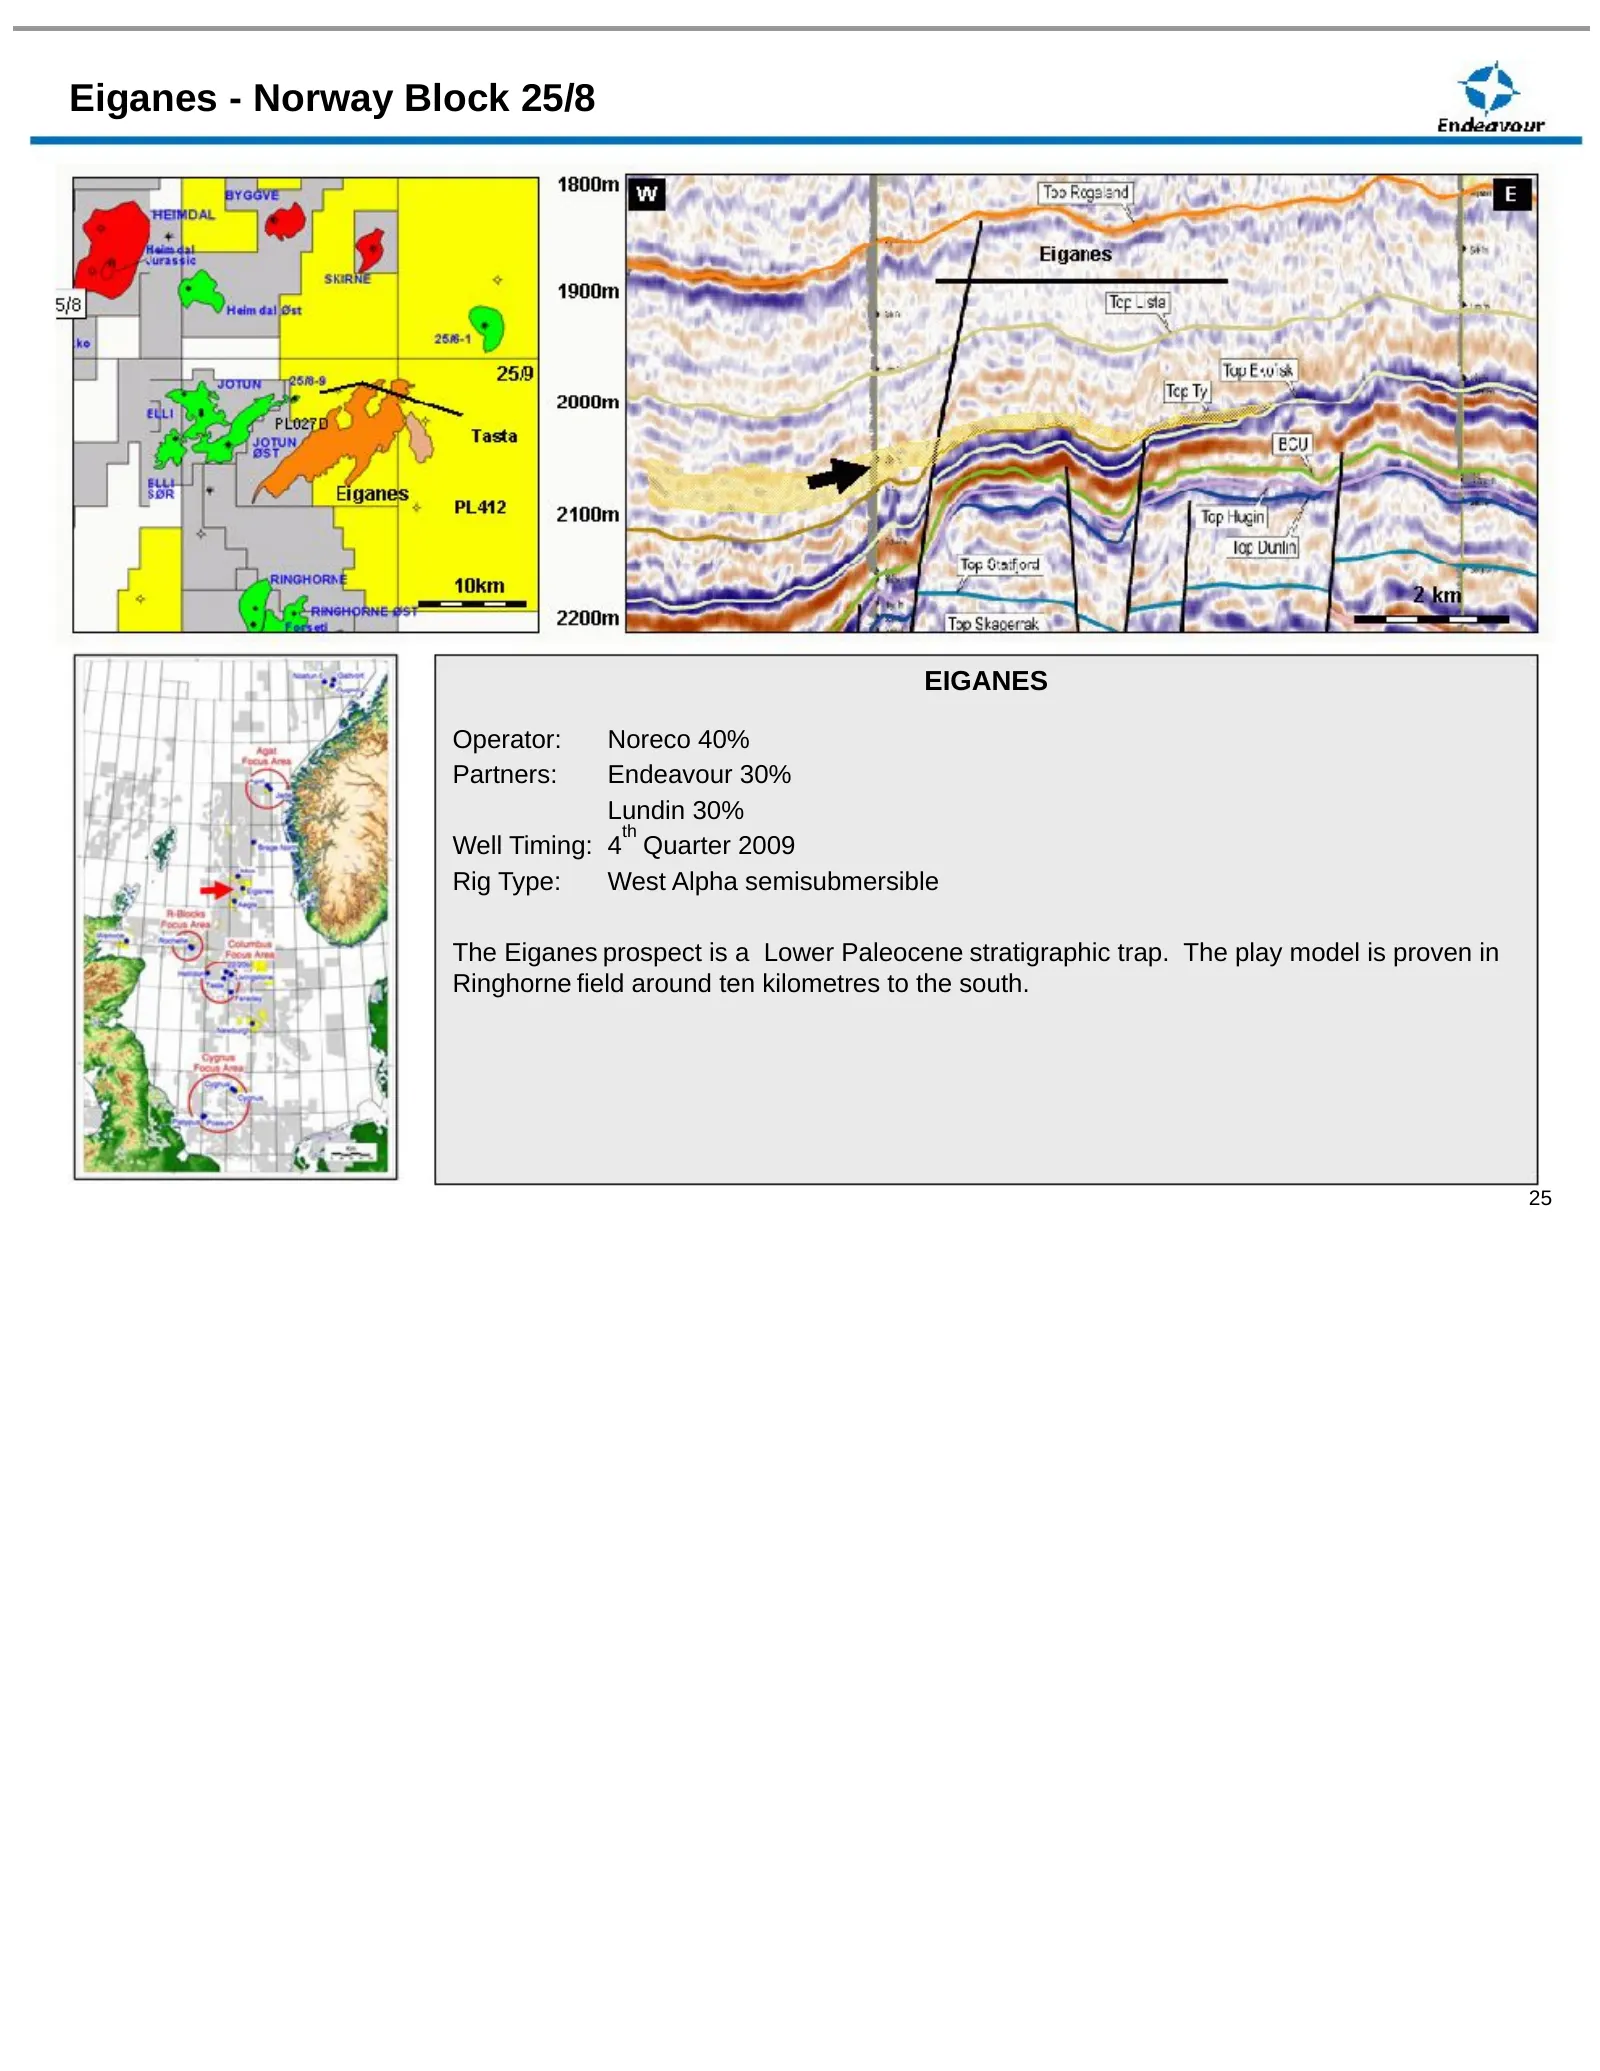
Slide 25: Eiganes - Norway Block 25/8
Eiganes - Norway Block 25/8 EIGANES Operator: Noreco 40% Partners: Endeavour 30% Lundin 30% th Well Timing: 4 Quarter 2009 Rig Type: West Alpha semisubmersible The Eiganes prospect is a Lower Paleocene stratigraphic trap. The play model is proven in Ringhorne field around ten kilometres to the south
Slide 26: Exploration Strategy
Exploration Strategy Retain high quality geoscience and reservoir engineering staff Define Focus Areas in which to explore Use Rose methodology to characterize prospects Use peer review to finalize prospect characterizations Manage global portfolio by force ranking prospects Manage risk, equity leve
Slide 27: Capital Structure
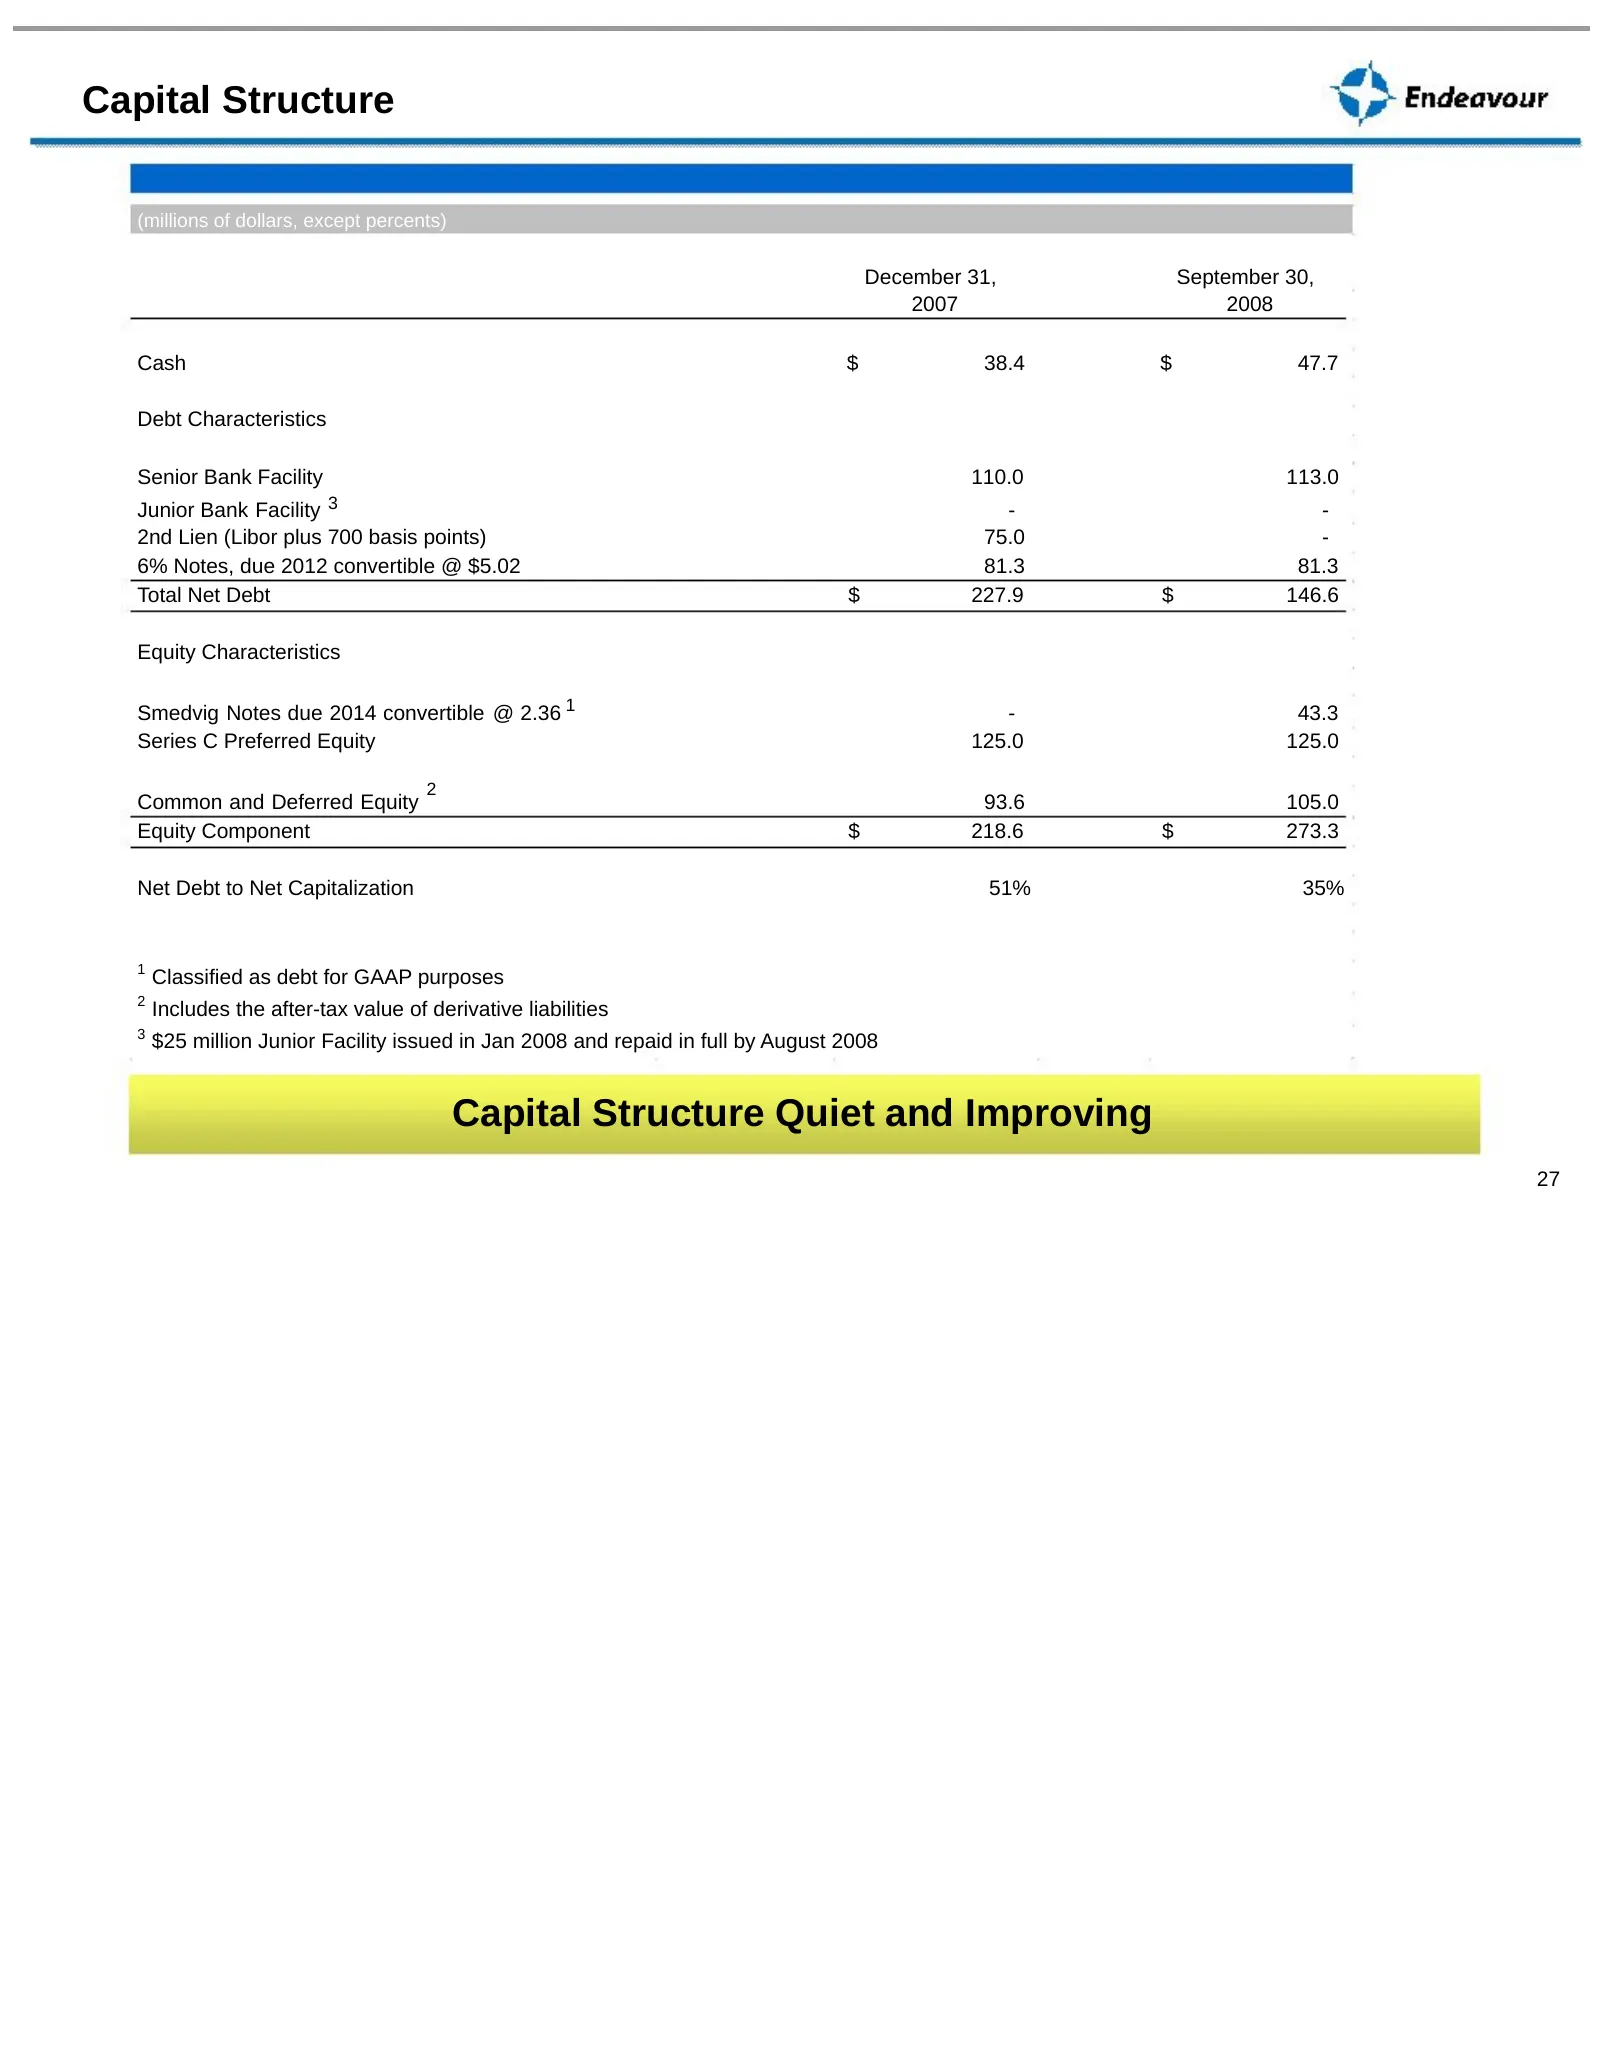
Capital Structure (millions of dollars, except percents) December 31, September 30, 2007 2008 Cash $ 38.4 $ 47.7 Debt Characteristics Senior Bank Facility 110.0 113.0 Junior Bank Facility 3 - - 2nd Lien (Libor plus 700 basis points) 75.0 - 6% Notes, due 2012 convertible @ $5.02 81.3 81.3 Total Net D
Slide 28: Acquisitions Show Excellent Returns
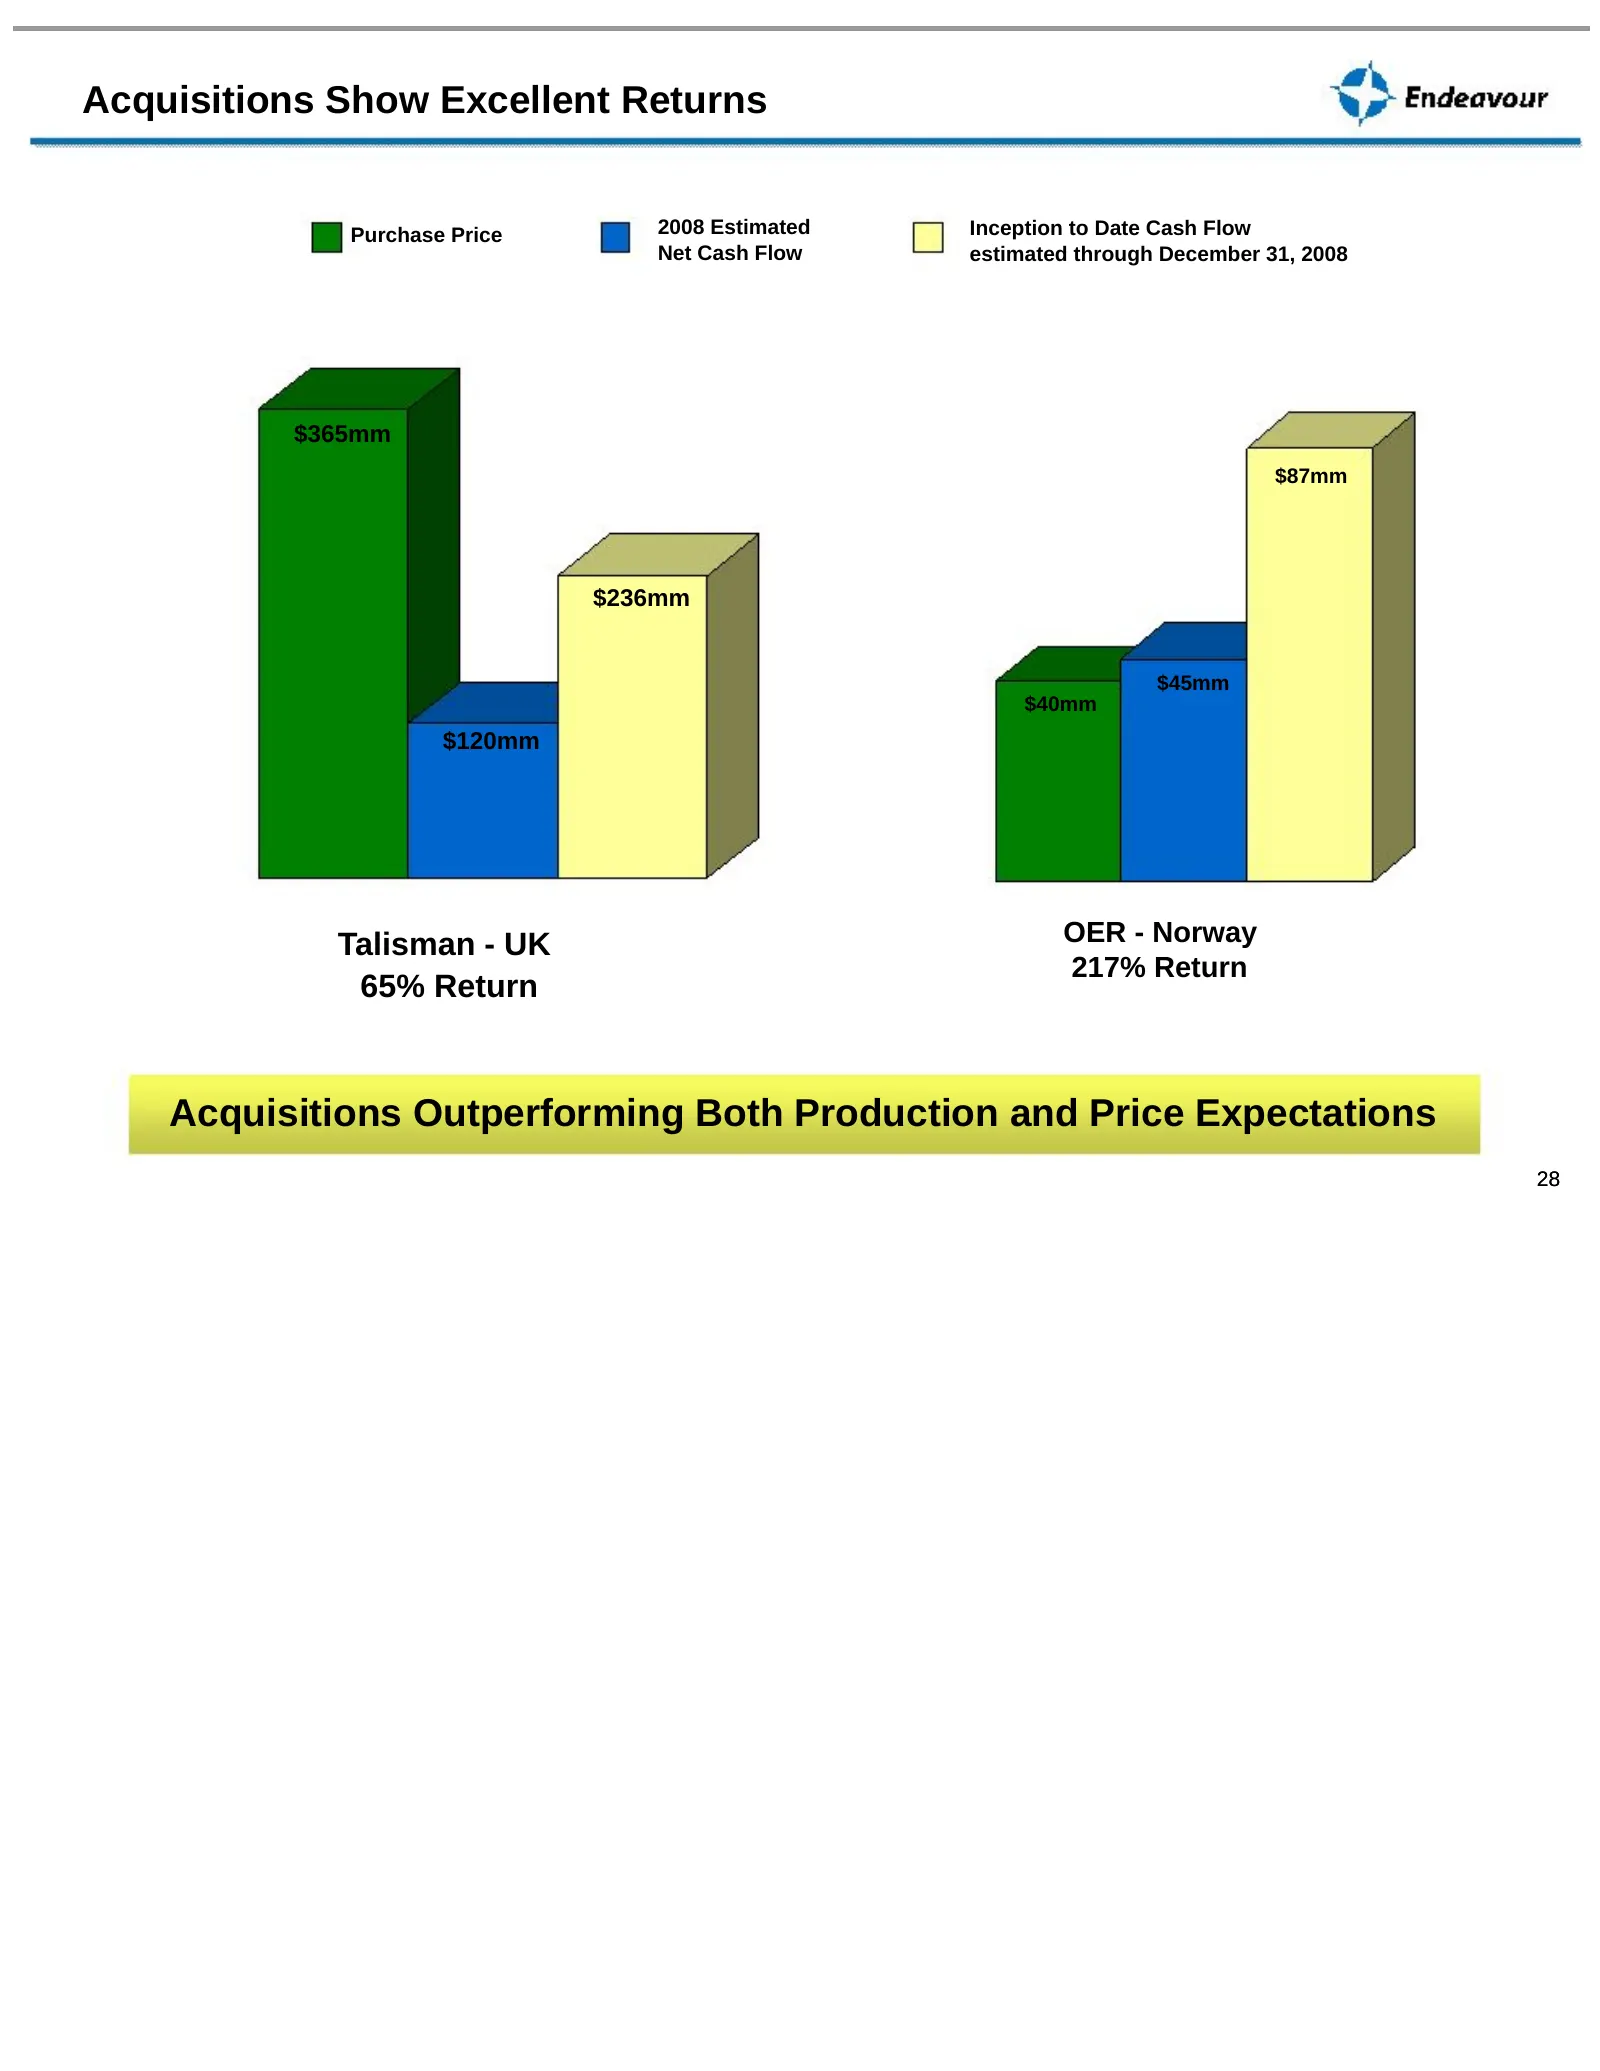
Acquisitions Show Excellent Returns Purchase Price 2008 Estimated Inception to Date Cash Flow Net Cash Flow estimated through December 31, 2008 $365mm $87mm $236mm $45mm $40mm $120mm Talisman - UK OER - Norway 217% Return 65% Return Acquisitions Outperforming Both Production and Price Expectations 2
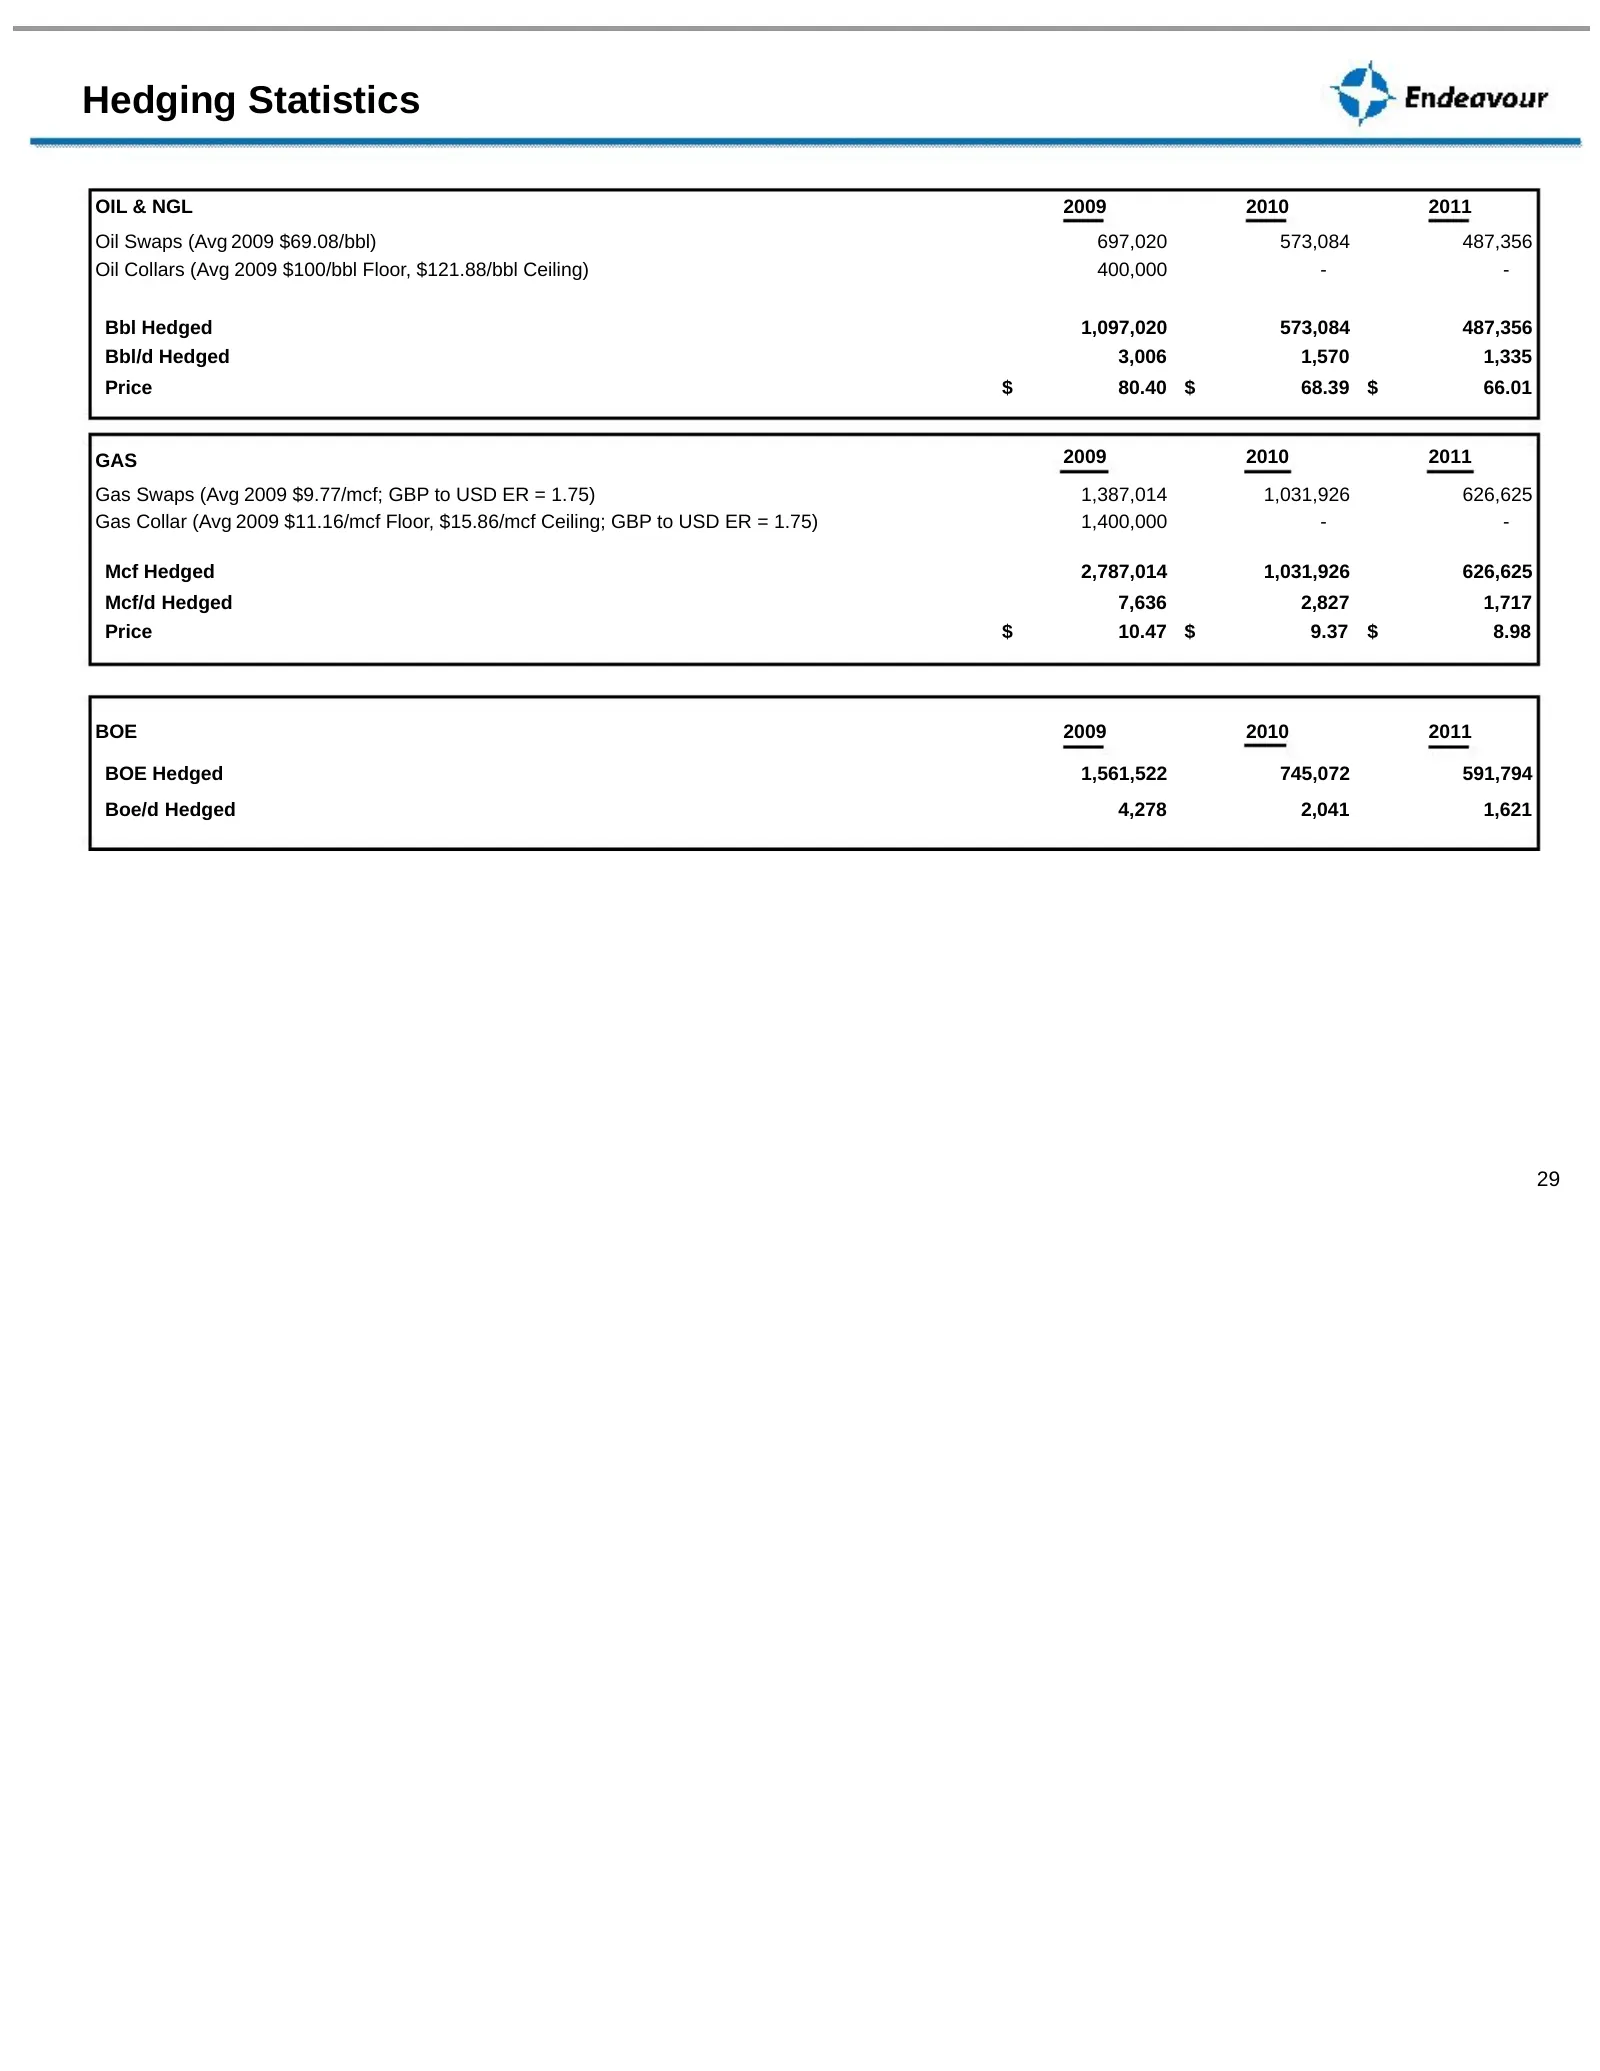
Slide 29: Hedging Statistics
Hedging Statistics OIL & NGL 2009 2010 2011 Oil Swaps (Avg 2009 $69.08/bbl) 697,020 573,084 487,356 Oil Collars (Avg 2009 $100/bbl Floor, $121.88/bbl Ceiling) 400,000 - - Bbl Hedged 1,097,020 573,084 487,356 Bbl/d Hedged 3,006 1,570 1,335 Price $ 80.40 $ 68.39 $ 66.01 GAS 2009 2010 2011 Gas Swaps (A
Slide 30: Conclusion
Conclusion Balanced strategy with experienced global team in place — North Sea and U.S. Strong continuing cash flow from existing assets — self-funding Solid and improving capital structure Multiple growth channels to organically grow company • Development and exploitation of existing assets — North
Source: SEC EDGAR · 8-K filed Feb 19, 2009
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014