Chiquita Brands International Inc
Chiquita Brands International — Merger or Acquisition (September 2014)
24 slides from Chiquita Brands International's merger presentation, Sep 2, 2014
Slide 1: Setting the Record Straight on Cutrale / Safra's Presentation
1 1 O Setting the Record Straight on Cutrale / Safra’s Presentation September 2014
Slide 2: Forward-looking statements
2 This presentation contains certain statements that are “forward - looking statements.” These statements are subject to a number of assumptions, risks and uncertainties, many of which are beyond the control of Chiquita and Fyffes plc (“Fyffes”), including: the customary risks experienced by global
Slide 3: Cutrale/Safra's Presentation to Chiquita Shareholders is Flawed and Misleading
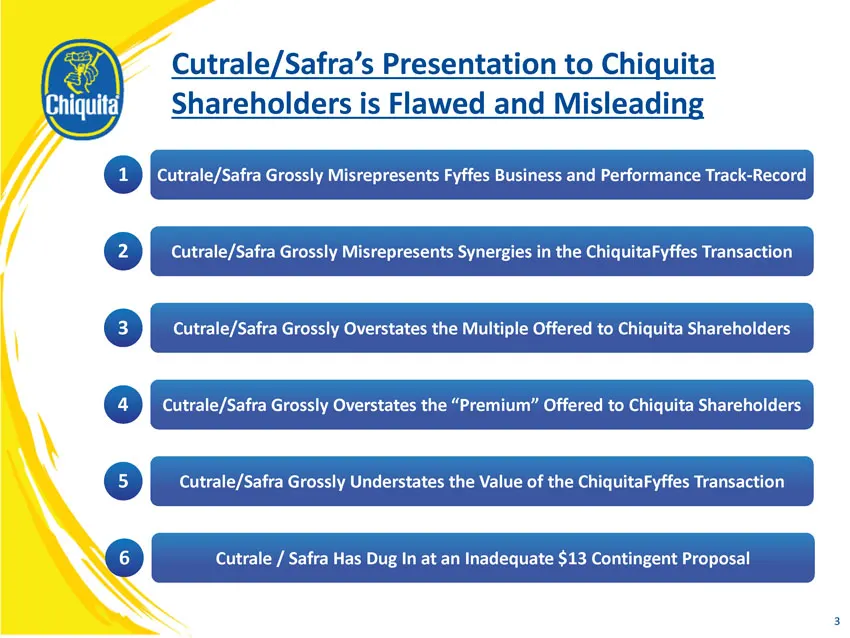
3 Cutrale/Safra’s Presentation to Chiquita Shareholders is Flawed and Misleading 1 Cutrale/Safra Grossly Misrepresents Fyffes Business and Performance Track - Record 2 Cutrale/Safra Grossly Misrepresents Synergies in the ChiquitaFyffes Transaction 3 Cutrale/Safra Grossly Overstates the Multiple Offe
Slide 4: Misrepresents Fyffes Business and Performance Track Record
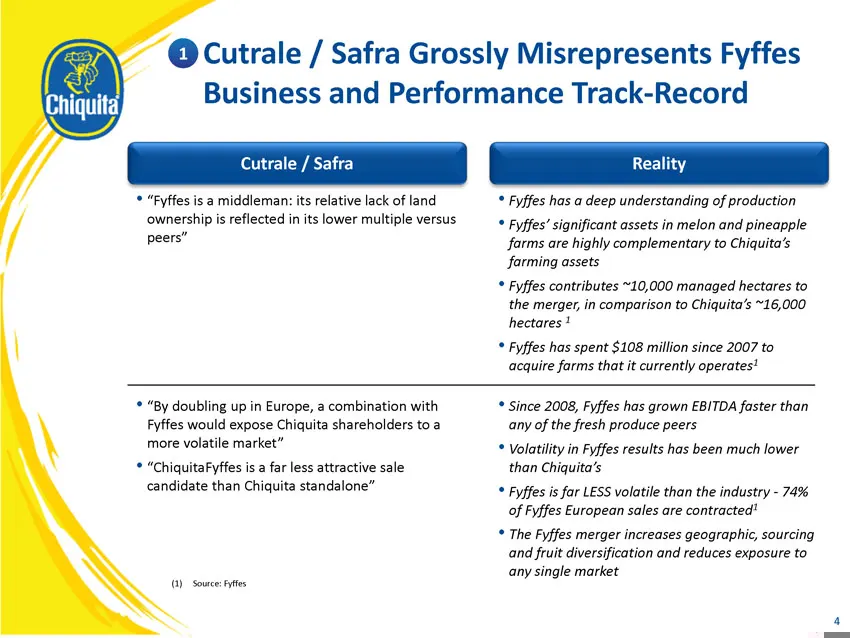
4 Cutrale / Safra Grossly Misrepresents Fyffes Business and Performance Track - Record 1 Cutrale / Safra Reality • “Fyffes is a middleman: its relative lack of land ownership is reflected in its lower multiple versus peers” • Fyffes has a deep understanding of production • Fyffes’ significant assets
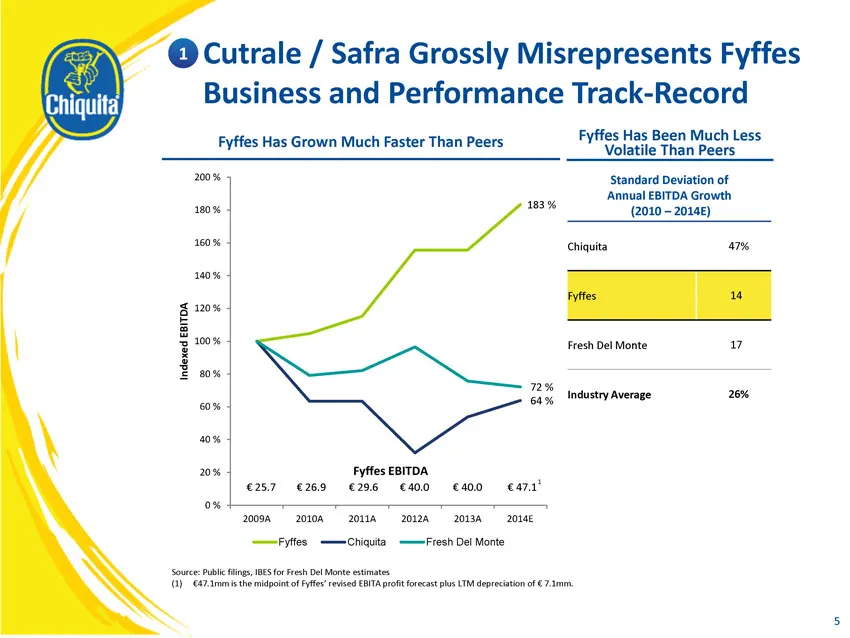
Slide 5: Fyffes Has Grown Much Faster Than Peers
Fyffes Has Grown Much Faster Than Peers Cutrale / Safra Grossly Misrepresents Fyffes Business and Performance Track - Record 1 Standard Deviation of Annual EBITDA Growth (2010 – 2014E) Chiquita 47% Fyffes 14 Fresh Del Monte 17 Industry Average 26% 5 Fyffes Has Been Much Less Volatile Than Peers Sour
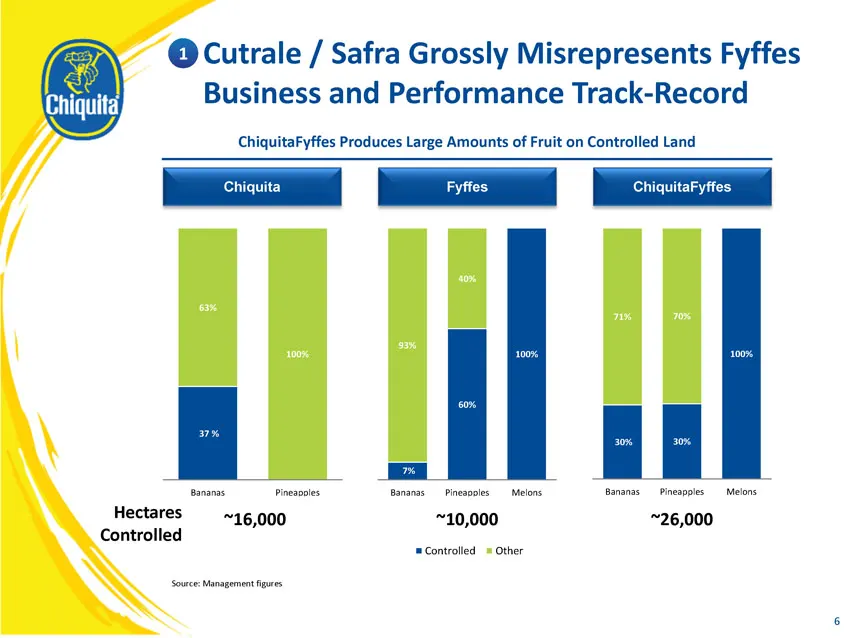
Slide 6: ChiquitaFyffes Produces Large Amounts of Fruit on Controlled Land
ChiquitaFyffes Produces Large Amounts of Fruit on Controlled Land Chiquita Fyffes ChiquitaFyffes Cutrale / Safra Grossly Misrepresents Fyffes Business and Performance Track - Record 1 ~16,000 ~26,000 ~10,000 Hectares Controlled 6 Source: Management figures 37 % 63% 100% Bananas Pineapples 30% 30% 10
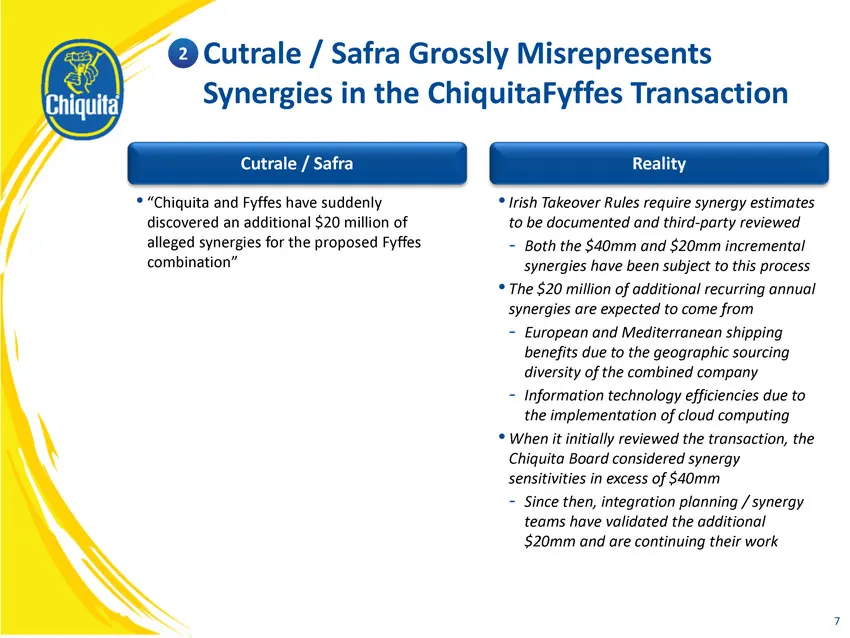
Slide 7: Misrepresents Synergies in the ChiquitaFyffes Transaction
7 Cutrale / Safra Grossly Misrepresents Synergies in the ChiquitaFyffes Transaction 2 Cutrale / Safra Reality • “Chiquita and Fyffes have suddenly discovered an additional $20 million of alleged synergies for the proposed Fyffes combination” • Irish Takeover Rules require synergy estimates to be doc
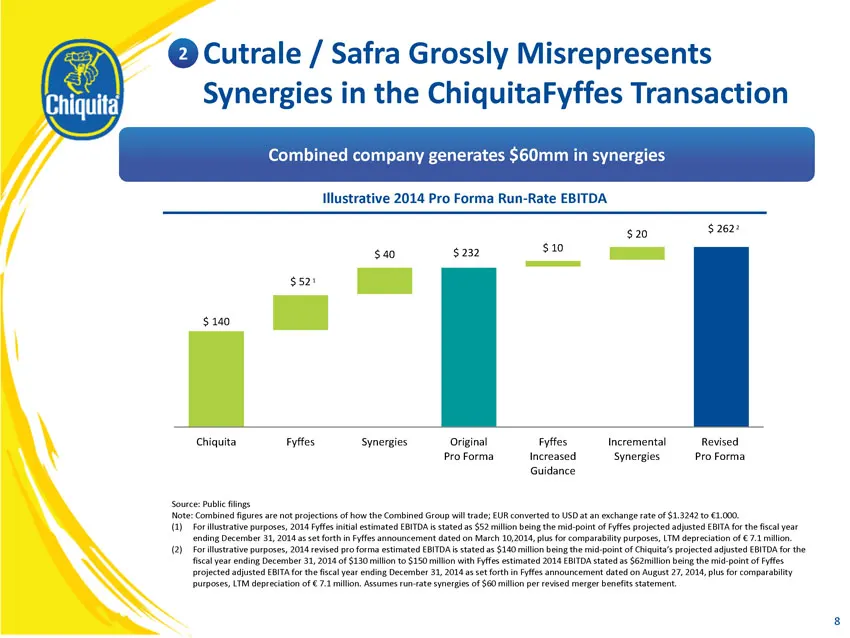
Slide 8: Combined EBITDA and synergies illustrative figures
8 Source: Public filings Note : Combined figures are not projections of how the Combined Group will trade ; EUR converted to USD at an exchange rate of $1.3242 to € 1.000. (1) For illustrative purposes, 2014 Fyffes initial estimated EBITDA is stated as $52 million being the mid - point of Fyffes pro
Slide 9: Overstates the Transaction Multiple Offered to Shareholders
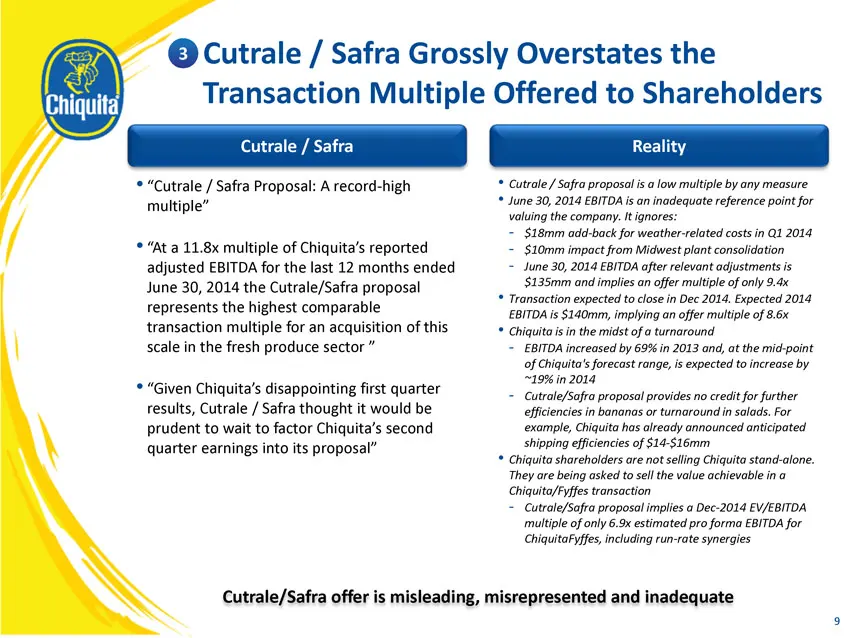
9 Cutrale / Safra Grossly Overstates the Transaction Multiple Offered to Shareholders 3 Cutrale / Safra Reality • “Cutrale / Safra Proposal : A record - high multiple ” • “At a 11.8x multiple of Chiquita’s reported adjusted EBITDA for the last 12 months ended June 30, 2014 the Cutrale/Safra proposal
Slide 10: Underlying EBITDA: Overstates the Transaction Multiple
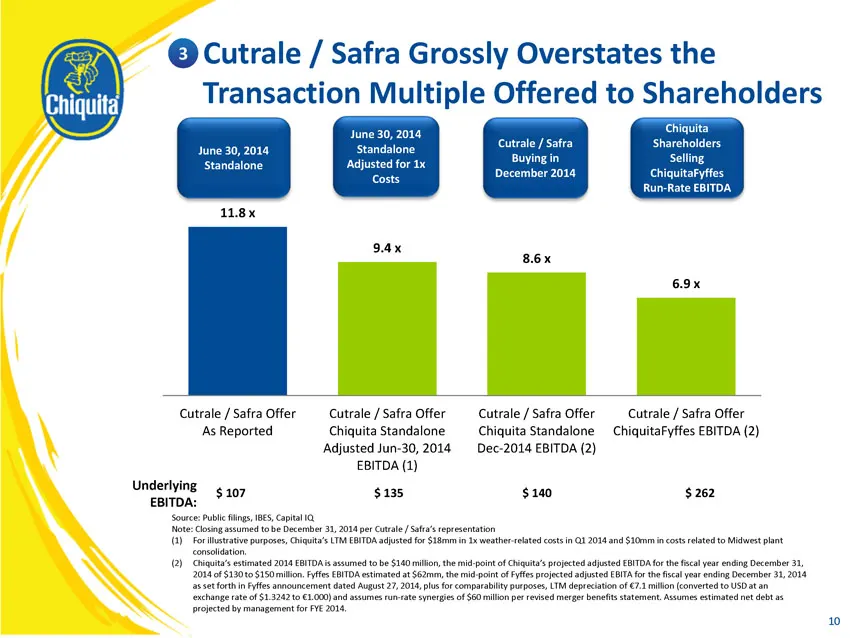
10 June 30, 2014 Standalone Cutrale / Safra Buying in December 2014 Chiquita Shareholders Selling ChiquitaFyffes Run - Rate EBITDA Underlying EBITDA: Cutrale / Safra Grossly Overstates the Transaction Multiple Offered to Shareholders 3 June 30, 2014 Standalone Adjusted for 1x Costs Source: Public fi
Slide 11: Chiquita shareholders are asked to abandon merger for low multiple
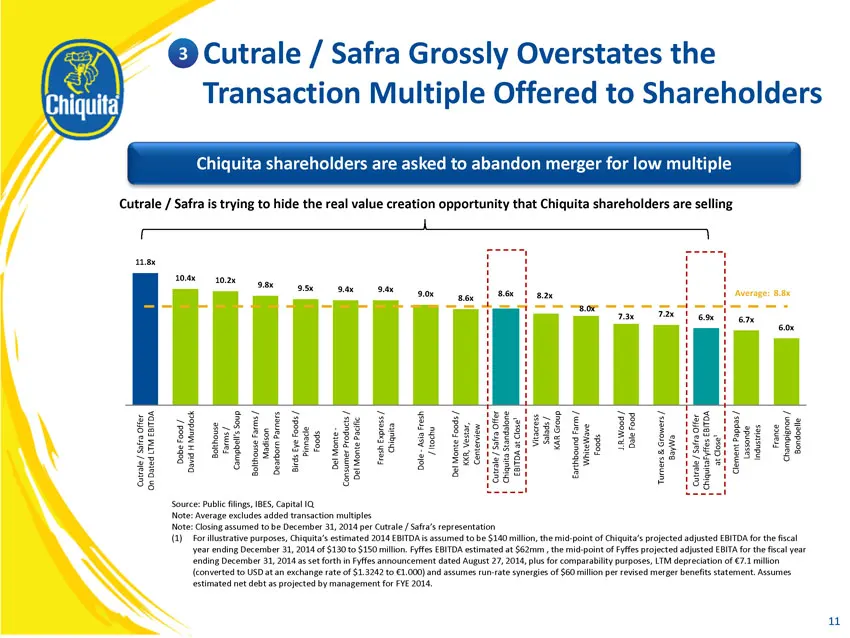
11 Cutrale / Safra is trying to hide the real value creation opportunity that C hiquita shareholders are selling Chiquita shareholders are asked to abandon merger for low multiple 11.8x 10.4x 10.2x 9.8x 9.5x 9.4x 9.4x 9.0x 8.6x 8.6x 8.2x 8.0x 7.3x 7.2x 6.9x 6.7x 6.0x Cutrale / Safra Offer On Dated L
Slide 12: Overstates the Premium Offered to Chiquita Shareholders
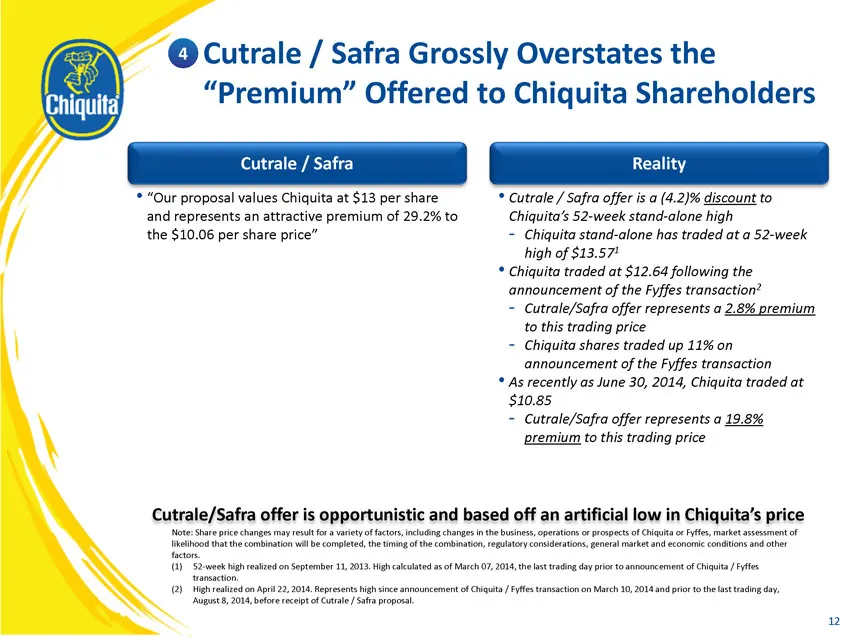
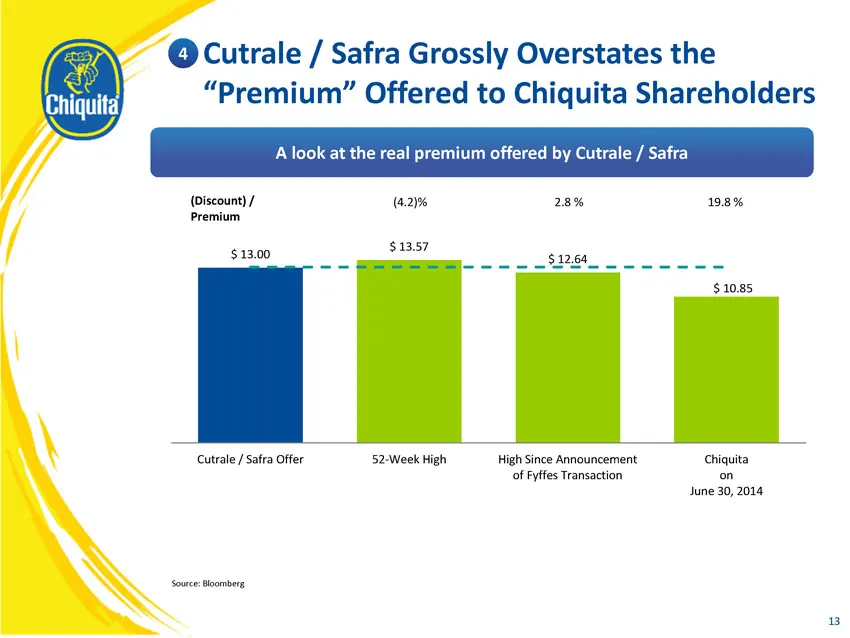
12 Cutrale / Safra Grossly Overstates the “Premium” Offered to Chiquita Shareholders 4 Cutrale / Safra Reality • “Our proposal values Chiquita at $13 per share and represents an attractive premium of 29.2% to the $10.06 per share price” • Cutrale / Safra offer is a (4.2)% discount to Chiquita’s 52 -
Slide 13: A look at the real premium offered by Cutrale / Safra
13 Cutrale / Safra Grossly Overstates the “Premium” Offered to Chiquita Shareholders 4 A look at the real premium offered by Cutrale / Safra $ 13.00 $ 13.57 $ 12.64 $ 10.85 Cutrale / Safra Offer 52-Week High High Since Announcement of Fyffes Transaction Chiquita on June 30, 2014 (4.2)% (Discount) /
Slide 14: The 5/10/15% EBITDA growth is not founded
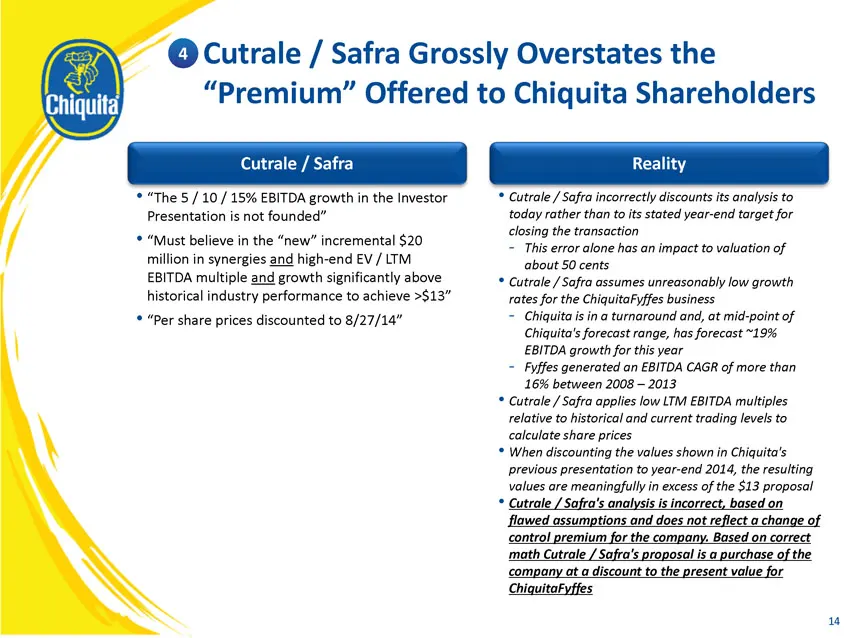
14 Cutrale / Safra Grossly Overstates the “Premium” Offered to Chiquita Shareholders 4 Cutrale / Safra Reality • “The 5 / 10 / 15% EBITDA growth in the Investor Presentation is not founded” • “Must believe in the “new” incremental $20 million in synergies and high - end EV / LTM EBITDA multiple and
Slide 15: Analysis incorrectly discounts future values to today
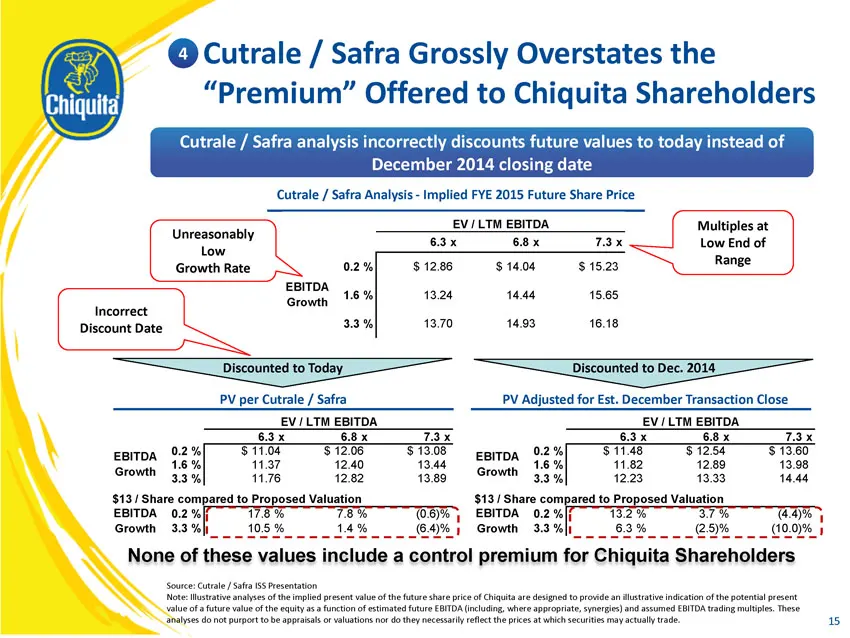
15 Cutrale / Safra Grossly Overstates the “Premium” Offered to Chiquita Shareholders 4 Cutrale / Safra analysis incorrectly discounts future values to today instead of December 2014 closing date Cutrale / Safra Analysis - Implied FYE 2015 Future Share Price Discounted to Dec. 2014 None of these valu
Slide 16: Cutrale / Safra Assumes 0.3% EBITDA Growth for Chiquita
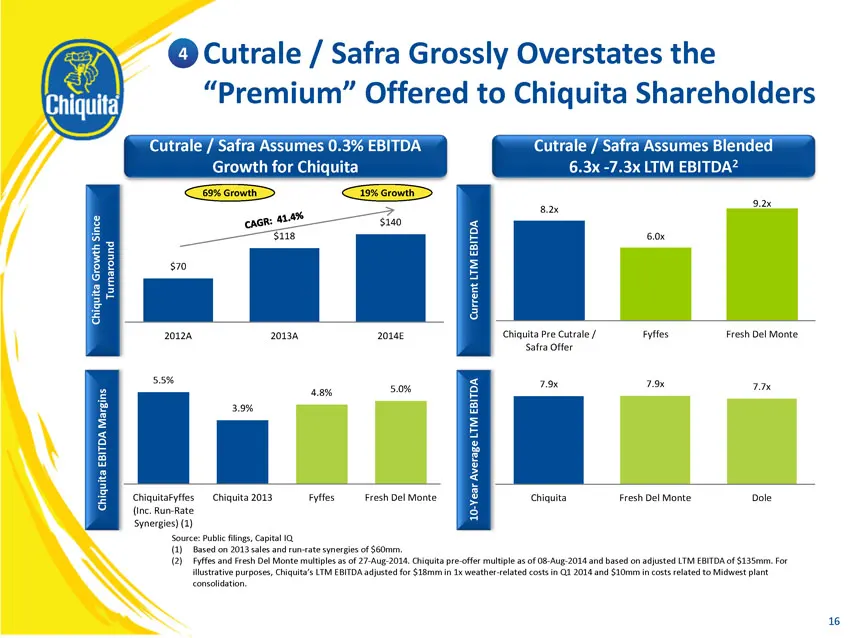
16 Cutrale / Safra Grossly Overstates the “Premium” Offered to Chiquita Shareholders 4 Cutrale / Safra Assumes 0.3% EBITDA Growth for Chiquita Cutrale / Safra Assumes Blended 6.3x - 7.3x LTM EBITDA 2 Chiquita Growth Since Turnaround Chiquita EBITDA Margins Current LTM EBITDA 10 - Year Average LTM EB
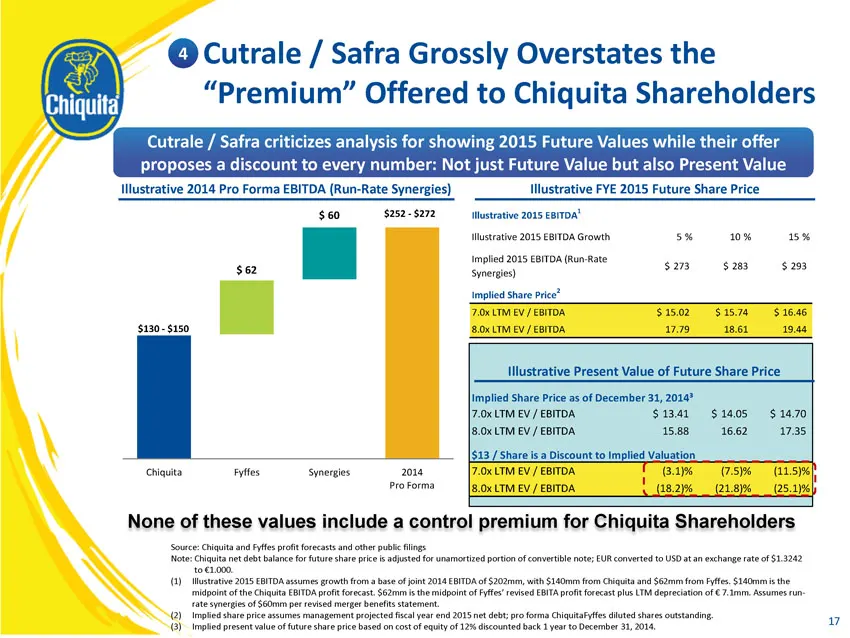
Slide 17: Illustrative FYE 2015 Future Share Price
17 Illustrative FYE 2015 Future Share Price Illustrative 2014 Pro Forma EBITDA (Run - Rate Synergies) Illustrative Present Value of Future Share Price Cutrale / Safra Grossly Overstates the “Premium” Offered to Chiquita Shareholders 4 Cutrale / Safra criticizes analysis for showing 2015 Future Value
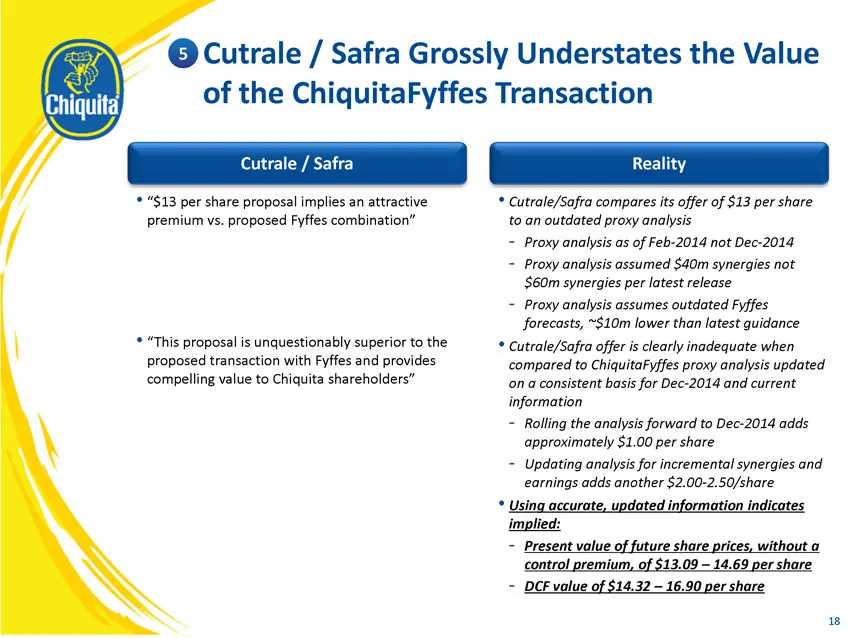
Slide 18: Understates the Value of the ChiquitaFyffes Transaction
18 Cutrale / Safra Grossly Understates the Value of the ChiquitaFyffes Transaction 5 Cutrale / Safra Reality • “$13 per share proposal implies an attractive premium vs. proposed Fyffes combination” • “This proposal is unquestionably superior to the proposed transaction with Fyffes and provides compe
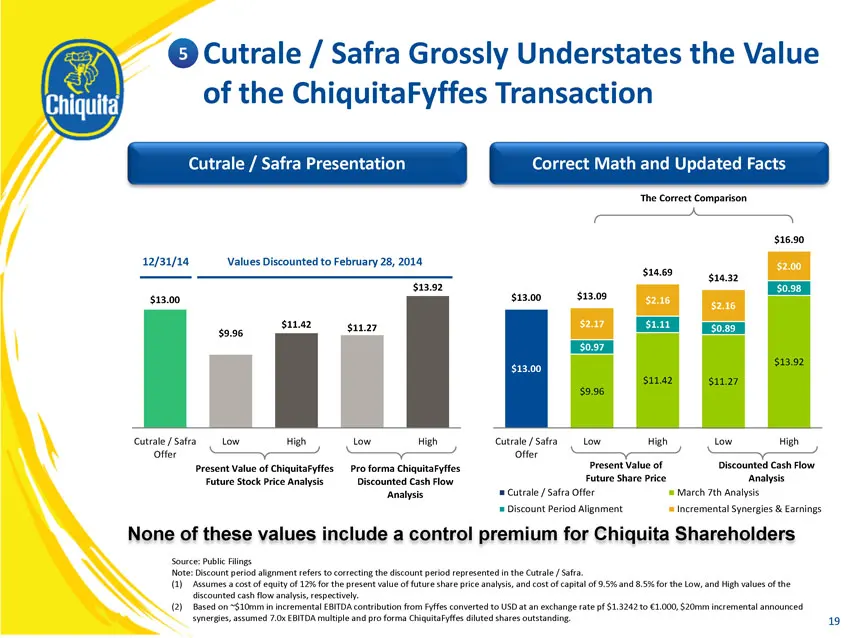
Slide 19: Correct Math and Updated Facts
19 Cutrale / Safra Presentation Correct Math and Updated Facts Cutrale / Safra Grossly Understates the Value of the ChiquitaFyffes Transaction 5 Values Discounted to February 28, 2014 12/31/14 $13.00 $9.96 $11.42 $11.27 $13.92 Cutrale / Safra Offer Low High Low High Present Value of ChiquitaFyffes F
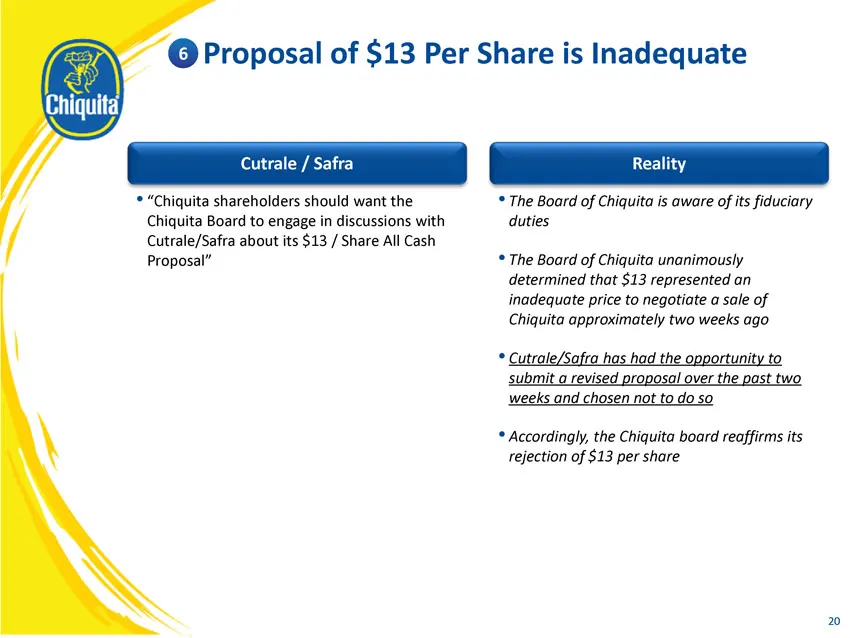
Slide 20: Proposal of $13 Per Share is Inadequate
20 Cutrale / Safra Reality • “Chiquita shareholders should want the Chiquita Board to engage in discussions with Cutrale/Safra about its $13 / Share All Cash Proposal” • The Board of Chiquita is aware of its fiduciary duties • The Board of Chiquita unanimously determined that $13 represented an inad
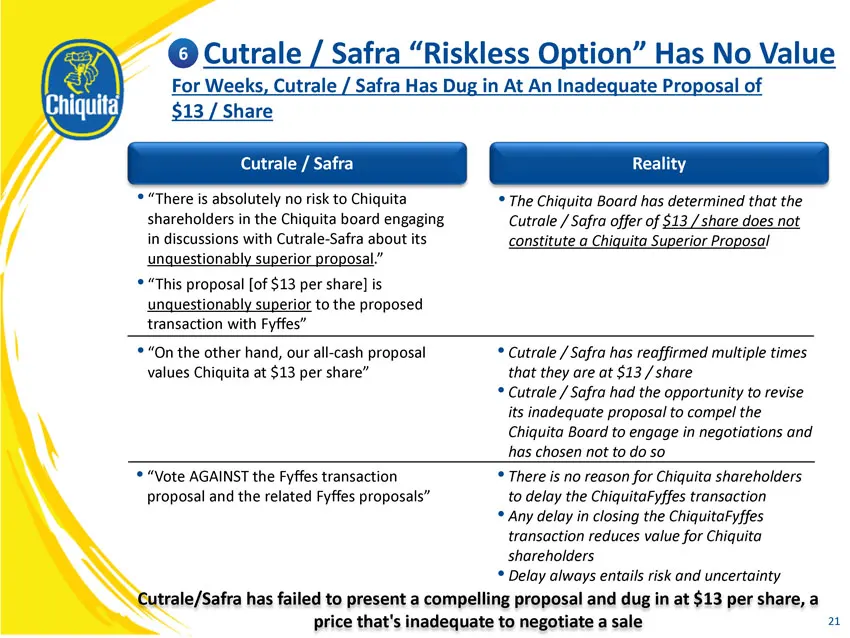
Slide 21: Cutrale / Safra Riskless Option Has No Value
21 Cutrale / Safra “Riskless Option” Has No Value For Weeks, Cutrale / Safra Has Dug in At An Inadequate Proposal of $13 / Share Cutrale / Safra Reality • The Chiquita Board has determined that the Cutrale / Safra offer of $13 / share does not constitute a Chiquita Superior Proposa l • “There is abs
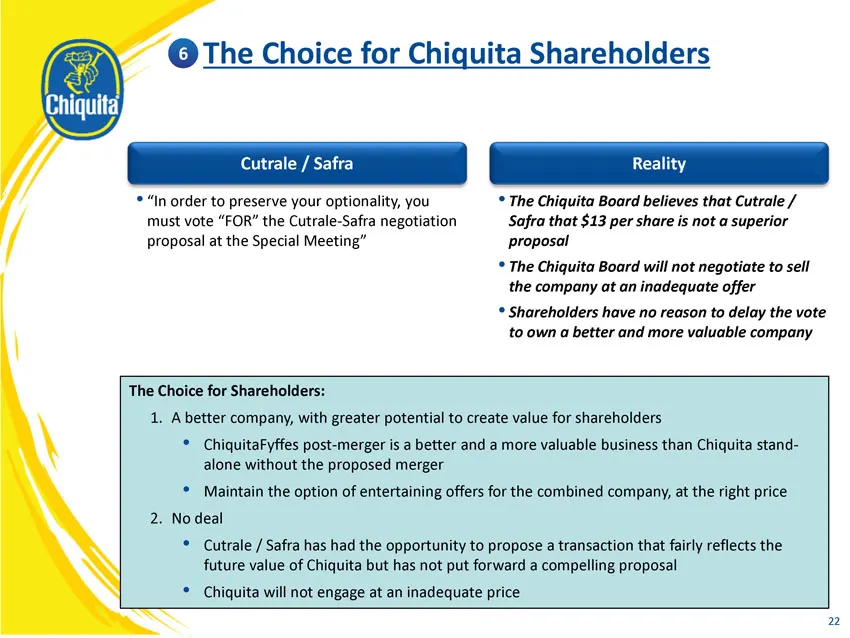
Slide 22: The Choice for Chiquita Shareholders
22 The Choice for Chiquita Shareholders Cutrale / Safra Reality • “In order to preserve your optionality, you must vote “FOR” the Cutrale - Safra negotiation proposal at the Special Meeting” • The Chiquita Board believes that Cutrale / Safra that $ 13 per share is not a superior proposal • The Chiqu
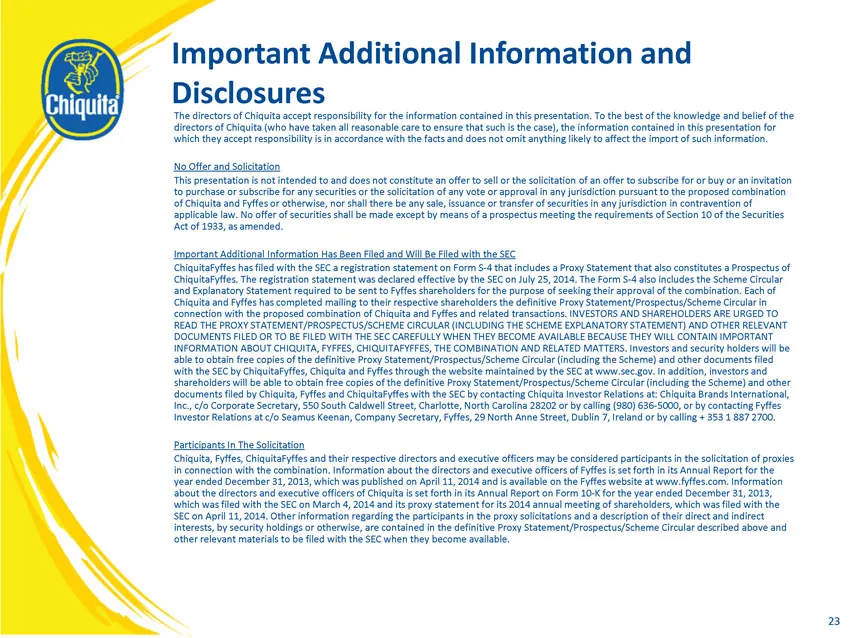
Slide 23: Responsibility statement and No Offer and Solicitation
23 The directors of Chiquita accept responsibility for the information contained in this presentation. To the best of the knowle dge and belief of the directors of Chiquita (who have taken all reasonable care to ensure that such is the case), the information contained in this pr esentation for which
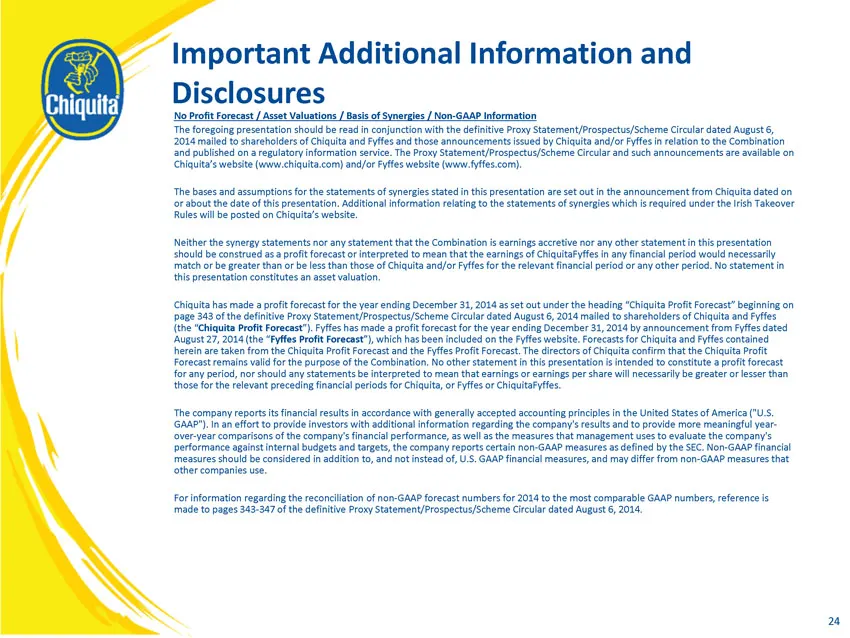
Slide 24: No Profit Forecast / Asset Valuations / Basis of Synergies / Non-GAAP Information
24 No Profit Forecast / Asset Valuations / Basis of Synergies / Non - GAAP Information The foregoing presentation should be read in conjunction with the definitive Proxy Statement/Prospectus/Scheme Circular dated Au gust 6, 2014 mailed to shareholders of Chiquita and Fyffes and those announcements i
Source: SEC EDGAR · 425 filed Sep 2, 2014
More decks from Chiquita Brands International Inc
 Merger or Acquisition (October 2014)24 slides · Oct 20, 2014
 Merger or Acquisition (October 2014)23 slides · Oct 20, 2014
 Proxy Contest (October 2014)15 slides · Oct 16, 2014
 Merger or Acquisition (October 2014)15 slides · Oct 14, 2014
 Proxy Contest (September 2014)28 slides · Sep 23, 2014
 Merger or Acquisition (September 2014)23 slides · Sep 17, 2014