INX — Security Research Associates 4th Annual Winter Technology Conference (February 2008)
29 slides from INX's conference presentation, Feb 11, 2008
Slide 1: Security Research Associates 4th Annual Winter Technology Conference
Security Research Associates 4th Annual Winter Technology Conference INX Inc. Nasdaq: INXI www.INXI.com February 11, 2008 Jim Long, Chairman & CEO
Slide 2: GAAP Reconciliation and Forward-Looking Statements
GAAP Reconciliation and Forward-Looking Statements This presentation contains "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995, including future operating results expectations. Statements associated with words such as "anticipate," "believe," "e
Slide 3: Overview - INX Inc. (Nasdaq: INXI)
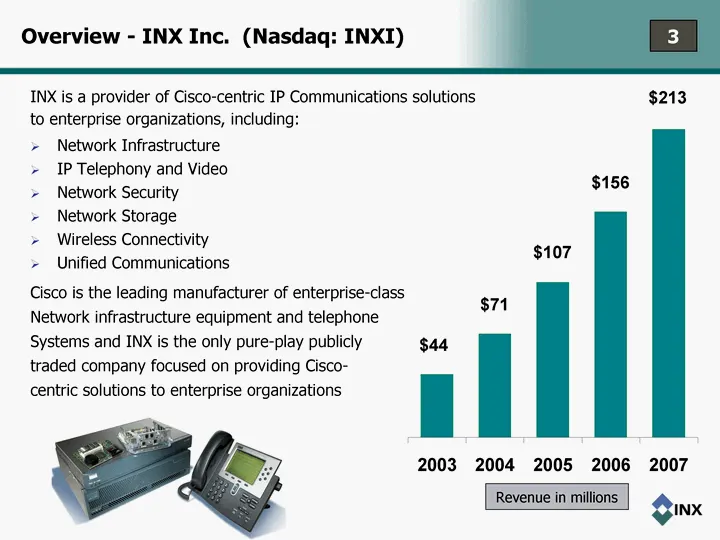
Overview - INX Inc. (Nasdaq: INXI) Overview - INX Inc. (Nasdaq: INXI) INX is a provider of Cisco-centric IP Communications solutions to enterprise organizations, including: Network Infrastructure IP Telephony and Video Network Security Network Storage Wireless Connectivity Unified Communications Cis
Slide 4: Overview - INX Inc.
Overview - INX Inc. (Nasdaq: INXI) NASDAQ GM: INXI Shares Outstanding: ~7.5MM Float: ~5.5MM Diluted shares: ~8.3MM 90-day avg. volume: ~30,000 Headquarters: Houston, Texas Headquarters: Houston, Texas Headquarters: Houston, Texas Headquarters: Houston, Texas Headquarters: Houston, Texas Headquarters
Slide 5: INX Key Investment Highlights
INX Key Investment Highlights Leading, focused player in a growing industry Industry-leading organic growth over a multi-year history Major opportunity to consolidate smaller operators and accelerate growth Proven track record of successful, accretive acquisitions Improving operating margins as scal
Slide 6: Industry Poised For Years of Growth - Focused Solutions Providers Will Benefit
Industry Poised For Years of Growth - Focused Solutions Providers Will Benefit Video will evolve to become an integral part of Enterprise communications over the next decade Microsoft Exchange will become a key VoIP communications component; will strengthen market momentum New and creative applicati
Slide 7: Industry Change Will Benefit Cisco As Well as Focused Solutions Providers
Industry Change Will Benefit Cisco As Well as Focused Solutions Providers IP Telephony / VoIP is rapidly displacing traditional business telephone systems, but currently represents only ~ 25%-30% of shipments; market expected to grow at 20%-25% per year over next several years Use of VoIP driving re
Slide 8: Increasing IP Network Importance & Complexity Benefits Focused Solutions Providers
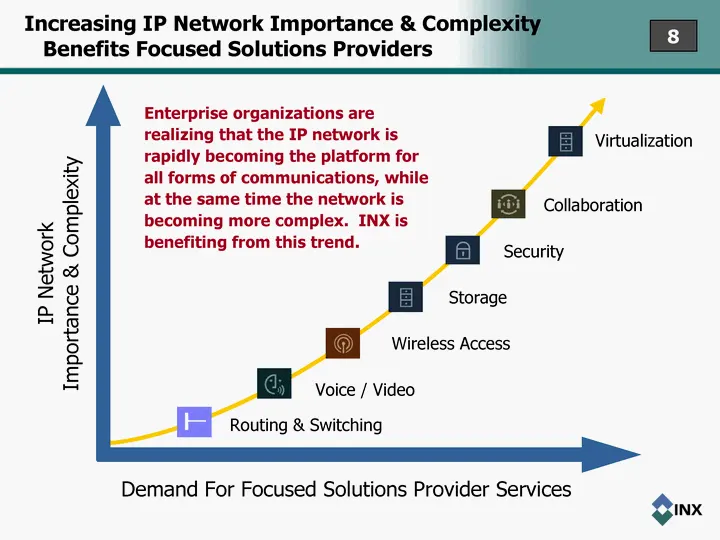
Increasing IP Network Importance & Complexity Benefits Focused Solutions Providers Voice / Video Wireless Access Storage Collaboration Security IP Network Importance & Complexity Demand For Focused Solutions Provider Services Routing & Switching Enterprise organizations are realizing that the IP net
Slide 9: The INX Solutions Set
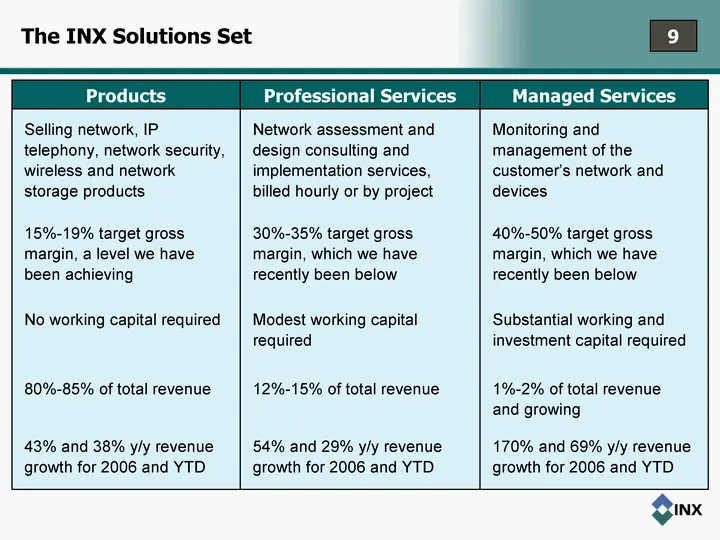
The INX Solutions Set Selling network, IP telephony, network security, wireless and network storage products Network assessment and design consulting and implementation services, billed hourly or by project 15%-19% target gross margin, a level we have been achieving 30%-35% target gross margin, whic
Slide 10: Growth Strategies
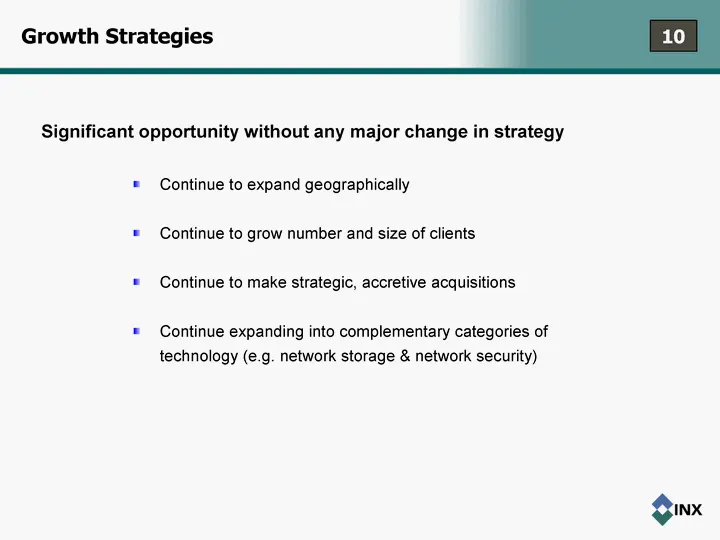
Growth Strategies Continue to expand geographically Continue to grow number and size of clients Continue to make strategic, accretive acquisitions Continue expanding into complementary categories of technology (e.g. network storage & network security) Significant opportunity without any major change
Slide 11: Increasing Number and Size of Customers
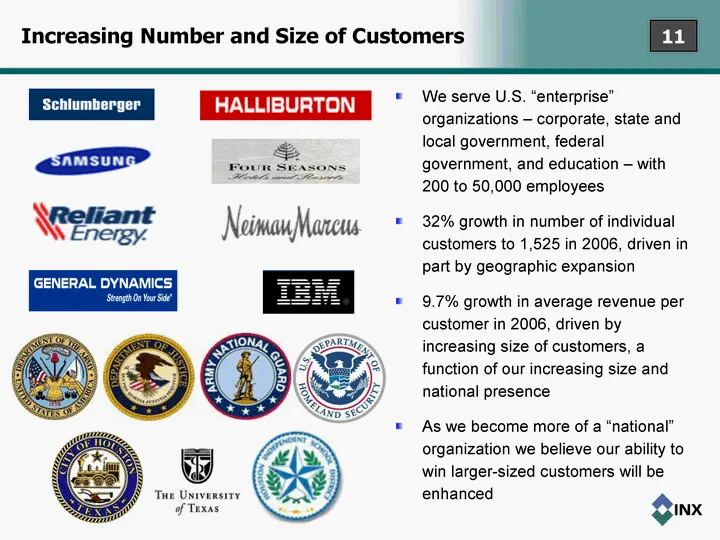
Increasing Number and Size of Customers We serve U.S. "enterprise" organizations - corporate, state and local government, federal government, and education - with 200 to 50,000 employees 32% growth in number of individual customers to 1,525 in 2006, driven in part by geographic expansion 9.7% growth
Slide 12: Geographic Expansion - Recent 3x Growth Of Markets Served
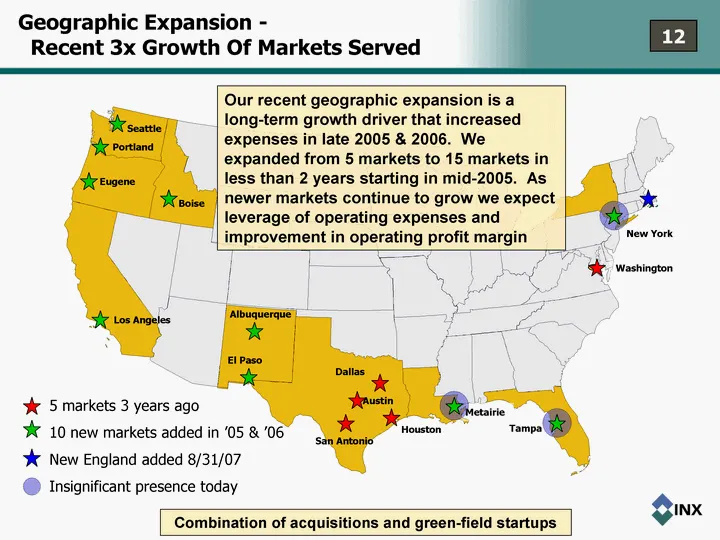
5 markets 3 years ago 10 new markets added in '05 & '06 New England added 8/31/07 Insignificant presence today Geographic Expansion - Recent 3x Growth Of Markets Served Houston Metairie San Antonio Austin Dallas El Paso Albuquerque Los Angeles Eugene Portland Seattle Washington Tampa New York Boise
Slide 13: Competition: National Presence + Focus & Expertise Are Competitive Advantages
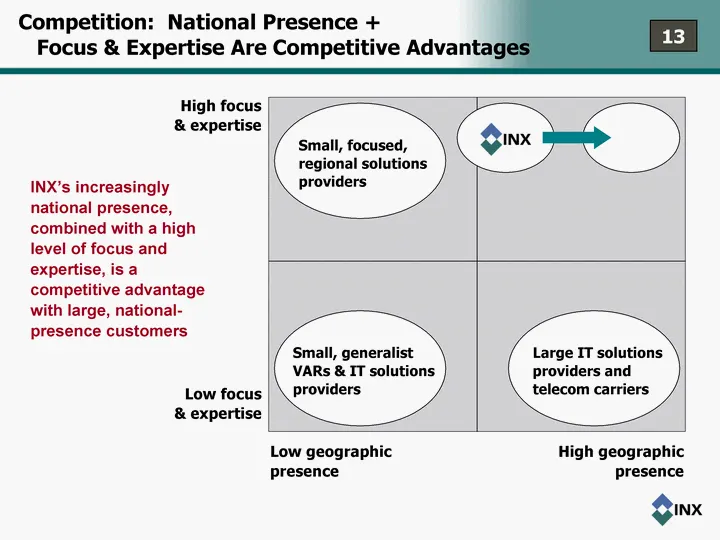
Competition: National Presence + Focus & Expertise Are Competitive Advantages High focus & expertise Low focus & expertise Low geographic presence High geographic presence INX's increasingly national presence, combined with a high level of focus and expertise, is a competitive advantage with large,
Slide 14: Acquisitions Strategy
Acquisitions Strategy We seek to acquire regional Cisco partners within a highly fragmented environment Financing is limited for smaller, privately-held solution providers, constraining growth relative to demand for IP Communications solutions Purchase prices for smaller, capital constrained, privat
Slide 15: Acquisitions History
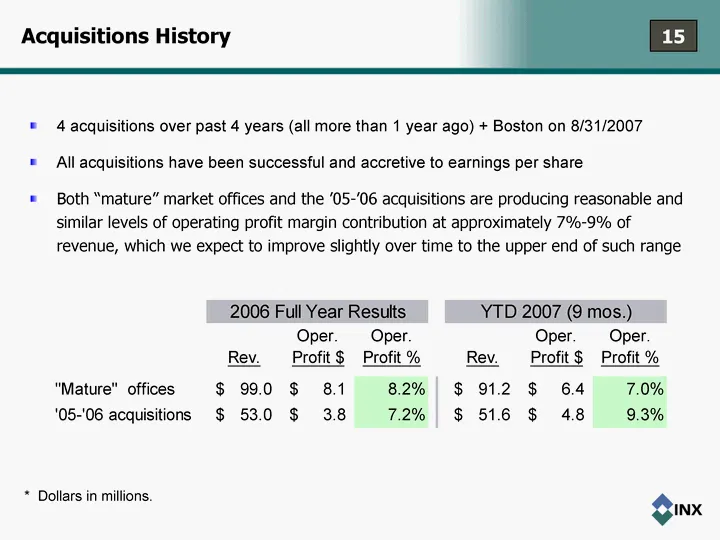
Acquisitions History 4 acquisitions over past 4 years (all more than 1 year ago) + Boston on 8/31/2007 All acquisitions have been successful and accretive to earnings per share Both "mature" market offices and the '05-'06 acquisitions are producing reasonable and similar levels of operating profit m
Slide 16: Our Two 2005 Acquisitions Delivered Substantial Organic Revenue Growth
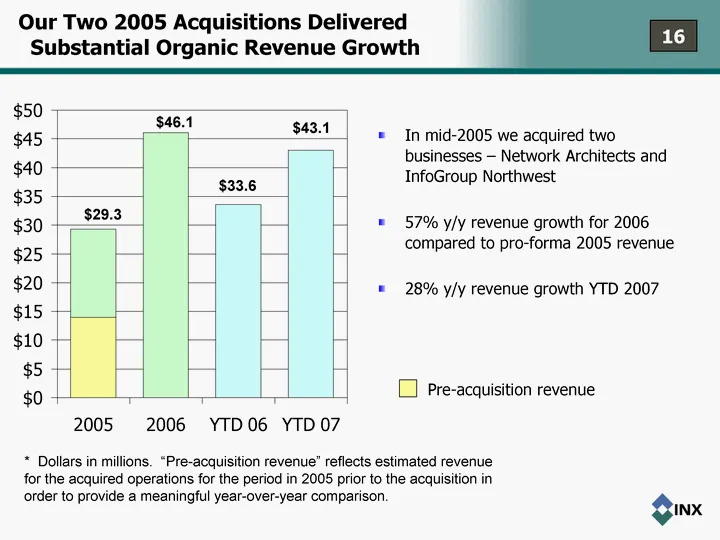
Our Two 2005 Acquisitions Delivered Substantial Organic Revenue Growth 2005 2006 YTD 06 YTD 07 Estimated pre-acquisition revenue 13.92 0 Post-acquisition revenue 15.4 46.1 33.6 43 In mid-2005 we acquired two businesses - Network Architects and InfoGroup Northwest 57% y/y revenue growth for 2006 comp
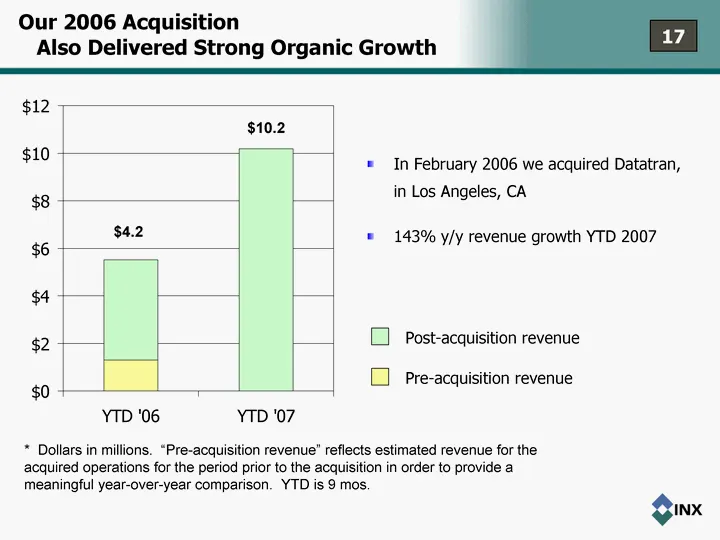
Slide 17: Our 2006 Acquisition Also Delivered Strong Organic Growth
Our 2006 Acquisition Also Delivered Strong Organic Growth YTD '06 YTD '07 Pre-acquisition revenue 1.3 0 Post-acquisition revenue 4.2067 10.182 $4.2 $10.2 * Dollars in millions. "Pre-acquisition revenue" reflects estimated revenue for the acquired operations for the period prior to the acquisition in
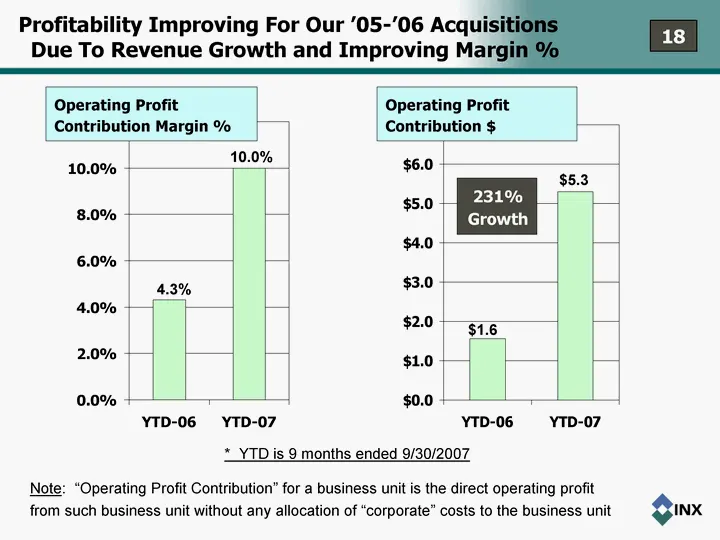
Slide 18: Profitability Improving For Our '05-'06 Acquisitions
YTD-06 YTD-07 Pre-acquisition revenue 0 0 Post-acquisition revenue 1.5634 5.3 Profitability Improving For Our '05-'06 Acquisitions Due To Revenue Growth and Improving Margin % YTD-06 YTD-07 Pre-acquisition revenue 0 0 Post-acquisition revenue 0.043 0.1 $1.6 4.3% $5.3 Operating Profit Contribution Ma
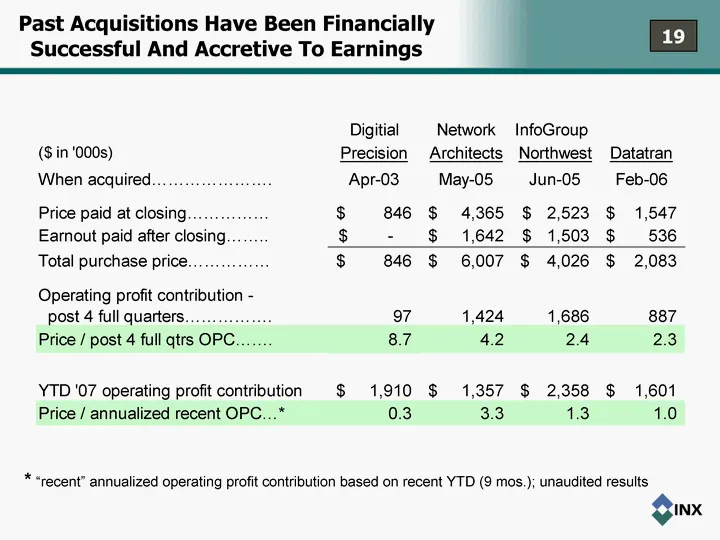
Slide 19: Past Acquisitions Have Been Financially Successful And Accretive To Earnings
Past Acquisitions Have Been Financially Successful And Accretive To Earnings * "recent" annualized operating profit contribution based on recent YTD (9 mos.); unaudited results
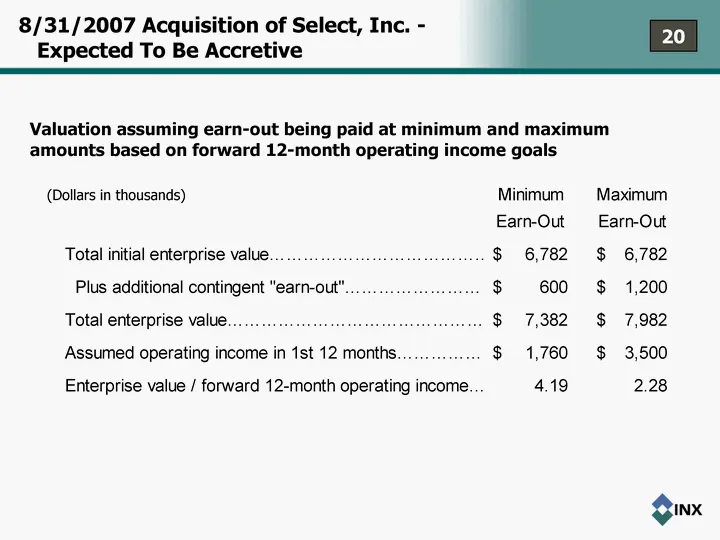
Slide 20: Acquisition of Select, Inc. - Expected To Be Accretive
(Dollars in thousands) 8/31/2007 Acquisition of Select, Inc. - Expected To Be Accretive Valuation assuming earn-out being paid at minimum and maximum amounts based on forward 12-month operating income goals
Slide 21: Our Longer-Term Financial Expectations
Our Longer-Term Financial Expectations We believe the market we serve in the U.S. is growing at ~15%-25% based on independent research and Cisco's growth in relevant subsets of their business We hope to grow faster than industry growth rates over the long run by: gaining market share because of our
Slide 22: Gross Margin Product vs. Services
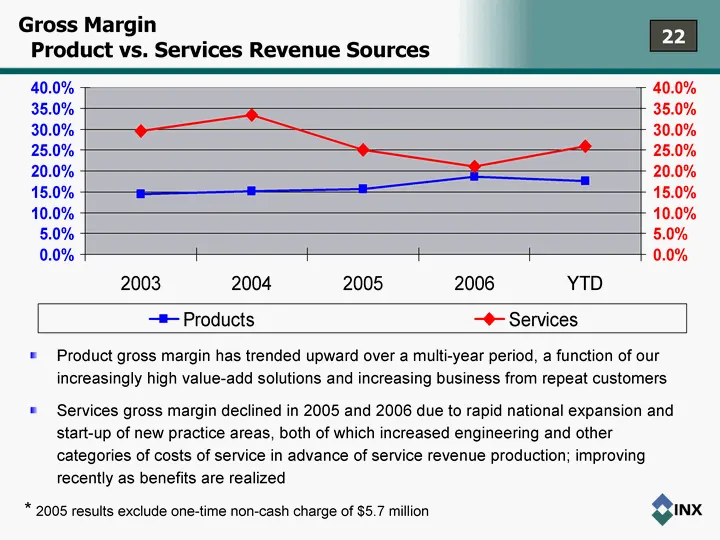
Gross Margin Product vs. Services Revenue Sources Product gross margin has trended upward over a multi-year period, a function of our increasingly high value-add solutions and increasing business from repeat customers Services gross margin declined in 2005 and 2006 due to rapid national expansion an
Slide 23: Gross and Operating Profit Margin
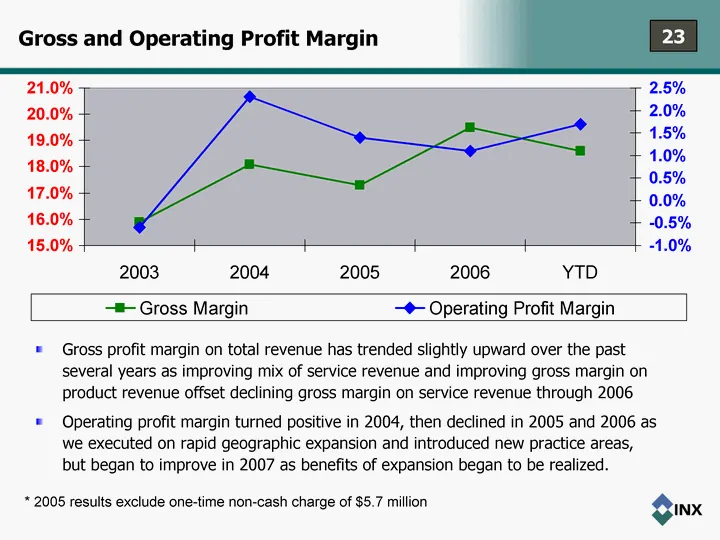
Gross and Operating Profit Margin Gross profit margin on total revenue has trended slightly upward over the past several years as improving mix of service revenue and improving gross margin on product revenue offset declining gross margin on service revenue through 2006 Operating profit margin turne
Slide 24: Staffing - Investing For Growth & Leveraging Cost
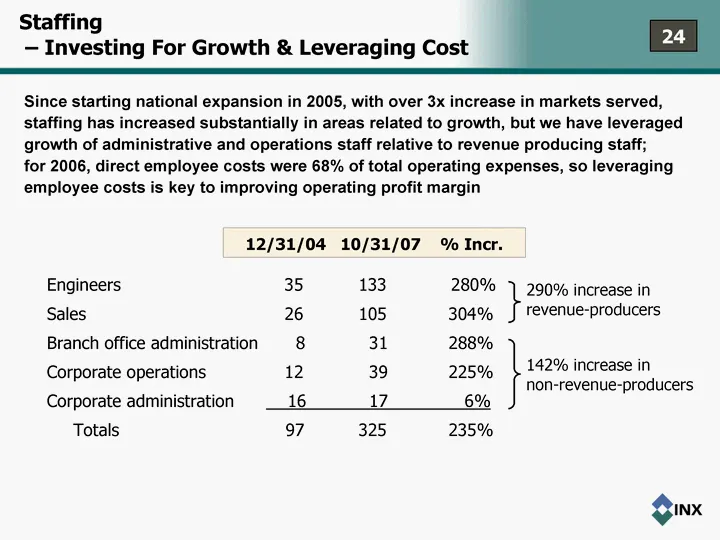
Staffing - Investing For Growth & Leveraging Cost Engineers 35 133 280% Sales 26 105 304% Branch office administration 8 31 288% Corporate operations 12 39 225% Corporate administration 16 17 6% Totals 97 325 235% 12/31/04 10/31/07 % Incr. Since starting national expansion in 2005, with over 3x incr
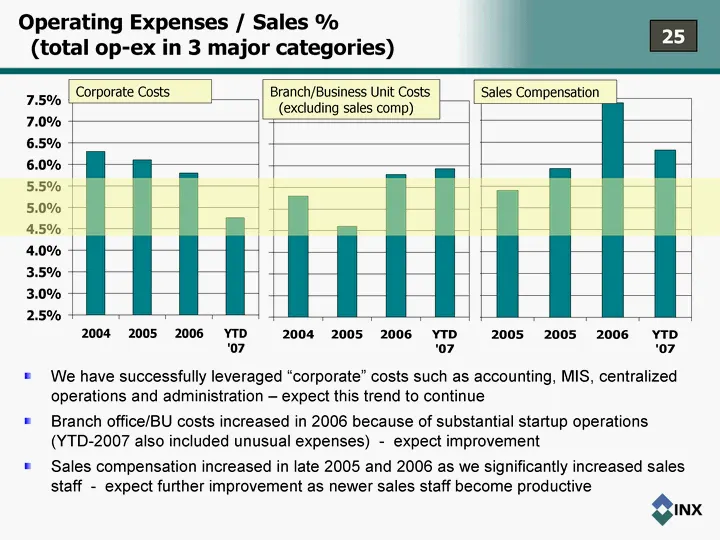
Slide 25: Operating Expenses / Sales %
2005 2005 2006 YTD '07 Sales compensation 0.054 0.059 0.074 0.0632 Operating Expenses / Sales % (total op-ex in 3 major categories) 2004 2005 2006 YTD '07 0.053 0.046 0.058 0.0593 Sales Compensation 2004 2005 2006 YTD '07 0.063 0.061 0.058 0.0476 Corporate Costs Branch/Business Unit Costs (excluding
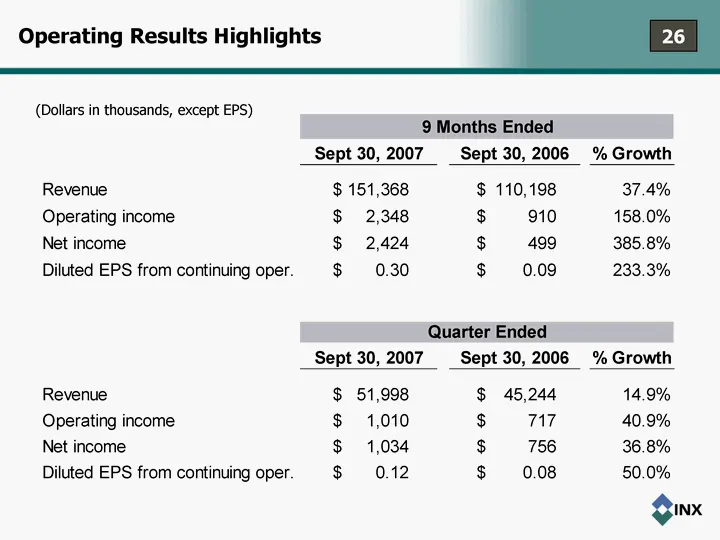
Slide 26: Operating Results Highlights
Operating Results Highlights (Dollars in thousands, except EPS)
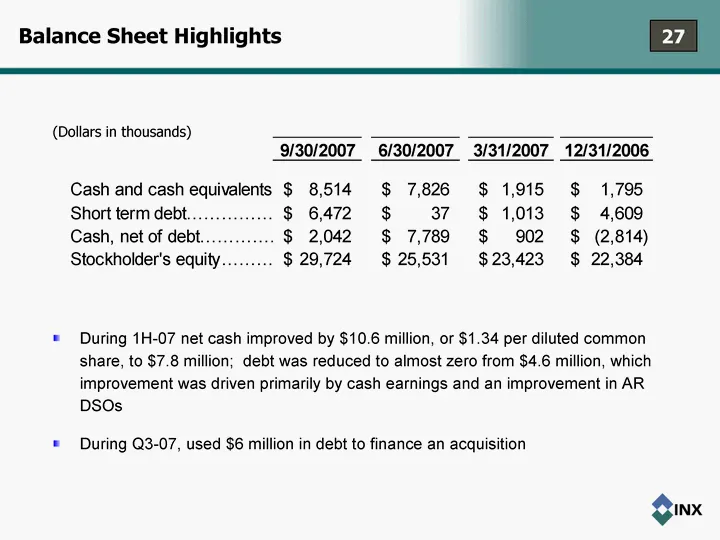
Slide 27: Balance Sheet Highlights
Balance Sheet Highlights (Dollars in thousands) During 1H-07 net cash improved by $10.6 million, or $1.34 per diluted common share, to $7.8 million; debt was reduced to almost zero from $4.6 million, which improvement was driven primarily by cash earnings and an improvement in AR DSOs During Q3-07,
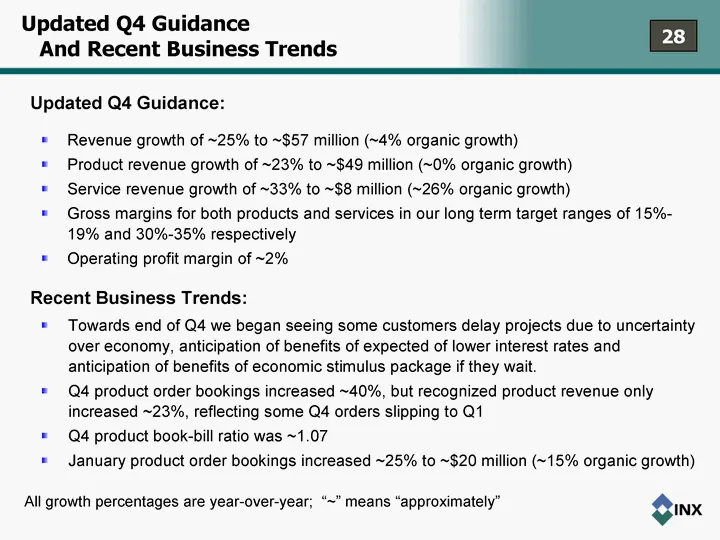
Slide 28: Updated Q4 Guidance And Recent Business Trends
Updated Q4 Guidance And Recent Business Trends Revenue growth of ~25% to ~$57 million (~4% organic growth) Product revenue growth of ~23% to ~$49 million (~0% organic growth) Service revenue growth of ~33% to ~$8 million (~26% organic growth) Gross margins for both products and services in our long
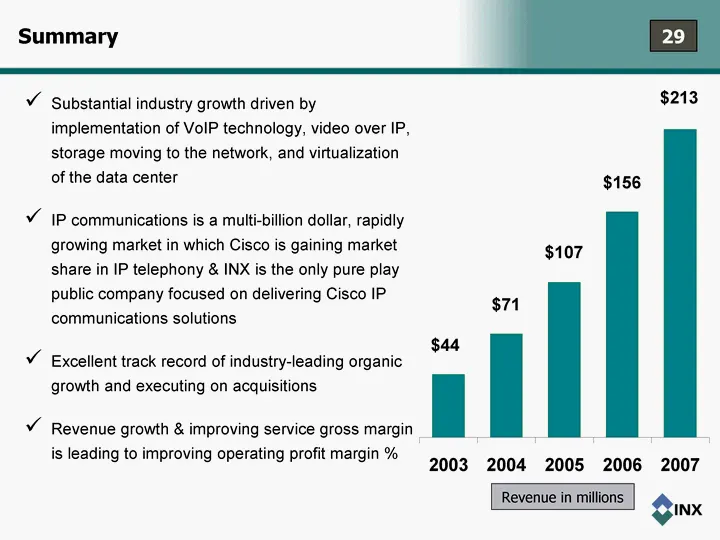
Slide 29: Summary
Summary Substantial industry growth driven by implementation of VoIP technology, video over IP, storage moving to the network, and virtualization of the data center IP communications is a multi-billion dollar, rapidly growing market in which Cisco is gaining market share in IP telephony & INX is the
Source: SEC EDGAR · 8-K filed Feb 11, 2008
More decks from INX Inc
 Merger or Acquisition (November 2011)10 slides · Nov 1, 2011
 Rodman & Renshaw Global Investment Conference 201120 slides · Sep 13, 2011
 Shareholder Meeting (July 2011)15 slides · Jul 19, 2011
 Q1 2011 Earnings Presentation15 slides · Jul 13, 2011
 FY2010 Earnings Presentation28 slides · Jun 6, 2011
 Corporate Update (November 2010)24 slides · Nov 10, 2010