Transatlantic — Merger or Acquisition (July 2011)
29 slides from Transatlantic's merger presentation, Jul 13, 2011
Slide 1: Greater Current and Long-Term Value for Transatlantic Stockholders
Greater Current and Long-Term Value for Transatlantic Stockholders July 13, 2011 Validus' Superior Proposal to Create a Global Reinsurance Leader FILED BY VALIDUS HOLDINGS, LTD. PURSUANT TO RULE 425 UNDER THE SECURITIES ACT OF 1933 AND DEEMED FILED PURSUANT TO RULE 14a-12 UNDER THE SECURITIES EXCHAN
Slide 2: Cautionary Note Regarding Forward-looking Statements
Cautionary Note Regarding Forward-looking Statements This presentation may include forward-looking statements, both with respect to us and our industry, that reflect our current views with respect to future events and financial performance. Statements that include the words "expect," "intend," "plan
Slide 3: Additional Information and Participants in the Solicitation
Additional Information and Participants in the Solicitation Additional Information about the Proposed Transaction and Where to Find It: This presentation relates to a proposed business combination transaction between Validus and Transatlantic which may become the subject of a registration statement
Slide 4: Note on Non-GAAP Financial Measures
Note on Non-GAAP Financial Measures In presenting Validus' results herein, management has included and discussed certain schedules containing diluted book and tangible book value per common share that are not calculated under standards or rules that comprise U.S. GAAP. Such measures are referred to
Slide 5: Validus' Superior Proposal for Transatlantic Stockholders
Validus' Superior Proposal for Transatlantic Stockholders Greater Current and Long-Term Value for Transatlantic Stockholders
Slide 6: Overview of Validus' Superior Proposal
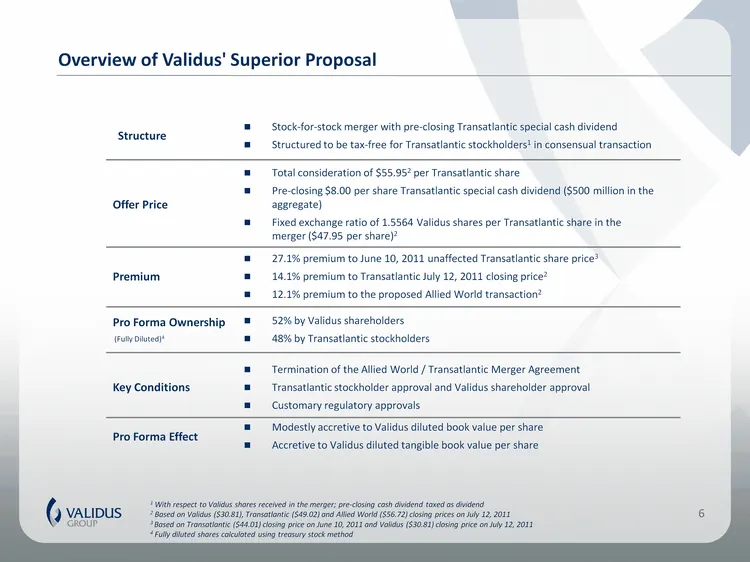
Overview of Validus' Superior Proposal 6 1 With respect to Validus shares received in the merger; pre-closing cash dividend taxed as dividend 2 Based on Validus ($30.81), Transatlantic ($49.02) and Allied World ($56.72) closing prices on July 12, 2011 3 Based on Transatlantic ($44.01) closing price
Slide 7: A Compelling Choice for Transatlantic Stockholders
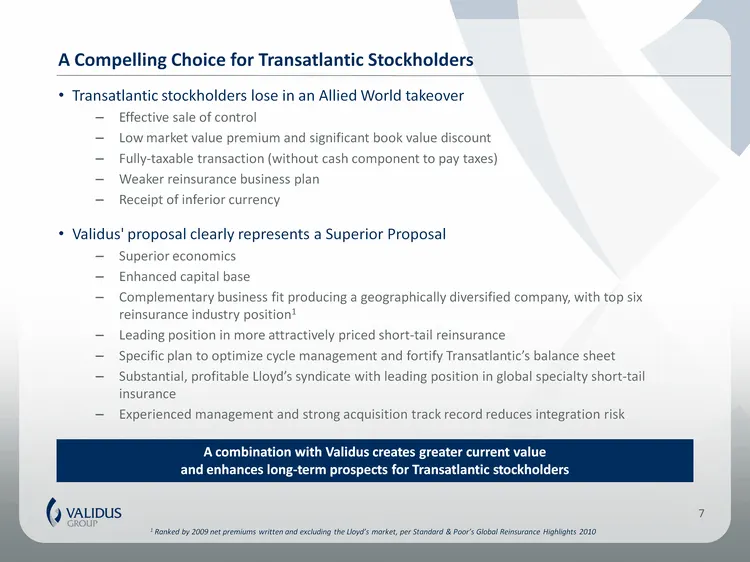
A Compelling Choice for Transatlantic Stockholders Transatlantic stockholders lose in an Allied World takeover Effective sale of control Low market value premium and significant book value discount Fully-taxable transaction (without cash component to pay taxes) Weaker reinsurance business plan Recei
Slide 8: Validus is Fully Committed to a Transaction with Transatlantic
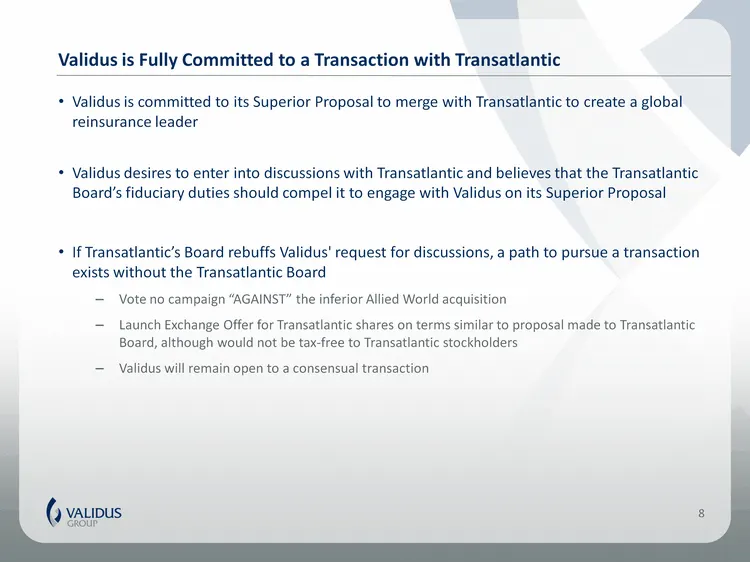
Validus is Fully Committed to a Transaction with Transatlantic Validus is committed to its Superior Proposal to merge with Transatlantic to create a global reinsurance leader Validus desires to enter into discussions with Transatlantic and believes that the Transatlantic Board's fiduciary duties sho
Slide 9: Validus Has a Track Record of Successfully Executing and Integrating Transactions
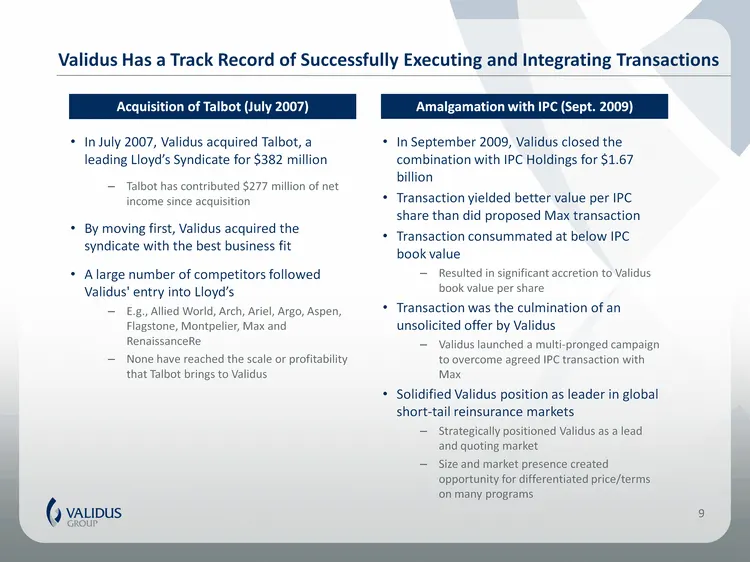
Validus Has a Track Record of Successfully Executing and Integrating Transactions Acquisition of Talbot (July 2007) In July 2007, Validus acquired Talbot, a leading Lloyd's Syndicate for $382 million Talbot has contributed $277 million of net income since acquisition By moving first, Validus acquire
Slide 10: Superior Financial Proposal - Higher Quality Currency
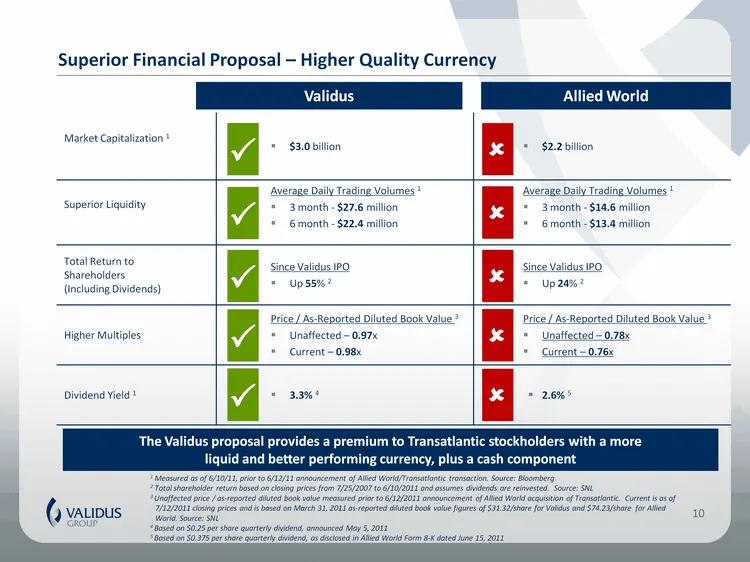
Superior Financial Proposal - Higher Quality Currency Validus Allied World Market Capitalization 1 $3.0 billion $2.2 billion Superior Liquidity Average Daily Trading Volumes 13 month - $27.6 million6 month - $22.4 million Average Daily Trading Volumes 13 month - $14.6 million6 month - $13.4 million
Slide 11: Superior Financial Proposal - Higher Quality Currency
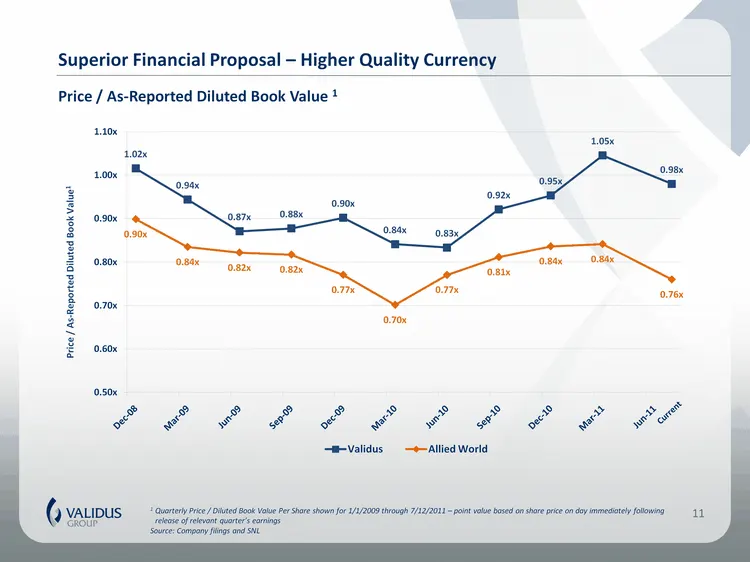
(CHART) Superior Financial Proposal - Higher Quality Currency 1 Quarterly Price / Diluted Book Value Per Share shown for 1/1/2009 through 7/12/2011 - point value based on share price on day immediately following release of relevant quarter's earnings Source: Company filings and SNL 11 Price / As-Rep
Slide 12: Validus Offers vs Allied World Offer Comparison
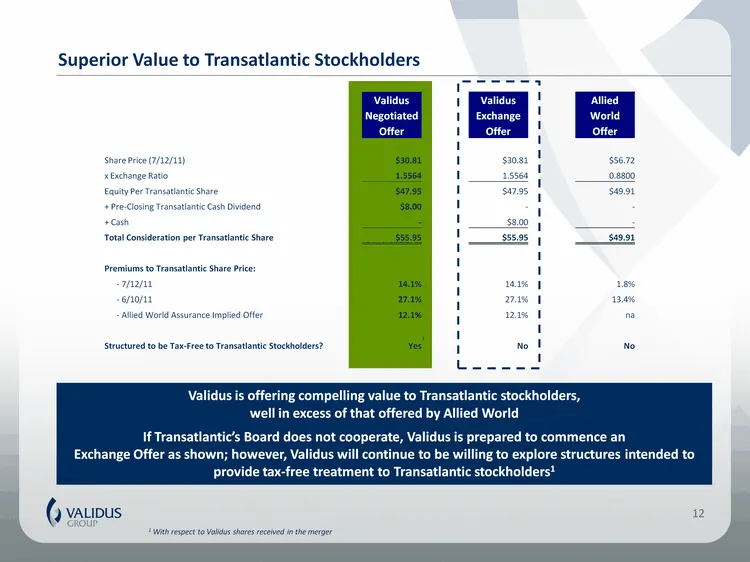
Validus Validus Allied Negotiated Exchange World Offer Offer Offer Share Price (7/12/11) Share Price (7/12/11) $30.81 $30.81 $56.72 x Exchange Ratio x Exchange Ratio 1.5564 1.5564 0.8800 Equity Per Transatlantic Share Equity Per Transatlantic Share Equity Per Transatlantic Share $47.95 $47.95 $49.91
Slide 13: Creating a Global Reinsurance Leader with a Clear Business Plan
Creating a Global Reinsurance Leader with a Clear Business Plan Greater Current and Long-Term Value for Transatlantic Stockholders
Slide 14: Post-Combination Business Plan
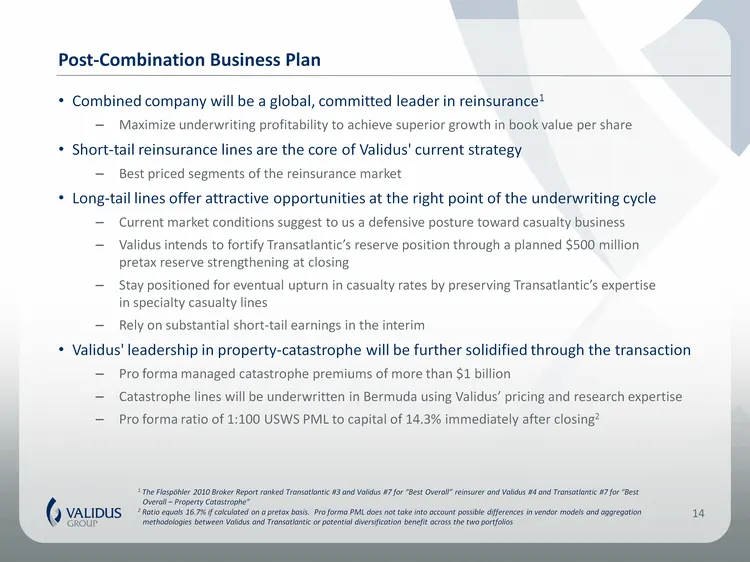
Post-Combination Business Plan Combined company will be a global, committed leader in reinsurance1 Maximize underwriting profitability to achieve superior growth in book value per share Short-tail reinsurance lines are the core of Validus' current strategy Best priced segments of the reinsurance mar
Slide 15: Pro Forma Reinsurance Market Position - By 2009 Net Premiums
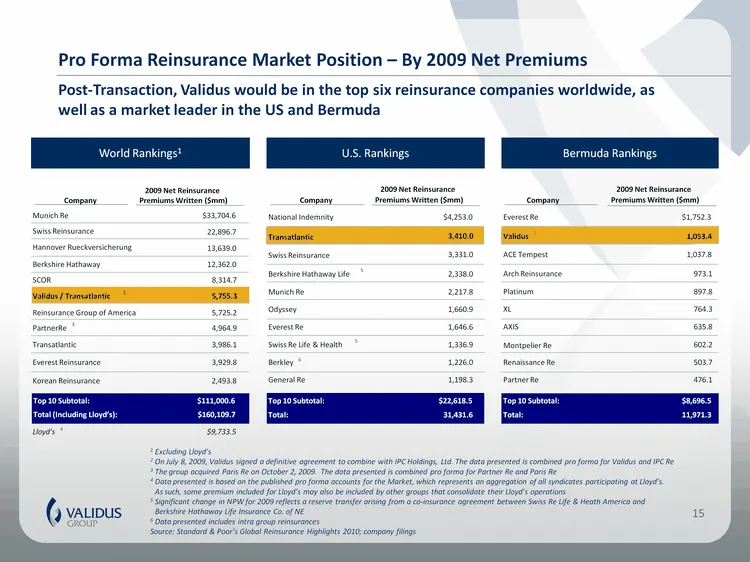
Pro Forma Reinsurance Market Position - By 2009 Net Premiums Post-Transaction, Validus would be in the top six reinsurance companies worldwide, as well as a market leader in the US and Bermuda U.S. Rankings Company 2009 Net Reinsurance Premiums Written ($mm) Berkshire Hathaway Life National Indemnit
Slide 16: Reinsurance Peer Group - By Capitalization
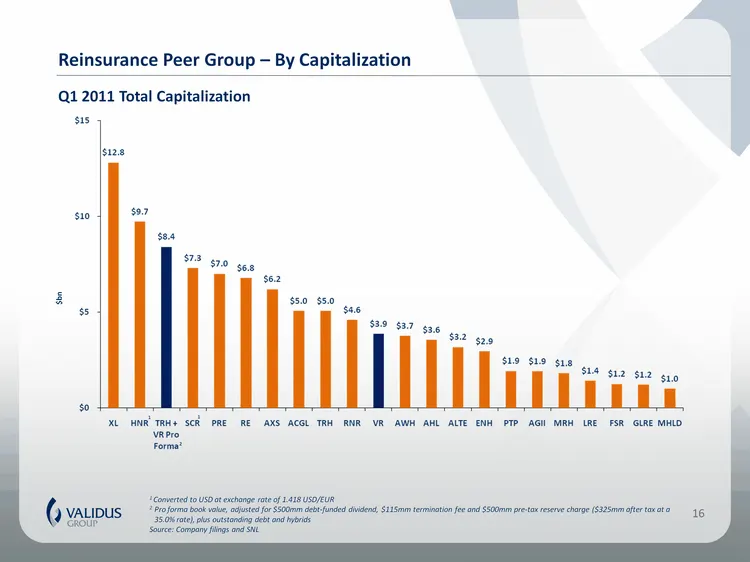
Reinsurance Peer Group - By Capitalization 16 $bn 2 Q1 2011 Total Capitalization 1 1 1 Converted to USD at exchange rate of 1.418 USD/EUR 2 Pro forma book value, adjusted for $500mm debt-funded dividend, $115mm termination fee and $500mm pre-tax reserve charge ($325mm after tax at a 35.0% rate), plu
Slide 17: Validus' Leadership in Property Cat will be Further Enhanced
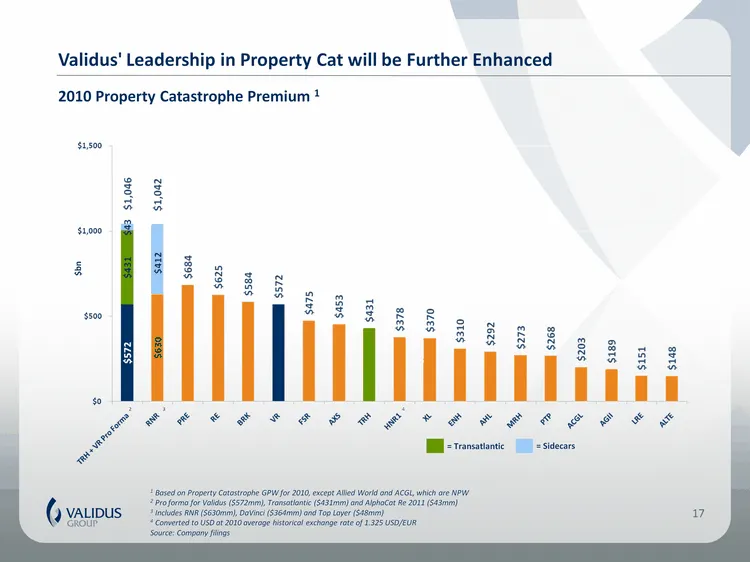
Validus' Leadership in Property Cat will be Further Enhanced 17 3 $bn 2 2010 Property Catastrophe Premium 1 4 1 Based on Property Catastrophe GPW for 2010, except Allied World and ACGL, which are NPW 2 Pro forma for Validus ($572mm), Transatlantic ($431mm) and AlphaCat Re 2011 ($43mm) 3 Includes RNR
Slide 18: ....But Will Remain Within Validus' Risk Tolerance
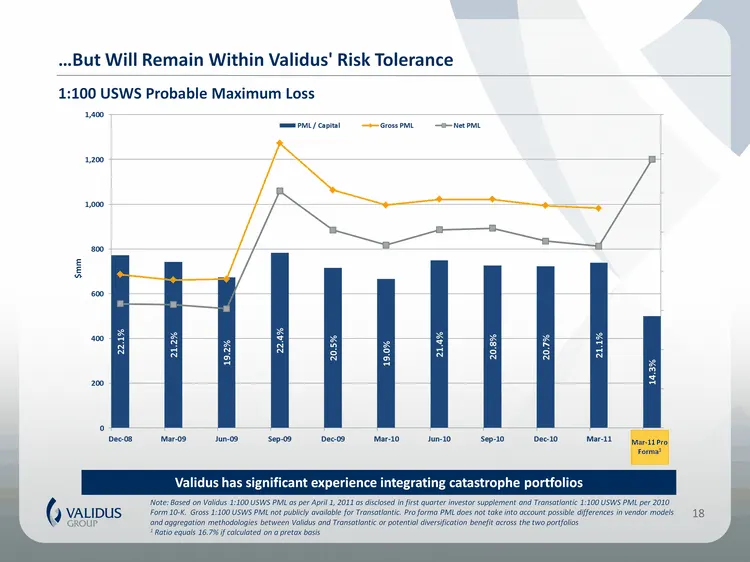
....But Will Remain Within Validus' Risk Tolerance Validus has significant experience integrating catastrophe portfolios Note: Based on Validus 1:100 USWS PML as per April 1, 2011 as disclosed in first quarter investor supplement and Transatlantic 1:100 USWS PML per 2010 Form 10-K. Gross 1:100 USWS
Slide 19: Property Catastrophe Rate Environment Continues to be Favorable
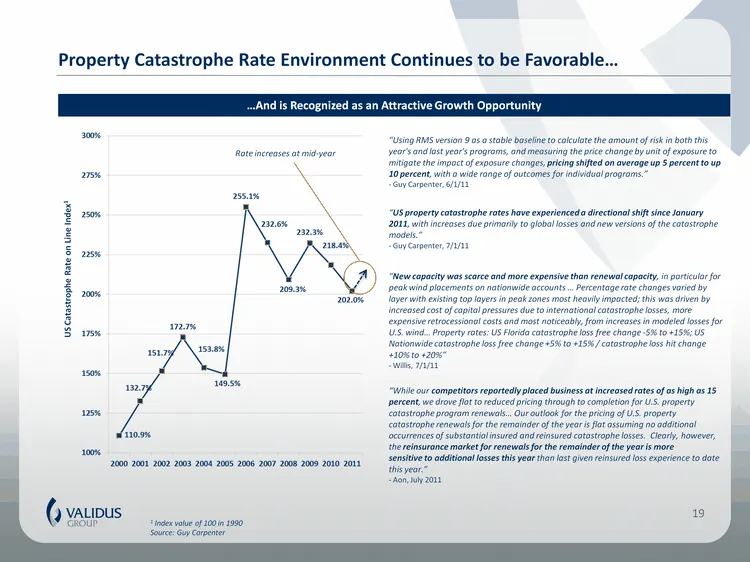
Property Catastrophe Rate Environment Continues to be Favorable... 19 1 Index value of 100 in 1990 Source: Guy Carpenter ....And is Recognized as an Attractive Growth Opportunity "Using RMS version 9 as a stable baseline to calculate the amount of risk in both this year's and last year's programs, a
Slide 20: Validus + Transatlantic - Better Diversification to Manage the Cycle
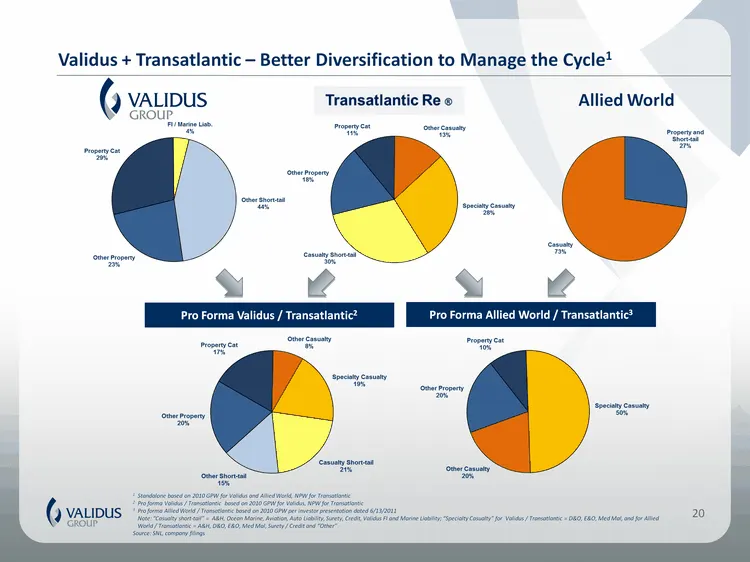
Pro Forma Validus / Transatlantic2 Pro Forma Allied World / Transatlantic3 20 Validus + Transatlantic - Better Diversification to Manage the Cycle1 1 Standalone based on 2010 GPW for Validus and Allied World, NPW for Transatlantic 2 Pro forma Validus / Transatlantic based on 2010 GPW for Validus, NP
Slide 21: Validus is More Committed to Reinsurance Business than Allied World
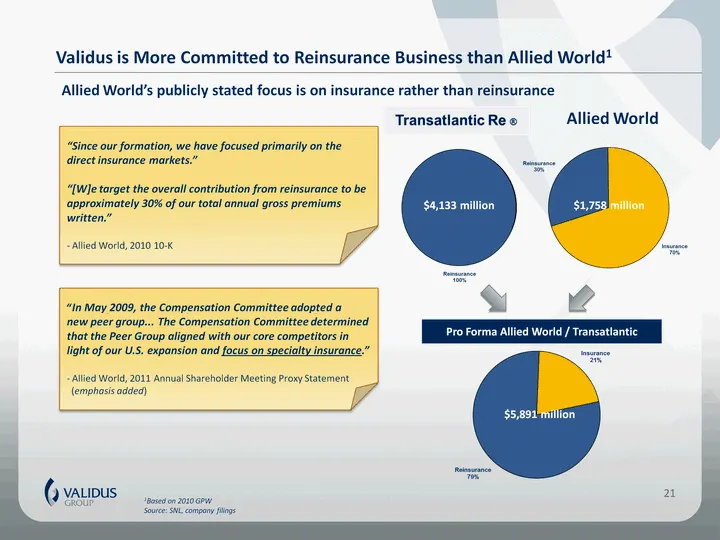
Validus is More Committed to Reinsurance Business than Allied World1 21 "Since our formation, we have focused primarily on the direct insurance markets." "[W]e target the overall contribution from reinsurance to be approximately 30% of our total annual gross premiums written." - Allied World, 2010 1
Slide 22: Validus' Insurance Operations Bring Better Returns and True Diversification
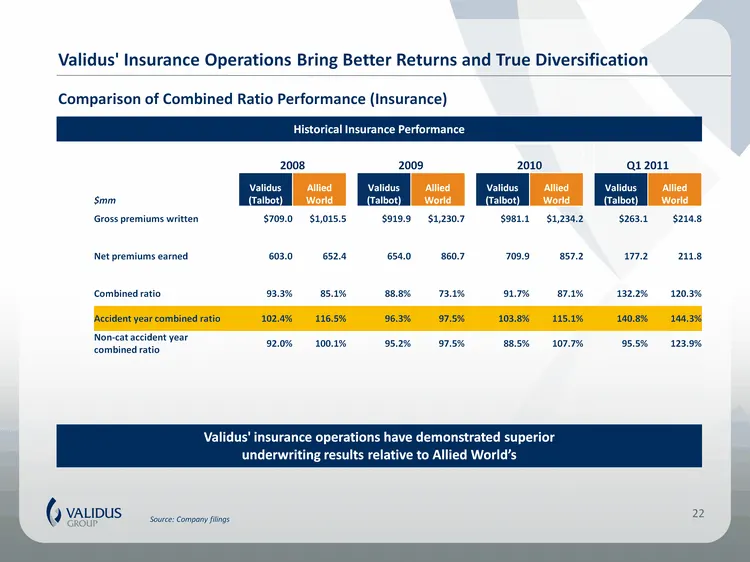
Validus' Insurance Operations Bring Better Returns and True Diversification 22 Source: Company filings Comparison of Combined Ratio Performance (Insurance) Validus' insurance operations have demonstrated superior underwriting results relative to Allied World's Historical Insurance Performance 2008 2
Slide 23: Validus' Defensive View of US Casualty
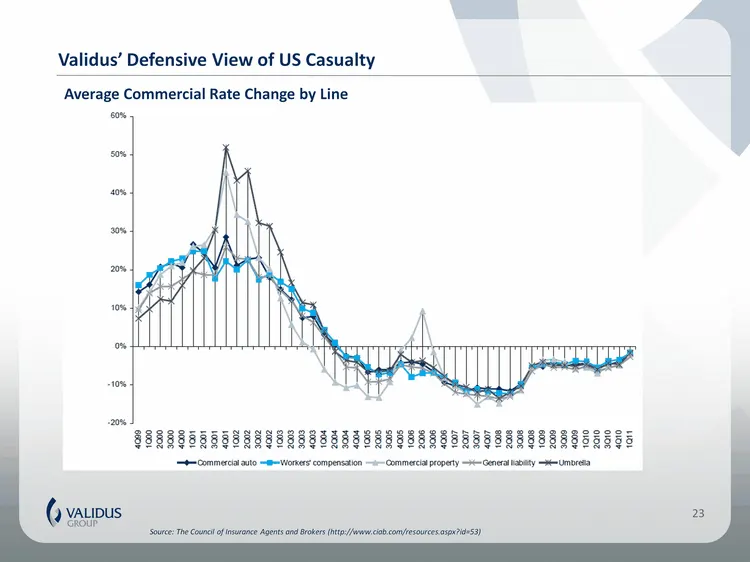
Validus' Defensive View of US Casualty Source: The Council of Insurance Agents and Brokers (http://www.ciab.com/resources.aspx?id=53) 23 Average Commercial Rate Change by Line
Slide 24: Plan to Fortify the Balance Sheet with Pre-Closing Transatlantic Reserve Increase
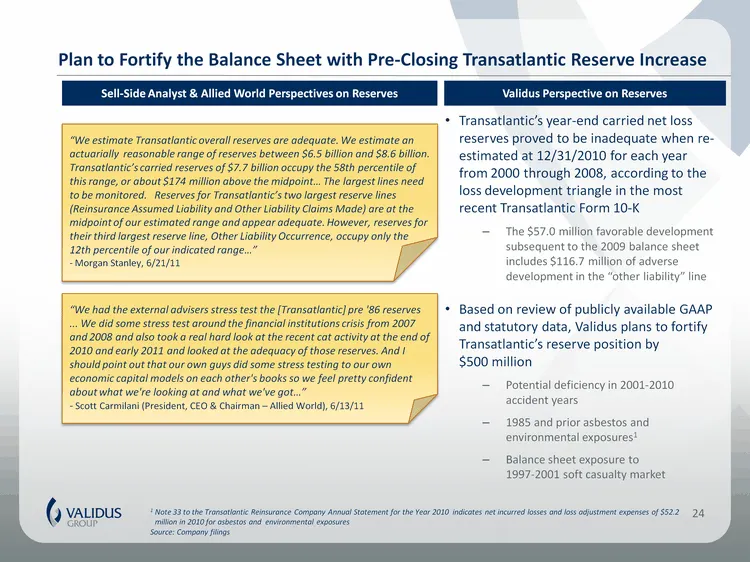
Plan to Fortify the Balance Sheet with Pre-Closing Transatlantic Reserve Increase Transatlantic's year-end carried net loss reserves proved to be inadequate when re- estimated at 12/31/2010 for each year from 2000 through 2008, according to the loss development triangle in the most recent Transatlan
Slide 25: Validus' Roadmap to Completion
Validus' Roadmap to Completion Greater Current and Long-Term Value for Transatlantic Stockholders
Slide 26: Validus' Roadmap to Completion
Validus' Roadmap to Completion One: Submit Proposal to Transatlantic Board Delivered proposal letter and merger agreement on July 12, 2011 containing Superior Proposal Validus desires Transatlantic Board to engage in discussions on proposal to deliver a superior, tax-free transaction1 for Transatlan
Slide 27: Creating a Global Reinsurance Leader
Creating a Global Reinsurance Leader Validus is committed to its Superior Proposal to merge with Transatlantic to create a global reinsurance leader Validus' proposal clearly represents a Superior Proposal Total consideration of $55.95 per Transatlantic share1 Superior current value: 27.1% premium t
Slide 28: Appendix
Greater Current and Long-Term Value for Transatlantic Stockholders APPENDIX Validus' Superior Proposal to Create a Global Reinsurance Leader
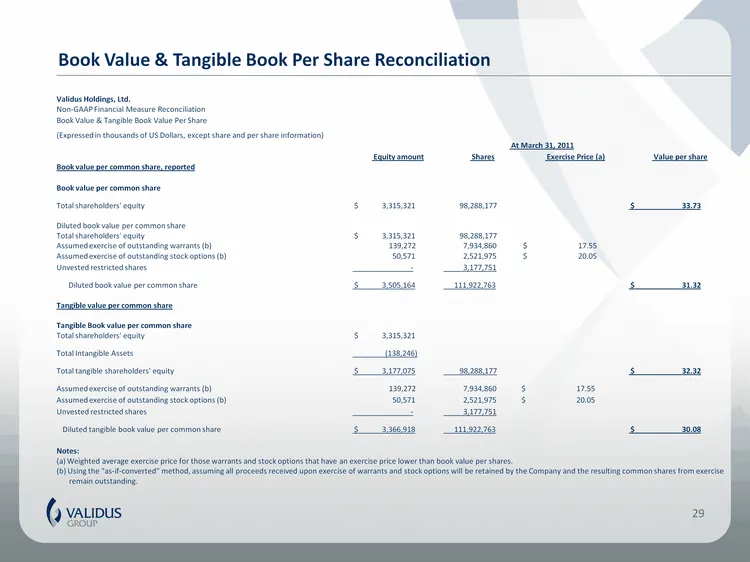
Slide 29: Book Value & Tangible Book Per Share Reconciliation
Book Value & Tangible Book Per Share Reconciliation 29 Validus Holdings, Ltd. Non-GAAP Financial Measure Reconciliation Non-GAAP Financial Measure Reconciliation Non-GAAP Financial Measure Reconciliation Book Value & Tangible Book Value Per Share Book Value & Tangible Book Value Per Share Book Value
Source: SEC EDGAR · 425 filed Jul 13, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011