Andeavor Logistics LP — Tesoro Logistics — 2012 RBC Capital Markets MLP Conference
21 slides from Andeavor Logistics LP's conference presentation, Nov 15, 2012
Slide 1: 2012 RBC Capital Markets MLP Conference
NYSE: TLLP 2012 RBC Capital Markets MLP Conference November 2012 Tesoro Logistics LP Exhibit 99.2
Slide 2: Forward Looking Statements
2 This Presentation includes forward-looking statements. These statements relate to, among other things, projections of operational volumetrics and improvements, growth projects, cash flows, capital expenditures future performance; past and potential purchases of logistics assets by Tesoro Logistics
Slide 3: Overview of Our Current Assets
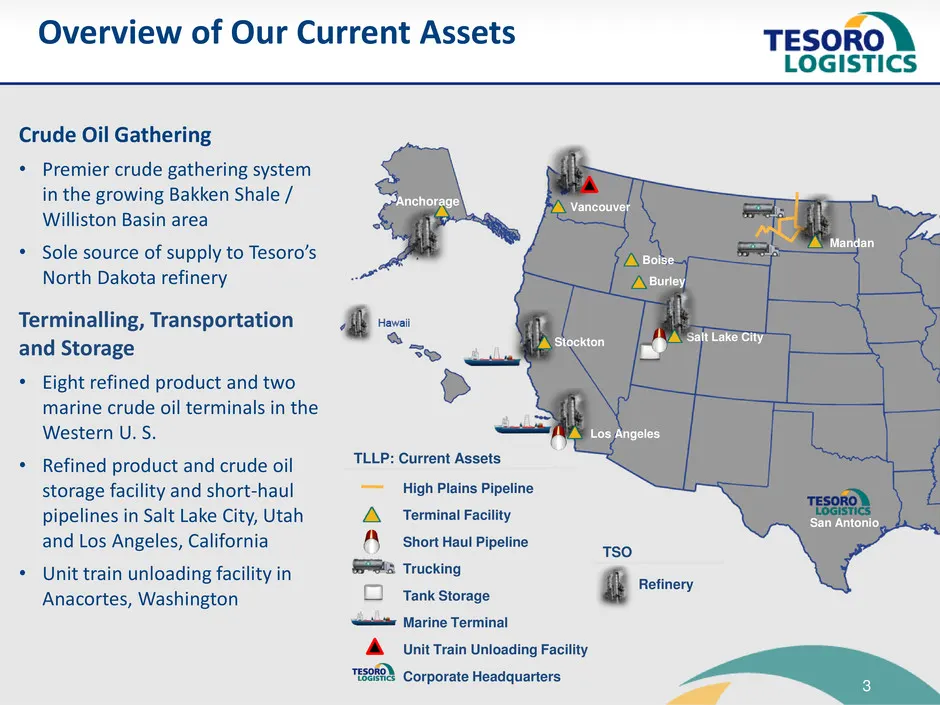
3 Overview of Our Current Assets Crude Oil Gathering • Premier crude gathering system in the growing Bakken Shale / Williston Basin area • Sole source of supply to Tesoro’s North Dakota refinery Terminalling, Transportation and Storage • Eight refined product and two marine crude oil terminals in th
Slide 4: Investment Highlights
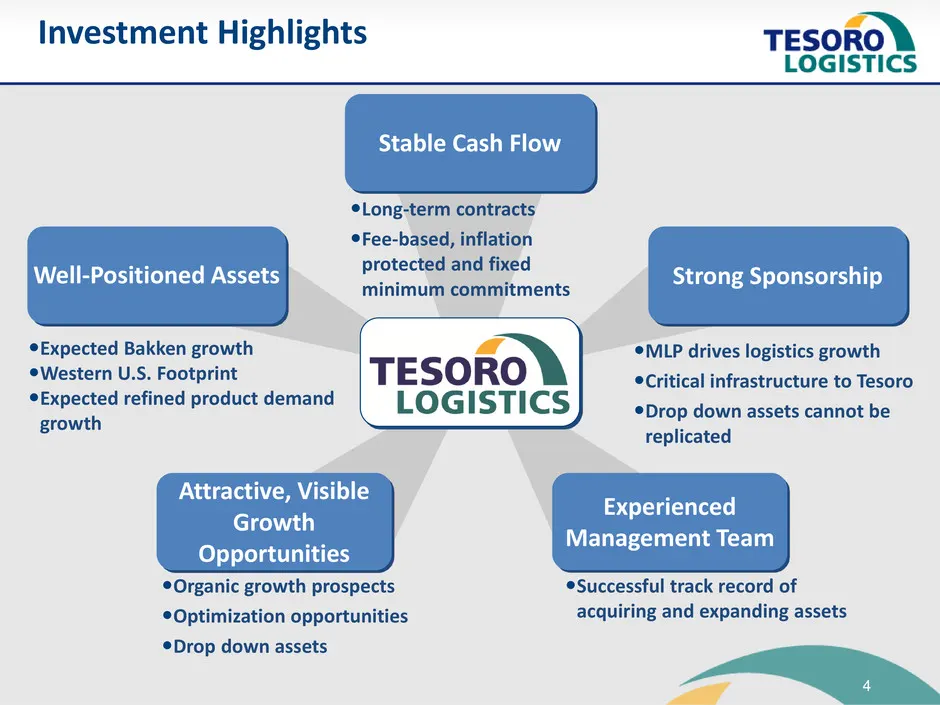
4 Investment Highlights Well-Positioned Assets Stable Cash Flow Experienced Management Team Strong Sponsorship Attractive, Visible Growth Opportunities Organic growth prospects Optimization opportunities Drop down assets Long-term contracts Fee-based, inflation protected and fixed minimum commi
Slide 5: Tesoro's Strategic Goals Support TLLP
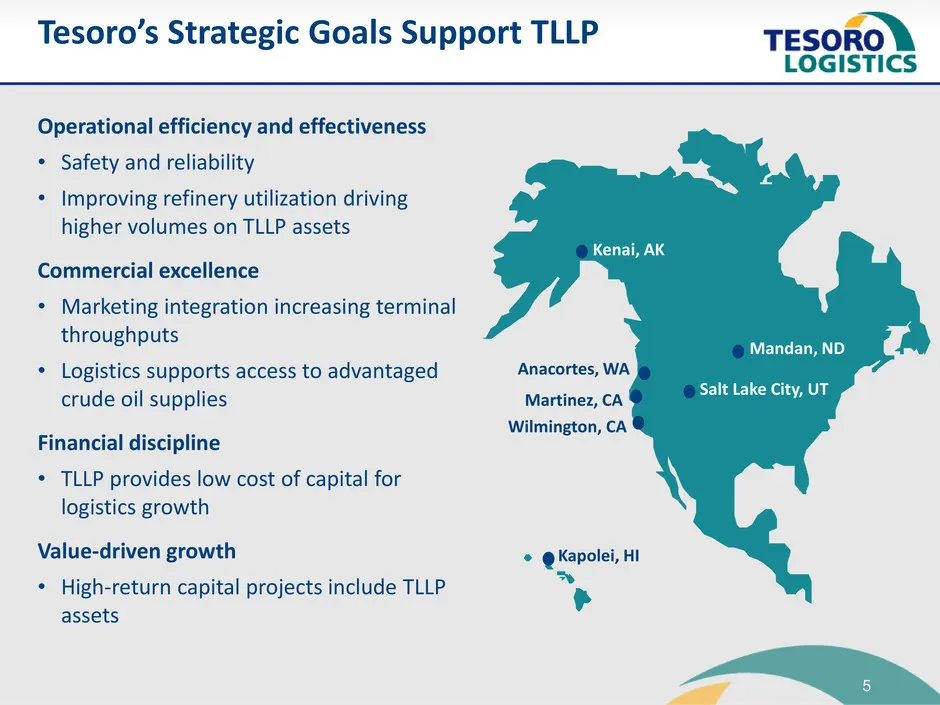
5 Tesoro’s Strategic Goals Support TLLP Operational efficiency and effectiveness • Safety and reliability • Improving refinery utilization driving higher volumes on TLLP assets Commercial excellence • Marketing integration increasing terminal throughputs • Logistics supports access to advantaged cru
Slide 6: Strategic Plan
6 Strategic Plan IPO • Base business generates approximately $53 million in EBITDA Optimization • Since IPO, added $8 million in annualized EBITDA by improving utilization of our assets Organic Growth • Grow Bakken system volumes to over 100,000 bpd on our High Plains system backed by Tesoro demand,
Slide 7: Crude Oil Gathering
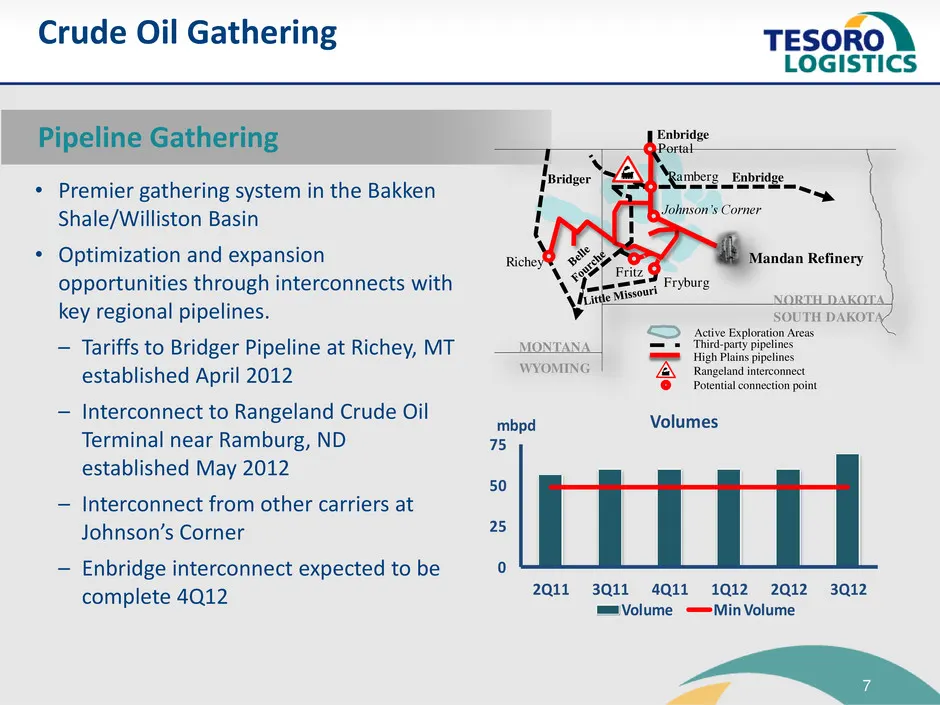
7 Mandan Refinery Enbridge Fryburg Fritz Bridger Richey Enbridge Portal Ramberg NORTH DAKOTA SOUTH DAKOTA WYOMING MONTANA Third-party pipelines High Plains pipelines Potential connection point Active Exploration Areas 0 25 50 75 2Q11 3Q11 4Q11 1Q12 2Q12 3Q12 Volumes Volume Min Volume mbpdCrude Oil G
Slide 8: Crude Oil Gathering Operations
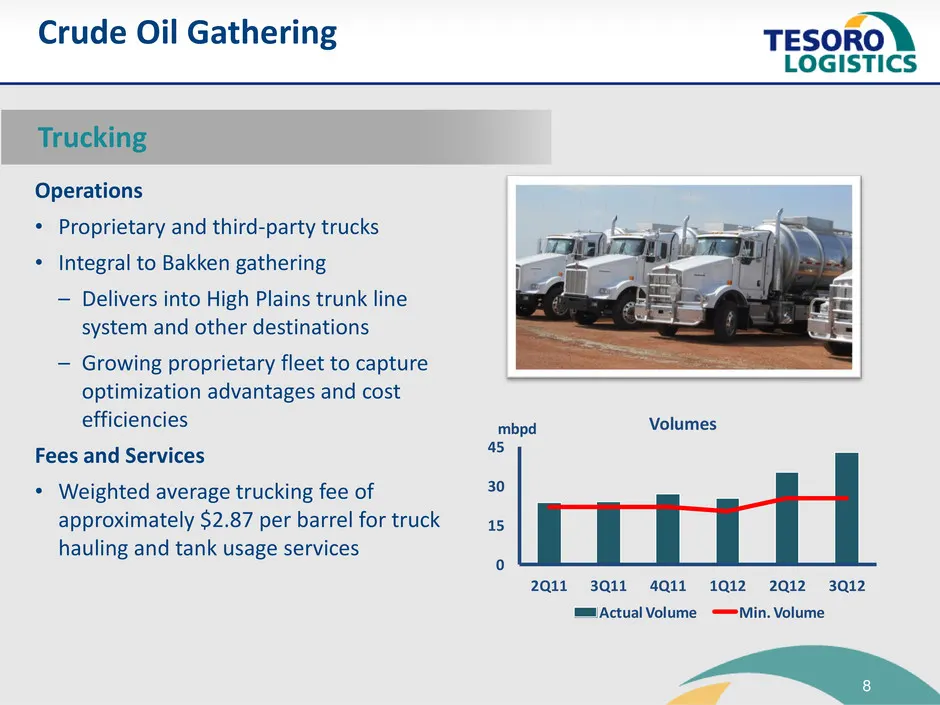
8 Crude Oil Gathering Operations • Proprietary and third-party trucks • Integral to Bakken gathering – Delivers into High Plains trunk line system and other destinations – Growing proprietary fleet to capture optimization advantages and cost efficiencies Fees and Services • Weighted average trucking
Slide 9: High Plains System Growth
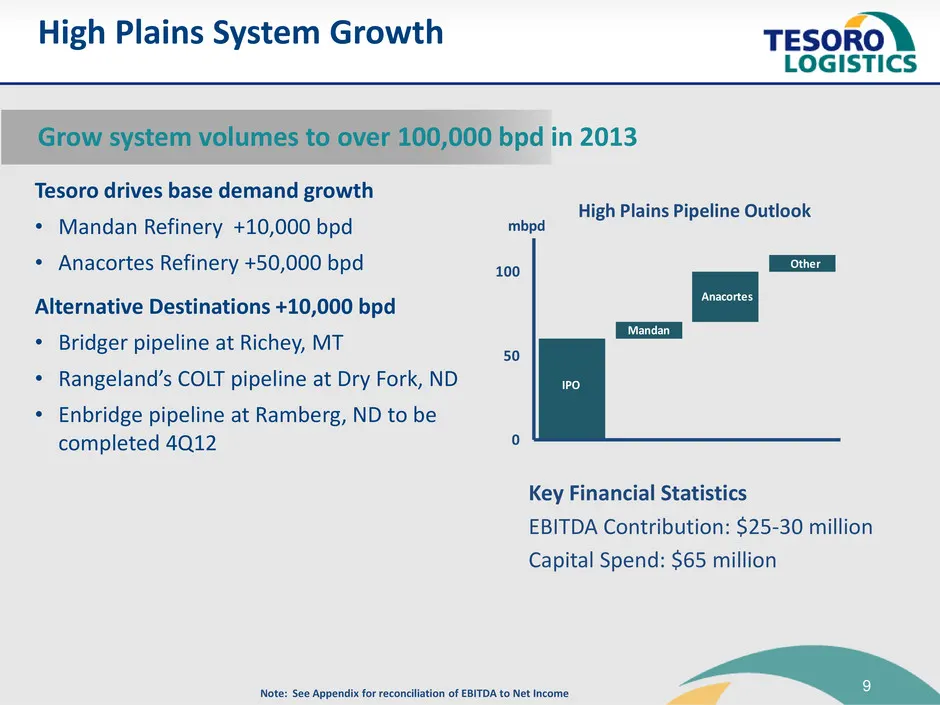
9 High Plains System Growth Tesoro drives base demand growth • Mandan Refinery +10,000 bpd • Anacortes Refinery +50,000 bpd Alternative Destinations +10,000 bpd • Bridger pipeline at Richey, MT • Rangeland’s COLT pipeline at Dry Fork, ND • Enbridge pipeline at Ramberg, ND to be completed 4Q12 Grow s
Slide 10: Terminal Operations
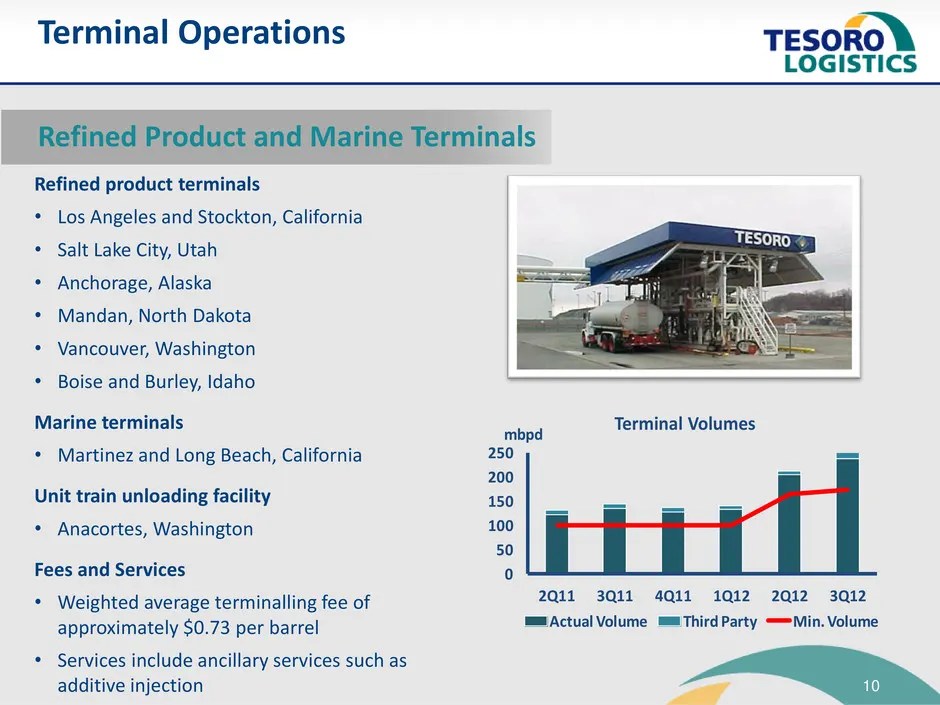
10 Terminal Operations Refined product terminals • Los Angeles and Stockton, California • Salt Lake City, Utah • Anchorage, Alaska • Mandan, North Dakota • Vancouver, Washington • Boise and Burley, Idaho Marine terminals • Martinez and Long Beach, California Unit train unloading facility • Anacortes
Slide 11: Transportation & Storage Facility and Pipelines
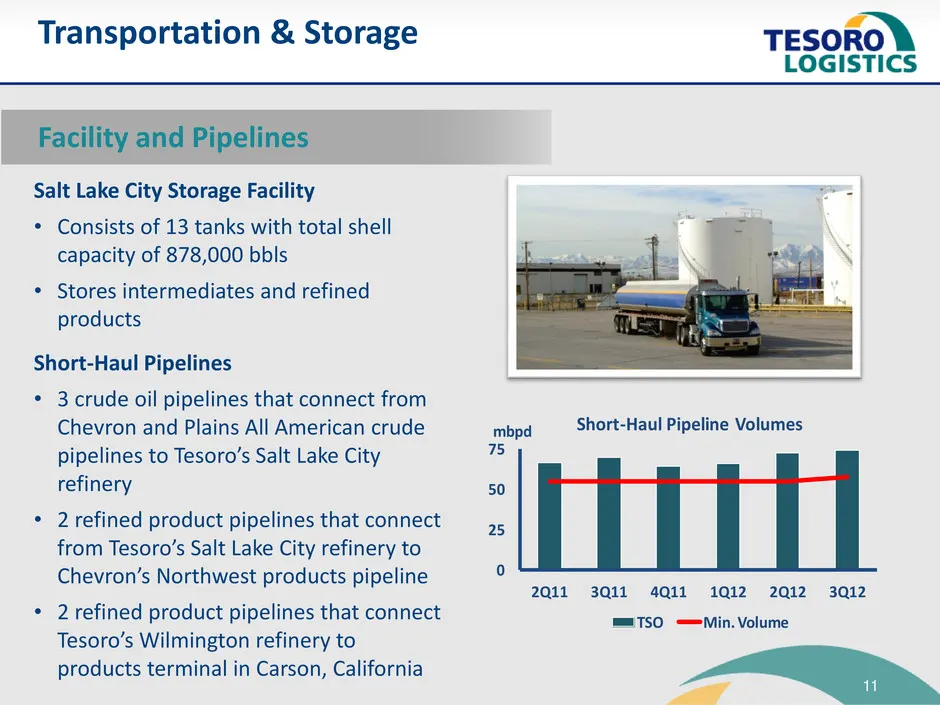
11 Transportation & Storage Facility and Pipelines Salt Lake City Storage Facility • Consists of 13 tanks with total shell capacity of 878,000 bbls • Stores intermediates and refined products Short-Haul Pipelines • 3 crude oil pipelines that connect from Chevron and Plains All American crude pipelin
Slide 12: Terminal Growth
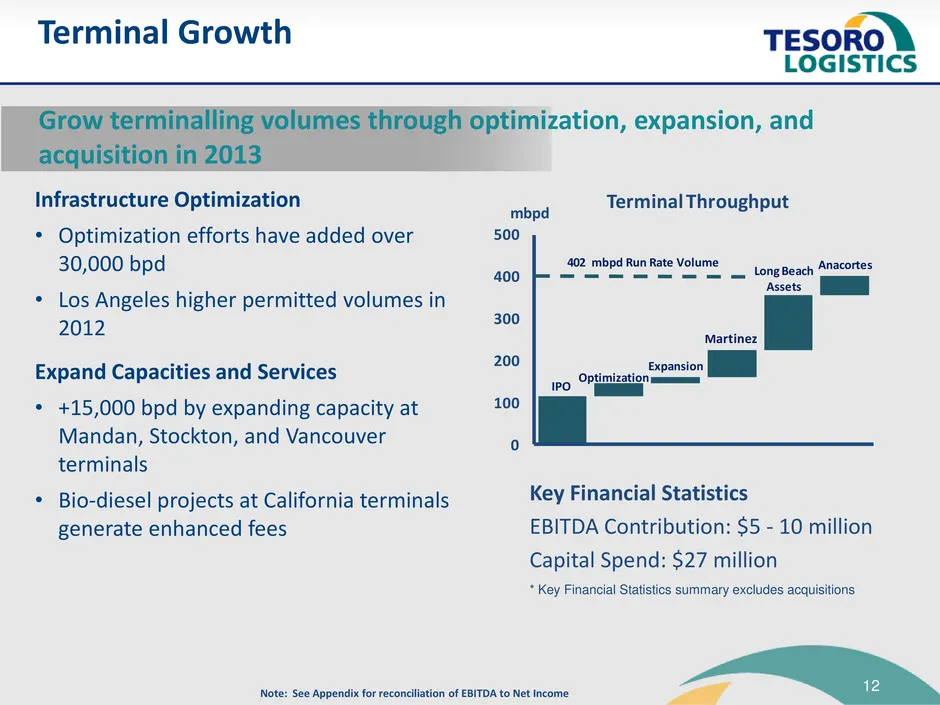
12 Terminal Growth Infrastructure Optimization • Optimization efforts have added over 30,000 bpd • Los Angeles higher permitted volumes in 2012 Expand Capacities and Services • +15,000 bpd by expanding capacity at Mandan, Stockton, and Vancouver terminals • Bio-diesel projects at California terminal
Slide 13: Recently Completed Drop Downs
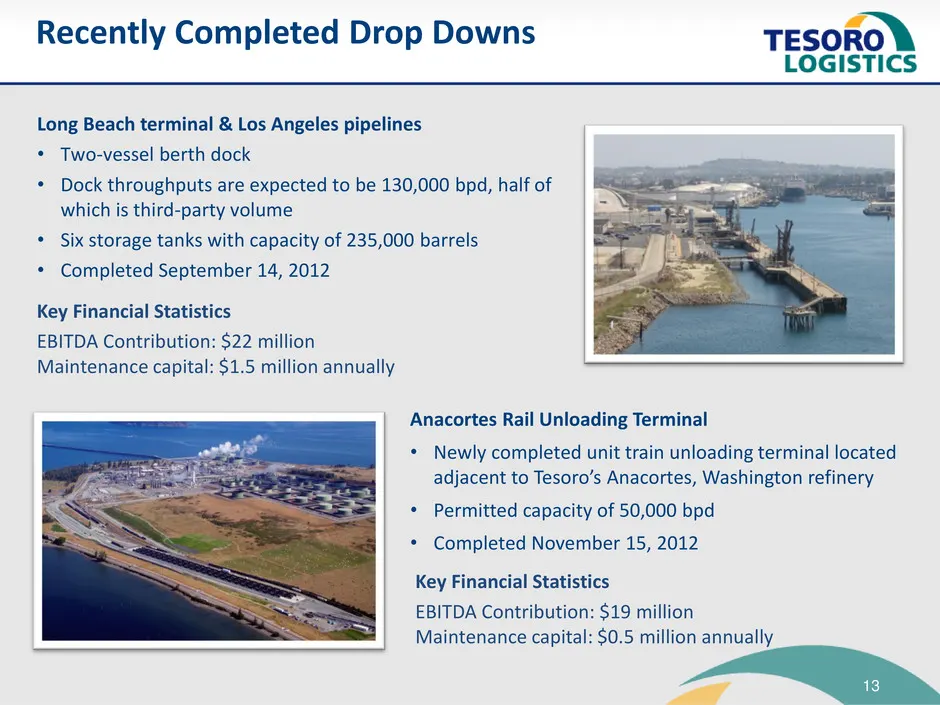
13 Recently Completed Drop Downs Long Beach terminal & Los Angeles pipelines • Two-vessel berth dock • Dock throughputs are expected to be 130,000 bpd, half of which is third-party volume • Six storage tanks with capacity of 235,000 barrels • Completed September 14, 2012 Anacortes Rail Unloading Ter
Slide 14: Tesoro's Acquisition of BP's Southern California Business
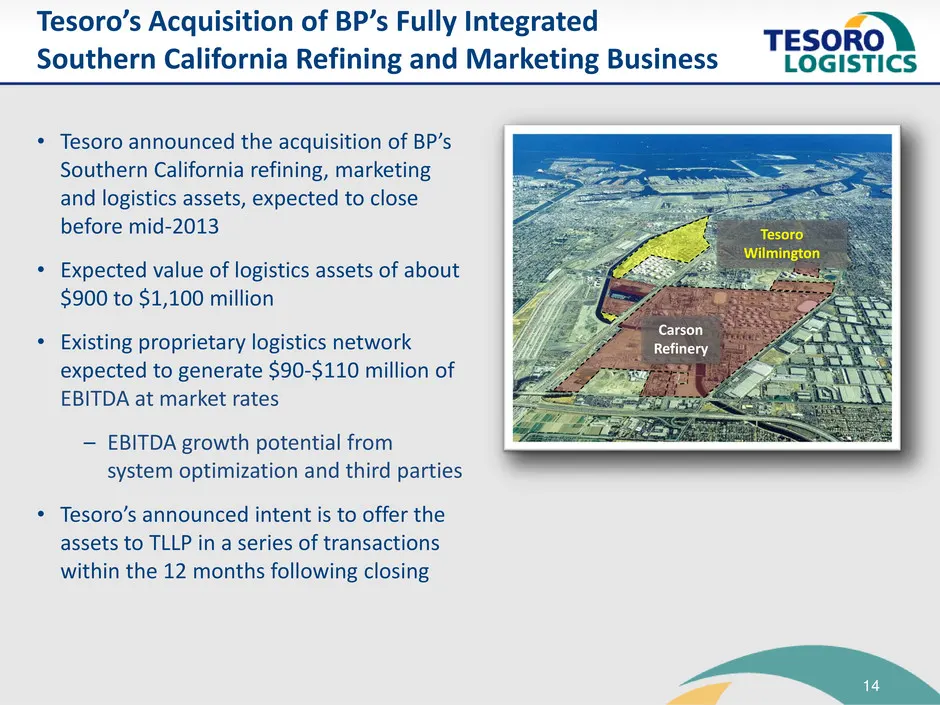
14 • Tesoro announced the acquisition of BP’s Southern California refining, marketing and logistics assets, expected to close before mid-2013 • Expected value of logistics assets of about $900 to $1,100 million • Existing proprietary logistics network expected to generate $90-$110 million of EBITDA
Slide 15: BP Southern California Logistics System
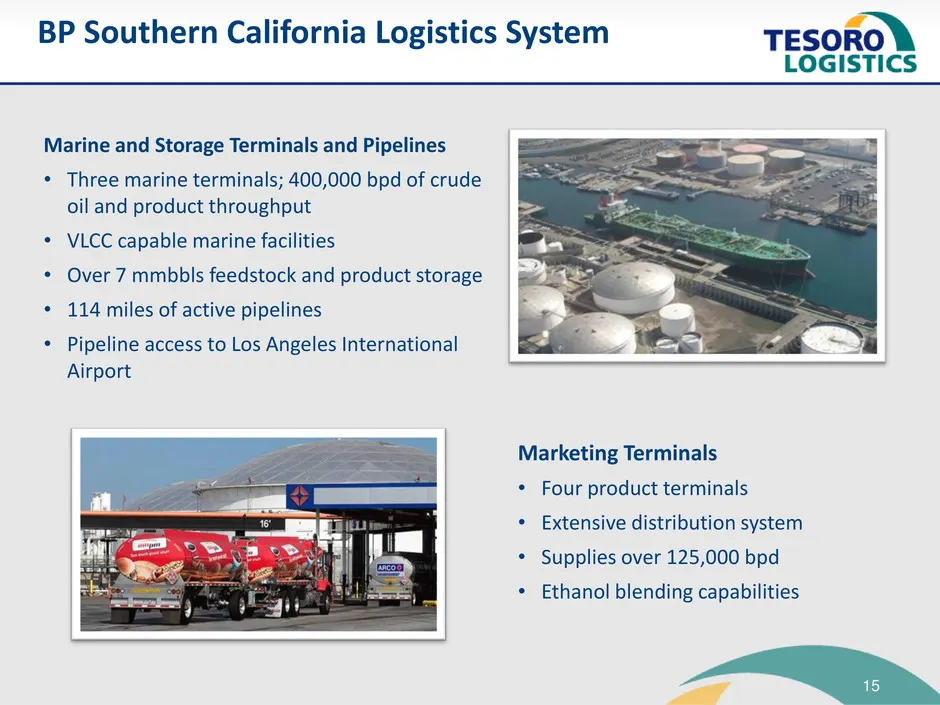
15 Marine and Storage Terminals and Pipelines • Three marine terminals; 400,000 bpd of crude oil and product throughput • VLCC capable marine facilities • Over 7 mmbbls feedstock and product storage • 114 miles of active pipelines • Pipeline access to Los Angeles International Airport Marketing Term
Slide 16: EBITDA Outlook
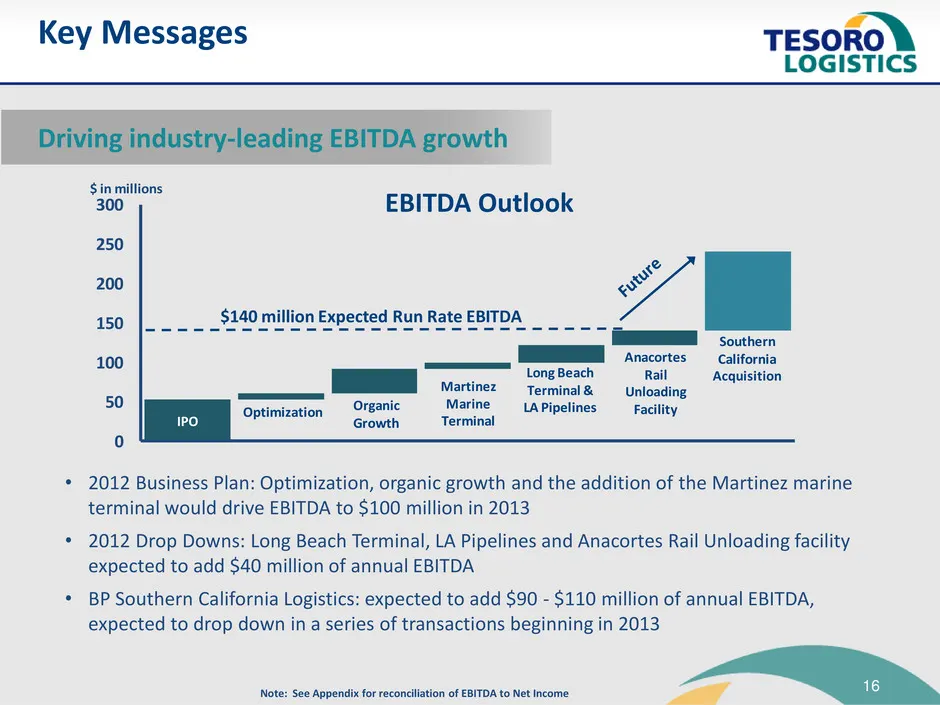
16 IPO 0 50 100 150 200 250 300 Optimization Organic Growth Martinez Marine Terminal Long Beach Terminal & LA Pipelines Anacortes Rail Unloading Facility Southern California Acquisition $ in millions EBITDA Outlook $140 million Expected Run Rate EBITDA Key Messages • 2012 Business Plan: Optimization
Slide 17: Financial Overview
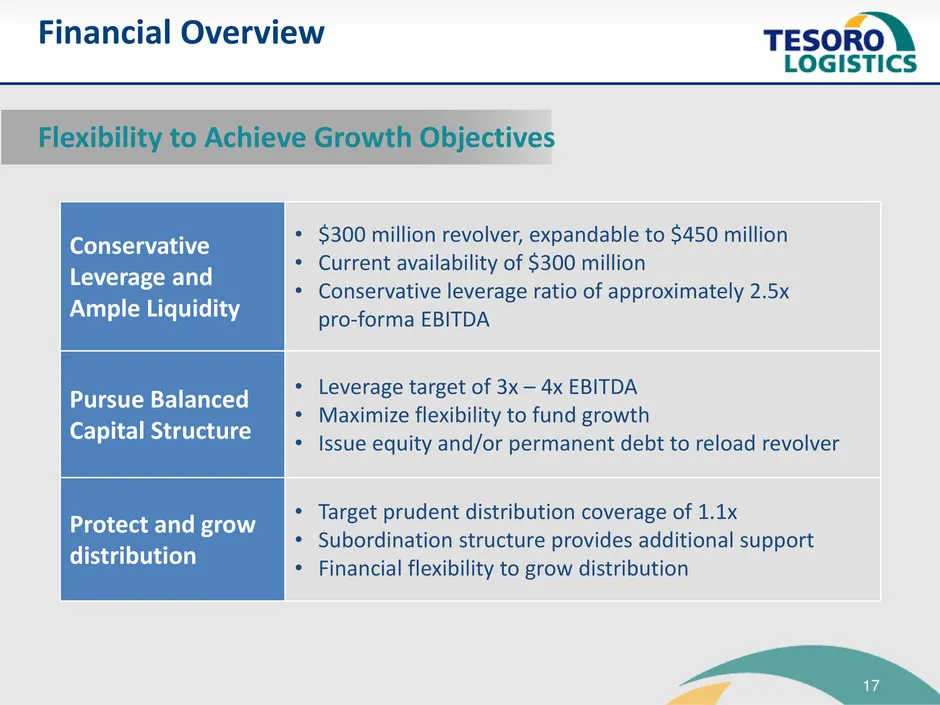
17 Financial Overview Conservative Leverage and Ample Liquidity • $300 million revolver, expandable to $450 million • Current availability of $300 million • Conservative leverage ratio of approximately 2.5x pro-forma EBITDA Pursue Balanced Capital Structure • Leverage target of 3x – 4x EBITDA • Maxi
Slide 18: Appendix
TESOROW LOGISTICS Appendix
Slide 19: Current Acquisition Growth Opportunities
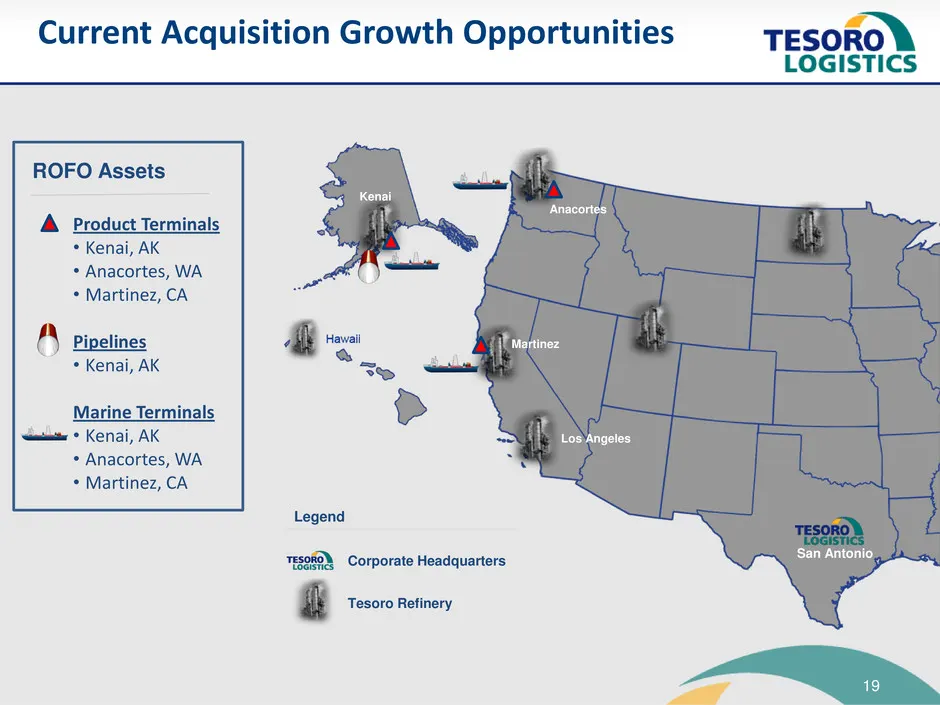
19 Current Acquisition Growth Opportunities Product Terminals • Kenai, AK • Anacortes, WA • Martinez, CA Pipelines • Kenai, AK Marine Terminals • Kenai, AK • Anacortes, WA • Martinez, CA ROFO Assets Legend Corporate Headquarters Tesoro Refinery San Antonio Anacortes Kenai Martinez Los Angeles
Slide 20: EBITDA Definition and Reconciliation
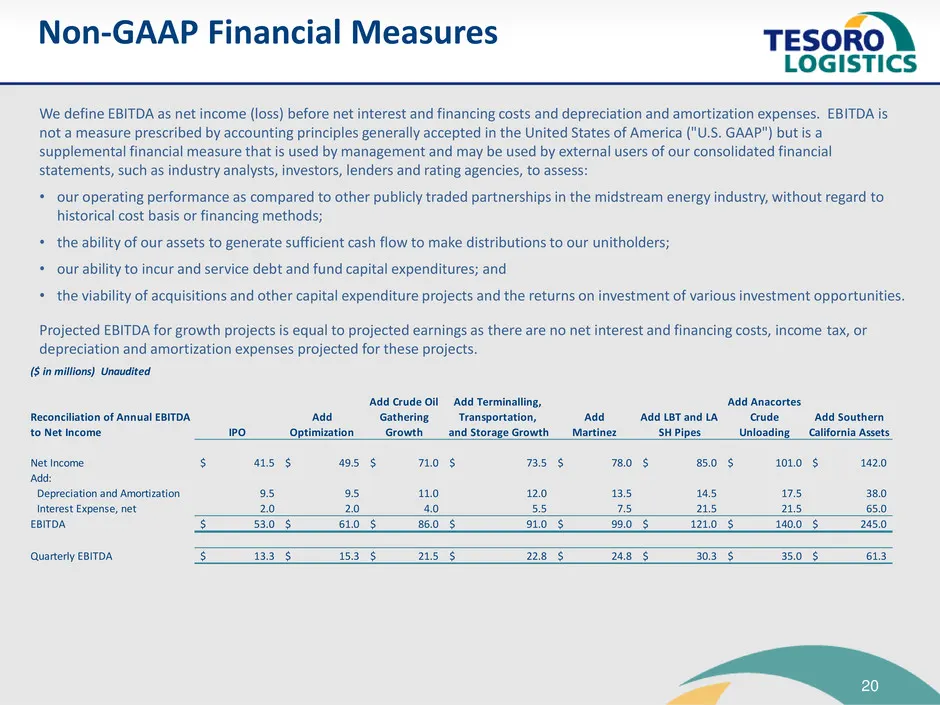
20 We define EBITDA as net income (loss) before net interest and financing costs and depreciation and amortization expenses. EBITDA is not a measure prescribed by accounting principles generally accepted in the United States of America ("U.S. GAAP") but is a supplemental financial measure that is us
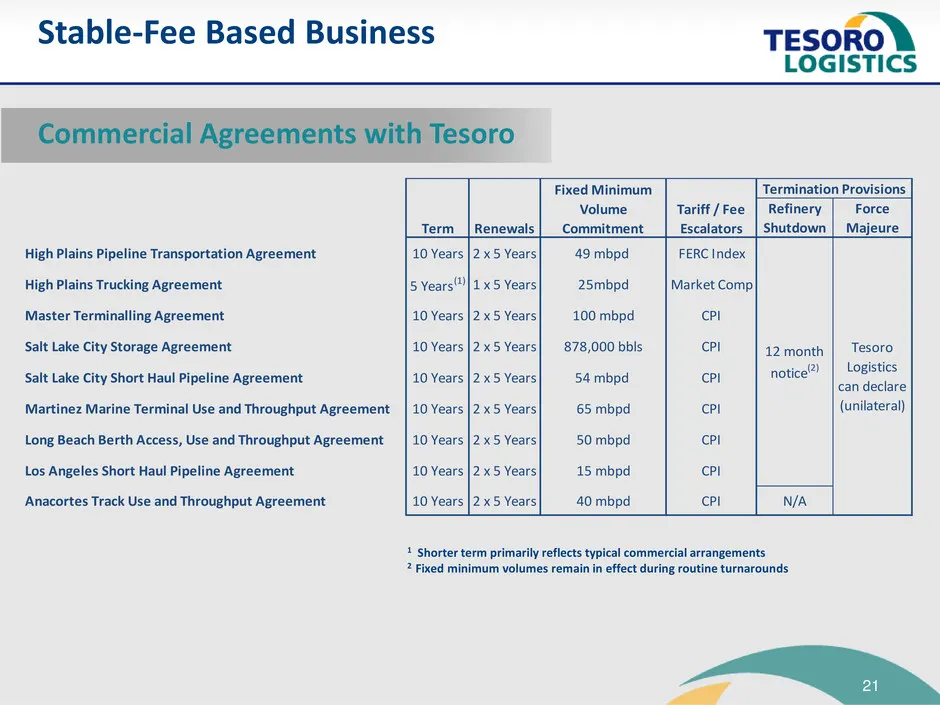
Slide 21: Stable Fee-Based Business
21 Stable-Fee Based Business 1 Shorter term primarily reflects typical commercial arrangements 2 Fixed minimum volumes remain in effect during routine turnarounds Commercial Agreements with Tesoro Refinery Shutdown Force Majeure High Plains Pipeline Transportation Agreement 10 Years 2 x 5 Years 49 m
Source: SEC EDGAR · 8-K filed Nov 15, 2012
More decks from Andeavor Logistics LP
 Merger or Acquisition (June 2019)40 slides · Jun 26, 2019
 Merger or Acquisition (June 2019)60 slides · Jun 3, 2019
 RBN Energy Export Conference 201917 slides · May 21, 2019
 2019 MLP & Energy Infrastructure Conference44 slides · May 15, 2019
 Merger or Acquisition (May 2019)59 slides · May 9, 2019
 Merger or Acquisition (May 2019)28 slides · May 8, 2019