Copano Energy L.L.C — Merger or Acquisition (September 2007)
24 slides from Copano Energy L.L.C's merger presentation, Sep 4, 2007
Slide 1: Acquisition of Cantera Natural Gas, LLC
Copano Energy NASDAQ: CPNO Acquisition of Cantera Natural Gas, LLC September 2007
Slide 2: Disclaimer
Disclaimer Statements made by representatives of Copano Energy, L.L.C. (the "Company") during this presentation may constitute "forward-looking statements" as defined by the Securities and Exchange Commission. All statements, other than statements of historical facts, made by representatives of the
Slide 3: Copano's Business Strategy
Copano's Business Strategy Pursue growth from our existing assets Pursue complementary acquisitions and organic expansion opportunities Reduce sensitivity of our cash flows to commodity price fluctuations Exploit the operating flexibility of our assets Expand our geographic scope into new regions wh
Slide 4: Primary Criteria for Strategic Acquisitions
Primary Criteria for Strategic Acquisitions Highly visible cash flows Long-lived reserves Sustainable drilling programs Franchise quality assets High performance for producers Strong competitive position Low environmental risk Opportunities to apply Copano's business strategy in new regions Organic
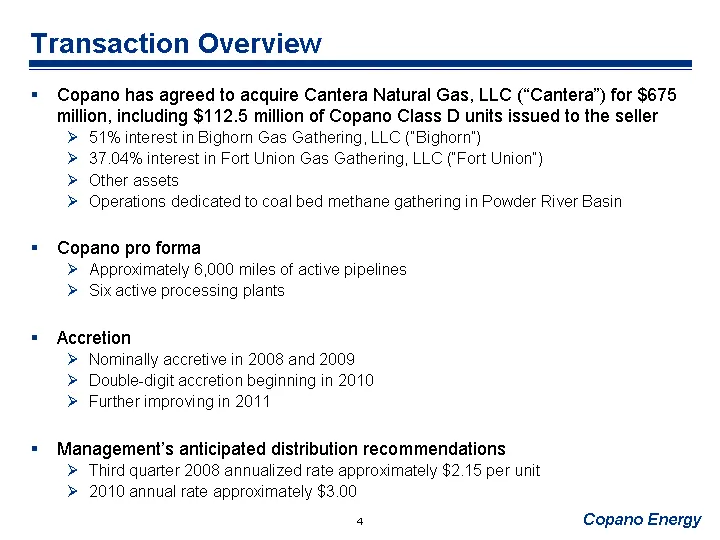
Slide 5: Transaction Overview
Transaction Overview Copano has agreed to acquire Cantera Natural Gas, LLC ("Cantera") for $675 million, including $112.5 million of Copano Class D units issued to the seller 51% interest in Bighorn Gas Gathering, LLC ("Bighorn") 37.04% interest in Fort Union Gas Gathering, LLC ("Fort Union") Other
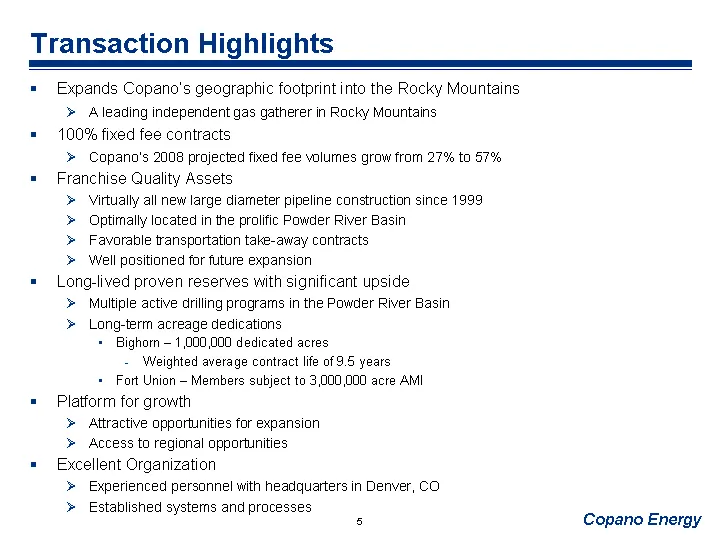
Slide 6: Transaction Highlights
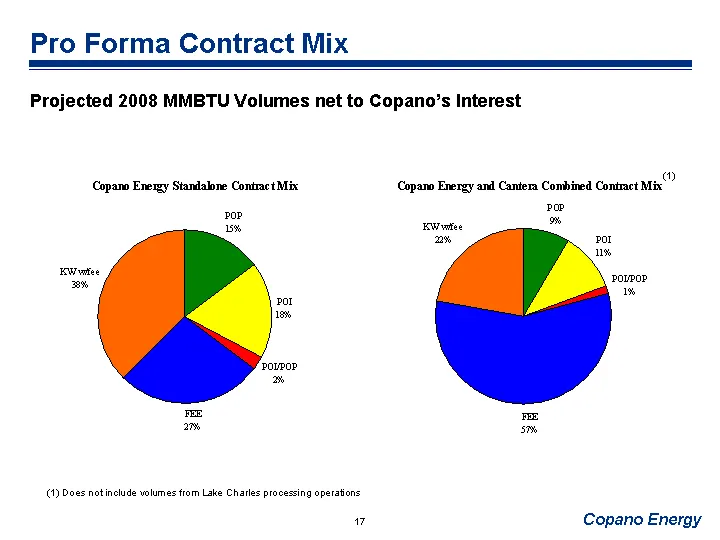
Transaction Highlights Expands Copano's geographic footprint into the Rocky Mountains A leading independent gas gatherer in Rocky Mountains 100% fixed fee contracts Copano's 2008 projected fixed fee volumes grow from 27% to 57% Franchise Quality Assets Virtually all new large diameter pipeline const
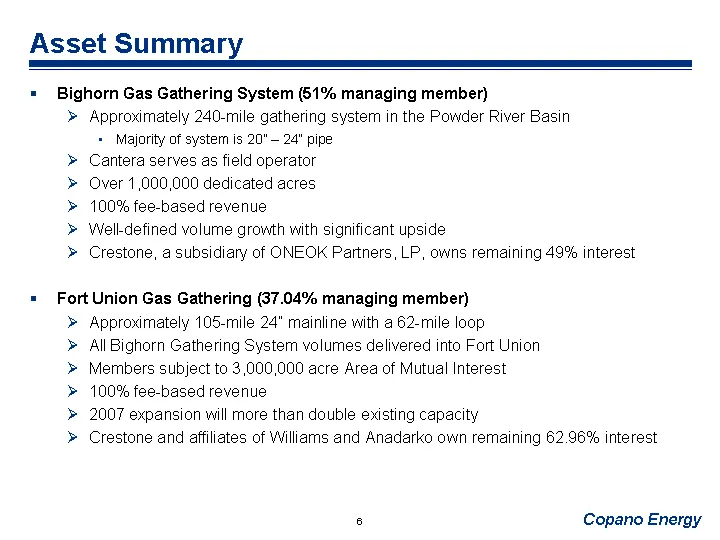
Slide 7: Asset Summary
Asset Summary Bighorn Gas Gathering System (51% managing member) Approximately 240-mile gathering system in the Powder River Basin Majority of system is 20" - 24" pipe Cantera serves as field operator Over 1,000,000 dedicated acres 100% fee-based revenue Well-defined volume growth with significant u
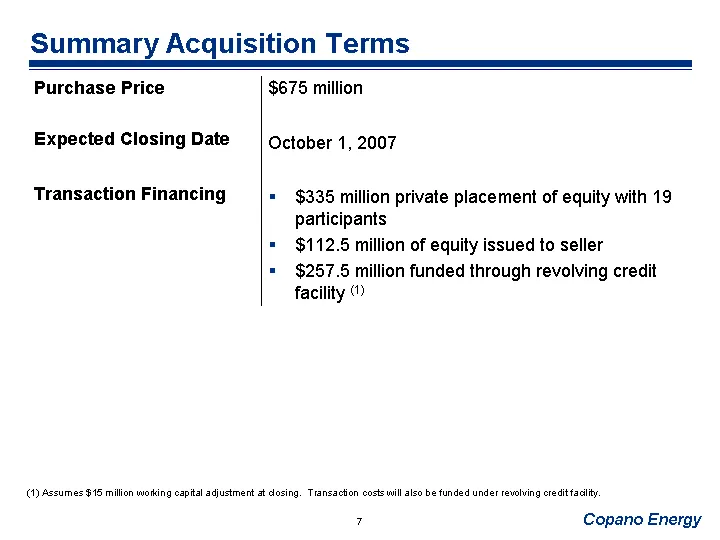
Slide 8: Summary Acquisition Terms
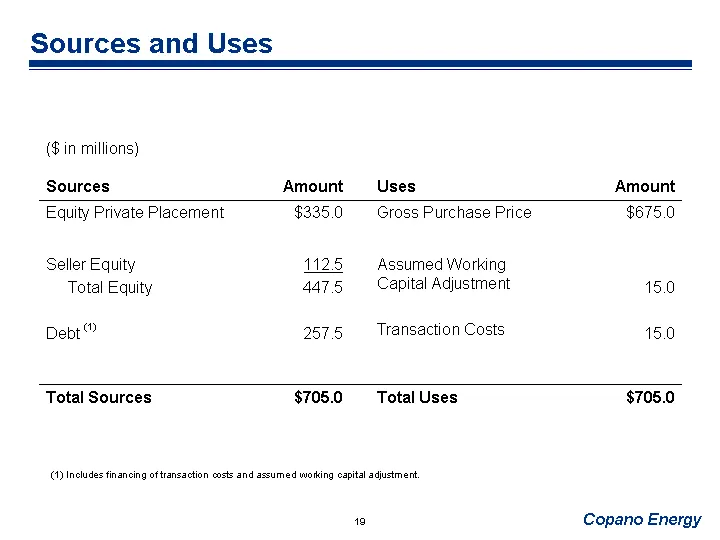
Summary Acquisition Terms Purchase Price $675 million Expected Closing Date October 1, 2007 Transaction Financing $335 million private placement of equity with 19 participants $112.5 million of equity issued to seller $257.5 million funded through revolving credit facility (1) (1) Assumes $15 millio
Slide 9: Cantera Systems
Cantera Systems
Slide 10: Bighorn & Fort Union Overview
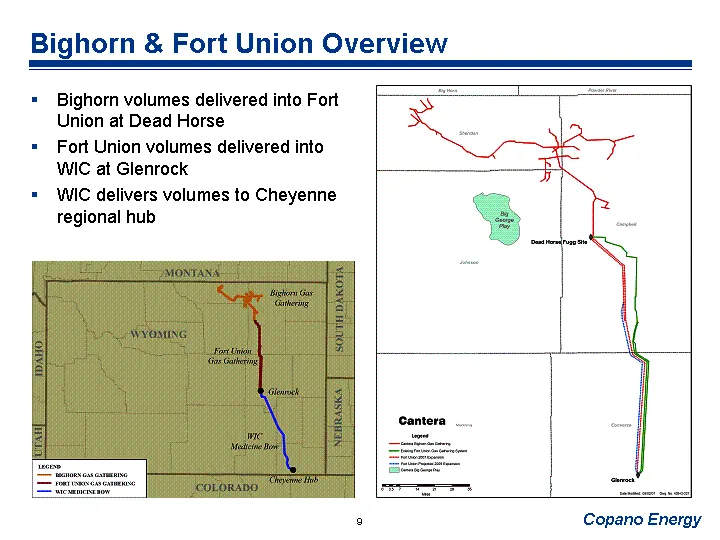
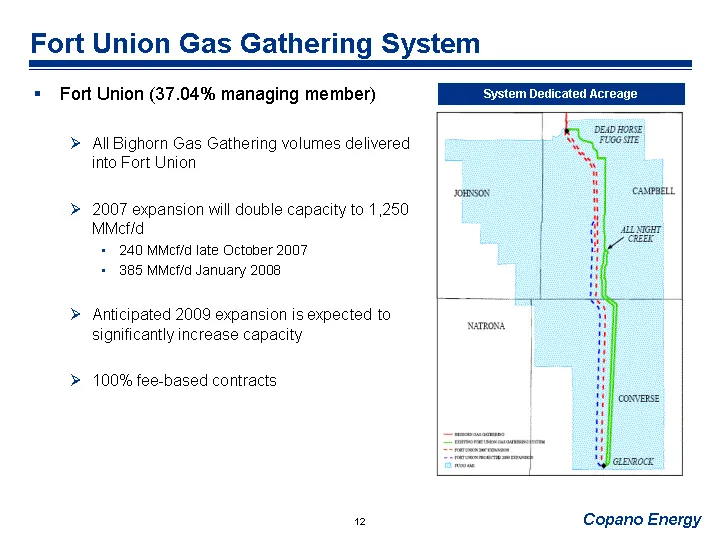
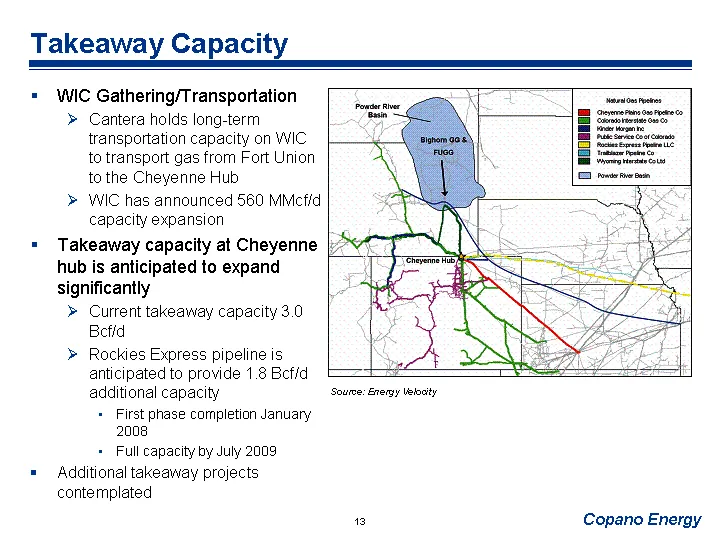
Bighorn & Fort Union Overview Bighorn volumes delivered into Fort Union at Dead Horse Fort Union volumes delivered into WIC at Glenrock WIC delivers volumes to Cheyenne regional hub
Slide 11: Bighorn Gas Gathering
Bighorn Gas Gathering Bighorn (51% managing member and field operator) Located in the largest Coal Bed Methane play in the US (8 of 10 new CBM wells in the U.S. are drilled in this area (1)) Estimated recoverable gas reserves of 20 to 30 TCF (1) Over 1,000,000 dedicated acres under long-term contrac
Slide 12: Bighorn Volume History & Forecast
Bighorn Volume History & Forecast In 2004, almost 800 wells were drilled in the Bighorn area A drilling moratorium in 2005 related to an environmental impact study significantly reduced drilling levels After 2005, drilling activity has returned to 2004 levels and is expected to increase over the nex
Slide 13: Fort Union Gas Gathering System
Fort Union Gas Gathering System Fort Union (37.04% managing member) All Bighorn Gas Gathering volumes delivered into Fort Union 2007 expansion will double capacity to 1,250 MMcf/d 240 MMcf/d late October 2007 385 MMcf/d January 2008 Anticipated 2009 expansion is expected to significantly increase ca
Slide 14: Takeaway Capacity
Takeaway Capacity WIC Gathering/Transportation Cantera holds long-term transportation capacity on WIC to transport gas from Fort Union to the Cheyenne Hub WIC has announced 560 MMcf/d capacity expansion Takeaway capacity at Cheyenne hub is anticipated to expand significantly Current takeaway capacit
Slide 15: Lake Charles Plant
Lake Charles Plant Located in Southwest Louisiana near Lake Charles Contract status Option to process Trunkline's gas on a keep-whole basis Volumes will not be available for processing after summer 2008 as Trunkline is installing its own processing plant at its LNG terminal Copano anticipates moving
Slide 16: Copano Pro Forma for Acquisition
Copano Pro Forma for Acquisition
Slide 17: Copano Pro Forma Assets
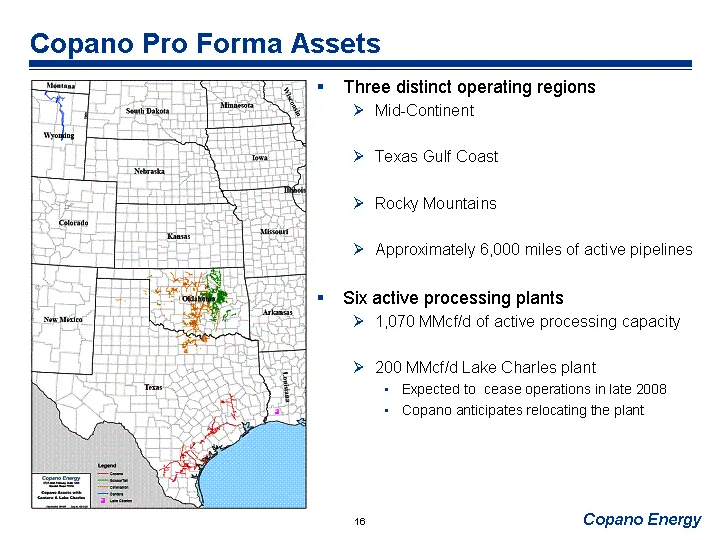
Copano Pro Forma Assets Three distinct operating regions Mid-Continent Texas Gulf Coast Rocky Mountains Approximately 6,000 miles of active pipelines Six active processing plants 1,070 MMcf/d of active processing capacity 200 MMcf/d Lake Charles plant Expected to cease operations in late 2008 Copano
Slide 18: Pro Forma Contract Mix
Pro Forma Contract Mix Projected 2008 MMBTU Volumes net to Copano's Interest (1) Does not include volumes from Lake Charles processing operations (1)
Slide 19: Financial Data
Financial Data
Slide 20: Sources and Uses
Sources and Uses ($ in millions) ($ in millions) Sources Amount Amount Uses Uses Uses Amount Equity Private Placement $335.0 $335.0 Gross Purchase Price Gross Purchase Price $675.0 $675.0 Seller Equity Total Equity Debt 112.5 447.5 257.5 112.5 447.5 257.5 Assumed Working Capital Adjustment Transacti
Slide 21: Pro Forma Capitalization
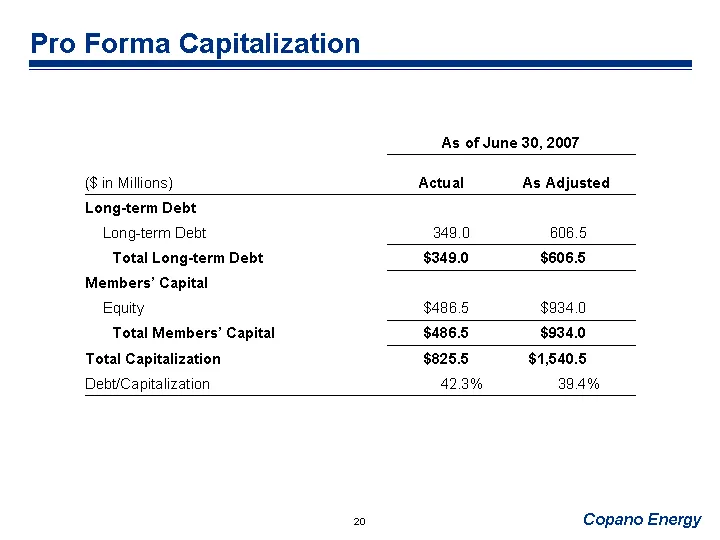
Pro Forma Capitalization As of June 30, 2007 As of June 30, 2007 ($ in Millions) Actual As Adjusted Long-term Debt Long-term Debt 349.0 606.5 Total Long-term Debt $349.0 $606.5 Members' Capital Equity $486.5 $934.0 Total Members' Capital $486.5 $934.0 Total Capitalization $825.5 $1,540.5 Debt/Capita
Slide 22: Projected Financial Outlook
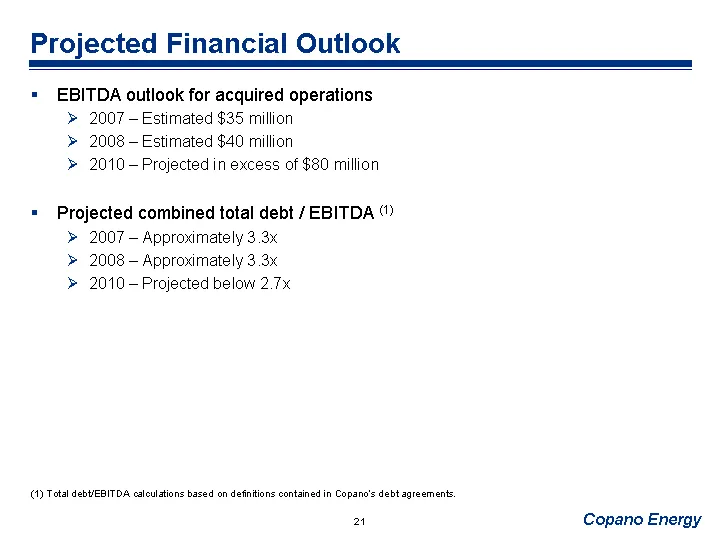
Projected Financial Outlook EBITDA outlook for acquired operations 2007 - Estimated $35 million 2008 - Estimated $40 million 2010 - Projected in excess of $80 million Projected combined total debt / EBITDA (1) 2007 - Approximately 3.3x 2008 - Approximately 3.3x 2010 - Projected below 2.7x (1) Total
Slide 23: Transaction Highlights
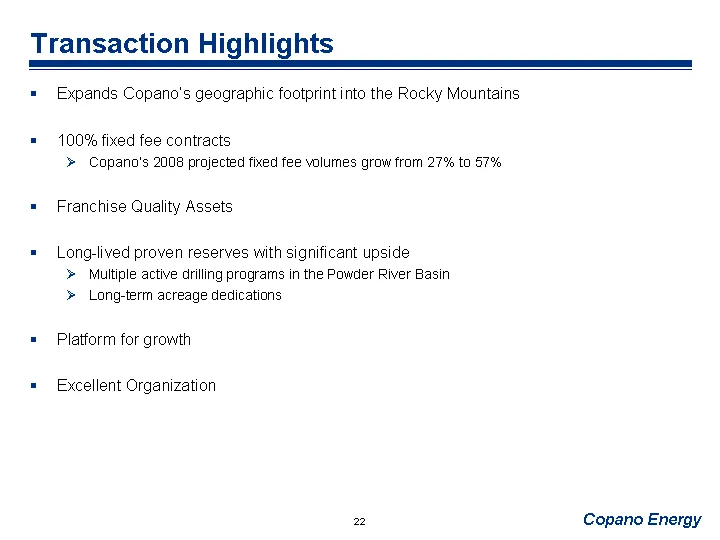
Transaction Highlights Expands Copano's geographic footprint into the Rocky Mountains 100% fixed fee contracts Copano's 2008 projected fixed fee volumes grow from 27% to 57% Franchise Quality Assets Long-lived proven reserves with significant upside Multiple active drilling programs in the Powder Ri
Slide 24: Copano Energy
Copano Energy NASDAQ: CPNO
Source: SEC EDGAR · 8-K filed Sep 4, 2007
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011