Transatlantic — Merger or Acquisition (August 2011)
36 slides from Transatlantic's merger presentation, Aug 4, 2011
Slide 1: Greater Current and Long-Term Value for Shareholders: Building a Global Reinsurance Leader
Greater Current and Long-Term Value for Shareholders August 2011 Building a Global Reinsurance Leader FILED BY VALIDUS HOLDINGS, LTD. PURSUANT TO RULE 425 UNDER THE SECURITIES ACT OF 1933 AND DEEMED FILED PURSUANT TO RULE 14a-12 UNDER THE SECURITIES EXCHANGE ACT OF 1934 SUBJECT COMPANY: TRANSATLANTI
Slide 2: Cautionary Note Regarding Forward-looking Statements
Cautionary Note Regarding Forward-looking Statements This presentation may include forward-looking statements, both with respect to Validus and its industry, that reflect Validus' current views with respect to future events and financial performance. Statements that include the words "expect," "inte
Slide 3: Additional Information and Participants in the Solicitation
Additional Information and Participants in the Solicitation Additional Information about the Proposed Transaction and Where to Find It: This presentation relates to the Exchange Offer by Validus to exchange each issued and outstanding share of common stock of Transatlantic for 1.5564 Validus voting
Slide 4: Note on Non-GAAP Financial Measures
Note on Non-GAAP Financial Measures In presenting the Company’s results herein, management has included and discussed certain schedules containing underwriting income, net operating income (loss), annualized return on average equity and diluted book value per common share that are not calculated und
Slide 5: Validus, From Formation to Today: A Case Study in Value Creation
Validus, From Formation to Today A Case Study in Value Creation
Slide 6: Validus, From Formation to Today: A Case Study in Value Creation
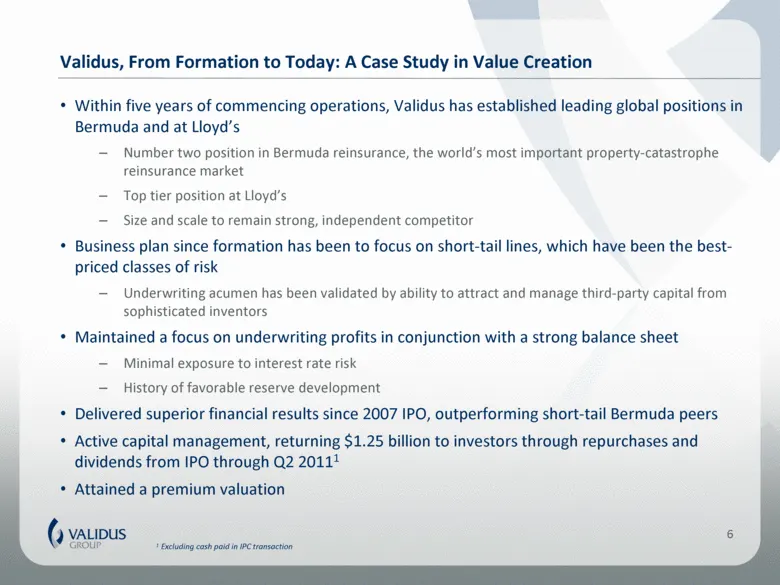
Validus, From Formation to Today: A Case Study in Value Creation Within five years of commencing operations, Validus has established leading global positions in Bermuda and at Lloyd’s Number two position in Bermuda reinsurance, the world’s most important property-catastrophe reinsurance market Top t
Slide 7: Bermuda and Lloyd's Each Generate $1bn in Short-Tail Business for Validus
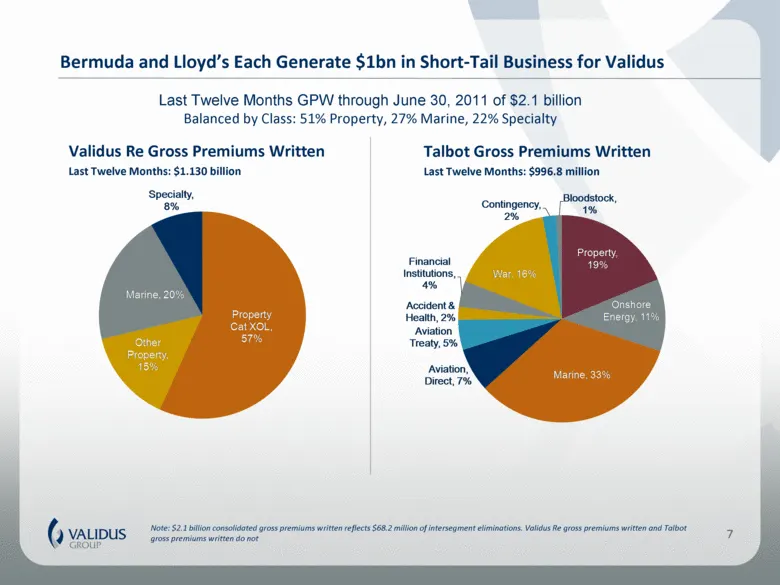
Bermuda and Lloyd’s Each Generate $1bn in Short-Tail Business for Validus 7 Last Twelve Months GPW through June 30, 2011 of $2.1 billion Balanced by Class: 51% Property, 27% Marine, 22% Specialty Validus Re Gross Premiums Written Last Twelve Months: $1.130 billion Talbot Gross Premiums Written Last
Slide 8: Each of Validus' Operating Segments is a Leader in its Markets
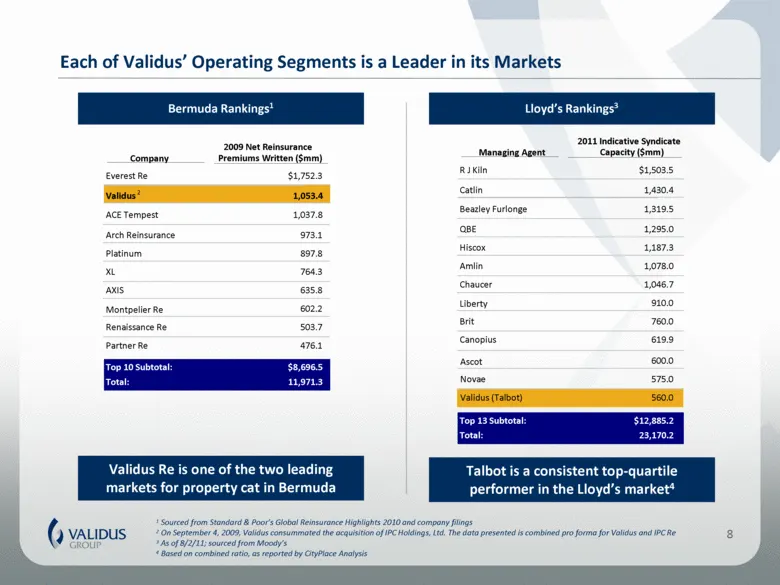
Each of Validus’ Operating Segments is a Leader in its Markets 8 Bermuda Rankings1 Company 2009 Net Reinsurance Premiums Written ($mm) Everest Re $1,752.3 Validus 1,053.4 Arch Reinsurance 973.1 Platinum 897.8 XL 764.3 AXIS 635.8 Montpelier Re 2 602.2 Renaissance Re 503.7 Partner Re 476.1 Top 10 Subt
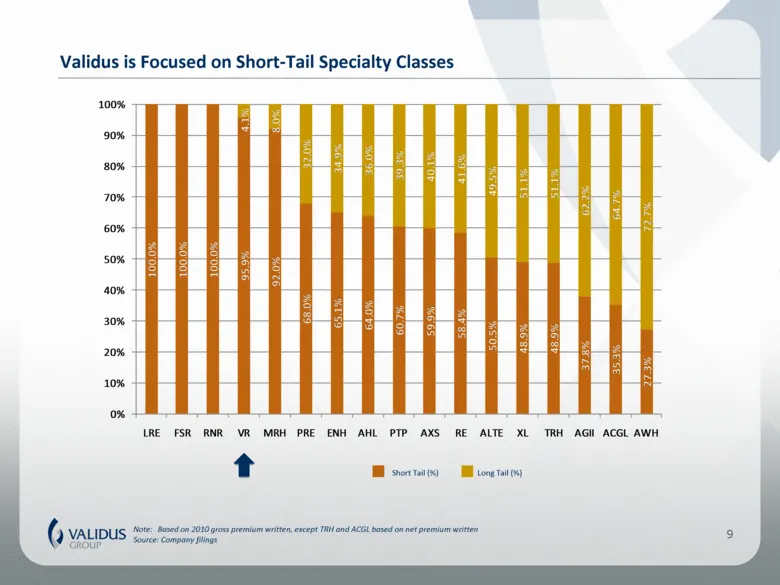
Slide 9: Validus is Focused on Short-Tail Specialty Classes
Validus is Focused on Short-Tail Specialty Classes 9 Short Tail (%) Long Tail (%) Note: Based on 2010 gross premium written, except TRH and ACGL based on net premium written Source: Company filings 100.0% 100.0% 100.0% 95.9% 92.0% 68.0% 65.1% 64.0% 60.7% 59.9% 58.4% 50.5% 48.9% 48.9% 37.8% 35.3% 27.
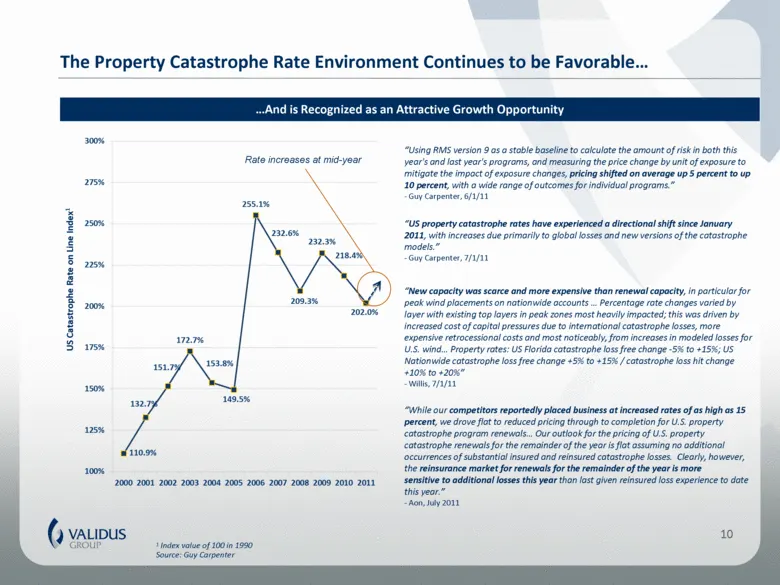
Slide 10: The Property Catastrophe Rate Environment Continues to be Favorable
The Property Catastrophe Rate Environment Continues to be Favorable... 10 1 Index value of 100 in 1990 Source: Guy Carpenter And is Recognized as an Attractive Growth Opportunity... “Using RMS version 9 as a stable baseline to calculate the amount of risk in both this year's and last year's programs
Slide 11: Strength of Validus' Underwriting Franchise Validated by Sophisticated Third Parties
Strength of Validus’ Underwriting Franchise Validated by Sophisticated Third Parties 2006: Petrel Re Formed in May 2006 $200 million facility for marine and energy risks 75% quota share of certain marine and offshore energy reinsurance contracts underwritten by Validus Re for 2006 and 2007 underwrit
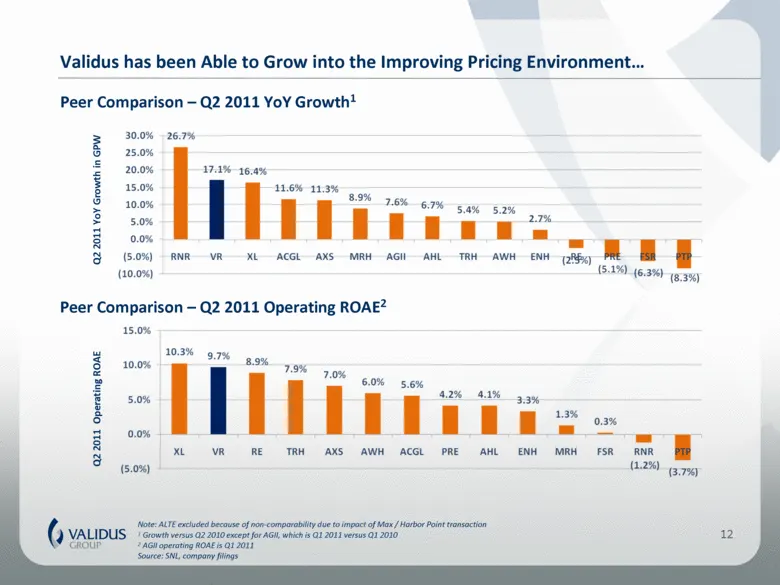
Slide 12: Validus has been Able to Grow into the Improving Pricing Environment
Validus has been Able to Grow into the Improving Pricing Environment Peer Comparison – Q2 2011 YoY Growth1 12 Q2 2011 YoY Growth in GPW Note: ALTE excluded because of non-comparability due to impact of Max / Harbor Point transaction 1 Growth versus Q2 2010 except for AGII, which is Q1 2011 versus Q1
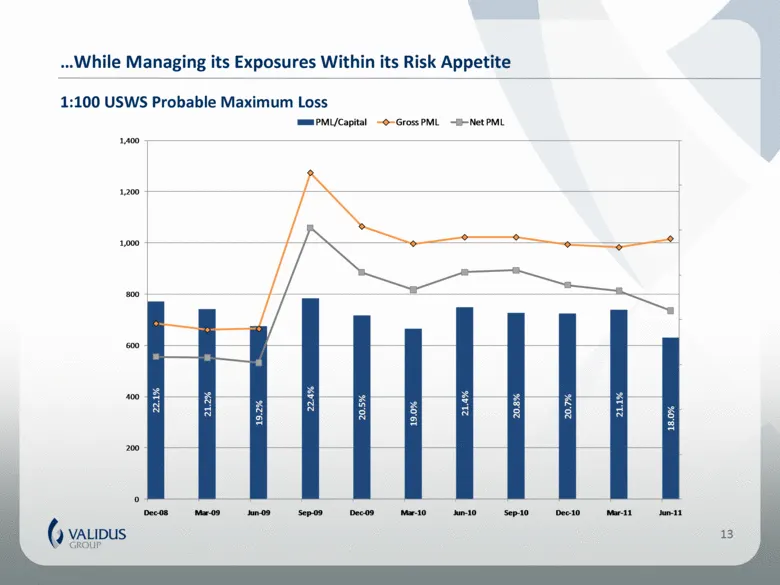
Slide 13: While Managing its Exposures Within its Risk Appetite
While Managing its Exposures Within its Risk Appetite 13 1:100 USWS Probable Maximum Loss 22.1% 21.2% 19.2% 22.4% 20.5% 19.0% 21.4% 20.8% 20.7% 21.1% 18.0% 0 200 400 600 800 1,000 1,200 1,400 Dec-08 Mar-09 Jun-09 Sep-09 Dec-09 Mar-10 Jun-10 Sep-10 Dec-10 Mar-11 Jun-11 PML/Capital Gross PML Net PML
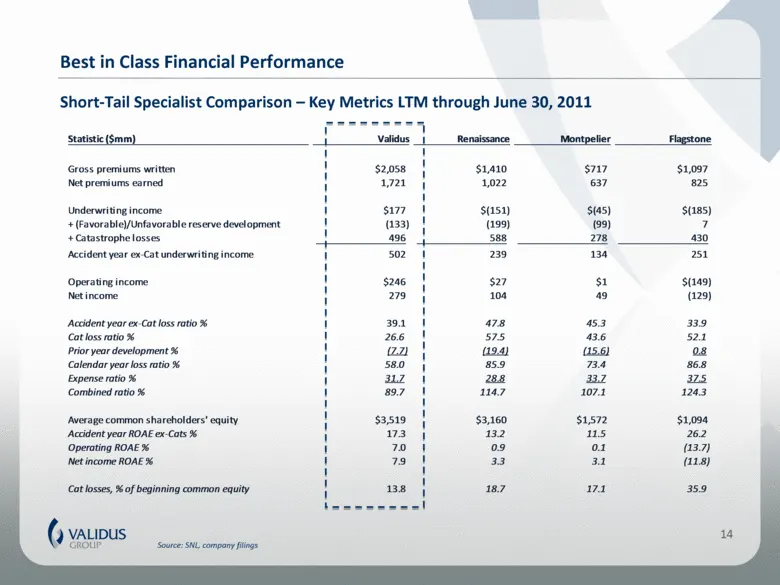
Slide 14: Best in Class Financial Performance
Best in Class Financial Performance Short-Tail Specialist Comparison – Key Metrics LTM through June 30, 2011 14 Source: SNL, company filings Statistic ($mm) Validus Renaissance Montpelier Flagstone Gross premiums written $2,058 $1,410 $717 $1,097 Net premiums earned 1,721 1,022 637 825 Underwriting
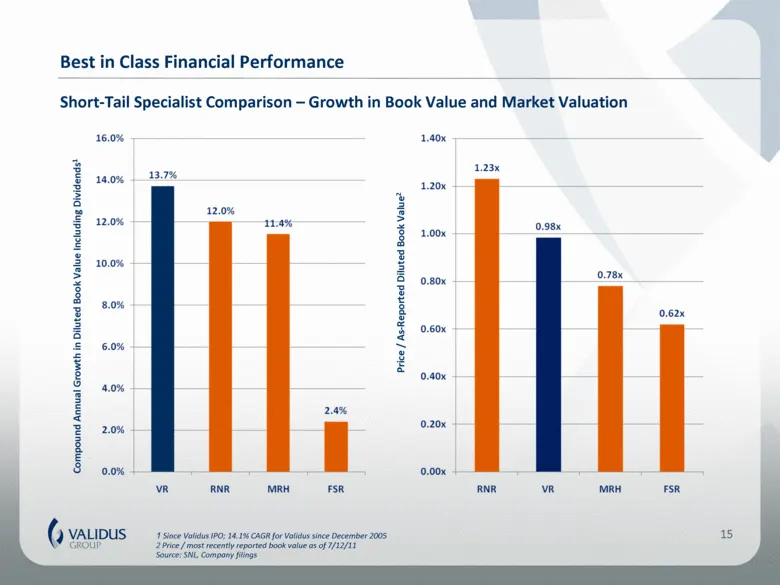
Slide 15: Short-Tail Specialist Comparison – Growth in Book Value and Market Valuation
Short-Tail Specialist Comparison – Growth in Book Value and Market Valuation 15 1 Since Validus IPO; 14.1% CAGR for Validus since December 2005 2 Price / most recently reported book value as of 7/12/11 Source: SNL, Company filings Compound Annual Growth in Diluted Book Value Including Dividends1 Pri
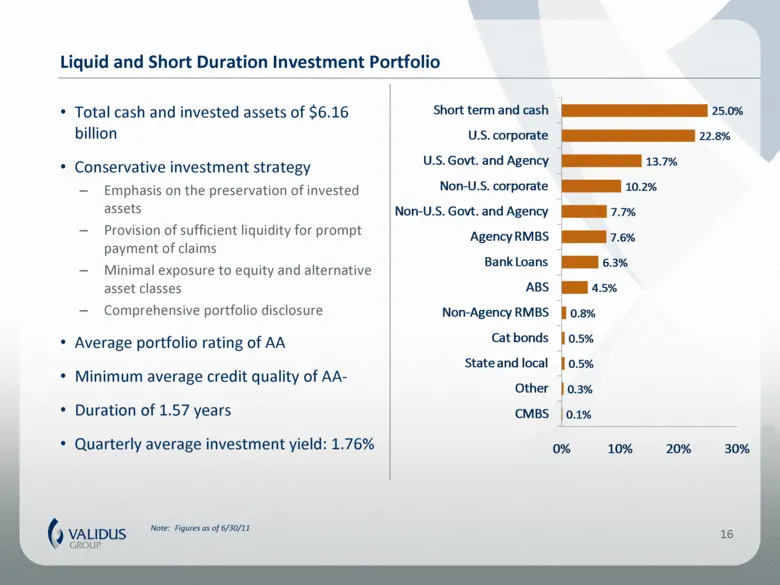
Slide 16: Liquid and Short Duration Investment Portfolio
Liquid and Short Duration Investment Portfolio Total cash and invested assets of $6.16 billion Conservative investment strategy Emphasis on the preservation of invested assets Provision of sufficient liquidity for prompt payment of claims Minimal exposure to equity and alternative asset classes Comp
Slide 17: Investment Leverage vs. Peers
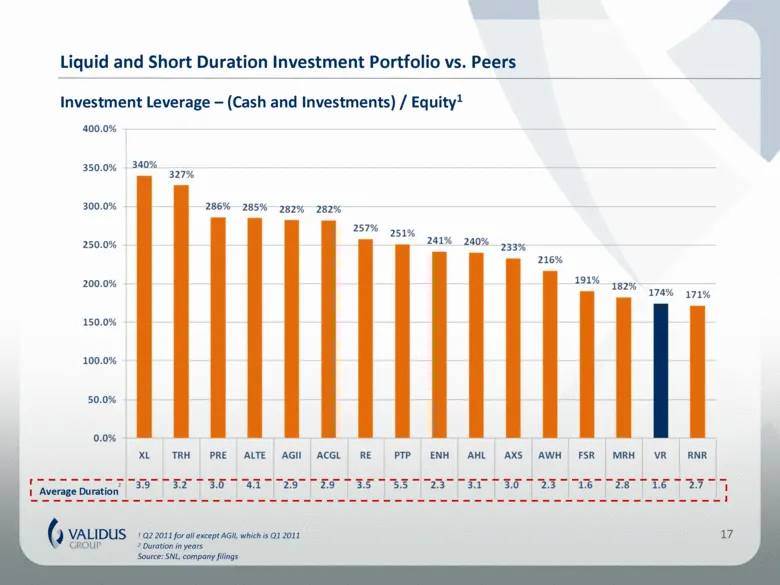
Investment Leverage – (Cash and Investments) / Equity1 17 Liquid and Short Duration Investment Portfolio vs. Peers 1 Q2 2011 for all except AGII, which is Q1 2011 2 Duration in years Source: SNL, company filings Average Duration 2
Slide 18: Loss Reserves at June 30, 2011
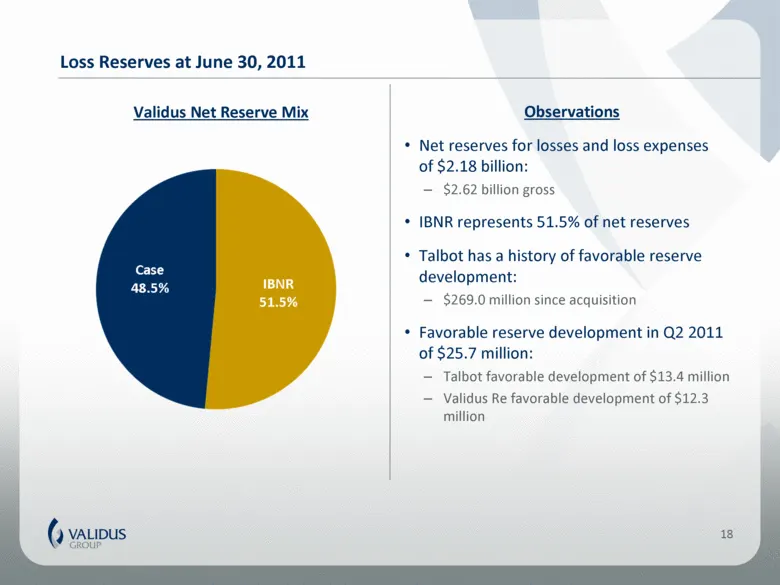
Loss Reserves at June 30, 2011 Validus Net Reserve Mix Observations Net reserves for losses and loss expenses of $2.18 billion: $2.62 billion gross IBNR represents 51.5% of net reserves Talbot has a history of favorable reserve development: $269.0 million since acquisition Favorable reserve developm
Slide 19: Active Capital Management - Rationalizing Capacity and Returning Capital
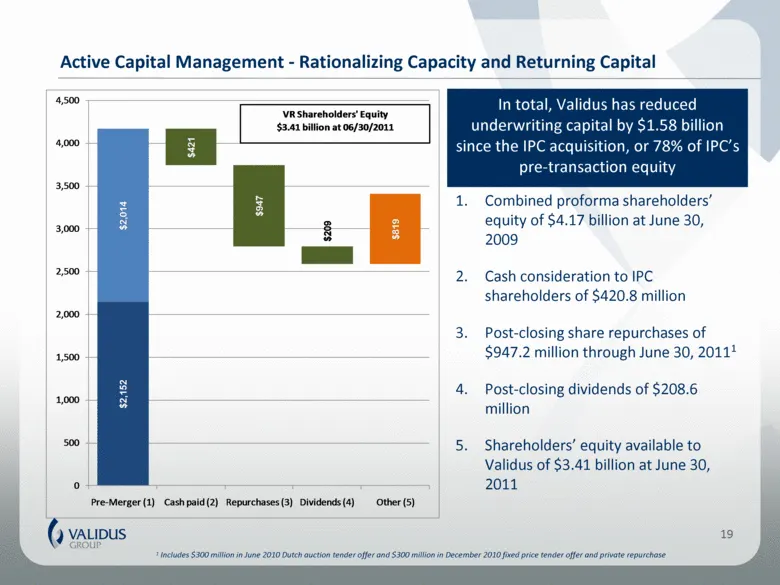
Active Capital Management - Rationalizing Capacity and Returning Capital Combined proforma shareholders’ equity of $4.17 billion at June 30, 2009 Cash consideration to IPC shareholders of $420.8 million Post-closing share repurchases of $947.2 million through June 30, 20111 Post-closing dividends of
Slide 20: Validus has Attained a Premium Valuation Over the Long Term
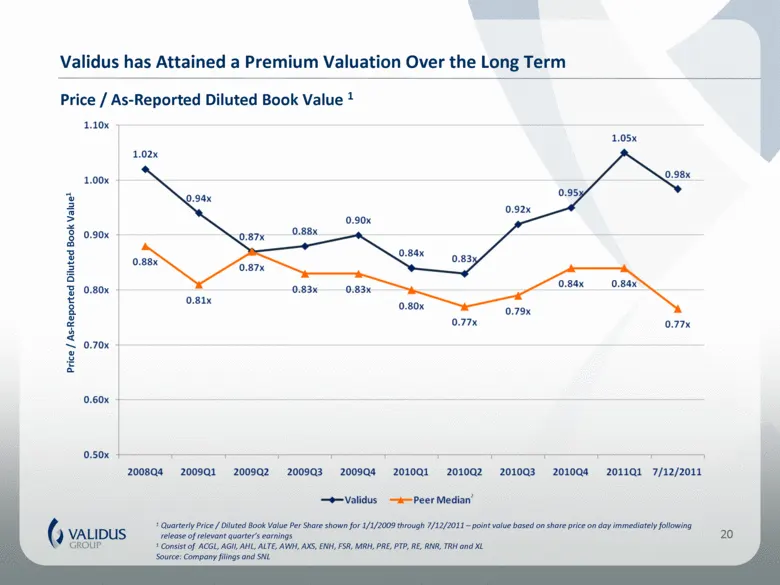
Validus has Attained a Premium Valuation Over the Long Term 1 Quarterly Price / Diluted Book Value Per Share shown for 1/1/2009 through 7/12/2011 – point value based on share price on day immediately following release of relevant quarter’s earnings 1 Consist of ACGL, AGII, AHL, ALTE, AWH, AXS, ENH,
Slide 21: Creating a Global Reinsurance Leader with a Clear Business Plan
Creating a Global Reinsurance Leader with a Clear Business Plan Greater Current and Long-Term Value for Transatlantic Stockholders
Slide 22: Compelling Post-Combination Business Plan, Driving Long-Term Value
Compelling Post-Combination Business Plan, Driving Long-Term Value Combined company will be a global, committed leader in reinsurance1 Maximize underwriting profitability to achieve superior growth in book value per share Short-tail reinsurance lines are the core of Validus' current strategy Best pr
Slide 23: Post-Combination Brand, Management and Governance
Post-Combination Brand, Management and Governance Historically, Transatlantic did not develop operations in Bermuda or at Lloyd’s, which are natural extensions of Transatlantic’s worldwide reinsurance franchise Validus brings leading positions in each market, through our Validus Re and Talbot subsid
Slide 24: Post-Transaction, Validus would be in the Top Six Reinsurance Companies Worldwide
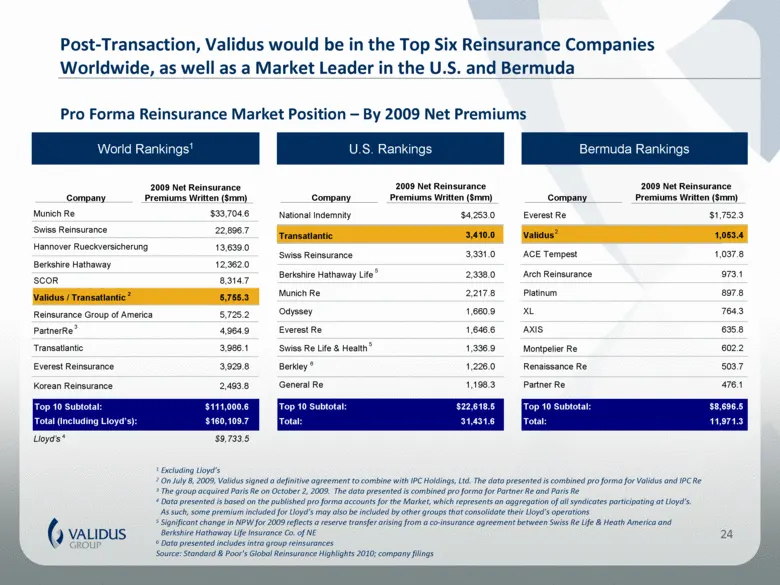
Post-Transaction, Validus would be in the Top Six Reinsurance Companies Worldwide, as well as a Market Leader in the U.S. and Bermuda Pro Forma Reinsurance Market Position – By 2009 Net Premiums U.S. Rankings Company 2009 Net Reinsurance Premiums Written ($mm) Berkshire Hathaway Life National Indemn
Slide 25: Bermuda and Reinsurance Peer Group – By Capitalization
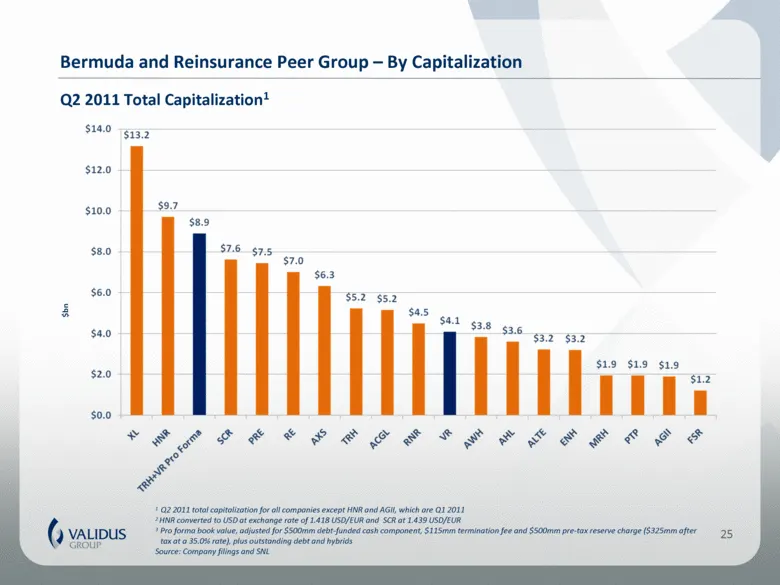
Bermuda and Reinsurance Peer Group – By Capitalization 25 $bn 3 Q2 2011 Total Capitalization1 2 2 1 Q2 2011 total capitalization for all companies except HNR and AGII, which are Q1 2011 2 HNR converted to USD at exchange rate of 1.418 USD/EUR and SCR at 1.439 USD/EUR 3 Pro forma book value, adjusted
Slide 26: Validus' Leadership in Property Cat will be Further Enhanced
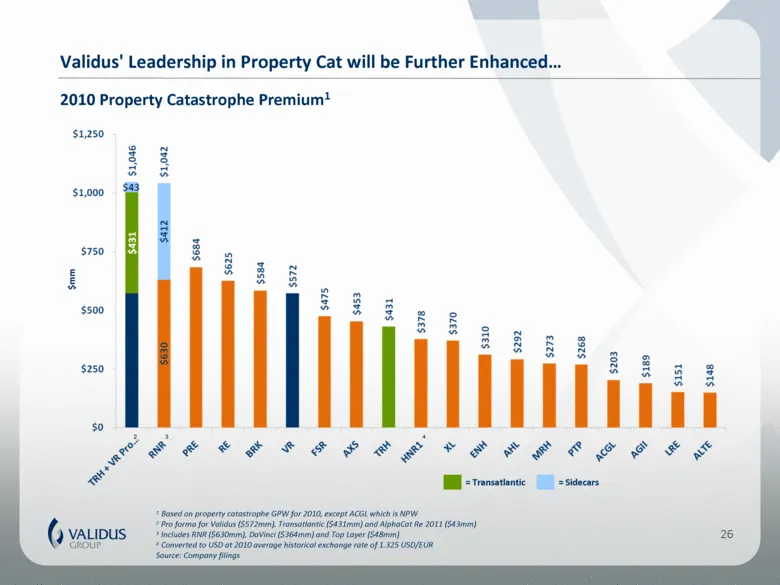
Validus' Leadership in Property Cat will be Further Enhanced... 26 3 $mm 2 2010 Property Catastrophe Premium1 4 1 Based on property catastrophe GPW for 2010, except ACGL which is NPW 2 Pro forma for Validus ($572mm), Transatlantic ($431mm) and AlphaCat Re 2011 ($43mm) 3 Includes RNR ($630mm), DaVinc
Slide 27: But Will Remain Within Validus' Risk Tolerance
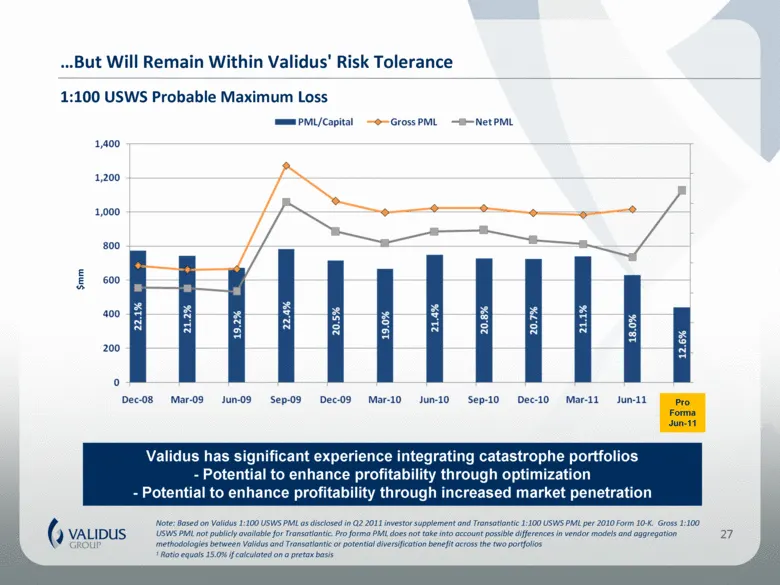
27 ...But Will Remain Within Validus' Risk Tolerance 1:100 USWS Probable Maximum Loss Validus has significant experience integrating catastrophe portfolios - Potential to enhance profitability through optimization - Potential to enhance profitability through increased market penetration Note: Based
Slide 28: Validus and Transatlantic – Diversification to Manage the Cycle
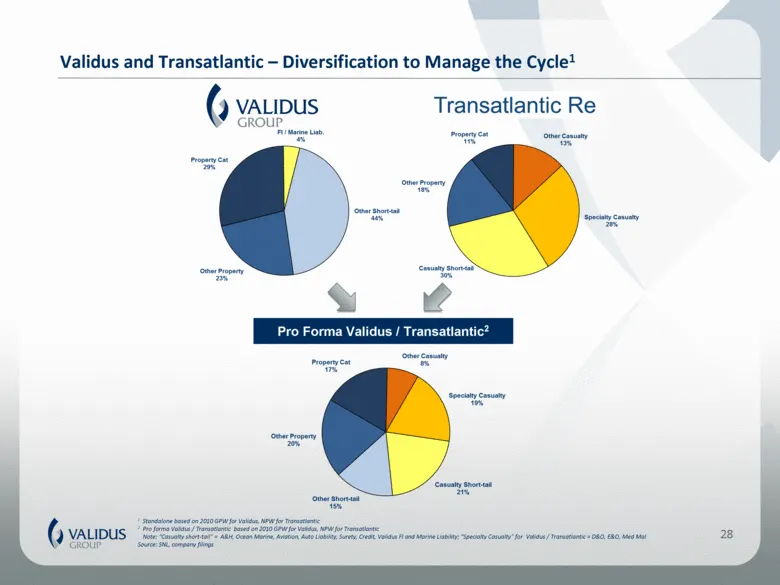
28 Validus and Transatlantic – Diversification to Manage the Cycle1 Pro Forma Validus / Transatlantic2 1 Standalone based on 2010 GPW for Validus, NPW for Transatlantic 2 Pro forma Validus / Transatlantic based on 2010 GPW for Validus, NPW for Transatlantic Note: “Casualty short-tail” = A&H, Ocean M
Slide 29: Validus Has a Track Record of Successfully Executing and Integrating Transactions
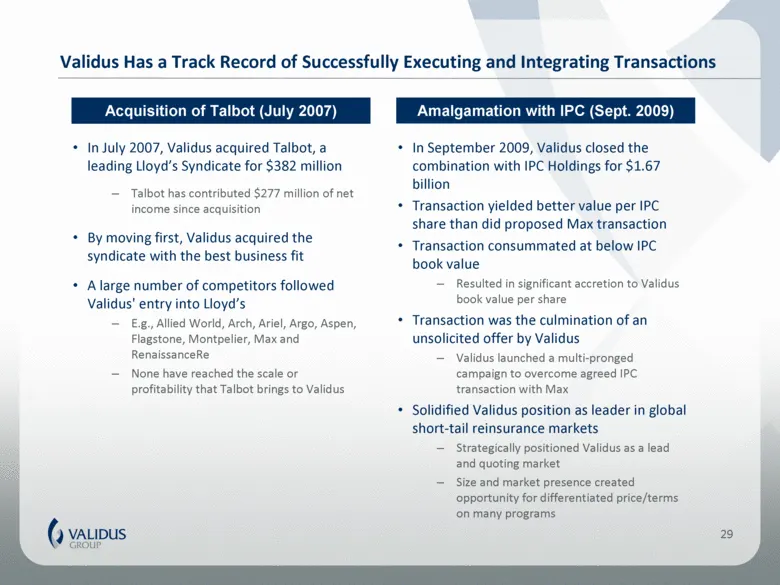
Validus Has a Track Record of Successfully Executing and Integrating Transactions Acquisition of Talbot (July 2007) In July 2007, Validus acquired Talbot, a leading Lloyd’s Syndicate for $382 million Talbot has contributed $277 million of net income since acquisition By moving first, Validus acquire
Slide 30: Potential Combination Synergies
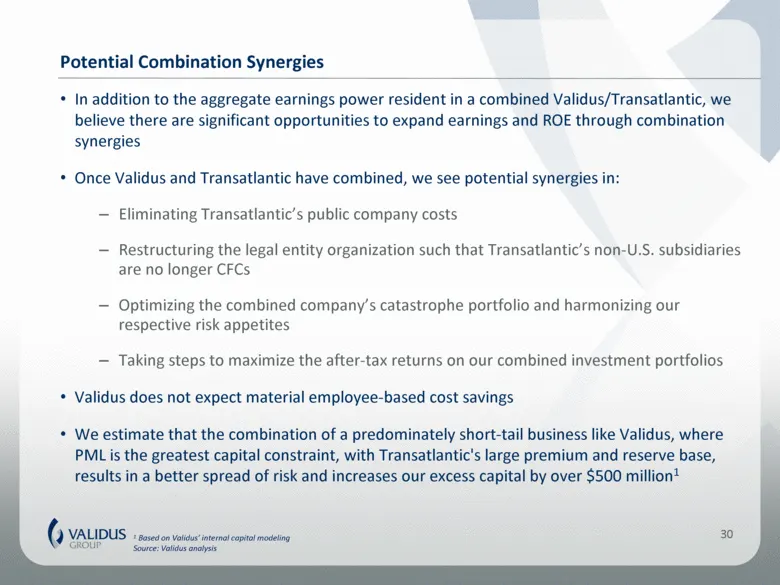
Potential Combination Synergies In addition to the aggregate earnings power resident in a combined Validus/Transatlantic, we believe there are significant opportunities to expand earnings and ROE through combination synergies Once Validus and Transatlantic have combined, we see potential synergies i
Slide 31: Combined LTM Earnings Power and Significant Capital Availability
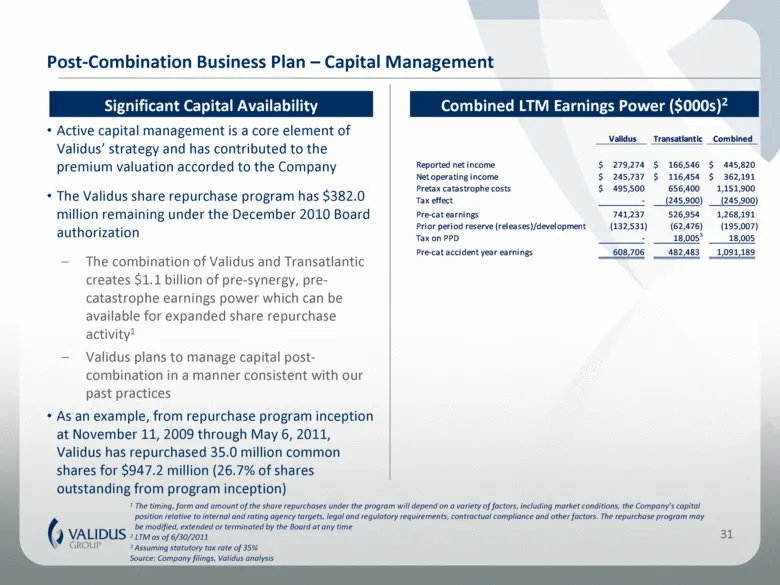
31 Combined LTM Earnings Power ($000s)2 Significant Capital Availability Active capital management is a core element of Validus’ strategy and has contributed to the premium valuation accorded to the Company The Validus share repurchase program has $382.0 million remaining under the December 2010 Boa
Slide 32: Conclusion: What You Get With Validus
Conclusion What You Get With Validus
Slide 33: What You Get With Validus
What You Get With Validus Board and management devoted to maximizing shareholder value, not premium volume Leading franchise positions in Bermuda and at Lloyd’s Deeply experienced reinsurance management team Proven expertise in integrating two transformational business combinations A commitment to a
Slide 34: Appendix: Reconciliation of Non-GAAP Measures
Appendix Reconciliation of Non-GAAP Measures
Slide 35: Net Operating Income Reconciliation
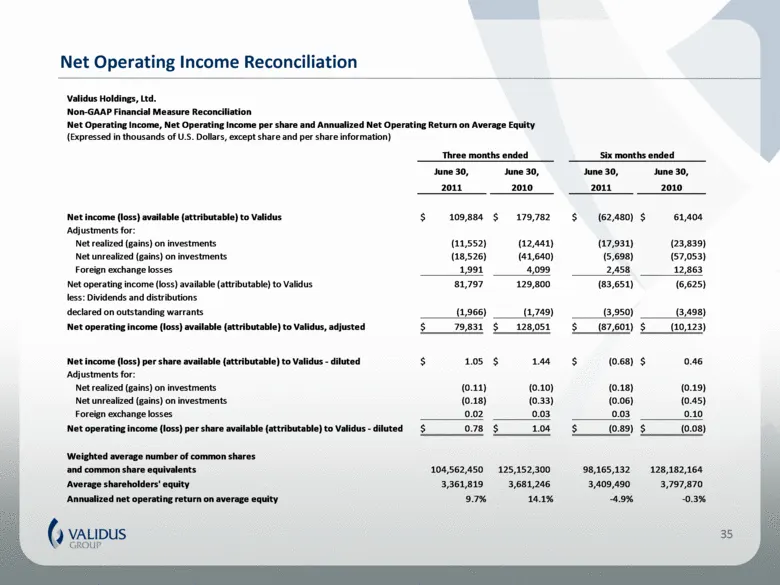
Net Operating Income Reconciliation 35 Validus Holdings, Ltd. Non-GAAP Financial Measure Reconciliation Net Operating Income, Net Operating Income per share and Annualized Net Operating Return on Average Equity (Expressed in thousands of U.S. Dollars, except share and per share information) June 30,
Slide 36: Diluted Book Value Per Share Reconciliation
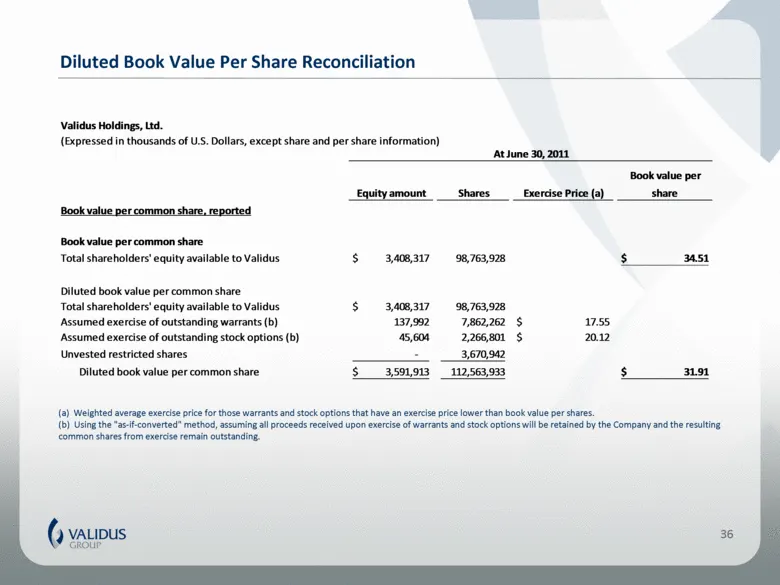
Diluted Book Value Per Share Reconciliation 36 (a) Weighted average exercise price for those warrants and stock options that have an exercise price lower than book value per shares. (b) Using the "as-if-converted" method, assuming all proceeds received upon exercise of warrants and stock options wil
Source: SEC EDGAR · 425 filed Aug 4, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011