Copano Energy L.L.C — RBC Capital Markets MLP Conference 2010
17 slides from Copano Energy L.L.C's conference presentation, Nov 18, 2010
Slide 1: RBC Capital Markets MLP Conference November 18, 2010
RBC Capital Markets MLP Conference November 18, 2010 NASDAQ: CPNO
Slide 2: Disclaimer
Disclaimer This presentation includes “forward-looking statements,” as defined in the federal securities laws. Statements that address activities, or events that Copano believes will or may occur in the future are forward-looking statements. These statements include, but are not limited to, statemen
Slide 3: Key Metrics
Key Metrics Service throughput volumes approximate 1,800,000 MMBtu/d of natural gas (1) Over 6,700 miles of active pipelines 8 natural gas processing plants with over 1.1 Bcf/d of combined processing capacity One NGL fractionation facility with total capacity of 22,000 Bbls/d ■ Expansion underway to
Slide 4: Growth Strategy
Growth Strategy Goal: to become a diversified midstream company with scale and stability of cash flows, above-average returns on invested capital and “investment-grade quality distributions” Key tenets of growth strategy: ■ Execute on organic growth opportunities around existing assets ■ Explore opp
Slide 5: 2011 Focus Areas
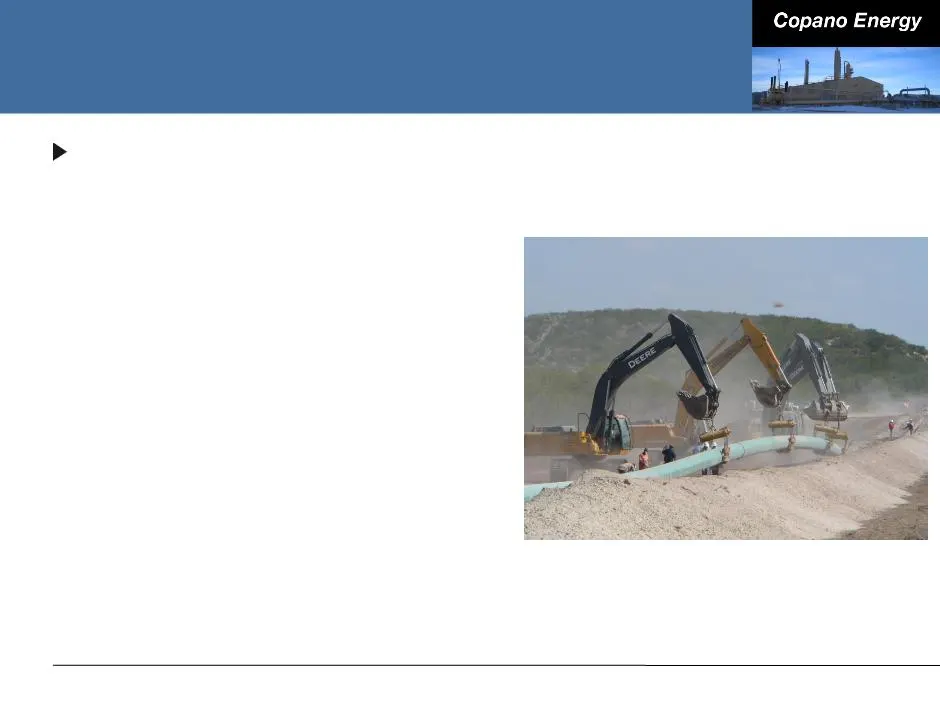
2011 Focus Areas Eagle Ford Shale ■ Eagle Ford Gathering joint venture ● Executed fee-based contracts with SM Energy and Chesapeake Energy - initial capacity now fully contracted ● Working to expand capacity to 600,000 MMBtu/d ■ DK Pipeline ● Initial capacity of 185 MMcf/d with ability to expand to
Slide 6: 2011 Focus Areas
2011 Focus Areas Saint Jo gathering system ■ Significant fee-based contract with highly rated producer ■ Volumes have continued to increase since the beginning of 2010 - October average of approximately 50,000 MMBtu/d ■ 19 rigs running in the area with approximately 30 new wells to be connected duri
Slide 7: 2011 Focus Areas
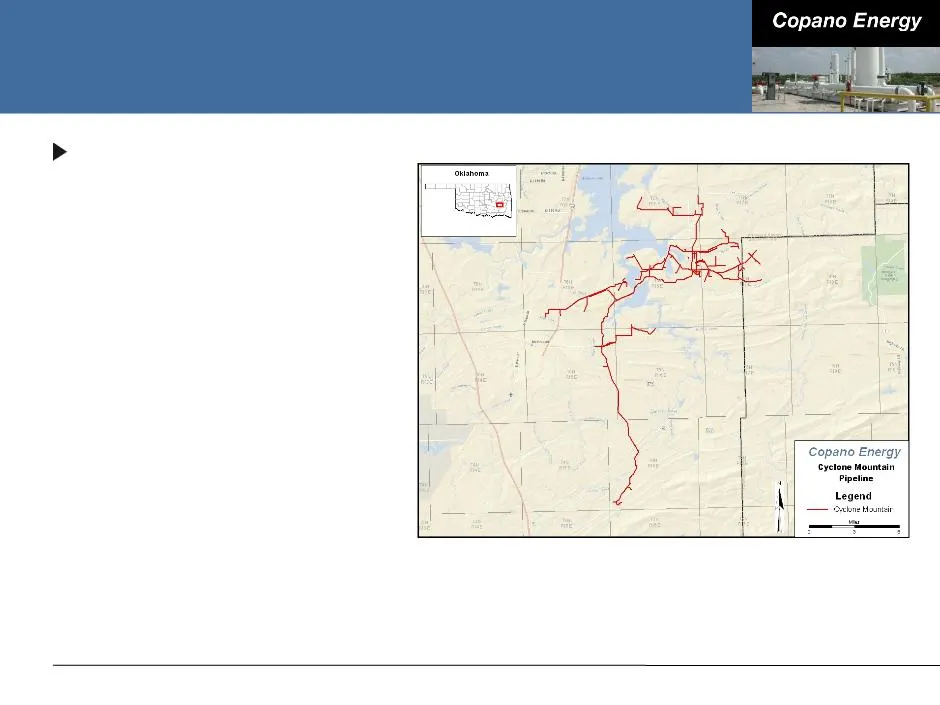
2011 Focus Areas Cyclone Mountain System - Woodford Shale ■ Current system capacity approximately 80 MMcf/d ● Expansion to 120 MMcf/d by year-end 2010 ■ 3Q 2010 average volumes of approximately 72,000 MMBtu/d vs. 58,000 MMBtu/d in 2Q 2010 ■ Based on producer volume expectations, likely system expans
Slide 8: Gulf Coast G&P: Will Demand for NGLs Last?
Gulf Coast G&P: Will Demand for NGLs Last?
Slide 9: Key Topics
Key Topics Ethane - largest component and least consensus ■ Current ethane market conditions suggest: ● Ethane expected to trade closer to natural gas value - both are cheap ● U.S. ethylene supply is competitive globally due to lower feedstock costs ● Current dynamic further support exports of ethyl
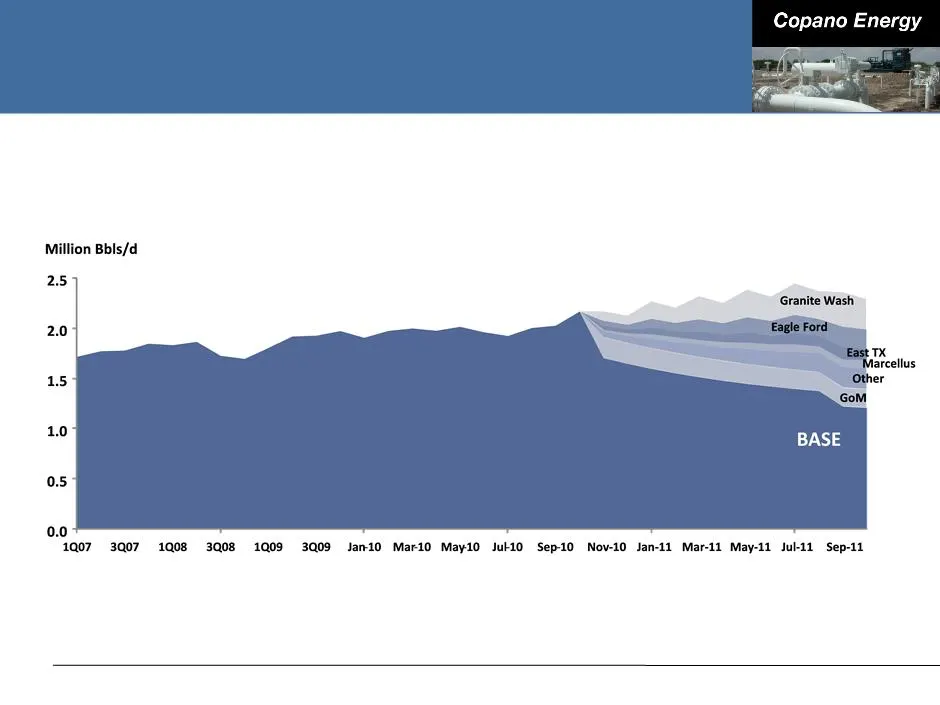
Slide 10: NGL Production Forecast (November 2010 - October 2011)
NGL Production Forecast (November 2010 - October 2011) Source: Goldman Sachs research report dated November 1, 2010: “’Processing’ our bullish NGL thesis” (“GS Report”) (EIA, company reports, Goldman Sachs Research estimates) Majority of NGL growth in 2011 expected to come primarily from Eagle Ford
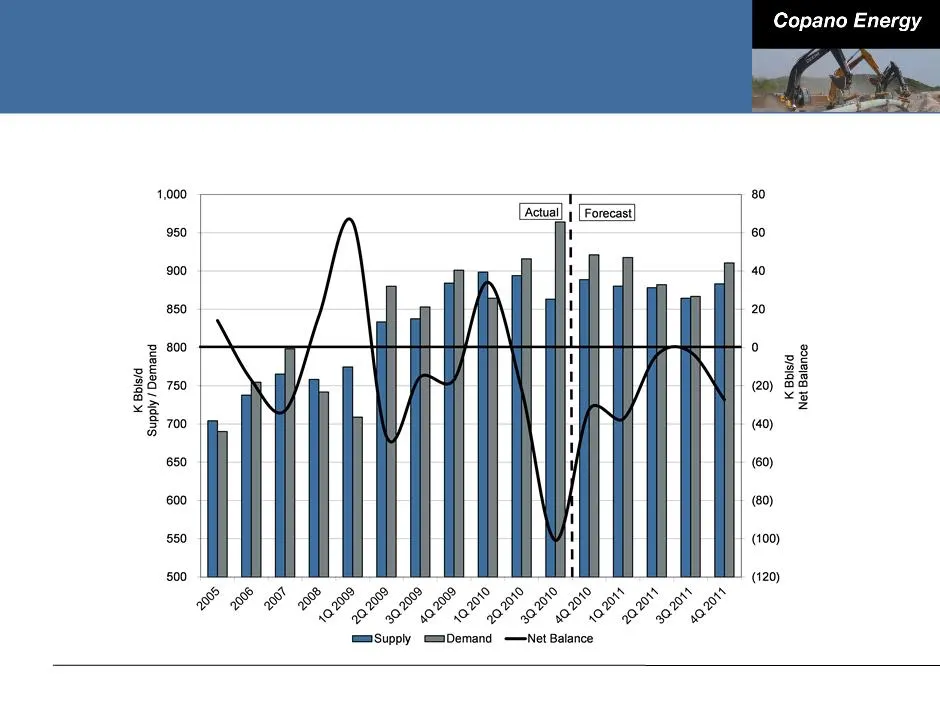
Slide 11: Ethane Supply-Demand Balance
Ethane Supply-Demand Balance Note: Prepared by Copano using data obtained from Petral Consulting Company Forecast indicates ethane demand continuing to exceed supply through 2011
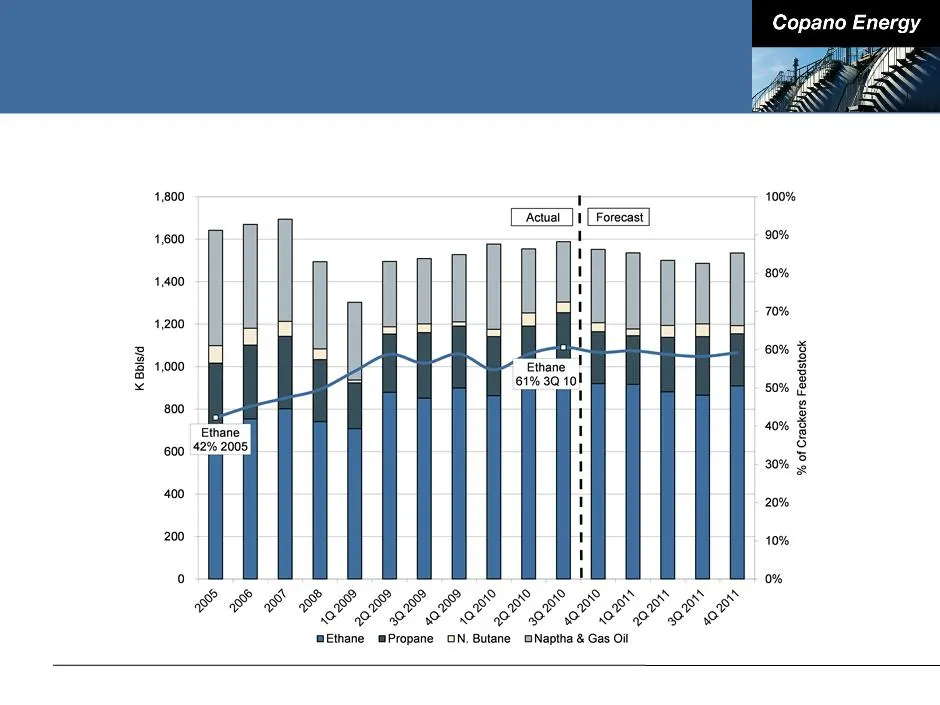
Slide 12: U.S. Ethylene Cracker Feedstock Consumption
U.S. Ethylene Cracker Feedstock Consumption Cracker consumption trend is moving from heavier to lighter feedstock based on lower cost Note: Prepared by Copano using data obtained from Petral Consulting Company
Slide 13: General Industry Trends Worth Watching
General Industry Trends Worth Watching Average NGL content of natural gas expected to increase from 1.25 to 1.45 GPM (1) ■ Drilling currently targeted at richer plays Greater processing plant efficiency - more NGLs extracted Fractionation capacity tight…for the near-term ■ Significant expansions und
Slide 14: Appendix - Goldman Sachs Disclosures
Appendix - Goldman Sachs Disclosures
Slide 15: Disclosures
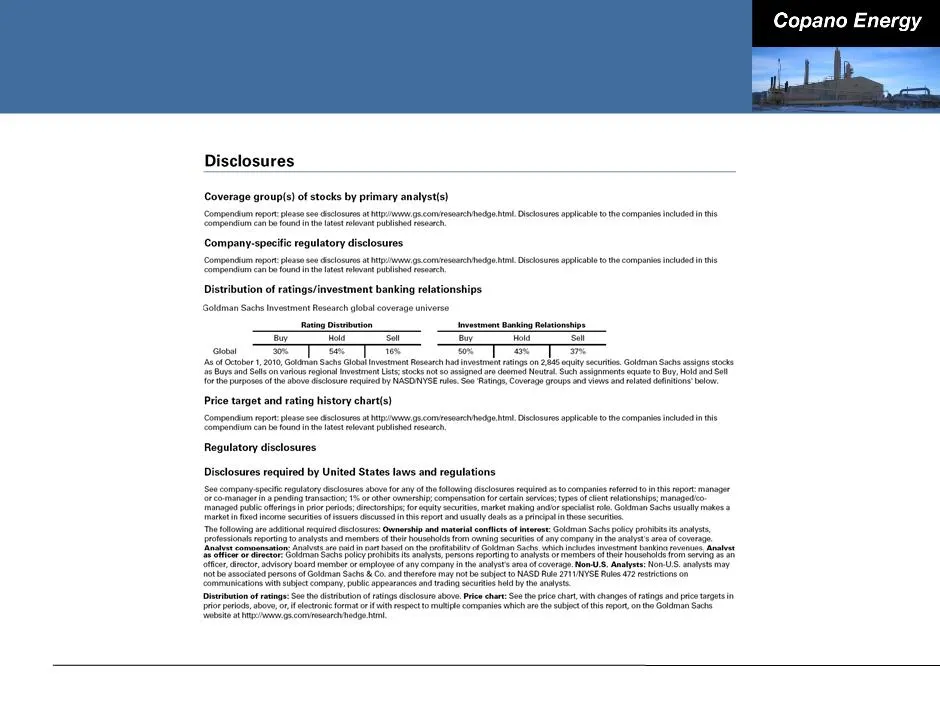
Disclosures Coverage group(s) of stocks by primary analysts) Compendium report eae se cose a pw. gsconvesacinede hm Dsosues applaieohe compans inclu is ‘cape ab aun in ts te roan pander Company-specific regulatory disclosures compen repo: please come pug coment Mn stu appa o he compa ila it ‘aogeram
Slide 16: Additional disclosures required under laws of jurisdictions other than the United States
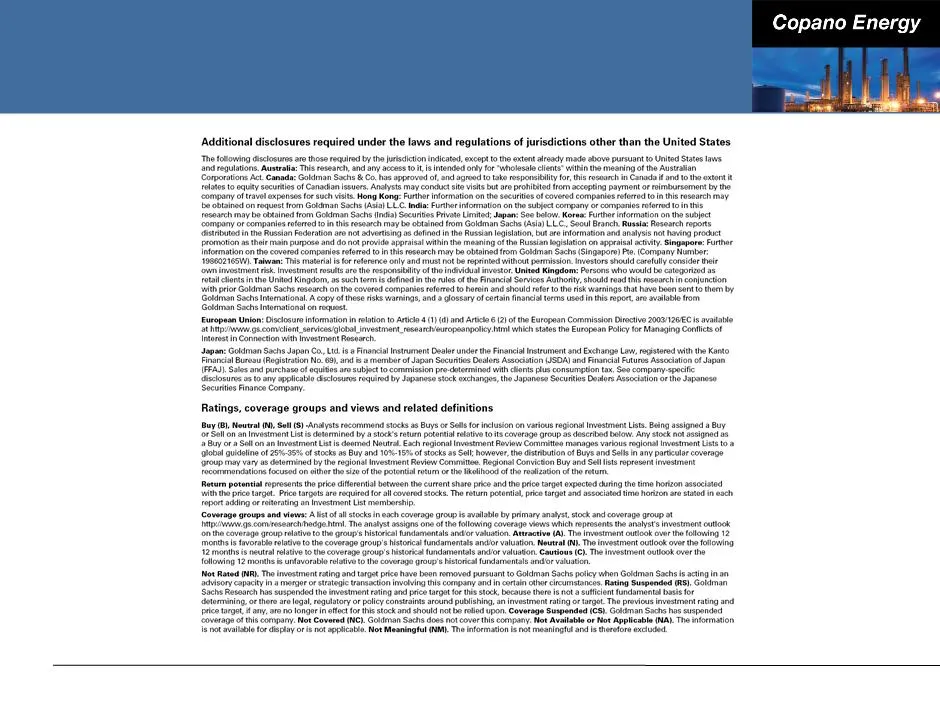
Additional disclosures required under the laws and regulations of jurisdictions other than the United States ato em honey ritonavir Ses ns dts eeu aati of arcane, Any ay cond Vs re ied frm ace entree by he ‘Sb on equa rom Gnman Sots aa CLC na: Furor ifomato nt subject cmpany e compares mesons ‘earch
Slide 17: Global product; distributing entities
Global product; distributing entities ‘The Gab nestart Reusch Divan of Golan Sachs produces astute esearch padi or cents Goldman Sachs sod prsnt to cenaln contac! anger, bal bua. Anas toed Goldman Sachs eles wound he Wor prosun equ rssh en tetas accompa doar es mecrscrtrncs caren anand a pote seeing
Source: SEC EDGAR · 8-K filed Nov 18, 2010
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011