Montpelier Re — Investor Presentation (December 2007)
15 slides from Montpelier Re's investor presentation, Dec 4, 2007
Slide 1: New York Stock Exchange Investor Presentation
December 4th, 2007 New York Stock Exchange Investor Presentation
Slide 2: Forward Looking Statements & Safe Harbor
2 Forward Looking Statements & Safe Harbor This presentation may contain, and Montpelier Re may from time to time make, written or oral "forward-looking statements" within the meaning of the U.S. federal securities laws, which are made pursuant to the safe harbor provisions of the Private Securities
Slide 3: Selected Stock Information
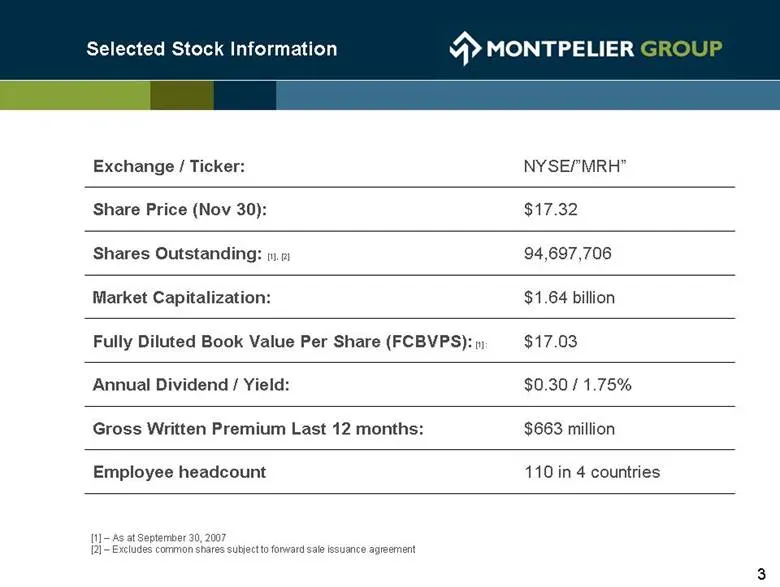
3 Selected Stock Information Exchange / Ticker: NYSE/”MRH” Share Price (Nov 30): $17.32 Shares Outstanding: [1], [2] 94,697,706 Market Capitalization: $1.64 billion Fully Diluted Book Value Per Share (FCBVPS): [1]: $17.03 Annual Dividend / Yield: $0.30 / 1.75% Gross Written Premium Last 12 months: $
Slide 4: The Montpelier Advantage
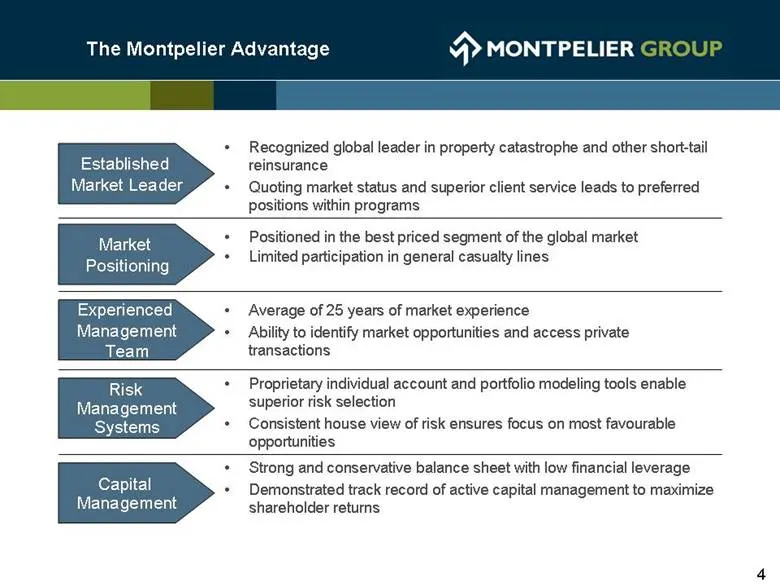
4 The Montpelier Advantage Recognized global leader in property catastrophe and other short-tail reinsurance Quoting market status and superior client service leads to preferred positions within programs Positioned in the best priced segment of the global market Limited participation in general casu
Slide 5: Business Mix
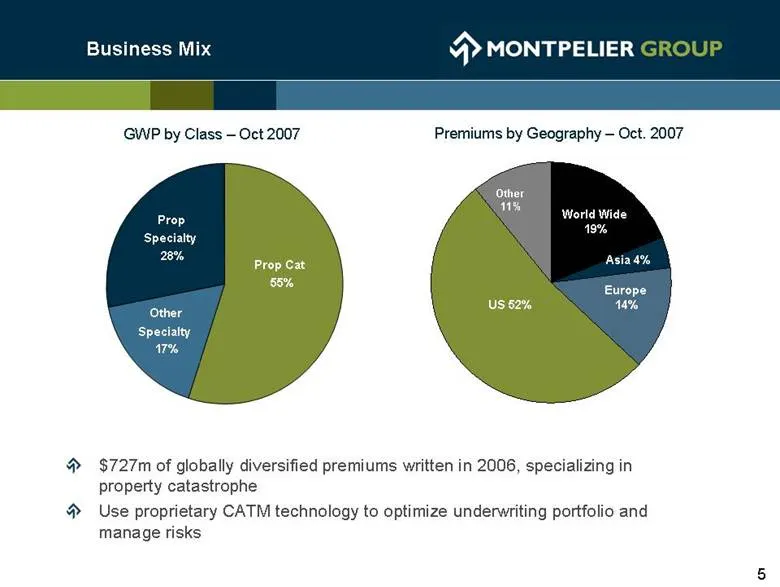
5 Business Mix $727m of globally diversified premiums written in 2006, specializing in property catastrophe Use proprietary CATM technology to optimize underwriting portfolio and manage risks Prop Cat 55% Other Specialty 17% Prop Specialty 28% GWP by Class – Oct 2007 Premiums by Geography – Oct. 200
Slide 6: Q3 2007 Financial Performance
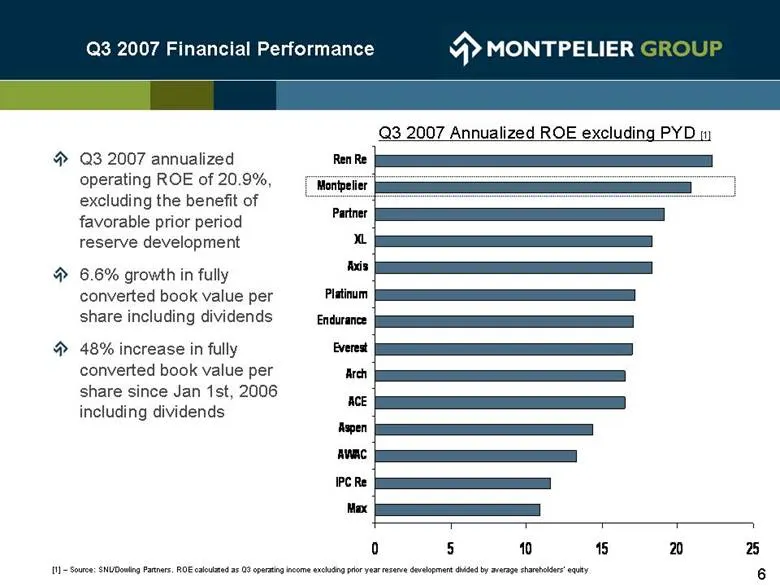
6 Q3 2007 Financial Performance Q3 2007 annualized operating ROE of 20.9%, excluding the benefit of favorable prior period reserve development 6.6% growth in fully converted book value per share including dividends 48% increase in fully converted book value per share since Jan 1st, 2006 including di
Slide 7: Consolidated Financial Summary
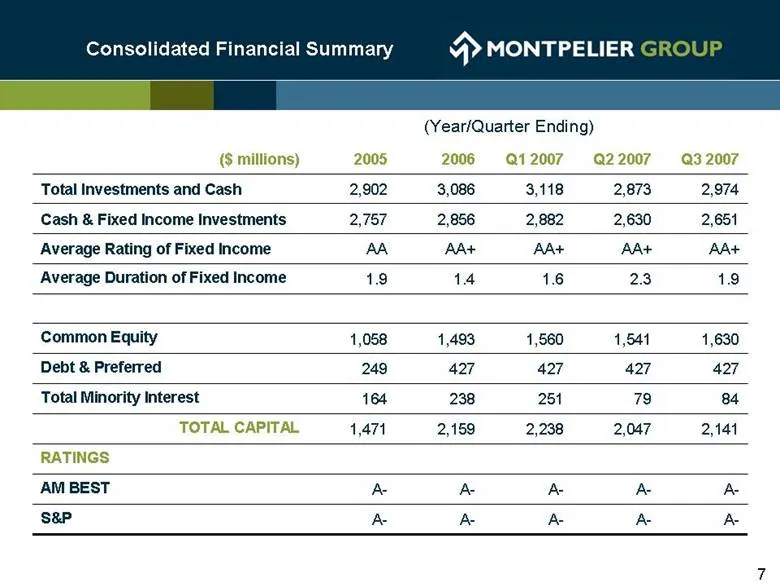
7 Consolidated Financial Summary ($ millions) 2005 2006 Q1 2007 Q2 2007 Q3 2007 Total Investments and Cash 2,902 3,086 3,118 2,873 2,974 Cash & Fixed Income Investments 2,757 2,856 2,882 2,630 2,651 Average Rating of Fixed Income AA AA+ AA+ AA+ AA+ Average Duration of Fixed Income 1.9 1.4 1.6 2.3 1.
Slide 8: Strong Balance Sheet
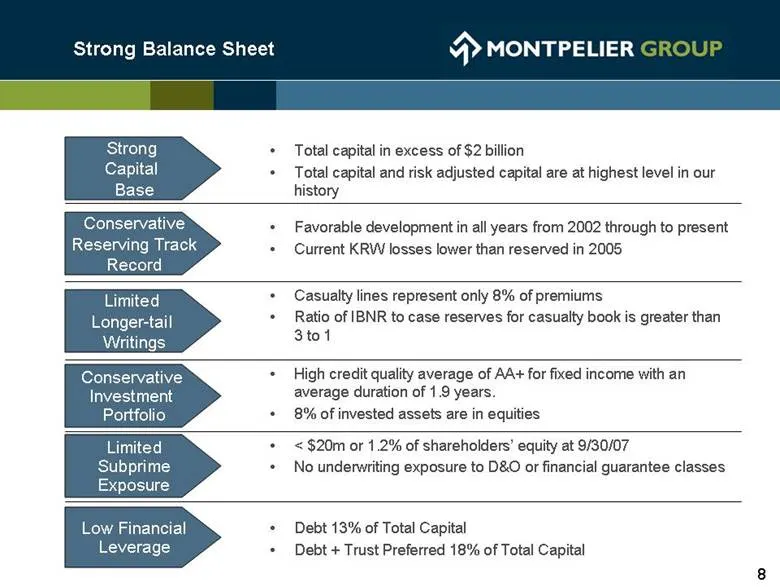
8 Strong Balance Sheet Total capital in excess of $2 billion Total capital and risk adjusted capital are at highest level in our history Favorable development in all years from 2002 through to present Current KRW losses lower than reserved in 2005 Casualty lines represent only 8% of premiums Ratio o
Slide 9: Loss Reserving History
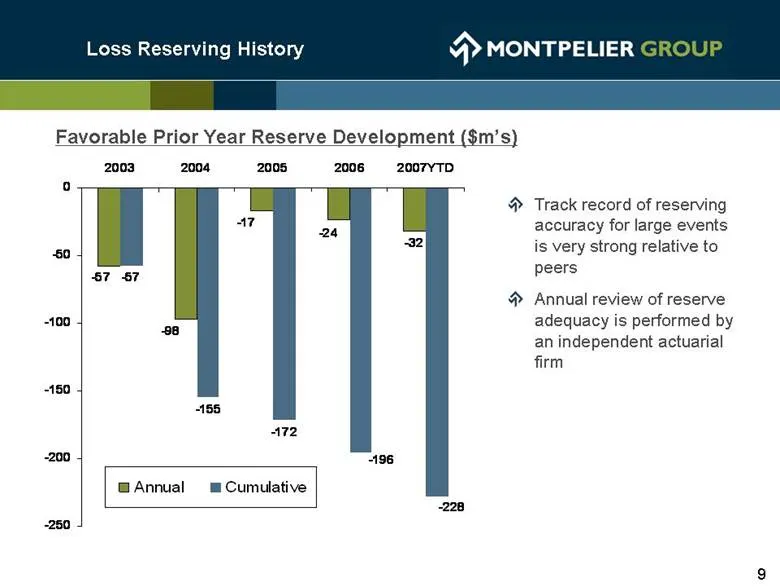
9 Loss Reserving History Favorable Prior Year Reserve Development ($m’s) Track record of reserving accuracy for large events is very strong relative to peers Annual review of reserve adequacy is performed by an independent actuarial firm -32 -57 -155 -172 -24 -17 -98 -57 -196 -228 -250 -200 -150 -10
Slide 10: Experienced Management Team
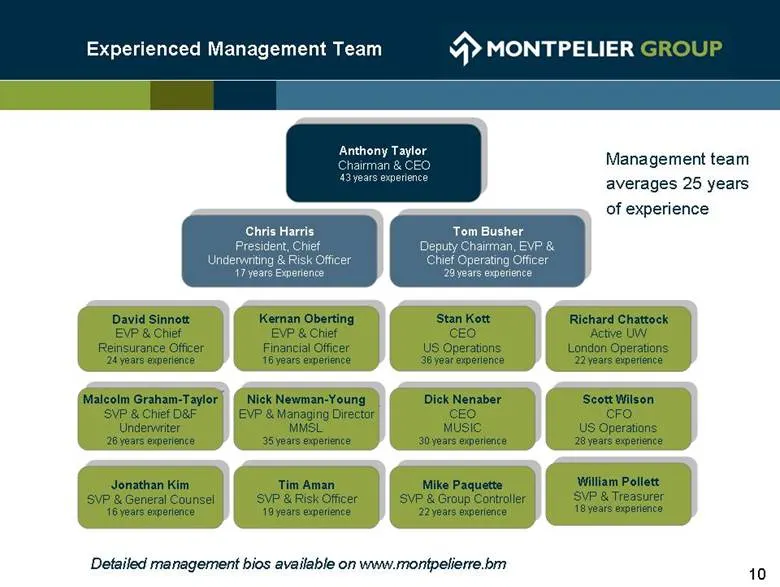
10 Experienced Management Team Tom Busher Deputy Chairman, EVP & Chief Operating Officer 29 years experience Kernan Oberting EVP & Chief Financial Officer 16 years experience Anthony Taylor Chairman & CEO 43 years experience Chris Harris President, Chief Underwriting & Risk Officer 17 years Experien
Slide 11: Risk Management
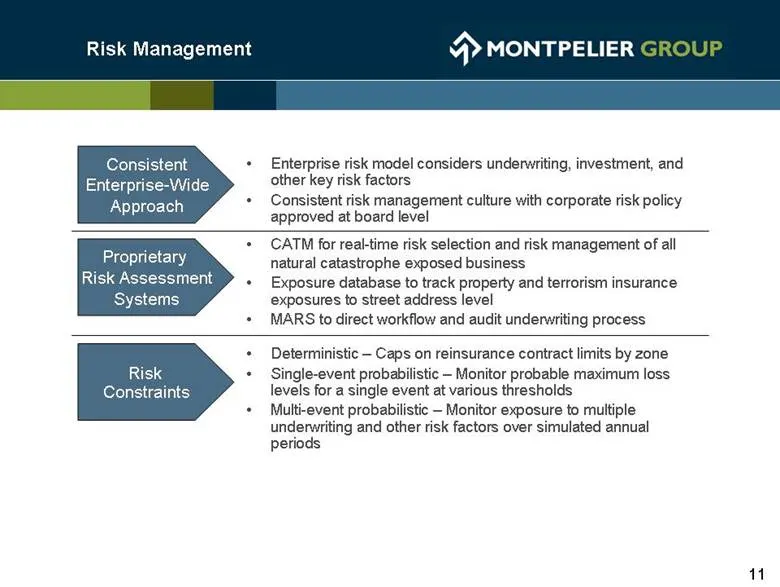
11 Risk Management Enterprise risk model considers underwriting, investment, and other key risk factors Consistent risk management culture with corporate risk policy approved at board level CATM for real-time risk selection and risk management of all natural catastrophe exposed business Exposure dat
Slide 12: 2008 Operating Platform
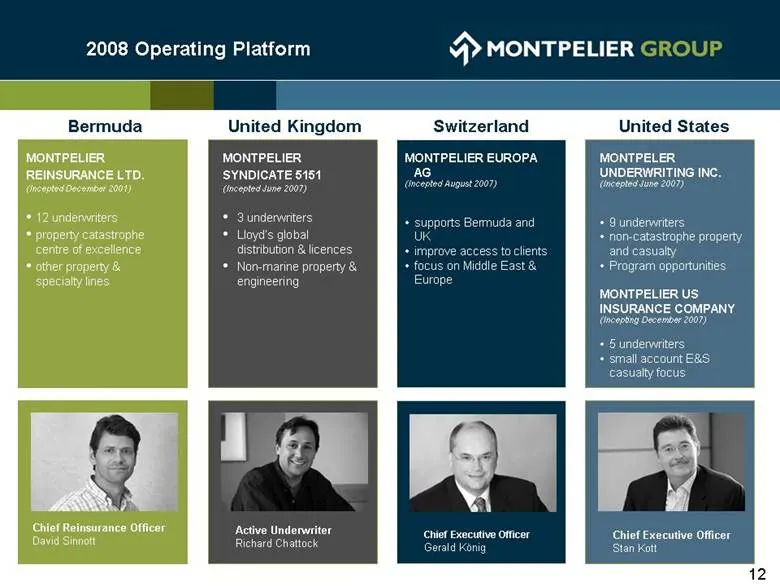
12 2008 Operating Platform Chief Reinsurance Officer David Sinnott Active Underwriter Richard Chattock Chief Executive Officer Stan Kott Chief Executive Officer Gerald König Bermuda United Kingdom United States Switzerland MONTPELIER SYNDICATE 5151 (Incepted June 2007) 3 underwriters Lloyd’s global
Slide 13: Benefits of Expanded Platform
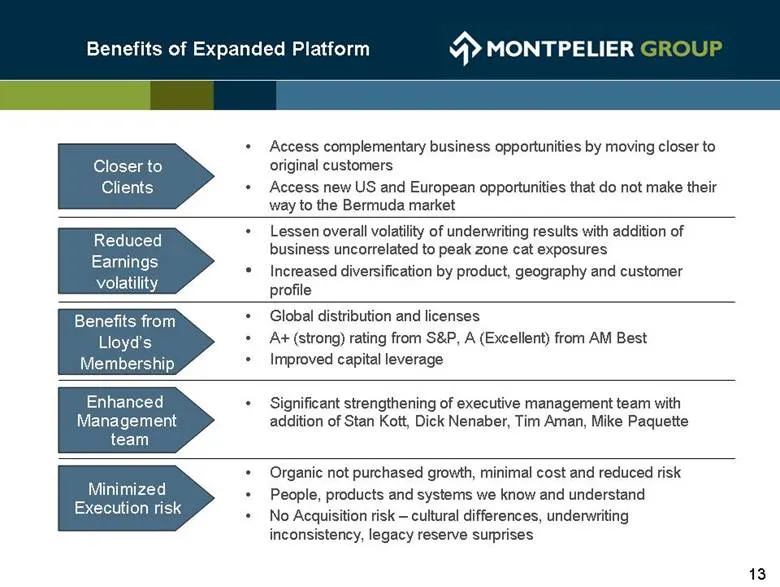
13 Benefits of Expanded Platform Access complementary business opportunities by moving closer to original customers Access new US and European opportunities that do not make their way to the Bermuda market Lessen overall volatility of underwriting results with addition of business uncorrelated to pe
Slide 14: The Montpelier Advantage
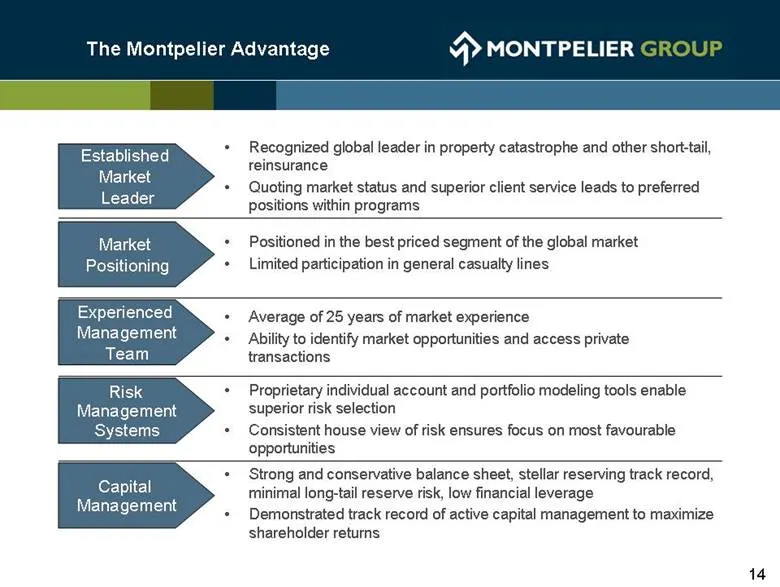
14 The Montpelier Advantage Recognized global leader in property catastrophe and other short-tail, reinsurance Quoting market status and superior client service leads to preferred positions within programs Positioned in the best priced segment of the global market Limited participation in general ca
Slide 15: Please visit our website for more information
Please visit our website for more information on our company, products and team members: Montpelier House, 94 Pitts Bay Road, Pembroke, Bermuda PO Box HM 2079, Hamilton, Bermuda, HMHX Tel: (441) 296-5550 Fax: (441) 296-5551 Email: [email protected] Web: www.montpelierre.bm Investor Contact: Willi
Source: SEC EDGAR · 8-K filed Dec 4, 2007
More decks from Montpelier Re Holdings Ltd
 Merger or Acquisition (March 2015)11 slides · Mar 31, 2015
 Merger or Acquisition (March 2015)11 slides · Mar 31, 2015
 Q4 2011 Earnings Presentation26 slides · Mar 5, 2012
 Investor Presentation (September 2011)27 slides · Sep 7, 2011
 KBW Investor Conference 201018 slides · Sep 8, 2010
 Investor Day (May 2009)47 slides · May 7, 2009