Copano Energy L.L.C — Howard Weil 35th Annual Energy Conference 2007
30 slides from Copano Energy L.L.C's conference presentation, Apr 2, 2007
Slide 1: Copano Energy Howard Weil 35th Annual Energy Conference
Copano Energy NASDAQ: CPNO Howard Weil 35th Annual Energy Conference April 2, 2007
Slide 2: Forward-Looking Statements
Forward-Looking Statements Statements made by representatives of Copano Energy, L.L.C. (the "Company") during this presentation may constitute "forward-looking statements" as defined by the Securities and Exchange Commission. All statements, other than statements of historical facts, made by represe
Slide 3: Introduction to Copano Energy, L.L.C.
Introduction to Copano Energy, L.L.C. Growth-oriented midstream energy company founded in 1992 Built through acquisitions - over 40 acquisitions plus extensive construction and integration projects Significant pipeline growth - from 23 miles to over 5,000 miles Five processing plants (a) - over 800
Slide 4: Overview
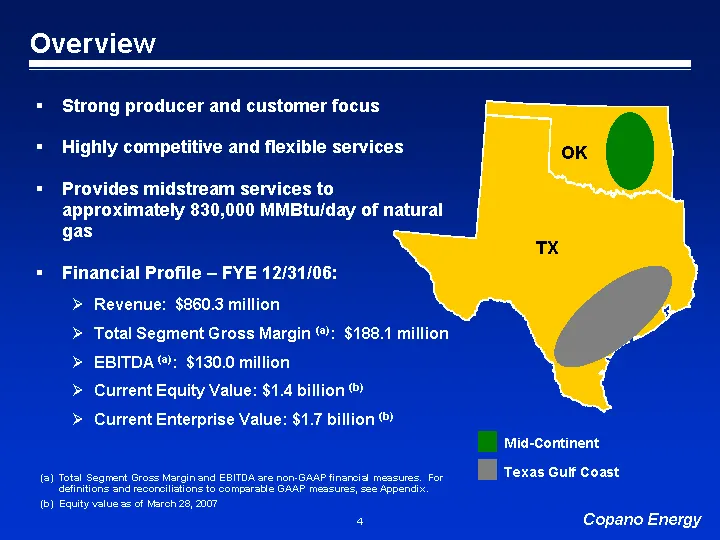
Overview Strong producer and customer focus Highly competitive and flexible services Provides midstream services to approximately 830,000 MMBtu/day of natural gas Financial Profile - FYE 12/31/06: Revenue: $860.3 million Total Segment Gross Margin (a): $188.1 million EBITDA (a): $130.0 million Curre
Slide 5: Copano's LLC Structure
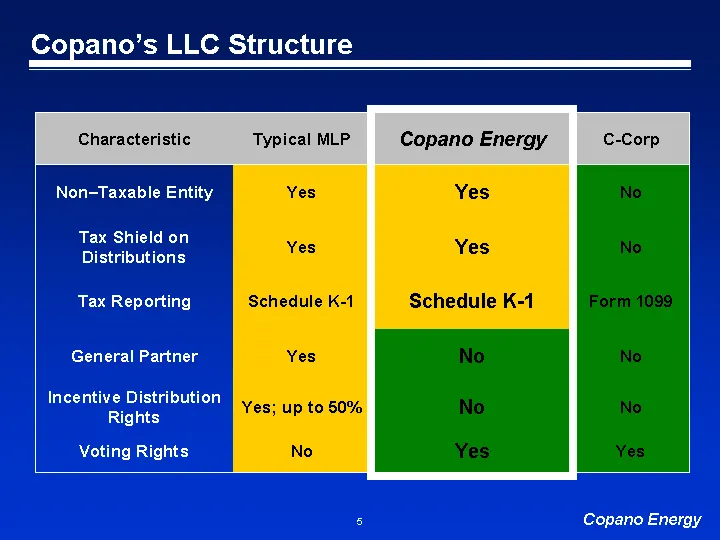
Copano's LLC Structure Characteristic Typical MLP Copano Energy C-Corp Non-Taxable Entity Yes Yes No Tax Shield on Distributions Yes Yes No Tax Reporting Schedule K-1 Schedule K-1 Form 1099 General Partner Yes No No Incentive Distribution Rights Yes; up to 50% No No Voting Rights No Yes Yes
Slide 6: LLC Benefits
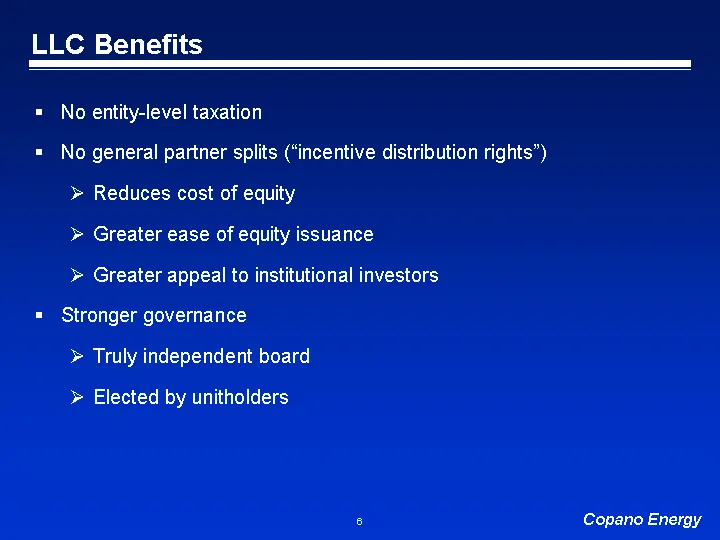
LLC Benefits No entity-level taxation No general partner splits ("incentive distribution rights") Reduces cost of equity Greater ease of equity issuance Greater appeal to institutional investors Stronger governance Truly independent board Elected by unitholders
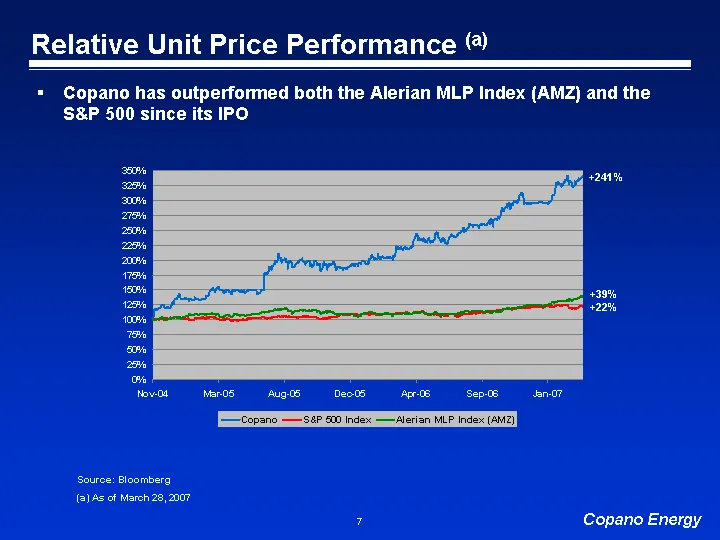
Slide 7: Copano has outperformed the Alerian MLP Index and the S&P 500 since its IPO
Copano has outperformed both the Alerian MLP Index (AMZ) and the S&P 500 since its IPO +241% +39% +22% Relative Unit Price Performance (a) Source: Bloomberg (a) As of March 28, 2007
Slide 8: Total Return Performance
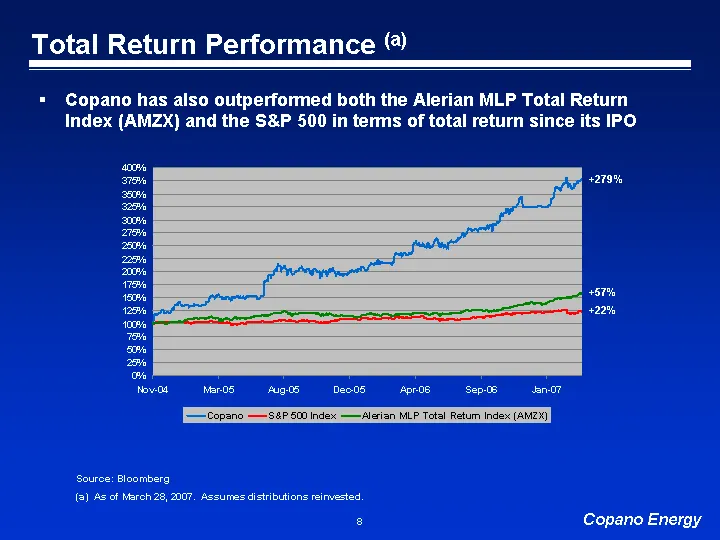
Total Return Performance (a) Copano has also outperformed both the Alerian MLP Total Return Index (AMZX) and the S&P 500 in terms of total return since its IPO +279% +22% +57% Source: Bloomberg (a) As of March 28, 2007. Assumes distributions reinvested.
Slide 9: Distribution Growth and Coverage
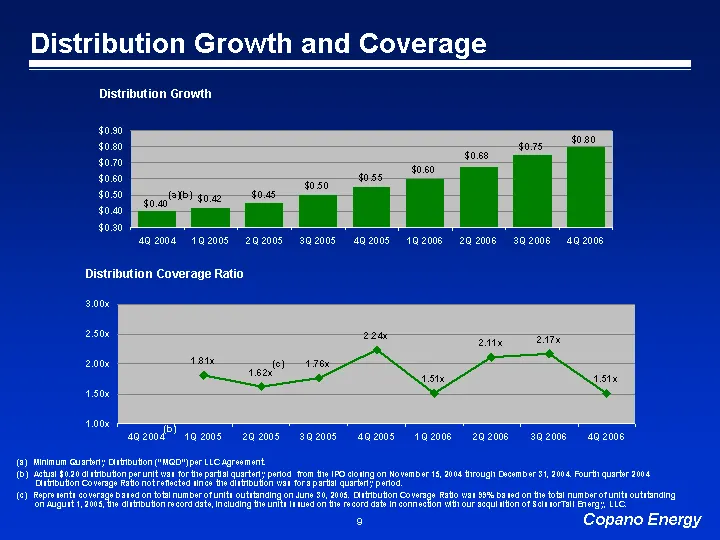
Distribution Growth and Coverage Distribution Growth (a) Minimum Quarterly Distribution ("MQD") per LLC Agreement. (b) Actual $0.20 distribution per unit was for the partial quarterly period from the IPO closing on November 15, 2004 through December 31, 2004. Fourth quarter 2004 Distribution Coverag
Slide 10: Comparative Distribution Yield
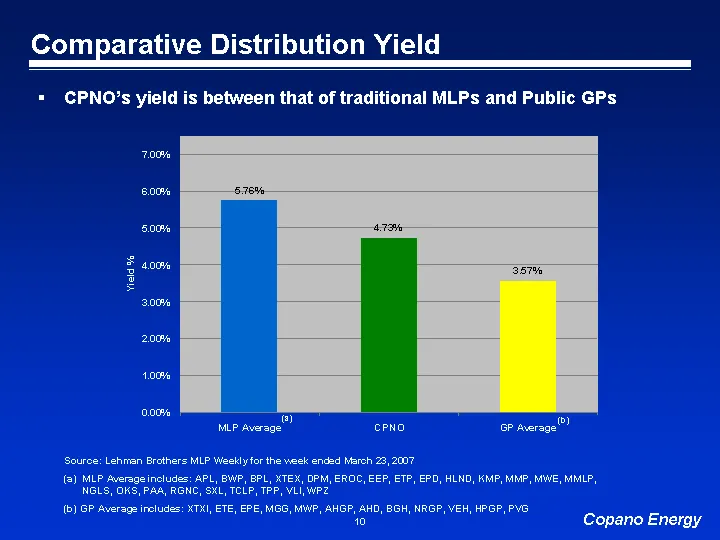
Comparative Distribution Yield CPNO's yield is between that of traditional MLPs and Public GPs Source: Lehman Brothers MLP Weekly for the week ended March 23, 2007 (a) MLP Average includes: APL, BWP, BPL, XTEX, DPM, EROC, EEP, ETP, EPD, HLND, KMP, MMP, MWE, MMLP, NGLS, OKS, PAA, RGNC, SXL, TCLP, TPP
Slide 11: CPNO Distributions vs. MLP with IDR's
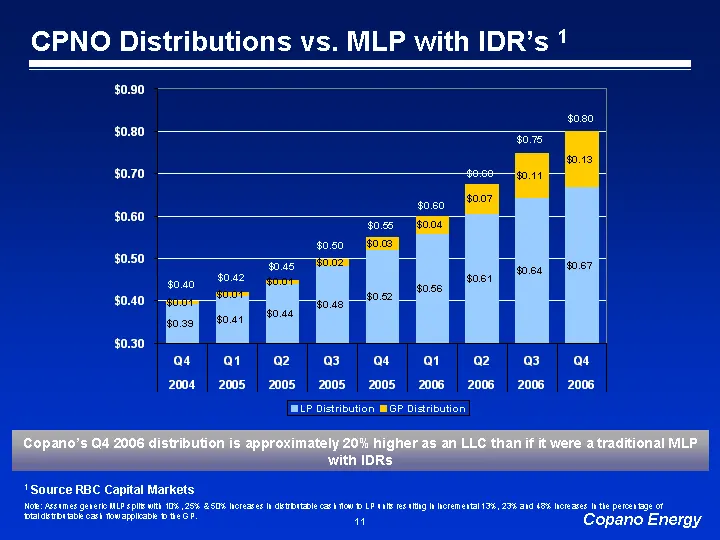
CPNO Distributions vs. MLP with IDR's 1 Note: Assumes generic MLP splits with 10%, 25% & 50% increases in distributable cash flow to LP units resulting in incremental 13%, 23% and 48% increases in the percentage of total distributable cash flow applicable to the GP. Copano's Q4 2006 distribution is
Slide 12: General Partner Incentive Distribution Loads
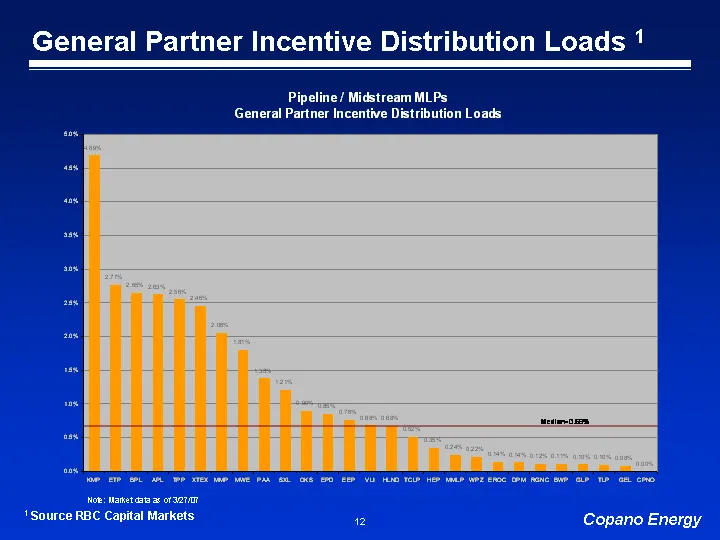
General Partner Incentive Distribution Loads 1 Note: Market data as of 3/27/07 1 Source RBC Capital Markets
Slide 13: Business Strategy
Business Strategy Pursue growth from our existing assets Pursue complementary acquisitions and organic expansion opportunities Reduce sensitivity of our cash flows to commodity price fluctuations Exploit the operating flexibility of our assets Expand our geographic scope into new regions where our g
Slide 14: Mid-Continent Operations
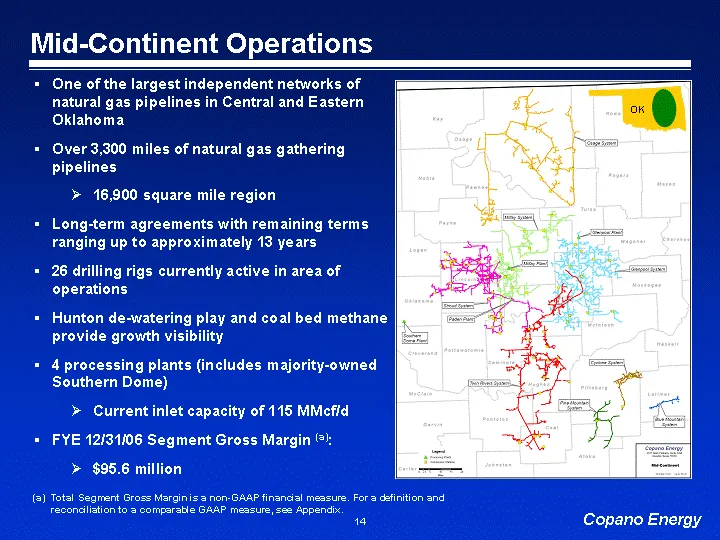
Mid-Continent Operations One of the largest independent networks of natural gas pipelines in Central and Eastern Oklahoma Over 3,300 miles of natural gas gathering pipelines 16,900 square mile region Long-term agreements with remaining terms ranging up to approximately 13 years 26 drilling rigs curr
Slide 15: Texas Gulf Coast Pipelines
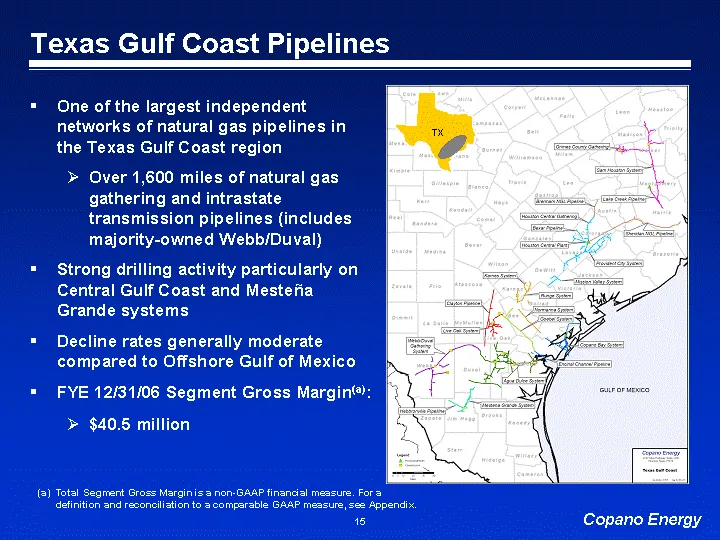
Texas Gulf Coast Pipelines One of the largest independent networks of natural gas pipelines in the Texas Gulf Coast region Over 1,600 miles of natural gas gathering and intrastate transmission pipelines (includes majority-owned Webb/Duval) Strong drilling activity particularly on Central Gulf Coast
Slide 16: Texas Gulf Coast Processing
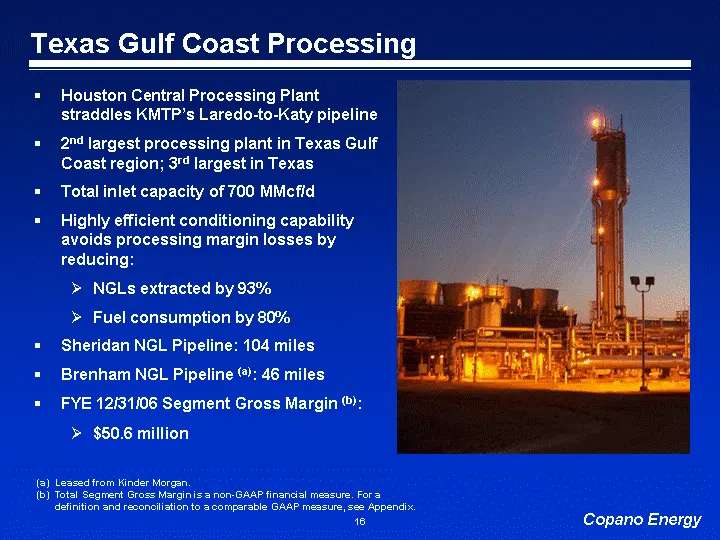
Texas Gulf Coast Processing Houston Central Processing Plant straddles KMTP's Laredo-to-Katy pipeline 2nd largest processing plant in Texas Gulf Coast region; 3rd largest in Texas Total inlet capacity of 700 MMcf/d Highly efficient conditioning capability avoids processing margin losses by reducing:
Slide 17: Producer Relationships
Producer Relationships NOTE: Partial list for Texas Gulf Coast and Mid-Continent Mestena Operating, Ltd.
Slide 18: Highly-Rated Service Provider
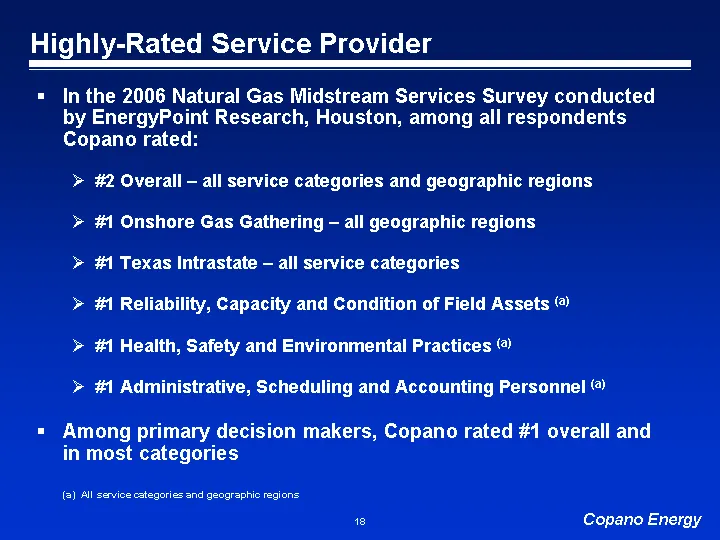
Highly-Rated Service Provider In the 2006 Natural Gas Midstream Services Survey conducted by EnergyPoint Research, Houston, among all respondents Copano rated: #2 Overall - all service categories and geographic regions #1 Onshore Gas Gathering - all geographic regions #1 Texas Intrastate - all servi
Slide 19: Organic Growth & Bolt-on Capital Spending
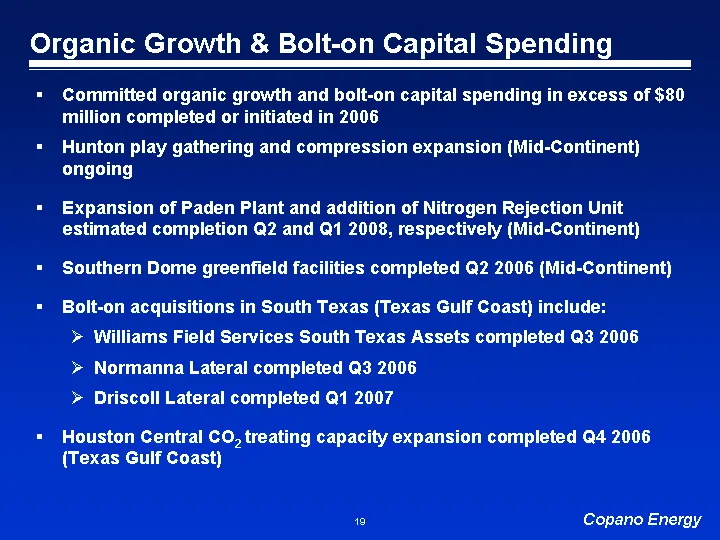
Organic Growth & Bolt-on Capital Spending Committed organic growth and bolt-on capital spending in excess of $80 million completed or initiated in 2006 Hunton play gathering and compression expansion (Mid-Continent) ongoing Expansion of Paden Plant and addition of Nitrogen Rejection Unit estimated c
Slide 20: Recent Announcements
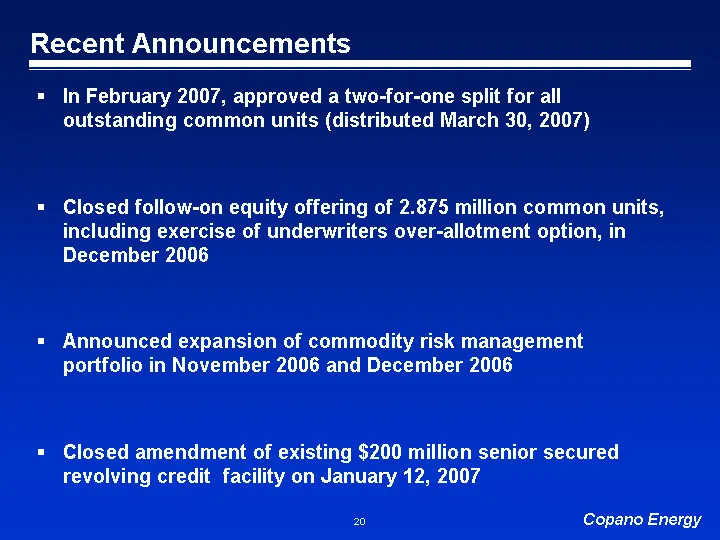
Recent Announcements In February 2007, approved a two-for-one split for all outstanding common units (distributed March 30, 2007) Closed follow-on equity offering of 2.875 million common units, including exercise of underwriters over-allotment option, in December 2006 Announced expansion of commodit
Slide 21: Hedging Program and Risk Management
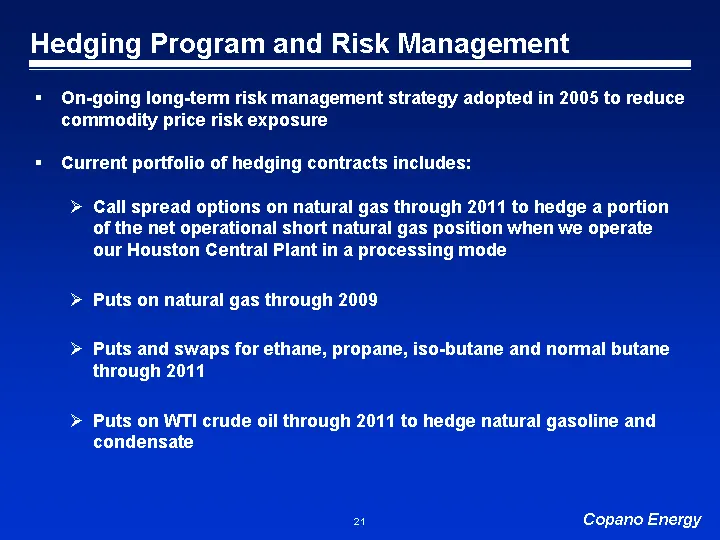
Hedging Program and Risk Management On-going long-term risk management strategy adopted in 2005 to reduce commodity price risk exposure Current portfolio of hedging contracts includes: Call spread options on natural gas through 2011 to hedge a portion of the net operational short natural gas positio
Slide 22: Financial Structure
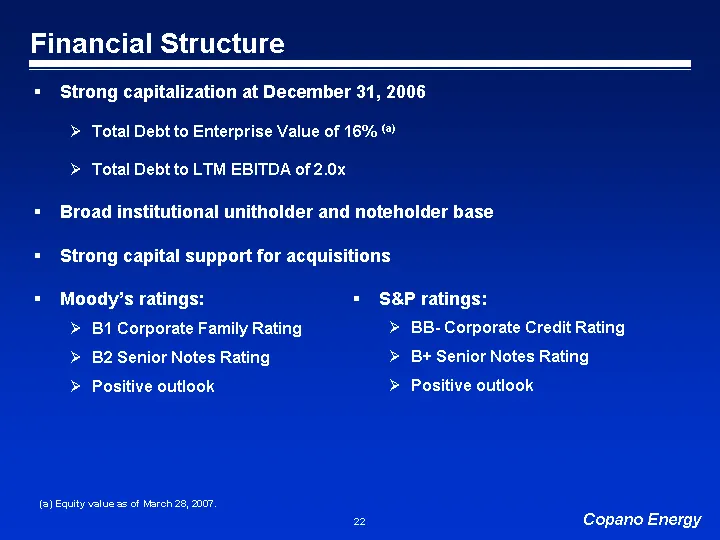
Financial Structure Strong capitalization at December 31, 2006 Total Debt to Enterprise Value of 16% (a) Total Debt to LTM EBITDA of 2.0x Broad institutional unitholder and noteholder base Strong capital support for acquisitions Moody's ratings: B1 Corporate Family Rating B2 Senior Notes Rating Posi
Slide 23: Financial Policy
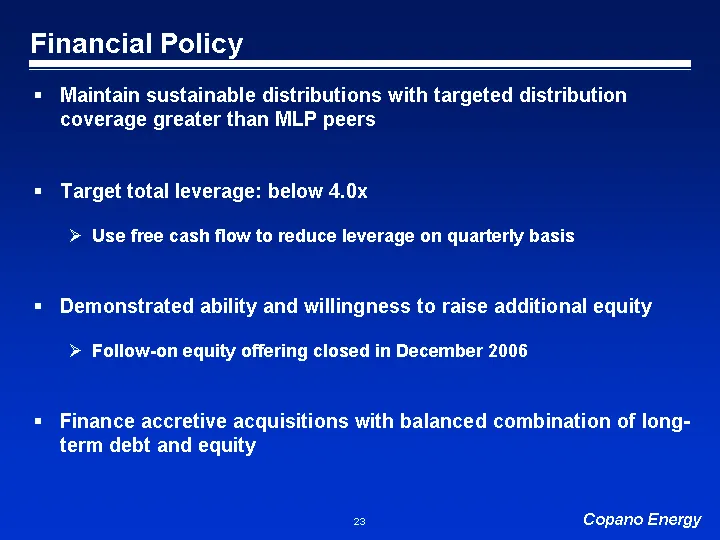
Financial Policy Maintain sustainable distributions with targeted distribution coverage greater than MLP peers Target total leverage: below 4.0x Use free cash flow to reduce leverage on quarterly basis Demonstrated ability and willingness to raise additional equity Follow-on equity offering closed i
Slide 24: Experienced Management Team and Board of Directors
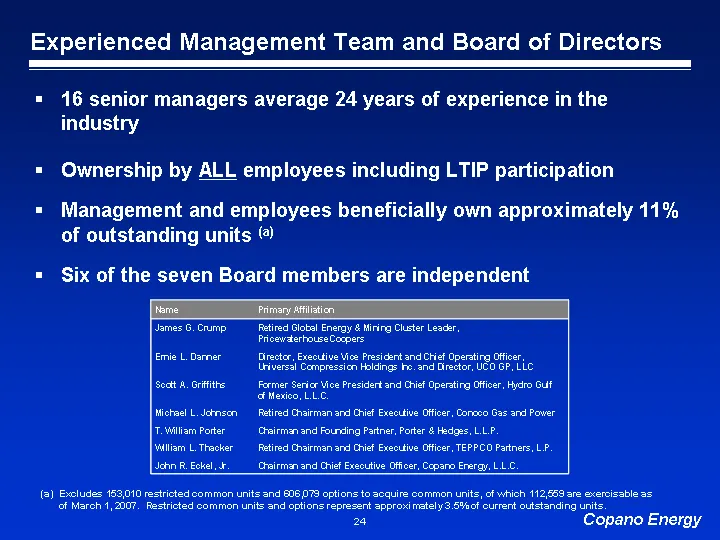
Experienced Management Team and Board of Directors 16 senior managers average 24 years of experience in the industry Ownership by ALL employees including LTIP participation Management and employees beneficially own approximately 11% of outstanding units (a) Six of the seven Board members are indepen
Slide 25: Total Segment Gross Margin
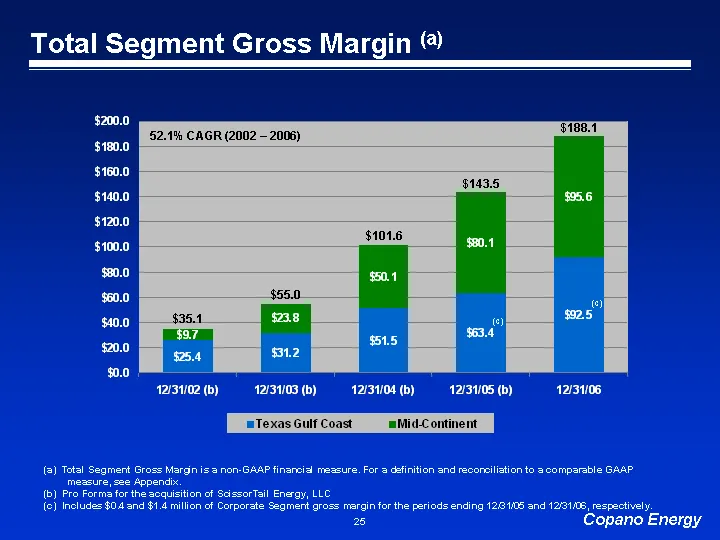
(c) $35.1 $55.0 $101.6 $143.5 (c) 52.1% CAGR (2002 - 2006) $188.1 Total Segment Gross Margin (a) (a) Total Segment Gross Margin is a non-GAAP financial measure. For a definition and reconciliation to a comparable GAAP measure, see Appendix. (b) Pro Forma for the acquisition of ScissorTail Energy, LL
Slide 26: Combined EBITDA
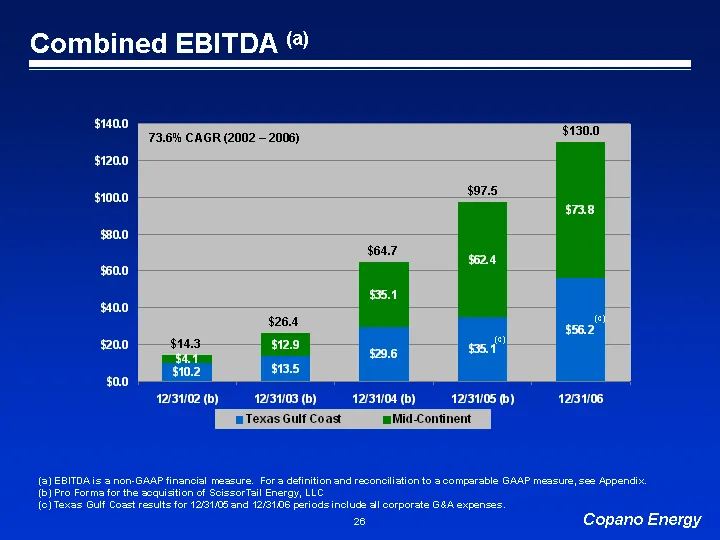
Combined EBITDA (a) (a) EBITDA is a non-GAAP financial measure. For a definition and reconciliation to a comparable GAAP measure, see Appendix. (b) Pro Forma for the acquisition of ScissorTail Energy, LLC (c) Texas Gulf Coast results for 12/31/05 and 12/31/06 periods include all corporate G&A expens
Slide 27: Appendix
Appendix
Slide 28: Reconciliation of Non-GAAP Financial Measures: Gross Margin
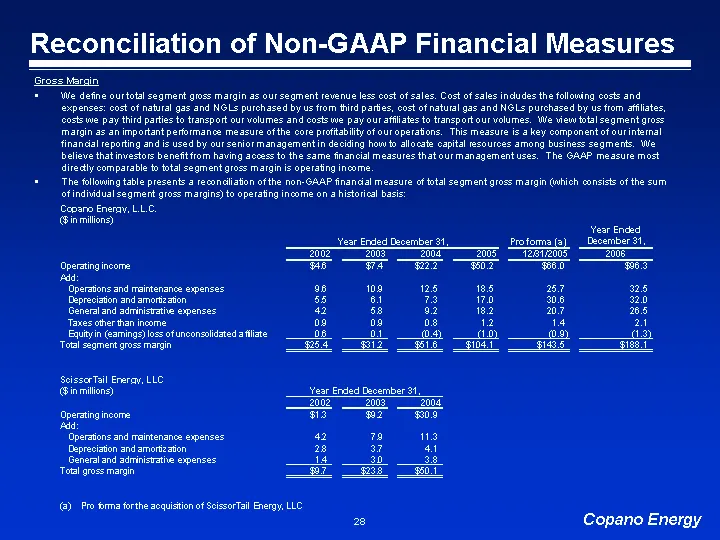
Reconciliation of Non-GAAP Financial Measures Gross Margin We define our total segment gross margin as our segment revenue less cost of sales. Cost of sales includes the following costs and expenses: cost of natural gas and NGLs purchased by us from third parties, cost of natural gas and NGLs purcha
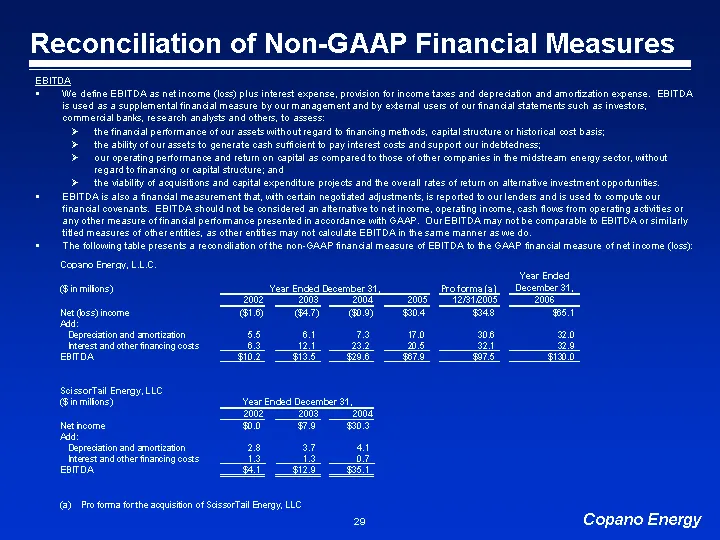
Slide 29: Reconciliation of Non-GAAP Financial Measures: EBITDA
Reconciliation of Non-GAAP Financial Measures EBITDA We define EBITDA as net income (loss) plus interest expense, provision for income taxes and depreciation and amortization expense. EBITDA is used as a supplemental financial measure by our management and by external users of our financial statemen
Slide 30: Copano Energy
Copano Energy
Source: SEC EDGAR · 8-K filed Apr 2, 2007
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011