CSI Compressco LP — 4th Annual Credit Suisse MLP and Energy Logistics Conference 2016
24 slides from CSI Compressco LP's conference presentation, Jun 21, 2016
Slide 1: Credit Suisse MLP and Energy Logistics Conference
Ath Annual Credit Suisse MEP and Energy Logistics Conference June 21, 2016 Tim Knox President Elijio Serrano Chief Finaneial Officer TETRA Technologies, Inc. <p’ COMPRESSCO LP” www.CSICompressco.com ©2016 CSI Compressco LP
Slide 2: Forward Looking Statements
Forward Looking Statements ‘<p’ COMPRESSCO LP” This presentation contains “forward-looking statements” and information based on our beliefs and those of our general partner. Forward-looking statements in this presentation are identifiable by the use of the following words and other similar words: “a
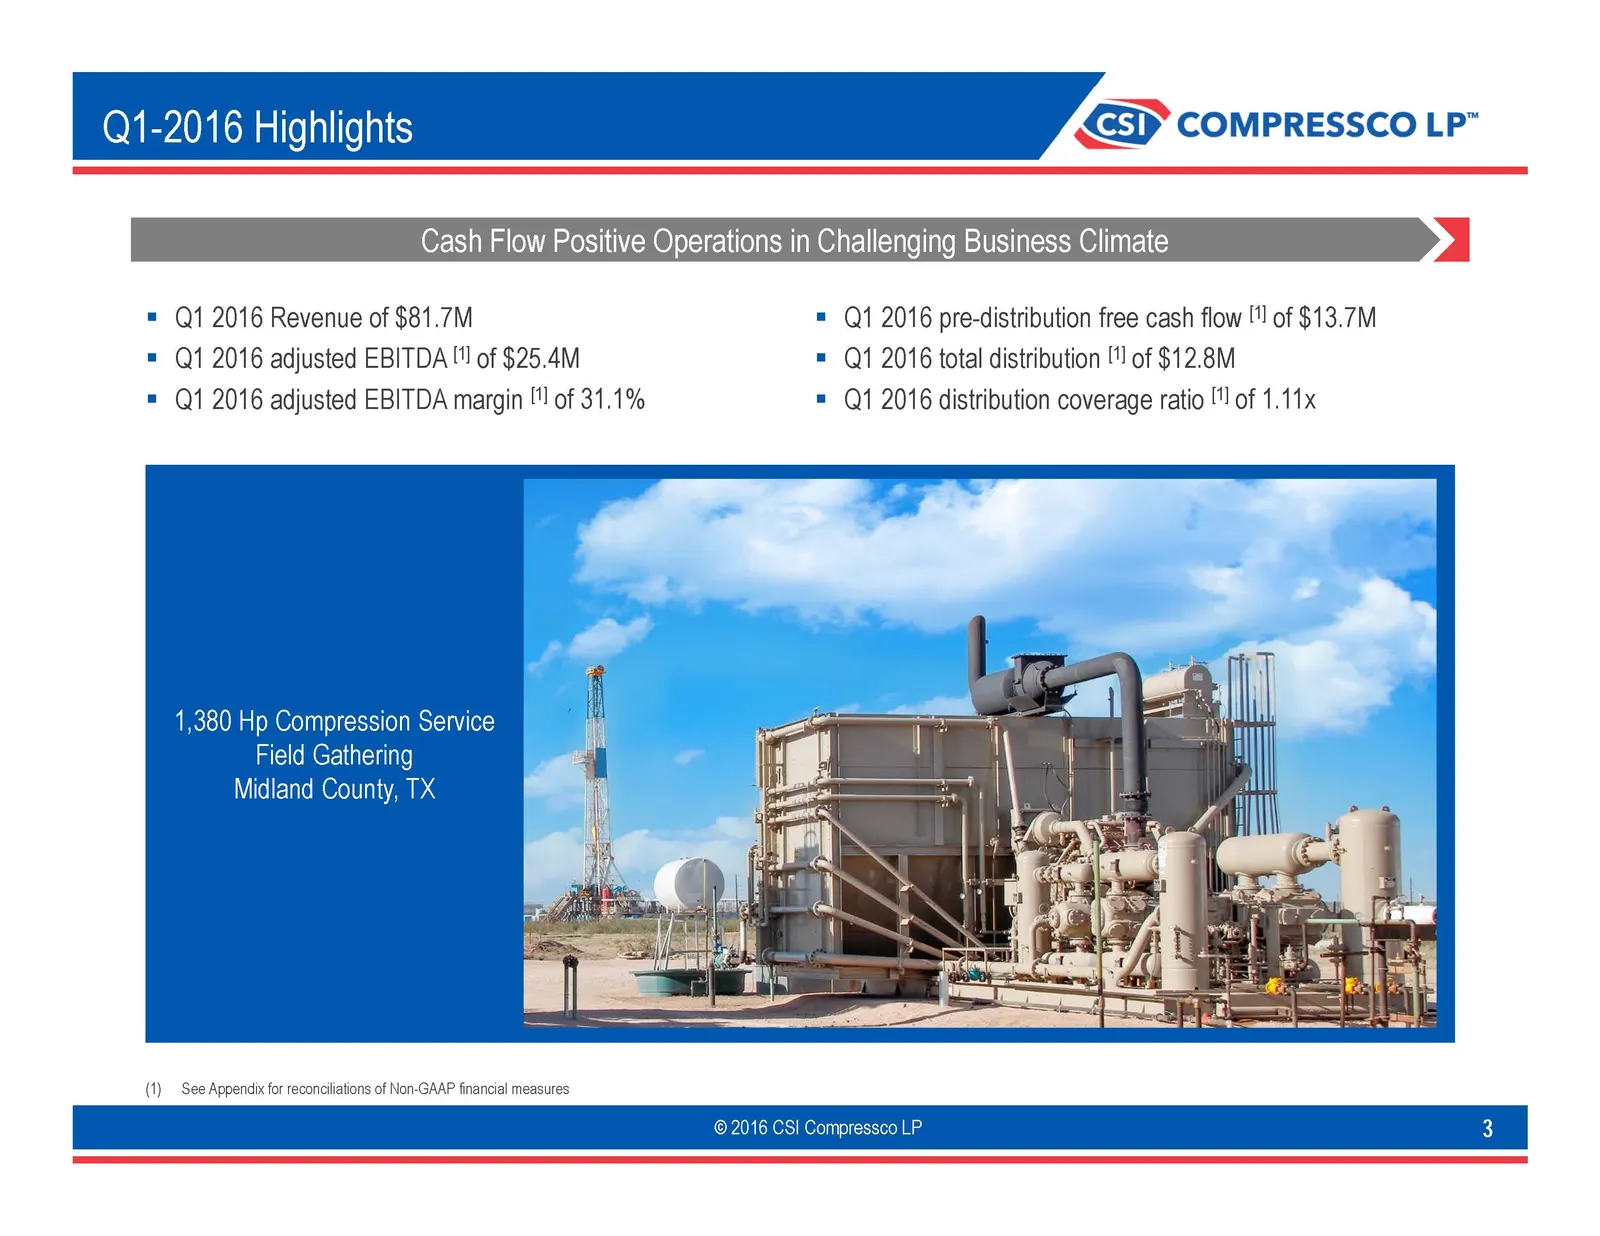
Slide 3: Q1-2016 Highlights
Q1-2016 Highlights ‘<p’ COMPRESSCO LP” Cash Flow Positive Operations in Challenging Business Climate > | = Q1 2016 Revenue of $81.7M = Q1 2016 pre-distribution free cash flow !"l of $13.7M = Q1 2016 adjusted EBITDA " of $25.4M = Q1 2016 total distribution "! of $12.8M = Q1 2016 adjusted EBITDA margi
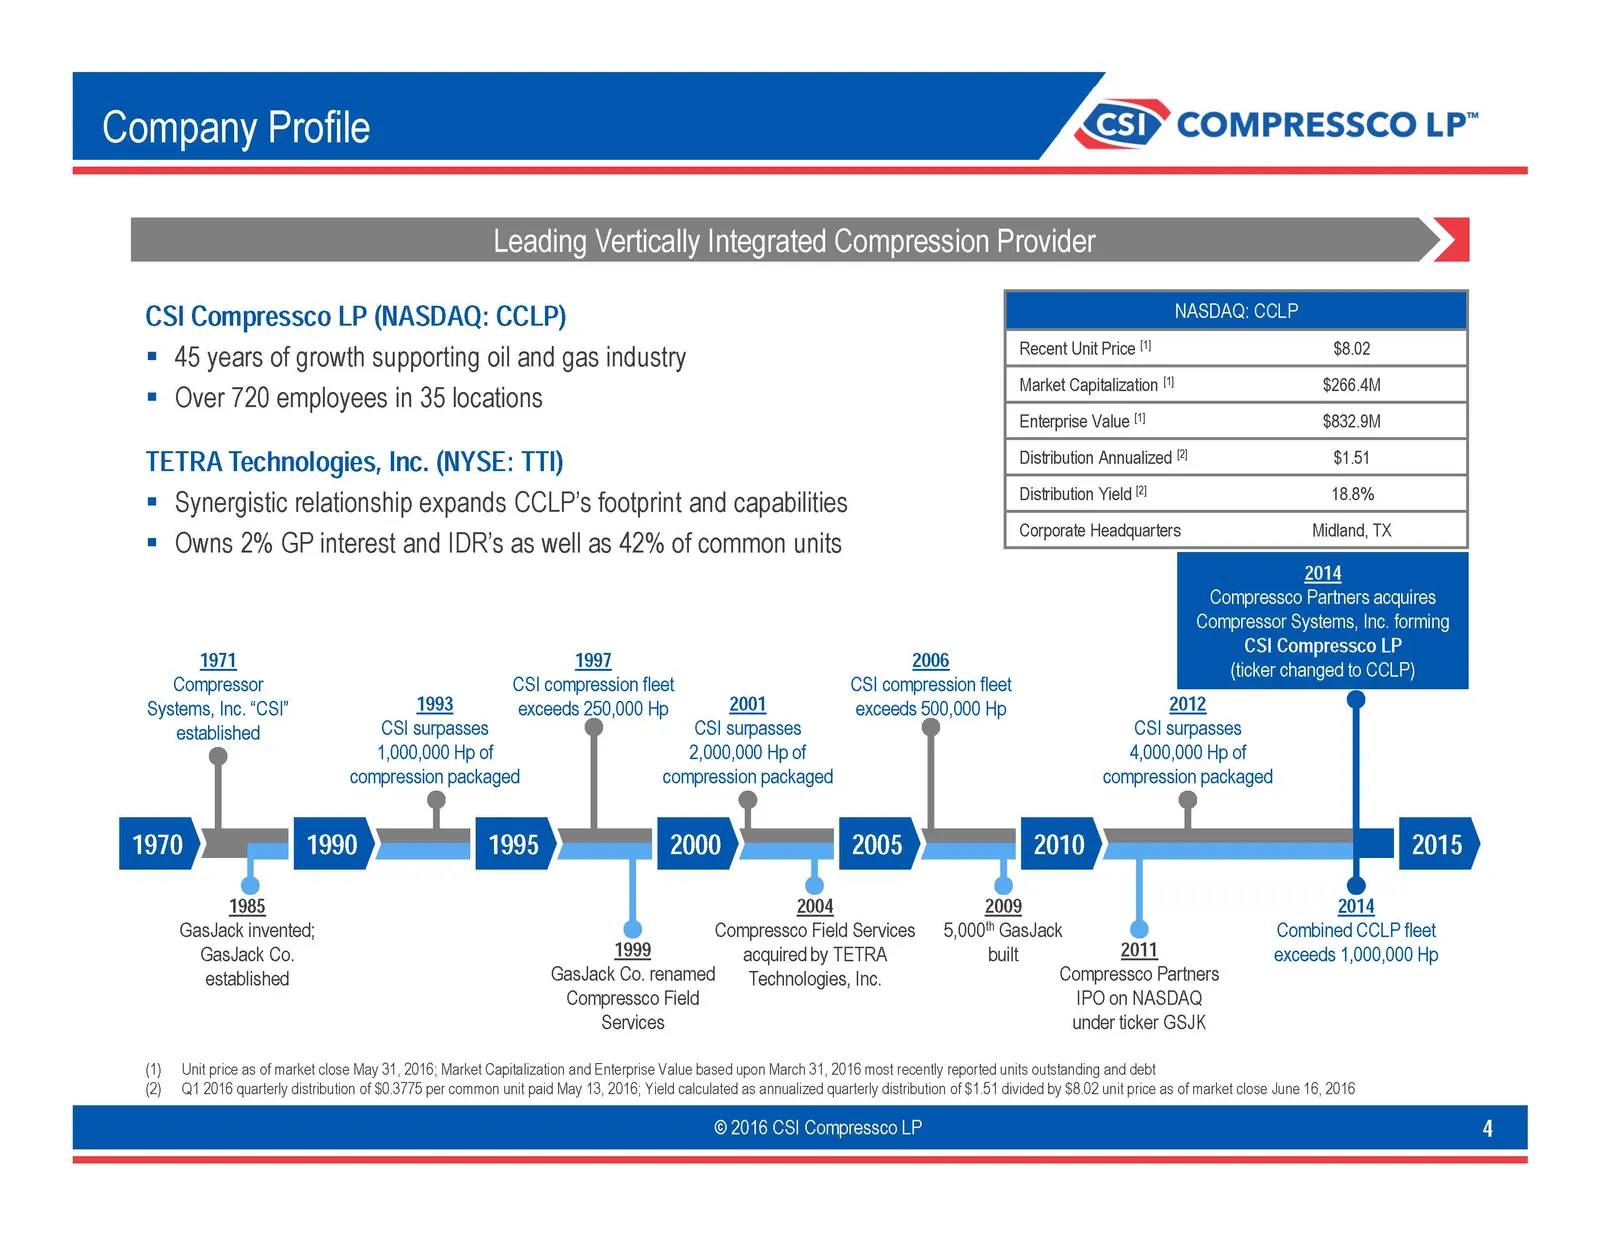
Slide 4: Company Profile
Company Profile ‘Ep’ COMPRESSCO LP™ ading Vertically Integrated Compression Provider >| CSI Compressco LP (NASDAQ: CCLP) = 45 years of growth supporting oil and gas industry Recent Und Price $8.02 = Over 720 employees in 35 locations Market Capitalization $266.44 Enterprise Value [11 $832.9M TETRA T
Slide 5: Investment Highlights
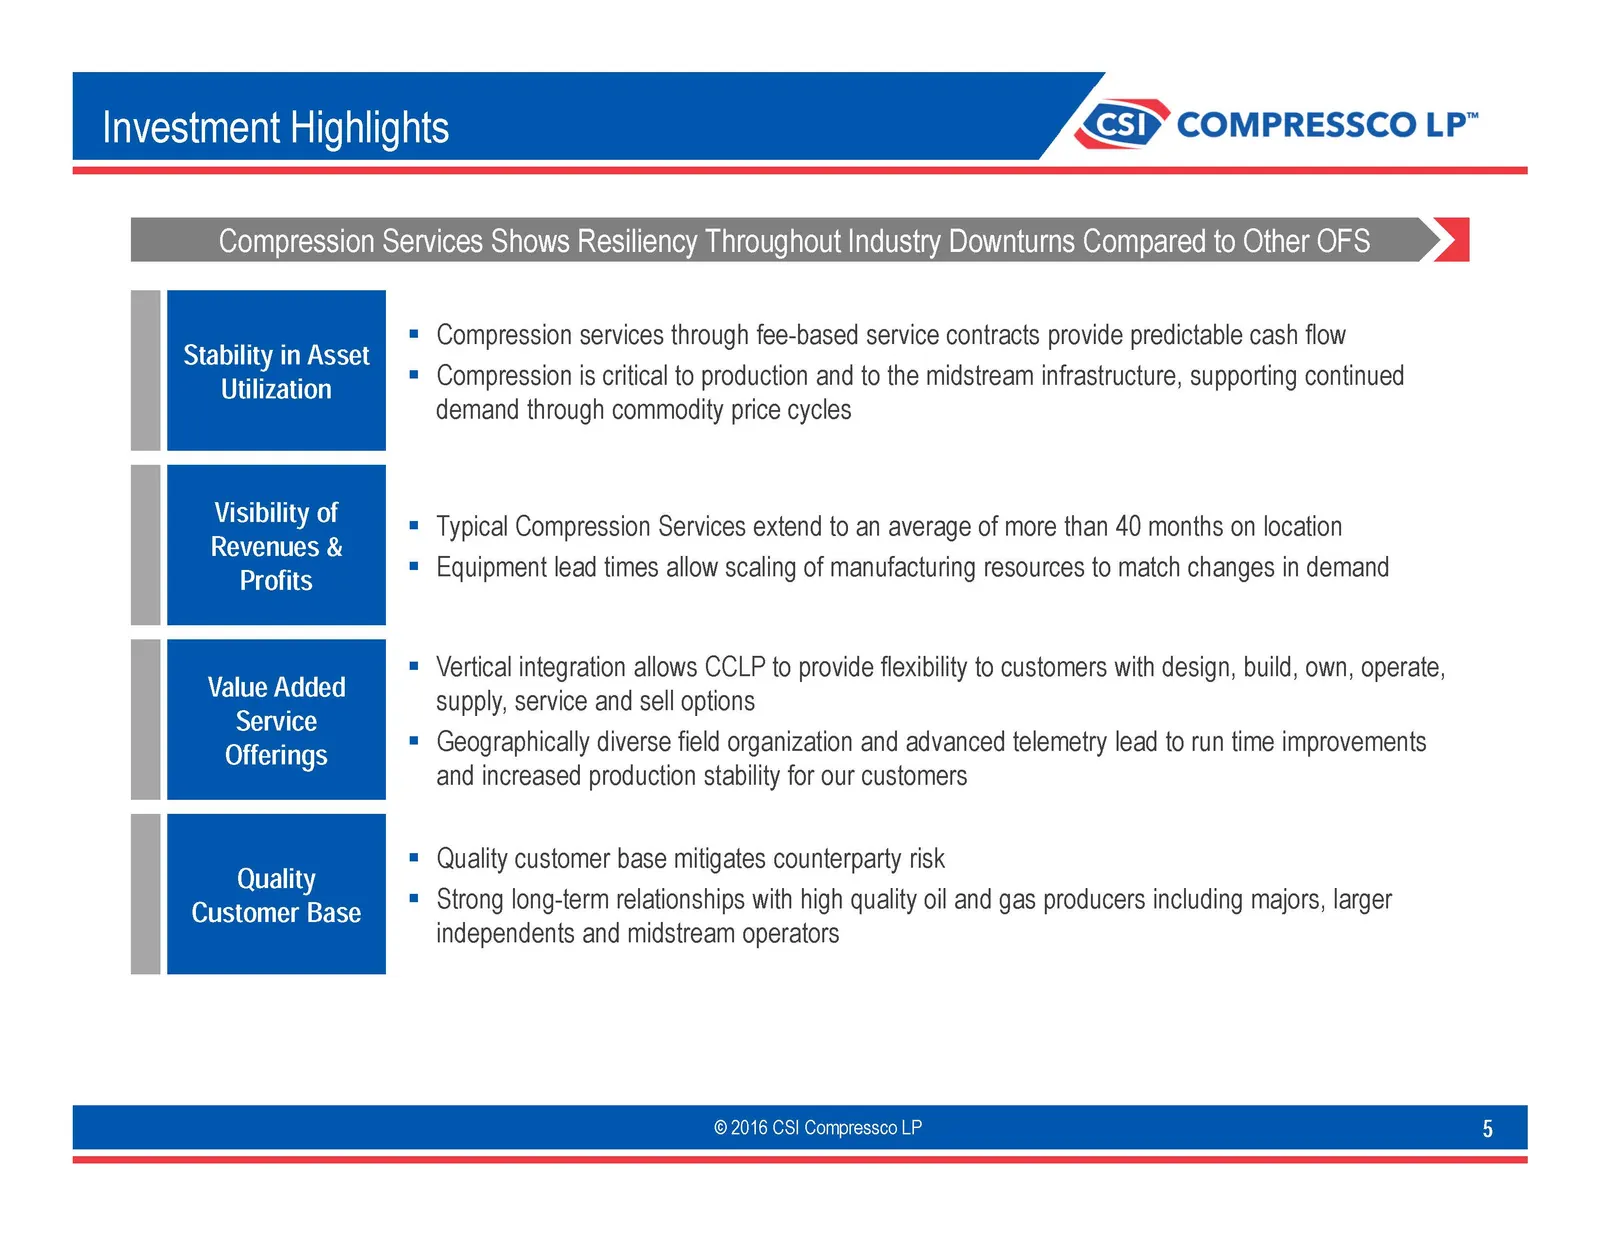
Inves Highlig ‘Ep’ COMPRESSCO LP™ Stability in Asset Utilization Visibility of Revenues & Profits Value Added Service Offerings Quality Customer Base Compression Services Shows Resiliency Throughout Industry Downturns Compared to Other OFS >| Compression services through fee-based service contracts
Slide 6: Compression Overview
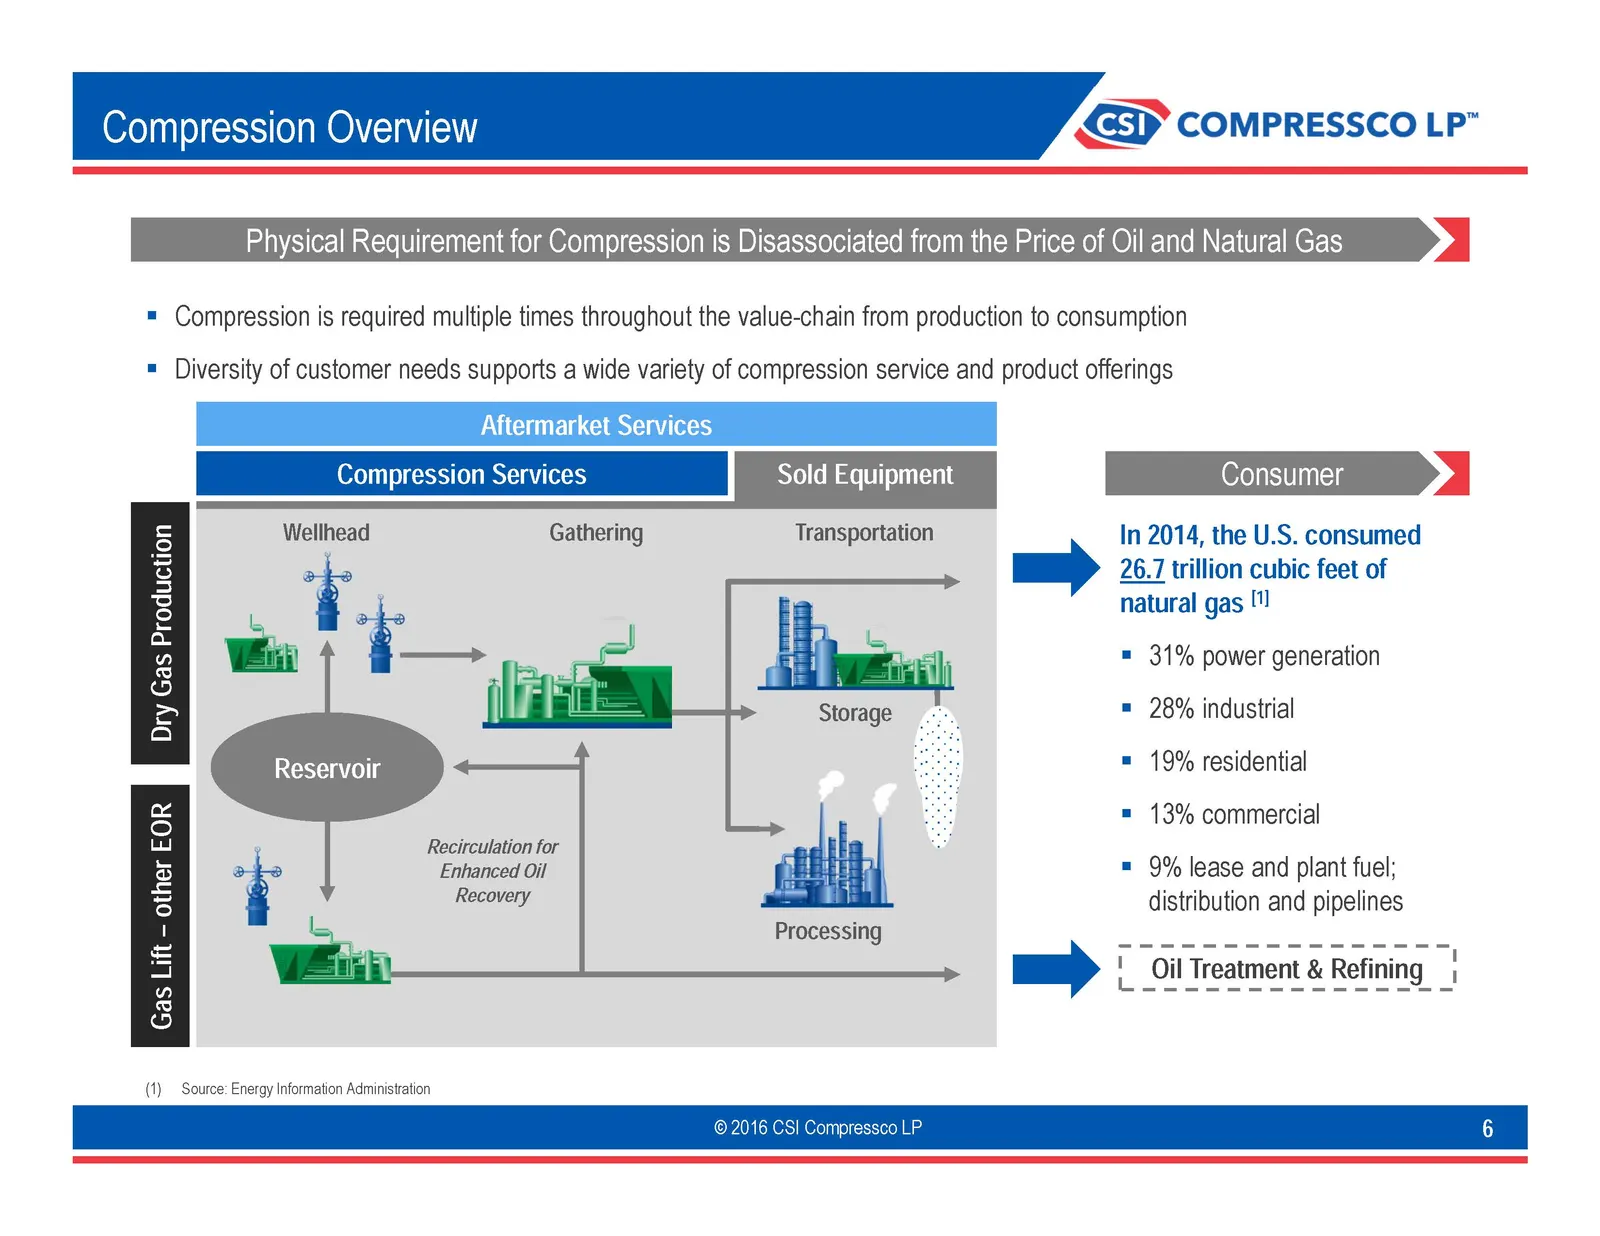
Compression Overview ‘<p’ COMPRESSCO LP” Physical Requirement for Compression is Disassociated from the Price of Oil and Natural Gas >| = Compression is required multiple times throughout the value-chain from production to consumption = Diversity of customer needs supports a wide variety of compress
Slide 7: Demand and Production
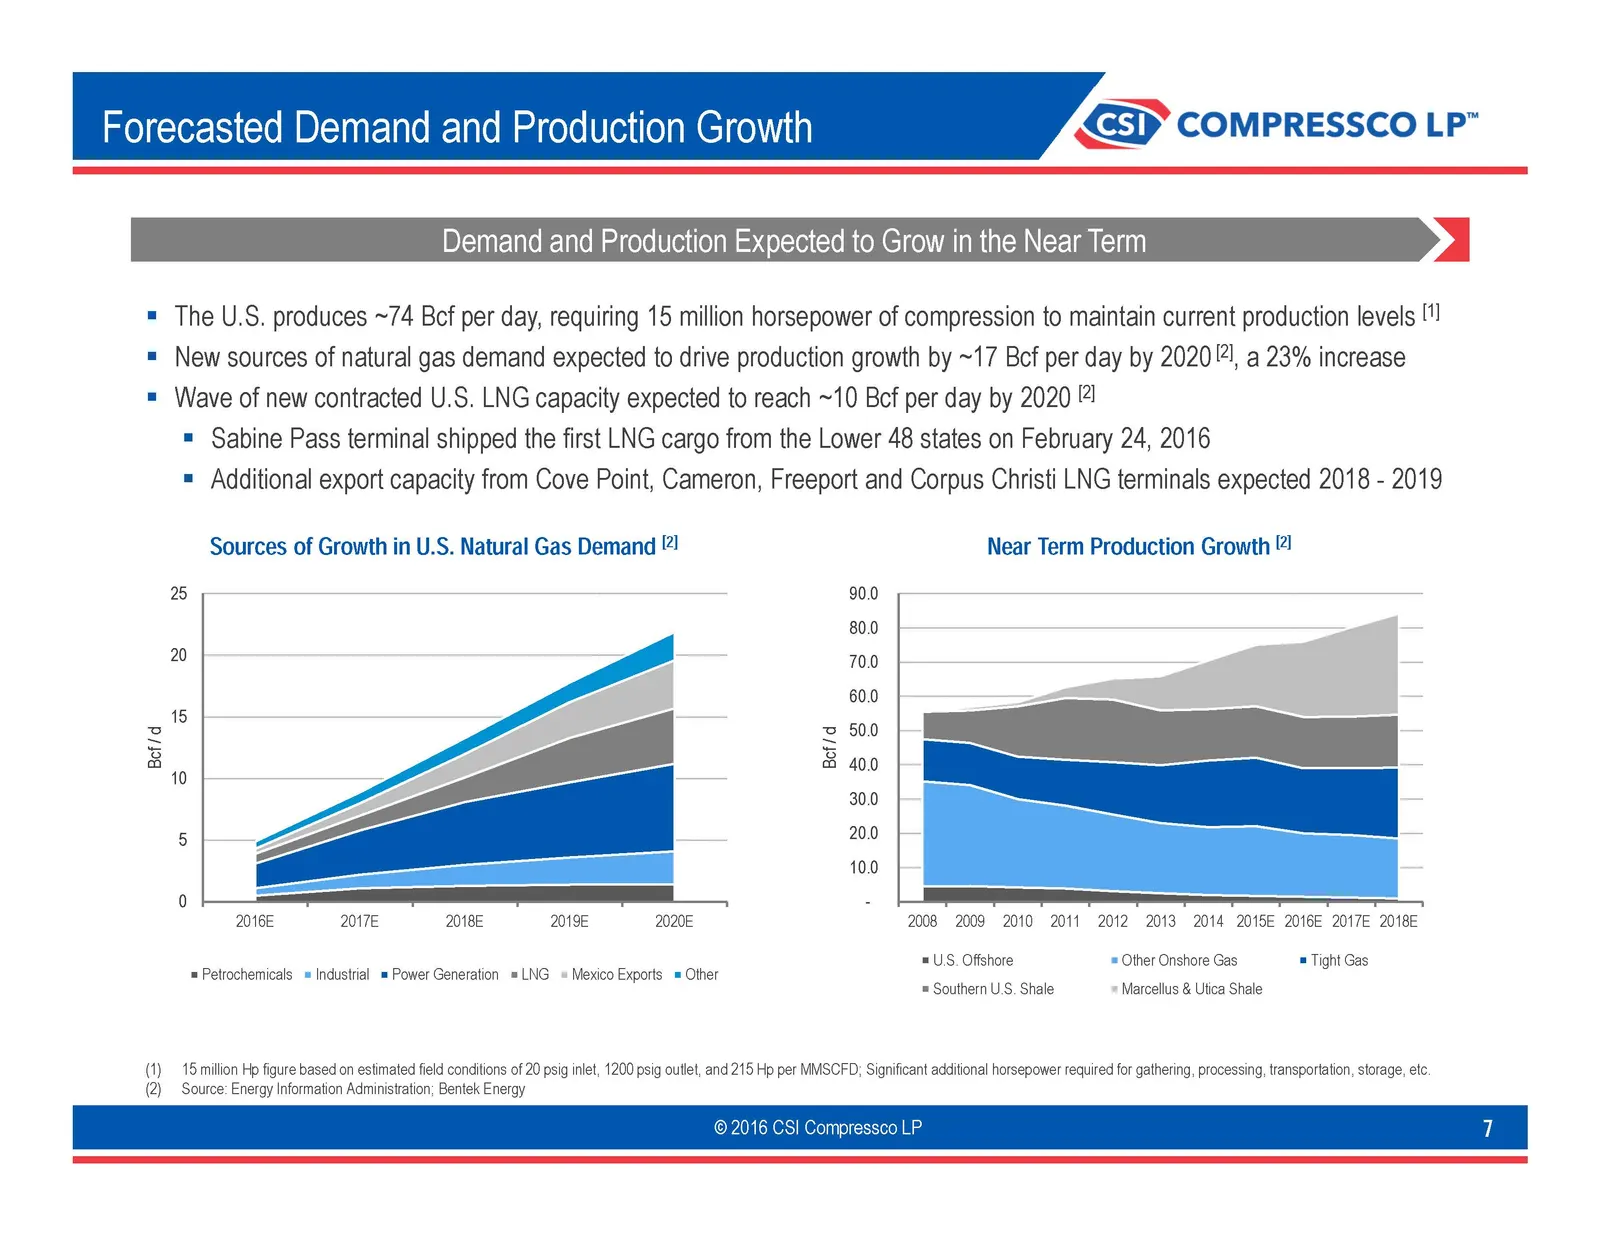
Demand and Production kcsiy COMPRESSCO LP” Demand and Production Expected to Grow in the Near Term >| = The U.S. produces ~74 Bef per day, requiring 15 million horsepower of compression to maintain current production levels !"! = New sources of natural gas demand expected to drive production growth
Slide 8: Shale gas supply and growth requires infrastructure
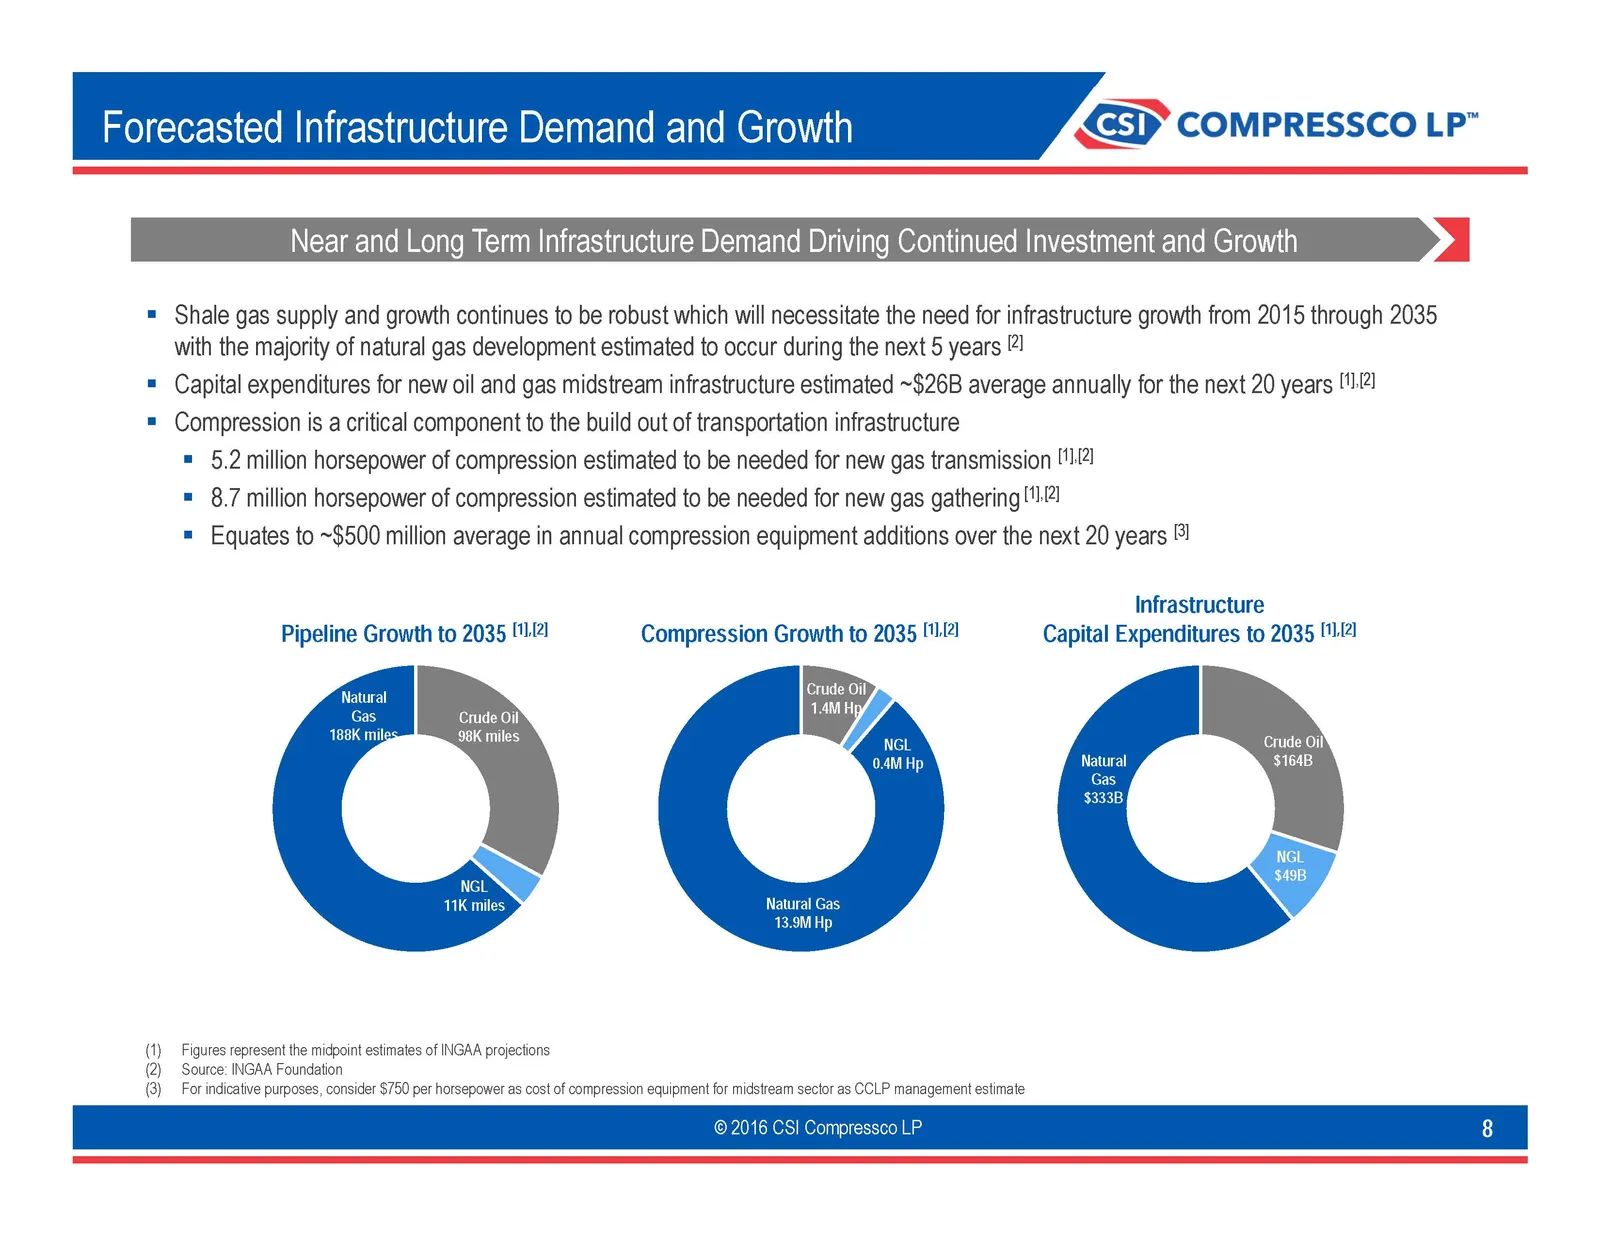
= Shale gas supply and growth continues to be robust which will necessitate the need for infrastructure growth from 2015 through 2035 with the majority of natural gas development estimated to occur during the next 5 years 21 = Capital expenditures for new oil and gas midstream infrastructure estimat
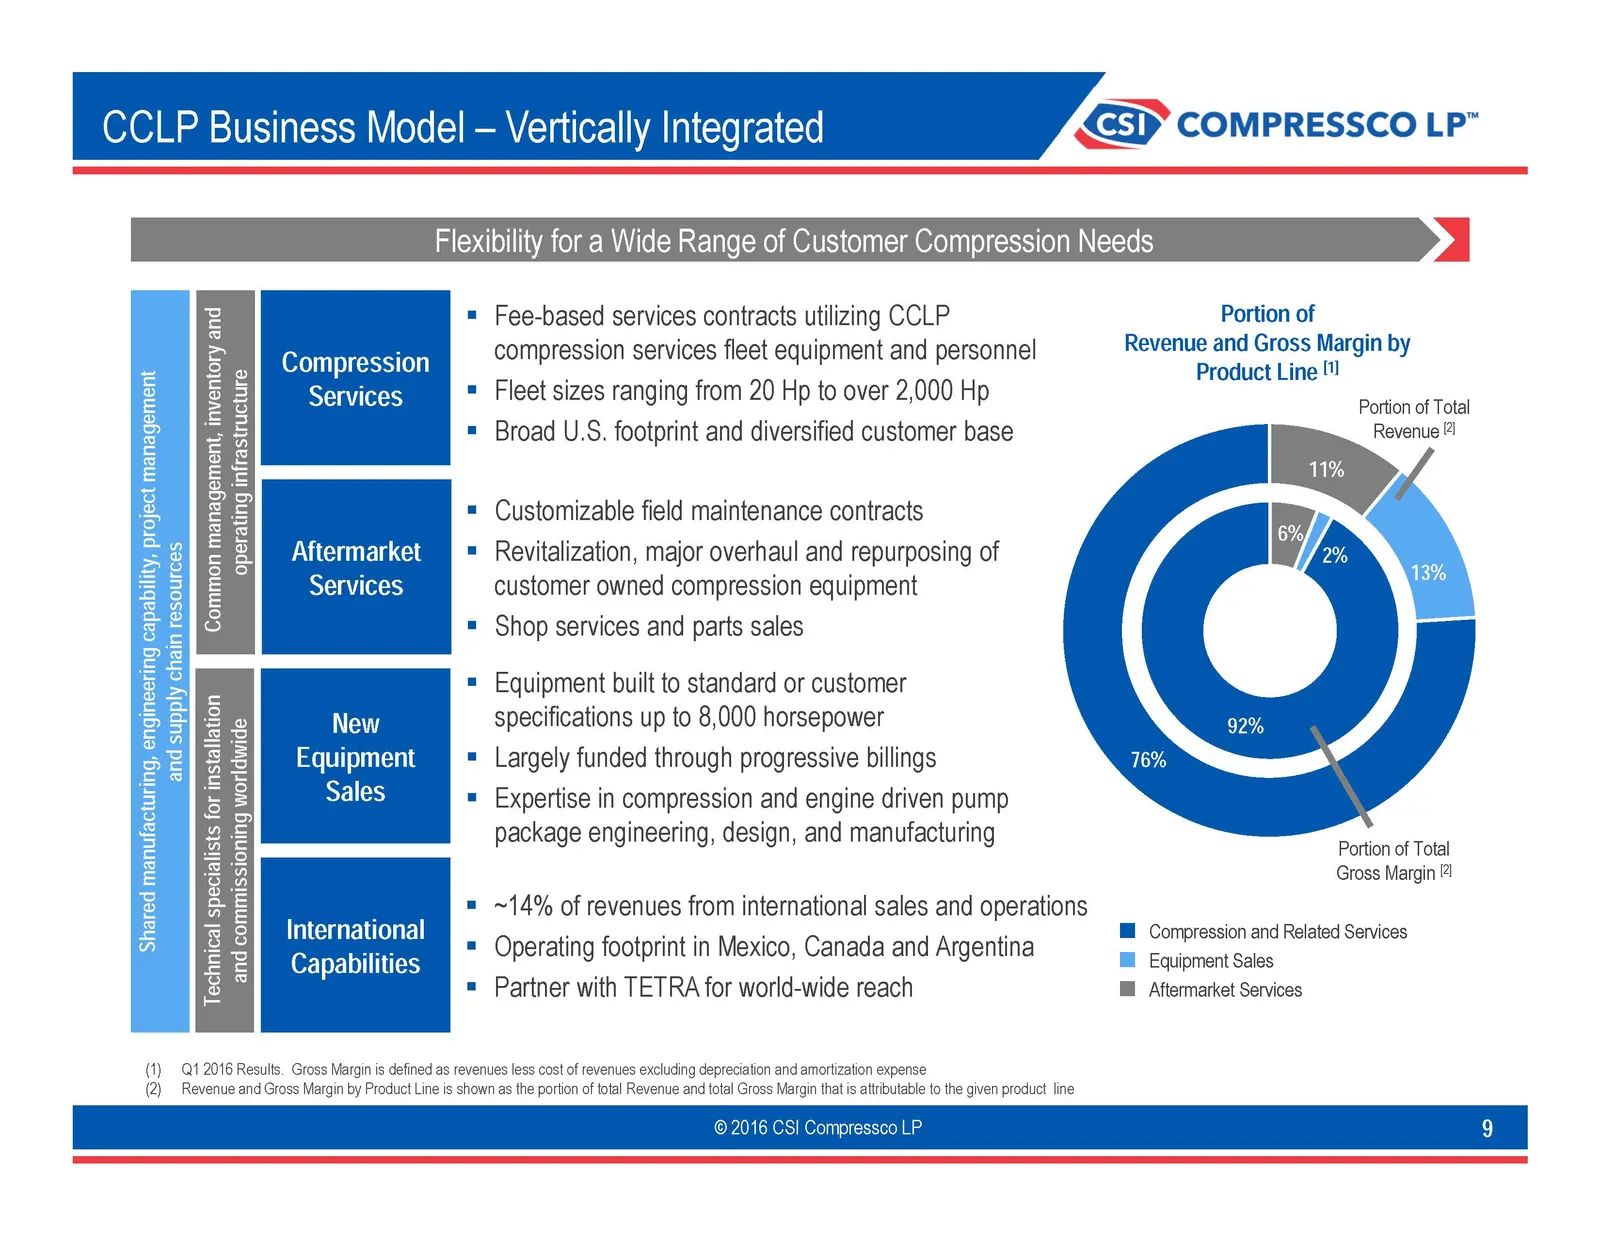
Slide 9: CCLP Business Model — Vertically Integrated
CCLP Business Model — Vertically Integrated = o 5, S i s £ 3 &. iS a a a 3 5 D & = i= = o i} £ FI o cs Sj S ] £ ao} 2 I ce a Compression Services Aftermarket Services Common management, inventory and operating infrastructure New Equipment Sales a ry 2 S| 3 ca & I iS o = rol eH SI a a=} = o Internati
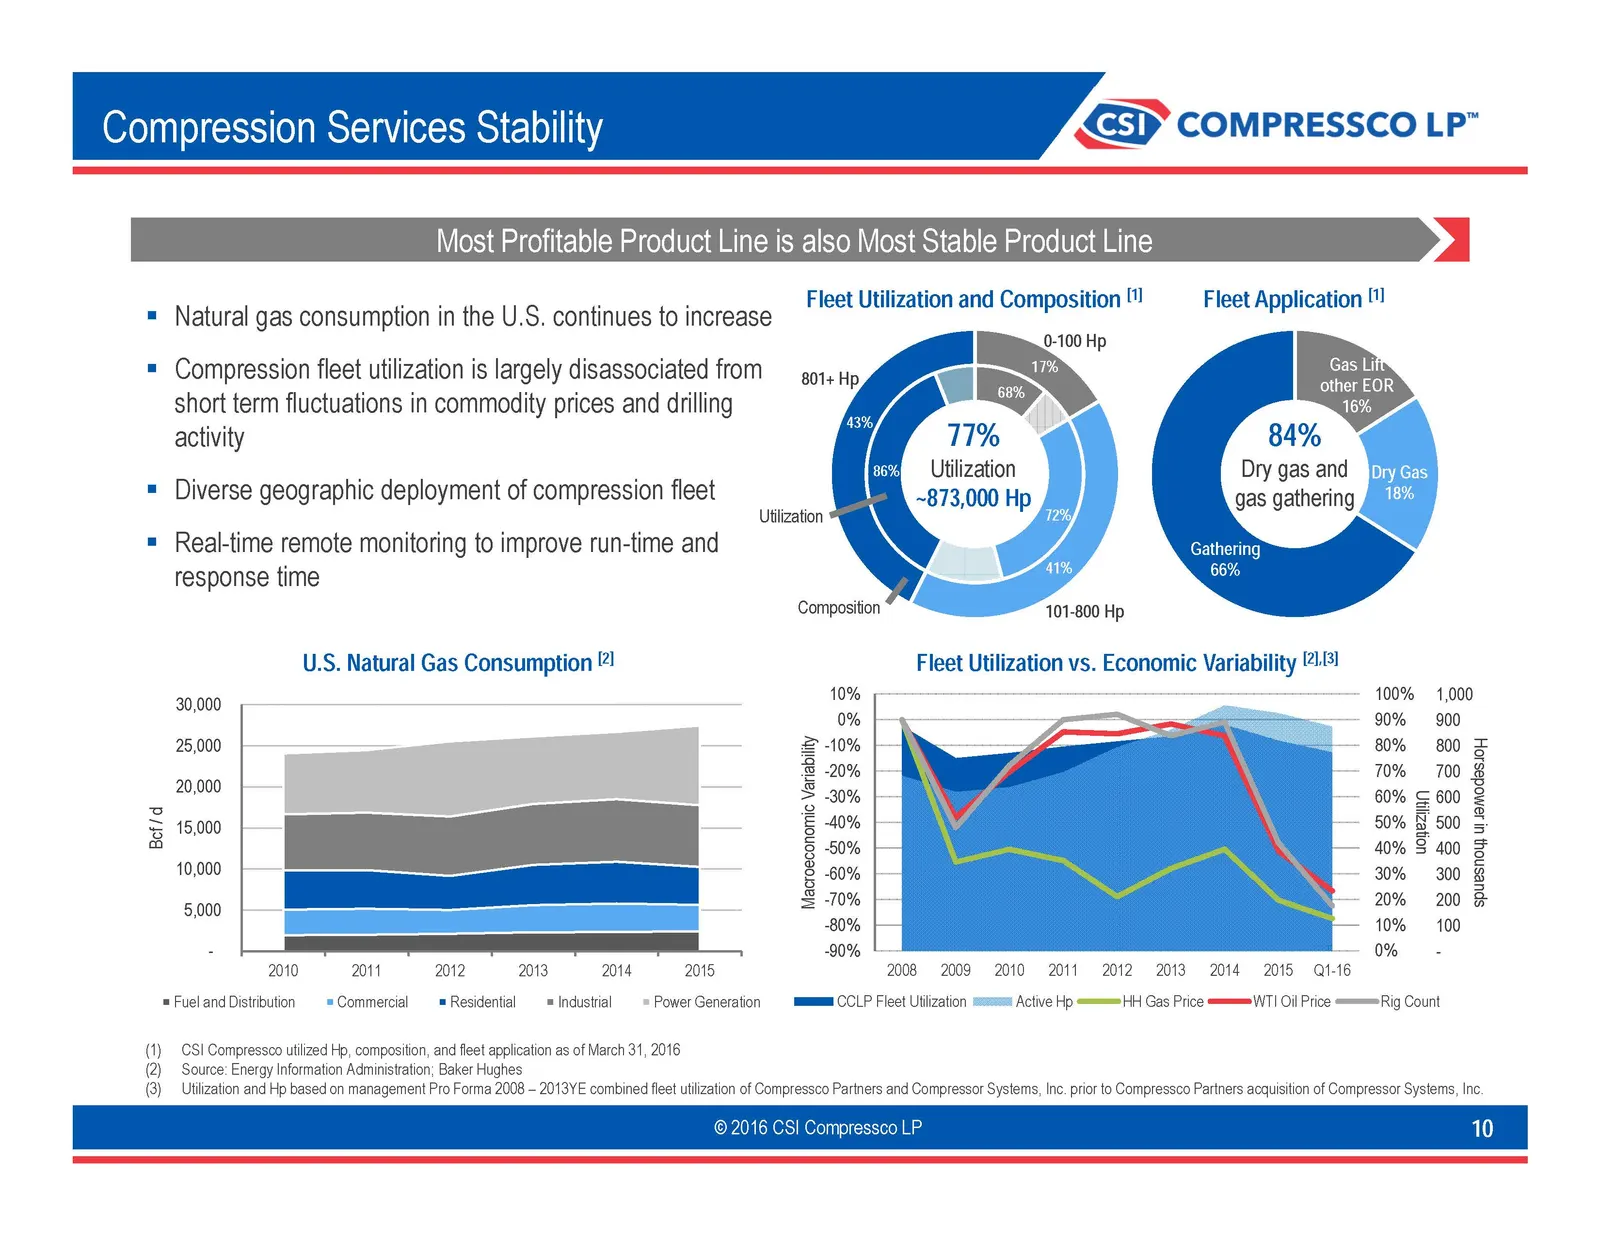
Slide 10: Compression Services Stability
Compression Services Stability t Line is also Most Stable Product Line Fleet Utilization and Composition " Fleet Application Natural gas consumption in the U.S. continues to increase 0-100 Hp Compression fleet utilization is largely disassociated from ——gg1, Hp short term fluctuations in commodity p
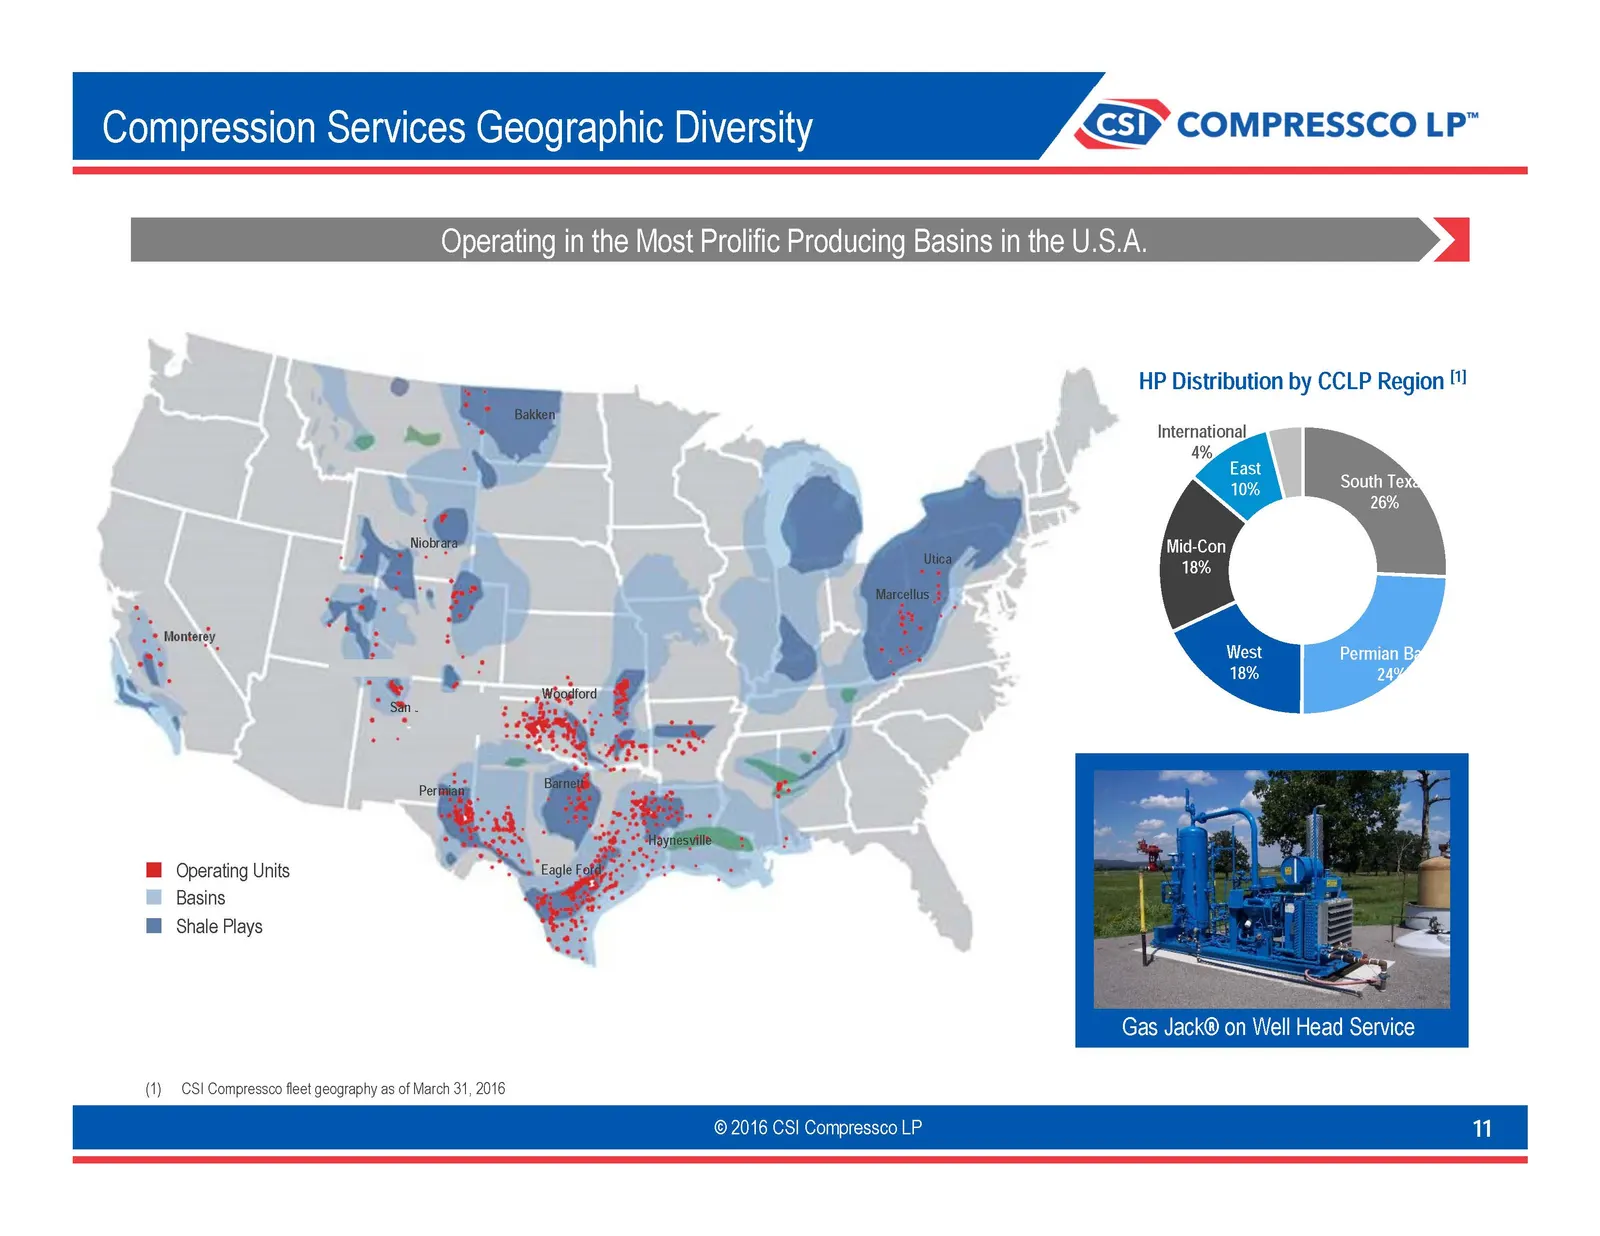
Slide 11: Compression Services Geographic Diversity
Compression Services Geographic Diversity ‘<p’ COMPRESSCO LP” Operating in the Most Prolific Producing Basins in the U.S.A. HP Distribution by CCLP Region ! International % " g \Ly A= Permian B 24g Operating Units Basins Shale Plays (1) CS1Compressco fleet geography as of March 31, 2016 ©2016 C pres
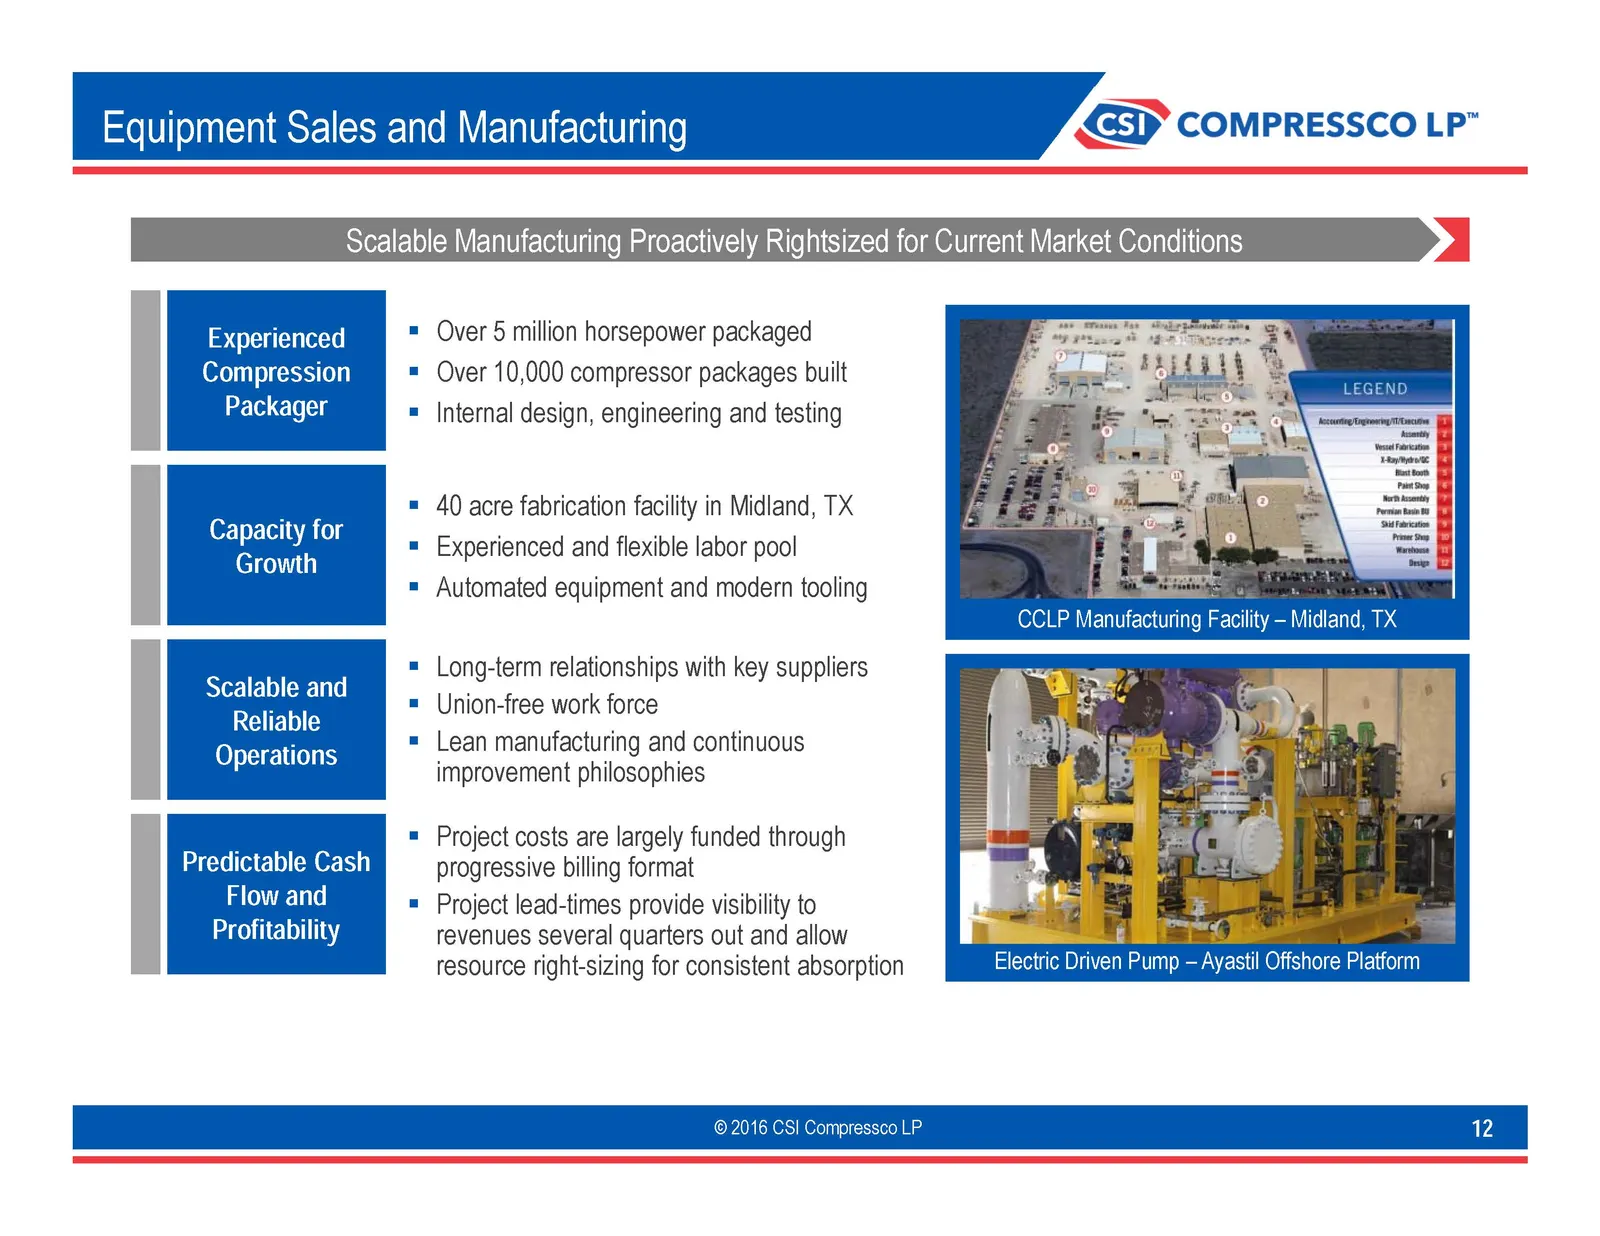
Slide 12: Equipment Sales and Manufacturing
Eq Sales a ufacturing <p’ COMPRESSCO LP” Scalable Manufacturing Proactively Rightsized for Current Market Conditions Over 5 million horsepower packaged Over 10,000 compressor packages built Internal design, engineering and testing Experienced Compression Packager 40 acre fabrication facility in Midl
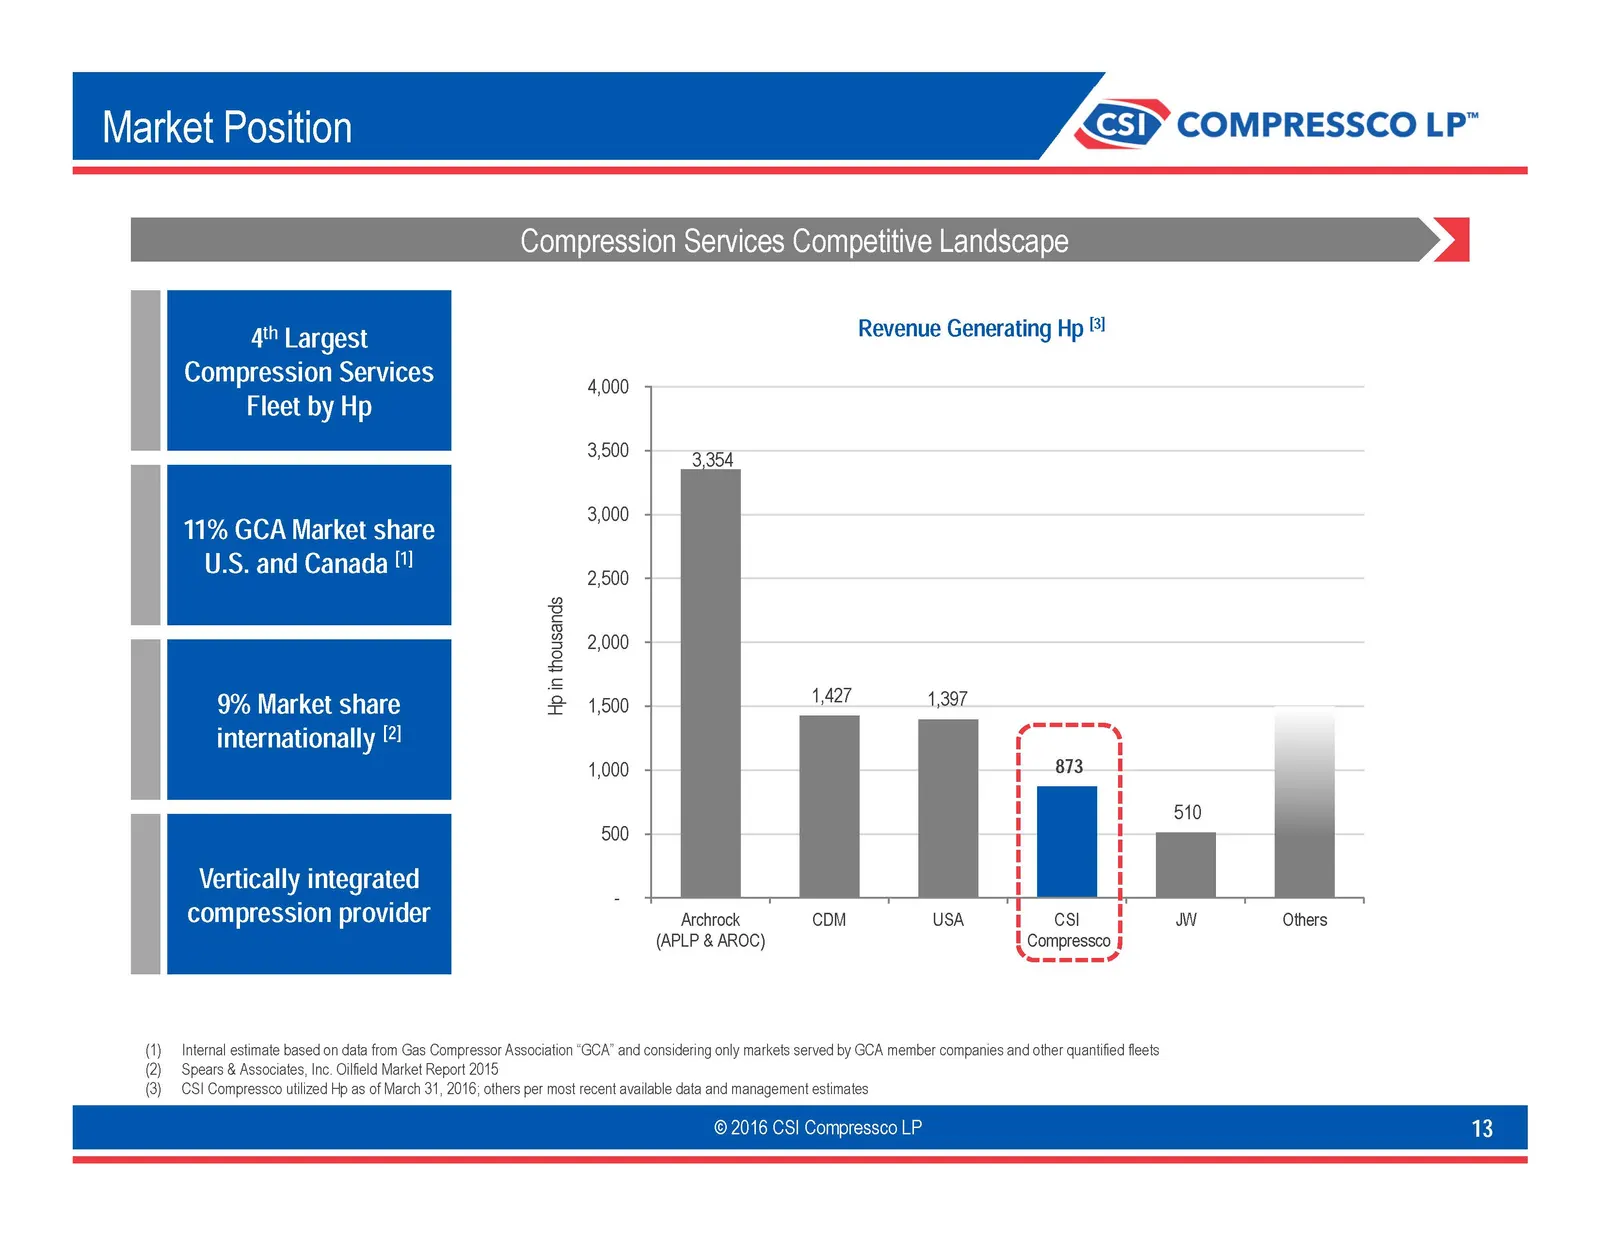
Slide 13: Market Position
Market Position 4" Largest Compression Services Fleet by Hp 11% GCA Market share S. and Canada " 9% Market share internationally 1 Vertically integrated compression provider Hp in thousands 4,000 3,500 3,000 2,500 2,000 1,500 1,000 500 es Competitive Landscape Revenue Generating Hp §! 3,354 1,427 1,
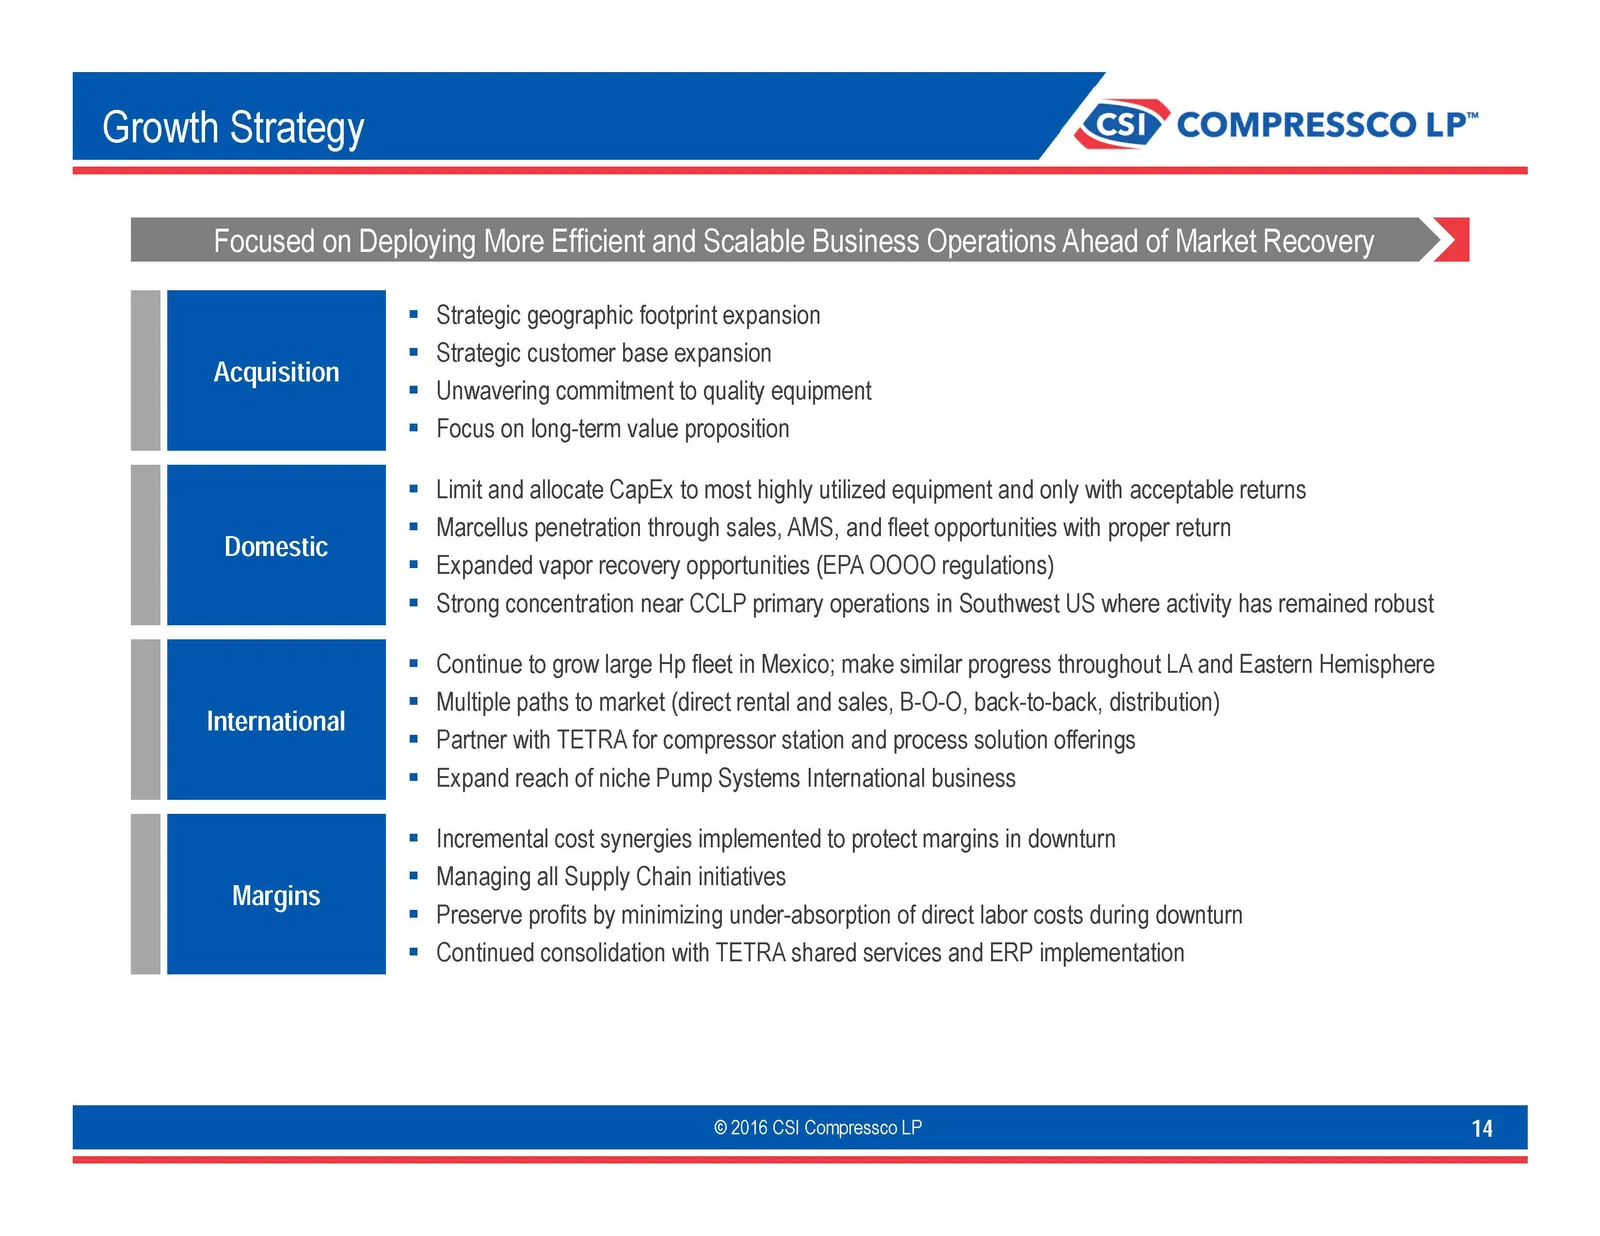
Slide 14: Growth Strategy
owth Strateg ‘Ep’ COMPRESSCO LP™ Deploying More Efficient and Scalable Business Operations Ahead of Market Recovery >| Strategic geographic footprint expansion Strategic customer base expansion Unwavering commitment to quality equipment Focus on long-term value proposition Acquisition i Limit and al
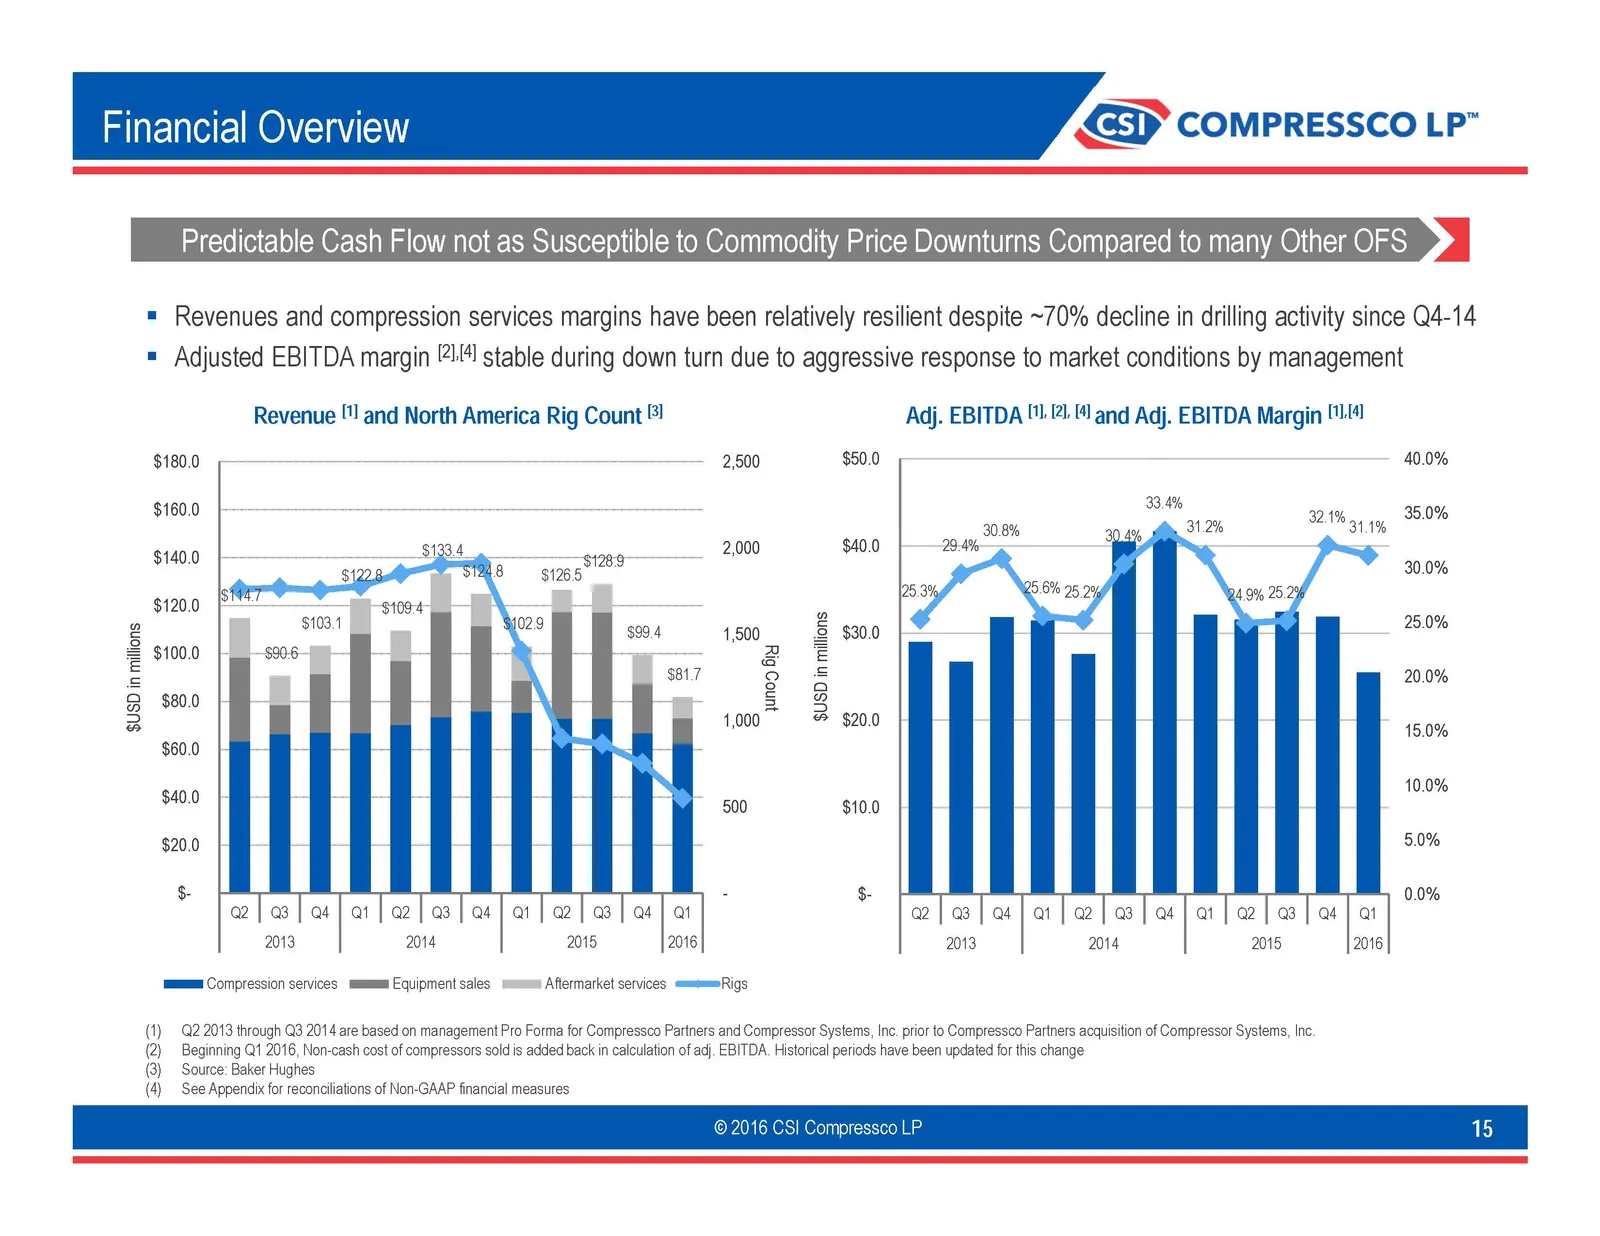
Slide 15: Financial Overview
Financial Overview ‘Ep’ COMPRESSCO LP™ ictable Cash Flow = Revenues and compression services margins have been relatively resilient despite ~70% decline in drilling activity since Q4-14 = Adjusted EBITDA margin )!4l stable during down turn due to aggressive response to market conditions by managemen
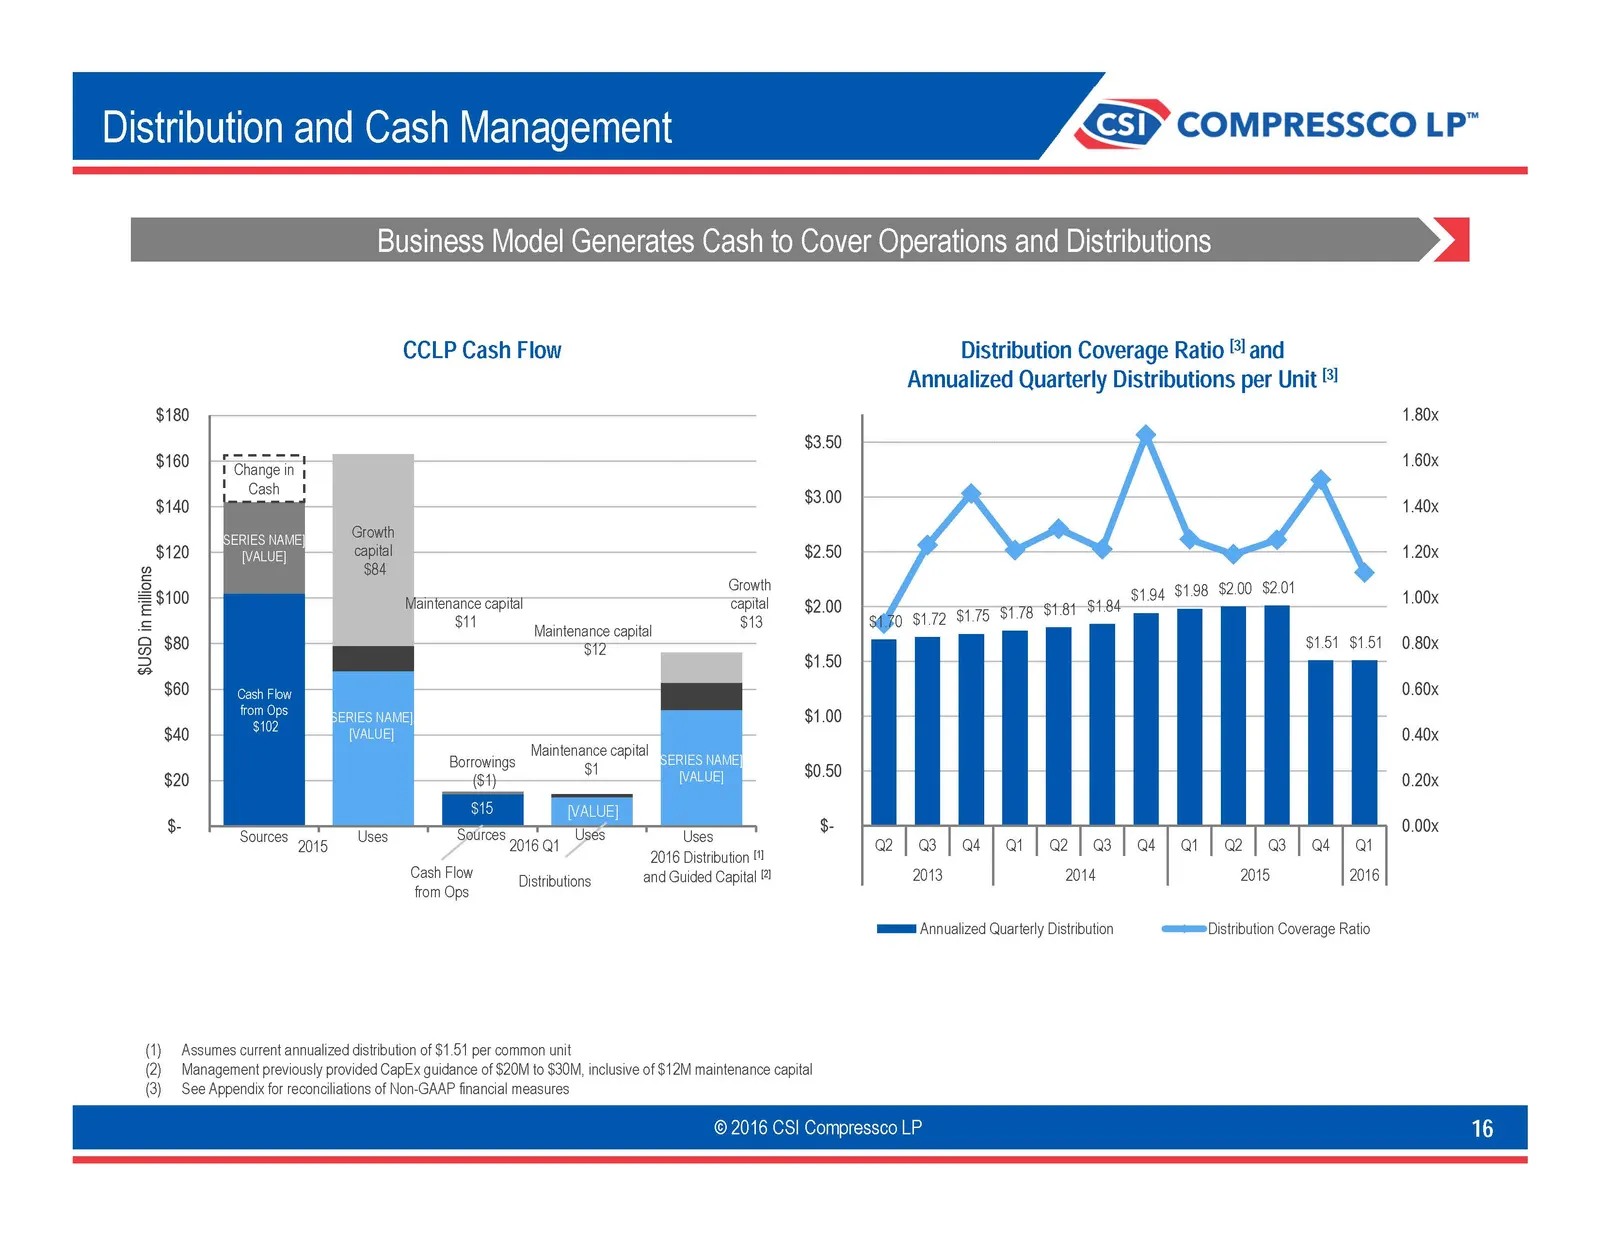
Slide 16: Distribution and Cash Management
Distribution and Cash Management $180 $160 $140 $120 $USD in millions a eg ¢ & 3 2 8 38.8 8 ae ¢ s € 8 6 ¥ CCLP Cash Flow ERIES NAME] Maintenance capital $12 Boronings Mainenene capi eee [VALUE] a E [VALUE] | ources: Uses rear 2016 Distribution (1 Cash Flow Distributions _-—_-and Guided Capita from
Slide 17: Covenants, Debt & Liquidity
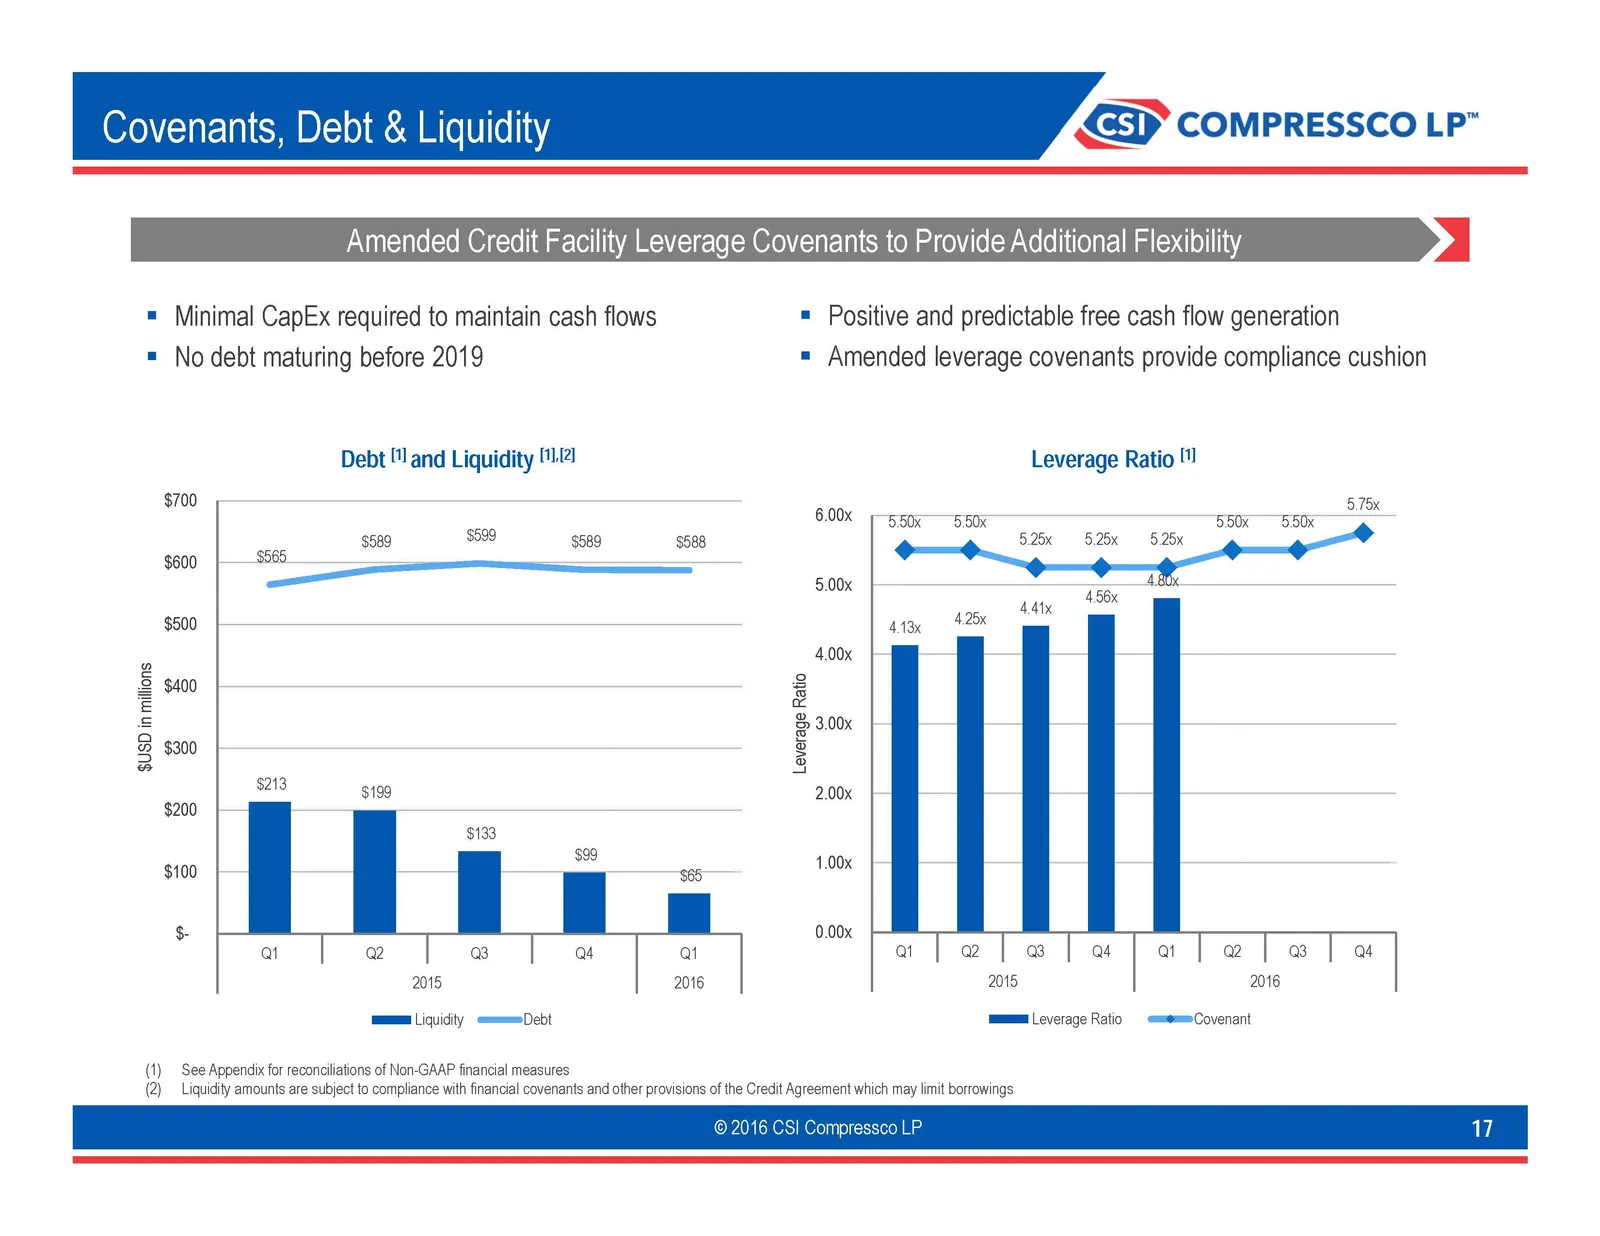
Covenants, Debt & Liquidity ‘Ep’ COMPRESSCO LP™ ide Additional Flexibility >| ded Credit Facility Leverage Covenants to Pri = Minimal CapEx required to maintain cash flows = No debt maturing before 2019 Debt "and Liquidity "1 = Positive and predictable free cash flow generation = Amended leverage co
Slide 18: Counterparty Risk
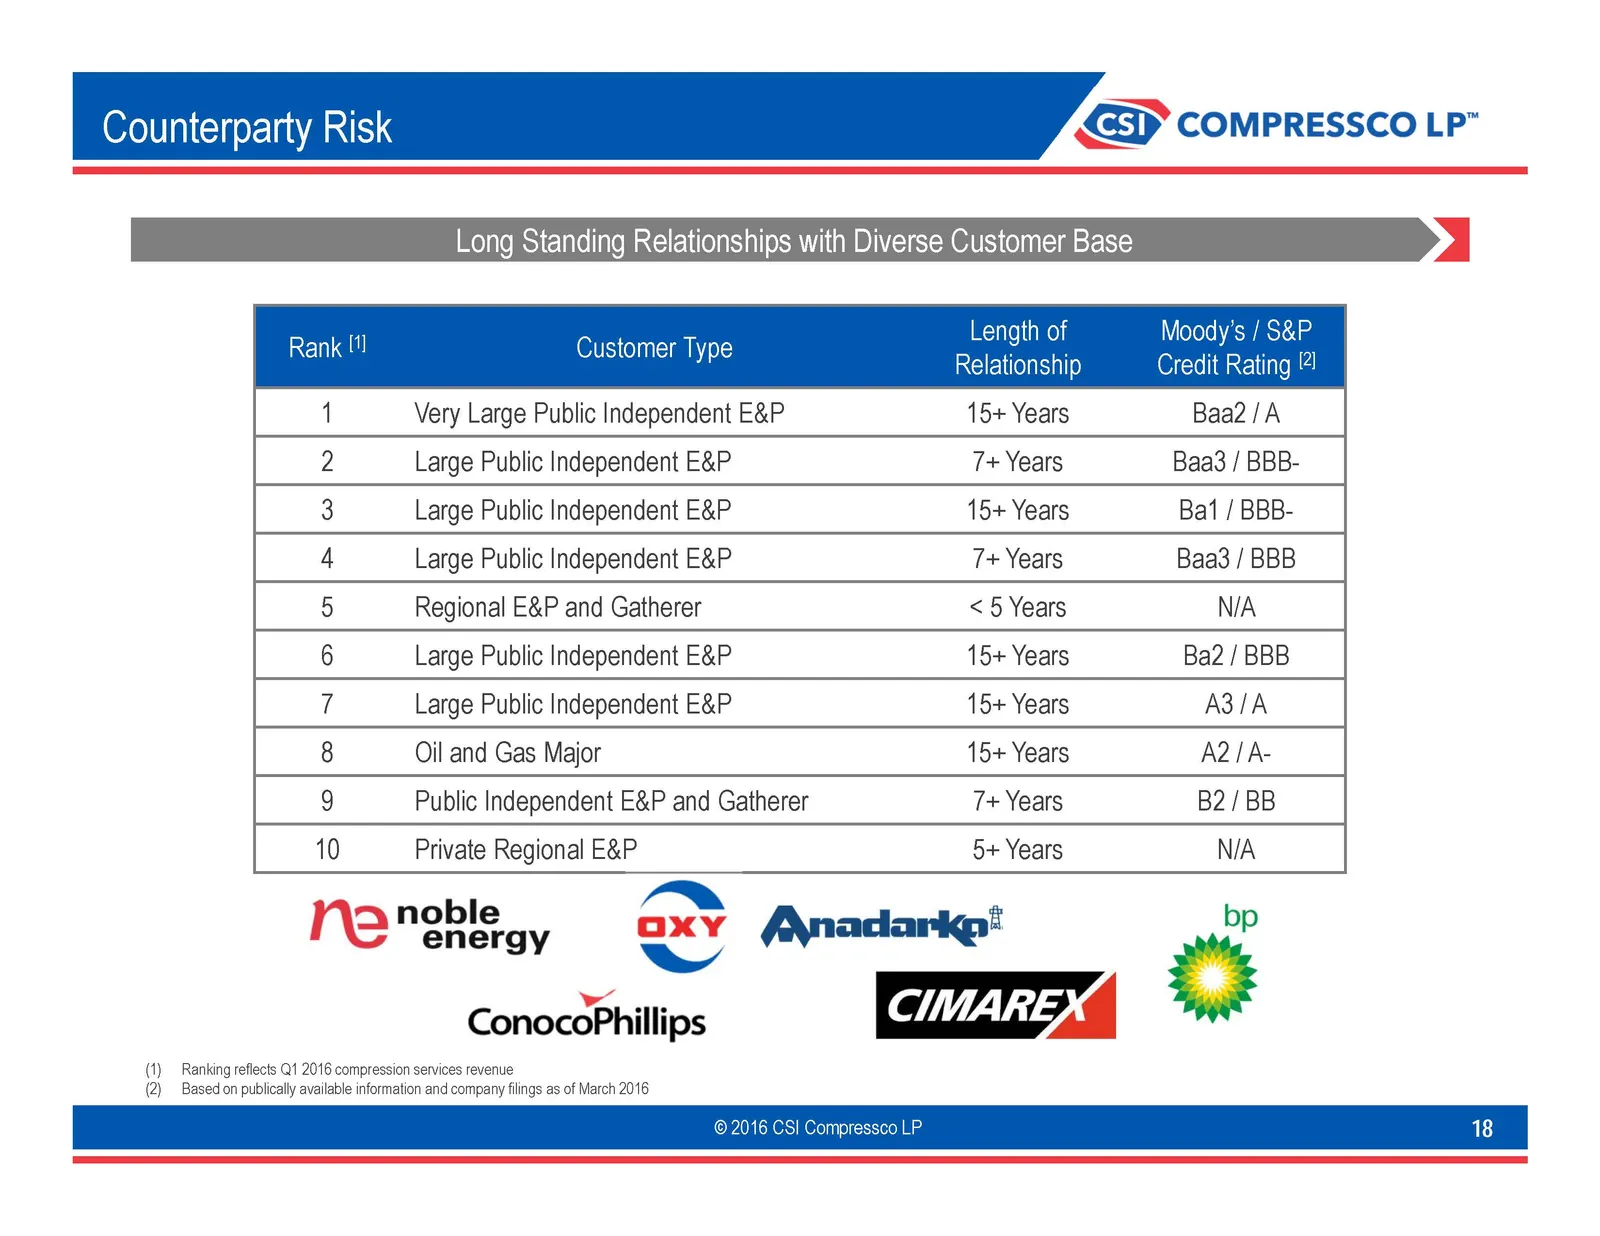
Counterparty Risk ‘Ep’ COMPRESSCO LP™ Long Standing Relationships with Diverse Customer Base >| Customer Type aii a Noga Veer Relationship Credit Rating "1 1 Very Large Public Independent E&P 15+ Years Baa2/A 2 Large Public Independent E&P 7+ Years Baa3 / BBB- 3 Large Public Independent E&P 15+ Year
Slide 19: 2016 Outlook
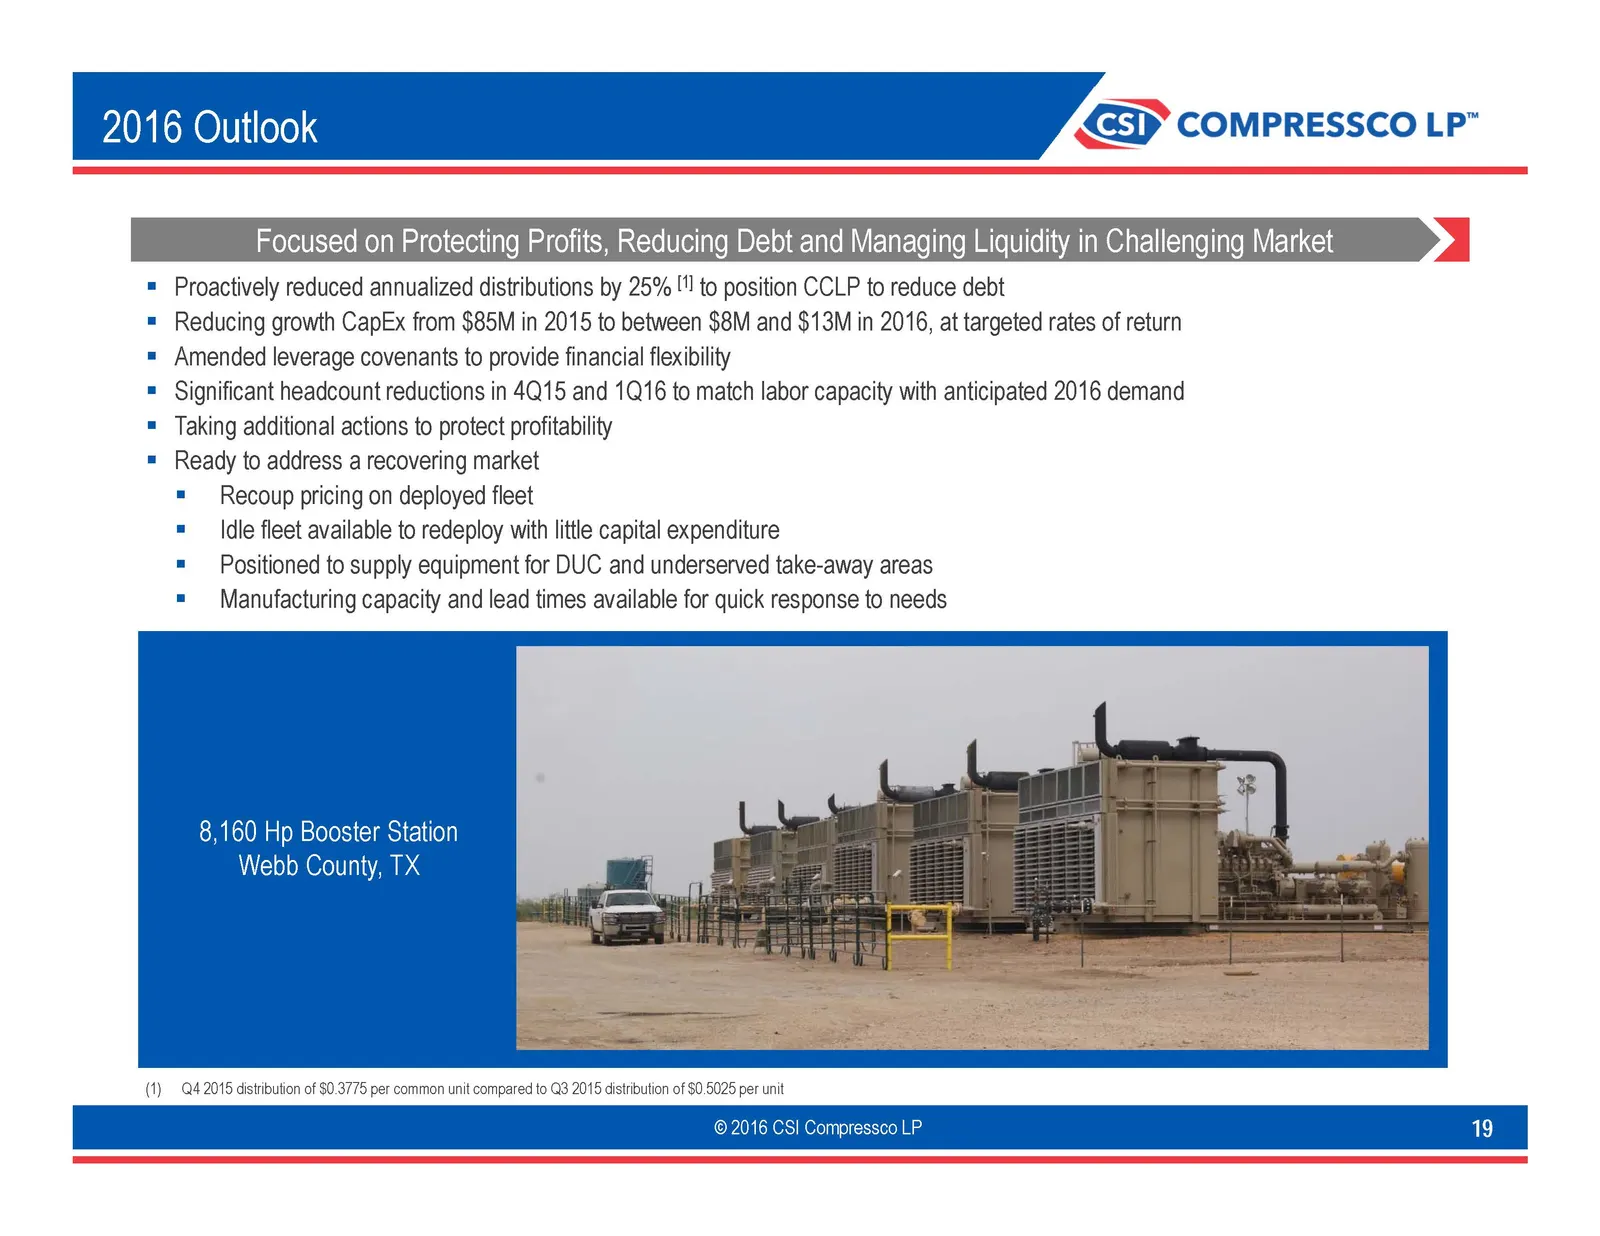
2016 Outlook <p’ COMPRESSCO LP” Focused on Protecting Profits, Reducing Debt and Managing Liquidity in Challenging Market Proactively reduced annualized distributions by 25% !"! to position CCLP to reduce debt Reducing growth CapEx from $85M in 2015 to between $8M and $13M in 2016, at targeted rates
Slide 20: Appendix
Dy compressco LP™ Appendix © 2016 CSI Compressco LP
Slide 21: Non-GAAP Financial Measures
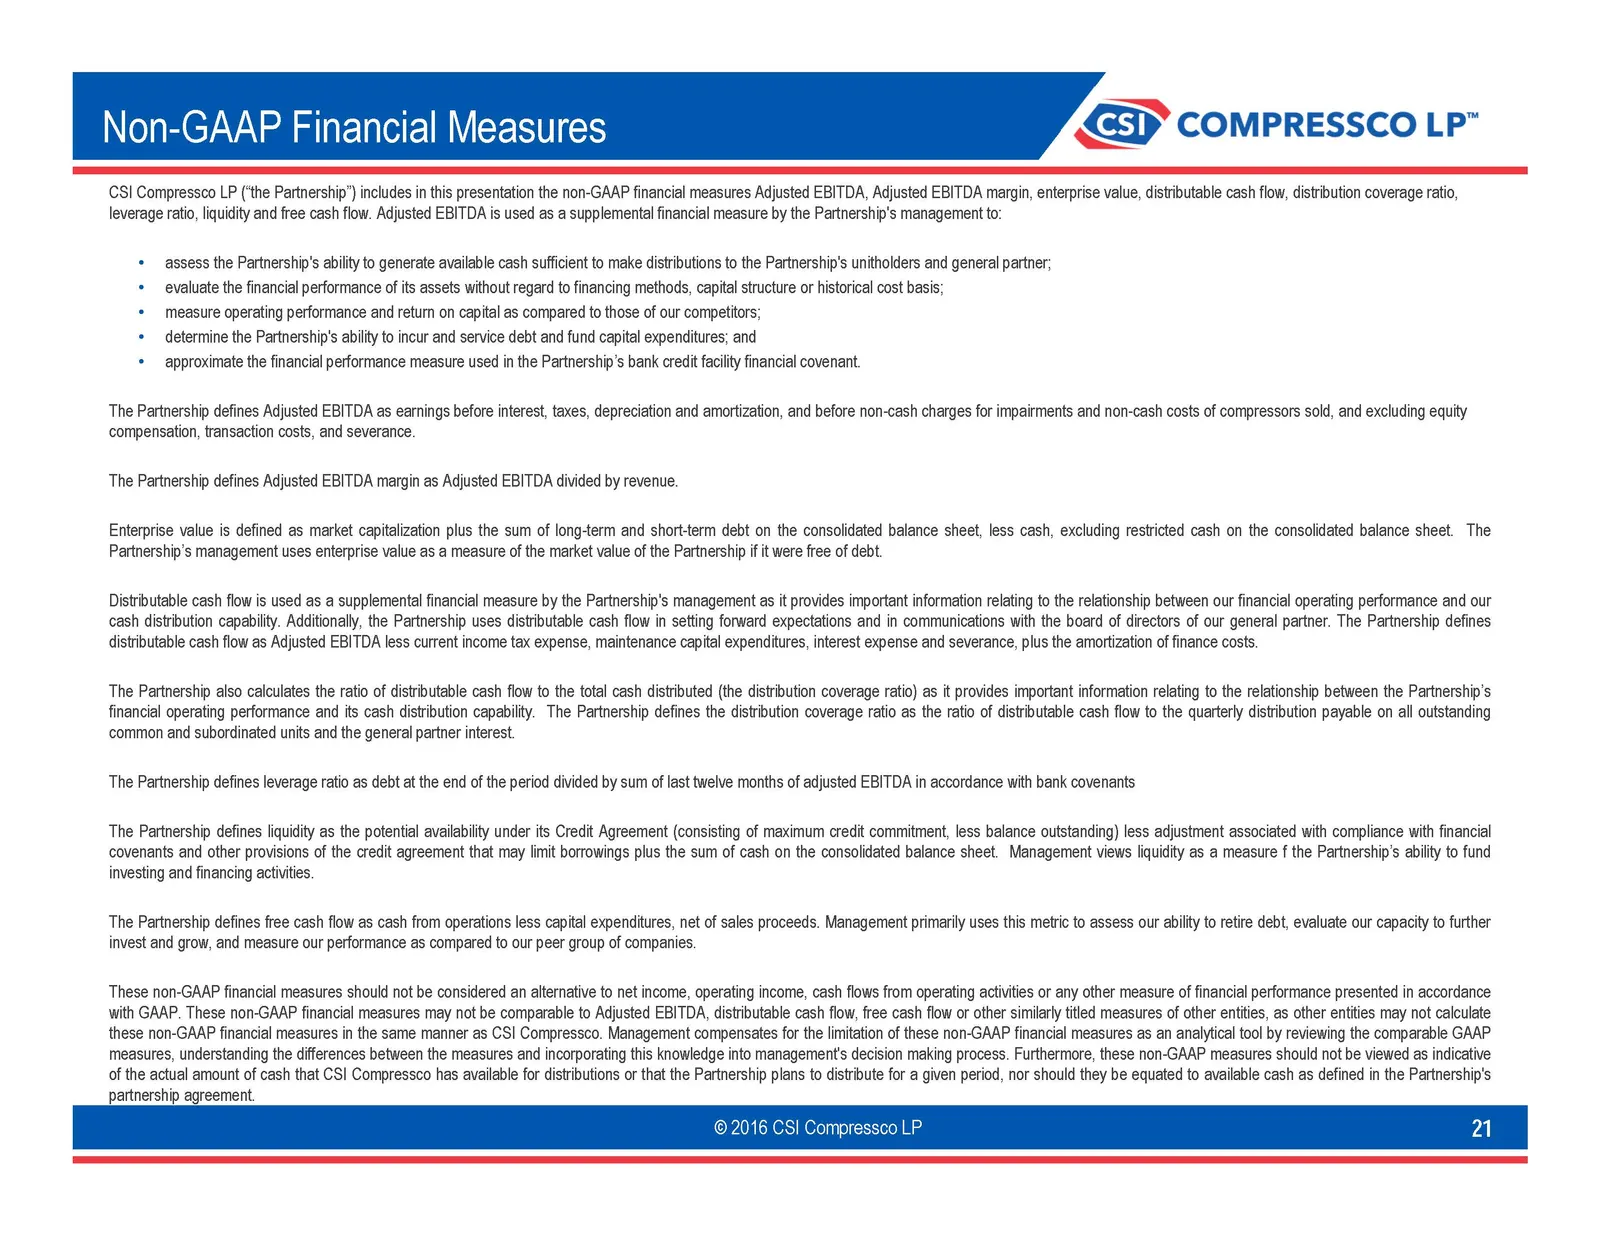
Non-GAAP Financial Measures ‘<p’ COMPRESSCO LP” CSI Compressco LP (‘the Partnership’) includes inthis presentation the non-GAAP financial measures Adjusted EBITDA, Adjusted EBITDA margin, enterprise value, di leverage ratio, liquidity and free cash flow, Adjusted EBITDA is used as financial measure
Slide 22: Non-GAAP Reconciliations
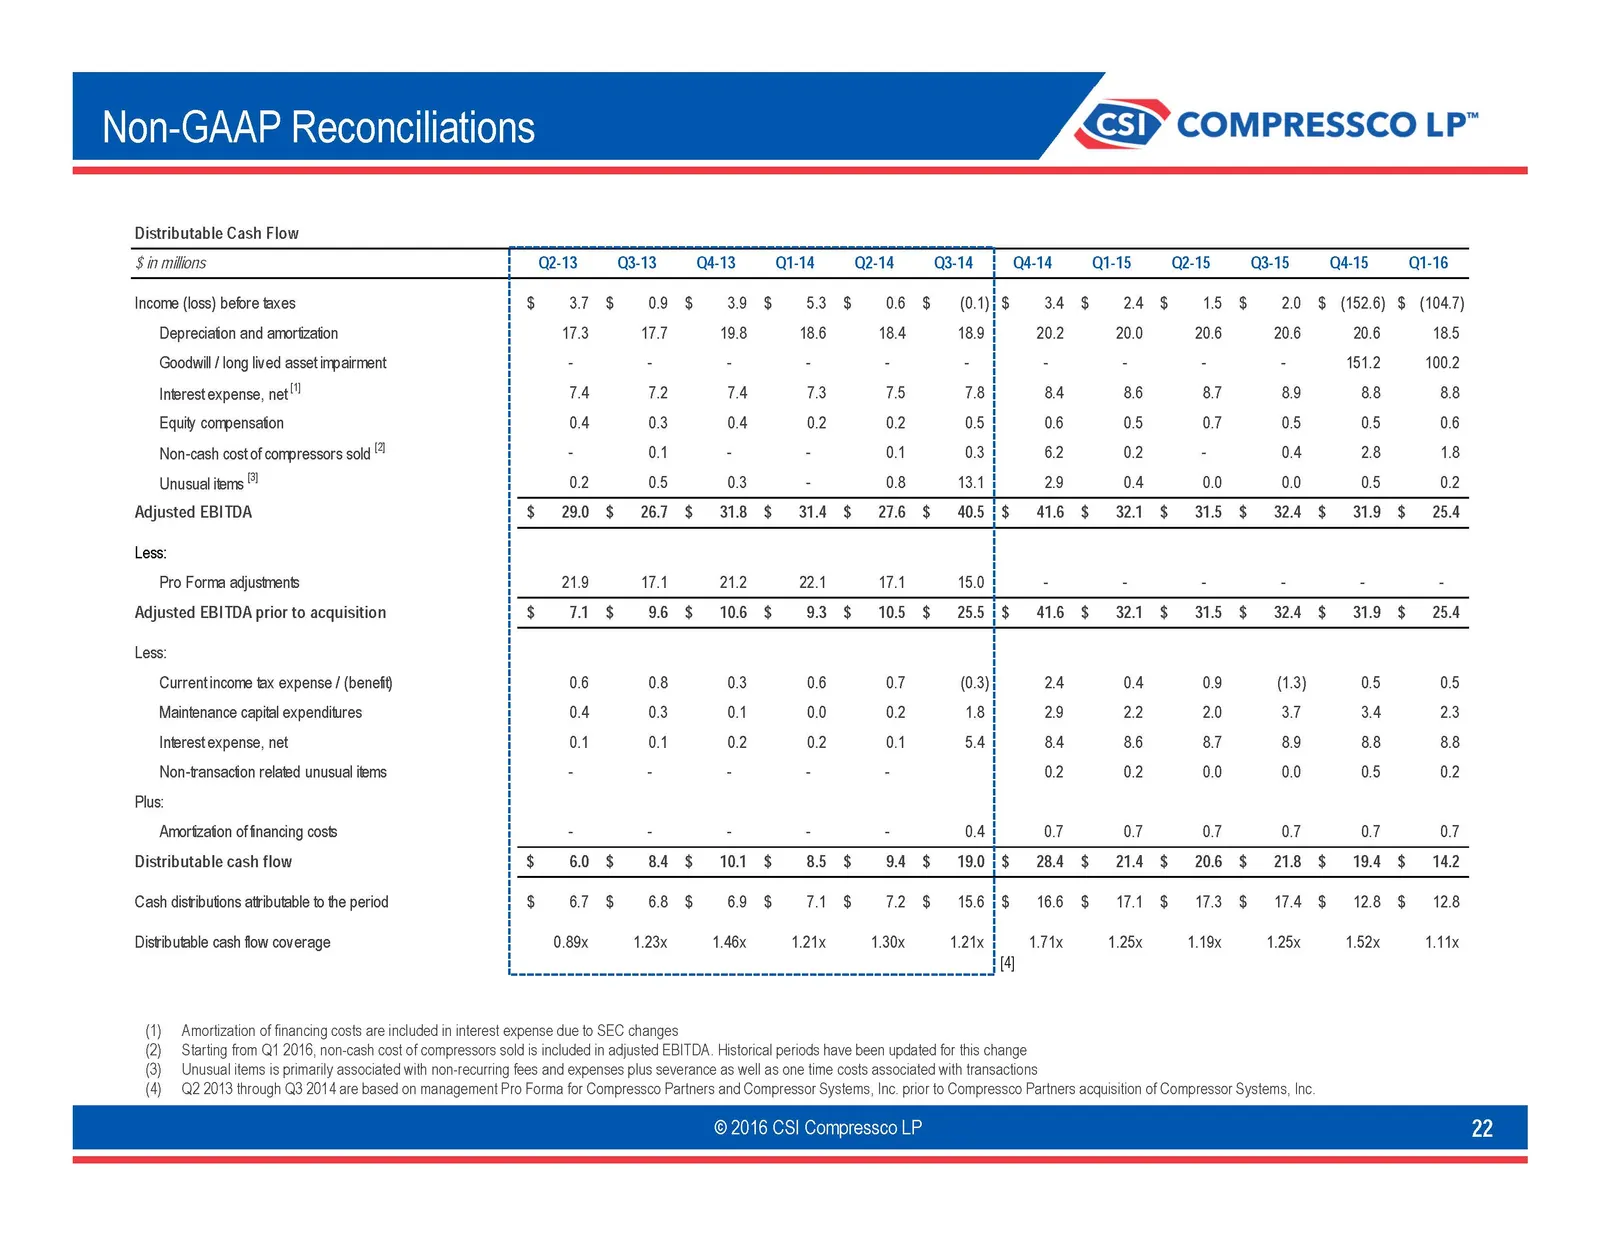
Non-GAAP Reconciliations Distributable Cash Flow ‘Ep’ COMPRESSCO LP™ $ in milions 213 3134134 243-14 F414 QS 215315 HS I-16 Income (loss) before taxes $ 37 $ 09 $ 39 $ 53 $ 06 $ (01)1$ 34 $ 24 $ 15 $ 20 $ (1526) $ (1047) Depreciaton and amortization 113 17 198 18.6 18.4 189 20.2 20.0 206 206 20.6 18
Slide 23: Non-GAAP Reconciliations
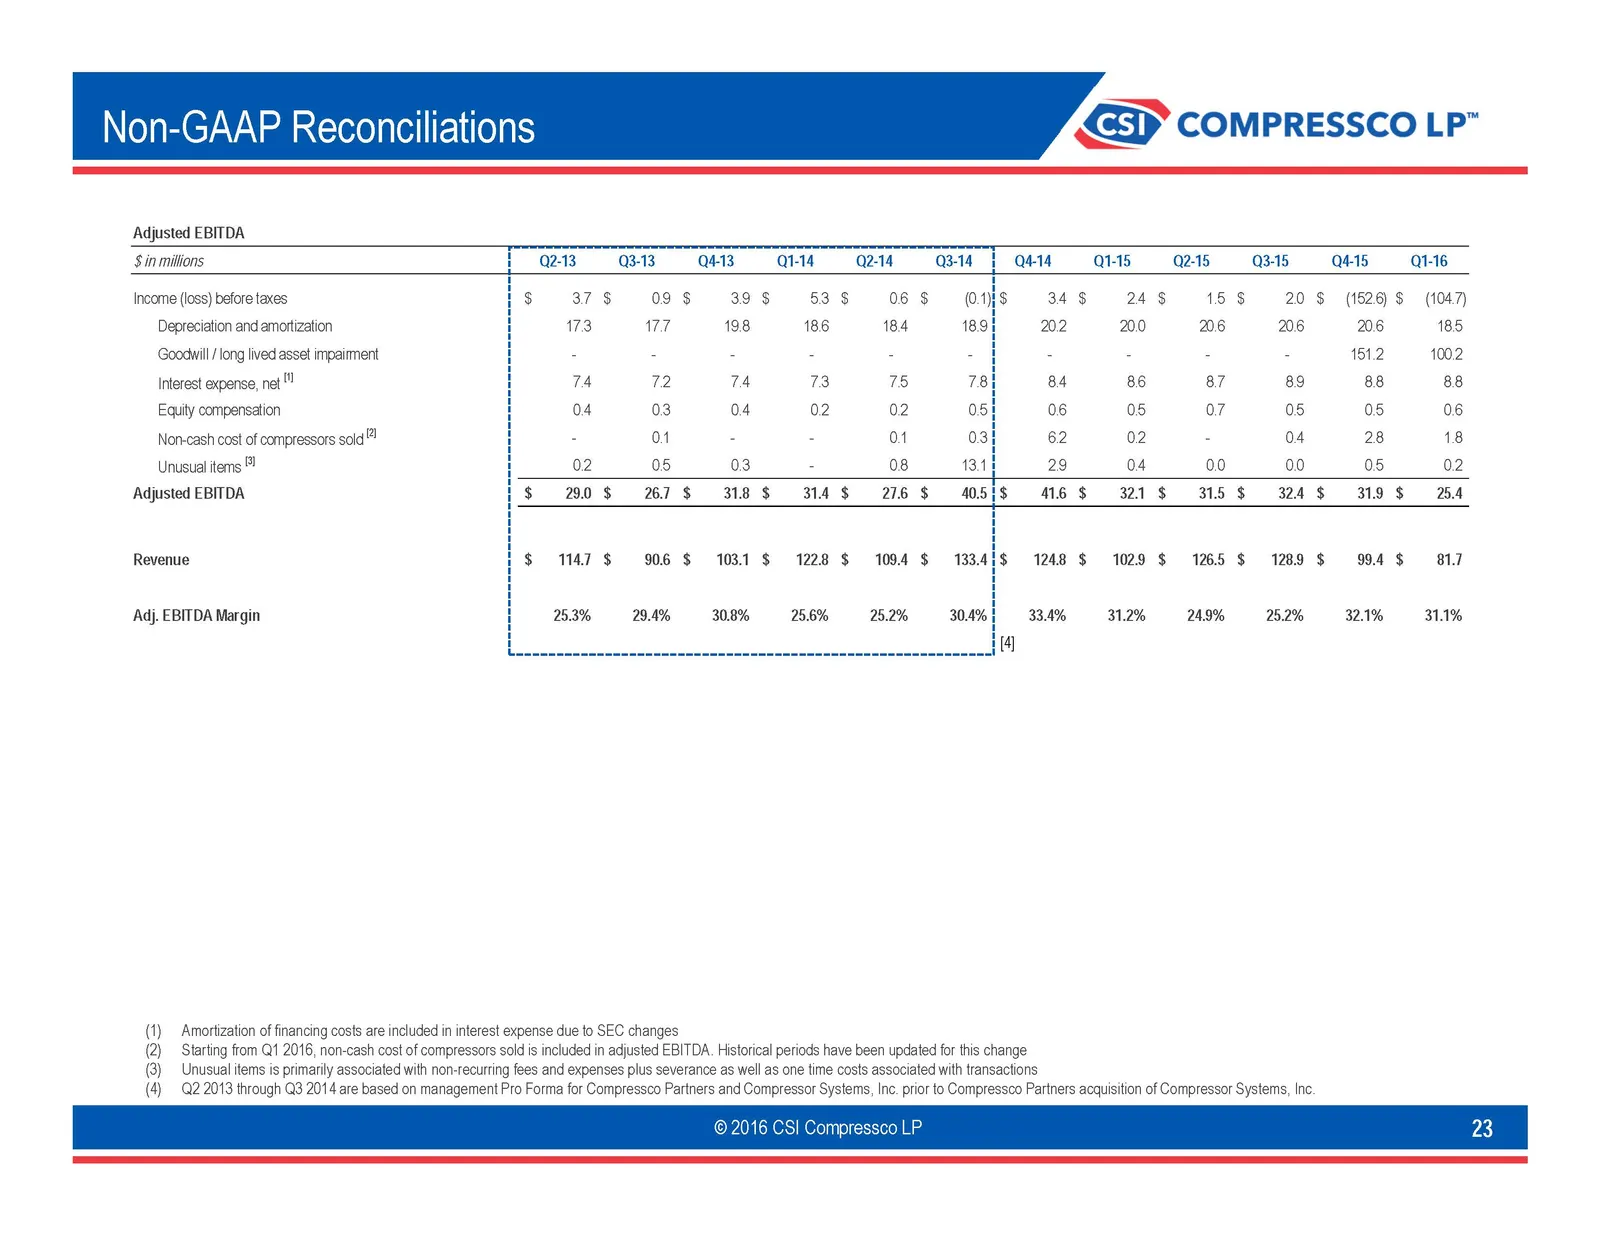
Non-GAAP Reconciliations ‘Ep’ COMPRESSCO LP™ Adjusted EBITDA $inmilions Q2-13 Q3-13 Q4-13 Q1-14 Q2-14 03-14 Q4-14 Q1-15 Q2-15 Q3-15 Q4-15, Q1-16 Income (loss) before taxes $ 37 $ 09 $ 39 $ 53 $ 06 $ = OAS 34 $ 24 16 $ 20 $ (1526) $ (1047) Depreciation and amortization 173 77 198 186 184 189 202 200
Slide 24: Non-GAAP Reconciliations
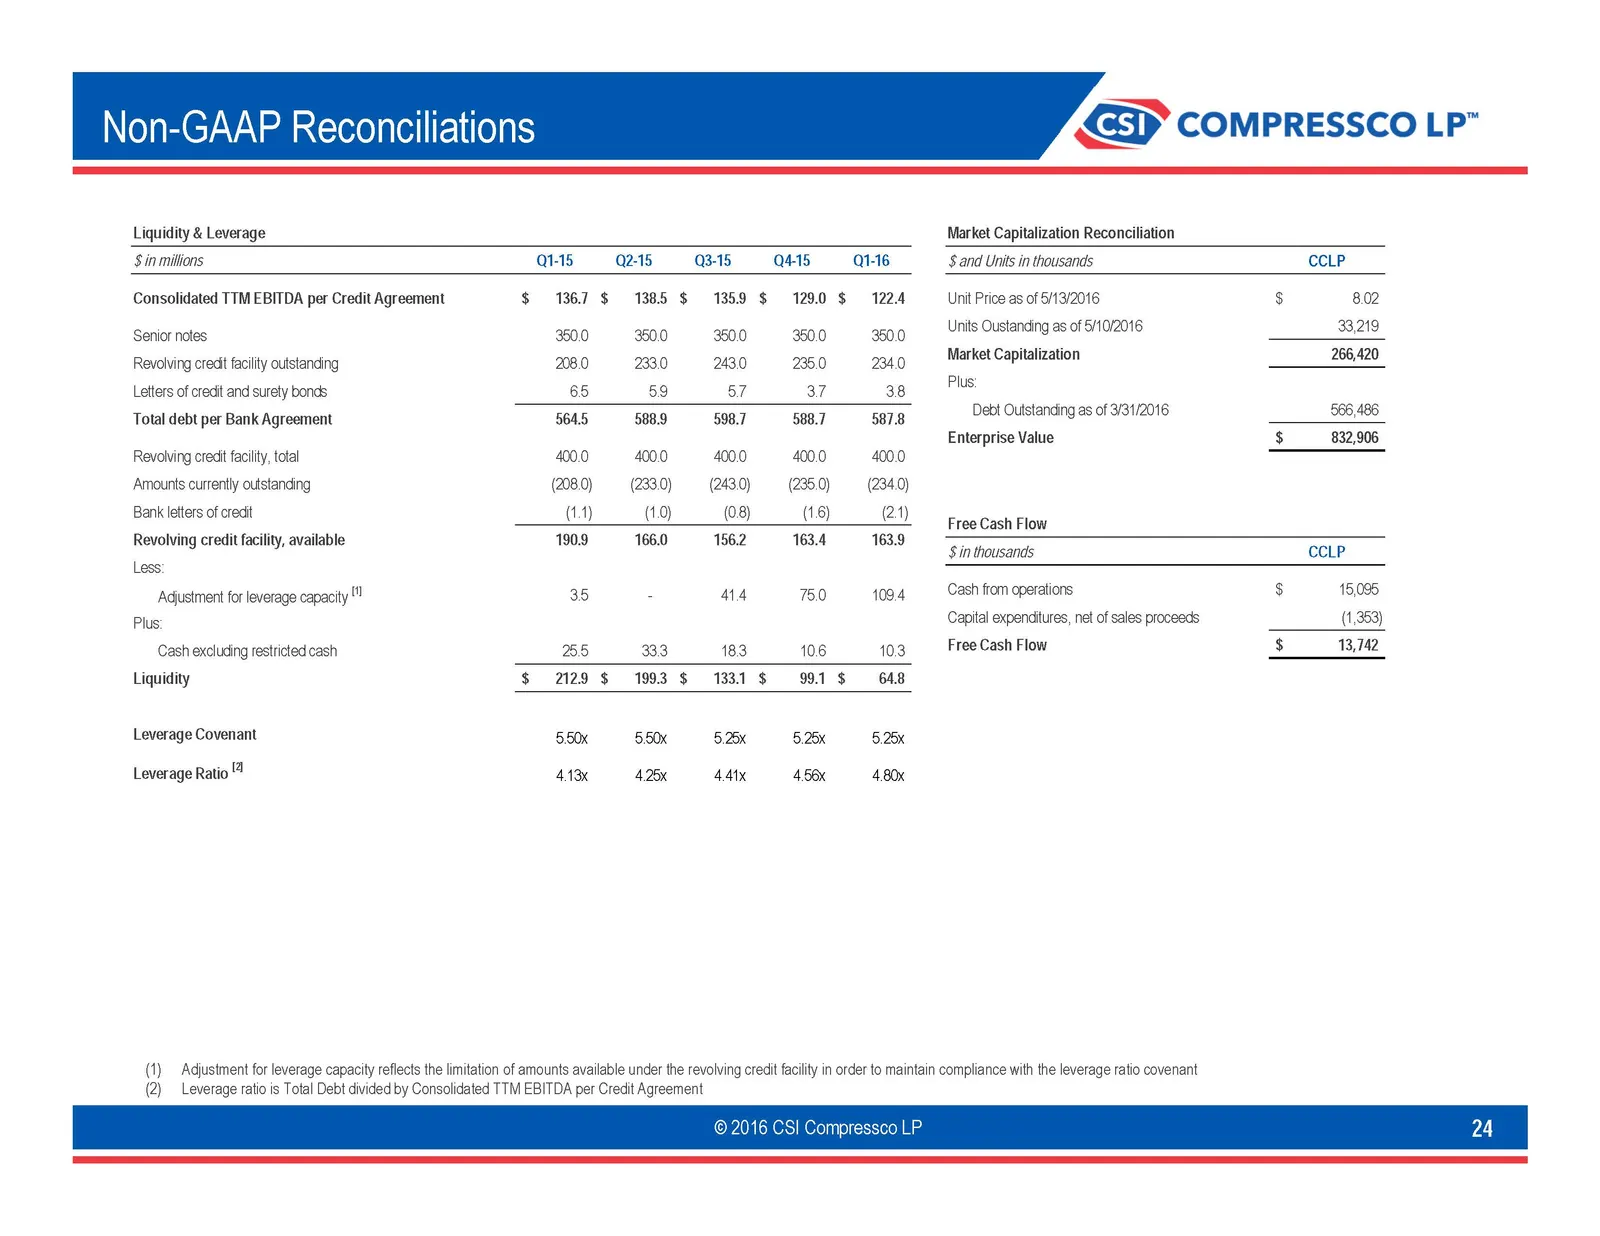
Non-GAAP Reconciliations ‘Ep COMPRESSCO LP” Liquidity & Leverage Market Sinmilions Qs O25 315 HIS TE ‘Sand Units in thousands ccLP Consolidated TTM EBITDA per Credit Agreement $ 1367 $ 1385 $ 1359 $ 1290 $ 1224 Unit Price as of 6/13/2016 $ 802 Senior notes 3500 ©3500-3500» 3600 600 -~_—*(rils Oustan
Source: SEC EDGAR · 8-K filed Jun 21, 2016
More decks from CSI Compressco LP
 Merger or Acquisition (November 2021)18 slides · Nov 12, 2021
 Investor Presentation (December 2019)30 slides · Dec 3, 2019
 Investor Day (May 2018)116 slides · May 31, 2018
 Wells Fargo Securities 15th Annual Energy Symposium 201624 slides · Dec 7, 2016
 Investor Presentation (November 2015)20 slides · Nov 12, 2015
 Investor Day (April 2015)34 slides · Apr 2, 2015