Whitney — KBW Regional Bank Conference 2007
33 slides from Whitney's conference presentation, Mar 1, 2007
Slide 1: KBW Regional Bank Conference
KBW Regional Bank Conference March 1, 2007 Tom Callicutt, EVP and CFO Lewis Rogers, EVP, Credit Administration
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation may include forward-looking statements containing expectations about future conditions and descriptions of future plans and strategies. Whitney's ability to accurately predict the effects of future plans or strategies is inherently limited such that actua
Slide 3: A Growing, Diversified Company
At 12/31/06 A Growing, Diversified Company $10.2B in Assets $7.1B in Loans $8.4B in Deposits Strong NIM (5.11% YTD) Solid credit measures 123-year old name started in New Orleans Over locations across 5 states Focus on Relationship Banking
Slide 4: Potential Expansion Markets
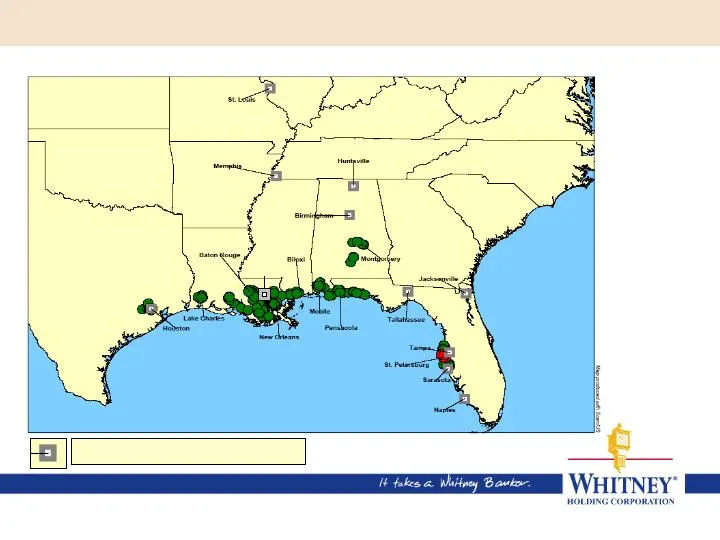
Potential Expansion Markets Northshore Following the Flow of Commerce
Slide 5: Geographic Diversification Through Acquisitions
Geographic Diversification Through Acquisitions Recent acquisition activity focused on high-growth Florida markets – Signature Holding Corp. (St. Petersburg) acquisition announced October 5th. (7 locations, $220MM in deposits) – First National Bancshares (Bradenton) acquisition completed April, 2006
Slide 6: Earnings
Earnings Update
Slide 7: 4Q'06 Earnings
4Q’06 Earnings • Earnings per share (diluted) --- $.51 • Net income --- $33.9MM – Include approximately $4.9MM in expenses associated with the 2005 hurricanes • Resiliency initiatives totaled approximately $2.9MM – $1.6MM recurring; $1.3MM periodic or nonrecurring • Insurance coverage premium increa
Slide 8: Mixed Lending Environment in 2006
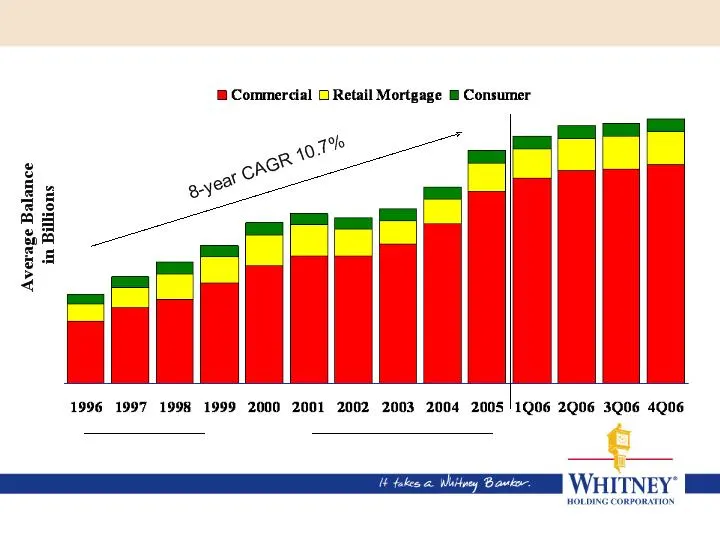
$2.3 $2.8 $3.2 $3.6 $4.2 $4.5 $4.4 $4.6 $5.2 $6.1 $6.5 $6.8 $6.8 Pre-storms $7.0 Mixed Lending Environment in 2006 Robust Production; Some Quarters Offset By Payoffs
Slide 9: Steady Growth In Deposits Multiplied Post Storms
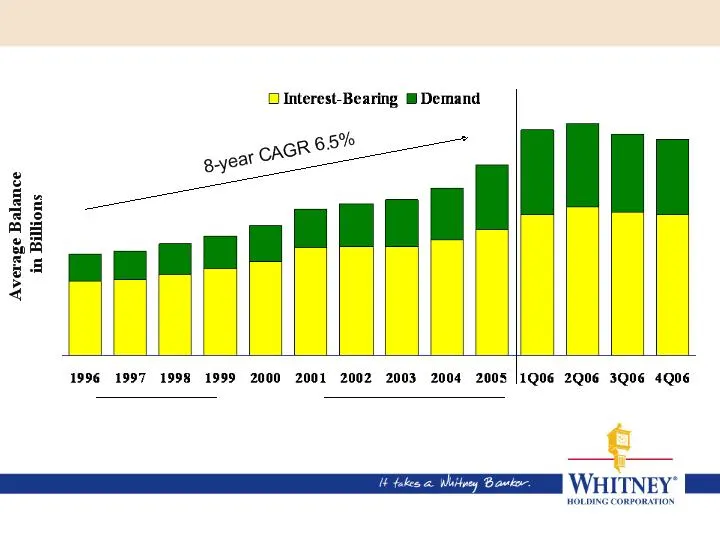
26% 27% 27% 27% 27% 26% 28% 30% 31% 34% 37% 36% 35% 35% $3.8 $4.0 $4.2 $4.5 $4.9 $5.5 $5.8 $5.9 $6.3 $7.2 $8.5 $8.8 $8.4 Although the timing cannot be predicted, some run-off of the post-storm deposit accumulation has been expected as the recovery process continues, the inflows from insurance procee
Slide 10: Additional Government Funds
Source: Louisiana Recovery Authority http://www.rememberrebirth.org/ritadocs/Ritadata091906update.pdf Additional Government Funds • Louisiana Recovery Authority – $10.4B available for Louisiana Community Development Block Grants • $8.1B available through the Road Home Program • $350MM allocated to b
Slide 11: LRA Distributions Limited
Source: The Road Home Program; as of February 15, 2007 LRA Distributions Limited • An estimated 123,000 homeowners are eligible for up to $150,000 in uncompensated damages – Total available: $7.5B – Applications received: 107,739 – Closings concluded: 632 – Average award paid: $64,439 – Total paid t
Slide 12: Continue to Report a Strong, Growing NIM
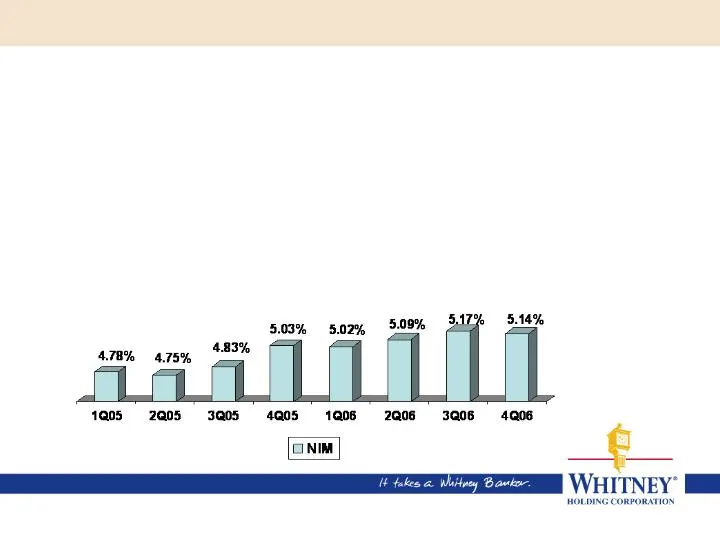
Continue to Report a Strong, Growing NIM • 4Q06 NIM --- 5.14% • NIM --- 5.11% (Rank 1 st in WTNY peer group) • Improved earning asset mix • Growth through acquisitions • Lower cost of deposits in Louisiana markets allows us to fund loans in higher-priced deposit markets of Florida, Texas and Alabama
Slide 13: Focus On Growing Fee-Based Businesses
Focus On Growing Fee-Based Businesses • Service Charges on Deposits is the largest component of fee income – Fees are “seasonal” as charges are based on movement in interest rates and in balances carried by customers • Expanded presence in fee-based businesses – Trust - Positioned relationship offic
Slide 14: Expense Levels Higher in New Operating Environment
Expense Levels Higher in New Operating Environment • Plans designed to make the company’s operations more resilient with less exposure to disasters were implemented in 2006 – Relocated mainframe computers and critical servers – Upgraded telecommunications systems using more modern technology and add
Slide 15: Asset Quality
Asset Quality
Slide 16: Diversified Loan Portfolio
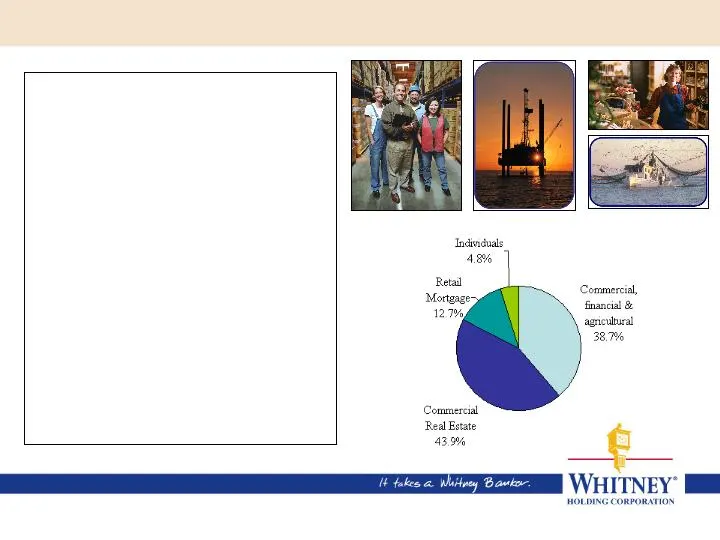
At 12/31/06 Diversified Loan Portfolio • Commercial portfolio 83%, Consumer portfolio 17% of total loans – Less diversification – But, less credit issues post-storms • No Indirect portfolio • Minimal Credit Card portfolio • Commercial customers diversified by industry • Real Estate portfolio diversi
Slide 17: Impact of Storms on Credit Quality
• Majority of loans to commercial customers had little to positive impact from the storm, and mortgage customers required to have insurance . Impact of Storms on Credit Quality • Continual Assessment Process – All criticized loans and larger loans will continue to be reviewed each quarter – There wi
Slide 18: Working Through Nonperforming Assets Post Storms
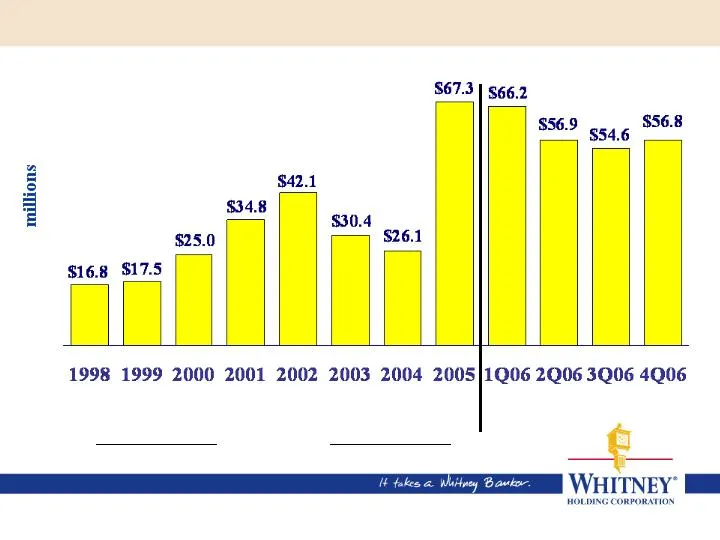
Working Through Nonperforming Assets Post Storms NPA ratio: .48% ..45% ..55% .77% ..95% .62% .46% 1.03% 1.02% .83% .80% ..81% Pre-storms
Slide 19: Loans Internally Classified as Having Above Normal Credit Risks
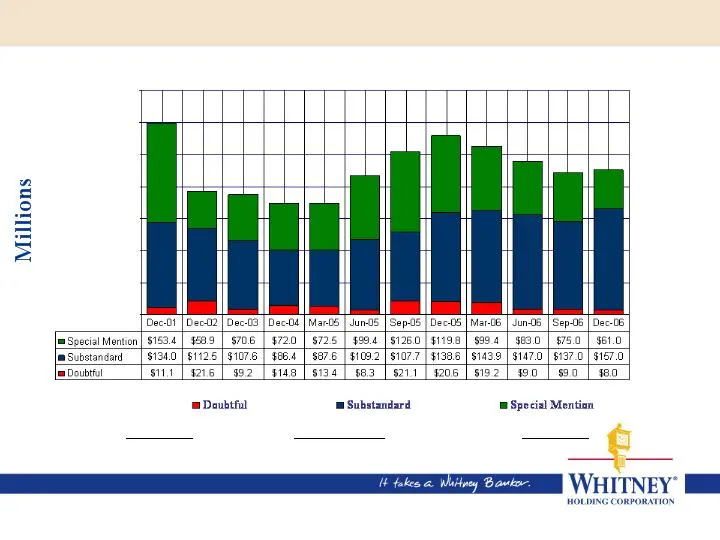
Loans Internally Classified as Having Above Normal Credit Risks Pre-storms Post-storms
Slide 20: Net Charge-Offs At or Below Peers
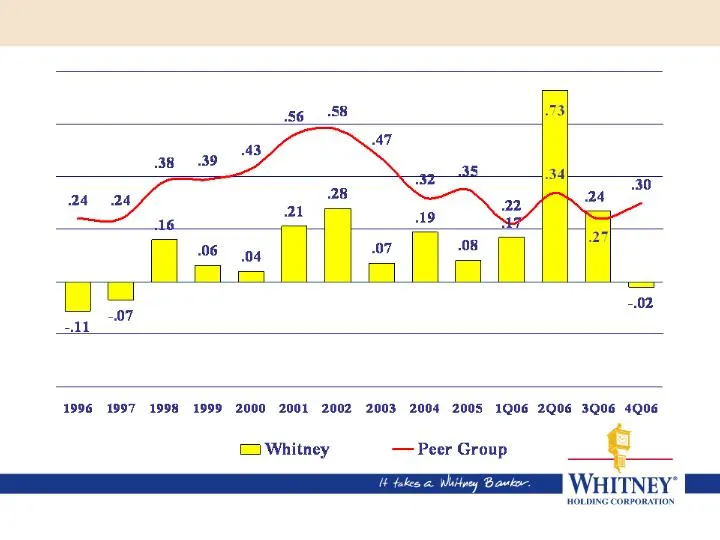
Net Charge-Offs At or Below Peers Percent Net Charge-offs to Average Loans Note: Increase in 2Q’06 net charge-offs related to one storm-impacted commercial relationship. Relationship identified as impaired shortly after storms in 2005 and a substantial impairment allowance had been established.
Slide 21: Adequate Allowance for Loan Losses
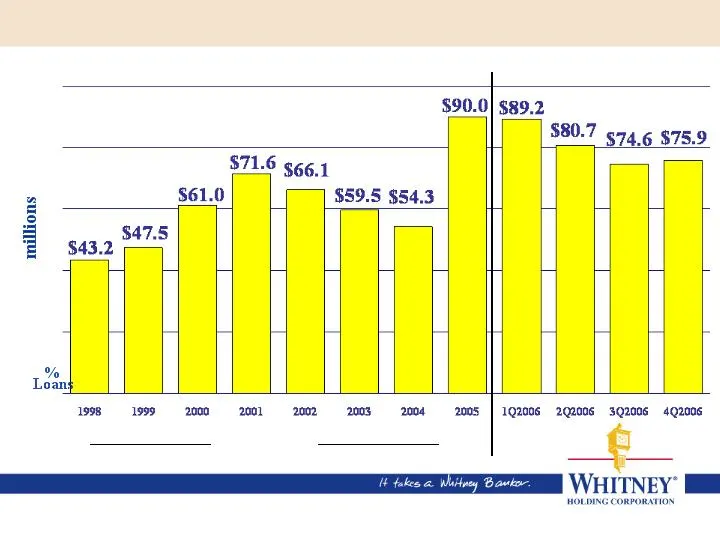
1.24% 1.21% 1.33% 1.59% 1.48% 1.22% .97% 1.37% 1.37% 1.18% 1.09% 1.08% Adequate Allowance for Loan Losses Pre-storms
Slide 22: Portfolio Risks and Uncertainties
• Length of recovery period • Long-term economic impact – Rebuilding of public infrastructure – Government, private or philanthropic investment – Population and economic contraction – Availability and affordability of insurance • Reminder: Over the last decade Whitney and many of its customers have
Slide 23: Post-Katrina Update: Greater New Orleans
Post-Katrina Update Greater New Orleans
Slide 24: Greater New Orleans Metro Area
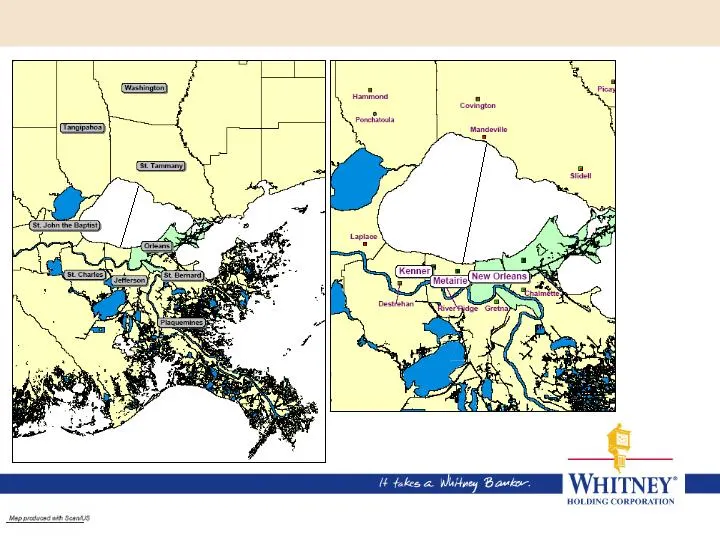
Greater New Orleans Metro Area
Slide 25: New Orleans Economy: Positive Impacts
Sources of information: N.O. Metropolitan Convention & Visitors Bureau, N.O. Times-Picayune, New Orleans Economy: Positive Impacts MARDI GRAS – Attendance at near pre-Katrina levels 700,000-800,000 estimated Carnival visitors – Hotel occupancy was as high as 95% with some hotels at 100% occupancy Mo
Slide 26: New Orleans Economy: Yet To Be Fixed
Sources of information: N.O. Metropolitan Convention & Visitors Bureau, N.O. Times-Picayune, New Orleans Economy: Yet To Be Fixed Education – New Orleans Public schools slow to re-open – Recovery District schools lack essential facilities and teaching tools – Charter schools have been “successful” t
Slide 27: Corporate Overview
Corporate Overview
Slide 28: We Will Continue to Operate Within the Guidelines of Our Mission
Our mission is to deliver extraordinary value and superior results to our our customers and shareholders, while providing leadership to our local communities and outstanding career opportunities to our valued employees. We do this within the framework of our three guiding principles: soundness, prof
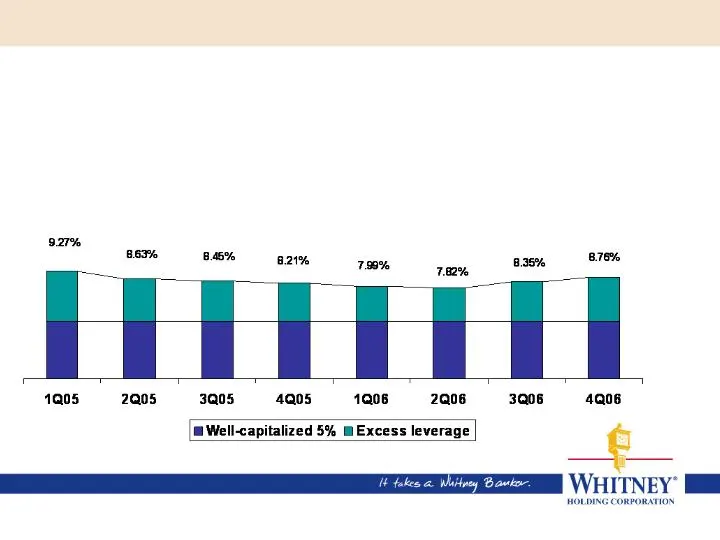
Slide 29: Sound Capital Levels
Sound Capital Levels • 4Q06 Leverage ratio 8.76% • Dividend payout ratio 53% (of fourth quarter 2006 diluted earnings per share) • Dividend yield 3.3% (based on Whitney’s February 20, 2006 closing price)
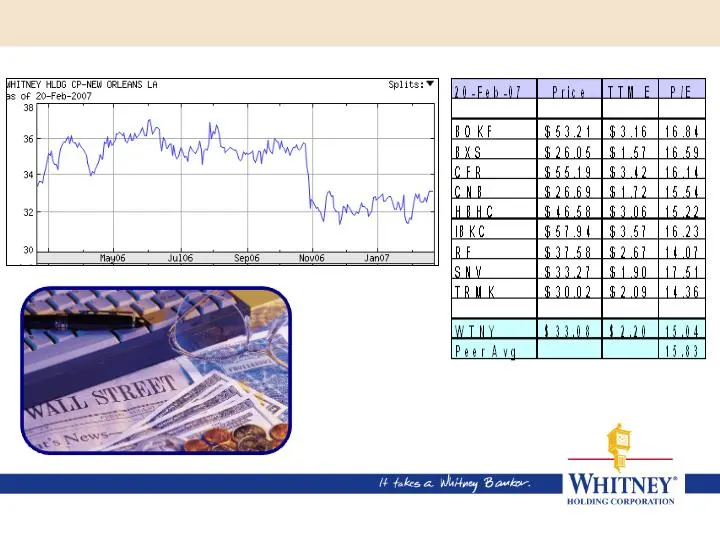
Slide 30: Trading At A Slight Discount To Peers
Source: Yahoo.com/finance Trading At A Slight Discount To Peers
Slide 31: Whitney Today
Whitney Today • Continuing geographic diversification through acquisitions in high-growth markets • Operational resiliency • Strong NIM with a focus on building fee-based business lines • Asset quality trends are showing signs of improvement reflecting sustained, better than anticipated performance
Slide 32: Focus On The Whitney Banker
Focus On The Whitney Banker
Slide 33: KBW Regional Bank Conference
KBW Regional Bank Conference March 1, 2007 Tom Callicutt, EVP and CFO Lewis Rogers, EVP, Credit Administration
Source: SEC EDGAR · 8-K filed Mar 1, 2007
More decks from Whitney Holding Corp
 Q4 2010 Earnings Presentation15 slides · Jan 27, 2011
 Merger or Acquisition (December 2010)18 slides · Dec 23, 2010
 Merger or Acquisition (December 2010)18 slides · Dec 22, 2010
 Stifel Nicolaus Bank & Thrift Conference 201030 slides · Nov 2, 2010
 Q3 2010 Earnings Presentation16 slides · Oct 26, 2010
 Q2 2010 Earnings Presentation18 slides · Jul 27, 2010