Plains Exploration & Production Company
Plains Exploration & Production — Merger or Acquisition (February 2003)
34 slides from Plains Exploration & Production's merger presentation, Feb 10, 2003
Slide 1: Investor Presentation - Plains Exploration & Production
Investor Presentation PX P Plains Exploration & Production February 2003
Slide 2: Forward Looking Statements and Additional Information
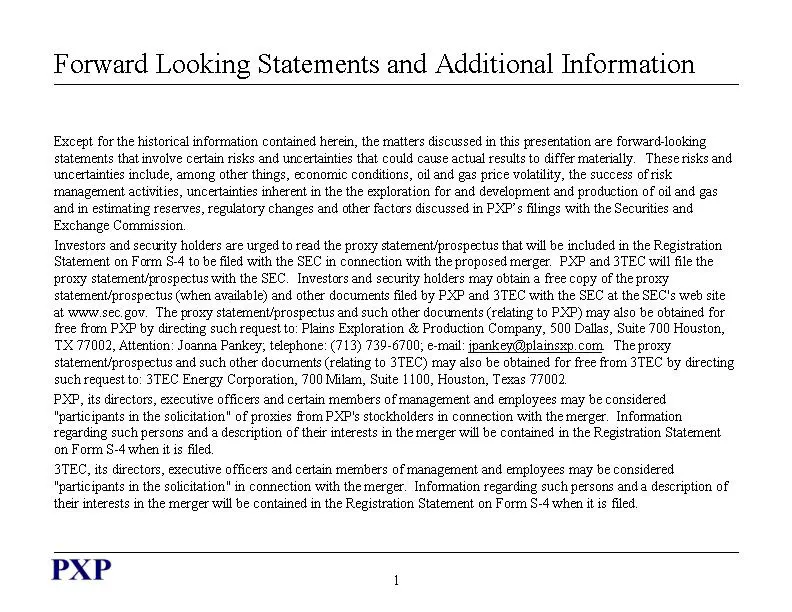
Forward Looking Statements and Additional Information Except for the historical information contained herein, the matters discussed in this presentation are forward-looking statements that involve certain risks and uncertainties that could cause actual results to differ materially. These risks and u
Slide 3: Plains Exploration & Production
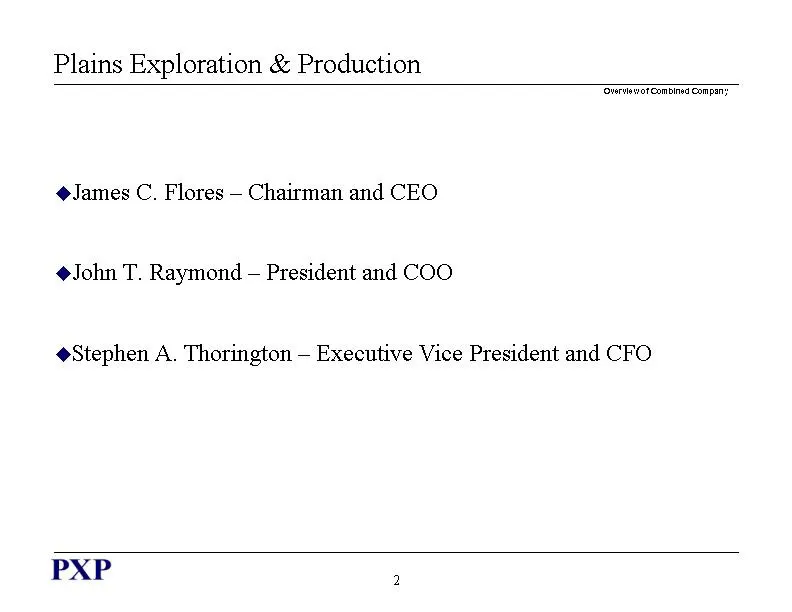
Plains Exploration & Production ‘Sweat Combined Company James C. Flores — Chairman and CEO John T. Raymond — President and COO Stephen A. Thorington — Executive Vice President and CFO PXP
Slide 4: Deal Terms
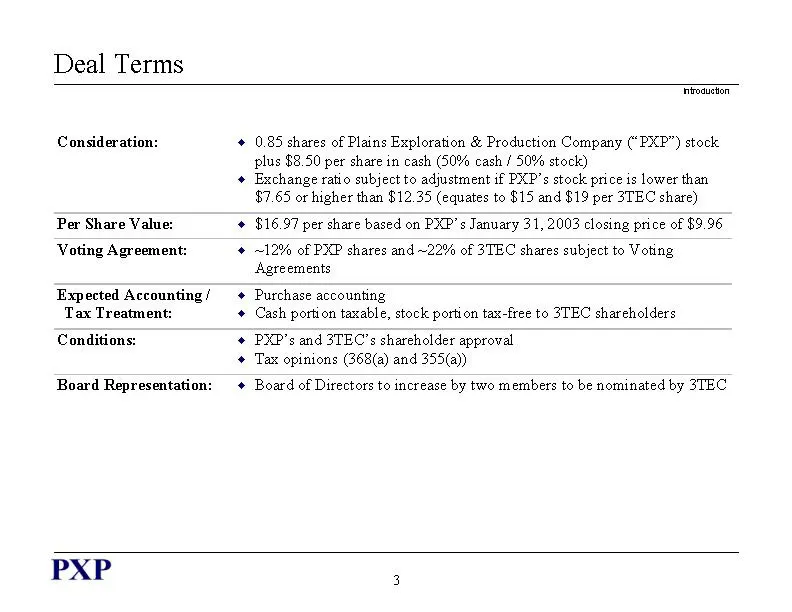
Deal Terms Consideration: Per Share Value: Voting Agreement: Expected Accounting / Tax Treatment: Conditions: Board Representation: + vifoaueton 0.85 shares of Plains Exploration & Production Company (“PXP") stock plus $8.50 per share in cash (50% cash / 50% stock) Exchange ratio subject to adjustme
Slide 5: Transaction Metrics
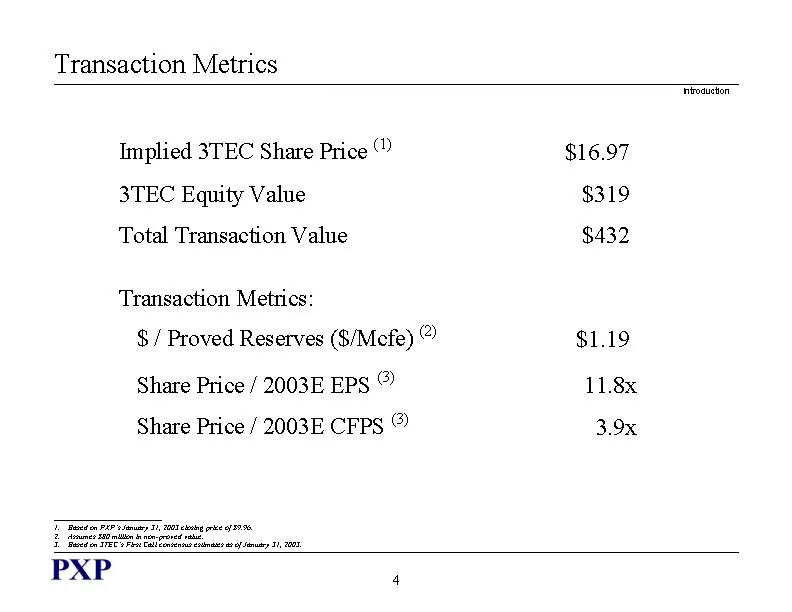
Transaction Metrics Implied 3TEC Share Price ‘? 3TEC Equity Value Total Transaction Value Transaction Metrics: $/ Proved Reserves ($/Mcfe) ® Share Price / 2003E EPS Share Price / 2003E CFPS teasing re of 295. $16.97 $319 $432 $1.19 11.8x 3.9% vifoaueton PXP 4
Slide 6: Transaction Rationale
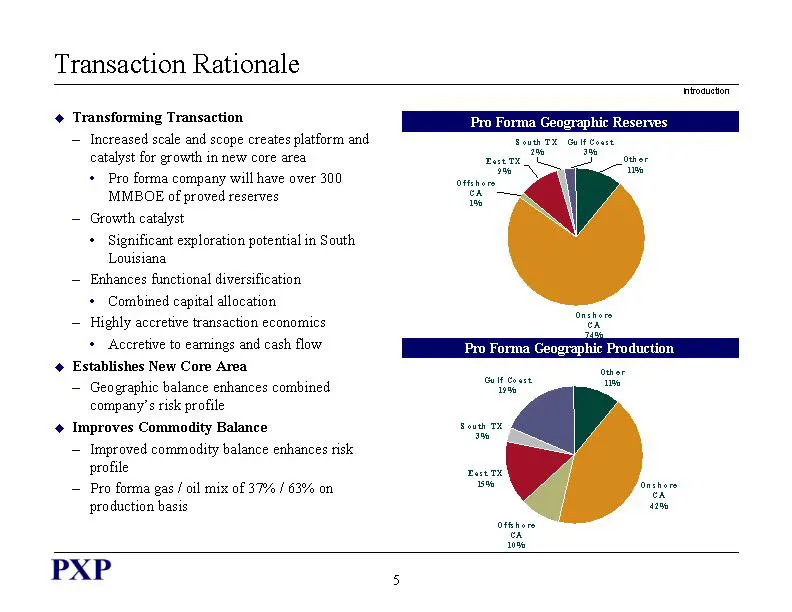
Transaction Rationale vifoaueton Transforming Transaction Pro Forma Geographic Reserves Increased scale and scope creates platform and Tout TH Gulf eoest catalyst for growth in new core area + Pro forma company will have over 300 MMBOE of proved reserves Growth catalyst + Significant exploration pot
Slide 7: Transaction Rationale - Combined Operations
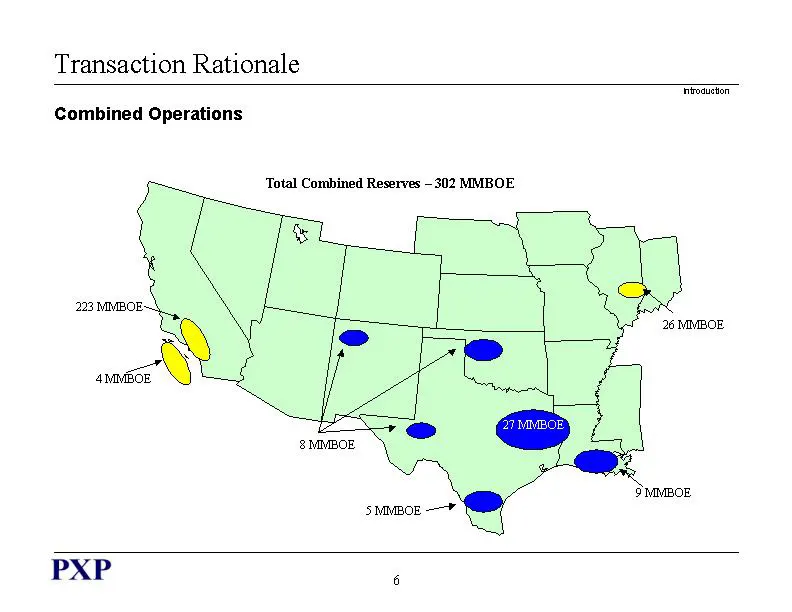
Transaction Rationale vifoaueton Combined Operations Total Combined Reserves - 302 MMBOE PXP ;
Slide 8: Oil and Gas Properties - Combined
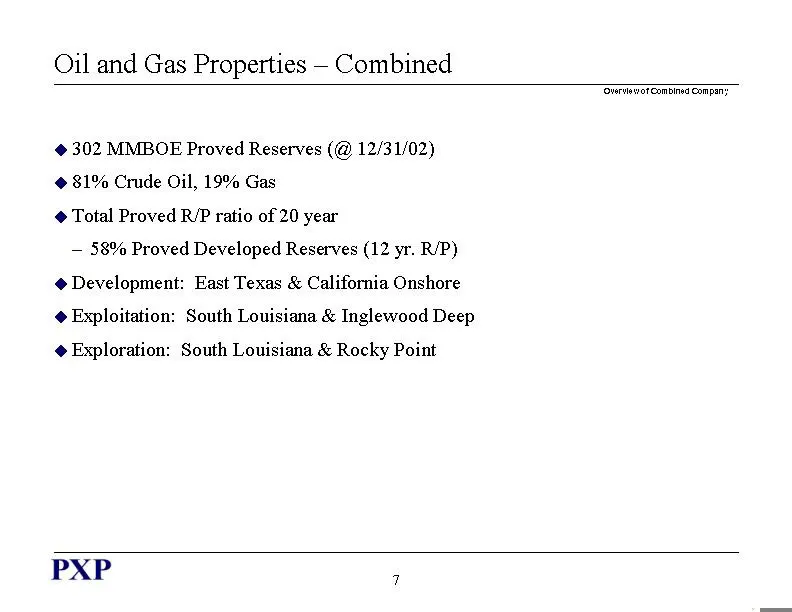
Oil and Gas Properties - Combined ‘Sweat Combined Company @ 302 MMBOE Proved Reserves (@ 12/31/02) © 81% Crude Oil, 19% Gas Total Proved R/P ratio of 20 year = 58% Proved Developed Reserves (12 yr. R/P) @ Development: East Texas & California Onshore @ Exploitation: South Louisiana & Inglewood Deep E
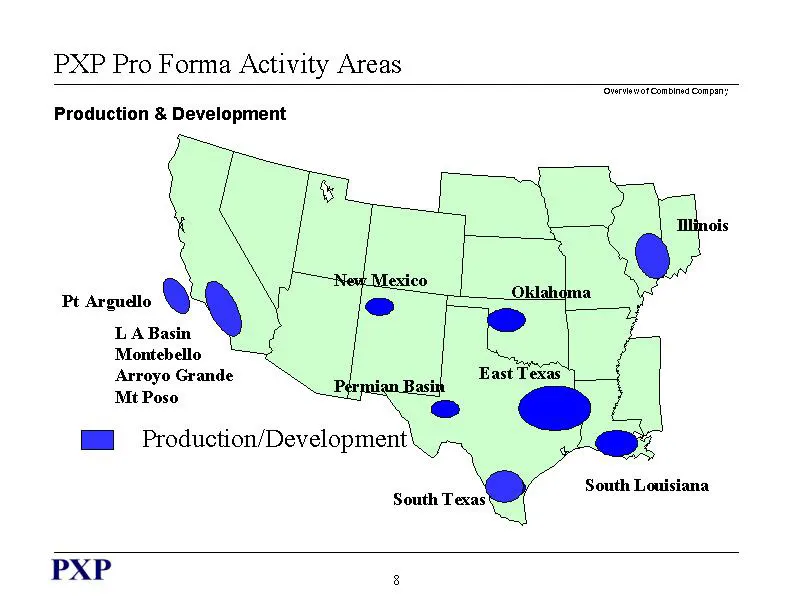
Slide 9: PXP Pro Forma Activity Areas
PXP Pro Forma Activity Areas ‘Sweat Combined Company Production & Development Arroyo Grande Mt Poso PXP :
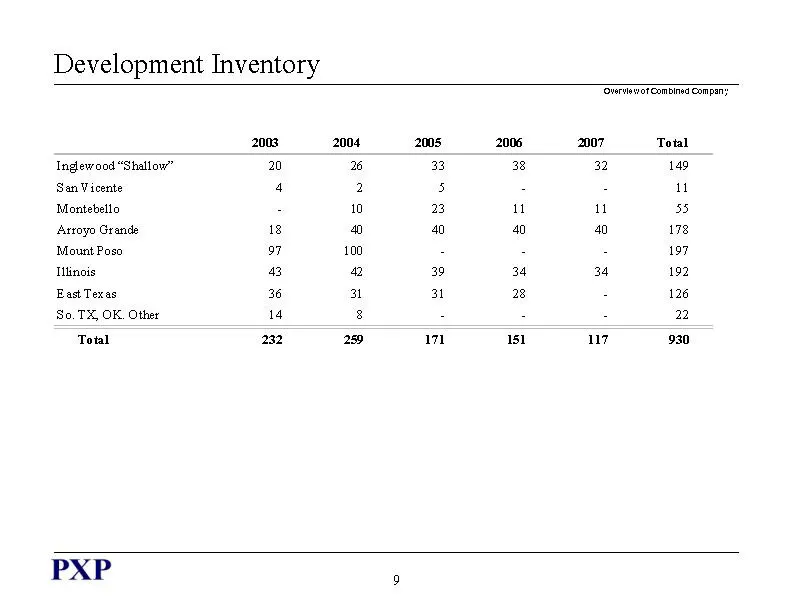
Slide 10: Development Inventory
Development Inventory ‘Sweat Combined Company 2003 2004 2005 2006 2007 Toval Inglewood “Shallow” 20 6 33 38 32 149 San Vicente 4 2 5 : ul Montebello 8 10 2 ul ul 55 Asroyo Grande 18 a 40 40 40 178 ‘Mount Poso 97 100 . a = 197 Illinais 43 a 39 34 34 192 East Texas 36 a at 28 £ 126 So. TX, OK. Other 1
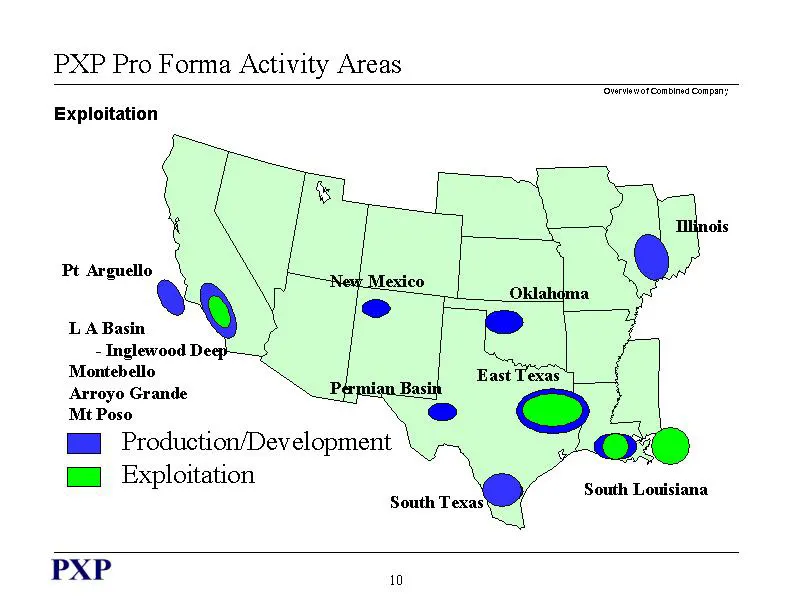
Slide 11: PXP Pro Forma Activity Areas
PXP Pro Forma Activity Areas Exploitation - Inglewood Deep Montebello Arroyo Grande Mt Poso GH Production/Development Ge Exploitation ‘Sweat Combined Company PXP 7
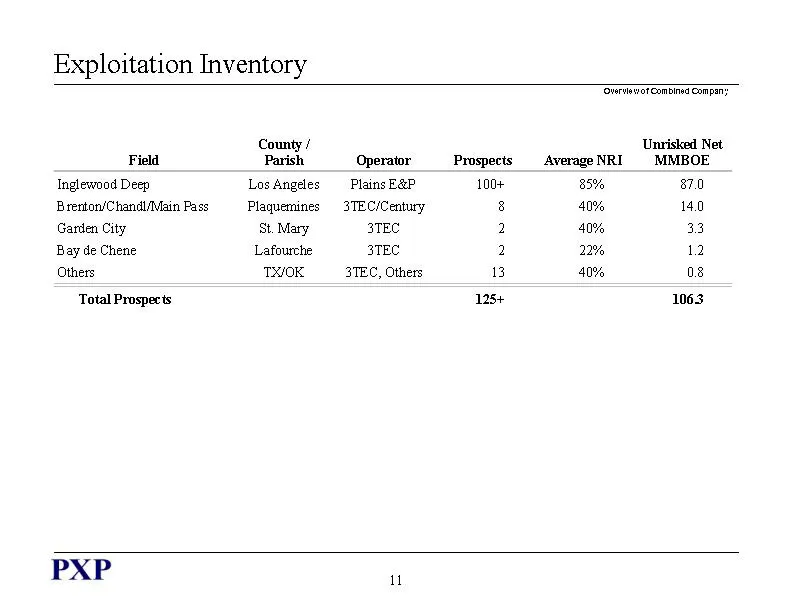
Slide 12: Exploitation Inventory
Exploitation Inventory ‘Sweat Combined Company County / Unrisked Net Field Parish Operator Prospects AverageNRI__ MMBOE Inglewood Deep Los Angeles Plains E&P 100+ 35% 870 Brentor/Chandl/Main Pass Plaquemines 3TEC/Century 3 40% 140 Garden City St. Mary 3TEC 2 40% 33 Bay de Chene Lafourche 3TEC 2 22%
Slide 13: California Exploitation
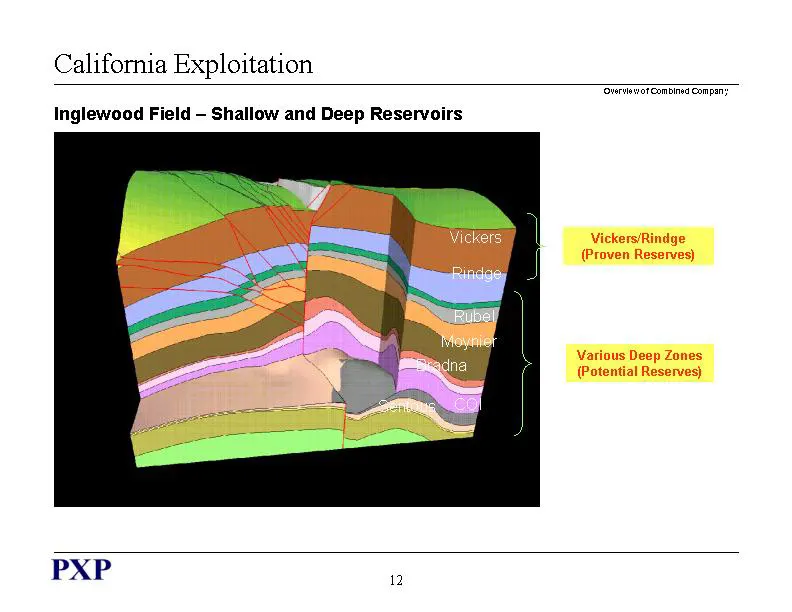
California Exploitation ‘Sweat Combined Company Inglewood Field — Shallow and Deep Reservoirs PXP 7
Slide 14: Inglewood Deep Composite Type Log
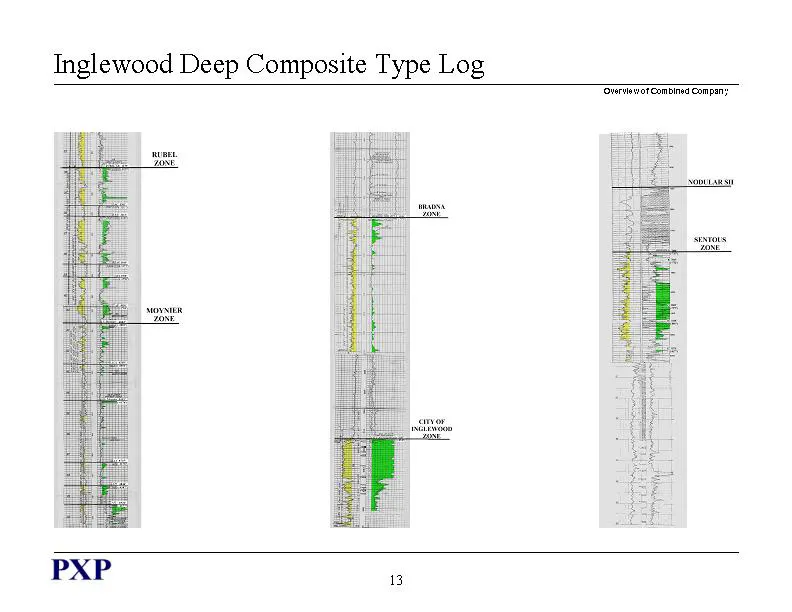
Inglewood Deep Composite Type Log PXP 13
Slide 15: PXP Inglewood Deep Development Sentous Reservoir
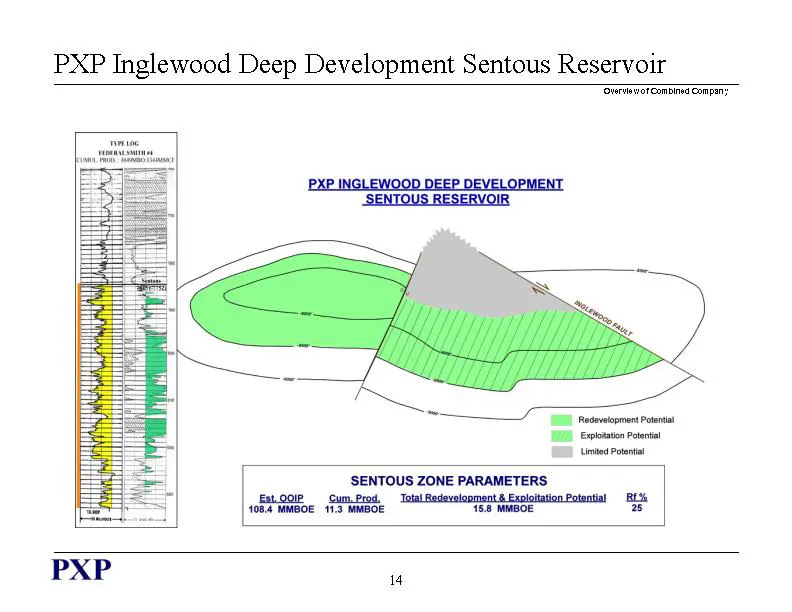
PXP Inglewood Deep Development Sentous Reservoir ‘Sweat Combined Company Redevelopment Potent (HDD. Explain Potent Umted Potent SENTOUS ZONE PARAMETERS Esto Cum. Prod, Rie 1084 MMGOE 11.3 NMBOE 168 MMBOE 28 PXP 4
Slide 16: South Louisiana Exploitation
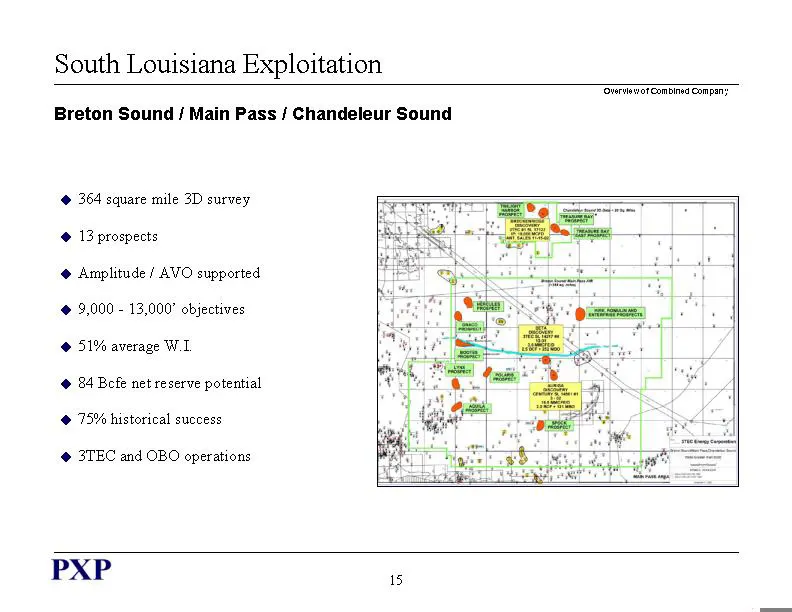
South Louisiana Exploitation ‘Sweat Combined Company Breton Sound / Main Pass / Chandeleur Sound © 364 square mile 3D survey © 13 prospects @ Amplitude / AVO supported © 9,000 - 13,000" objectives © 51% average W.L © 84 Befe net reserve potential © 75% historical success © 3TEC and OBO operations PX
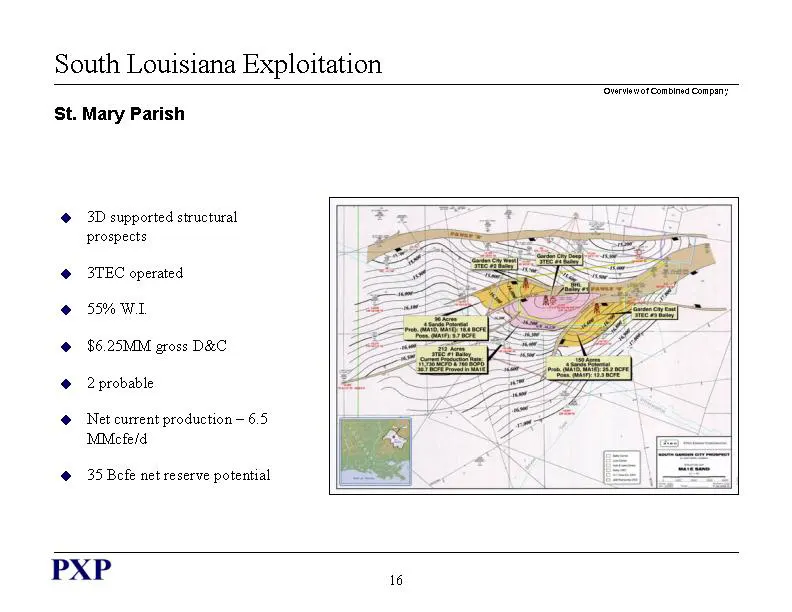
Slide 17: South Louisiana Exploitation
South Louisiana Exploitation ‘Sweat Combined Company St. Mary Parish © 3D supported structural prospects © BTEC operated © 55% WL @ 86.25MM gross D&C © 2probable © Net current production - 6.5 MMofeld @ 35 3Befe net reserve potential 16
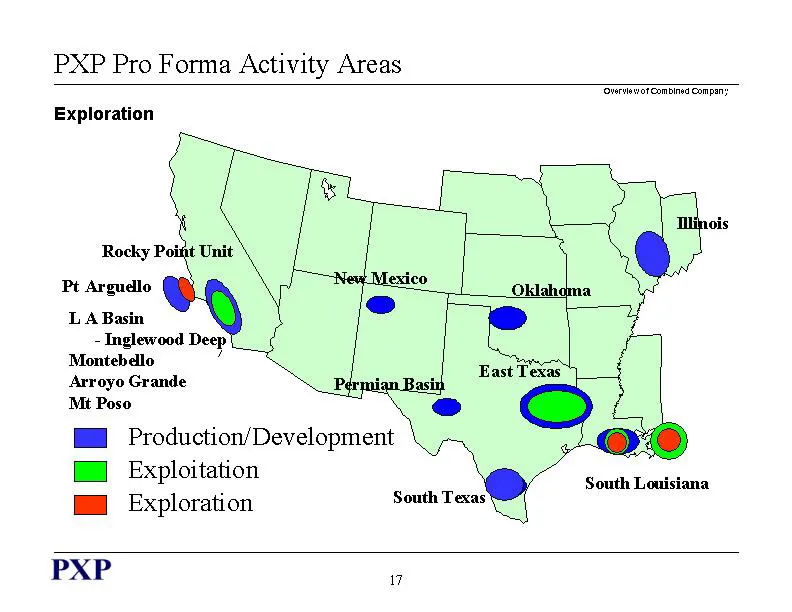
Slide 18: PXP Pro Forma Activity Areas
PXP Pro Forma Activity Areas ‘Sweat Combined Company Exploration - Inglewood Deep Montebello , Arroyo Grande Mt Poso HH Production/Development Exploitation @ Exploration PXP 7
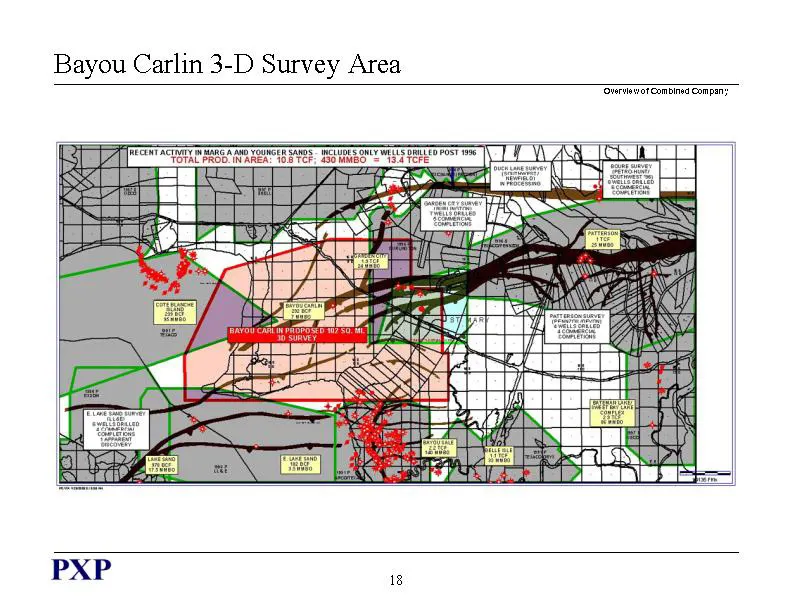
Slide 19: Bayou Carlin 3-D Survey Area
Bayou Carlin 3-D Survey Area ‘Sweat Combined Company pe ACTTAL PROD. N AREA" 108 TCE: PXP 7
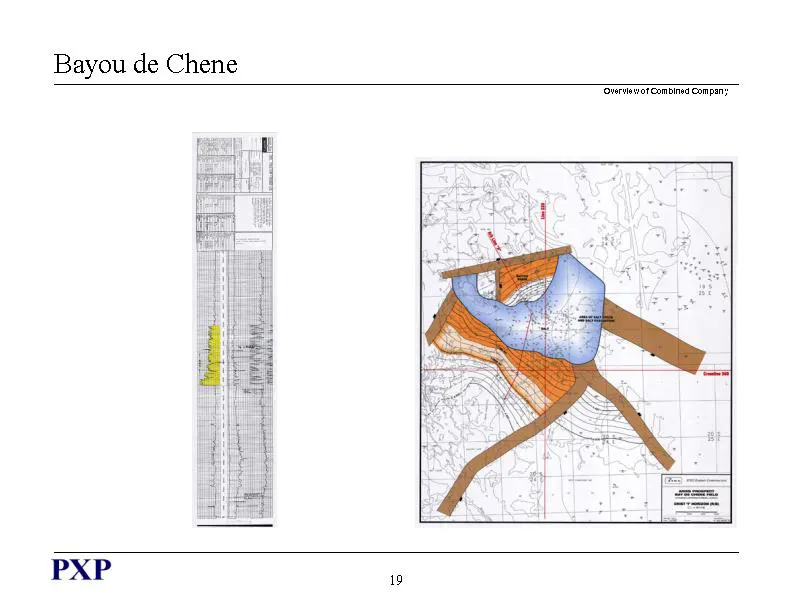
Slide 20: Bayou de Chene
Bayou de Chene ‘Sweat Combined Company PXP 19
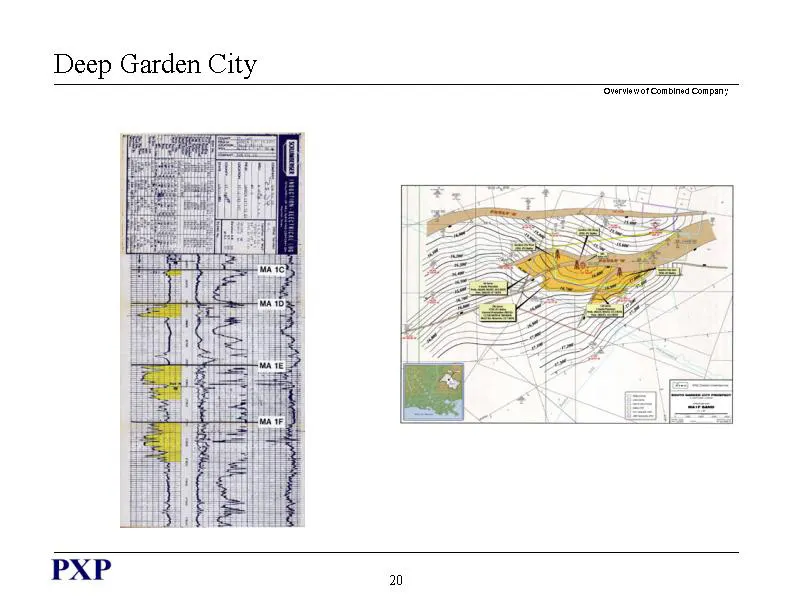
Slide 21: Deep Garden City
Deep Garden City an fi aD G 4 I aA un te fi ua Us H a i lt! je : ‘Sweat Combined Company PXP 20
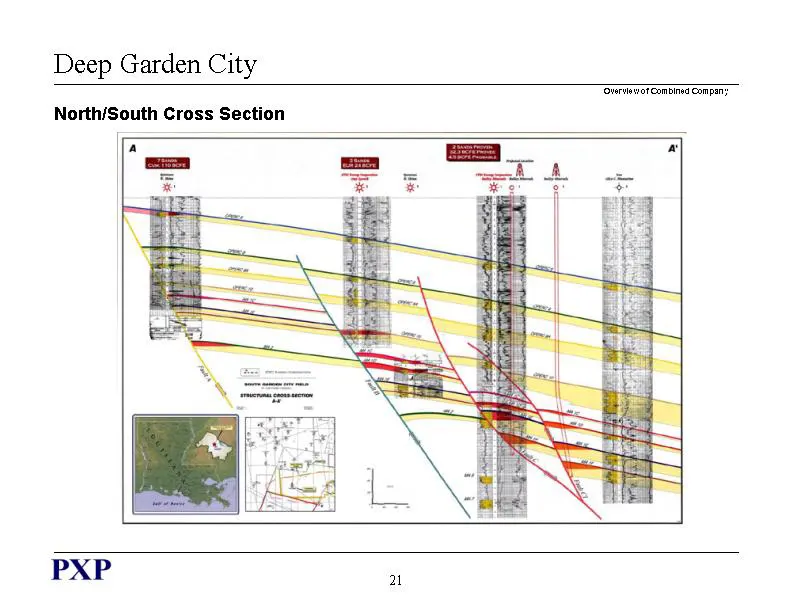
Slide 22: Deep Garden City North/South Cross Section
Deep Garden City North/South Cross Section PXP a
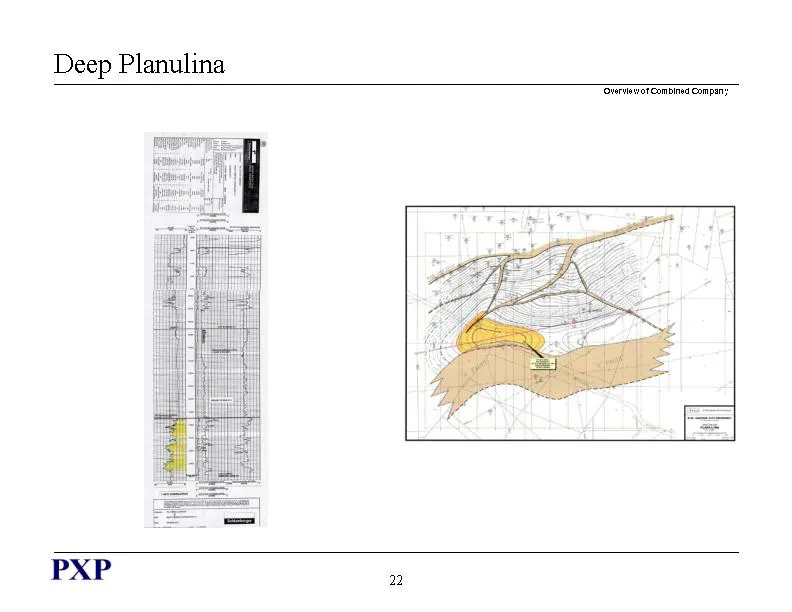
Slide 23: Deep Planulina
Deep Planulina ‘Sweat Combined Company PXP n
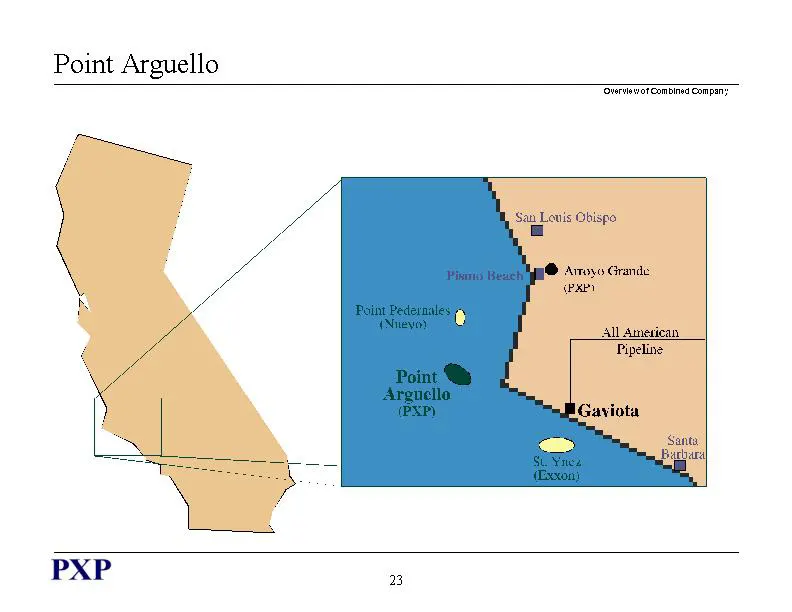
Slide 24: Point Arguello
Point Arguello ‘Sweat Combined Company San Louis Obispo z= © Arroyo Grande PAE: All Amevican Pipeline Gaviota PXP 7
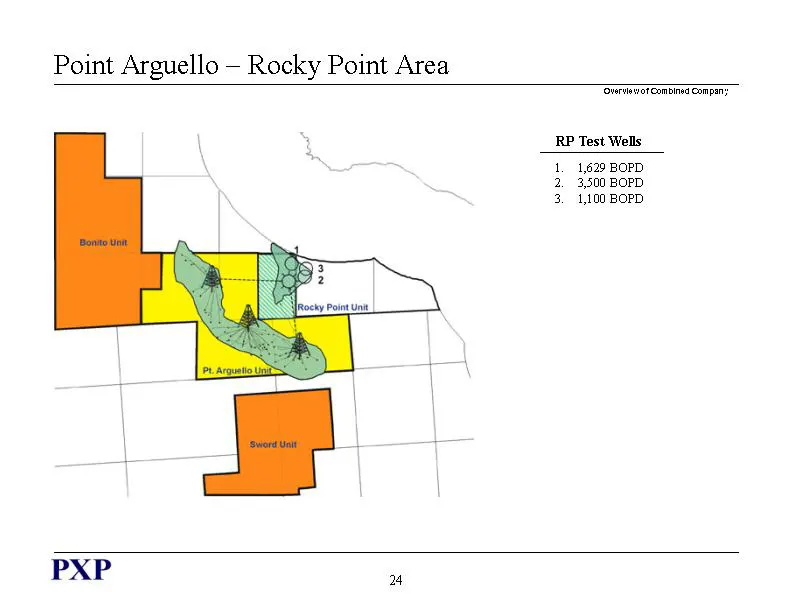
Slide 25: Point Arguello — Rocky Point Area
Point Arguello — Rocky Point Area ‘Sweat Combined Company RP Test Wells 1, 1,629 BOPD 2, 3,500 BOPD 3, 1,100 BOPD PXP “4
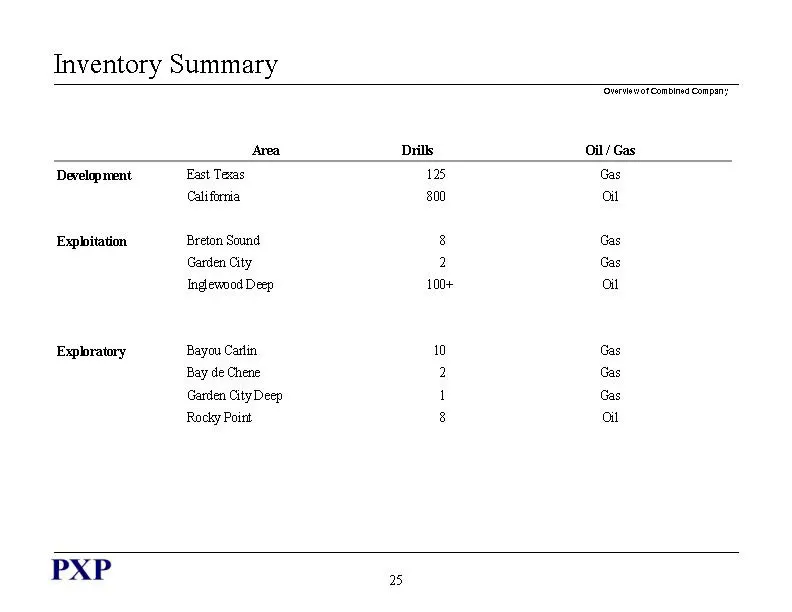
Slide 26: Inventory Summary
Inventory Summary Developitent East Texas Expbitation Breton Sound Expbratory Bayou Carlin Bay de Chene Garden CityDeep Rocky Point ‘Sweat Combined Company Drills Oil/ Gas 125 Gas 800 fort 8 Gas 2 Gas 100+ fort 10 Gas 2 Gas 1 Gas 8 fort PXP oo
Slide 27: Financial Summary
Financial Summary
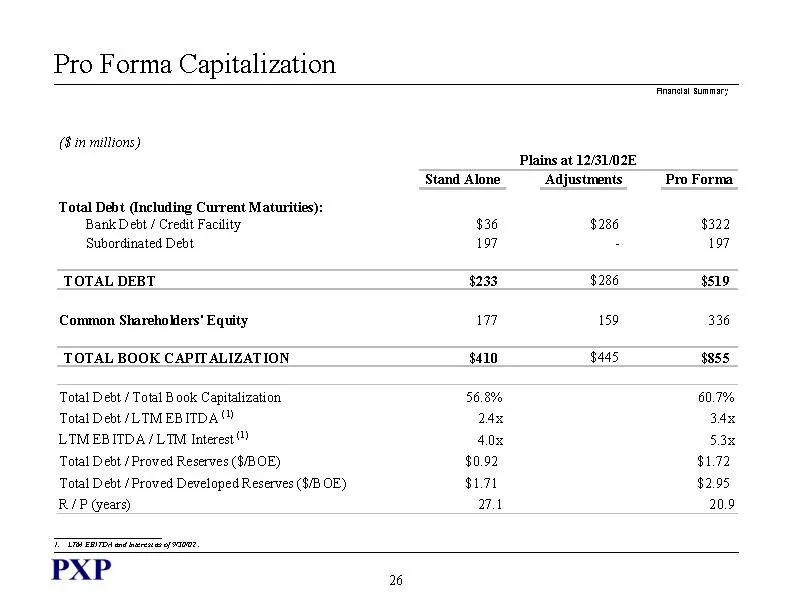
Slide 28: Pro Forma Capitalization
Pro Forma Capitalization (8 in millions) Total Debt (cluding Current Maturities): Bank Debt / Credit Facility Subordinated Debt TOTAL DEBT Common SharehoWers' Equity TOTAL BOOK CAPITALIZATION Total Debt / Total B ook Capitalization Total Debt /LTM EBITDA? LTMEBITDA/LTM Interest Total Debt / Proved R
Slide 29: Combined Hedge Positions
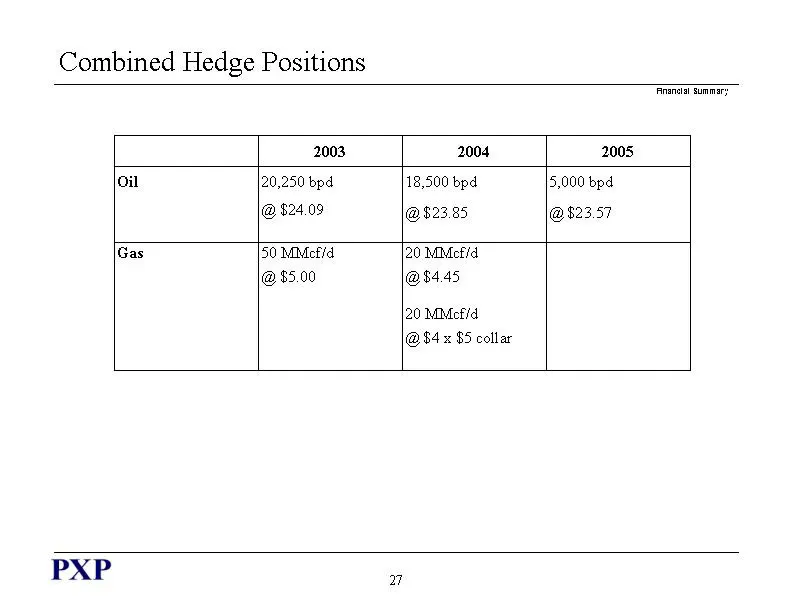
Combined Hedge Positions 2003 2004 2005 oi 20,250 bpd 18,500 bpd 5,000 bpd @ $24.09 @ $23.85 @ $23.57 Gas 50 MMMciid 20 MiMciid @ $5.00 @s445 20 MMMcffd @84 x $5 collar PXP n
Slide 30: 2003 Guidance
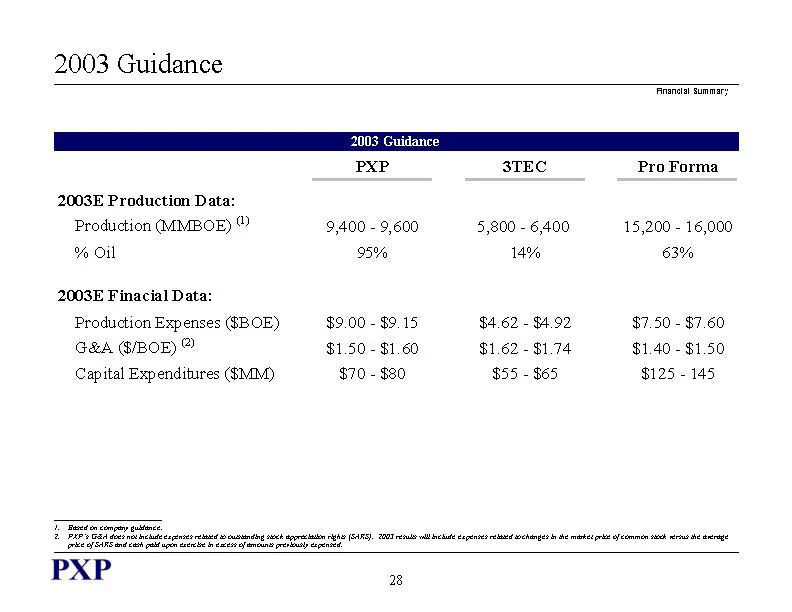
2003 Guidance 2003E Production Data: Production (MMBOE) ® 9,400 - 9,600 % Oil 95% 2003E Finacial Data: Production Expenses @BOE) $9.00 - $9.15 G&A G/BOE) $1.50 - $1.60 Capital Expenditures (SMM) $70 - $80 5,800 - 6,400 14% $4.62 - $4.92 $1.62 - $1.74 $55 - $65 Pro Forma 15,200 - 16,000 63% $7.50 - $
Slide 31: Financing Strategy
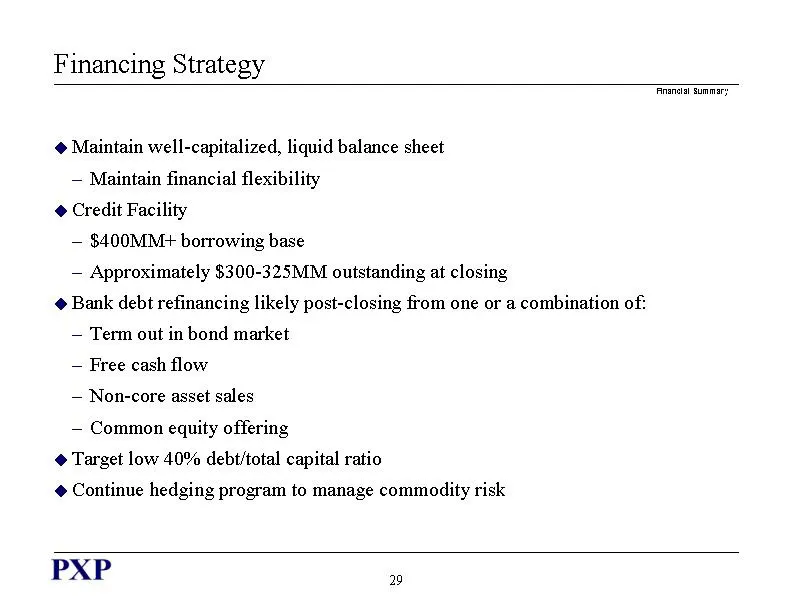
Financing Strategy Maintain well-capitalized, liquid balance sheet — Maintain financial flexibility Credit Facility — $400MM+ borrowing base — Approximately $300-325MM outstanding at closing @ Bank debt refinancing likely post-closing from one or a combination of: — Term out in bond market = Free ca
Slide 32: Summary
Summary
Slide 33: Combined Operating Objectives
Combined Operating Objectives iro Forma Campa Maintain strong free cash flow from operations using consistent long-term hedging program Continue cost reductions and efficiencies while developing large, indigenous development, exploitation, and exploration inventory Build on strategic acquisition suc
Slide 34: Forward-looking statements
This presentation includes “forward-looking statements” as defined by the Securities and Exchange Commission. Such statements are those concerning the companies’ merger and strategic plans, expectations and objectives for future operations. All statements included in this presentation that address a
Source: SEC EDGAR · 425 filed Feb 10, 2003
More decks from Plains Exploration & Production Company
 Global Metals, Mining & Steel Conference 201333 slides · May 14, 2013
 Q1 2013 Earnings Presentation46 slides · Apr 19, 2013
 Merger or Acquisition (February 2013)35 slides · Feb 25, 2013
 2013 Credit Suisse Energy Summit10 slides · Feb 5, 2013
 Merger or Acquisition (January 2013)30 slides · Jan 17, 2013
 Credit Suisse 2012 Energy Summit32 slides · Feb 7, 2012