Sterling Bancorp — Provident New York Bancorp — Investor Presentation (October 2005)
19 slides from Sterling Bancorp's investor presentation, Oct 31, 2005
Slide 1: Connecting People With Opportunities
Exhibit 99 Connecting People With Opportunities SM PBNY
Slide 2: Deposit Growth - George Strayton
George Strayton President Chief Executive Officer Deposit Growth November 2, 2005
Slide 3: Forward-looking Statements
Forward-looking Statements Statements contained in this news release that are not historical facts are forward-looking statements as that term is defined in the Private Securities Litigation Reform Act of 1995. Such forward-looking statements are subject to risks and uncertainties which could cause
Slide 4: A Quick Look at Provident Bank
A Quick Look at Provident Bank Established in 1888 with Thrift charter Reorganized into an MHC in 1999 and conducted IPO that raised $38.6 million, second step in 2004 raised $195.7 million Provident Municipal Bank created in 2002 as a wholly-owned subsidiary Recent acquisitions: HSBC South Fallsbur
Slide 5: Concentrated Franchise in Growing Area
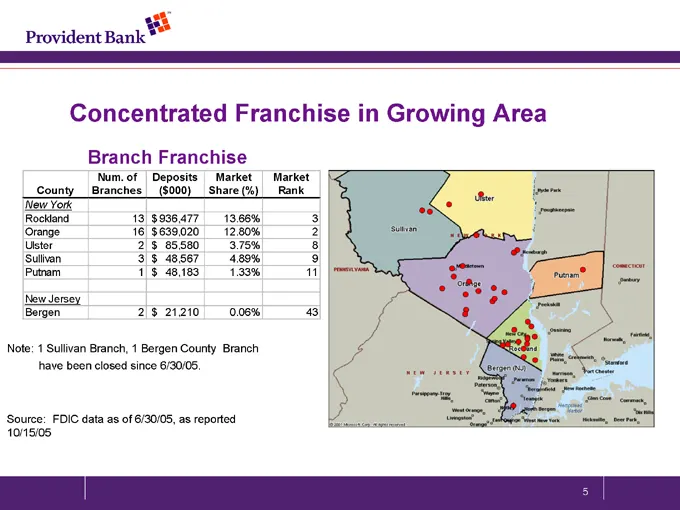
Concentrated Franchise in Growing Area Branch Franchise County Num. of Branches Deposits ($ 000) Market Share (%) Market Rank New York Rockland 13 $ 936,477 13.66% 3 Orange 16 $ 639,020 12.80% 2 Ulster 2 $ 85,580 3.75% 8 Sullivan 3 $ 48,567 4.89% 9 Putnam 1 $ 48,183 1.33% 11 New Jersey Bergen 2 $ 21
Slide 6: Hudson Valley Economy per NYS Comptroller
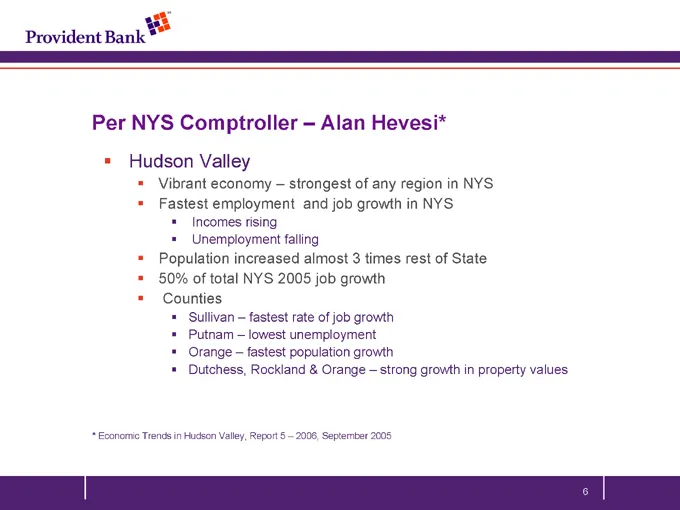
Per NYS Comptroller – Alan Hevesi* Hudson Valley Vibrant economy – strongest of any region in NYS Fastest employment and job growth in NYS Incomes rising Unemployment falling Population increased almost 3 times rest of State 50% of total NYS 2005 job growth Counties Sullivan – fastest rate of job gr
Slide 7: Robust Market Place
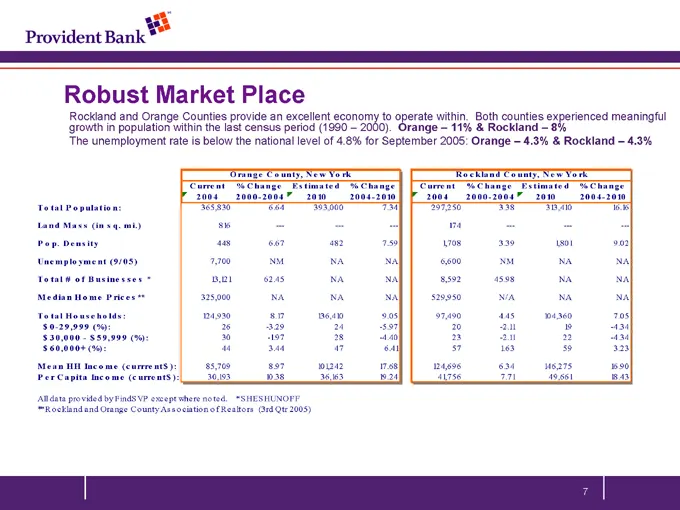
Robust Market Place Rockland and Orange Counties provide an excellent economy to operate within. Both counties experienced meaningful growth in population within the last census period (1990 – 2000). Orange – 11% & Rockland – 8% The unemployment rate is below the national level of 4.8% for September
Slide 8: Successful Business Strategy
Successful Business Strategy Full Service Community Bank Vibrant and Growing Market Place Full array of Products Profitable, Strategically Positioned Institution Exceptional Asset Quality Commercial Profile Bold new look Large Core Deposit base
Slide 9: Deposits come in many flavors
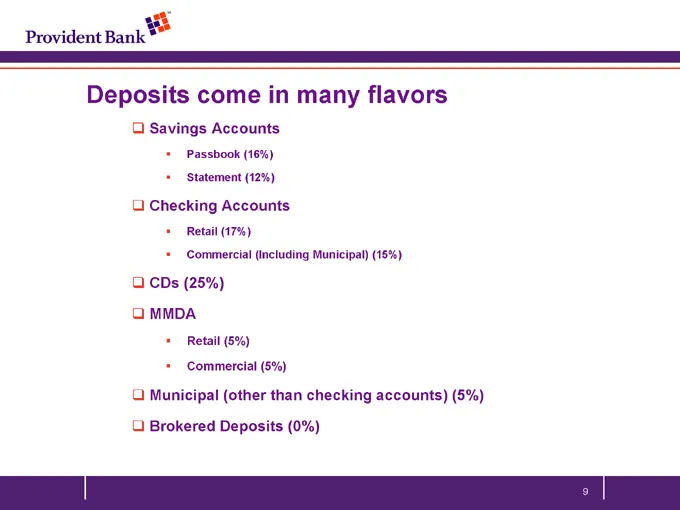
Deposits come in many flavors Savings Accounts Passbook (16%) Statement (12%) Checking Accounts Retail (17%) Commercial (Including Municipal) (15%) CDs (25%) MMDA Retail (5%) Commercial (5%) Municipal (other than checking accounts) (5%) Brokered Deposits (0%)
Slide 10: Every Flavor is Good
Every Flavor is Good - Low cost funds Management of interest rate risk First chance for new business relationships Fee income opportunities BUT …
Slide 11: But … Some Flavors are better
But … Some Flavors are better Deposits that stay (Core deposits) Deposits that produce higher profitability Deposits that produce fees Transitory deposits that are less than wholesale borrowing Lets look at results …
Slide 12: Building and Keeping Deposits
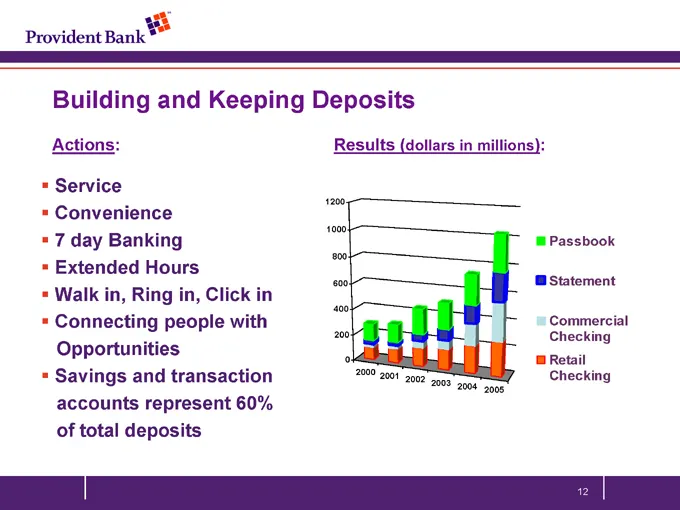
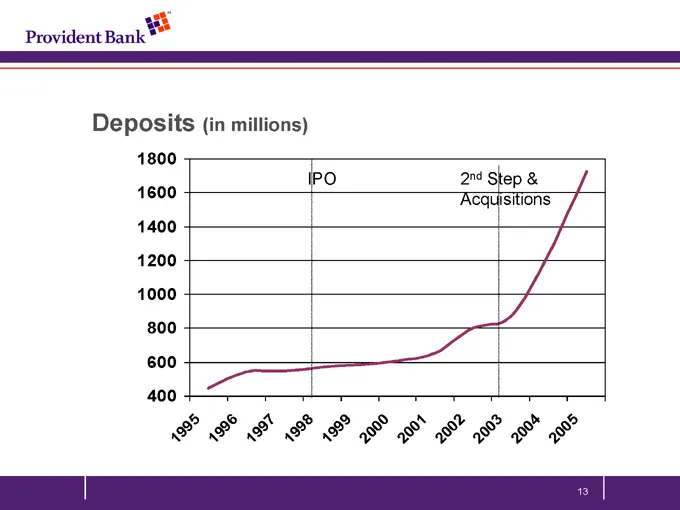
Building and Keeping Deposits Actions: Service Convenience 7 day Banking Extended Hours Walk in, Ring in, Click in Connecting people with Opportunities Savings and transaction accounts represent 60% of total deposits Results (dollars in millions): 1200 1000 800 600 400 200 0 2000 2001 2002 2003 2004
Slide 13: Deposits (in millions)
Deposits (in millions) 1800 1600 1400 1200 1000 800 600 400 IPO 2nd Step & Acquisitions 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005
Slide 14: Cost of Funds (in percent)
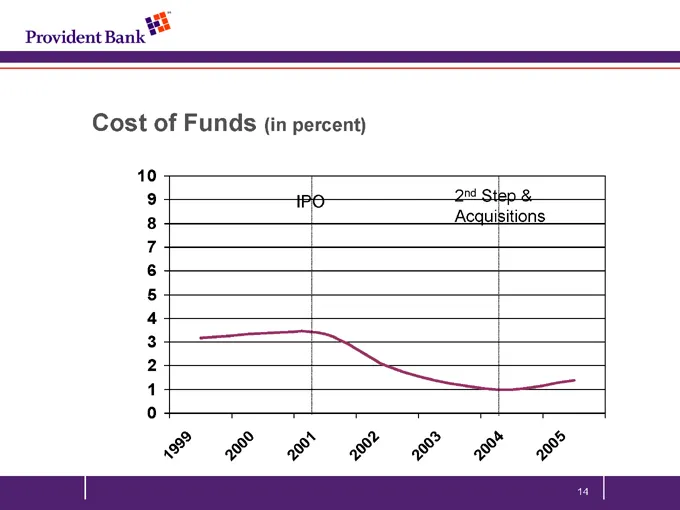
Cost of Funds (in percent) 10 9 8 7 6 5 4 3 2 1 0 IPO 2nd Step & Acquisitions 1999 2000 2001 2002 2003 2004 2005
Slide 15: Net Interest Margin (NIM)
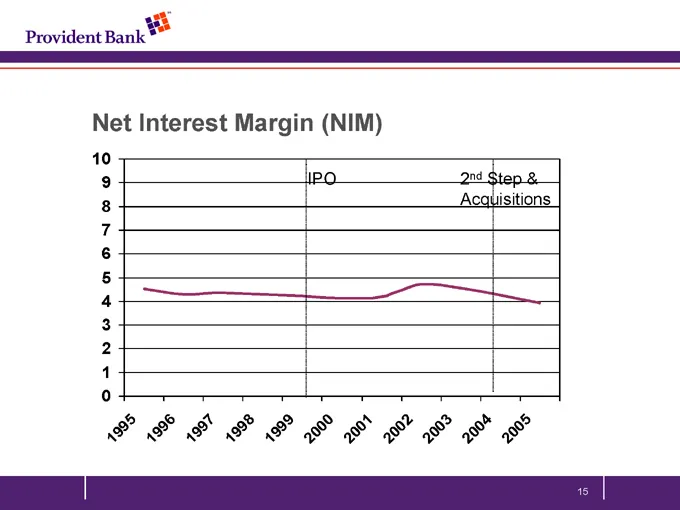
Net Interest Margin (NIM) 10 9 8 7 6 5 4 3 2 1 0 IPO 2nd Step & Acquisitions 1995 996 1997 1998 1999 2000 2001 2002 2003 2004 2005
Slide 16: Cost of Interest Bearing Deposits & Federal Funds Rate
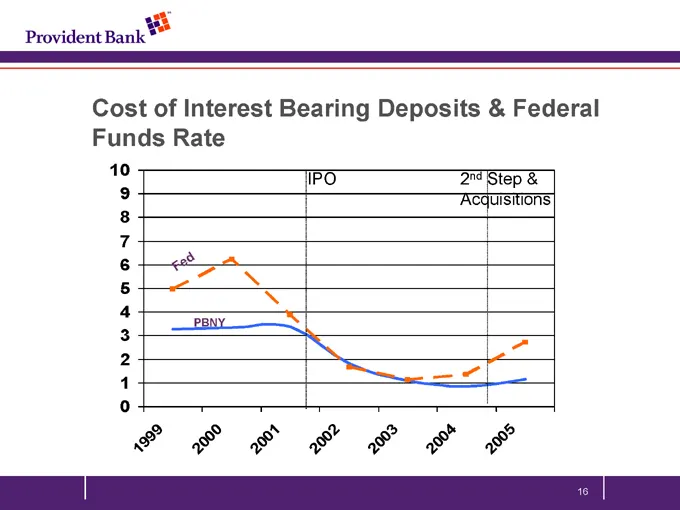
Cost of Interest Bearing Deposits & Federal Funds Rate 10 9 8 7 6 5 4 3 2 1 0 IPO 2nd Step & Acquisitions 1999 2000 2001 2002 2003 2004 2005
Slide 17: Efficiency Ratio (in percent)
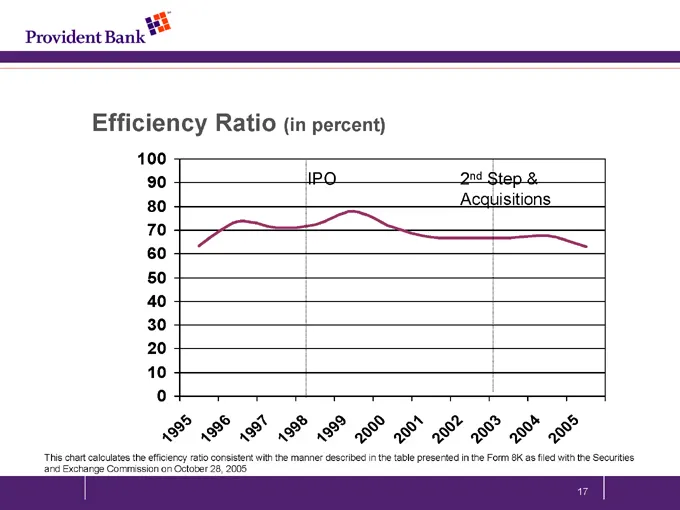
Efficiency Ratio (in percent) 100 90 80 70 60 50 40 30 20 10 0 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 IPO 2nd Step & Acquisitions This chart calculates the efficiency ratio consistent with the manner described in the table presented in the Form 8K as filed with the Securities and Exc
Slide 18: A Delicate Balance—attracting deposits while controlling cost
A Delicate Balance—attracting deposits while controlling cost Service Access Technology Vibrant Market Right Products for the Market Strong Asset Quality Attract stronger credits Maintain spread Putting it all together …
Slide 19: Fiscal 2006: Growing Stronger, Serving Better
Fiscal 2006 Revenue Growing Stronger, Serving Better … It’s All Coming Together Expense
Source: SEC EDGAR · 8-K filed Oct 31, 2005
More decks from Sterling Bancorp
 Merger or Acquisition (April 2021)27 slides · Apr 19, 2021
 IPO Roadshow (October 2020)27 slides · Oct 28, 2020
 IPO Roadshow (December 2019)23 slides · Dec 11, 2019
 Investor Presentation (May 2019)29 slides · May 13, 2019
 Shareholder Meeting (May 2015)15 slides · May 28, 2015
 Provident New York Bancorp — Merger or Acquisition (July 2013)13 slides · Jul 31, 2013