Ditech — Walter Investment Management — Investor Day (September 2012)
105 slides from Ditech's investor day presentation, Sep 11, 2012
Slide 1: 2012 Investor and Financial Analyst Day
2012 Investor and Financial Analyst Day September 11, 2012 0
Slide 2: Welcoming Comments
Welcoming Comments Whitney K. Finch Vice President, Investor Relations September 11, 2012 1
Slide 3: Legal Disclaimers
Legal Disclaimers Disclaimer and Cautionary Note Regarding Forward-Looking Statements This press release contains forward-looking statements, including forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements include, but
Slide 4: Opening Remarks
Opening Remarks Mark J. O'Brien Chairman and Chief Executive Officer September 11, 2012 3
Slide 5: Walter Investment Management Corp.
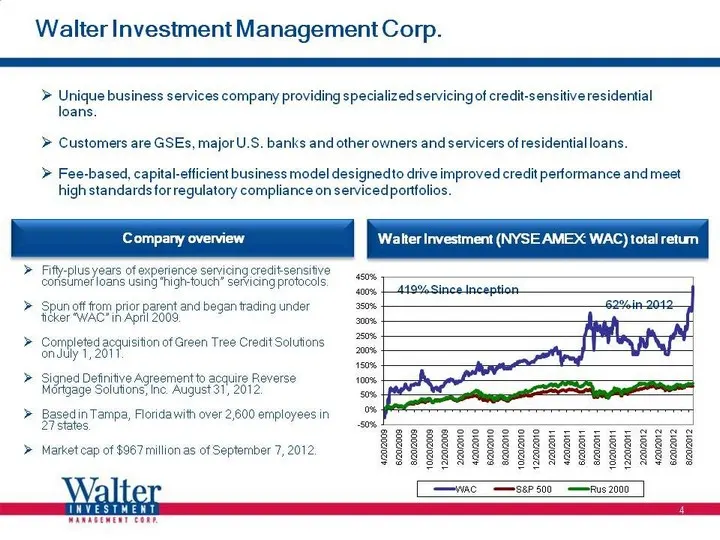
4 Walter Investment Management Corp. Unique business services company providing specialized servicing of credit-sensitive residential loans. Customers are GSEs, major U.S. banks and other owners and servicers of residential loans. Fee-based, capital-efficient business model designed to drive improve
Slide 6: Investment Thesis
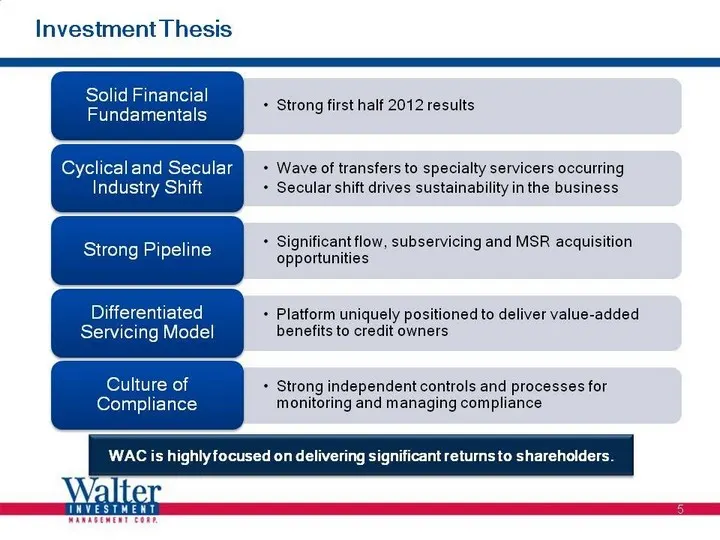
Investment Thesis 5 WAC is highly focused on delivering significant returns to shareholders.
Slide 7: Strategic Overview
Strategic Overview Denmar Dixon Vice Chairman and Executive Vice President September 11, 2012 6
Slide 8: Strategic Overview
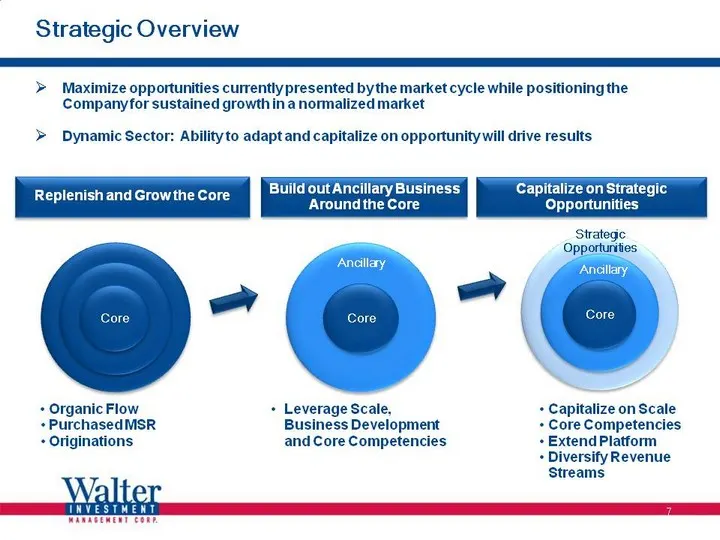
Strategic Overview Maximize opportunities currently presented by the market cycle while positioning the Company for sustained growth in a normalized market Dynamic Sector: Ability to adapt and capitalize on opportunity will drive results 7 Organic Flow Purchased MSR Originations Leverage Scale, Busi
Slide 9: Building Scale and Sustainability in the New Environment
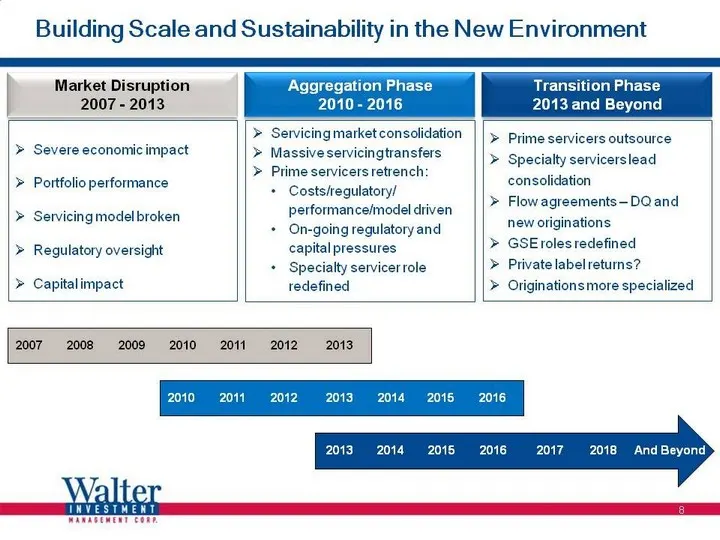
8 Building Scale and Sustainability in the New Environment Market Disruption 2007 - 2013 Aggregation Phase 2010 - 2016 Transition Phase 2013 and Beyond Severe economic impact Portfolio performance Servicing model broken Regulatory oversight Capital impact Servicing market consolidation Massive servi
Slide 10: Capitalizing on Opportunity
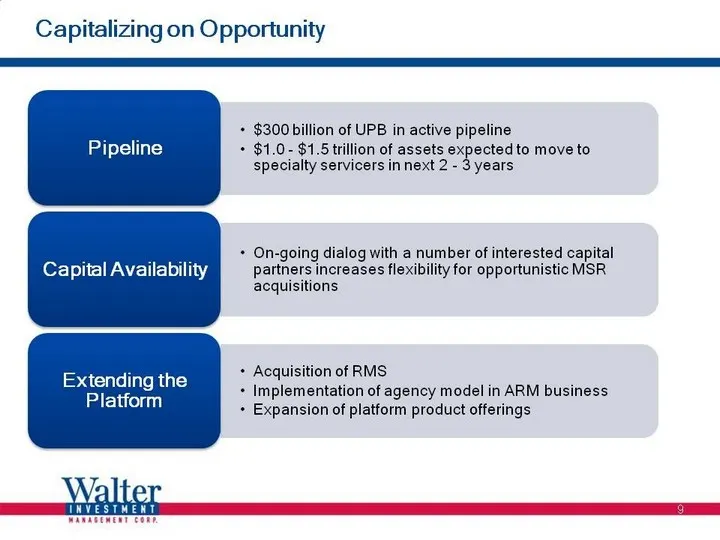
Capitalizing on Opportunity 9
Slide 11: Green Tree Overview
Green Tree Overview Keith A. Anderson President and CEO, Green Tree September 11, 2012
Slide 12: Green Tree Overview
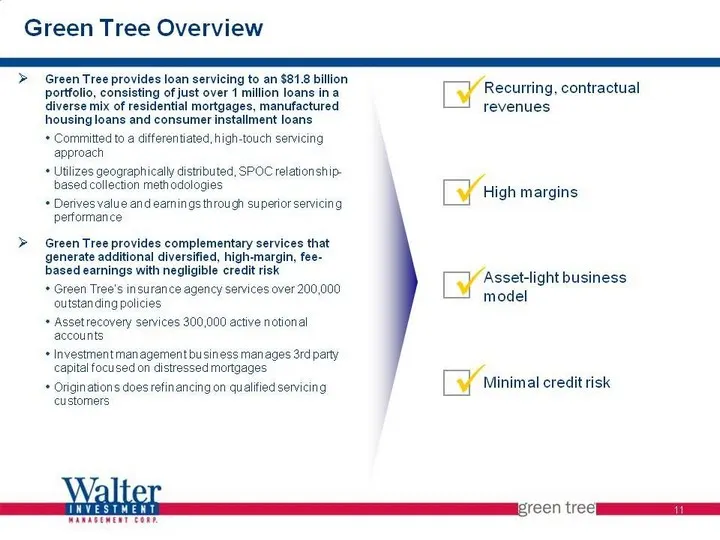
Green Tree Overview 11 Green Tree provides loan servicing to an $81.8 billion portfolio, consisting of just over 1 million loans in a diverse mix of residential mortgages, manufactured housing loans and consumer installment loans Committed to a differentiated, high-touch servicing approach Utilizes
Slide 13: Complementary Business Lines
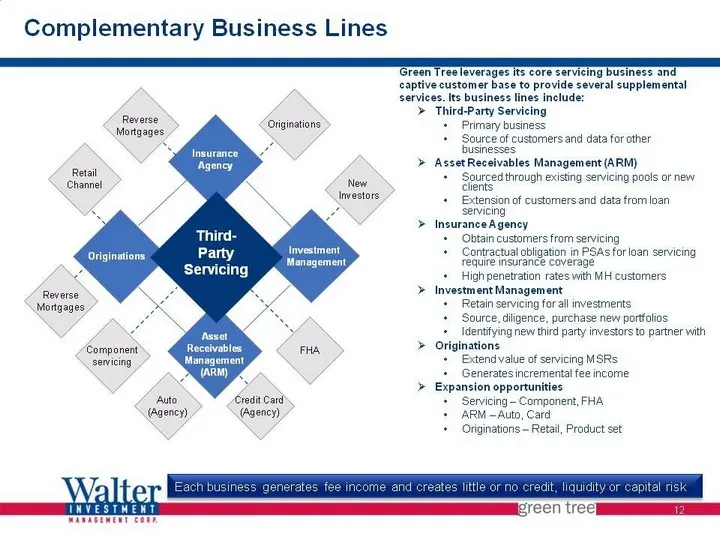
Complementary Business Lines Investment Management Insurance Agency Asset Receivables Management (ARM) Originations Retail Channel Reverse Mortgages Credit Card (Agency) Component servicing FHA Originations Third- Party Servicing New Investors Reverse Mortgages Green Tree leverages its core servicin
Slide 14: Complementary Business Lines (cont.)
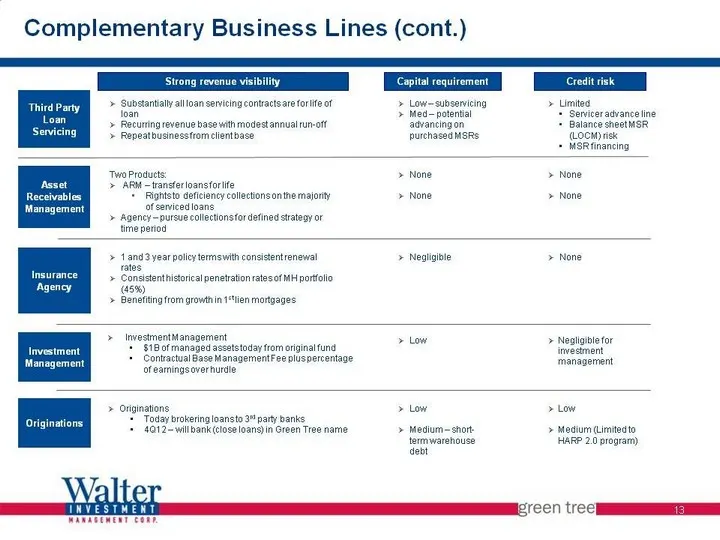
Complementary Business Lines (cont.) 13 Third Party Loan Servicing Substantially all loan servicing contracts are for life of loan Recurring revenue base with modest annual run-off Repeat business from client base Strong revenue visibility Low - subservicing Med - potential advancing on purchased MS
Slide 15: Organizational Chart
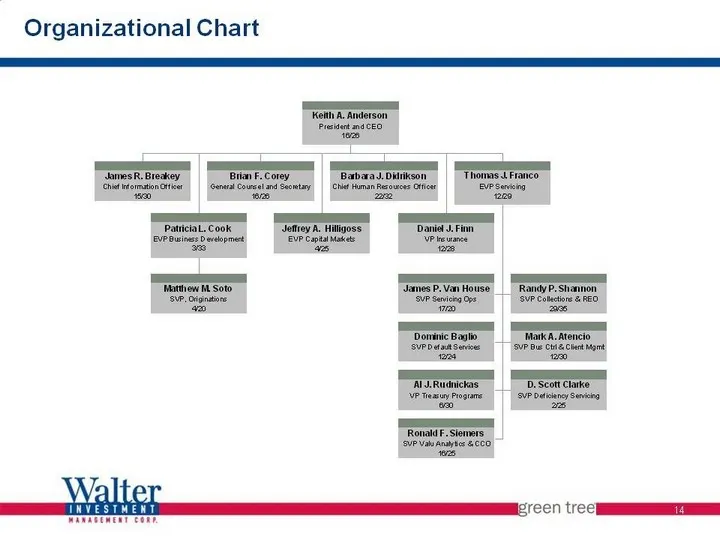
Organizational Chart EV ———EE a
Slide 16: Green Tree Presence
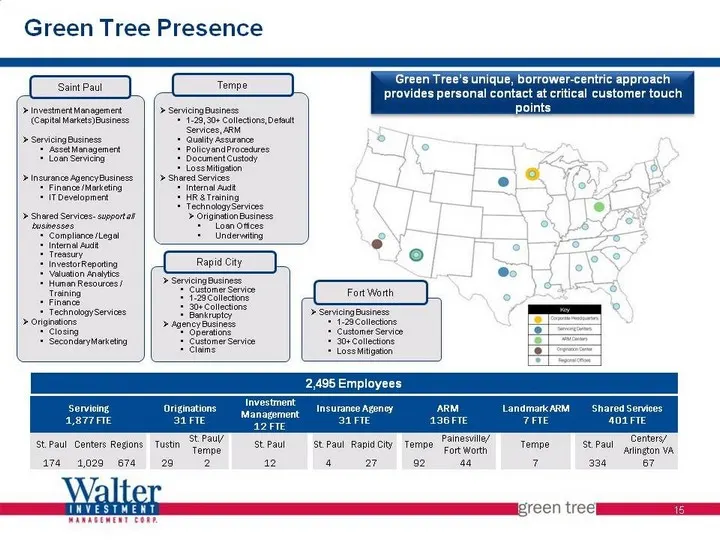
Green Tree Presence 15 Green Tree's unique, borrower-centric approach provides personal contact at critical customer touch points Servicing 1,877 FTE Servicing 1,877 FTE Servicing 1,877 FTE Originations 31 FTE Originations 31 FTE Investment Management 12 FTE Insurance Agency 31 FTE Insurance Agency
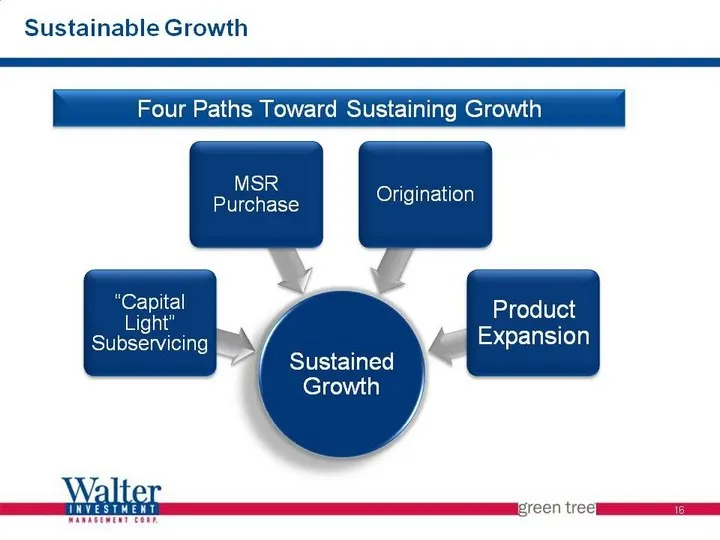
Slide 17: Sustainable Growth: Four Paths Toward Sustaining Growth
Sustainable Growth 16 Four Paths Toward Sustaining Growth 16
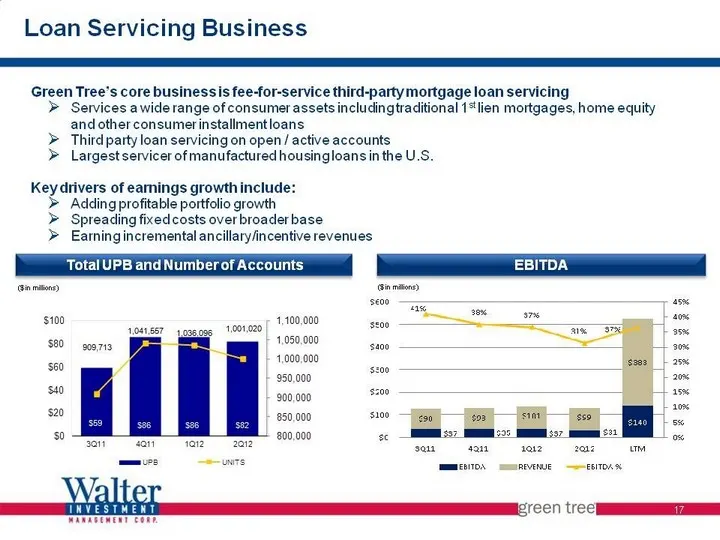
Slide 18: Loan Servicing Business
Loan Servicing Business 17 Green Tree's core business is fee-for-service third-party mortgage loan servicing Services a wide range of consumer assets including traditional 1st lien mortgages, home equity and other consumer installment loans Third party loan servicing on open / active accounts Larges
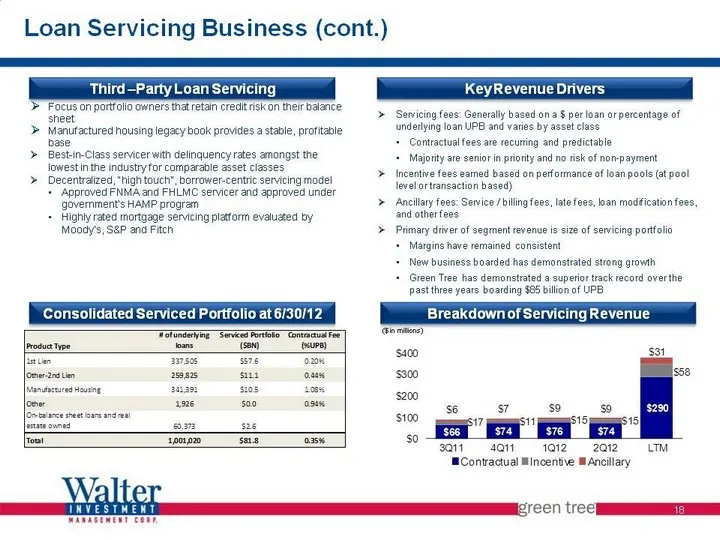
Slide 19: Loan Servicing Business (cont.)
Loan Servicing Business (cont.) 18 Focus on portfolio owners that retain credit risk on their balance sheet Manufactured housing legacy book provides a stable, profitable base Best-in-Class servicer with delinquency rates amongst the lowest in the industry for comparable asset classes Decentralized,
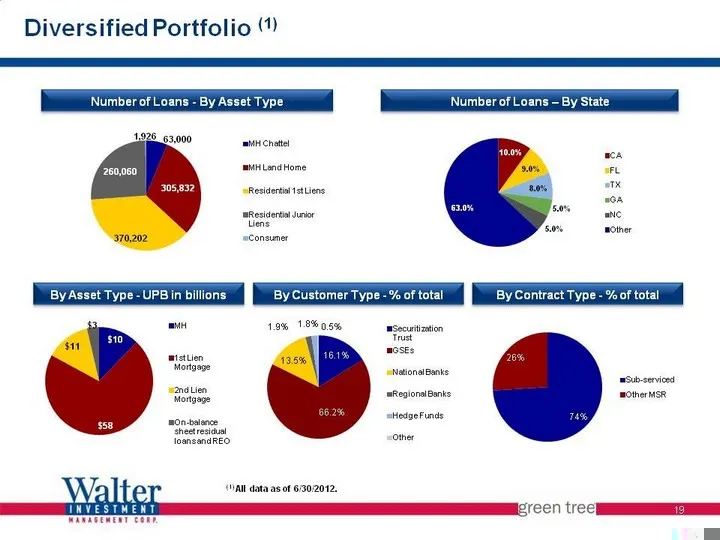
Slide 20: Diversified Portfolio
Diversified Portfolio (1) 19 By Asset Type - UPB in billions By Contract Type - % of total By Customer Type - % of total Number of Loans - By Asset Type Number of Loans - By State (1) All data as of 6/30/2012. 19
Slide 21: Recurring Earnings
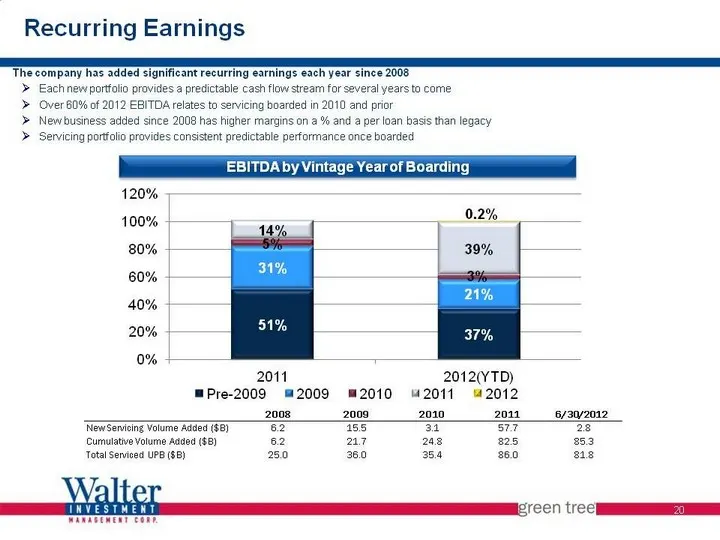
Recurring Earnings 20 The company has added significant recurring earnings each year since 2008 Each new portfolio provides a predictable cash flow stream for several years to come Over 60% of 2012 EBITDA relates to servicing boarded in 2010 and prior New business added since 2008 has higher margins
Slide 22: Asset Receivables Management
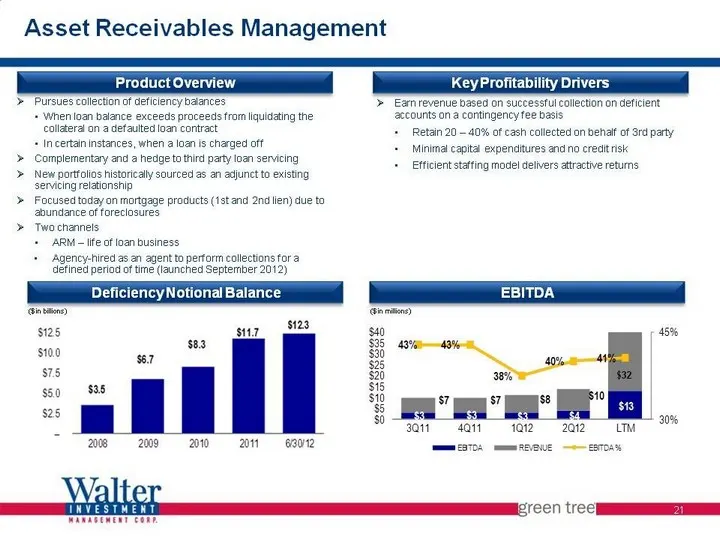
Asset Receivables Management 21 Pursues collection of deficiency balances When loan balance exceeds proceeds from liquidating the collateral on a defaulted loan contract In certain instances, when a loan is charged off Complementary and a hedge to third party loan servicing New portfolios historical
Slide 23: Insurance Agency
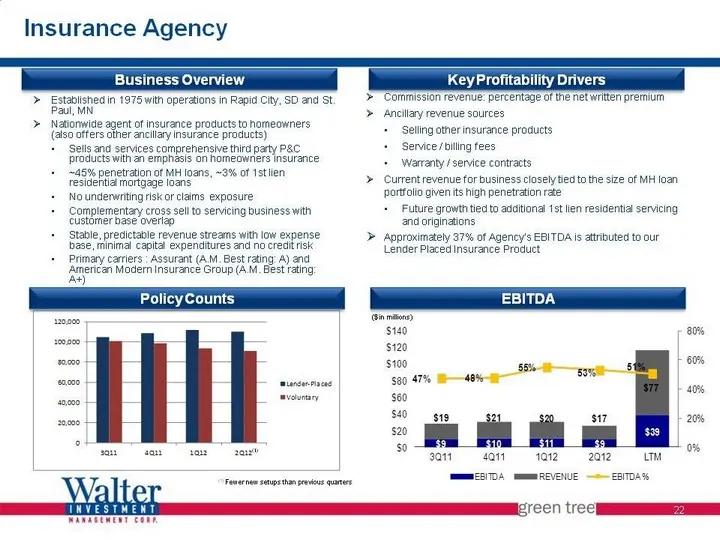
Insurance Agency 22 Established in 1975 with operations in Rapid City, SD and St. Paul, MN Nationwide agent of insurance products to homeowners (also offers other ancillary insurance products) Sells and services comprehensive third party P&C products with an emphasis on homeowners insurance ~45% pen
Slide 24: Originations Business
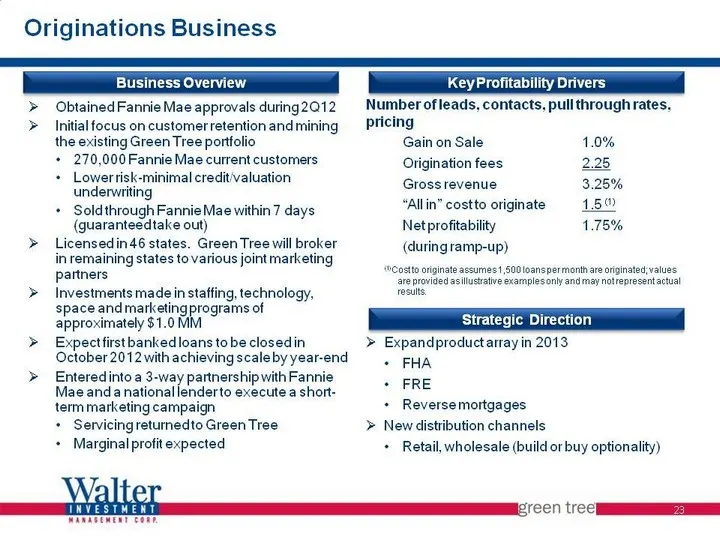
Originations Business 23 Obtained Fannie Mae approvals during 2Q12 Initial focus on customer retention and mining the existing Green Tree portfolio 270,000 Fannie Mae current customers Lower risk-minimal credit/valuation underwriting Sold through Fannie Mae within 7 days (guaranteed take out) Licens
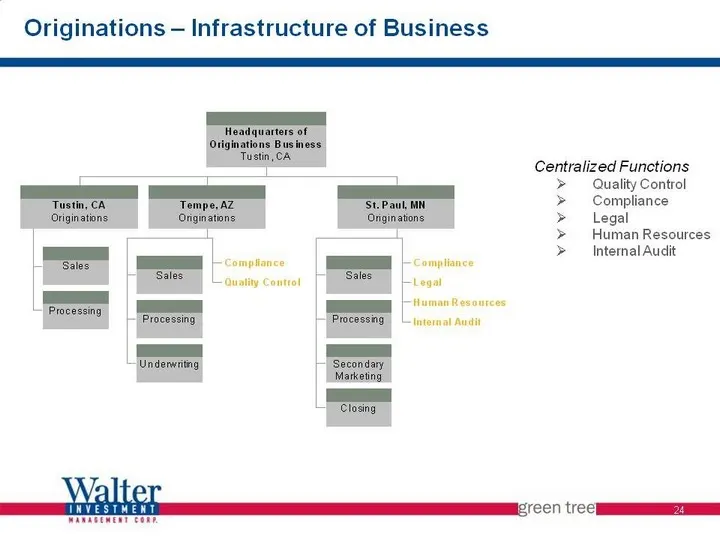
Slide 25: Originations - Infrastructure of Business
Originations - Infrastructure of Business 24 Centralized Functions Quality Control Compliance Legal Human Resources Internal Audit 24
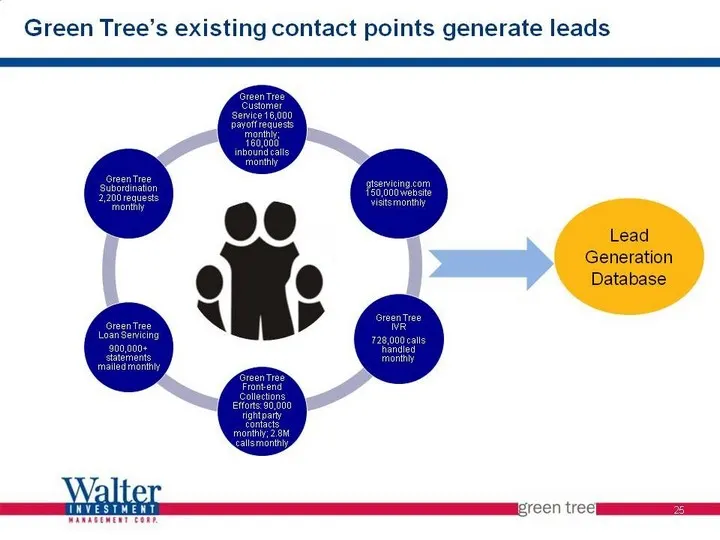
Slide 26: Existing contact points generate leads
Green Tree's existing contact points generate leads 25 25 Lead Generation Database 25
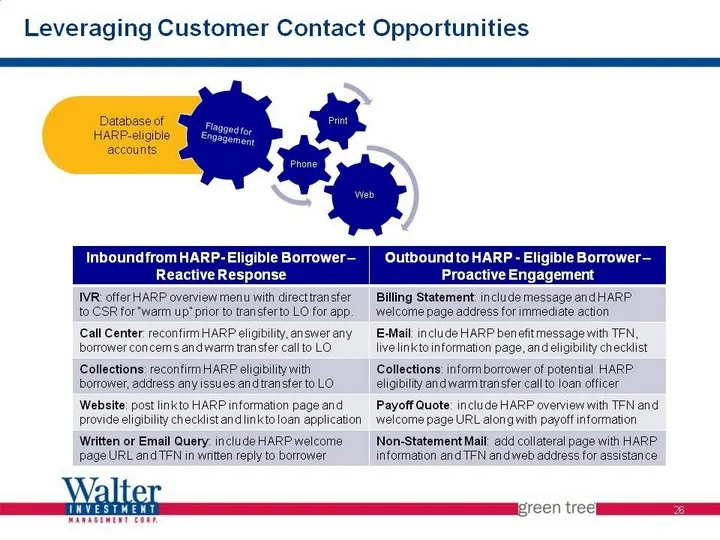
Slide 27: Leveraging Customer Contact Opportunities
Leveraging Customer Contact Opportunities 26 Database of HARP-eligible accounts Inbound from HARP- Eligible Borrower - Reactive Response Outbound to HARP - Eligible Borrower - Proactive Engagement IVR: offer HARP overview menu with direct transfer to CSR for "warm up" prior to transfer to LO for app
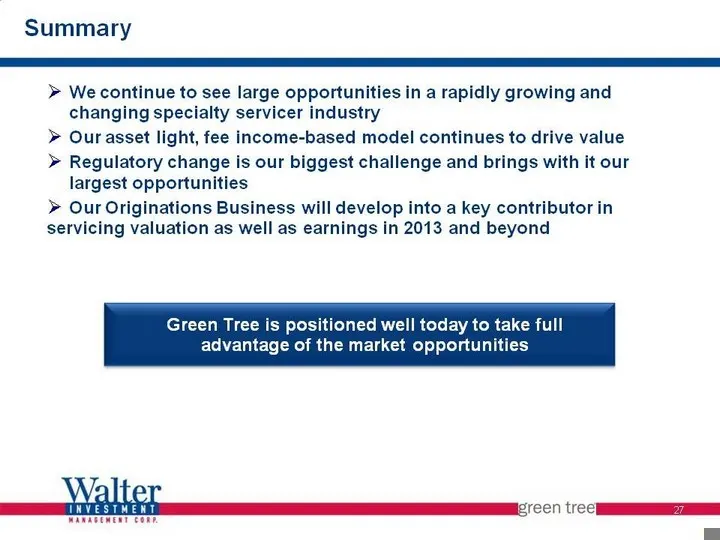
Slide 28: Summary
Summary 27 We continue to see large opportunities in a rapidly growing and changing specialty servicer industry Our asset light, fee income-based model continues to drive value Regulatory change is our biggest challenge and brings with it our largest opportunities Our Originations Business will deve
Slide 29: Appendix
2 MANAGEMENT CORP. relationships that work green tree Appendix
Slide 30: Use of Non-GAAP Measures
29 Use of Non-GAAP Measures Generally Accepted Accounting Principles ("GAAP") is the term used to refer to the standard framework of guidelines for financial accounting. GAAP includes the standards, conventions, and rules accountants follow in recording and summarizing transactions and in the prepar
Slide 31: Q2 2012 Pro Forma Adjusted EBITDA
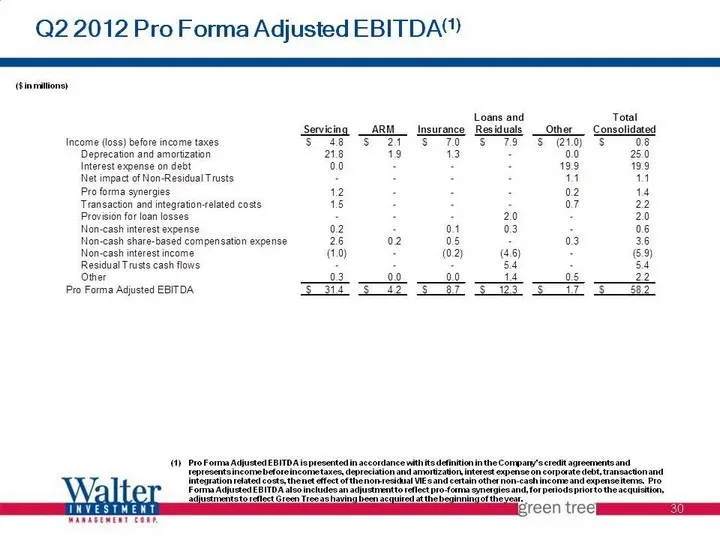
Q2 2012 Pro Forma Adjusted EBITDA(1) 30 Pro Forma Adjusted EBITDA is presented in accordance with its definition in the Company's credit agreements and represents income before income taxes, depreciation and amortization, interest expense on corporate debt, transaction and integration related costs,
Slide 32: Q1 2012 Pro Forma Adjusted EBITDA
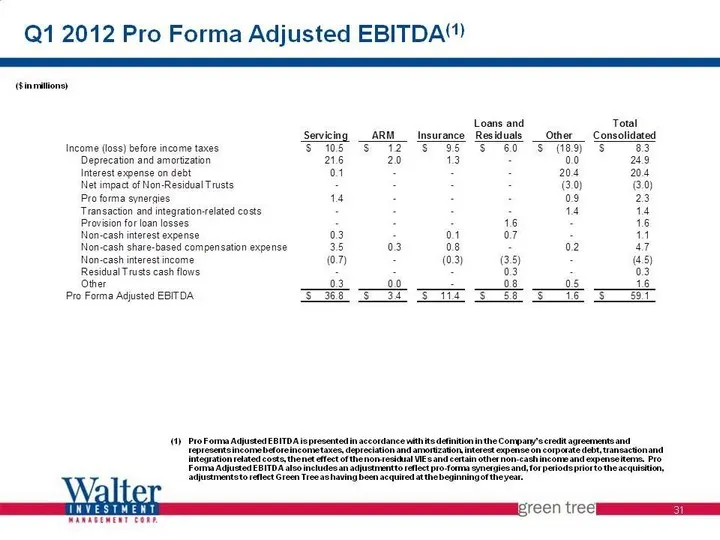
Q1 2012 Pro Forma Adjusted EBITDA(1) 31 Pro Forma Adjusted EBITDA is presented in accordance with its definition in the Company's credit agreements and represents income before income taxes, depreciation and amortization, interest expense on corporate debt, transaction and integration related costs,
Slide 33: Q4 2011 Pro Forma Adjusted EBITDA
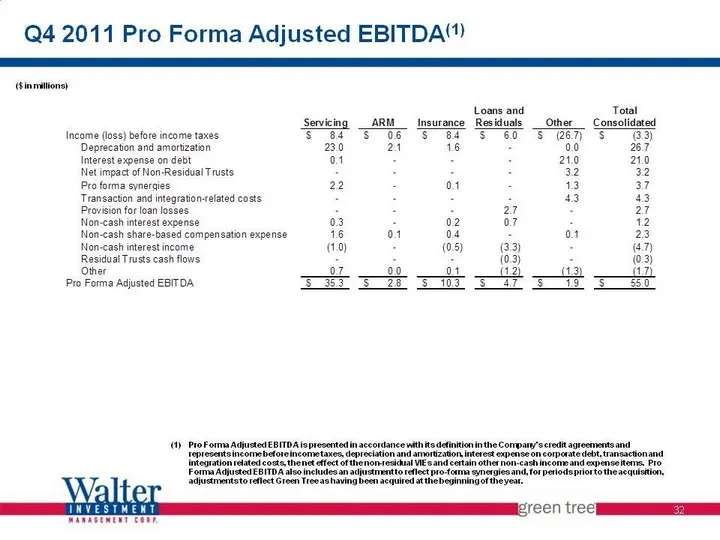
32 Q4 2011 Pro Forma Adjusted EBITDA(1) Pro Forma Adjusted EBITDA is presented in accordance with its definition in the Company's credit agreements and represents income before income taxes, depreciation and amortization, interest expense on corporate debt, transaction and integration related costs,
Slide 34: Q3 2011 Pro Forma Adjusted EBITDA
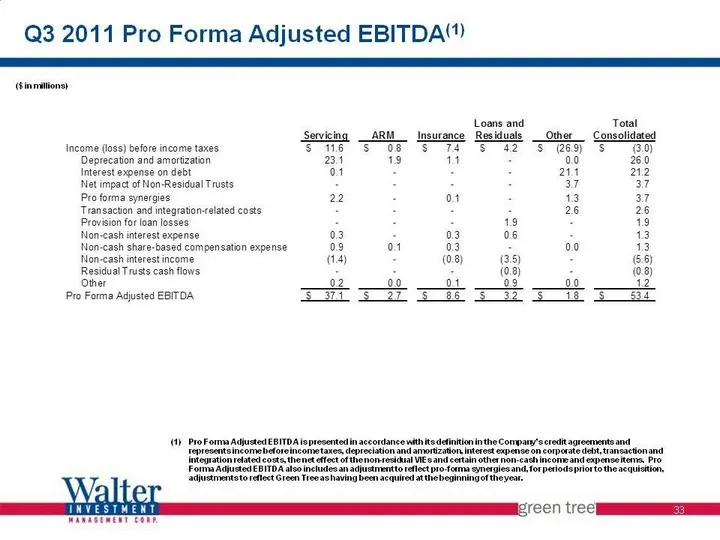
33 Q3 2011 Pro Forma Adjusted EBITDA(1) Pro Forma Adjusted EBITDA is presented in accordance with its definition in the Company's credit agreements and represents income before income taxes, depreciation and amortization, interest expense on corporate debt, transaction and integration related costs,
Slide 35: Regulatory Overview
September 11, 2012 Regulatory Overview Brian F. Corey Senior Vice President, General Counsel
Slide 36: New and Expanding Loan Servicer Regulation
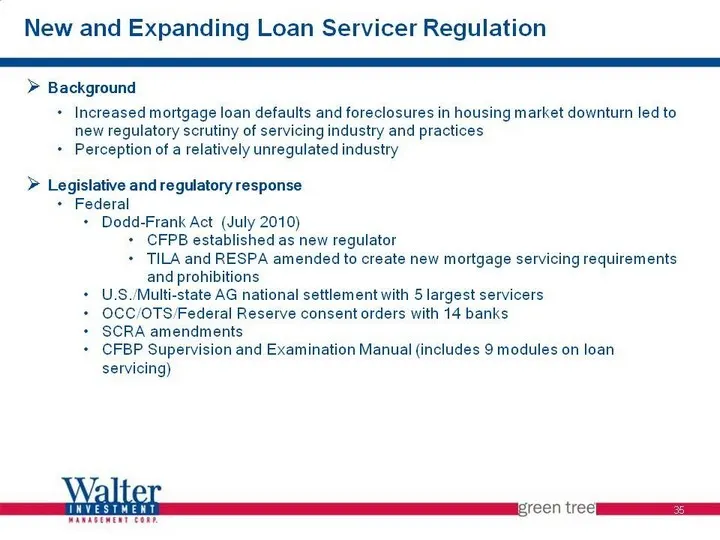
New and Expanding Loan Servicer Regulation 35 Background Increased mortgage loan defaults and foreclosures in housing market downturn led to new regulatory scrutiny of servicing industry and practices Perception of a relatively unregulated industry Legislative and regulatory response Federal Dodd-Fr
Slide 37: New and Expanding Loan Servicer Regulation
New and Expanding Loan Servicer Regulation 36 State and local: Increased regulatory examinations and investigations New licensing requirements for servicers From 2008 forward, a vast array of new and revised loan servicing laws and regulations have been enacted or promulgated, including requirements
Slide 38: Current Regulatory Matters
Current Regulatory Matters 37 37 37
Slide 39: Current Regulatory Matters
Current Regulatory Matters 38 38 38
Slide 40: Current Regulatory Matters CFPB (cont.)
Current Regulatory Matters 39 CFPB (cont.) Error resolution and information requests Information management policies and procedures Early intervention with delinquent borrowers Continuity of contact with delinquent borrowers Loss mitigation procedures Comment period ends on October 9, 2012 Final rul
Slide 41: Law Change Implementation
Law Change Implementation 40 Challenge: Staying abreast of changes In a rapidly evolving regulatory environment, imperative to identify, analyze and implement new legal requirements and restrictions Accomplished by Utilizing well-established and broad ranging information resources for legislative, r
Slide 42: Business Controls & Client Management
September 11, 2012 Business Controls & Client Management Mark A. Atencio SVP, Business Controls & Client Management
Slide 43: Business Controls
2 MANAGEMENT CORP. relationships that work green tree Business Controls
Slide 44: Business Controls Continue to Work
Business Controls Continue to Work 43 Green Tree has the necessary independent controls and processes to mitigate risk. This is monitored through: Legal and Compliance Departments Internal Audit Quality Control Call Monitoring Policy and Procedures These controls and functions exist to mitigate regu
Slide 45: Independent Controls and Monitoring
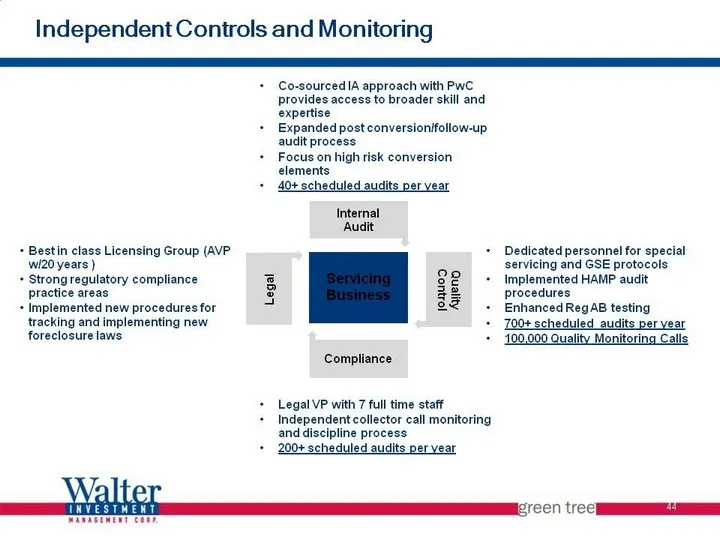
Independent Controls and Monitoring 44 Best in class Licensing Group (AVP w/20 years ) Strong regulatory compliance practice areas Implemented new procedures for tracking and implementing new foreclosure laws Co-sourced IA approach with PwC provides access to broader skill and expertise Expanded pos
Slide 46: Policy and Procedure Controls
Policy and Procedure Controls
Slide 47: Policy and Procedures Change Control
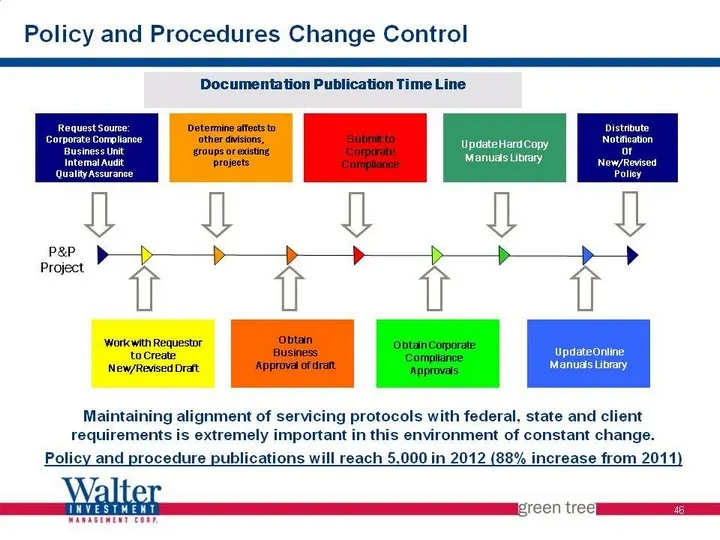
Policy and Procedures Change Control 46 Distribute Notification Of New/Revised Policy Update Online Manuals Library Work with Requestor to Create New/Revised Draft Request Source: Corporate Compliance Business Unit Internal Audit Quality Assurance P&P Project Documentation Publication Time Line Main
Slide 48: Policy and Procedures Change Control (Continued)
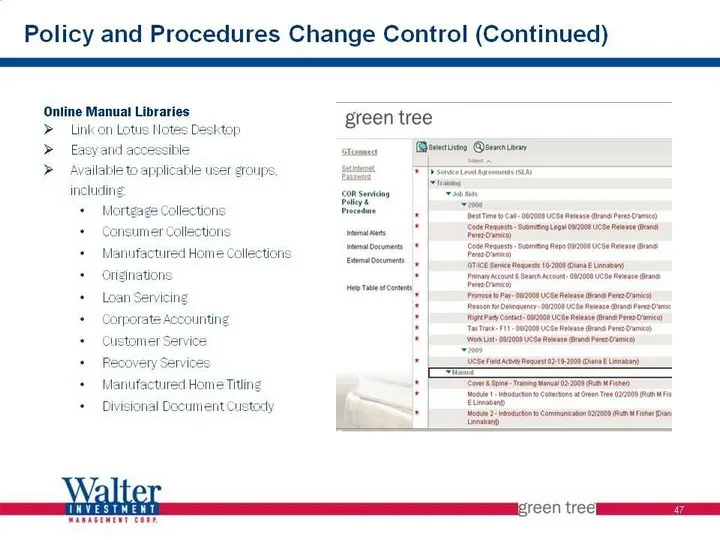
Policy and Procedures Change Control (Continued) 47 Online Manual Libraries Link on Lotus Notes Desktop Easy and accessible Available to applicable user groups, including: Mortgage Collections Consumer Collections Manufactured Home Collections Originations Loan Servicing Corporate Accounting Custome
Slide 49: Client Management
2 MANAGEMENT CORP. relationships that work green tree Client Management
Slide 50: Client Management - Client Single Point of Contact
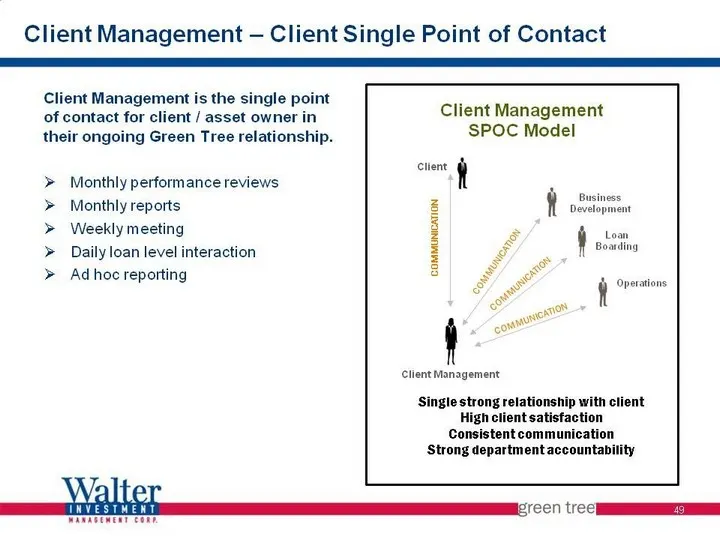
Client Management - Client Single Point of Contact 49 Client Management is the single point of contact for client / asset owner in their ongoing Green Tree relationship. Monthly performance reviews Monthly reports Weekly meeting Daily loan level interaction Ad hoc reporting Client Management SPOC Mo
Slide 51: Client Management Involvement
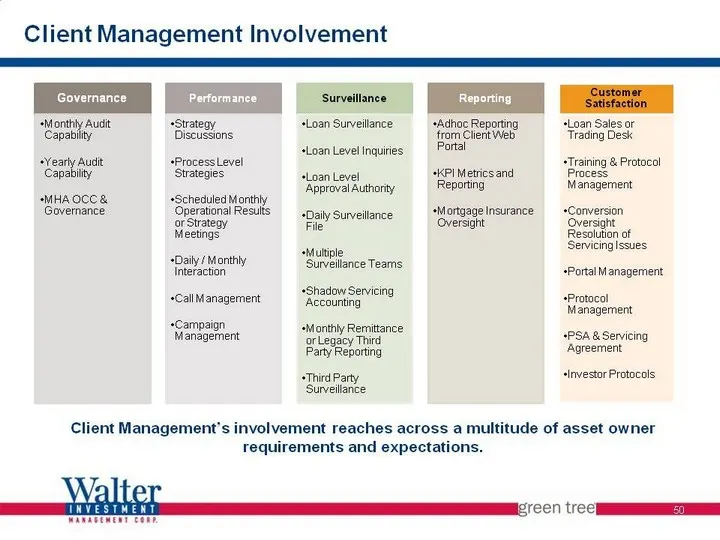
Client Management Involvement 50 Client Management's involvement reaches across a multitude of asset owner requirements and expectations. 50
Slide 52: Sample Monthly Performance Review Agenda
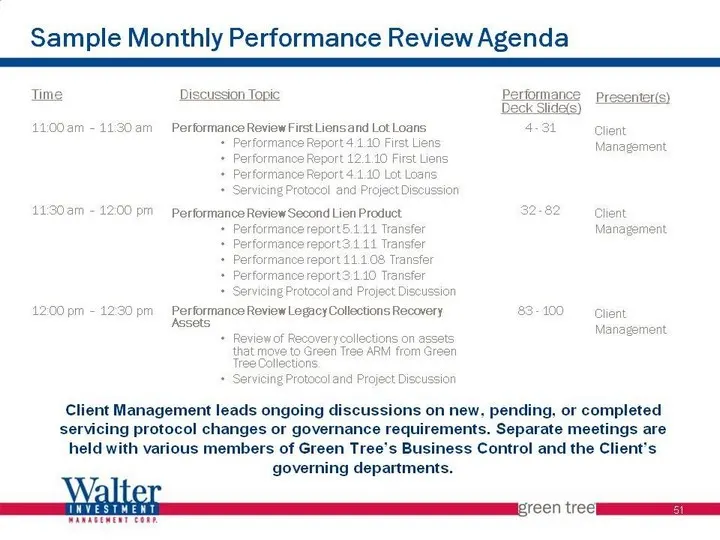
Sample Monthly Performance Review Agenda Time Discussion Topic Performance Deck Slide(s) Presenter(s) 11:00 am - 11:30 am Performance Review First Liens and Lot Loans Performance Report 4.1.10 First Liens Performance Report 12.1.10 First Liens Performance Report 4.1.10 Lot Loans Servicing Protocol a
Slide 53: Servicing Ratings
2 MANAGEMENT CORP. relationships that work green tree Servicing Ratings
Slide 54: Strong Servicer Ratings
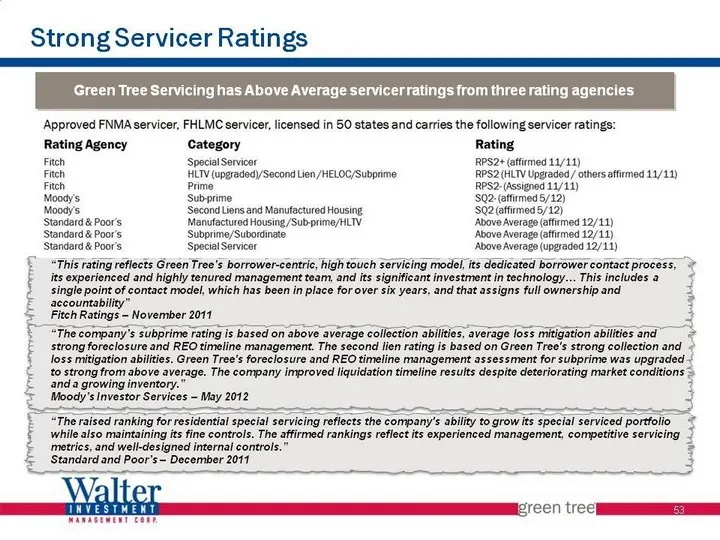
Strong Servicer Ratings Approved FNMA servicer, FHLMC servicer, licensed in 50 states and carries the following servicer ratings: Rating Agency Category Rating Fitch Special Servicer RPS2+ (affirmed 11/11) Fitch HLTV (upgraded)/Second Lien /HELOC/Subprime RPS2 (HLTV Upgraded / others affirmed 11/11)
Slide 55: Servicing Overview
Servicing Overview Thomas J. Franco Executive Vice President, Servicing September 11, 2012
Slide 56: Borrower-Centric Servicing Model
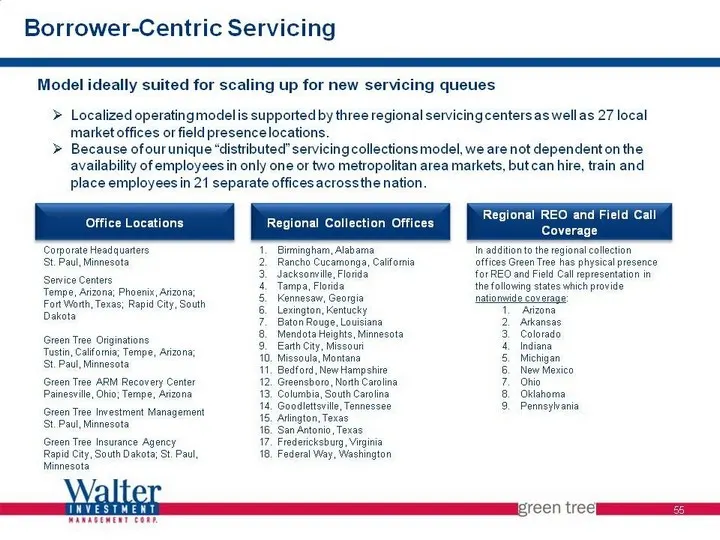
Borrower-Centric Servicing 55 Model ideally suited for scaling up for new servicing queues Localized operating model is supported by three regional servicing centers as well as 27 local market offices or field presence locations. Because of our unique "distributed" servicing collections model, we ar
Slide 57: Customer Service
2 MANAGEMENT CORP. relationships that work green tree Customer Service
Slide 58: Customer Service Overview
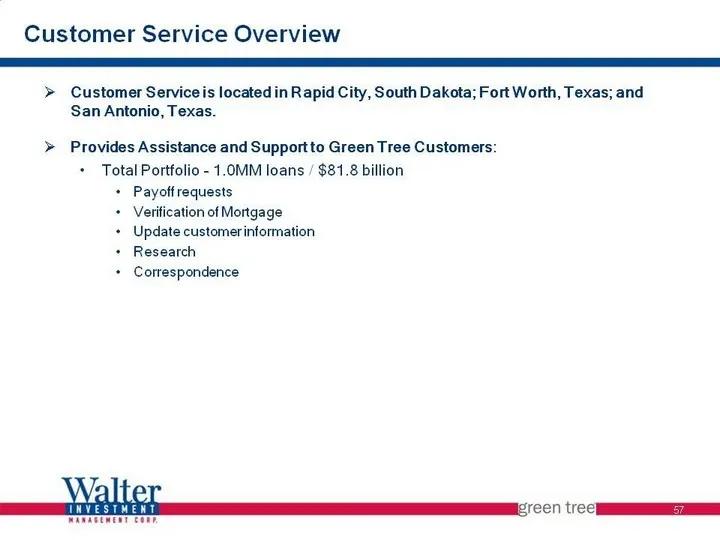
Customer Service Overview Customer Service is located in Rapid City, South Dakota; Fort Worth, Texas; and San Antonio, Texas. Provides Assistance and Support to Green Tree Customers: Total Portfolio - 1.0MM loans / $81.8 billion Payoff requests Verification of Mortgage Update customer information Re
Slide 59: Key Metrics and Productivity
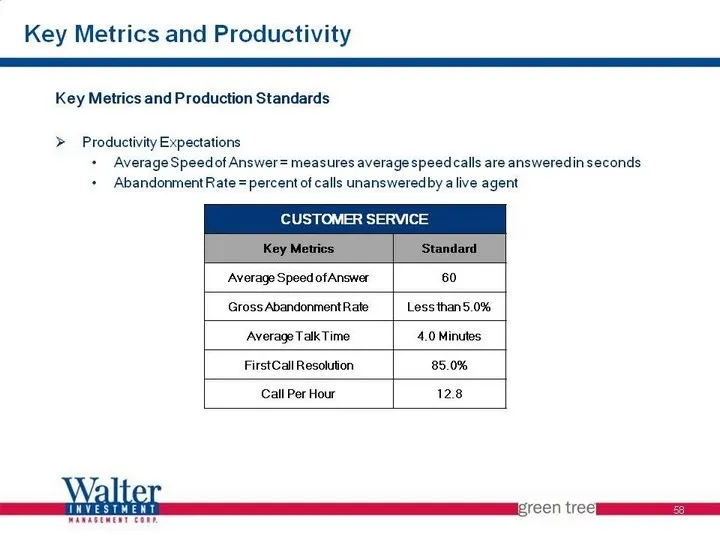
Key Metrics and Productivity 58 Key Metrics and Production Standards Productivity Expectations Average Speed of Answer = measures average speed calls are answered in seconds Abandonment Rate = percent of calls unanswered by a live agent CUSTOMER SERVICE CUSTOMER SERVICE Key Metrics Standard Average
Slide 60: Front End Collections
Front End Collections (1 - 29 days past due)
Slide 61: Modeling Process / Approach
Modeling Process / Approach 60 Green Tree has internal resources dedicated to building statistical models to support Front End collection efforts Key driver for collection efforts are One Cycle Behavior Models Credit scorecards that predict the likelihood of 1-29dpd accounts rolling to 30-59dpd buck
Slide 62: Statistical Benefit to Green Tree Approach
Statistical Benefit to Green Tree Approach 61 Champion/Challenger approach allows for constant improvements to strategies and treatments Varying strategies tested head-to-head, superior strategy becomes Champion and new Challenger developed for further testing Grading accounts based on risk provides
Slide 63: Back End Collections
Back End Collections (30+ days past due)
Slide 64: Single Point of Contact (SPOC) Life-of-Loan
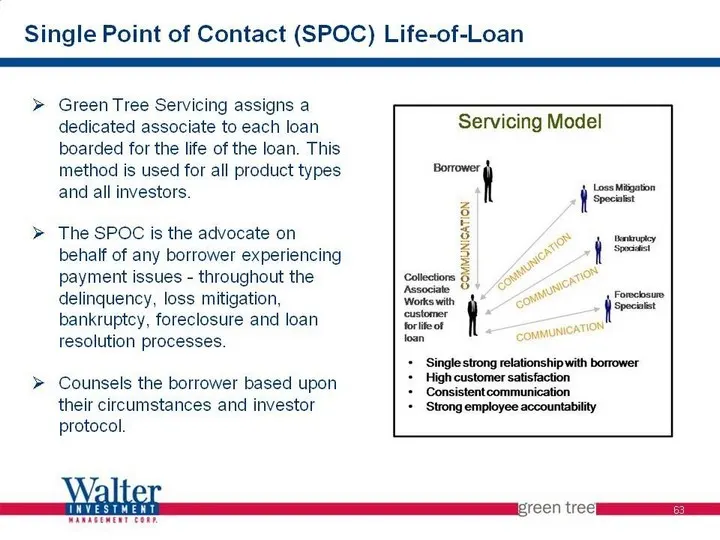
Single Point of Contact (SPOC) Life-of-Loan 63 Green Tree Servicing assigns a dedicated associate to each loan boarded for the life of the loan. This method is used for all product types and all investors. The SPOC is the advocate on behalf of any borrower experiencing payment issues - throughout th
Slide 65: Life-of-Loan Accountability
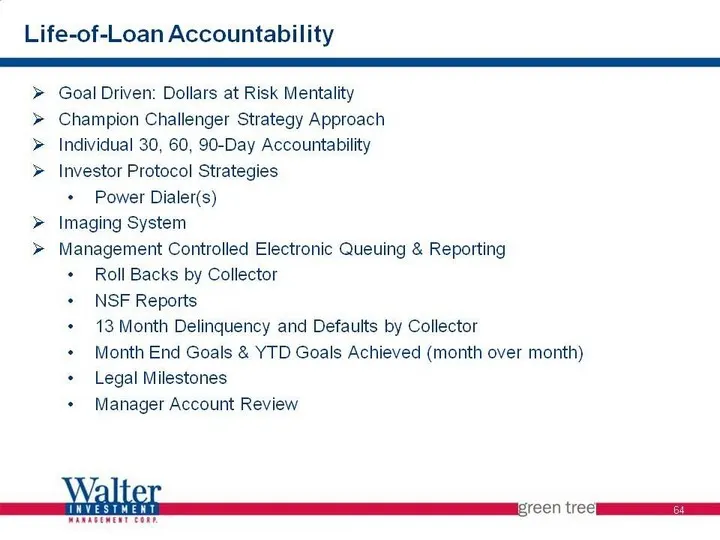
Life-of-Loan Accountability 64 Goal Driven: Dollars at Risk Mentality Champion Challenger Strategy Approach Individual 30, 60, 90-Day Accountability Investor Protocol Strategies Power Dialer(s) Imaging System Management Controlled Electronic Queuing & Reporting Roll Backs by Collector NSF Reports 13
Slide 66: Loss Mitigation
2 MANAGEMENT CORP. relationships that work green tree Loss Mitigation
Slide 67: Strategies to Get Customers Performing
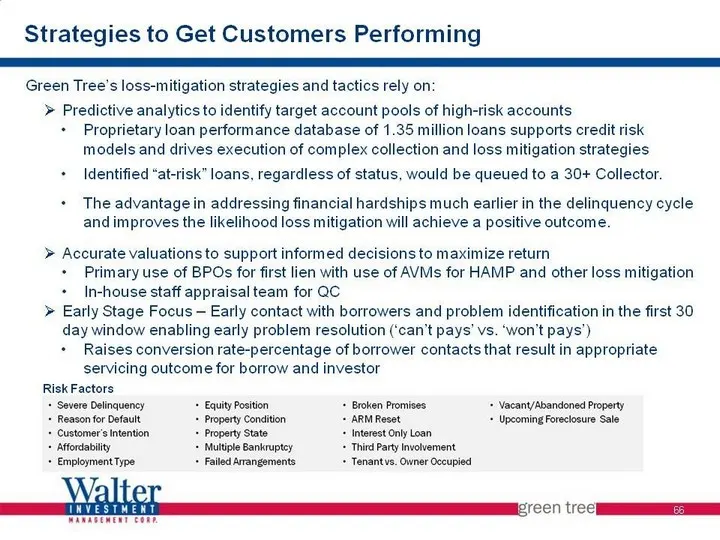
Strategies to Get Customers Performing 66 Green Tree's loss-mitigation strategies and tactics rely on: Predictive analytics to identify target account pools of high-risk accounts Proprietary loan performance database of 1.35 million loans supports credit risk models and drives execution of complex c
Slide 68: Loss Resolution/Loss Mitigation Process
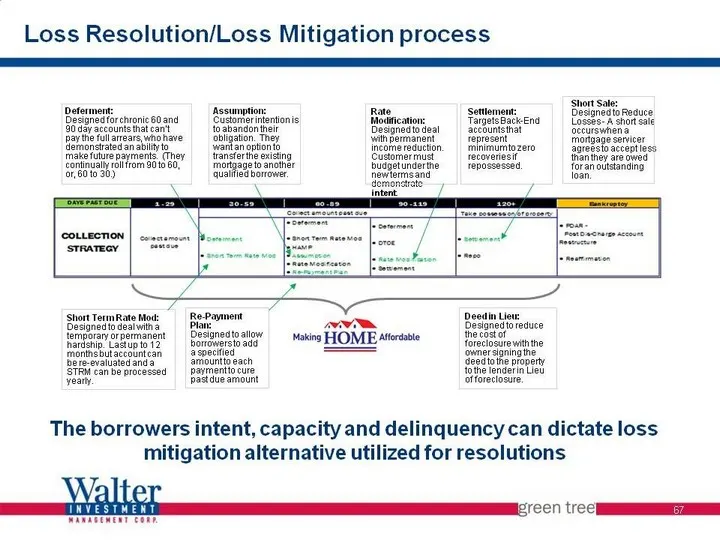
Loss Resolution/Loss Mitigation process 67 Deed in Lieu: Designed to reduce the cost of foreclosure with the owner signing the deed to the property to the lender in Lieu of foreclosure. Short Sale: Designed to Reduce Losses - A short sale occurs when a mortgage servicer agrees to accept less than th
Slide 69: Foreclosure
2 MANAGEMENT CORP. relationships that work green tree Foreclosure
Slide 70: Foreclosure Overview
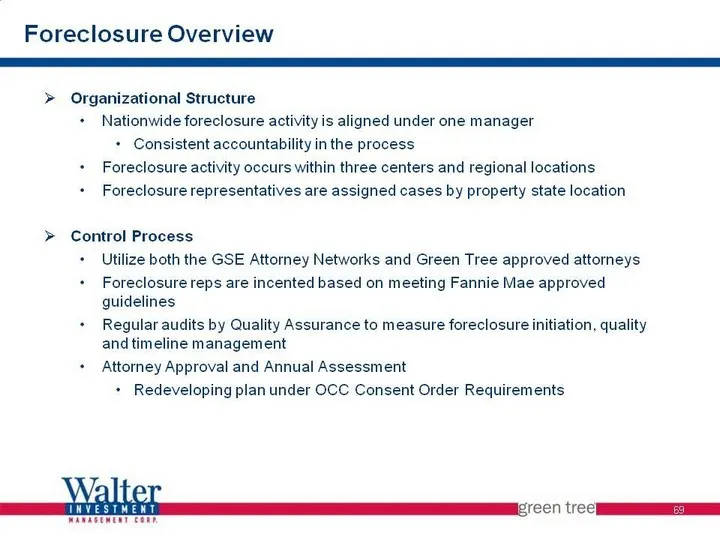
Foreclosure Overview 69 Organizational Structure Nationwide foreclosure activity is aligned under one manager Consistent accountability in the process Foreclosure activity occurs within three centers and regional locations Foreclosure representatives are assigned cases by property state location Con
Slide 71: Bankruptcy Collections
2 MANAGEMENT CORP. relationships that work green tree Bankruptcy Collections
Slide 72: Bankruptcy Strategies
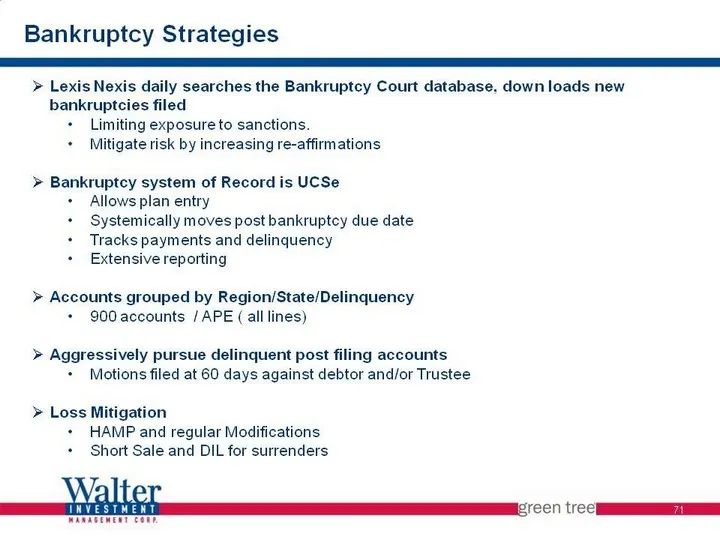
Bankruptcy Strategies 71 Lexis Nexis daily searches the Bankruptcy Court database, down loads new bankruptcies filed Limiting exposure to sanctions. Mitigate risk by increasing re-affirmations Bankruptcy system of Record is UCSe Allows plan entry Systemically moves post bankruptcy due date Tracks pa
Slide 73: REO
2 MANAGEMENT CORP. relationships that work green tree REO
Slide 74: Life Cycle of REO
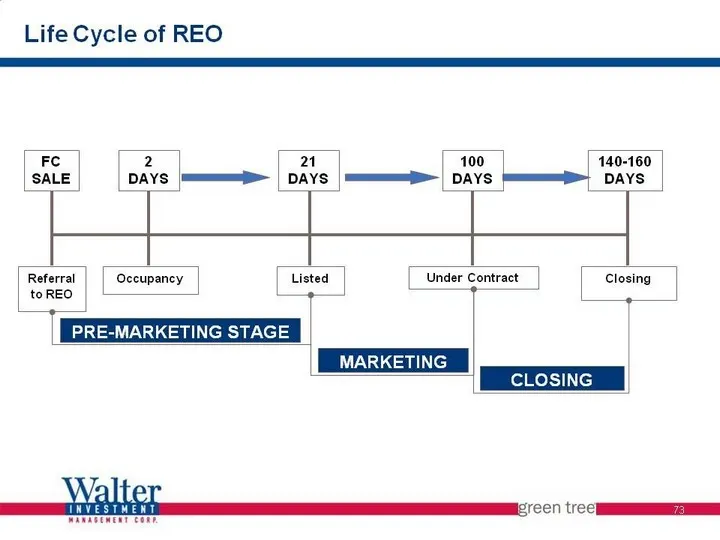
Life Cycle of REO 73 FC SALE 2 DAYS 21 DAYS 100 DAYS 140-160 DAYS Referral to REO Occupancy Listed Under Contract Closing PRE-MARKETING STAGE MARKETING STAGE CLOSING STAGE 73
Slide 75: Asset Receivables Management
Asset Receivables Management Thomas J. Franco Executive Vice President, Servicing September 11, 2012
Slide 76: GT ARM Overview
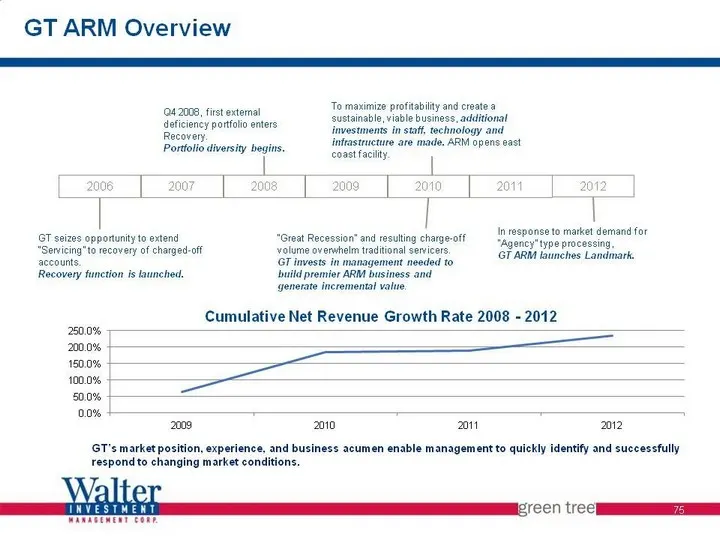
GT ARM Overview 75 2006 GT seizes opportunity to extend "Servicing" to recovery of charged-off accounts. Recovery function is launched. 2007 2008 2009 2010 2011 2012 "Great Recession" and resulting charge-off volume overwhelm traditional servicers. GT invests in management needed to build premier AR
Slide 77: GT ARM Overview (continued)
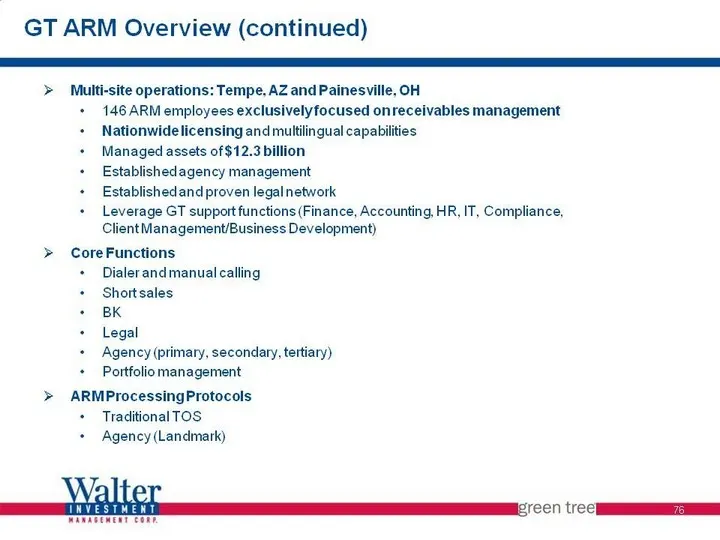
GT ARM Overview (continued) 76 Multi-site operations: Tempe, AZ and Painesville, OH 146 ARM employees exclusively focused on receivables management Nationwide licensing and multilingual capabilities Managed assets of $12.3 billion Established agency management Established and proven legal network Le
Slide 78: GT ARM Portfolio Composition
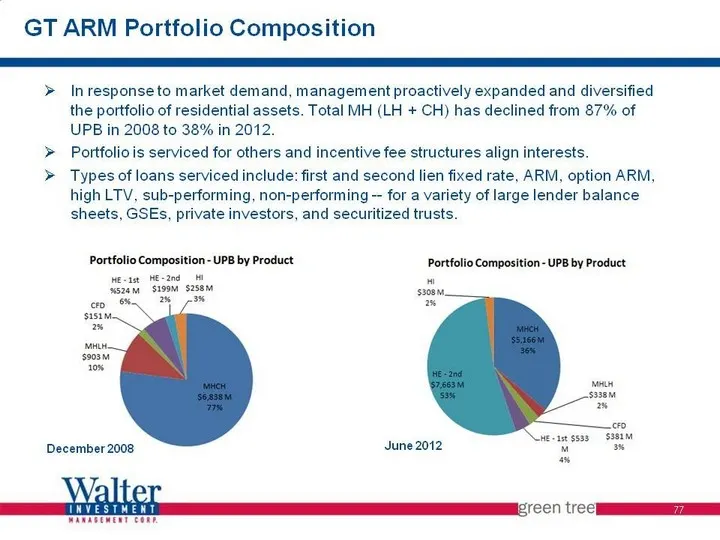
GT ARM Portfolio Composition 77 In response to market demand, management proactively expanded and diversified the portfolio of residential assets. Total MH (LH + CH) has declined from 87% of UPB in 2008 to 38% in 2012. Portfolio is serviced for others and incentive fee structures align interests. Ty
Slide 79: Value Proposition
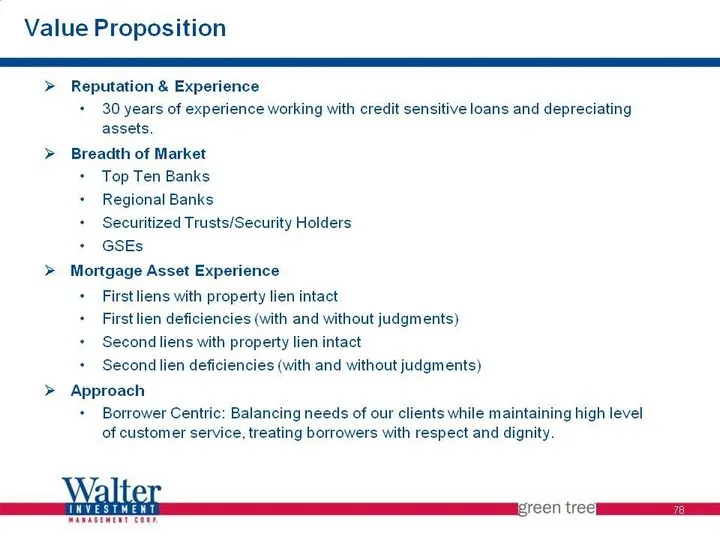
Value Proposition 78 Reputation & Experience 30 years of experience working with credit sensitive loans and depreciating assets. Breadth of Market Top Ten Banks Regional Banks Securitized Trusts/Security Holders GSEs Mortgage Asset Experience First liens with property lien intact First lien deficien
Slide 80: Value Proposition (continued)
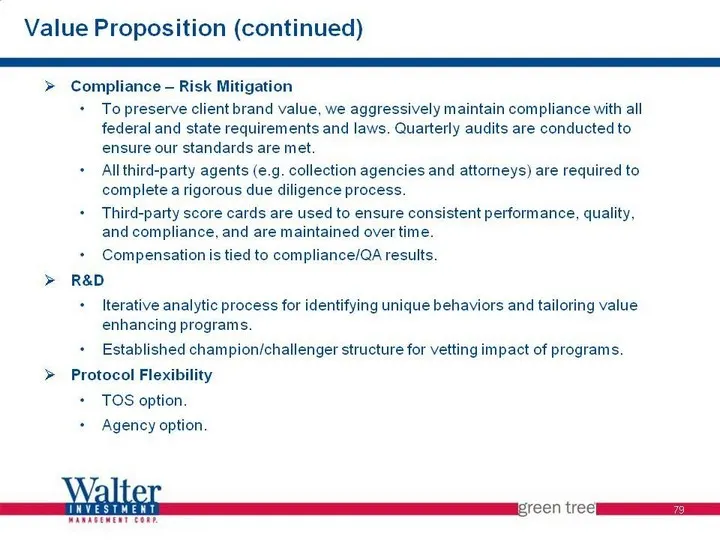
Value Proposition (continued) 79 Compliance - Risk Mitigation To preserve client brand value, we aggressively maintain compliance with all federal and state requirements and laws. Quarterly audits are conducted to ensure our standards are met. All third-party agents (e.g. collection agencies and att
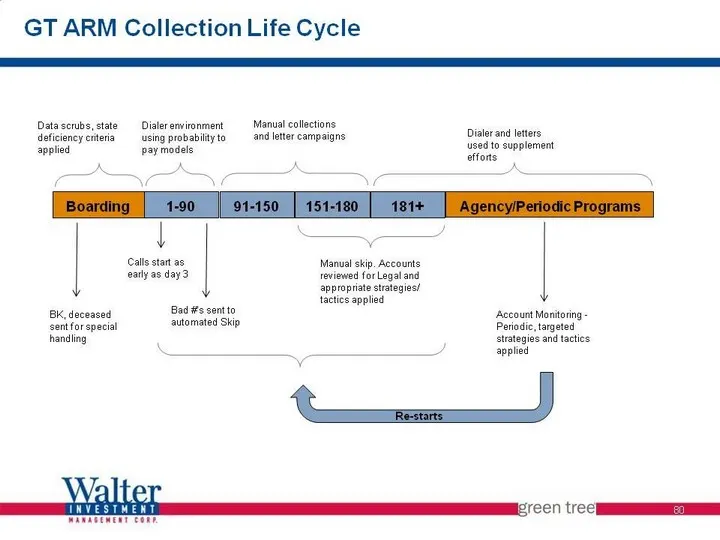
Slide 81: GT ARM Collection Life Cycle Re-starts
GT ARM Collection Life Cycle 80 Re-starts 80
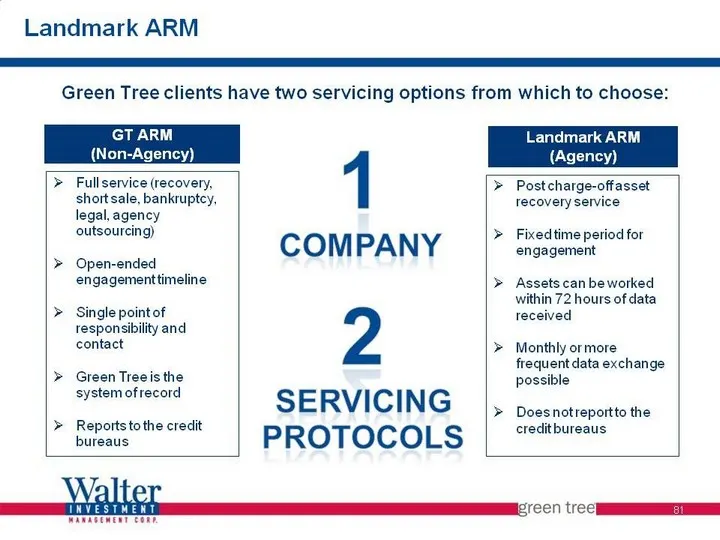
Slide 82: Landmark ARM
Landmark ARM 81 Green Tree clients have two servicing options from which to choose: Full service (recovery, short sale, bankruptcy, legal, agency outsourcing) Open-ended engagement timeline Single point of responsibility and contact Green Tree is the system of record Reports to the credit bureaus GT
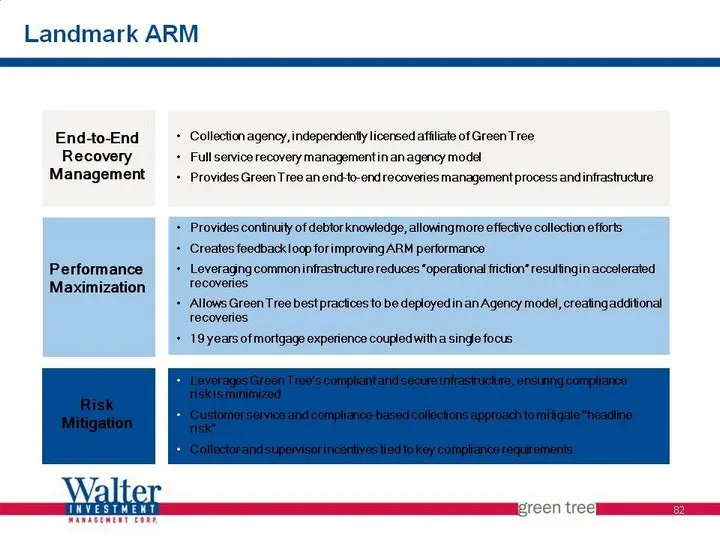
Slide 83: Provides continuity of debtor knowledge, allowing more effective collection efforts Creates feedback loop for
82 Provides continuity of debtor knowledge, allowing more effective collection efforts Creates feedback loop for improving ARM performance Leveraging common infrastructure reduces "operational friction" resulting in accelerated recoveries Allows Green Tree best practices to be deployed in an Agency
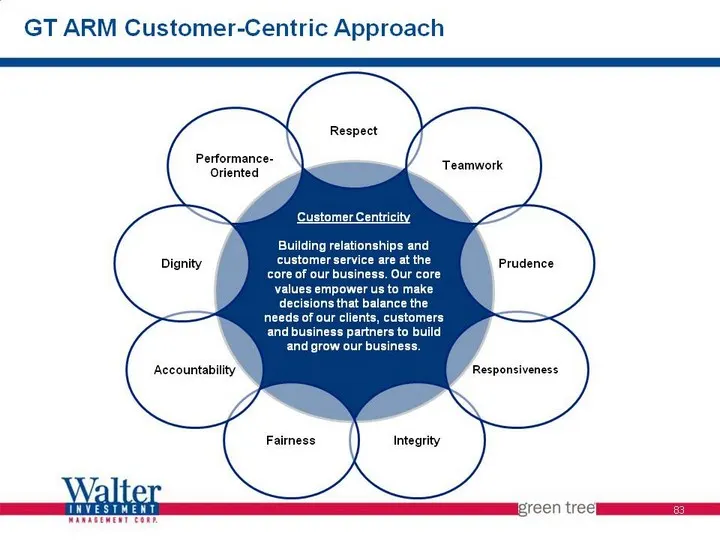
Slide 84: GT ARM Customer-Centric Approach
GT ARM Customer-Centric Approach 83 Customer Centricity Building relationships and customer service are at the core of our business. Our core values empower us to make decisions that balance the needs of our clients, customers and business partners to build and grow our business. Respect Performance
Slide 85: Business Development
Business Development Patricia L. Cook EVP, Business Development September 11, 2012
Slide 86: The US Mortgage Market is tremendous
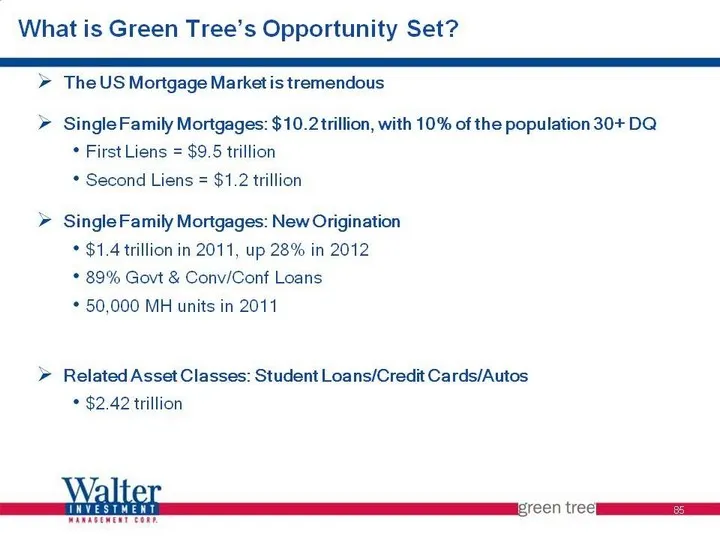
The US Mortgage Market is tremendous Single Family Mortgages: $10.2 trillion, with 10% of the population 30+ DQ First Liens = $9.5 trillion Second Liens = $1.2 trillion Single Family Mortgages: New Origination $1.4 trillion in 2011, up 28% in 2012 89% Govt & Conv/Conf Loans 50,000 MH units in 2011 R
Slide 87: Who are Green Tree's potential clients?
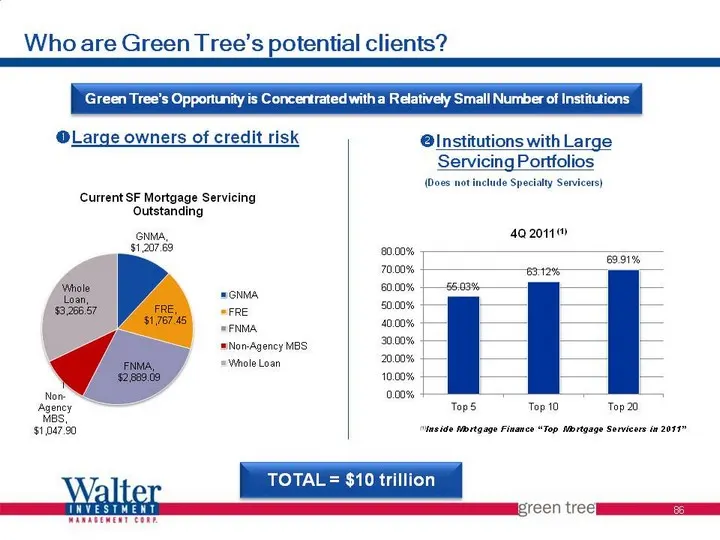
?Large owners of credit risk (Does not include Specialty Servicers) TOTAL = $10 trillion Who are Green Tree's potential clients? ?Institutions with Large Servicing Portfolios 4Q 2011 (1) (1)Inside Mortgage Finance "Top Mortgage Servicers in 2011" 86 Green Tree's Opportunity is Concentrated with a Re
Slide 88: Why are institutions moving / selling servicing?
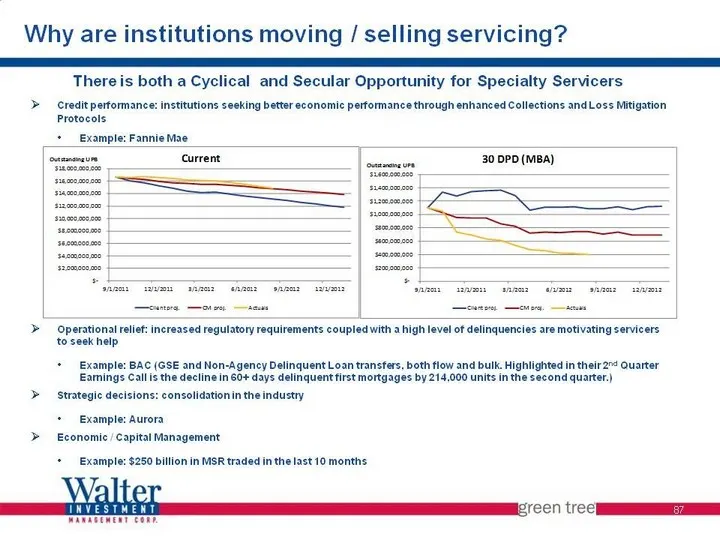
Why are institutions moving / selling servicing? 87 There is both a Cyclical and Secular Opportunity for Specialty Servicers Credit performance: institutions seeking better economic performance through enhanced Collections and Loss Mitigation Protocols Example: Fannie Mae Operational relief: increas
Slide 89: How is servicing transferred?
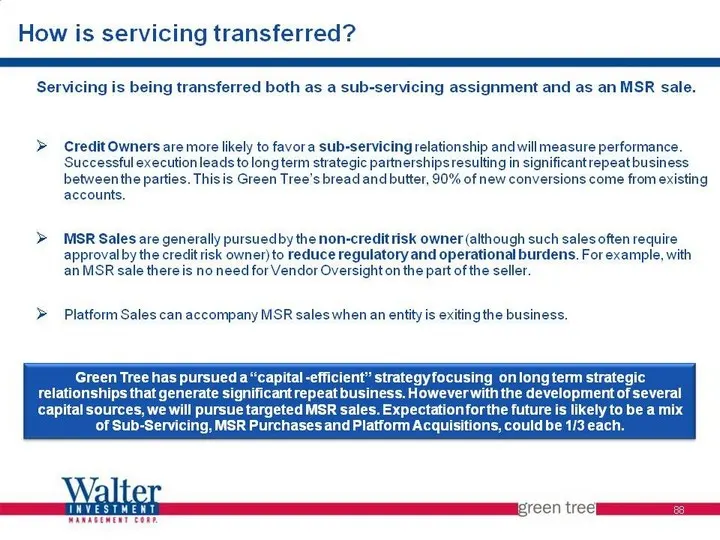
How is servicing transferred? Servicing is being transferred both as a sub-servicing assignment and as an MSR sale. Credit Owners are more likely to favor a sub-servicing relationship and will measure performance. Successful execution leads to long term strategic partnerships resulting in significan
Slide 90: Transaction Timeline is Long and Unpredictable
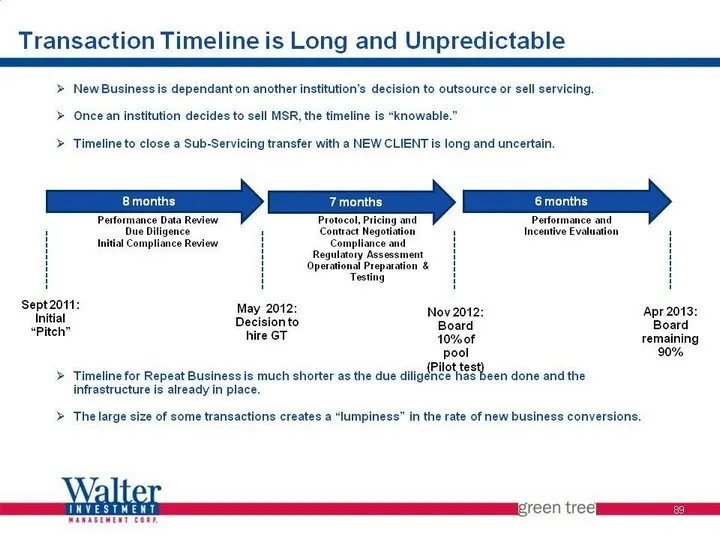
Transaction Timeline is Long and Unpredictable 89 New Business is dependant on another institution's decision to outsource or sell servicing. Once an institution decides to sell MSR, the timeline is "knowable." Timeline to close a Sub-Servicing transfer with a NEW CLIENT is long and uncertain. Timel
Slide 91: Green Tree's Clients and Prospects
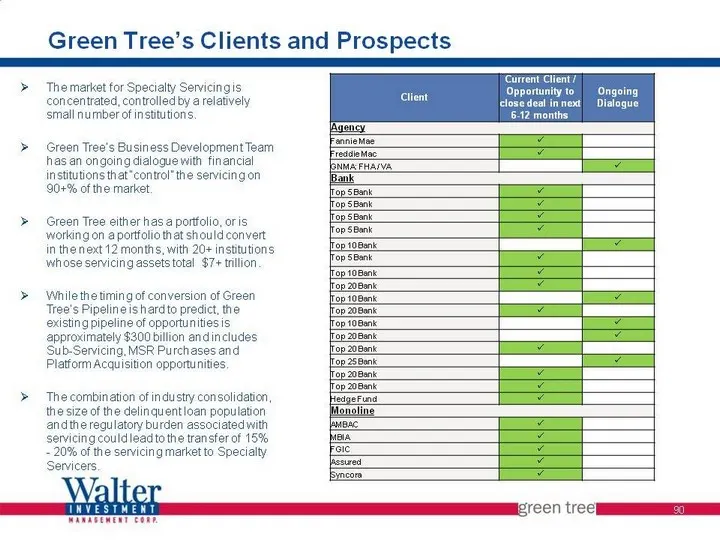
Client Current Client / Opportunity to close deal in next 6-12 months Ongoing Dialogue Agency Agency Agency Fannie Mae ? Freddie Mac ? GNMA: FHA / VA ? Bank Bank Bank Top 5 Bank ? Top 5 Bank ? Top 5 Bank ? Top 5 Bank ? Top 10 Bank ? Top 5 Bank ? Top 10 Bank ? Top 20 Bank ? Top 10 Bank ? Top 20 Bank
Slide 92: Conclusion
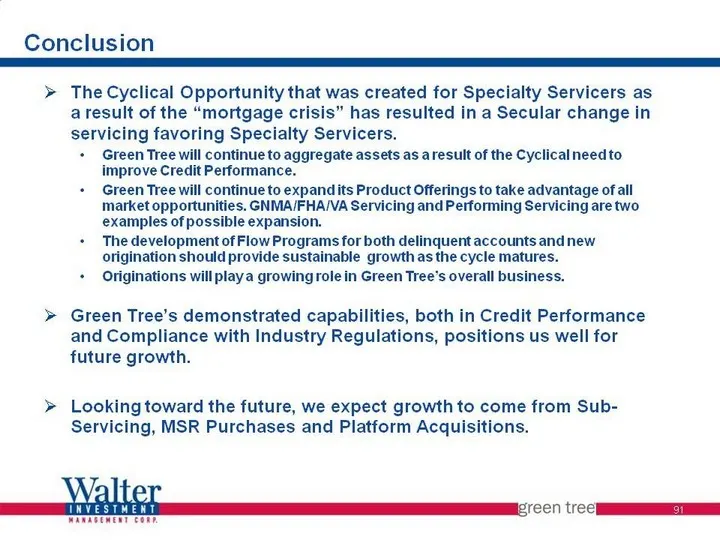
Conclusion 91 The Cyclical Opportunity that was created for Specialty Servicers as a result of the "mortgage crisis" has resulted in a Secular change in servicing favoring Specialty Servicers. Green Tree will continue to aggregate assets as a result of the Cyclical need to improve Credit Performance
Slide 93: Reverse Mortgage Solutions, Inc.
September 11, 2012 92 Reverse Mortgage Solutions, Inc. H. Marc Helm President and Chief Executive Officer
Slide 94: Reverse Mortgage Industry
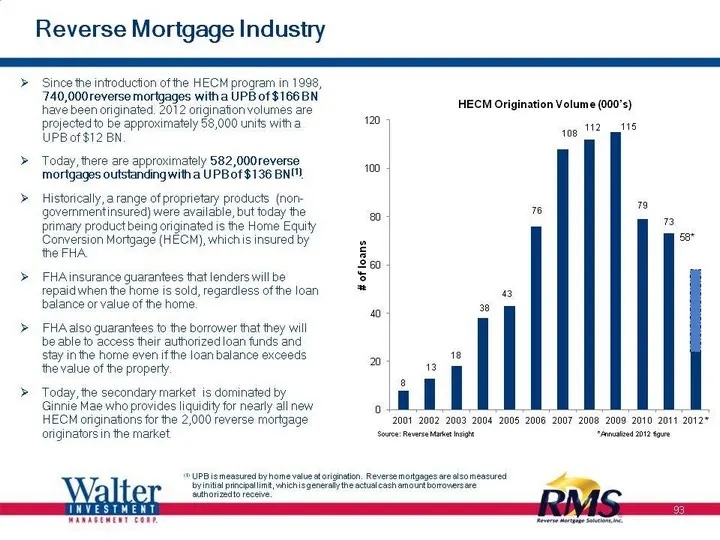
Reverse Mortgage Industry Reverse Mortgage Industry Since the introduction of the HECM program in 1998, 740,000 reverse mortgages with a UPB of $166 BN have been originated. 2012 origination volumes are projected to be approximately 58,000 units with a UPB of $12 BN. Today, there are approximately 5
Slide 95: Company Overview
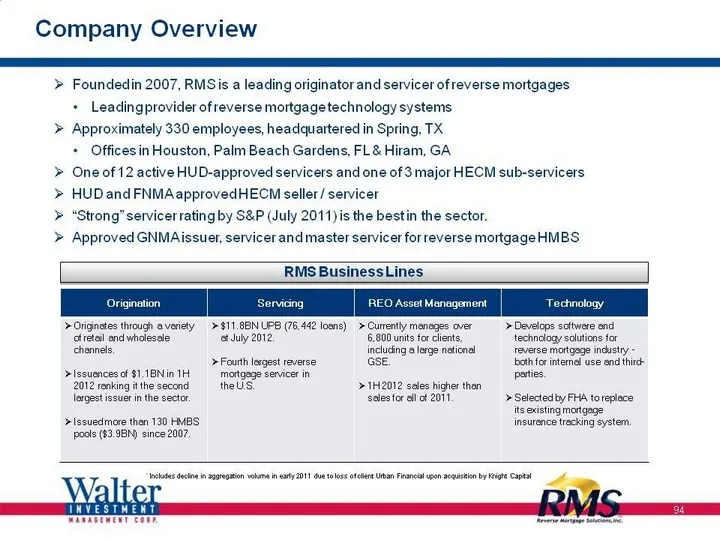
Company Overview Founded in 2007, RMS is a leading originator and servicer of reverse mortgages Leading provider of reverse mortgage technology systems Approximately 330 employees, headquartered in Spring, TX Offices in Houston, Palm Beach Gardens, FL & Hiram, GA One of 12 active HUD-approved servic
Slide 96: Competitive Advantages
Competitive Advantages 95 Proven Management Team & Staff Reverse Mortgage - servicing and sub-servicing Forward Mortgage - servicing and sub-servicing Employee Experience Executive Management - average years in mortgage related fields - 29 years Operations Management - average years in mortgage rela
Slide 97: Diversified Business Model
Diversified Business Model Multiple Business Lines and Income Streams Reverse Mortgage - servicing, sub-servicing & originations Aggregation/Ginnie Mae securitizations REO Management / REO Leasing System Applications RM-Navigator(r) RMCompass(r) REO Central STORM? RMS's diversification minimizes the
Slide 98: Loan Origination Overview
Loan Origination Overview The company aggregates pools of reverse mortgages and issues GNMA HMBS securities. RMS earns a spread on the securitization, keeping either the full amount for retail originated loans or a fixed spread (90 - 225 bps) on the wholesale channels. RMS originates loans through i
Slide 99: Servicing Overview
Servicing Overview RMS's servicing portfolio consists of the master servicing rights for FNMA and GNMA collateral as well as a $5.0 BN sub-servicing portfolio for 20 different clients. The company's proprietary servicing platform was developed and is managed in-house, providing scalability and custo
Slide 100: REO Management Overview
REO Management Overview In March 2011, RMS entered into a contract to manage and liquidate a GSE's REO related to its reverse mortgage portfolio. This nationwide project resulted in a substantial reduction in losses incurred for their reverse mortgage REO. Additionally, the company has been enlisted
Slide 101: Technology Overview
Technology Overview In 2010, RMS was selected by FHA to develop a system that will replace the existing FHA Mortgage insurance collection and tracking system (IACS), known internally as the STORM project. The contract with FHA is for five years and consists of development and maintenance fees. The c
Slide 102: Appendix
2 MANAGEMENT CORP. Appendix
Slide 103: Reverse Mortgage Product
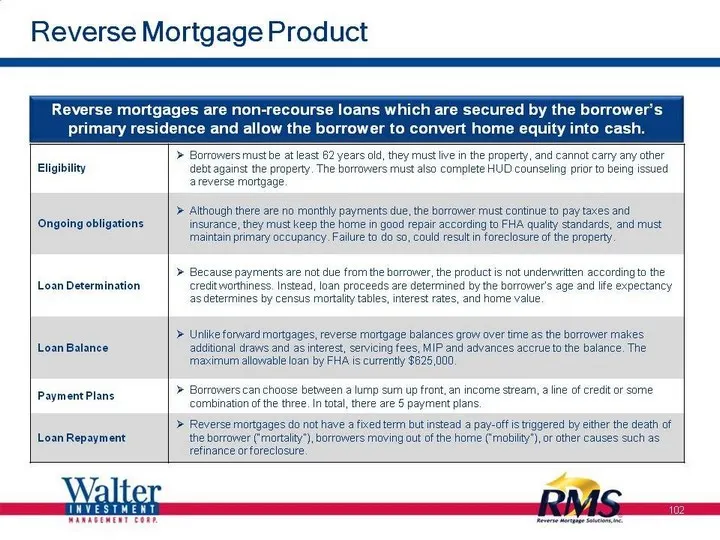
Reverse Mortgage Product Reverse mortgages are non-recourse loans which are secured by the borrower's primary residence and allow the borrower to convert home equity into cash. Eligibility Borrowers must be at least 62 years old, they must live in the property, and cannot carry any other debt agains
Slide 104: Competitive Landscape
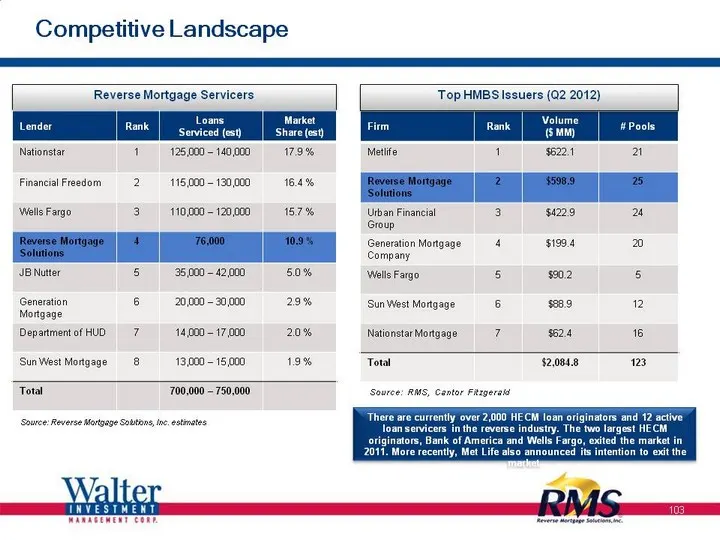
Competitive Landscape Reverse Mortgage Servicers Lender Rank Loans Serviced (est) Market Share (est) Nationstar 1 125,000 - 140,000 17.9 % Financial Freedom 2 115,000 - 130,000 16.4 % Wells Fargo 3 110,000 - 120,000 15.7 % Reverse Mortgage Solutions 4 76,000 10.9 % JB Nutter 5 35,000 - 42,000 5.0 %
Slide 105: Closing Comments
Closing Comments Mark J. O'Brien Chairman and Chief Executive Officer September 11, 2012
Source: SEC EDGAR · 8-K filed Sep 11, 2012
More decks from Ditech Holding Corporation
 Presentation (December 2018)27 slides · Dec 14, 2018
 Q2 2018 Earnings Presentation21 slides · Aug 9, 2018
 Q1 2018 Earnings Presentation27 slides · Jun 6, 2018
 Walter Investment Management — Debt Investor Presentation (October 2017)15 slides · Oct 23, 2017
 Walter Investment Management — Debt Investor Presentation (August 2017)35 slides · Aug 1, 2017
 Walter Investment Management — Debt Investor Presentation (August 2017)5 slides · Aug 1, 2017