Texas Industries — Stephens Inc. Fall Investment Conference 2008
37 slides from Texas Industries's conference presentation, Nov 19, 2008
Slide 1: Stephens Inc. Fall Investment Conference 2008
COMPANY COLORS Blue: R = 0 G = 0 B = 255 Beige: R = 251 G = 248 B = 216 STEPHENS INC. FALL INVESTMENT CONFERENCE 2008 November 19, 2008 New York City 1
Slide 2: Forward-Looking Statement
FORWARD-LOOKING STATEMENT Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are subject to risks, uncertainties and other factors, which could cause actual results to differ m
Slide 3: A Building Materials Company
A BUILDING MATERIALS COMPANY Cement, Aggregate and Concrete Used in all types of construction Cement accounts for approximately 75% of earnings 3
Slide 4: Cement Capacity Expansion Projects
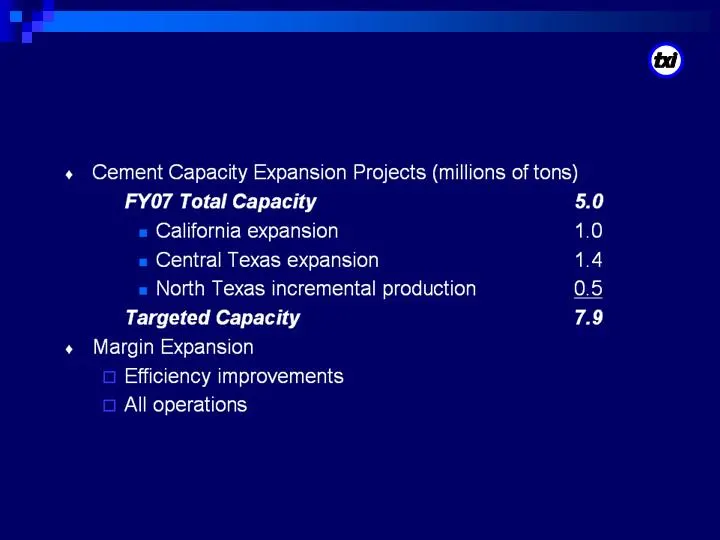
2 ¢ Cement Capacity Expansion Projects (millions of tons) FY07 Total Capacity 5.0 « California expansion 1.0 = Central Texas expansion 1.4 » North Texas incremental production 0.5 Targeted Capacity 7.9 + Margin Expansion 0 Efficiency improvements 2 All operations
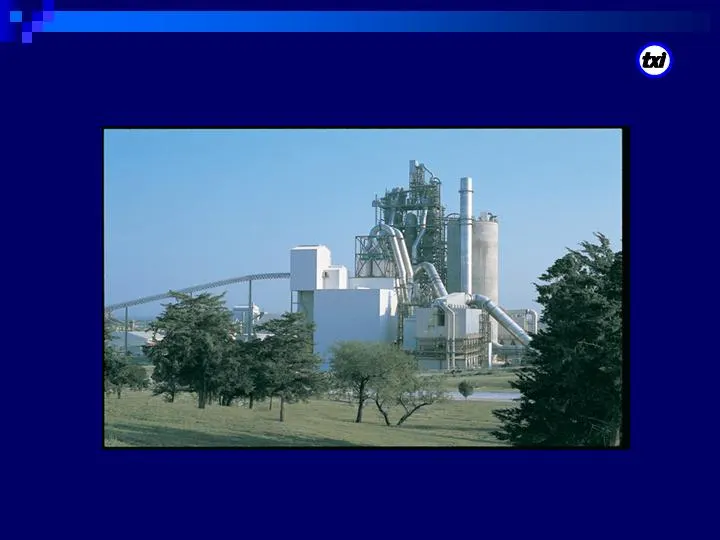
Slide 5: Cement Plant
CEMENT PLANT 5
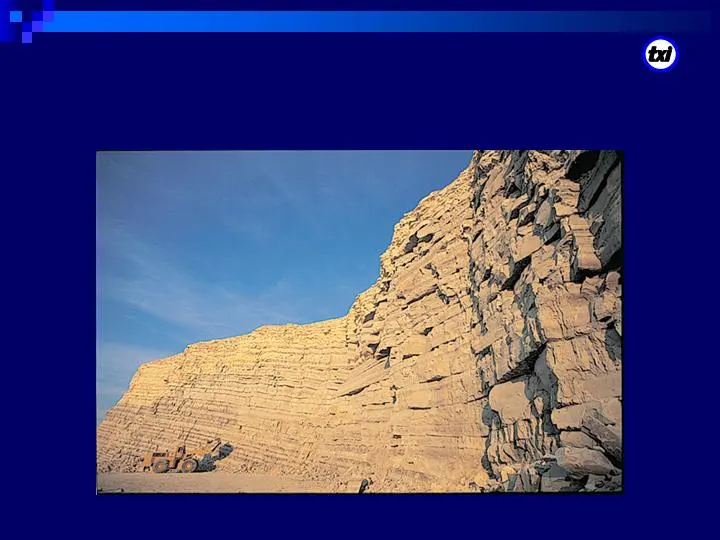
Slide 6: Quarry
QUARRY 6
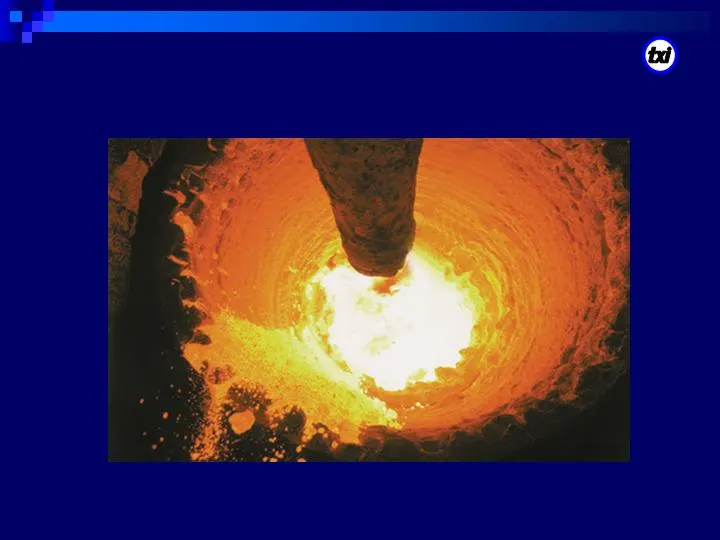
Slide 7: Cement Plant Kiln
CEMENT PLANT KILN 7
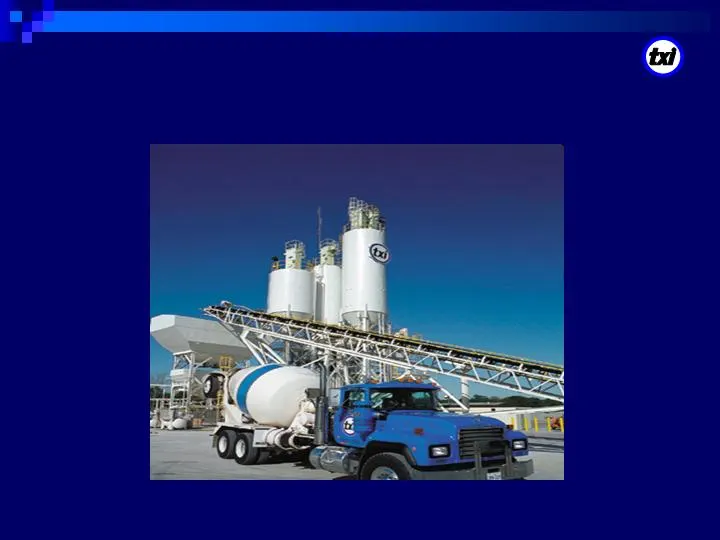
Slide 8: Ready-Mix Concrete
READY-MIX CONCRETE 8
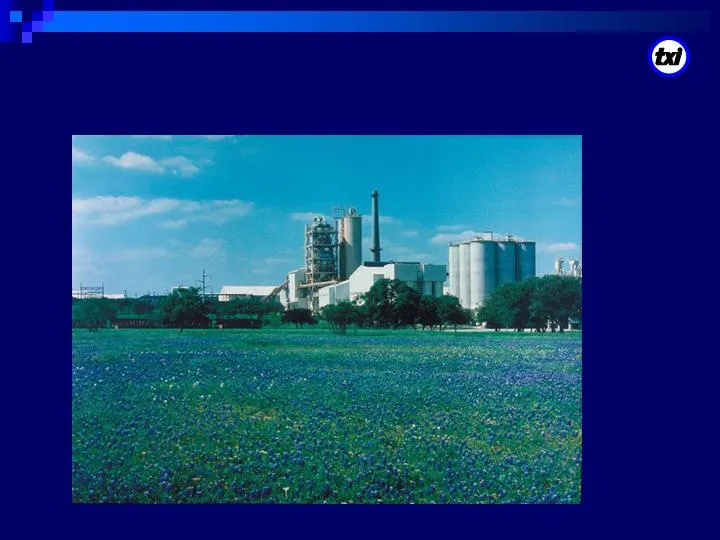
Slide 9: Central Texas Cement Plant
CENTRAL TEXAS CEMENT PLANT 9
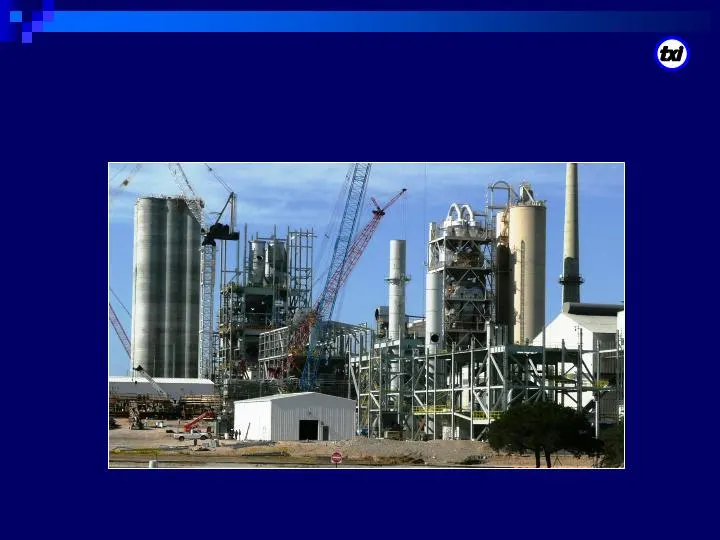
Slide 10: Construction for Central Texas Cement Plant Expansion
CONSTRUCTION FOR CENTRAL TEXAS CEMENT PLANT EXPANSION 10
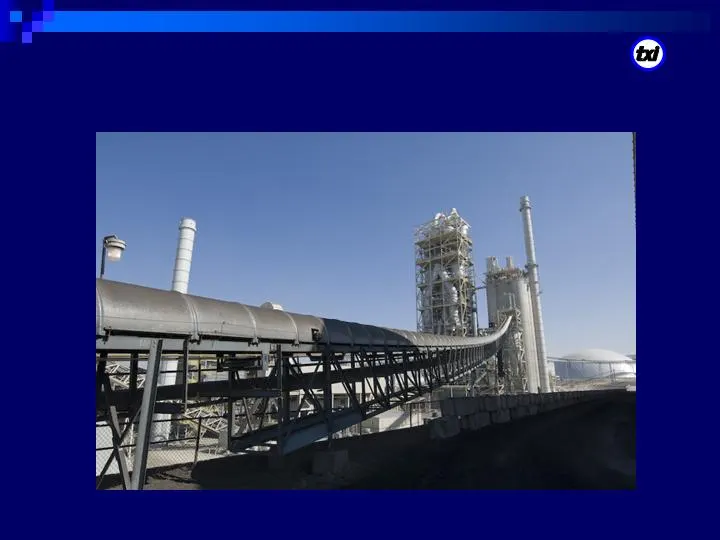
Slide 11: New California Cement Plant
NEW CALIFORNIA CEMENT PLANT 11
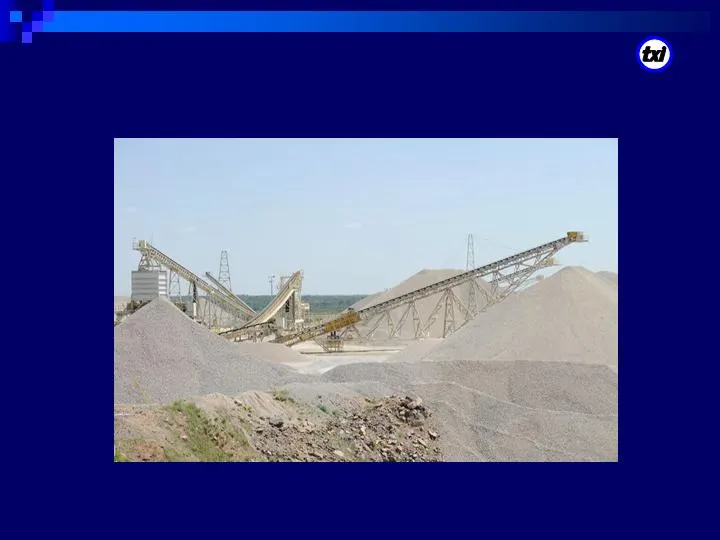
Slide 12: Stone Plant in Oklahoma
STONE PLANT IN OKLAHOMA 12
Slide 13: Drivers of Cement Demand
DRIVERS OF CEMENT DEMAND 13
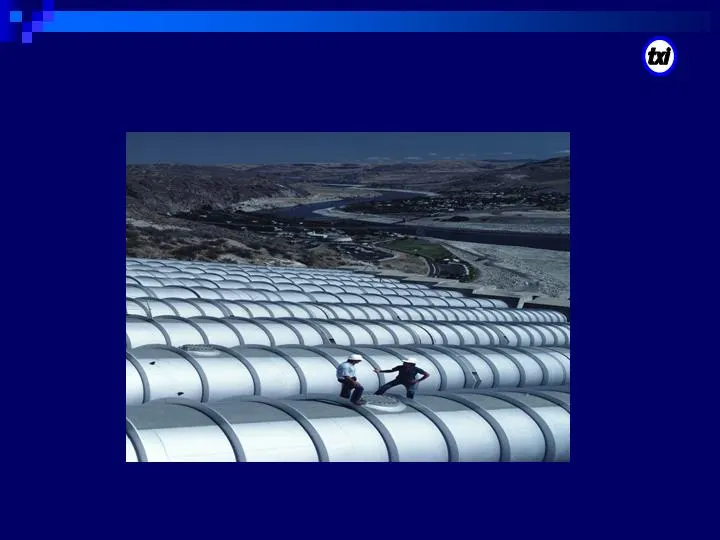
Slide 14: Public Works – 50%
PUBLIC WORKS – 50% 14
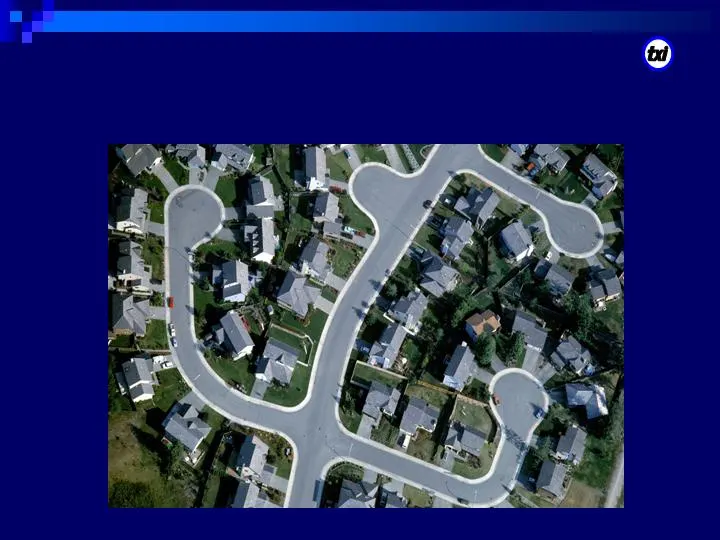
Slide 15: Residential – 25%
RESIDENTIAL – 25% 15
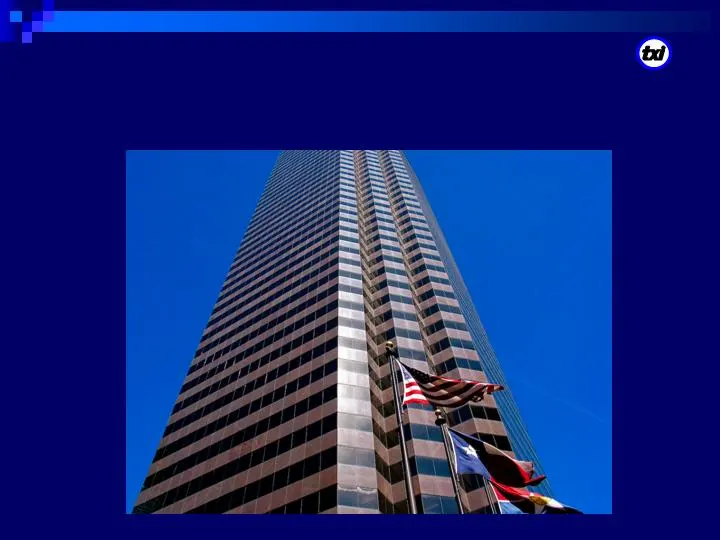
Slide 16: Non-Residential – 25%
NON-RESIDENTIAL – 25% 16
Slide 17: Favorable U.S. Cement Industry Structure
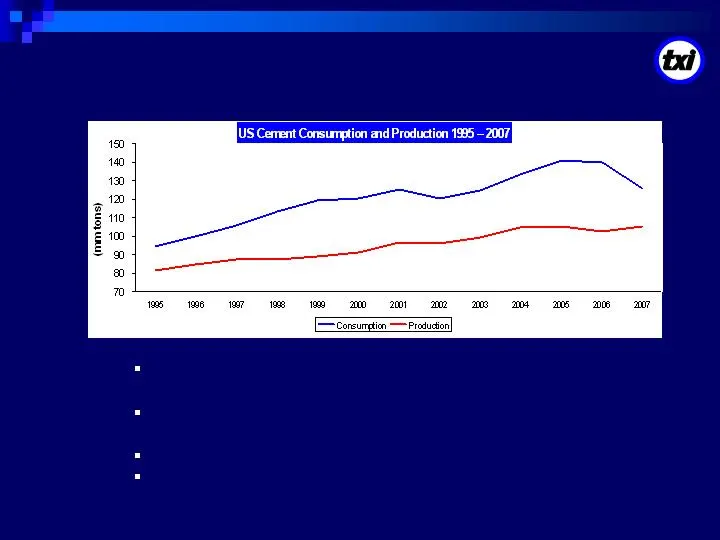
FAVORABLE U.S. CEMENT INDUSTRY STRUCTURE U. S. cement consumption has historically exceeded domestic production capacity U. S. cement capacity and import terminals largely owned or controlled by international producers Significant barriers to entry exist for new cement capacity Regional business due
Slide 18: Attractive Long-Term Markets: Texas and California
ATTRACTIVE LONG-TERM MARKETS TEXAS AND CALIFORNIA The two largest cement markets in the U.S. Account for almost 25% of cement consumption Receive the largest shares of federal transportation funding Favorable demographics Large populations Above average population growth rates 18
Slide 19: Strong Market Positions
STRONG MARKET POSITIONS Texas Accounts for approximately 80% of TXI sales TXI is the largest cement supplier in the state TXI is a low cost cement supplier Aggregate and ready mix operations are concentrated in Texas Largest expanded shale and clay supplier in Texas California Cement plant expansion
Slide 20: Texas Market – 1980, 2000 and 2020
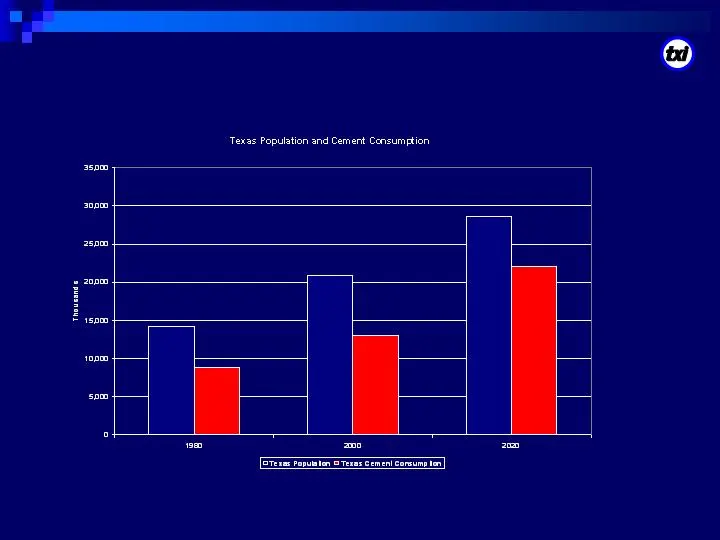
TEXAS MARKET – 1980, 2000 AND 2020 Sources: U. S. Census Bureau, Portland Cement Association (PCA), USGS (projected) 20
Slide 21: California Market – 1980, 2000 and 2020
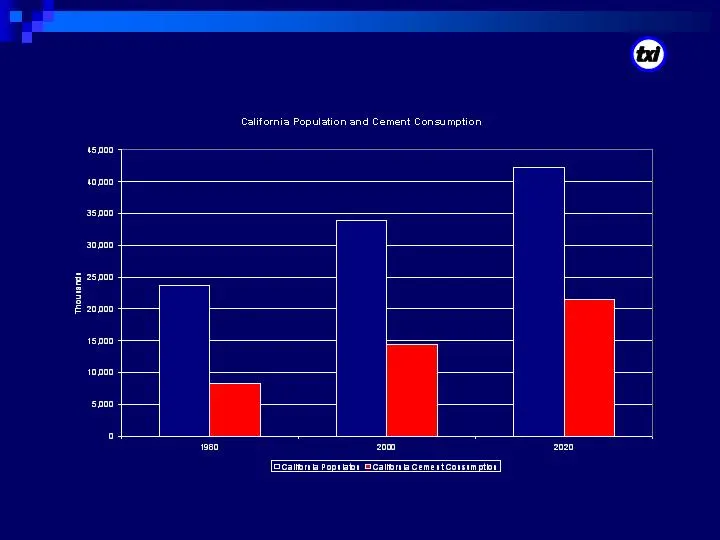
CALIFORNIA MARKET – 1980, 2000 AND 2020 Sources: U.S. Census Bureau, Portland Cement Association (PCA), USGS (projected) 21
Slide 22: Low Cost Operations Are Key
LOW COST OPERATIONS ARE KEY Notes: 1 North Texas productivity from the dry kiln for the twelve months ended May 31, 2008 2 Old California productivity for the twelve months ended May 31, 2007 3 Expected California productivity for the new kiln at full capacity 4 Current Central Texas productivity fo
Slide 23: Cement Plant Expansions
CEMENT PLANT EXPANSIONS 23
Slide 24: California Cement Plant Modernization and Expansion
CALIFORNIA CEMENT PLANT MODERNIZATION AND EXPANSION Commissioned May 2008 Added 2.3 million tons of state-of-the-art annual cement capacity Replaced 1.3 million tons of 50 year old production capacity Combined benefit of more capacity and significantly increased production efficiencies 24
Slide 25: Central Texas Cement Plant Expansion
CENTRAL TEXAS CEMENT PLANT EXPANSION Enhances TXI’s market-leading position in Texas Adds 1.4 million tons of state-of-the-art cement capacity Existing .9 million ton cement facility will remain in operation Expected investment of $325-350 million Required permits and permissions are in place Schedu
Slide 26: North Texas Cement Plant Incremental Production
NORTH TEXAS CEMENT PLANT INCREMENTAL PRODUCTION Current annual plant capacity of 2.8 million tons Potential to increase production by .5 million tons annually Increase will come from kiln added in 2001 Have already realized significant clinker production improvement Expect full realization of increa
Slide 27: Current Market Conditions
CURRENT MARKET CONDITIONS 27
Slide 28: Current Economic Conditions
CURRENT ECONOMIC CONDITIONS The U.S. economy has slowed U.S. credit markets are difficult Energy costs are volatile The Texas economy is relatively solid California construction activity is weak 28
Slide 29: Summary of Construction Activity
SUMMARY OF CONSTRUCTION ACTIVITY Source: F.W. Dodge, Portland Cement Association -25% 1% YTD 08 vs YTD 07 – August -15% 1% CY07 vs CY06 Cement Consumption -36% -6% YTD 08 vs YTD 07 – September -19% -3% CY07 vs CY06 Nonresidential Contracts -48% -26% YTD 08 vs YTD 07 - September -39% -25% CY07 vs CY0
Slide 30: Current Market Conditions
CURRENT MARKET CONDITIONS Texas cement consumption continues to exceed cement capacity – imports required California cement consumption is below capacity – and construction has yet to bottom Imports have declined with declining cement demand in California California highway contract awards are begin
Slide 31: Actions in a Challenging Environment
ACTIONS IN A CHALLENGING ENVIRONMENT Cement price increases April, July and October 2008 increases have resulted in a modest positive trend in Texas Effective January 2009: Announced $15 per ton in Texas and California Ready mix price increase effective October 1 of $25 per cubic yard – some positiv
Slide 32: Earnings Potential and Strategy
EARNINGS POTENTIAL AND STRATEGY 32
Slide 33: Earnings Potential
EARNINGS POTENTIAL Note: Potential values assume a recovery in construction activity, cement consumption equal to or greater than cement capacity in Texas and California, normalized industry margins, and expected performance from new cement operations. 166 FY08 EBITDA 383 EBITDA 85 Depreciation (30)
Slide 34: TXI's Strategy in Summary
TXI’S STRATEGY IN SUMMARY Aggressively expand TXI’s most important business line Increase TXI cement capacity by 60% All projects are at existing sites Utilize infrastructure already in place Underlying permits already in place Organic growth versus acquisition All projects are in attractive long te
Slide 35: Addendum - Reconciliation of EBITDA to Net Income
ADDENDUM - RECONCILIATION OF EBITDA TO NET INCOME 35
Slide 36: Reconciliation of EBITDA to Net Income
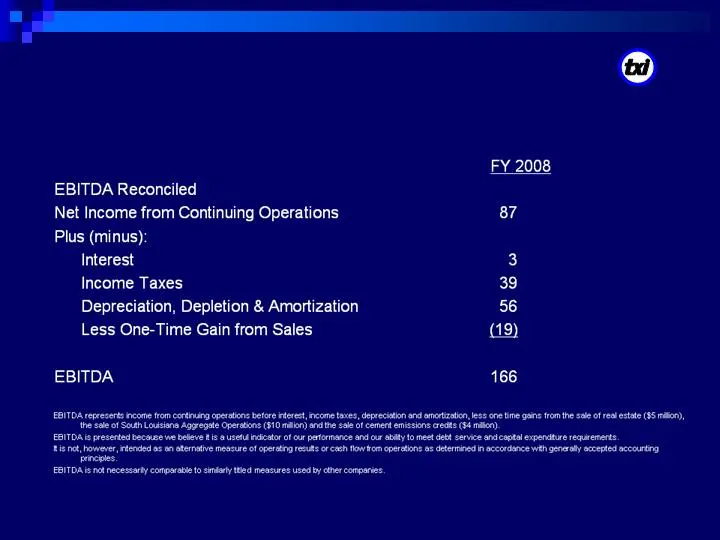
RECONCILIATION OF EBITDA TO NET INCOME IN $ MILLIONS 36
Slide 37: Stephens Inc. Fall Investment Conference 2008
COMPANY COLORS Blue: R = 0 G = 0 B = 255 Beige: R = 251 G = 248 B = 216 STEPHENS INC. FALL INVESTMENT CONFERENCE 2008 November 19, 2008 New York City 37
Source: SEC EDGAR · 8-K filed Nov 19, 2008
More decks from Texas Industries Inc
 BB&T 8th Annual Commercial & Industrial Investor Conference (March 2014)26 slides · Mar 26, 2014
 Merger or Acquisition (January 2014)16 slides · Jan 28, 2014
 Stephens Conference 201337 slides · Nov 12, 2013
 Investor Presentation (March 2013)39 slides · Mar 5, 2013
 Investor Presentation (September 2012)33 slides · Sep 11, 2012
 Bank of America Merrill Lynch Leveraged Finance Conference 201133 slides · Dec 1, 2011