StoneMor Partners LP — Merrill Lynch 2005 Death Care Conference
33 slides from StoneMor Partners LP's conference presentation, Apr 21, 2005
Slide 1: Merrill Lynch 2005 Death Care Conference
Merrill Lynch 2005 Death Care Conference April 21, 2005 Presented by:
Slide 2: StoneMor Presentation Team
StoneMor Presentation Team Lawrence Miller CEO, President and Chairman of the Board of Directors William R. Shane CFO, Executive Vice President and Director
Slide 3: Disclaimer
Disclaimer This presentation contains certain statements that may be deemed to be “forward-looking statements” within the meaning of the Securities Acts. All statements, other than statements of historical facts, that address activities, events or developments that the Partnership expects, projects,
Slide 4: Table of Contents
Table of Contents 1. Who We Are 2. MLP Structure – Unique Advantages 3. Why We Reorganized 4. Where Do We Go From Here 5. Financial Overview 6. Appendix
Slide 5: Who We Are
Who We Are StoneMor STONEMOn PARTNERS L.P.
Slide 6: Who We Are
Who We Are 4th largest owner and operator of cemeteries in the U.S. 132 cemeteries 7 funeral homes More than 22,000 burials performed in 2004 Geographically-diverse operations Located in 12 states, primarily along the Eastern Seaboard Operate more than 6,000 acres of land Weighted average sales life
Slide 7: Geographic Scope
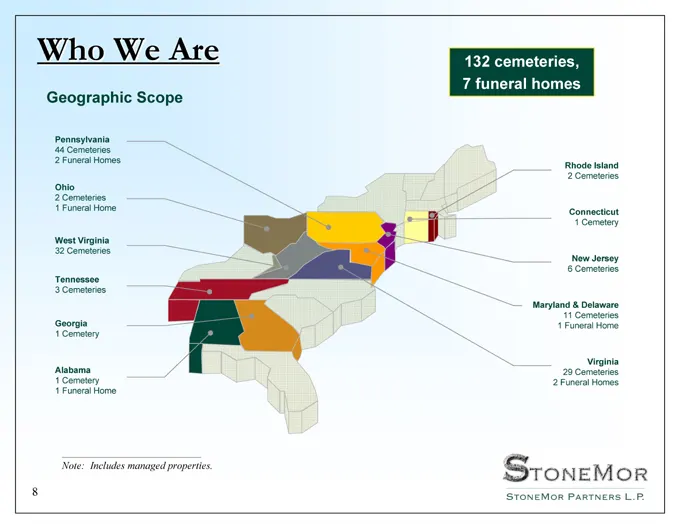
Who We Are 132 cemeteries, 7 funeral homes Geographic Scope Pennsylvania 44 Cemeteries 2 Funeral Homes Ohio 2 Cemeteries 1 Funeral Home West Virginia 32 Cemeteries Tennessee 3 Cemeteries Georgia 1 Cemetery Alabama 1 Cemetery 1 Funeral Home Rhode Island 2 Cemeteries Connecticut 1 Cemetery New Jersey
Slide 8: Highly Experienced Management Team
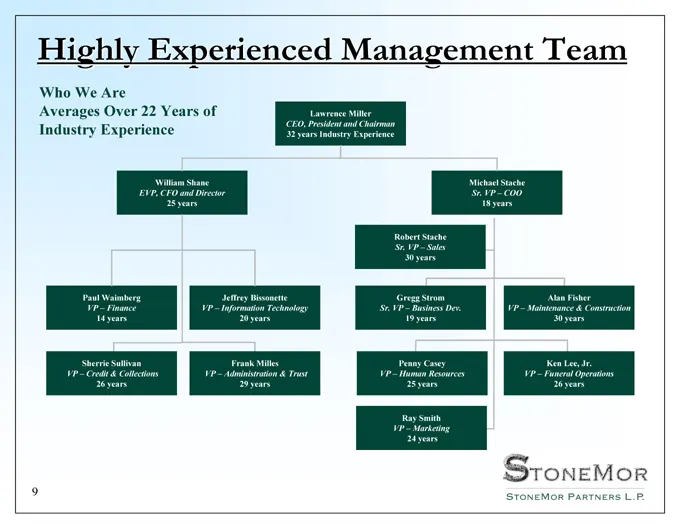
Highly Experienced Management Team Who We Are Averages Over 22 Years of Industry Experience Lawrence Miller CEO, President and Chairman 32 years Industry Experience William Shane EVP, CFO and Director 25 years Michael Stache Sr. VP – COO 18 years Paul Waimberg VP – Finance 14 years Jeffrey Bissonett
Slide 9: Management Team
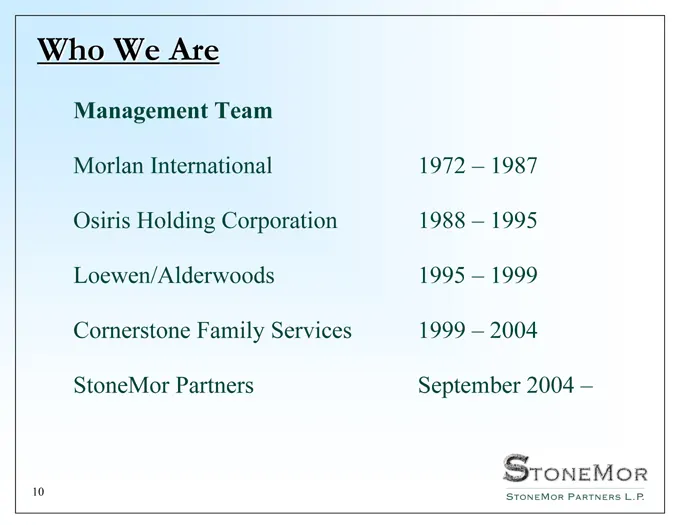
Who We Are Management Team Morlan International 1972 – 1987 Osiris Holding Corporation 1988 – 1995 Loewen/Alderwoods 1995 – 1999 Cornerstone Family Services 1999 – 2004 StoneMor Partners September 2004 –
Slide 10: Cemetery Industry Overview
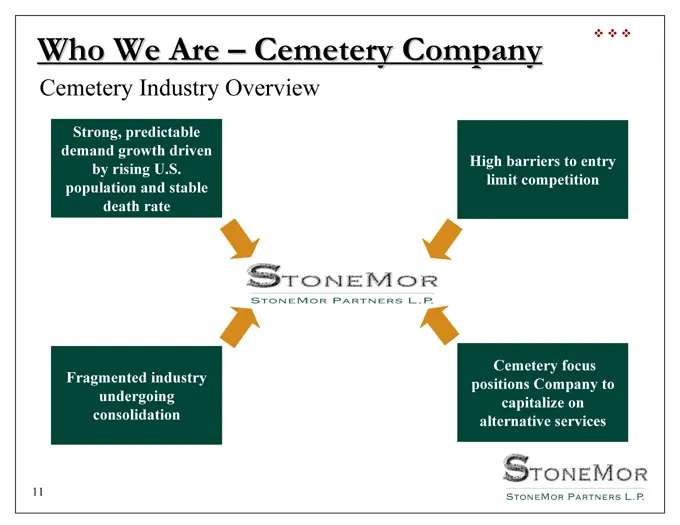
Who We Are – Cemetery Company Cemetery Industry Overview Strong, predictable demand growth driven by rising U.S. population and stable death rate Fragmented industry undergoing consolidation High barriers to entry limit competition Cemetery focus positions Company to capitalize on alternative servic
Slide 11: MLP Structure – Unique Advantages
MLP Structure – Unique Advantages
Slide 12: MLP Structure – Unique Advantages
MLP Structure – Unique Advantages StoneMor Partners is a cemetery company organized as a Master Limited Partnership (MLP).
Slide 13: MLP Structure – Unique Advantages
MLP Structure – Unique Advantages StoneMor is: An investing vehicle with general and limited partners Publicly-traded partnership taxed as a partnership, not a corporation MLPs distribute available cash flow on a quarterly basis Portion of distribution is tax deferred Minimum annual per unit distrib
Slide 14: Ownership Profile
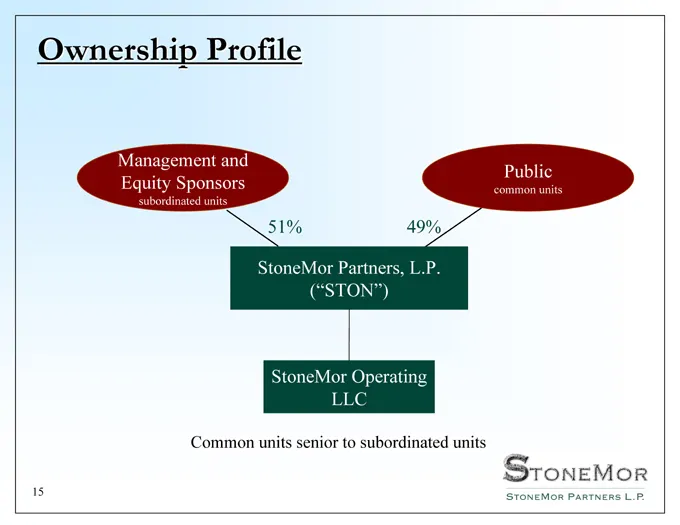
Ownership Profile Management and Equity Sponsors subordinated units 51% Public common units 49% StoneMor Partners, L.P. (“STON”) StoneMor Operating LLC Common units senior to subordinated units
Slide 15: Why We Reorganized
Why We Reorganized StoneMor STONEMOn PARTNERS L.P.
Slide 16: Why We Reorganized
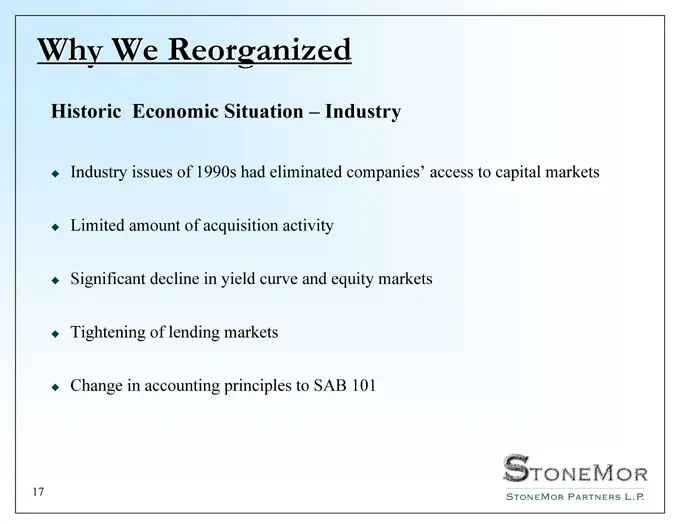
Why We Reorganized Historic Economic Situation – Industry Industry issues of 1990s had eliminated companies’ access to capital markets Limited amount of acquisition activity Significant decline in yield curve and equity markets Tightening of lending markets Change in accounting principles to SAB 101
Slide 17: Where Do We Go From Here?
Where Do We Go From Here? StoneMor STONEMOn PARTNERS L.P.
Slide 18: Where Do We Go From Here?
Where Do We Go From Here? We generate return for our investors by growing distributable cash flow. Grow unit distributions by Acquisitions Pre-need sales Manage trusts
Slide 19: Where Do We Go From Here?
Where Do We Go From Here? Robust opportunity for growth through acquisition Fragmented industry structure affords plentiful acquisition opportunities Target acquisitions intended to be accretive on a cash basis Rigorous diligence process leads to attractive acquisition multiples Experienced manageme
Slide 20: Impact of Acquisitions – How We Intend to Grow
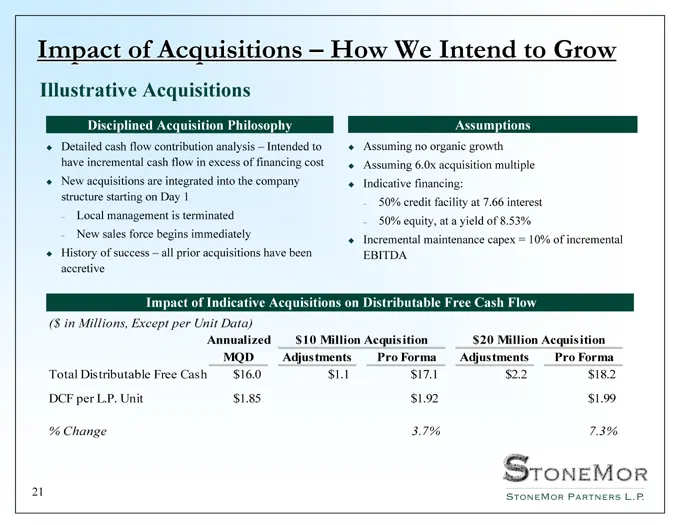
Impact of Acquisitions – How We Intend to Grow Illustrative Acquisitions Disciplined Acquisition Philosophy Detailed cash flow contribution analysis – Intended to have incremental cash flow in excess of financing cost New acquisitions are integrated into the company structure starting on Day 1 Local
Slide 21: Financial Overview
Financial Overview StoneMor [STONEMOR PARTNERS L.P.
Slide 22: Distribution of Revenues
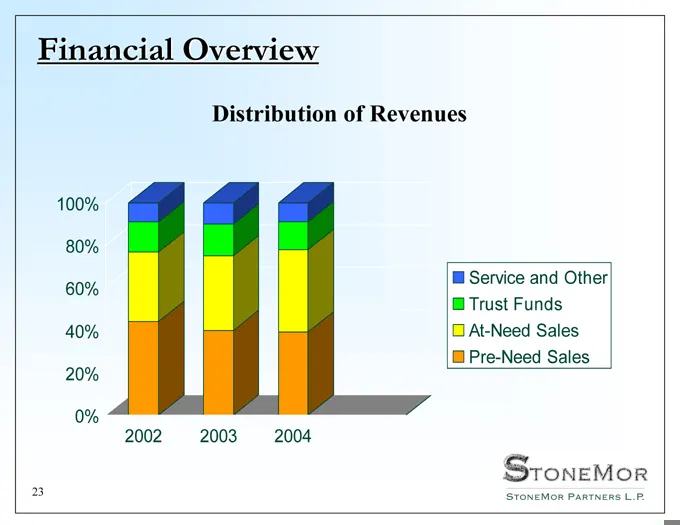
Financial Overview Distribution of Revenues 100% 80% 60% 40% 20% 0% 2002 2003 2004 Service and Other Trust Funds At-Need Sales Pre-Need Sales
Slide 23: Diversified Revenue Mix
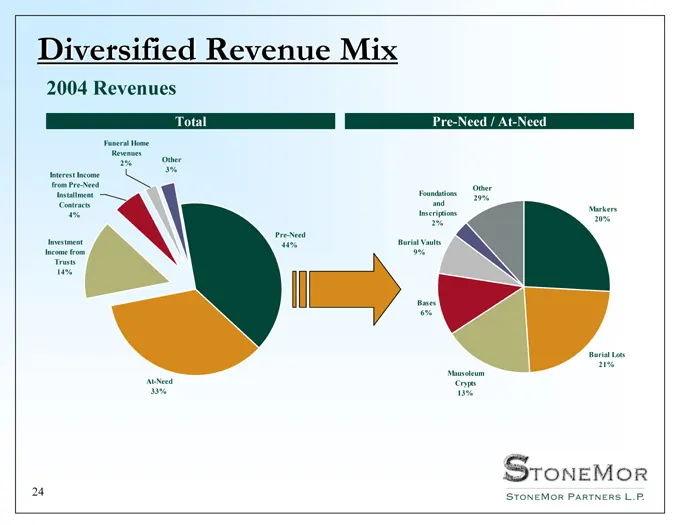
Diversified Revenue Mix 2004 Revenues Total Funeral Home Revenues 2% Other 3% Interest Income from Pre-Need Installment Contracts 4% Investment Income from Trusts 14% At-Need 33% Pre-Need 44% Foundations and Inscriptions 2% Burial Vaults 9% Bases 6% Mausoleum Crypts 13% Burial Lots 21% Markers 20% O
Slide 24: Merchandise Trust Funds
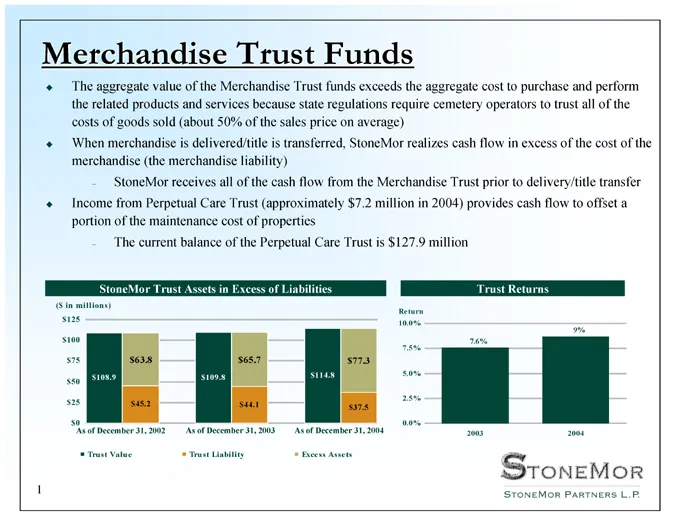
Merchandise Trust Funds The aggregate value of the Merchandise Trust funds exceeds the aggregate cost to purchase and perform the related products and services because state regulations require cemetery operators to trust all of the costs of goods sold (about 50% of the sales price on average) When
Slide 25: Financial Overview
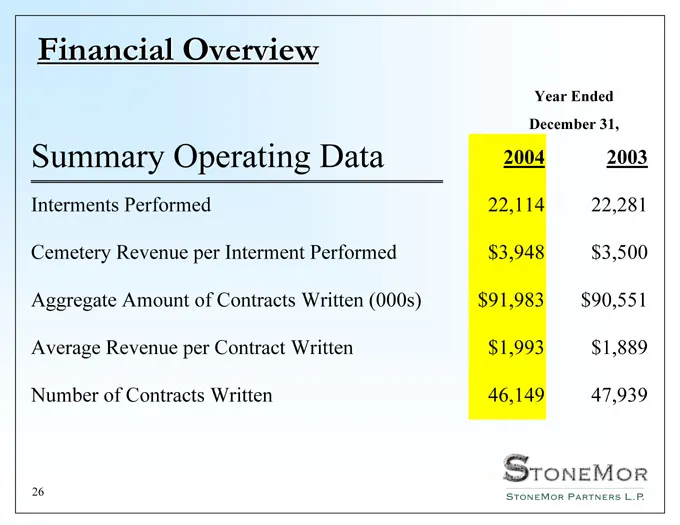
Financial Overview Year Ended December 31, Summary Operating Data 2004 2003 Interments Performed 22,114 22,281 Cemetery Revenue per Interment Performed $3,948 $3,500 Aggregate Amount of Contracts Written (000s) $91,983 $ 90,551 Average Revenue per Contract Written $1,993 $1,889 Number of Contracts W
Slide 26: Financial Overview
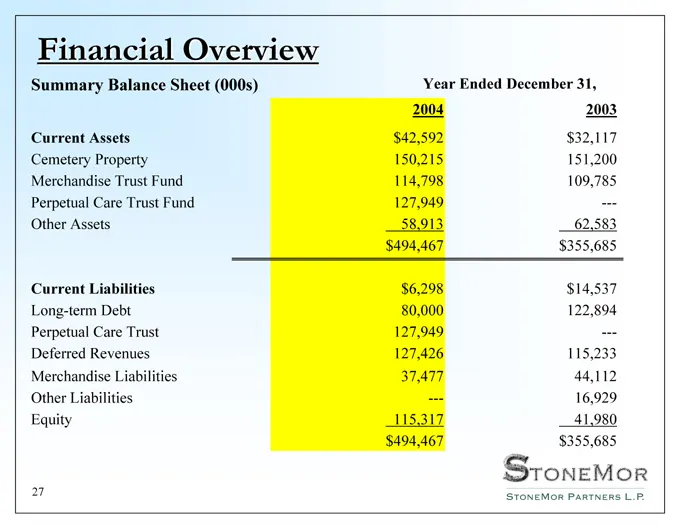
Financial Overview Summary Balance Sheet (000s) Year Ended December 31, 2004 2003 Current Assets $42,592 $32,117 Cemetery Property 150,215 151,200 Merchandise Trust Fund 114,798 109,785 Perpetual Care Trust Fund 127,949 —- Other Assets 58,913 62,583 $494,467 $355,685 Current Liabilities $6,298 $14,5
Slide 27: Financial Overview
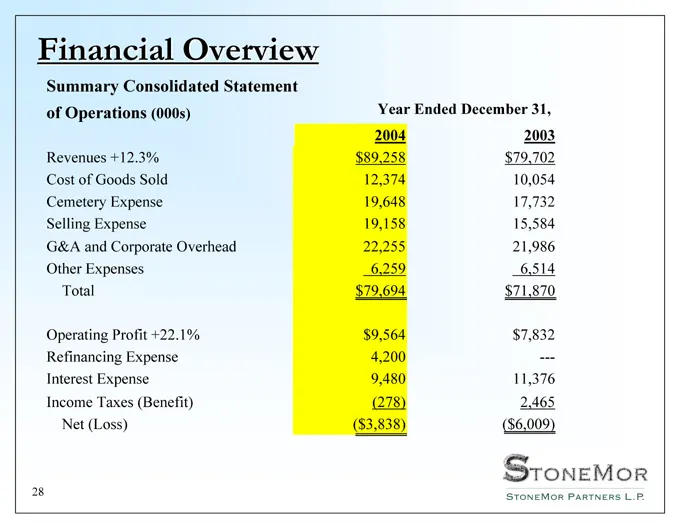
Financial Overview Summary Consolidated Statement of Operations (000s) Year Ended December 31, 2004 2003 Revenues +12.3% $89,258 $79,702 Cost of Goods Sold 12,374 10,054 Cemetery Expense 19,648 17,732 Selling Expense 19,158 15,584 G&A and Corporate Overhead 22,255 21,986 Other Expenses 6,259 6,514 T
Slide 28: Financial Overview – Cash Flow
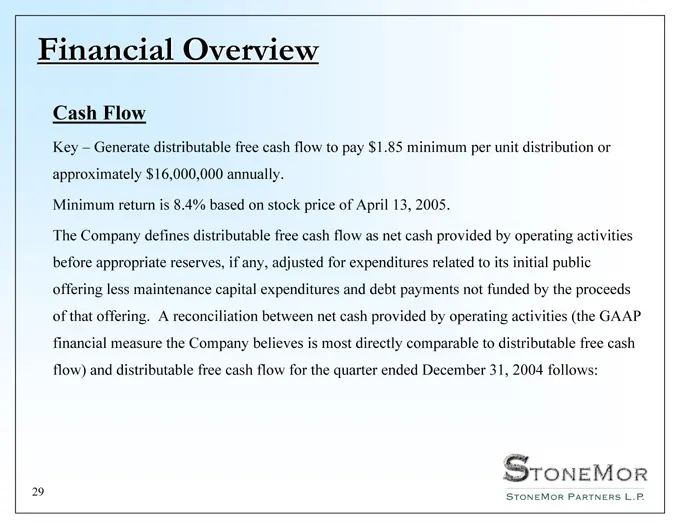
Financial Overview Cash Flow Key – Generate distributable free cash flow to pay $1.85 minimum per unit distribution or approximately $16,000,000 annually. Minimum return is 8.4% based on stock price of April 13, 2005. The Company defines distributable free cash flow as net cash provided by operating
Slide 29: Distributable Free Cash Flow
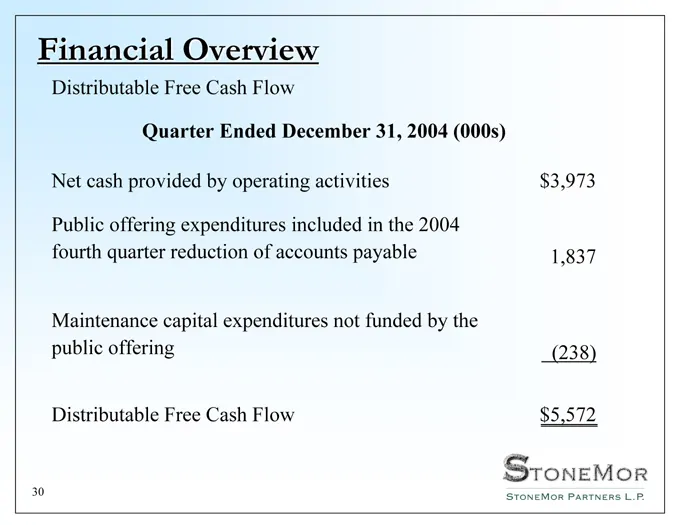
Financial Overview Distributable Free Cash Flow Quarter Ended December 31, 2004 (000s) Net cash provided by operating activities $3,973 Public offering expenditures included in the 2004 fourth quarter reduction of accounts payable 1,837 Maintenance capital expenditures not funded by the public offer
Slide 30: Investment Highlights
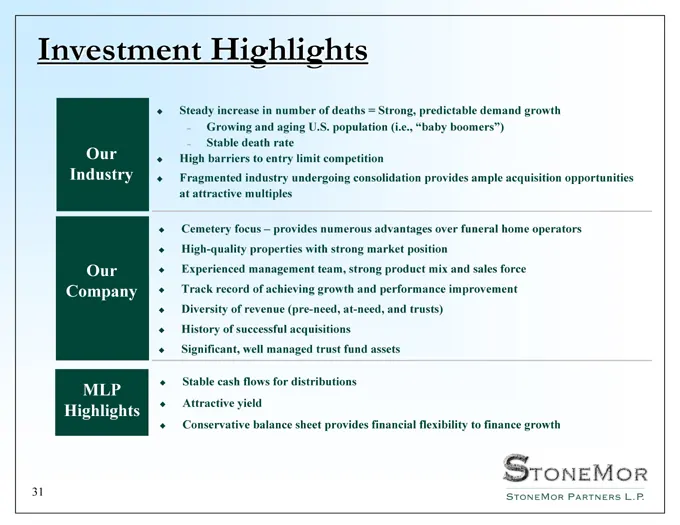
Investment Highlights Steady increase in number of deaths = Strong, predictable demand growth Growing and aging U.S. population (i.e., “baby boomers”) Stable death rate High barriers to entry limit competition Fragmented industry undergoing consolidation provides ample acquisition opportunities at a
Slide 31: Investment Highlights
Investment Highlights American Jobs Creation Act of 2004 MLP income is qualified income for mutual funds Mutual funds allowed to hold 25% of their assets in MLPs No state tax in states that follow federal tax rules
Slide 32: Appendix
Appendix SroneMor sro aS LP Jeon Pai
Slide 33: Distributable Free Cash Flow
Appendix Distributable Free Cash Flow We present distributable free cash flow because management believes this information is a useful adjunct to net cash provided by operating activities under GAAP. Distributable free cash flow is a significant liquidity metric that we believe is an indicator of ou
Source: SEC EDGAR · 8-K filed Apr 21, 2005