Atlas Financial — IPO Roadshow (May 2014)
20 slides from Atlas Financial's IPO roadshow presentation, May 13, 2014
Slide 1: Free Writing Follow-on May 2014 Offering
Free Writing Follow-on May 2014 Offering Prospectus Filed pursuant to Rule 433 Registration No. 333-195495
Slide 2: Safe Harbor Statement
Safecould The Alternatively, Statements Insurance Such different “may,” performance looking include: expansion regulation; ability business and guarantees 2affecting other issuer Harbor forward to “will,” statements (i) plan. from Atlas retain documents Company cause effectively; has of (ix) in mark
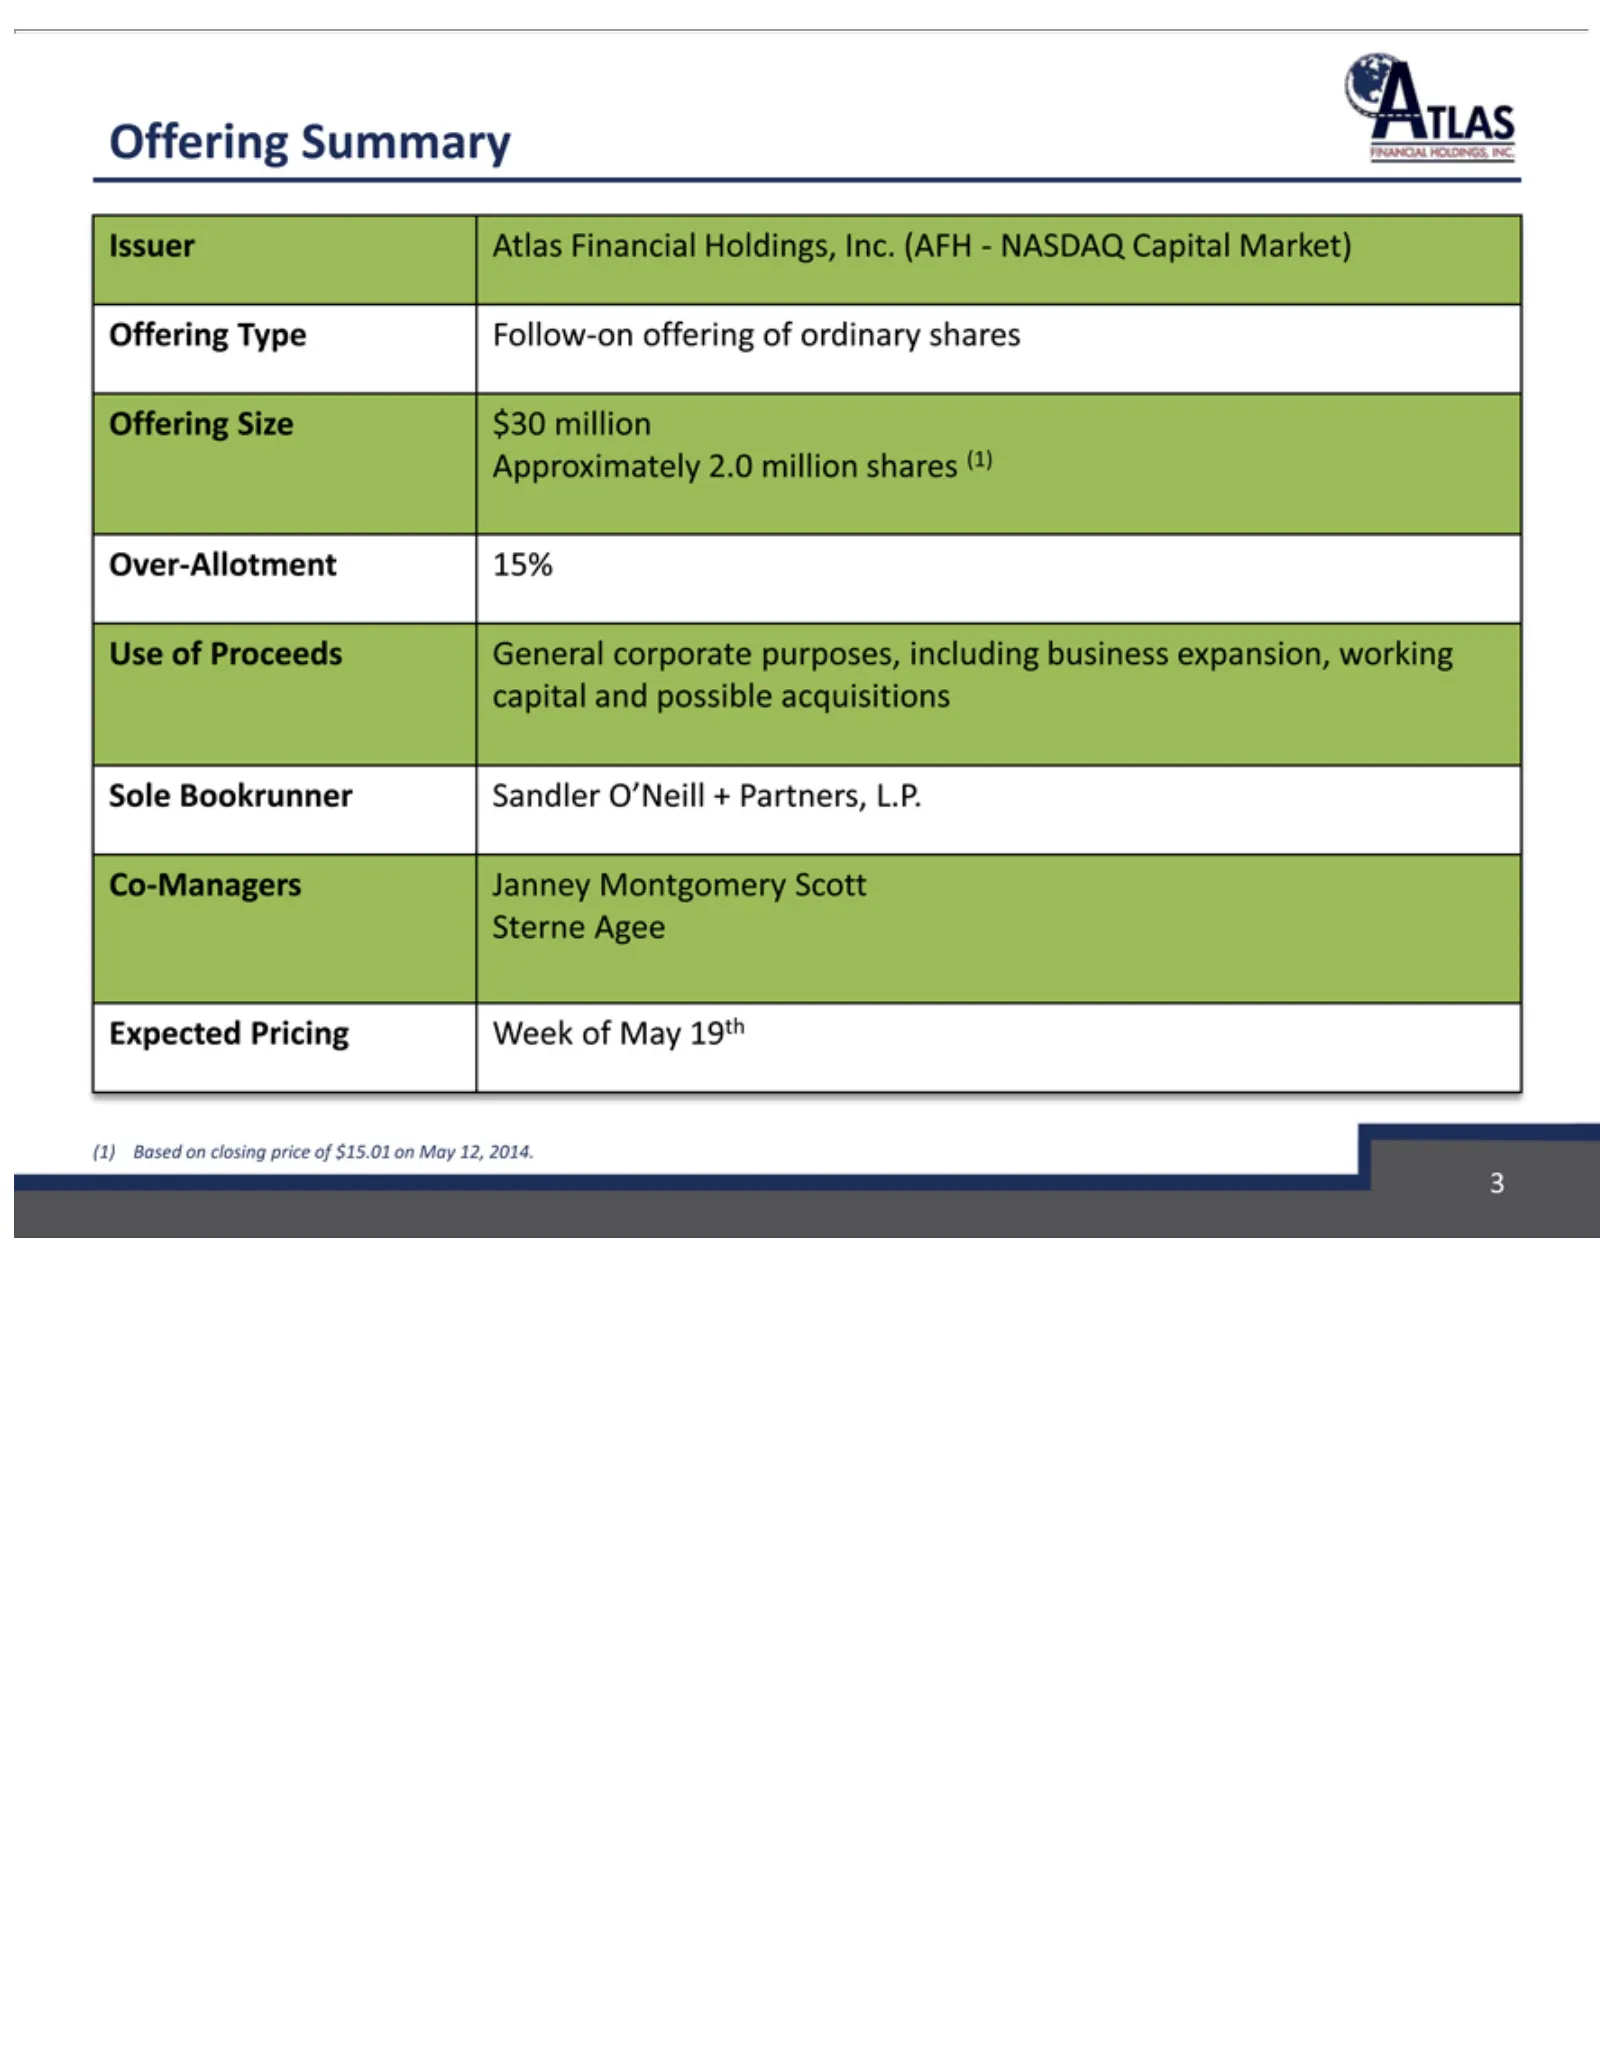
Slide 3: Offering Summary
Issuer Offering Approximately Over-Allotment Use capital Sole Co-Managers Sterne Expected 3(1) Based of Bookrunner Atlas Agee Proceeds and Type Summary Size Pricing on possible Financial closing $30 Janney Follow-on 2.0 15% General Sandler Week million million acquisitions price Montgomery Holdings,
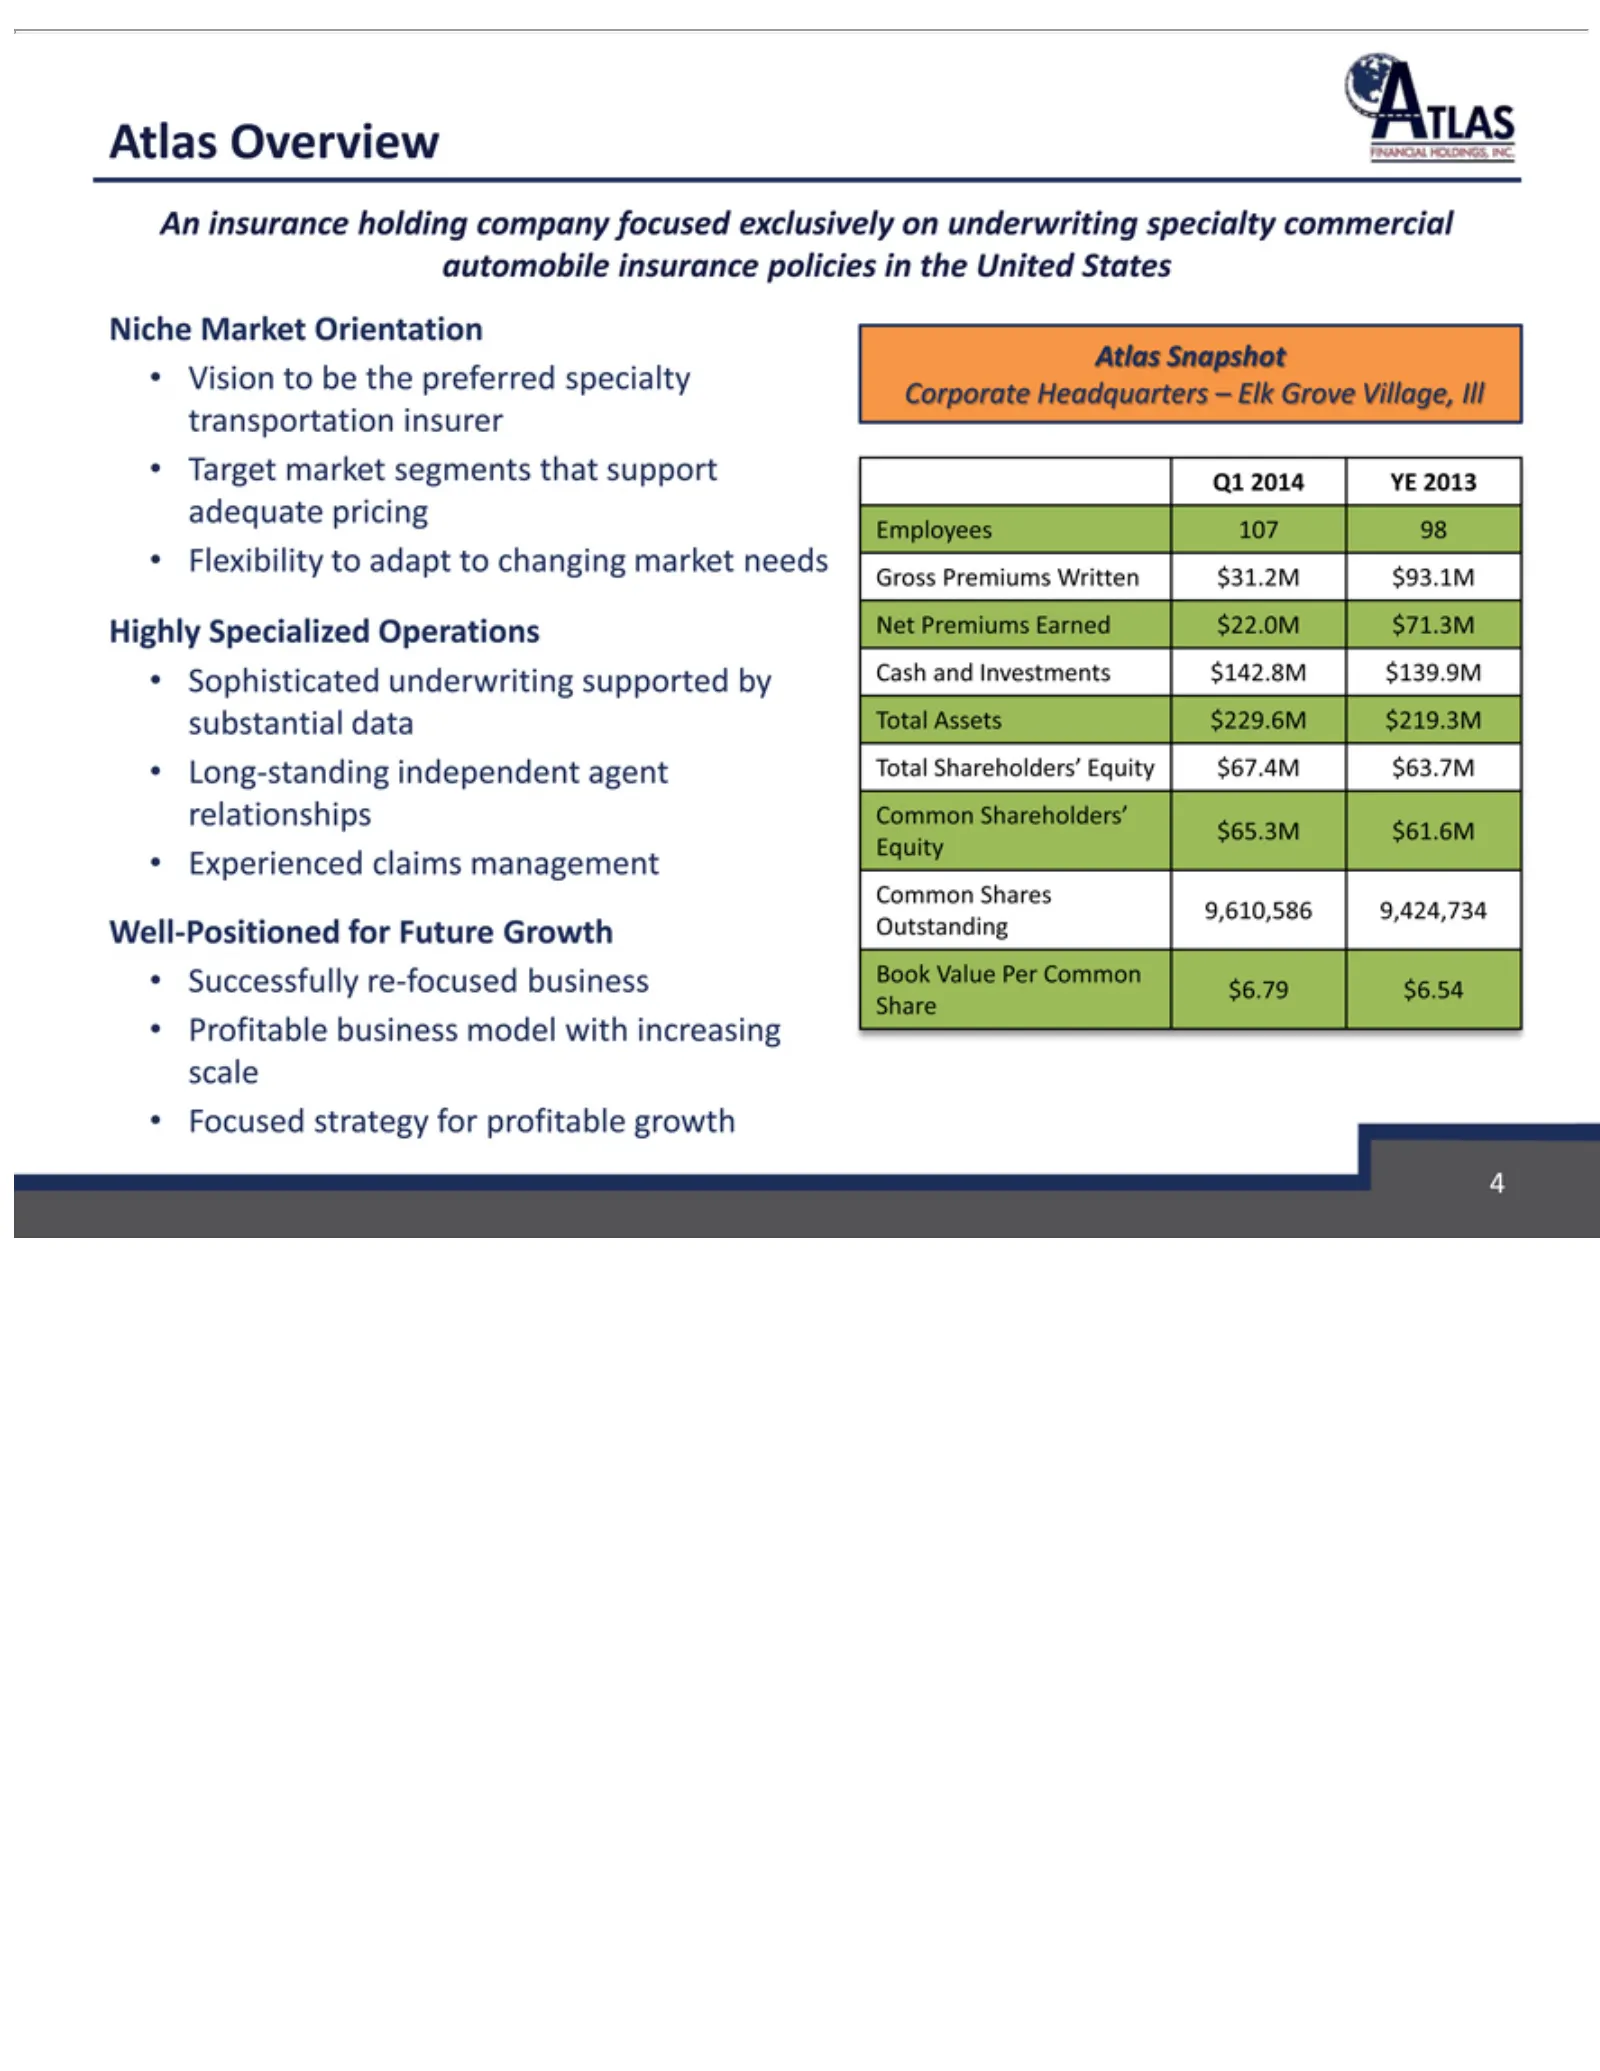
Slide 4: Atlas Corporate Overview and Snapshot
An 2014 Niche Vision Target Flexibility Highly Sophisticated Long-standing Experienced Well-Positioned Successfully Profitable Focused Atlas Corporate Q1 Employees Gross Net Cash Total Common Equity Book 4Outstanding Share insurance Premiums Assets and Shareholders’ Overview Snapshot Value Premiums
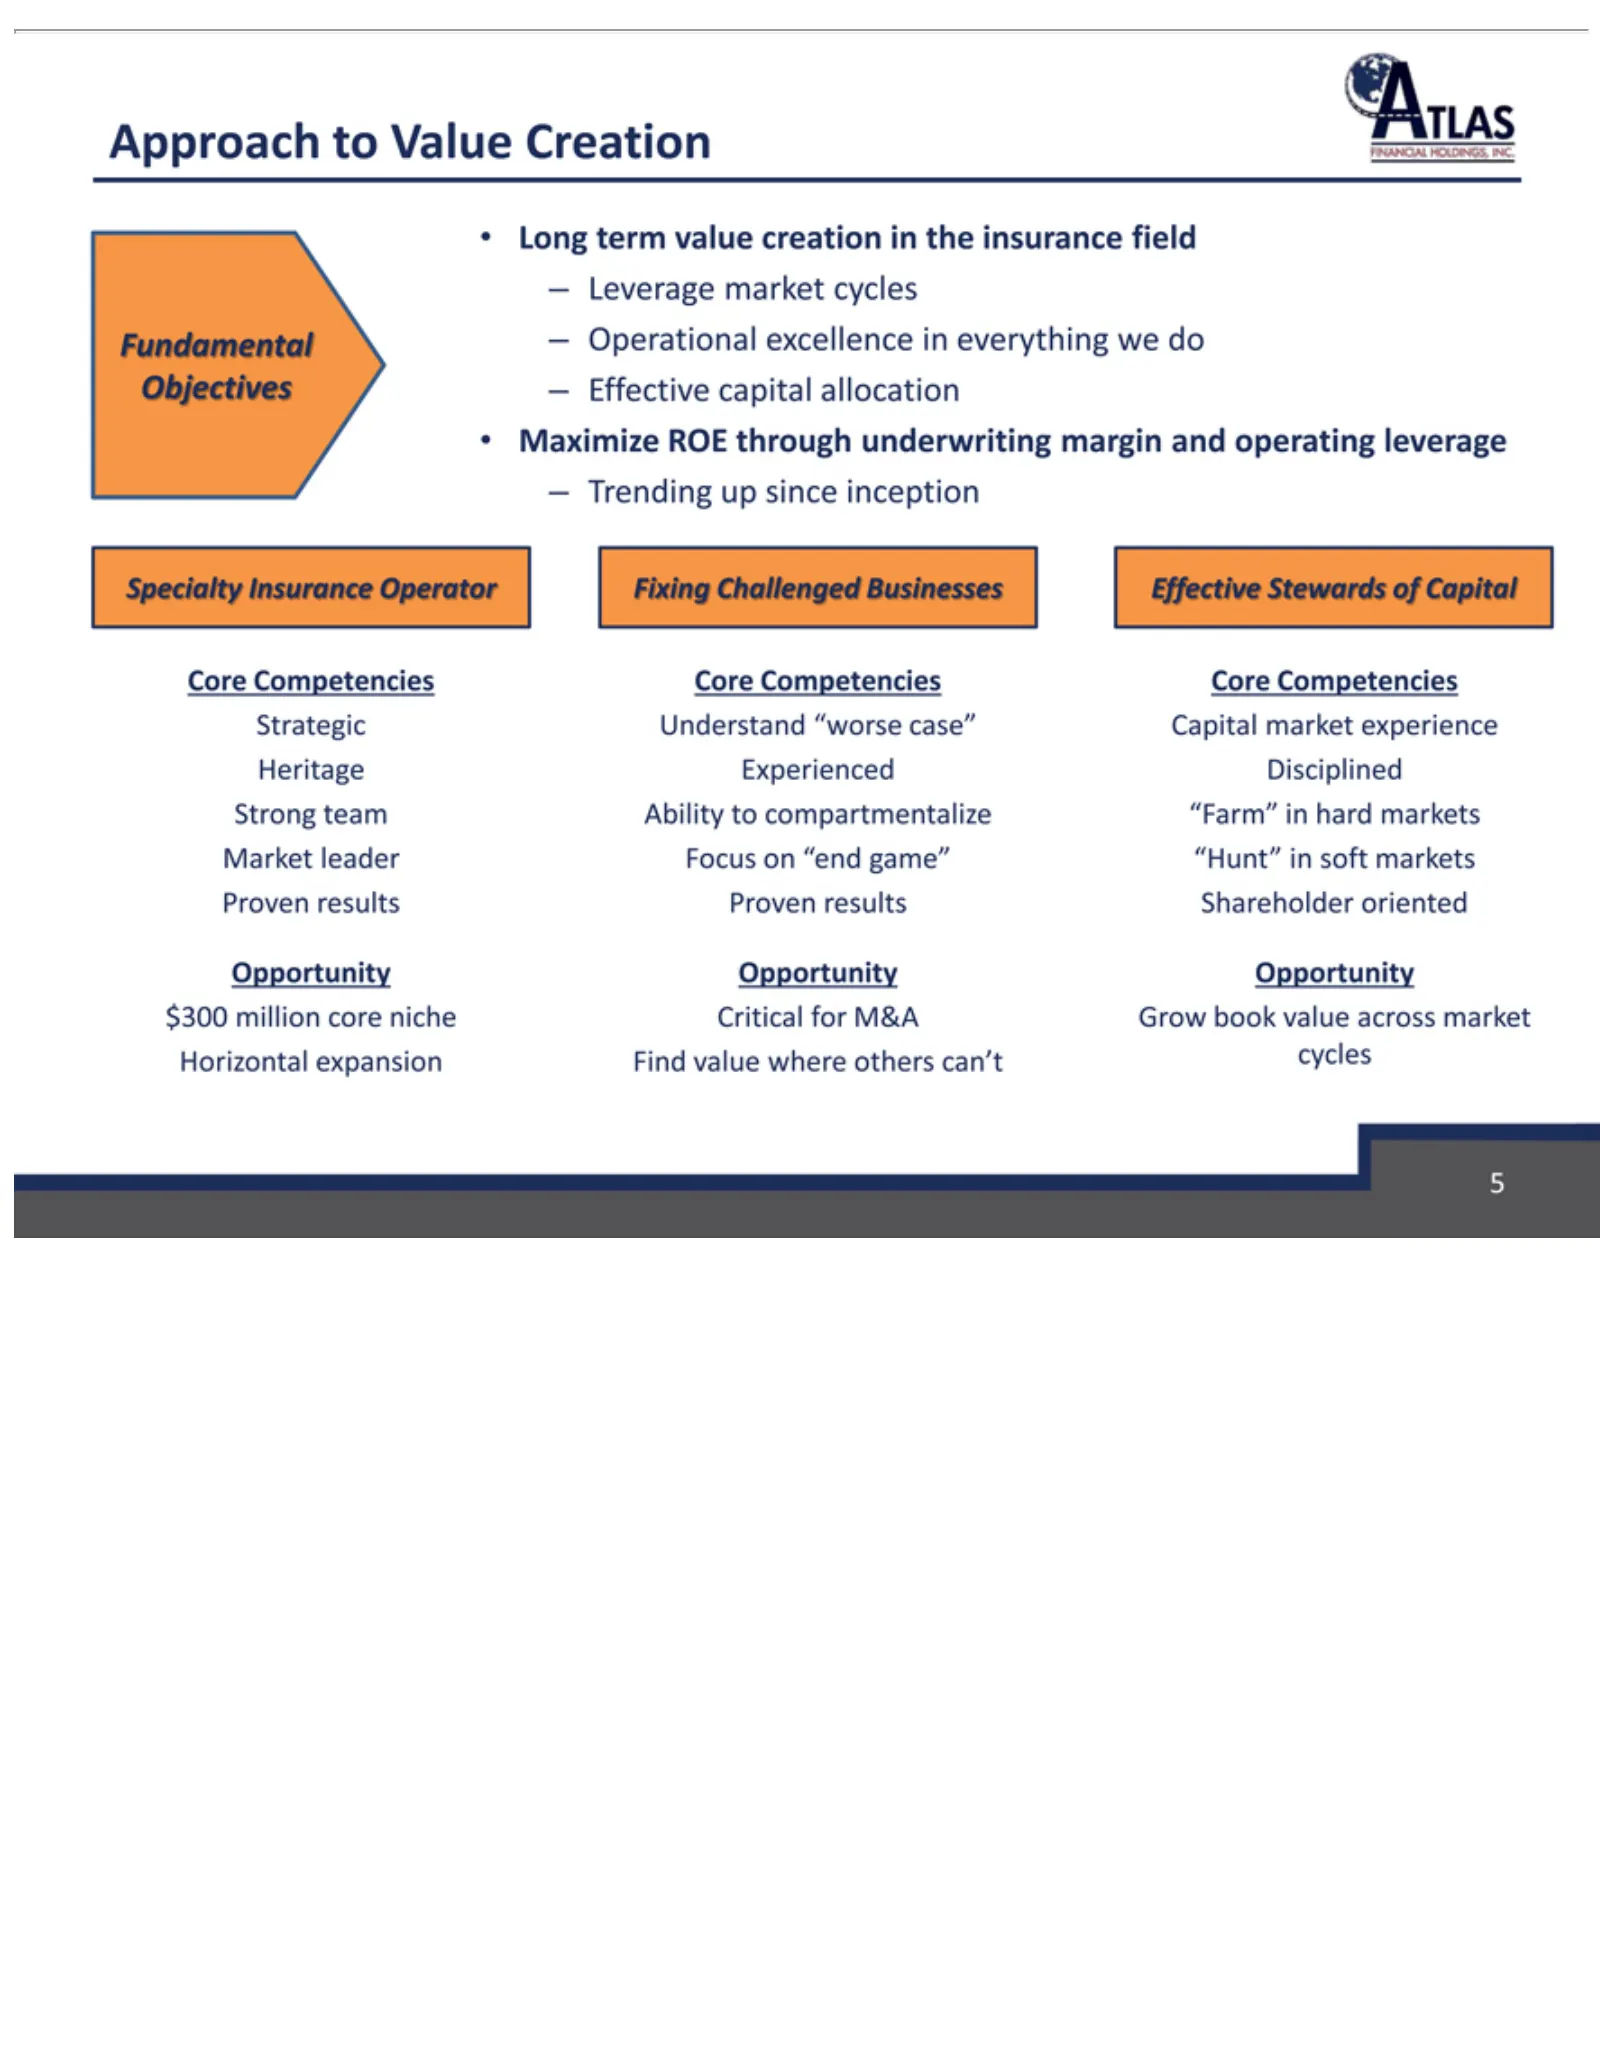
Slide 5: Fundamental Approach to Value Creation
Approach Long Fundamental –Maximize Specialty Core Strategic markets 5Opportunity Trending Leverage Competencies term Proven Understand Insurance to ROE value up market Opportunity Value –since Operational results through creation Creation cycles Operator Core inception “worse Proven underwriting Op
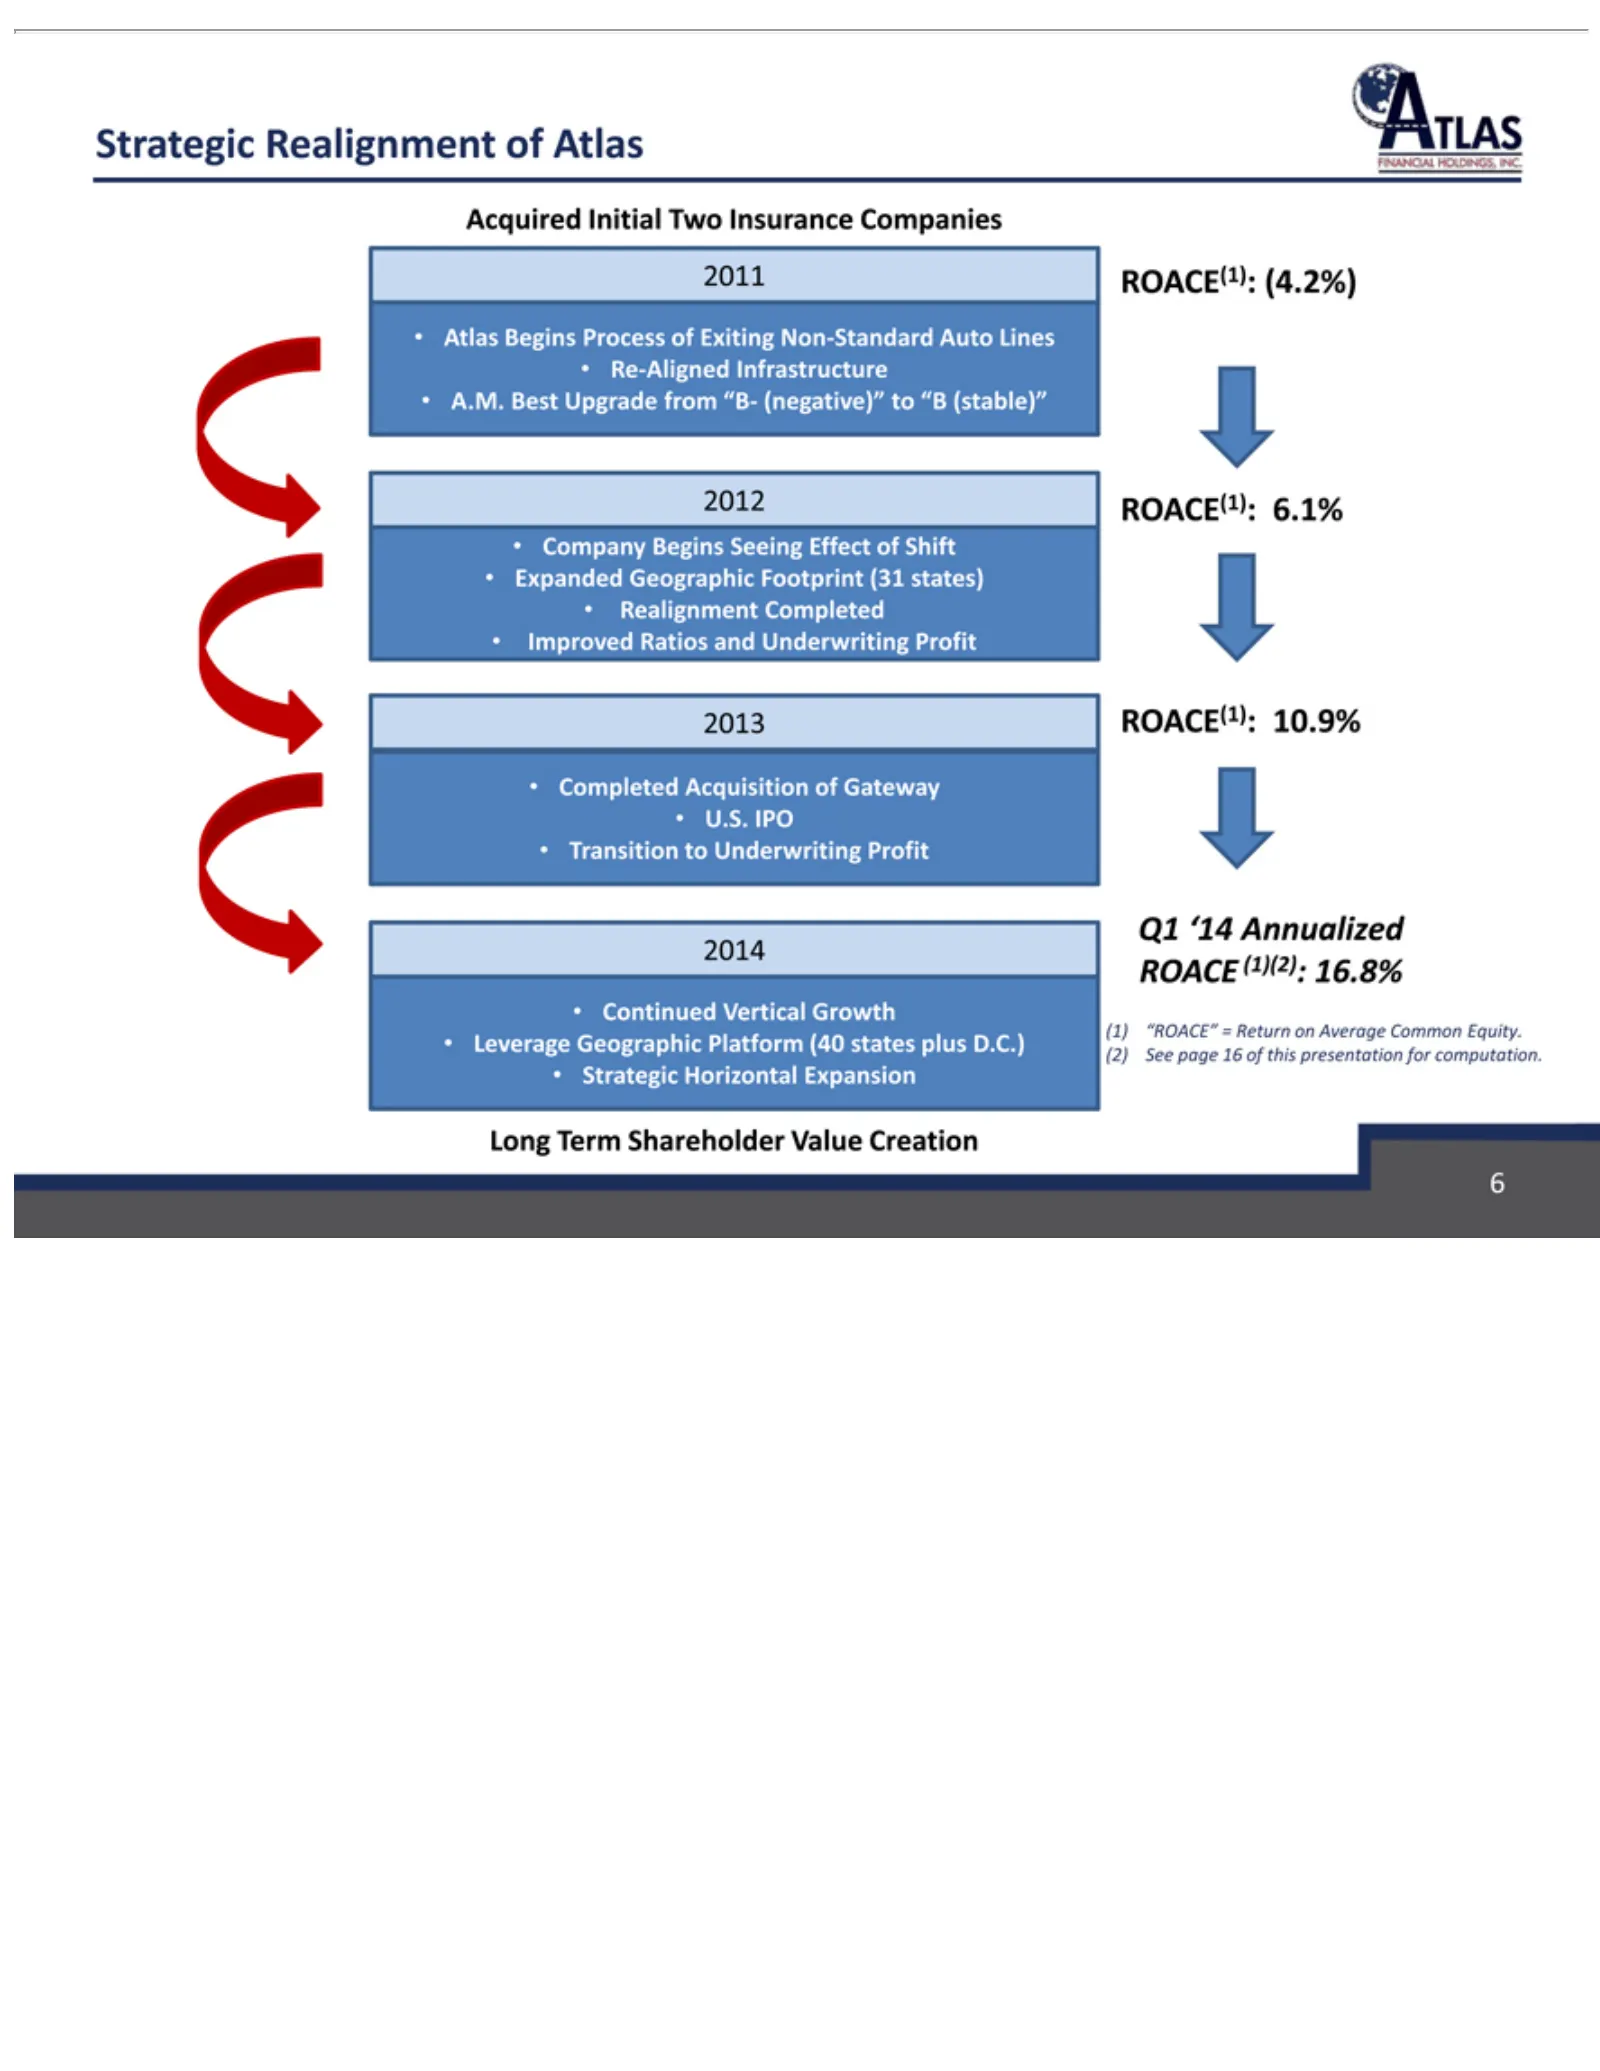
Slide 6: Strategic Realignment Timeline
Acquired 2011 Atlas Re-Aligned A.M. 2012 Company Expanded Realignment Improved 2013 Completed U.S. Transition Q1 ROACE 2014 Continued Leverage (2) Strategic 6Long See ‘14 IPO ROACE(1): Term Begins Best Annualized page (1)(2): Realignment Horizontal Geographic Initial Ratios Begins Geographic to Upgr
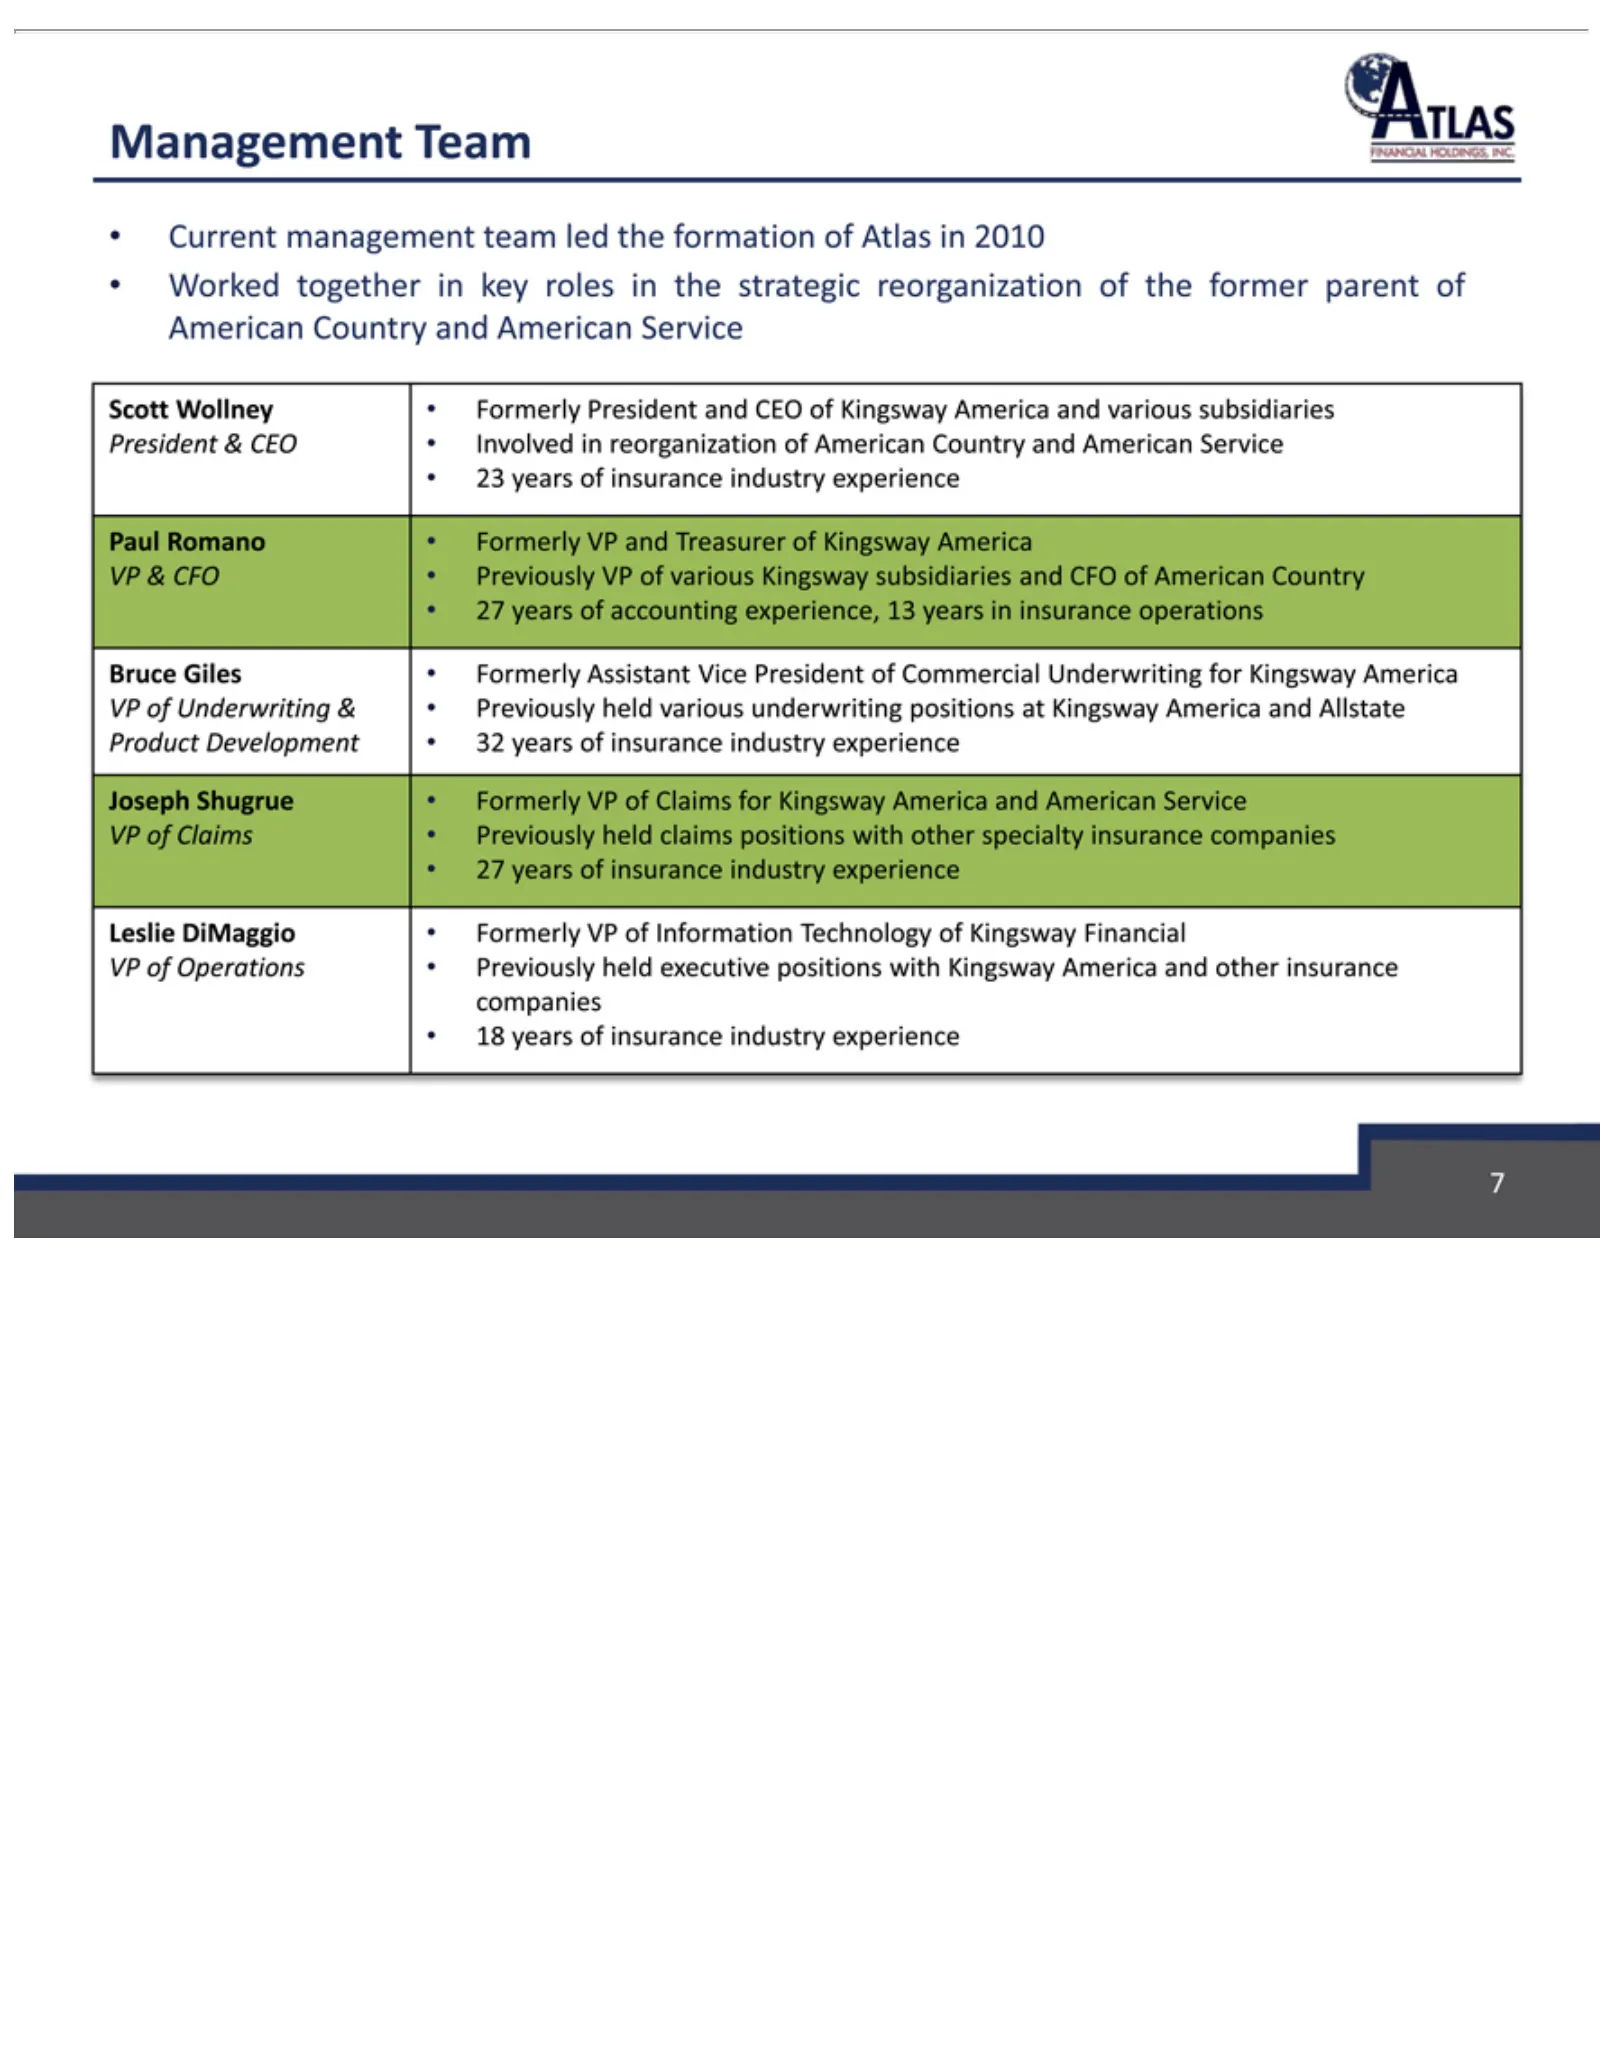
Slide 7: Experienced Management Team
Management Current Worked Scott 23 Bruce 27 Leslie •VP 718 Involved 32 Formerly Previously years &years ofWollney CFO Operations Giles DiMaggio management together ofof in Assistant VP President accounting insurance VP held insurance reorganization Team ofof in various claims executive Claims Inform
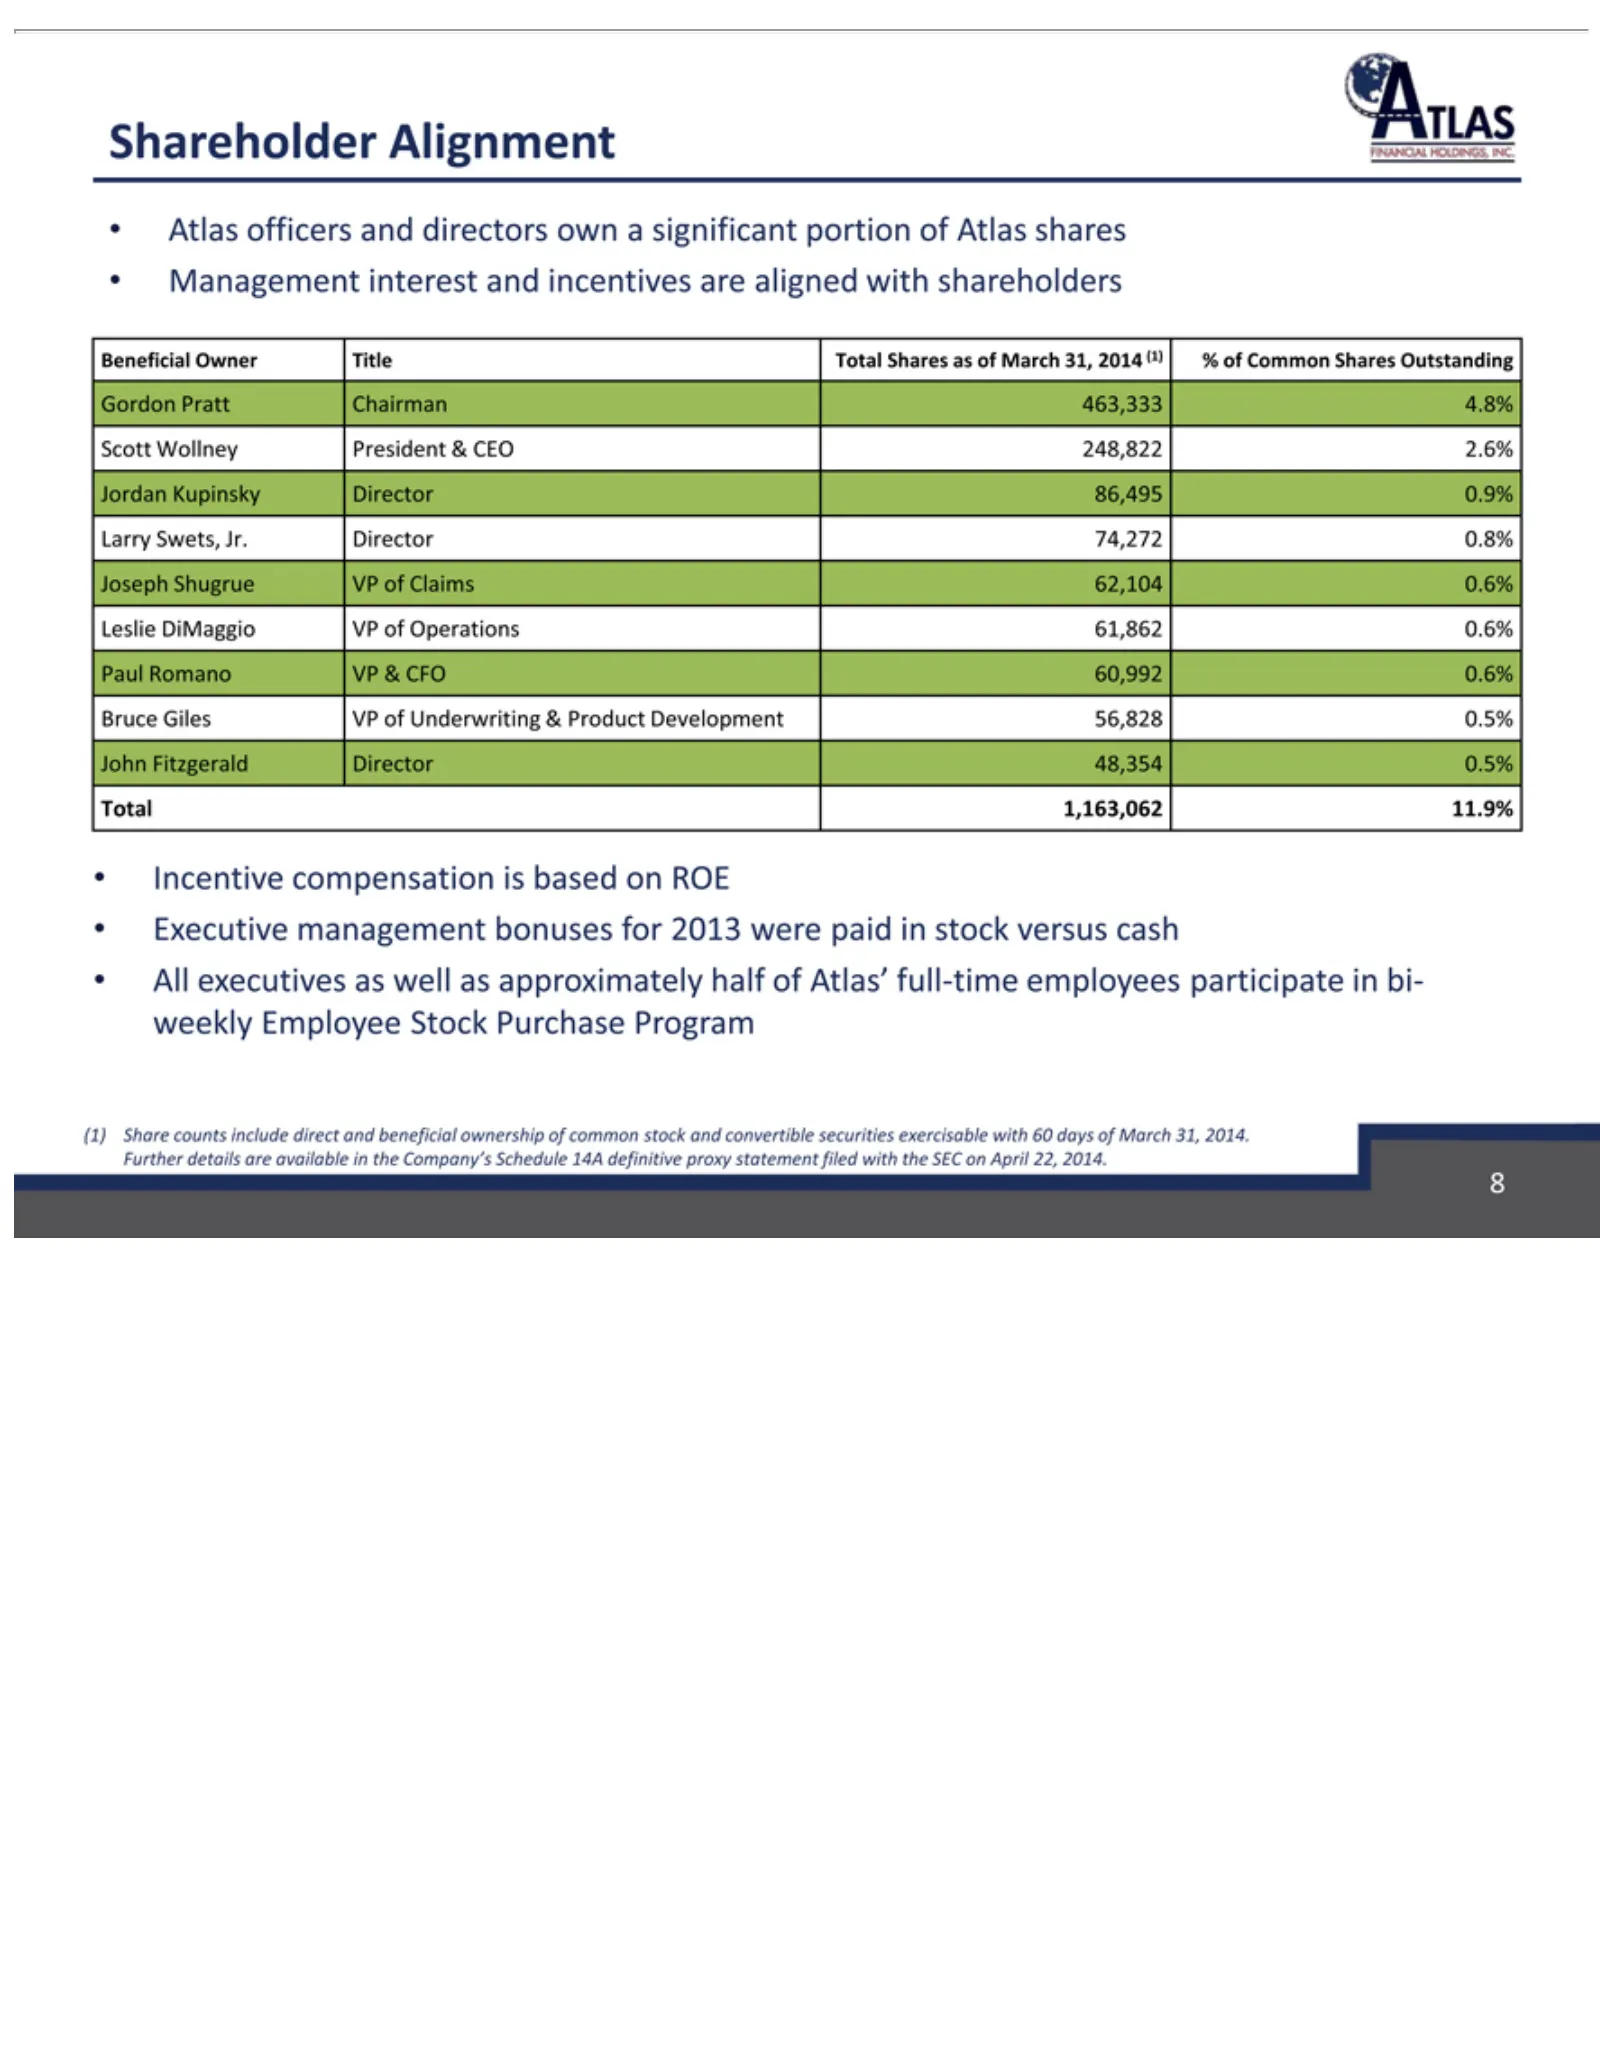
Slide 8: Shareholder and Management Alignment
Shareholder Atlas Management Beneficial Gordon Scott Jordan Larry Joseph Leslie Paul Bruce John Total Incentive Executive All (1) 8proxy Share executives Romano Fitzgerald Wollney 1,163,062 officers Swets, statement Giles DiMaggio Kupinsky Shugrue Pratt counts compensation management Owner VP Alignm
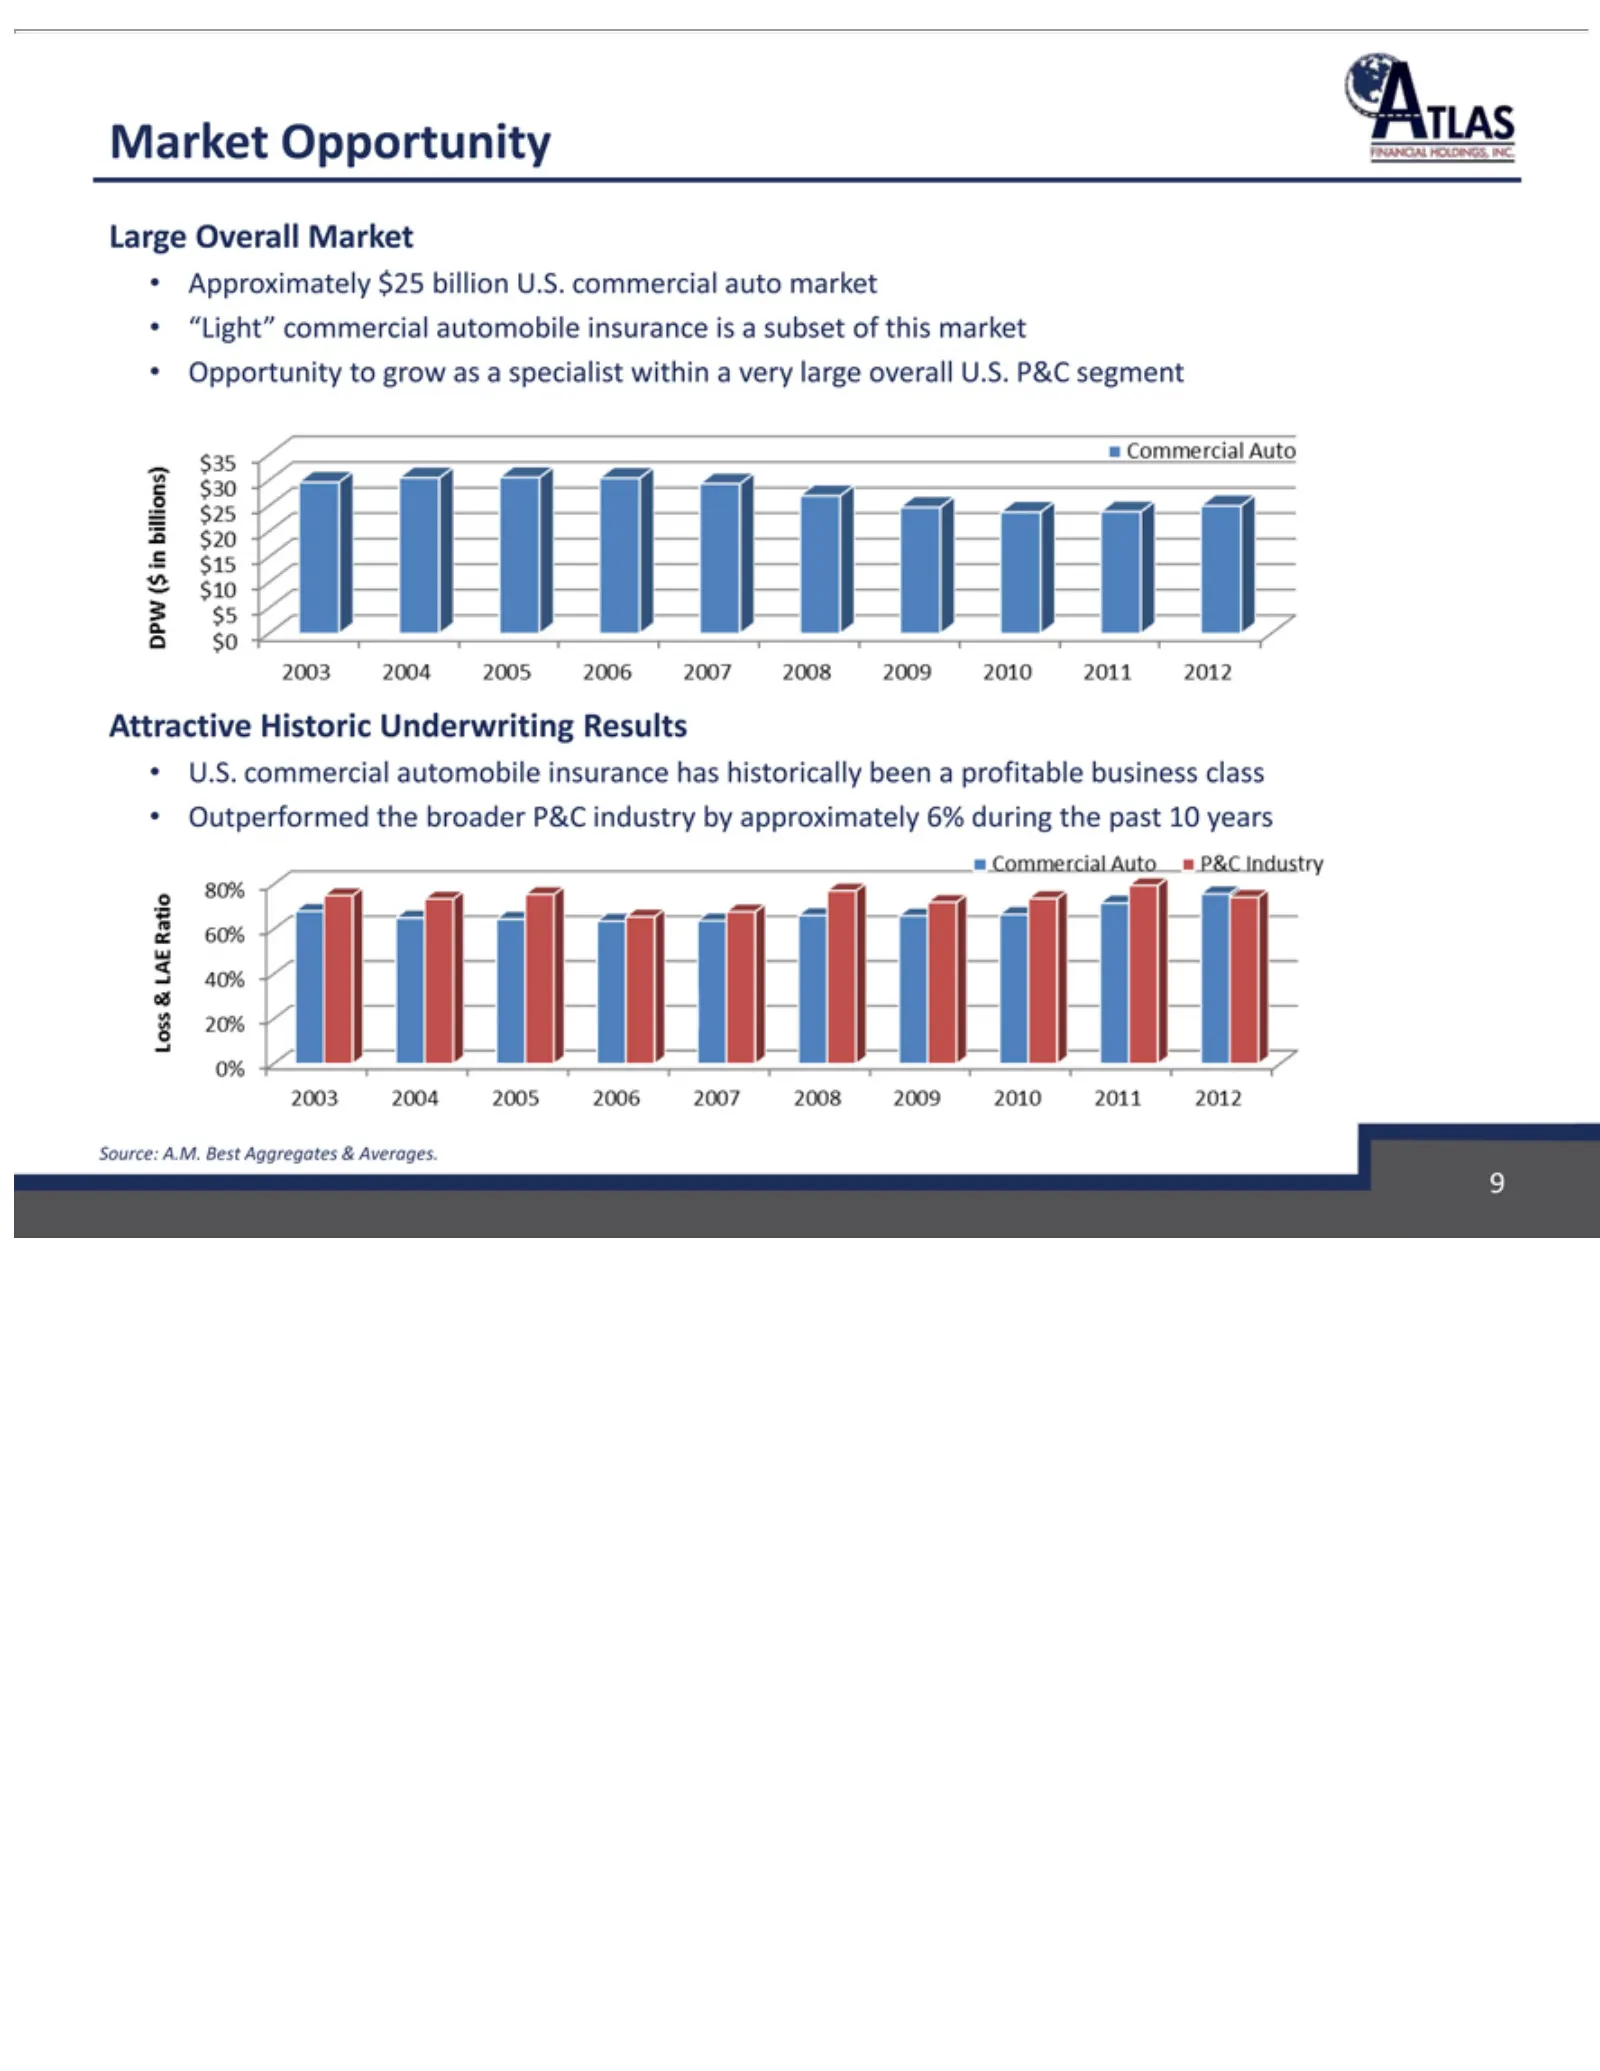
Slide 9: Large Market Opportunity
Market Large Approximately “Light” Opportunity DPW $0 Attractive U.S. Outperformed Loss 0% 2003 Commercial 9Source: $5 20% commercial & 2004 ($ $10 Overall Opportunity LAE A.M. commercial in 40% Historic $15 2005 billions) Auto to Ratio Best 60% Market the $20 grow $25 2006 automobile broader P&C Ag
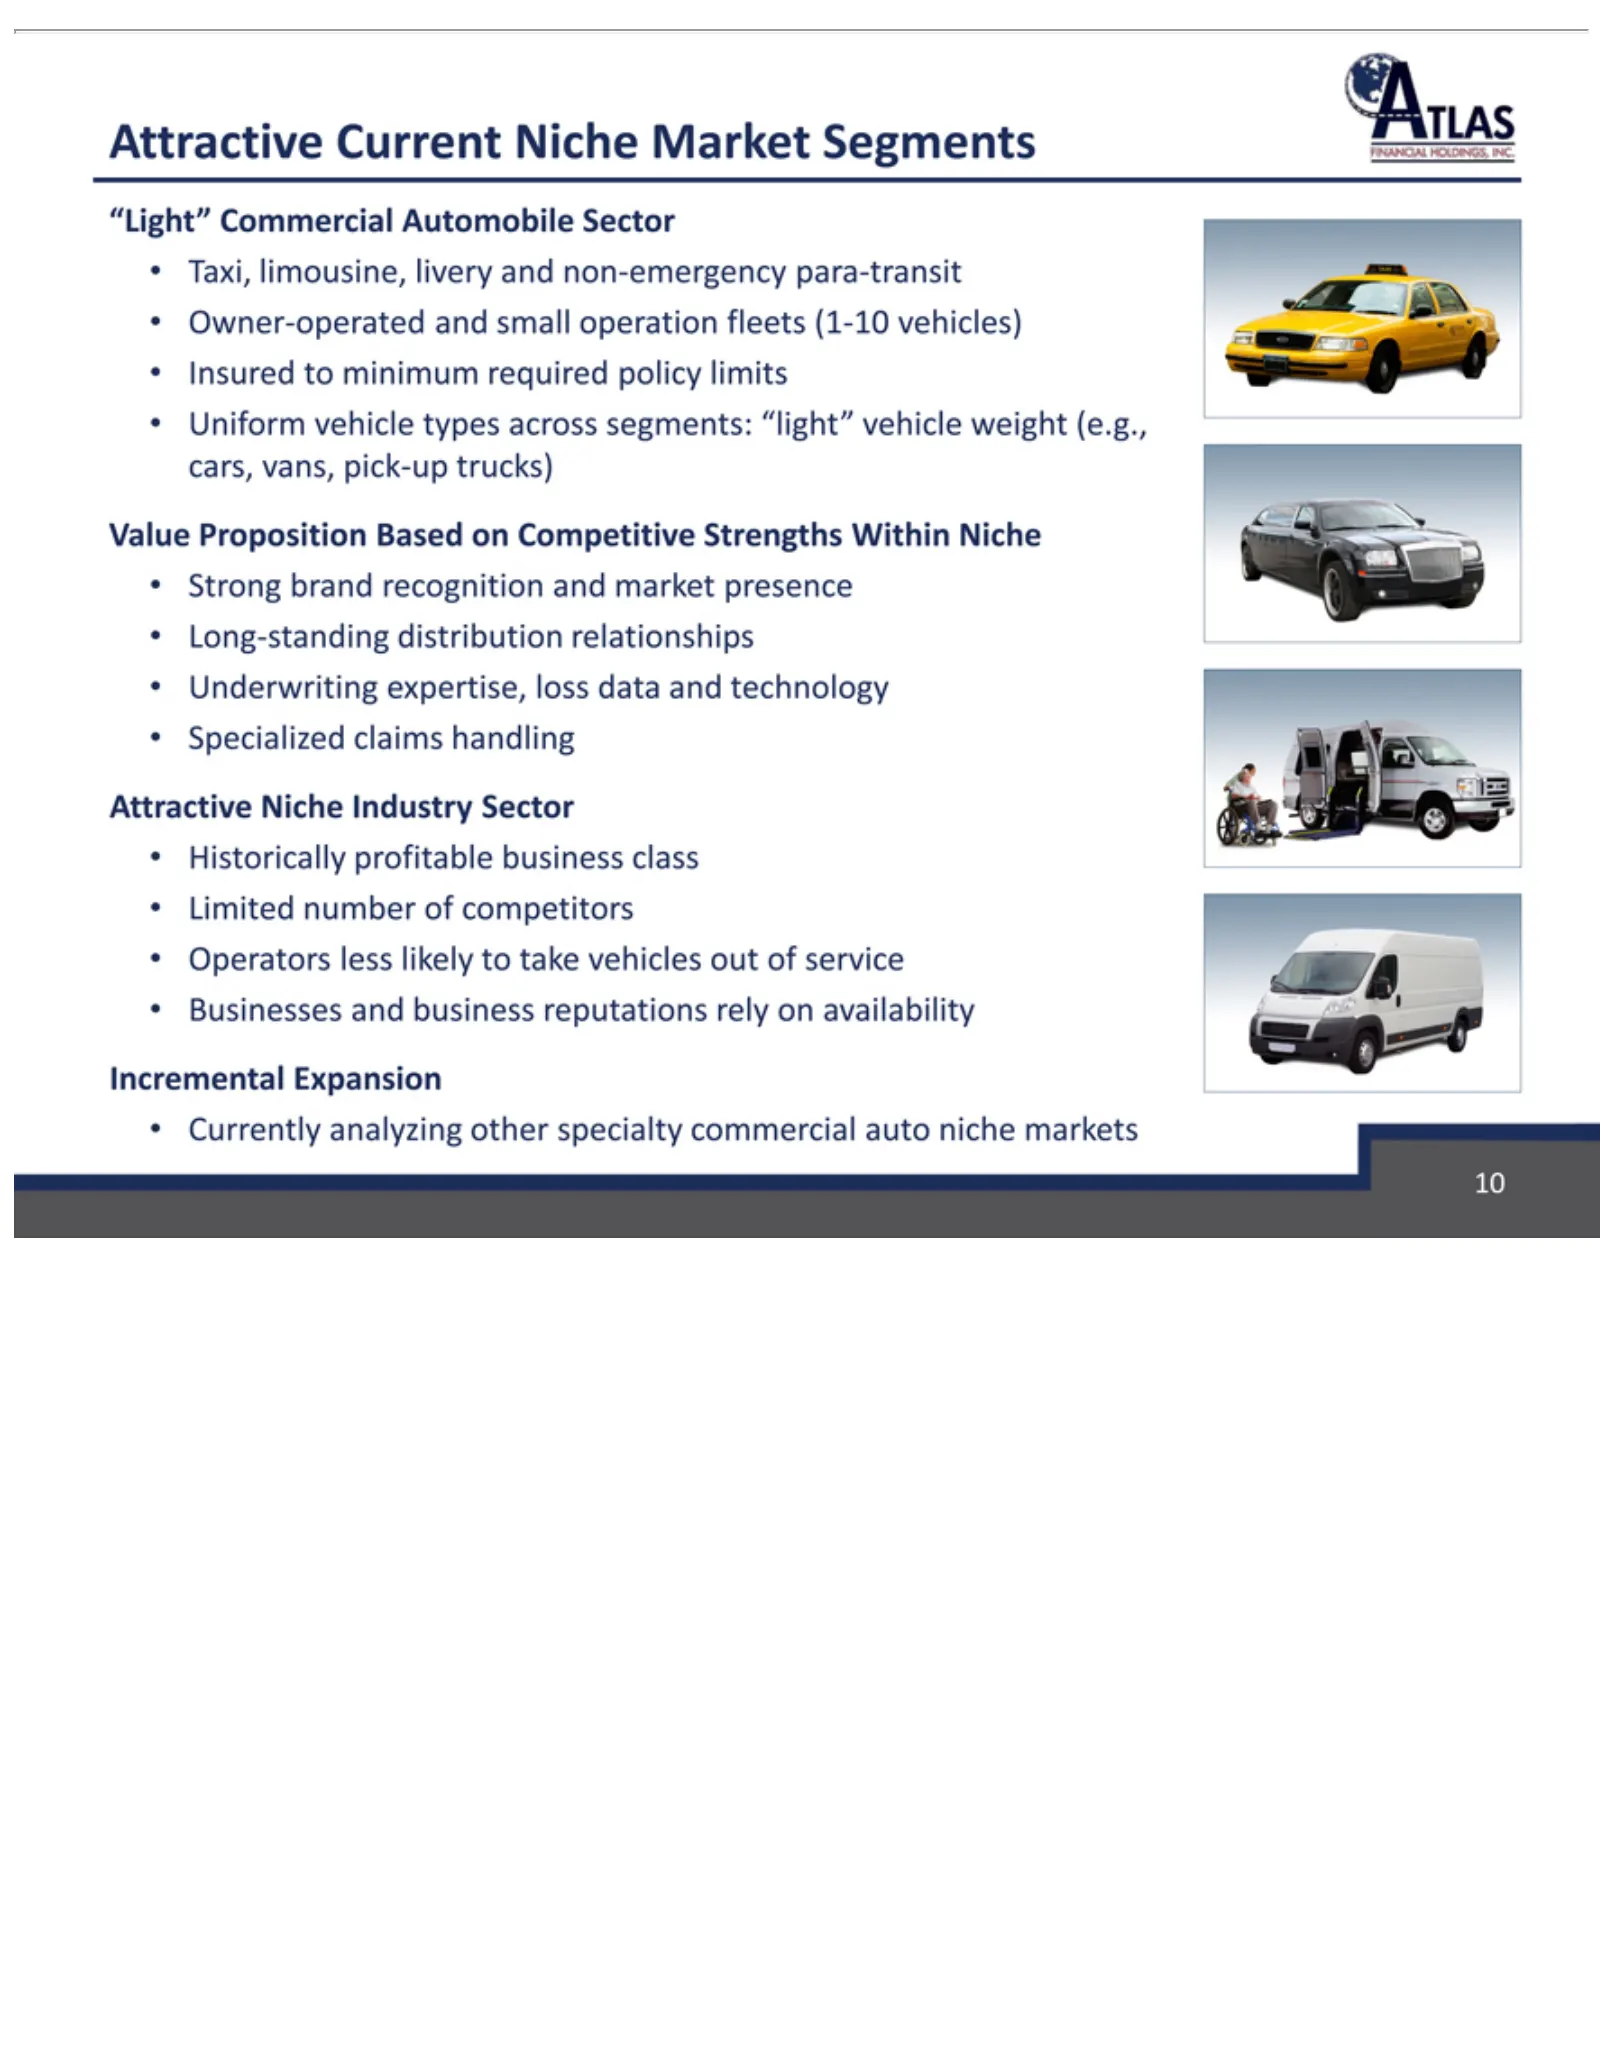
Slide 10: Niche Market Segments and Competitive Strengths
“Light” Taxi, Owner-operated Insured Uniform Value Strong Long-standing Underwriting Specialized Attractive Historically Limited Operators Businesses Incremental Currently 10 limousine, Proposition brand to Commercial number vehicle analyzing less Current Niche minimum and claims profitable Expansio
Slide 11: Distribution Strength and Brand Recognition
Distribution In-force Volume Strong Accelerates American Gateway Diversified 2-5 Focus Significant –Discontinued 11Florida MGA Private strategic on Distribution Brand insurance of business Insurance passenger personal Specialty Country: Service: applications marketing Agent development Channel “corn
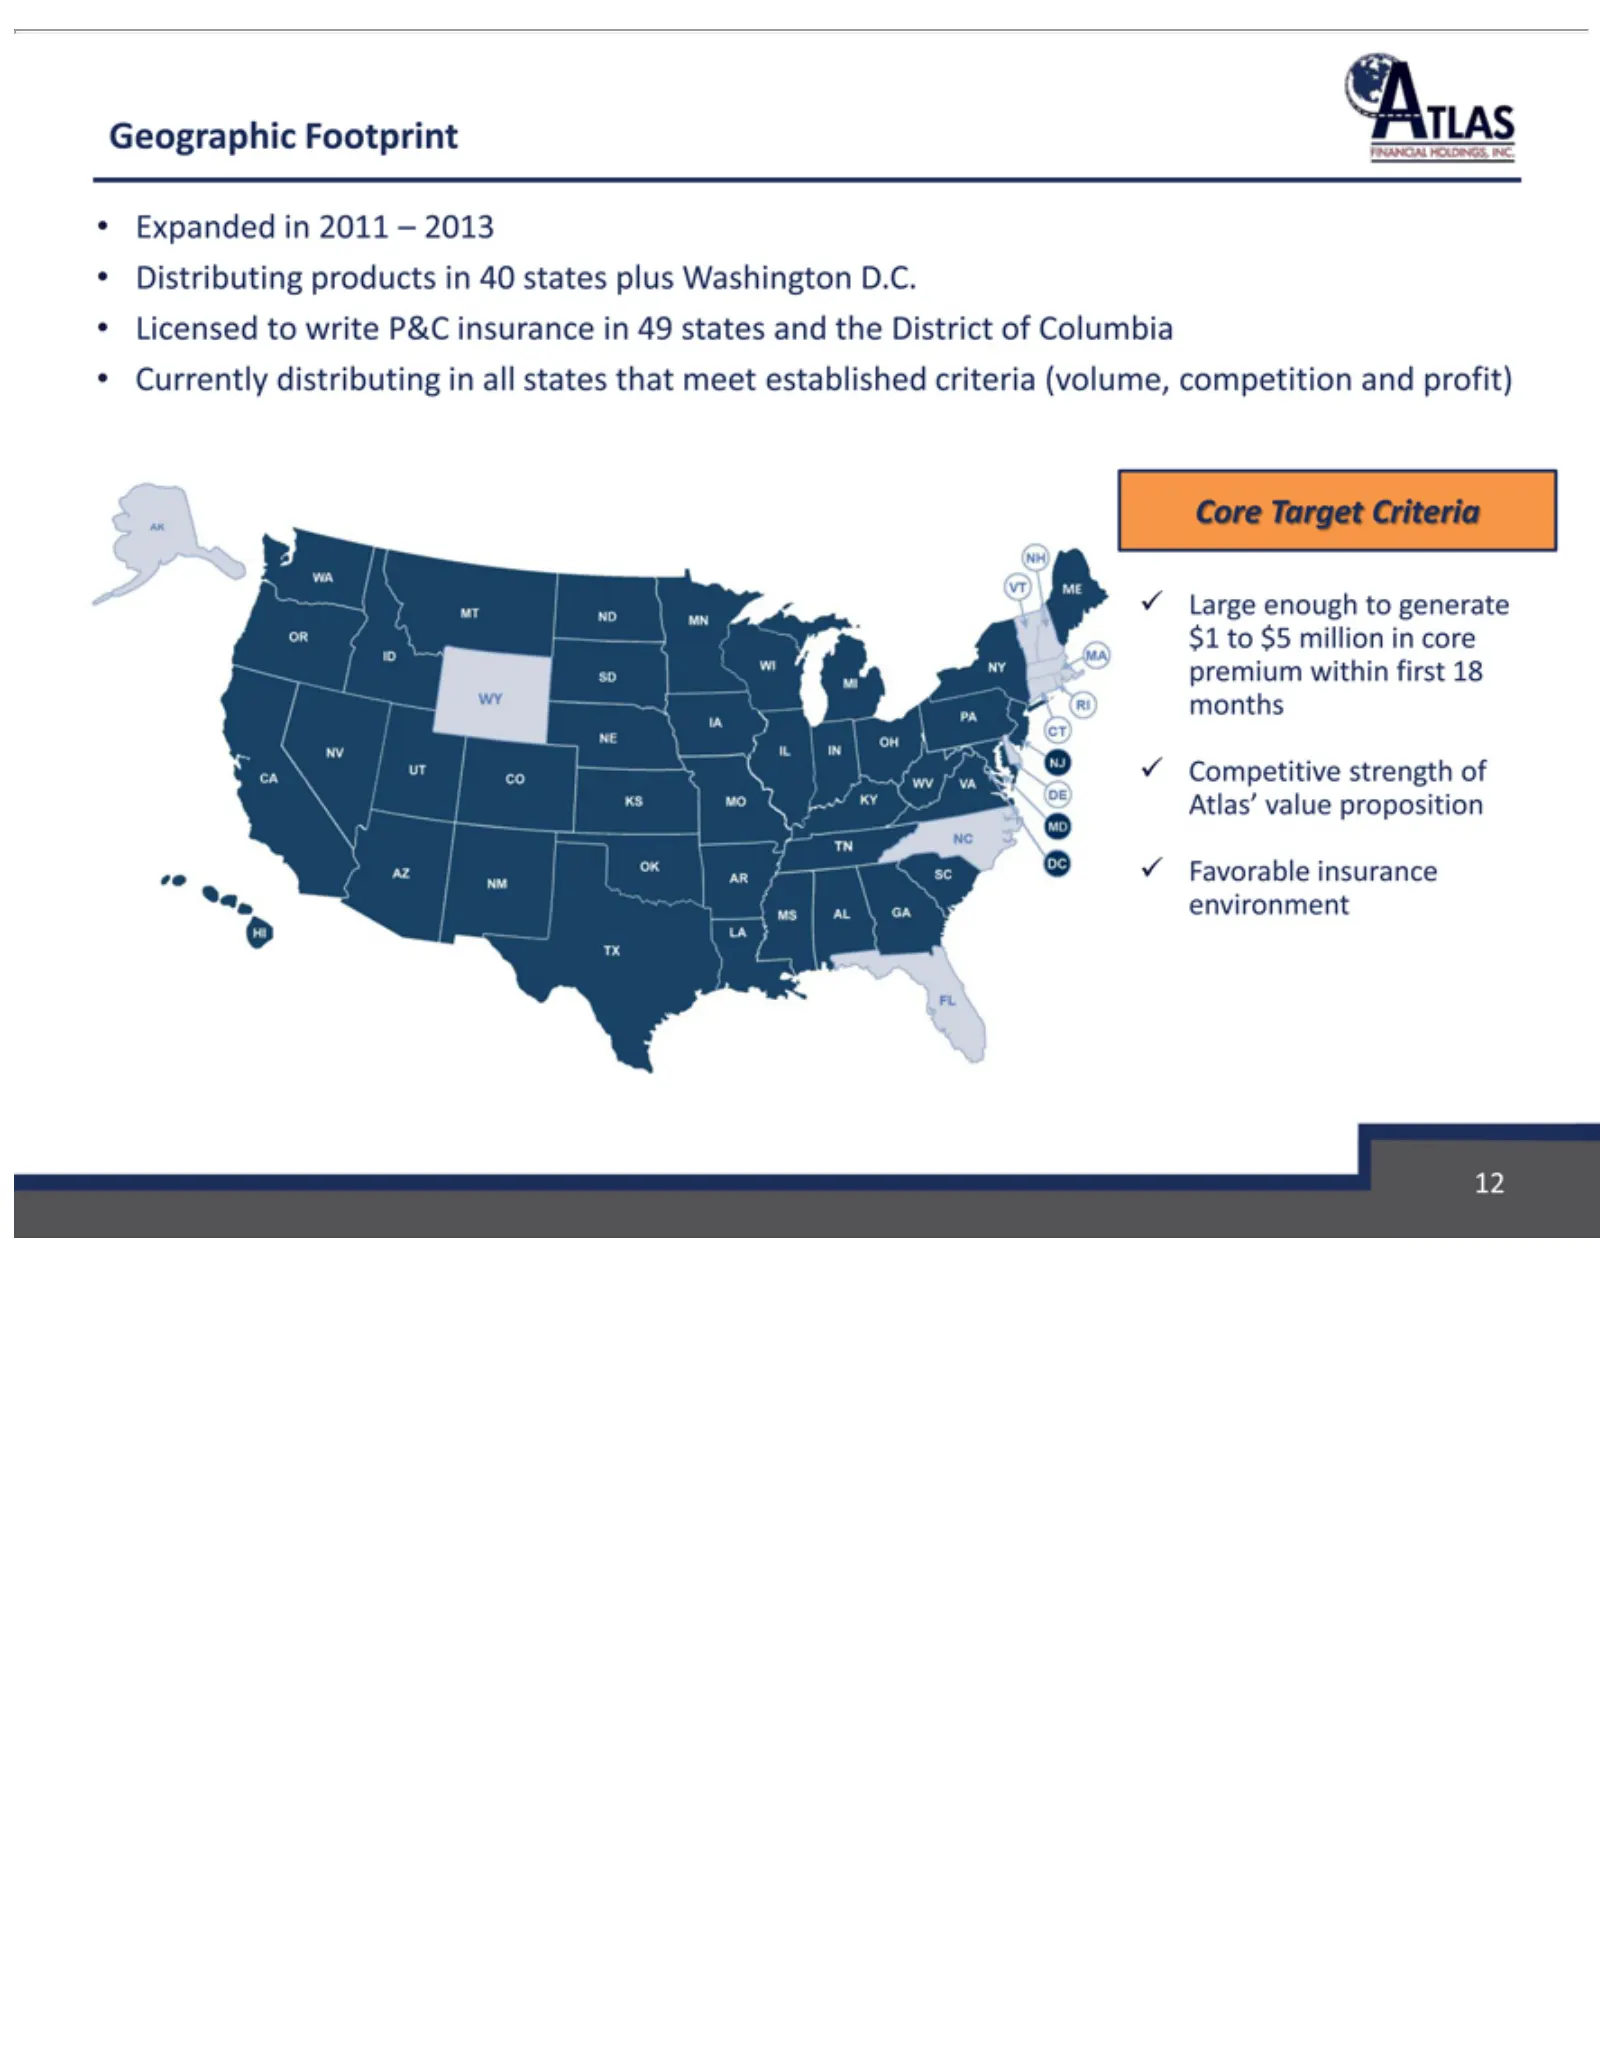
Slide 12: Expanded Geographic Footprint
Geographic Expanded Distributing Licensed Currently Core Large 12 Target enough to distributing inwrite Footprint Criteria products 2011 to generate P&C – 2013 in ininsurance 40 all $1states states to $5in plus that million 49Washington meet states inestablished core and the premium D.C. District cr
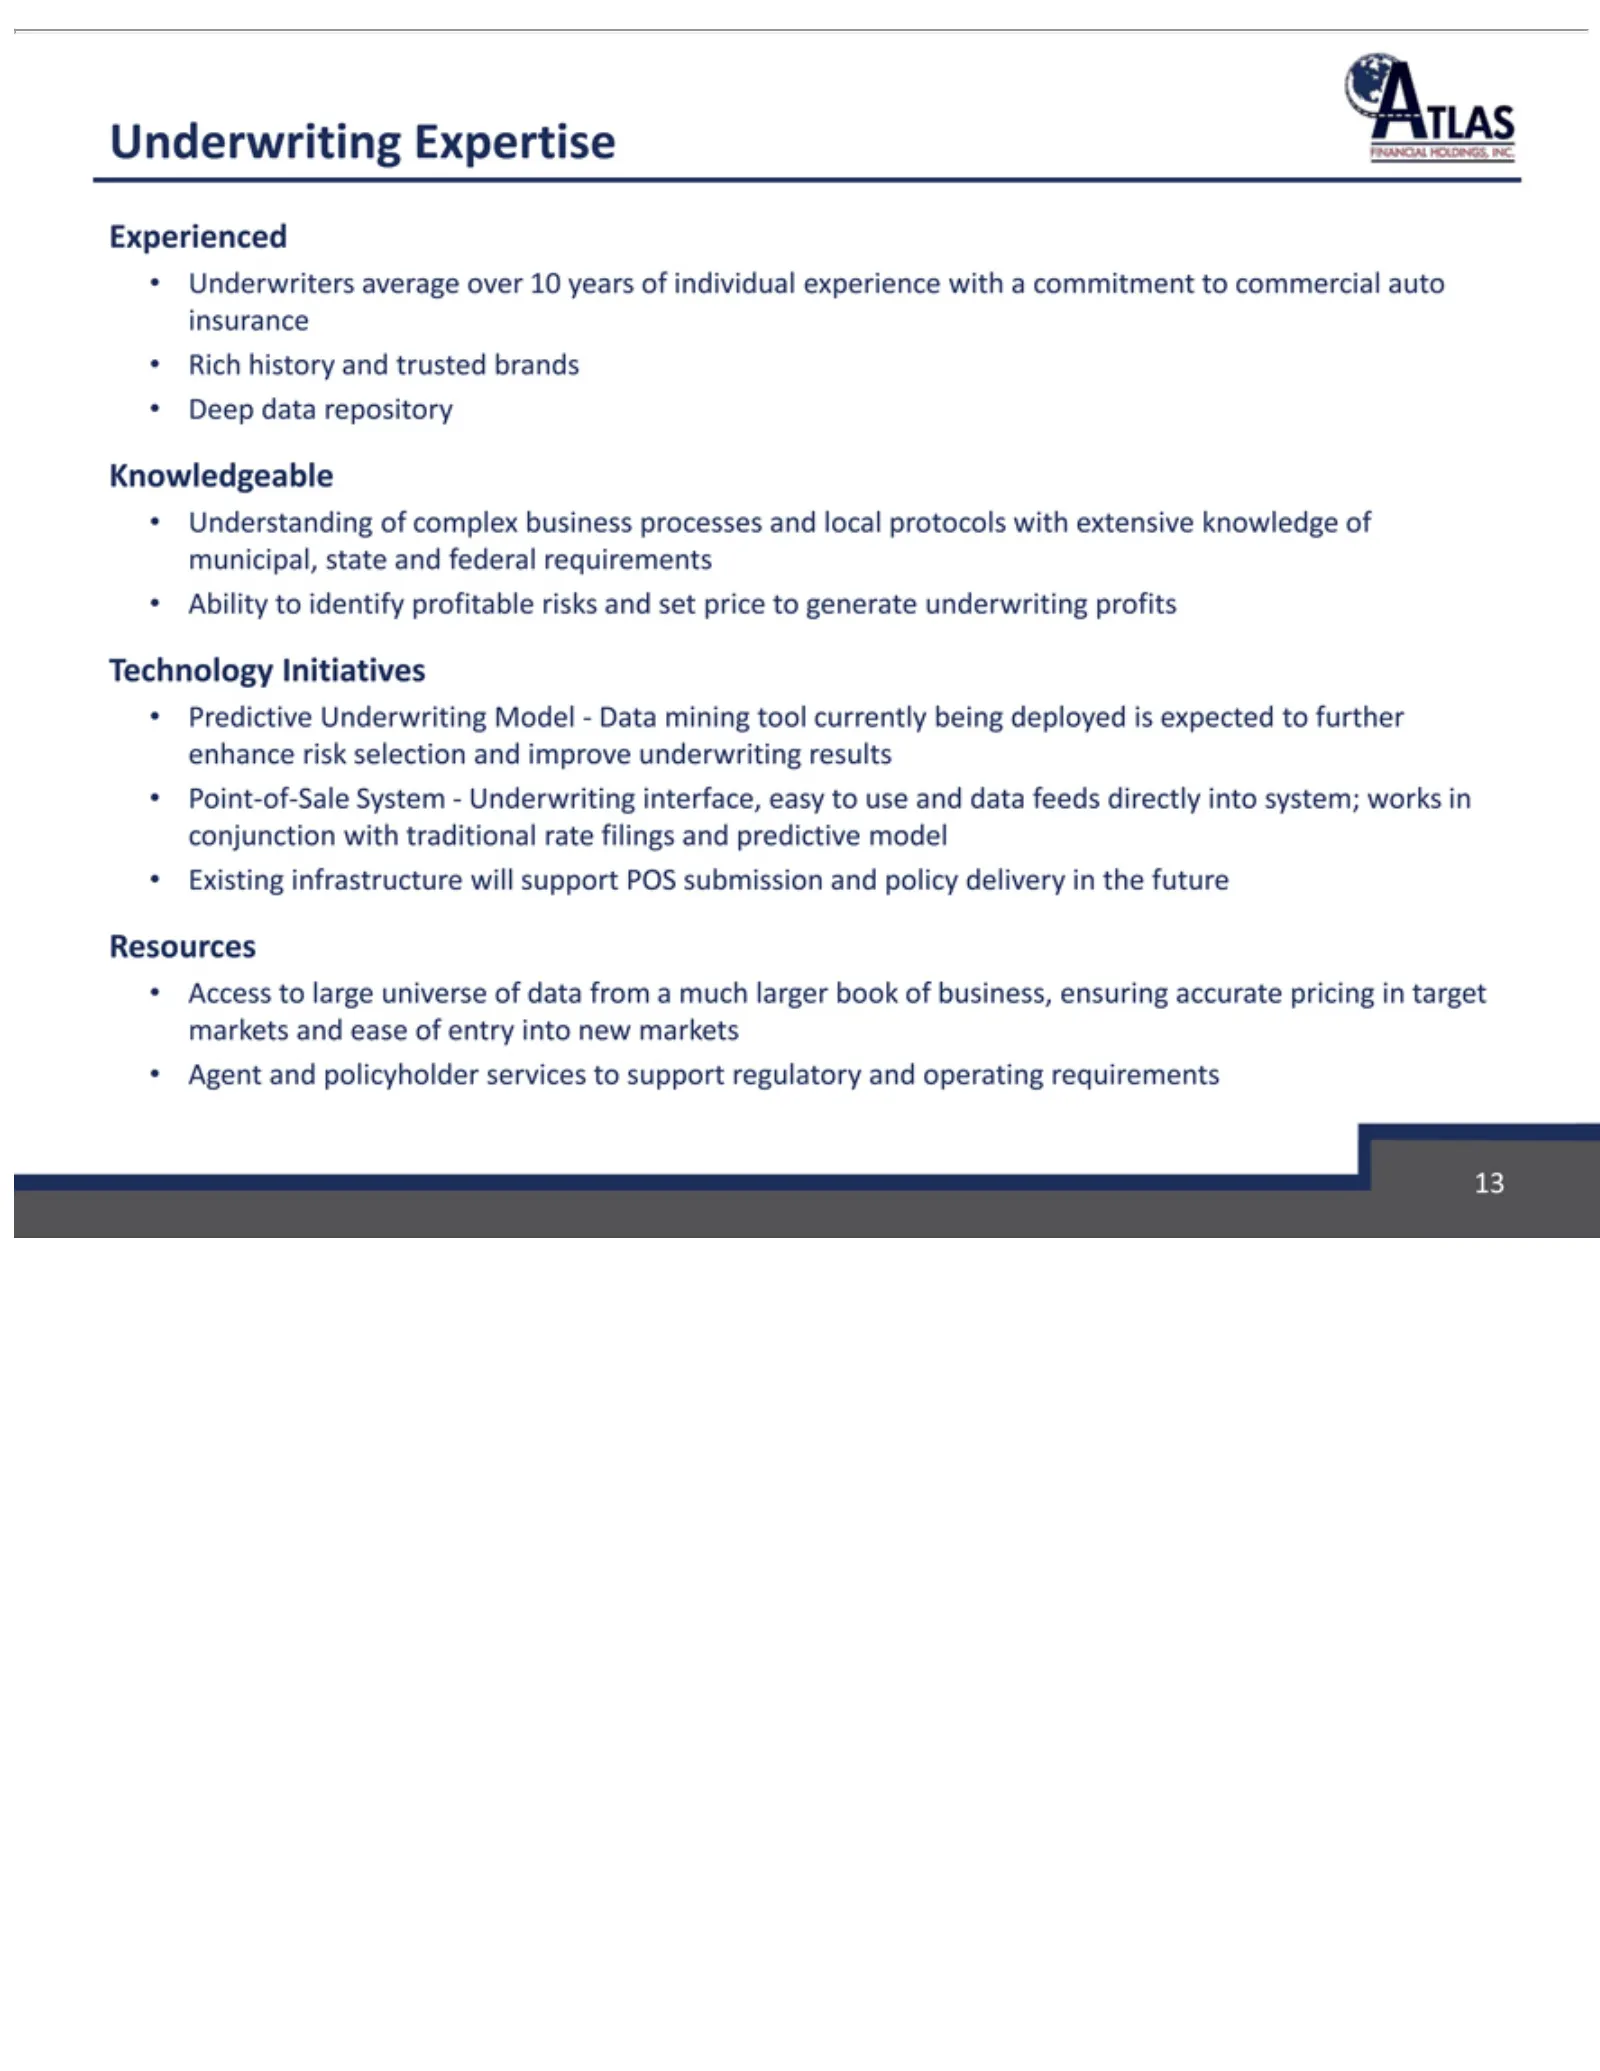
Slide 13: Underwriting Expertise and Technology
Underwriting Underwriters Experienced Rich Deep Understanding Knowledgeable Ability Technology Predictive Point-of-Sale Existing Access Resources Agent 13 history data and toinfrastructure large identify repository Underwriting policyholder Initiatives and average System Expertise of universe truste
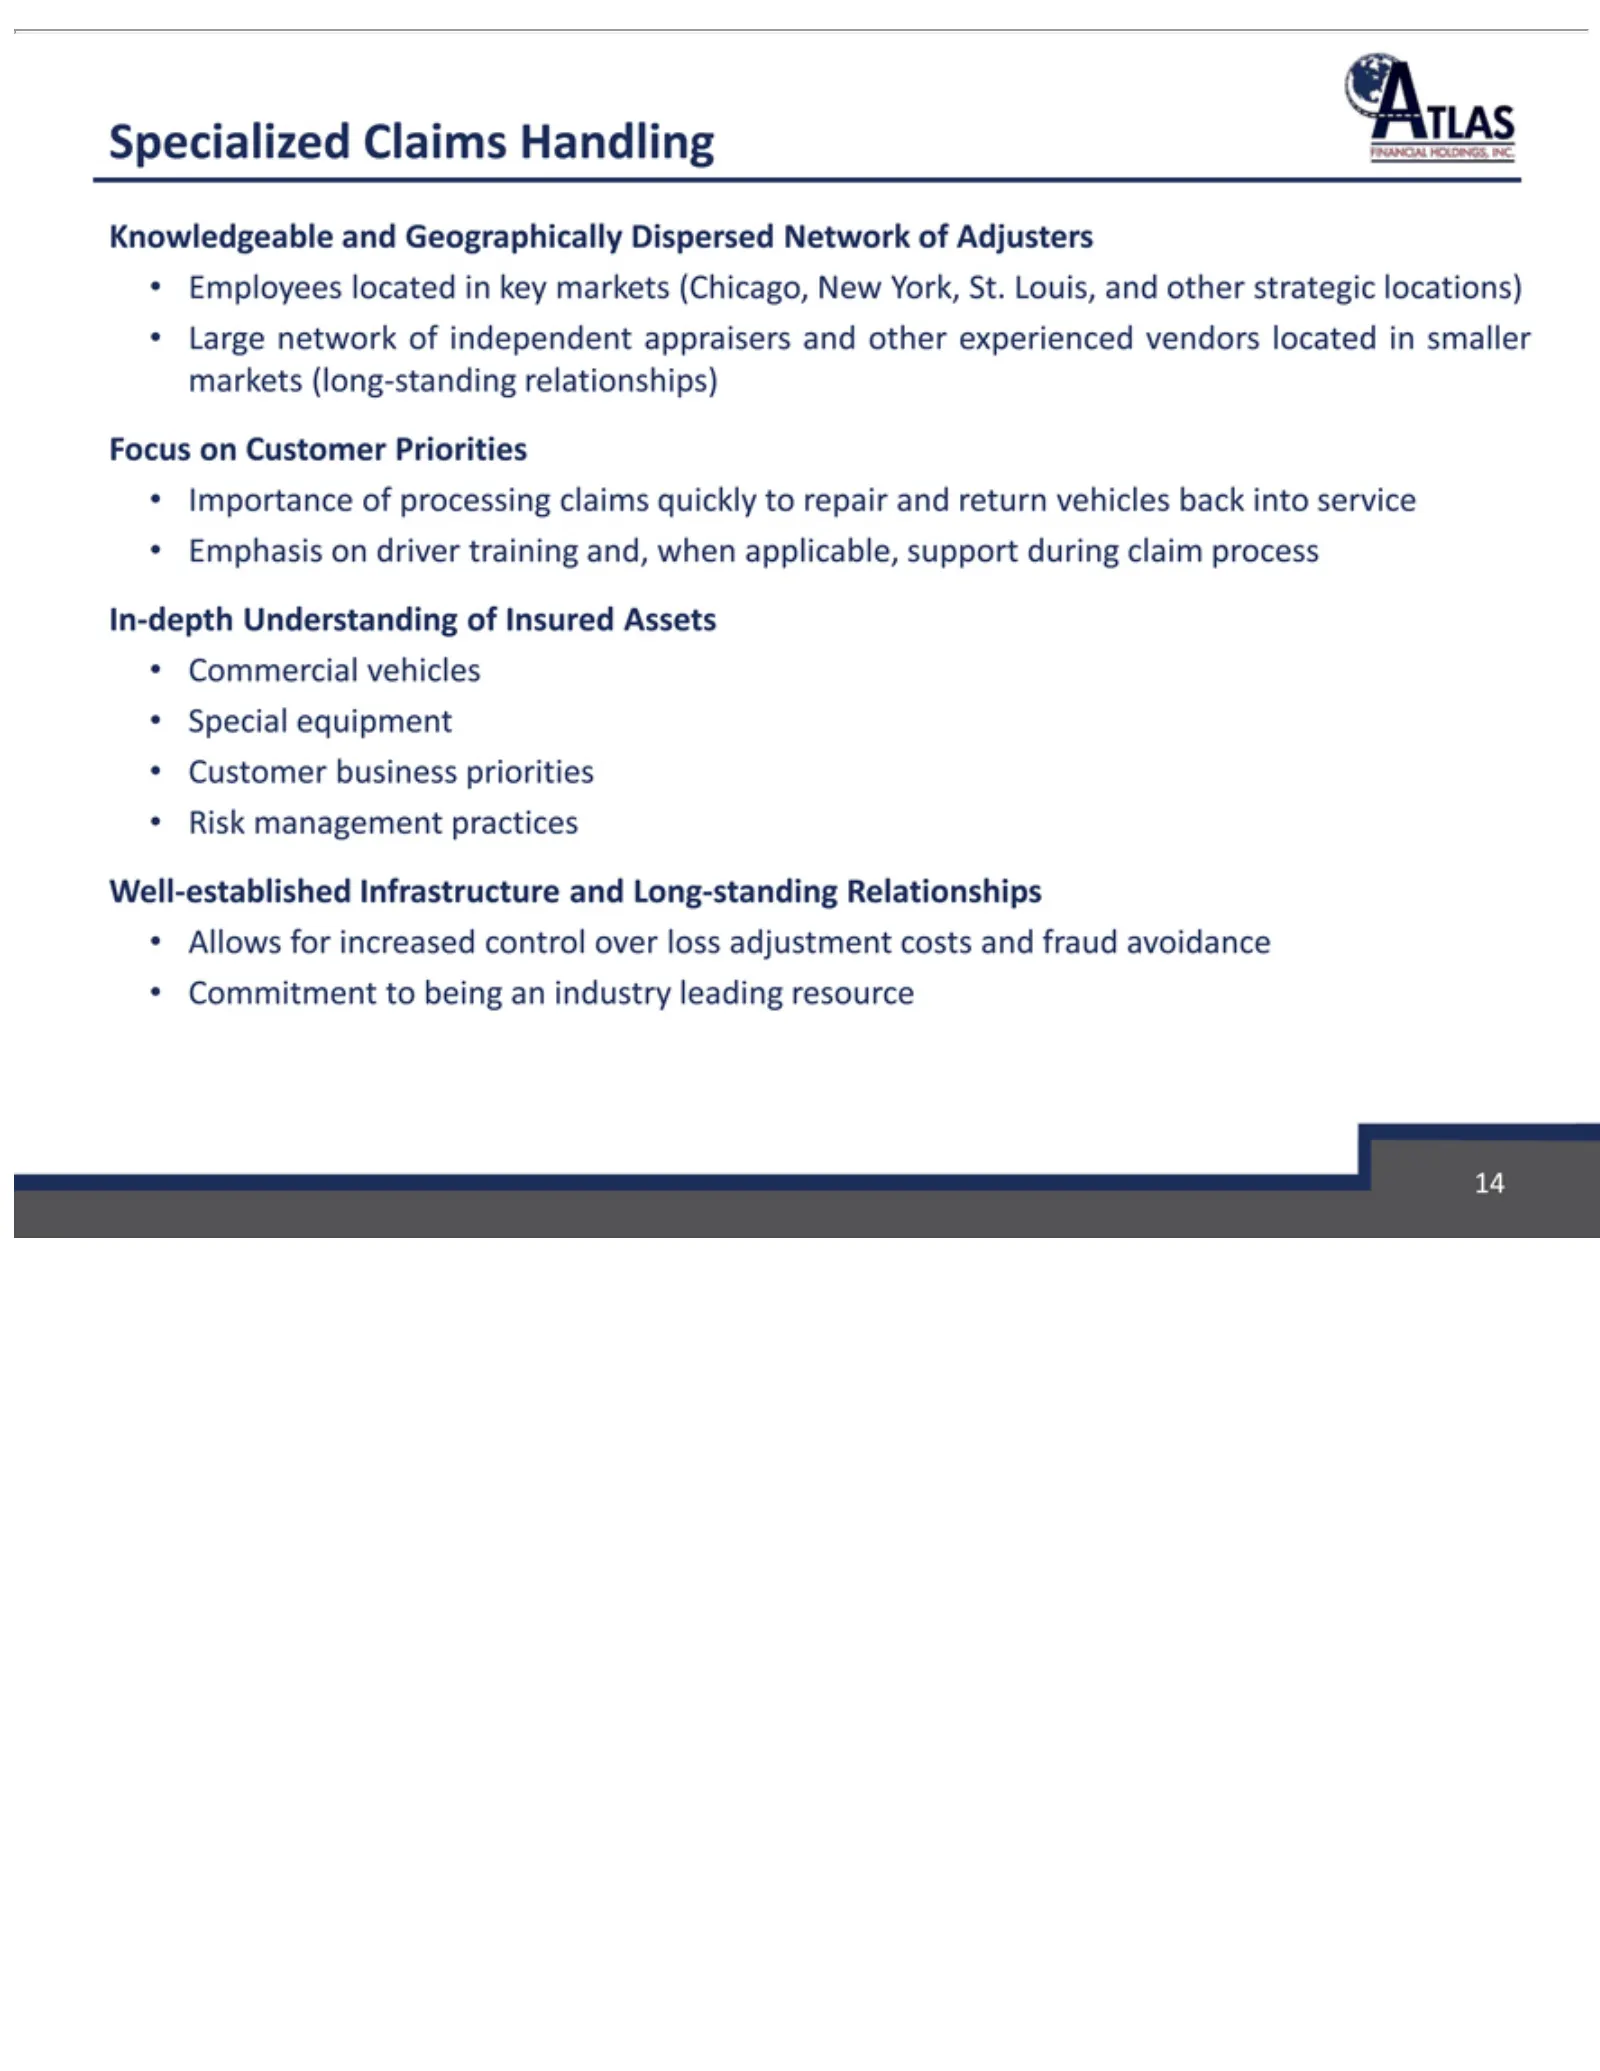
Slide 14: Specialized Claims Handling and Knowledgeable Employees
Specialized Knowledgeable Employees Large Focus Importance Emphasis In-depth Commercial Special Customer Risk Well-established Allows Commitment 14 management network onfor equipment Understanding Customer on business increased located of Claims vehicles driver toprocessing ofand being Infrastructur
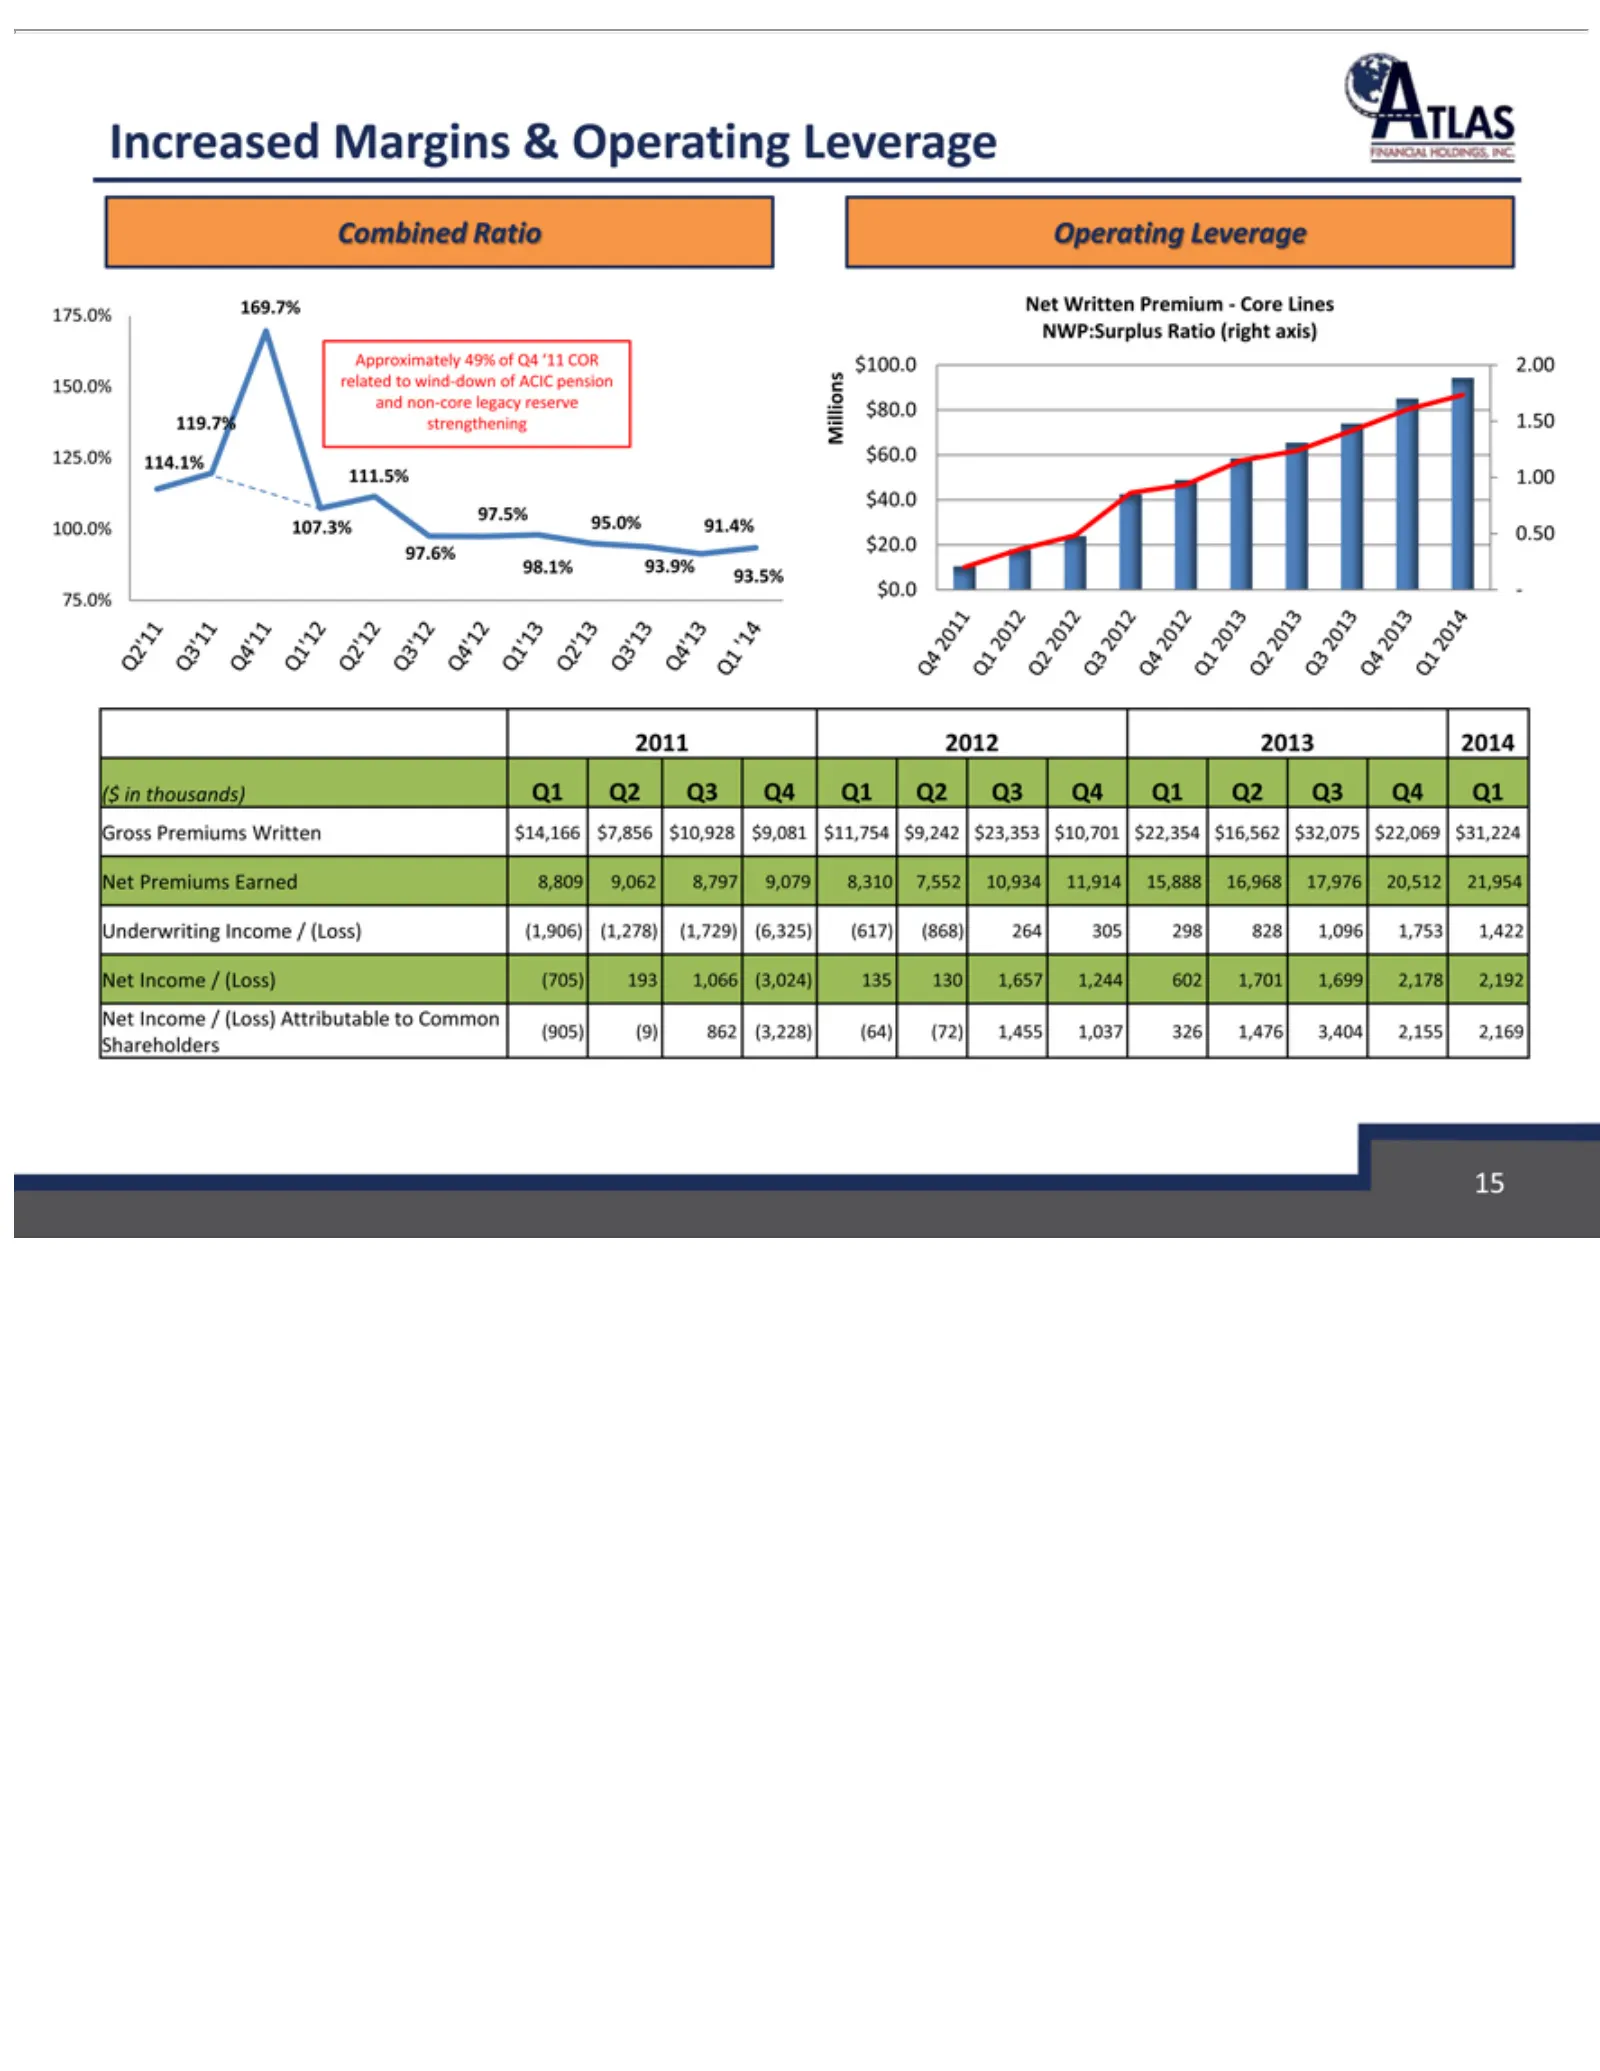
Slide 15: Increased Premiums and Improved Combined Ratio
Increased Combined 175.0% Approximately 125.0% 97.5% 100.0% Q2’11 75.0% Operating Millions 1.00 0.50 $0.0 Q4 2011 ($ Gross Underwriting Net Shareholders 15 in2011 Written Premiums Income $40.0 -$20.0 thousands) 2012 Premiums Q3’11 95.0% 169.7% 114.1% 107.3% 1.50 Q1 Margins Leverage Ratio 2013 Premiu
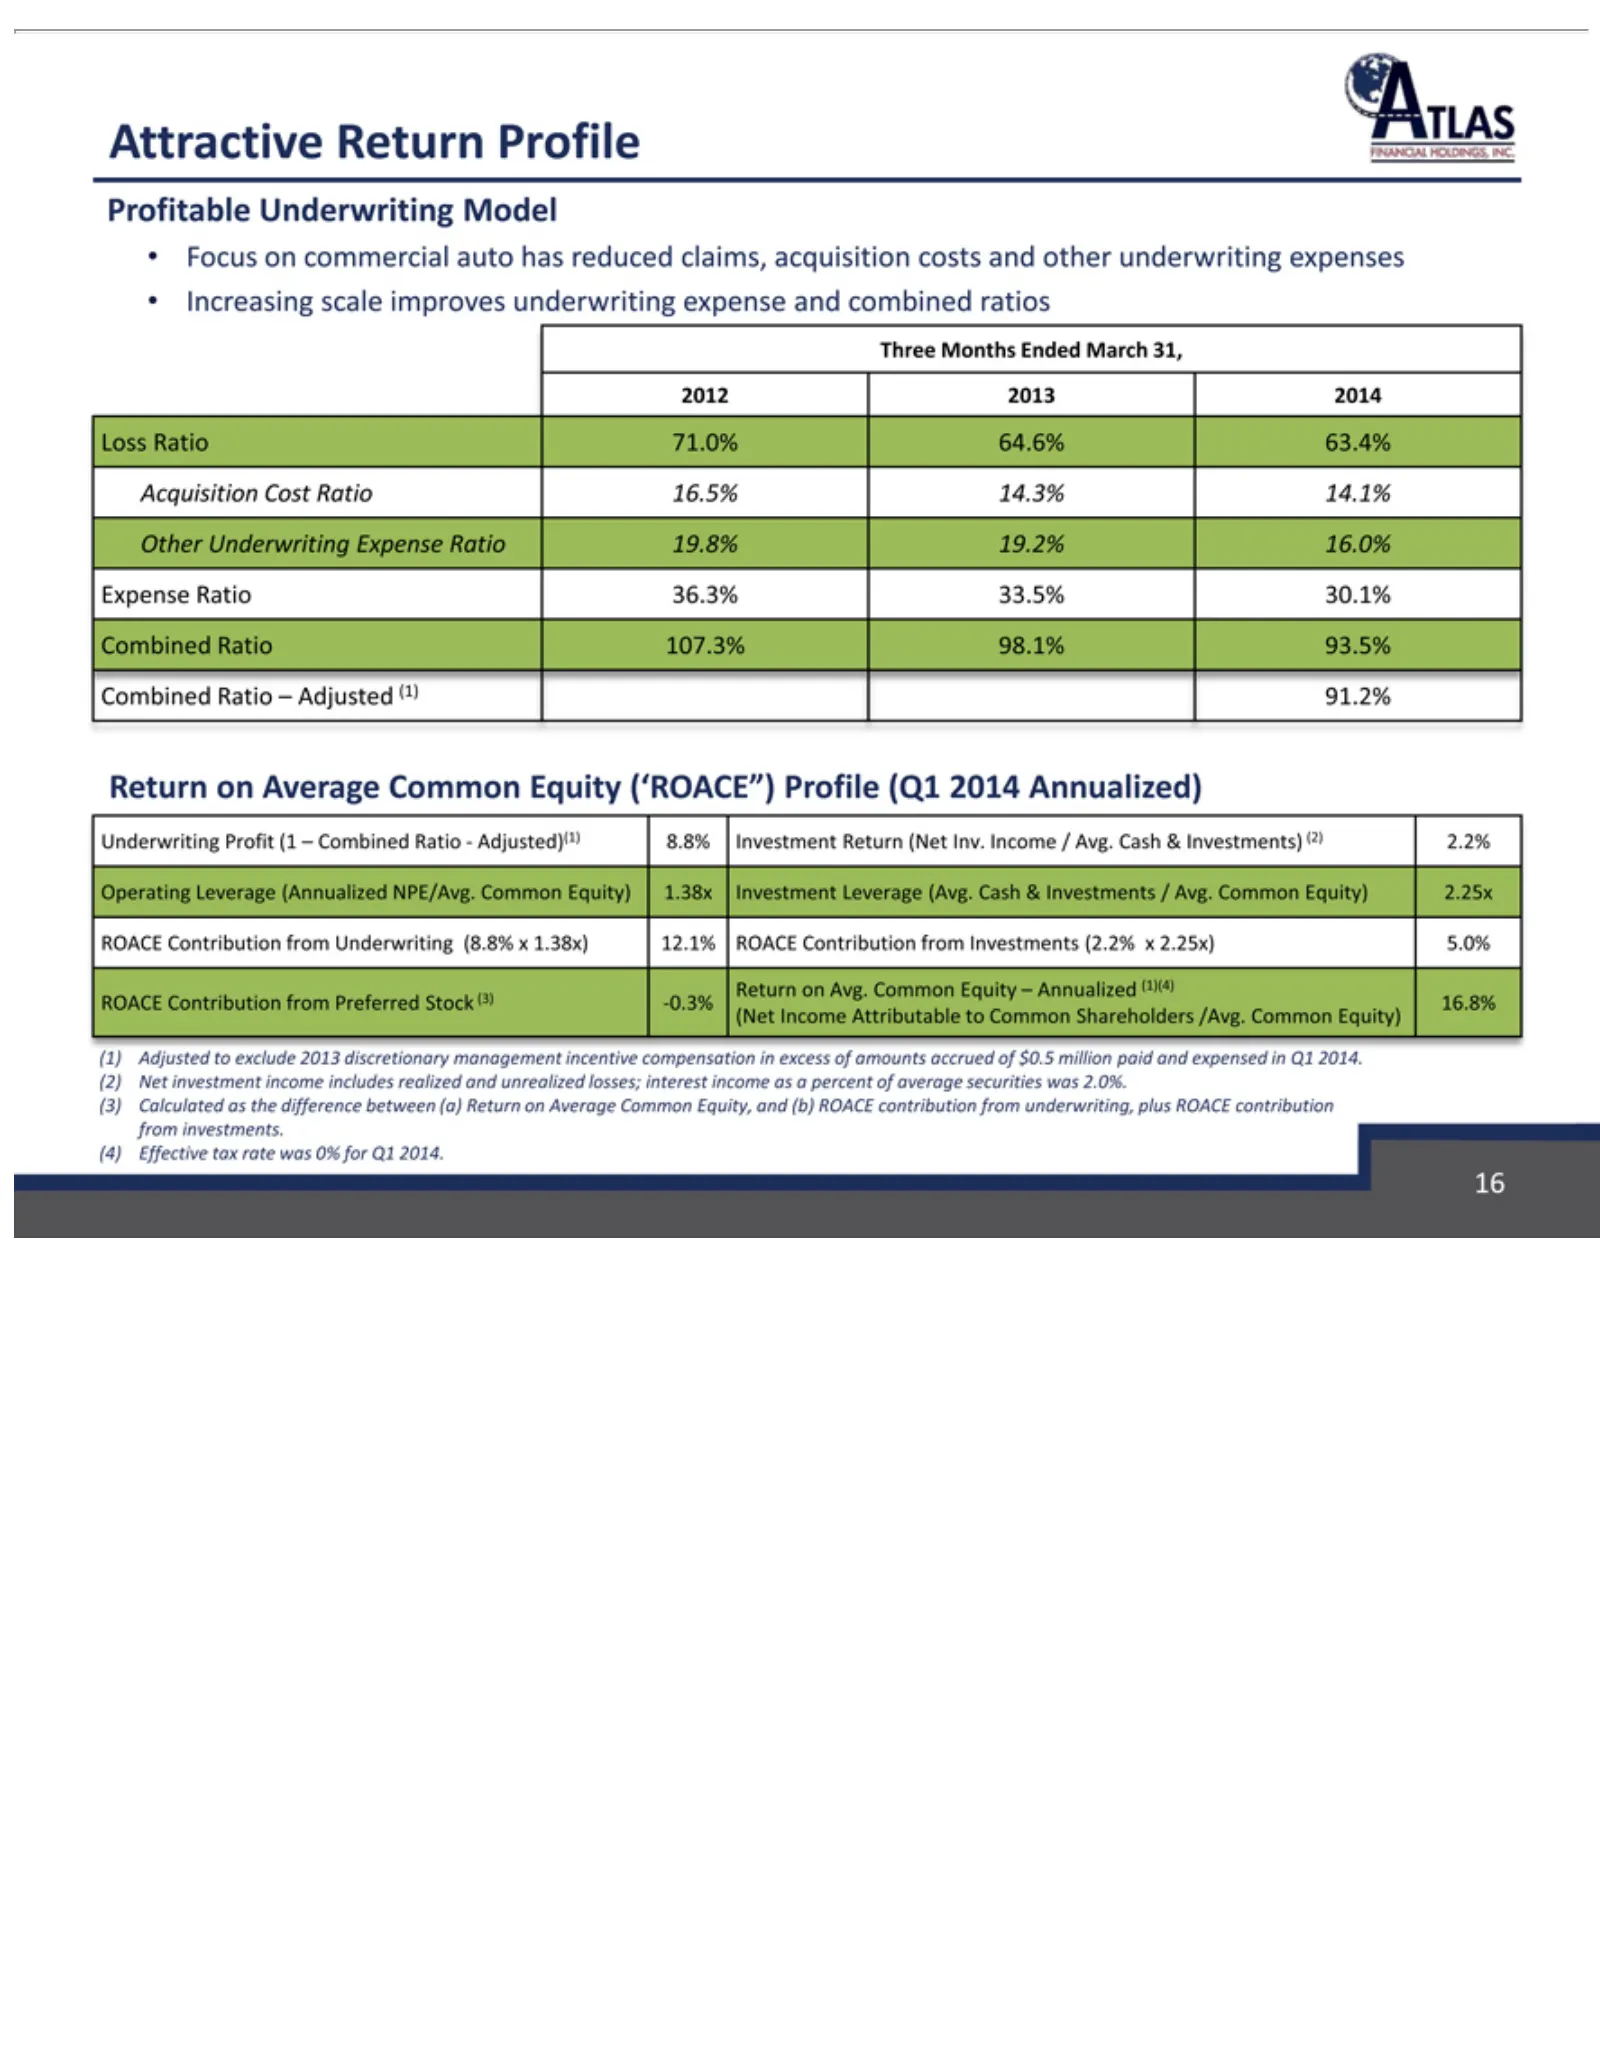
Slide 16: Attractive Profitable Underwriting Model
Attractive Profitable Focus Increasing Three 2012 Loss Acquisition Other Expense Combined Underwriting Operating Return ROACE (Net (1) losses; (3) (4) 16 Adjusted Calculated Effective Income Ratio 2013 Underwriting Months on interest onRatio Contribution commercial Average Avg. Underwriting Return L
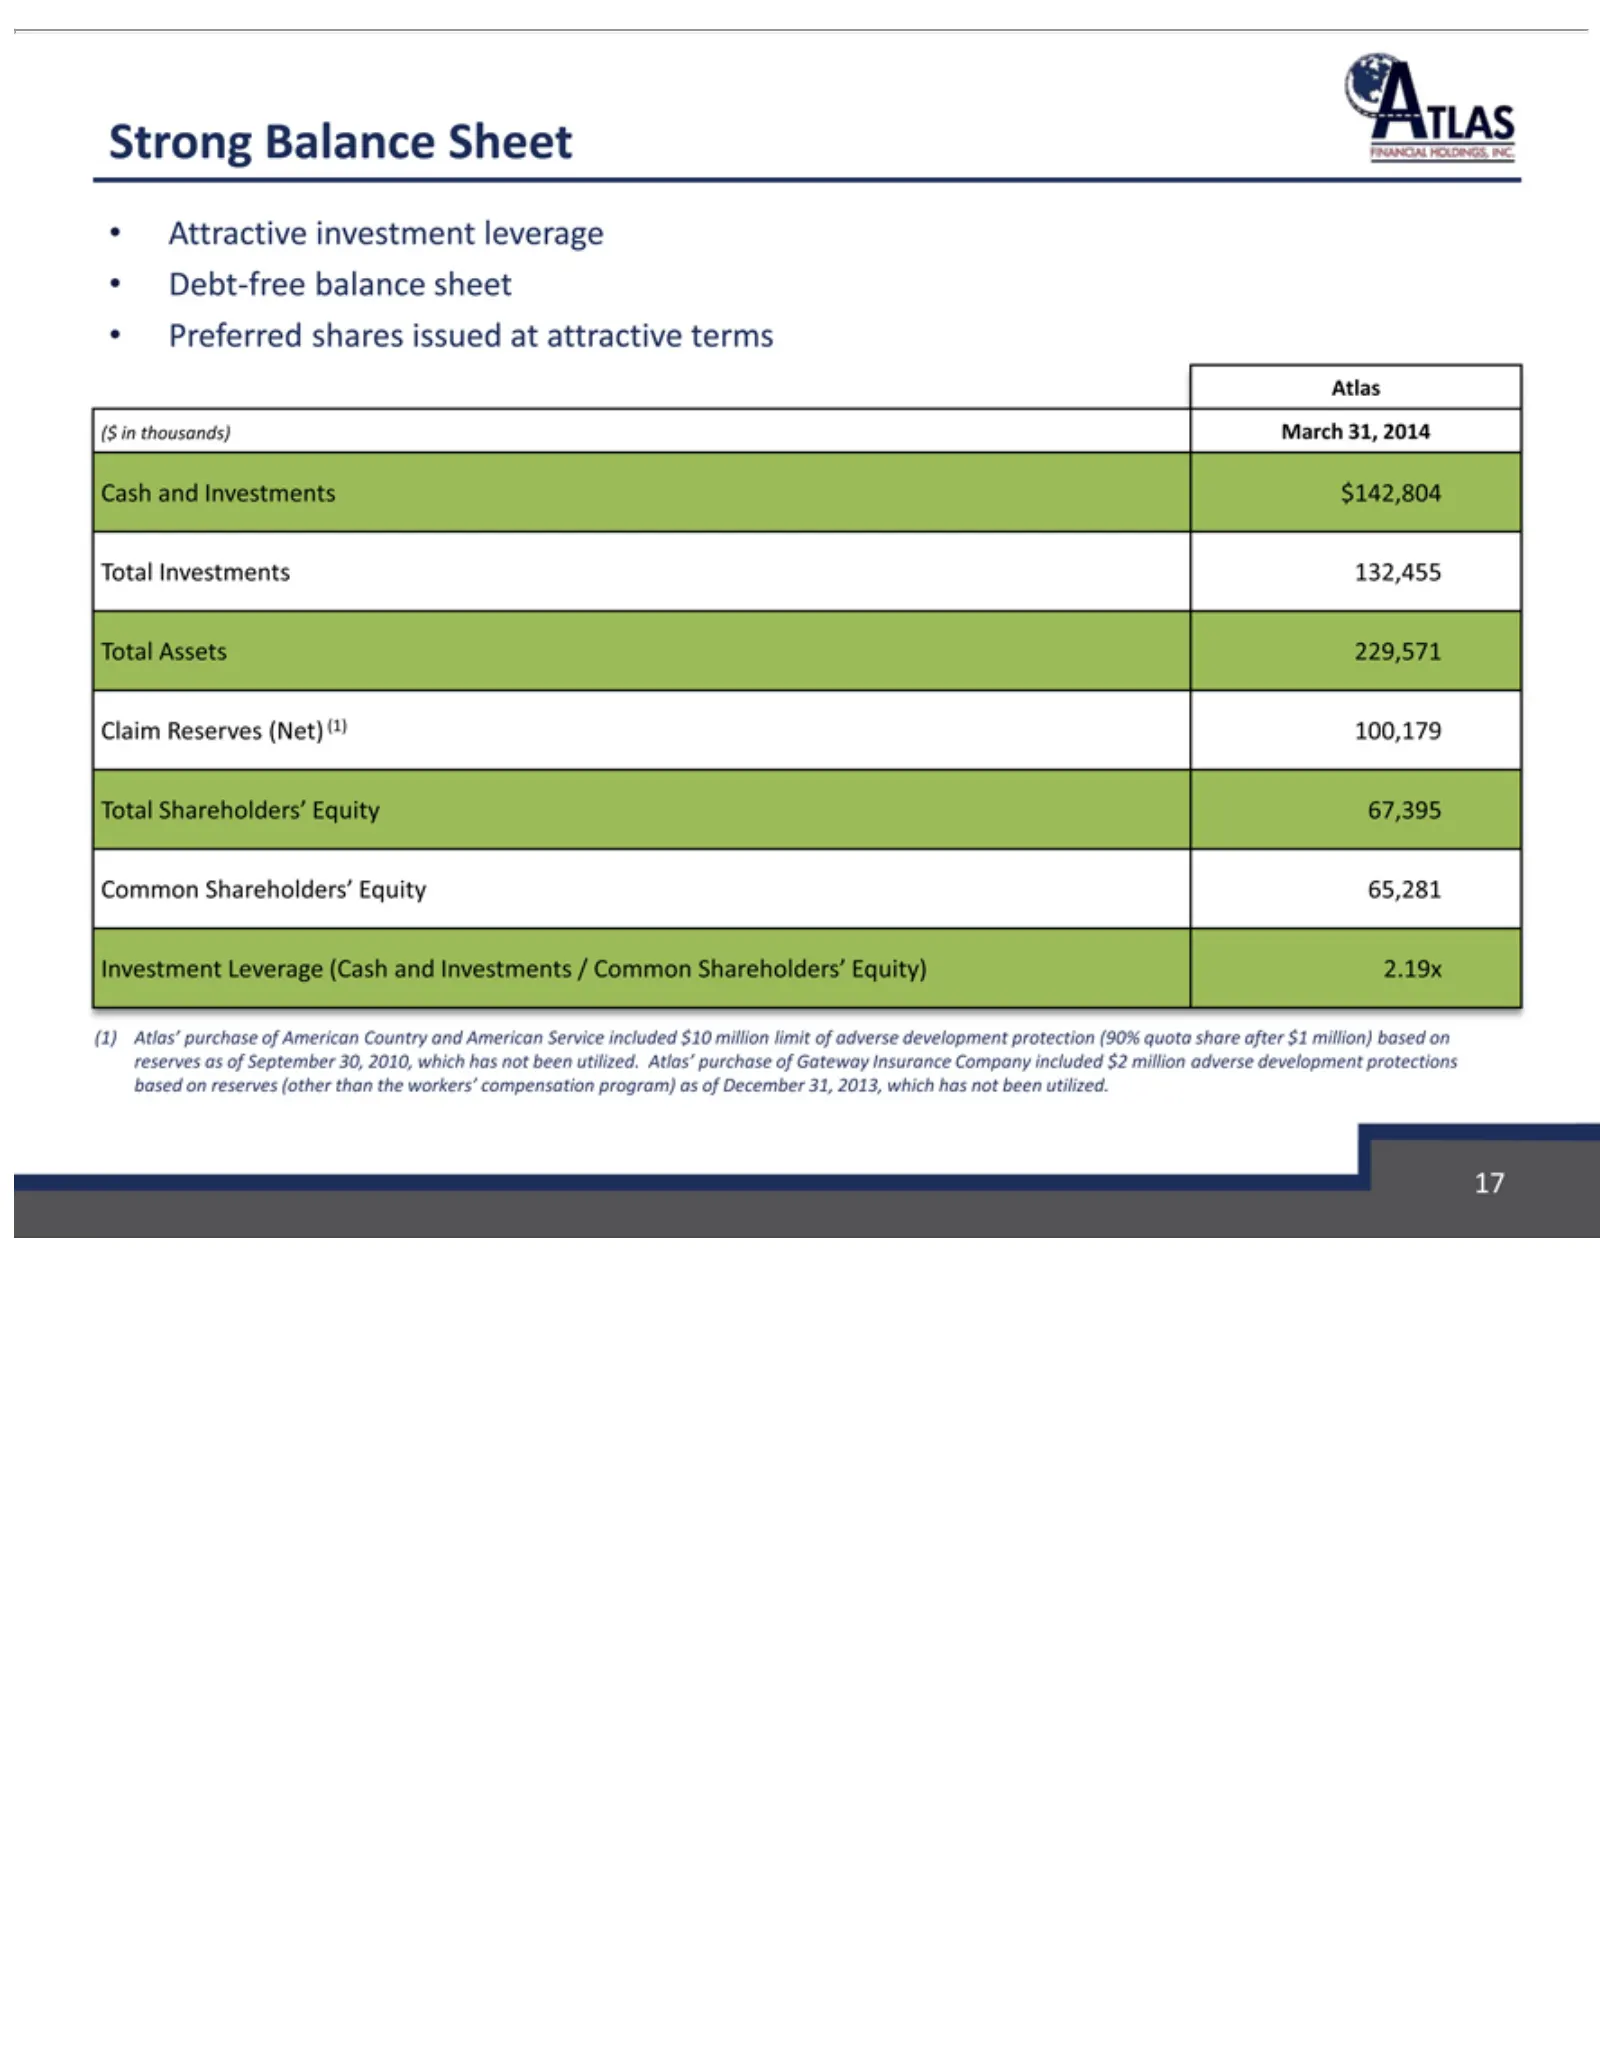
Slide 17: Strong Debt-free Balance Sheet
Strong Attractive Debt-free Preferred ($ Atlas Cash Claim Total Common Investment (1) not which 17 in Atlas’ been thousands) Assets and Investments Shareholders’ has Reserves Balance utilized. Investments shares Shareholders’ purchase balance investment not Leverage 229,571 been Sheet (Net) March is
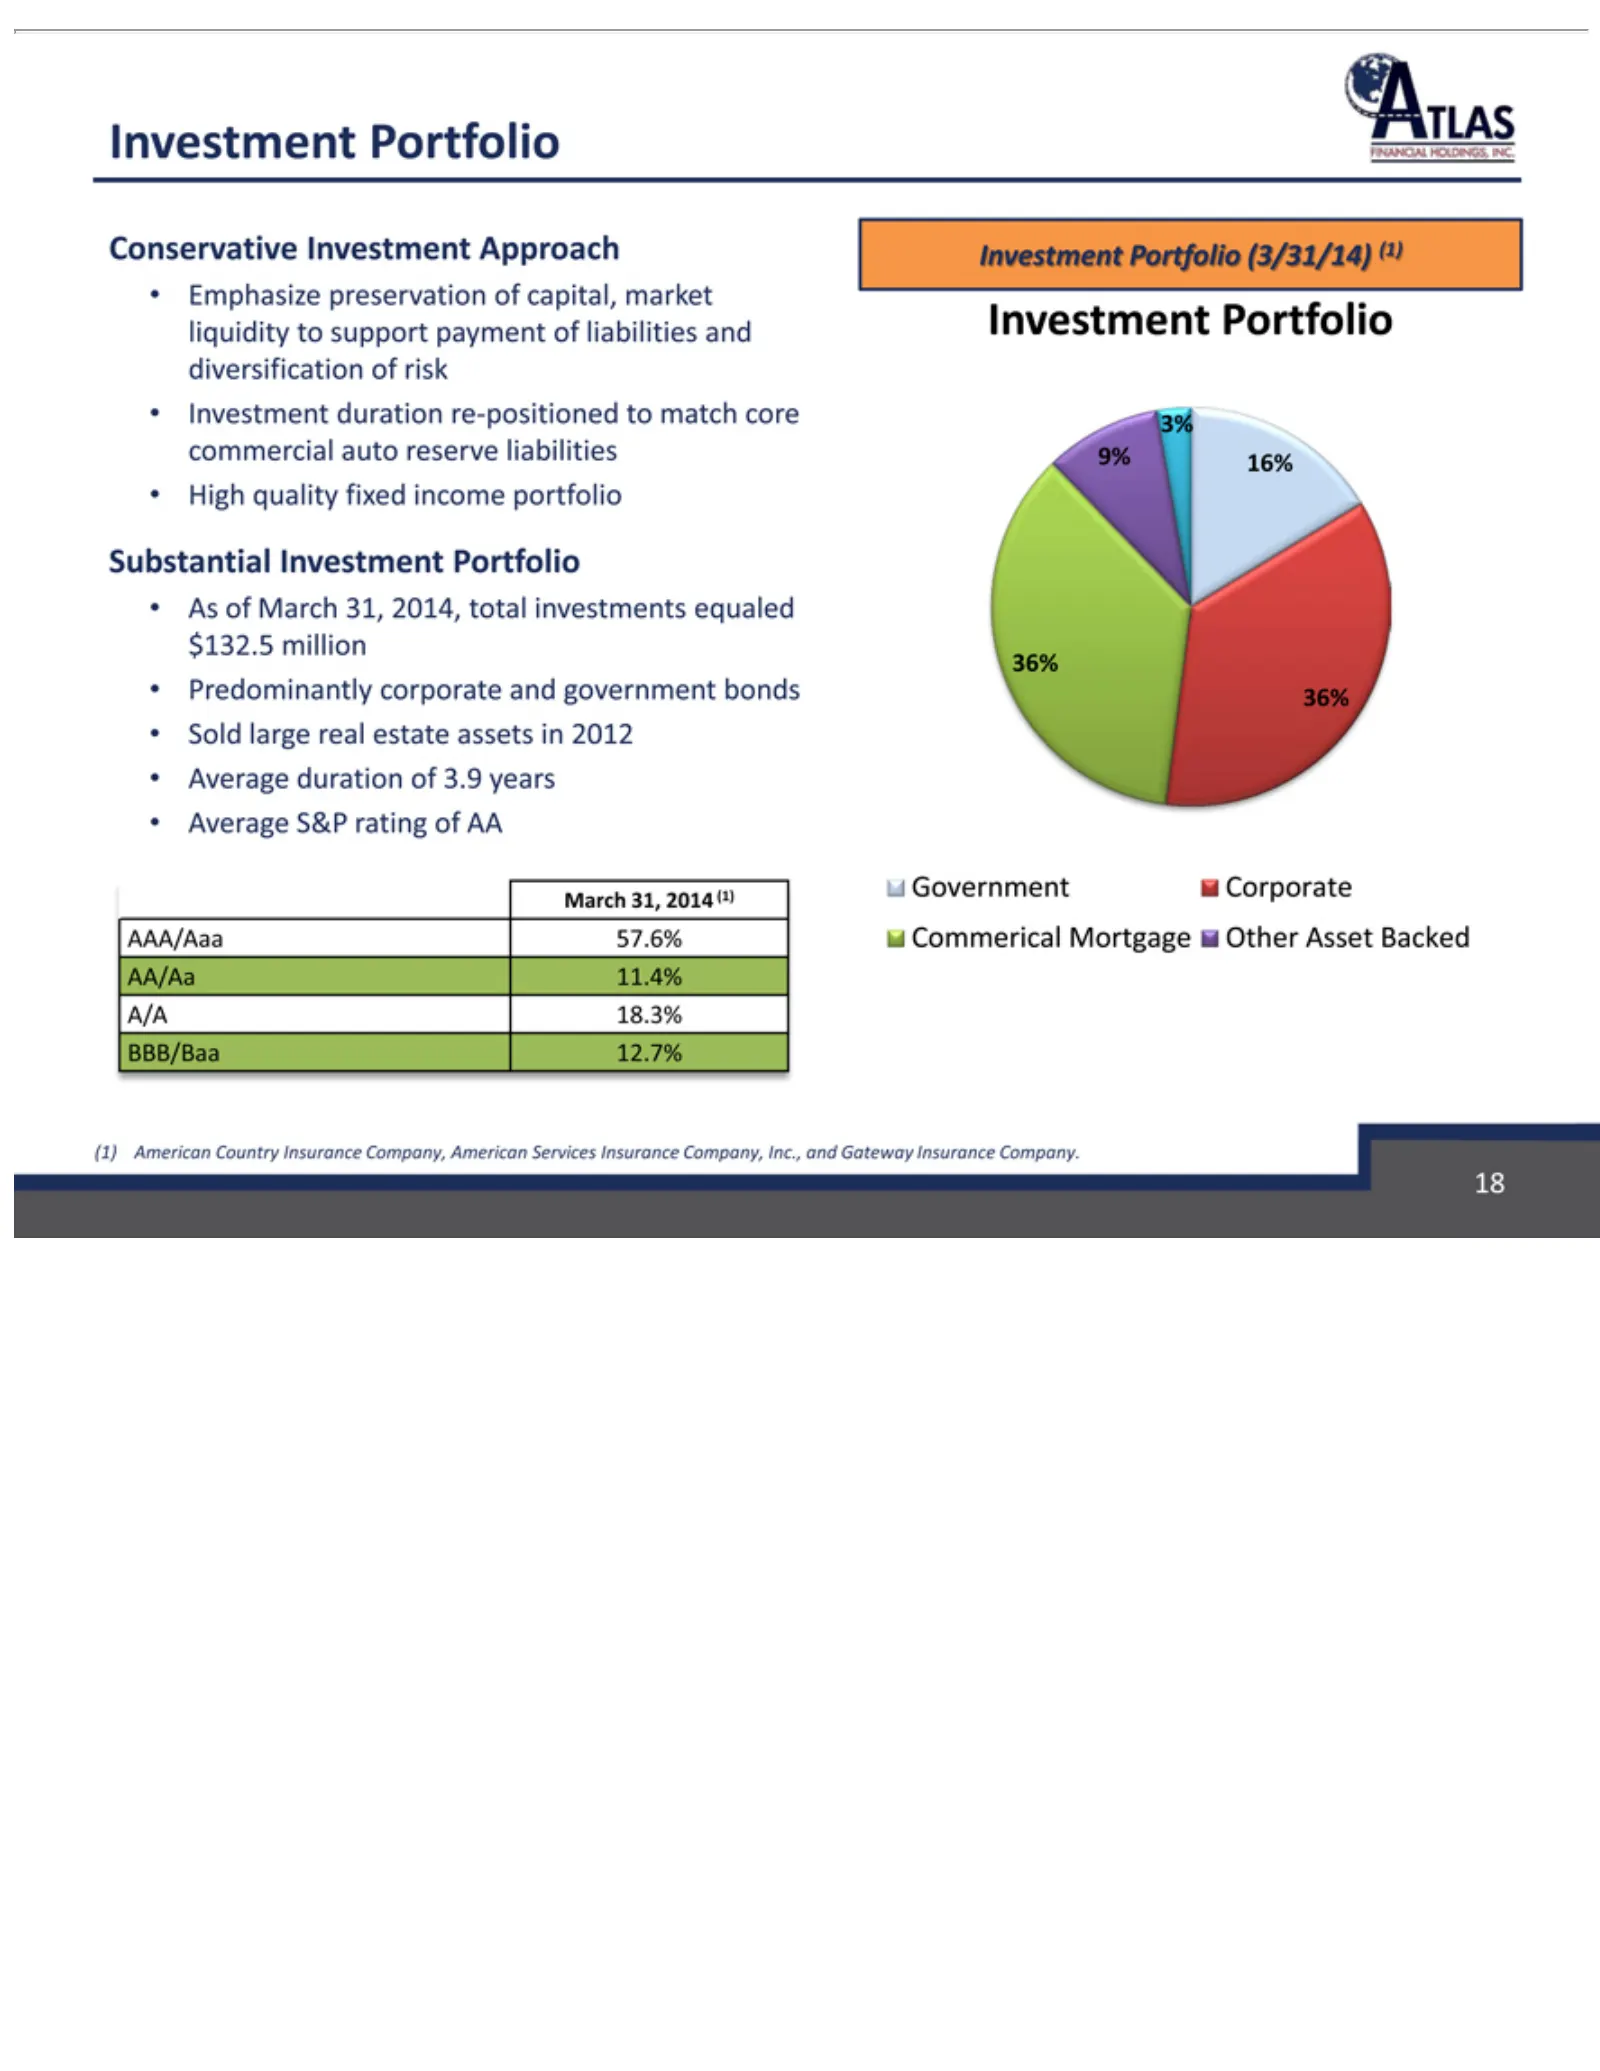
Slide 18: Conservative Investment Portfolio
Conservative Emphasize High Substantial As Predominantly Sold Average Investment 9% 3% Government 36% Commerical March AAA/Aaa AA/Aa A/A BBB/Baa (1) 18 American of 16% 18.3% large quality March 31, 11.4% duration S&P 12.7% 57.6% real 2014 preservation duration Portfolio Investment Mortgage Corporate
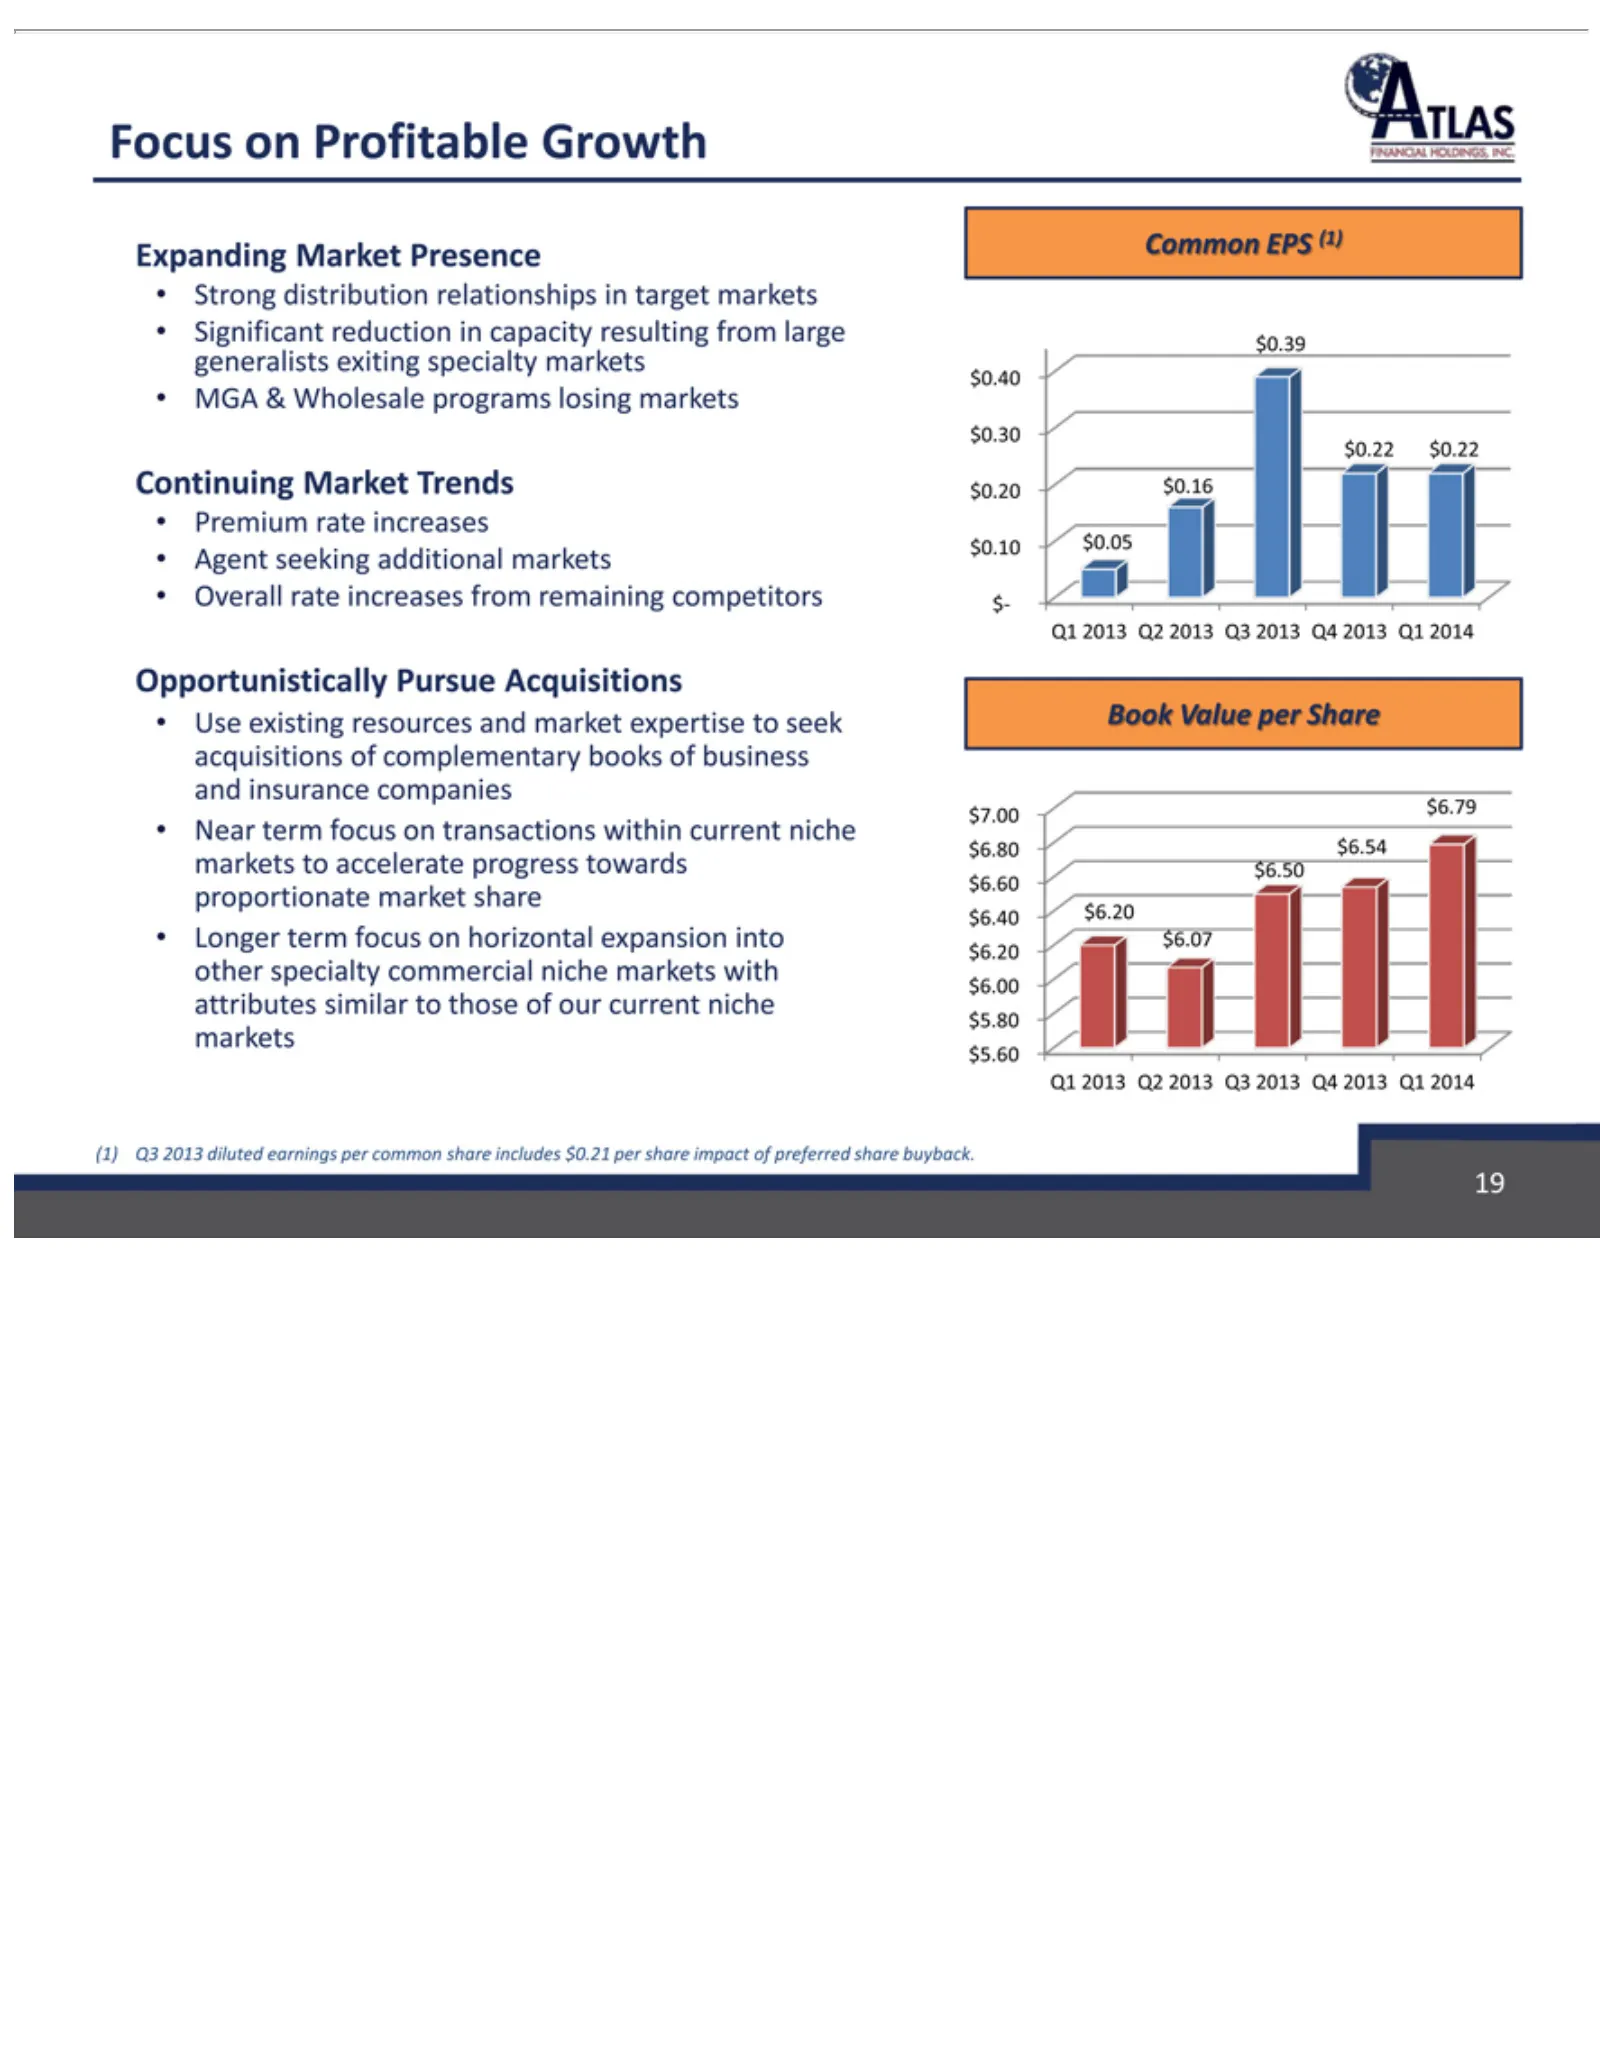
Slide 19: Focus on Expanding Profitable Growth
Focus Expanding Strong Significant MGA Continuing Premium Agent Overall Opportunistically Use Near Longer Common $0.22 $0.30 $0.40 $0.39 $0.20 $0.10 $- Book $7.00 $6.80 $6.40 $6.60 $6.50 Q1 $5.60 $5.80 $6.00 $6.20 $6.07 (1) 19 Q3 2013 existing term Value $0.22 $0.16 $0.05 $6.79 $6.54 $6.20 & on seek
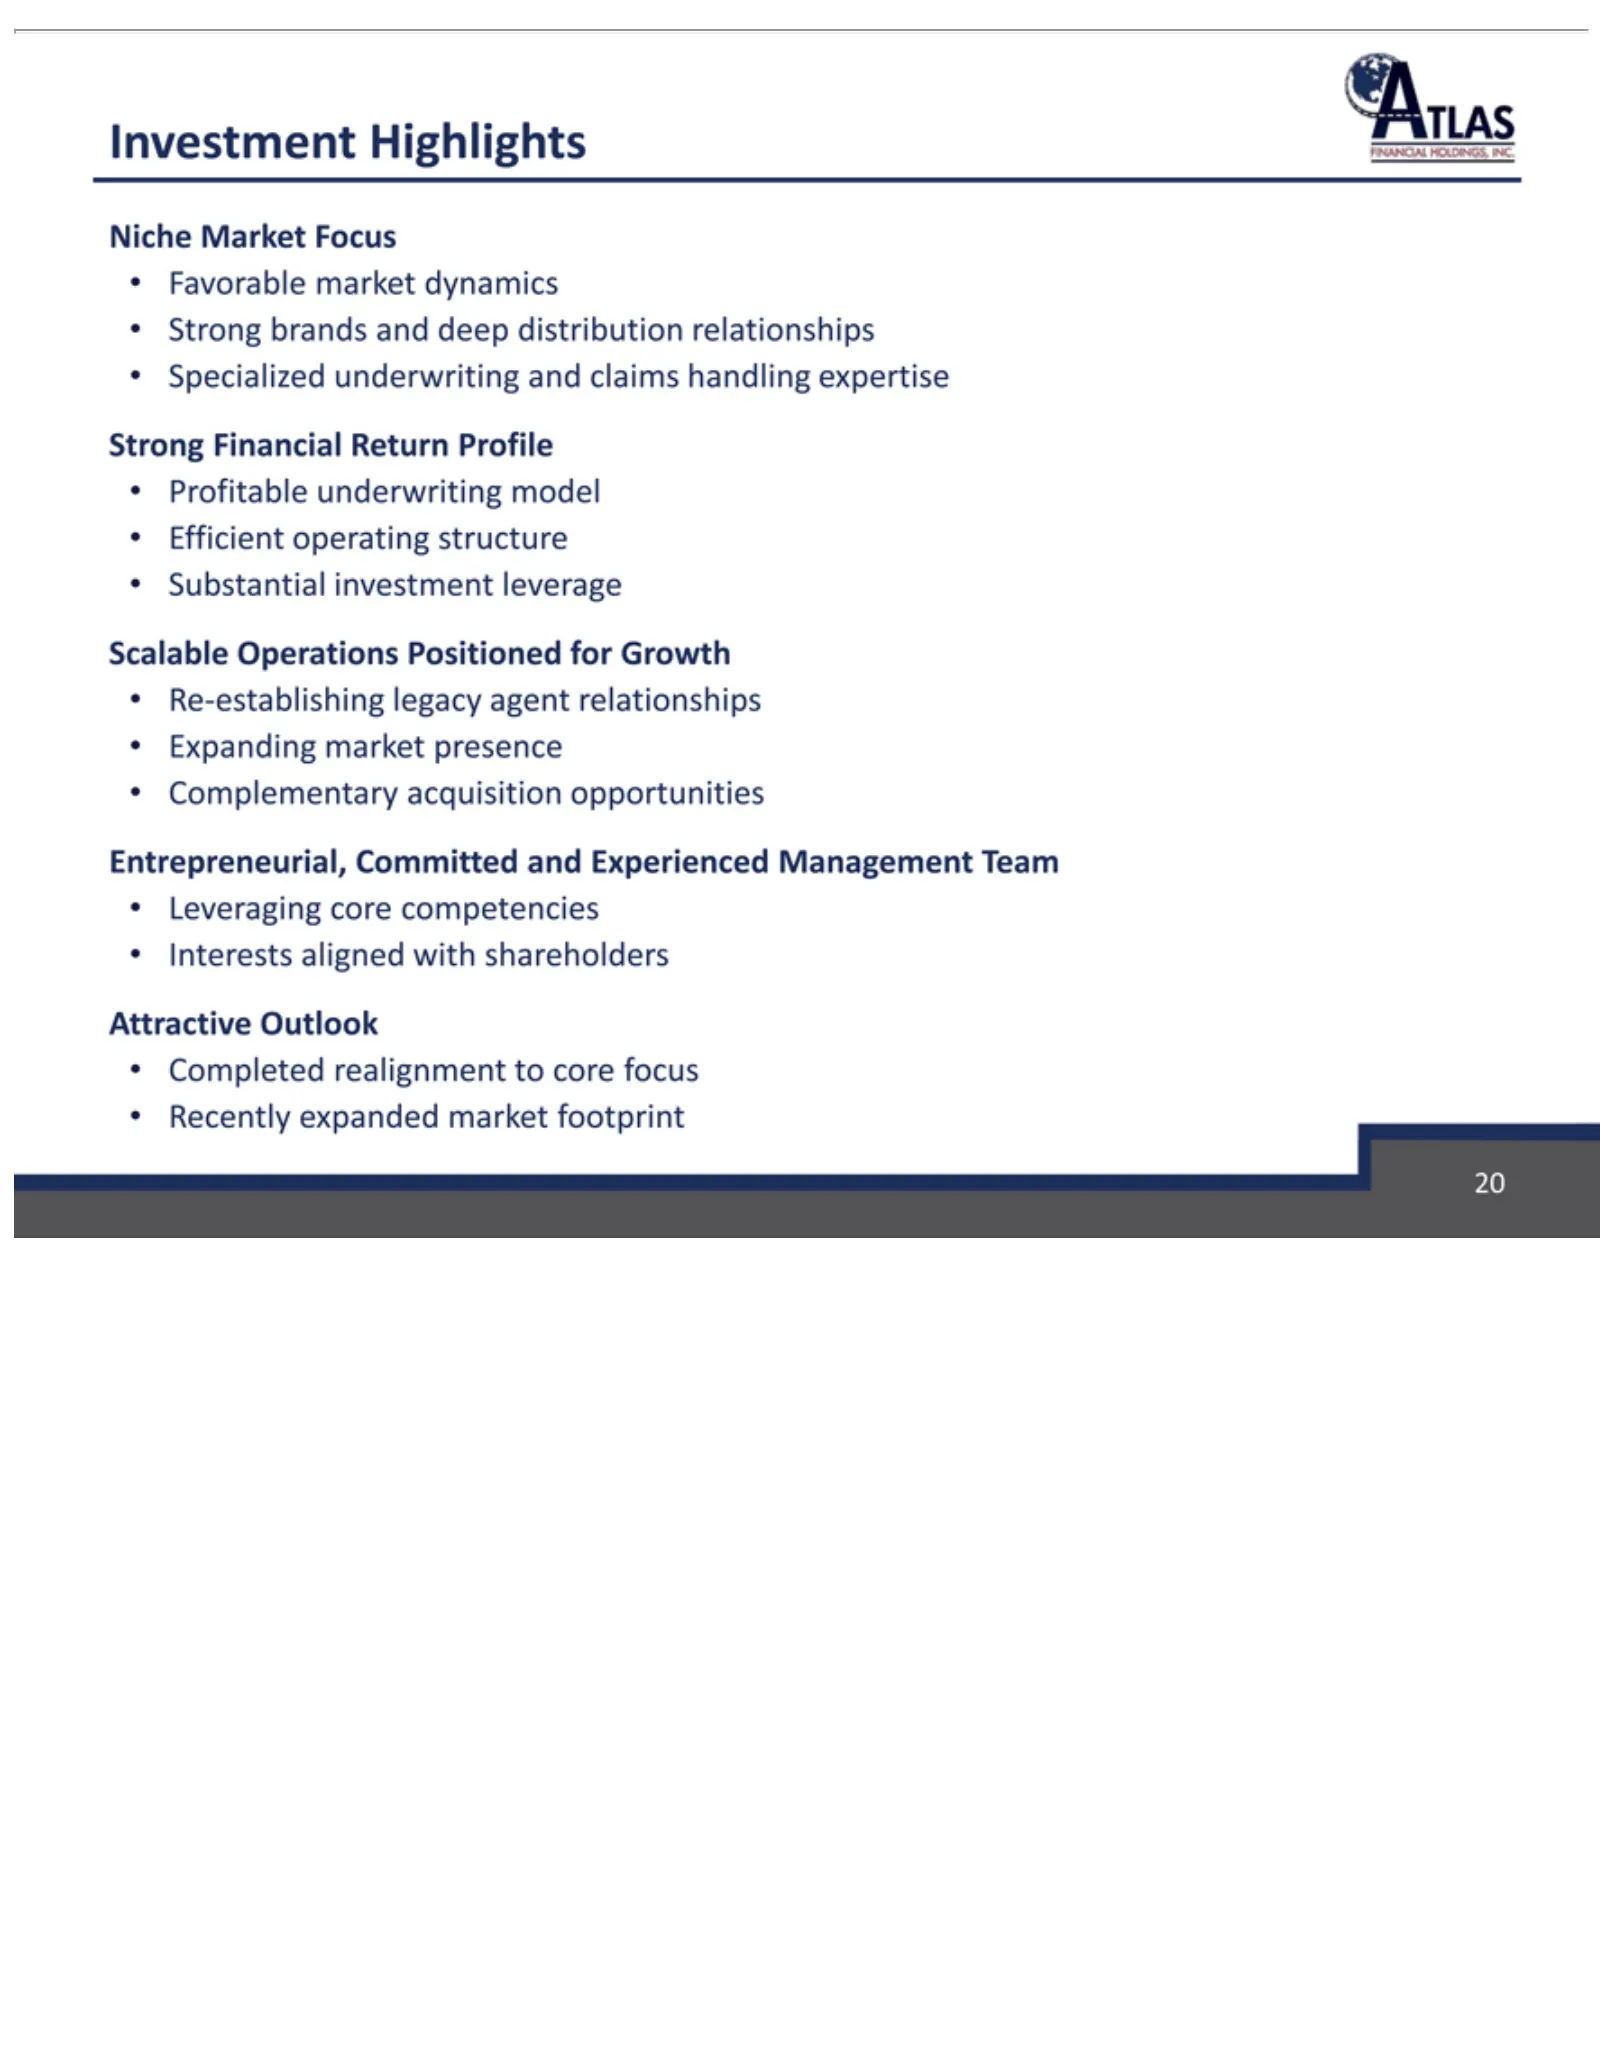
Slide 20: Investment Highlights
Investment Niche Favorable Specialized Strong Profitable Efficient Substantial Scalable Re-establishing Expanding Complementary Entrepreneurial, Leveraging Interests Attractive Completed Recently 20 Market brands Financial Operations aligned operating expanded underwriting Outlook market market real
Source: SEC EDGAR · FWP filed May 13, 2014
More decks from Atlas Financial Holdings Inc
 Investor Presentation (November 2022)20 slides · Nov 14, 2022
 Investor Presentation (August 2022)21 slides · Aug 12, 2022
 Investor Presentation (May 2022)20 slides · May 23, 2022
 Investor Presentation (April 2022)18 slides · Apr 4, 2022
 Investor Presentation (November 2021)28 slides · Nov 8, 2021
 Q2 2021 Earnings Presentation26 slides · Aug 10, 2021