Chittenden — Merger or Acquisition (November 2002)
33 slides from Chittenden's merger presentation, Nov 8, 2002
Slide 1: Acquisition of Granite State Bankshares
Chittnln CORPORATION Acquisition of GRANITE STATE BANKSHARES The Power of Local Banking November 8, 2002 Chittndn SEX ALSIP
Slide 2: Forward-Looking Statements
Forward-Looking Statements “This presentation contans forward-ookng statements wthh the meaning ofthe Prvate Secues gation Reform ‘et of 1006, These Forwarc locking statemerts Prelude, Ee are nt limed a, ceatemonts abut () tho Boneh ofthe Merger between Chittenden Corporation (chktenden” cr “CH” and
Slide 3: Additional Information
Additional Information ‘The proposed transection wl be subitted to Granite State's stockholders or thet conideaten, chittenden and Grane State wil le wih the SEC a fegizraton tatemeré, a are proxy satemont|prospecus ard cher Faovare documents concerning the proposed transaction withthe SEC, stocthol
Slide 4: Outline
Transaction Summary + Strategie Rationale ‘+ ProForma Financial Impact + Summary © Appendix Outline
Slide 5: Transaction Summary
Transaction Summary
Slide 6: Summary of Significant Terms
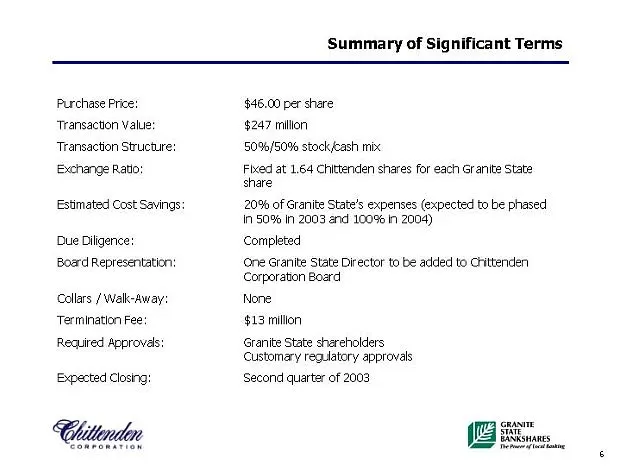
Purchase Price: ‘Transaction Value Transaction Structure: Exchange Ratio’ Estimated Cost Savings Due Diigence: Board Representation: Collars / Walk-Away: ‘Termination Fee: Required Approvals: Expected Closing Summary of Significant Terms $46.00 per share $247 milion, '5094/50% stock/eash mix Fhxed a
Slide 7: Deal Pricing
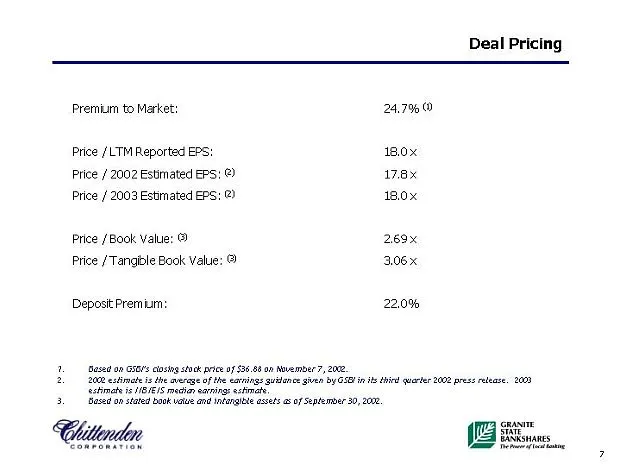
Deal Pricing Premium to Market: 24.7% 0 Price /LTM Reported EPS: 180% Price / 2002 Estimated EPS: © 17.8x Price / 2003 Estimated EPS: @ 180% Price / Book Value: © 269 Price / Tangible Book Value: @ 06% Deposit Premium 22.0% Desed on Gs casing stock pie 0f $36.58 ap November 7, 202. 2D estimate iste
Slide 8: Strategic Rationale
Strategic Rationale
Slide 9: Snapshot of Granite State
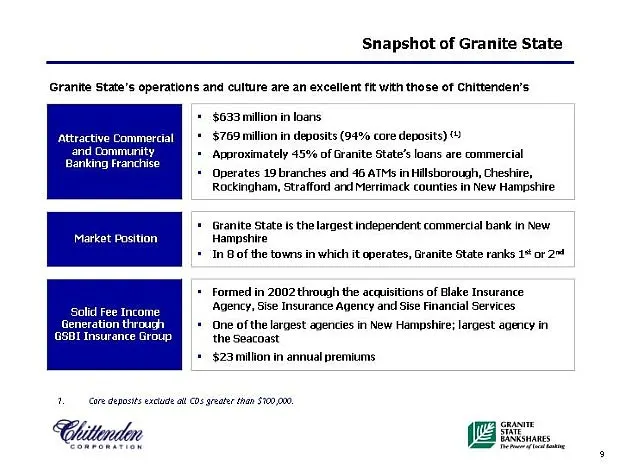
Snapshot of Granite State Granite State's operations and culture are an excellent fit with these of Chittenden’s ‘Attractive Commercial ‘and Communit Banking Franchise Market Position Solid Fee Income Generation through GSBI Insurance Group $633 million in loans {$769 million in deposits (94% core d
Slide 10: Franchise Enhancing
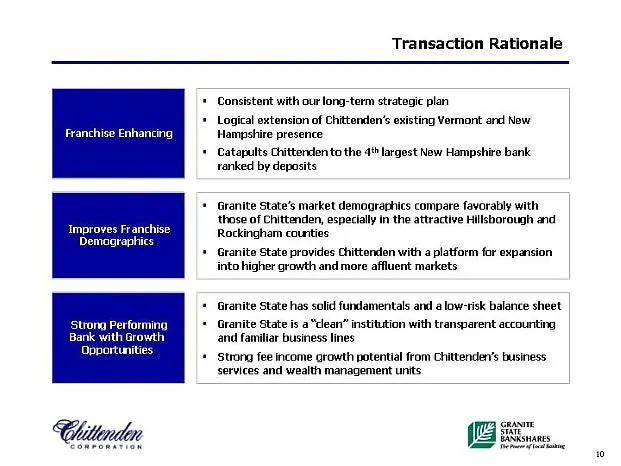
Franchise Enhancing Improves Franchise Demographics Strong Performing Bank with Growth Opportunities Transaction Rationale Consistent with our long-term strategic plan Logical extension of Chittenden’s existing Vermont and Now Hampshire presence Catapults Chittenden to the 4'* largest New Hampshire
Slide 11: Attractive Financial Results
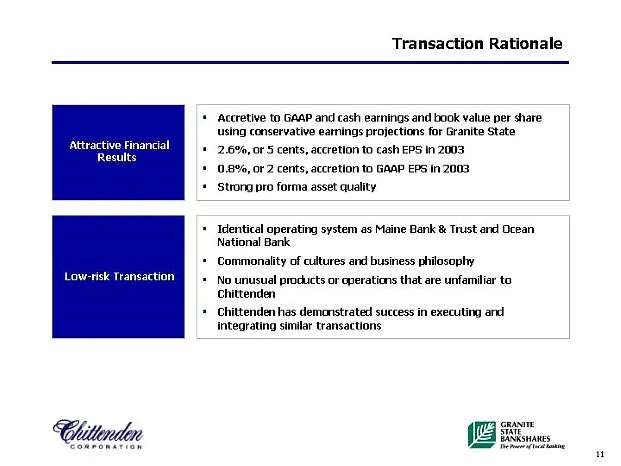
Attractive Financial Results Low-tisk Transaction Transaction Rationale Accretive to GAAP and cash earnings and book value per share Using conservative earnings projections for Granite State 2.6%, or 5 cents, accretion to cash EPS in 2003 (0.8%, or 2 cents, accretion to GAAP EPS in 2003, Strong pro
Slide 12: Building a Strong Commercial Banking Franchise in New Hampshire
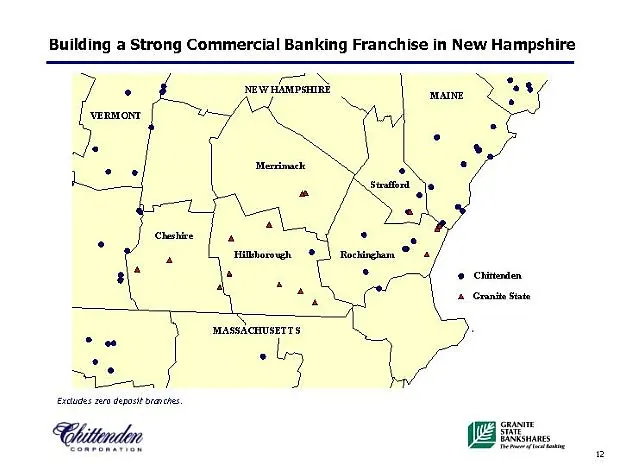
Building a Strong Commercial Banking Franchise in New Hampshire
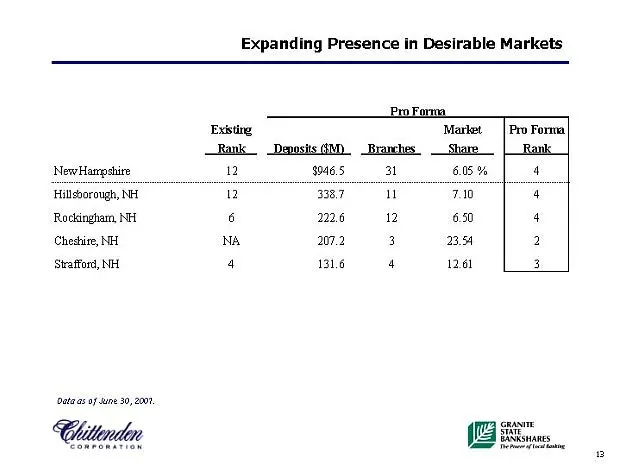
Slide 13: Expanding Presence in Desirable Markets
NewHaxpshice “Hillsborough, NEC Rockinghaan, NHL Cheshire, NH Stafford, NH ates 0f sane 30,200 Expanding Presence in Desirable Markets
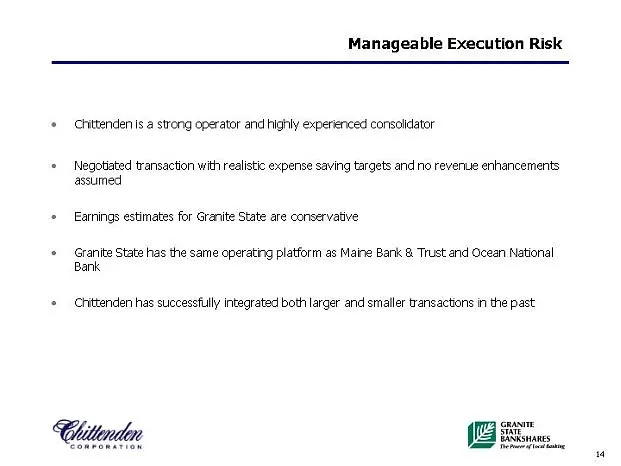
Slide 14: Manageable Execution Risk
Manageable Execution Risk Chittenden is a strong operator and highly experienced consolidator Negotiated transaction with realistic expense saving targets and ino revenue enhancements assumed Earnings estimates for Granite State are conservative Granite State has the same operating platform as Maine
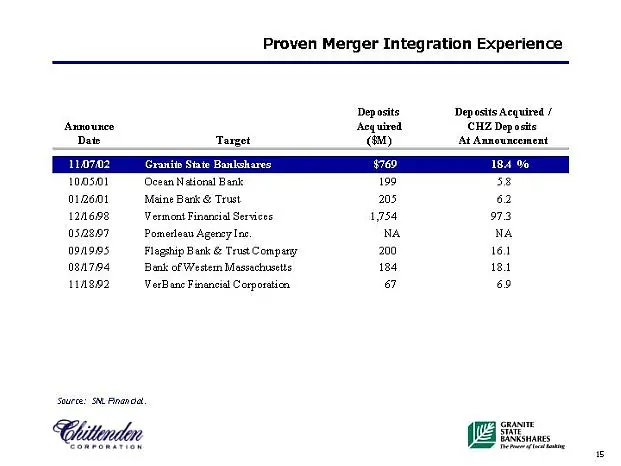
Slide 15: Proven Merger Integration Experience
Proven Merger Integration Experience Deposits Deposits Acquired / Acquired (CHZ Dep osite ‘At Announcement Target te Banlchare 100501 Ocean Neional Bank 199 58 012601 Meine Bark & Trust 05 62 121688 Vermont Finansial Services 1754 973 050267 Pomerteau Ageney ne NA NA 09985 Flegship Bank & Trust Comp
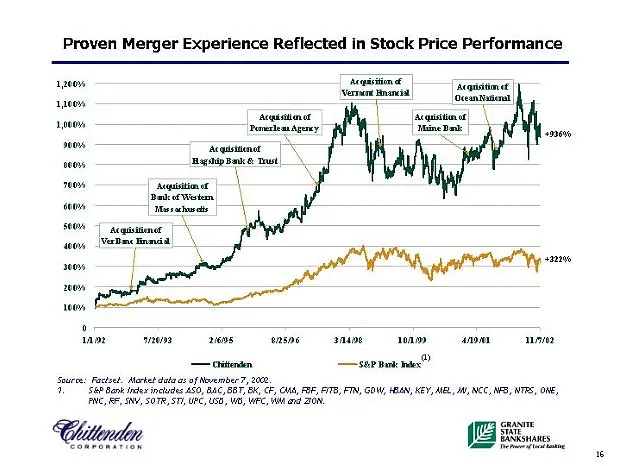
Slide 16: Proven Merger Experience Reflected in Stock Price Performance
Proven Merger Experience Reflected in Stock Price Performance 100% 10% a crete se mat tes Source: Fateeh. Markt data a of Movember, 2008 1 See Bank indeed: 450, BAC, SBT, BK, CE, CU, FB, FB, FIN, GOW, HEN, KEY MEL, NCC, AFB, ATES, ONE,
Slide 17: Pro Forma Financial Impact
Pro Forma Financial Impact
Slide 18: Pro Forma Earnings Impact
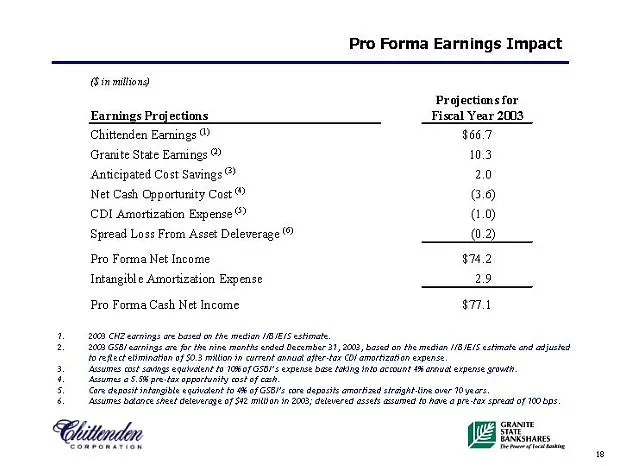
Pro Forma Earnings Impact Gin miiond Projections for Earnings Projections Fiscal Year 2003, Chittenden Earnings ® $66.7 Granite State Eamings © 103 Anticipated Cost Savings 20 Net Cash Opportunity Cost 68) CDI Amortization Expense ® 0® Spread Loss From Asset Deleverage 0.2 Pro Forma Net Income $4.2
Slide 19: Accretive to GAAP and Cash Earnings
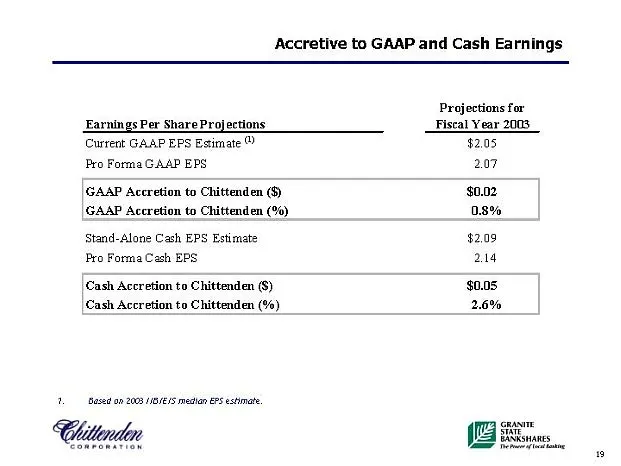
Accretive to GAAP and Cash Earnings Projections for Earnings Per Share Projections Fiscal Year 2008 Current GAAP EPS Estimate © $2.05 Pro Forma GAAP EPS 207 GAAP Accretion to Chittenden $0.02 GAAP Accretion to Chittenden (%) 0.8% Stand-Alone Cash EPS Estimate $2.09 Pro Forma Cash EPS 214 ‘Cash Accre
Slide 20: Estimated Cost Savings
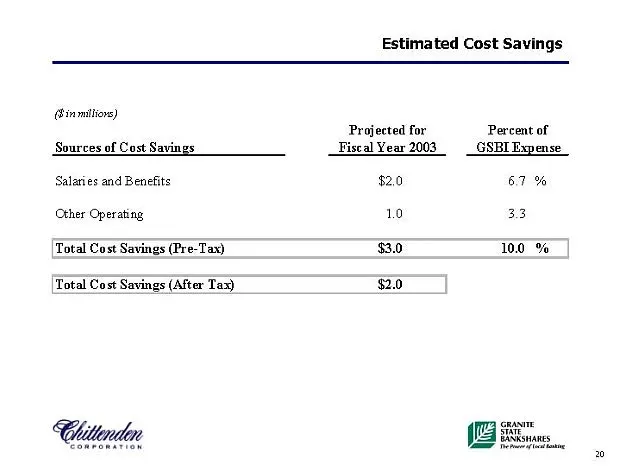
Estimated Cost Savings (inmiiors) Projected for Percent of Sources of Cost Savings Fiscal Year 2003 _GSBI Expense Salaries and Benefits $20 61% Other Operating 10 33 Total Cost Savings (Pre-Tax) $3.0 100 % Total Cost Savings (After Tas) 0)
Slide 21: Estimated Deal Costs
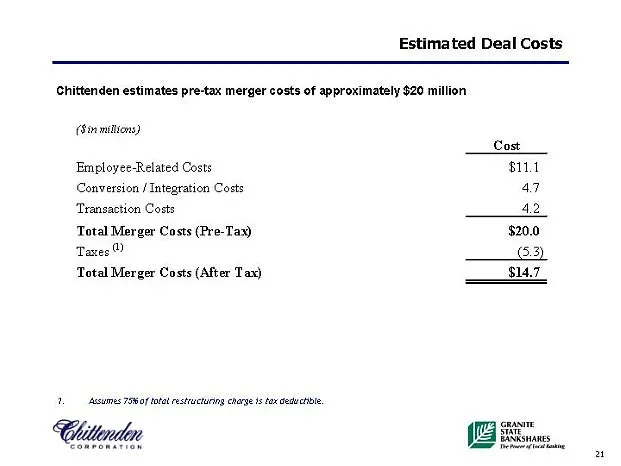
Estimated Deal Costs Chittenden estimates pre-tax merger costs of approximately $20 million (Sn miions) Cost Employee-Related Costs B11 (Conversion / Integration Costs aq ‘Transaction Costs 42 Total Merger Costs (Pre-Tax) $20.0 Taxes fox) Total Merger Costs (After Tax} 1. Assumes 75% oat restructuri
Slide 22: Strong Financial Position
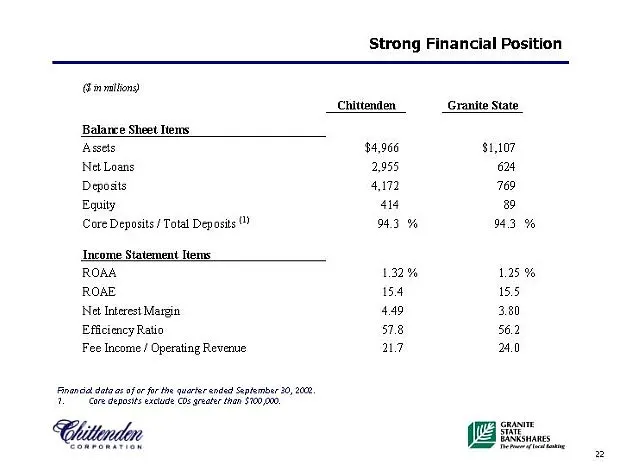
Strong Financial Position @ imo) Chittenden Granite State Balance Sheet Items Asses $4,966 $1,107 NetLoans 2,955 614 Deposits 4172 769 Equity 414 89 Core Deposits / Total Deposits 943% 943 % Income Statement Items ROAA 132% 1.25% ROAE 64 155 Net Interest Mesgin 449 3.80 Efficiency Ratio 518 56.2 Fee
Slide 23: Loan Composition Remains Diversified
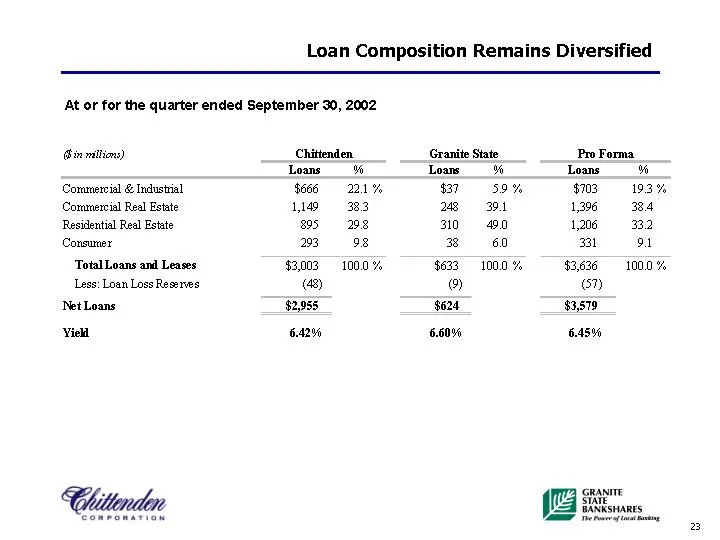
Loan Composition Remains Diversified At or for the quarter ended September 30, 2002 Gn mltions) Commercial @ Industrial Comanercial Real Estate Residential Real Estate Consumer ‘TotalLoans and Leases Less: Loan Loss Reserves Det Loans Yield Chittenden. Loans $666 221% 114 383 95 8 2388 $3003 1000.%
Slide 24: Maintains Excellent Asset Quality
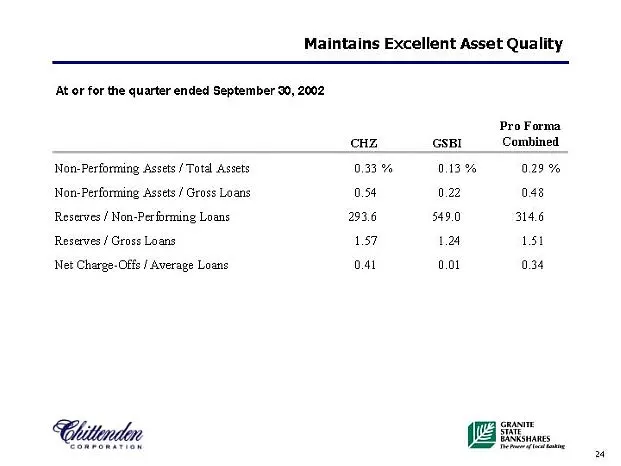
Maintains Excellent Asset Quality At or for the quarter ended September 90, 2002 Pro Forma CHE, GSBI___ Combined Non-Performing Assets / Total Assets 0.33 % 0.13% 0.239% Non-Performing Assets / Gross Loans 0.54 0.22 048 Reserves / Non-Performing Loans 2936 549.0 3146 Reserves / Gross Loans, 157 124
Slide 25: Deposit Mix
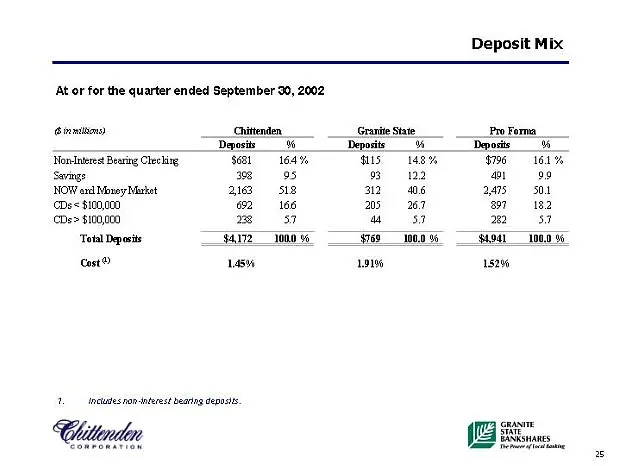
Deposit Mix At or for the quarter ended September 90, 2002 einmains) Chittenden, Pro Ferma Deposits Deposis TNomintreat Bearing Clee ling se 164% $796 161% Savings we 95 og NOW end Moxey Mixiat 21e 1B 2050 be $100,000 2 166 eT 1a2 cbe> $100,000 me 59 225d Total Deposit arr lono Son 1900 6 cost 134 1
Slide 26: Maintaining Capital Strength
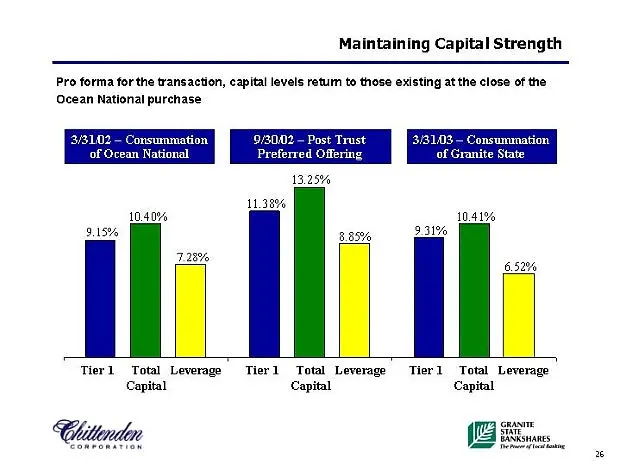
Maintaining Capital Strength Pro forma forthe transaction, capital levels retum to those existing at the close of the (Ocean National purchase ‘02 ~ Consummation 9/3002 — Post Trust (31,03 - Consummation of Ocean National Preferred Offering of Granite State 13.25% 11.38% 10.40% 10.41% 9.15% Me 9.31%
Slide 27: Rapid Capital Generation
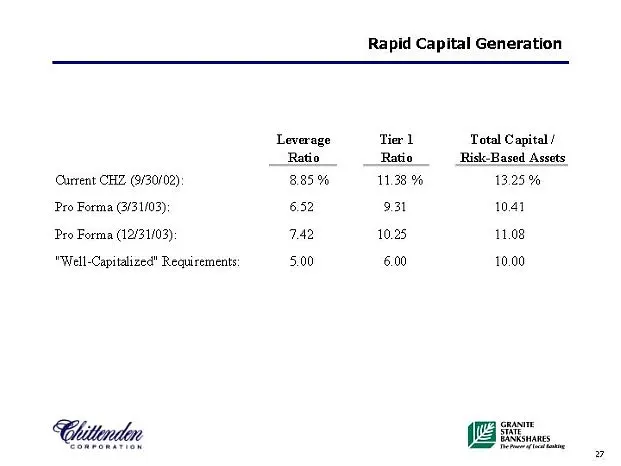
Rapid Capital Generation Leverage Tier 1 Total Capital / Ratio Ratio Rise Based Assets Current CHZ (9/30/02) 885% 11.38 % 13.25% Pro Forma (3/31/03): 652 931 1041 Pro Forma (12/31/03) 742 10.25 11.08 "Well-Capitalized" Requirements 5.00 6.00 10.00
Slide 28: Summary
Summary
Slide 29: Summary
Summary Granite State is a sold, profitable franchise Great strategic fit that enhances franchise Expands presence in demographically attractive markets ‘Consistent with our strategy of pursuing in-market or contiguous acquisitions of high quality companies Granite State has excellent asset quality
Slide 30: Appendix
Appendix
Slide 31: Pro Forma Market Position
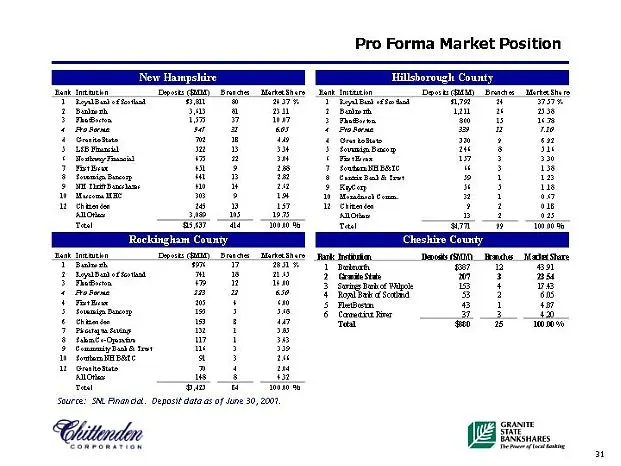
Pro Forma Market Position om — Seen eT ETT see sete ee } im z a mF ou ieee Bob immer «62 iB | i, BS ies Sie 7 Pharm saeny BE 1 bea = = =es ee, RB = wits sai aceai, eaw asayearaee
Slide 32: Historical Financial Performance
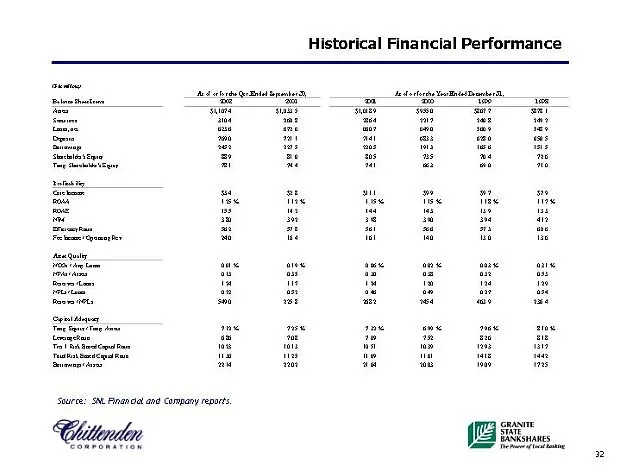
Historical Financial Performance Aes endo Qetaal ptr, Sure: SM Fnanctal ane Company repat Chitin
Slide 33: Chittenden Corporation
CORPORATION Visit our website for a wide range of products, latest financial reports and many other interactive services: www.chittendencorp.com ‘This presenttion cerns "orwarleckingstateants™ which may deere Future plant and stage natve, These Forward Ioeking eaters ate based on curent pln ad oepec
Source: SEC EDGAR · 425 filed Nov 8, 2002
More decks from Chittenden Corp
 Investor Presentation (September 2007)38 slides · Sep 7, 2007
 Merger or Acquisition (June 2007)27 slides · Jun 27, 2007
 Chittenden — Merger or Acquisition (June 2007)25 slides · Jun 27, 2007
 Merger or Acquisition (June 2007)9 slides · Jun 5, 2007
 Investor Presentation (May 2007)36 slides · May 14, 2007
 Investor Presentation (February 2007)37 slides · Feb 16, 2007