Argo Group International Holdings Ltd
Argo Group International — Merger or Acquisition (November 2016)
12 slides from Argo Group International's merger presentation, Nov 14, 2016
Slide 1: Acquisition of Ariel Re: Scale and Diversification
Acquisition of Ariel Re: Scale and Diversification Investor Presentation November 2016 Exhibit 99.2
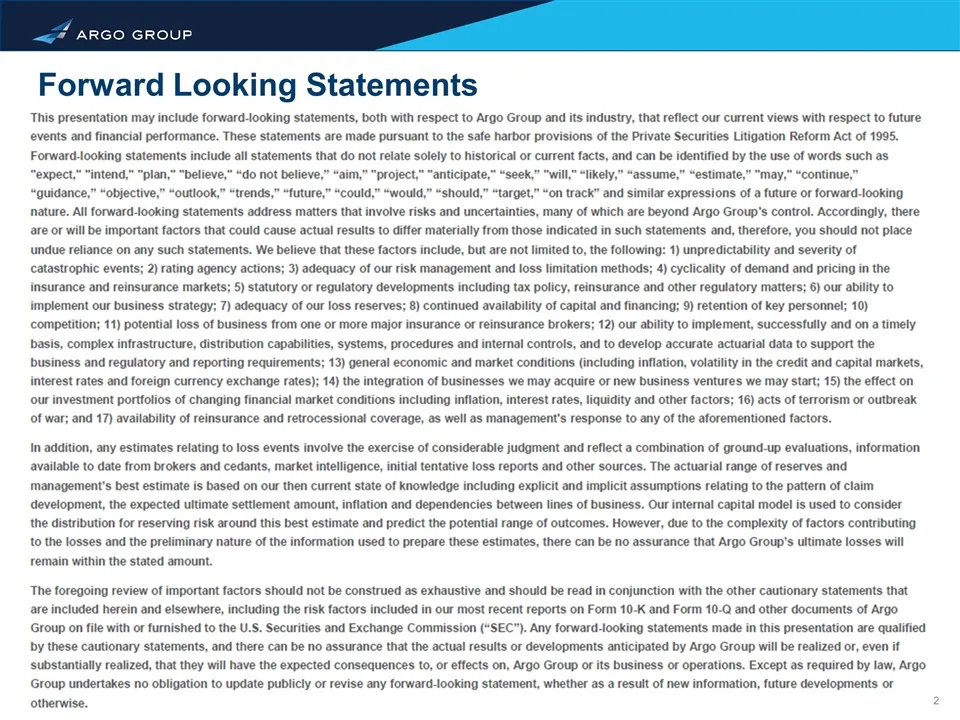
Slide 2: Forward Looking Statements
Forward Looking Statements provisions of foject,” “anticipate,” “seek,” “will,” “likely,” “assume,” “estimat “expect,” “intend,” “plan,” “believe,” “do not believe,” “aim,” " te! “siden, object” Couto” “trend,” ture” “could” “wou” “shoul” “target” “on Wack nd snr expressions of a future oom toking t
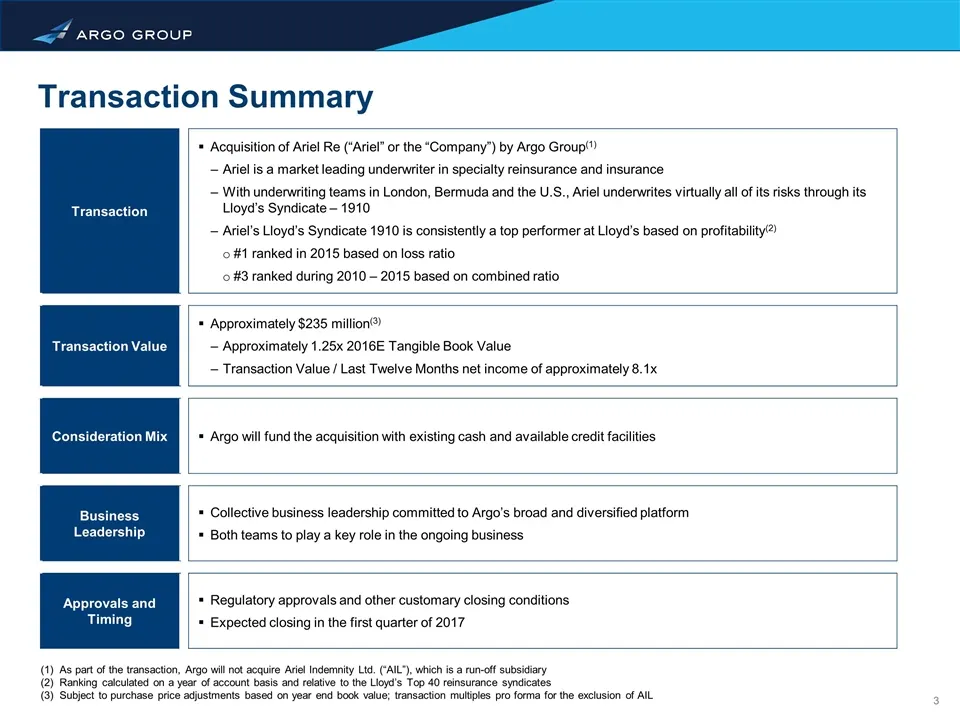
Slide 3: Transaction Summary
Transaction Summary Transaction Acquisition of Ariel Re (“Ariel” or the “Company”) by Argo Group(1) Ariel is a market leading underwriter in specialty reinsurance and insurance With underwriting teams in London, Bermuda and the U.S., Ariel underwrites virtually all of its risks through its Lloyd’s S
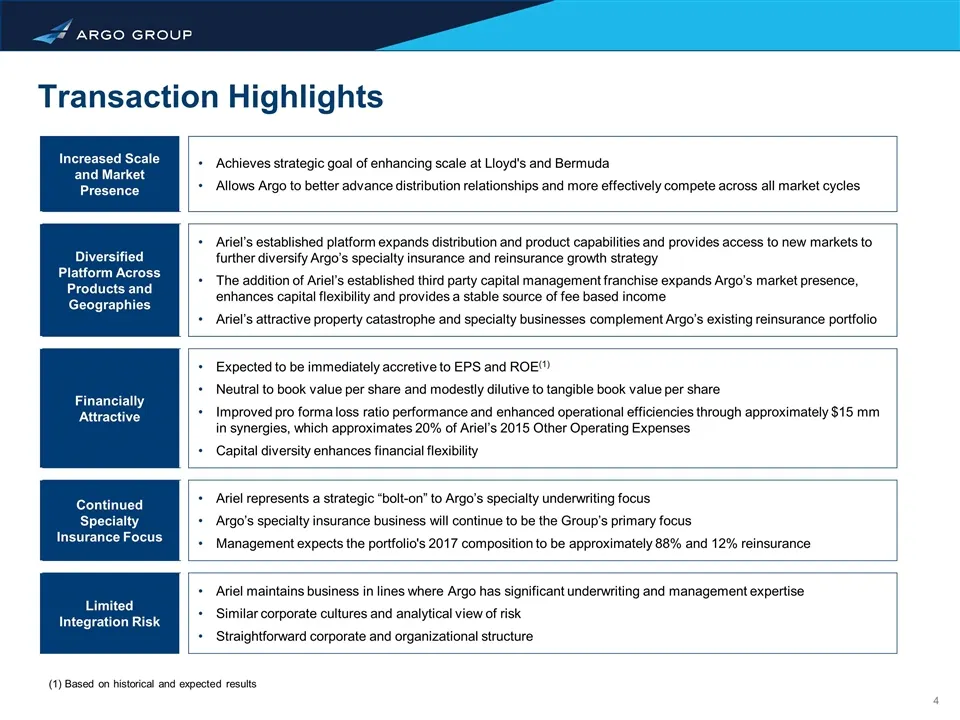
Slide 4: Transaction Highlights
Transaction Highlights Increased Scale and Market Presence Achieves strategic goal of enhancing scale at Lloyd's and Bermuda Allows Argo to better advance distribution relationships and more effectively compete across all market cycles Diversified Platform Across Products and Geographies Ariel’s est
Slide 5: Excess & Surplus Lines
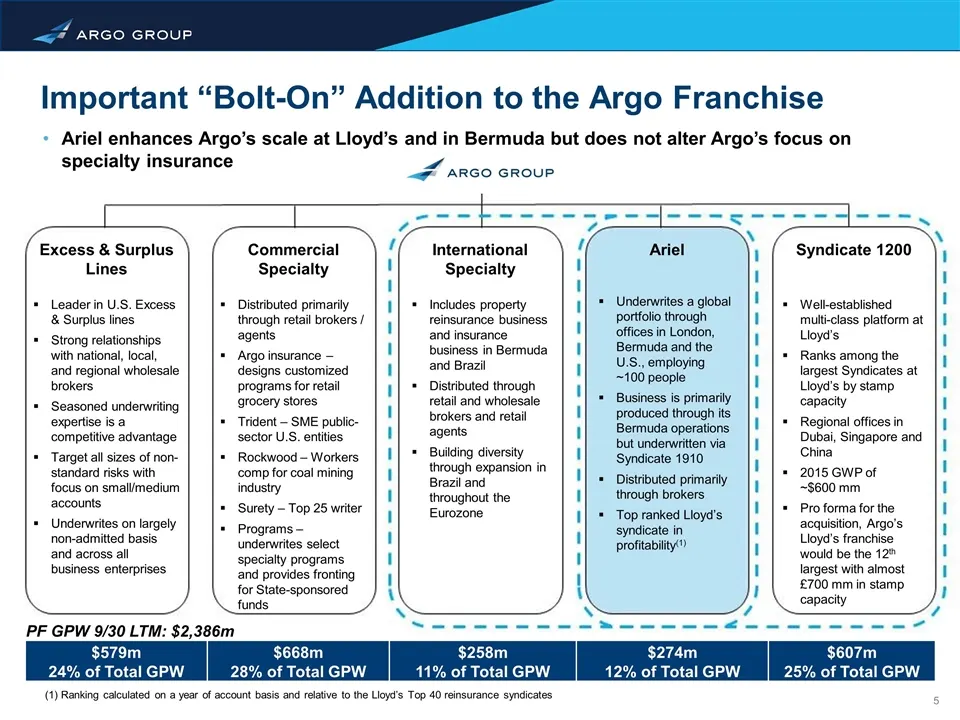
Excess & Surplus Lines Leader in U.S. Excess & Surplus lines Strong relationships with national, local, and regional wholesale brokers Seasoned underwriting expertise is a competitive advantage Target all sizes of non-standard risks with focus on small/medium accounts Underwrites on largely non-admi
Slide 6: Argo's Continued Specialty Focus
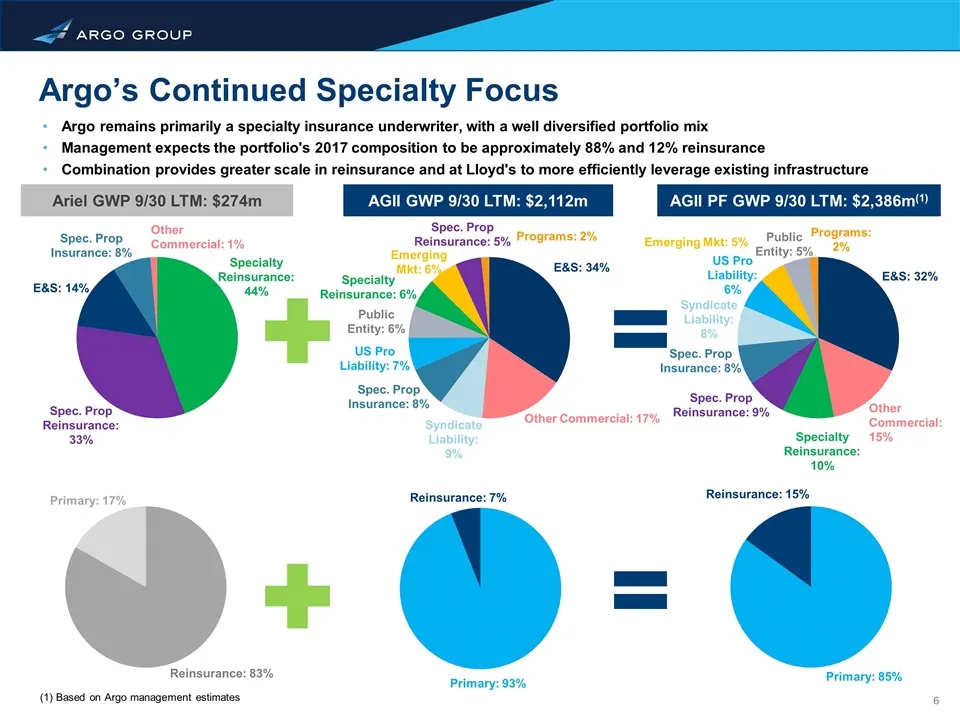
Argo’s Continued Specialty Focus Argo remains primarily a specialty insurance underwriter, with a well diversified portfolio mix Management expects the portfolio's 2017 composition to be approximately 88% and 12% reinsurance Combination provides greater scale in reinsurance and at Lloyd's to more ef
Slide 7: Enhanced Scale, Diversification and Profitability
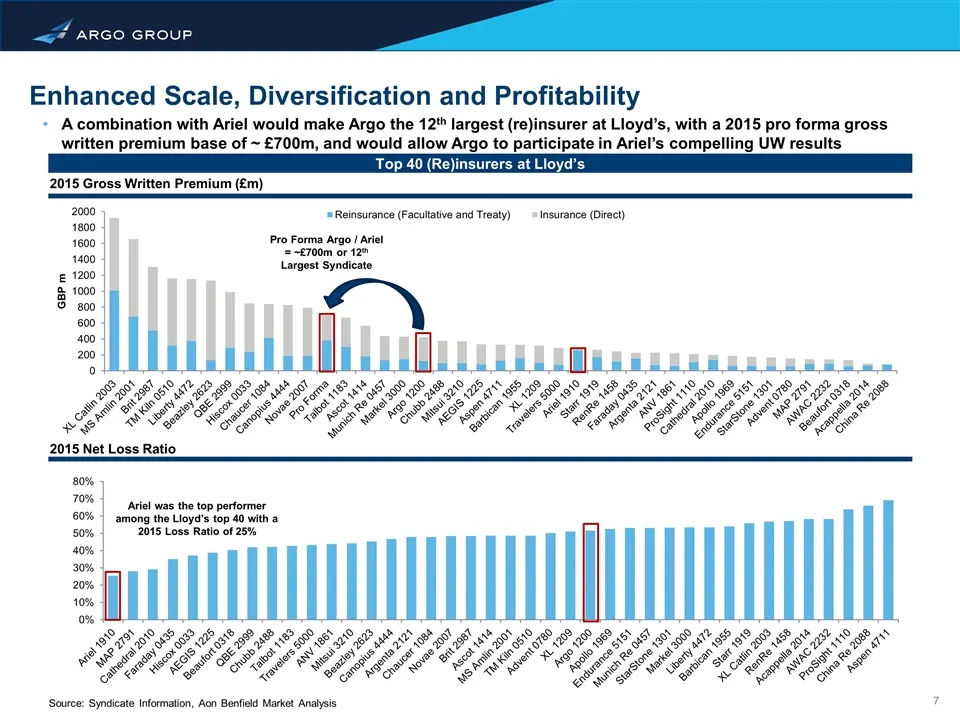
2015 Net Loss Ratio Enhanced Scale, Diversification and Profitability Top 40 (Re)insurers at Lloyd’s Pro Forma Argo / Ariel = ~£700m or 12th Largest Syndicate 2015 Gross Written Premium (£m) A combination with Ariel would make Argo the 12th largest (re)insurer at Lloyd’s, with a 2015 pro forma gross
Slide 8: Strategic Deployment of Third Party Capital
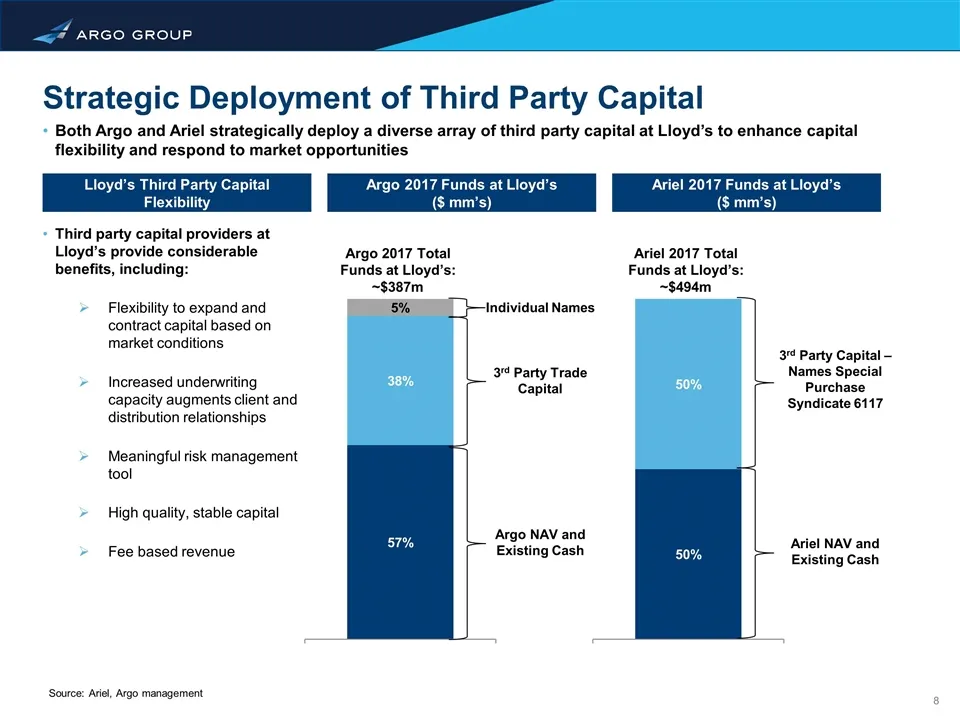
Strategic Deployment of Third Party Capital Both Argo and Ariel strategically deploy a diverse array of third party capital at Lloyd’s to enhance capital flexibility and respond to market opportunities Lloyd’s Third Party Capital Flexibility Ariel 2017 Funds at Lloyd’s ($ mm’s) Source: Ariel, Argo m
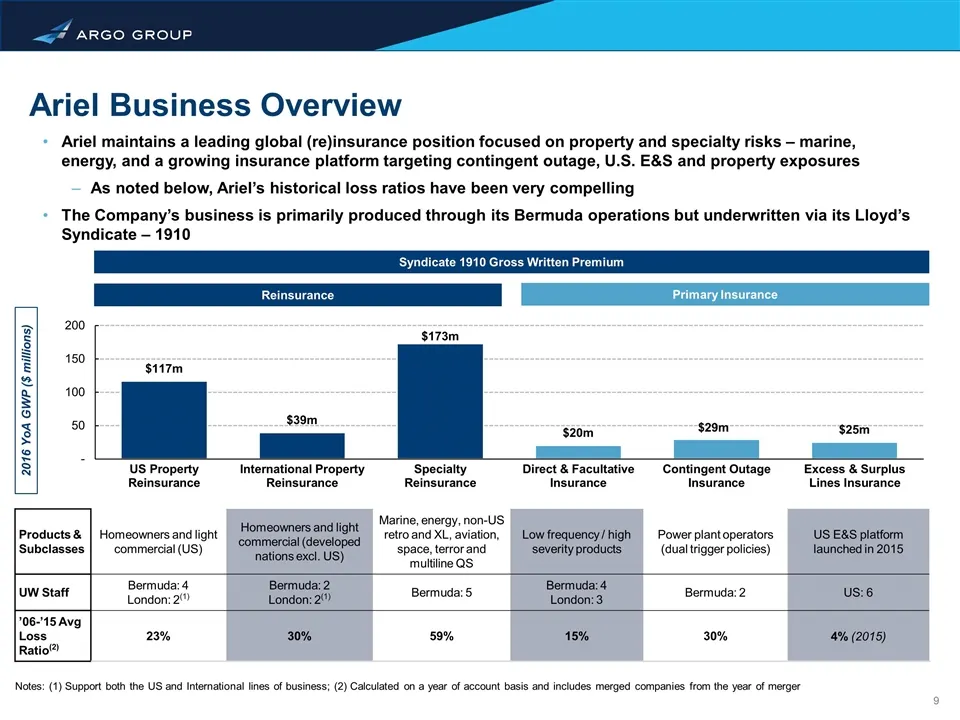
Slide 9: Ariel Business Overview
Ariel Business Overview Products & Subclasses Homeowners and light commercial (US) Homeowners and light commercial (developed nations excl. US) Marine, energy, non-US retro and XL, aviation, space, terror and multiline QS Low frequency / high severity products Power plant operators (dual trigger pol
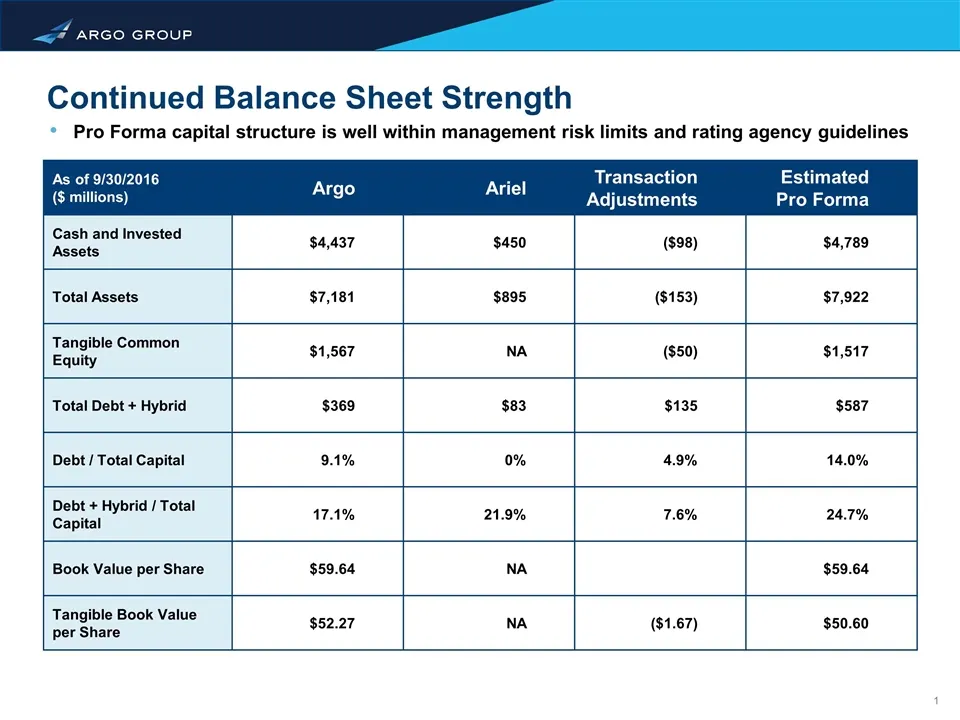
Slide 10: Continued Balance Sheet Strength
Continued Balance Sheet Strength As of 9/30/2016 ($ millions) Argo Ariel Transaction Adjustments Estimated Pro Forma Cash and Invested Assets $4,437 $450 ($98) $4,789 Total Assets $7,181 $895 ($153) $7,922 Tangible Common Equity $1,567 NA ($50) $1,517 Total Debt + Hybrid $369 $83 $135 $587 Debt / To
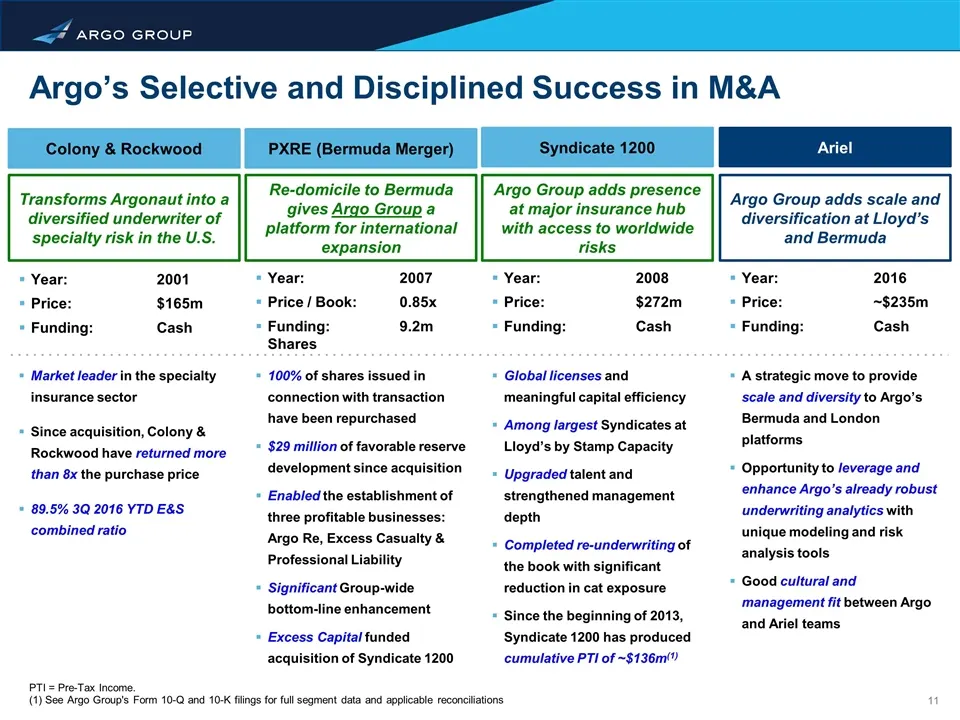
Slide 11: Track Record of Successful Acquisitions
100% of shares issued in connection with transaction have been repurchased $29 million of favorable reserve development since acquisition Enabled the establishment of three profitable businesses: Argo Re, Excess Casualty & Professional Liability Significant Group-wide bottom-line enhancement Excess
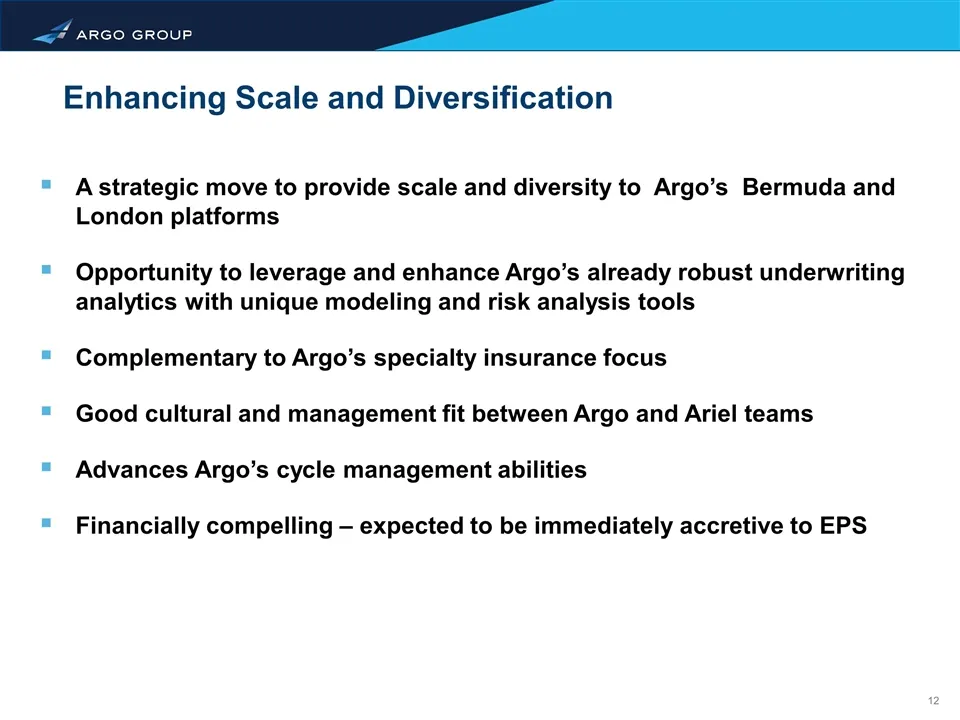
Slide 12: Enhancing Scale and Diversification
Enhancing Scale and Diversification A strategic move to provide scale and diversity to Argo’s Bermuda and London platforms Opportunity to leverage and enhance Argo’s already robust underwriting analytics with unique modeling and risk analysis tools Complementary to Argo’s specialty insurance focus G
Source: SEC EDGAR · 8-K filed Nov 14, 2016
More decks from Argo Group International Holdings Ltd
 Proxy Contest (November 2022)39 slides · Nov 18, 2022
 Corporate Update (September 2022)23 slides · Sep 8, 2022
 Investor Presentation (February 2022)24 slides · Feb 23, 2022
 Q3 2021 Earnings Presentation7 slides · Nov 3, 2021
 Investor Day (March 2021)59 slides · Mar 12, 2021
 Investor Presentation (November 2020)17 slides · Nov 10, 2020