Meritor — Arvinmeritor — Deutsche Bank 2009 Leveraged Finance Conference
22 slides from Meritor's conference presentation, Sep 30, 2009
Slide 1: Deutsche Bank 2009 Leveraged Finance Conference
Deutsche Bank 2009 Leveraged Finance Conference September 30, 2009 Jay Craig Senior Vice President and CFO 1
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains statements relating to future results of the company (including certain projections and business trends) that are “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995. Forward-looking statements are typi
Slide 3: Diverse Business Portfolio
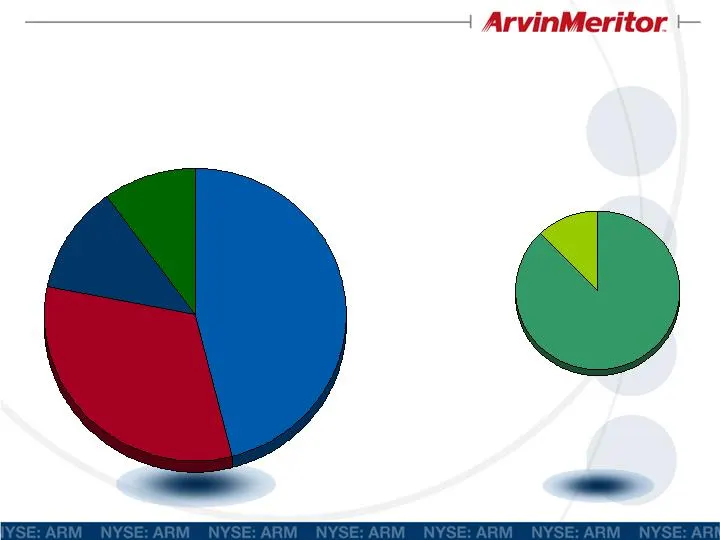
North America 46% Europe 32% South America 12% Asia Pacific 10% Body 88% Chassis 12% Diverse Business Portfolio Based on 2008 Sales CVS $4.8 Billion $1.6 Billion LVS Remaining
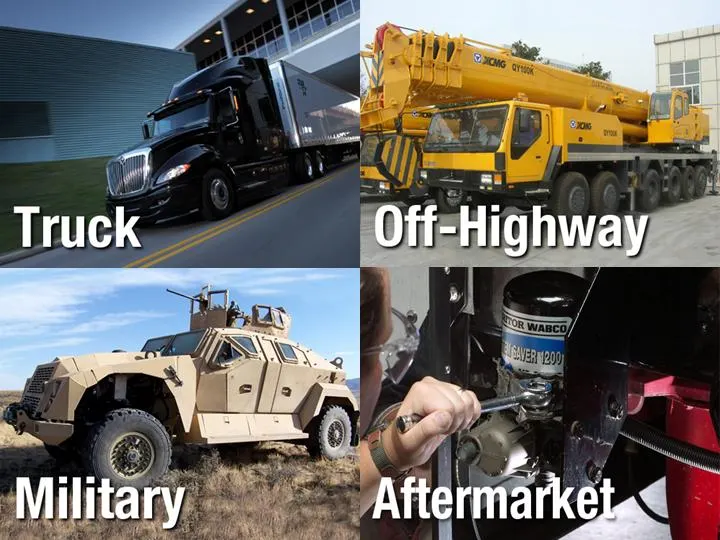
Slide 4: Truck, Off-Highway, Military, Aftermarket
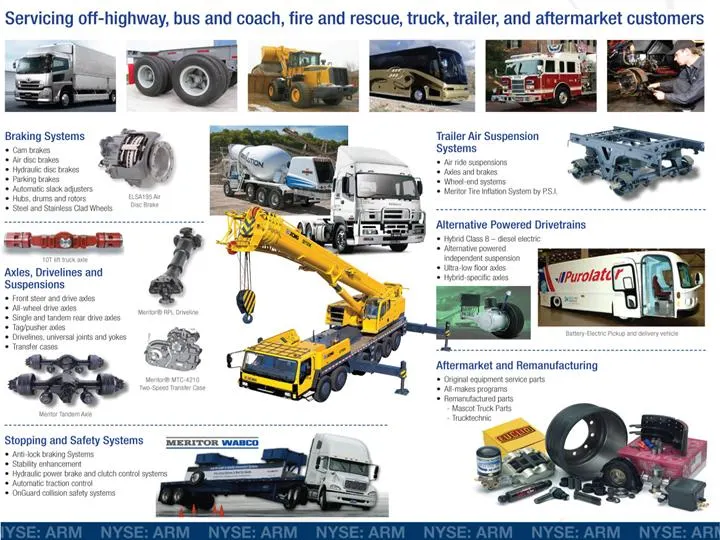
Slide 5: Servicing off-highway, bus and coach, fire and rescue, truck, trailer, and aftermarket customers
Servicing off-highway, bus and coach, fire and rescue, truck, trailer, and aftermarket customers Trailer Air Suspension systems Axles, Drivelines and Suspensions
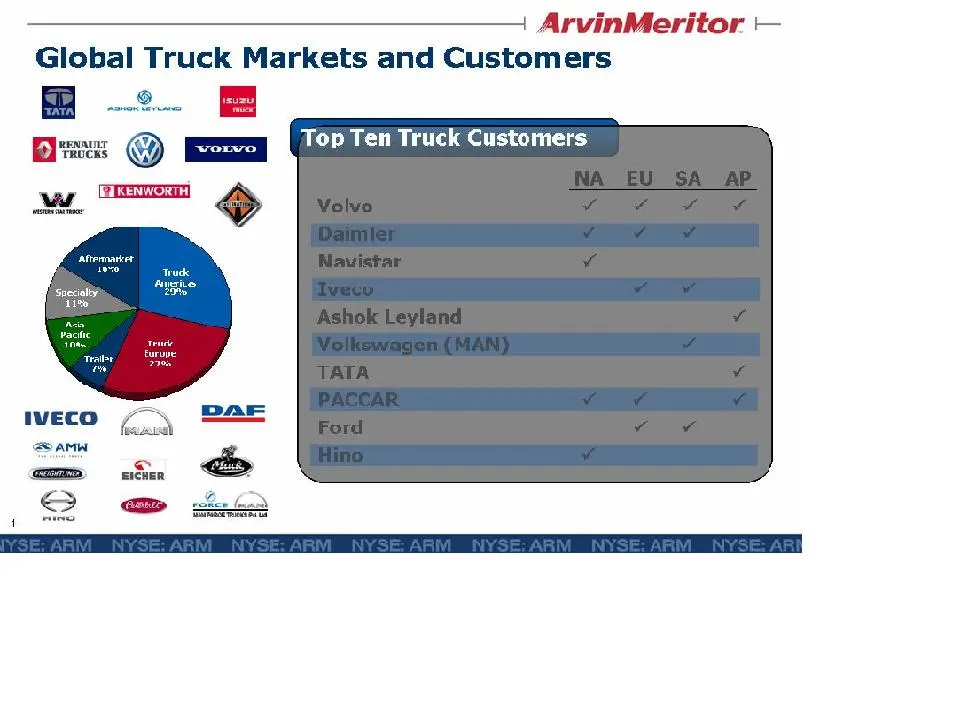
Slide 6: Global Truck Markets and Customers
| Arvi Global Truck Markets and Customers TRUCKS Bes See Top Ten Truck Customers Aftermasker ud Augie Ey Wweco (yy) AM mmm —eidicr
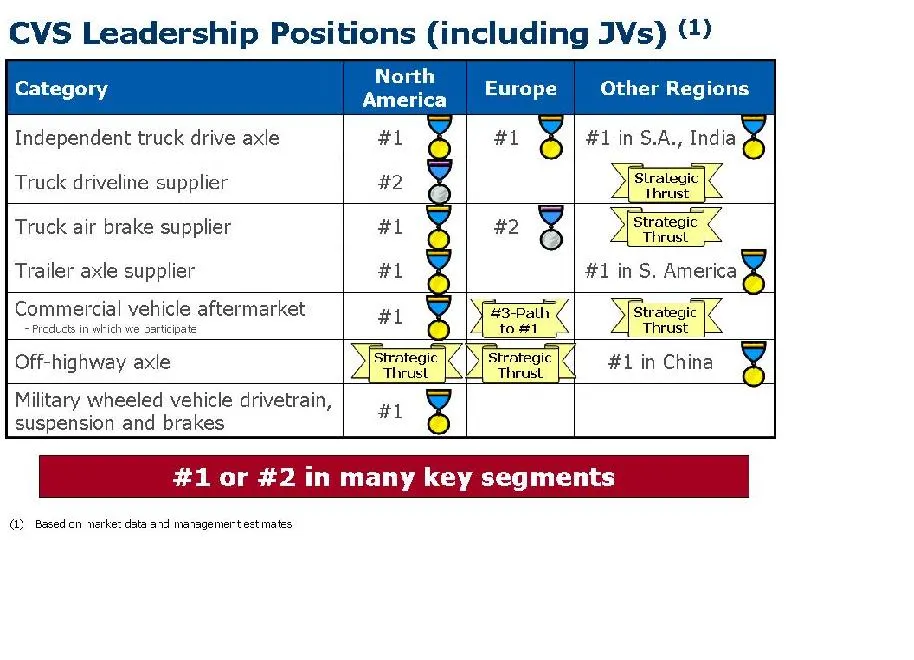
Slide 7: CVS Leadership Positions (including JVs)
CVS Leadership Positions (including JVs) (4 North Independent truck drive axle Truck driveline supplier America Europe Other Regions #1 in S.A., India Truck air brake supplier Trailer axle supplier ARES Commercial vehicle aftermarket = Predicts in which we sarticinate #1ins. America & | Off-highway
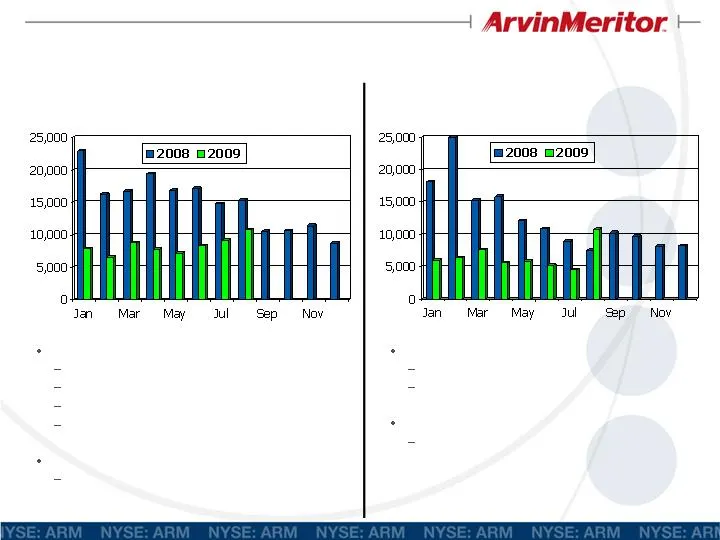
Slide 8: Truck Net Orders by Month
Truck Net Orders by Month North America August 2009 : 10,740 Highest heavy truck net orders in nine months 17% above July ’09 30% below August ’08 Credit concerns and low freight traffic continue to hold orders down at low levels Fiscal YTD average: 8,860 52% below FY08 period; seasonally adjusted r
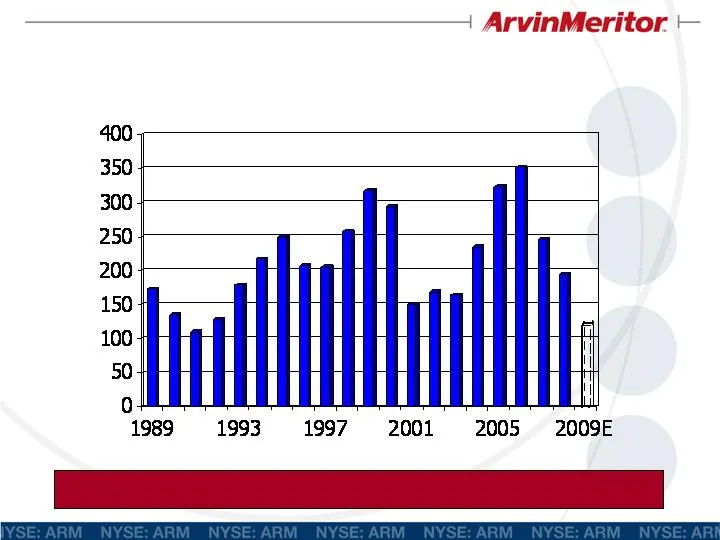
Slide 9: In bottom of trough and preparing for the upturn
In bottom of trough and preparing for the upturn Historical Class 8 Production North America Units (000)
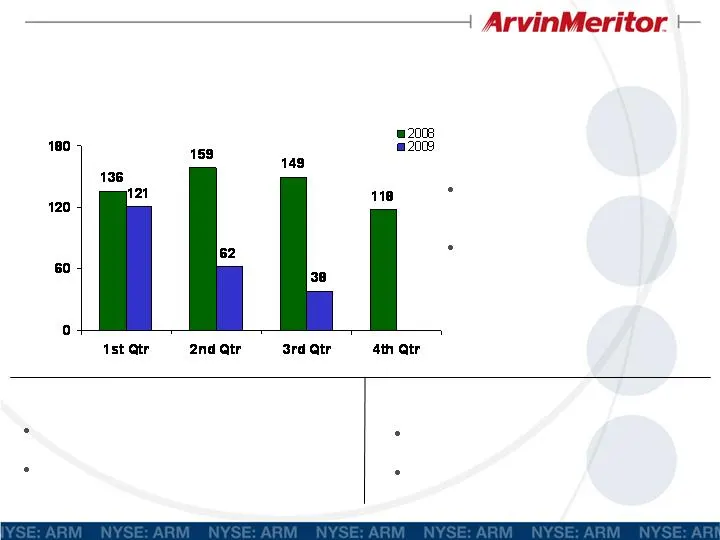
Slide 10: Commercial Vehicle Markets - ROW
Commercial Vehicle Markets - ROW Fiscal Quarters Europe Med. & Heavy Truck Production (000) Q3 production down 74% year-over-year and down 39% from Q2 More down time in fiscal Q4 South America Asia Pacific Q3 production down 36% year-over- year, but up 9% from Q2 Could see further small increases in
Slide 11: Strategic Priorities
Strategic Priorities 1. Ensure adequate liquidity while minimizing cost Clear covenants Benefit from current favorable credit agreement 2. Continued restructuring and other cost reductions Resist workforce and cost increases as volume returns Tight controls on discretionary spending Performance Plus
Slide 12: Credit Line Covenant Compliance
Credit Line Covenant Compliance Completed identified actions needed to clear covenants at September measurement New, two-year U.S. receivables financing arrangement completed on September 8, 2009 Total commitment under the facility is $125 million after additional lender participation Daily borrowin
Slide 13: Light Vehicle Systems
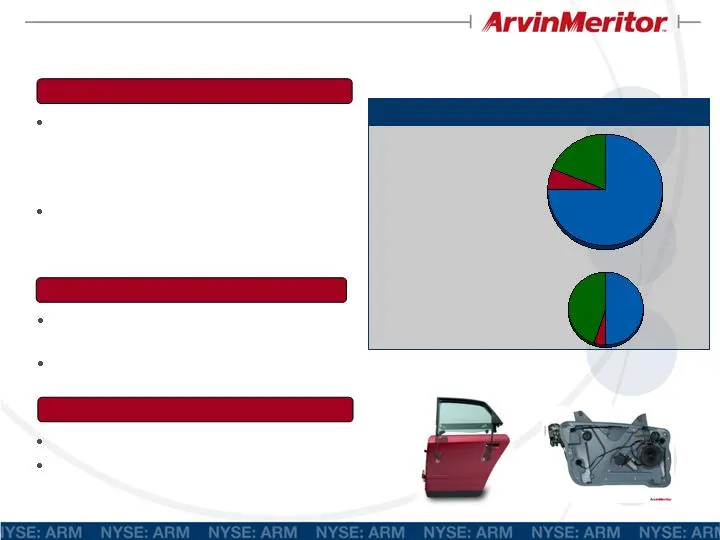
Wheels Chassis Body North America 75% Q4 Discontinued Operations Light Vehicle Systems Closed sale of Wheels to lochpe-Maxion S.A. on September 21, 2009 Received $169 million of net proceeds Chassis divestitures - Gabriel de Venezuela - Gabriel Ride Control North America - JV Mitsubishi Steel (MSSC)
Slide 14: Product Highlights
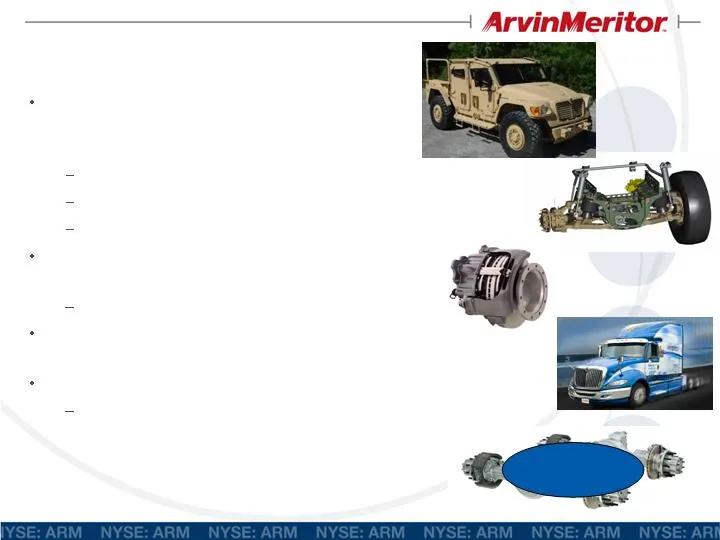
Expected launch at MATS in 2010 Product Highlights Meritor ® TACTX TM High Mobility Independent Suspension in production with British TSV program Semi-active damping shocks Meritor ® Air Suspension Height Control Lightweight aluminum carrier assemblies Expanding ELSA Disc Brake Platform into North A
Slide 15: Franchise value we can sustain and grow
Franchise value we can sustain and grow Strategic repositioning nearing completion Aggressively lowered breakeven levels with the goal of being cash flow neutral at current industry size Well-positioned to benefit from a rebound in the commercial vehicle industry Current North American industry abou
Slide 16: Frequently Asked Questions
Frequently Asked Questions 1. Will you be negatively impacted by the FMTV award to Oshkosh? 2. What is the status of your French Factoring and Swedish Securitization programs? 3. With the fourth quarter covenant issue behind you, are you planning any changes to your capital structure? 4. What exposu
Slide 17: FAQ #1: Will you be negatively impacted by the FMTV award to Oshkosh?
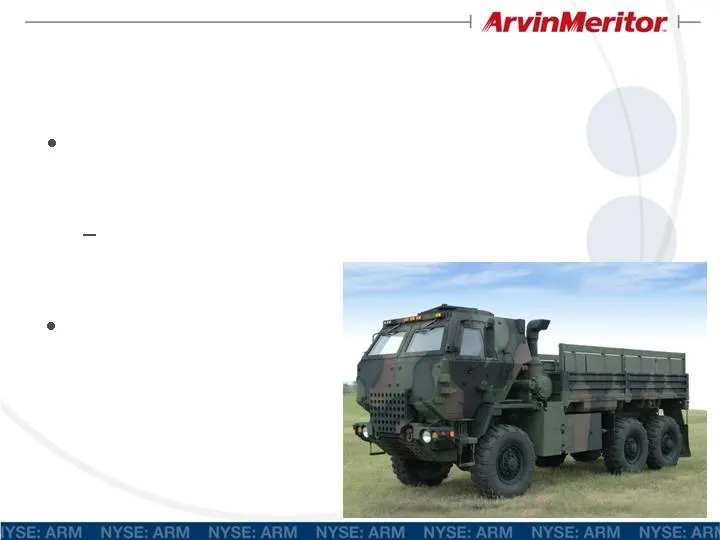
FAQ #1: Will you be negatively impacted by the FMTV award to Oshkosh? Oshkosh will fundamentally build the same FMTV vehicles as BAE Systems to maintain continuity in the military's vehicle fleet Award currently under protest by BAE Systems and Navistar We expect to supply the same components regard
Slide 18: FAQ #2: What is the status of your French Factoring and Swedish Securitization programs?
FAQ #2: What is the status of your French Factoring and Swedish Securitization programs? Both facilities backed by 364-day liquidity commitments from Nordea Bank renewed through mid-October 2009 We expect renewal of the two facilities based on verbal communication with Nordea
Slide 19: FAQ #3: Any changes to your capital structure?
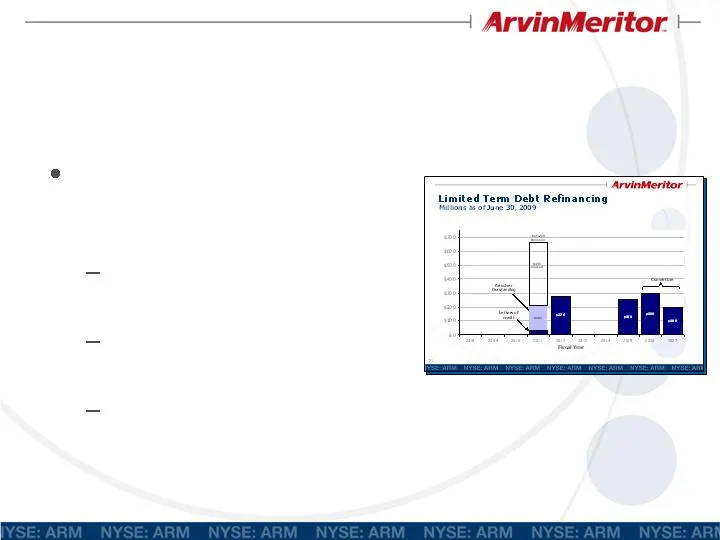
FAQ #3: With the fourth quarter covenant issue behind you, are you planning any changes to your capital structure? We continue to look at available options to address the balance sheet, including Renewing the 2011 revolver Addressing the 2012 unsecured notes Progressing towards investment grade stat
Slide 20: FAQ #4: What exposure do you have to higher steel prices?
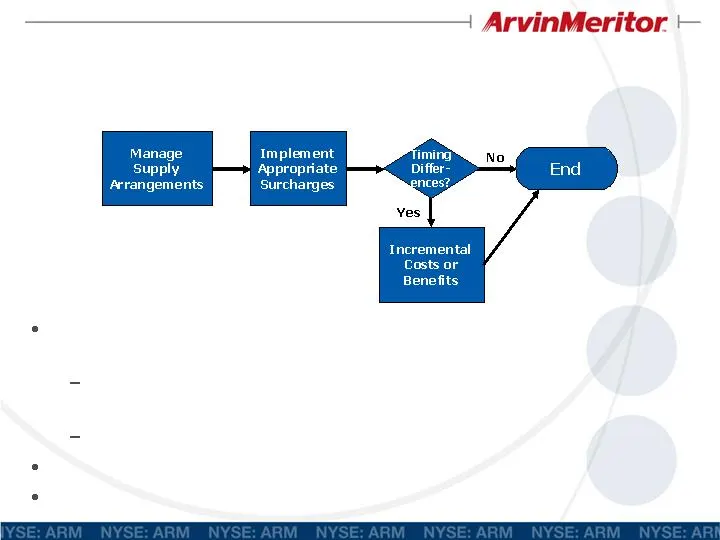
FAQ #4: What exposure do you have to higher steel prices? We do not expect to experience any significant impact from increasing steel prices Contractually recover/refund steel price differences from/to our customers Similar to prior periods of rising steel prices Surcharges will increase/decrease in
Slide 21: FAQ #5: Profitability targets relative to past cycles
FAQ #5: Do you have any targets on where your profitability could go relative to past cycles? (1) We have a long-term Return on Equity target in the mid teens or higher Therefore, we have a long-term EBITDA margin target of 10% average through the cycle We believe becoming exclusively a commercial v
Slide 22: ArvinMeritor
ArvinMeritor www.arvinmeritor.com
Source: SEC EDGAR · 8-K filed Sep 30, 2009
More decks from Meritor Inc
 Merger or Acquisition (March 2022)12 slides · Mar 7, 2022
 Merger or Acquisition (February 2022)8 slides · Feb 22, 2022
 Investor Day (December 2021)66 slides · Dec 7, 2021
 Merger or Acquisition (May 2019)14 slides · May 8, 2019
 Investor Day (December 2018)66 slides · Dec 6, 2018
 Investor Day (December 2017)70 slides · Dec 7, 2017