Evans Bancorp — Sterne Agee Financial Institutions Investor Conference 2013
29 slides from Evans Bancorp's conference presentation, Feb 12, 2013
Slide 1: Sterne Agee Financial Institutions Investor Conference
Sterne Agee Financial Institutions Investor Conference February 12-13, 2013 NYSE MKT: EVBN Gary A. Kajtoch Executive Vice President & CFO David J. Nasca President & CEO Exhibit 99
Slide 2: Safe Harbor Statement
Safe Harbor Statement Safe Harbor Statement This presentation includes "forward looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements include, but are not limited to, statements concerning future business, revenue and earnings. These statemen
Slide 3: Evans Bancorp, Inc. (NYSE MKT: EVBN)
Recent Price $17.15 52 week range $12.90-18.70 Market Capitalization Total Shares Outstanding 4.17 million Ownership – Insider 5.9% Institutional 32.2% Dividend Yield 2.8% Total Assets $809.7 million Total Gross Loans (excluding Leases) $581.3 million Total Deposits $679.0 million Total Common Equit
Slide 4: Geographic Reach
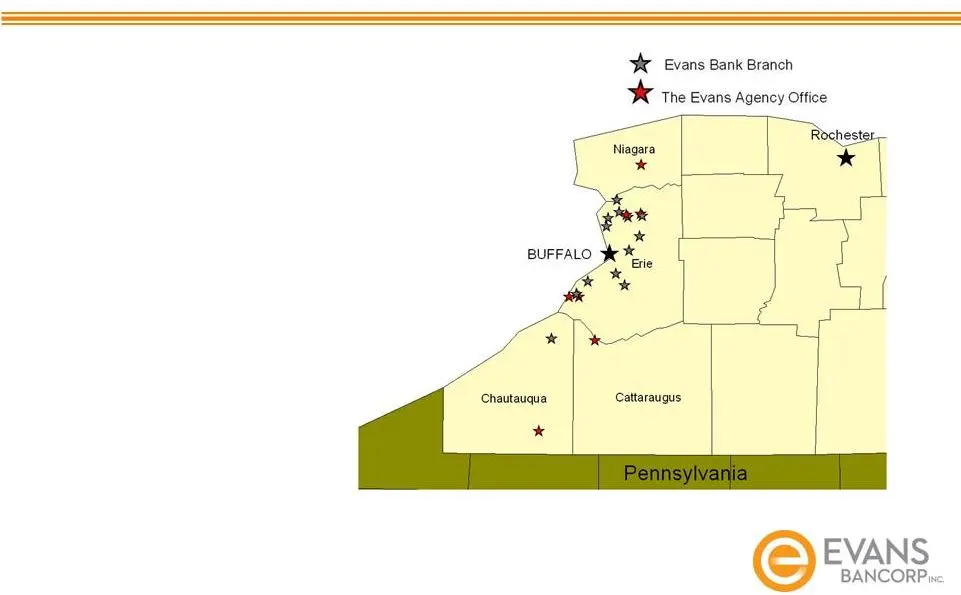
Geographic Reach Geographic Reach As of December 31, 2012 Evans Established: 1920 Bank Branches: 13 Insurance Agency Locations: 7
Slide 5: Diversified Financial Services Company
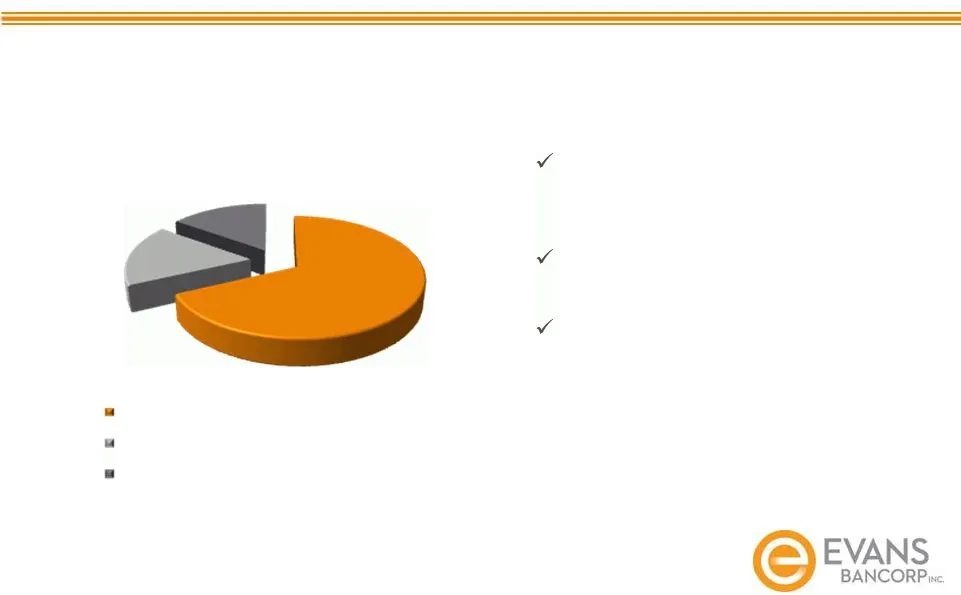
15% Diversified Financial Services Company Diversified Financial Services Company Diversified Revenue Sources 2012: $40.6 million Approximately 32% of revenue from non-interest sensitive relationships Significant insurance agency presence in WNY Focus on commercial lending and portfolio diversificat
Slide 6: Foundation for Growth
Organic Growth Scalable Organization Capital Sufficiency Commercial Portfolio Branding Talent Management Non-Interest Income Focus Foundation for Growth Foundation for Growth
Slide 7: Market Strategies
Market Strategies Market Strategies Laser-focused upon WNY market Proactive customer acquisition and sales efforts Loan portfolio diversification leads the way Alternative channels: Strong web presence, mobile banking and first to market with remote deposit capture Incent value-added and solution-ba
Slide 8: Successful Performance
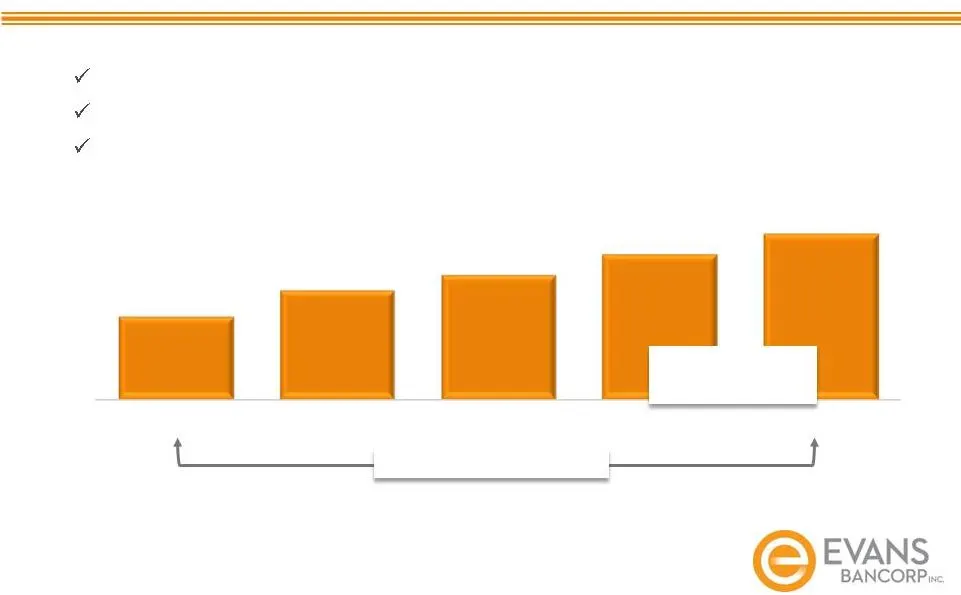
Successful Performance Successful Performance ($ in millions) Expanded asset base through organic loan growth and acquisition Increased future earnings power potential Assets expanded 83% since restructuring balance sheet in 2007 11.2% CAGR (2008 – 2012) Asset growth of 53% $529.0 $619.4 $671.5 $740
Slide 9: Opportunity for Expansion
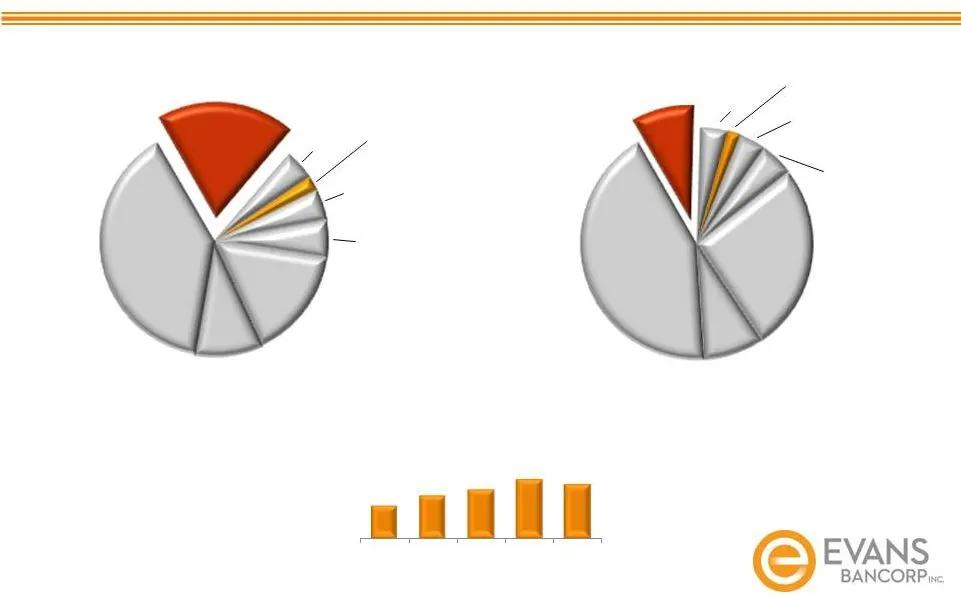
HSBC 19.6% HSBC 8.8% Source: FDIC, as of June 30, 2011 and 2012 Opportunity for Expansion Opportunity for Expansion Market Share by Deposits $26.2B Total Deposits M&T 39.0% Key Bank 9.6% First Niagara 15.8% Evans 2.1% Citizens 5.3% Bank of America 4.43% All Others 4.3% $32.3B Total Deposits M&T 42.7
Slide 10: Financial Highlights and Results
Financial Highlights and Results
Slide 11: Core Banking: Loan Growth
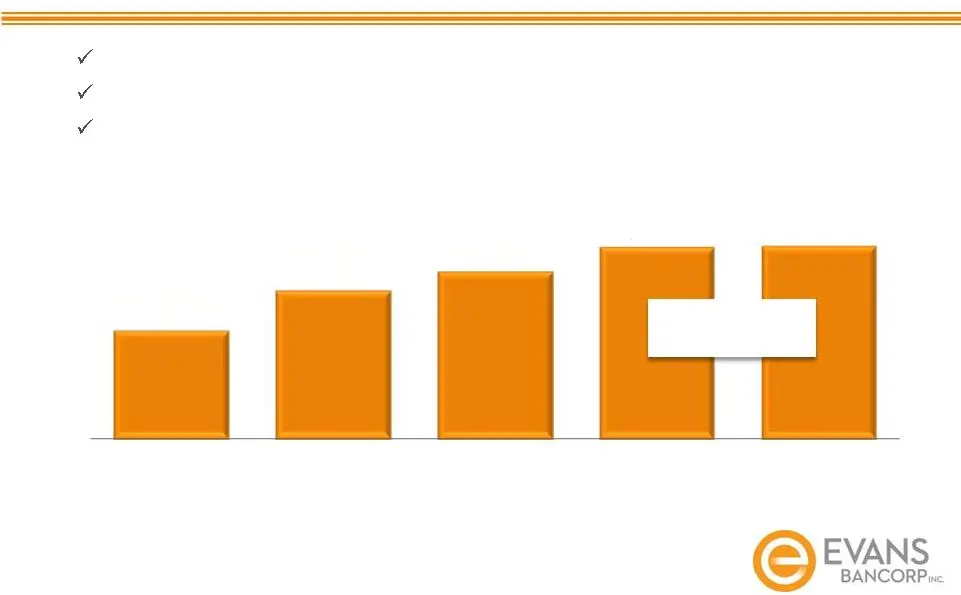
Core Banking: Loan Growth Core Banking: Loan Growth High quality in-market commercial loans Capturing strong credits from larger banks Supports core business strategy ($ in millions) $349.1 $458.1 $512.5 $577.4 $581.3 13.6% CAGR (2008 – 2012)
Slide 12: Diverse Loan and Lease Portfolio
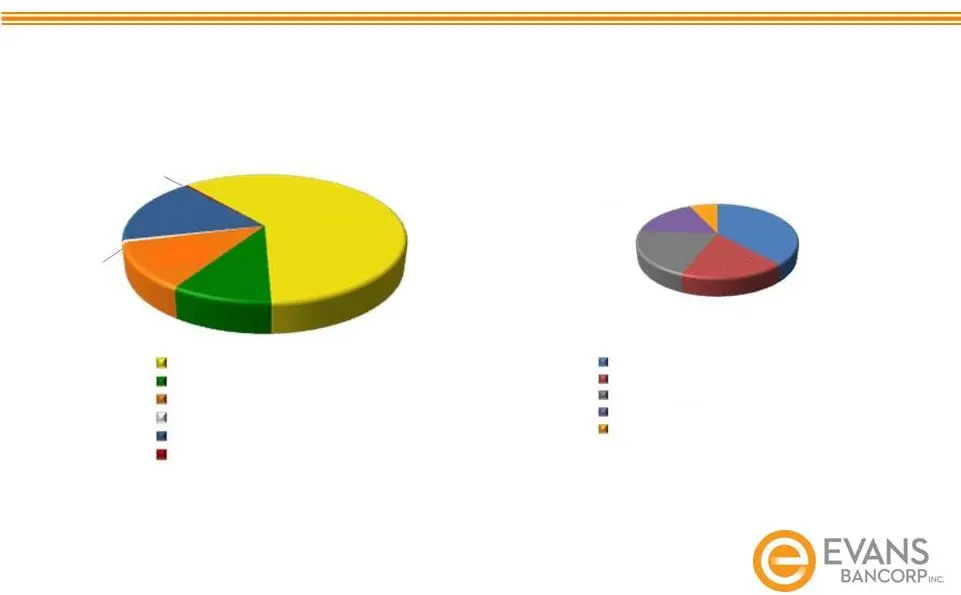
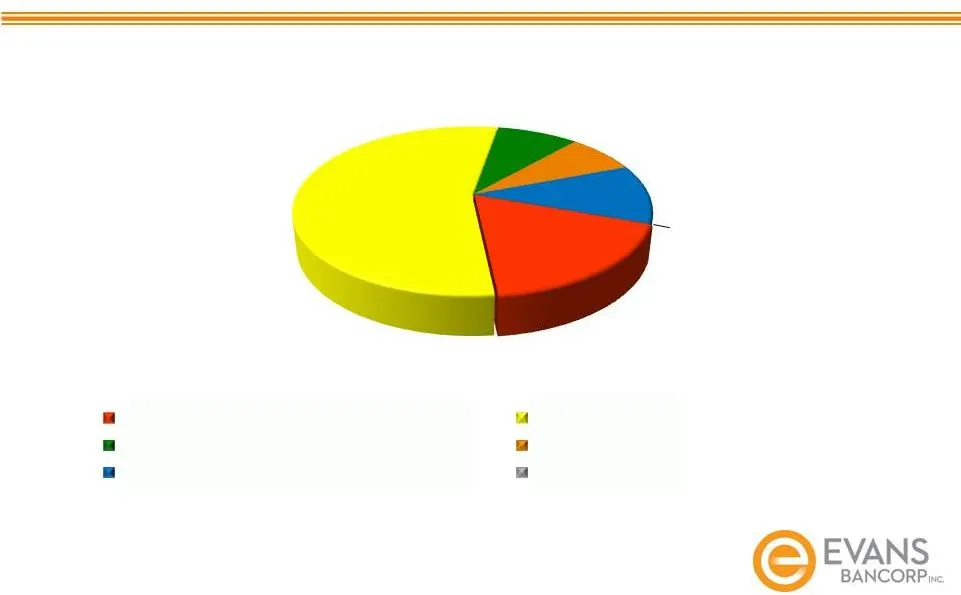
9.7% 11.8% 17.1% 38.4% 17.6% 20.2% As of December 31, 2012 Diverse Loan and Lease Portfolio Diverse Loan and Lease Portfolio * Includes construction loans Commercial Loans Total Loans and Lease Portfolio: $582.9 million 60.5% 0.6% 0.3% Commercial Mortgages* Home Equities Residential Mortgages* Consu
Slide 13: Asset Quality: NPAs to Total Loan + OREO
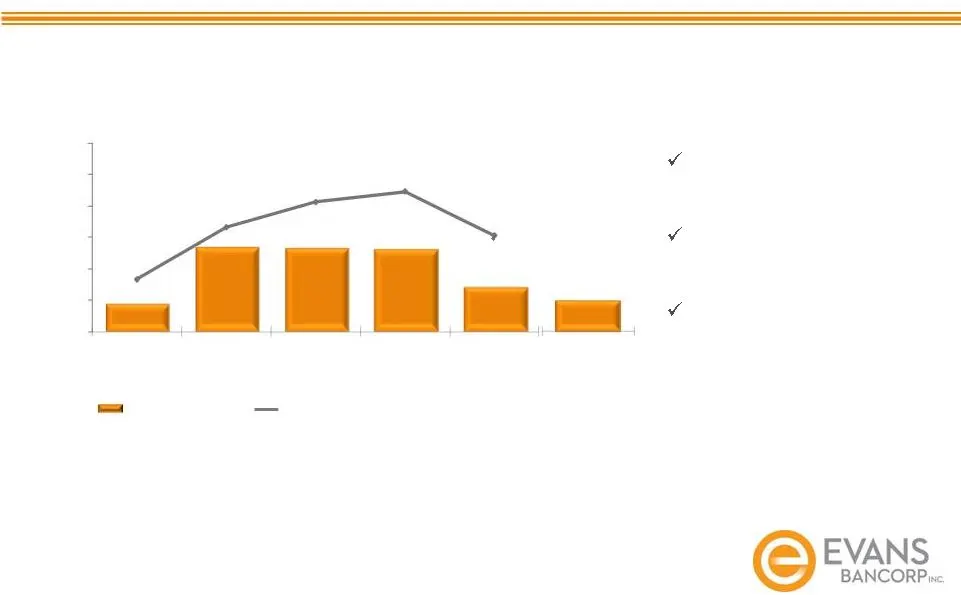
NPAs to Total Loan + OREO * Peer data per SNL Booking high quality assets Solid underwriting discipline Strong customer relationships EVBN (GAAP) Banks > $500 Million and < $1 Billion in Assets* 0.89% 2.65% 2.64% 2.60% 1.41% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 1.11% EVBN without ENL & WVB Asse
Slide 14: Conservative Credit Quality
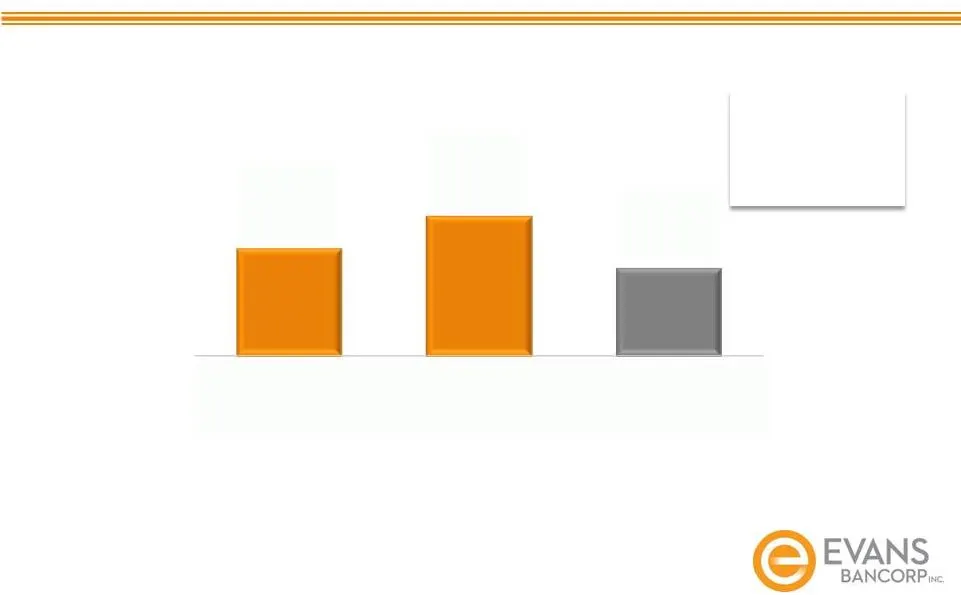
Conservative Credit Quality Conservative Credit Quality Allowance for Loan Loss / Non-Accruals Q4 2012 * Peer data per SNL Allowance to Loan Ratio (as of 12/31/2012) 1.67% ** Allowance for ENL: $47 thousand; Allowance for WVB: $119 thousand 118.3% 154.1% 96.1% EVBN (GAAP) EVBN with ENL & WVB** Banks
Slide 15: Q4 2012 Non-Performing Loans by Portfolio
$1.4 $0.7 $0.6 $0.9 Q4 2012 Non-Performing Loans by Portfolio ($ in millions) Asset Quality Asset Quality NPL Ratios by Portfolio $4.3 $0.04 Residential Mortgage (2.12%) Commercial & Multi-Family (1.33%) Construction (2.45%) Home Equity (1.10%) Commercial Loans (0.91%) Consumer (1.36%)
Slide 16: Low Cost Core Deposits
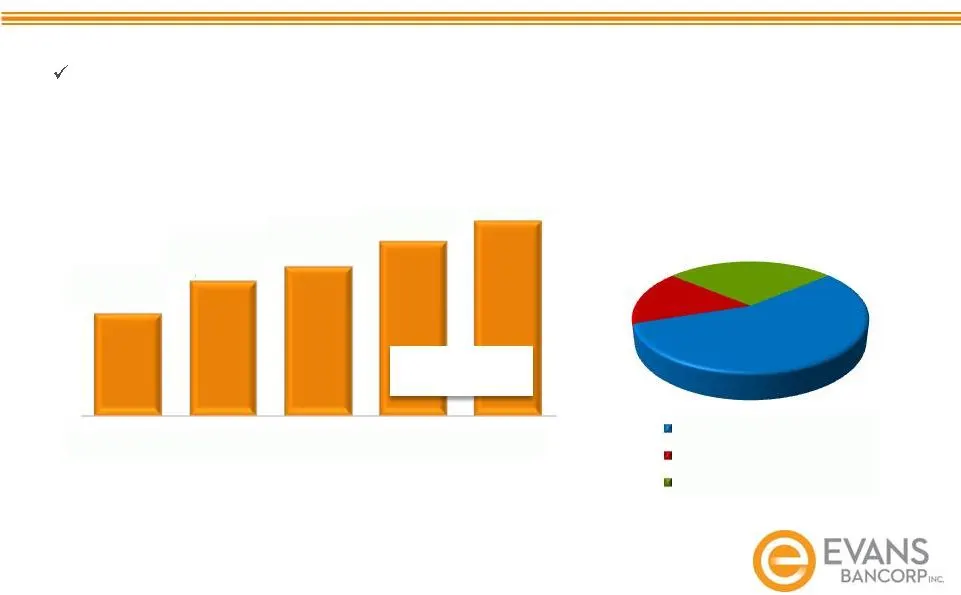
56.1% 16.0% 27.9% Low Cost Core Deposits Low Cost Core Deposits ($ in millions) 13.9% CAGR (2008 – 2012) 13.4% increase since December 31, 2011 in regular savings, demand deposits and NOW deposits Deposit Composition: $679.0 million $404.0 $499.5 $544.5 $616.2 $679.0 Savings & Money Market Time Depo
Slide 17: Strong Margins and Revenue Growth
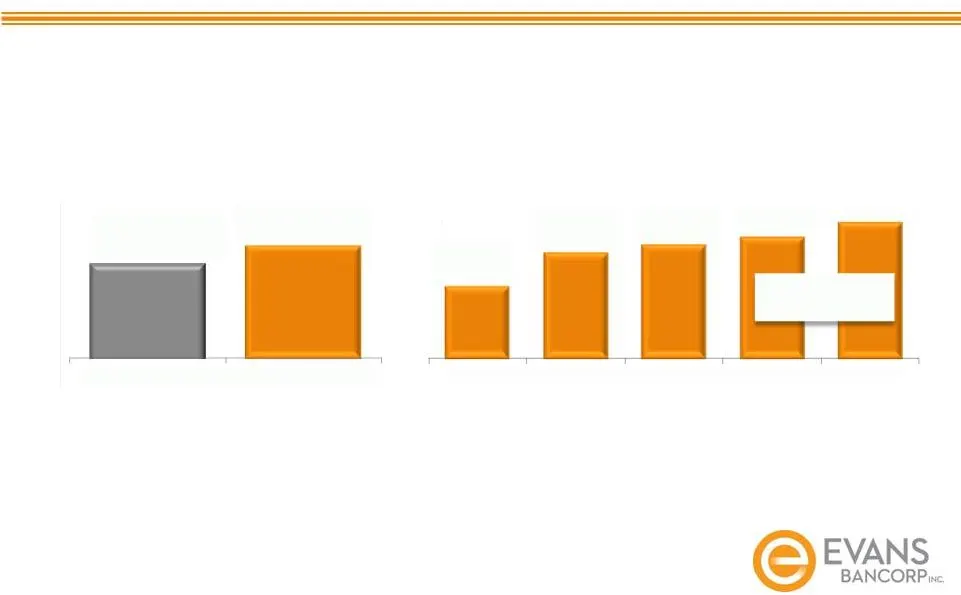
* Excludes $0.7 million gain on bargain purchase Strong Margins and Revenue Growth Strong Margins and Revenue Growth Net Interest Margin Comparison Q4 2012 Revenue * Peer data per SNL **Q4 Net Interest Margin includes loan prepayment fees. Q4 2012 NIM excluding these fees equals 3.69%. ($ in million
Slide 18: Non-Interest Income
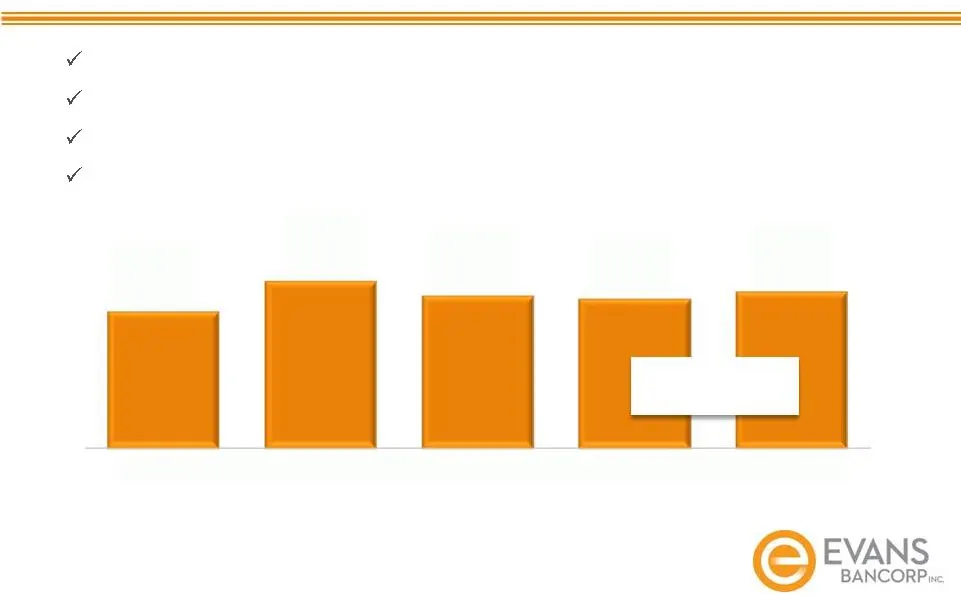
Fee income less rate sensitive Capitalize on relationship management Insurance 54% of 2012 non-interest income Focusing on growing commercial lines 2.3% CAGR (2008 – 2012) Non-Interest Income Non-Interest Income * Excludes $0.7 million gain on bargain purchase. ($ in millions) $11.7 $13.4 $12.6 $12.
Slide 19: Bottom-line Results
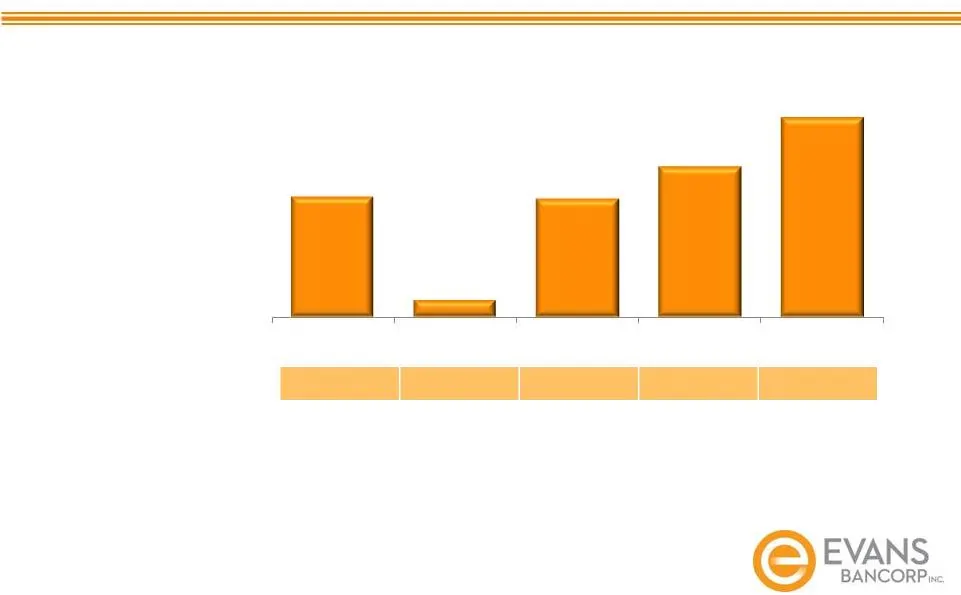
Bottom-line Results Bottom-line Results ($ in millions) Net Income $ 1.78 $ 0.25 $ 1.34 $ 1.49 $ 1.95 Earnings Per Share * (diluted) * 2009 and 2010 EPS include leasing losses of $(1.35) and $(0.09), respectively $4.9 $0.7 $4.8 $6.1 $8.1 2009* 2010*
Slide 20: Fourth Quarter – Core Business Strength
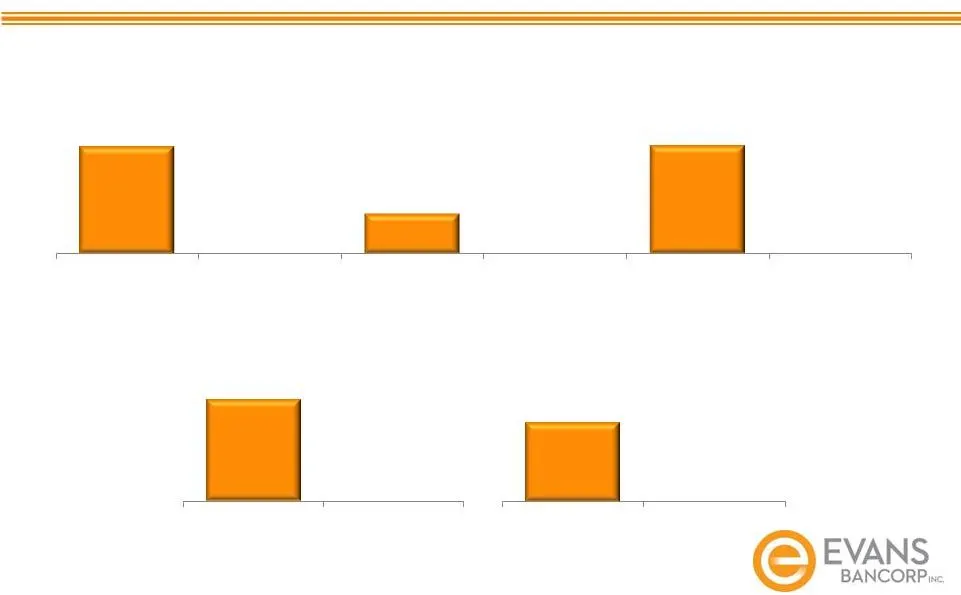
Fourth Fourth Quarter Quarter – – Core Business Strength Core Business Strength ($ in millions, except per share data; % y-o-y) Net Interest Income Non-Interest Income Non-Interest Expense Net Income Earnings Per Share (diluted) Increased 3.0% Increased 14.7% Increased 1.9% Increased 58.6% Increased
Slide 21: Building Return on Capital
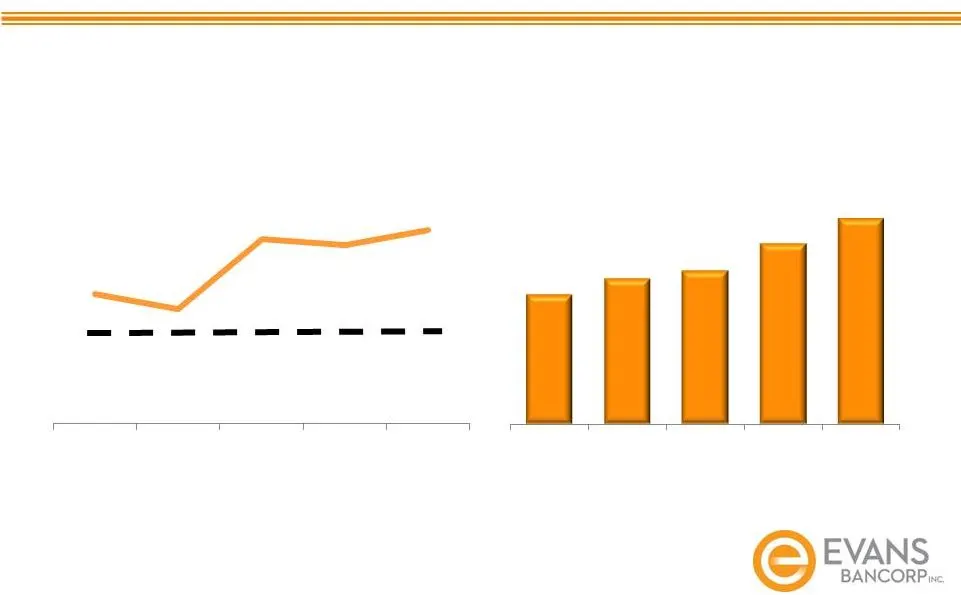
10% Regulatory guideline Tangible Book Value Building Return on Capital Building Return on Capital 11.8% 11.2% 14.3% 14.0% 14.7% $11.90 $12.72 $13.18 $14.60 $15.92 Total Risk Based Capital
Slide 22: Driving Growth, Managing Risk
Driving Growth Managing Risk
Slide 23: Why Growth is Important
Why Growth is Important Why Growth is Important Competitive Pressures Margin Compression Regulatory Burden Expansion Requirements for Increased Capital
Slide 24: Opportunity: Organic and Human Capital
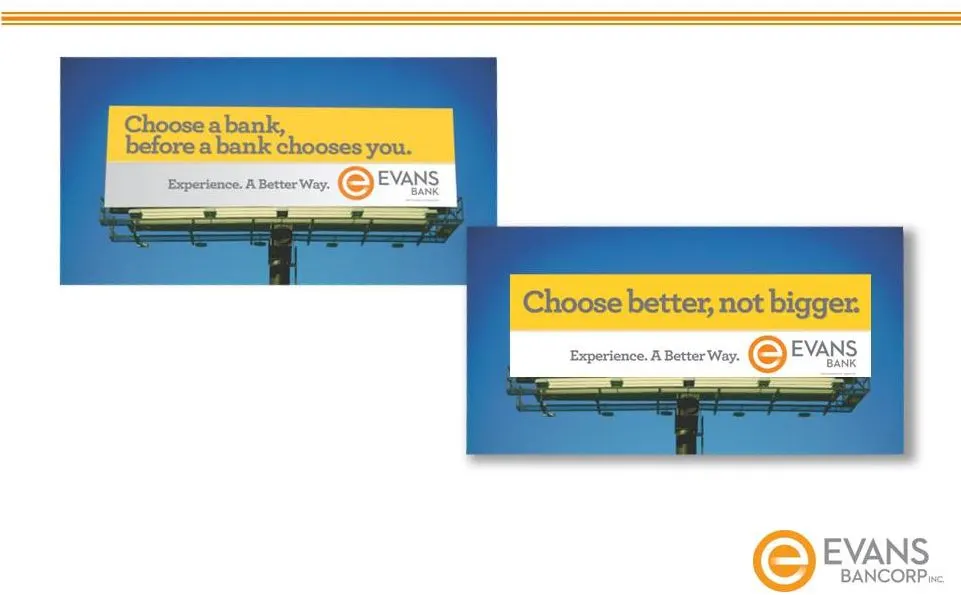
Opportunity: Organic and Human Capital Market Disruption Created Opportunity Market Disruption Created Opportunity
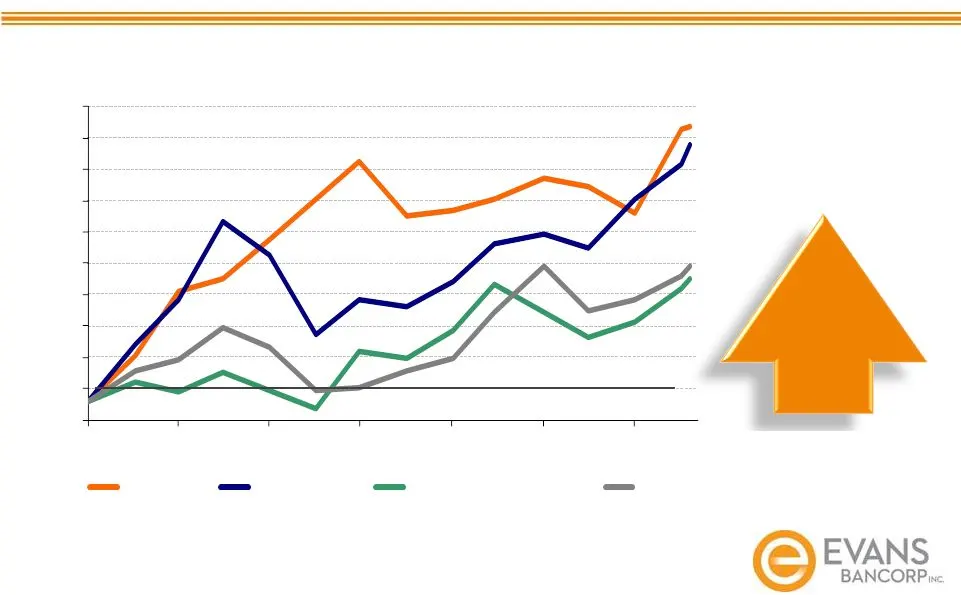
Slide 25: Stock Market Performance
44% EVBN EVBN outperformed Local Banks & High Performing Peer groups since 1/1/12 Stock Market Performance Stock Market Performance (through 2/6/2013) EVBN SNL Bank High Performing Peers Local -3% 2% 7% 12% 17% 22% 27% 32% 37% 42% 47% Dec-11 Feb-12 Apr-12 Jun-12 Aug-12 Oct-12 Dec-12
Slide 26: Investment Highlights
Diverse revenue mix, strong operating fundamentals Strong and growing franchise in WNY Sophisticated / experienced management team Solid capital base Quality core deposit growth Low risk balance sheet Shareholder return orientation Historically reasonable valuation Investment Highlights Investment H
Slide 27: NYSE MKT: EVBN Sterne Agee Financial Institutions Investor Conference
NYSE MKT: EVBN Sterne Agee Financial Institutions Investor Conference February 12-13, 2013
Slide 28: Evans Bancorp, Inc.
Experience. A Better Way. EVA N S BANCORP ic.
Slide 29: Executive Compensation
Executive Compensation Base Salary : – Benchmarked against peer group – Scope and complexity of position – Market value of job – Level of expertise – Performance in position – Company performance factors Short-Term Cash Incentives: – Performance compared to financial, operational and strategic goals
Source: SEC EDGAR · 8-K filed Feb 12, 2013
More decks from Evans Bancorp Inc
 Piper Sandler & Co East Coast Financial Services Conference 202324 slides · Nov 15, 2023
 Investor Presentation (August 2023)24 slides · Aug 8, 2023
 HOVDE Financial Services Conference 202226 slides · Nov 2, 2022
 Raymond James Conference 202225 slides · Sep 7, 2022
 Investor Presentation (June 2022)25 slides · Jun 7, 2022
 Q4 2021 Earnings Presentation9 slides · Feb 3, 2022