FGX International Holdings LTD
FGX International — Investor Presentation (December 2008)
22 slides from FGX International's investor presentation, Dec 8, 2008
Slide 1: Management Presentation December 2008
1 Management Presentation December 2008
Slide 2: Forward-looking statements
2 This presentation contains forward-looking statements (as defined in the Private Securities Litigation Reform Act of 1995) that are based on current expectations, estimates, forecasts and projections, as the case may be, and as such involve substantial risks and uncertainties. All statements, othe
Slide 3: The FGX Advantage
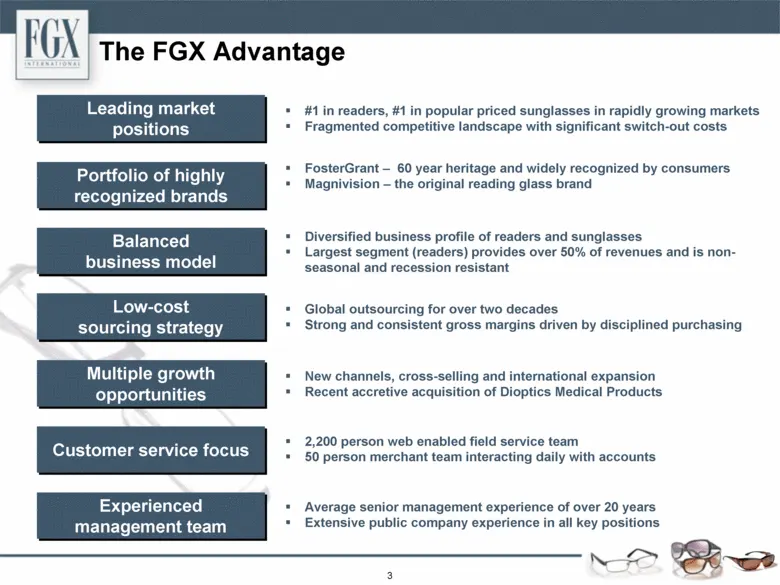
3 The FGX Advantage Leading market positions Portfolio of highly recognized brands Balanced business model Low-cost sourcing strategy Multiple growth opportunities Customer service focus · #1 in readers, #1 in popular priced sunglasses in rapidly growing markets · Fragmented competitive landscape wi
Slide 4: Leading Market Positions in Key Product Categories
4 Leading Market Positions in Key Product Categories · Foster Grant + Magnivision creates leading share in a growing market estimated at 50%+ share in category that grows low double digits · Magnivision – the original reading glass brand has #1 market share · Foster Grant #1 market share in mass/pop
Slide 5: Compelling Industry Trends
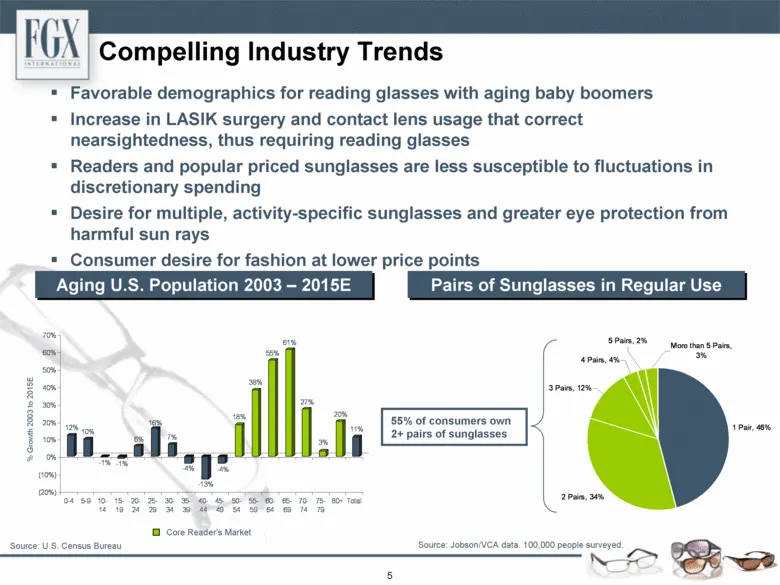
5 Compelling Industry Trends · Favorable demographics for reading glasses with aging baby boomers · Increase in LASIK surgery and contact lens usage that correct nearsightedness, thus requiring reading glasses · Readers and popular priced sunglasses are less susceptible to fluctuations in discretion
Slide 6: Portfolio of Highly Recognized, Quality Eyewear Brands
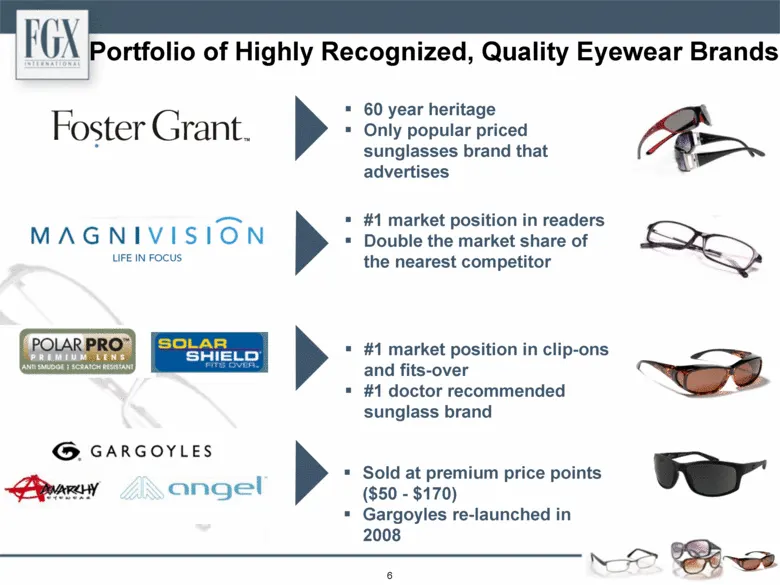
6 Portfolio of Highly Recognized, Quality Eyewear Brands · 60 year heritage · Only popular priced sunglasses brand that advertises · #1 market position in readers · Double the market share of the nearest competitor · #1 market position in clip-ons and fits-over · #1 doctor recommended sunglass brand
Slide 7: Capitalize on Existing Brand Awareness
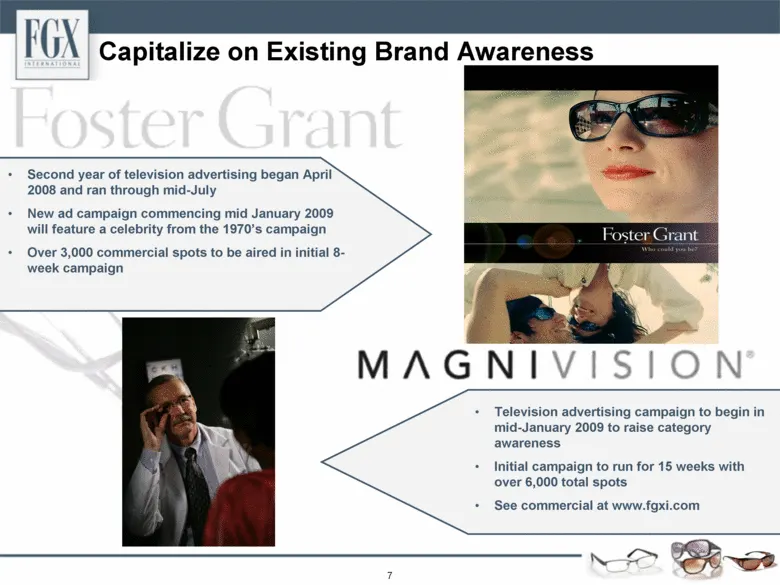
7 Capitalize on Existing Brand Awareness • Television advertising campaign to begin in mid-January 2009 to raise category awareness • Initial campaign to run for 15 weeks with over 6,000 total spots • See commercial at www.fgxi.com • Second year of television advertising began April 2008 and ran thr
Slide 8: Balanced Business Model
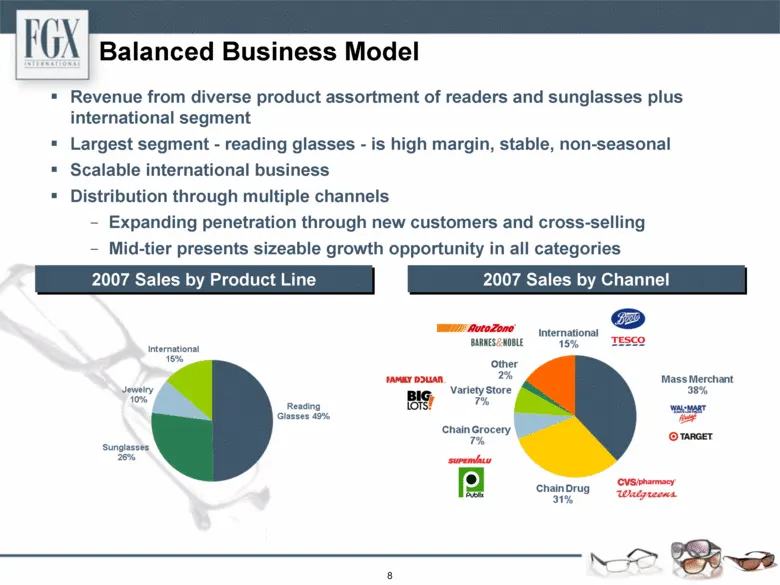
8 Balanced Business Model 2007 Sales by Product Line 2007 Sales by Channel · Revenue from diverse product assortment of readers and sunglasses plus international segment · Largest segment - reading glasses - is high margin, stable, non-seasonal · Scalable international business · Distribution throug
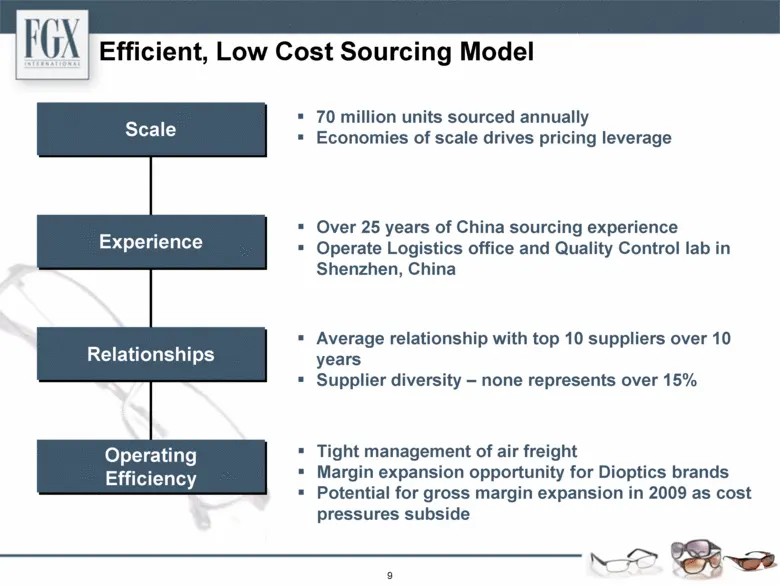
Slide 9: Efficient, Low Cost Sourcing Model
9 Efficient, Low Cost Sourcing Model Scale Experience Relationships Operating Efficiency · 70 million units sourced annually · Economies of scale drives pricing leverage · Over 25 years of China sourcing experience · Operate Logistics office and Quality Control lab in Shenzhen, China · Average relat
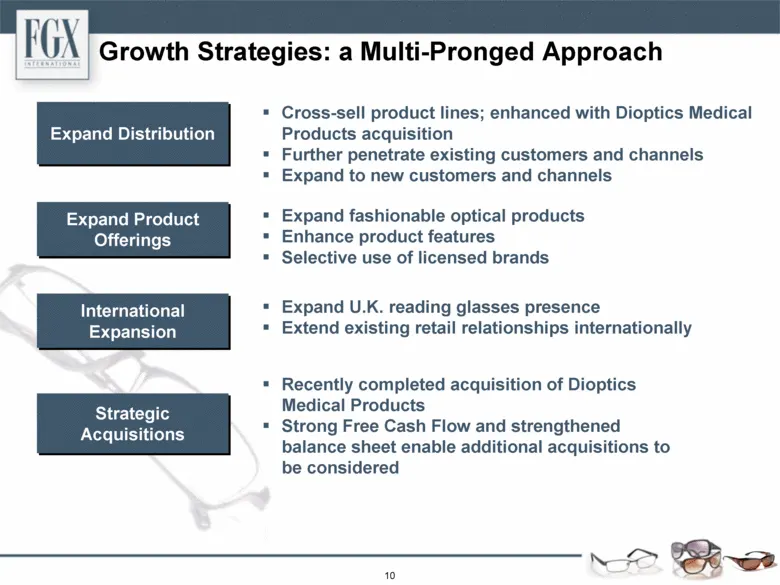
Slide 10: Growth Strategies: a Multi-Pronged Approach
10 Growth Strategies: a Multi-Pronged Approach Expand Distribution Cross-sell product lines; enhanced with Dioptics Medical Products acquisition Further penetrate existing customers and channels Expand to new customers and channels Expand Product Offerings Expand fashionable optical products Enhance
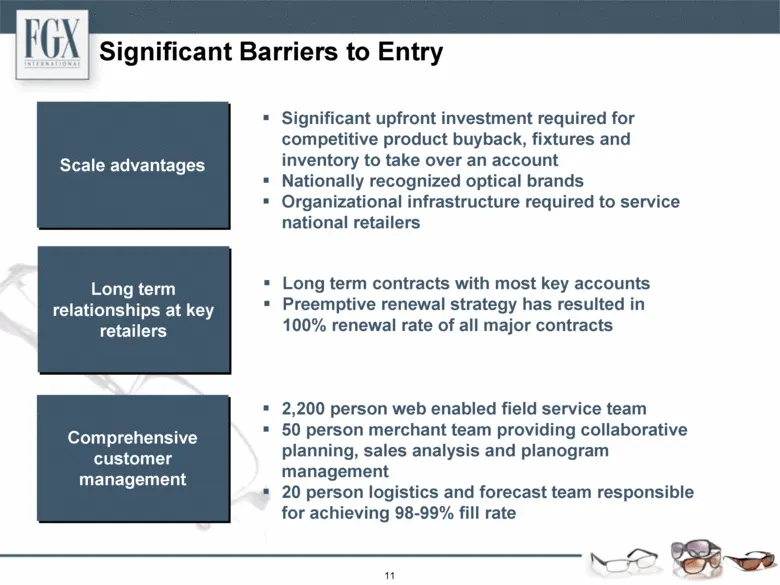
Slide 11: Significant Barriers to Entry
11 Significant Barriers to Entry Comprehensive customer management 2,200 person web enabled field service team 50 person merchant team providing collaborative planning, sales analysis and planogram management 20 person logistics and forecast team responsible for achieving 98-99% fill rate Scale adva
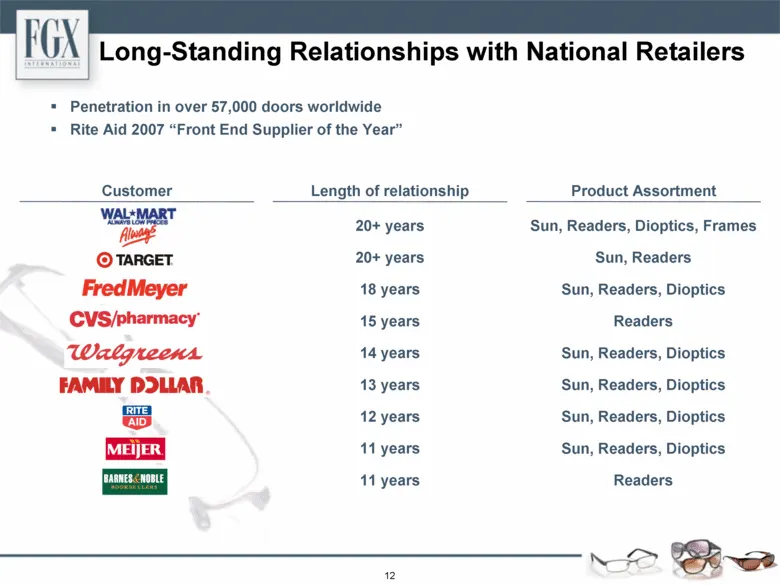
Slide 12: Long-Standing Relationships with National Retailers
12 Long-Standing Relationships with National Retailers Length of relationship Product Assortment Customer 20+ years 20+ years 18 years 15 years 14 years 13 years 12 years 11 years 11 years Sun, Readers, Dioptics, Frames Sun, Readers Sun, Readers, Dioptics Readers Sun, Readers, Dioptics Sun, Readers,
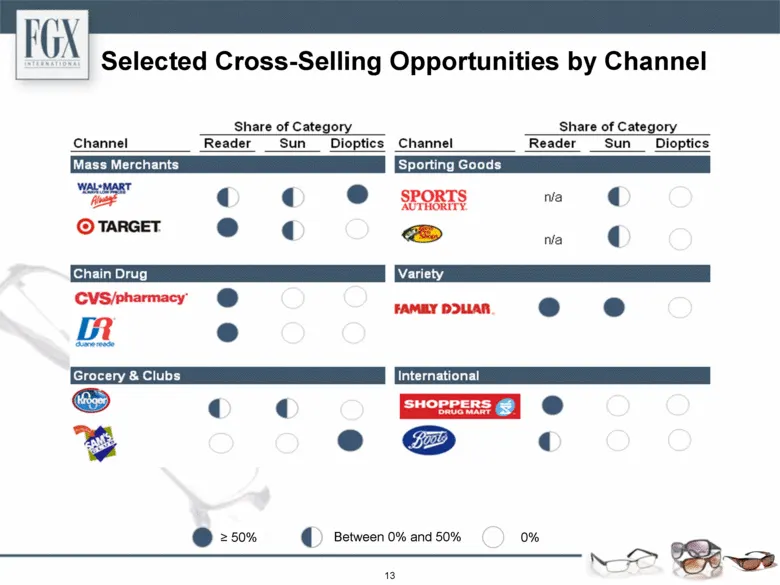
Slide 13: Selected Cross-Selling Opportunities by Channel
13 Selected Cross-Selling Opportunities by Channel > 50% Between 0% and 50% 0%
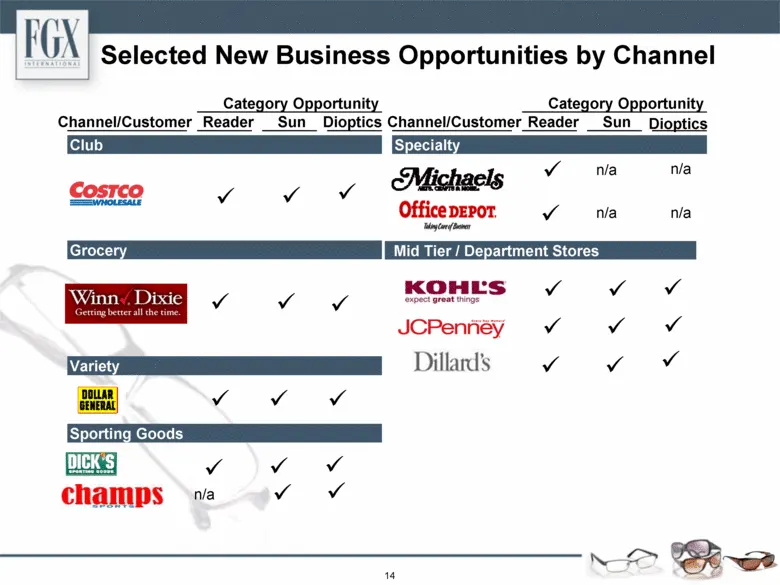
Slide 14: Selected New Business Opportunities by Channel
14 Selected New Business Opportunities by Channel Category Opportunity Category Opportunity Channel/Customer Reader Sun Dioptics Channel/Customer Reader Sun Dioptics Club Specialty Grocery Mid Tier / Department Stores Variety Sporting Goods n/a n/a n/a n/a n/a
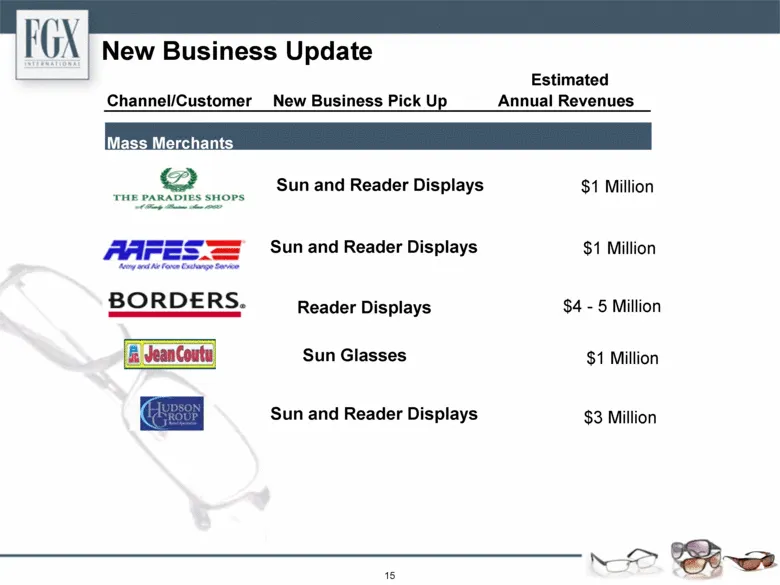
Slide 15: New Business Update
15 New Business Update Estimated Channel/Customer New Business Pick Up Annual Revenues Mass Merchants Specialty Sun and Reader Displays $1 Million Sun and Reader Displays $1 Million Reader Displays $4 - 5 Million Sun Glasses $1 Million Sun and Reader Displays $3 Million
Slide 16: Strong Capital Structure to Support Growth
16 Strong Capital Structure to Support Growth Current loan facility includes $100 million term loan with a $75 million revolving credit facility and a $50 million accordion feature Interest rate swap - fixed interest rate at 3.2% plus LIBOR for $50 million of term loan; balance floats at LIBOR + 1.7
Slide 17: Dioptics Acquisition Overview
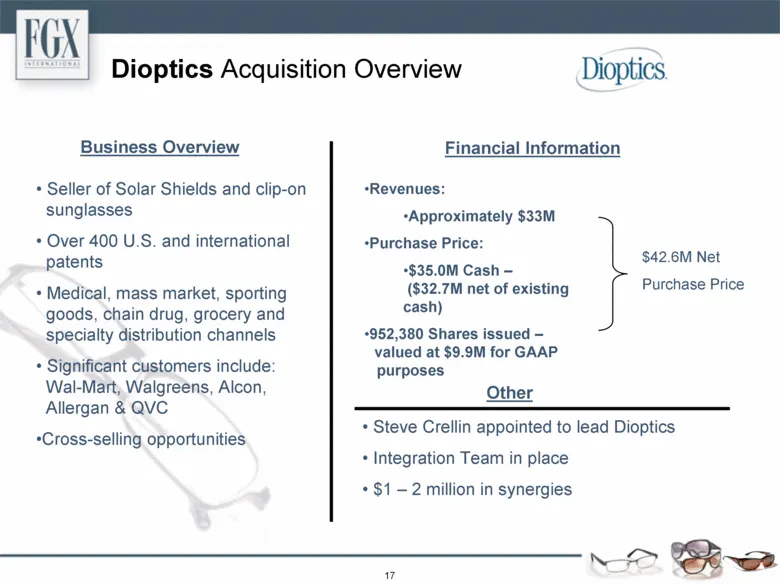
17 Dioptics Acquisition Overview Other Financial Information Business Overview • Seller of Solar Shields and clip-on sunglasses • Over 400 U.S. and international patents • Medical, mass market, sporting goods, chain drug, grocery and specialty distribution channels • Significant customers include: W
Slide 18: Historical Financial Performance Summary Income Statement
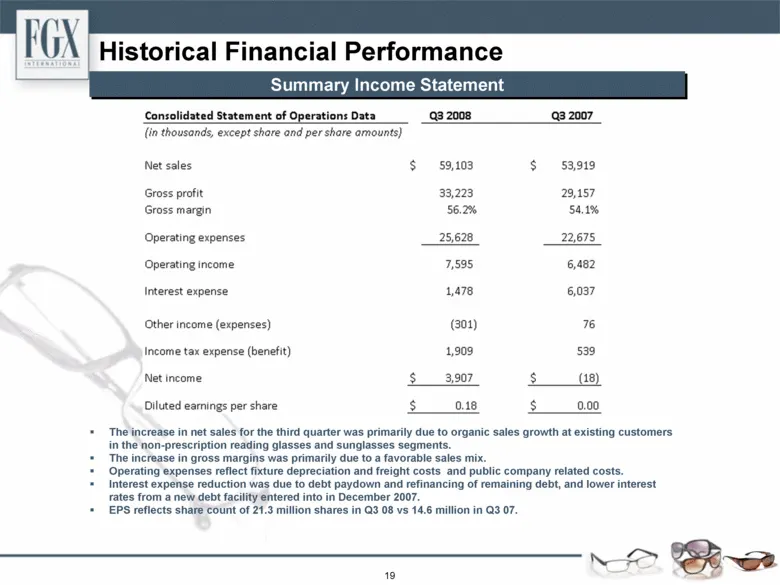
19 Historical Financial Performance Summary Income Statement The increase in net sales for the third quarter was primarily due to organic sales growth at existing customers in the non-prescription reading glasses and sunglasses segments. The increase in gross margins was primarily due to a favorable
Slide 19: Selected Balance Sheet Data and Key Working Capital Metrics
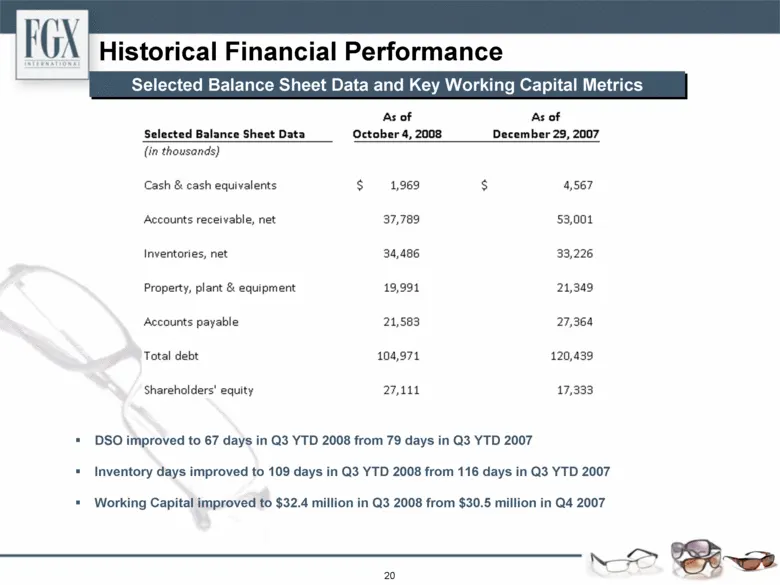
20 Historical Financial Performance Selected Balance Sheet Data and Key Working Capital Metrics DSO improved to 67 days in Q3 YTD 2008 from 79 days in Q3 YTD 2007 Inventory days improved to 109 days in Q3 YTD 2008 from 116 days in Q3 YTD 2007 Working Capital improved to $32.4 million in Q3 2008 from
Slide 20: Summary
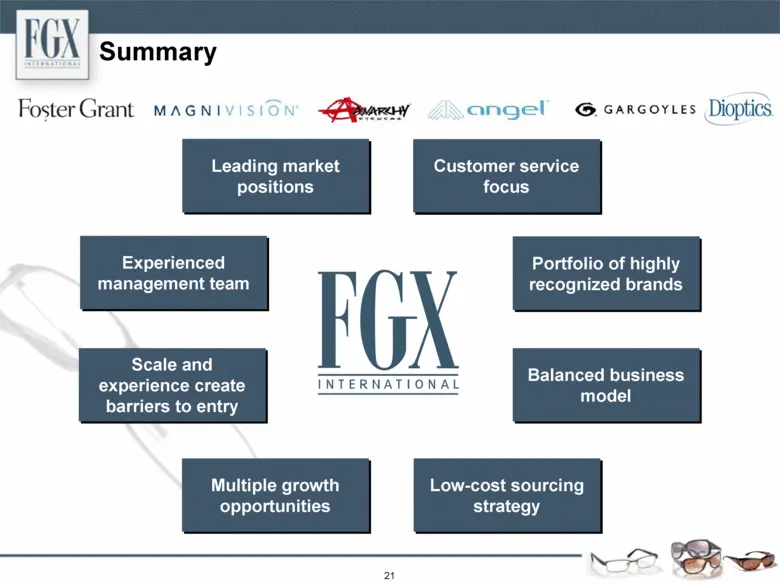
21 Summary Leading market positions Balanced business model Portfolio of highly recognized brands Low-cost sourcing strategy Scale and experience create barriers to entry Multiple growth opportunities Experienced management team Customer service focus
Slide 21: EBITDA Reconciliation
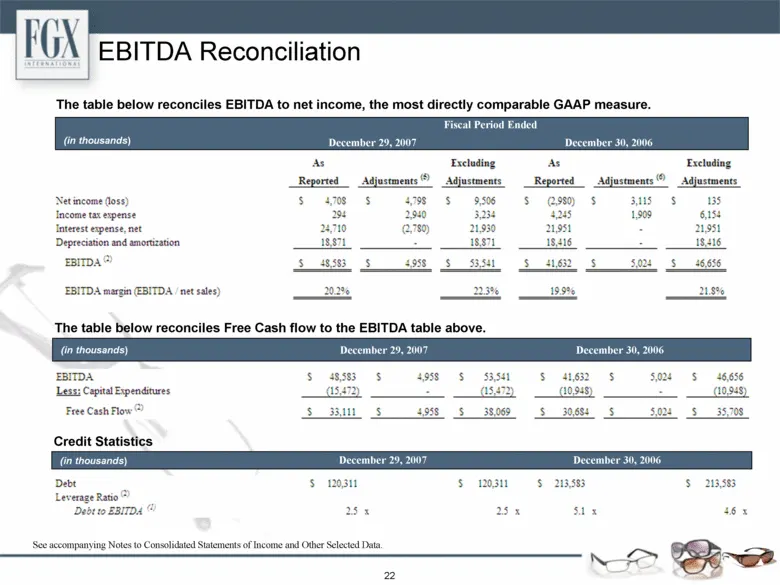
22 EBITDA Reconciliation (in thousands) The table below reconciles EBITDA to net income, the most directly comparable GAAP measure. Fiscal Period Ended December 29, 2007 December 30, 2006 (in thousands) (in thousands) The table below reconciles Free Cash flow to the EBITDA table above. December 29,
Slide 22: Notes to Consolidated Statements of Income and Other Selected Data
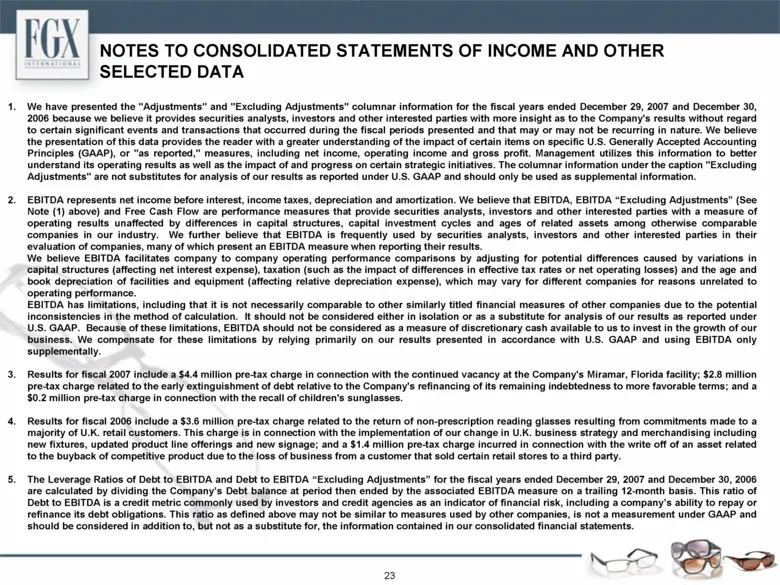
23 NOTES TO CONSOLIDATED STATEMENTS OF INCOME AND OTHER SELECTED DATA 1. We have presented the “Adjustments” and “Excluding Adjustments” columnar information for the fiscal years ended December 29, 2007 and December 30, 2006 because we believe it provides securities analysts, investors and other int
Source: SEC EDGAR · 8-K filed Dec 8, 2008
More decks from FGX International Holdings LTD
 Investor Presentation (November 2009)24 slides · Nov 9, 2009
 Investor Presentation (September 2009)24 slides · Sep 22, 2009
 Oppenheimer Annual Consumer Conference 200930 slides · Jul 13, 2009
 Investor Presentation (June 2009)29 slides · Jun 26, 2009
 Investor Presentation (June 2009)26 slides · Jun 8, 2009
 Investor Presentation (May 2009)25 slides · May 28, 2009