Alpha Natural Resources — Foundation Coal Holdings — Platts 30th Annual Coal Marketing Days (September 2007)
14 slides from Alpha Natural Resources's conference presentation, Sep 20, 2007
Slide 1: Mining the Past…Powering the Future
Exhibit 99.1 Mining the Past…Powering the Future Platts 30 th Annual Coal Marketing Days Scott Pack Senior Vice President Sales & Marketing Omni William Penn Hotel Pittsburgh, PA September 20, 2007
Slide 2: Forward-Looking Statements and Reconciliation of Non-GAAP Measures
FORWARD-LOOKING STATEMENTS AND RECONCILIATION OF NON-GAAP MEASURES Statements in this presentation which are not statements of historical fact are “forward-looking statements” within the “safe harbor” provision of the Private Securities Litigation Reform Act of 1995. These forward-looking statements
Slide 3: Presentation Overview
YE PRESENTATION OVERVIEW = Foundation Coal Highlights u Attractive Asset Base = Positive Outlook for Growth =u Proven Market Strategy = Summary Scorecard
Slide 4: A Commitment to Safety
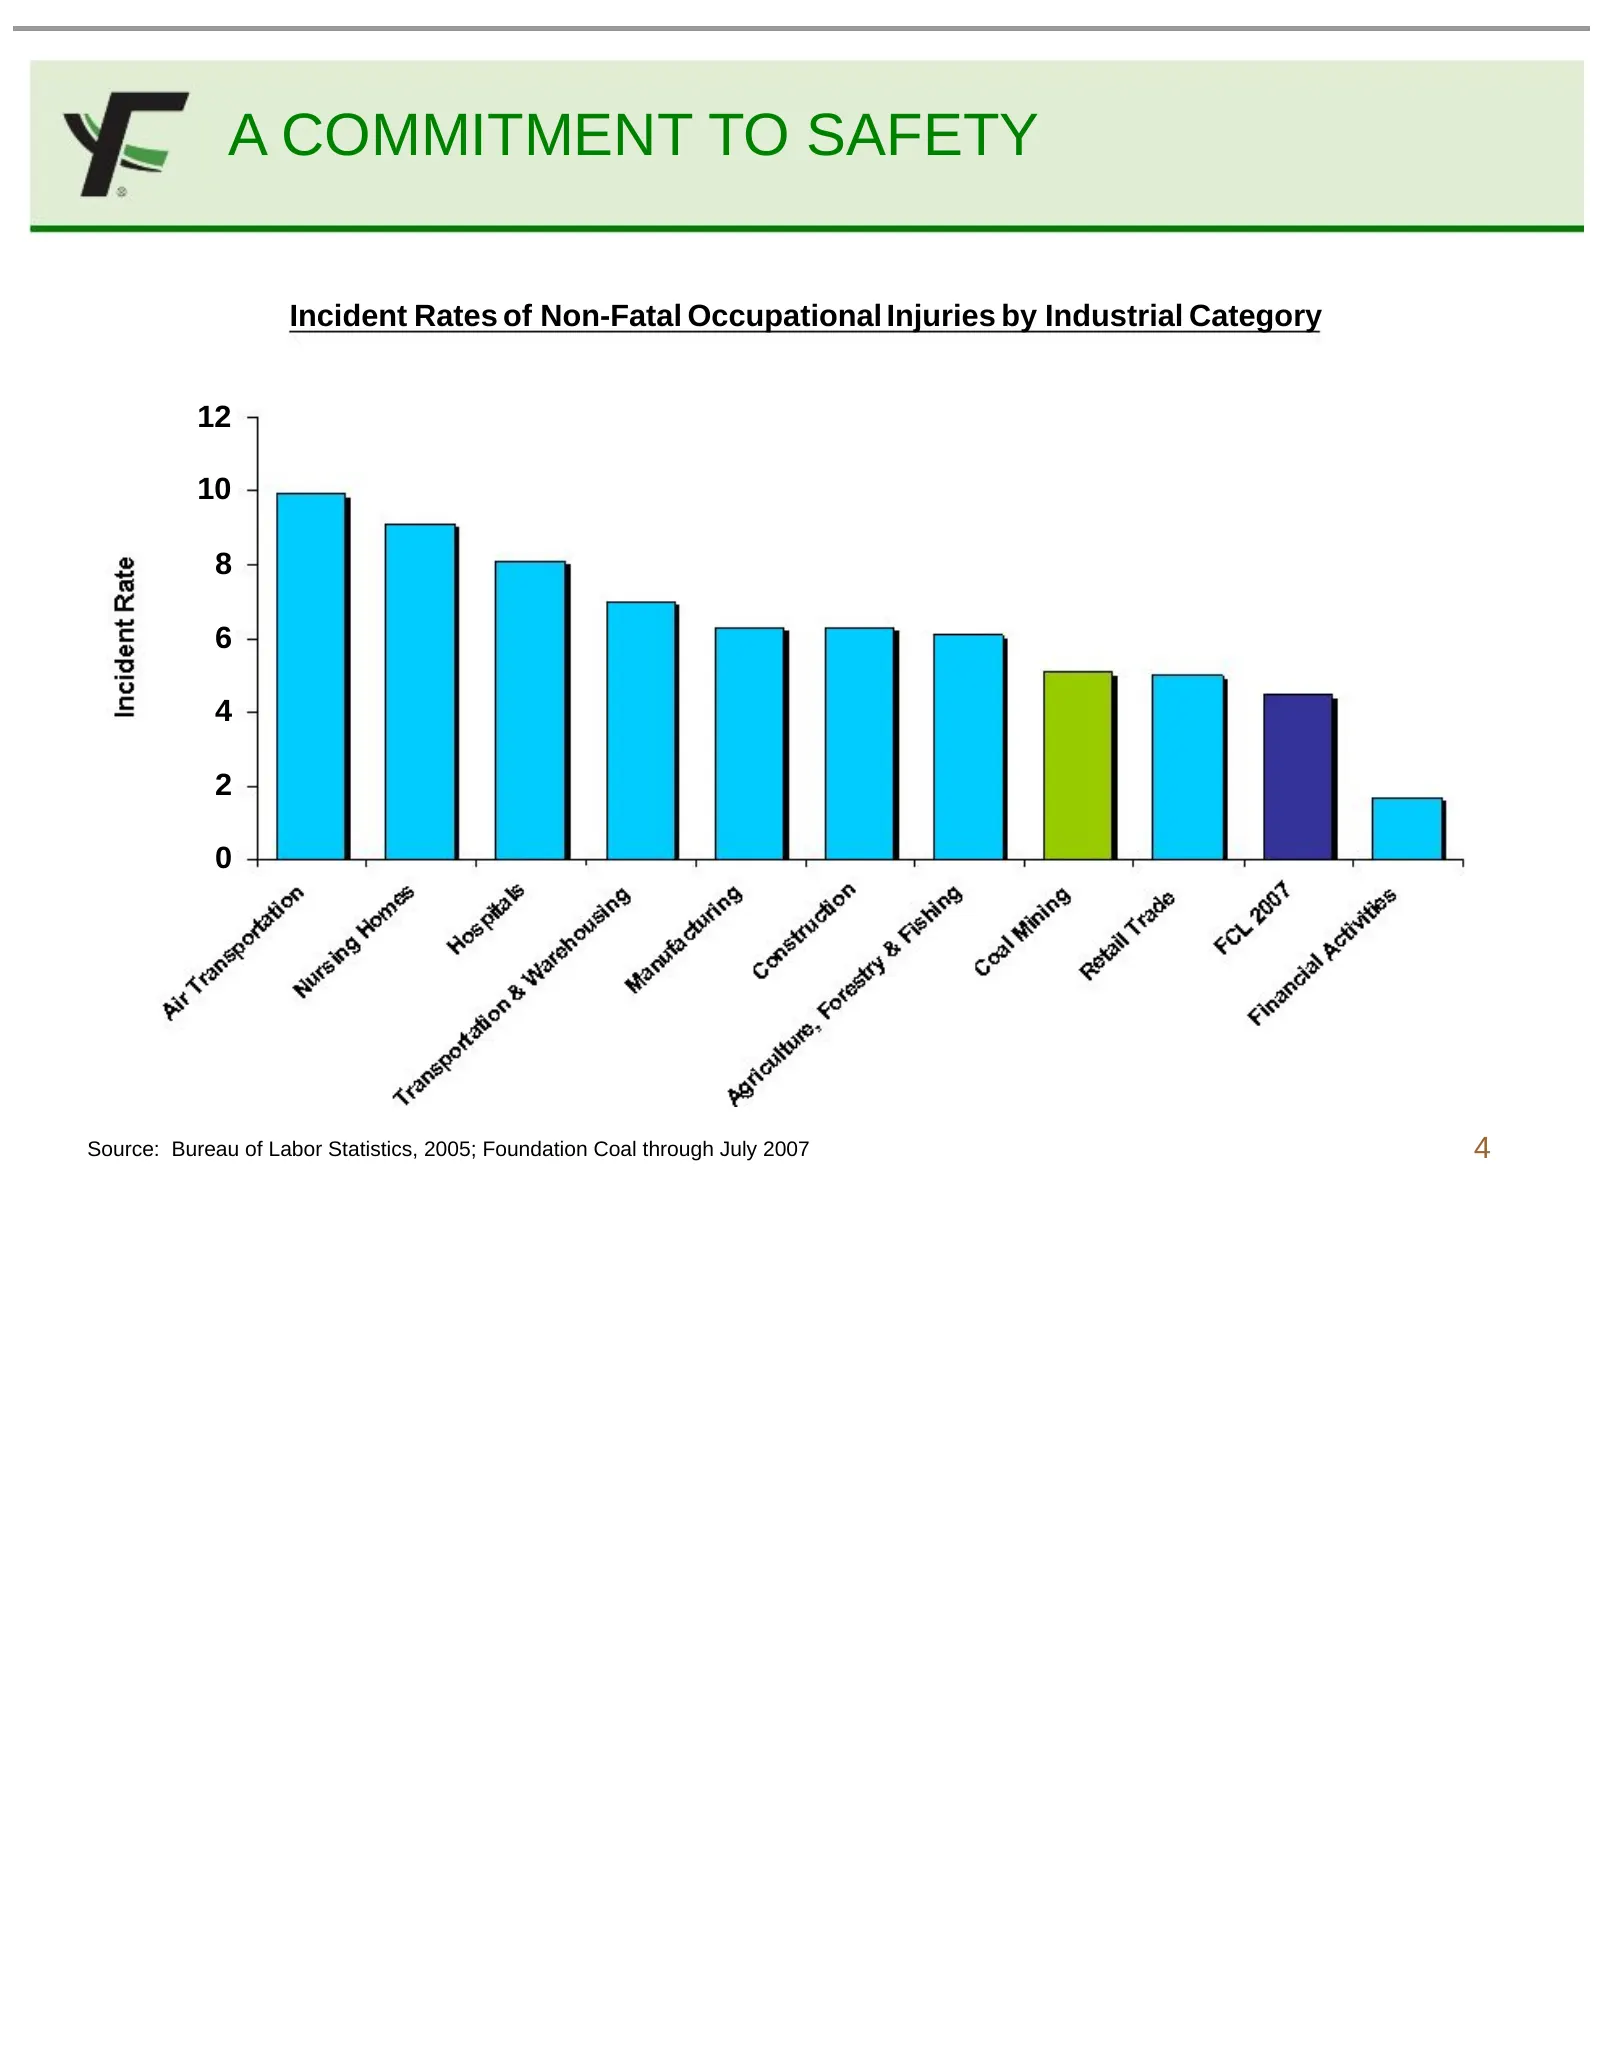
A COMMITMENT TO SAFETY Incident Rates of Non-Fatal Occupational Injuries by Industrial Category 12 10 8 6 4 2 0 Source: Bureau of Labor Statistics, 2005; Foundation Coal through July 2007 4
Slide 5: A Commitment to Environmental Compliance
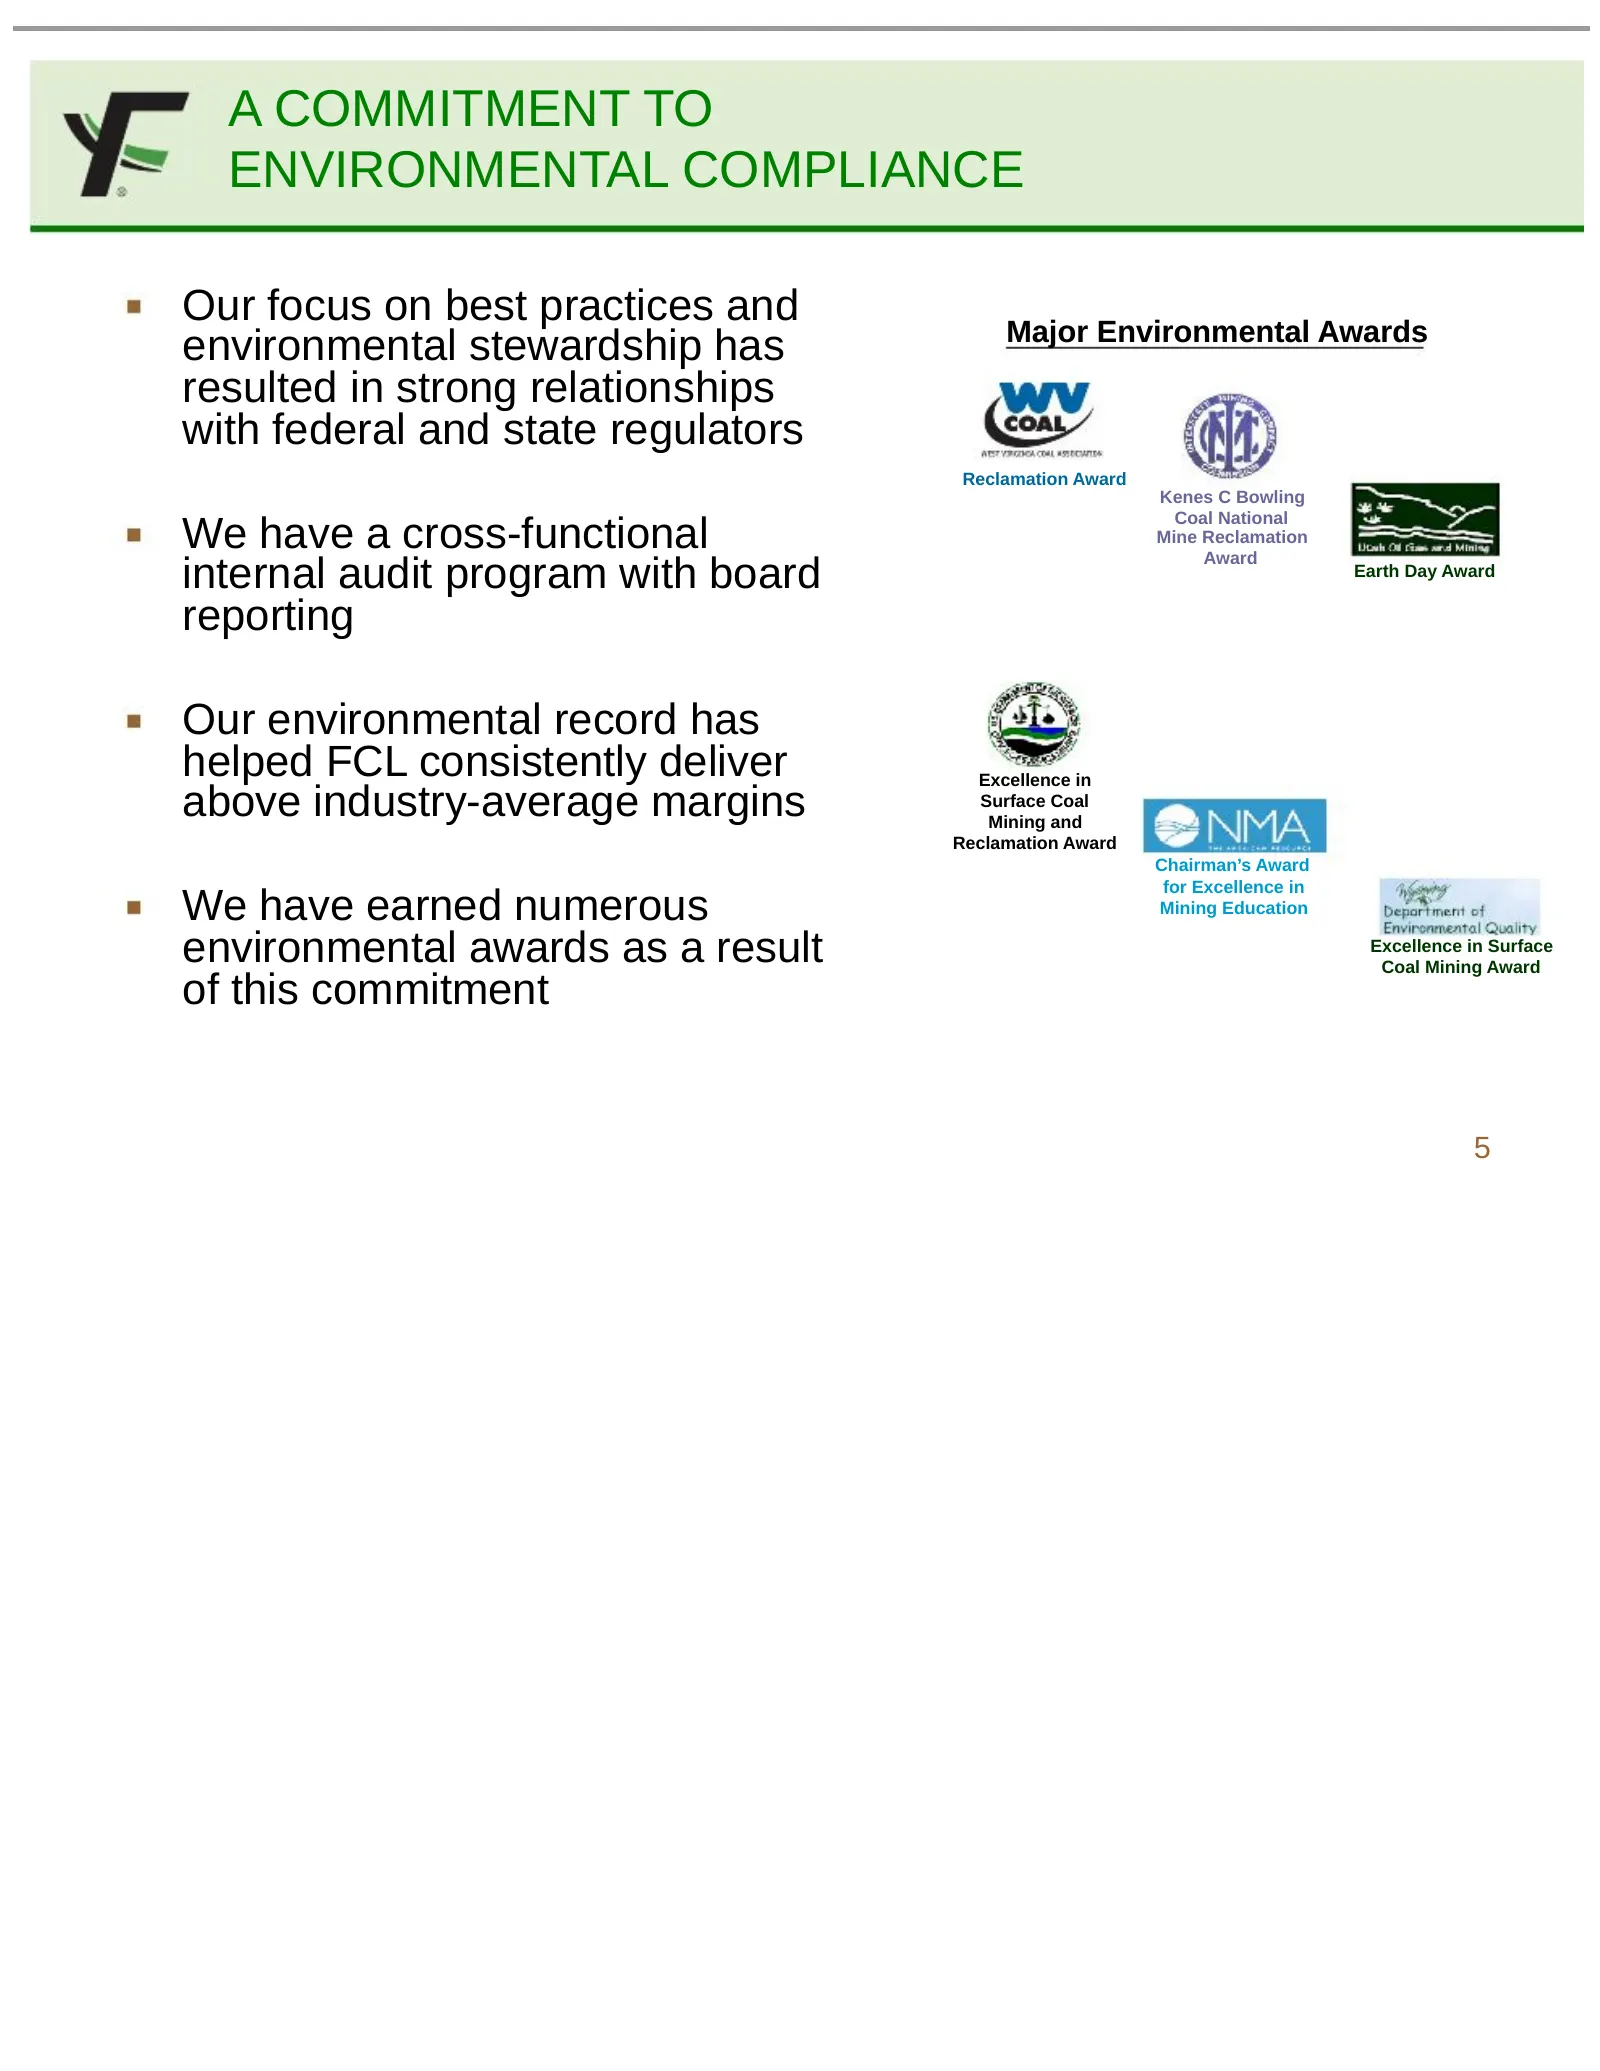
A COMMITMENT TO ENVIRONMENTAL COMPLIANCE Our focus on best practices and Major Environmental Awards environmental stewardship has resulted in strong relationships with federal and state regulators Reclamation Award Kenes C Bowling Coal National We have a cross-functional Mine Reclamation Award inter
Slide 6: Diversified Operations
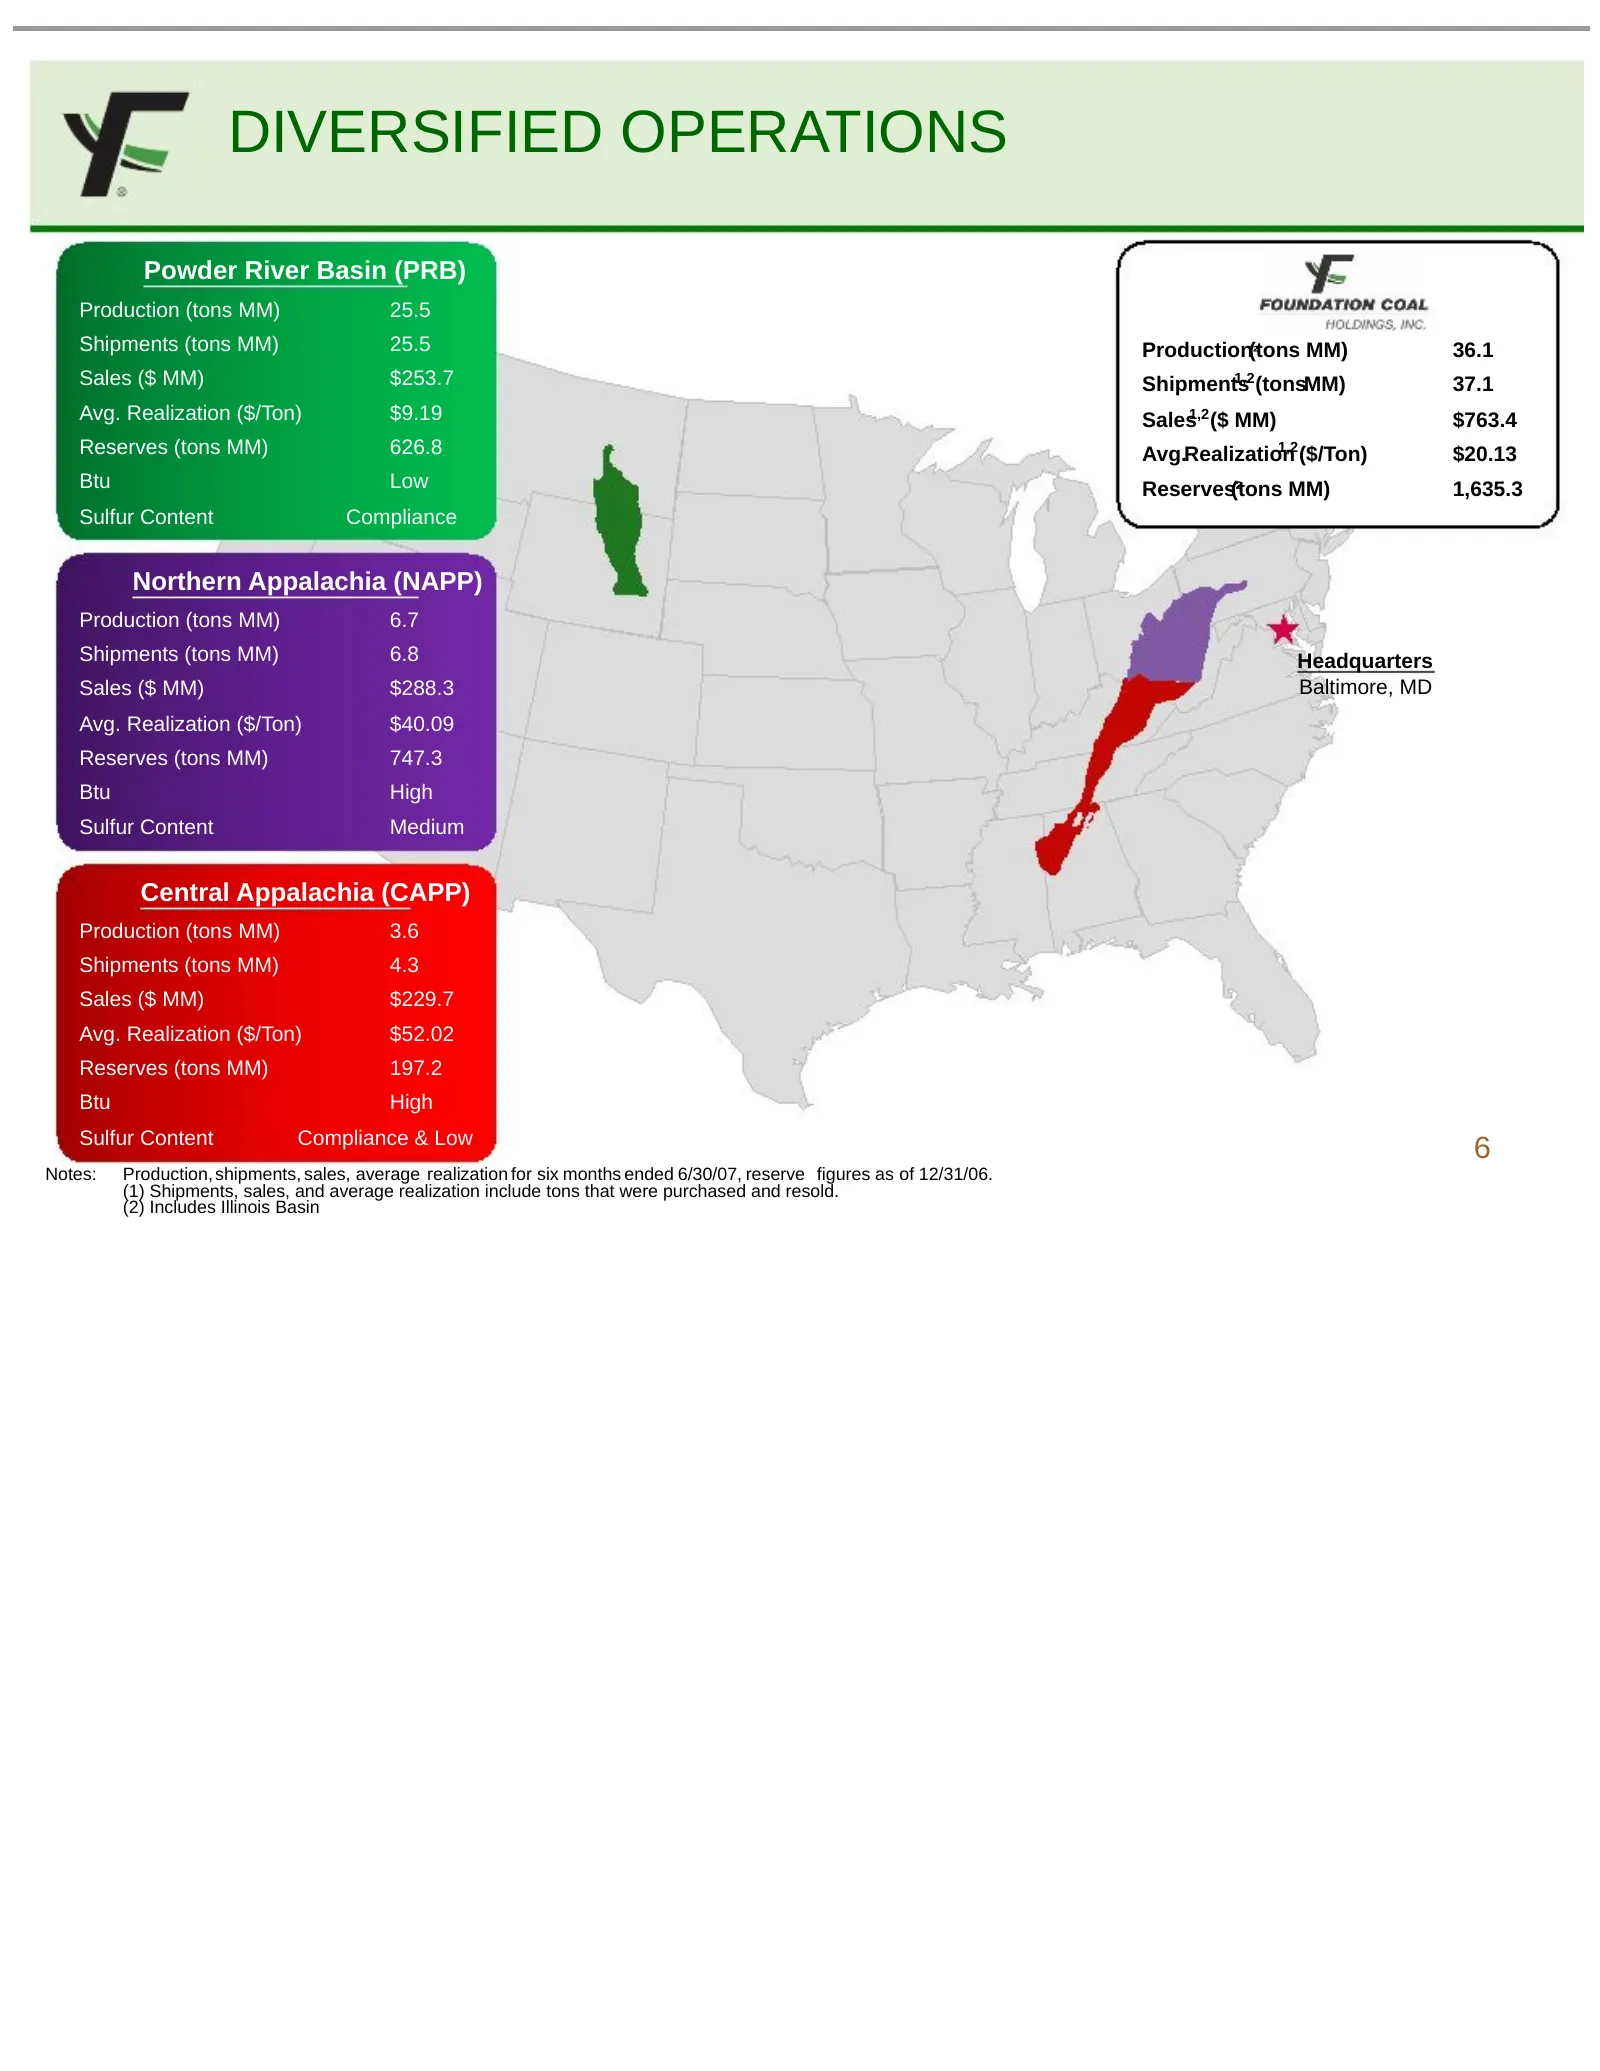
DIVERSIFIED OPERATIONS Powder River Basin (PRB) Production (tons MM) 25.5 Shipments (tons MM) 25.5 Production(tons ² MM) 36.1 Sales ($ MM) $253.7 1,2 Shipments (tonsMM) 37.1 Avg. Realization ($/Ton) $9.19 Sales1,2 ($ MM) $763.4 Reserves (tons MM) 626.8 1,2 Avg.Realization ($/Ton) $20.13 Btu Low Rese
Slide 7: Diverse Mining Methods
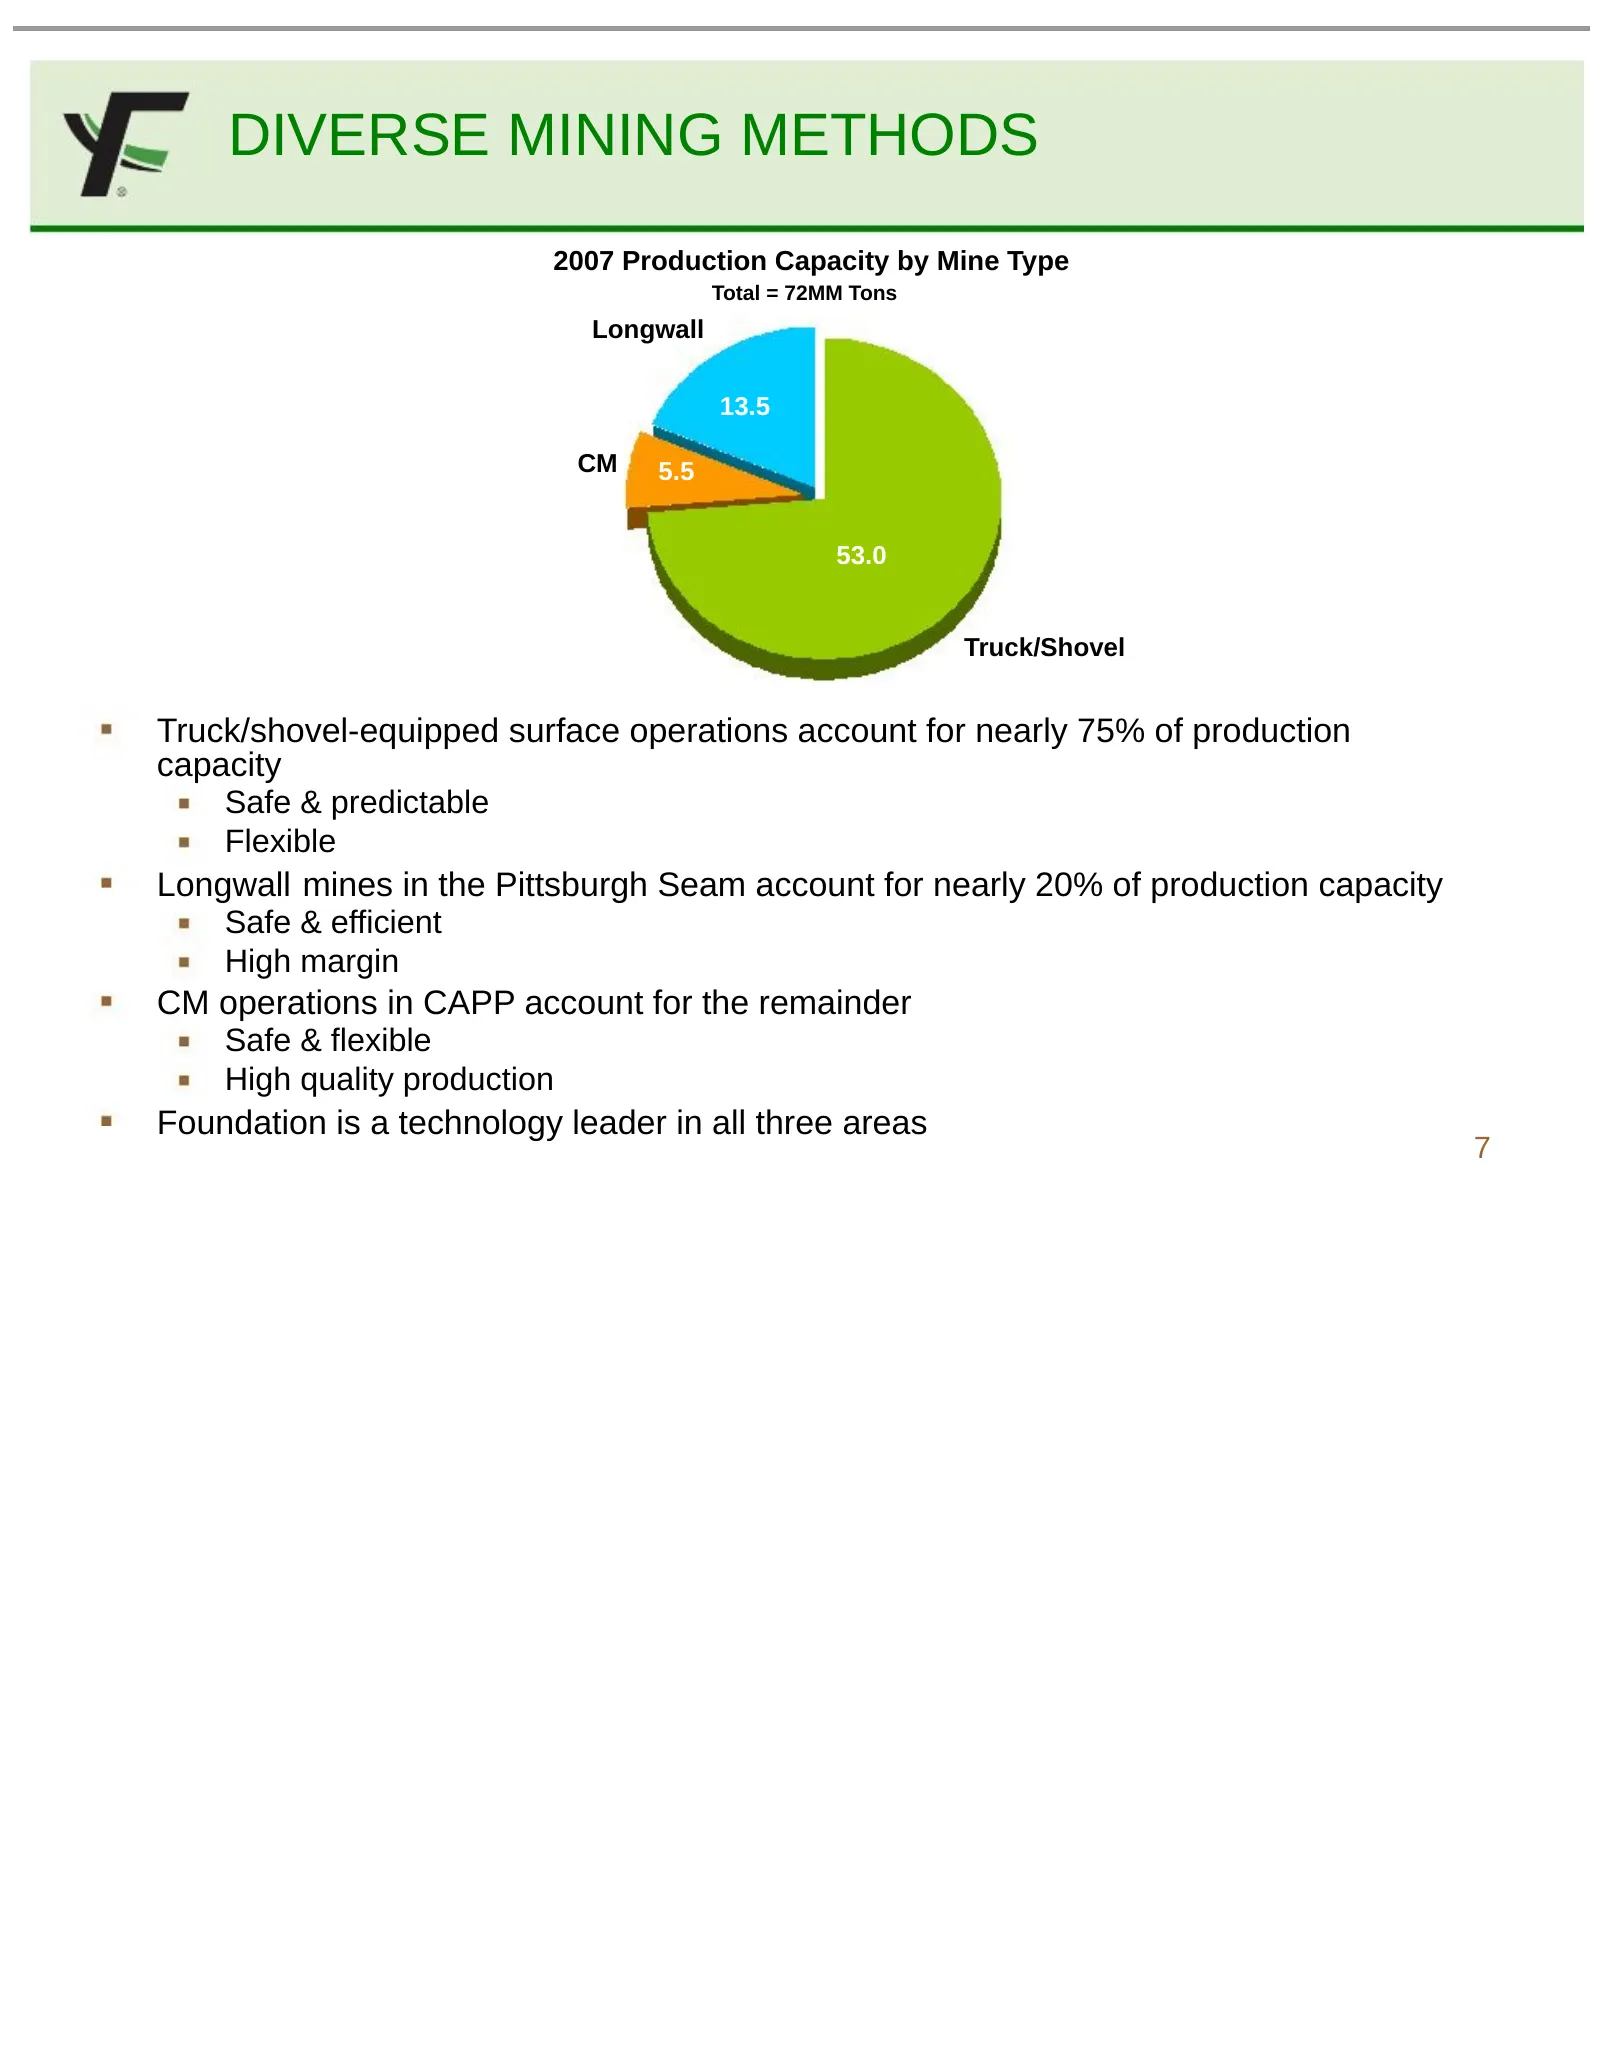
DIVERSE MINING METHODS 2007 Production Capacity by Mine Type Total = 72MM Tons Longwall 13.5 CM 5.5 53.0 Truck/Shovel Truck/shovel-equipped surface operations account for nearly 75% of production capacity Safe & predictable Flexible Longwall mines in the Pittsburgh Seam account for nearly 20% of pro
Slide 8: Diverse Transportation Methods & Providers
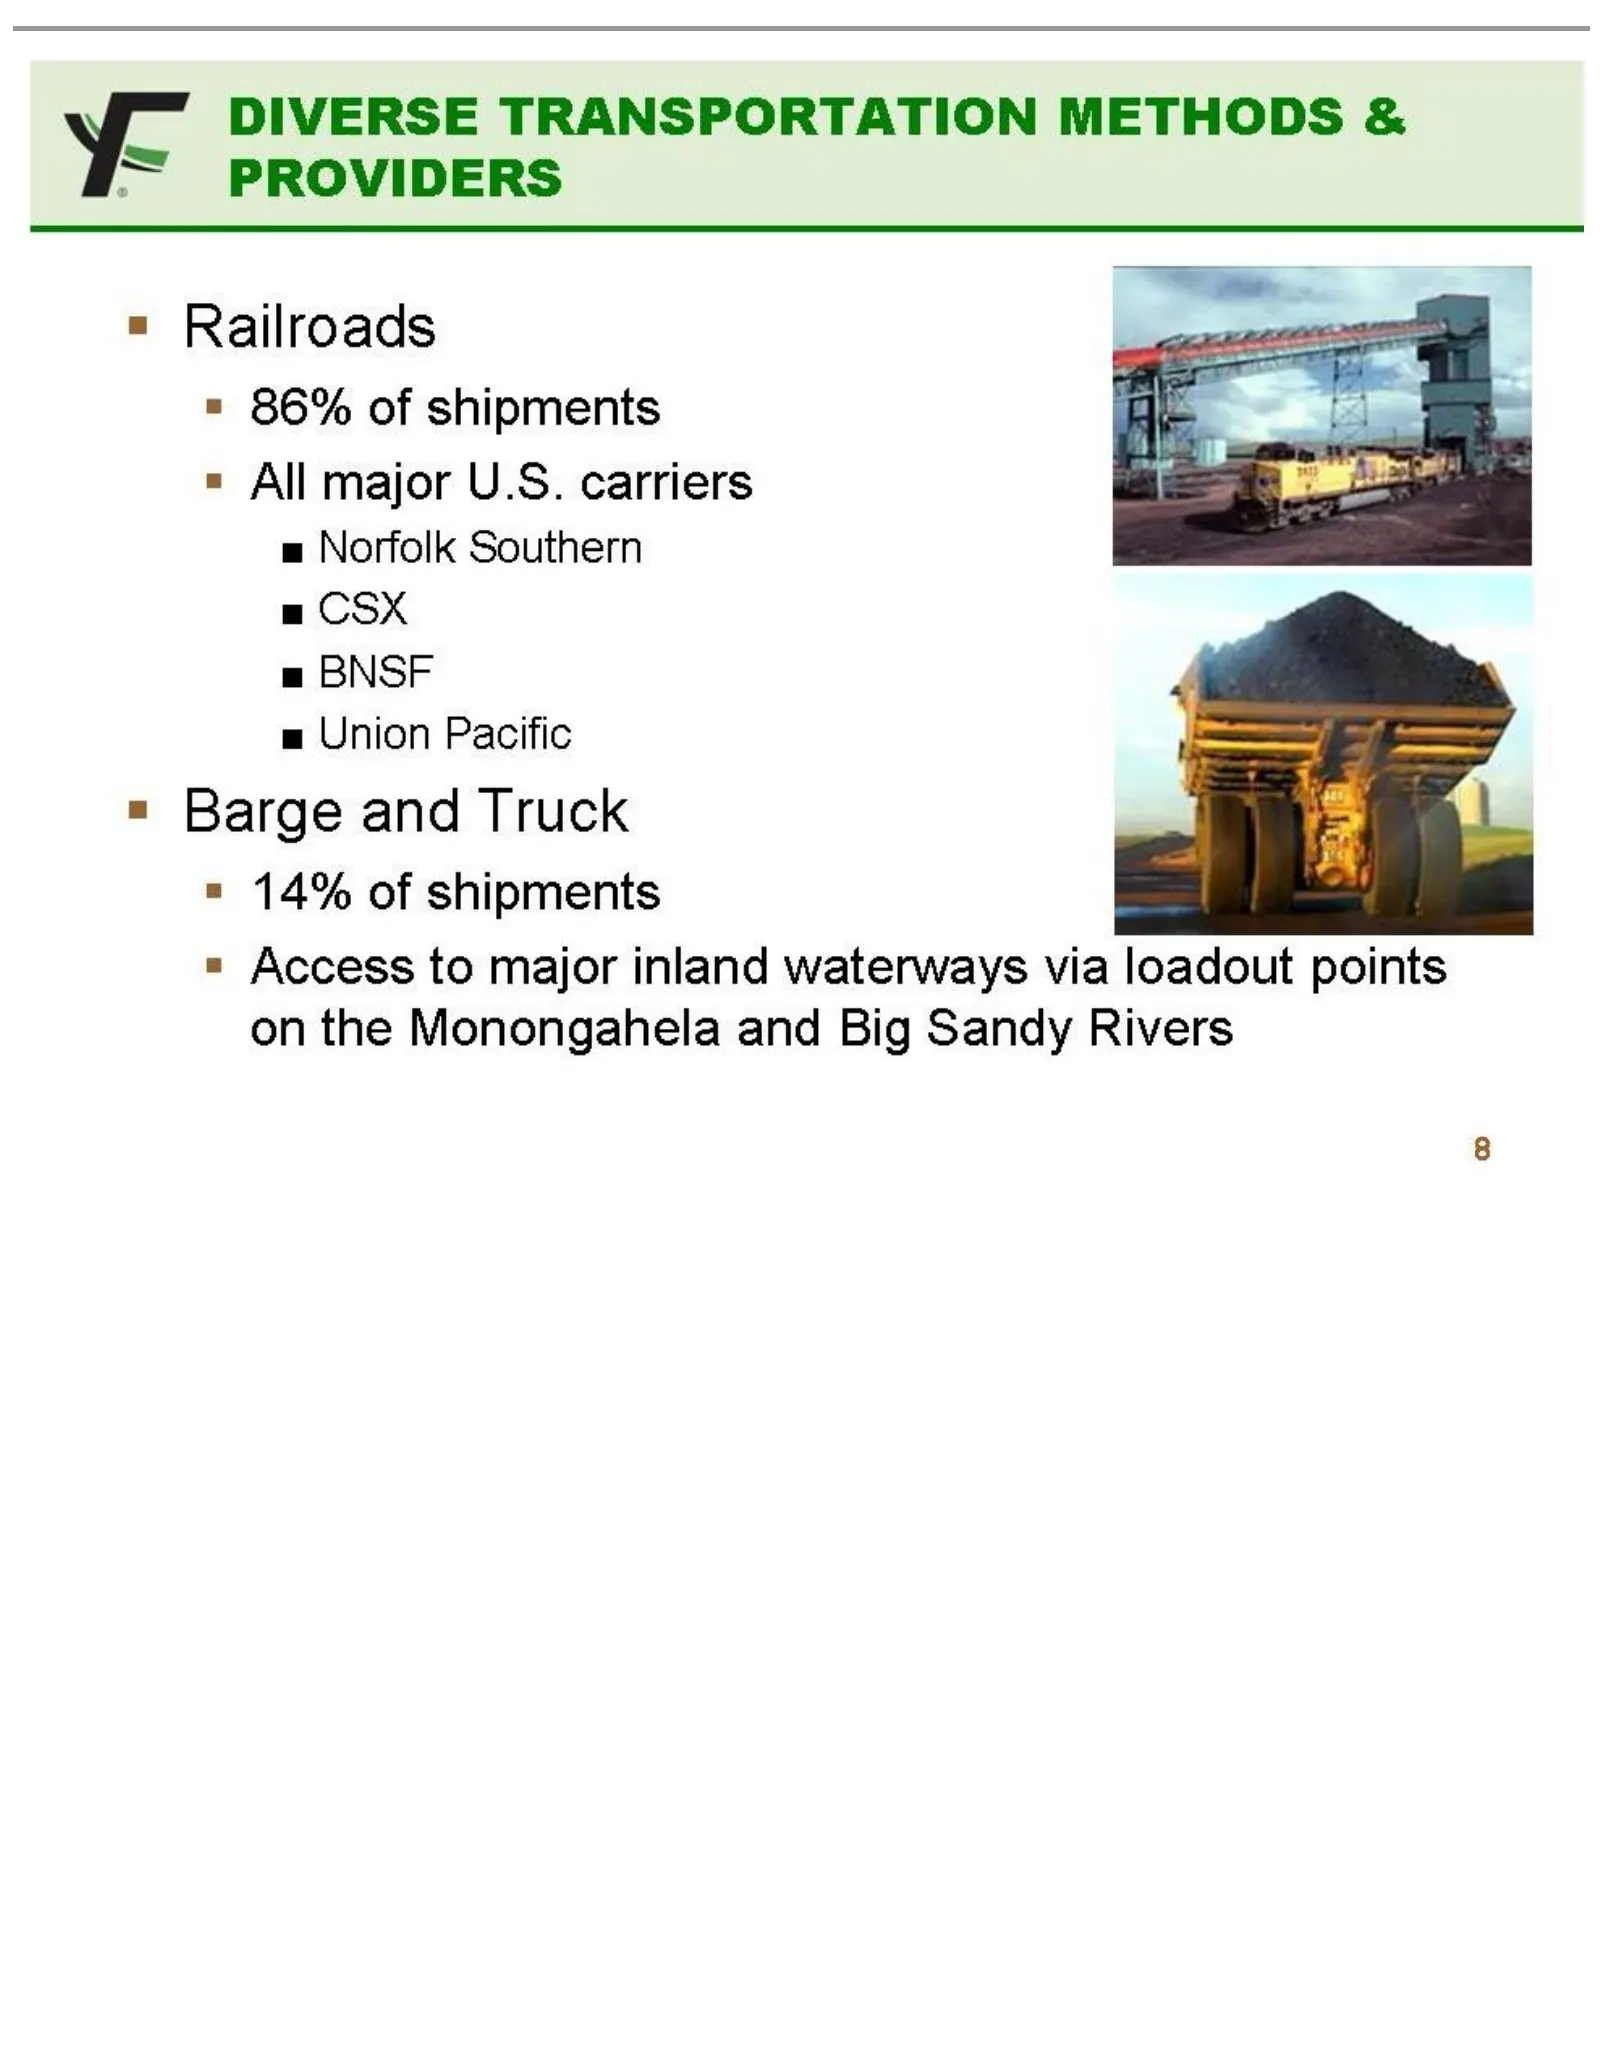
DIVERSE TRANSPORTATION METHODS & ‘= PROVIDERS = Railroads = 86% of shipments = All major U.S. carriers a Norfolk Southern a CSX a BNSF a Union Pacific = Barge and Truck = 14% of shipments = Access to major inland waterways via loadout points on the Monongahela and Big Sandy Rivers
Slide 9: Future Production Potential
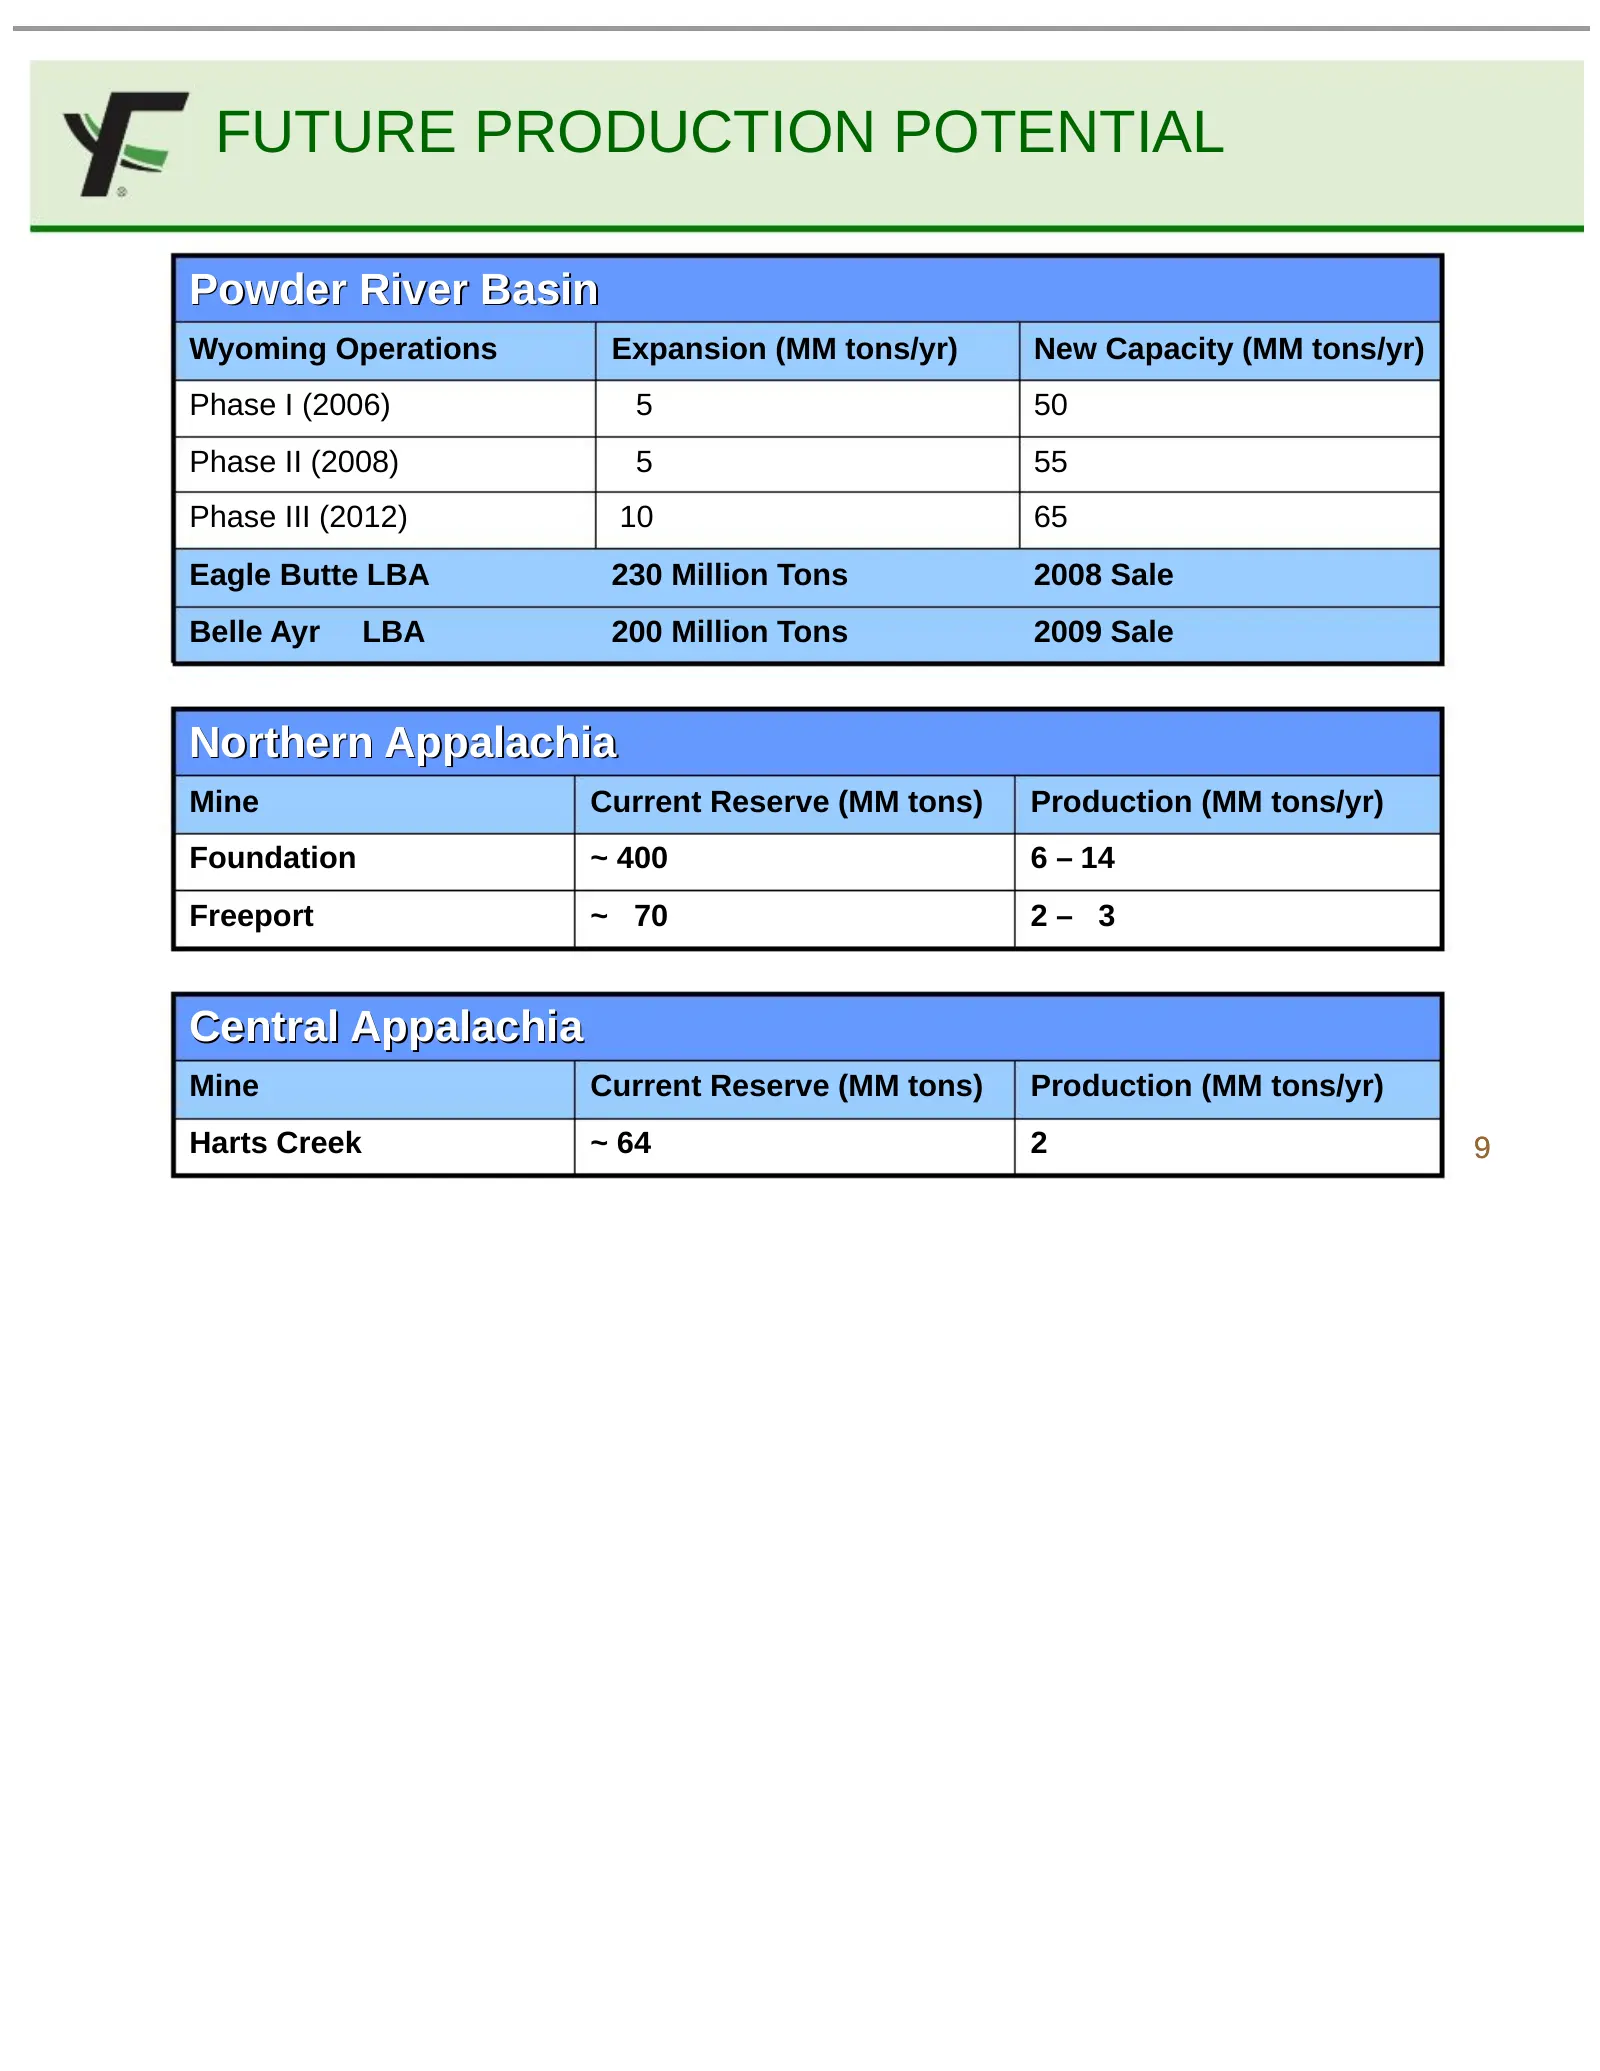
FUTURE PRODUCTION POTENTIAL Powder River Basin Wyoming Operations Expansion (MM tons/yr) New Capacity (MM tons/yr) Phase I (2006) 5 50 Phase II (2008) 5 55 Phase III (2012) 10 65 Eagle Butte LBA 230 Million Tons 2008 Sale Belle Ayr LBA 200 Million Tons 2009 Sale Northern Appalachia Mine Current Rese
Slide 10: Sustainability
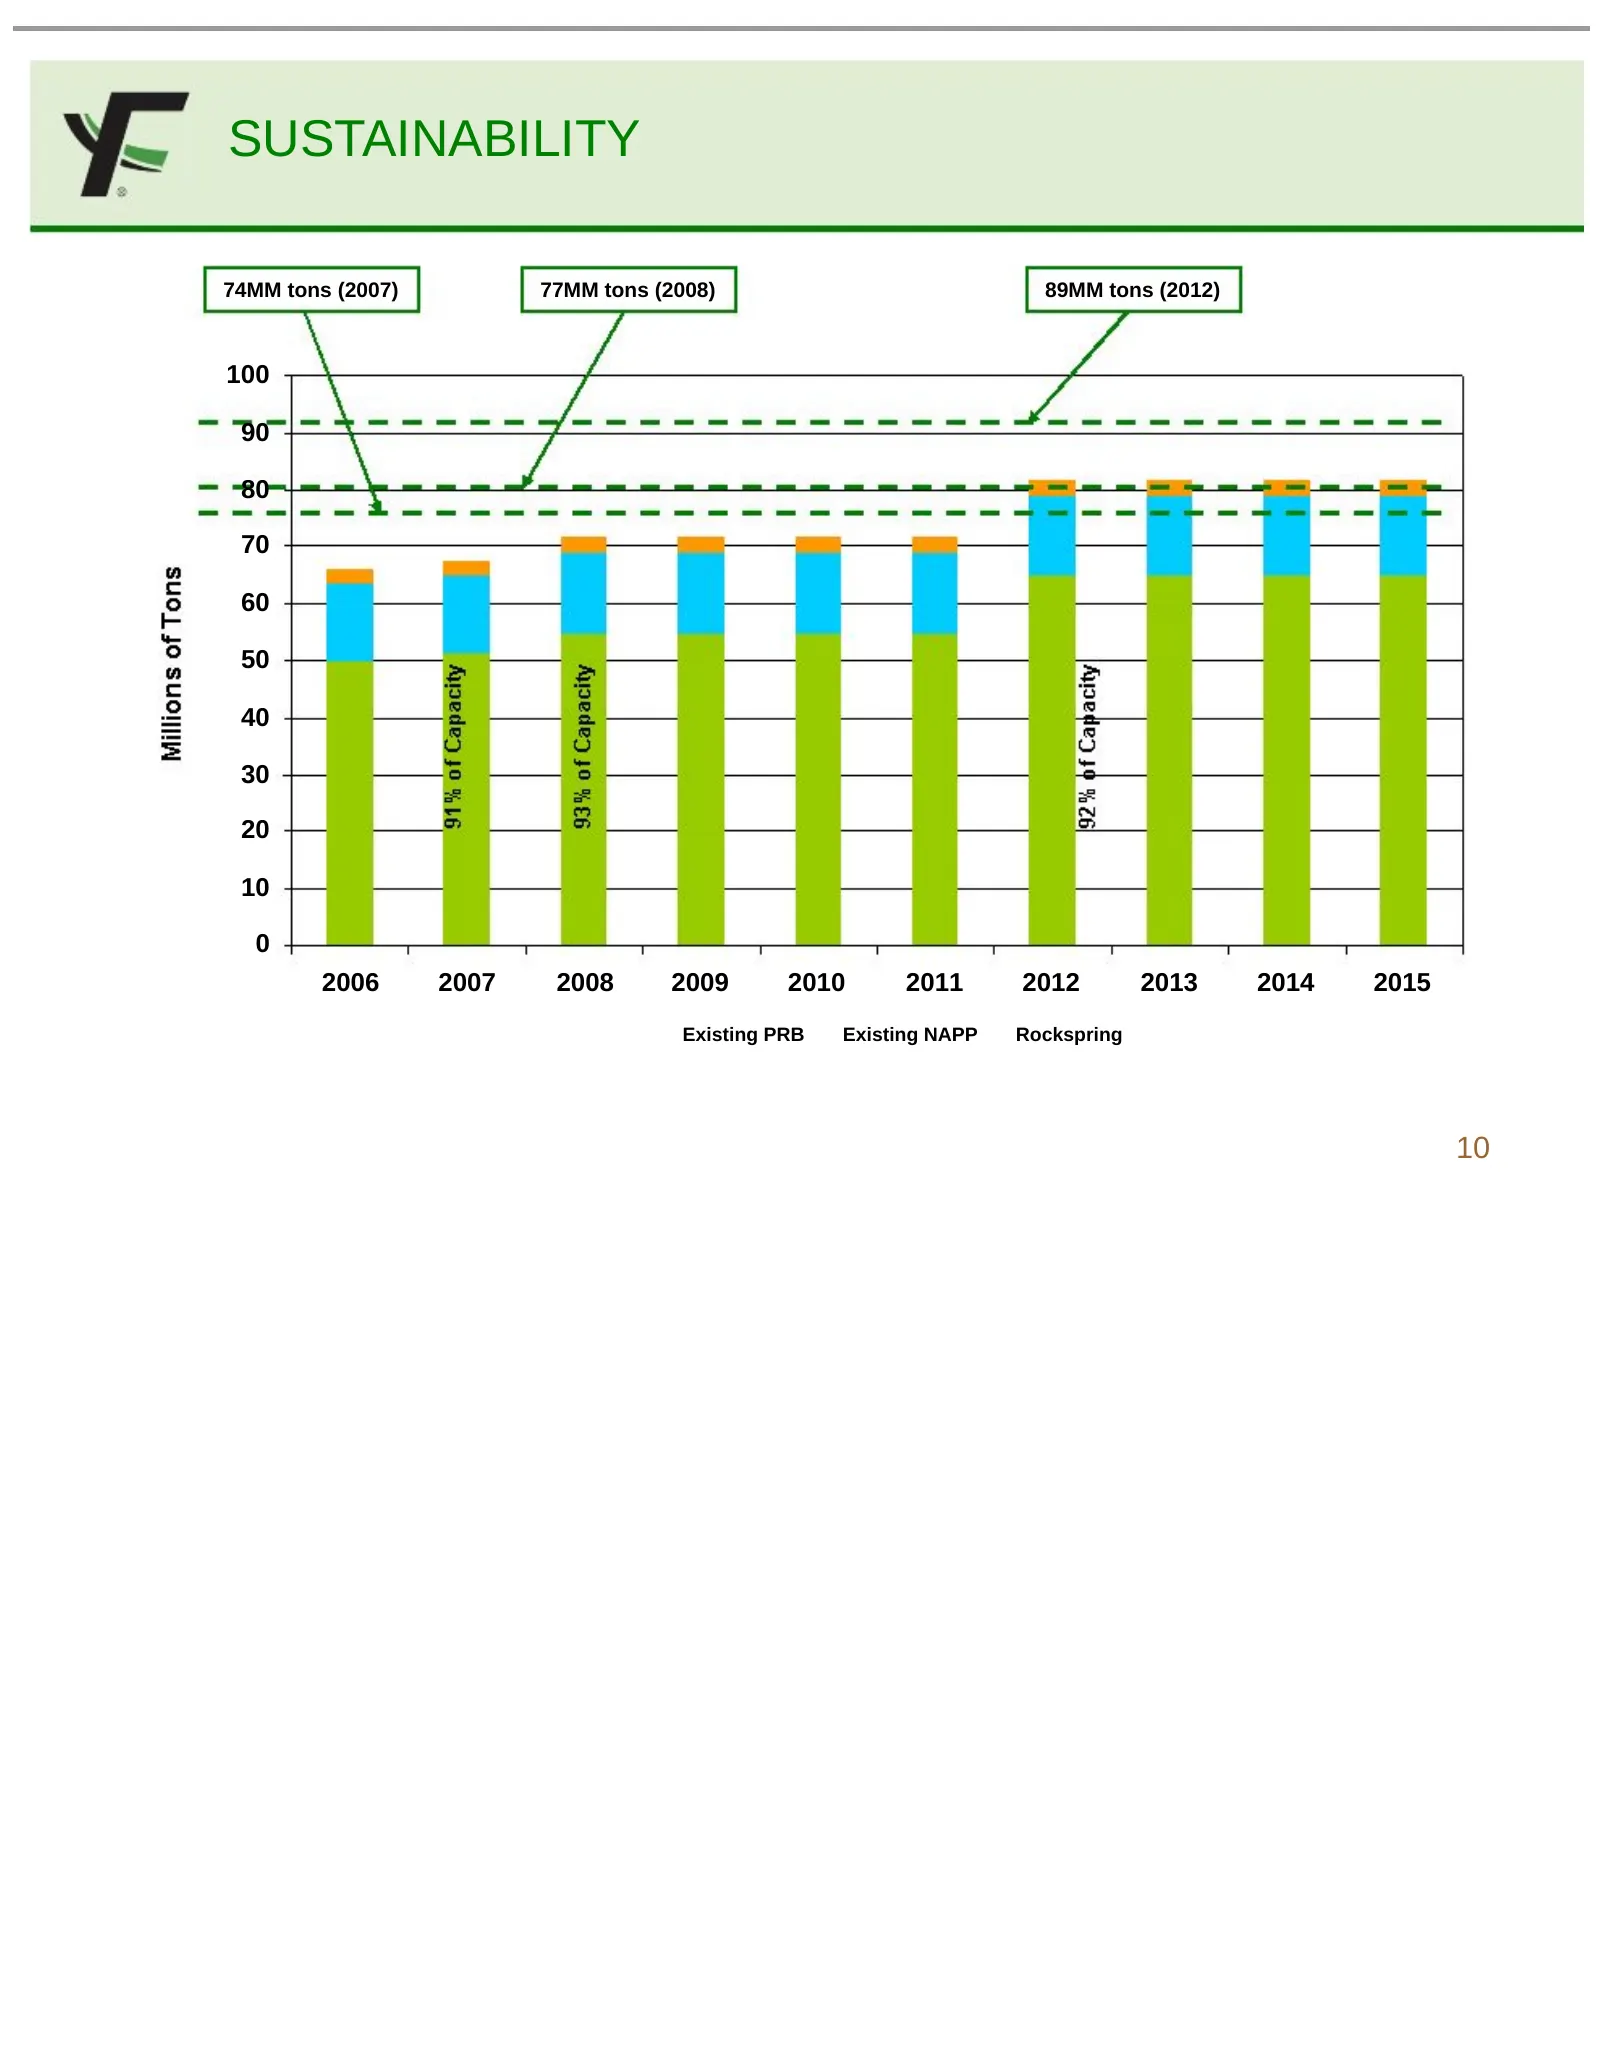
SUSTAINABILITY 74MM tons (2007) 77MM tons (2008) 89MM tons (2012) 100 90 80 70 60 50 40 30 20 10 0 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 Existing PRB Existing NAPP Rockspring 10
Slide 11: Opportunities for External Growth
OPPORTUNITIES FOR EXTERNAL GROWTH We may be entering a period of consolidation in the industry Valuations becoming more realistic Coal companies need critical mass to even the playing field with customers and railroads Foundation has an active business development group Seeking opportunities that wo
Slide 12: Proven Market Strategy
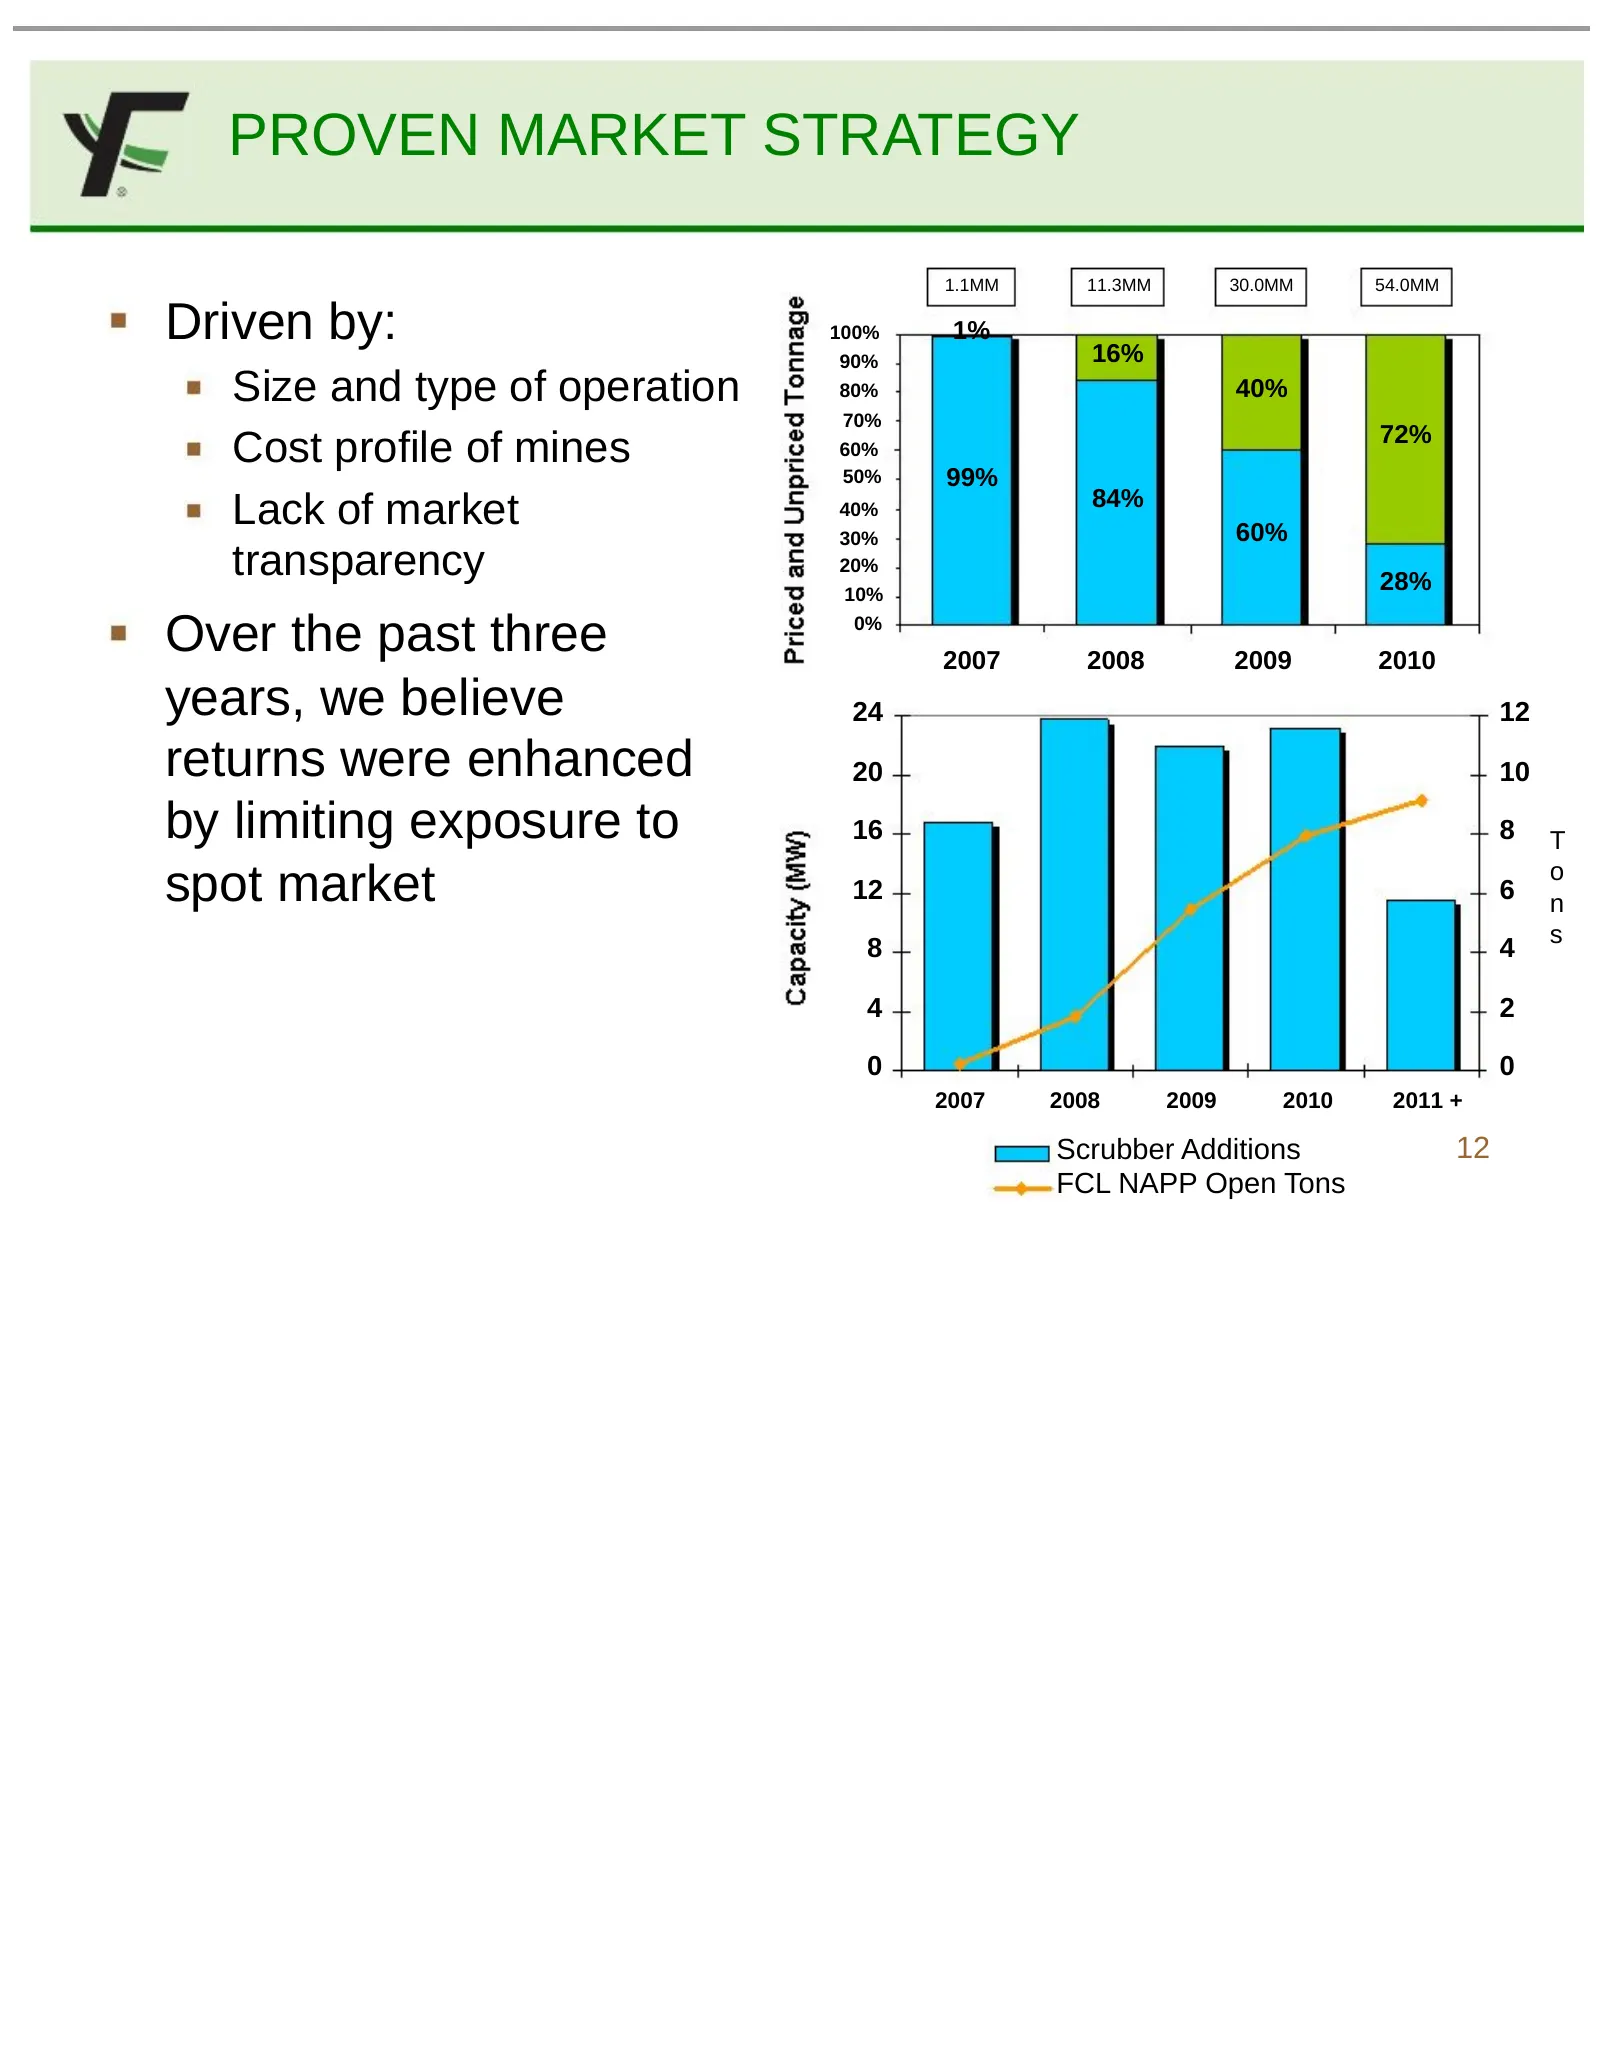
PROVEN MARKET STRATEGY 1.1MM 11.3MM 30.0MM 54.0MM Driven by: 100% 1% 16% 90% Size and type of operation 80% 40% 70% 72% Cost profile of mines 60% 50% 99% 84% Lack of market 40% 30% 60% transparency 20% 28% 10% Over the past three 0% 2007 2008 2009 2010 years, we believe 24 12 returns were enhanced 2
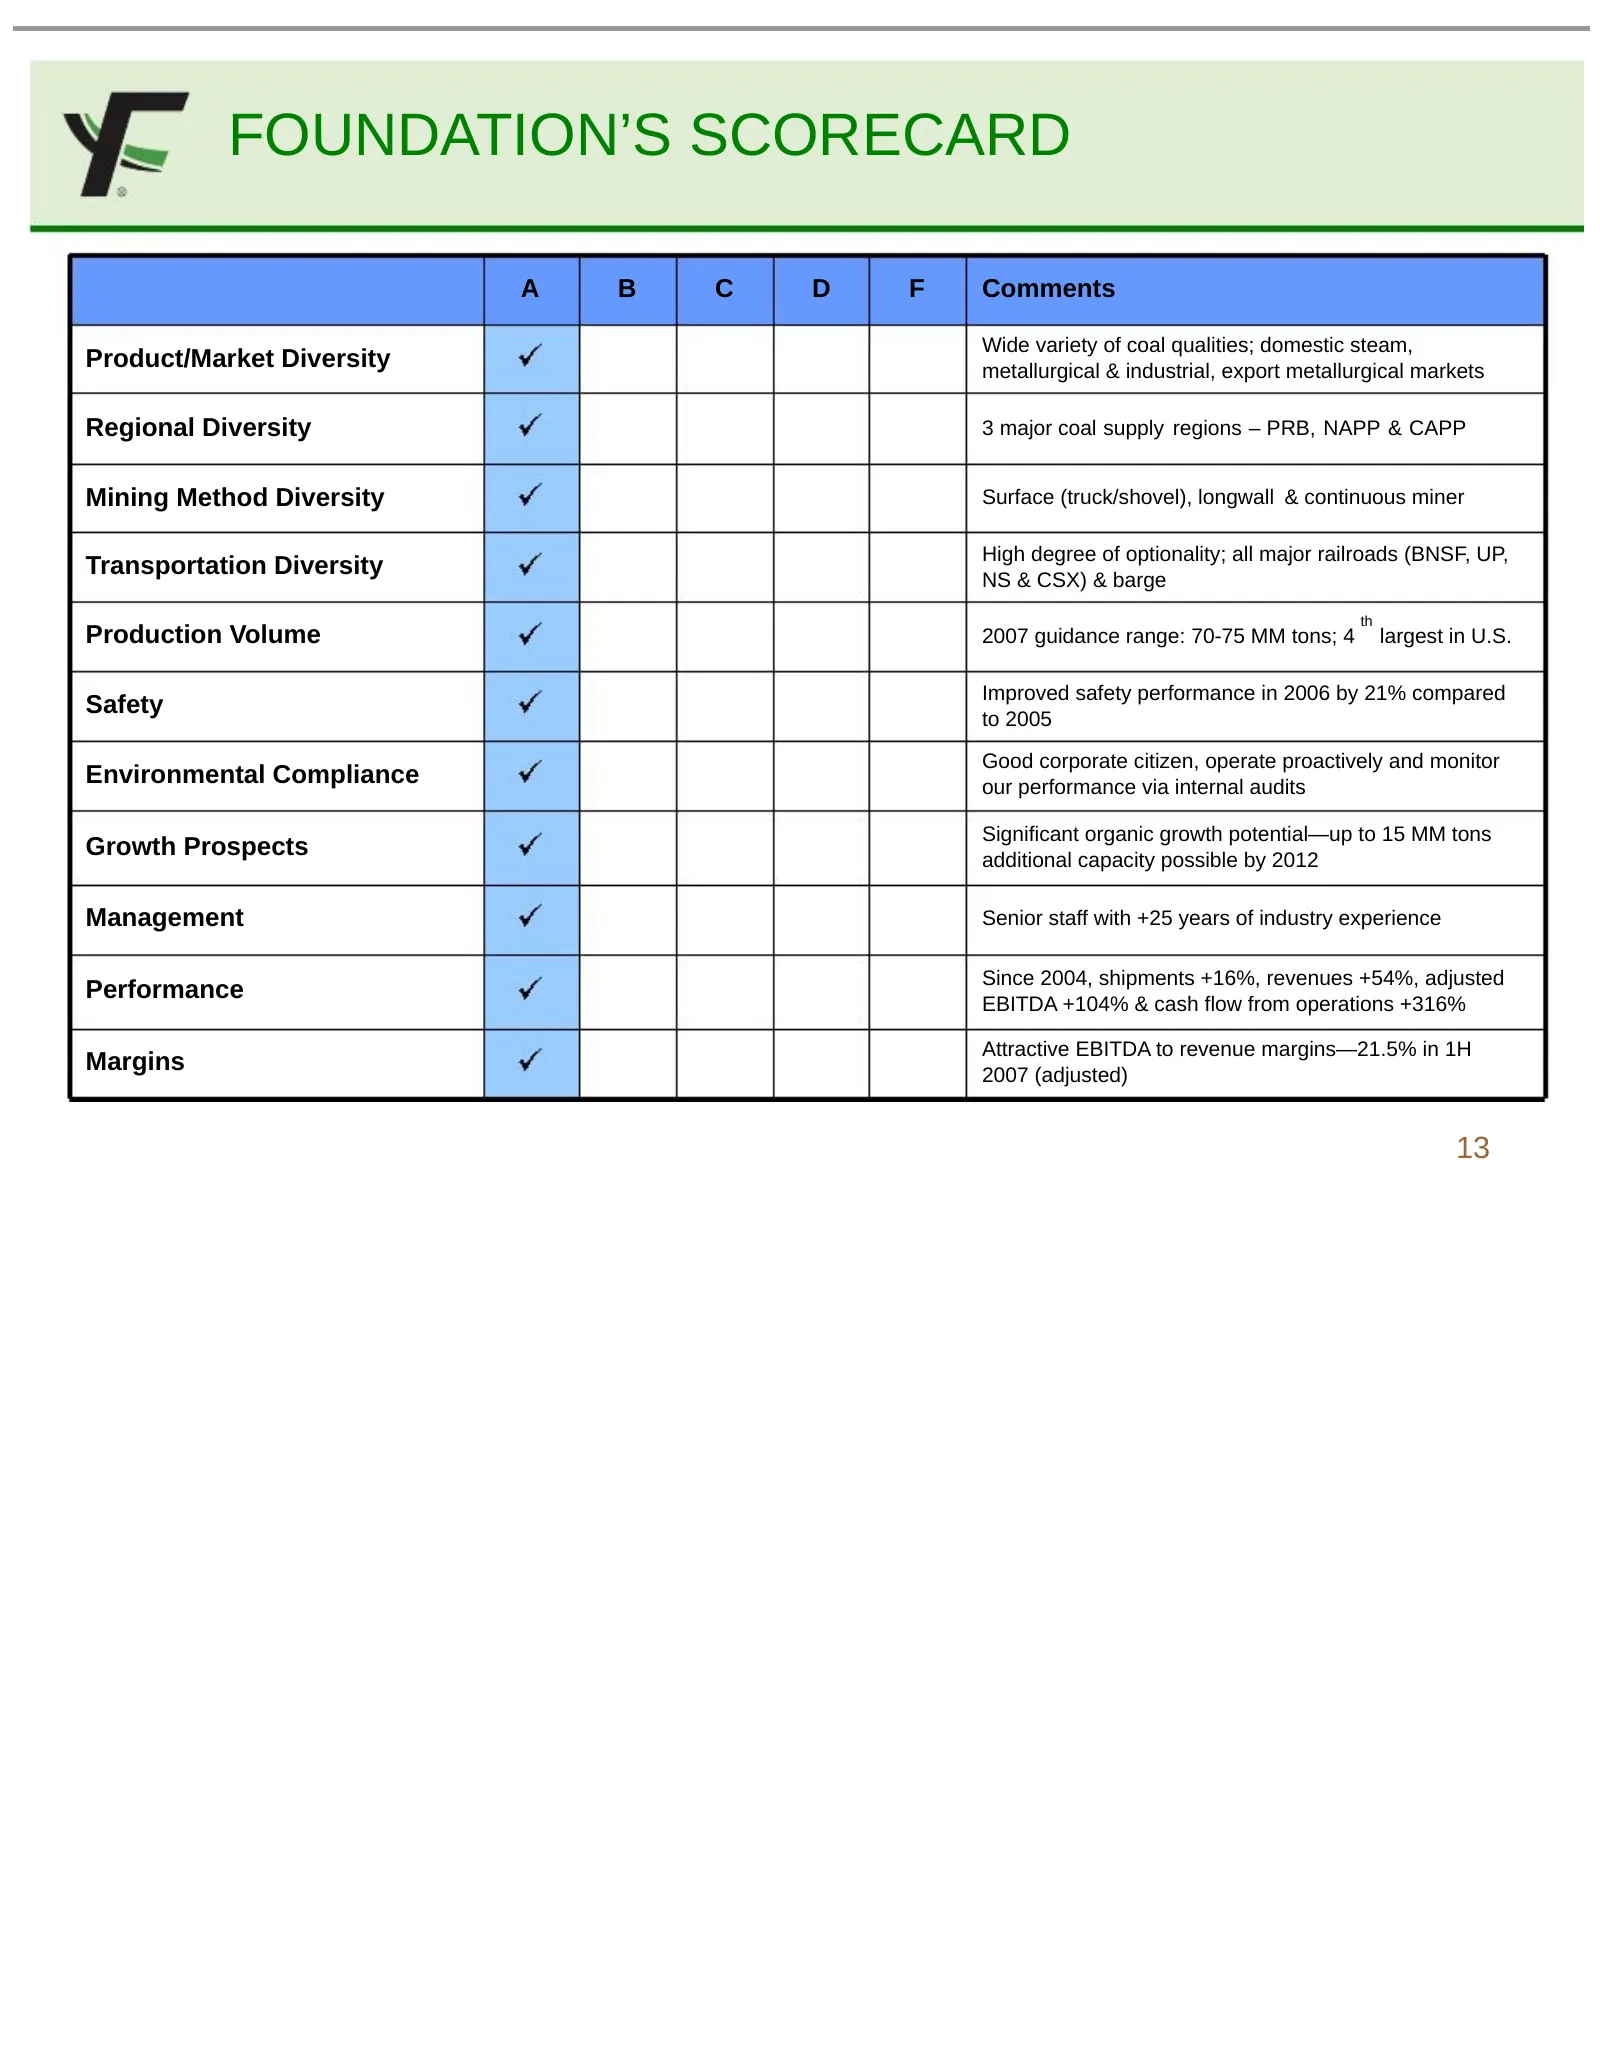
Slide 13: Foundation's Scorecard
FOUNDATION’S SCORECARD A B C D F Comments Wide variety of coal qualities; domestic steam, Product/Market Diversity metallurgical & industrial, export metallurgical markets Regional Diversity 3 major coal supply regions – PRB, NAPP & CAPP Mining Method Diversity Surface (truck/shovel), longwall & con
Slide 14: Foundation Coal Holdings, Inc.
FOUNDATION COAL HOLDINGS, INC. 14
Source: SEC EDGAR · 8-K filed Sep 20, 2007
More decks from Alpha Natural Resources Inc
 J.P. Morgan Global High Yield & Leveraged Finance Conference (February 2015)36 slides · Feb 23, 2015
 Barclays CEO Energy-Power Conference 201435 slides · Sep 2, 2014
 2014 BMO 23rd Global Metals and Mining Conference; Sterne Agee 2014 Boston Executive Summi33 slides · Jun 17, 2014
 2014 BMO 23rd Global Metals and Mining Conference / Brean Capital 2014 Global Resources &30 slides · May 28, 2014
 2014 BMO 23rd Global Metals and Mining Conference30 slides · Feb 24, 2014
 Tuohy Brothers' 4th Annual Energy Conference (August 2013)26 slides · Aug 5, 2013