Inland Real Estate — 2010 Citi Global Property CEO Conference
29 slides from Inland Real Estate's conference presentation, Mar 1, 2010
Slide 1: 2010 Citi Global Property CEO Conference
2010 Citi Global Property CEO Conference March 1-3, 2010 www.inlandrealestate.com NYSE: IRC
Slide 2: IRC Snapshot Profile
IRC SNAPSHOT PROFILE Inception 1994; self-administered and self-managed 2000; listed on NYSE June 2004 Targets stable, demographically-strong Midwest markets 84% of retail assets located in high density infill locations in Chicago & Minneapolis MSAs 139 Neighborhood, Community, Power, Lifestyle cent
Slide 3: Company Highlights
COMPANY HIGHLIGHTS Source: Company and company filings as of 12/31/09 Focus on a strong balance sheet: May 2009 equity raise produced net proceeds of $106.4 MM Established ATM program for issuance of up to $100 MM in common stock Dividend adjusted to 100% of REIT taxable income for 2009; monthly div
Slide 4: Experienced Leadership Team
EXPERIENCED LEADERSHIP TEAM Senior Leadership Inland Tenure Background / Experience Thomas D’Arcy Non-executive chairman 5 yrs. as IRC independent director & audit committee member (20+ yrs. real estate experience) Recently named president & CEO of Grubb & Ellis; formerly CEO of a publicly traded, M
Slide 5: Maintaining a Strong Balance Sheet
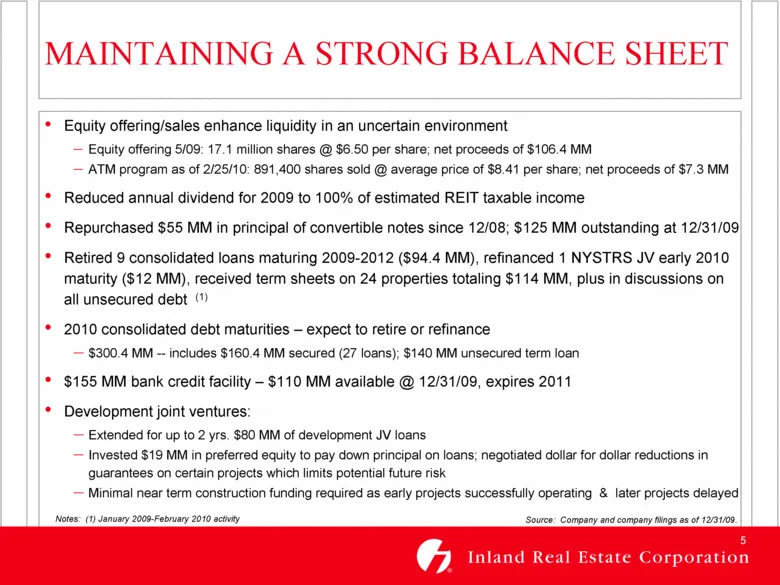
MAINTAINING A STRONG BALANCE SHEET Equity offering/sales enhance liquidity in an uncertain environment Equity offering 5/09: 17.1 million shares @ $6.50 per share; net proceeds of $106.4 MM ATM program as of 2/25/10: 891,400 shares sold @ average price of $8.41 per share; net proceeds of $7.3 MM Red
Slide 6: Operating Strategy
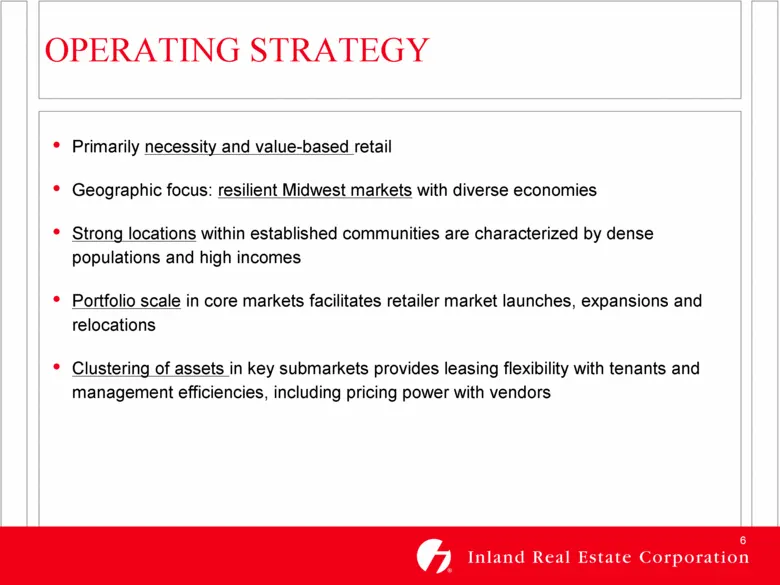
OPERATING STRATEGY Primarily necessity and value-based retail Geographic focus: resilient Midwest markets with diverse economies Strong locations within established communities are characterized by dense populations and high incomes Portfolio scale in core markets facilitates retailer market launche
Slide 7: Core Markets
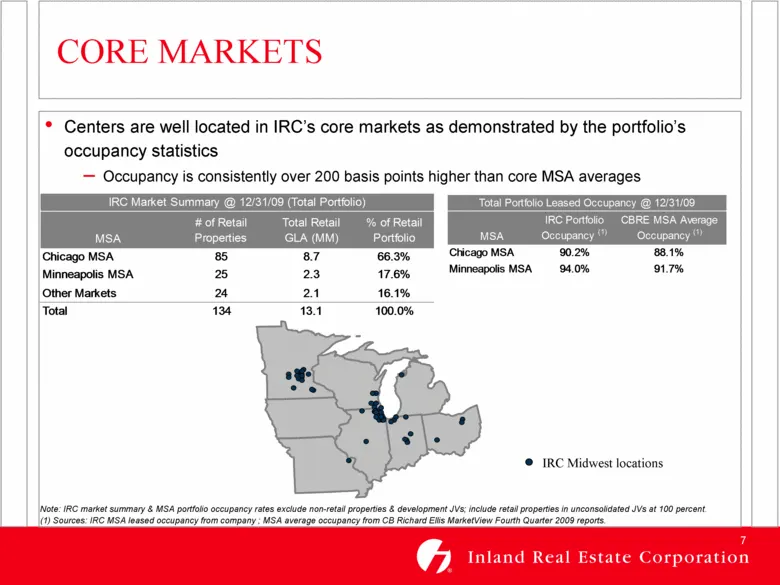
CORE MARKETS Note: IRC market summary & MSA portfolio occupancy rates exclude non-retail properties & development JVs; include retail properties in unconsolidated JVs at 100 percent. (1) Sources: IRC MSA leased occupancy from company ; MSA average occupancy from CB Richard Ellis MarketView Fourth Qu
Slide 8: Strong Market Demographics
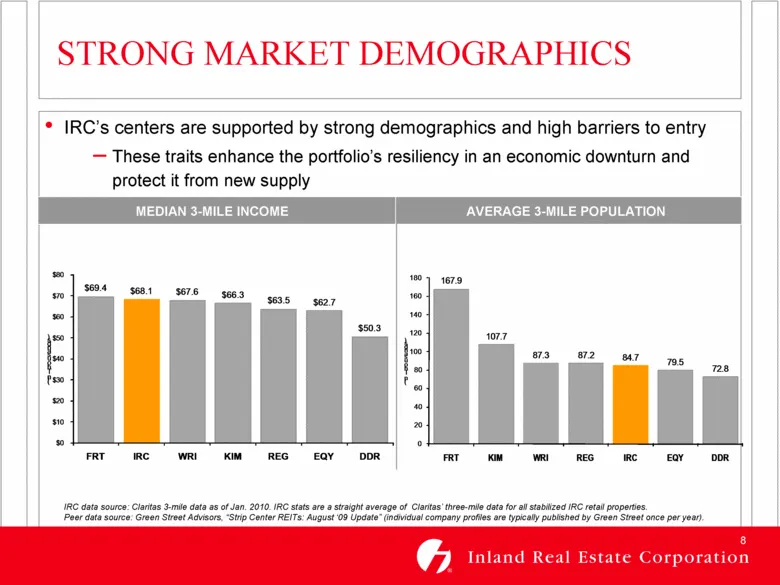
STRONG MARKET DEMOGRAPHICS IRC data source: Claritas 3-mile data as of Jan. 2010. IRC stats are a straight average of Claritas’ three-mile data for all stabilized IRC retail properties. Peer data source: Green Street Advisors, “Strip Center REITs: August ‘09 Update” (individual company profiles are
Slide 9: Diversified Tenant Base
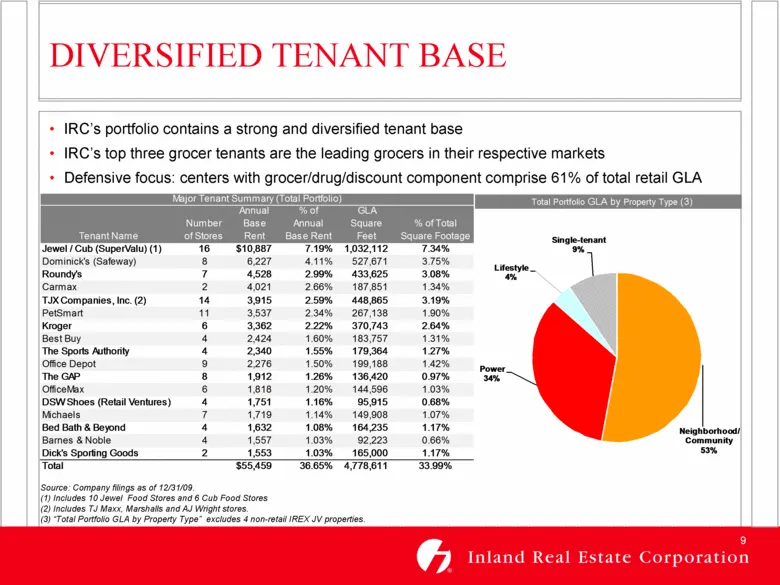
DIVERSIFIED TENANT BASE IRC’s portfolio contains a strong and diversified tenant base IRC’s top three grocer tenants are the leading grocers in their respective markets Defensive focus: centers with grocer/drug/discount component comprise 61% of total retail GLA (1) Source: Company filings as of 12/
Slide 10: Portfolio Management Expertise
PORTFOLIO MANAGEMENT EXPERTISE Experienced and proactive leasing team Deep market knowledge Strong national, regional, local retailer relationships Creative leasing strategies maximize income potential Skilled portfolio management at both the property and corporate levels Perform regular portfolio r
Slide 11: Total Portfolio Rent Spreads: Releasing & Retenanting
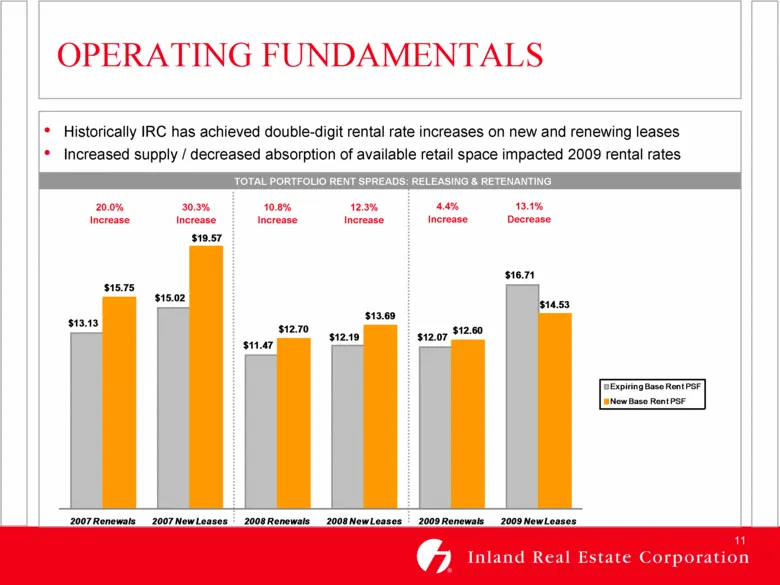
Historically IRC has achieved double-digit rental rate increases on new and renewing leases Increased supply / decreased absorption of available retail space impacted 2009 rental rates TOTAL PORTFOLIO RENT SPREADS: RELEASING & RETENANTING OPERATING FUNDAMENTALS 20.0% Increase 30.3% Increase 10.8% In
Slide 12: Well Staggered Lease Expirations
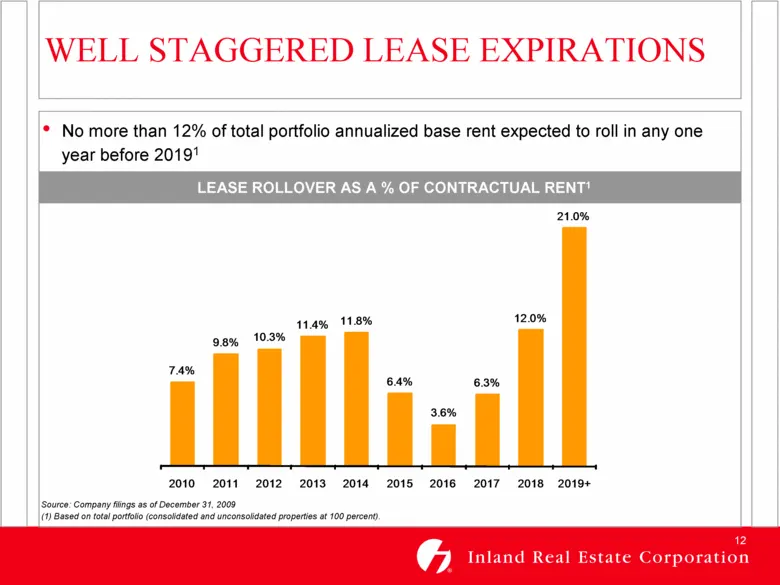
WELL STAGGERED LEASE EXPIRATIONS No more than 12% of total portfolio annualized base rent expected to roll in any one year before 20191 Source: Company filings as of December 31, 2009 (1) Based on total portfolio (consolidated and unconsolidated properties at 100 percent). LEASE ROLLOVER AS A % OF C
Slide 13: Leasing Efficiencies
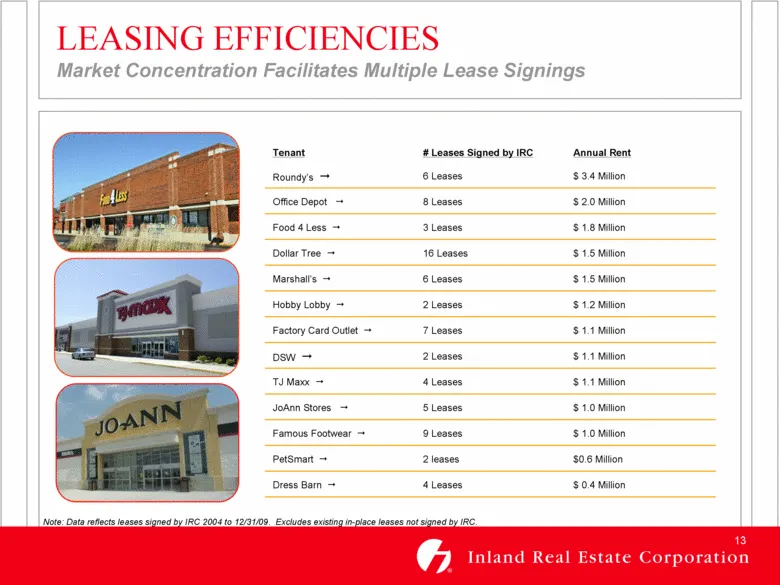
Tenant # Leases Signed by IRC Annual Rent Roundy’s 6 Leases $ 3.4 Million Office Depot 8 Leases $ 2.0 Million Food 4 Less 3 Leases $ 1.8 Million Dollar Tree 16 Leases $ 1.5 Million Marshall’s 6 Leases $ 1.5 Million Hobby Lobby 2 Leases $ 1.2 Million Factory Card Outlet 7 Leases $ 1.1 Million DSW 2 L
Slide 14: Meeting Operational Challenges: Big Box Vacancies
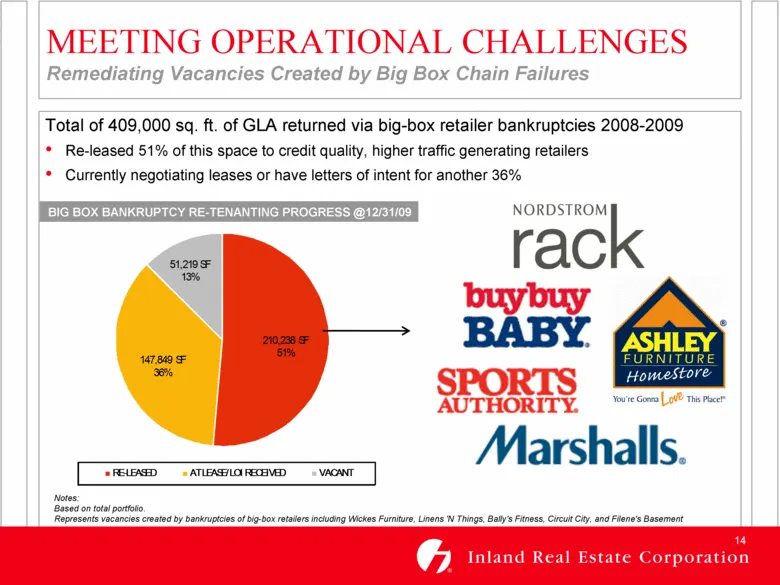
MEETING OPERATIONAL CHALLENGES Remediating Vacancies Created by Big Box Chain Failures Total of 409,000 sq. ft. of GLA returned via big-box retailer bankruptcies 2008-2009 Re-leased 51% of this space to credit quality, higher traffic generating retailers Currently negotiating leases or have letters
Slide 15: Case Study: Wickes Furniture Bankruptcy
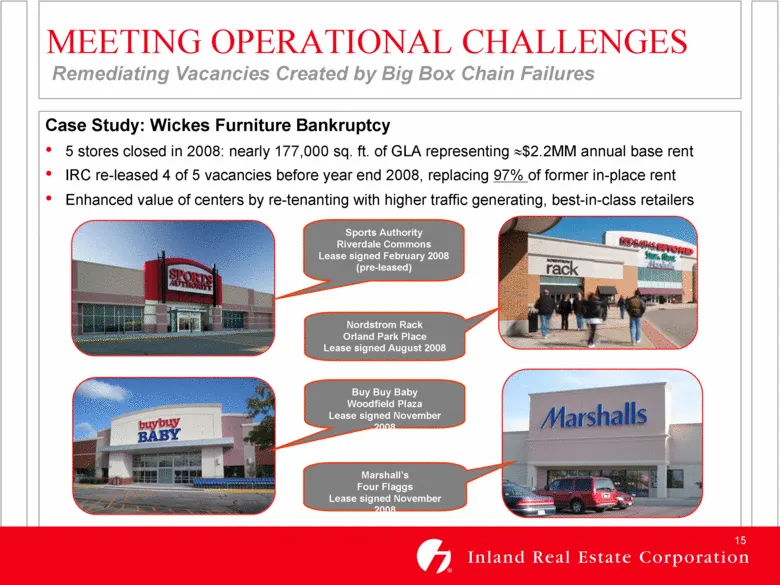
MEETING OPERATIONAL CHALLENGES Remediating Vacancies Created by Big Box Chain Failures Case Study: Wickes Furniture Bankruptcy 5 stores closed in 2008: nearly 177,000 sq. ft. of GLA representing $2.2MM annual base rent IRC re-leased 4 of 5 vacancies before year end 2008, replacing 97% of former in-p
Slide 16: Case Study: Schaumburg Market
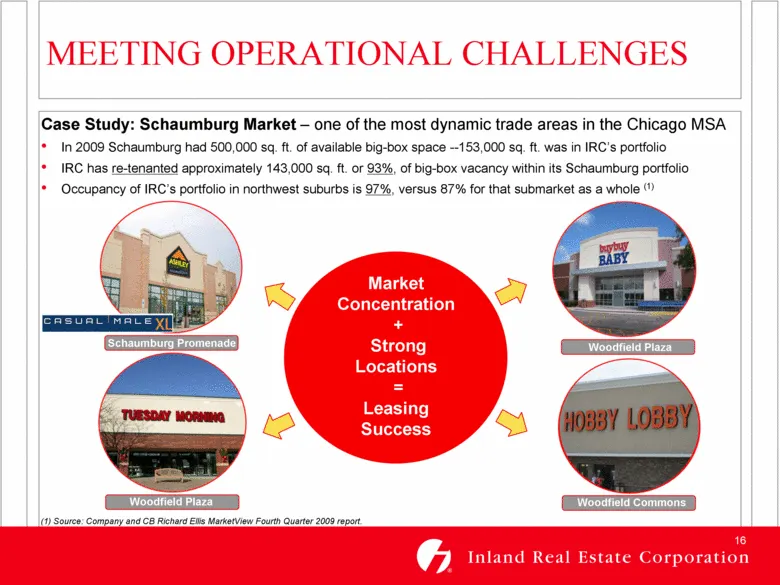
Schaumburg Promenade MEETING OPERATIONAL CHALLENGES Case Study: Schaumburg Market – one of the most dynamic trade areas in the Chicago MSA In 2009 Schaumburg had 500,000 sq. ft. of available big-box space --153,000 sq. ft. was in IRC’s portfolio IRC has re-tenanted approximately 143,000 sq. ft. or 9
Slide 17: Growth from Existing Portfolio: Completed Initiatives
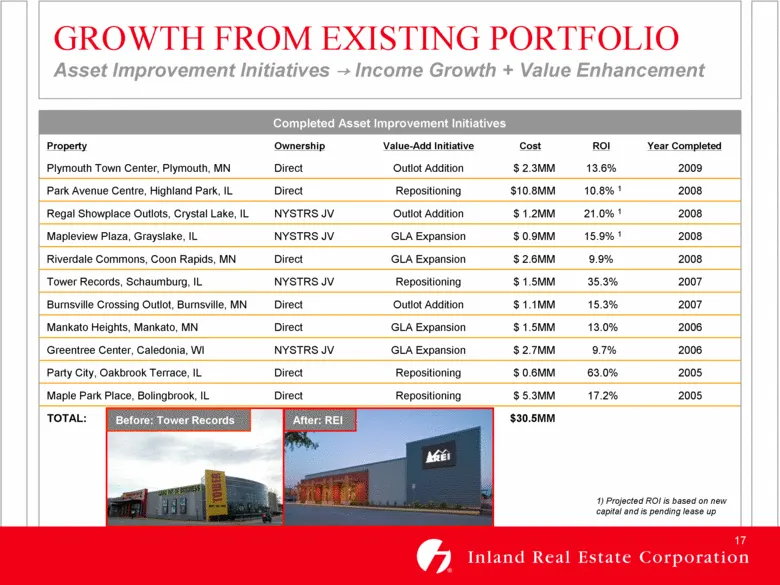
GROWTH FROM EXISTING PORTFOLIO Asset Improvement Initiatives ® Income Growth + Value Enhancement Completed Asset Improvement Initiatives Property Ownership Value-Add Initiative Cost ROI Year Completed Plymouth Town Center, Plymouth, MN Direct Outlot Addition $ 2.3MM 13.6% 2009 Park Avenue Centre, Hi
Slide 18: Growth from Existing Portfolio: In-Process Initiatives
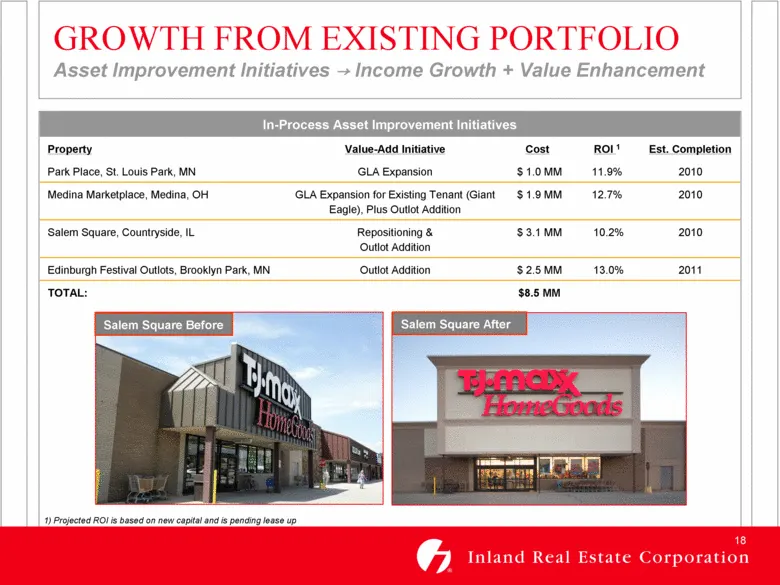
GROWTH FROM EXISTING PORTFOLIO Asset Improvement Initiatives ® Income Growth + Value Enhancement In-Process Asset Improvement Initiatives Property Value-Add Initiative Cost ROI 1 Est. Completion Park Place, St. Louis Park, MN GLA Expansion $ 1.0 MM 11.9% 2010 Medina Marketplace, Medina, OH GLA Expan
Slide 19: Acquisition History
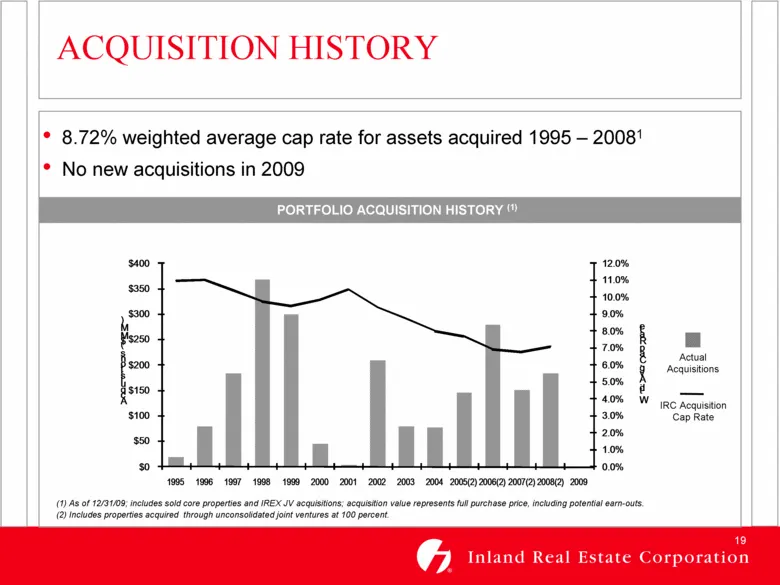
(1) As of 12/31/09; includes sold core properties and IREX JV acquisitions; acquisition value represents full purchase price, including potential earn-outs. (2) Includes properties acquired through unconsolidated joint ventures at 100 percent. ACQUISITION HISTORY 8.72% weighted average cap rate for
Slide 20: Consolidated Debt Maturities
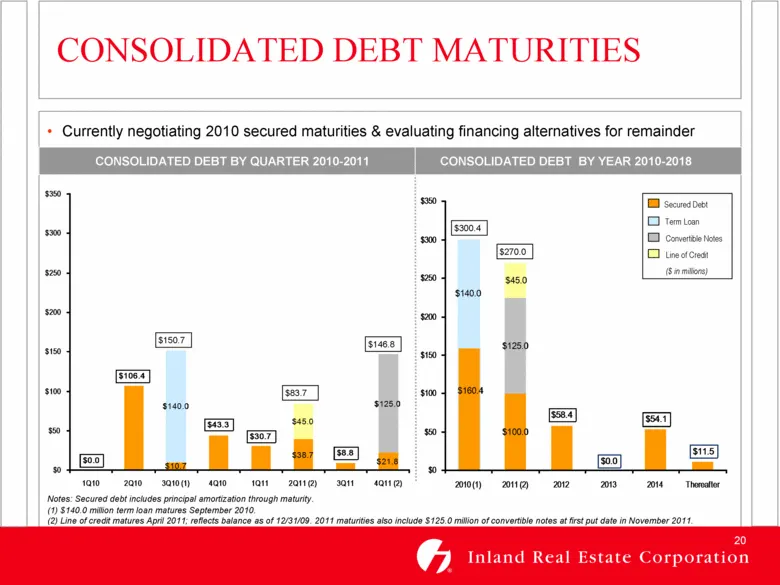
$300.4 $270.0 CONSOLIDATED DEBT MATURITIES Currently negotiating 2010 secured maturities & evaluating financing alternatives for remainder Notes: Secured debt includes principal amortization through maturity. (1) $140.0 million term loan matures September 2010. (2) Line of credit matures April 2011;
Slide 21: Joint Venture Strategies
JOINT VENTURE STRATEGIES Diversify Capital Resources + Expand Platform + Drive Future Growth Asset Based, Asset Management and Development JV Strategies Retail Focus ® IRC Knowledge High Quality Partners ® ‘Union of Expertise’ Long-term Asset Management Role Value-enhancing
Slide 22: Asset-Based Joint Venture
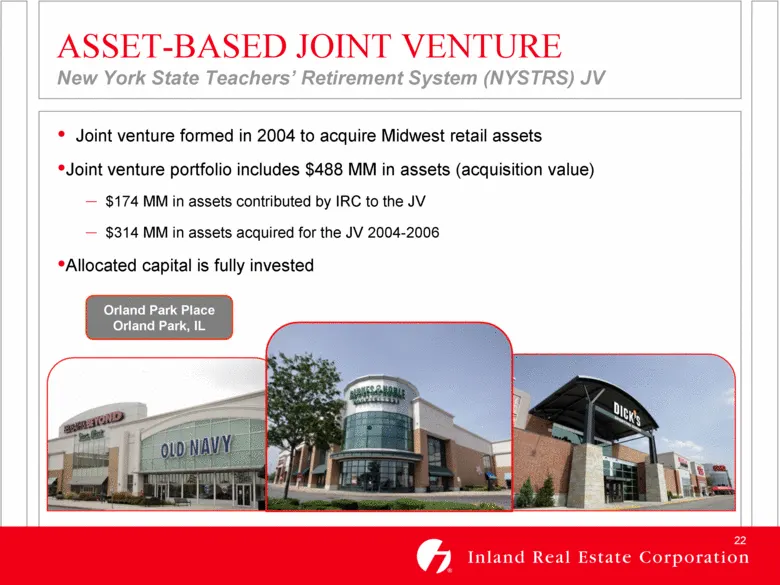
ASSET-BASED JOINT VENTURE New York State Teachers’ Retirement System (NYSTRS) JV Joint venture formed in 2004 to acquire Midwest retail assets Joint venture portfolio includes $488 MM in assets (acquisition value) $174 MM in assets contributed by IRC to the JV $314 MM in assets acquired for the JV 2
Slide 23: Asset Management Joint Venture (IREX)
ASSET MANAGEMENT JOINT VENTURE Inland Real Estate Exchange Corporation (IREX) Joint Venture Venture formed 9/06 to explore growth potential of 1031 exchange business “Union of Expertise” IRC provides acquisition / asset management expertise to premiere 1031 Exchange sponsor IREX provides syndication
Slide 24: Development Joint Ventures
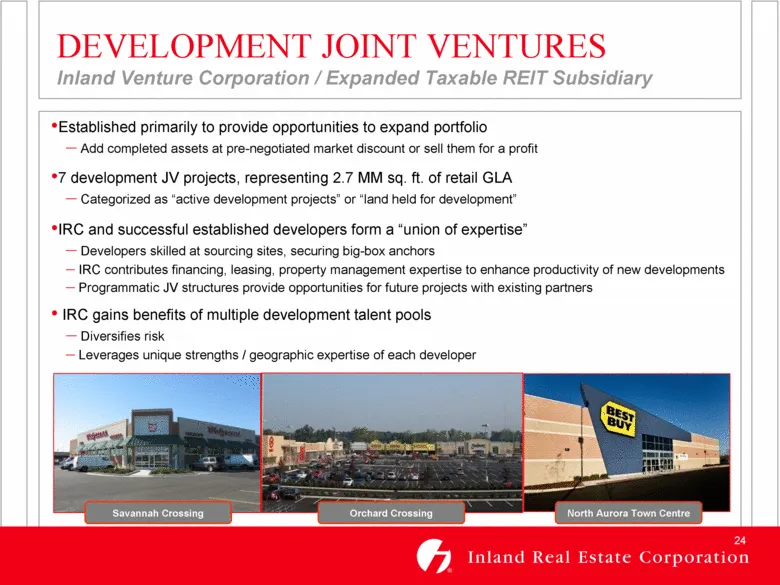
DEVELOPMENT JOINT VENTURES Inland Venture Corporation / Expanded Taxable REIT Subsidiary Established primarily to provide opportunities to expand portfolio Add completed assets at pre-negotiated market discount or sell them for a profit 7 development JV projects, representing 2.7 MM sq. ft. of retai
Slide 25: Active Development Projects
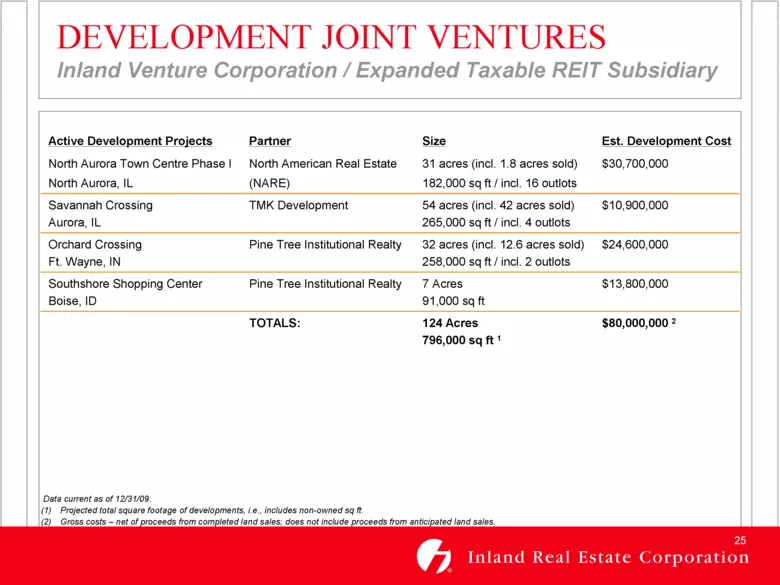
Active Development Projects Partner Size Est. Development Cost North Aurora Town Centre Phase I North Aurora, IL North American Real Estate (NARE) 31 acres (incl. 1.8 acres sold) 182,000 sq ft / incl. 16 outlots $30,700,000 Savannah Crossing Aurora, IL TMK Development 54 acres (incl. 42 acres sold)
Slide 26: Land Held for Development
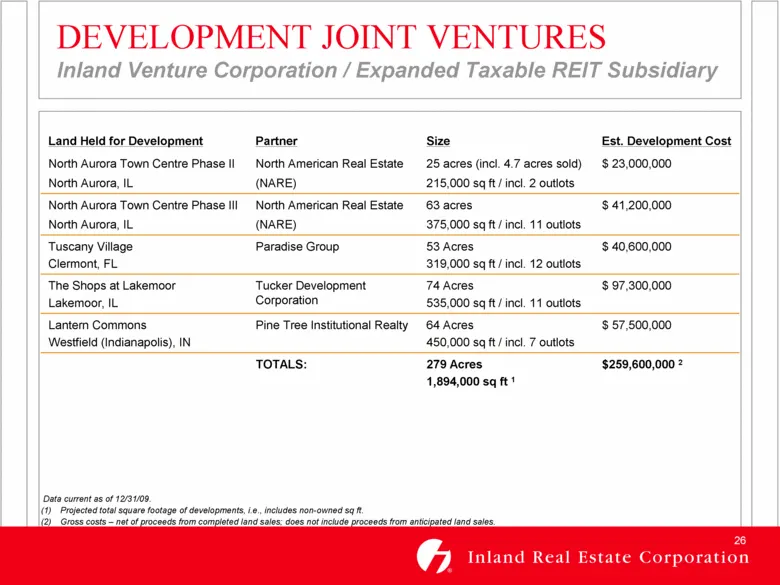
Land Held for Development Partner Size Est. Development Cost North Aurora Town Centre Phase II North Aurora, IL North American Real Estate (NARE) 25 acres (incl. 4.7 acres sold) 215,000 sq ft / incl. 2 outlots $ 23,000,000 North Aurora Town Centre Phase III North Aurora, IL North American Real Estat
Slide 27: Joint Venture Fee Income
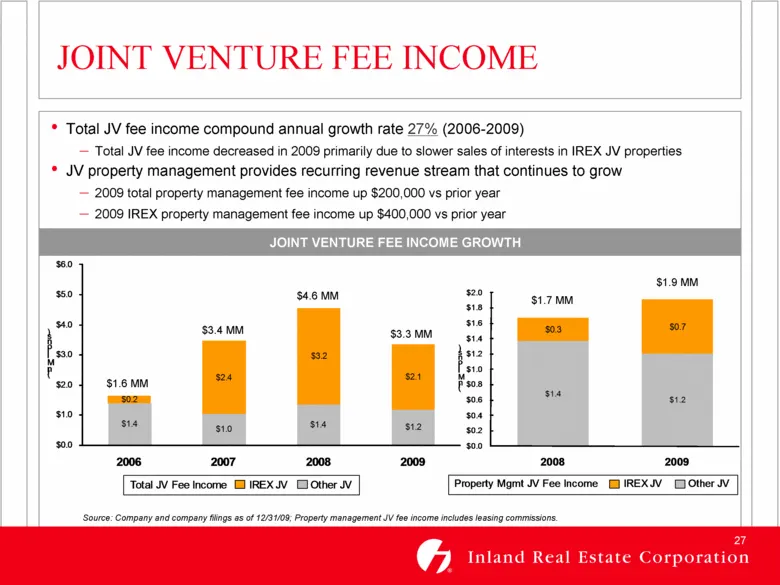
JOINT VENTURE FEE INCOME JOINT VENTURE FEE INCOME GROWTH $1.6 MM $3.4 MM $4.6 MM Total JV fee income compound annual growth rate 27% (2006-2009) Total JV fee income decreased in 2009 primarily due to slower sales of interests in IREX JV properties JV property management provides recurring revenue st
Slide 28: IRC is well positioned to weather current conditions
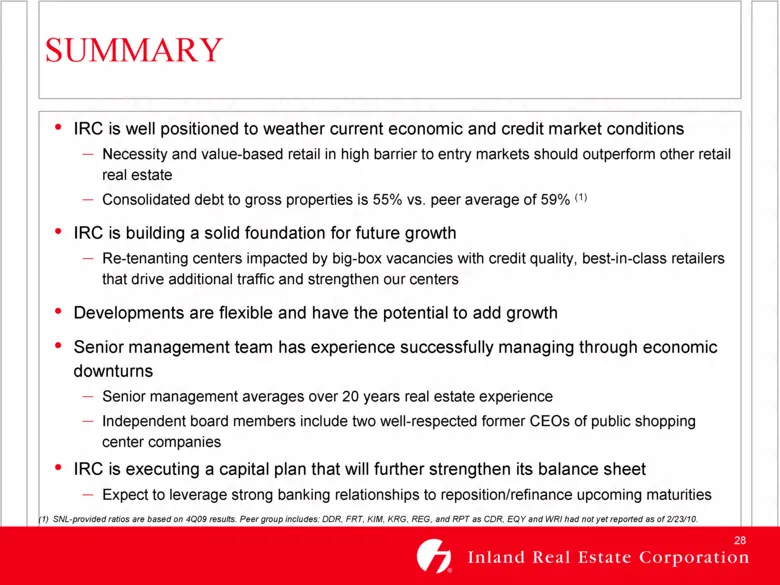
IRC is well positioned to weather current economic and credit market conditions Necessity and value-based retail in high barrier to entry markets should outperform other retail real estate Consolidated debt to gross properties is 55% vs. peer average of 59% (1) IRC is building a solid foundation for
Slide 29: Forward-Looking Statements
FORWARD-LOOKING STATEMENTS These presentation materials contain forward-looking statements. Forward-looking statements are statements that are not historical, including statements regarding management's intentions, beliefs, expectations, representations, plans or predictions of the future, and are t
Source: SEC EDGAR · 8-K filed Mar 1, 2010
More decks from Inland Real Estate Corp
 Investor Presentation (November 2015)30 slides · Nov 17, 2015
 Investor Presentation (September 2015)29 slides · Sep 16, 2015
 Investor Presentation (June 2015)29 slides · Jun 9, 2015
 Investor Presentation (May 2015)26 slides · May 15, 2015
 Investor Presentation (February 2015)26 slides · Feb 24, 2015
 Investor Presentation (November 2014)26 slides · Nov 5, 2014