Scpie — Merger or Acquisition (December 2007)
19 slides from Scpie's merger presentation, Dec 5, 2007
Slide 1: Schedule 14A
UNITED STATES SECURITIES AND EXCHANGE COMMISSION WASHINGTON, D.C. 20549 SCHEDULE 14A Proxy Statement Pursuant to Section 14(a) of the Securities Exchange Act of 1934 (AMENDMENT NO. ) Filed by the Registrant x Filed by a Party other than the Registrant ¨ Check the appropriate box: ¨ Preliminary Proxy
Slide 2: SCPIE's Proposed Transaction with The Doctors Company: Maximizing Shareholder Value
SCPIE’s Proposed Transaction with The Doctors Company: Maximizing Shareholder Value December 2007
Slide 3: Safe Harbor Statement
Safe Harbor Statement In addition to historical information, this presentation contains forward-looking statements that are based upon SCPIE’s estimates and expectations concerning future events and are subject to certain risks and uncertainties that could cause actual results to differ materially f
Slide 4: Summary
Summary SCPIE conducted a thorough evaluation of strategic alternatives Comprehensive auction process The time to sell is now Scrupulous adherence to corporate governance tenets The Doctors Company bid is the most direct path to shareholder value maximization 3
Slide 5: Historical process snapshot
Historical process snapshot August 2006 – Strategic Planning Committee established to identify and analyze current and future business prospects January 2007 – Deutsche Bank hired to provide financial advisory and investment banking services March 2007 – Board reached the decision to pursue a sale i
Slide 6: SCPIE's Board observes prevailing corporate governance practices
SCPIE’s Board observes prevailing corporate governance practices Majority of Board is independent Strategic Planning Committee established Investment banker retained Independent Directors retain independent counsel in connection with the auction process Potential conflict identified: Board member Jo
Slide 7: Outlook for stand-alone SCPIE supports a sale today
Outlook for stand-alone SCPIE supports a sale today Outlook for stand-alone growth/profitability For the nine months ended September 30, 2007 (year to date), net written premiums of $95.6 million as compared to $98.9 during the same period one year ago California (one core state) medical malpractice
Slide 8: SCPIE's share price has continued to underperform
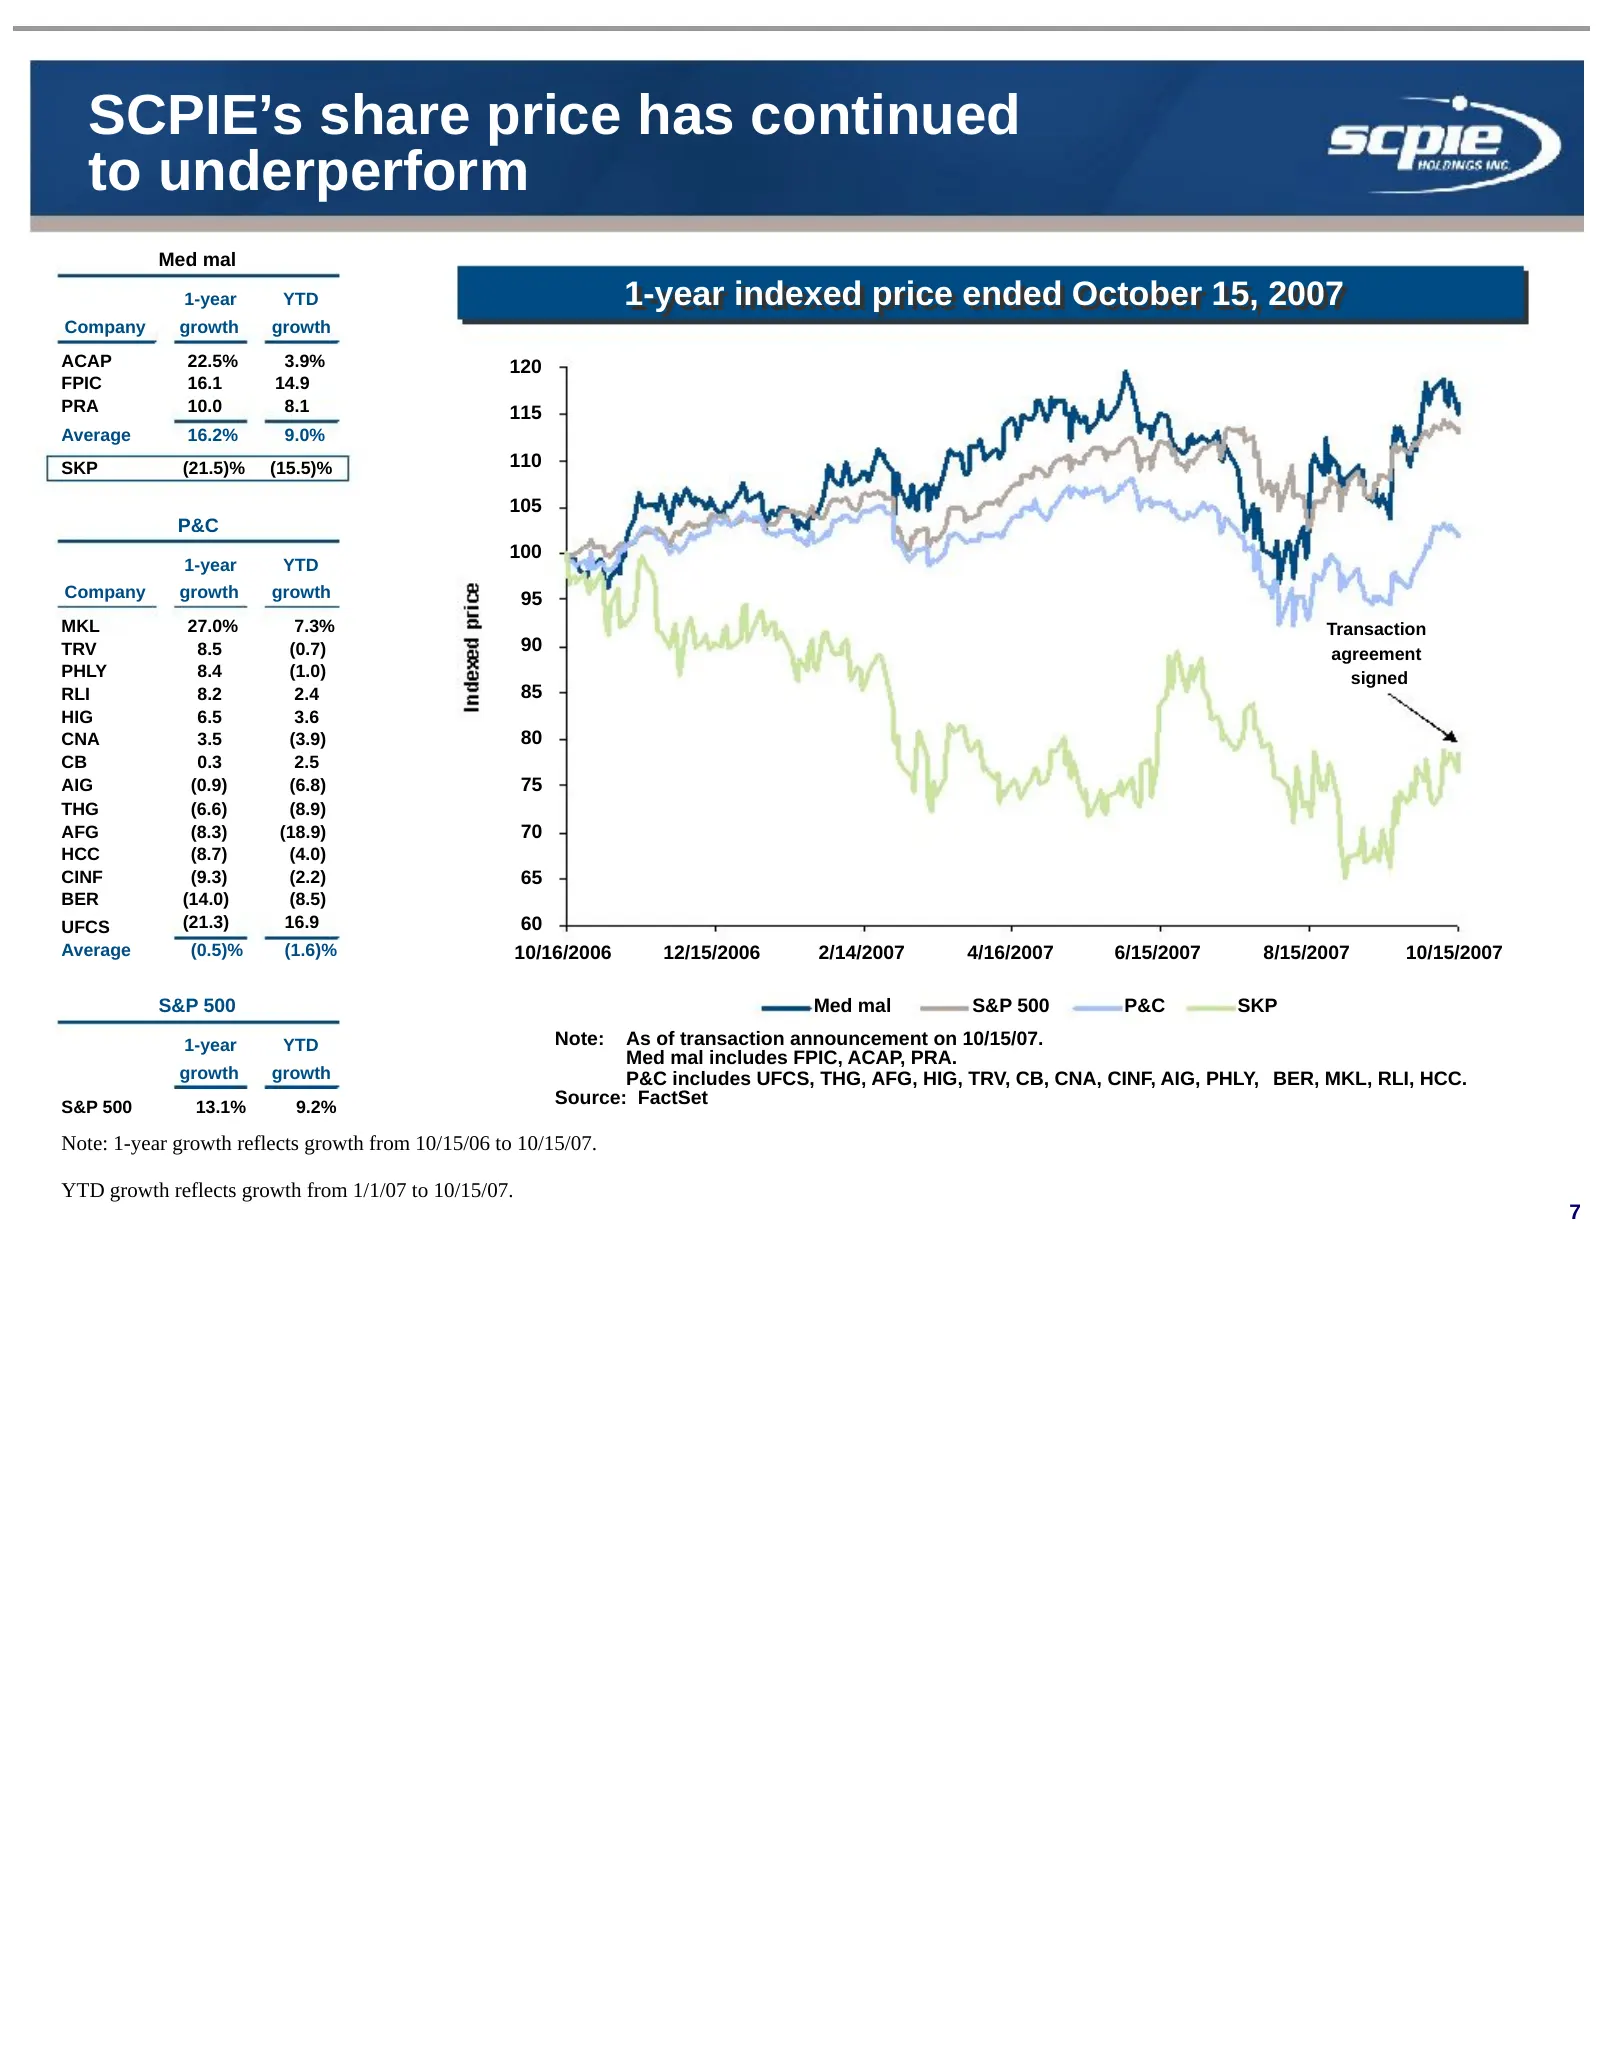
SCPIE’s share price has continued to underperform Med mal 1-year YTD 1-year 1-year indexed indexed price price ended ended October October 15, 15, 2007 2007 Company growth growth ACAP 22.5% 3.9% 120 FPIC 16.1 14.9 PRA 10.0 8.1 115 Average 16.2% 9.0% SKP (21.5)% (15.5)% 110 105 P&C 100 1-year YTD Com
Slide 9: The med mal market is dominated by large, highly-rated companies
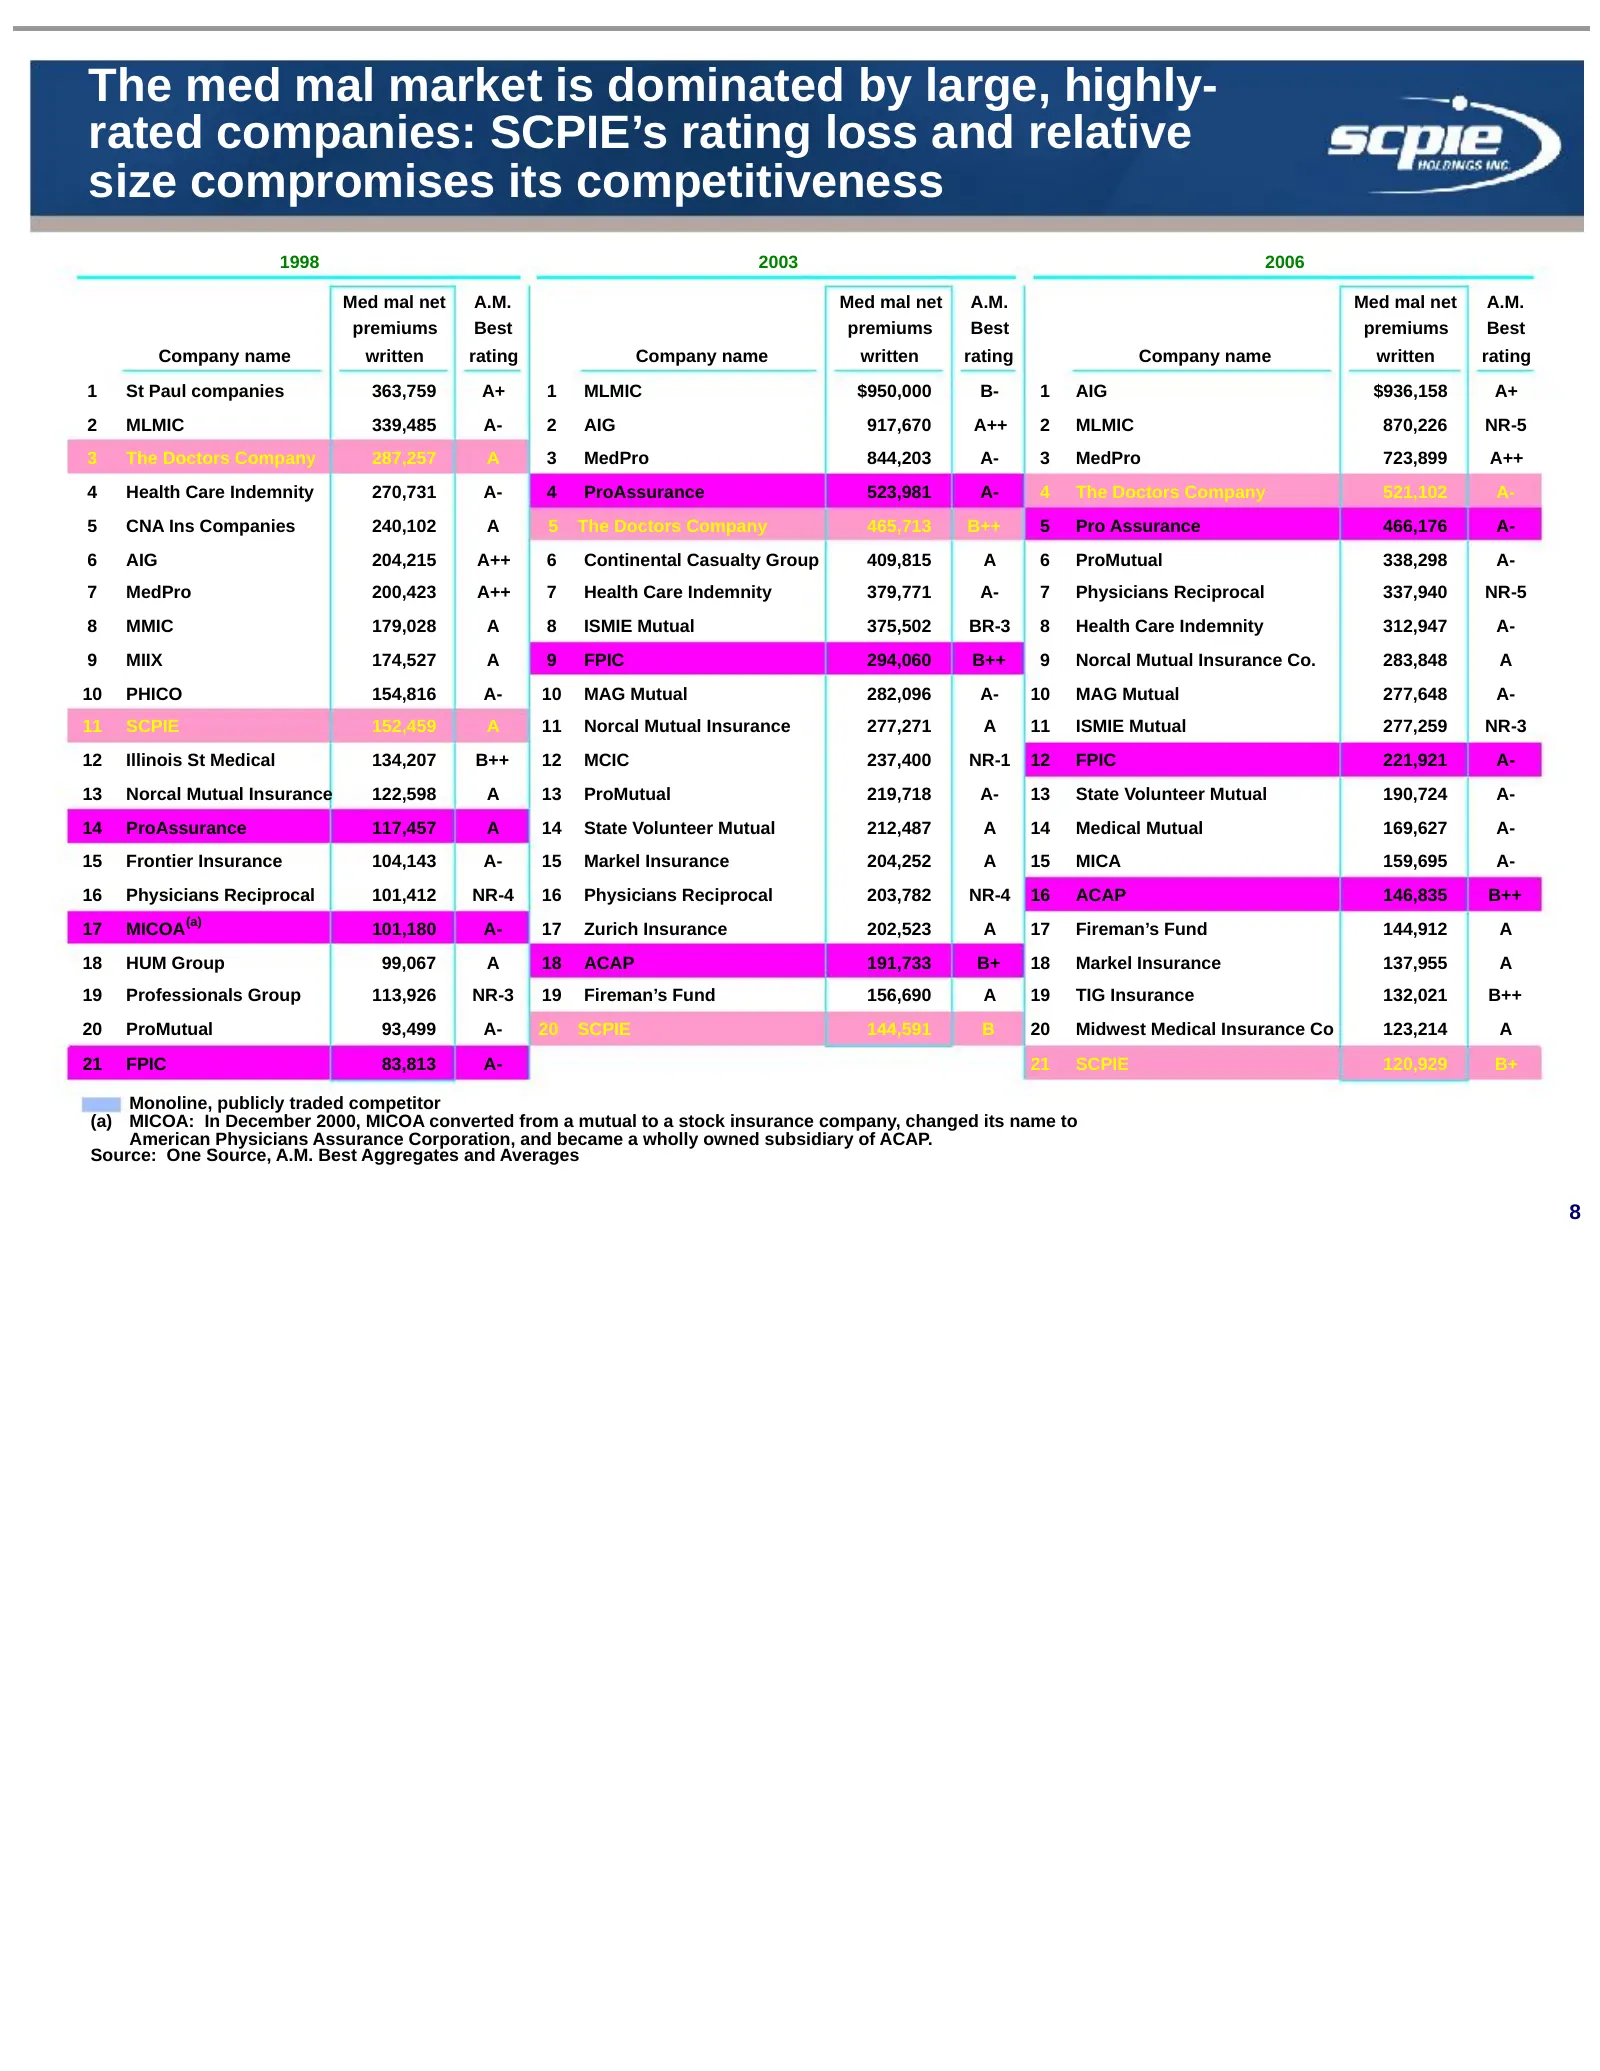
The med mal market is dominated by large, highly- rated companies: SCPIE’s rating loss and relative size compromises its competitiveness 1998 2003 2006 Med mal net A.M. Med mal net A.M. Med mal net A.M. premiums Best premiums Best premiums Best Company name written rating Company name written rating
Slide 10: Over the last five years, SCPIE has traded at an average of 49% discount to peers
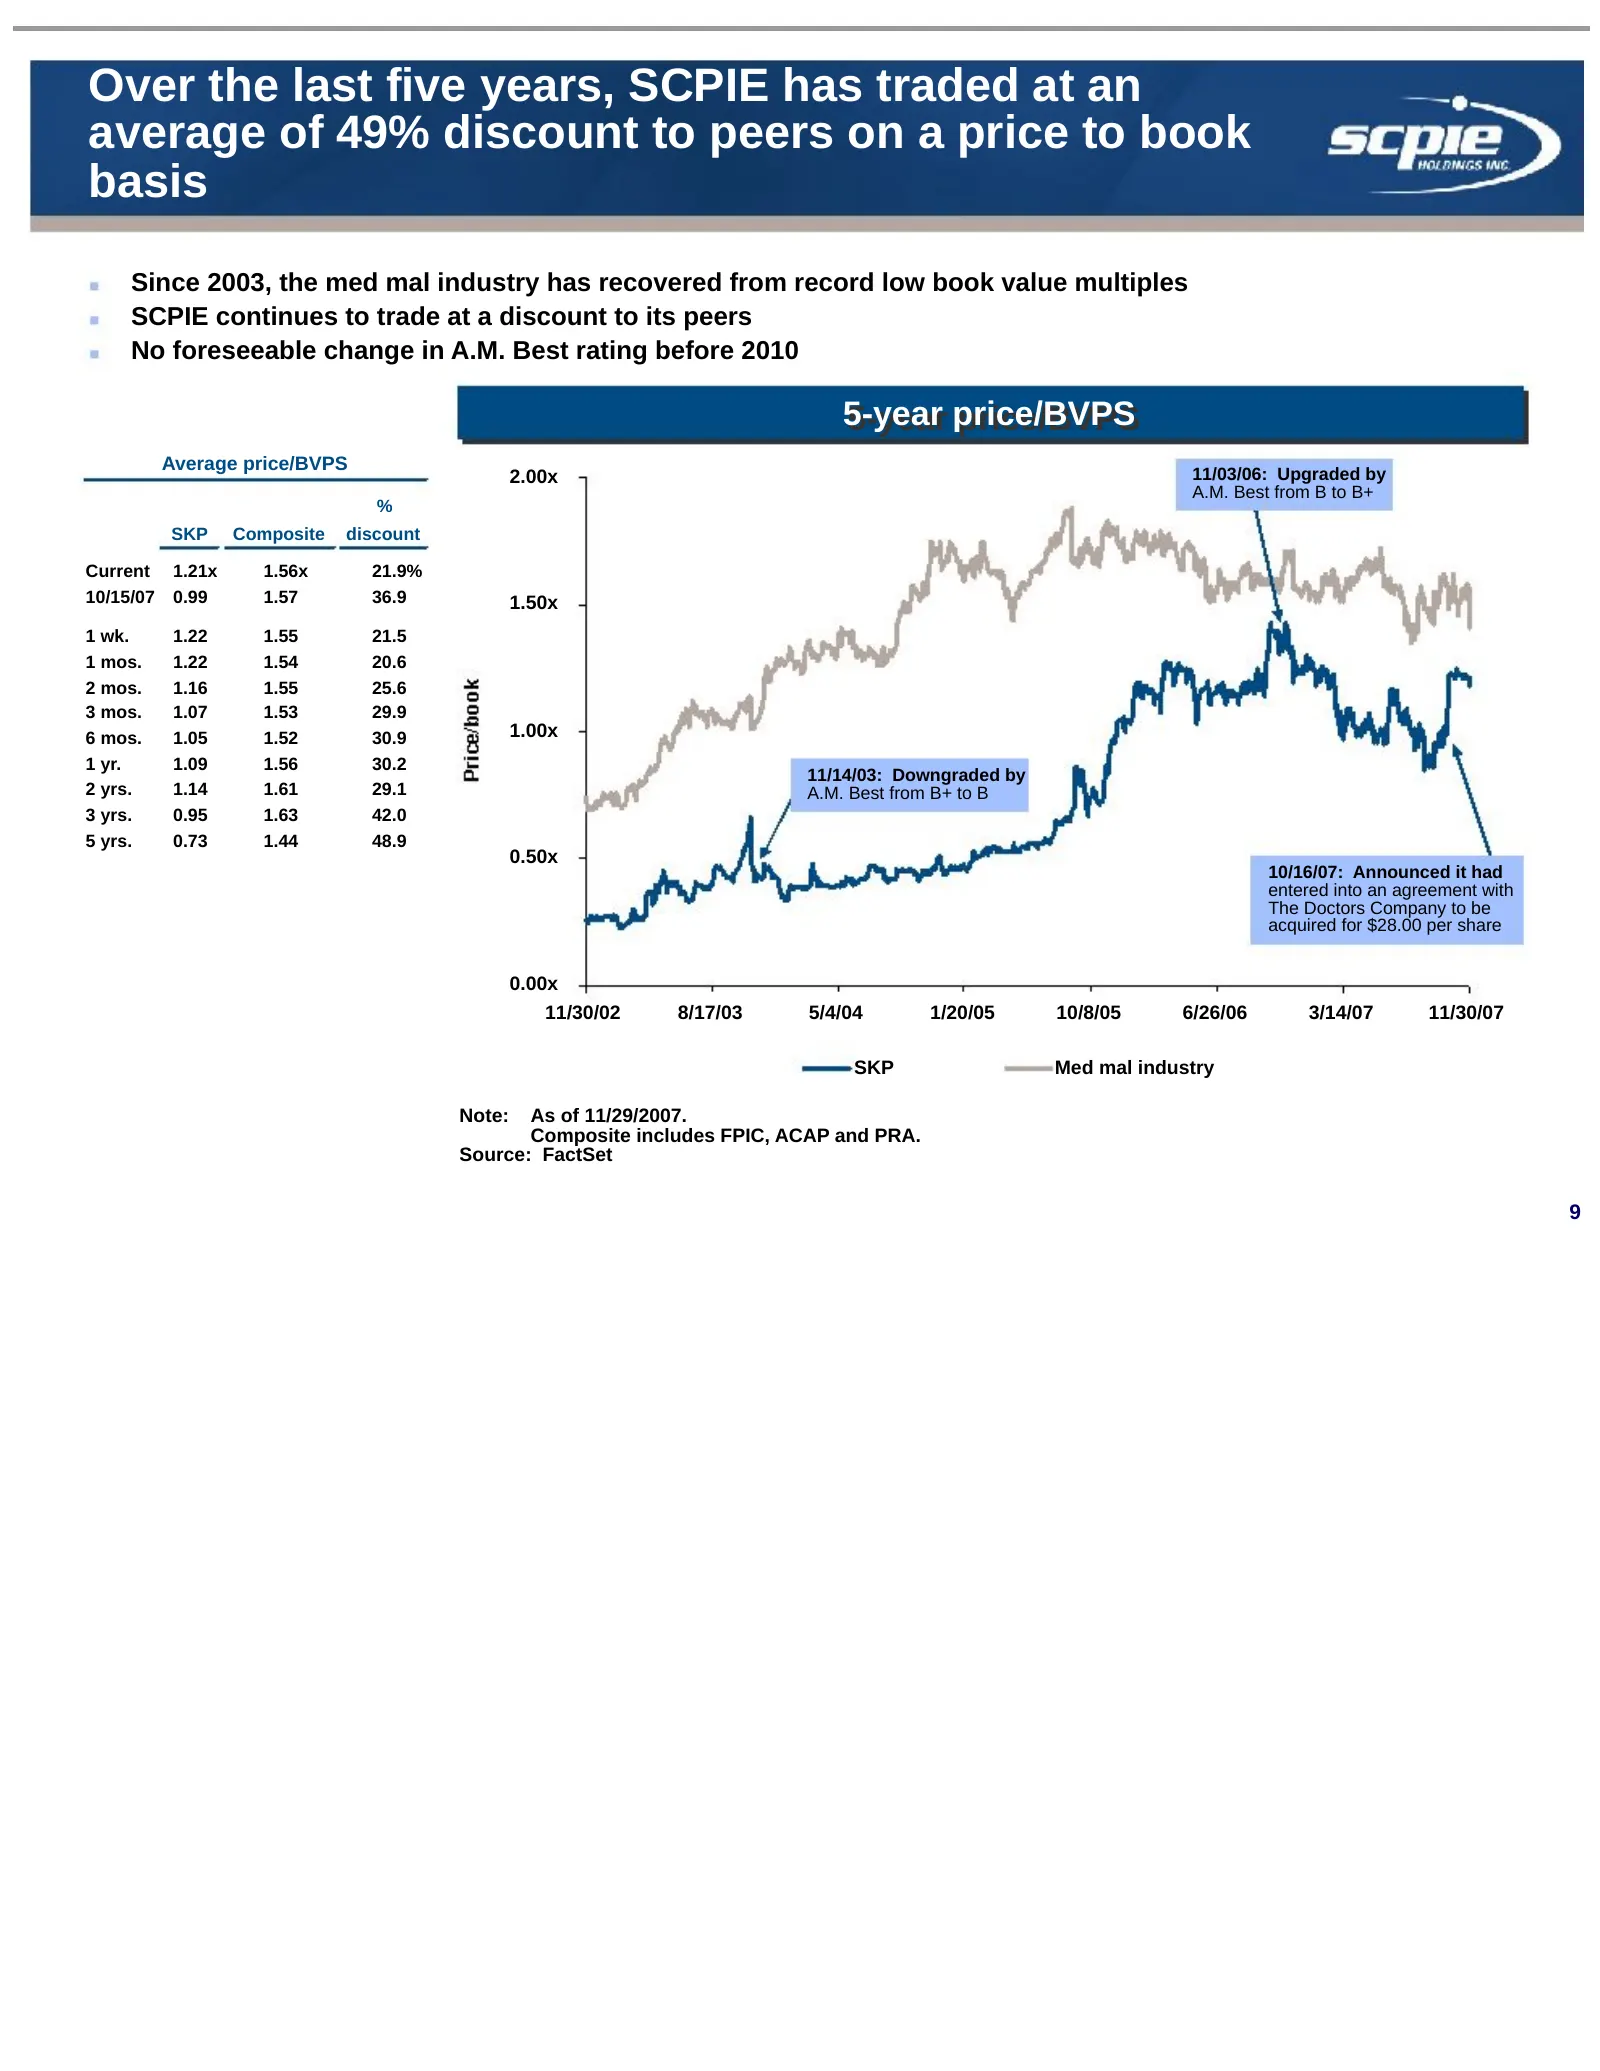
Over the last five years, SCPIE has traded at an average of 49% discount to peers on a price to book basis Since 2003, the med mal industry has recovered from record low book value multiples SCPIE continues to trade at a discount to its peers No foreseeable change in A.M. Best rating before 2010 5-y
Slide 11: SCPIE faces significant financial challenges
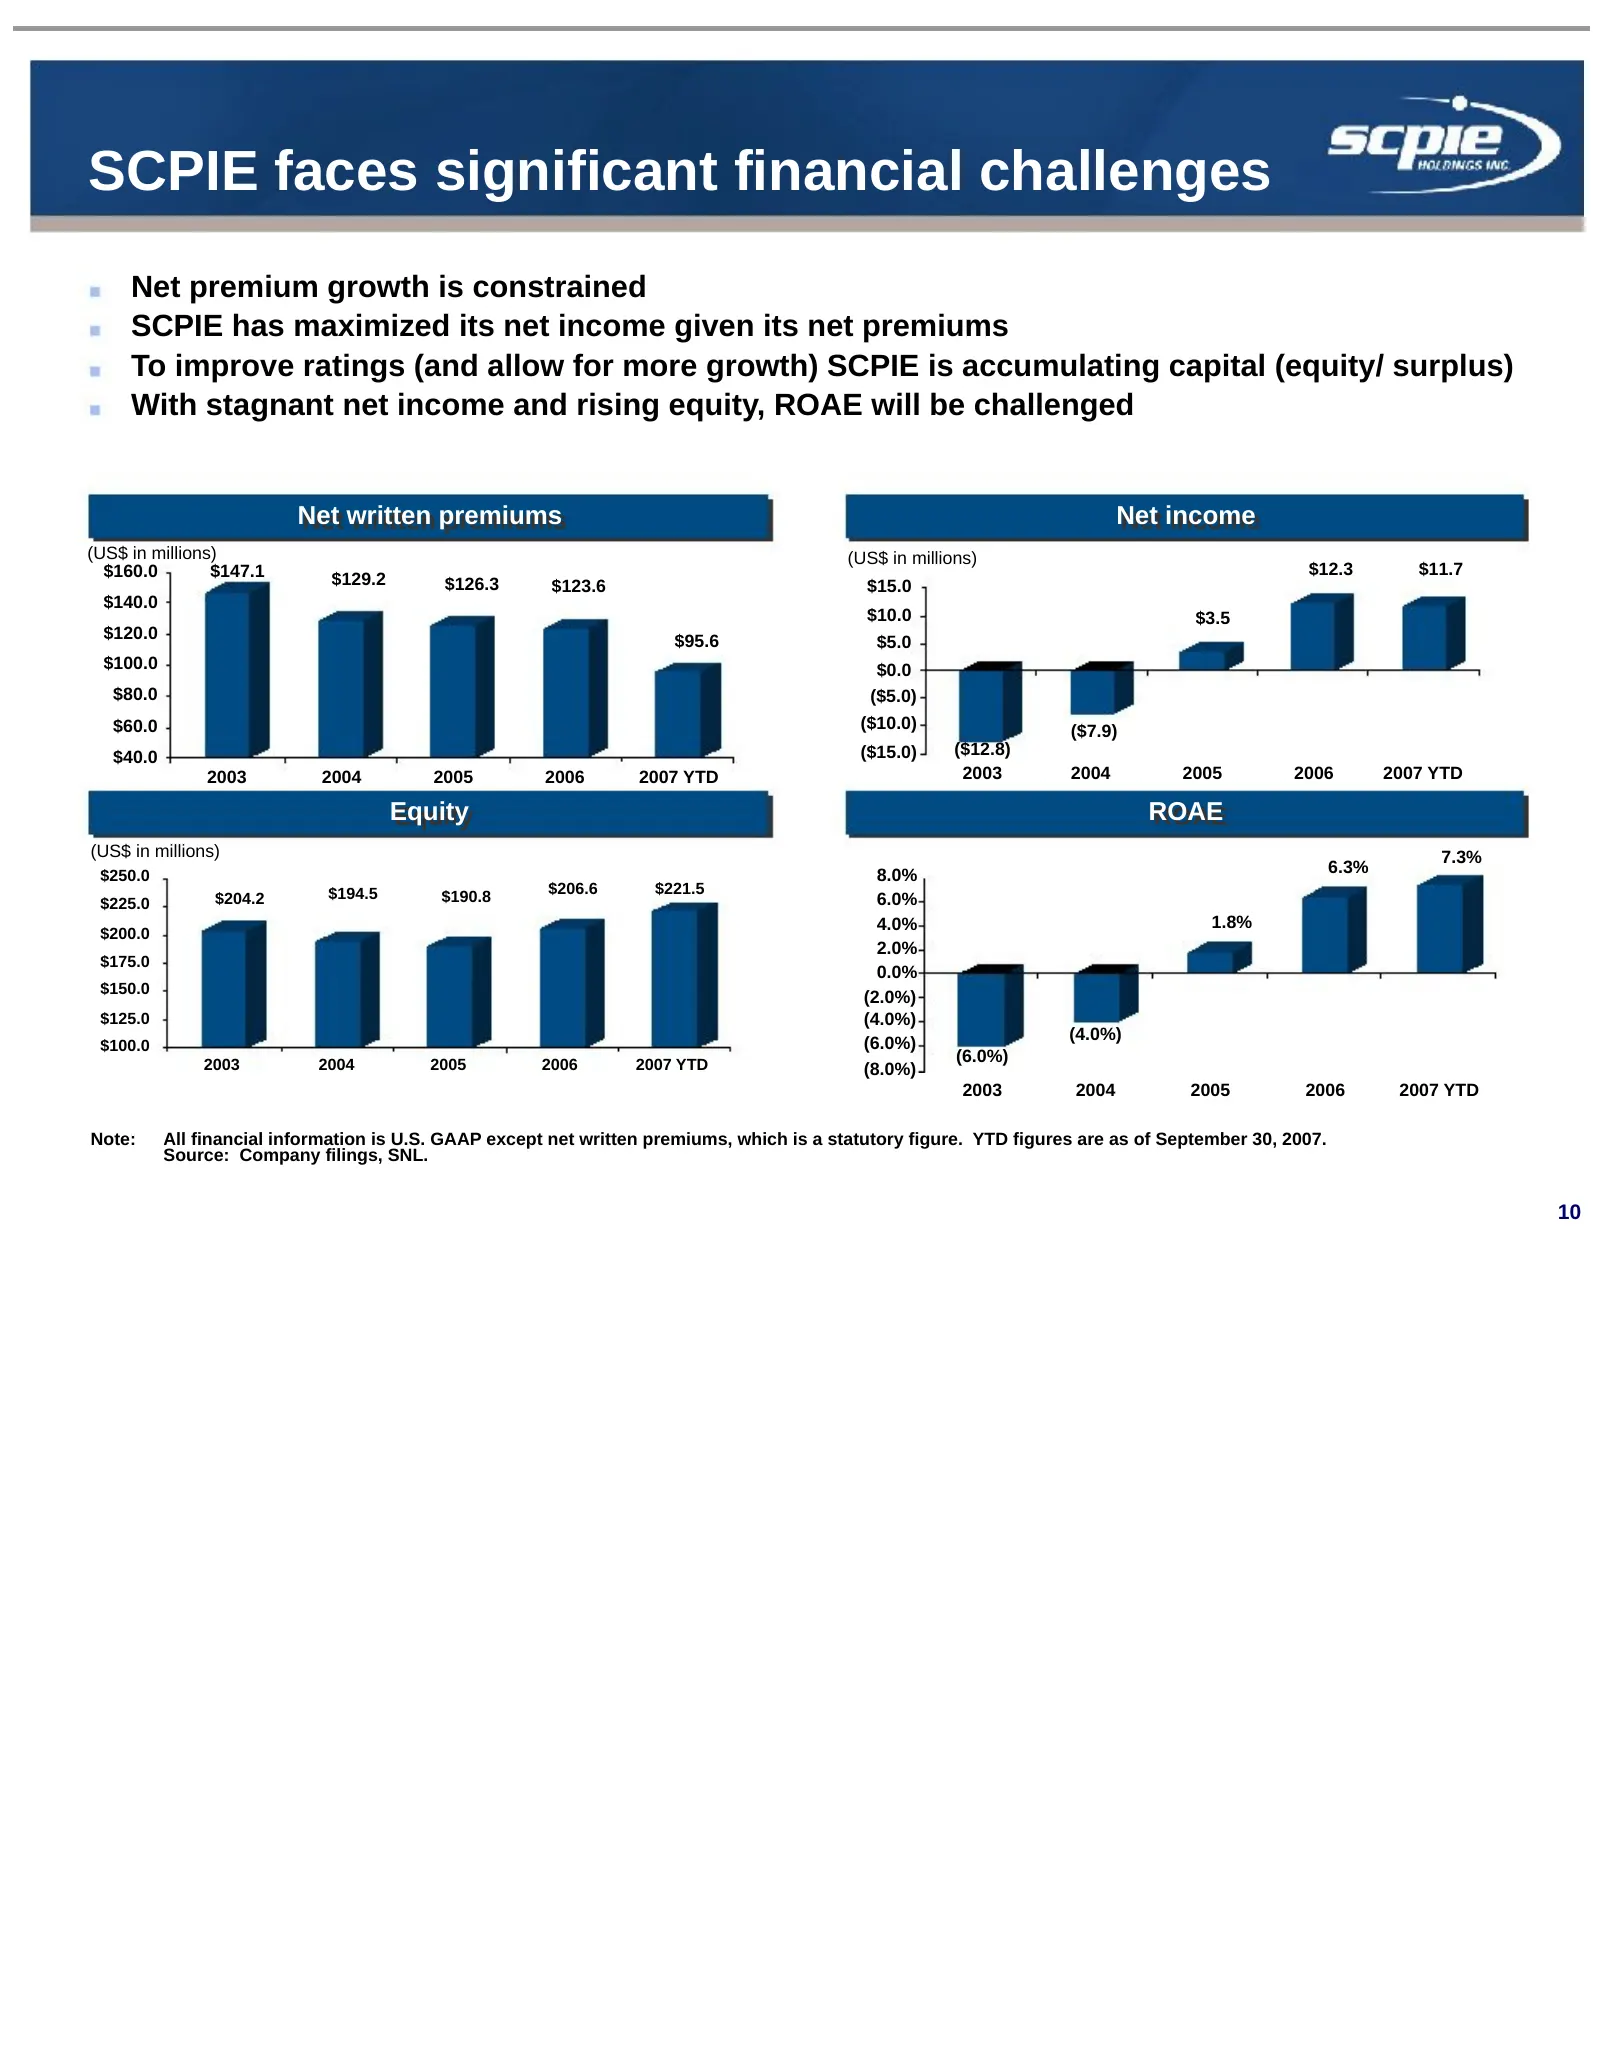
SCPIE faces significant financial challenges Net premium growth is constrained SCPIE has maximized its net income given its net premiums To improve ratings (and allow for more growth) SCPIE is accumulating capital (equity/ surplus) With stagnant net income and rising equity, ROAE will be challenged
Slide 12: SCPIE has lowest ROAE among its peers
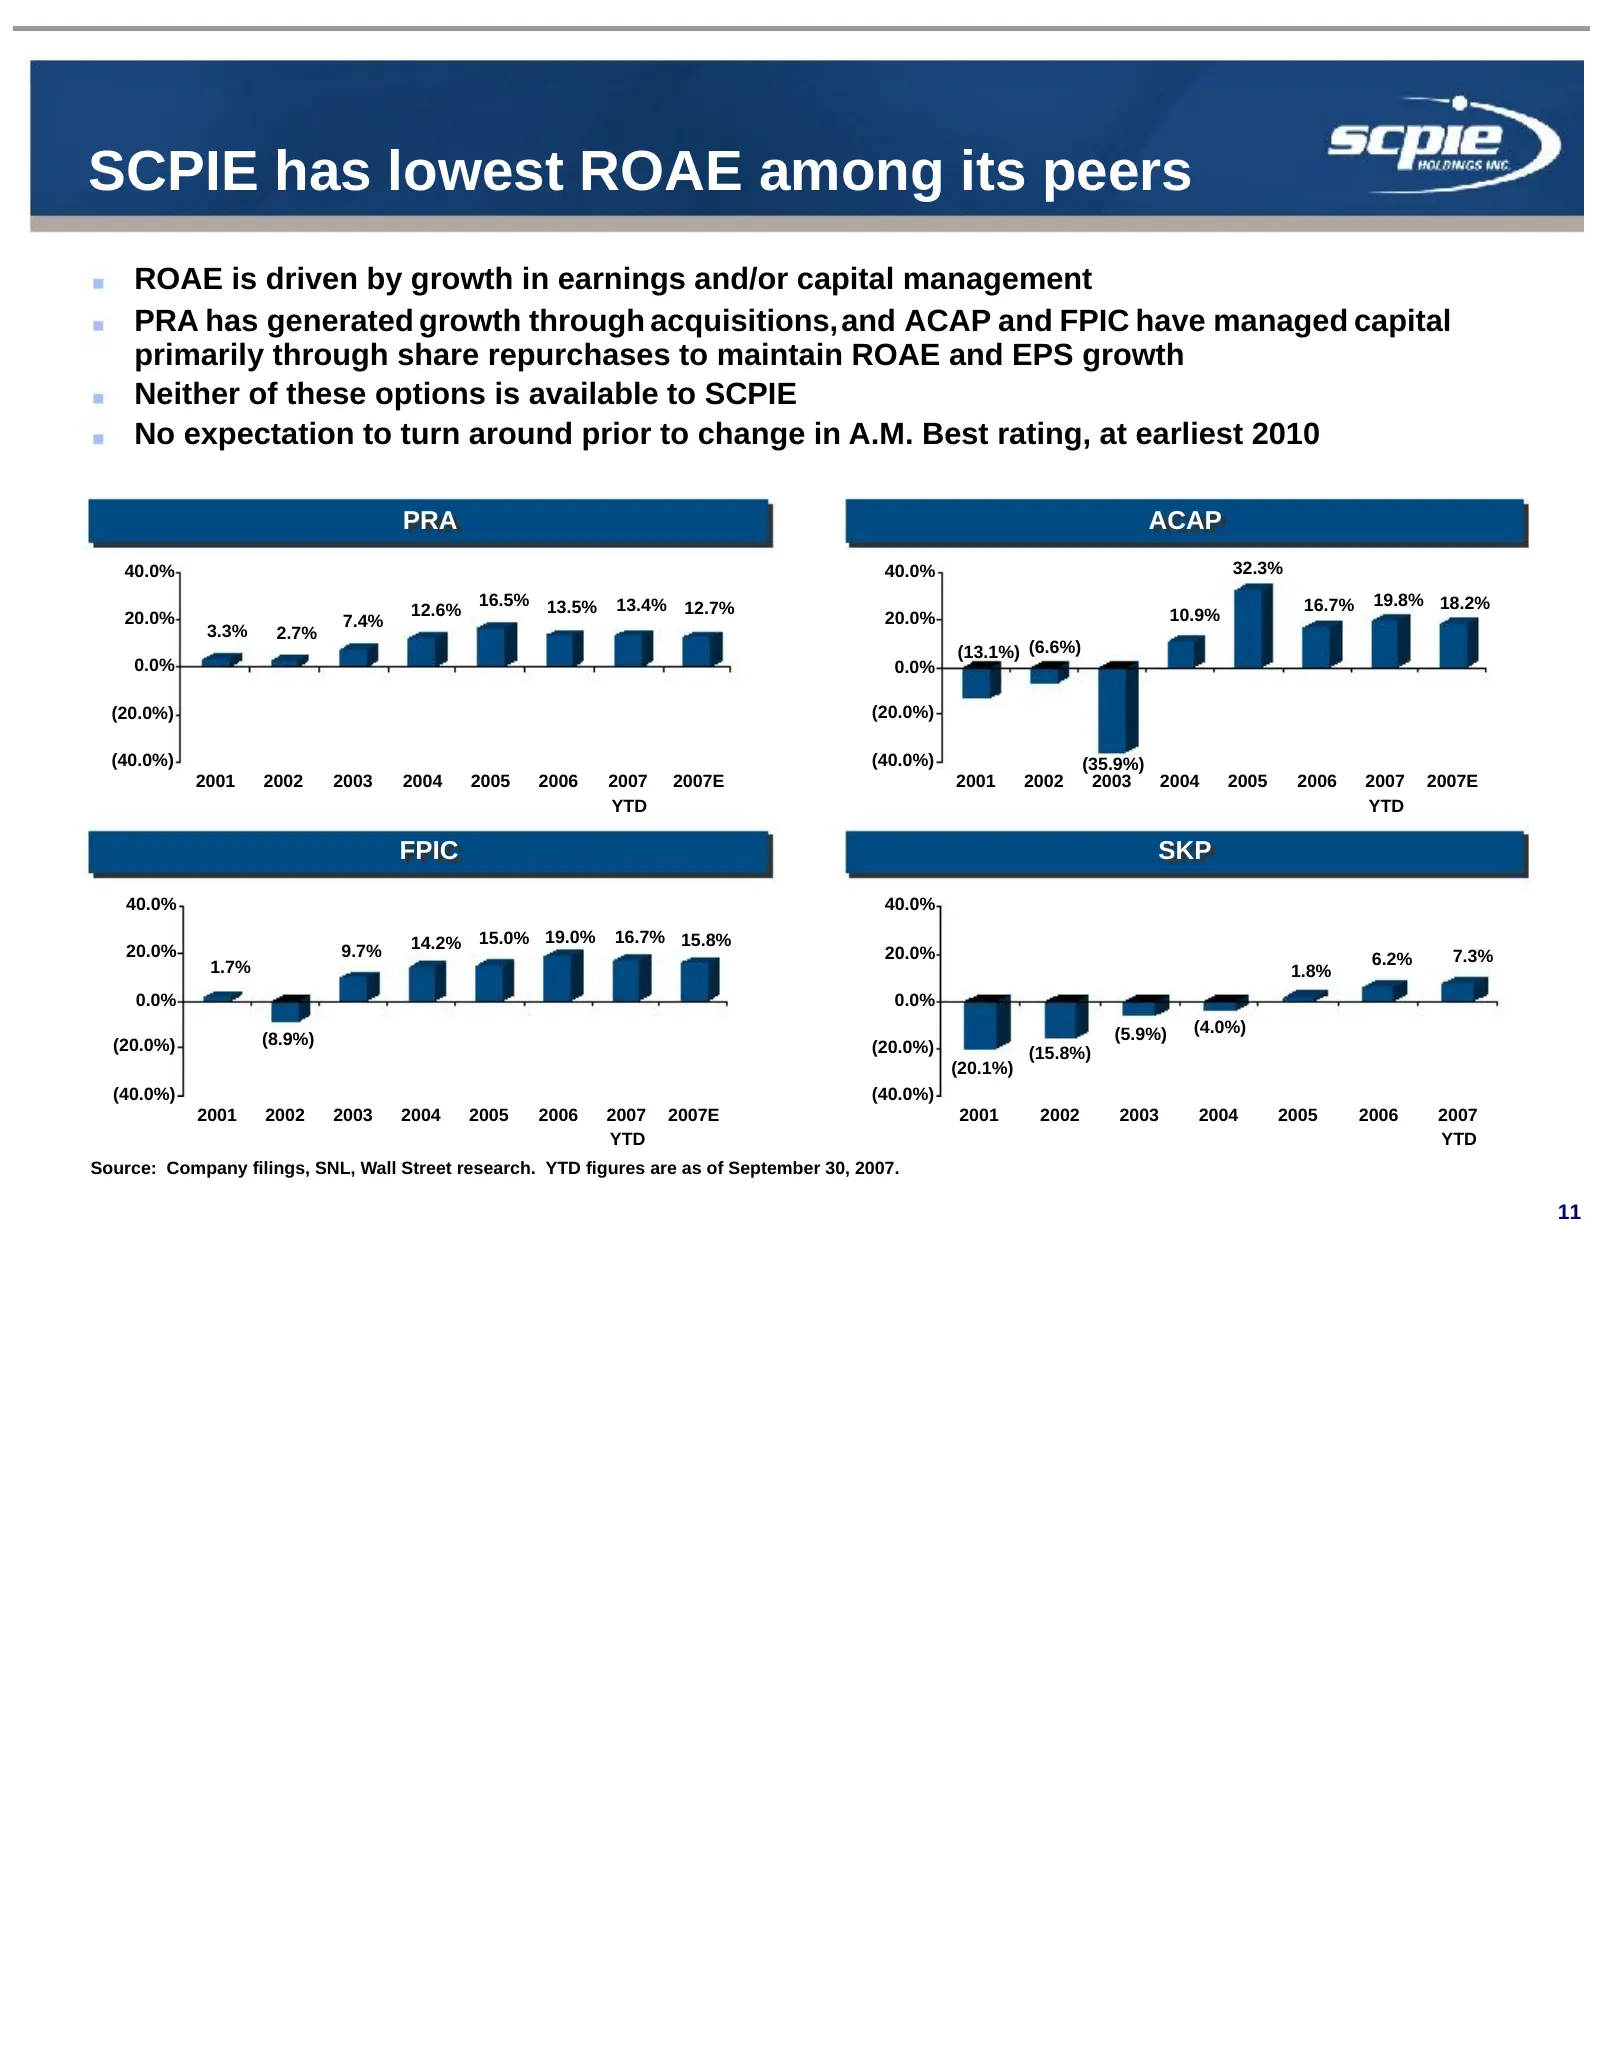
SCPIE has lowest ROAE among its peers ROAE is driven by growth in earnings and/or capital management PRA has generated growth through acquisitions,and ACAP and FPIC have managed capital primarily through share repurchases to maintain ROAE and EPS growth Neither of these options is available to SCPIE
Slide 13: SCPIE book value multiple is unlikely to improve
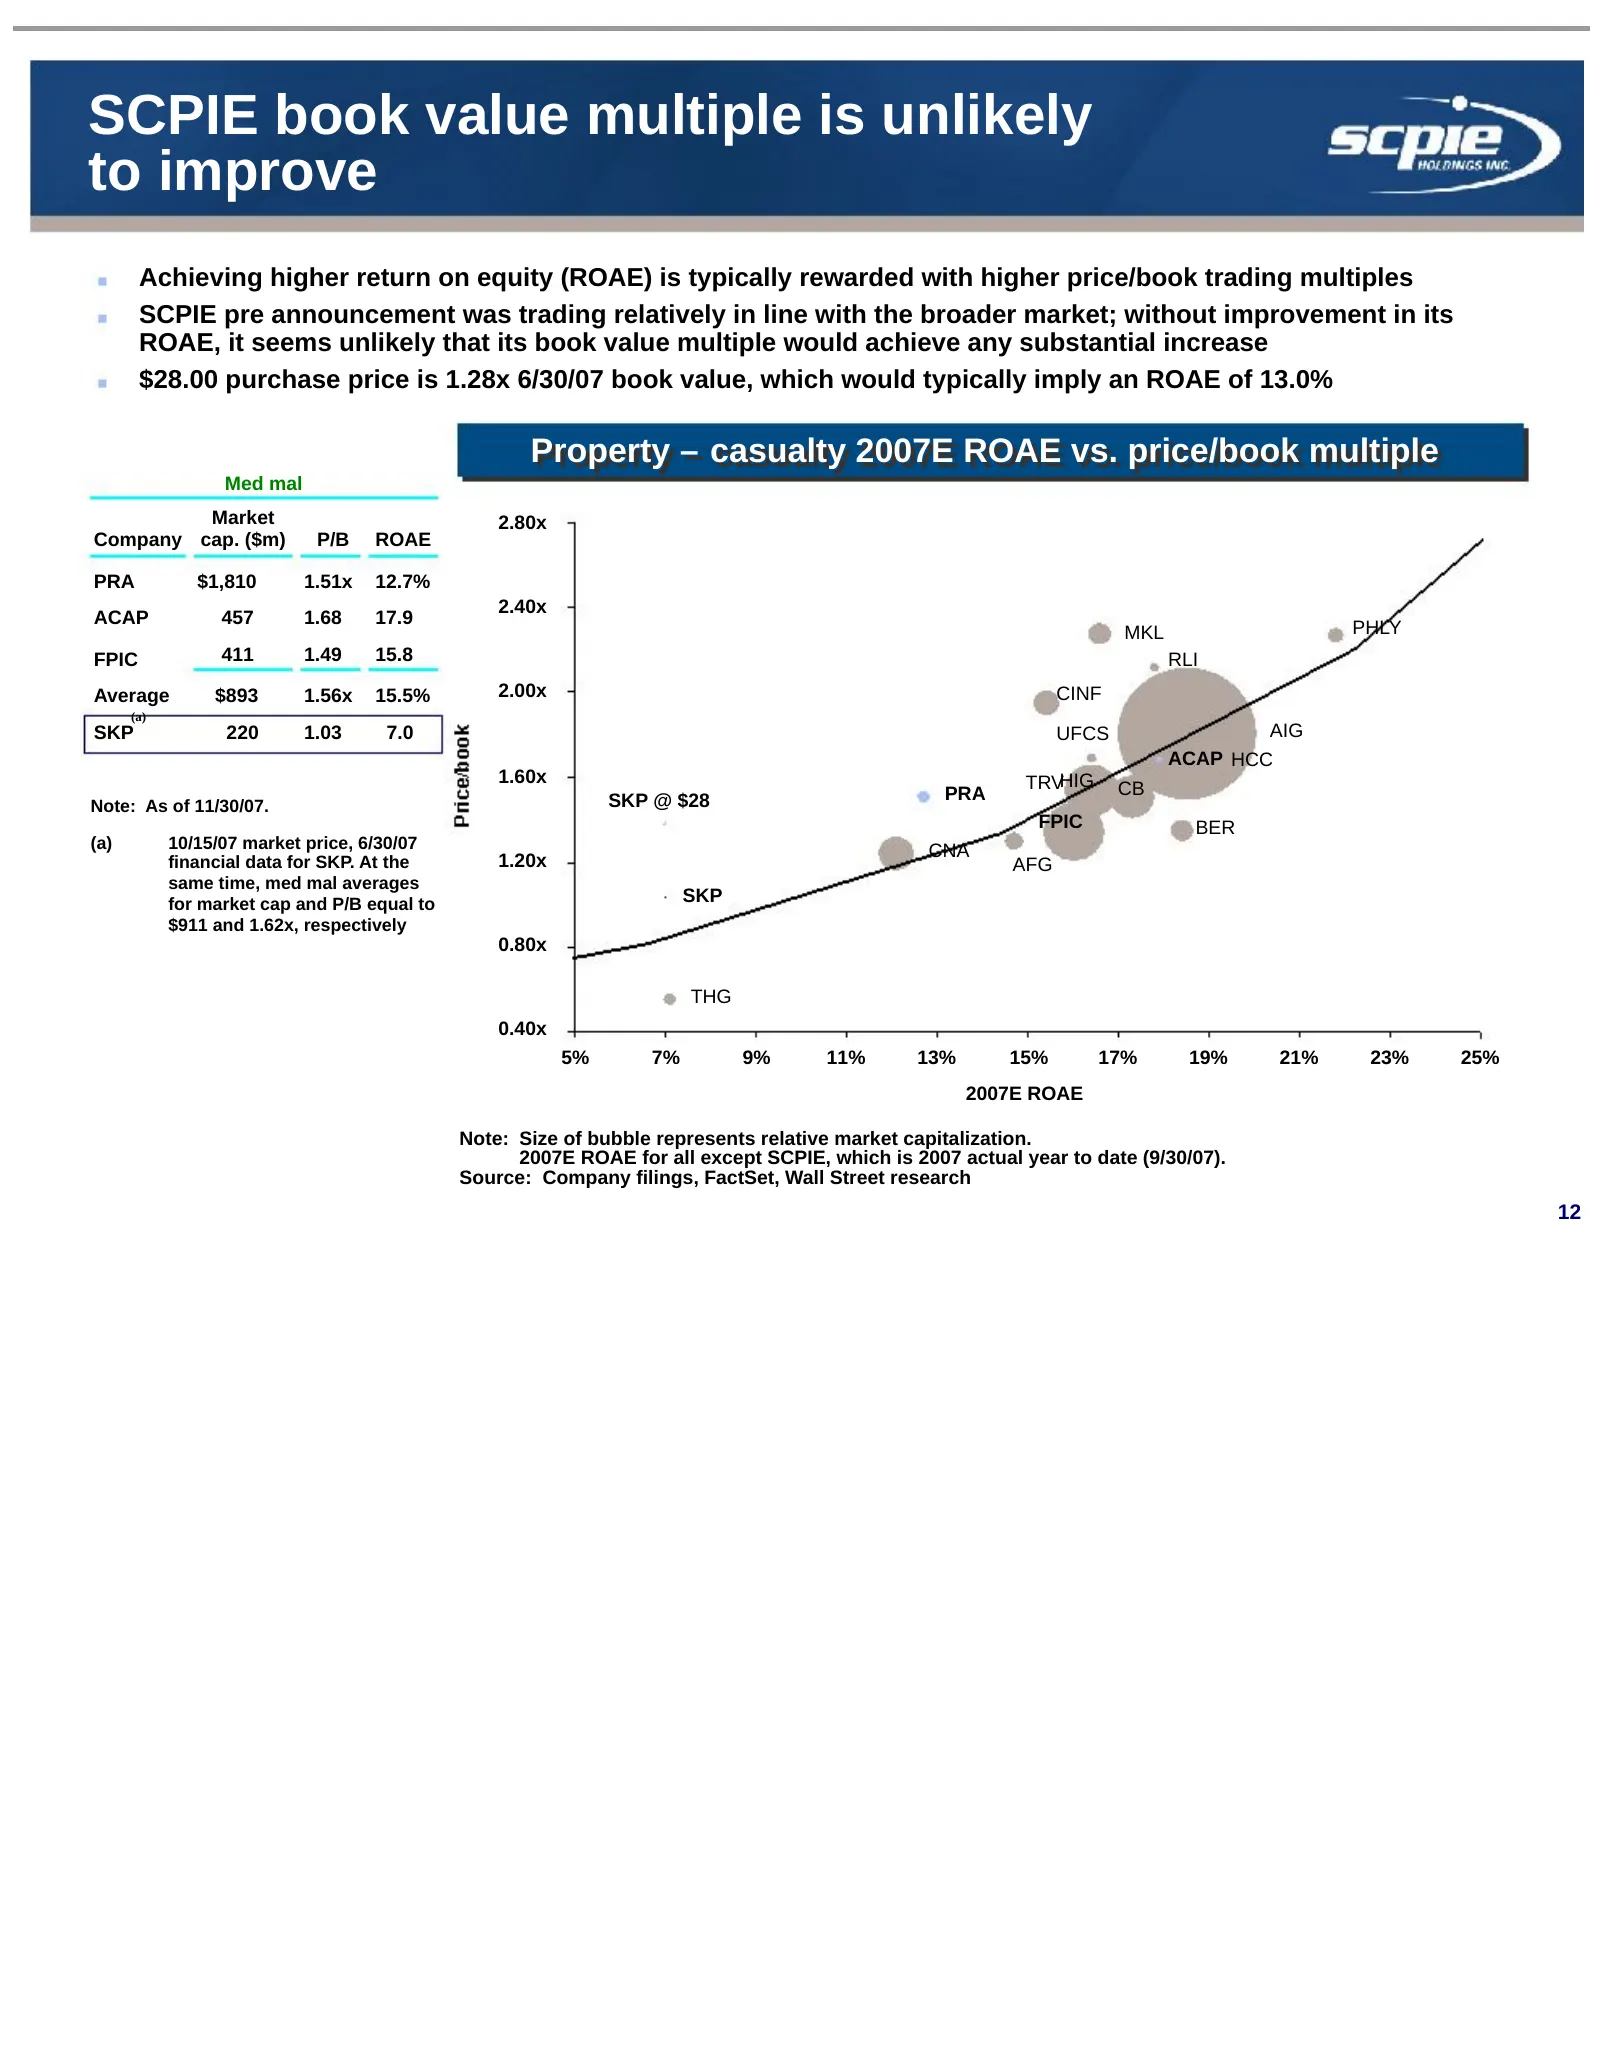
SCPIE book value multiple is unlikely to improve Achieving higher return on equity (ROAE) is typically rewarded with higher price/book trading multiples SCPIE pre announcement was trading relatively in line with the broader market; without improvement in its ROAE, it seems unlikely that its book val
Slide 14: SCPIE Board ran a robust auction
SCPIE Board ran a robust auction March 2007 - October 2007 25 potential strategic and financial buyers contacted 11 signed confidentiality agreements Reverse due diligence explored on 3 stock bidders; 1 proceeded to advanced stages 4 active final bidders The Doctors Company final bid represents a 9.
Slide 15: SCPIE Holdings Inc. to be acquired by The Doctors Company
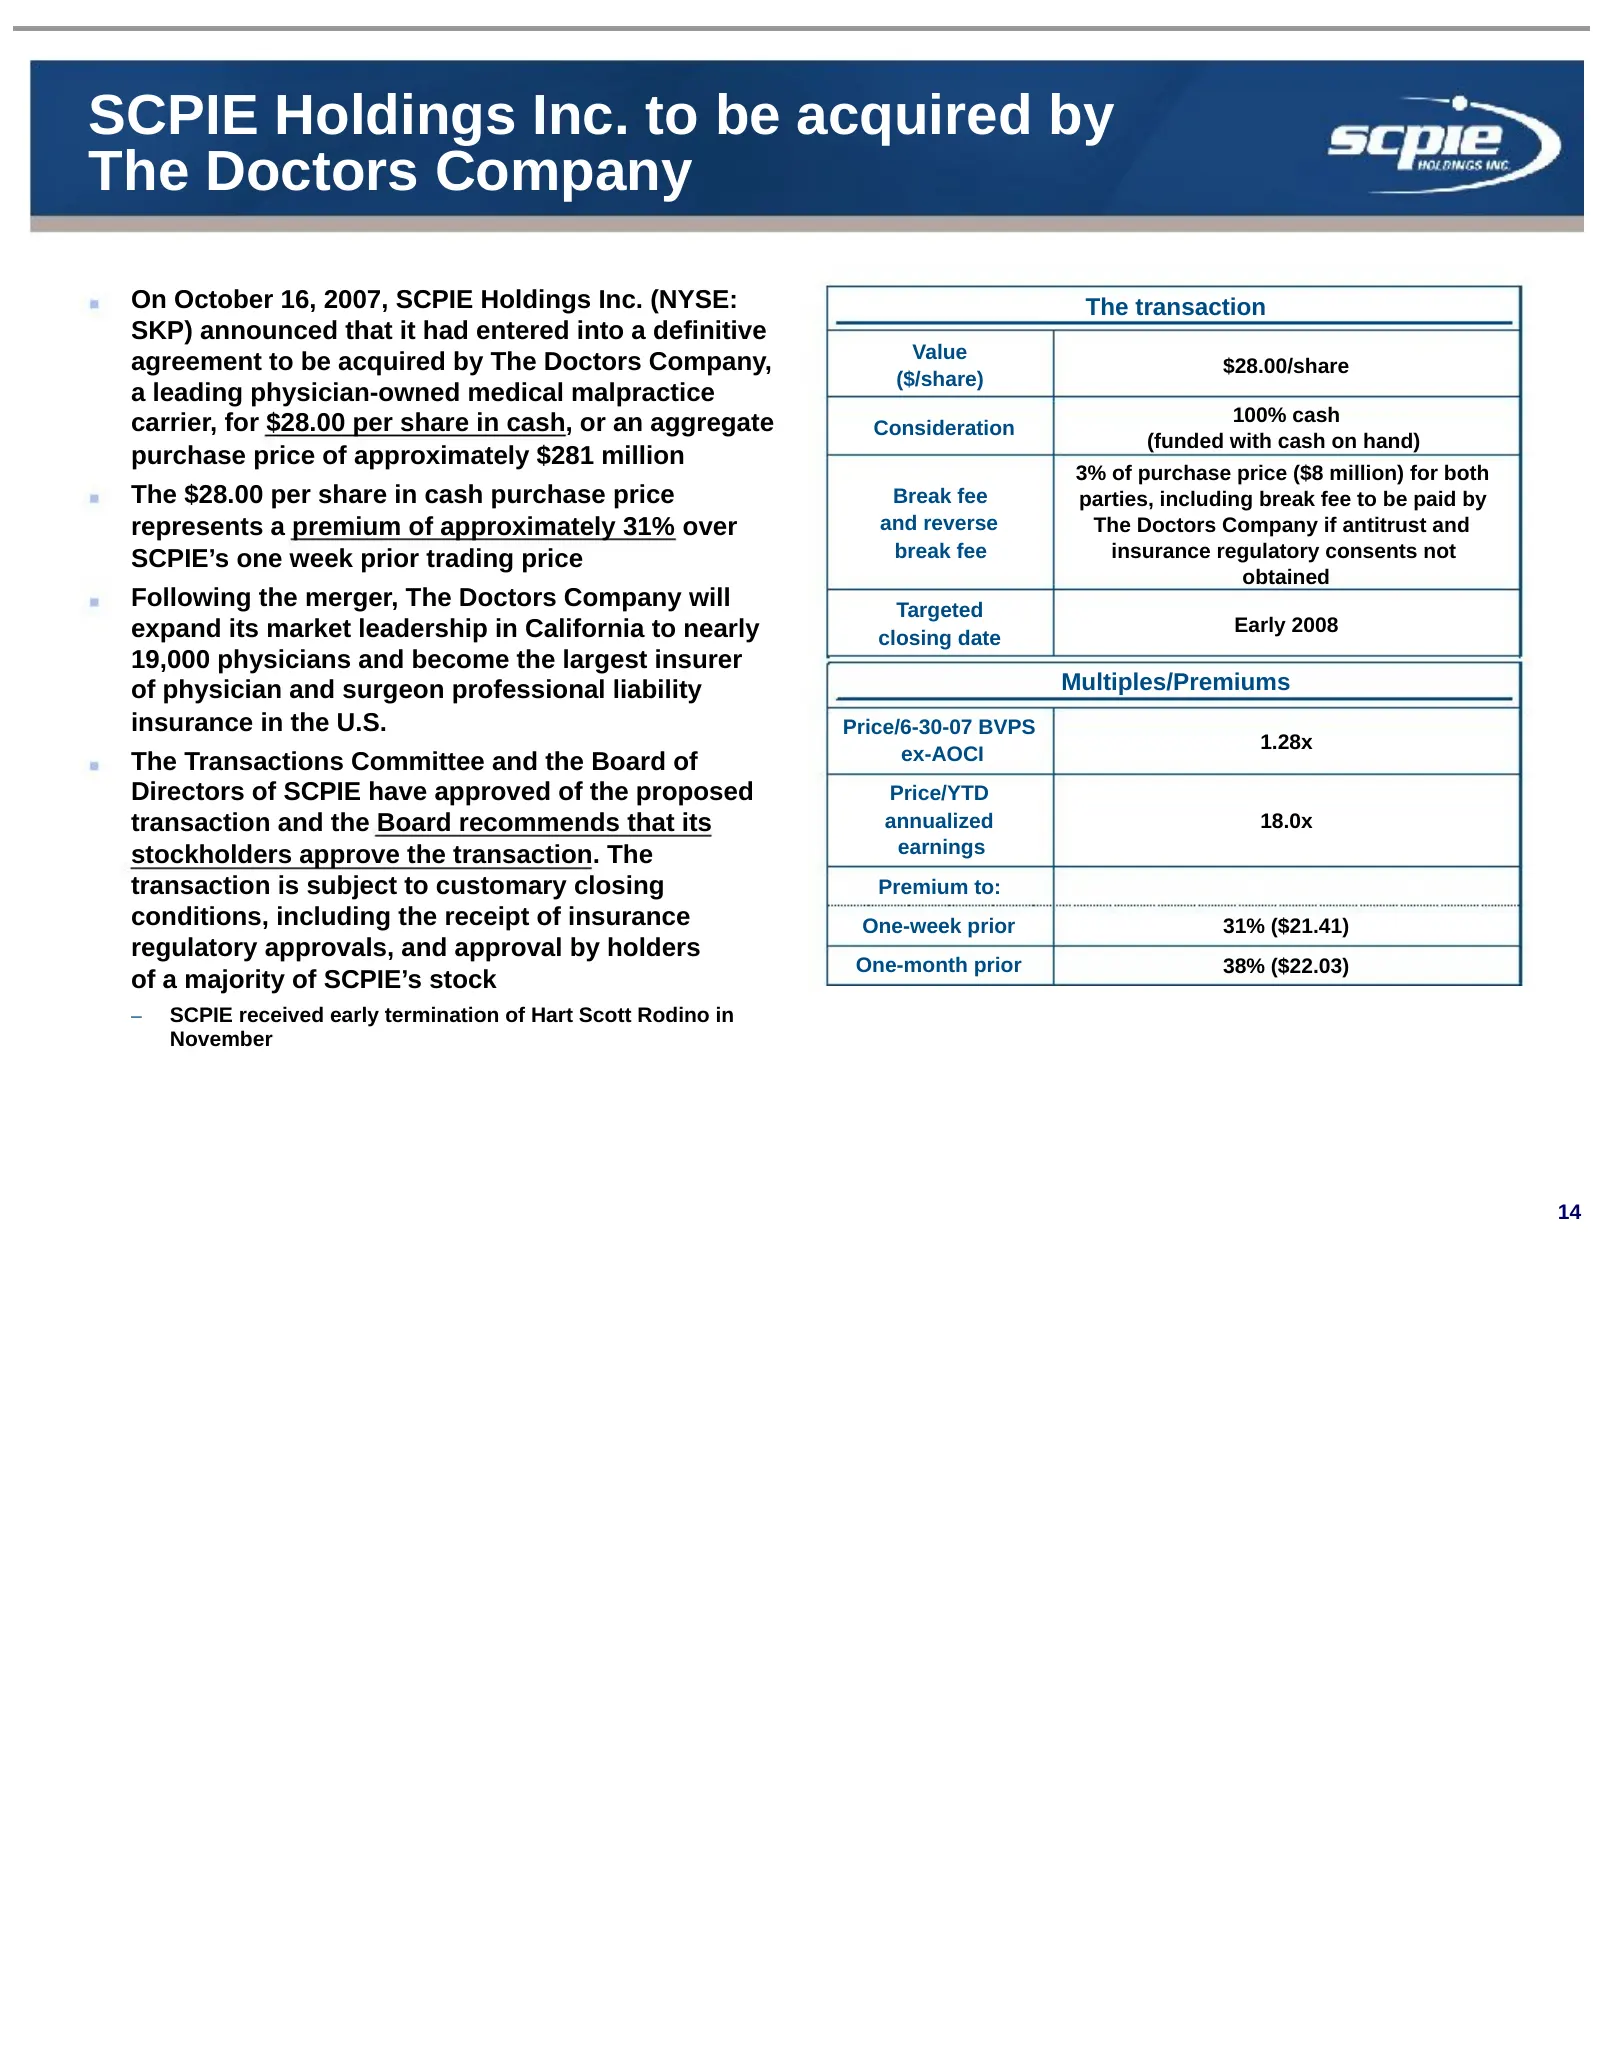
SCPIE Holdings Inc. to be acquired by The Doctors Company On October 16, 2007, SCPIE Holdings Inc. (NYSE: The transaction SKP) announced that it had entered into a definitive Value agreement to be acquired by The Doctors Company, $28.00/share ($/share) a leading physician-owned medical malpractice c
Slide 16: The Doctors Company bid is the most direct path to shareholder value maximization
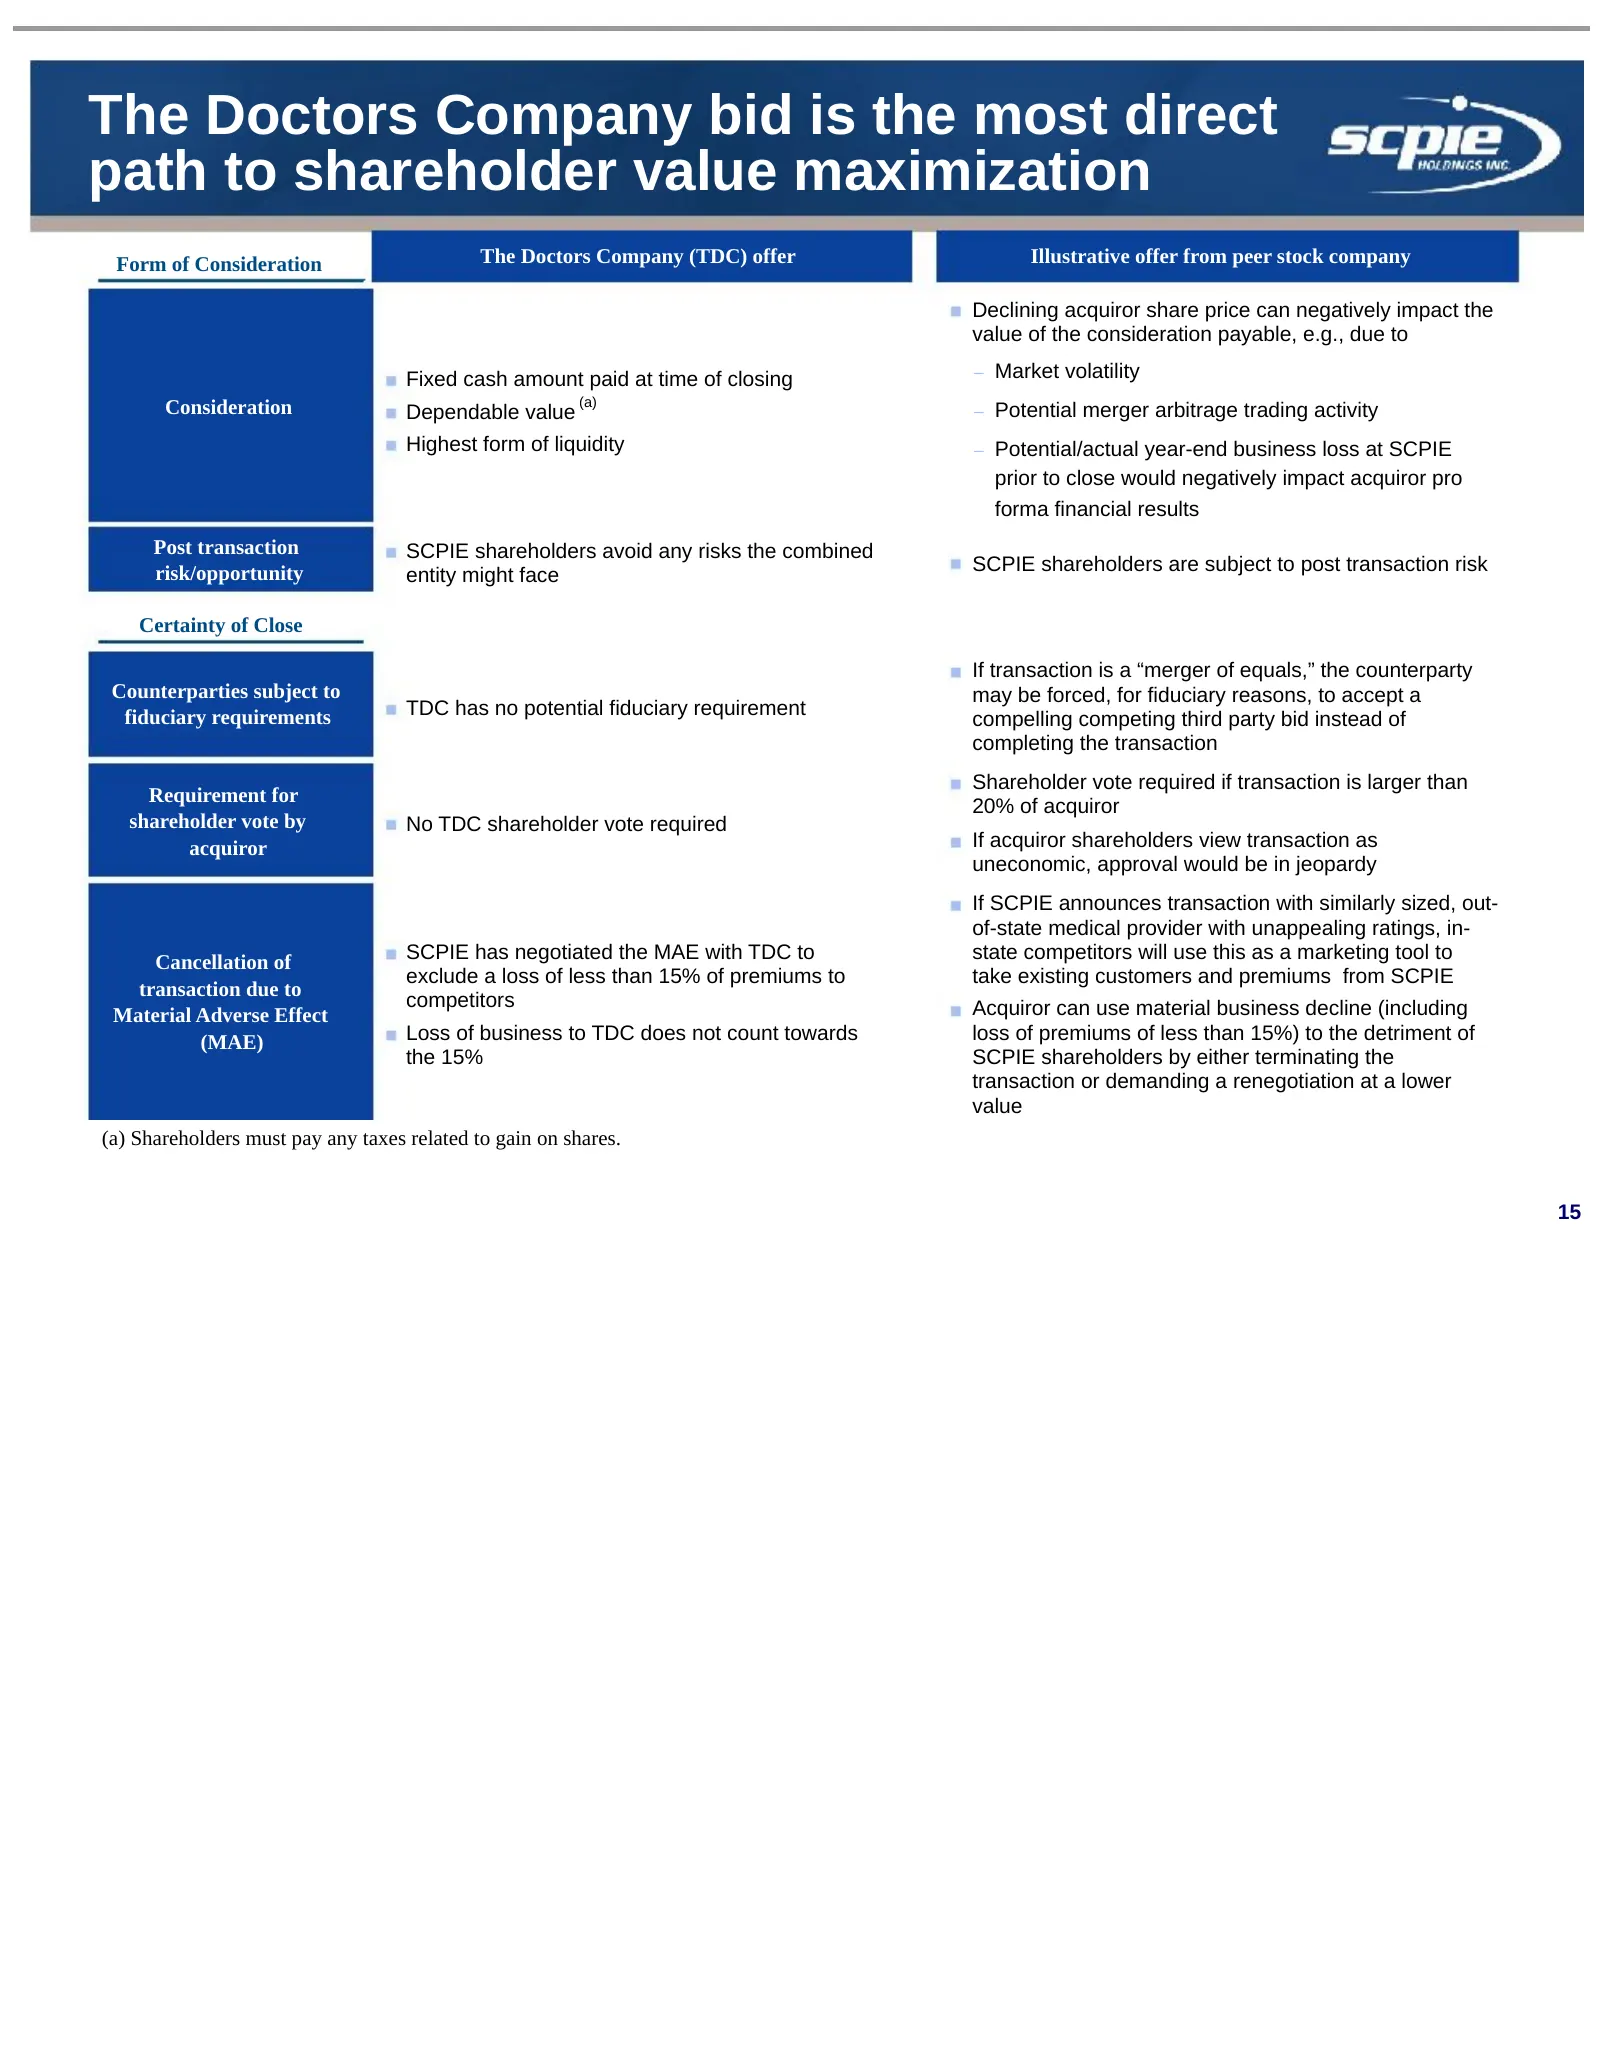
The Doctors Company bid is the most direct path to shareholder value maximization Form of Consideration The Doctors Company (TDC) offer Illustrative offer from peer stock company Declining acquiror share price can negatively impact the value of the consideration payable, e.g., due to Fixed cash amou
Slide 17: The Doctors Company bid is in line with transaction comparables
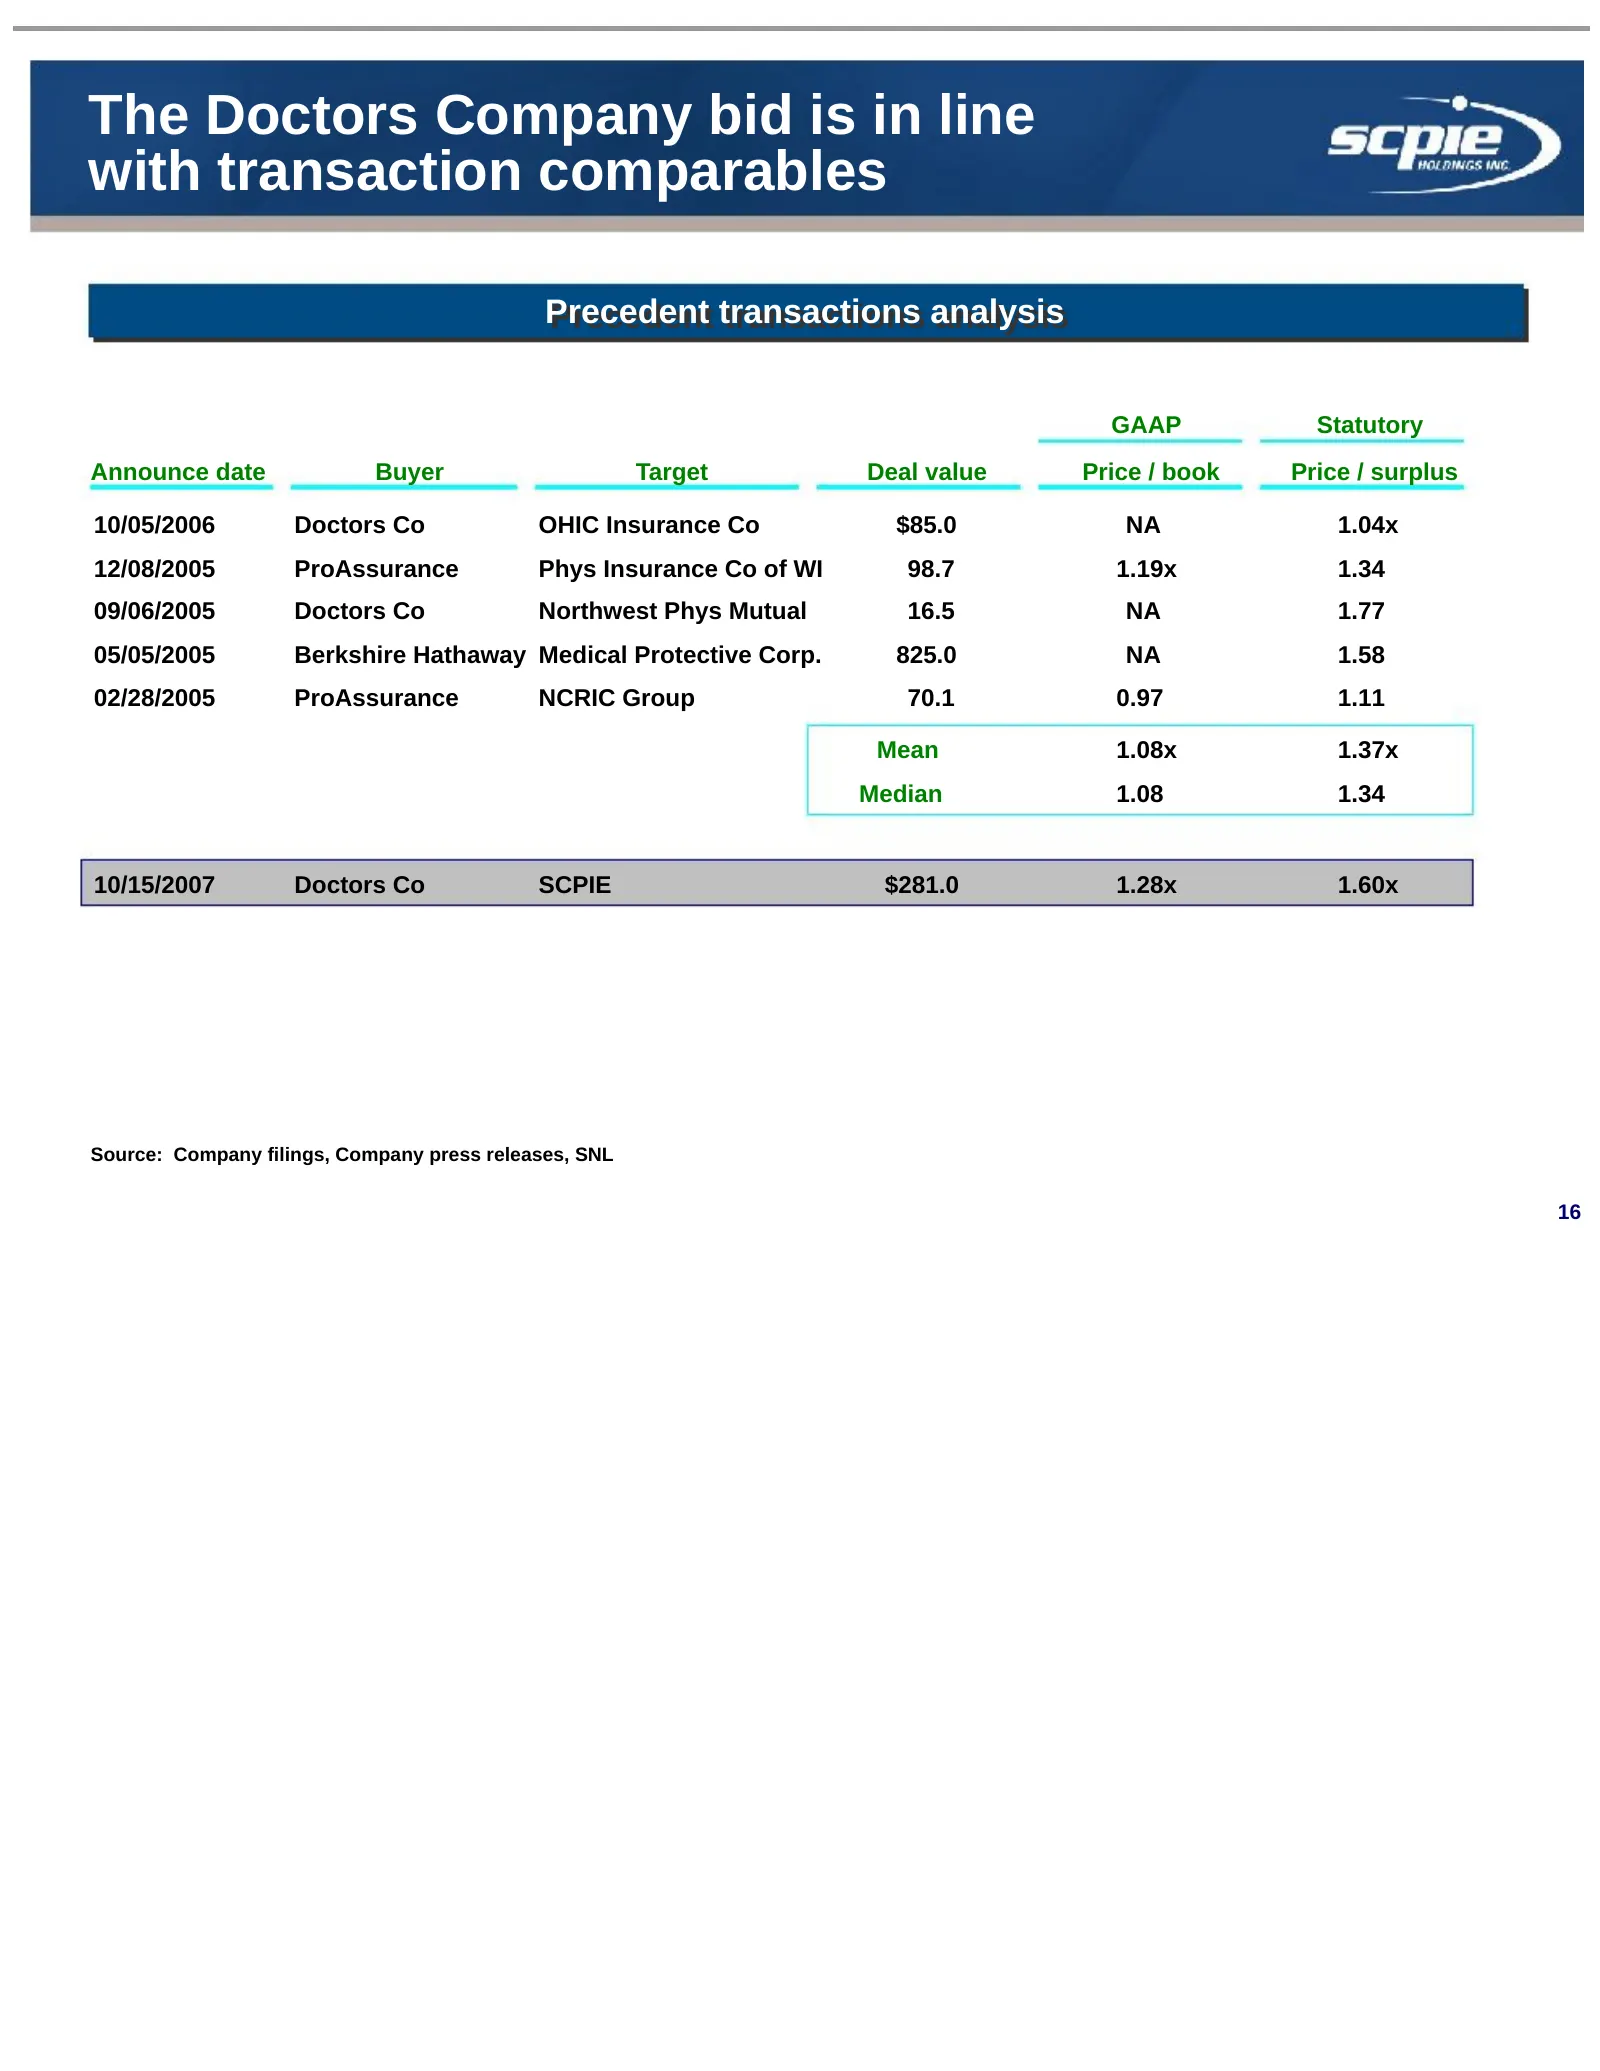
The Doctors Company bid is in line with transaction comparables Precedent Precedent transactions transactions analysis analysis GAAP Statutory Announce date Buyer Target Deal value Price / book Price / surplus 10/05/2006 Doctors Co OHIC Insurance Co $85.0 NA 1.04x 12/08/2005 ProAssurance Phys Insura
Slide 18: Conclusion
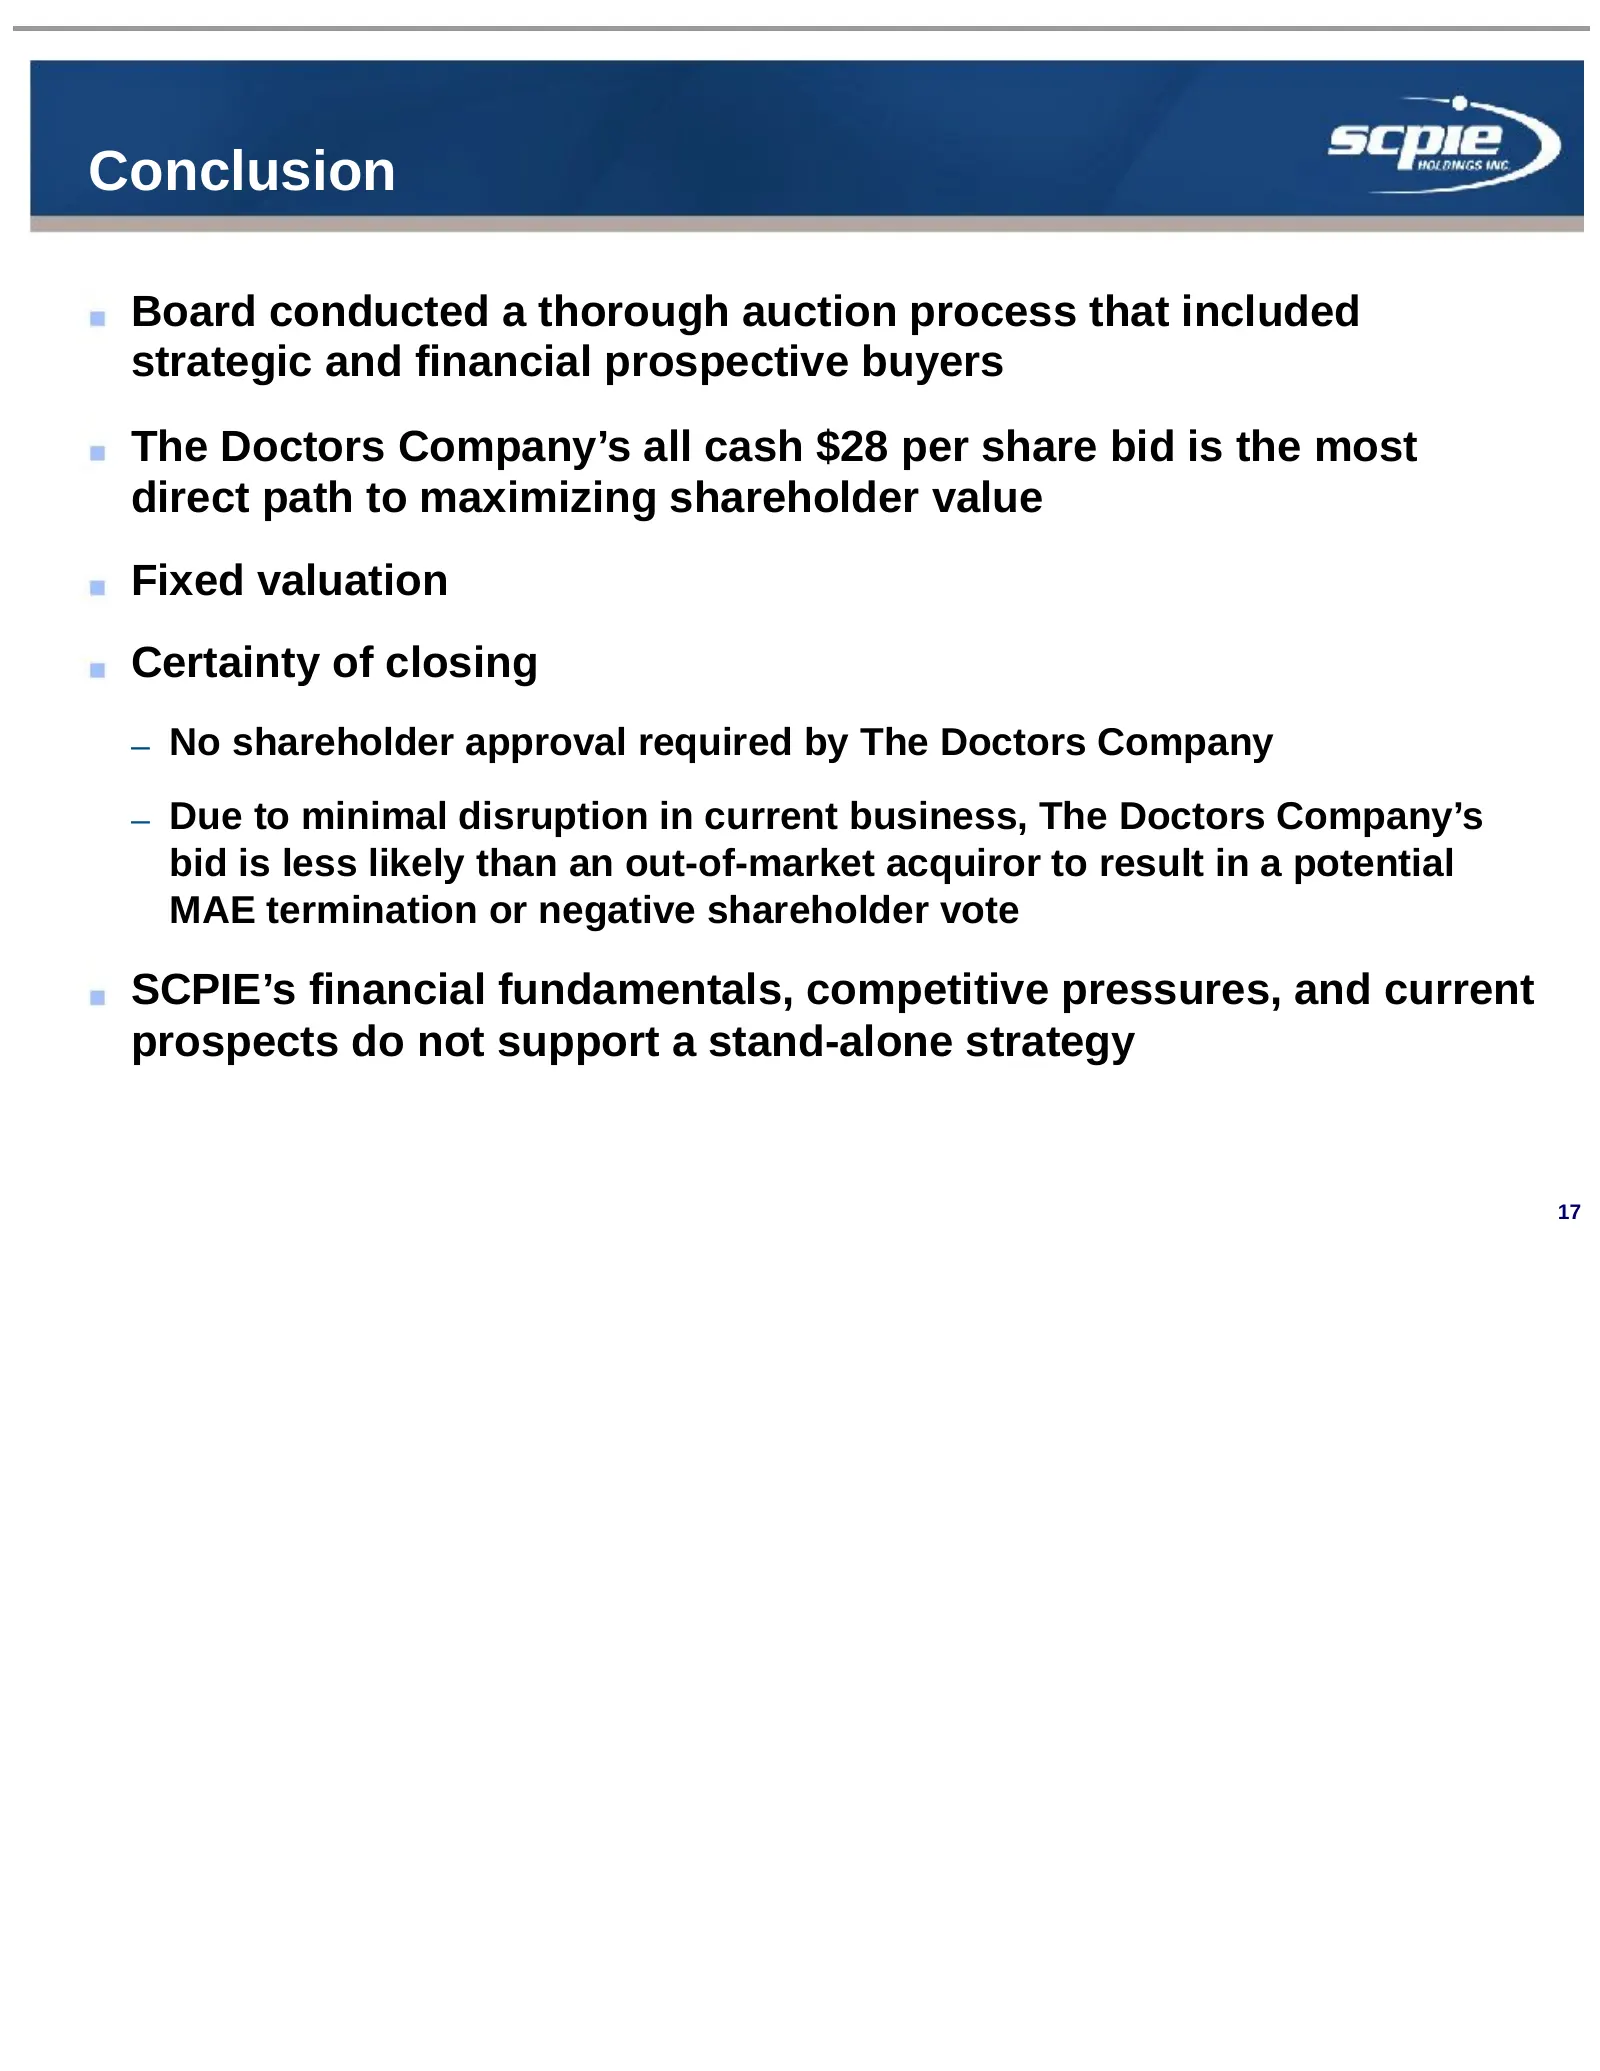
Conclusion Board conducted a thorough auction process that included strategic and financial prospective buyers The Doctors Company’s all cash $28 per share bid is the most direct path to maximizing shareholder value Fixed valuation Certainty of closing – No shareholder approval required by The Docto
Slide 19: Additional information and where to find it
Additional information and where to find it SCPIE intends to file a definitive proxy statement in connection with the proposed acquisition.The proxy statement will be mailed to SCPIE’s stockholders, who are urged to read the proxy statement and other relevant materials when they become available bec
Source: SEC EDGAR · DEFA14A filed Dec 5, 2007