SureWest Communications — Cowen and Company 20/20 TMT Conference 2008
32 slides from SureWest Communications's conference presentation, May 28, 2008
Slide 1: SureWest – Cowen and Company 20/20 TMT Conference
Sureywest Steve Oldham President and Chief Executive Officer Cowen and Company 20/20 TMT Conference New York, NY May 28, 2008
Slide 2: Safe Harbor Statement
Safe Harbor Statement Forward Looking Statements Statements made in {his presentation that are not historical facts are forward-looking statements and are made pursuant to the safe harbor provisions of the Securities Litigation Reform Act of 1995. In some cases, these forward-looking statements may
Slide 3: Triple-play communications provider serving Greater Sacramento and Kansas City
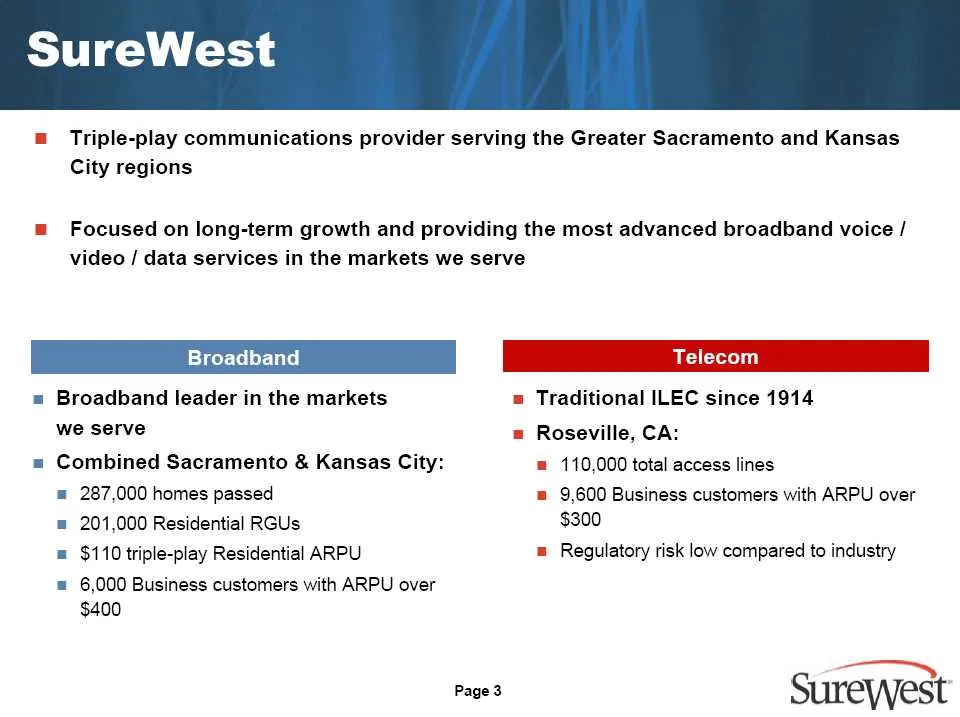
= Triple-play communications provider serving the Greater Sacramento and Kansas City regions = Focused on long-term growth and providing the most advanced broadband voice / video / data services in the markets we serve = Broadband leader in the markets = Traditional ILEC since 1914 we serve = Rosevi
Slide 4: Broadband Segment: Sacramento
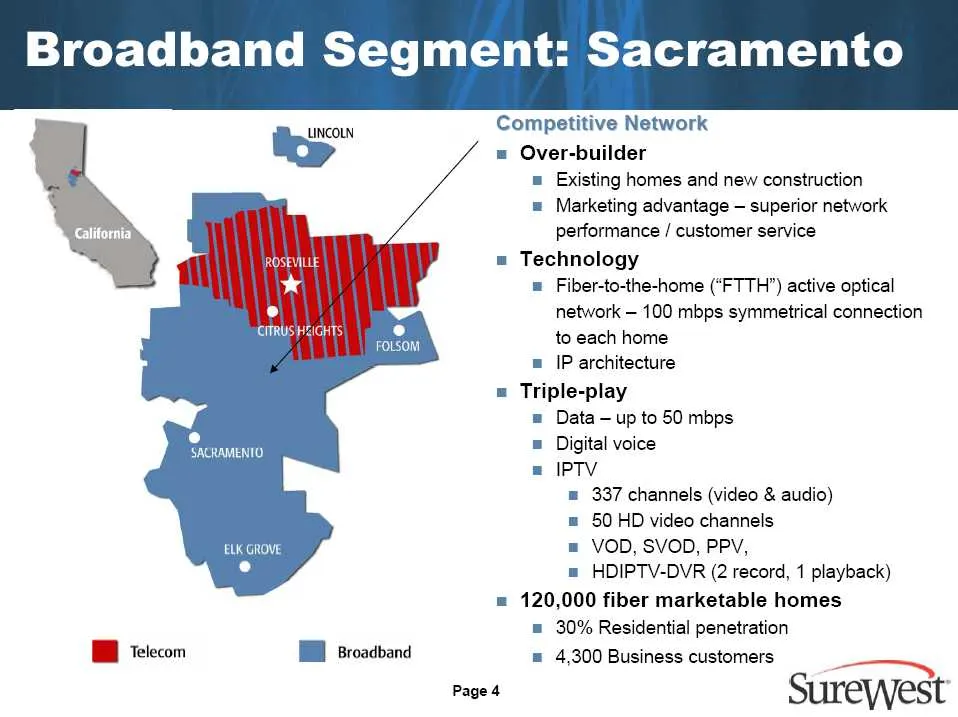
Broadband Segment: Sacramento Competitive Network = Over-builder = Existing homes and new construction = Marketing advantage — superior network performance / customer service = Technology = Fiber-to-the-home (“FTTH”) active optical network — 100 mbps symmetrical connection to each home = IP architec
Slide 5: Broadband Segment: Kansas City
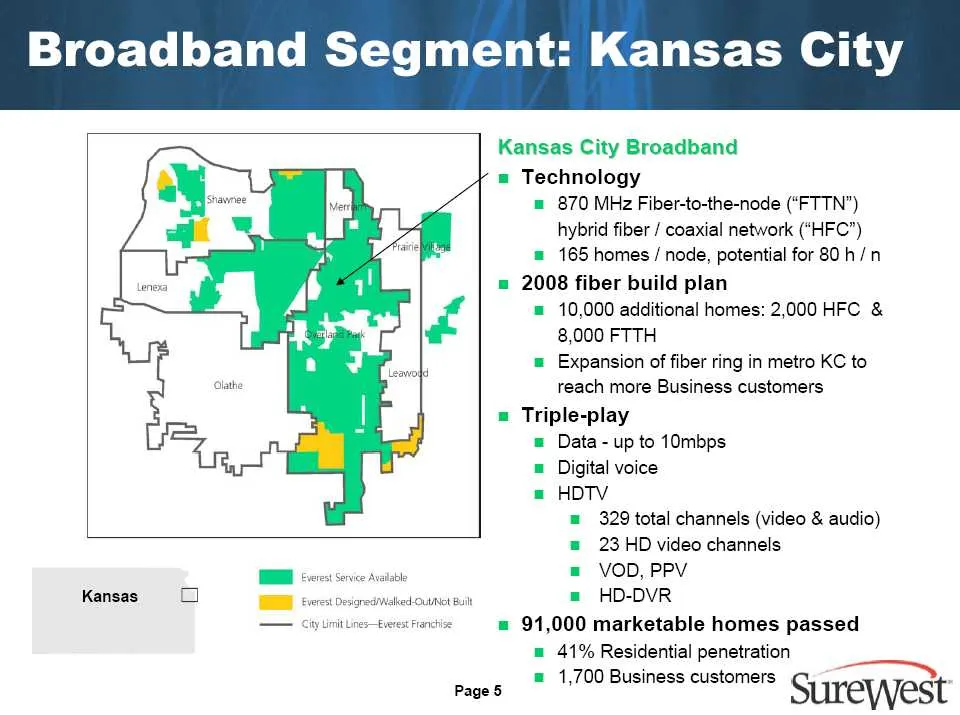
Broadband Segment: Kansas City HIRI rest Service Avaable me — City Lit Lines Everest Franchise Kansas st Designed Walked: Out Bult = 1,700 Business customers >. Page s Sureyest Kansas City Broadband = Technology m 870 MHz Fiber-to-the-node (“FTTN”) hybrid fiber / coaxial network (“HFC”) = 165 homes
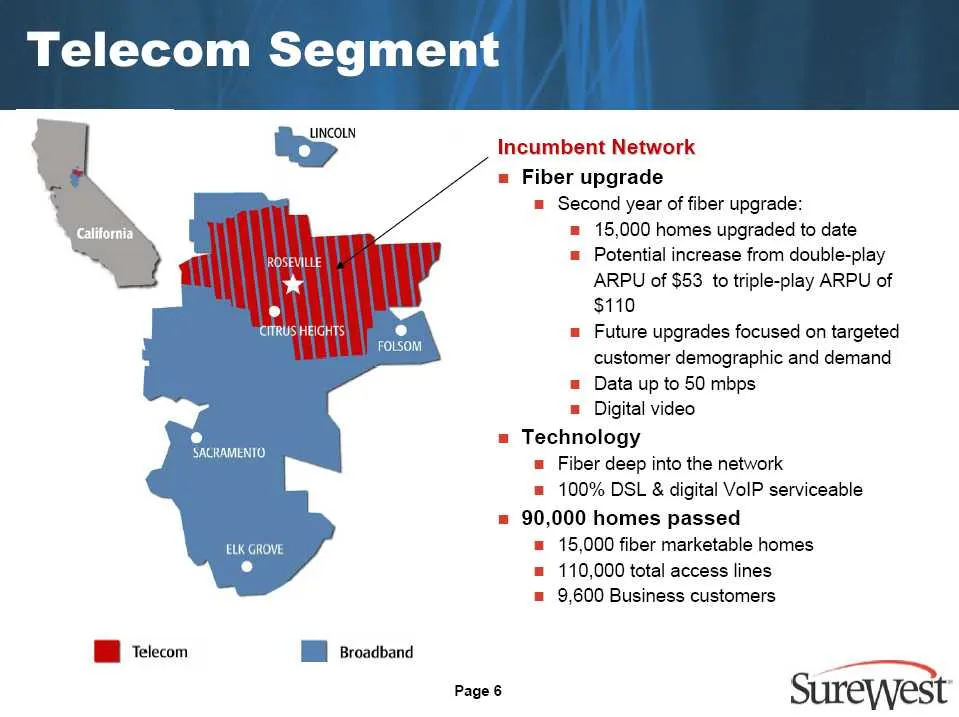
Slide 6: Telecom Segment
Telecom Segment Network iber upgrade Second year of fiber upgrade: 15,000 homes upgraded to date Potential increase from double-play ARPU of $53 to triple-play ARPU of $110 Future upgrades focused on targeted customer demographic and demand Data up to 50 mbps Digital video Technology Fiber deep into
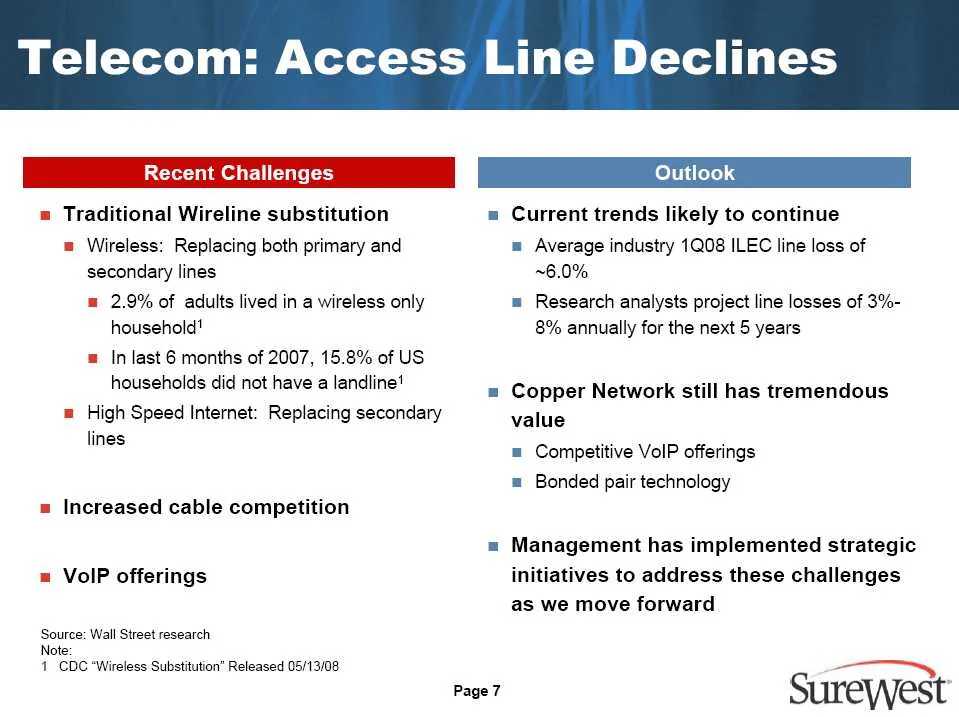
Slide 7: Telecom: Access Line Declines
Telecom: Access Line Declines Rec Challenges = Traditional Wireline substitution = Wireless: Replacing both primary and secondary lines = 2.9% of adults lived in a wireless only household! = Inlast 6 months of 2007, 15.8% of US households did not have a landline! = High Speed Internet: Replacing sec
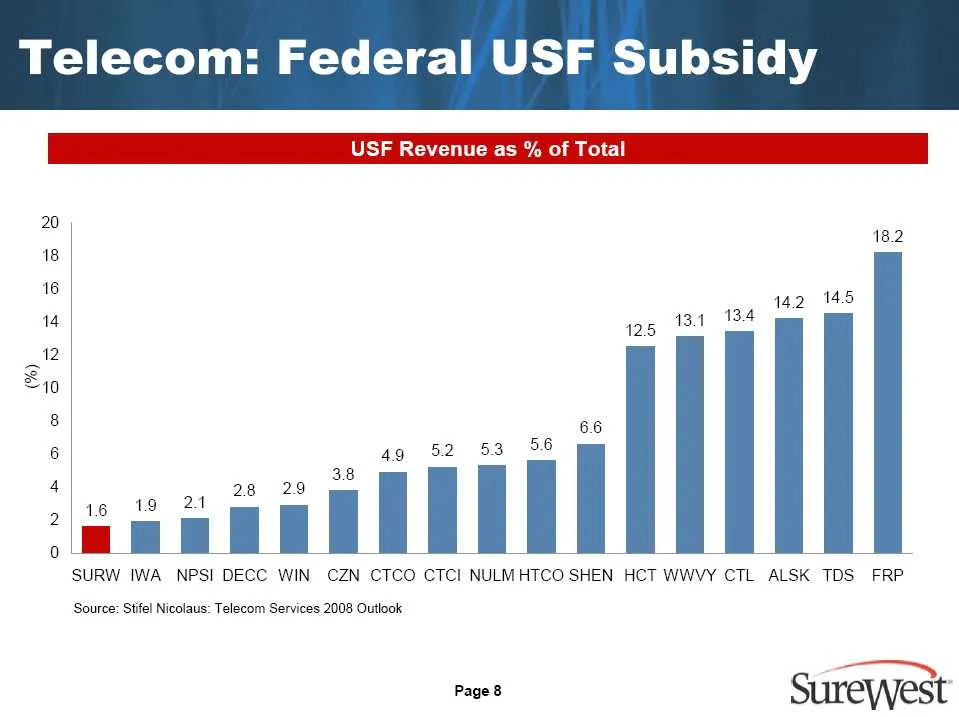
Slide 8: Telecom: Federal USF Subsidy
Telecom: Federal USF Subsidy 18.2 18 16 14.2 14 14 12 = =10 P 29 7 all [ I I I i geal J SURW IWA NPSI DECC WIN CZN CTCO CTC] NULMHTCO SHEN HCT WWVY CTL ALSK TDS FRP oN Ro Source: Stifel Nicolaus: Telecom Services 2008 Outlook Pages Surewest
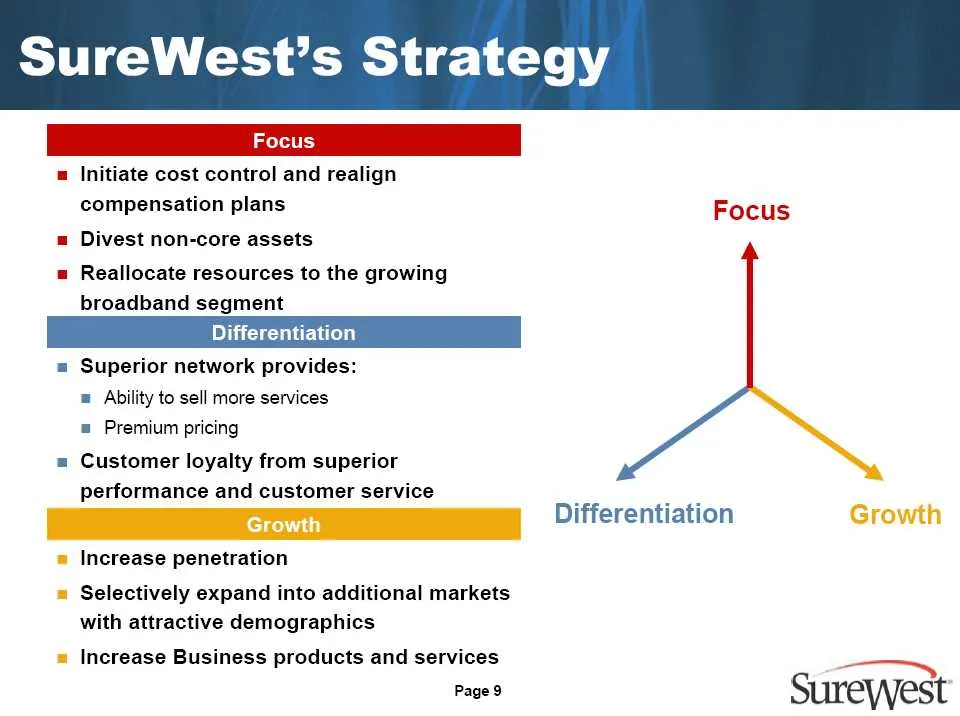
Slide 9: SureWest's Strategy
SureWest’s Strategy Focus a Initiate cost control and realign compensation plans Focus = Divest non-core assets = Reallocate resources to the growing broadband segment Differentiation = Superior network provides: = Ability to sell more services = Premium pricing = Customer loyalty from superior perf
Slide 10: SureWest's Strategy: Focus
SureWest’s Strategy Focus Differentiation Growth Page 10 Surewest
Slide 11: Focus: Cost Controls
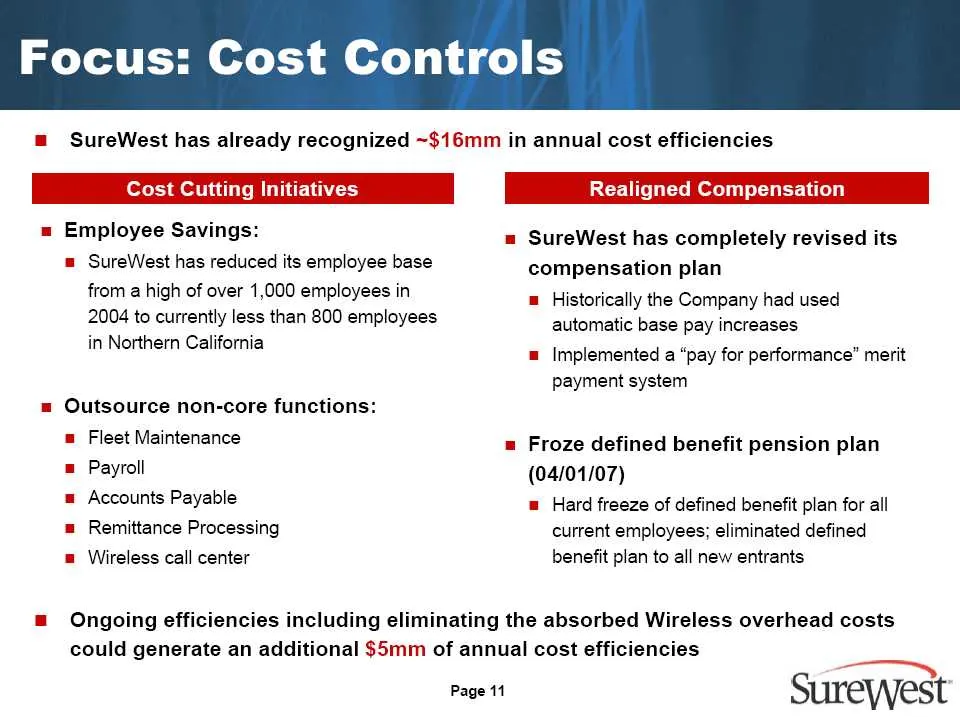
Focus: Cost Controls m= SureWest has already recognized ~$16mm in annual cost efficiencies Cost Cutting Initiatives Realigned Compensation = Employee Savings: = SureWest has completely revised its = SureWest has reduced its employee base compensation plan from a high of over 1,000 employees in = His
Slide 12: Focus: Divest Non-Core Assets
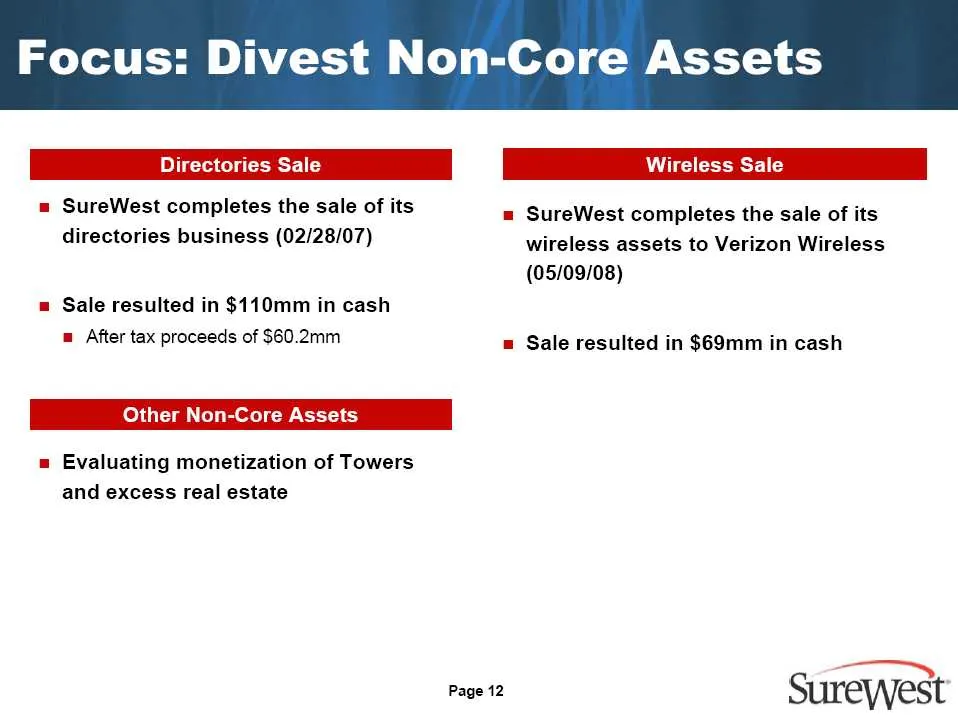
Focus: Divest Non-Core Assets Directories Sale Wireless Sale = SureWest completes the sale of its = SureWest completes the sale of its directories business (02/28/07) wireless assets to Verizon Wireless (05/09/08) = Sale resulted in $110mm in cash = After tax proceeds of $60.2mm = Sale resulted in $
Slide 13: Focus: Reallocate Resources
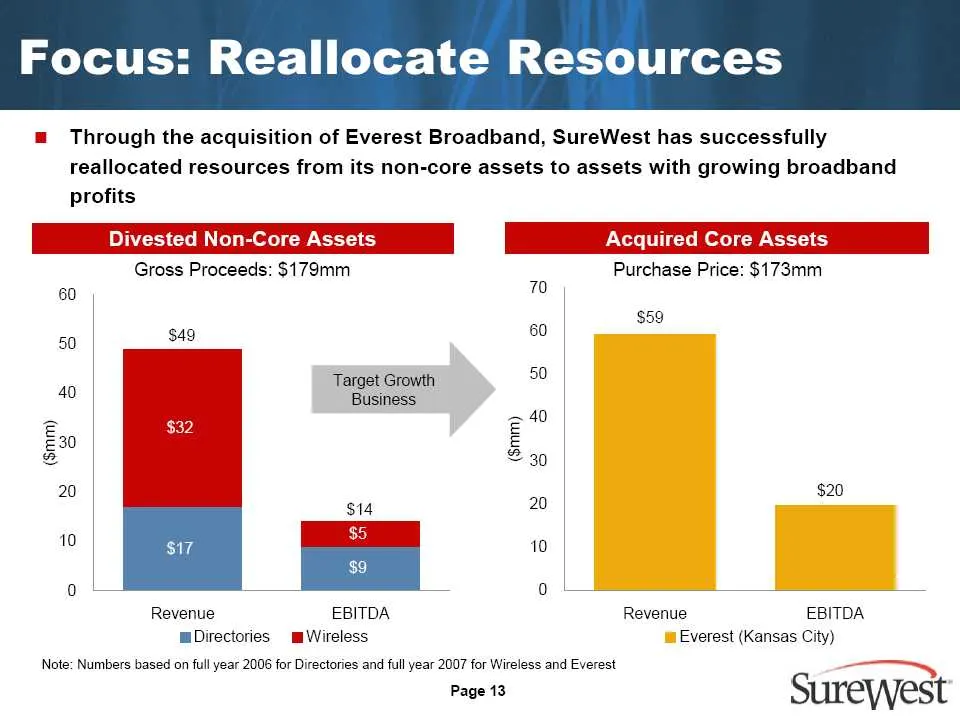
Focus: Reallocate Resources profits Gross Proceeds: $179mm Sit 10 0 J Revenue 60 50 sia Target Growth a Business E50 ba & 20 si7 EBITDA mWireless mDirectories Note: Numbers based on full year 2006 for Directories and full year 2007 for Wireless and Everest Page 13 Through the acquisition of Everest
Slide 14: Focus: Reallocate Resources
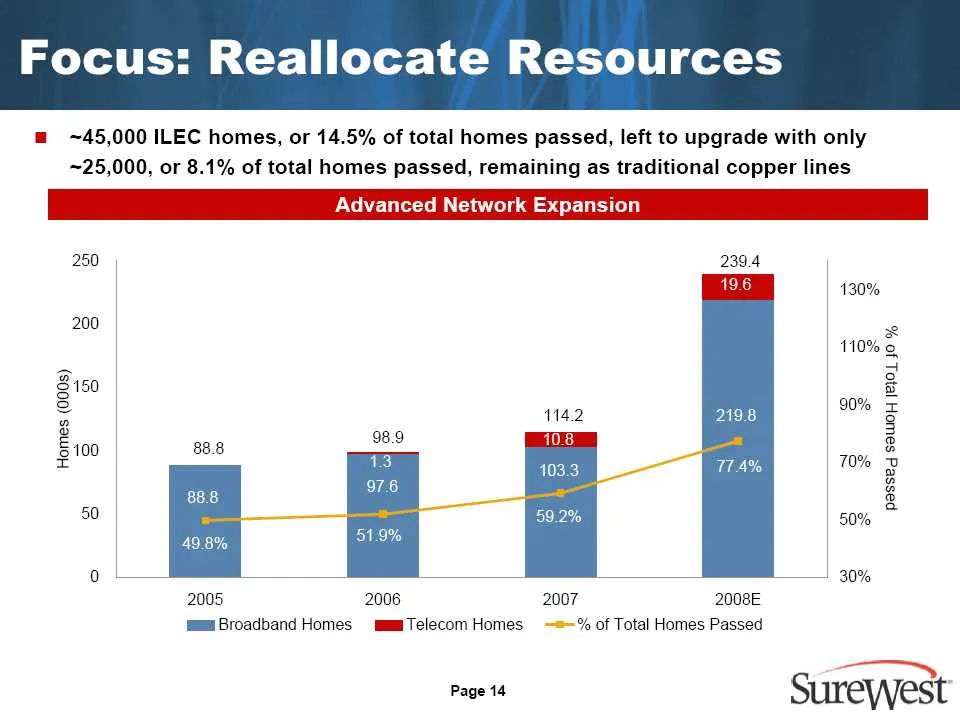
Focus: Reallocate Resources ~45,000 ILEC homes, or 14.5% of total homes passed, left to upgrade with only ~25,000, or 8.1% of total homes passed, remaining as traditional copper lines 250 239.4 goo] 130% 200 2 110% © x a 3150 8 = 2198 0% z 98.9 5100 88.8 1 70% ; = T1A% 6 88.8 us 3 50 50% none 51.9%
Slide 15: Focus: Capital Spend
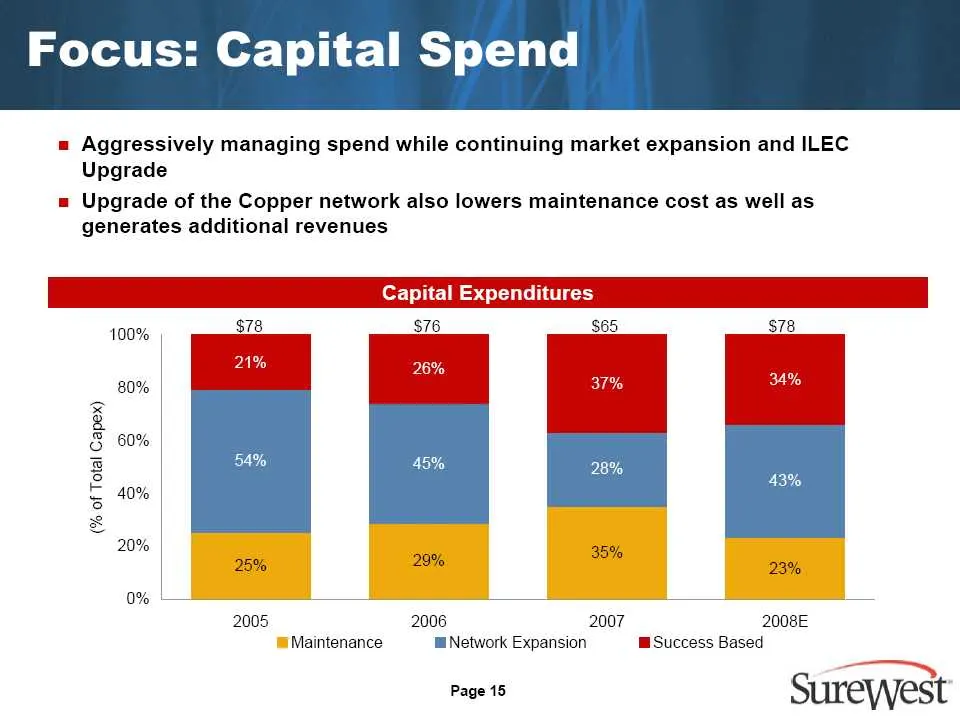
Focus: Capital Spend 7 Aggressively managing spend while continuing market expansion and ILEC Upgrade Upgrade of the Copper network also lowers maintenance cost as well as generates additional revenues 100% S78 | S76 $65 $78 80% | 37% & § 60% g 3 40% 3 x 20% So, 35% 25% 29% 23% 0% \— E 2005 2006 200
Slide 16: SureWest's Strategy: Differentiation
SureWest’s Strategy Focus Differentiation °c Page 16 Surewest
Slide 17: Differentiation: Superior Network
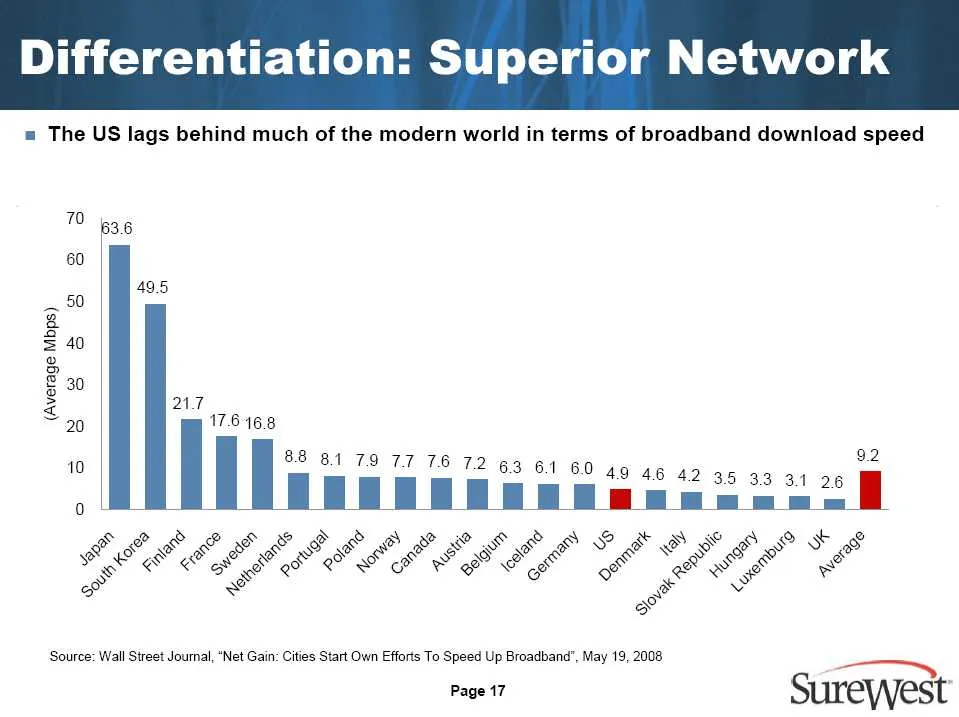
Differentiation: Superior Network = The US lags behind much of the modern world in terms of broadband download speed (Average Mbps) Source: Wall Street Journal, “Net Gain: Cities Start Own Efforts To Speed Up Broadband”, May 19, 2008 Page 17 Sureyest
Slide 18: Differentiation: Superior Network
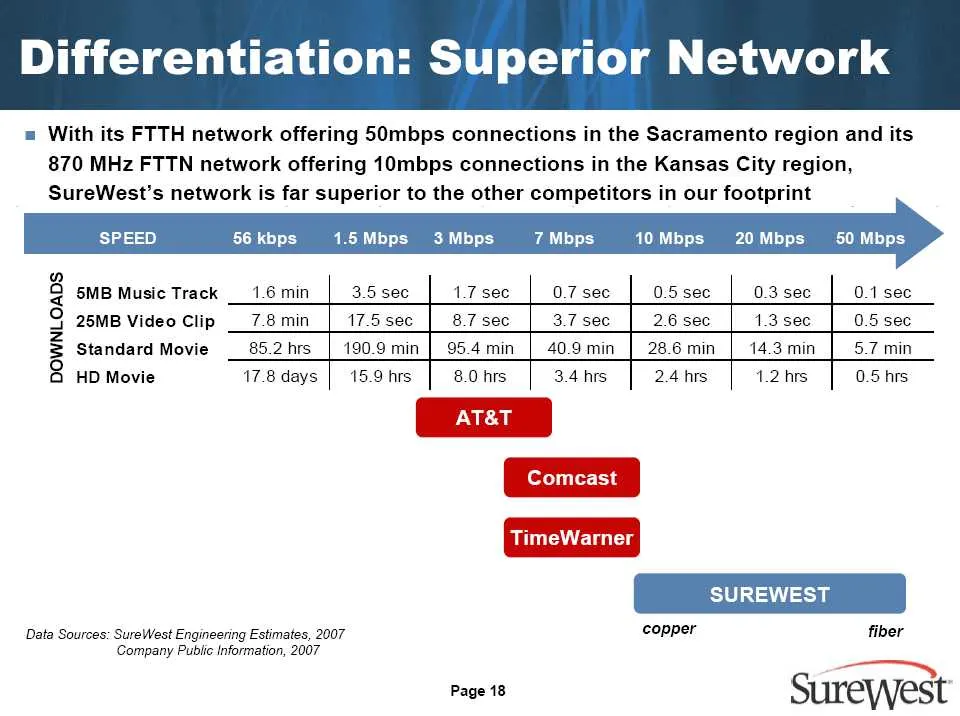
Differentiation: Superior Network = With its FTTH network offering 50mbps connections in the Sacramento region and its 870 MHz FTTN network offering 10mbps connections in the Kansas City region, SureWest’s network is far superior to the other competitors in our footprint 56kbps 1.5Mbps 3Mbps 7Mbps 1
Slide 19: Differentiation: Increasing Services
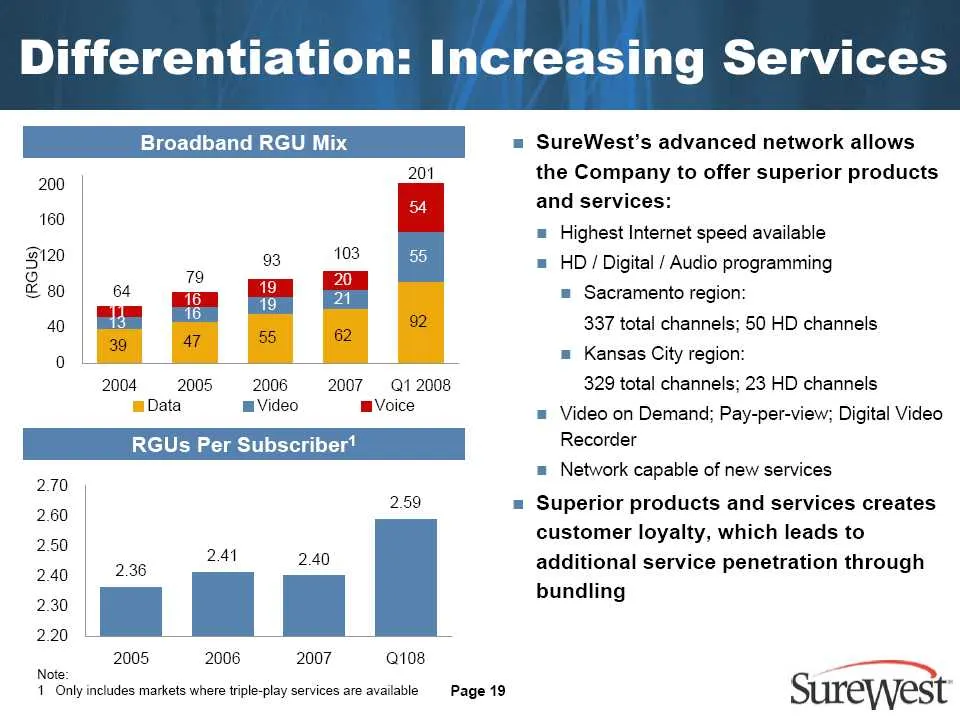
Differentiation: Increasing Services = SureWest’s advanced network allows the Company to offer superior products 200 ; and services: te0 = Highest Internet speed available gi = HD/ Digital / Audio programming © 80 = Sacramento region: 40 337 total channels; 50 HD channels. oF _ im | | | a = Kansas C
Slide 20: Differentiation: Premium Pricing
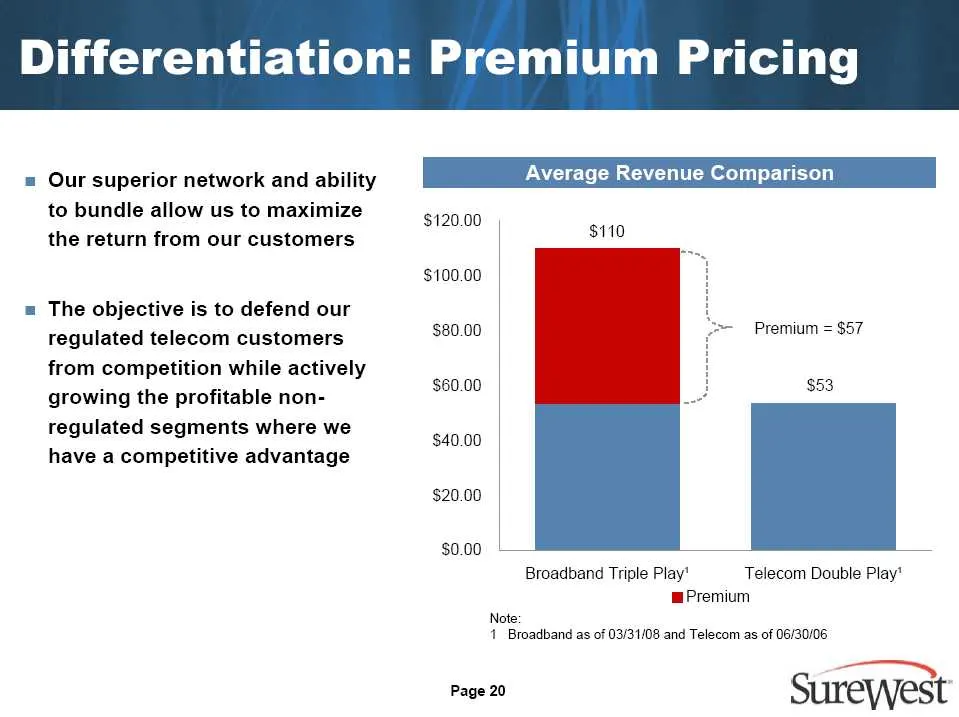
Differentiation: Premium Pricing = Our superior network and ability to bundle allow us to maximize the return from our customers = The objective is to defend our regulated telecom customers from competition while actively growing the profitable non- regulated segments where we have a competitive adv
Slide 21: Differentiation: Double Benefit
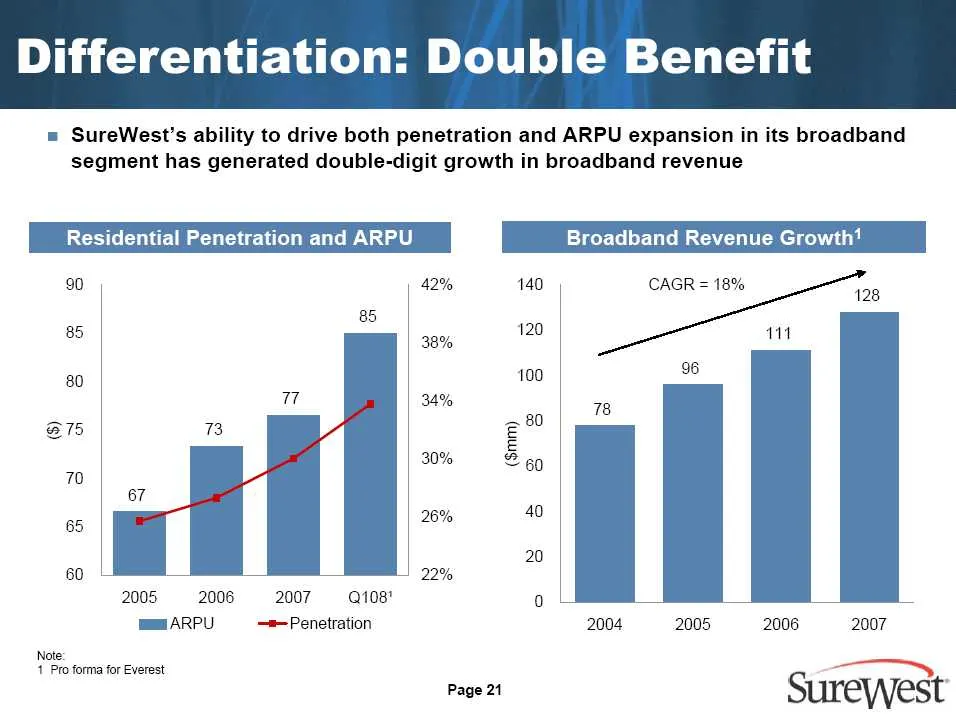
Differentiation: Double Benefit = SureWest’s ability to drive both penetration and ARPU expansion in its broadband segment has generated double-digit growth in broadband revenue Residential tration and ARPU Broadband Revenue wth? CAGR = 18% 90 42% 140 128 » 120 » 38% 96 80 100 7 34% 0 78 S15 3 VY =
Slide 22: SureWest's Strategy: Growth
SureWest’s Strategy Focus Differentiation G rowth Page 22 Surewest
Slide 23: Growth: Increased Penetration
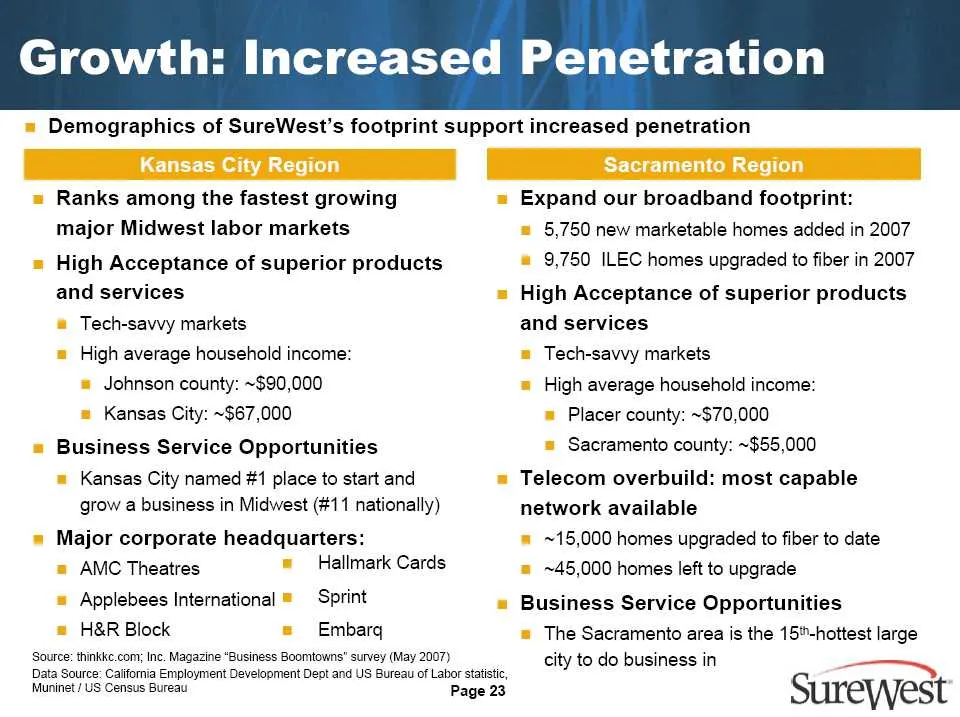
Growth: Increased Penetration = Demographics of SureWest’s footprint support increased penetration Kansas City Region Sacramento Region = Ranks among the fastest growing major Midwest labor markets = High Acceptance of superior products and services = Tech-savvy markets = High average household inco
Slide 24: Growth: Increased Penetration
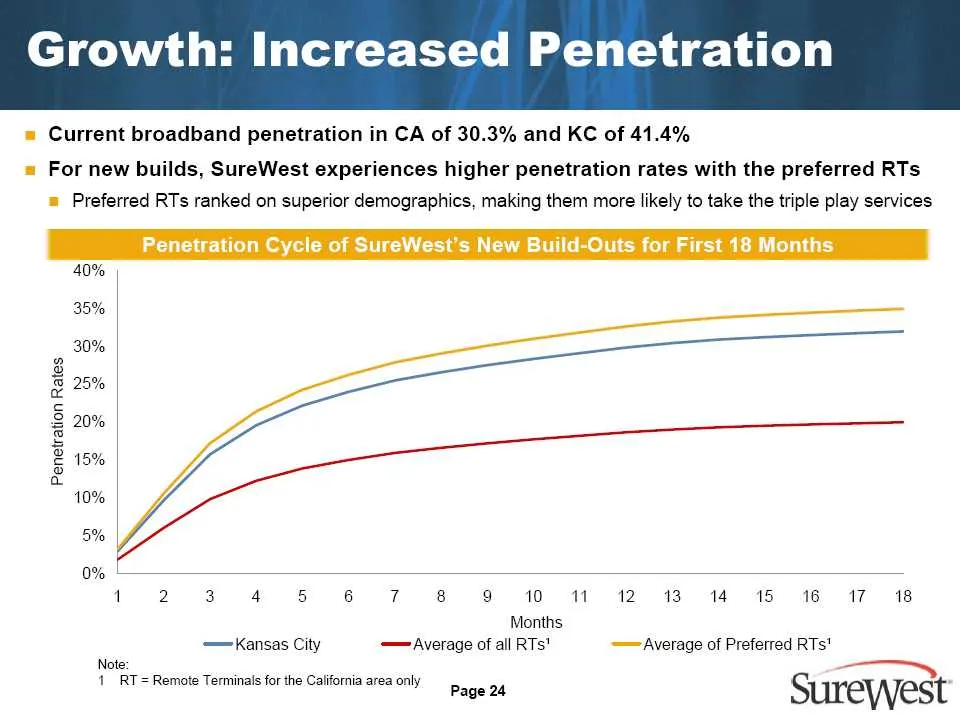
Growth: Increased Penetration = Current broadband penetration in CA of 30.3% and KC of 41.4% = For new builds, SureWest experiences higher penetration rates with the preferred RTs = Preferred RTs ranked on superior demographics, making them more likely to take the triple play services Penetration Cy
Slide 25: Growth: Market Expansion
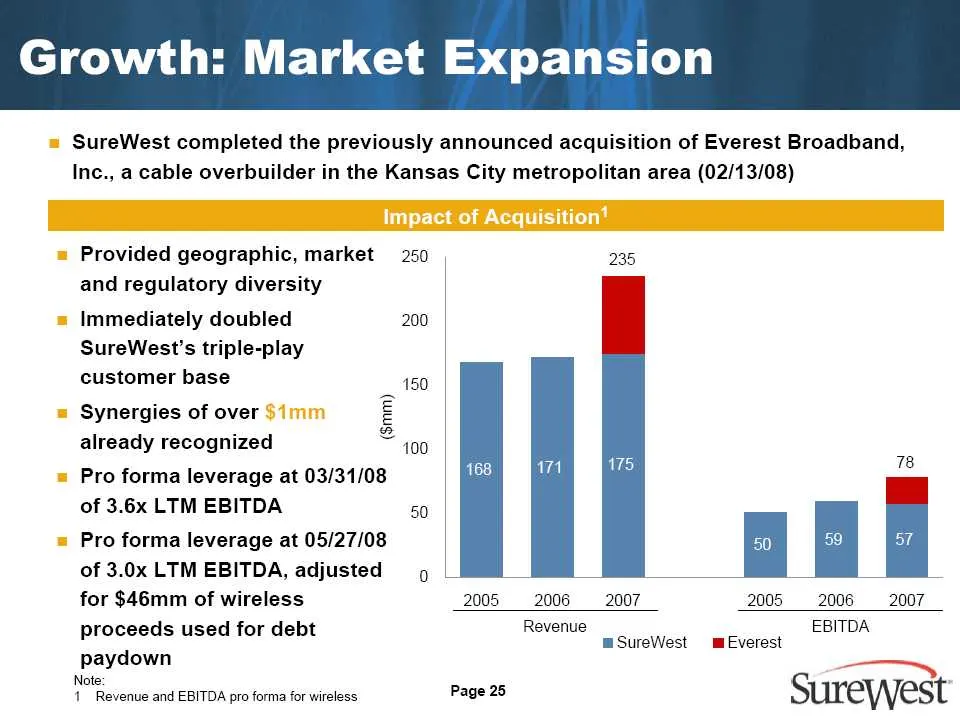
Growth: Market Expansion = SureWest completed the previously announced acquisition of Everest Broadband, Inc., a cable overbuilder in the Kansas City metropolitan area (02/13/08) Impact of Acquisition’ = Provided geographic, market 250 and regulatory diversity = Immediately doubled 200 SureWest’s tr
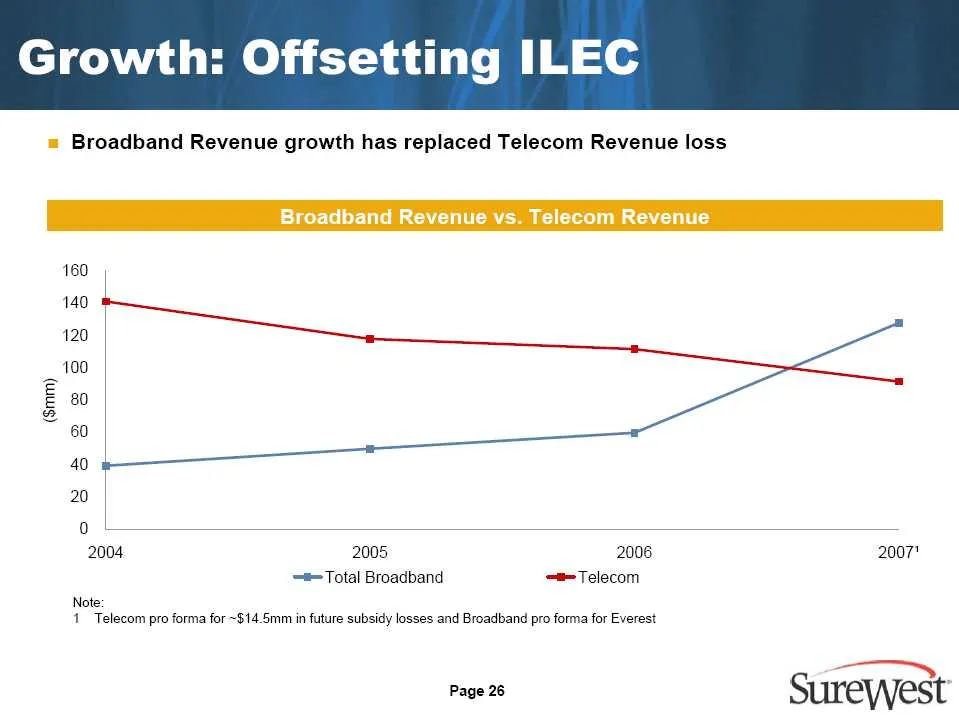
Slide 26: Growth: Offsetting ILEC
Growth: Offsetting ILEC = Broadband Revenue growth has replaced Telecom Revenue loss Broadband Revenue vs. Telecom Revenue 160 140 120 2004 2005 2006 2007" =—®Total Broadband —™Telecom Note: 1 Telecom pro forma for ~$14.5mm in future subsidy losses and Broadband pro forma for Everest a Page 28 Surew
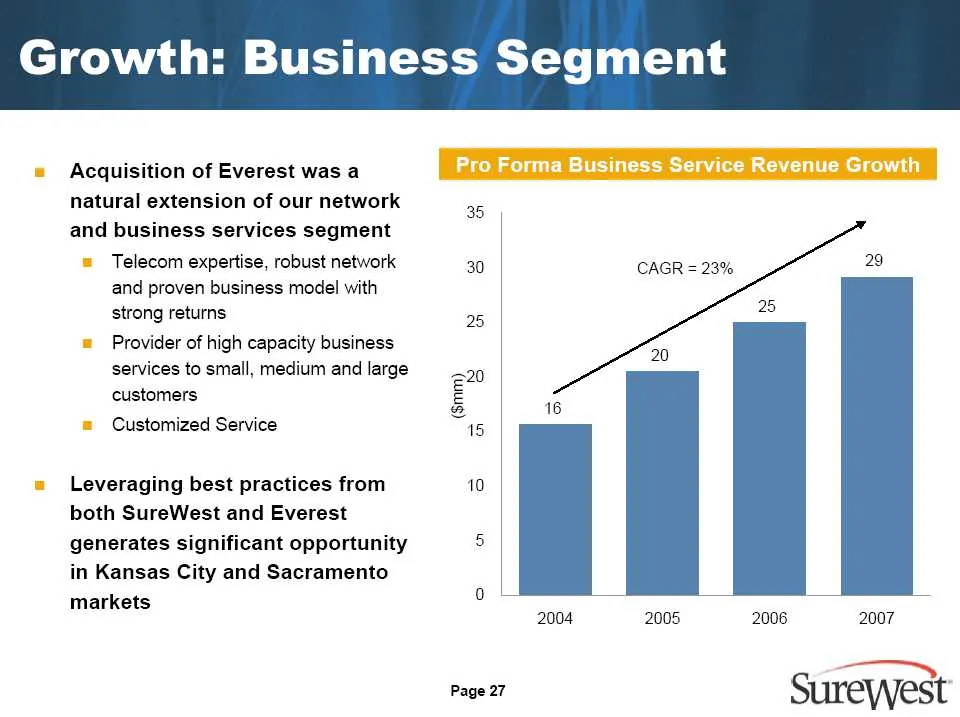
Slide 27: Growth: Business Segment
Growth: Business Segment Acquisition of Everest was a natural extension of our network and business services segment Telecom expertise, robust network 30 CAGR = 23% 29 and proven business model with strong returns Provider of high capacity business services to small, medium and large 20 customers E
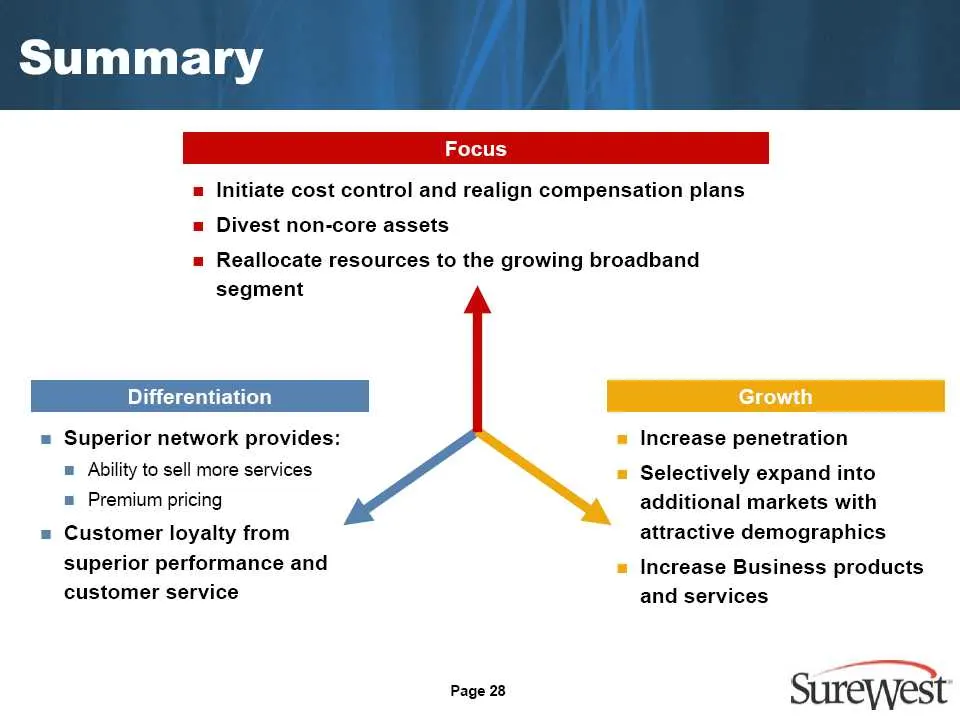
Slide 28: Summary
Summary Focus a Initiate cost control and realign compensation plans = Divest non-core assets = Reallocate resources to the growing broadband segment Differentiation = Superior network provides: ® Ability to sell more services = Premium pricing = Customer loyalty from superior performance and custom
Slide 29: Q&A
Q&A Page 29 Sureyest
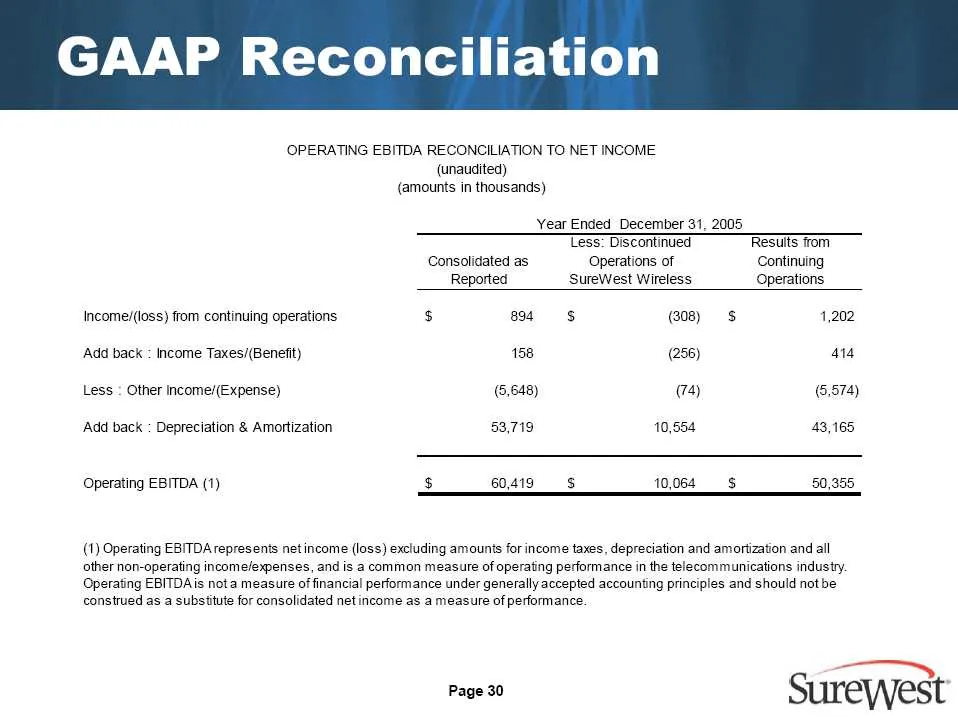
Slide 30: GAAP Reconciliation
GAAP Reconciliation OPERATING EBITDA RECONCILIATION TO NET INCOME (unaudited) {amounts in thousands) Year Ended December 31, 2005 Tess: Discontinued Resuits from Consolidated as Operations of Continuing Reported ‘SureWest Wireless Operations Income/(loss) from continuing operations $ a4 S (308) 1,20
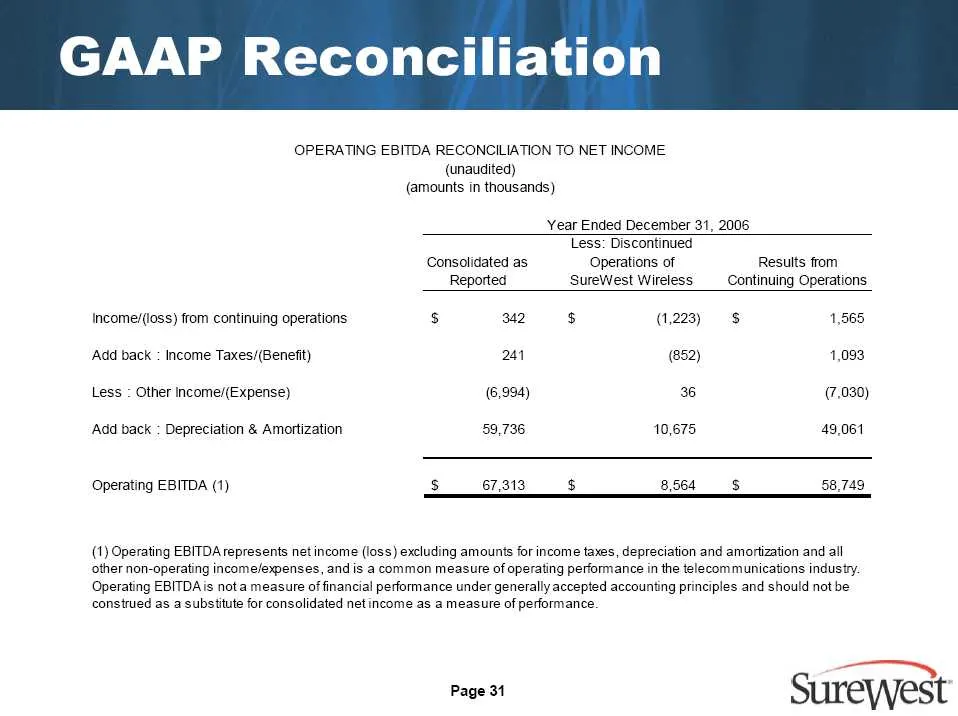
Slide 31: GAAP Reconciliation
GAAP Reconciliation OPERATING EBITDA RECONCILIATION TO NET INCOME (unaudited) (amounts in thousands) Year Ended December 31, 2006 Less: Discontinued Consolidated as Operations of Results from Reported SureWest Wireless Continuing Operations Income/(loss) from continuing operations $ 342 $ (1,223) $
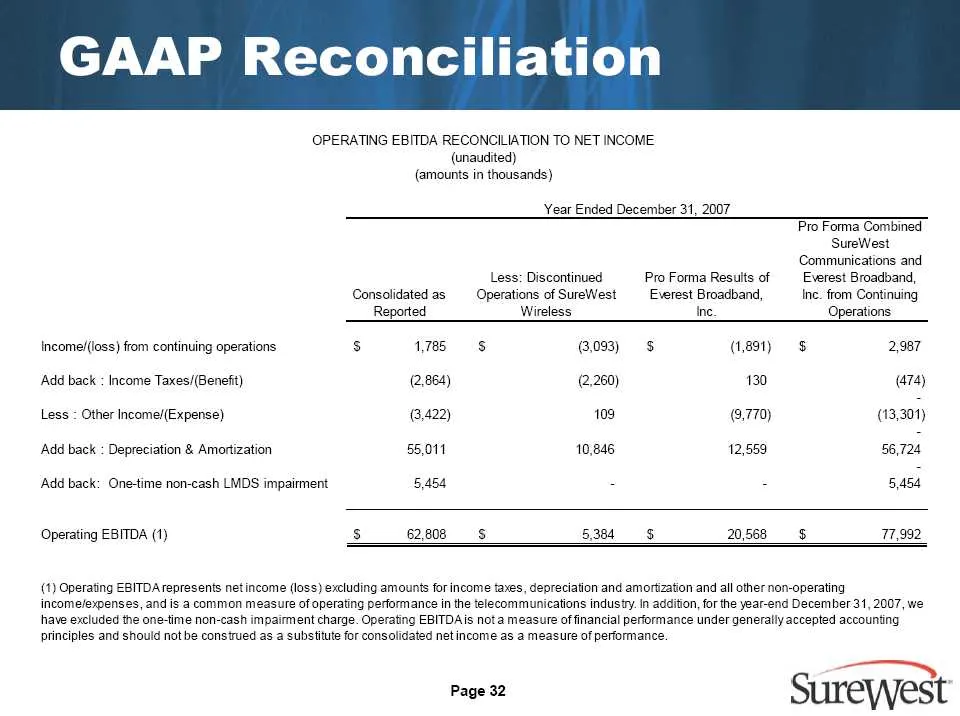
Slide 32: GAAP Reconciliation
GAAP Reconciliation OPERATING EBITDA RECONCILIATION TO NET INCOME (unaudited) (amounts in thousands) ‘Year Ended December 31, 2007 Pro Forma Combined SureWest Communications and Less: Discontinued Pro Forma Results of Everest Broadband, Consolidated as Operations of SureWest Everest Broadband, _ ine
Source: SEC EDGAR · 8-K filed May 28, 2008