Goodrich — UBS Aerospace and Defense Boston Investor Day 2008
30 slides from Goodrich's conference presentation, May 14, 2008
Slide 1: UBS Aerospace and Defense Boston Investor Day May 14, 2008
UBS Aerospace and Defense Boston Investor Day May 14, 2008
Slide 2: Forward Looking Statements
Certain statements made in this presentation are forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the Company's future plans, objectives and expected performance. The Company cautions readers that any such forward- looking statements are
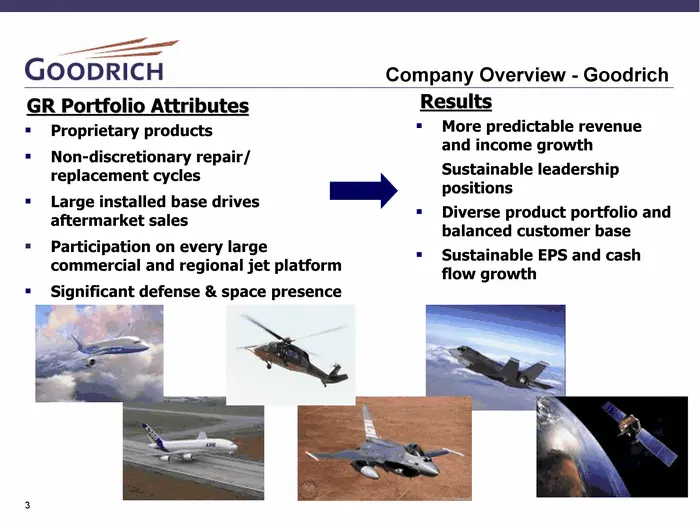
Slide 3: Company Overview - Goodrich
Company Overview - Goodrich GR Portfolio Attributes Proprietary products Non-discretionary repair/ replacement cycles Large installed base drives aftermarket sales Participation on every large commercial and regional jet platform Significant defense & space presence Results More predictable revenue
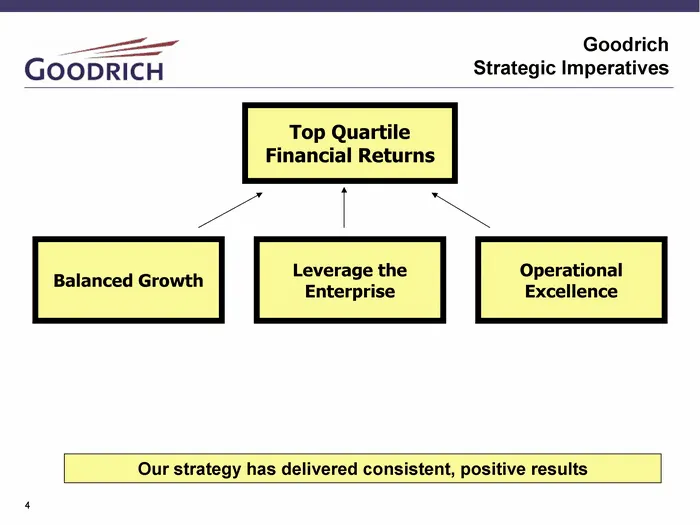
Slide 4: Conclusion: Goodrich Strategic Imperatives
Conclusion Top Quartile Financial Returns Operational Excellence Leverage the Enterprise Balanced Growth Goodrich Strategic Imperatives Our strategy has delivered consistent, positive results
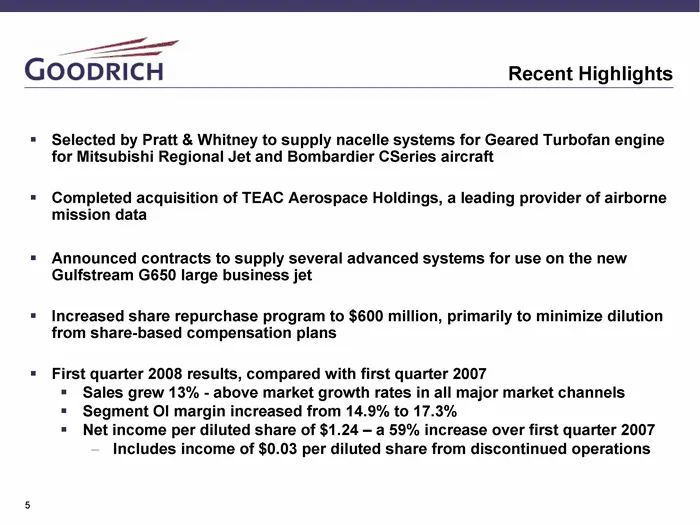
Slide 5: Recent Highlights
Recent Highlights Selected by Pratt & Whitney to supply nacelle systems for Geared Turbofan engine for Mitsubishi Regional Jet and Bombardier CSeries aircraft Completed acquisition of TEAC Aerospace Holdings, a leading provider of airborne mission data Announced contracts to supply several advanced
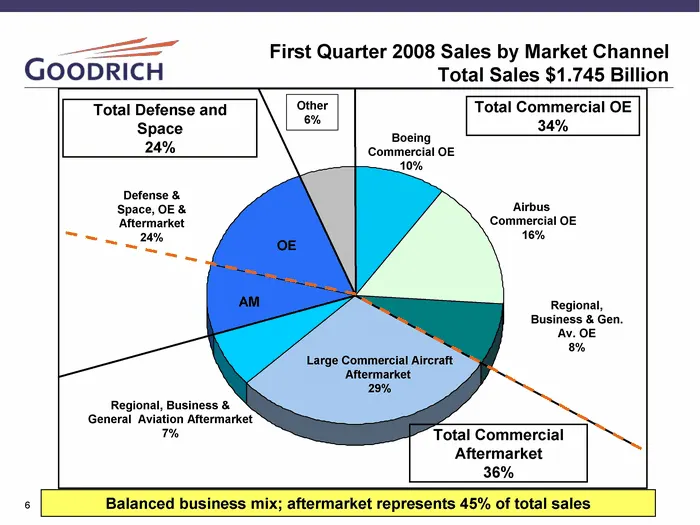
Slide 6: First Quarter 2008 Sales by Market Channel
Boeing Airbus Regional, Business, GA OE Commercial A/C Aftermarket Regional, Business & GA Aftmkt Military aftermarket Milatary OE Other East 10 16 8 29 7 9 15 6 First Quarter 2008 Sales by Market Channel Total Sales $1.745 Billion Large Commercial Aircraft Aftermarket 29% Regional, Business & Gener
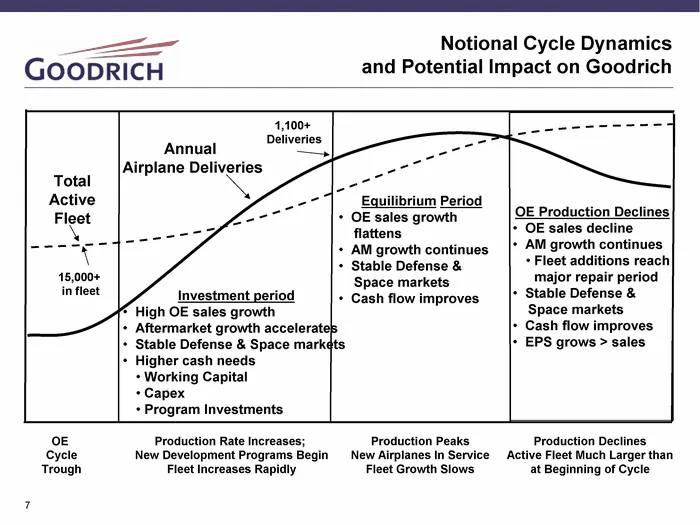
Slide 7: Notional Cycle Dynamics and Potential Impact on Goodrich
Notional Cycle Dynamics and Potential Impact on Goodrich Annual Airplane Deliveries OE Cycle Trough Production Rate Increases; New Development Programs Begin Fleet Increases Rapidly Investment period High OE sales growth Aftermarket growth accelerates Stable Defense & Space markets Higher cash needs
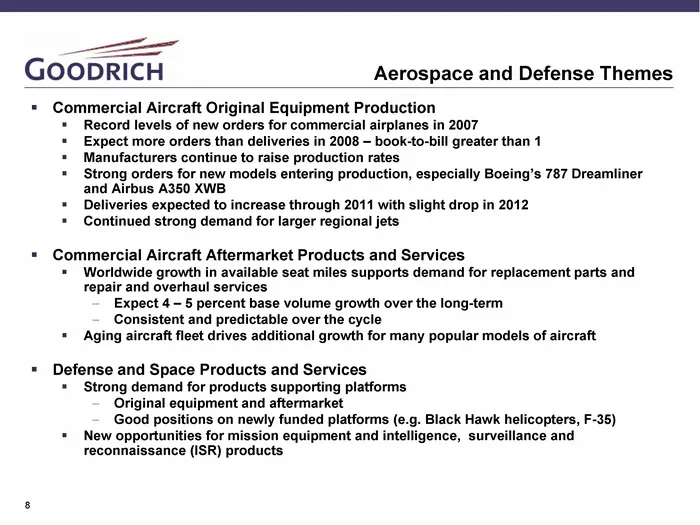
Slide 8: Aerospace and Defense Themes
Aerospace and Defense Themes Commercial Aircraft Original Equipment Production Record levels of new orders for commercial airplanes in 2007 Expect more orders than deliveries in 2008 - book-to-bill greater than 1 Manufacturers continue to raise production rates Strong orders for new models entering
Slide 9: Commercial Original Equipment
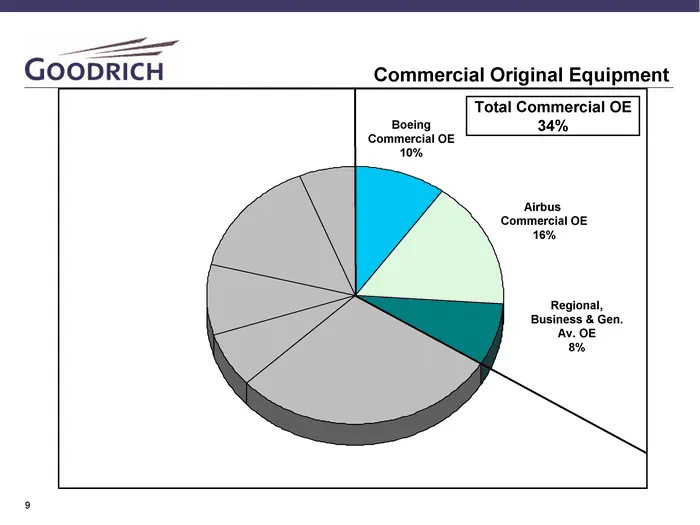
Boeing Airbus Regional, Business, GA OE Commercial A/C Aftermarket Regional, Business & GA Aftmkt Military aftermarket Milatary OE Other East 10 16 8 29 7 9 15 6 Commercial Original Equipment Boeing Commercial OE 10% Airbus Commercial OE 16% Regional, Business & Gen. Av. OE 8% Total Commercial OE 34
Slide 10: Commercial OE Production Drivers
Commercial OE Production Drivers World GDP: macro driver World available seat mile (ASM) and revenue passenger mile (RPM) growth Airline profitability Aircraft retirements Driven by aircraft age and fuel burn efficiency
Slide 11: Commercial Airplane Delivery Forecast
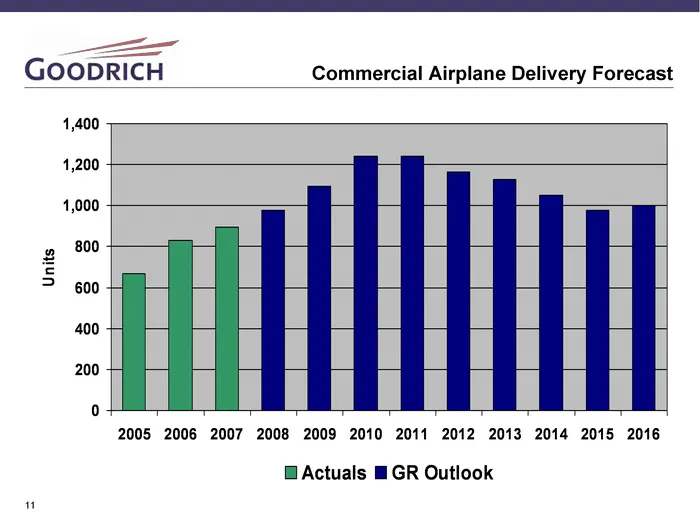
Commercial Airplane Delivery Forecast 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Actuals 668 832 897 GR Outlook 0 0 976 1094 1243 1243 1164 1126 1049 978 1000 Airline Monitor 0 0 888 1037 1133 1180 1065 815 840 1045 1135 1205
Slide 12: Large Commercial Aircraft - On Order Distribution
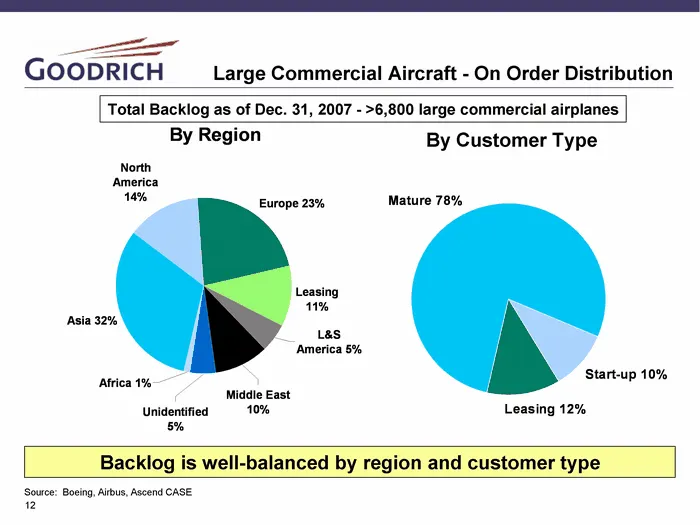
Large Commercial Aircraft - On Order Distribution Asia North America Europe Leasing L&S America Middle East Unidentified Africa 0.315 0.138 0.225 0.11 0.054 0.099 0.046 0.012 Mature Start-up Leasing Boeing 0.777 0.101 0.122 Backlog is well-balanced by region and customer type By Customer Type Source
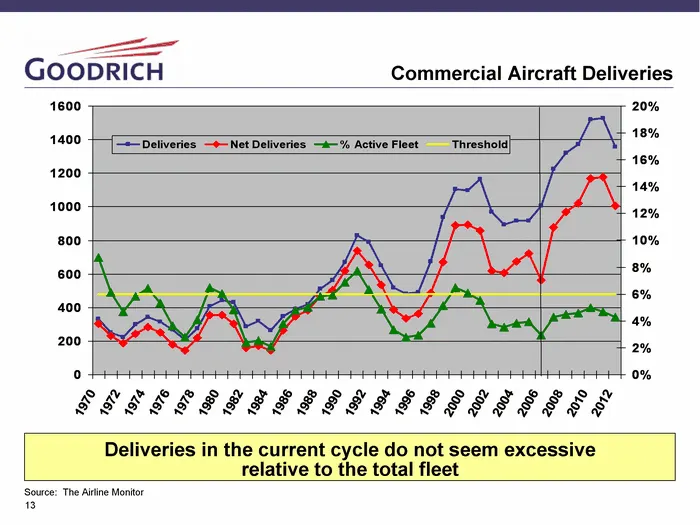
Slide 13: Commercial Aircraft Deliveries
Commercial Aircraft Deliveries 1970 1971 1972 1973 1974 1975 1976 1977 1978 1979 1980 1981 1982 1983 1984 1985 1986 1987 1988 1989 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 Deliveries 331 251 223 299 343 314 267 208 275 407 442
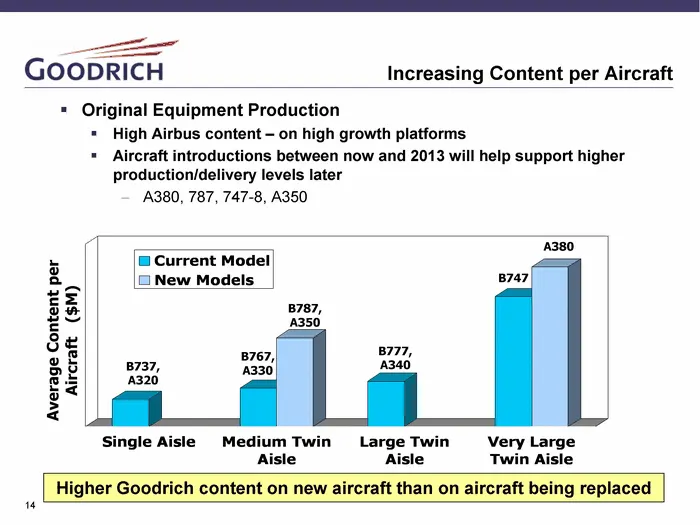
Slide 14: Increasing Content per Aircraft
Increasing Content per Aircraft Original Equipment Production High Airbus content - on high growth platforms Aircraft introductions between now and 2013 will help support higher production/delivery levels later A380, 787, 747-8, A350 Single Aisle Medium Twin Aisle Large Twin Aisle Very Large Twin Ai
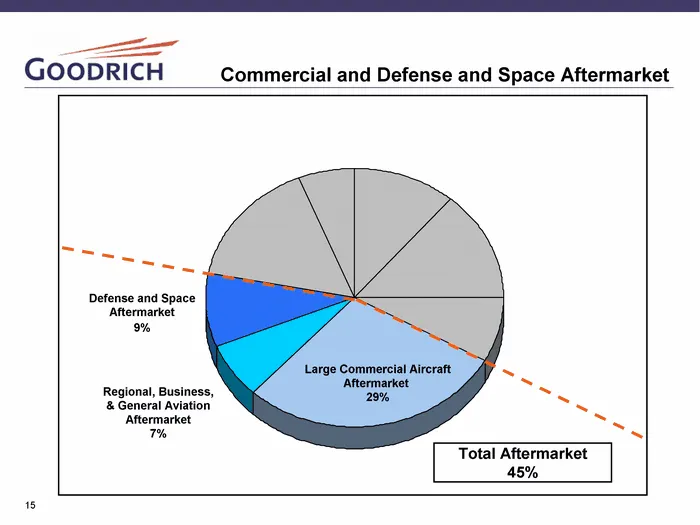
Slide 15: Commercial and Defense and Space Aftermarket
Boeing Airbus Regional, Business, GA OE Commercial A/C Aftermarket Regional, Business & GA Aftmkt Military aftermarket Milatary OE Other East 11 14 8 29 7 9 16 6 Commercial and Defense and Space Aftermarket Large Commercial Aircraft Aftermarket 29% Regional, Business, & General Aviation Aftermarket
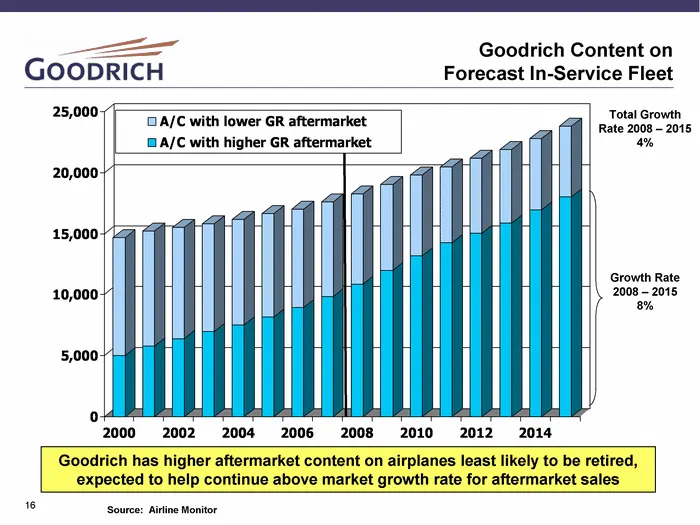
Slide 16: Goodrich Content on Forecast In-Service Fleet
Goodrich Content on Forecast In-Service Fleet 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 A/C with higher GR aftermarket 5014 5774 6408 6959 7526 8155 8940 9822 10859 11992 13172 14237 15052 15891 16927 18048 A/C with lower GR aftermarket 9651 9427 9111 8853 8648
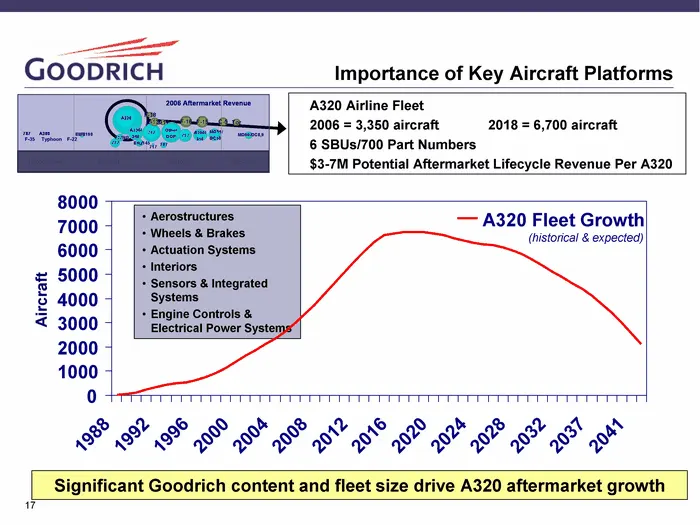
Slide 17: Importance of Key Aircraft Platforms: A320
A320 Airline Fleet 2006 = 3,350 aircraft 2018 = 6,700 aircraft 6 SBUs/700 Part Numbers $3-7M Potential Aftermarket Lifecycle Revenue Per A320 Aerostructures Wheels & Brakes Actuation Systems Interiors Sensors & Integrated Systems Engine Controls & Electrical Power Systems Significant Goodrich conten
Slide 18: Aftermarket Summary
Aftermarket Summary 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Aerostructures 445 463.2 506.9 547.9 594.6 647.8 707.1 781.9 865.6 958.3 Goodrich 818.4 874.2 958.4 1039.2 1122.7 1216.5 1316.4 1433.9 1562.7 1703.1 Market Rate 723.6 760.5 800.8 844.9 858.4 900.4 949.1 999.4 1053.3 1109.2 Market
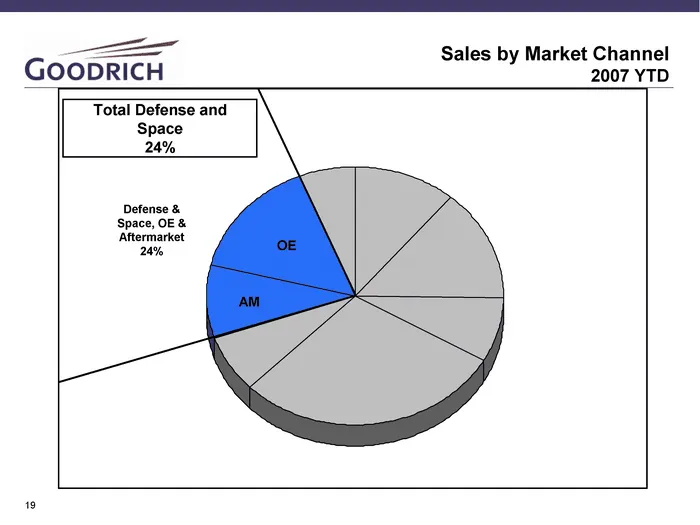
Slide 19: Sales by Market Channel: Defense and Space
Boeing Airbus Regional, Business, GA OE Commercial A/C Aftermarket Regional, Business & GA Aftmkt Military aftermarket Milatary OE Other East 11 14 8 29 7 9 15 6 Sales by Market Channel 2007 YTD Defense & Space, OE & Aftermarket 24% OE AM Total Defense and Space 24%
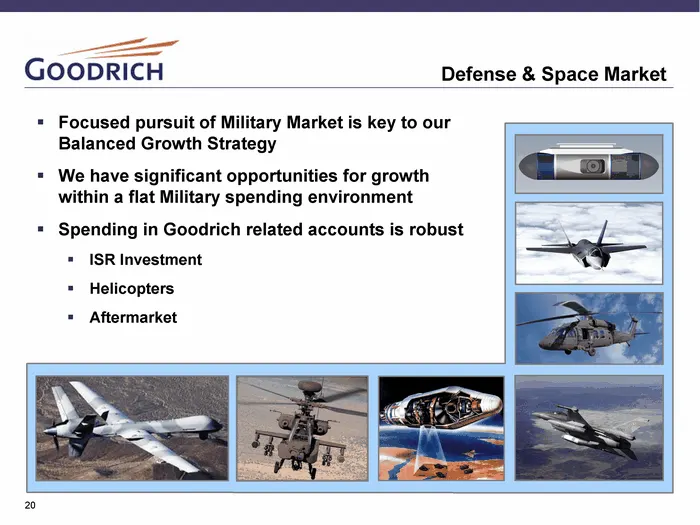
Slide 20: Focused Pursuit of Military Market is Key to Balanced Growth Strategy
Focused pursuit of Military Market is key to our Balanced Growth Strategy We have significant opportunities for growth within a flat Military spending environment Spending in Goodrich related accounts is robust ISR Investment Helicopters Aftermarket Defense & Space Market
Slide 21: Goodrich Defense & Space Sales
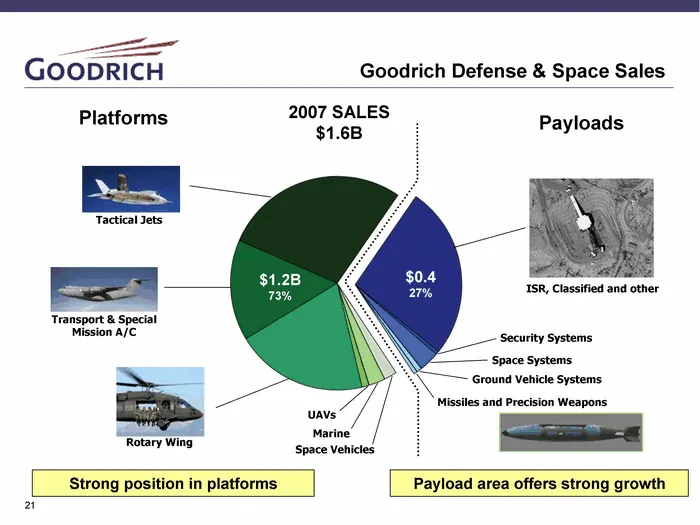
Goodrich Defense & Space Sales UAVs Marine Space Vehicles Missiles and Precision Weapons Ground Vehicle Systems Space Systems Security Systems 2007 SALES $1.6B Payloads Platforms Transport & Special Mission A/C Rotary Wing Tactical Jets ISR, Classified and other $1.2B 73% $0.4 27% Strong position in
Slide 22: F-35 (Joint Strike Fighter) Goodrich Content
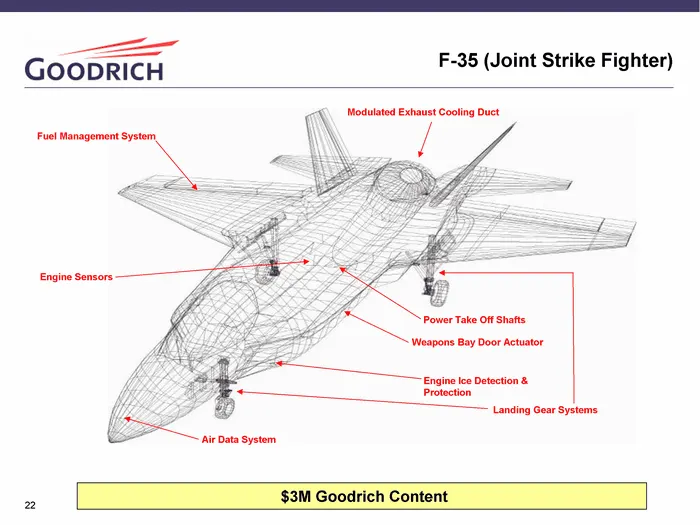
F-35 (Joint Strike Fighter) Landing Gear Systems Power Take Off Shafts Weapons Bay Door Actuator Engine Ice Detection & Protection Fuel Management System Engine Sensors Air Data System Modulated Exhaust Cooling Duct $3M Goodrich Content
Slide 23: CH-53K Goodrich Potential Content
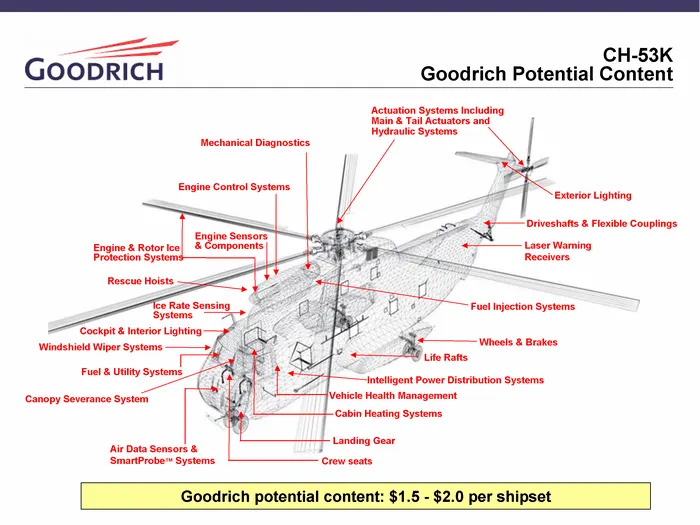
23 ? ? Actuation Systems Including Main & Tail Actuators and Hydraulic Systems Exterior Lighting Driveshafts & Flexible Couplings Laser Warning Receivers Fuel Injection Systems Wheels & Brakes Intelligent Power Distribution Systems Life Rafts Vehicle Health Management Cabin Heating Systems Landing G
Slide 24: Military Helicopter Market
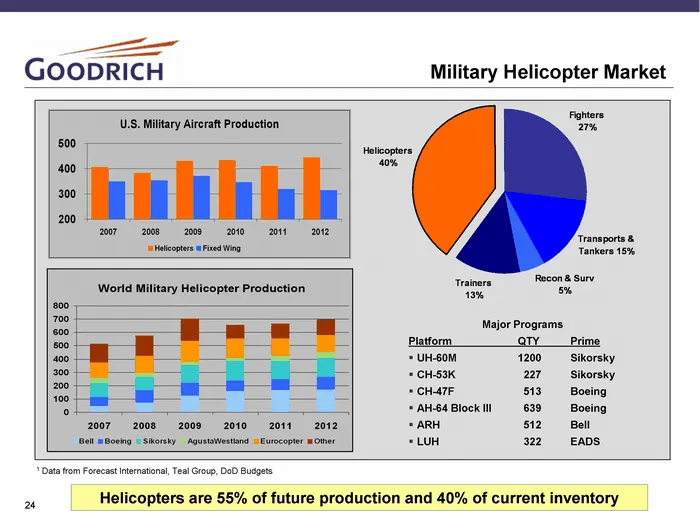
Military Helicopter Market Helicopters are 55% of future production and 40% of current inventory 2007 2008 2009 2010 2011 2012 Helicopters 406 383 431 434 412 445 Fixed Wing 350 353 372 346 319 315 Major Programs Platform QTY Prime UH-60M 1200 Sikorsky CH-53K 227 Sikorsky CH-47F 513 Boeing AH-64 Blo
Slide 25: Intelligence Surveillance Reconnaissance Market
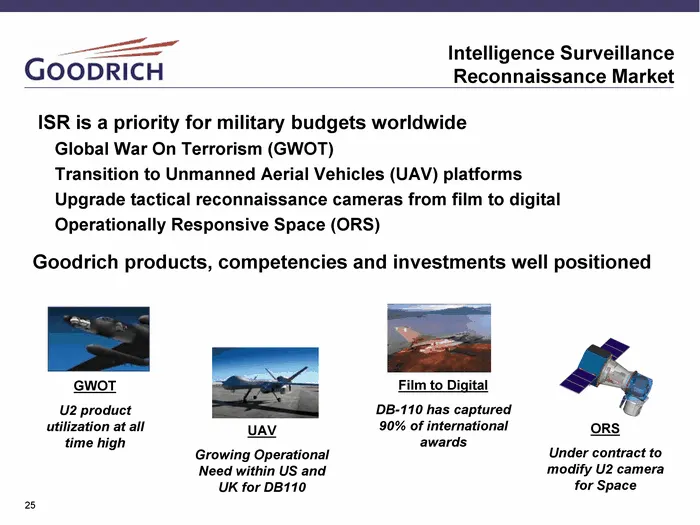
Intelligence Surveillance Reconnaissance Market ISR is a priority for military budgets worldwide Global War On Terrorism (GWOT) Transition to Unmanned Aerial Vehicles (UAV) platforms Upgrade tactical reconnaissance cameras from film to digital Operationally Responsive Space (ORS) Goodrich products,
Slide 26: Defense & Space Market Summary
Defense & Space Market Summary Focused pursuits and advanced technology are keys to growth Space Airborne Ground Goodrich well positioned in aircraft platform content New Programs, Upgrades, Aftermarket Payload area offers significant growth potential ISR Systems - GWOT, UAV, ORS
Slide 27: Delivering Sustained Sales Growth and Margin Expansion
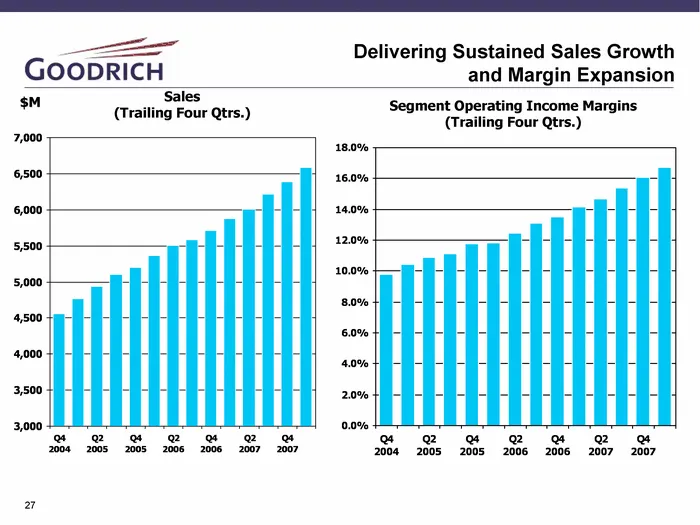
Delivering Sustained Sales Growth and Margin Expansion Q4 2004 Q1 2005 Q2 2005 Q3 2005 Q4 2005 Q1 2006 Q2 2006 Q3 2006 Q4 2006 Q1 2007 Q2 2007 Q3 2007 Q4 2007 Q1 2008 East 4554 4765 4940 5103 5203 5368 5508 5578 5719 5879 6013 6219 6392 6591 Q4 2004 Q1 2005 Q2 2005 Q3 2005 Q4 2005 Q1 2006 Q2 2006 Q3
Slide 28: 2008 Sales Expectations By Market Channel
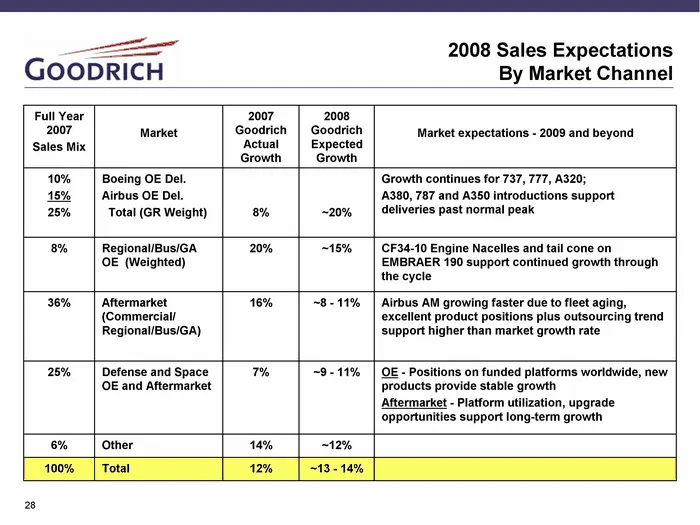
2008 Sales Expectations By Market Channel Full Year 2007 Sales Mix Market 2007 Goodrich Actual Growth 2008 Goodrich Expected Growth Market expectations - 2009 and beyond 10% 15% 25% Boeing OE Del. Airbus OE Del. Total (GR Weight) 8% ~20% Growth continues for 737, 777, A320; A380, 787 and A350 introd
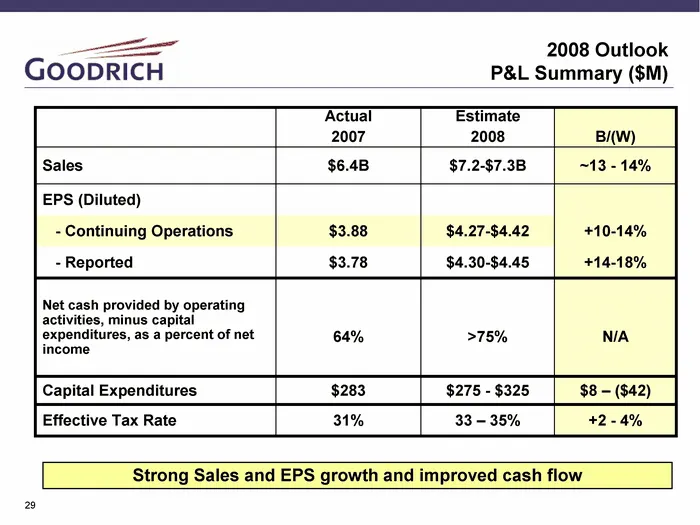
Slide 29: 2008 Outlook P&L Summary
2008 Outlook P&L Summary ($M) Actual 2007 Estimate 2008 B/(W) Sales $6.4B $7.2-$7.3B ~13 - 14% EPS (Diluted) - Continuing Operations $3.88 $4.27-$4.42 +10-14% - Reported $3.78 $4.30-$4.45 +14-18% Net cash provided by operating activities, minus capital expenditures, as a percent of net income 64% >7
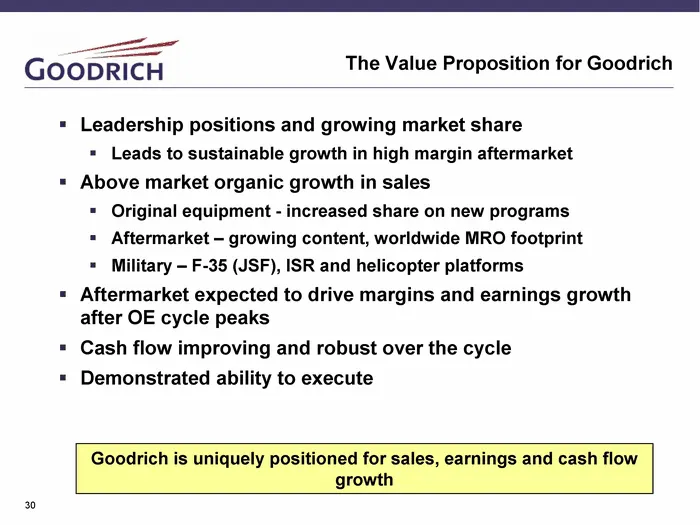
Slide 30: The Value Proposition for Goodrich
Leadership positions and growing market share Leads to sustainable growth in high margin aftermarket Above market organic growth in sales Original equipment - increased share on new programs Aftermarket - growing content, worldwide MRO footprint Military - F-35 (JSF), ISR and helicopter platforms Af
Source: SEC EDGAR · 8-K filed May 14, 2008
More decks from Goodrich Corp
 Q4 2009 Earnings Presentation23 slides · Jan 28, 2010
 Q3 2009 Earnings Presentation21 slides · Oct 22, 2009
 Q2 2009 Earnings Presentation21 slides · Jul 23, 2009
 Macquarie Capital Aerospace & Defense Conference 200920 slides · May 14, 2009
 Q1 2009 Earnings Presentation21 slides · Apr 23, 2009
 FY2008 Earnings Presentation28 slides · Feb 4, 2009