Air Transport Services Group Inc
Air Transport Services — Imperial Capital Global Opportunities Conference 2013
16 slides from Air Transport Services's conference presentation, Sep 19, 2013
Slide 1: Imperial Capital Global Opportunities Conference
0 Imperial Capital Global Opportunities Conference September 19, 2013 Joe Hete President & CEO Quint Turner Chief Financial Officer Boeing 767-200 Freighters Boeing 767-300 Freighters Boeing 757-200 Freighters Boeing 757-200 Combis The World’s Largest Integrated Source of Midsize Freighter Aircraft,
Slide 2: Safe Harbor Statement
Safe Harbor Statement Except for historical information contained herein, the matters discussed in this presentation contain forward-looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual resu
Slide 3: ATSG: An Undervalued Cash Generator
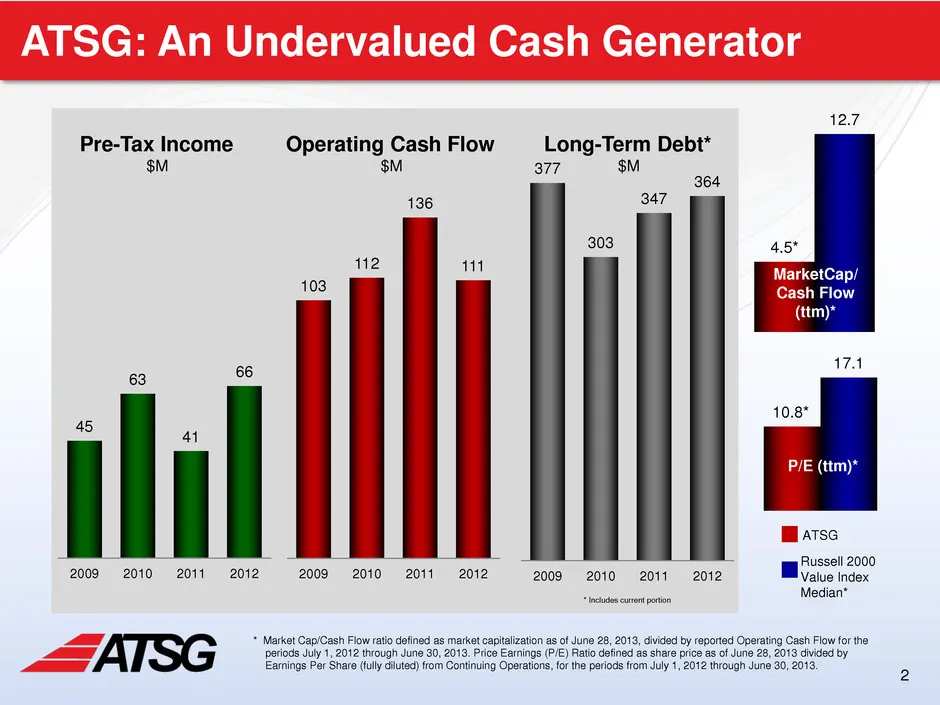
2 ATSG: An Undervalued Cash Generator 4.5* 12.7 10.8* 17.1 103 112 136 111 2009 2010 2011 2012 Operating Cash Flow $M MarketCap/ Cash Flow (ttm)* P/E (ttm)* ATSG Russell 2000 Value Index Median* 45 63 41 66 2009 2010 2011 2012 Pre-Tax Income $M 377 303 347 364 2009 2010 2011 2012 Long-Term Debt* $M
Slide 4: Unique Business Model, Leverage-Lite
3 Unique Business Model, Leverage-Lite Differentiated Business Model With Global Leadership Lessor and operator of world’s largest fleet of converted medium widebody Boeing 767 freighters Long-term relationships with global logistics leader DHL, plus U.S. Military, USPS, TNT Provide full spect
Slide 5: ATSG at a Glance
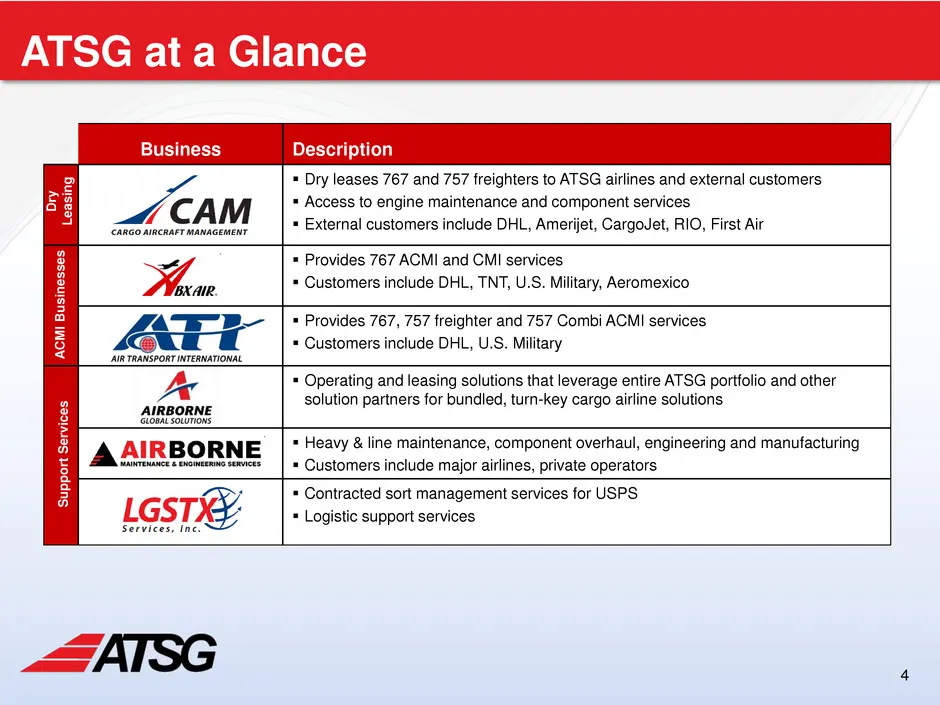
4 ATSG at a Glance Business Description Dry leases 767 and 757 freighters to ATSG airlines and external customers Access to engine maintenance and component services External customers include DHL, Amerijet, CargoJet, RIO, First Air Provides 767 ACMI and CMI services Customers include DHL,
Slide 6: ATSG Strategy – It Starts With The Lease
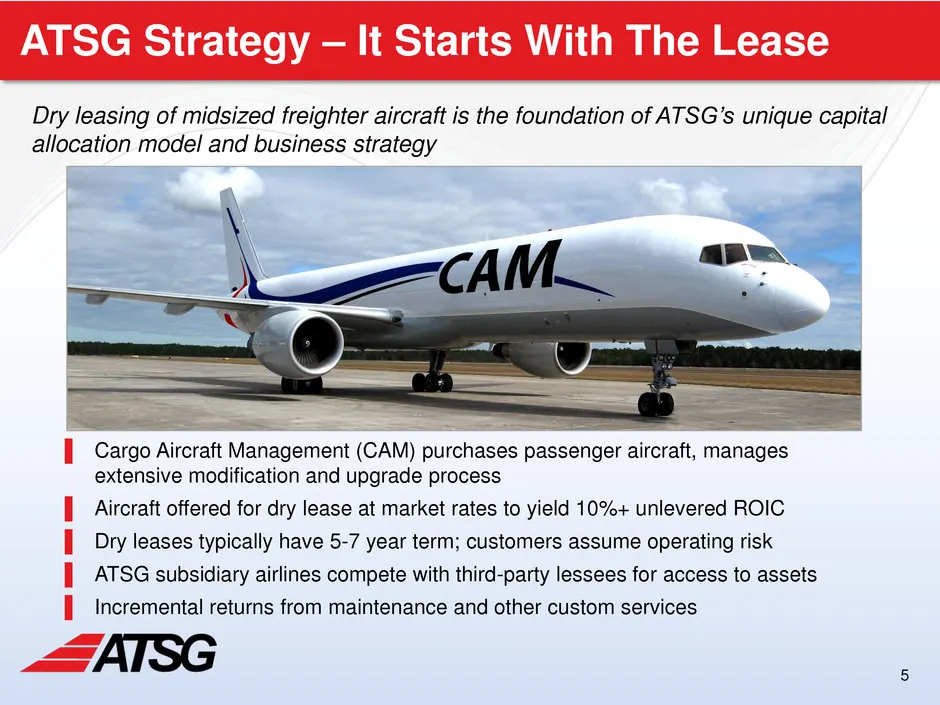
5 ATSG Strategy – It Starts With The Lease Dry leasing of midsized freighter aircraft is the foundation of ATSG’s unique capital allocation model and business strategy ▌ Cargo Aircraft Management (CAM) purchases passenger aircraft, manages extensive modification and upgrade process ▌ Aircraft offere
Slide 7: ATSG Strategy – ACMI or CMI Operations
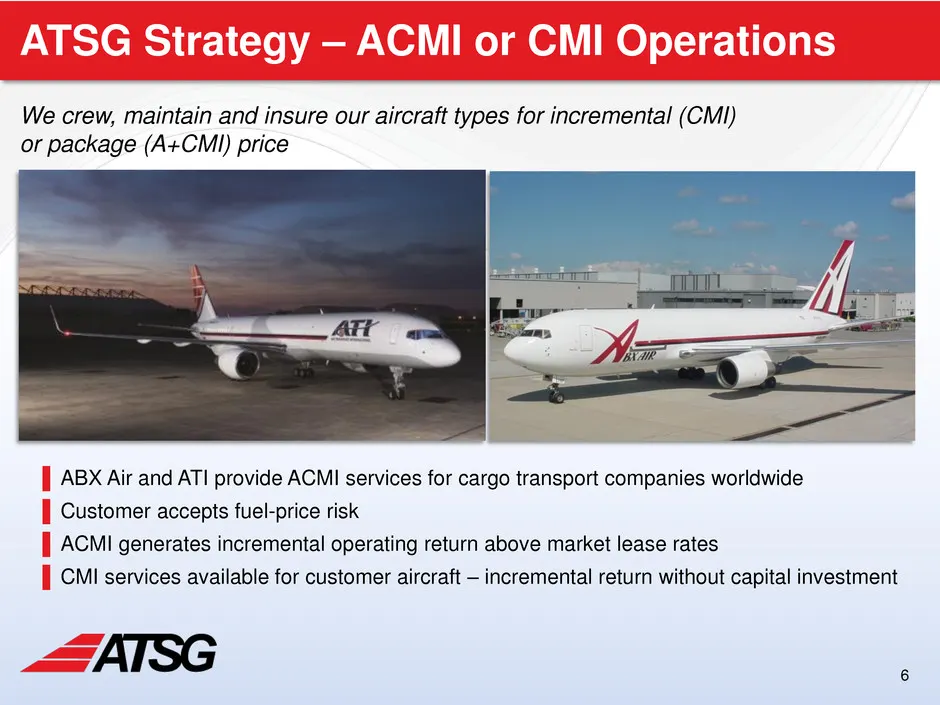
6 ATSG Strategy – ACMI or CMI Operations We crew, maintain and insure our aircraft types for incremental (CMI) or package (A+CMI) price ▌ABX Air and ATI provide ACMI services for cargo transport companies worldwide ▌Customer accepts fuel-price risk ▌ACMI generates incremental operating return above
Slide 8: ATSG Strategy – Customized Support
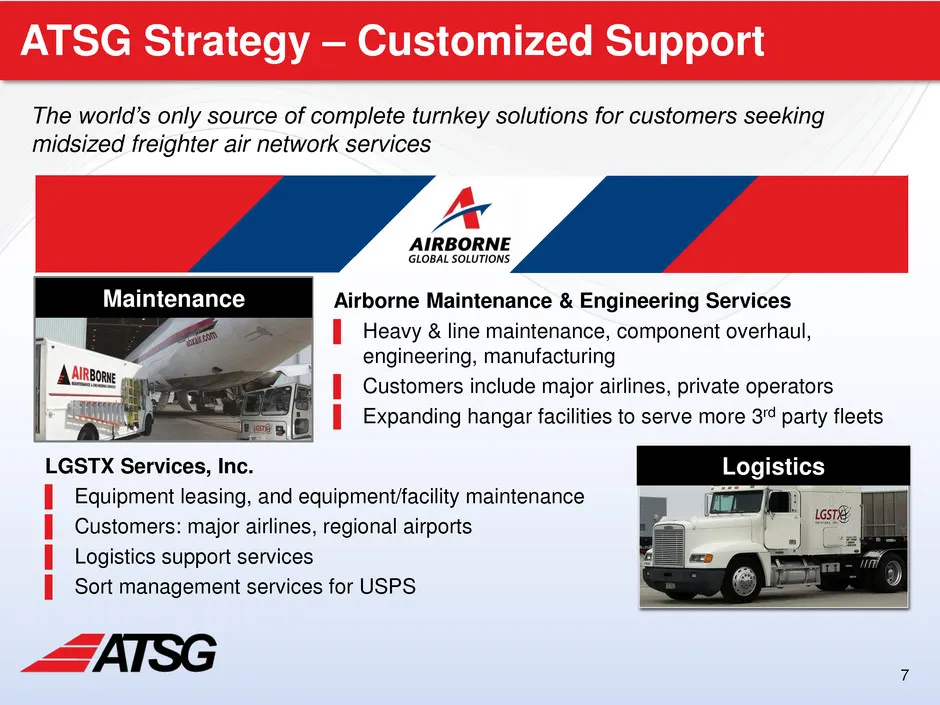
7 ATSG Strategy – Customized Support The world’s only source of complete turnkey solutions for customers seeking midsized freighter air network services Airborne Maintenance & Engineering Services ▌ Heavy & line maintenance, component overhaul, engineering, manufacturing ▌ Customers include major ai
Slide 9: ATSG Investment Strategy
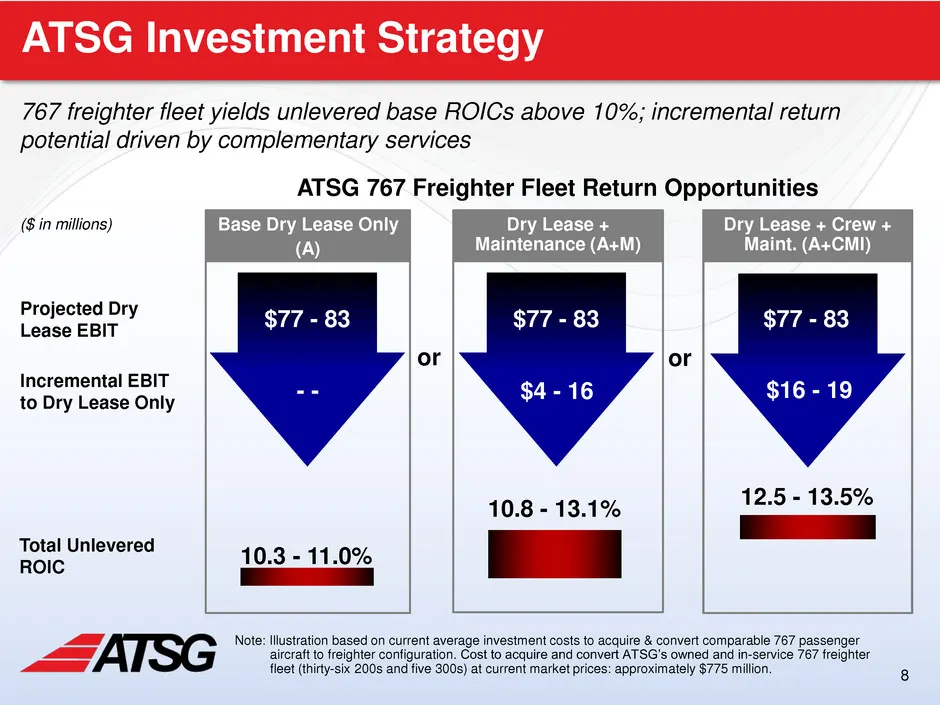
8 ATSG Investment Strategy 767 freighter fleet yields unlevered base ROICs above 10%; incremental return potential driven by complementary services Base Dry Lease Only (A) Dry Lease + Crew + Maint. (A+CMI) Dry Lease + Maintenance (A+M) Projected Dry Lease EBIT Incremental EBIT to Dry Lease Only Tota
Slide 10: First Half 2013 Results
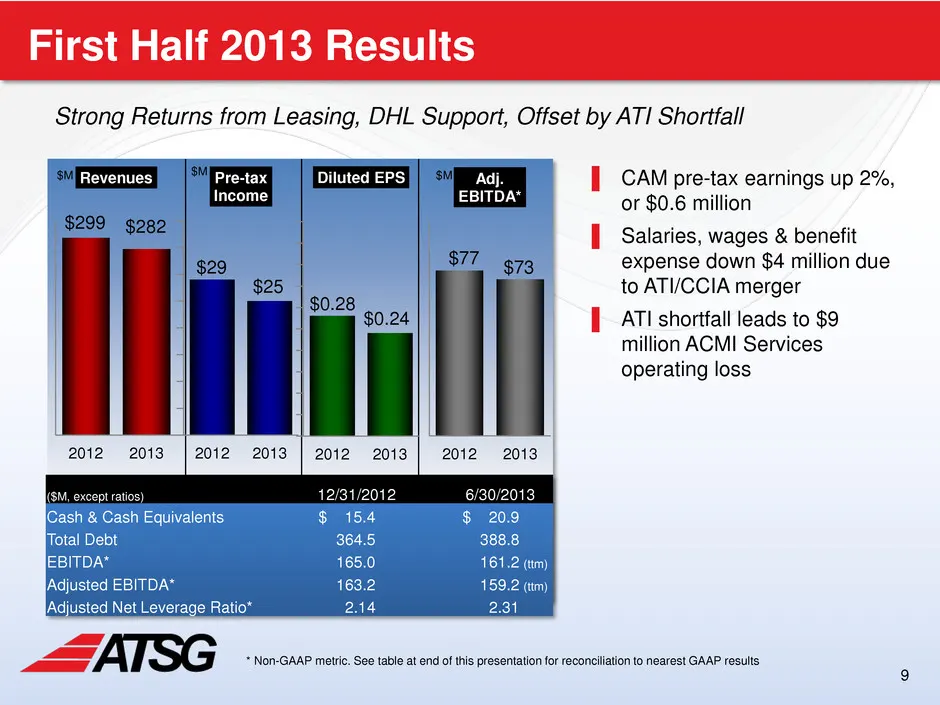
9 2012 2013 Adj. EBITDA* First Half 2013 Results ▌ CAM pre-tax earnings up 2%, or $0.6 million ▌ Salaries, wages & benefit expense down $4 million due to ATI/CCIA merger ▌ ATI shortfall leads to $9 million ACMI Services operating loss $73 $77 Strong Returns from Leasing, DHL Support, Offset by ATI S
Slide 11: Strong Capital Base
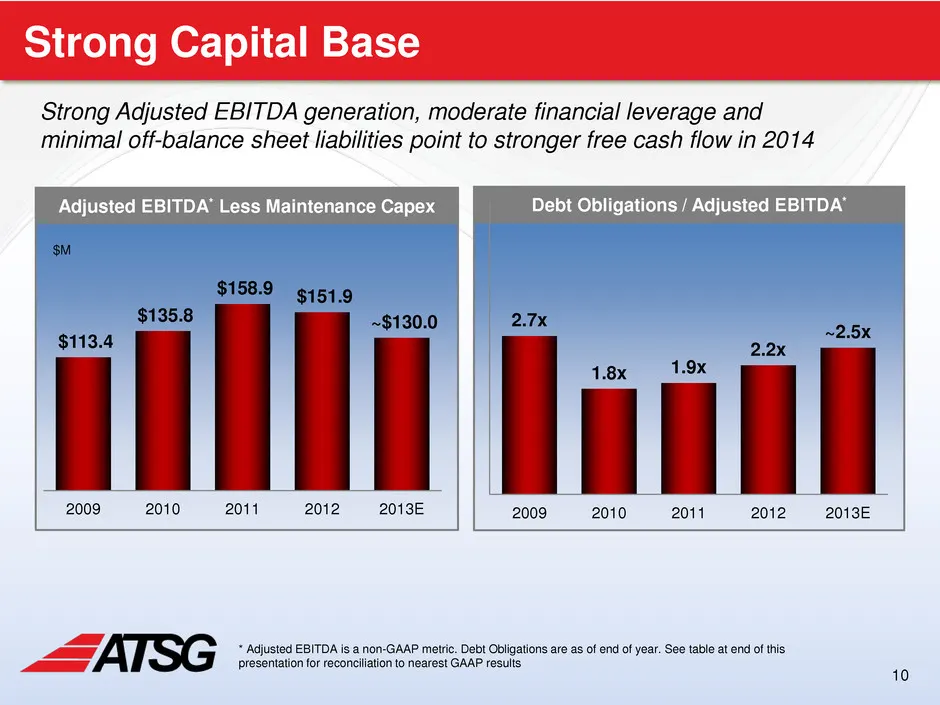
10 Strong Capital Base Strong Adjusted EBITDA generation, moderate financial leverage and minimal off-balance sheet liabilities point to stronger free cash flow in 2014 $113.4 $135.8 $158.9 $151.9 ~$130.0 2009 2010 2011 2012 2013E Debt Obligations / Adjusted EBITDA* Adjusted EBITDA* Less Maintenance
Slide 12: Unrivaled Leader in ACMI Medium Wide-body
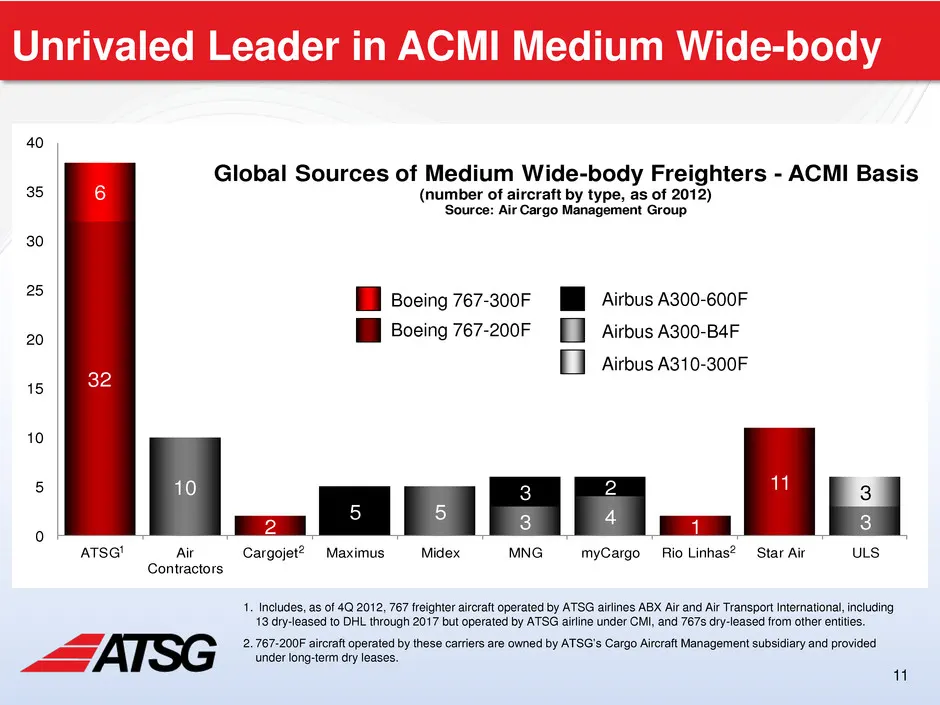
11 32 2 1 11 6 10 5 3 4 3 5 3 2 3 0 5 10 15 20 25 30 35 40 ATSG Air Contractors Cargojet Maximus Midex MNG myCargo Rio Linhas Star Air ULS Global Sources of Medium Wide-body Freighters - ACMI Basis (number of aircraft by type, as of 2012) Source: Air Cargo Management Group Unrivaled Leader in ACMI M
Slide 13: Penetrating Global Markets
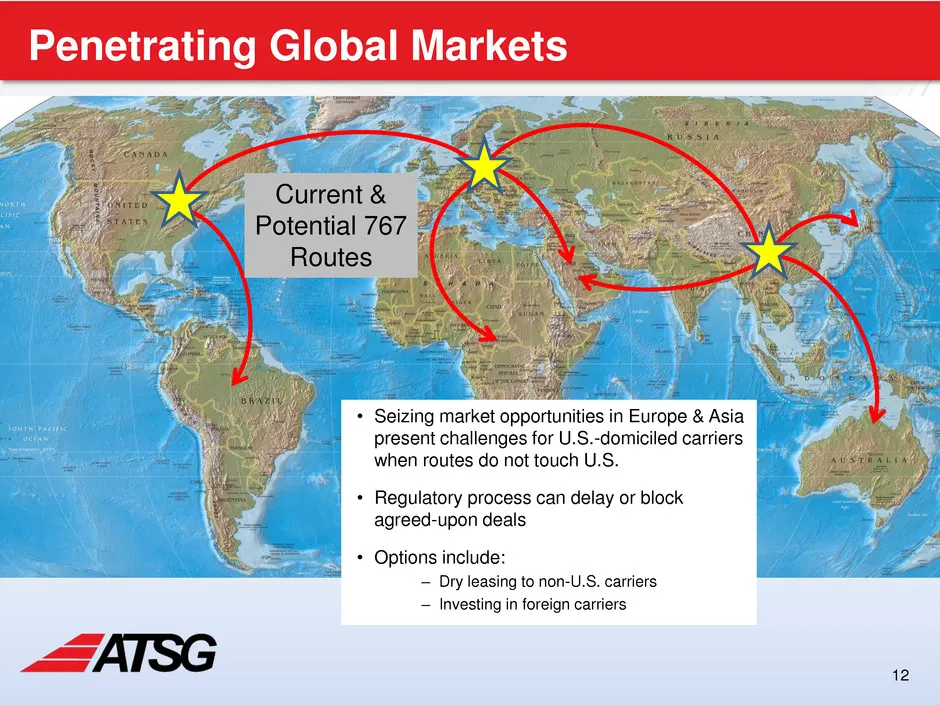
12 Penetrating Global Markets • Seizing market opportunities in Europe & Asia present challenges for U.S.-domiciled carriers when routes do not touch U.S. • Regulatory process can delay or block agreed-upon deals • Options include: – Dry leasing to non-U.S. carriers – Investing in foreign carriers C
Slide 14: Combi Transition Update
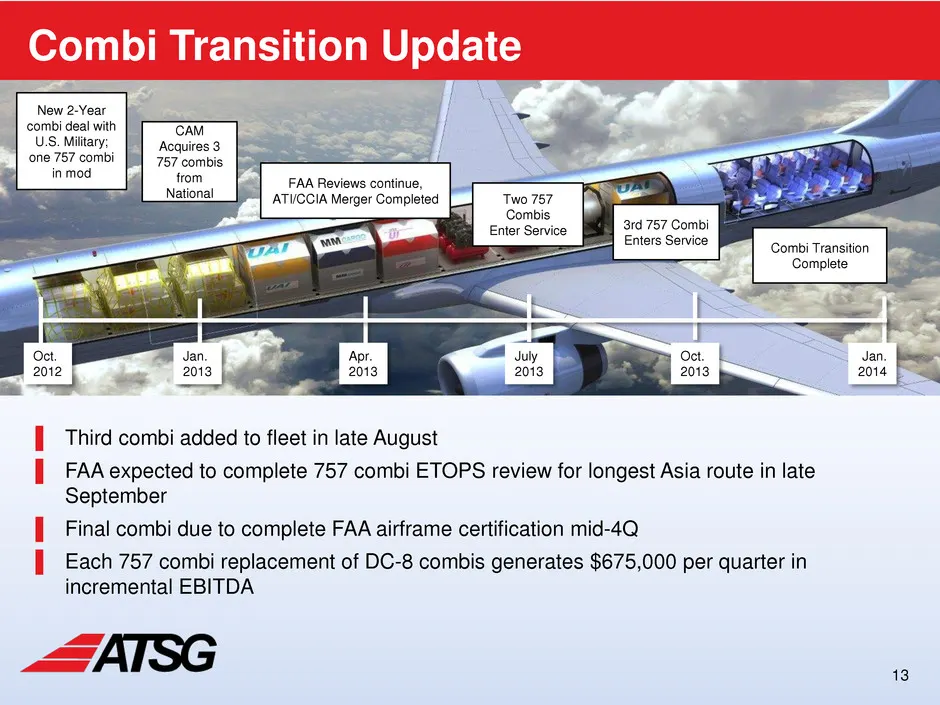
13 Combi Transition Update New 2-Year combi deal with U.S. Military; one 757 combi in mod CAM Acquires 3 757 combis from National FAA Reviews continue, ATI/CCIA Merger Completed Two 757 Combis Enter Service 3rd 757 Combi Enters Service Combi Transition Complete Oct. 2012 Jan. 2014 Jan. 2013 Apr. 201
Slide 15: 2014 – Expanding Free Cash Flow Creates Options
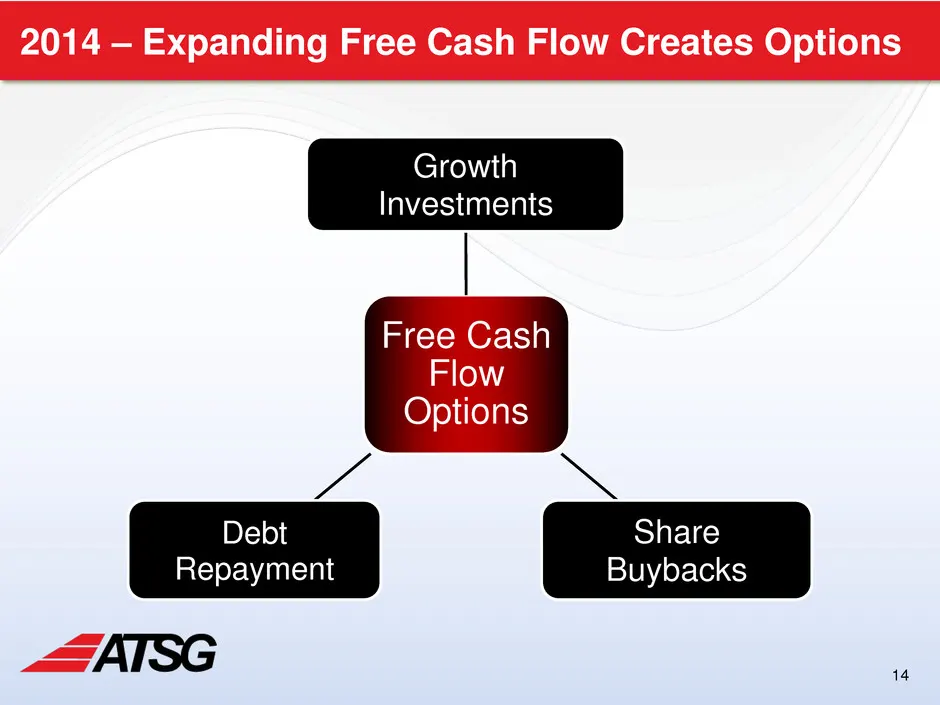
14 2014 – Expanding Free Cash Flow Creates Options Free Cash Flow Options Growth Investments Share Buybacks Debt Repayment
Slide 16: Non-GAAP Reconciliation Statement
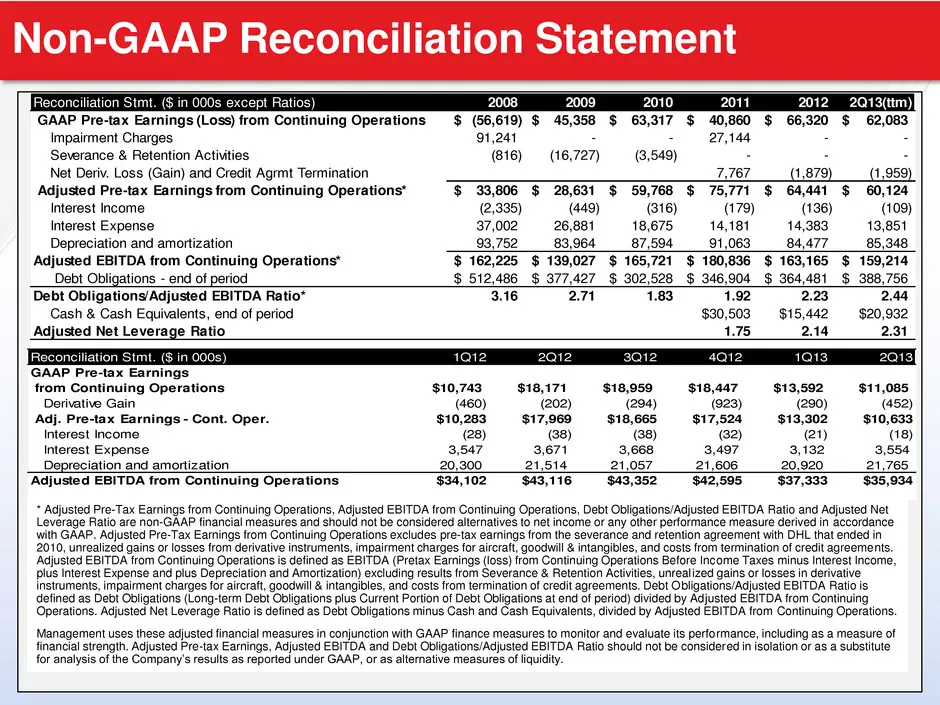
15 Non-GAAP Reconciliation Statement * Adjusted Pre-Tax Earnings from Continuing Operations, Adjusted EBITDA from Continuing Operations, Debt Obligations/Adjusted EBITDA Ratio and Adjusted Net Leverage Ratio are non-GAAP financial measures and should not be considered alternatives to net income or a
Source: SEC EDGAR · 8-K filed Sep 19, 2013
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020