Columbia Property Trust — Investor Presentation (November 2018)
28 slides from Columbia Property Trust's investor presentation, Nov 7, 2018
Slide 1: Investor Presentation November 2018
INVESTOR PRESENTATION 11. 2018 1
Slide 2: Forward-Looking Statements
FORWARD-LOOKING STATEMENTS Certain statements contained in this presentation other than historical facts may be considered forward-looking statements. Such statements include, in particular, statements about our plans, strategies, and prospects, and are subject to certain risks and uncertainties, in
Slide 3: Overview: Investment Highlights
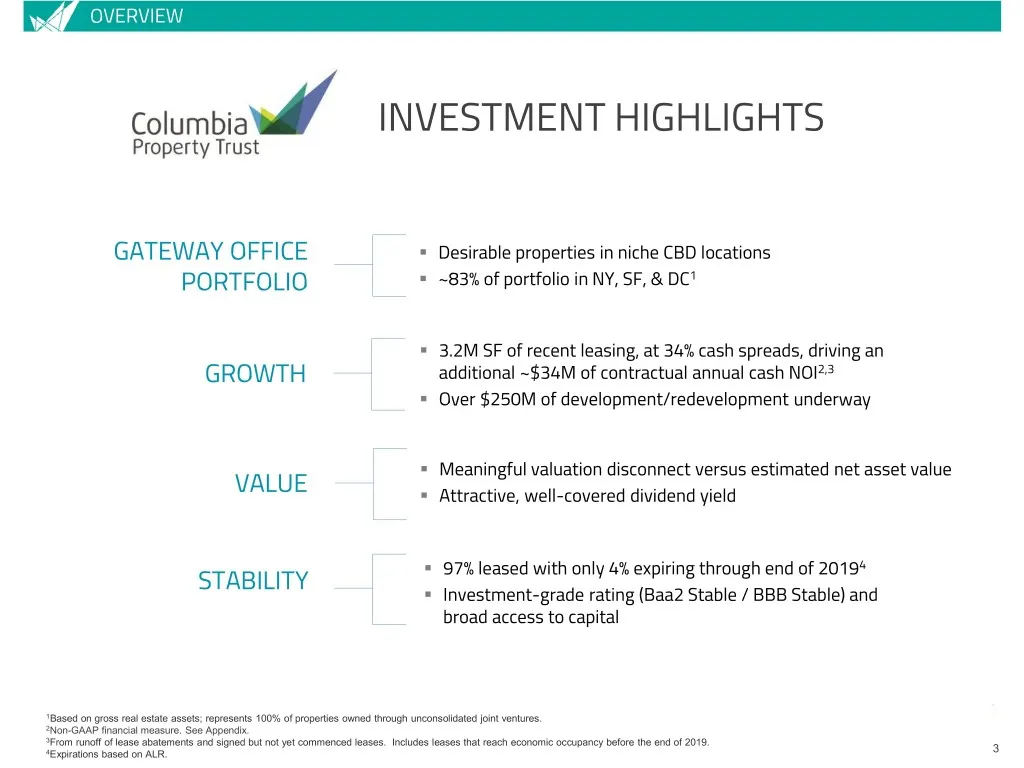
OVERVIEW INVESTMENT HIGHLIGHTS GATEWAY OFFICE . Desirable properties in niche CBD locations PORTFOLIO . ~83% of portfolio in NY, SF, & DC1 . 3.2M SF of recent leasing, at 34% cash spreads, driving an GROWTH additional ~$34M of contractual annual cash NOI2,3 . Over $250M of development/redevelopment
Slide 4: Portfolio: Desirable Buildings in Prime Locations
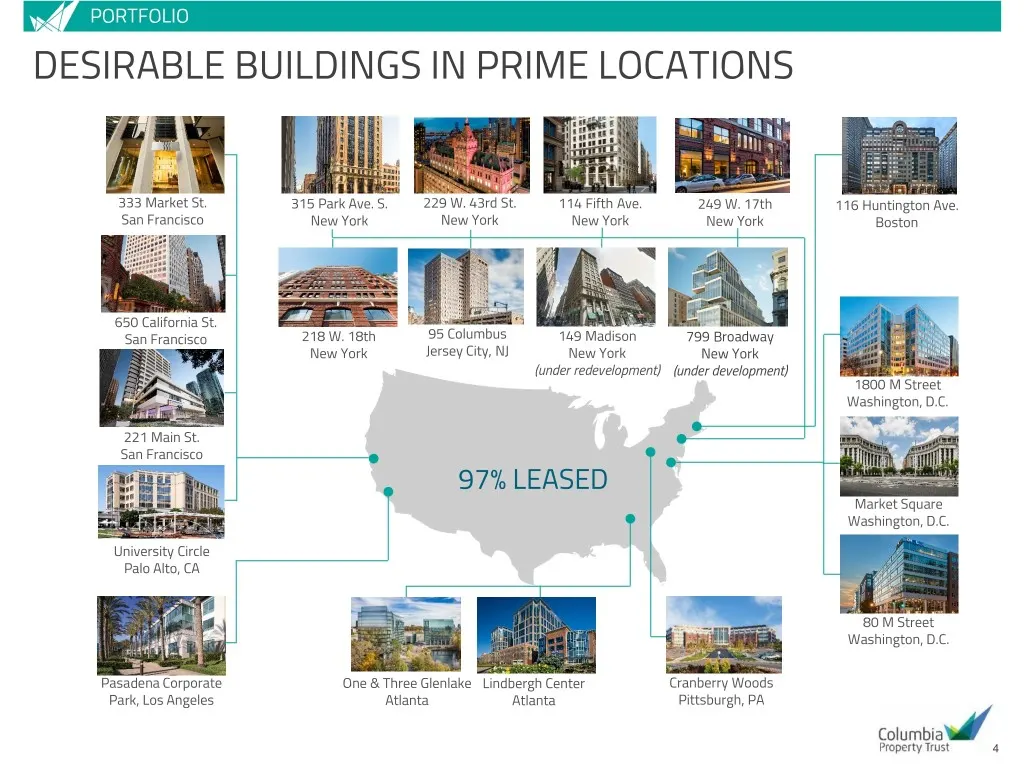
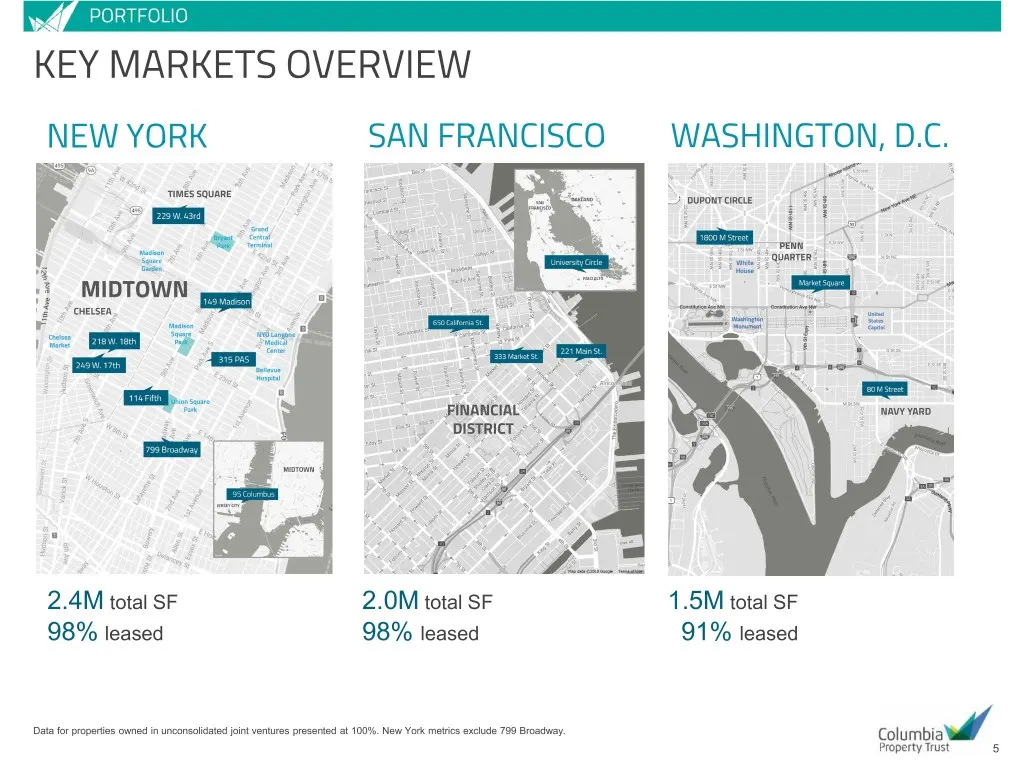
PORTFOLIO DESIRABLE BUILDINGS IN PRIME LOCATIONS 333 Market St. 315 Park Ave. S. 229 W. 43rd St. 114 Fifth Ave. 249 W. 17th 116 Huntington Ave. San Francisco New York New York New York New York Boston 650 California St. San Francisco 218 W. 18th 95 Columbus 149 Madison 799 Broadway New York Jersey C
Slide 5: Portfolio: Key Markets Overview
PORTFOLIO KEY MARKETS OVERVIEW NEW YORK SAN FRANCISCO WASHINGTON, D.C. 2.4M total SF 2.0M total SF 1.5M total SF 98% leased 98% leased 91% leased Data for properties owned in unconsolidated joint ventures presented at 100%. New York metrics exclude 799 Broadway. 5
Slide 6: Portfolio: A Differentiated Approach
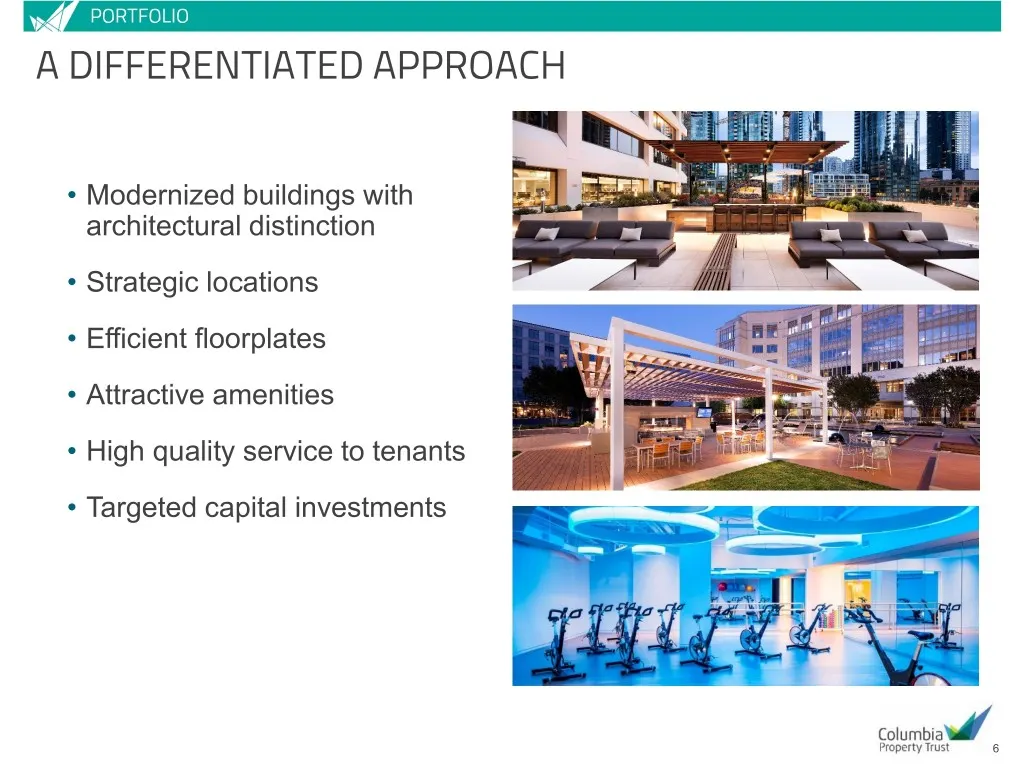
PORTFOLIO A DIFFERENTIATED APPROACH • Modernized buildings with architectural distinction • Strategic locations • Efficient floorplates • Attractive amenities • High quality service to tenants • Targeted capital investments 6
Slide 7: Growth: Leasing Driving Growth
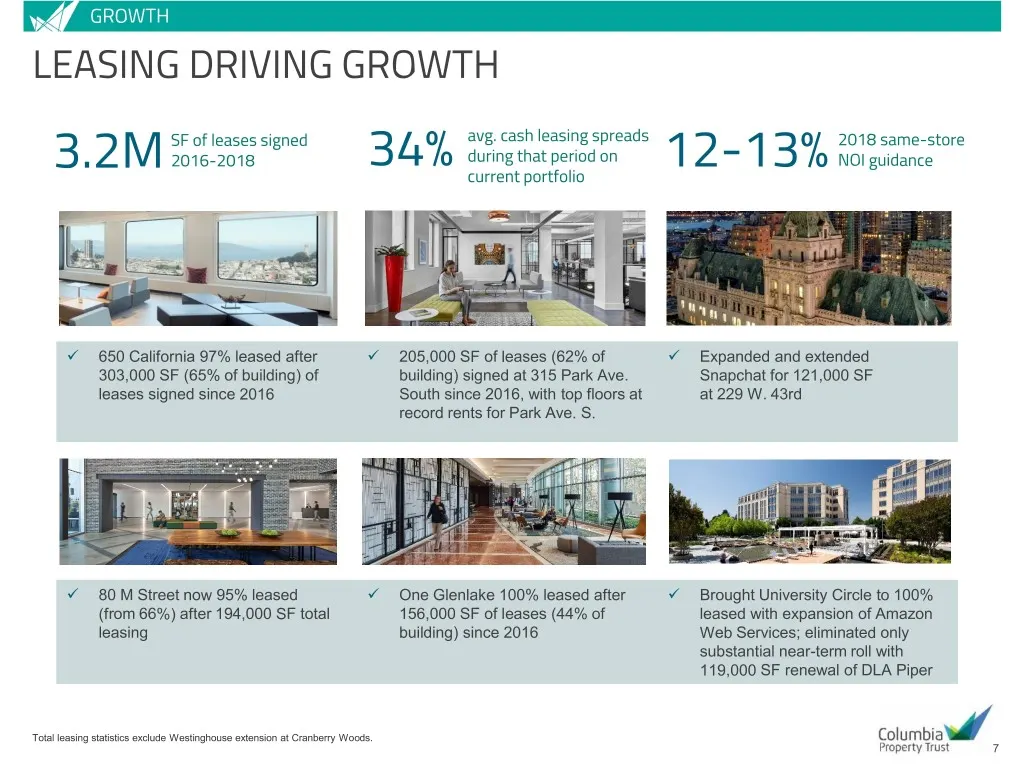
GROWTH LEASING DRIVING GROWTH SF of leases signed avg. cash leasing spreads 2018 same-store 2016-2018 during that period on NOI guidance 3.2M 34% current portfolio 12-13% 650 California 97% leased after 205,000 SF of leases (62% of Expanded and extended 303,000 SF (65% of building) of building
Slide 8: Growth: Attractive Leasing Opportunities
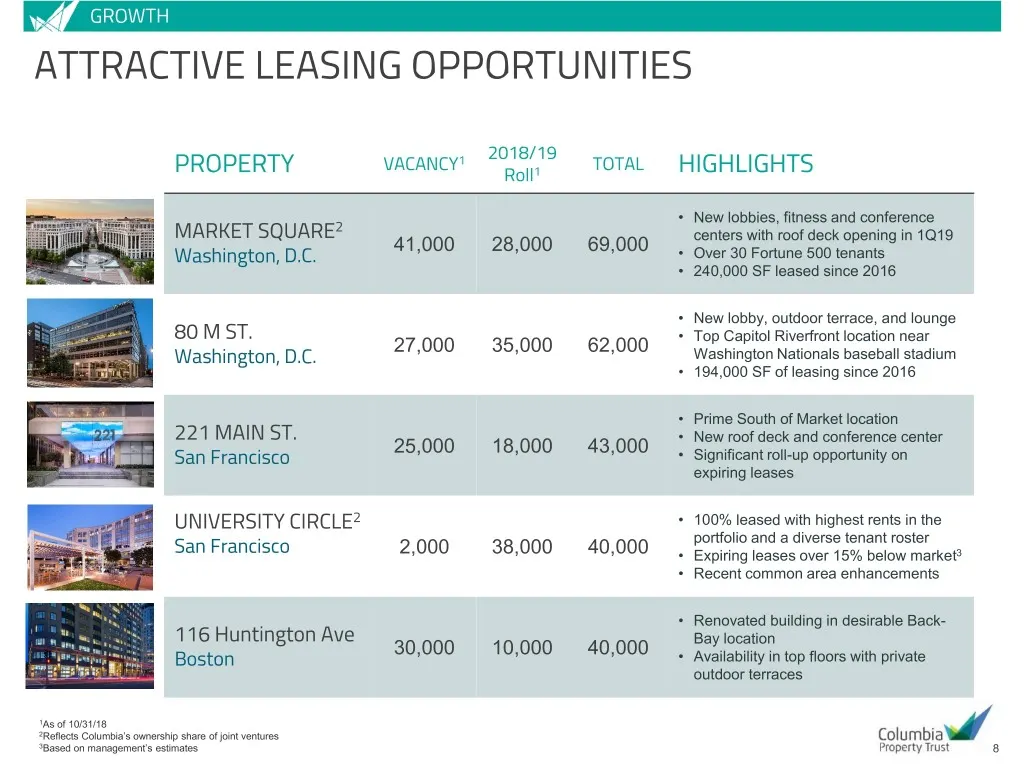
GROWTH ATTRACTIVE LEASING OPPORTUNITIES 2018/19 VACANCY1 TOTAL PROPERTY Roll1 HIGHLIGHTS • New lobbies, fitness and conference MARKET SQUARE2 41,000 28,000 69,000 centers with roof deck opening in 1Q19 Washington, D.C. • Over 30 Fortune 500 tenants • 240,000 SF leased since 2016 • New lobby, outdoor
Slide 9: Value: Illustrative Net Asset Value Analysis
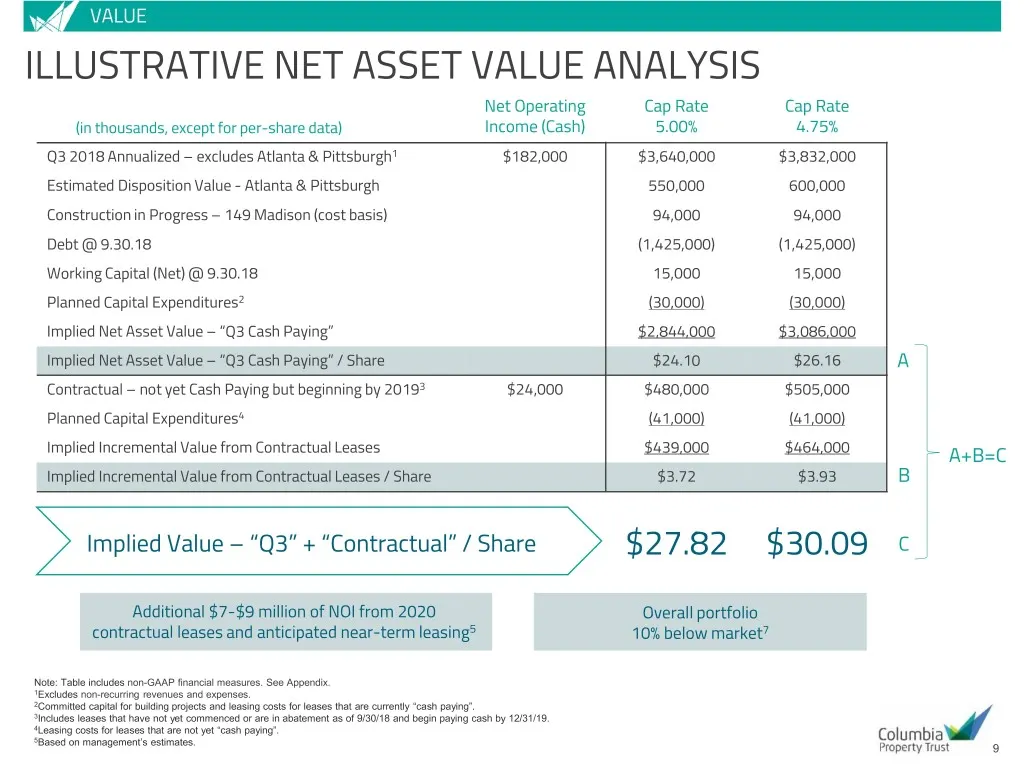
VALUE ILLUSTRATIVE NET ASSET VALUE ANALYSIS Net Operating Cap Rate Cap Rate (in thousands, except for per-share data) Income (Cash) 5.00% 4.75% Q3 2018 Annualized – excludes Atlanta & Pittsburgh1 $182,000 $3,640,000 $3,832,000 Estimated Disposition Value - Atlanta & Pittsburgh 550,000 600,000 Constr
Slide 10: Value: Embedded Growth from Signed Leases
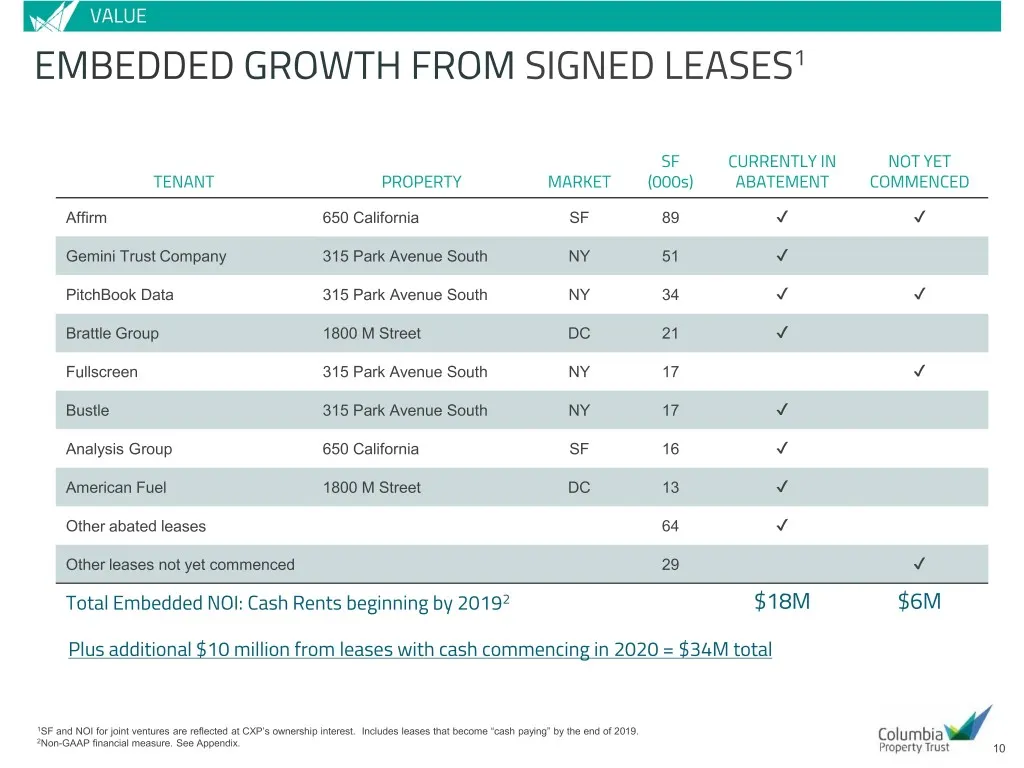
VALUE EMBEDDED GROWTH FROM SIGNED LEASES1 SF CURRENTLY IN NOT YET TENANT PROPERTY MARKET (000s) ABATEMENT COMMENCED Affirm 650 California SF 89 ✔ ✔ Gemini Trust Company 315 Park Avenue South NY 51 ✔ PitchBook Data 315 Park Avenue South NY 34 ✔ ✔ Brattle Group 1800 M Street DC 21 ✔ Fullscreen 315 Par
Slide 11: Value: Attractive Yield
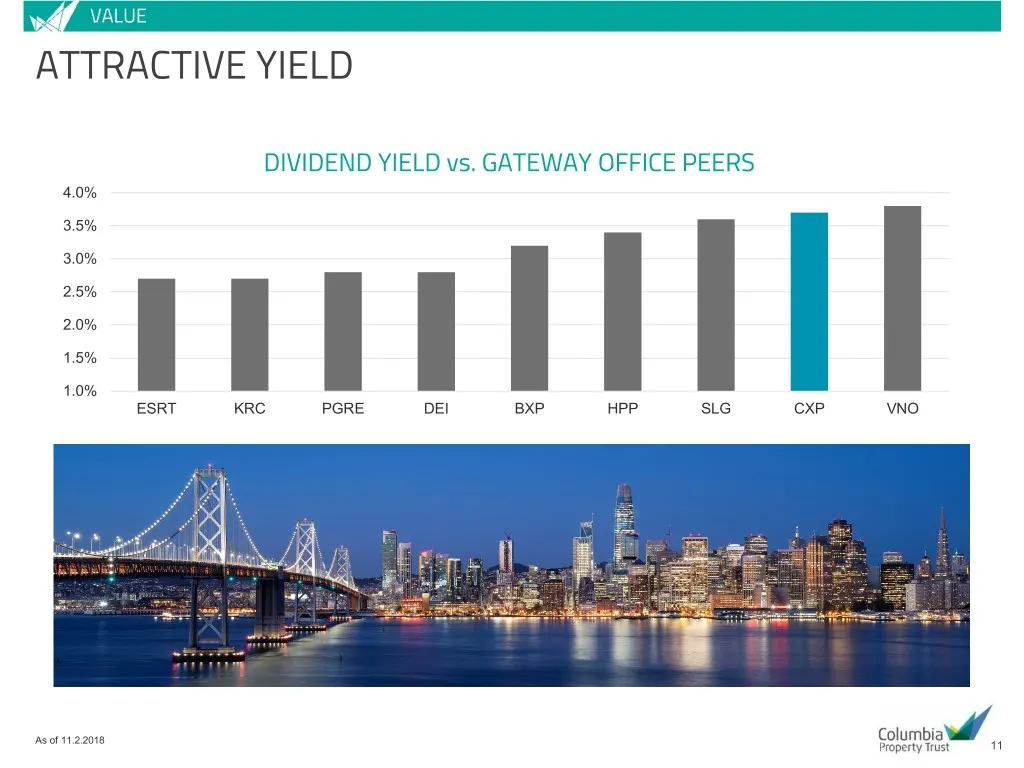
VALUE ATTRACTIVE YIELD DIVIDEND YIELD vs. GATEWAY OFFICE PEERS 4.0% 3.5% 3.0% 2.5% 2.0% 1.5% 1.0% ESRT KRC PGRE DEI BXP HPP SLG CXP VNO As of 11.2.2018 11
Slide 12: Stability: Limited Near-Term Rollover
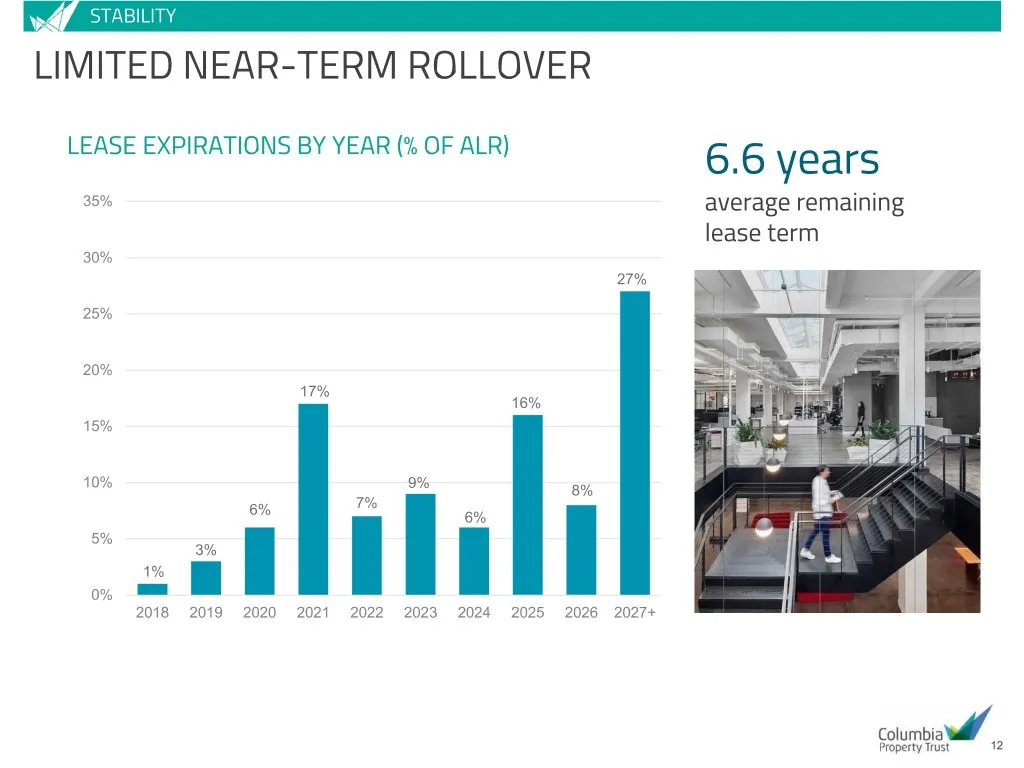
STABILITY LIMITED NEAR-TERM ROLLOVER LEASE EXPIRATIONS BY YEAR (% OF ALR) 6.6 years 35% average remaining lease term 30% 27% 25% 20% 17% 16% 15% 10% 9% 8% 6% 7% 6% 5% 3% 1% 0% 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027+ 12
Slide 13: Stability: Redeveloped Portfolio
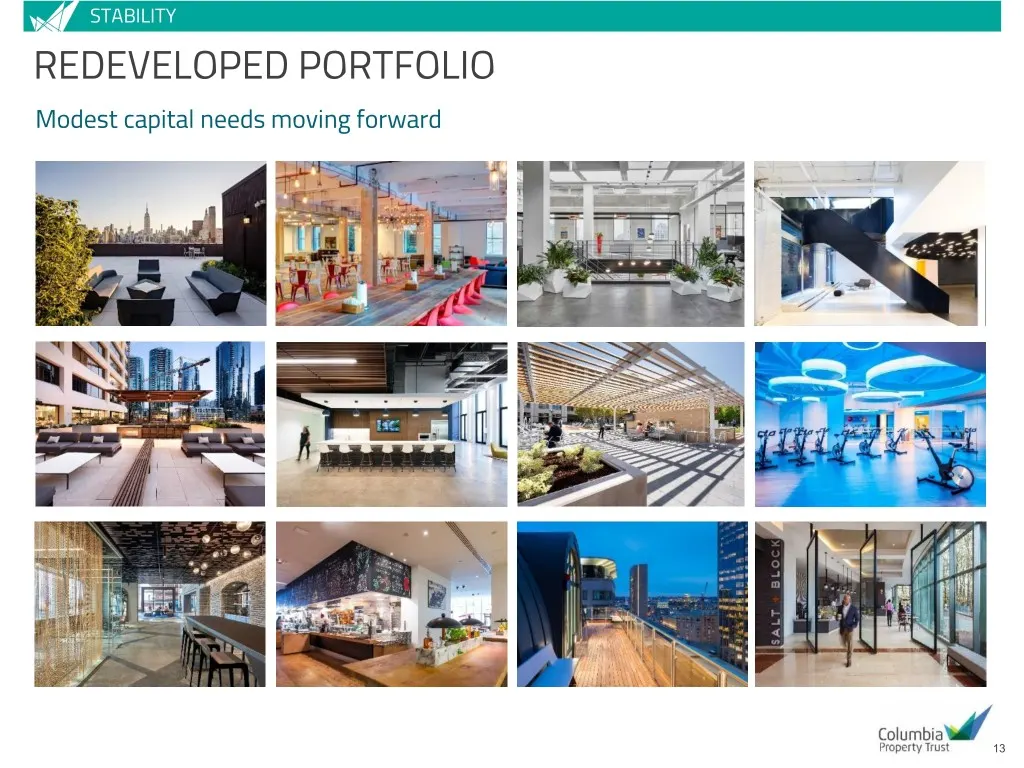
STABILITY REDEVELOPED PORTFOLIO Modest capital needs moving forward 13
Slide 14: Stability: Strong & Flexible Balance Sheet
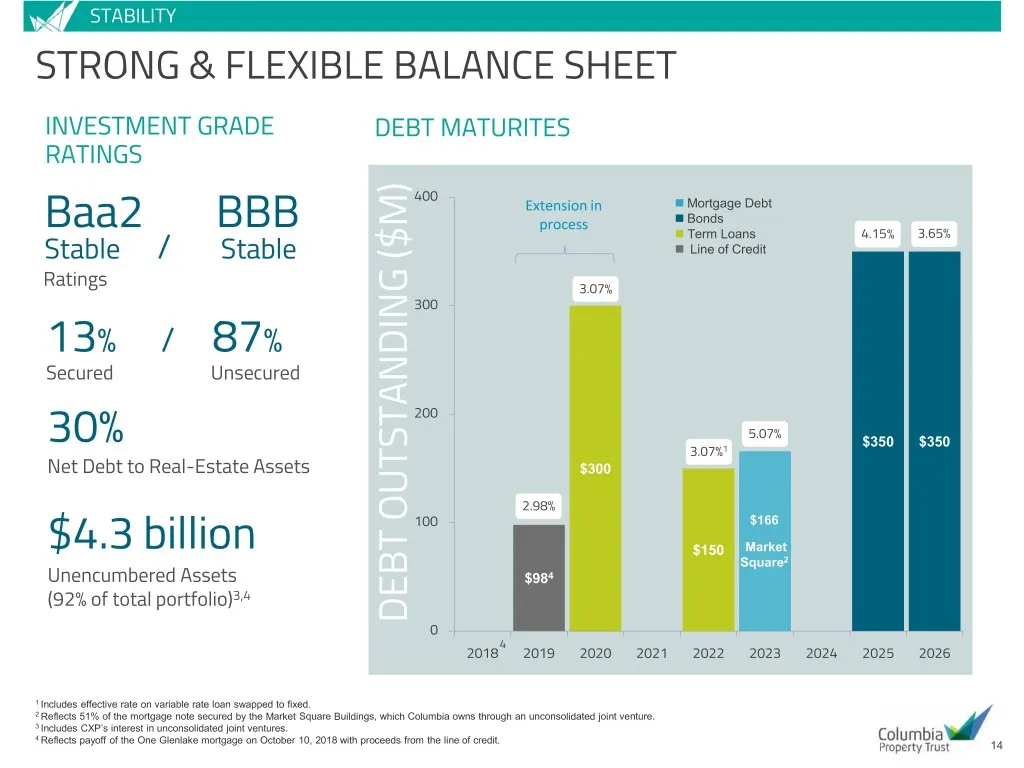
STABILITY STRONG & FLEXIBLE BALANCE SHEET INVESTMENT GRADE DEBT MATURITES RATINGS 400 Extension in Mortgage Debt process Bonds Baa2 BBB Term Loans 4.15% 3.65% Stable / Stable Line of Credit Ratings 3.07% 300 13% / 87% Secured Unsecured 200 5.07% 30% 1 $350 $350 3.07% Net Debt to Real-Estate
Slide 15: For More Information
APPENDIX FOR MORE INFORMATION Columbia Property Trust INVESTOR RELATIONS 404.465.2227 [email protected] www.columbia.reit 063-CORPPRES1808 15
Slide 16: Dramatic Cash Leasing Spreads
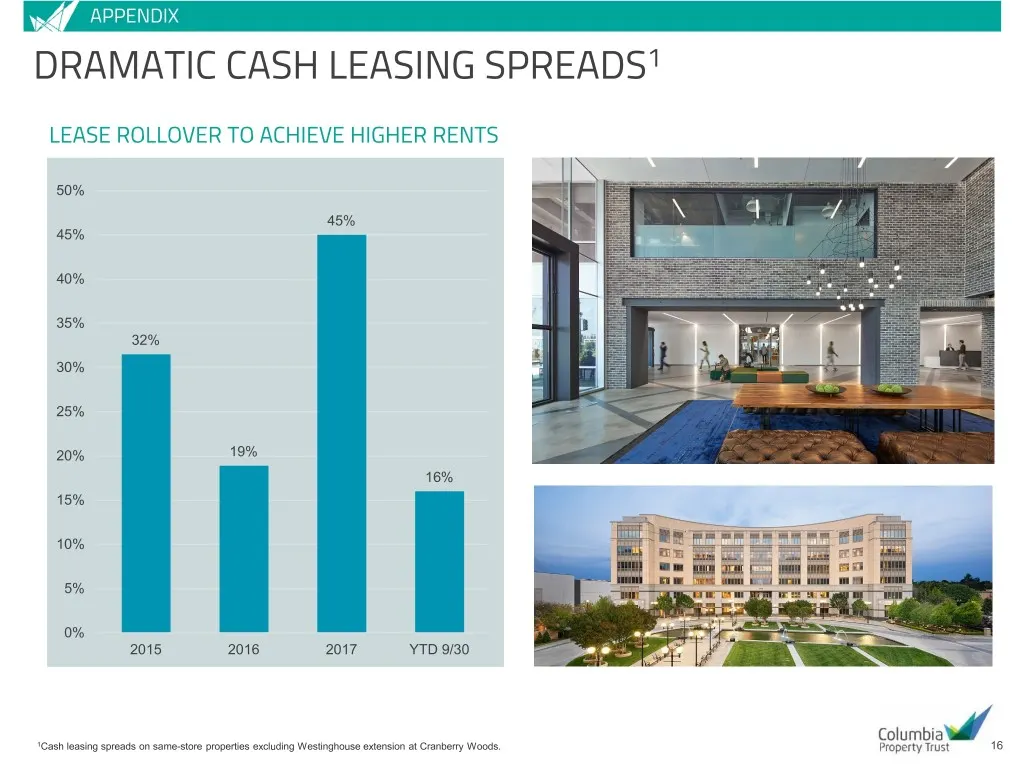
APPENDIX DRAMATIC CASH LEASING SPREADS1 LEASE ROLLOVER TO ACHIEVE HIGHER RENTS 50% 45% 45% 40% 35% 32% 30% 25% 20% 19% 16% 15% 10% 5% 0% 2015 2016 2017 YTD 9/30 1Cash leasing spreads on same-store properties excluding Westinghouse extension at Cranberry Woods. 16
Slide 17: Development Projects: 799 Broadway
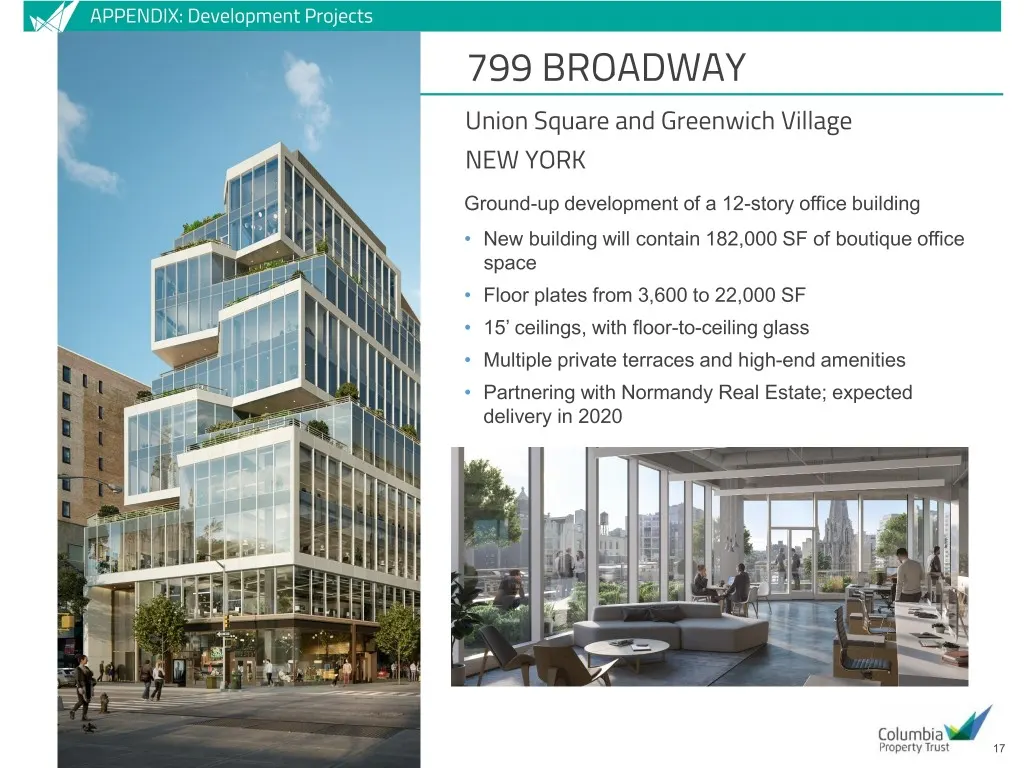
APPENDIX: Development Projects 799 BROADWAY Union Square and Greenwich Village NEW YORK Ground-up development of a 12-story office building • New building will contain 182,000 SF of boutique office space • Floor plates from 3,600 to 22,000 SF • 15’ ceilings, with floor-to-ceiling glass • Multiple pr
Slide 18: Development Projects: 149 Madison
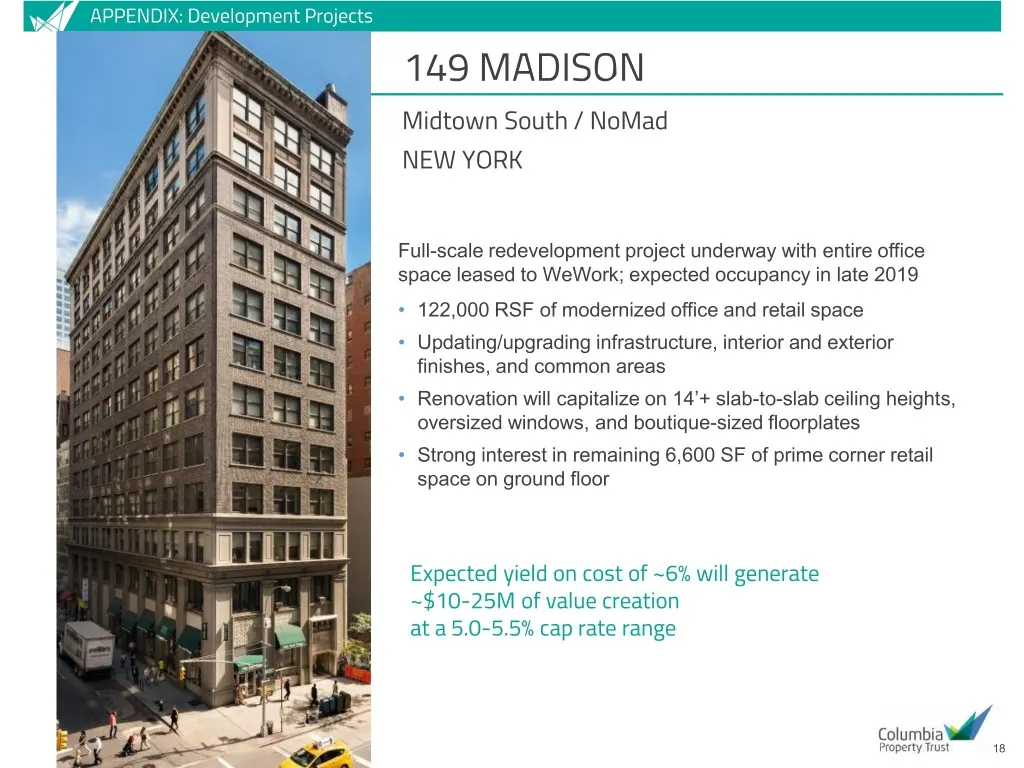
APPENDIX: Development Projects 149 MADISON Midtown South / NoMad NEW YORK Full-scale redevelopment project underway with entire office space leased to WeWork; expected occupancy in late 2019 • 122,000 RSF of modernized office and retail space • Updating/upgrading infrastructure, interior and exterio
Slide 19: Joint Venture with Allianz Real Estate
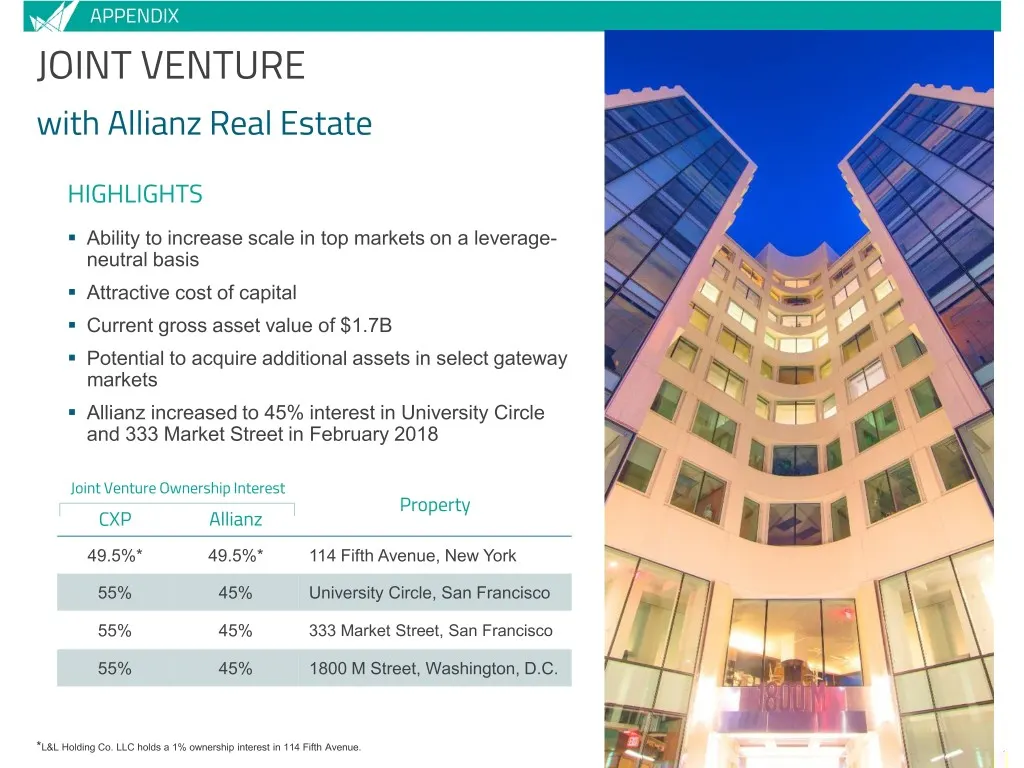
APPENDIX JOINT VENTURE with Allianz Real Estate HIGHLIGHTS . Ability to increase scale in top markets on a leverage- neutral basis . Attractive cost of capital . Current gross asset value of $1.7B . Potential to acquire additional assets in select gateway markets . Allianz increased to 45% interest
Slide 20: Executive and Corporate Operations Team
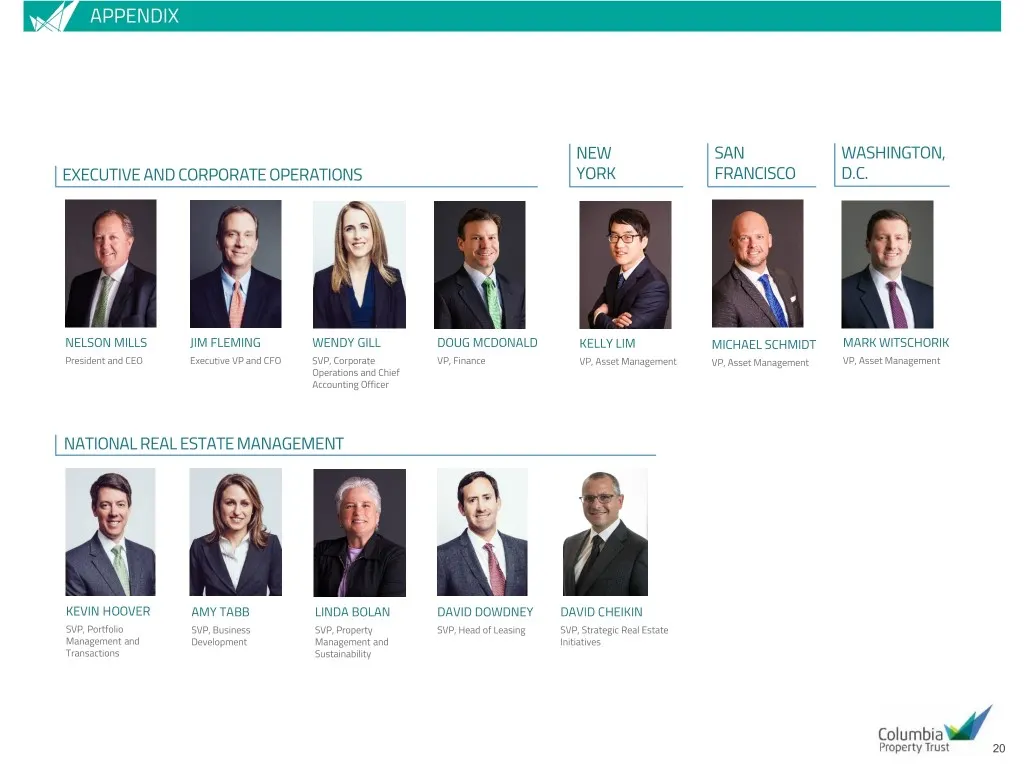
APPENDIX NEW SAN WASHINGTON, EXECUTIVE AND CORPORATE OPERATIONS YORK FRANCISCO D.C. NELSON MILLS JIM FLEMING WENDY GILL DOUG MCDONALD KELLY LIM MICHAEL SCHMIDT MARK WITSCHORIK President and CEO Executive VP and CFO SVP, Corporate VP, Finance VP, Asset Management VP, Asset Management VP, Asset Manage
Slide 21: Case Studies: 650 California Street
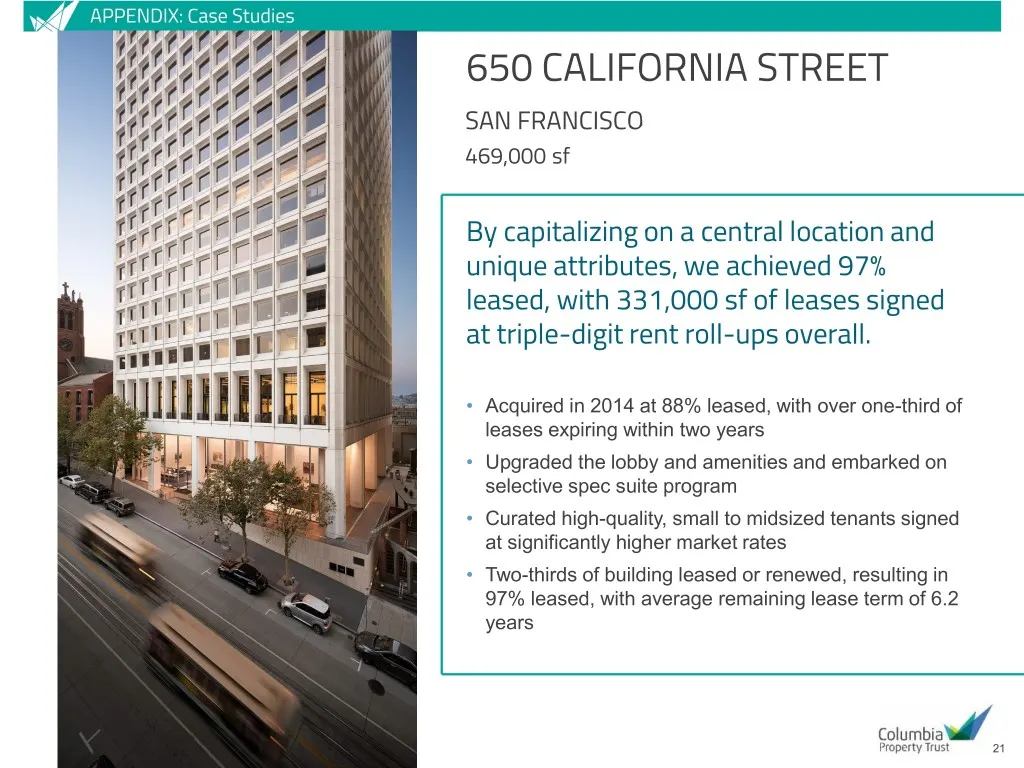
APPENDIX: Case Studies 650 CALIFORNIA STREET SAN FRANCISCO 469,000 sf By capitalizing on a central location and unique attributes, we achieved 97% leased, with 331,000 sf of leases signed at triple-digit rent roll-ups overall. • Acquired in 2014 at 88% leased, with over one-third of leases expiring
Slide 22: Case Studies: 315 Park Avenue South
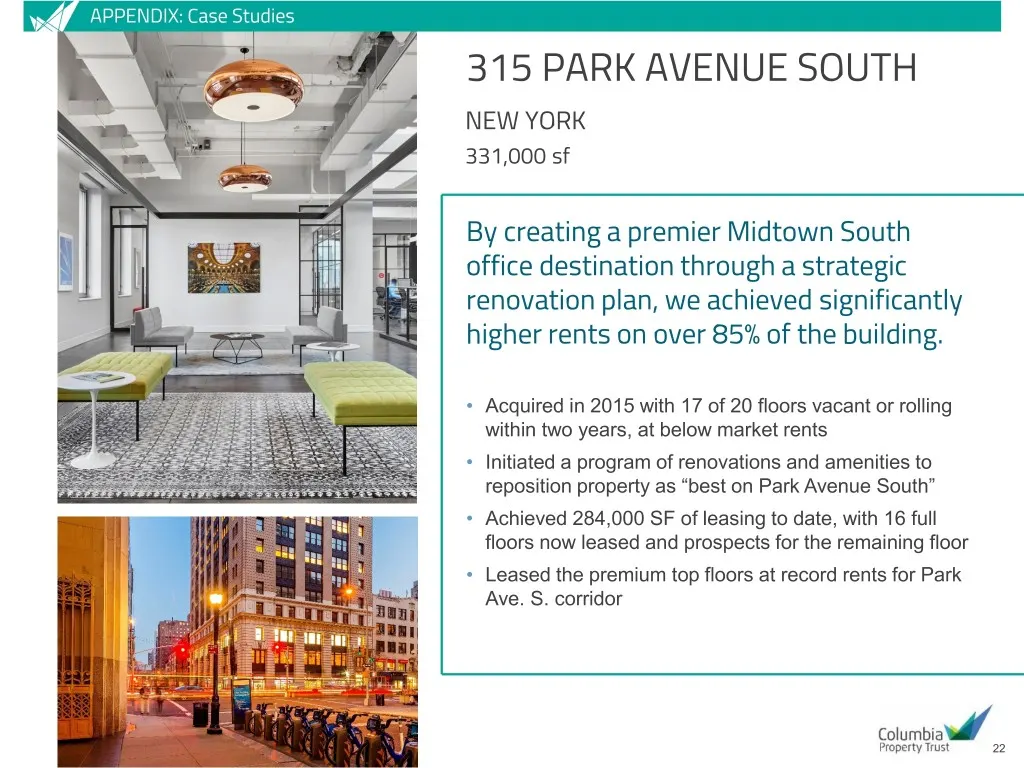
APPENDIX: Case Studies 315 PARK AVENUE SOUTH NEW YORK 331,000 sf By creating a premier Midtown South office destination through a strategic renovation plan, we achieved significantly higher rents on over 85% of the building. • Acquired in 2015 with 17 of 20 floors vacant or rolling within two years,
Slide 23: Case Studies: 221 Main Street
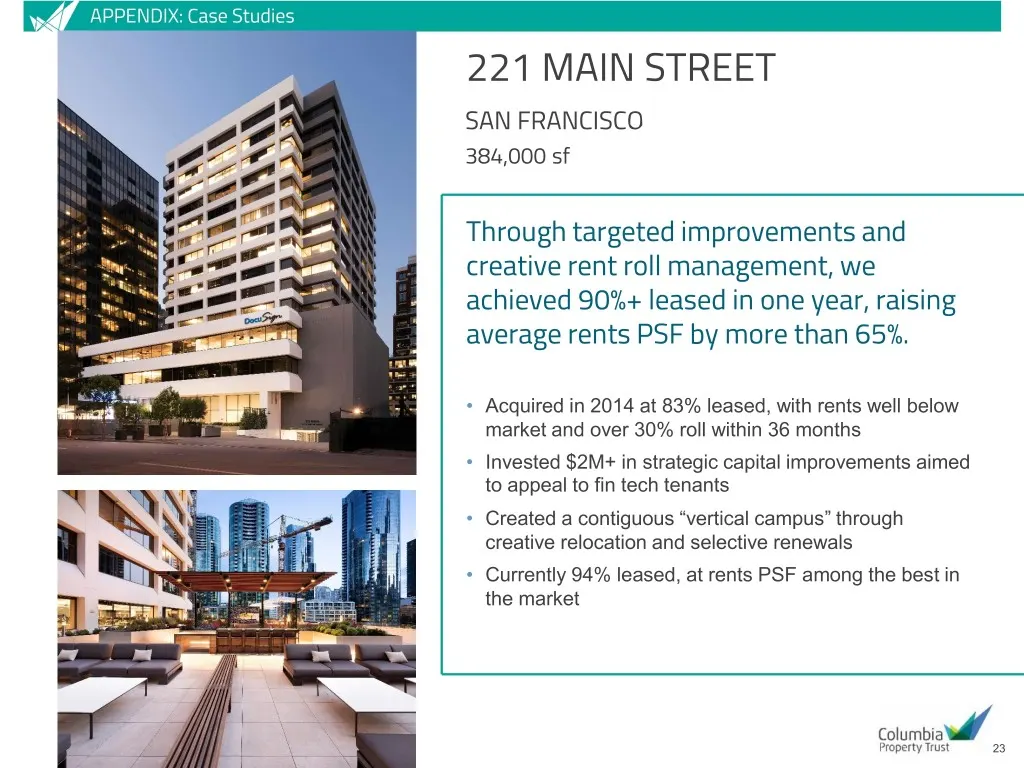
APPENDIX: Case Studies 221 MAIN STREET SAN FRANCISCO 384,000 sf Through targeted improvements and creative rent roll management, we achieved 90%+ leased in one year, raising average rents PSF by more than 65%. • Acquired in 2014 at 83% leased, with rents well below market and over 30% roll within 36
Slide 24: Case Studies: University Circle
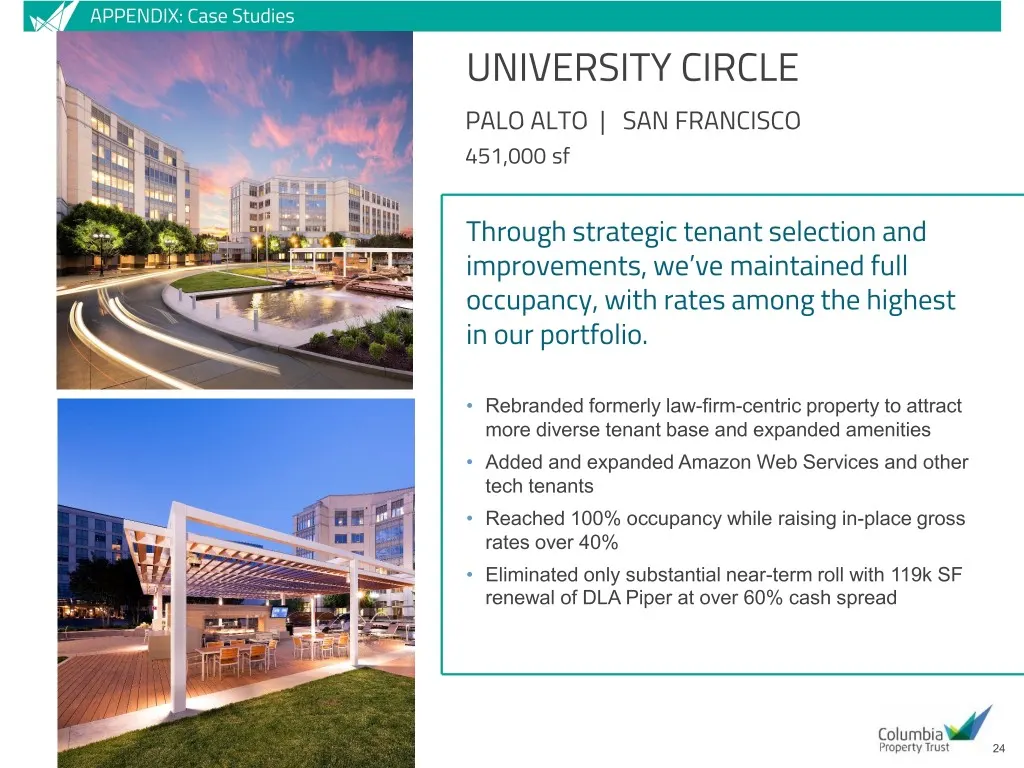
APPENDIX: Case Studies UNIVERSITY CIRCLE PALO ALTO | SAN FRANCISCO 451,000 sf Through strategic tenant selection and improvements, we’ve maintained full occupancy, with rates among the highest in our portfolio. • Rebranded formerly law-firm-centric property to attract more diverse tenant base and ex
Slide 25: Case Studies: One & Three Glenlake, 80 M Street
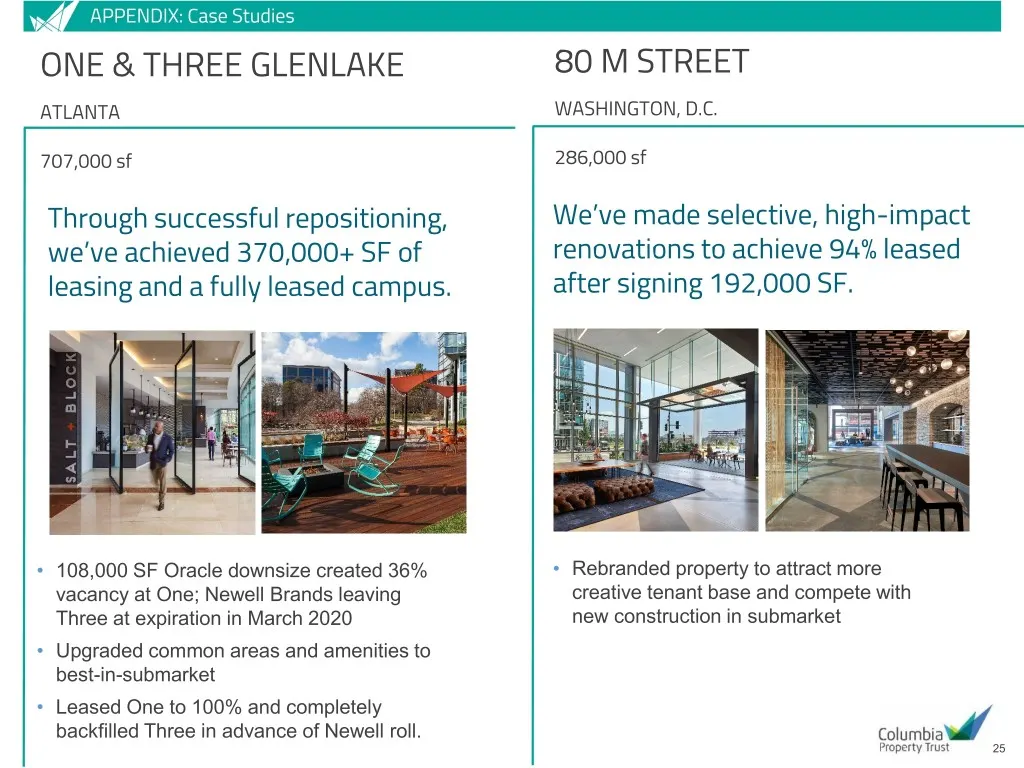
APPENDIX: Case Studies ONE & THREE GLENLAKE 80 M STREET ATLANTA WASHINGTON, D.C. 707,000 sf 286,000 sf Through successful repositioning, We’ve made selective, high-impact we’ve achieved 370,000+ SF of renovations to achieve 94% leased leasing and a fully leased campus. after signing 192,000 SF. • 10
Slide 26: Case Studies: 114 Fifth Avenue
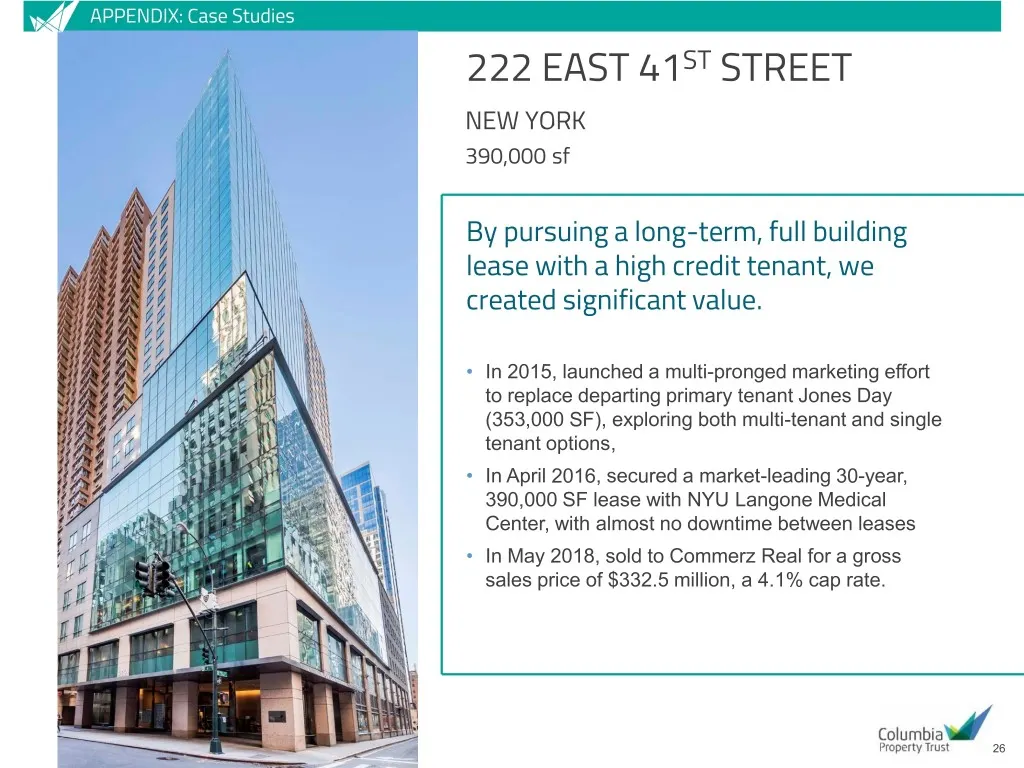
APPENDIX: Case Studies 222 EAST 41ST STREET NEW YORK 390,000 sf By pursuing a long-term, full building lease with a high credit tenant, we created significant value. • In 2015, launched a multi-pronged marketing effort to replace departing primary tenant Jones Day (353,000 SF), exploring both multi-
Slide 27: Reconciliations: Non-GAAP to Comparable GAAP Measures
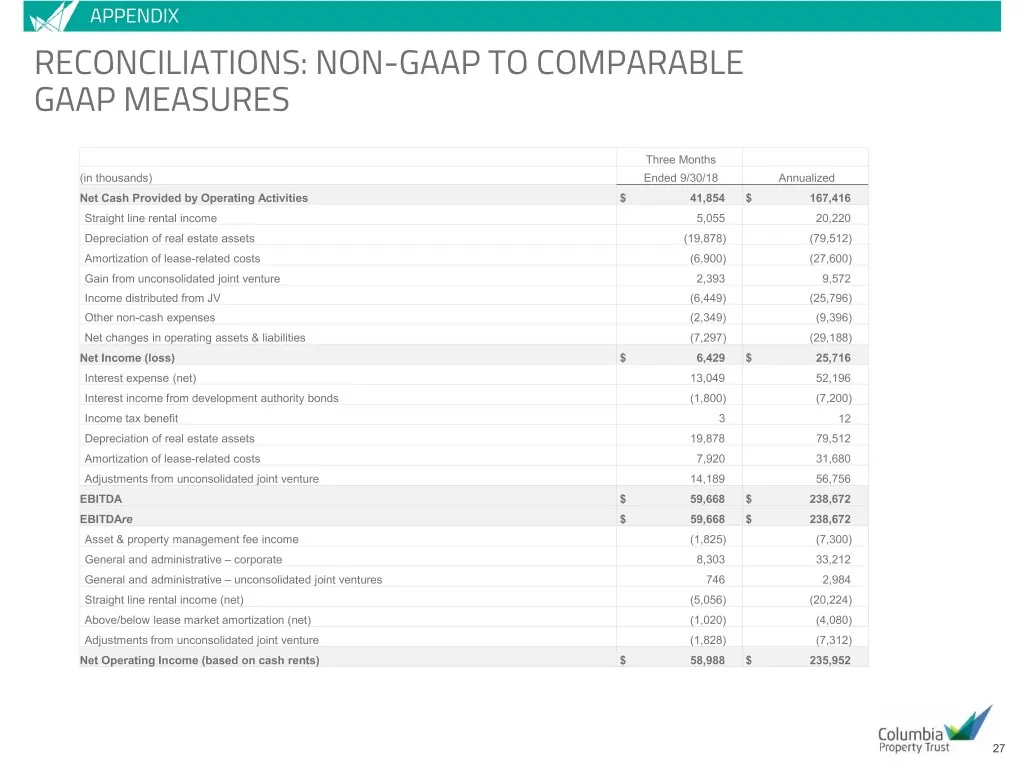
APPENDIX RECONCILIATIONS: NON-GAAP TO COMPARABLE GAAP MEASURES Three Months (in thousands) Ended 9/30/18 Annualized Net Cash Provided by Operating Activities $ 41,854 $ 167,416 Straight line rental income 5,055 20,220 Depreciation of real estate assets (19,878) (79,512) Amortization of lease-related
Slide 28: Reconciliations: Non-GAAP to Comparable GAAP Measures (continued)
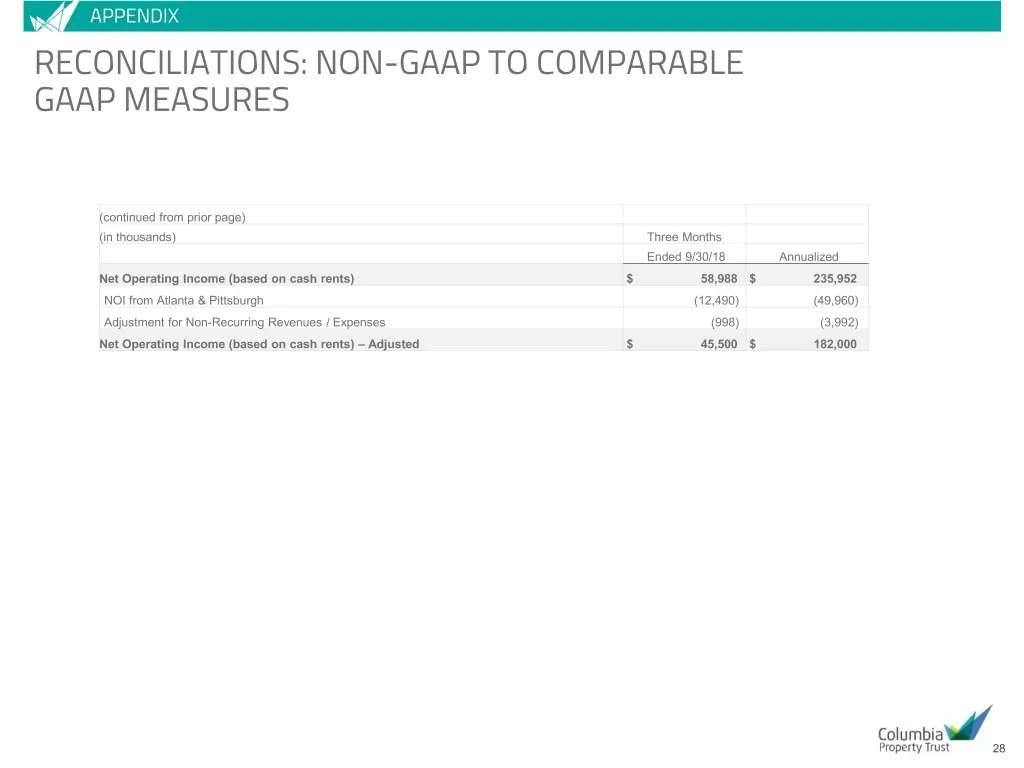
APPENDIX RECONCILIATIONS: NON-GAAP TO COMPARABLE GAAP MEASURES (continued from prior page) (in thousands) Three Months Ended 9/30/18 Annualized Net Operating Income (based on cash rents) $ 58,988 $ 235,952 NOI from Atlanta & Pittsburgh (12,490) (49,960) Adjustment for Non-Recurring Revenues / Expens
Source: SEC EDGAR · 8-K filed Nov 7, 2018
More decks from Columbia Property Trust Inc
 Investor Presentation (November 2020)33 slides · Nov 17, 2020
 Investor Presentation (August 2020)34 slides · Aug 31, 2020
 Investor Presentation (June 2020)34 slides · Jun 1, 2020
 Investor Presentation (February 2020)29 slides · Feb 26, 2020
 Corporate Update (December 2019)12 slides · Dec 3, 2019
 Investor Presentation (November 2019)28 slides · Nov 12, 2019