Discover Financial Services — 2014 BancAnalysts Association of Boston Conference
15 slides from Discover Financial Services's conference presentation, Nov 7, 2014
Slide 1: 2014 BancAnalysts Association of Boston Conference
2014 BancAnalysts Association of Boston Conference ©2014 DISCOVER FINANCIAL SERVICES Mark Graf EVP & Chief Financial Officer November 7, 2014 Exhibit 99.1
Slide 2: Notice
Notice The following slides are part of a presentation by Discover Financial Services (the "Company") and are intended to be viewed as part of that presentation. No representation is made that the information in these slides is complete. The presentation contains forward-looking statements. You are
Slide 3: Positioning to be the leading direct bank
Positioning to be the leading direct bank U.S. Card Issuing • $54Bn in card receivables • Leading cash rewards program • 1 in 4 U.S. households Deposits and Lending • $29Bn direct-to-consumer deposits • $13Bn personal loans and private student loans • $2.5Bn home loan originations • Home equity inst
Slide 4: U.S. Deposit Growth vs. Fed Funds Rate
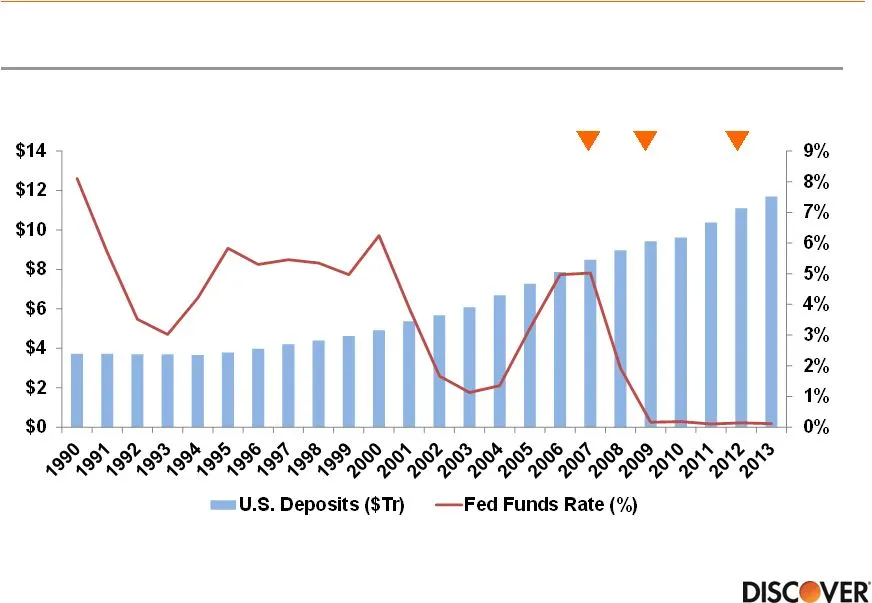
Discover Milestones: U.S. Deposit Growth vs. Fed Funds Rate Today - uncharted environment Source: Federal Reserve Board Flow of Funds and Fed Funds rate reported annually $28Bn DTC $13Bn DTC DFS Spin 1. Direct-to-consumer deposits (DTC); see Notice for complete definition
Slide 5: Deposits strategy – Great service and good pricing
Deposits strategy – Great service and good pricing • Segment: Savvy, value-oriented consumers • Value Proposition Outstanding service and convenience Consistently good rates • Execution Path Expand product breadth with distinctive offerings over time Enhance product features and functionality Integr
Slide 6: Preference for direct channels has grown among consumers
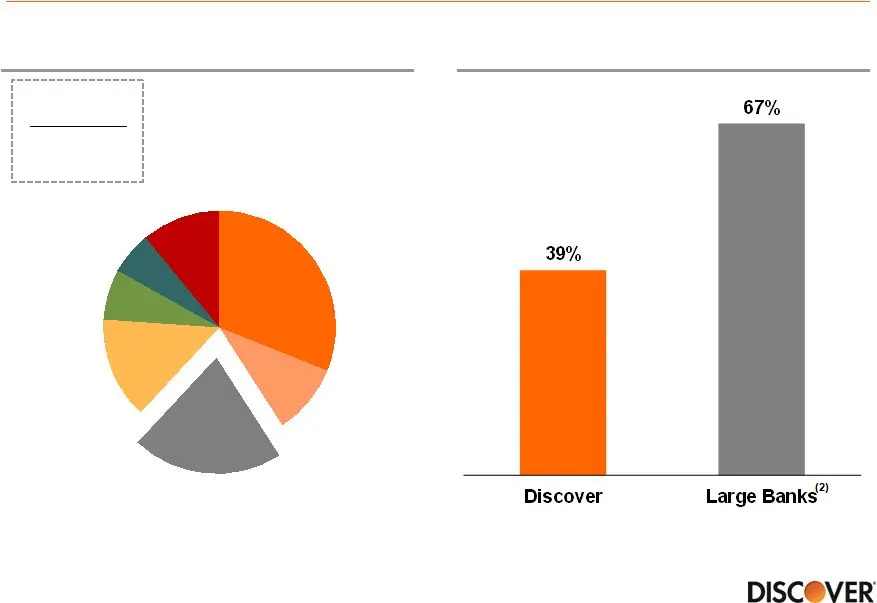
2013 Efficiency Ratio Preference for direct channels has grown among consumers Preferred Banking Channel Source: American Bankers Association Survey Branch Preference 2008: 34% 2014: 21% Source: SNL 1. Total operating expenses divided by revenue net of interest expense 2. Bank holding companies part
Slide 7: Funding asset growth with deposits
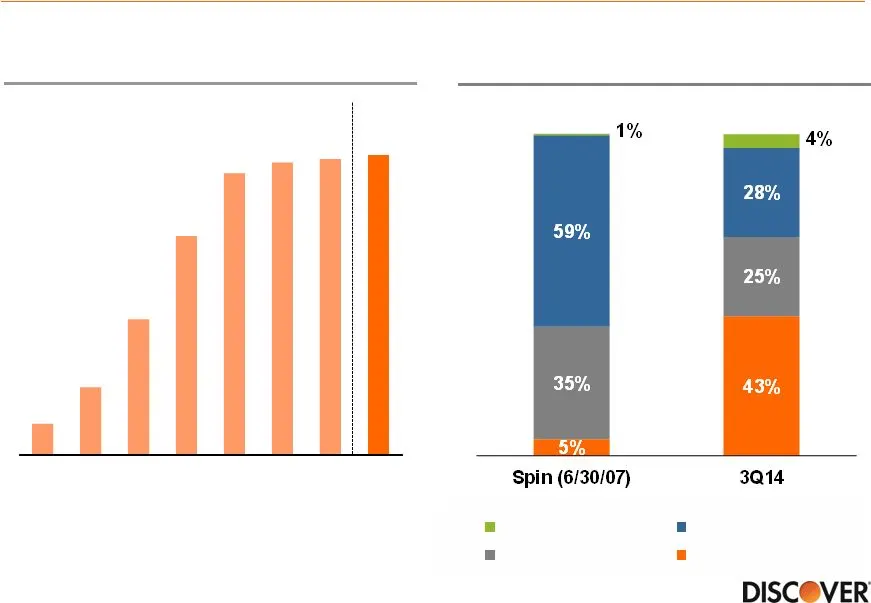
Funding asset growth with deposits Direct-to-Consumer Deposits ($Bn) Funding Mix 1. Includes affinity deposits Senior Bank Notes ABS and Other Brokered Deposits Direct Deposits $3 $7 $13 $21 $27 $28 $28 $29 3Q14
Slide 8: Pricing to balance growth and stability of book
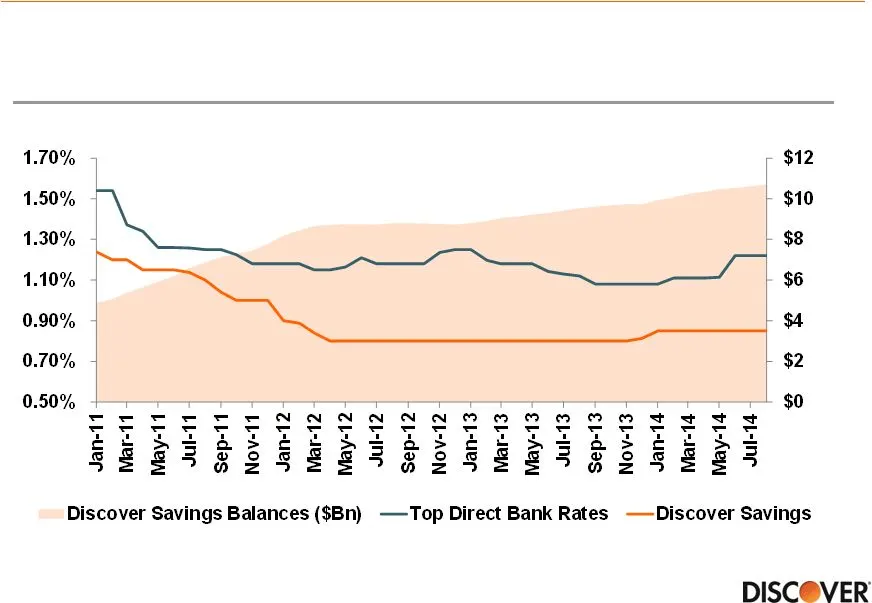
Pricing to balance growth and stability of book Discover Savings Rate vs. Top Direct Bank Rates 1. Data set through August 2014; Top Direct Bank Rates reflects monthly average of top three rates posted online weekly by banks without a traditional branch network Source: Internal data & Informa Resear
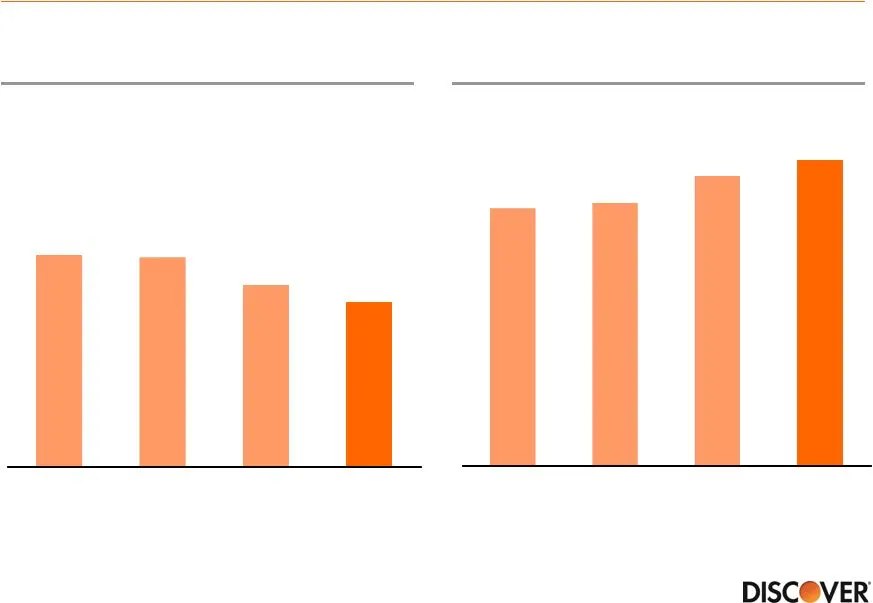
Slide 9: Optimizing product mix to manage rate sensitivity
Optimizing product mix to manage rate sensitivity Indeterminate Balances Acquired at 10%+ Above Competitor Rates (1,2) Indeterminate Balances as a % of Deposits Portfolio 1. Indeterminate Balances defined as savings and money market balances 2. Competitor Rates reflects monthly average of rates post
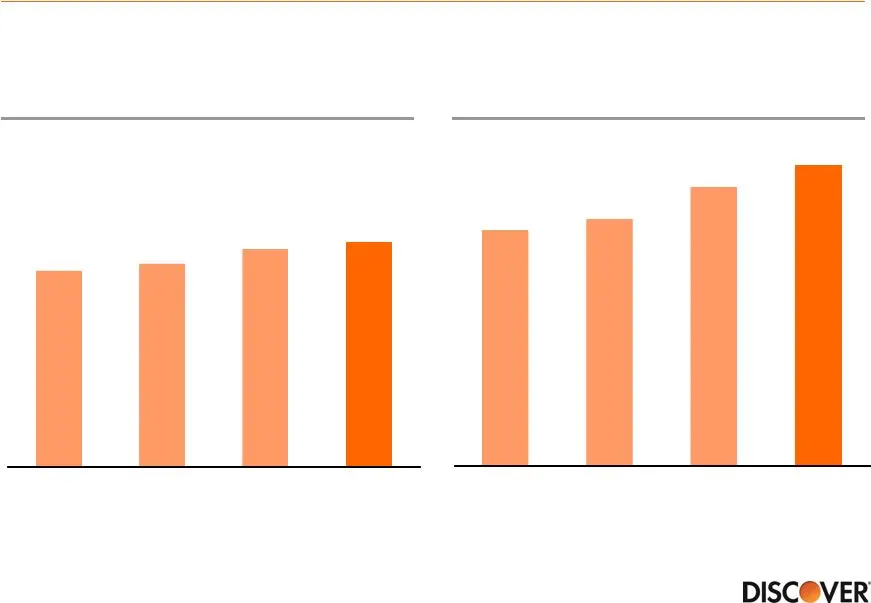
Slide 10: Optimizing customer mix to manage rate sensitivity
Optimizing customer mix to manage rate sensitivity 1.2014 YTD is as of 9/30/2014 Deposits from Card or Affinity Customers (% of Total) New Deposit Accounts Opened by Card or Affinity Customers (% of Total) 66% 69% 78% 84% 2014 YTD 54% 56% 60% 62% 2014 YTD
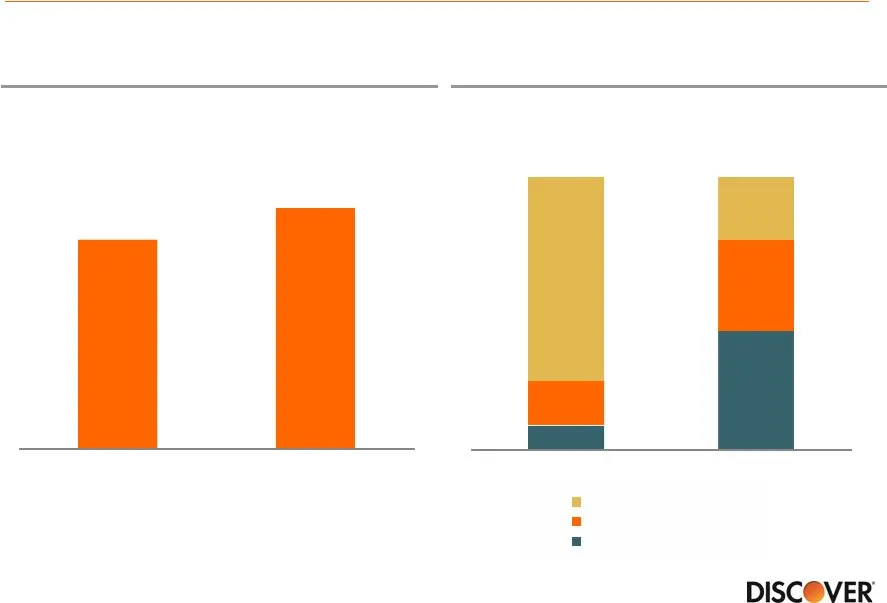
Slide 11: Positive trends in depositor behavior
9% 44% Positive trends in depositor behavior DTC Balances by Life of Relationship CD Retention Rates $21Bn $29Bn 1. CD retention rates based on direct-to-consumer CDs; excludes brokered CDs 2. 2014 YTD is as of 9/30/2014 78% 82% 2014 YTD 16% 33% 75% 23% 2014 YTD Less than 2 Years 2 to 4 Years Over 4
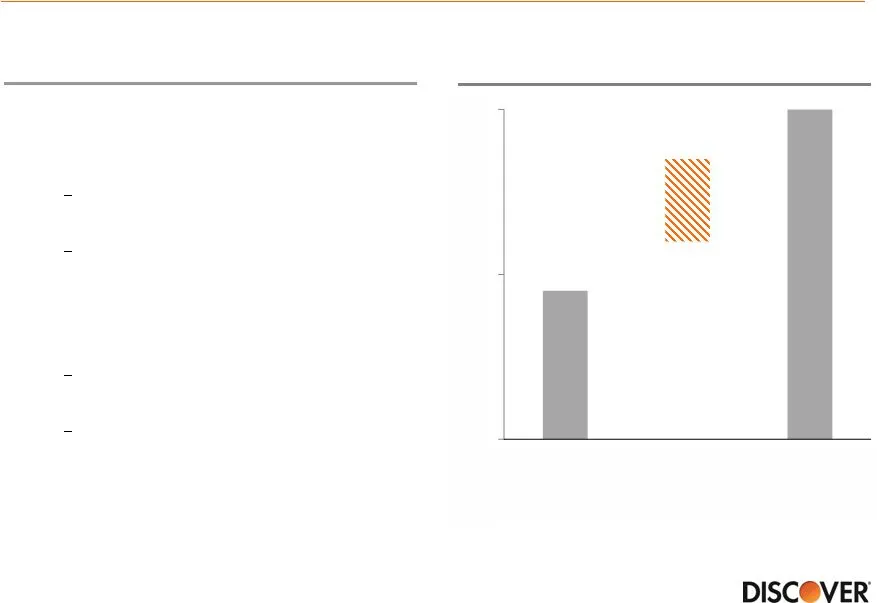
Slide 12: Our beta will be higher than a traditional bank but not 1
Our beta will be higher than a “traditional” bank but not “1” DFS vs. Traditional Bank Illustrative Betas • Similar to “traditional” bank, strong synergy between right and left hand side of balance sheet 62% of current accounts have a loan product relationship with DFS 78% of new accounts have a loa
Slide 13: Establish core banking presence with checking product
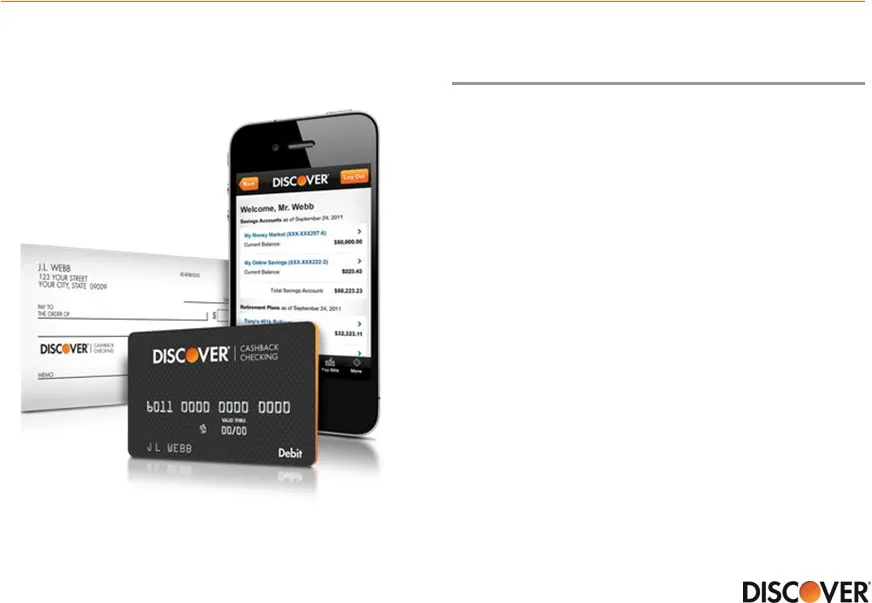
• Achieves cost of funds benefit in a rising rate environment • Deepens customer relationships given transactional nature of product • Delivers richer product features and better value given lower direct banking cost structure • Leverages Discover and PULSE networks Establish core banking presence a
Slide 14: Strong digital presence with great customer service is key
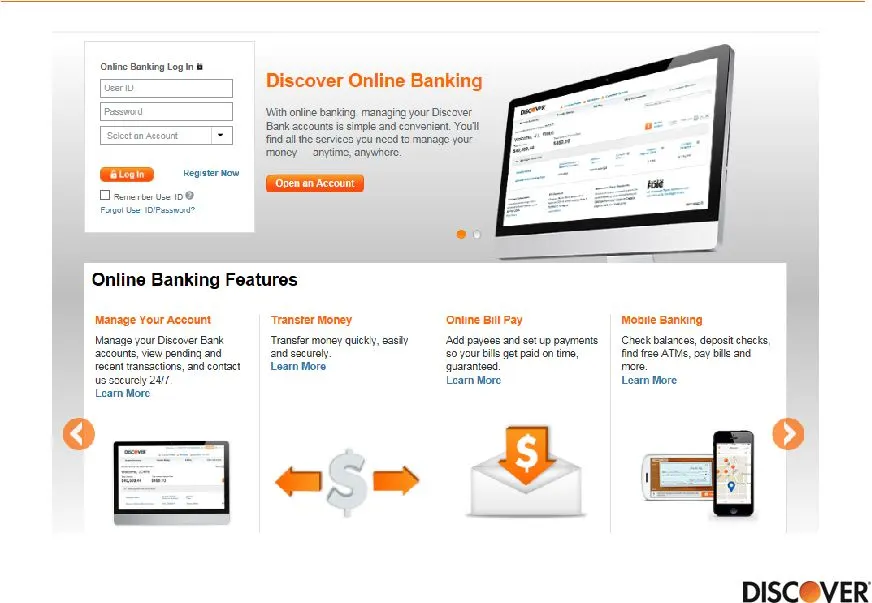
Strong digital presence with great customer service is key
Slide 15: Summary
Summary • Utilizing all current funding channels • Focusing on funding that is favorable in terms of cost, beta, liquidity and term • Committed to DTC funding channel as a large percentage of funding mix • Focusing on product mix and customer retention to prepare for rising rate environment
Source: SEC EDGAR · 8-K filed Nov 7, 2014
More decks from Discover Financial Services
 Q1 2025 Earnings Presentation15 slides · Apr 23, 2025
 Q4 2024 Earnings Presentation17 slides · Jan 22, 2025
 Q3 2024 Earnings Presentation17 slides · Oct 16, 2024
 Q2 2024 Earnings Presentation17 slides · Jul 17, 2024
 Q1 2024 Earnings Presentation17 slides · Apr 17, 2024
 Merger or Acquisition (February 2024)27 slides · Feb 20, 2024