Gulfmark Offshore — Capital One Southcoast 2009 Energy Conference
18 slides from Gulfmark Offshore's conference presentation, Dec 9, 2009
Slide 1: GulfMark Offshore, Inc: 20 Years of Making Waves
GulfMark Offshore, Inc: 20 Years of Making WavesCapital One Southcoast 2009 Energy Conference December 2009
Slide 2: Cautionary Statement Regarding Forward-Looking Statements
Cautionary Statement Regarding Forward-Looking Statements This presentation includes forward-looking statements and projections, made in reliance on the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. The Company has made every reasonable effort to ensure that the inf
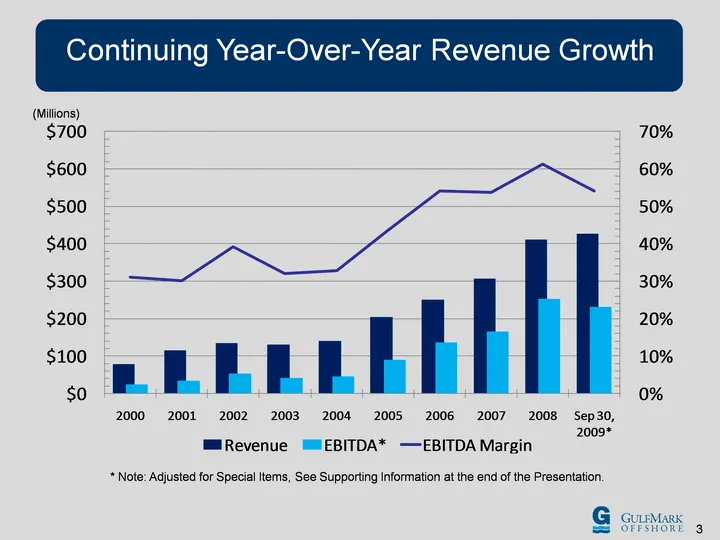
Slide 3: Continuing Year-Over-Year Revenue Growth
Continuing Year-Over-Year Revenue Growth (Millions) * Note: Adjusted for Special Items, See Supporting Information at the end of the Presentation.
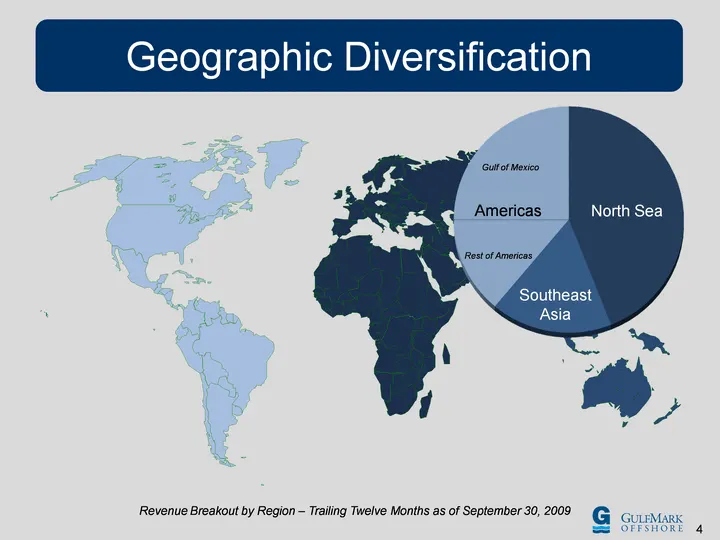
Slide 4: Geographic Diversification
4 Geographic Diversification Revenue Breakout by Region - Trailing Twelve Months as of September 30, 2009 North Sea SoutheastAsia Americas Rest of Americas Gulf of Mexico
Slide 5: North Sea Regional
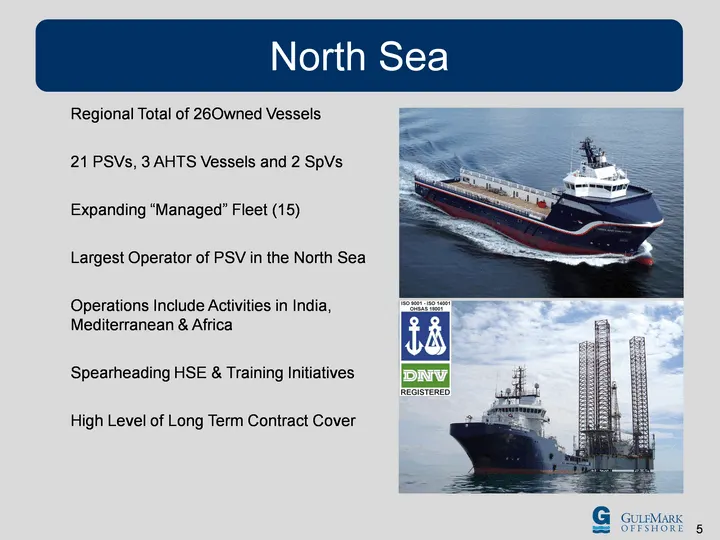
North Sea Regional Total of 26Owned Vessels21 PSVs, 3 AHTS Vessels and 2 SpVsExpanding "Managed" Fleet (15)Largest Operator of PSV in the North SeaOperations Include Activities in India, Mediterranean & AfricaSpearheading HSE & Training InitiativesHigh Level of Long Term Contract Cover
Slide 6: Americas Regional
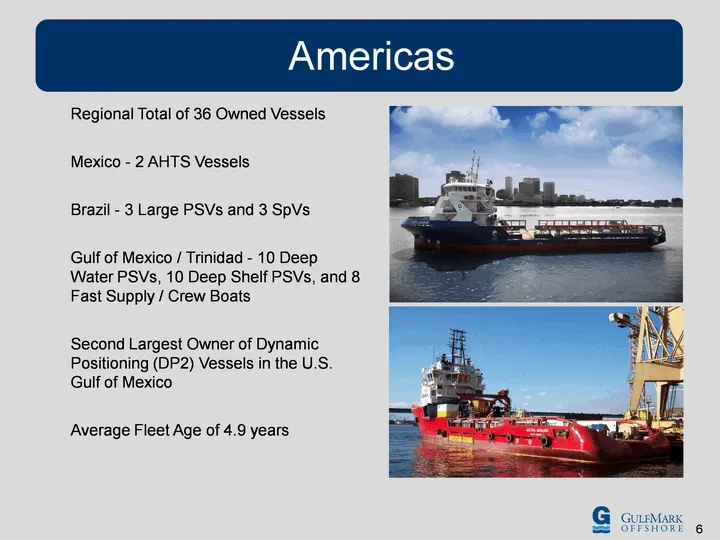
Americas Regional Total of 36 Owned Vessels Mexico - 2 AHTS Vessels Brazil - 3 Large PSVs and 3 SpVsGulf of Mexico / Trinidad - 10 Deep Water PSVs, 10 Deep Shelf PSVs, and 8 Fast Supply / Crew Boats Second Largest Owner of Dynamic Positioning (DP2) Vessels in the U.S. Gulf of MexicoAverage Fleet Age
Slide 7: Southeast Asia
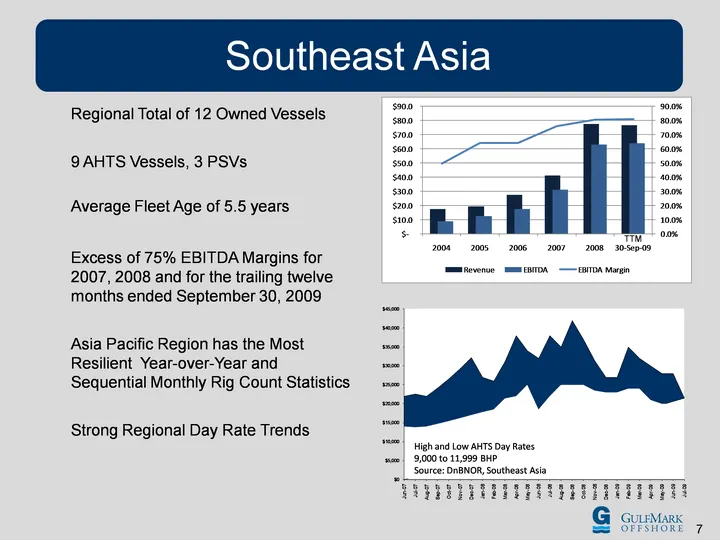
Southeast Asia High and Low AHTS Day Rates9,000 to 11,999 BHPSource: DnBNOR, Southeast Asia TTM Regional Total of 12 Owned Vessels 9 AHTS Vessels, 3 PSVsAverage Fleet Age of 5.5 yearsExcess of 75% EBITDA Margins for 2007, 2008 and for the trailing twelve months ended September 30, 2009Asia Pacific R
Slide 8: Strong Customer Base
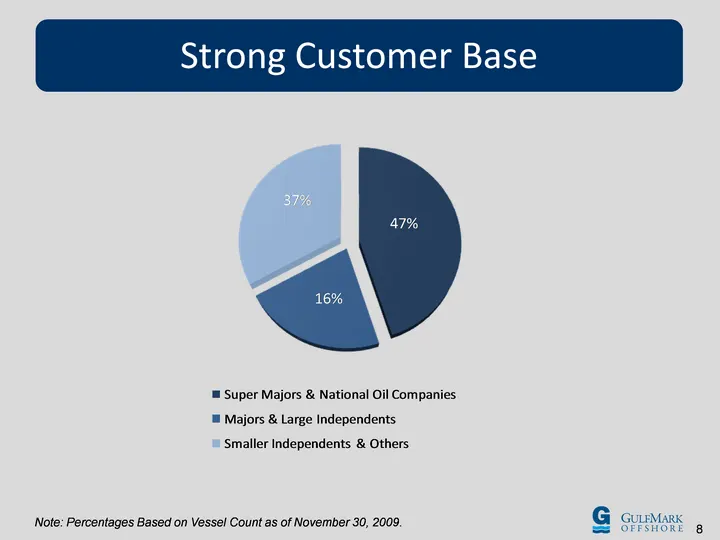
Strong Customer Base Note: Percentages Based on Vessel Count as of November 30, 2009.
Slide 9: The GulfMark Fleet
The GulfMark Fleet if) GULEMaRK SEBNORE 9
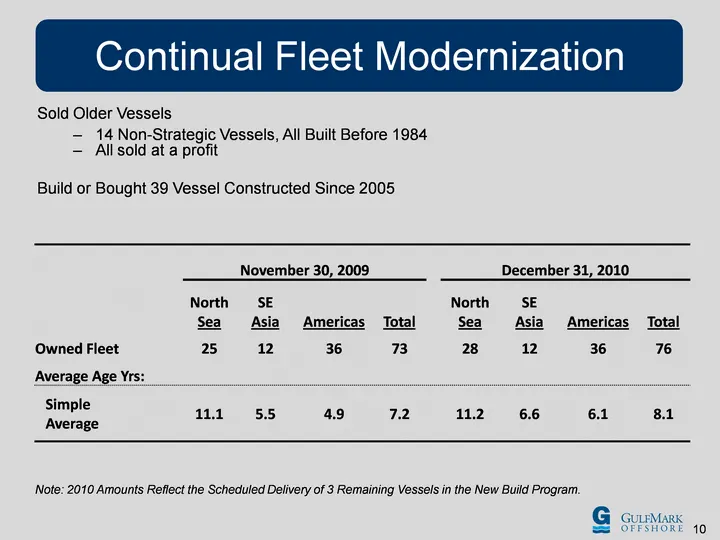
Slide 10: Continual Fleet Modernization
Note: 2010 Amounts Reflect the Scheduled Delivery of 3 Remaining Vessels in the New Build Program. November 30, 2009 November 30, 2009 November 30, 2009 November 30, 2009 December 31, 2010 December 31, 2010 December 31, 2010 December 31, 2010 NorthSea SEAsia Americas Total NorthSea SEAsia Americas T
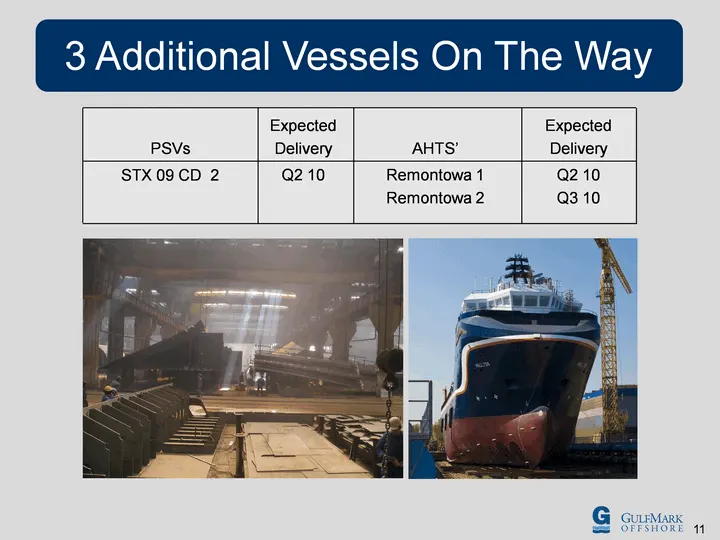
Slide 11: 3 Additional Vessels On The Way
PSVs ExpectedDelivery AHTS' ExpectedDelivery STX 09 CD 2 Q2 10 Remontowa 1Remontowa 2 Q2 10Q3 10 3 Additional Vessels On The Way
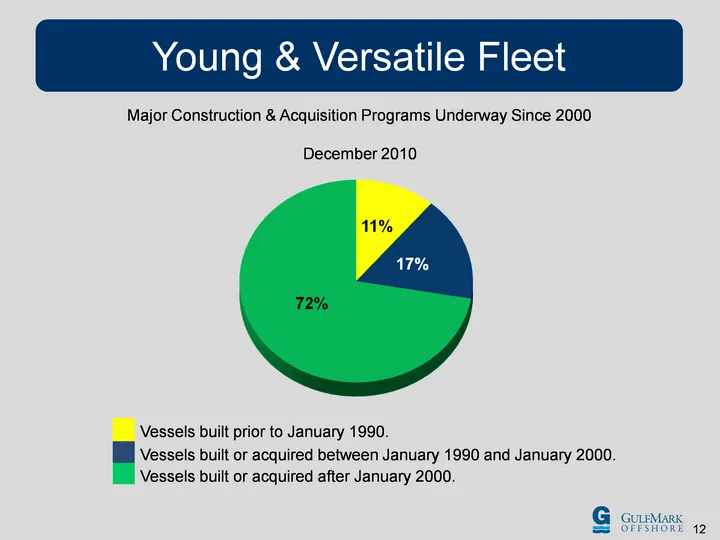
Slide 12: Young & Versatile Fleet
December 2010 Vessels built prior to January 1990. Vessels built or acquired between January 1990 and January 2000. Vessels built or acquired after January 2000. Young & Versatile Fleet Major Construction & Acquisition Programs Underway Since 2000
Slide 13: Financial Information
Financial Information
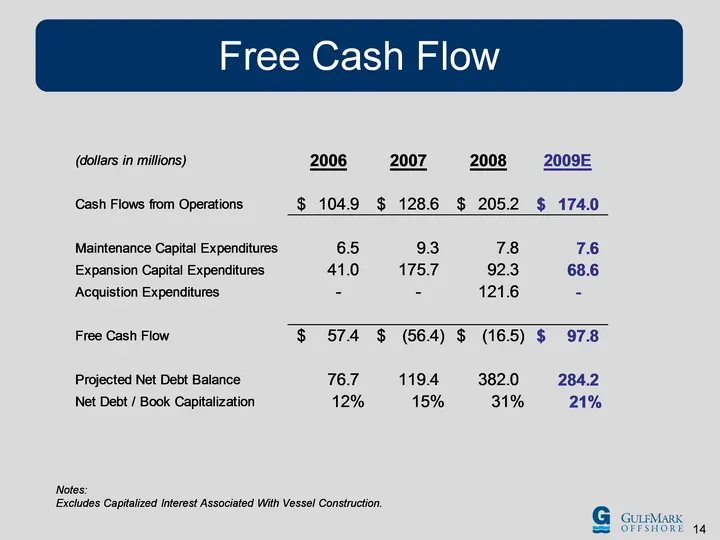
Slide 14: Free Cash Flow
Notes: Excludes Capitalized Interest Associated With Vessel Construction. Free Cash Flow
Slide 15: Vessel Cash Operating Margin
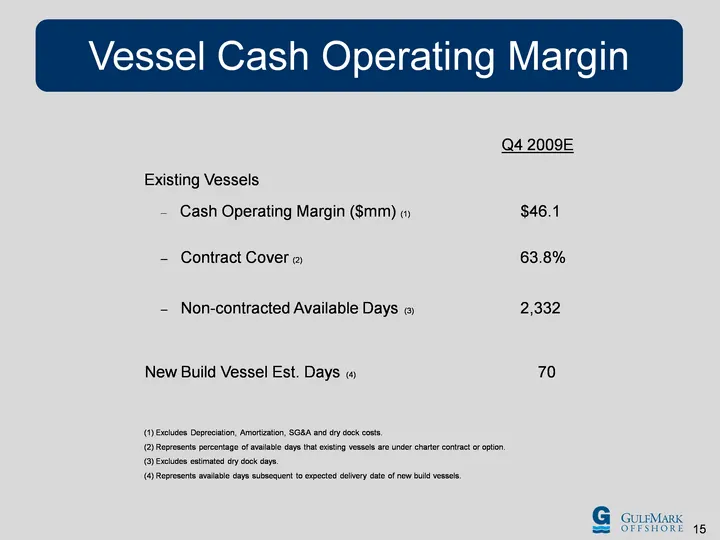
Vessel Cash Operating Margin (1) Excludes Depreciation, Amortization, SG&A and dry dock costs.(2) Represents percentage of available days that existing vessels are under charter contract or option.(3) Excludes estimated dry dock days.(4) Represents available days subsequent to expected delivery date
Slide 16: Investment Highlights
Industry Leaders in HSE Performance & People DevelopmentStrong Demand for Modern Offshore Marine Equipment Global Presence and Operations ExpertiseFinancial Stability & Flexibility to Pursue OpportunitiesGrowth though Acquisition and New ConstructionYoung, Versatile, High-Specification Fleet Investm
Slide 17: GulfMark Offshore
G GULEMARK OFFSHORE
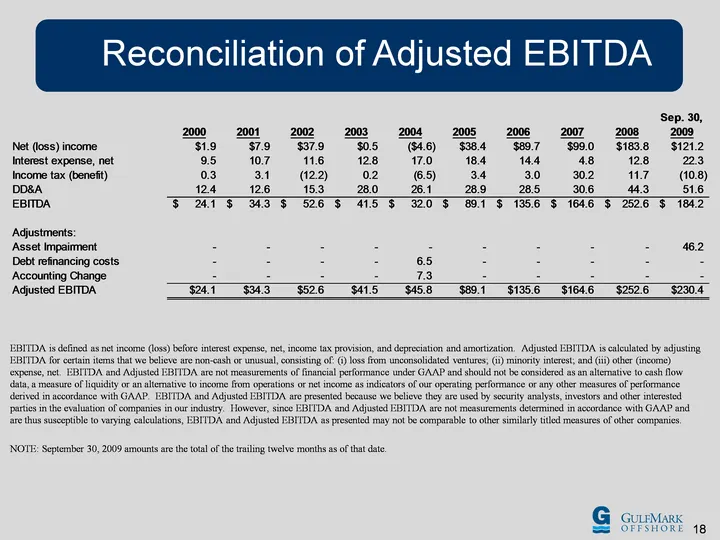
Slide 18: EBITDA and Adjusted EBITDA definitions
EBITDA is defined as net income (loss) before interest expense, net, income tax provision, and depreciation and amortization. Adjusted EBITDA is calculated by adjusting EBITDA for certain items that we believe are non-cash or unusual, consisting of: (i) loss from unconsolidated ventures; (ii) minori
Source: SEC EDGAR · 8-K filed Dec 9, 2009
More decks from Gulfmark Offshore Inc
 Merger or Acquisition (July 2018)11 slides · Jul 16, 2018
 Merger or Acquisition (July 2018)15 slides · Jul 16, 2018
 Investor Presentation (March 2018)22 slides · Mar 6, 2018
 Debt Investor Presentation (October 2017)16 slides · Oct 2, 2017
 Debt Investor Presentation (May 2017)41 slides · May 18, 2017
 Debt Investor Presentation (November 2016)28 slides · Nov 28, 2016