United Financial Bancorp — Rockville Financial — FIG Partners' Bank CEO Forum (September 2012)
39 slides from United Financial Bancorp's conference presentation, Sep 20, 2012
Slide 1: Transition to Growth - FIG Partners' Bank CEO Forum
Exhibit 99.1 Transition NASDAQ RCKB September •Global ValuesSelect 20, • Success 2012 Market FIG Partners’ Bank CEO Forum
Slide 2: Forward-Looking Statements
Forward This management and statements are update forward-looking With 2presented beyond future Presentation regard forward-looking Looking in or can involve our to this and conditional presentations be control nature presentation are contains Statements identified risks subject — we statements and
Slide 3: Table of Contents
TableRockville Why Page Infrastructure Recent Strategic Financial Municipal Loans Deposits Asset Institutional Insider 3Appendix—Peer of Quality 21Strategic Ownership Contents 25 Priorities Performance Bond Ownership Investment 30Financial Portfolio Initiatives Analysis 34 11 14325619 35 10
Slide 4: Corporate Contacts
Corporate William President Scott John Mark Executive Eric Investor Senior 4860-291-3622 R. T. C. A.Vice Newell Lund Bechtle H. Information: Kucia &Vice Contacts W. President, Chief or Crawford, President, [email protected] Executive Marliese Director Investor IV Chief Commercial Officer L. Re
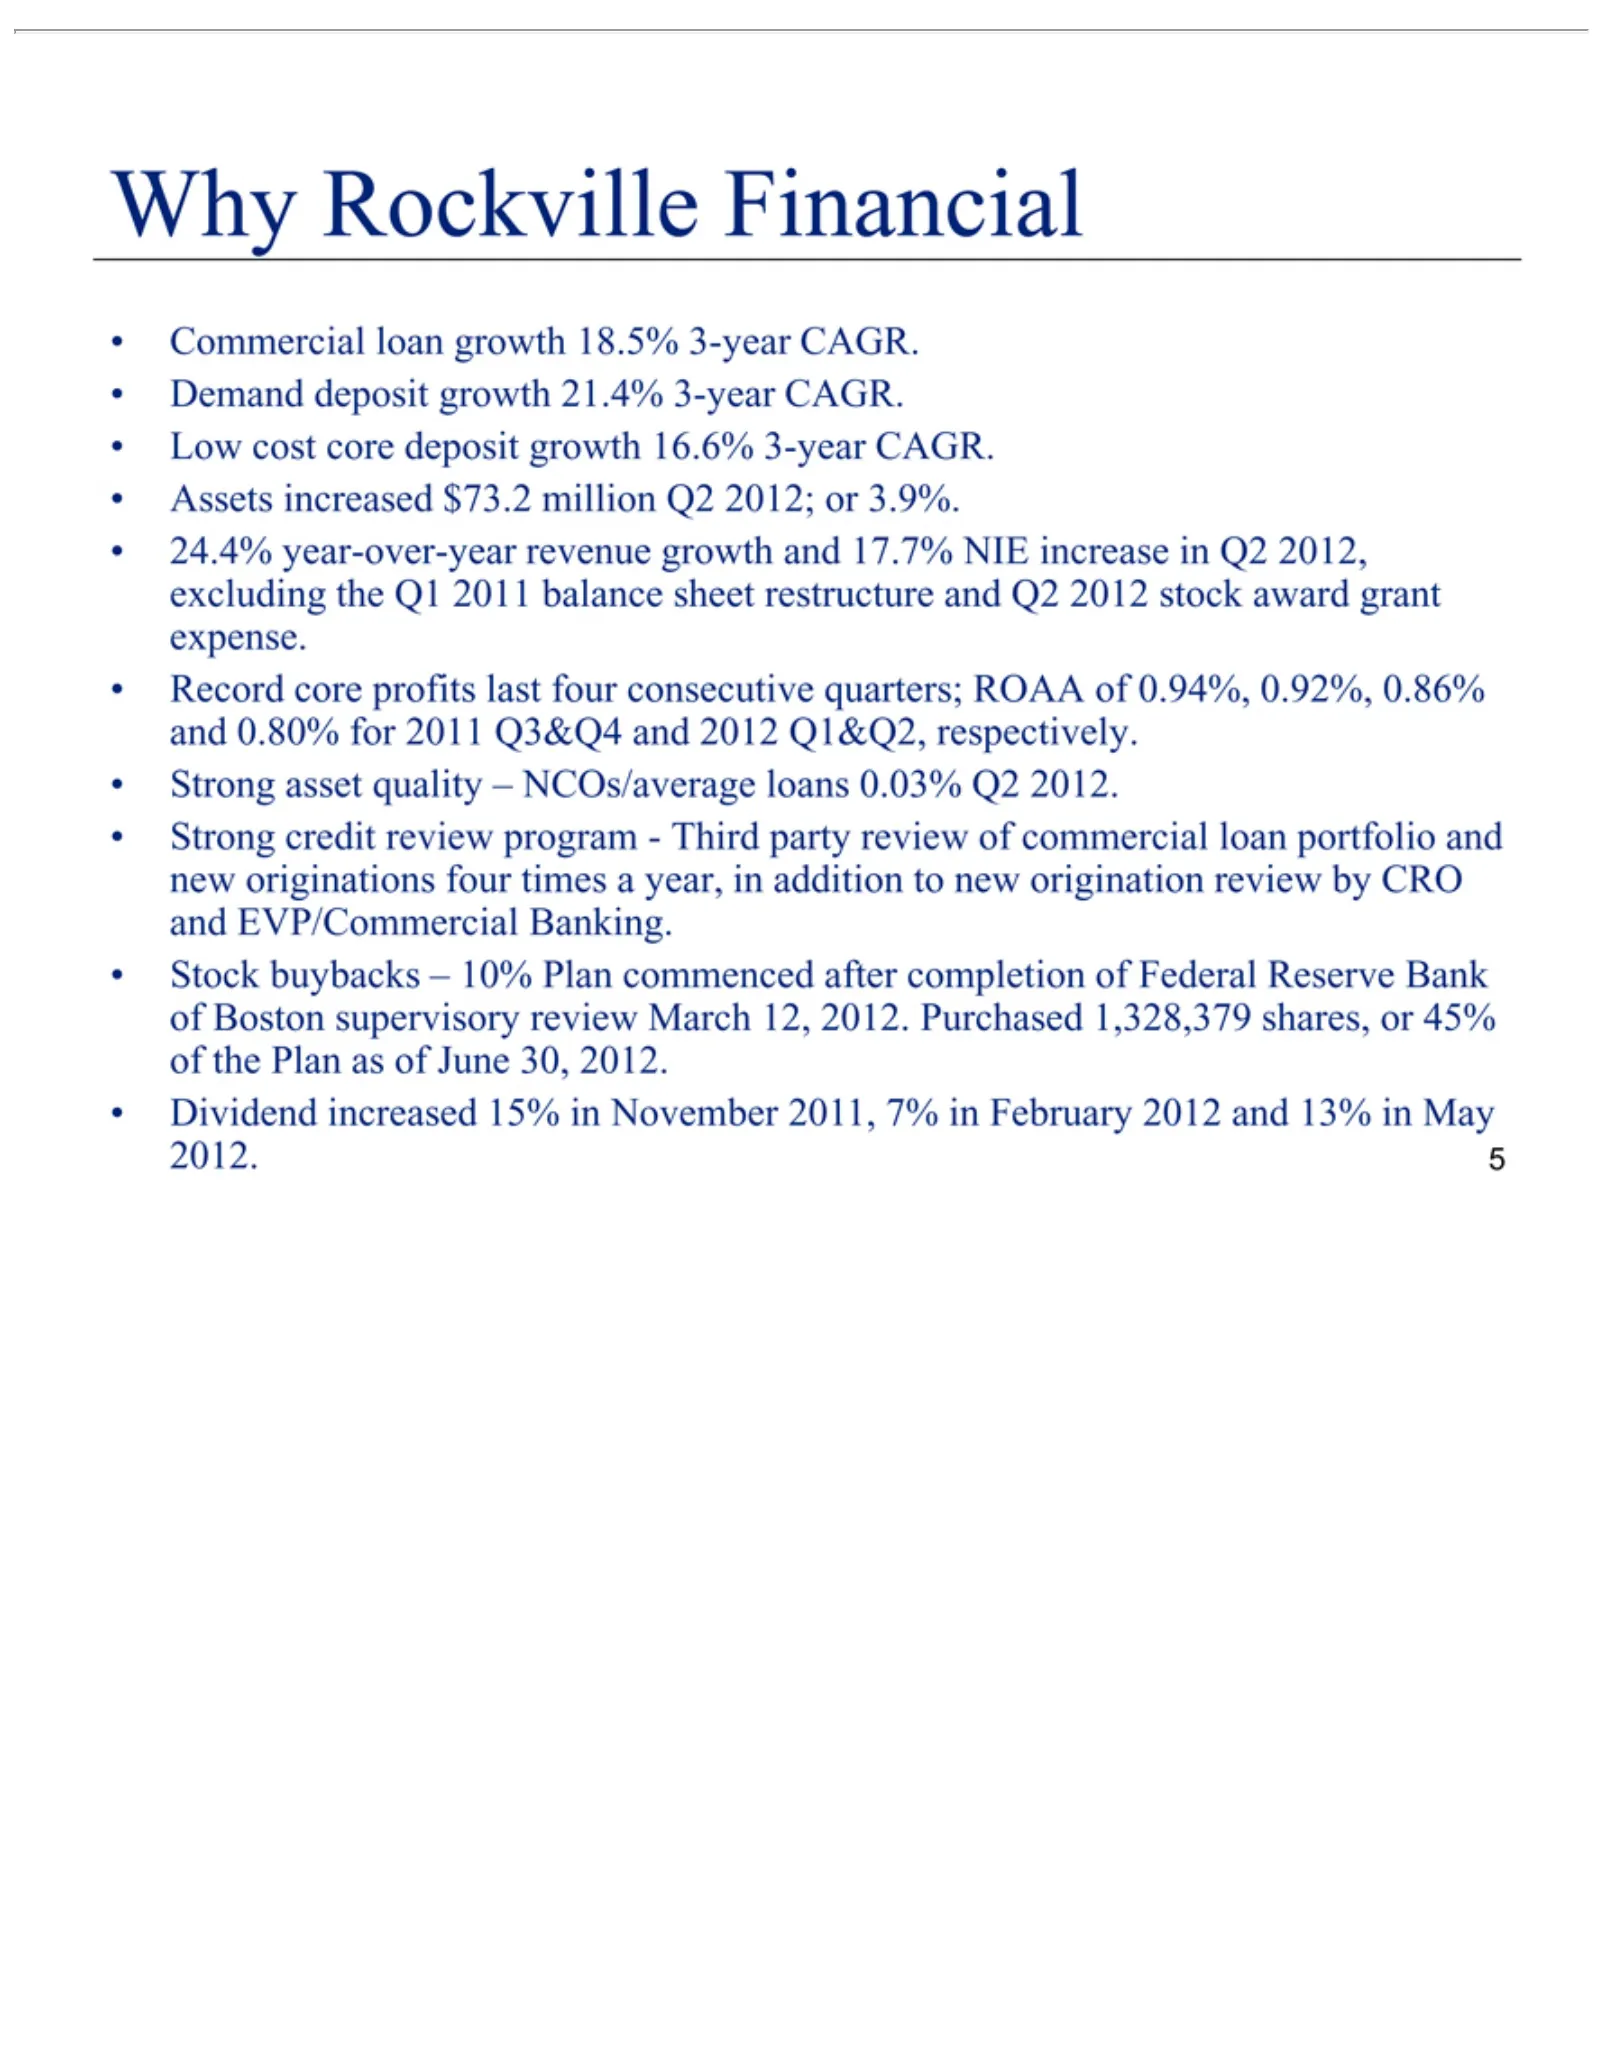
Slide 5: Why Rockville Financial
5•Why Assets Commercial Demand Low 24.4% Record Strong Stock Dividend Rockville cost buybacks increased year-over-year asset credit core deposit core increased profits quality loan review Financial deposit –growth $73.2 growth 10% last 15% –program—Third NCOs/average revenue growth million Plan four
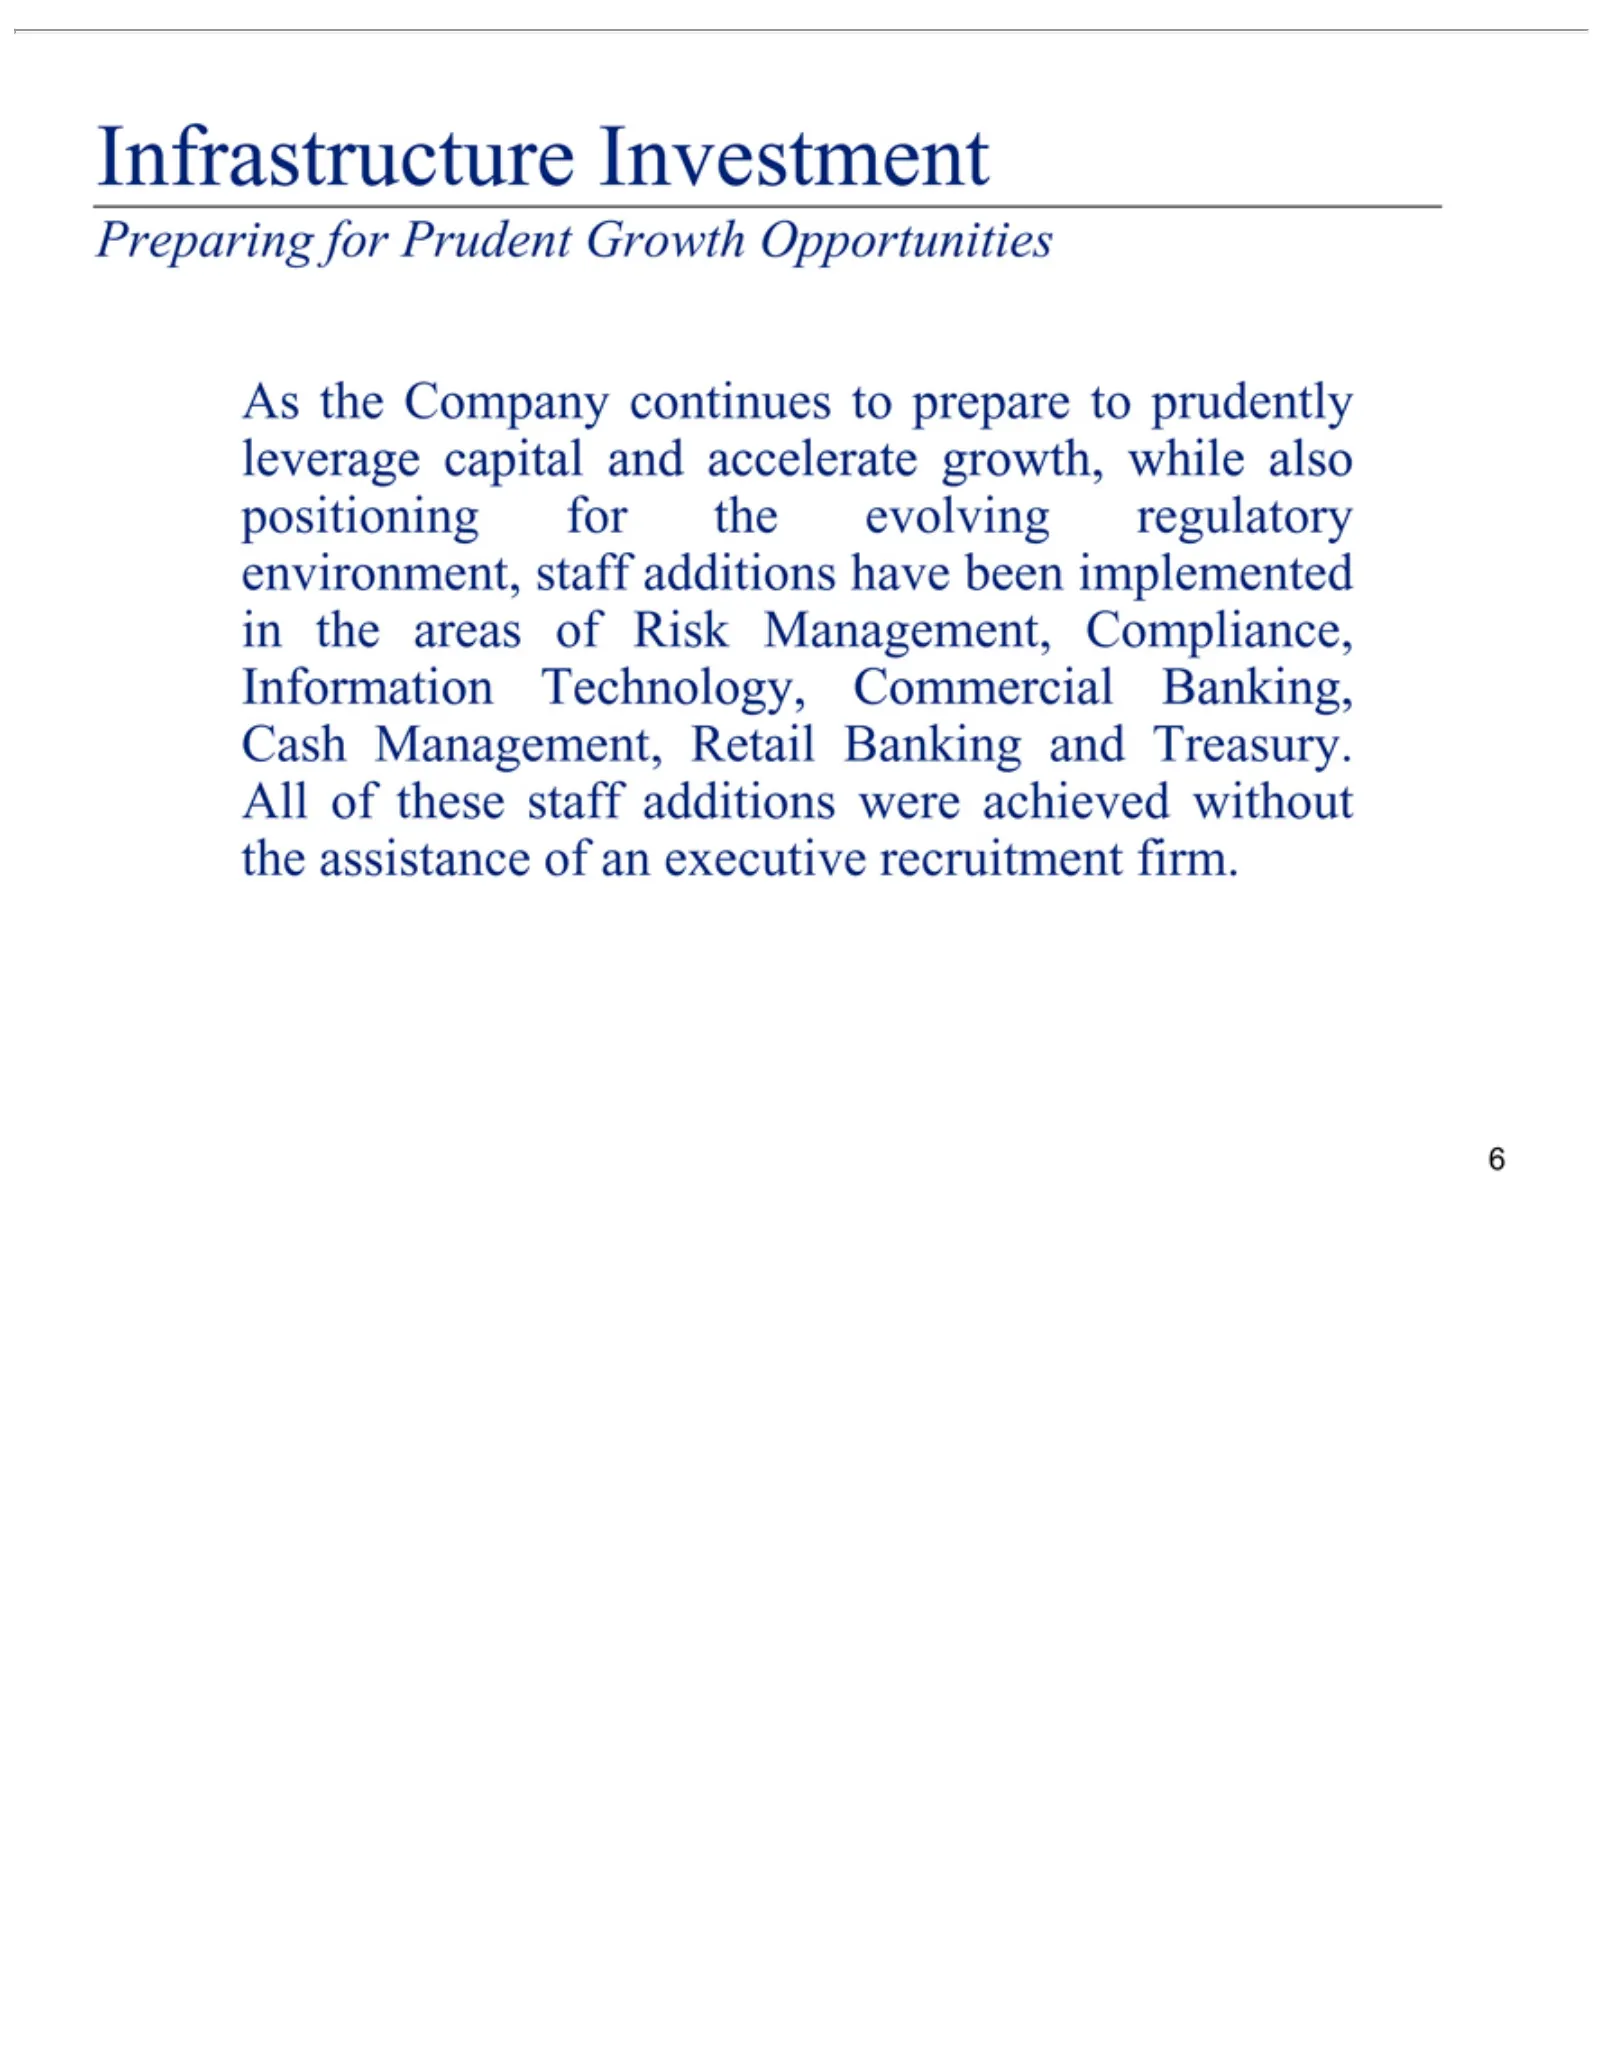
Slide 6: Infrastructure Preparing for Prudent Growth
Infrastructure Preparing As Management, 6All the of these Company forstaff Prudent Investment Compliance, additions continues Growth were Information to prepare Opportunities achieved toTechnology, prudently without the leverage Commercial assistance capital ofBanking, an andexecutive accelerate Cas
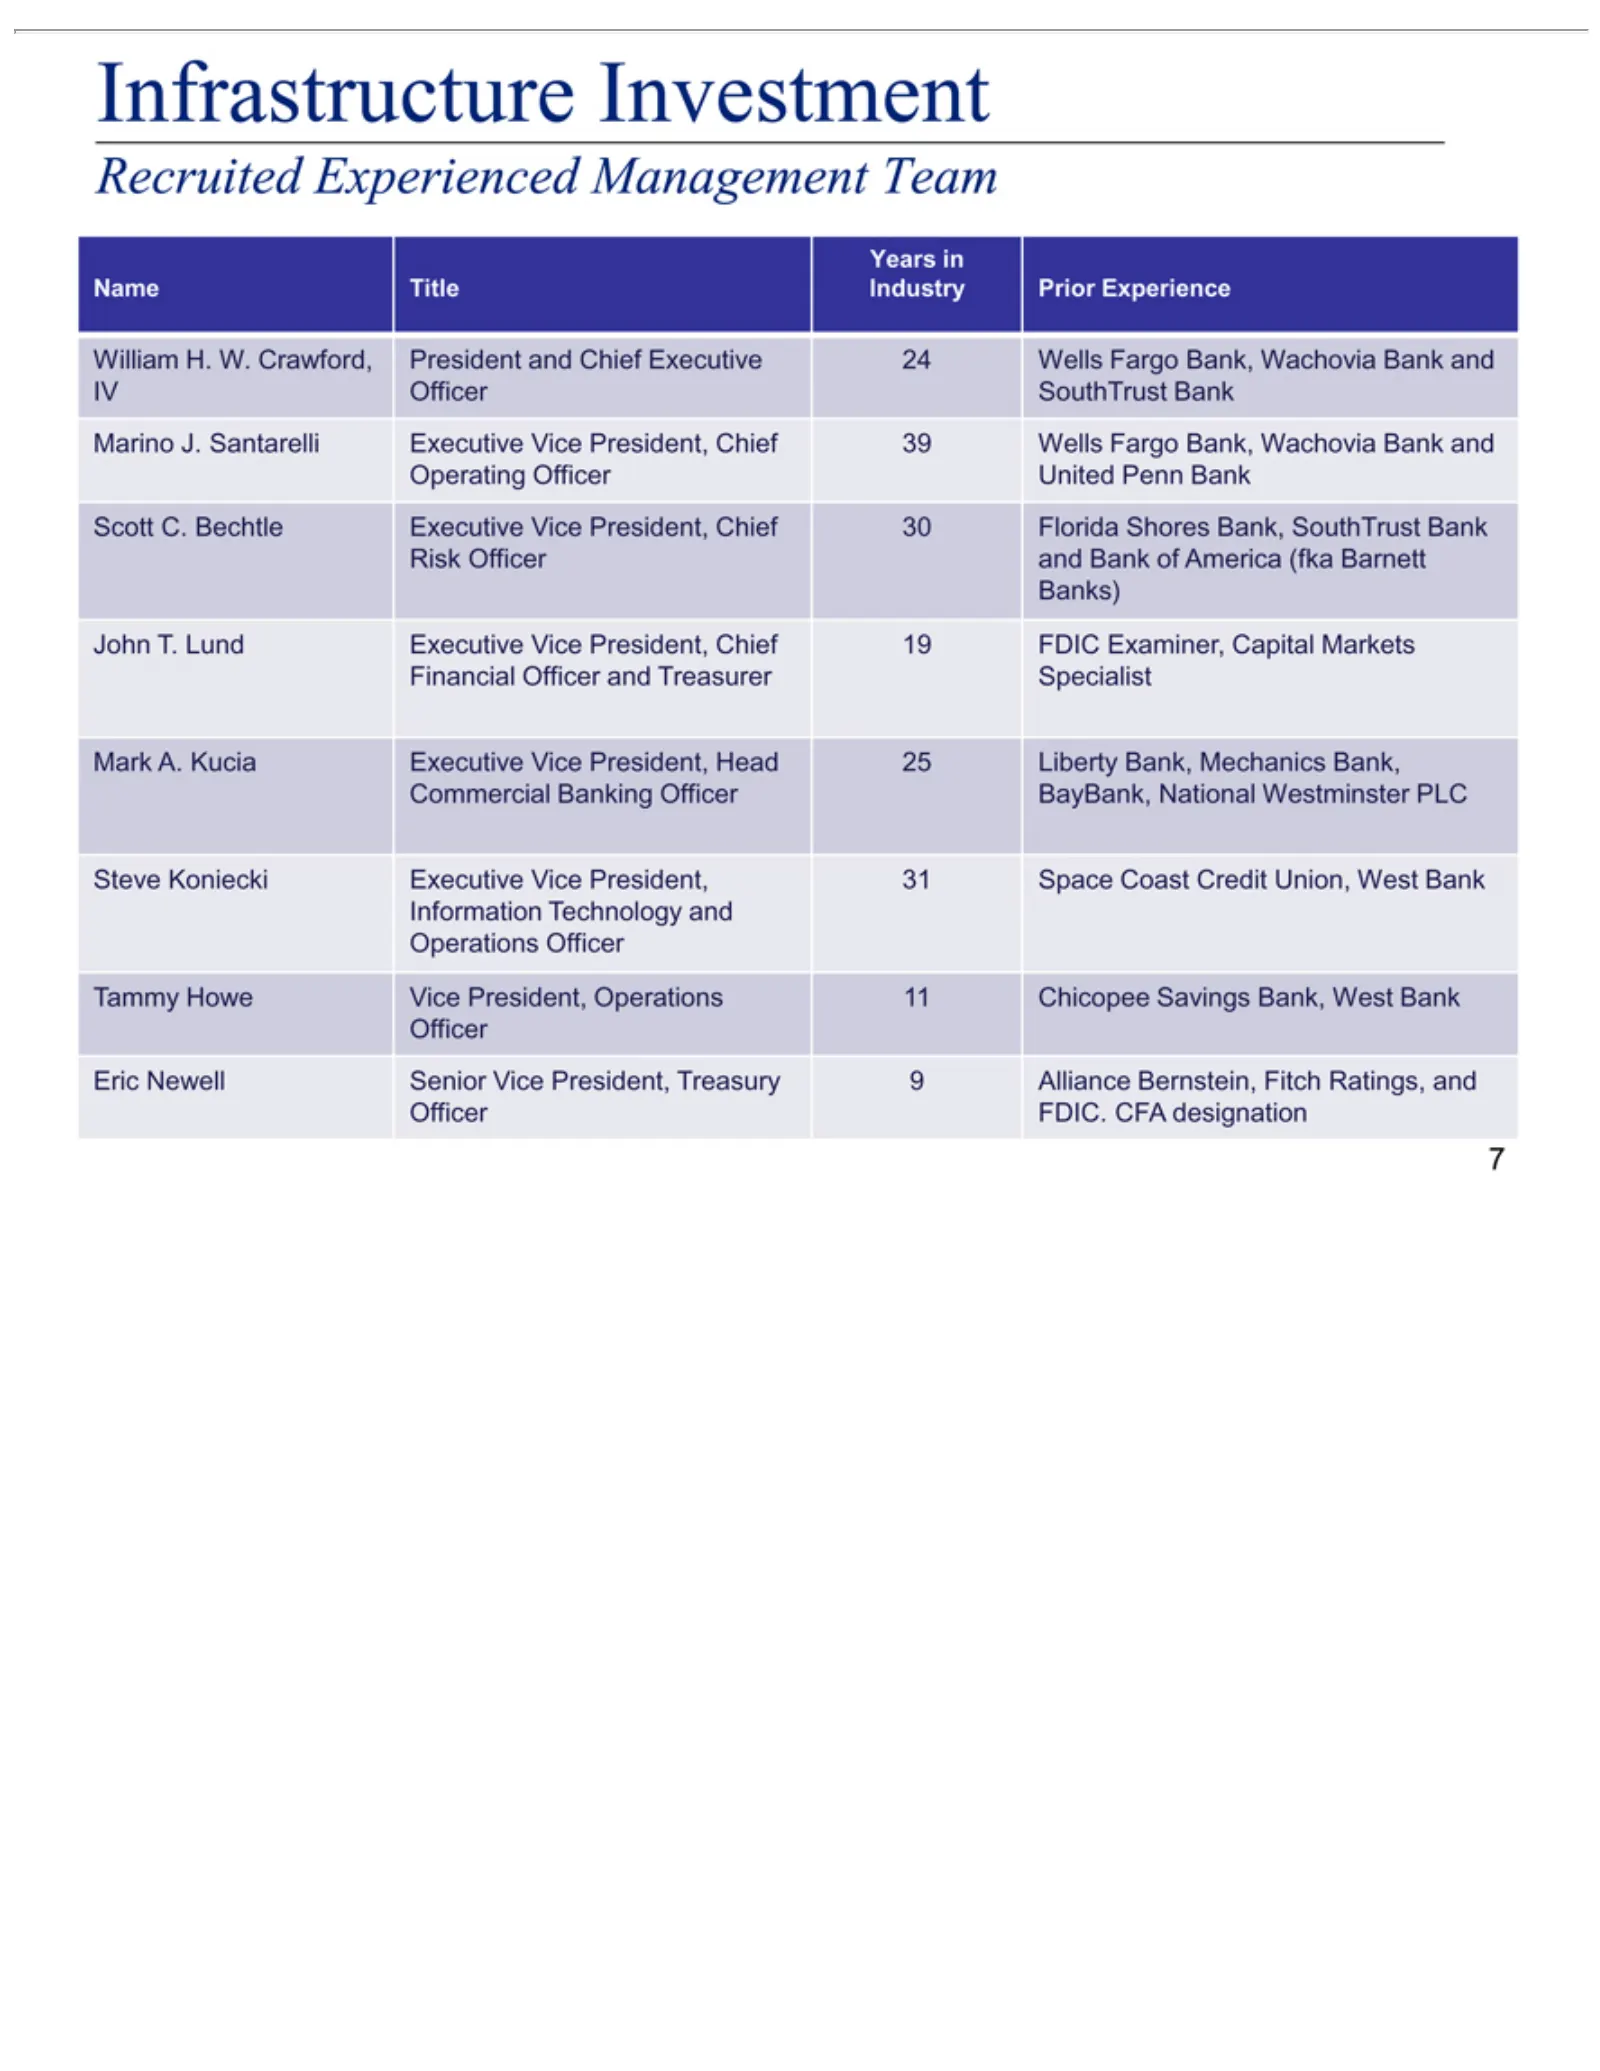
Slide 7: Infrastructure: Recruited Management
Infrastructure Recruited Years Name William IV Marino Operating Scott Risk John Banks) Financial Mark Commercial Steve Information Operations Tammy Eric 7Officer Officer Newell Officer T. C. A. Koniecki in Title FDIC. Lund J. Howe Bechtle H. Kucia Officer Santarelli Experienced Officer SouthTrust Of
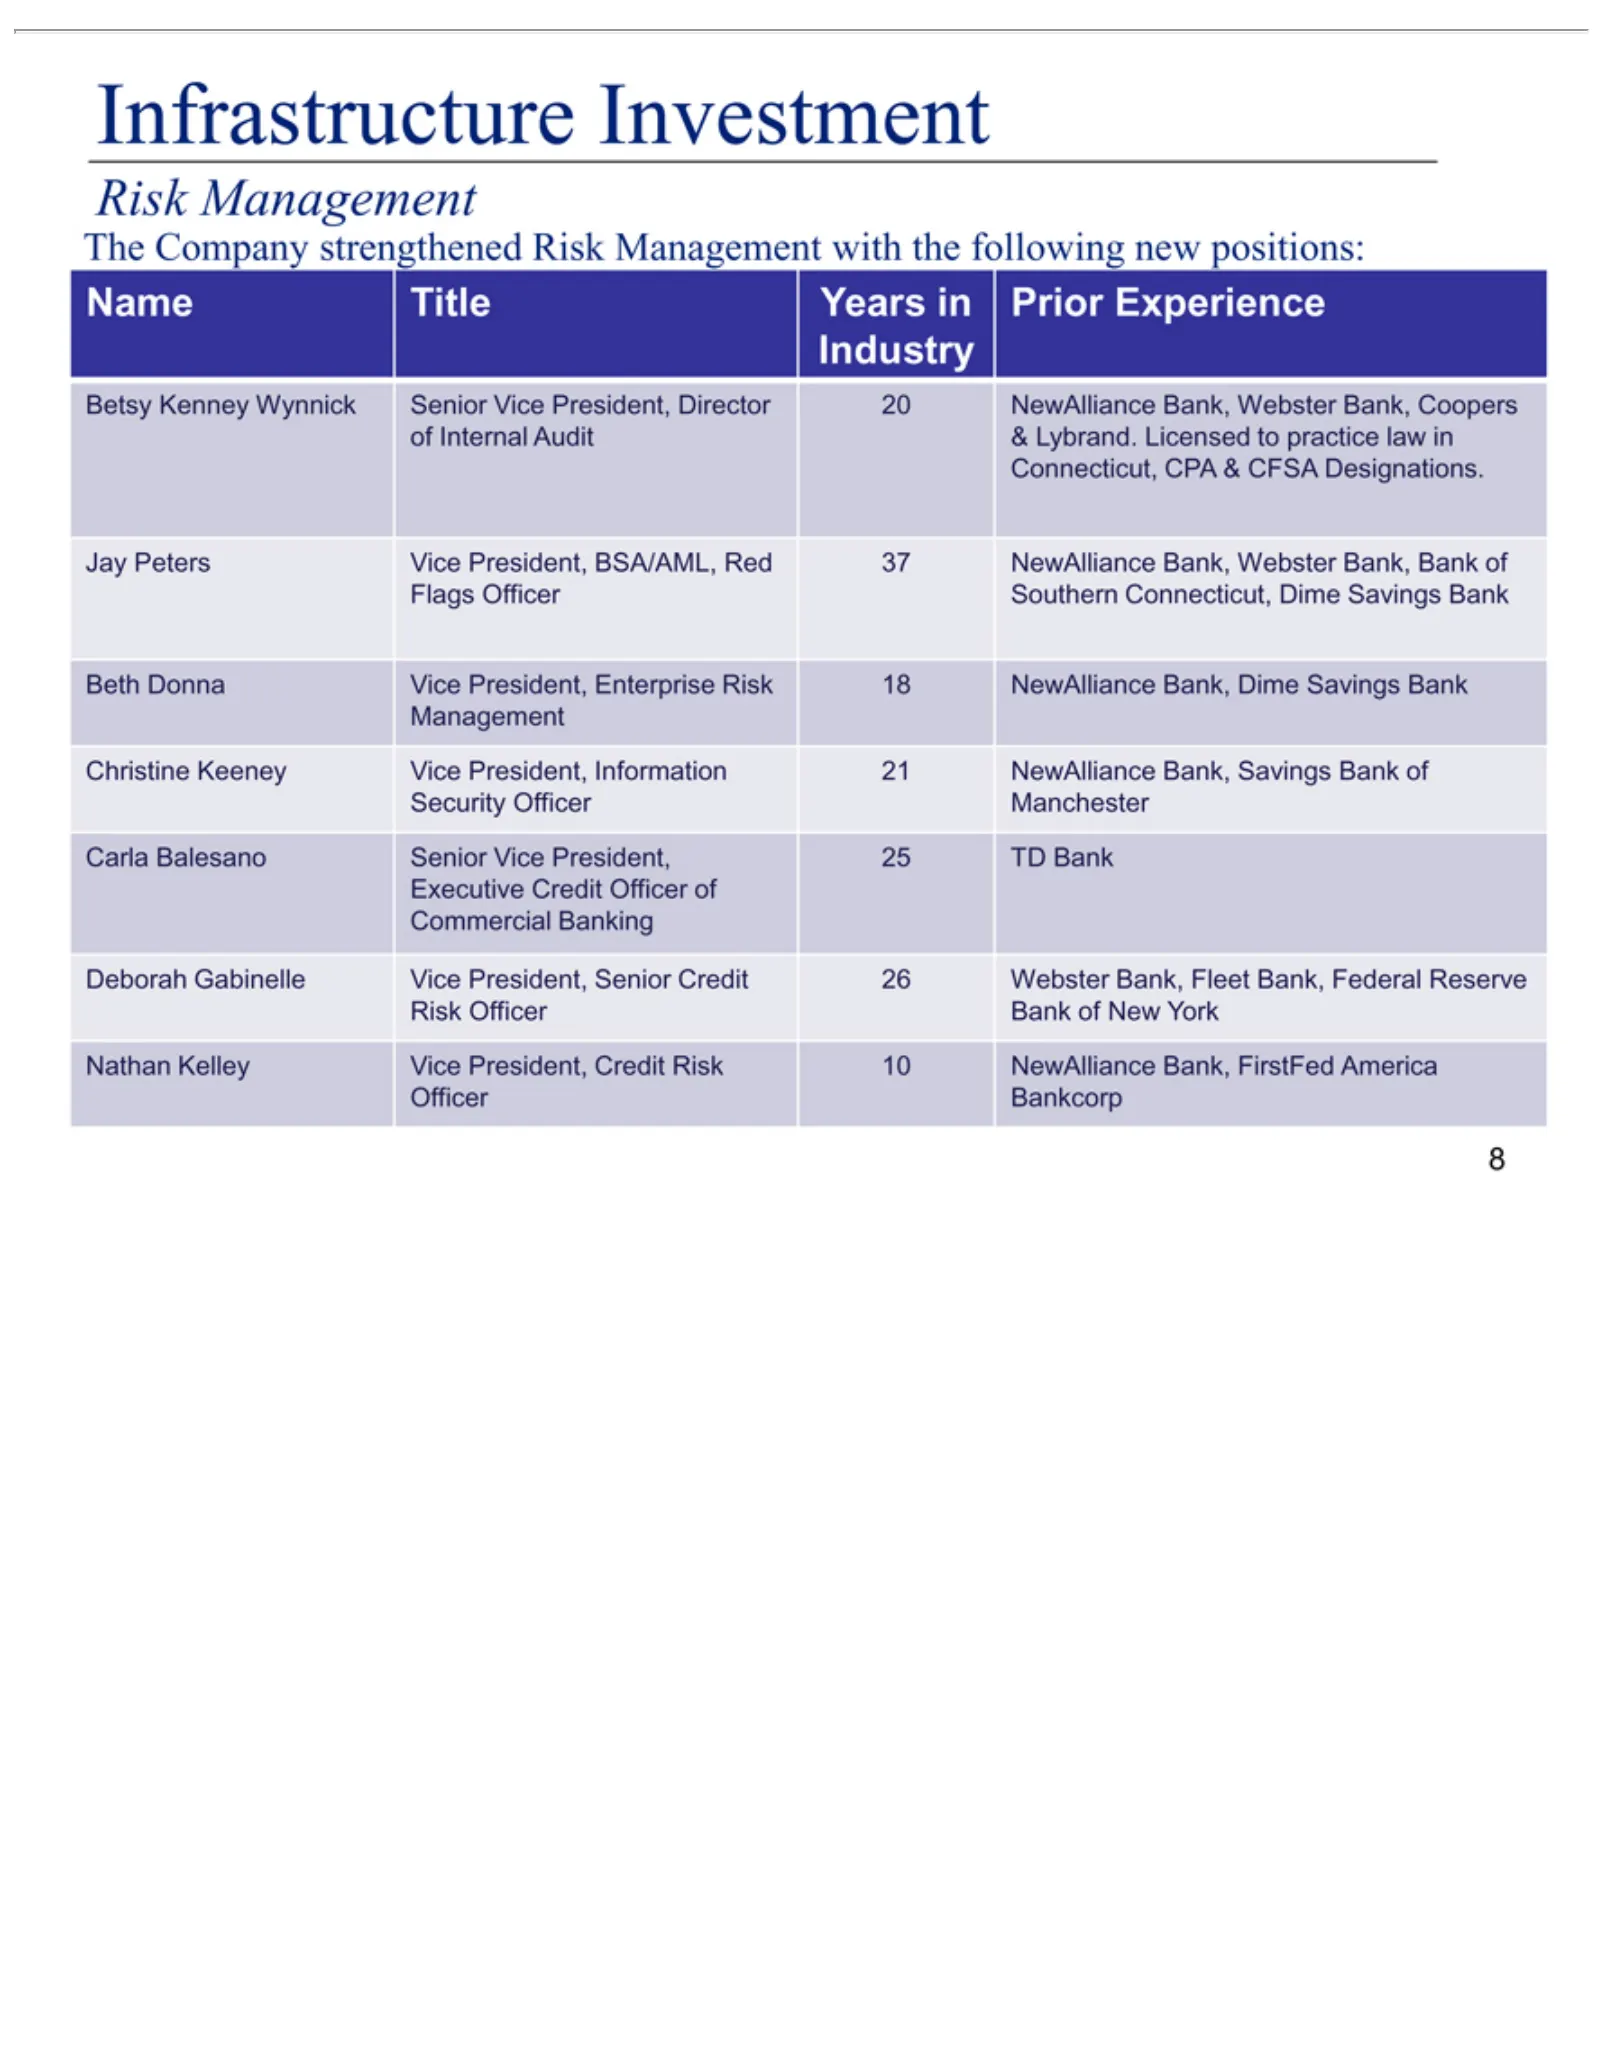
Slide 8: Infrastructure: Risk and Credit Management
Infrastructure The Name Betsy Industry of Connecticut, Jay Flags Beth Christine Management Security Carla Executive Commercial Deborah Risk Nathan 8Officer Internal Peters Company Management Officer Donna Balesano Officer Kenney Title Bankcorp Kelley Officer Gabinelle Keeney Credit Vice Audit Years
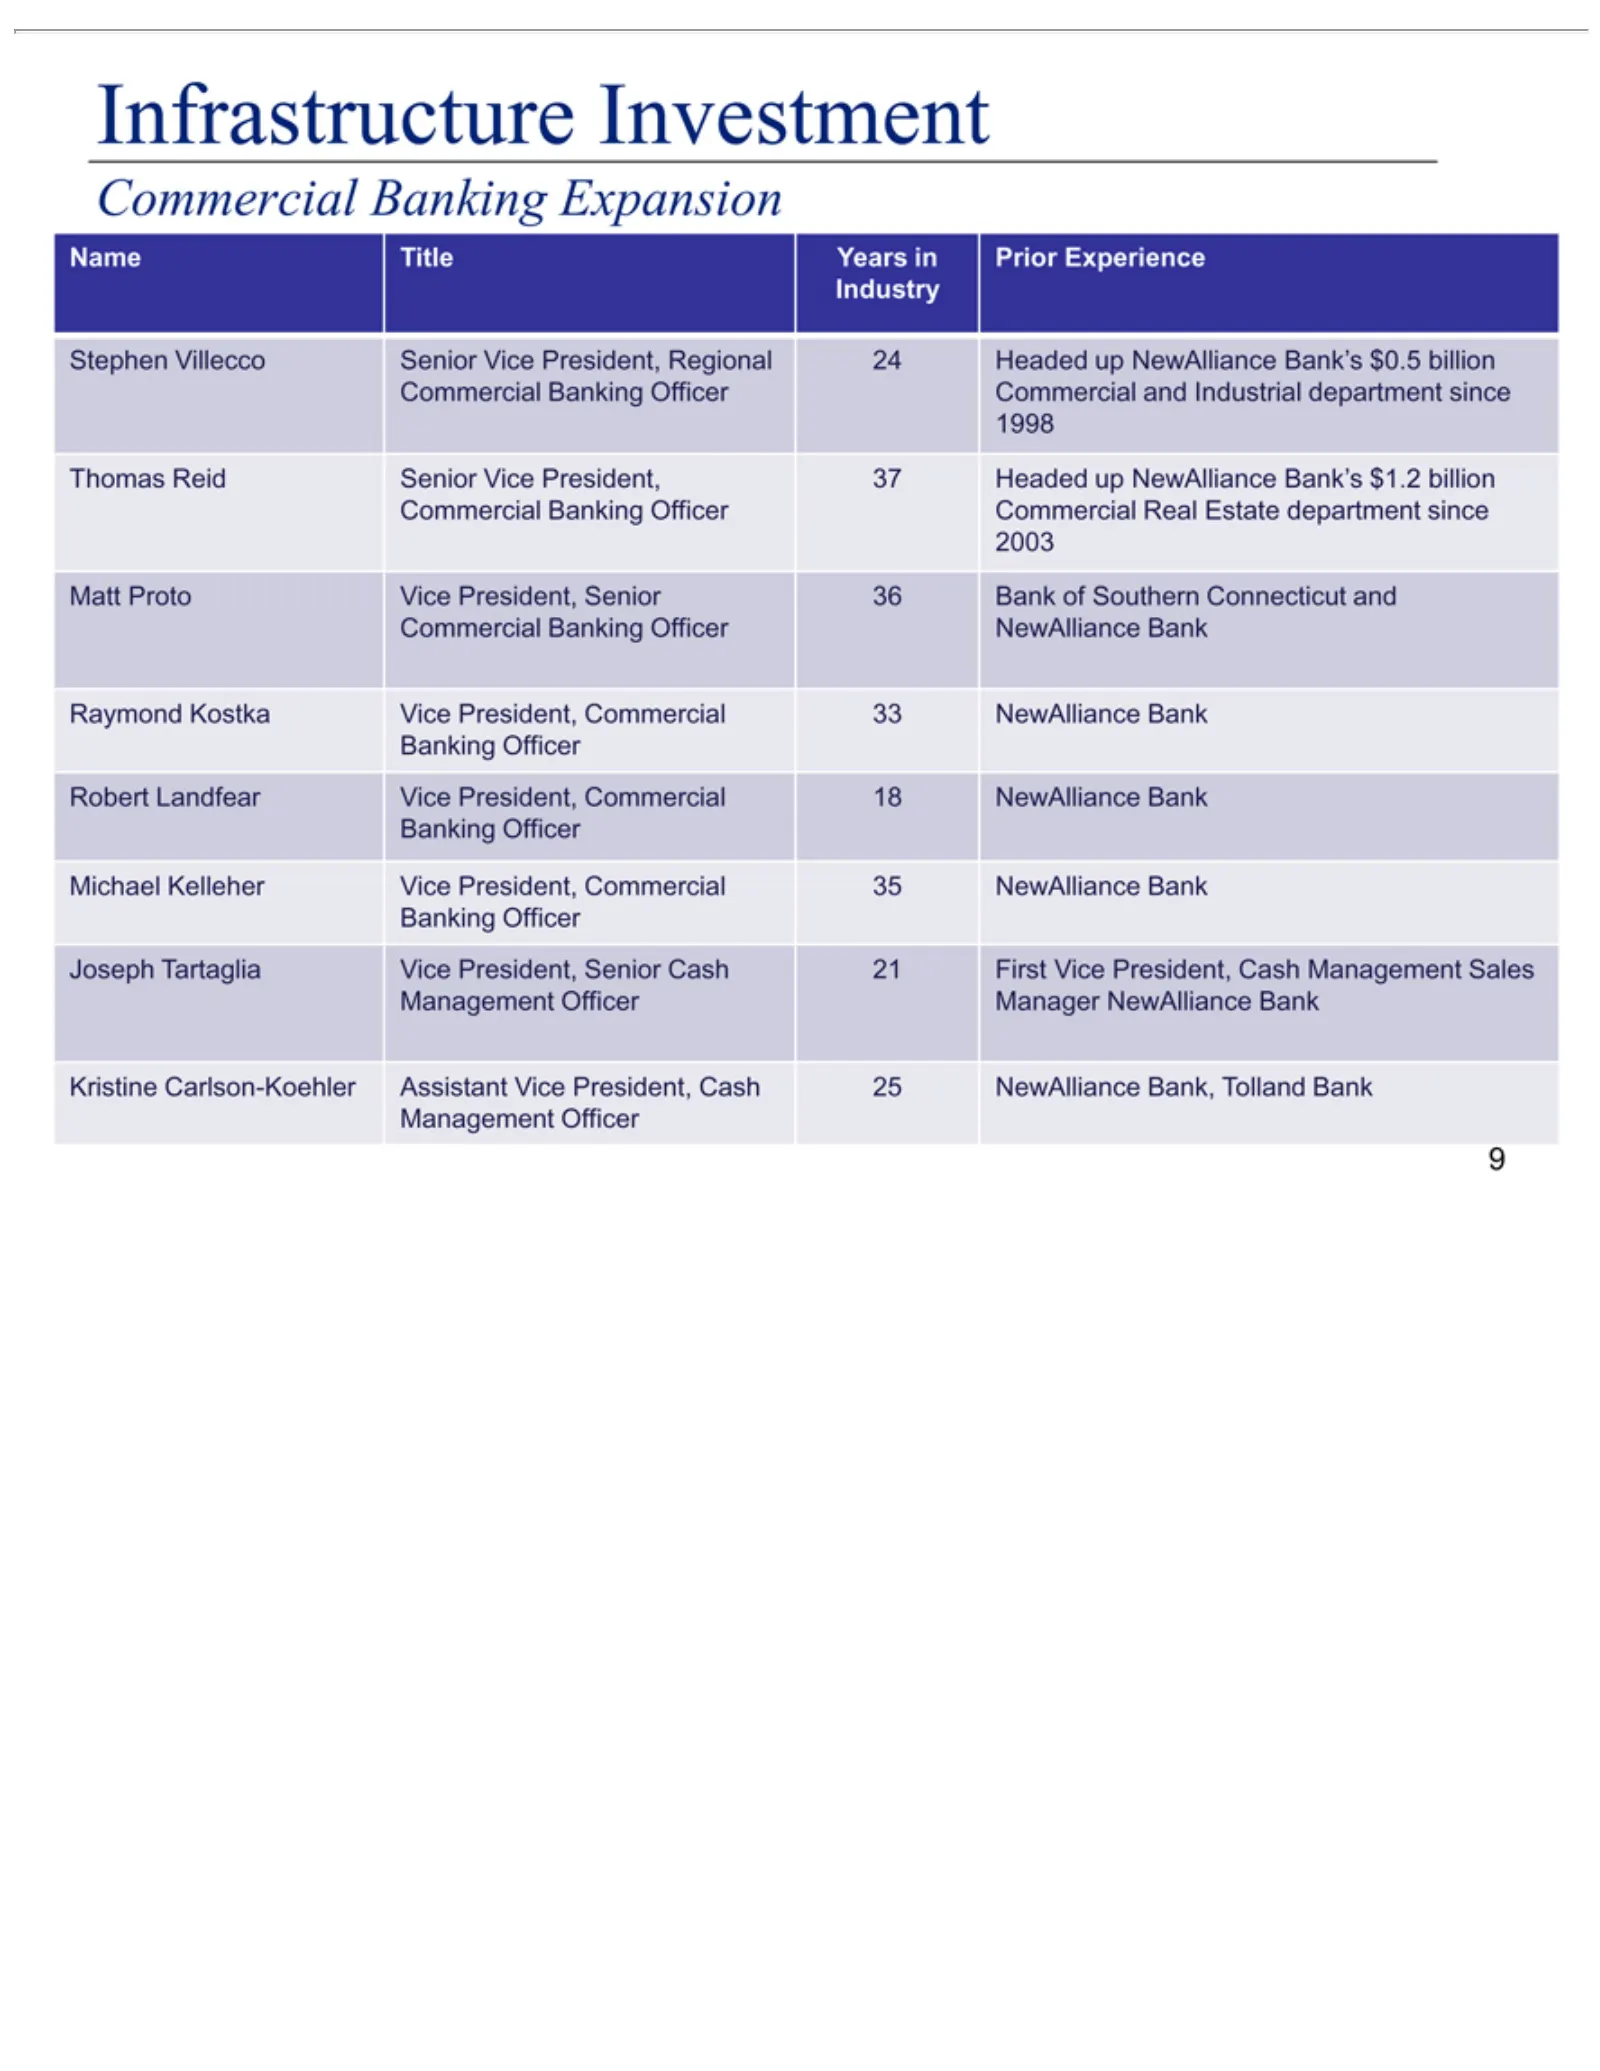
Slide 9: Infrastructure: Commercial Banking
Infrastructure Name Stephen Industry Thomas 1998 Matt 2003 Commercial Raymond Robert Michael Banking Joseph Kristine 9Management Proto Title Tartaglia Landfear Villecco Reid Carlson-Koehler Kelleher Officer Kostka Vice Years Banking Officer Senior Investment President, Vice Senior in Vice Prior Vice
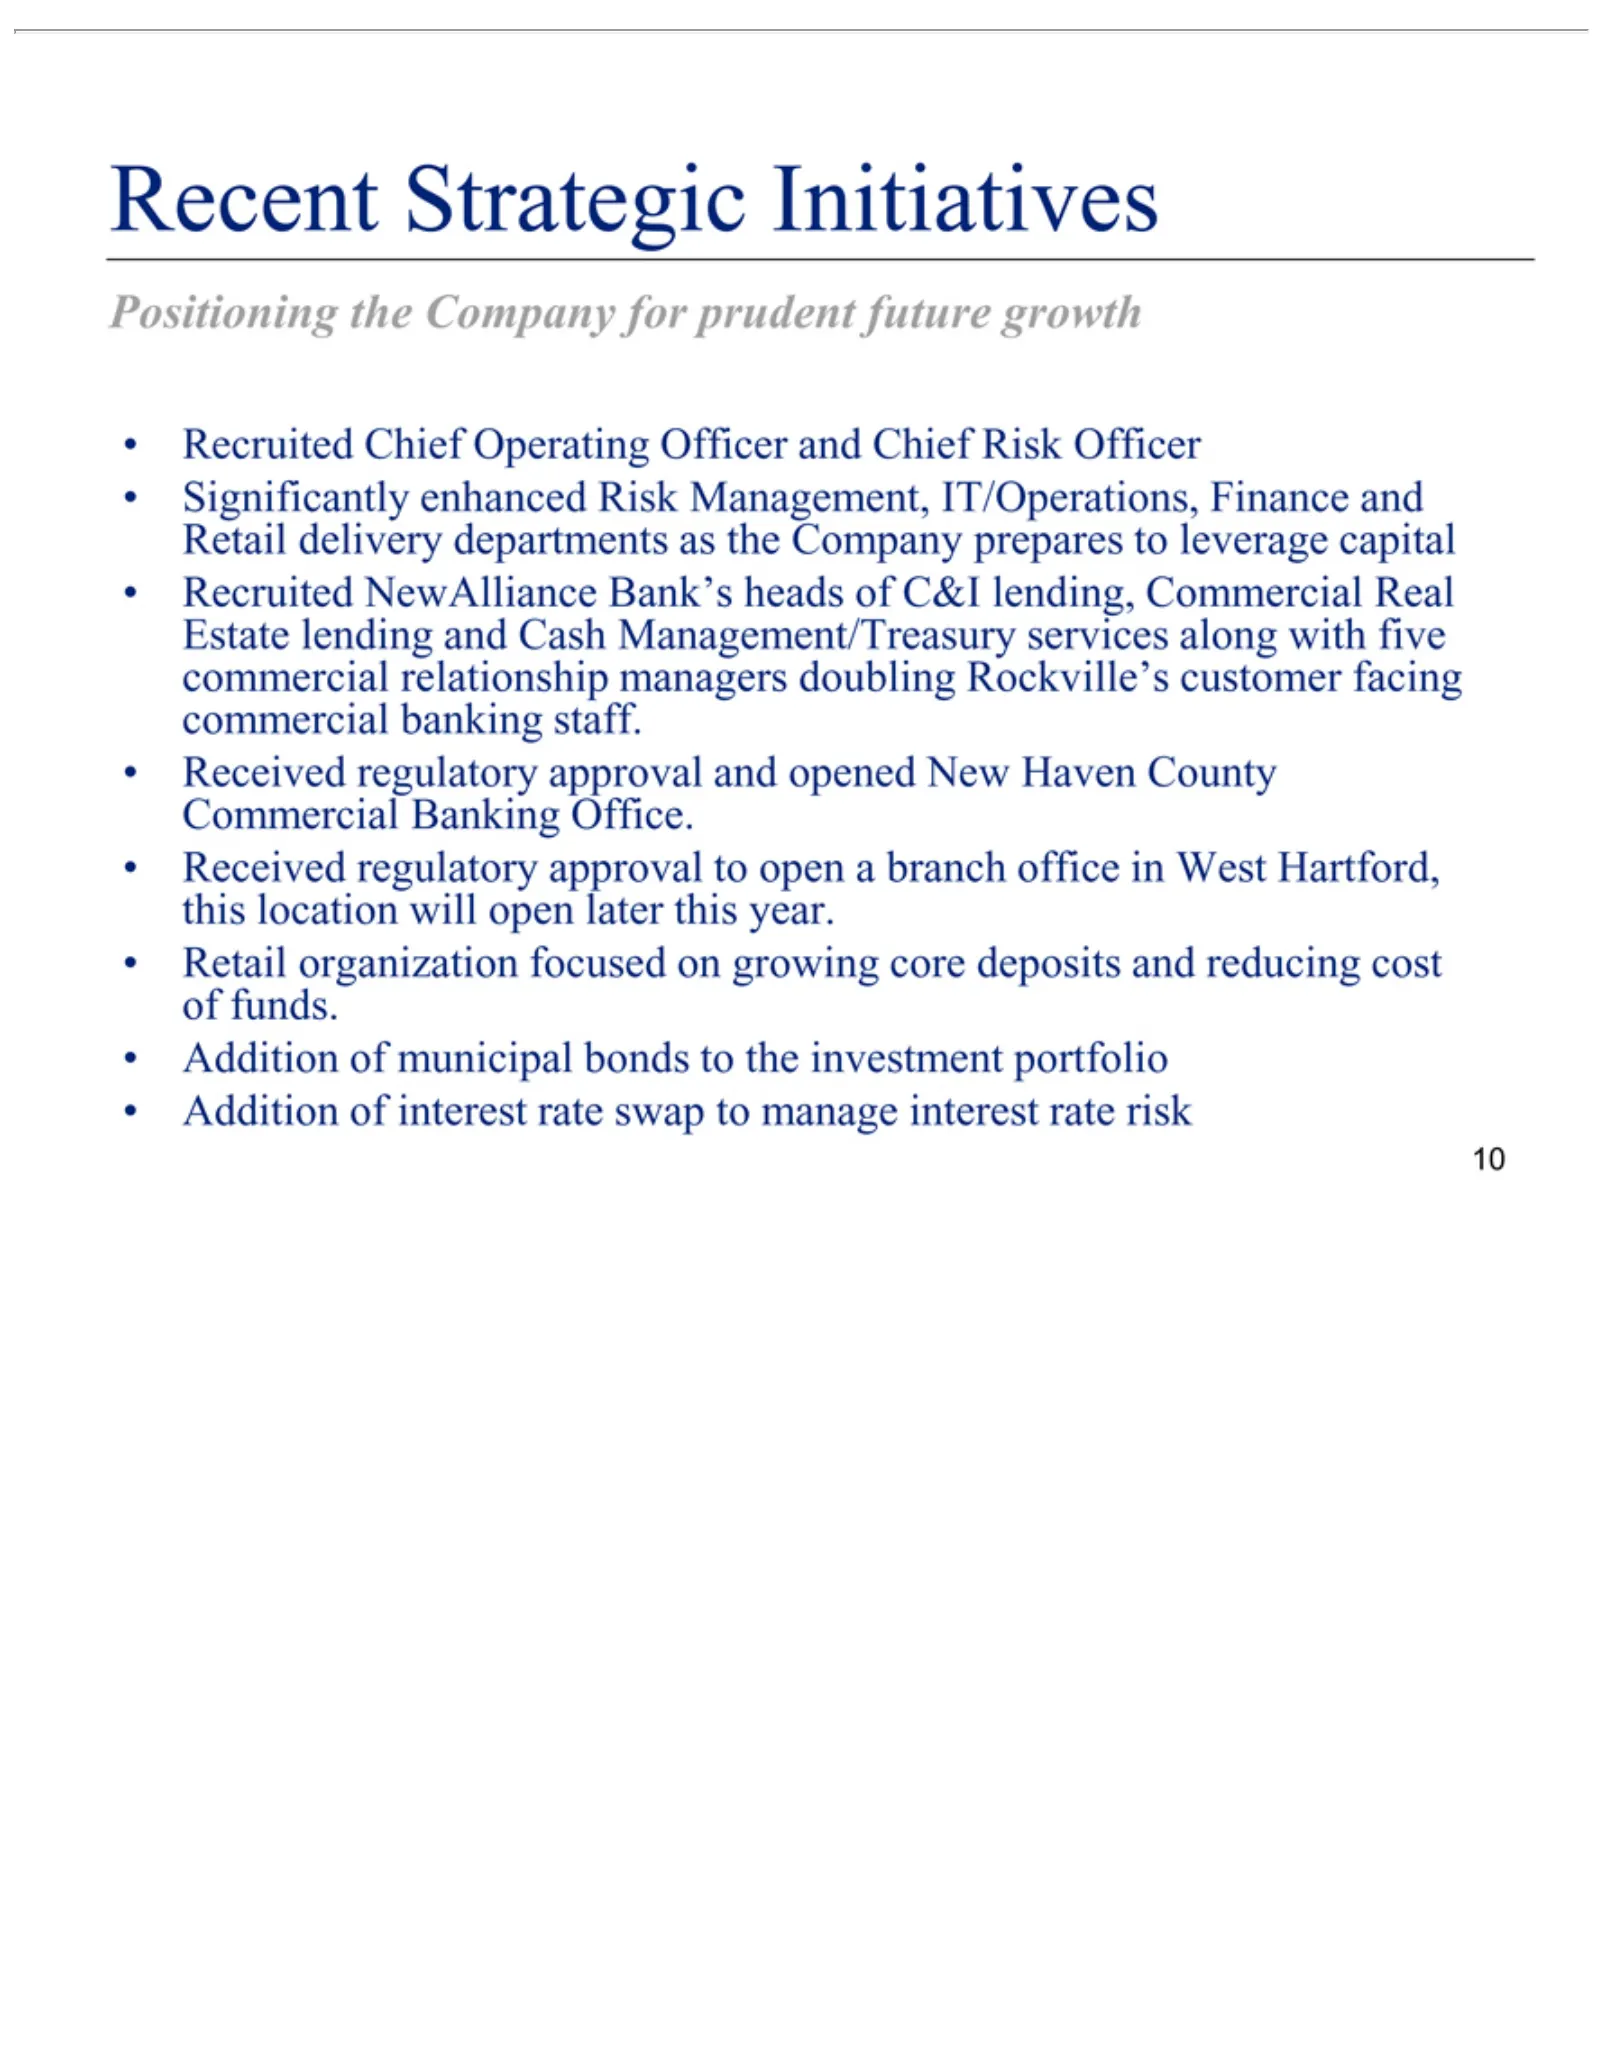
Slide 10: Recent Strategic Initiatives
Recent Positioning •Estate 10 Addition Significantly Recruited Received Retaillending Strategic organization of regulatory Chief NewAlliance the municipal interest and enhanced Company Initiatives Operating Cash focused rate approval bonds Management/Treasury Risk Bank’s swap forOfficer on prudent M
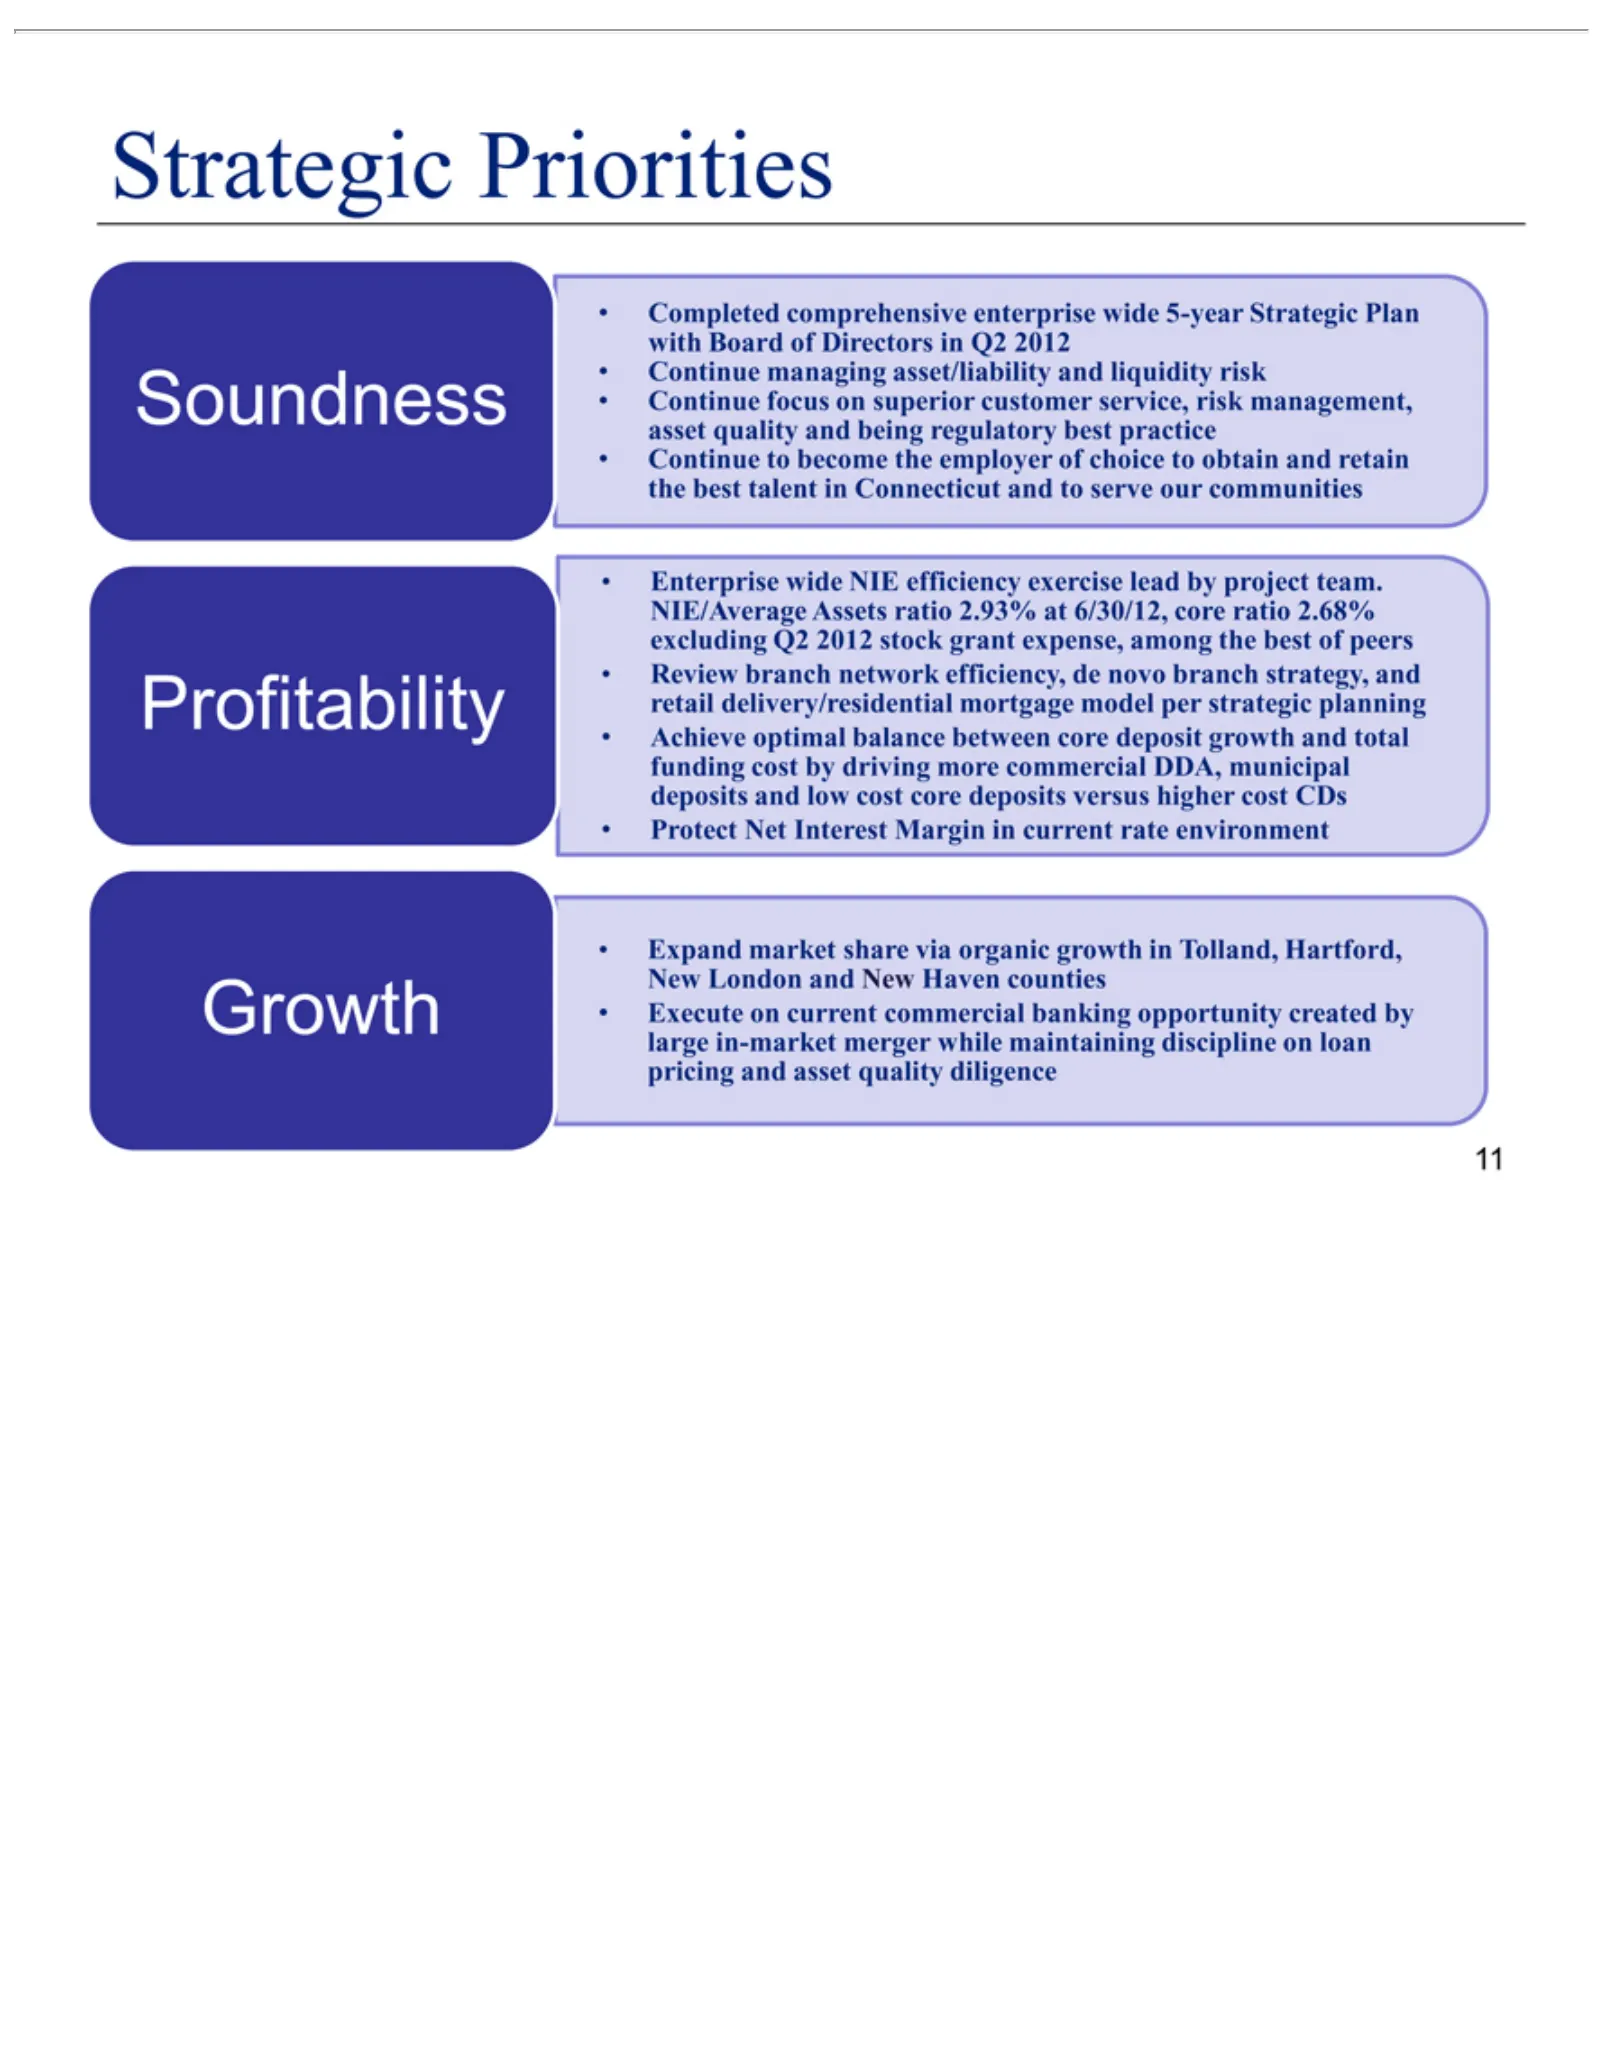
Slide 11: Strategic Priorities
Strategic •Soundness 11 Achieve Completed Continue Enterprise Review Protect Expand Execute Net Priorities market branch on optimal managing focus to Profitability wide comprehensive current Interest become network share on NIE balance superior commercial Margin asset/liability the efficiency via Gr
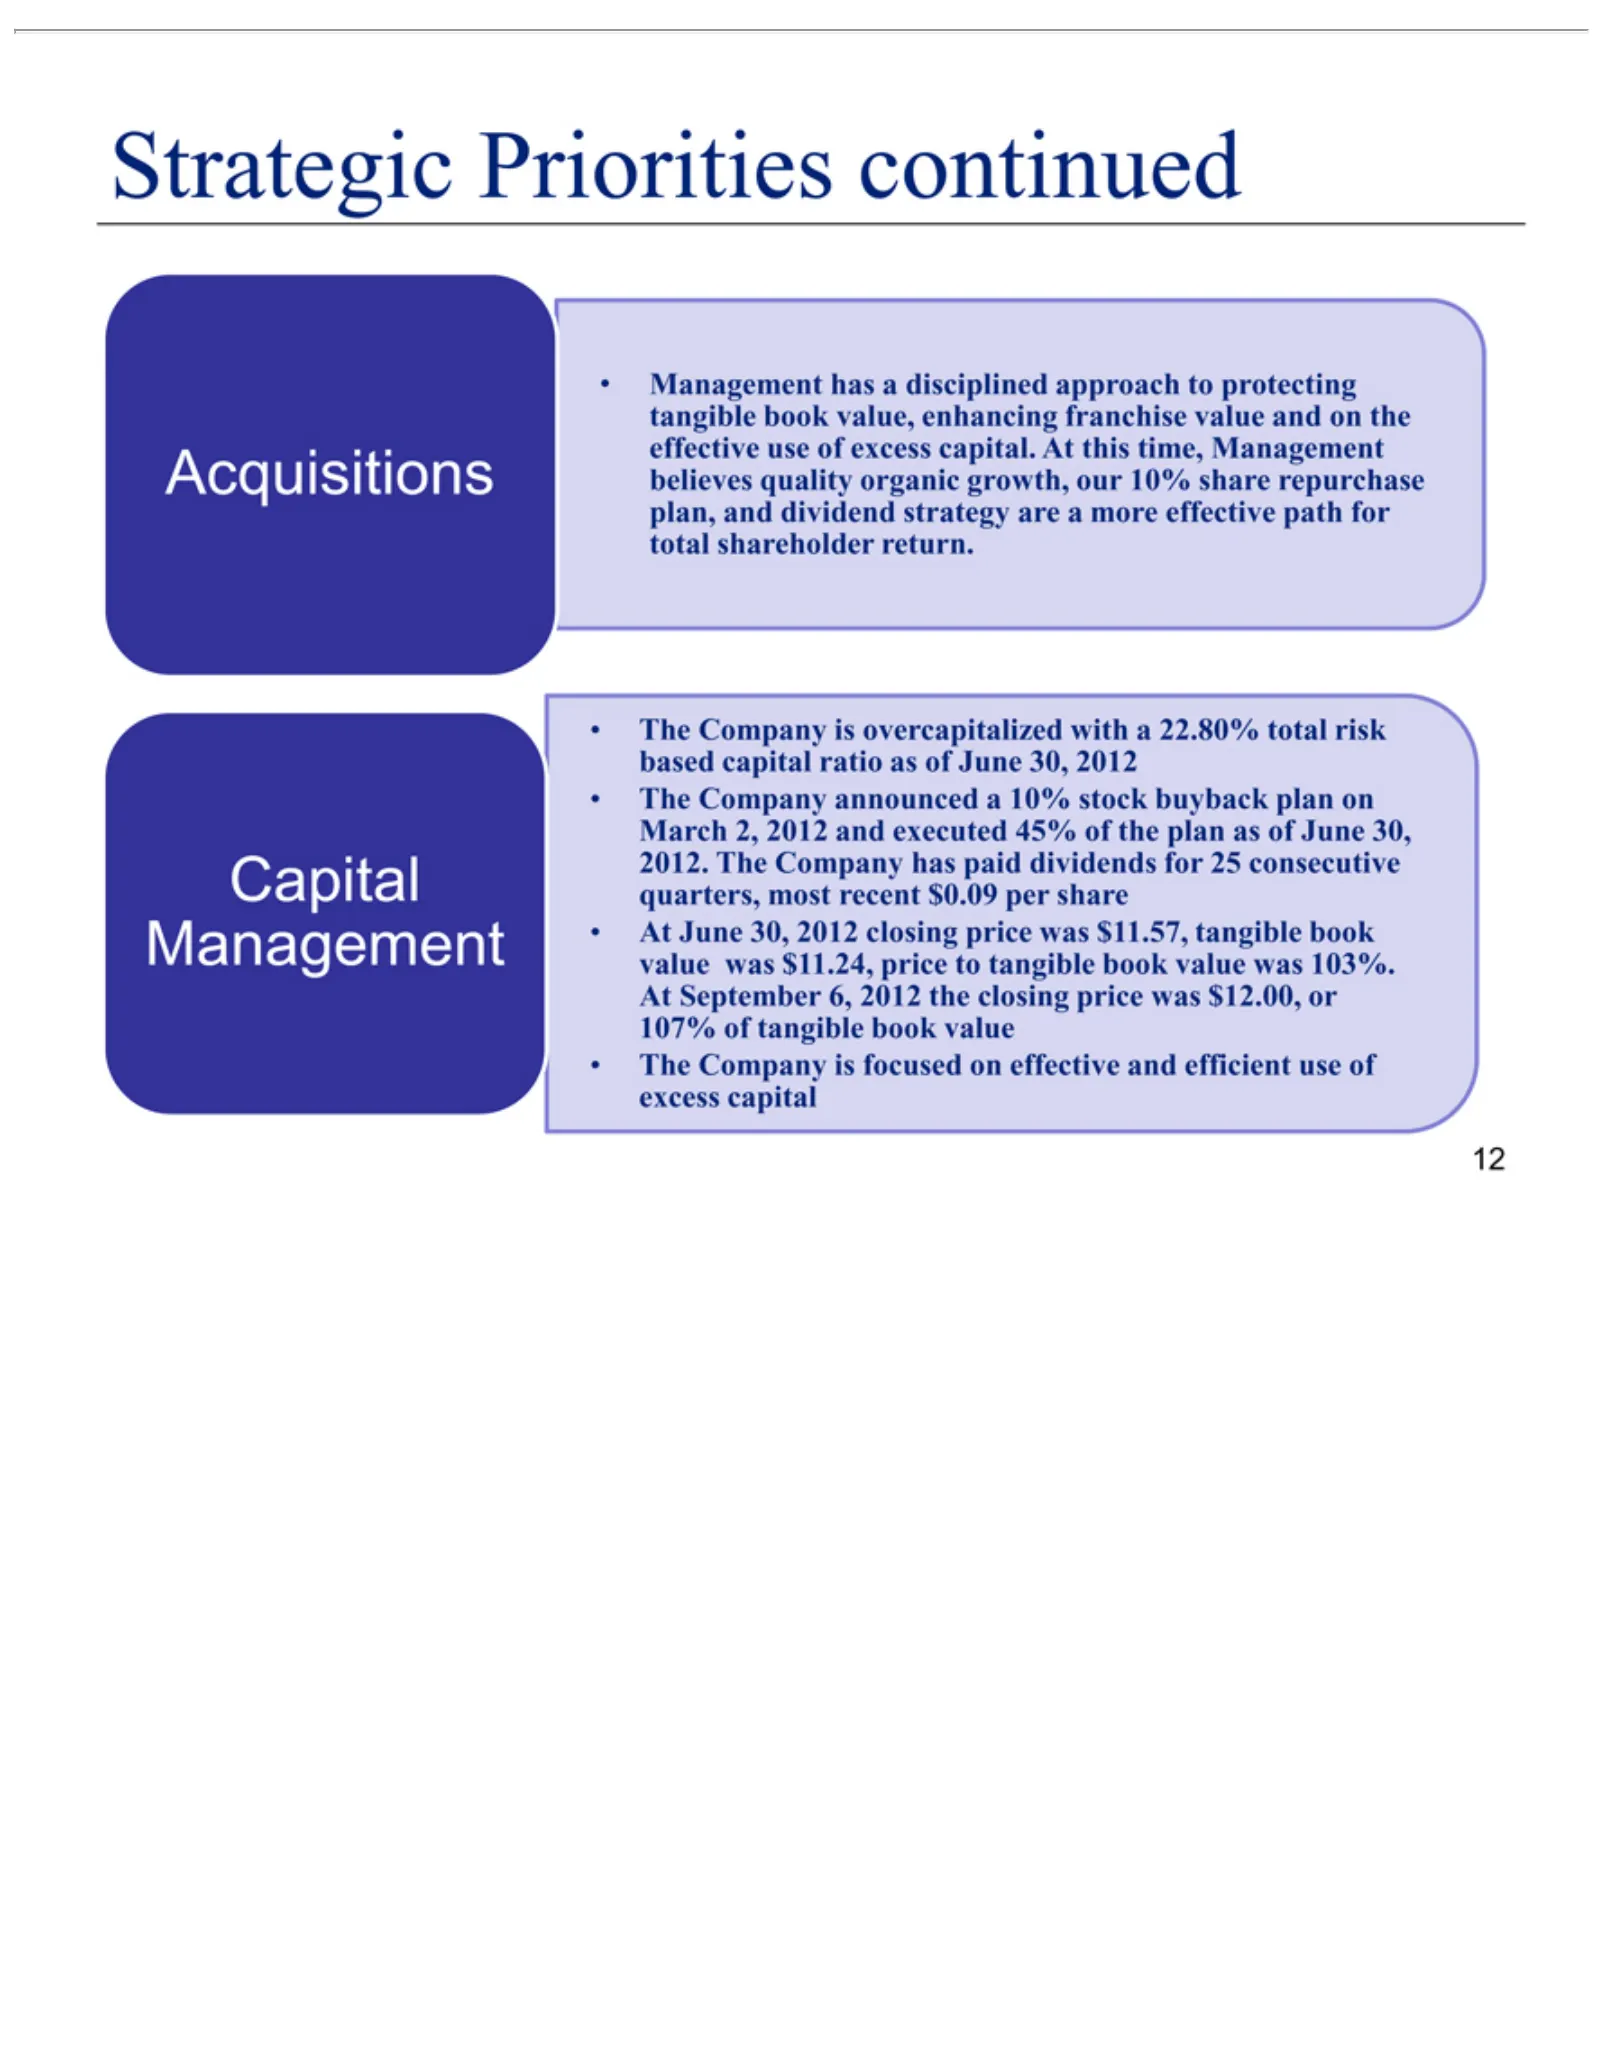
Slide 12: Strategic Priorities: Capital Management
Strategic Capital Acquisitions •share 12 At The Management June repurchase Company Management Priorities 30, 2012 has announced is plan, overcapitalized focused closing acontinued disciplined and price on dividend a 10% effective approach was with stock strategy $11.57, and abuyback 22.80% toefficie
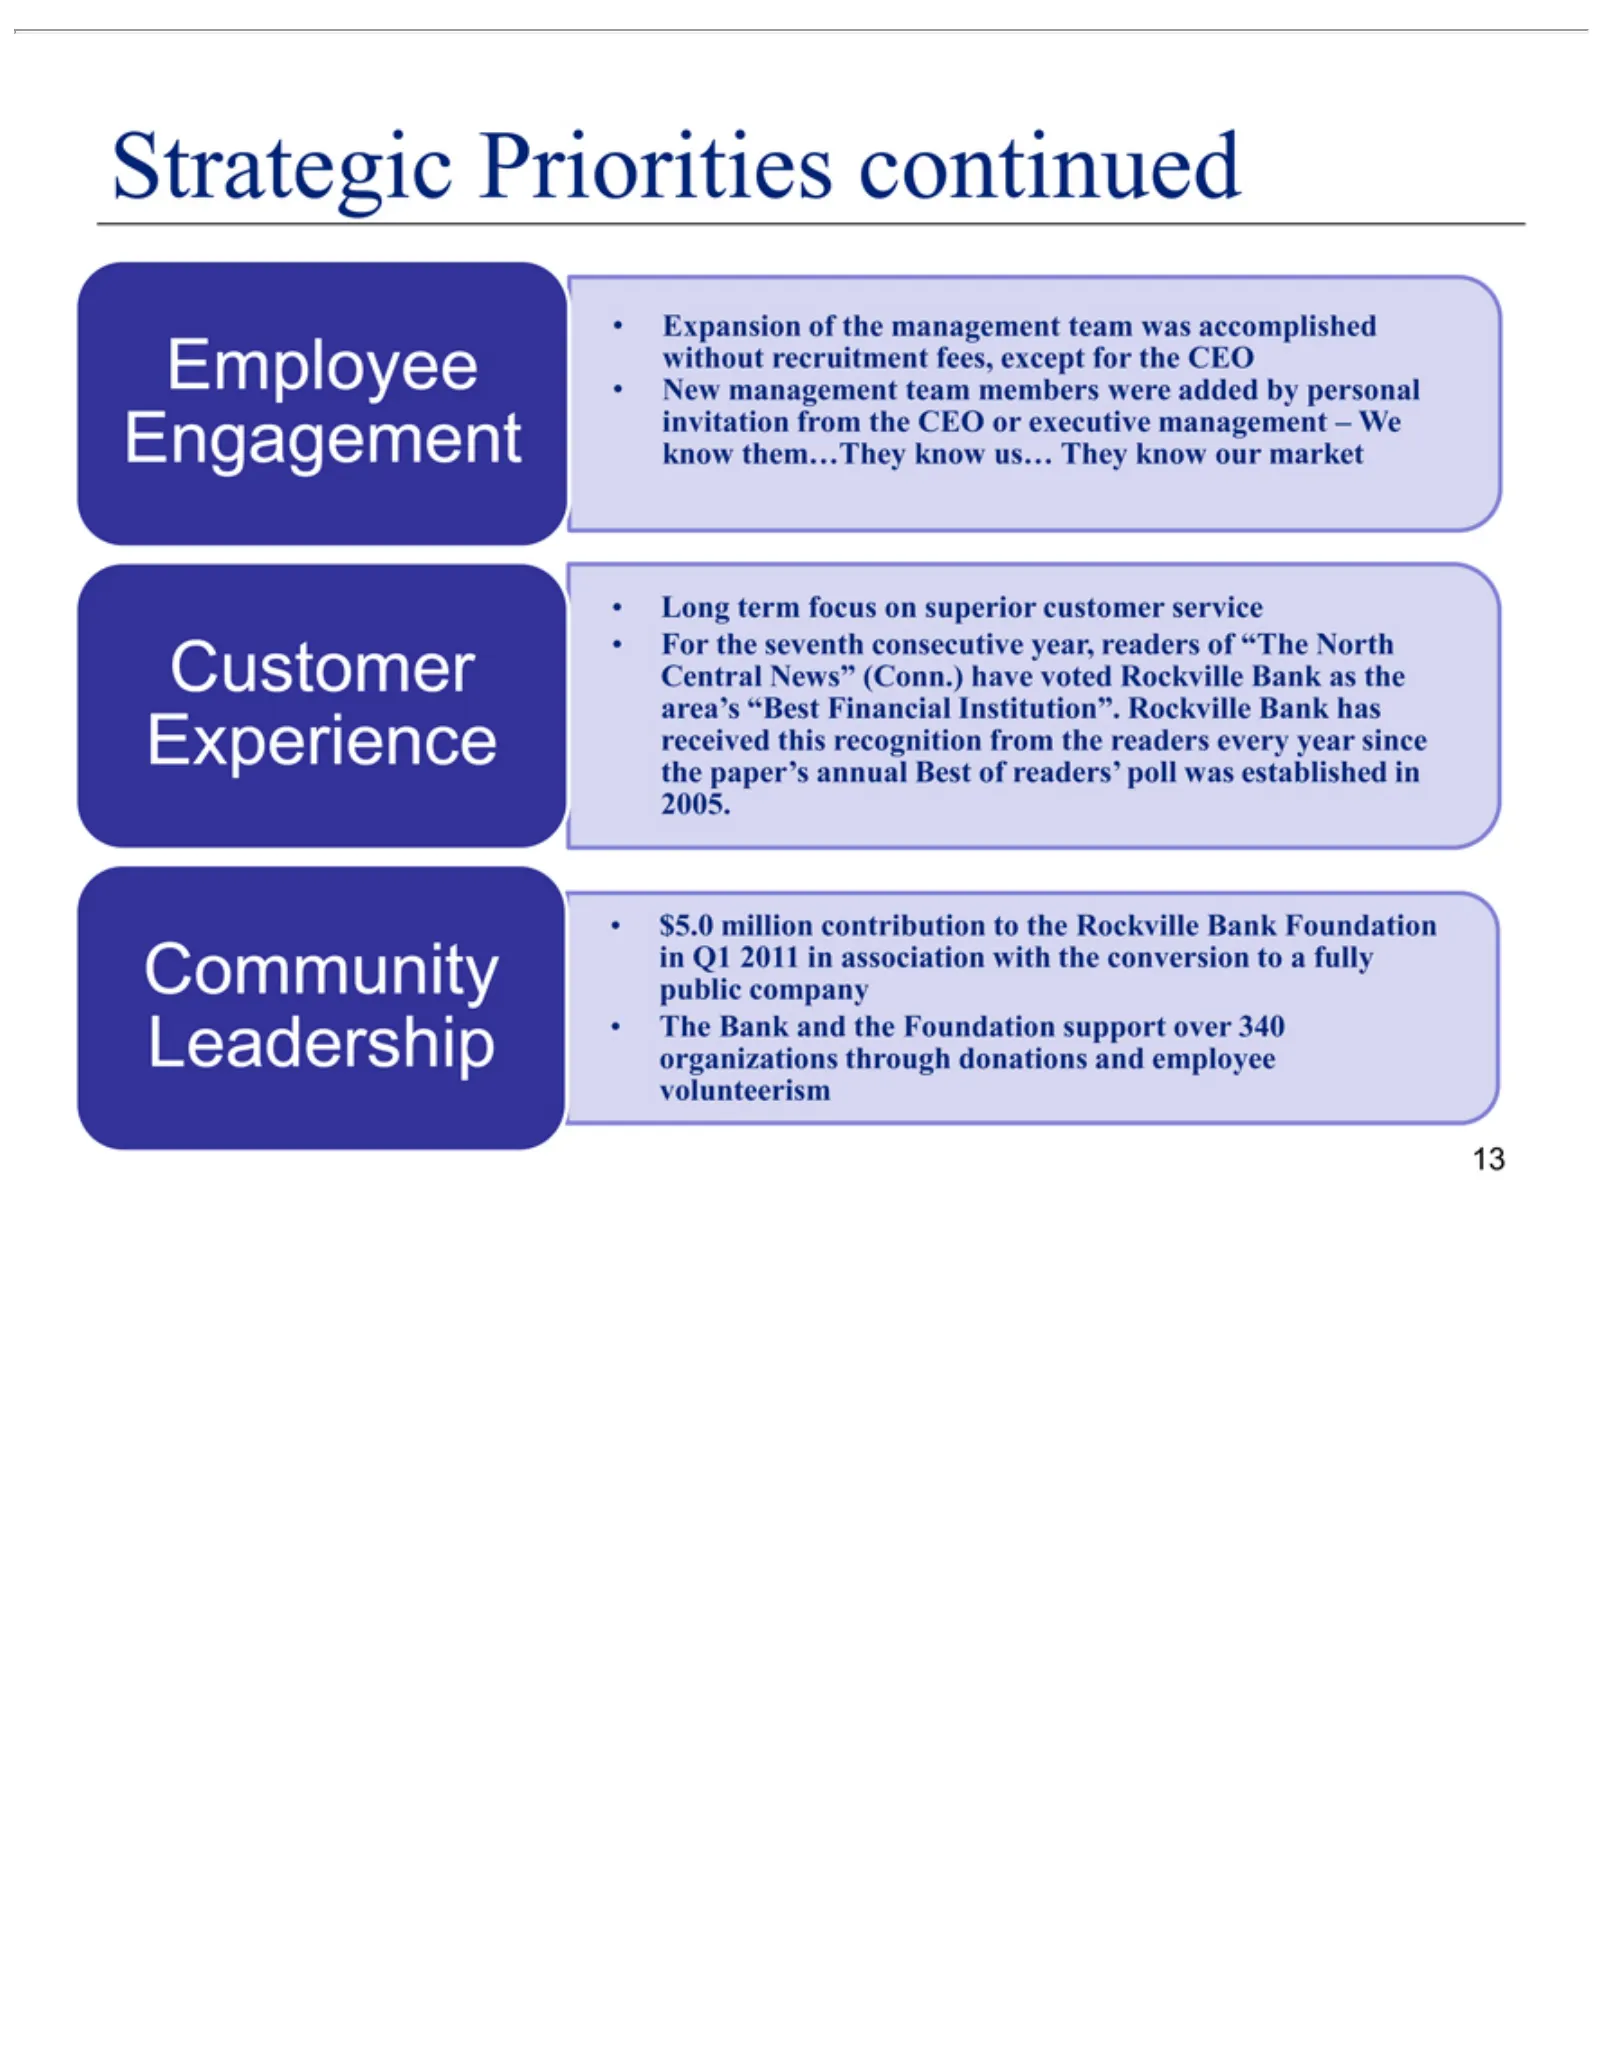
Slide 13: Strategic Priorities: Employee, Customer, Community
Strategic Employee Customer Community Expansion New Long For year $5.0 2005. employee 13 the since million management term seventh Priorities volunteerism Experience the Engagement focus ofLeadership contribution the paper’s consecutive on management team continued superior annual members to the yea
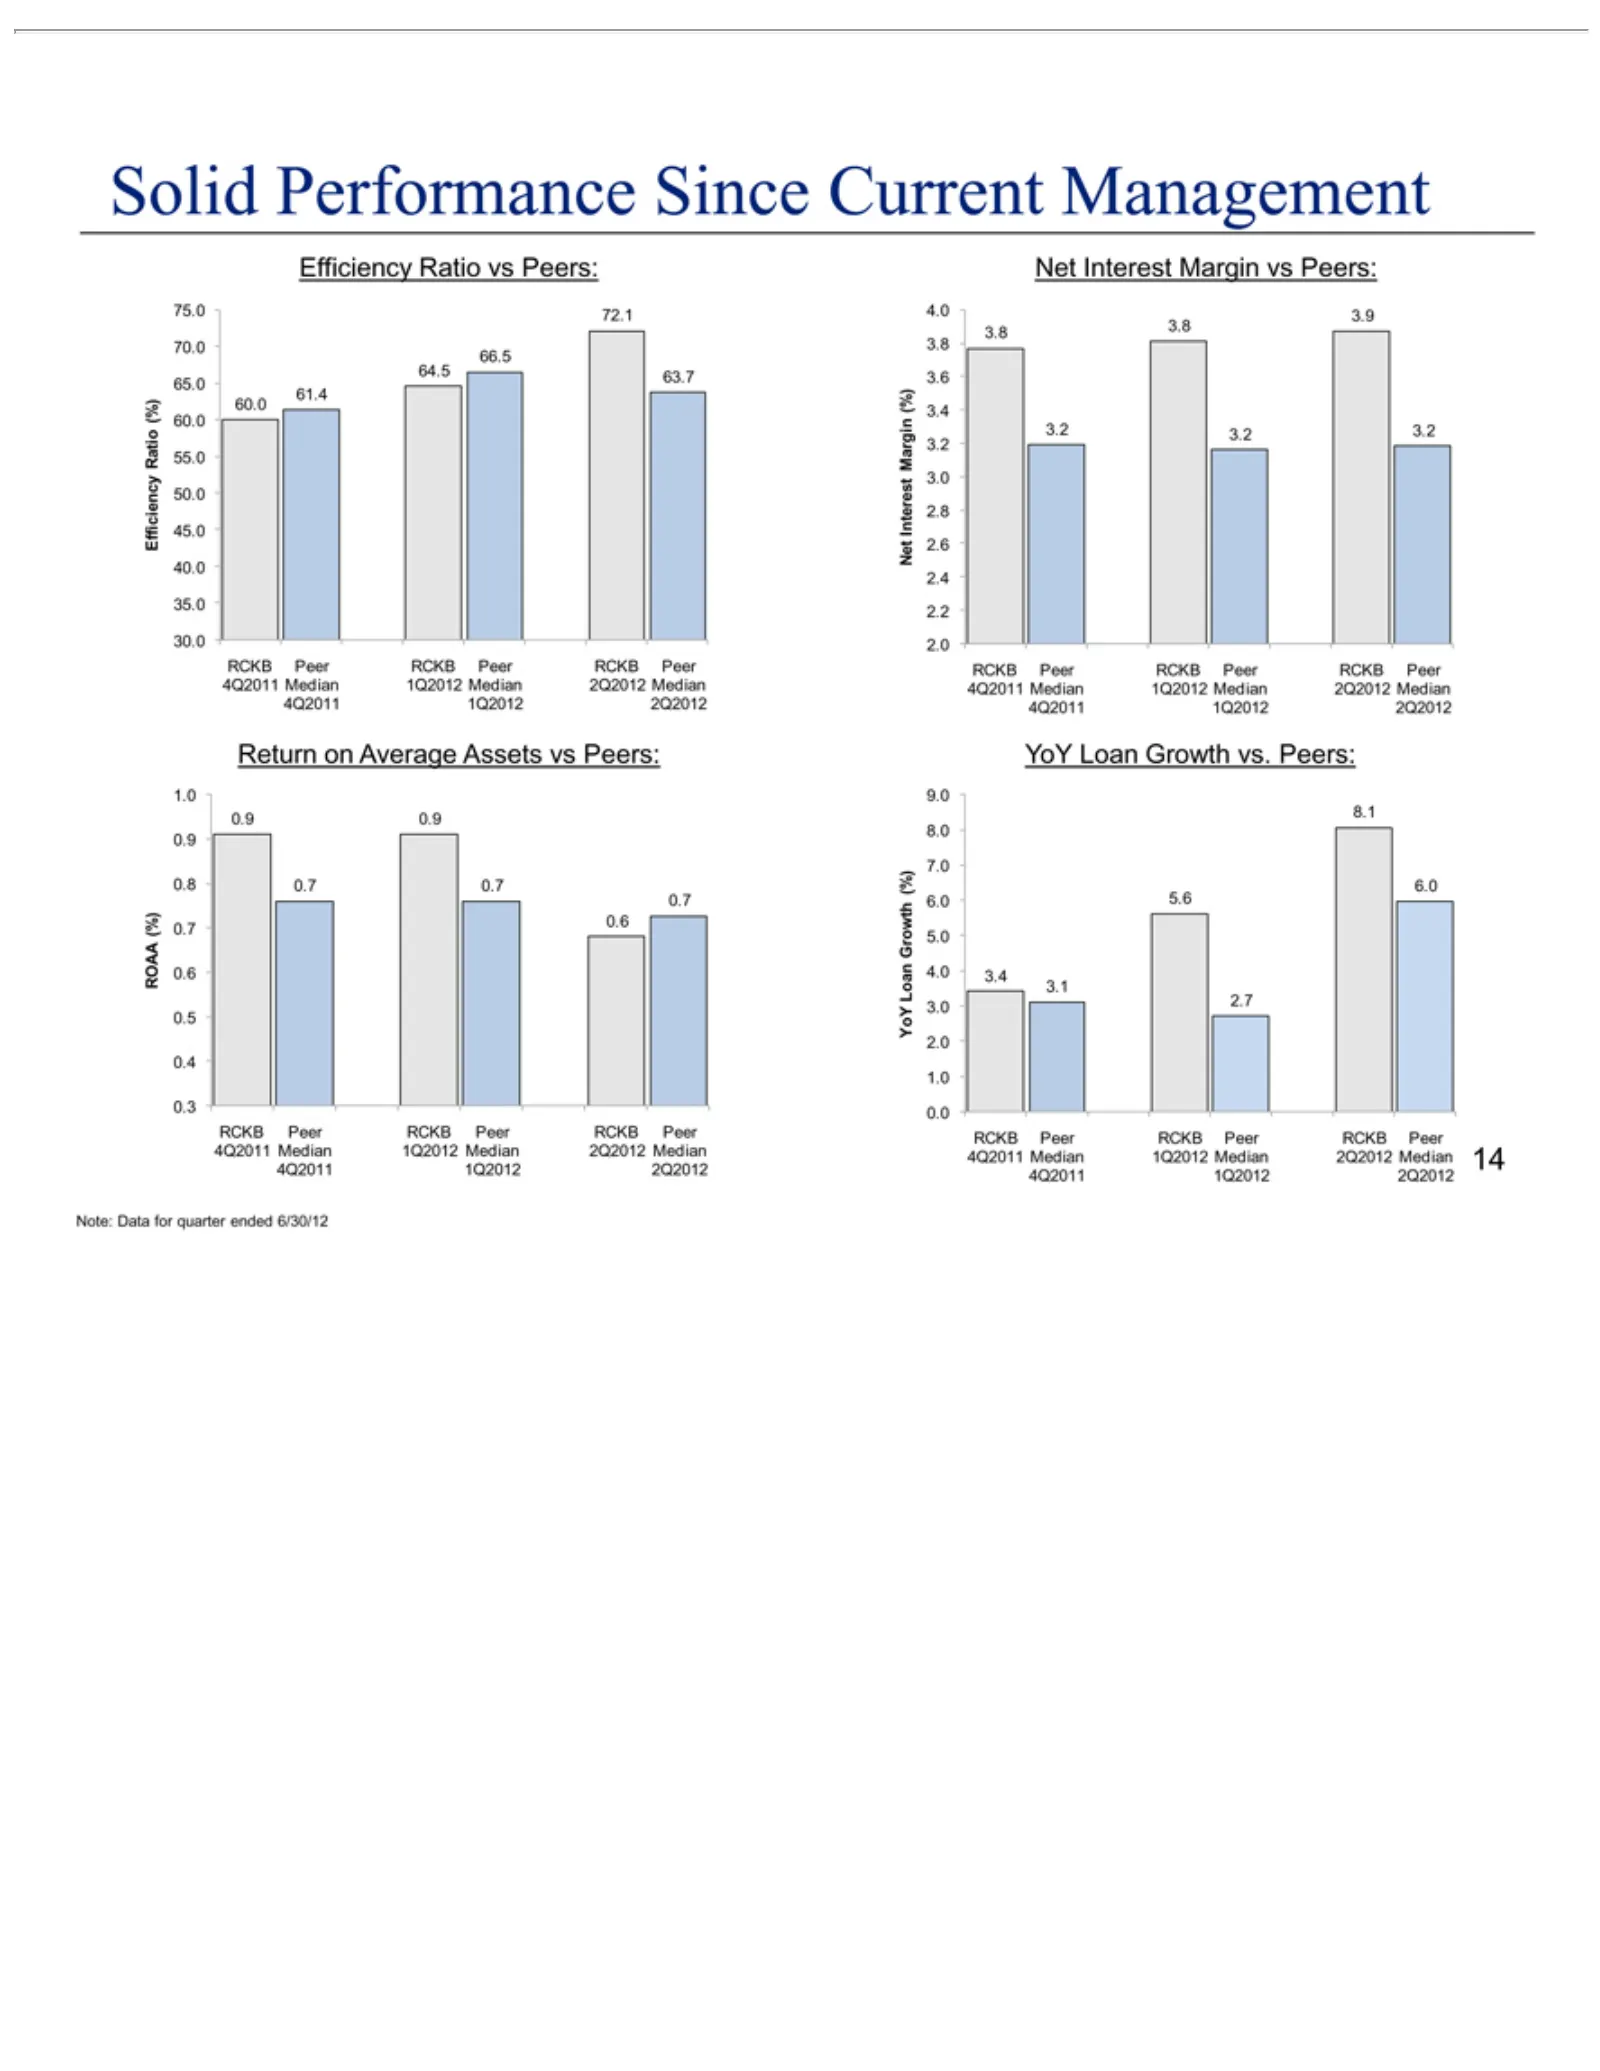
Slide 14: Solid Performance vs Peers
Solid Efficiency 75.0 64.5 70.0 30.0 35.0 40.0 45.0 50.0 55.0 60.0 61.4 65.0 63.7 Net 3.2 3.4 3.6 3.8 2.2 2.4 2.6 2.8 Return ROAA 0.8 0.9 0.3 0.4 0.5 0.6 0.7 YoY 6.0 7.0 8.0 8.1 9.0 4.0 5.0 3.0 RCKB 0.0 1.0 2.0 Note: 14 3.8 3.2 0.9 0.7 5.6 3.4 2.7 Interest 72.1 66.5 Loan Performance Data on Peer 3.9
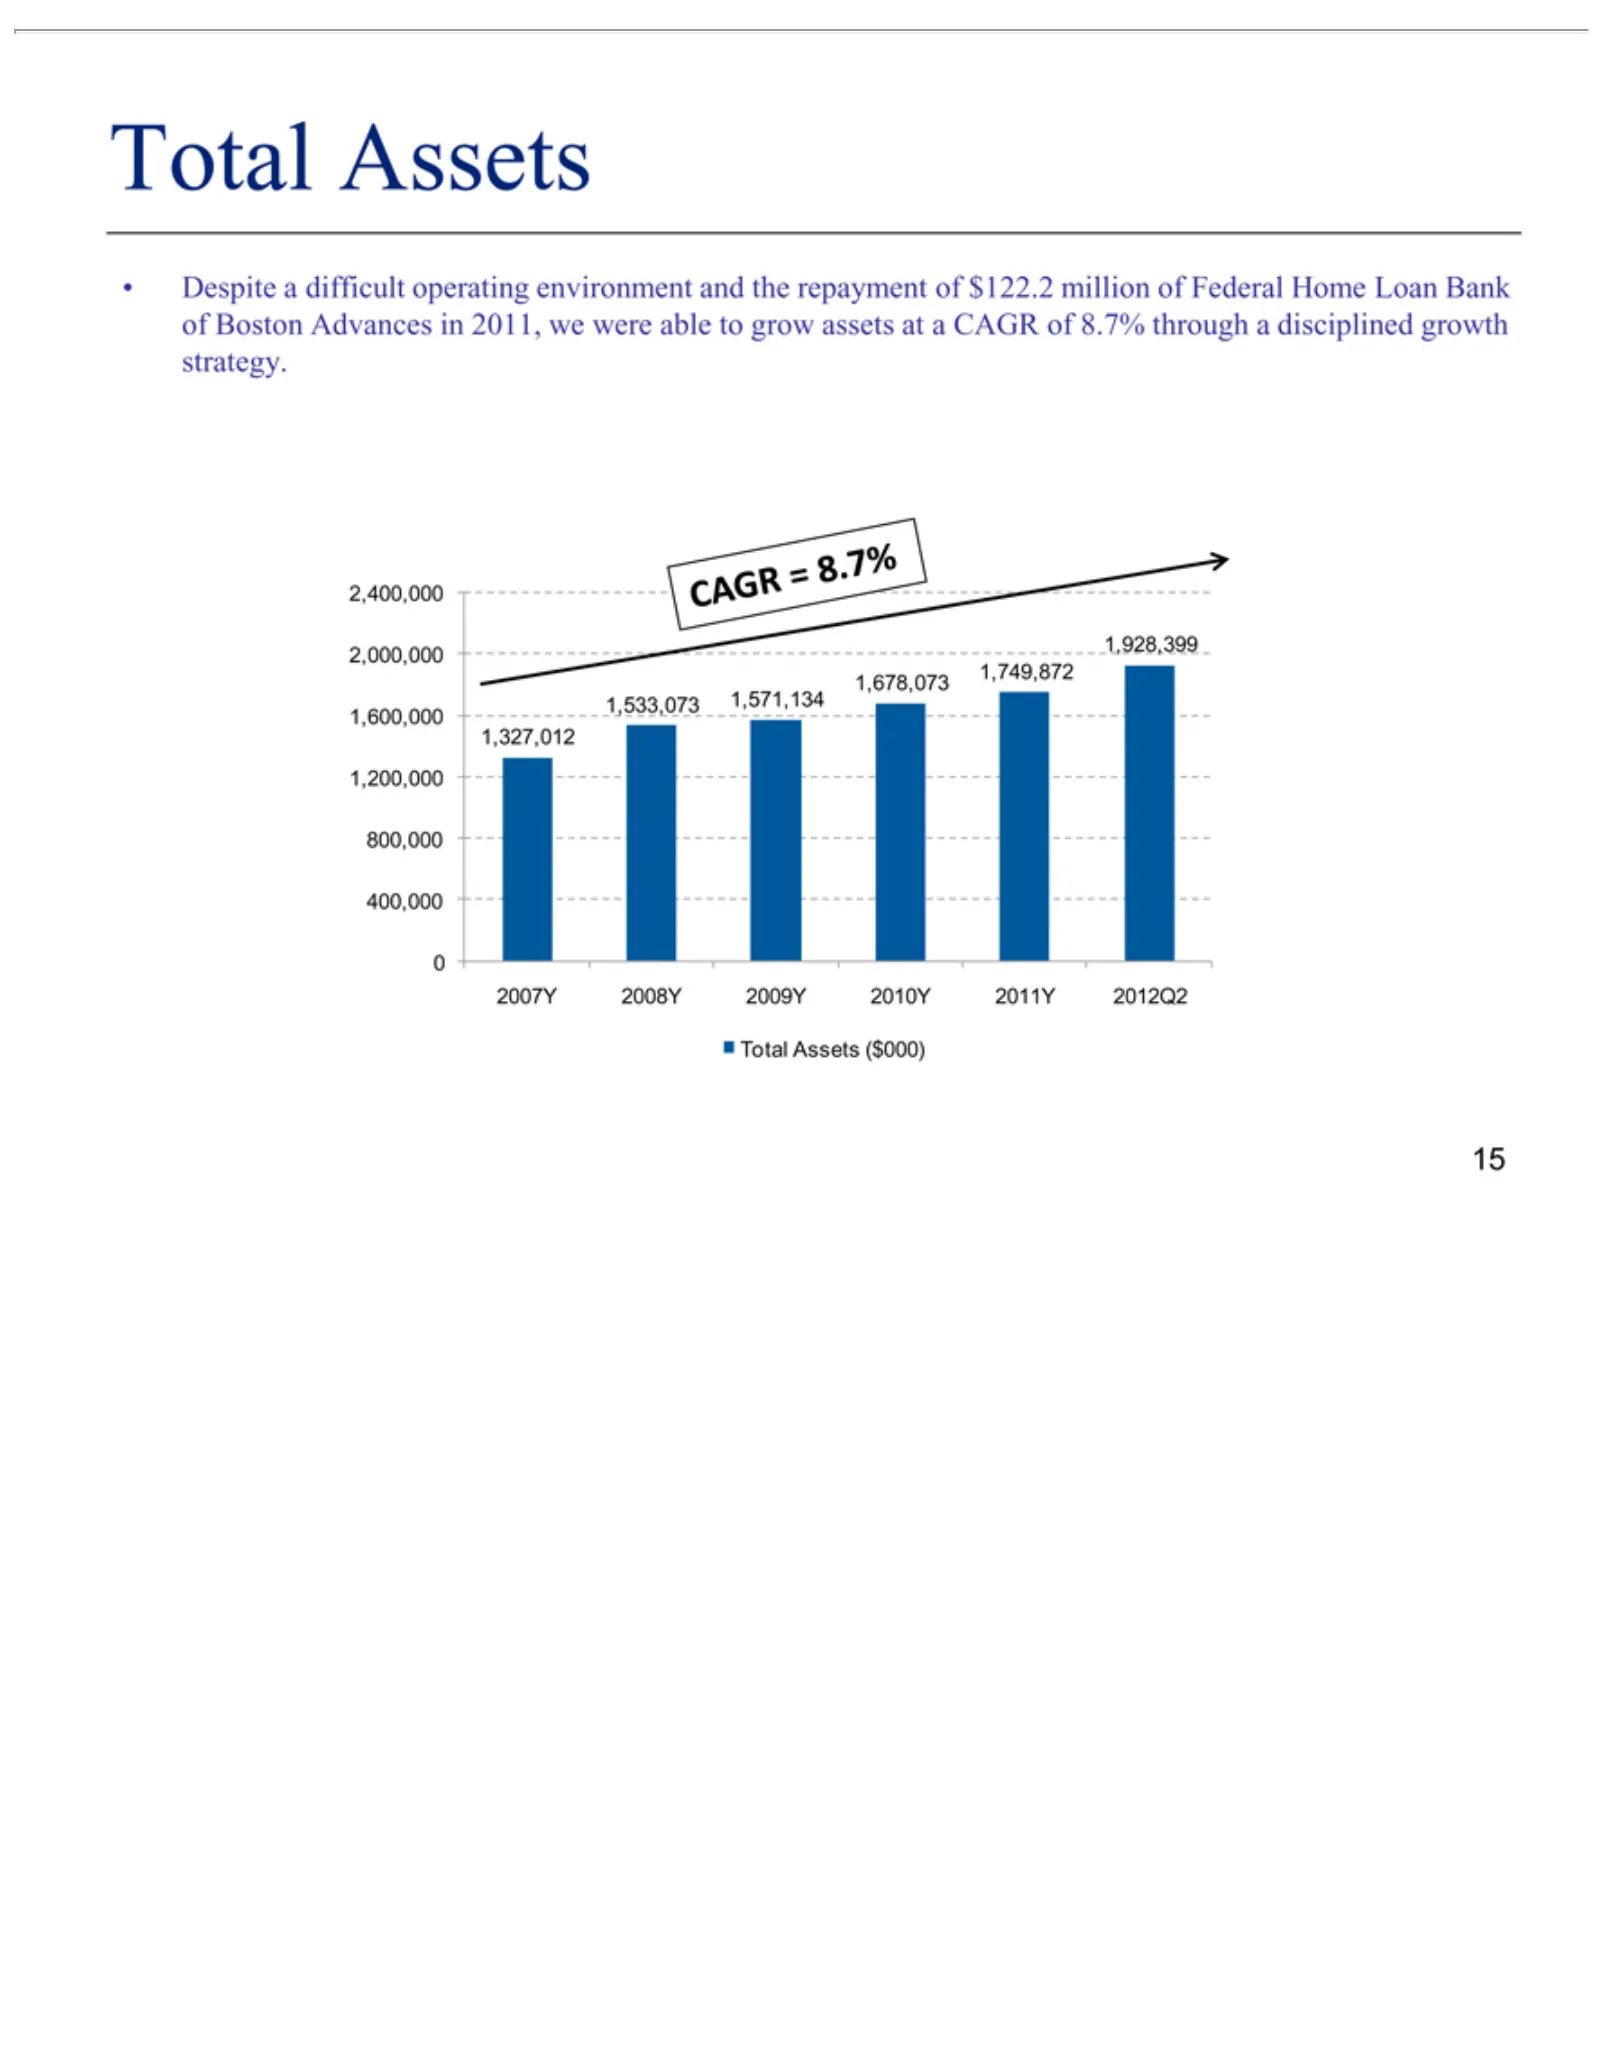
Slide 15: Total Assets Growth
01• ,928,399 400,000 800,000 1,200,000 1,600,000 2,000,000 2,400,000 strategy. 2007Y 1,327,012 Total 15Despite Assets 2008Y a1,749,872 difficult ($000) 2009Y operating 1,678,073 2010Y 2011Y environment 1,533,073 2012Q2 1,571,134 and the repayment of $122.2 million of Federal Home Loan Bank of Boston
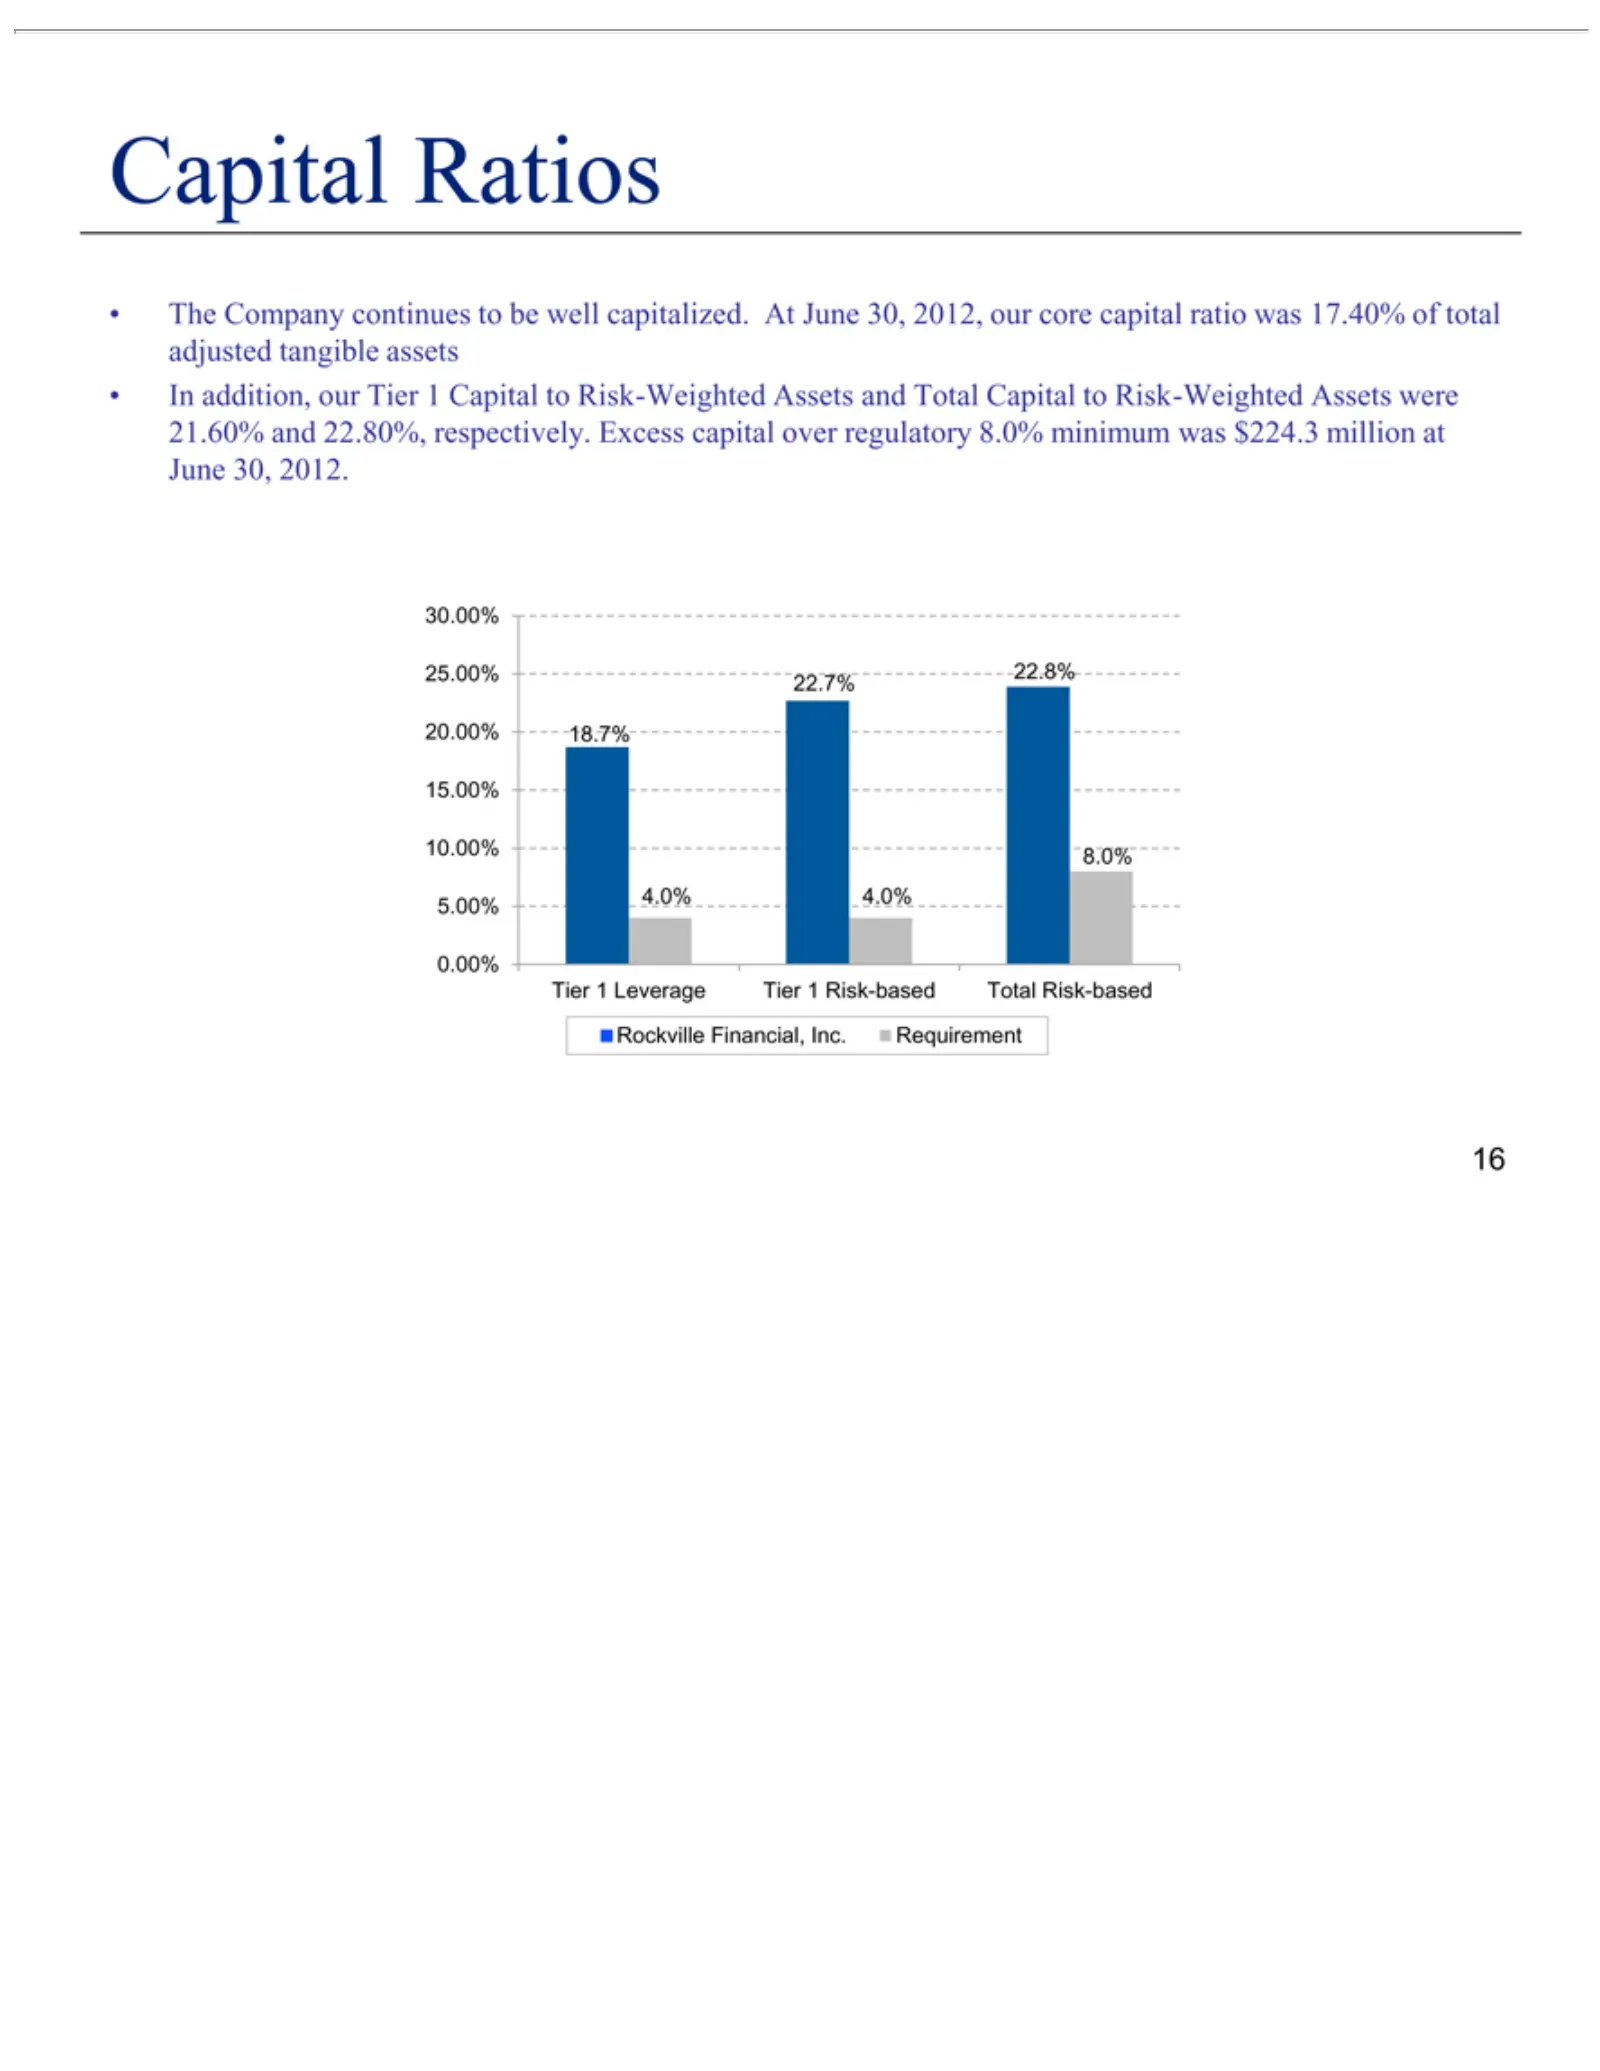
Slide 16: Capital Ratios
•Capital 21.60% 25.00% 30.00% 20.00% 22.7% 10.00% 15.00% 4.0% Tier 0.00% 5.00% Rockville 16 The In addition, 14.0% Company Leverage Ratios and 22.8% 18.7% 8.0% Financial, 22.80%, ourcontinues Tier TierInc. 1respectively. 1Risk-based Capital Requirement to be to well Risk-Weighted Excess Total capita
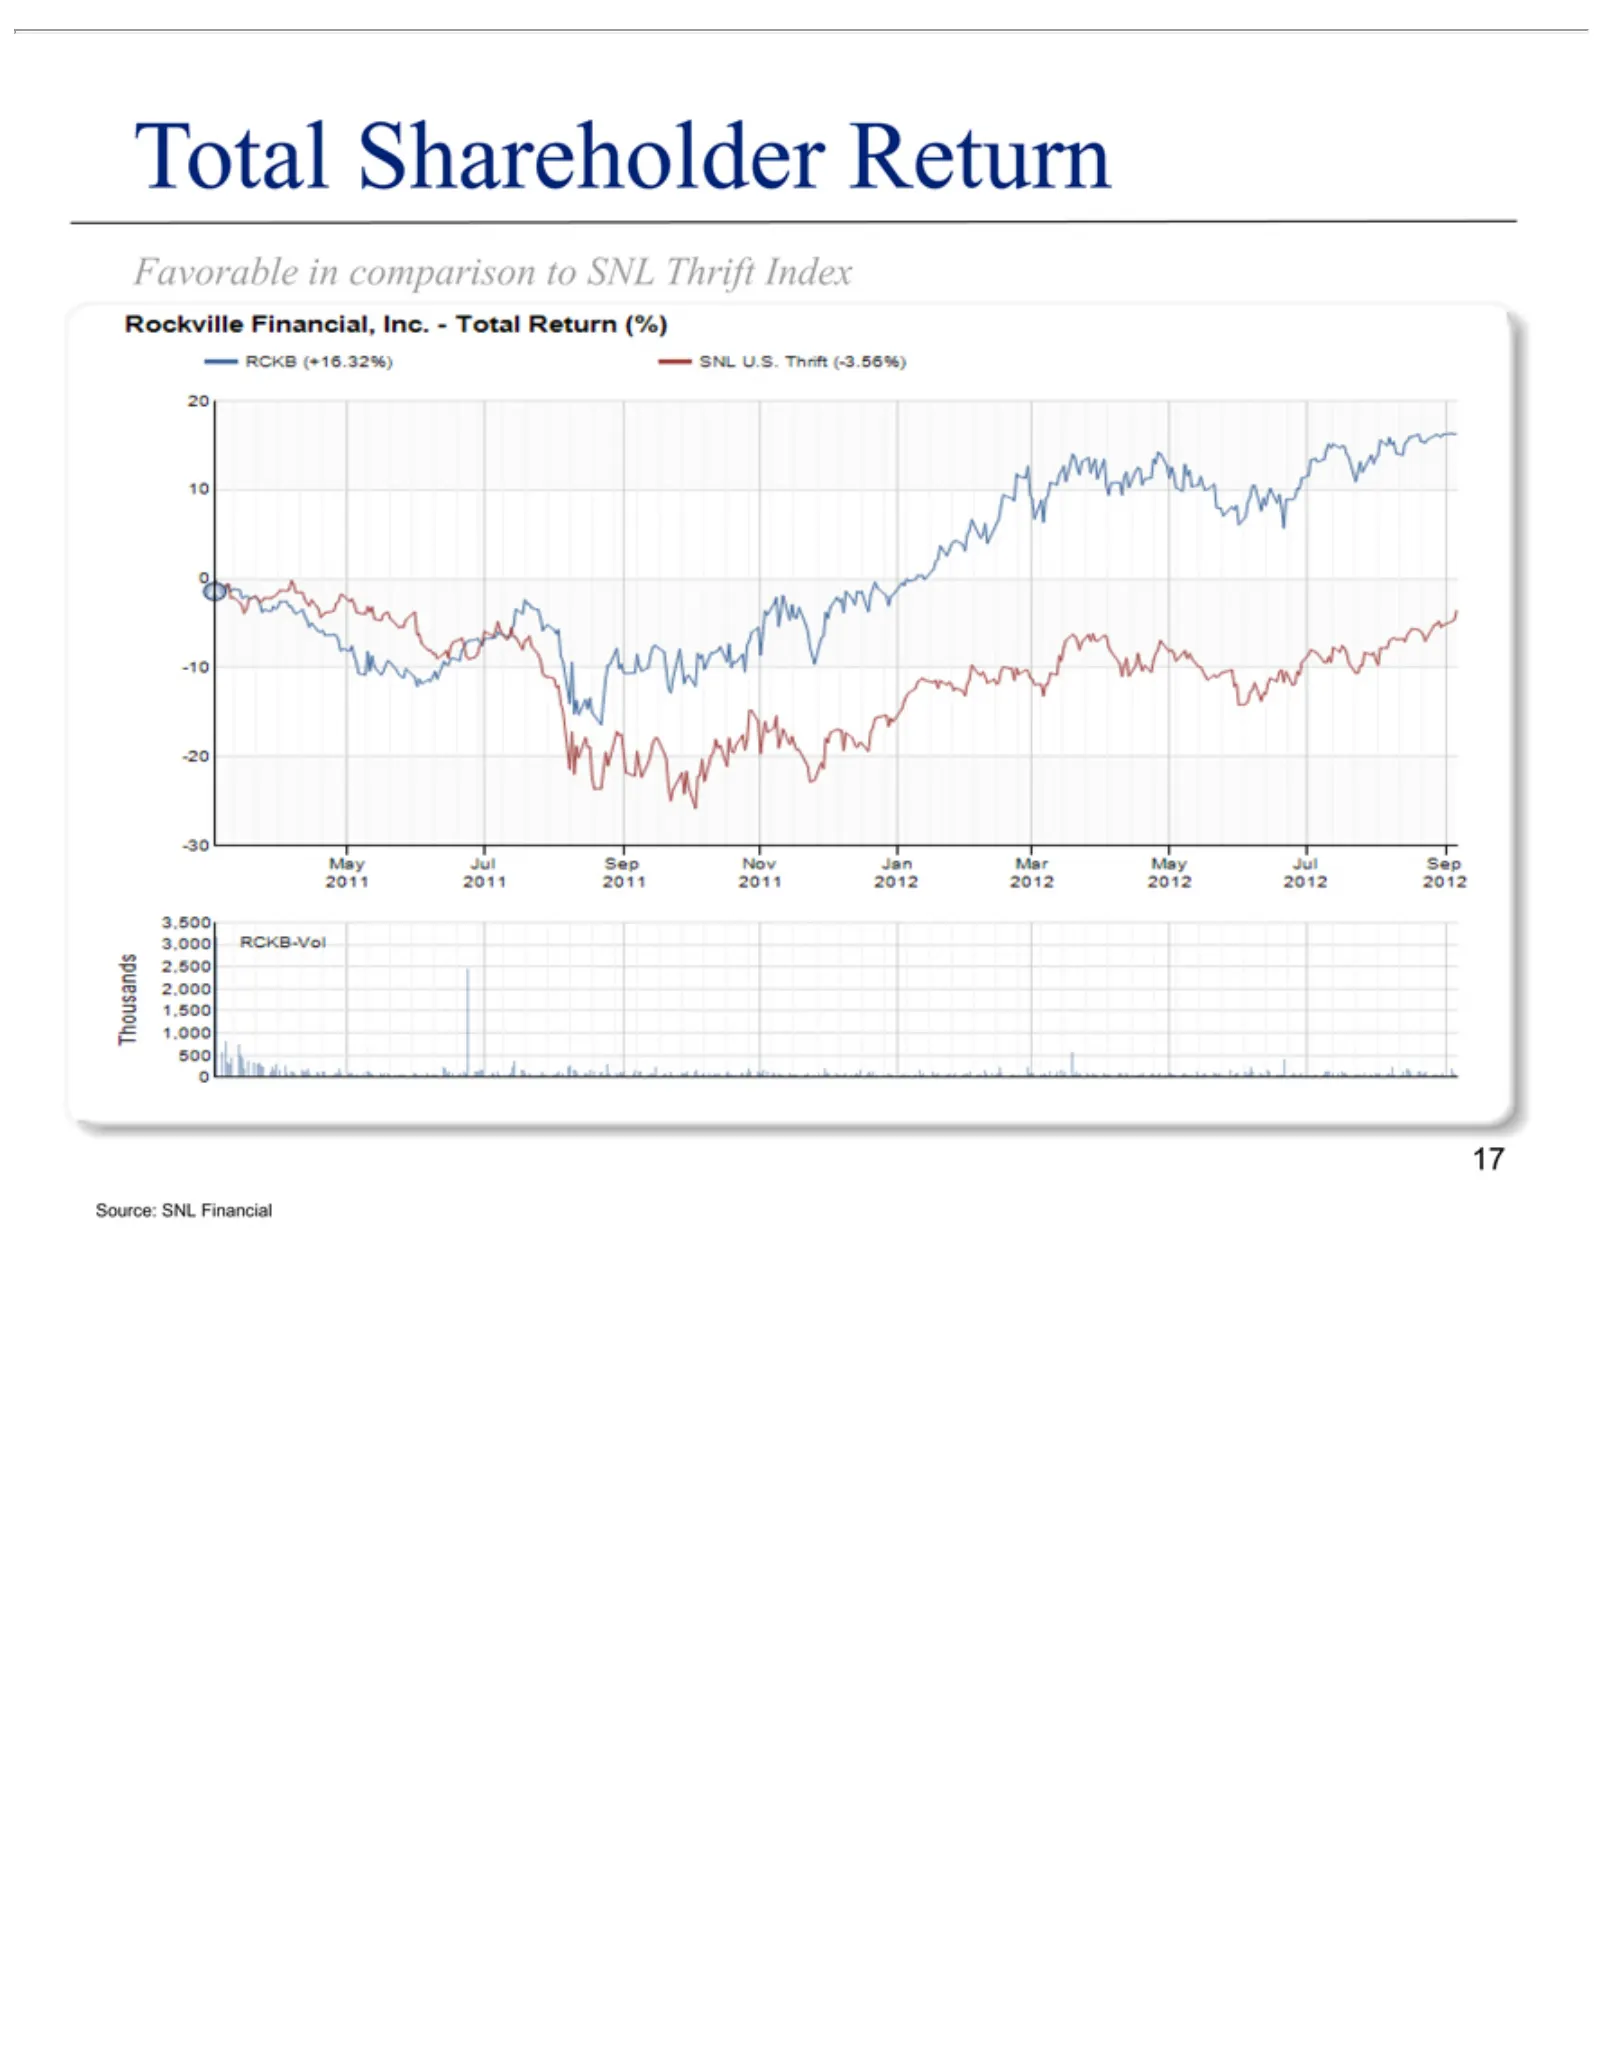
Slide 17: Total Shareholder Return vs SNL Thrift Index
Total Shareholder Favorable Source: 17 SNL in comparison Financial Return to SNL Thrift Index
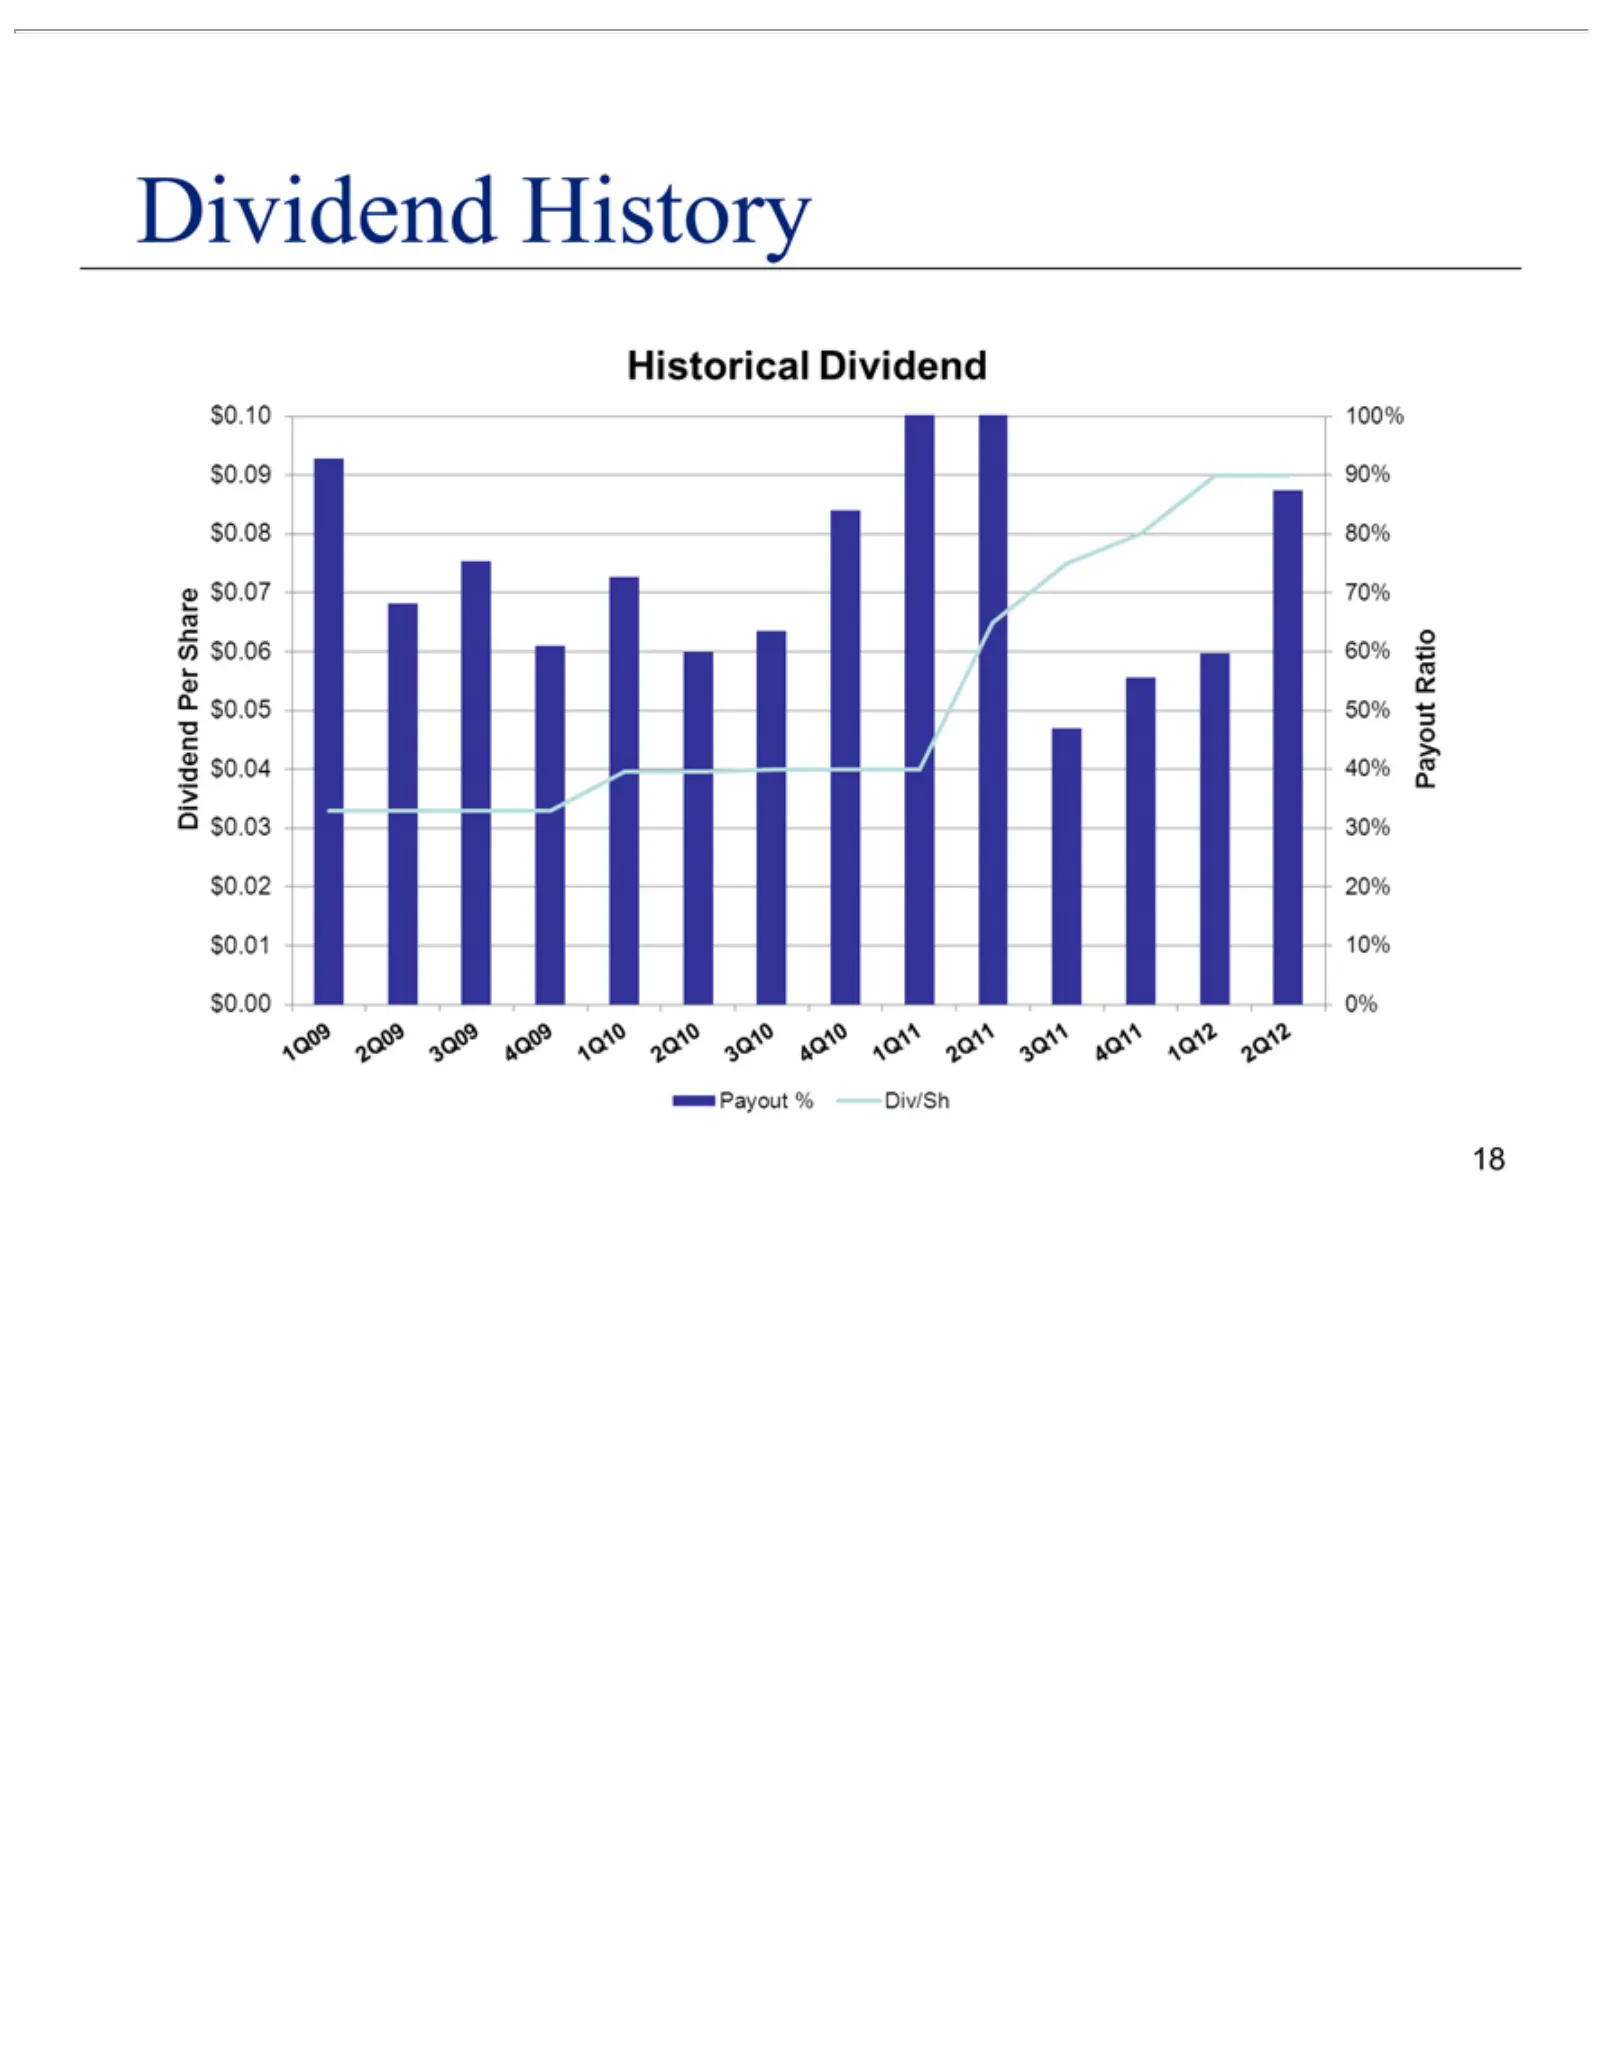
Slide 18: Dividend History
HistoricalPer Dividend 18 History Dividend Share
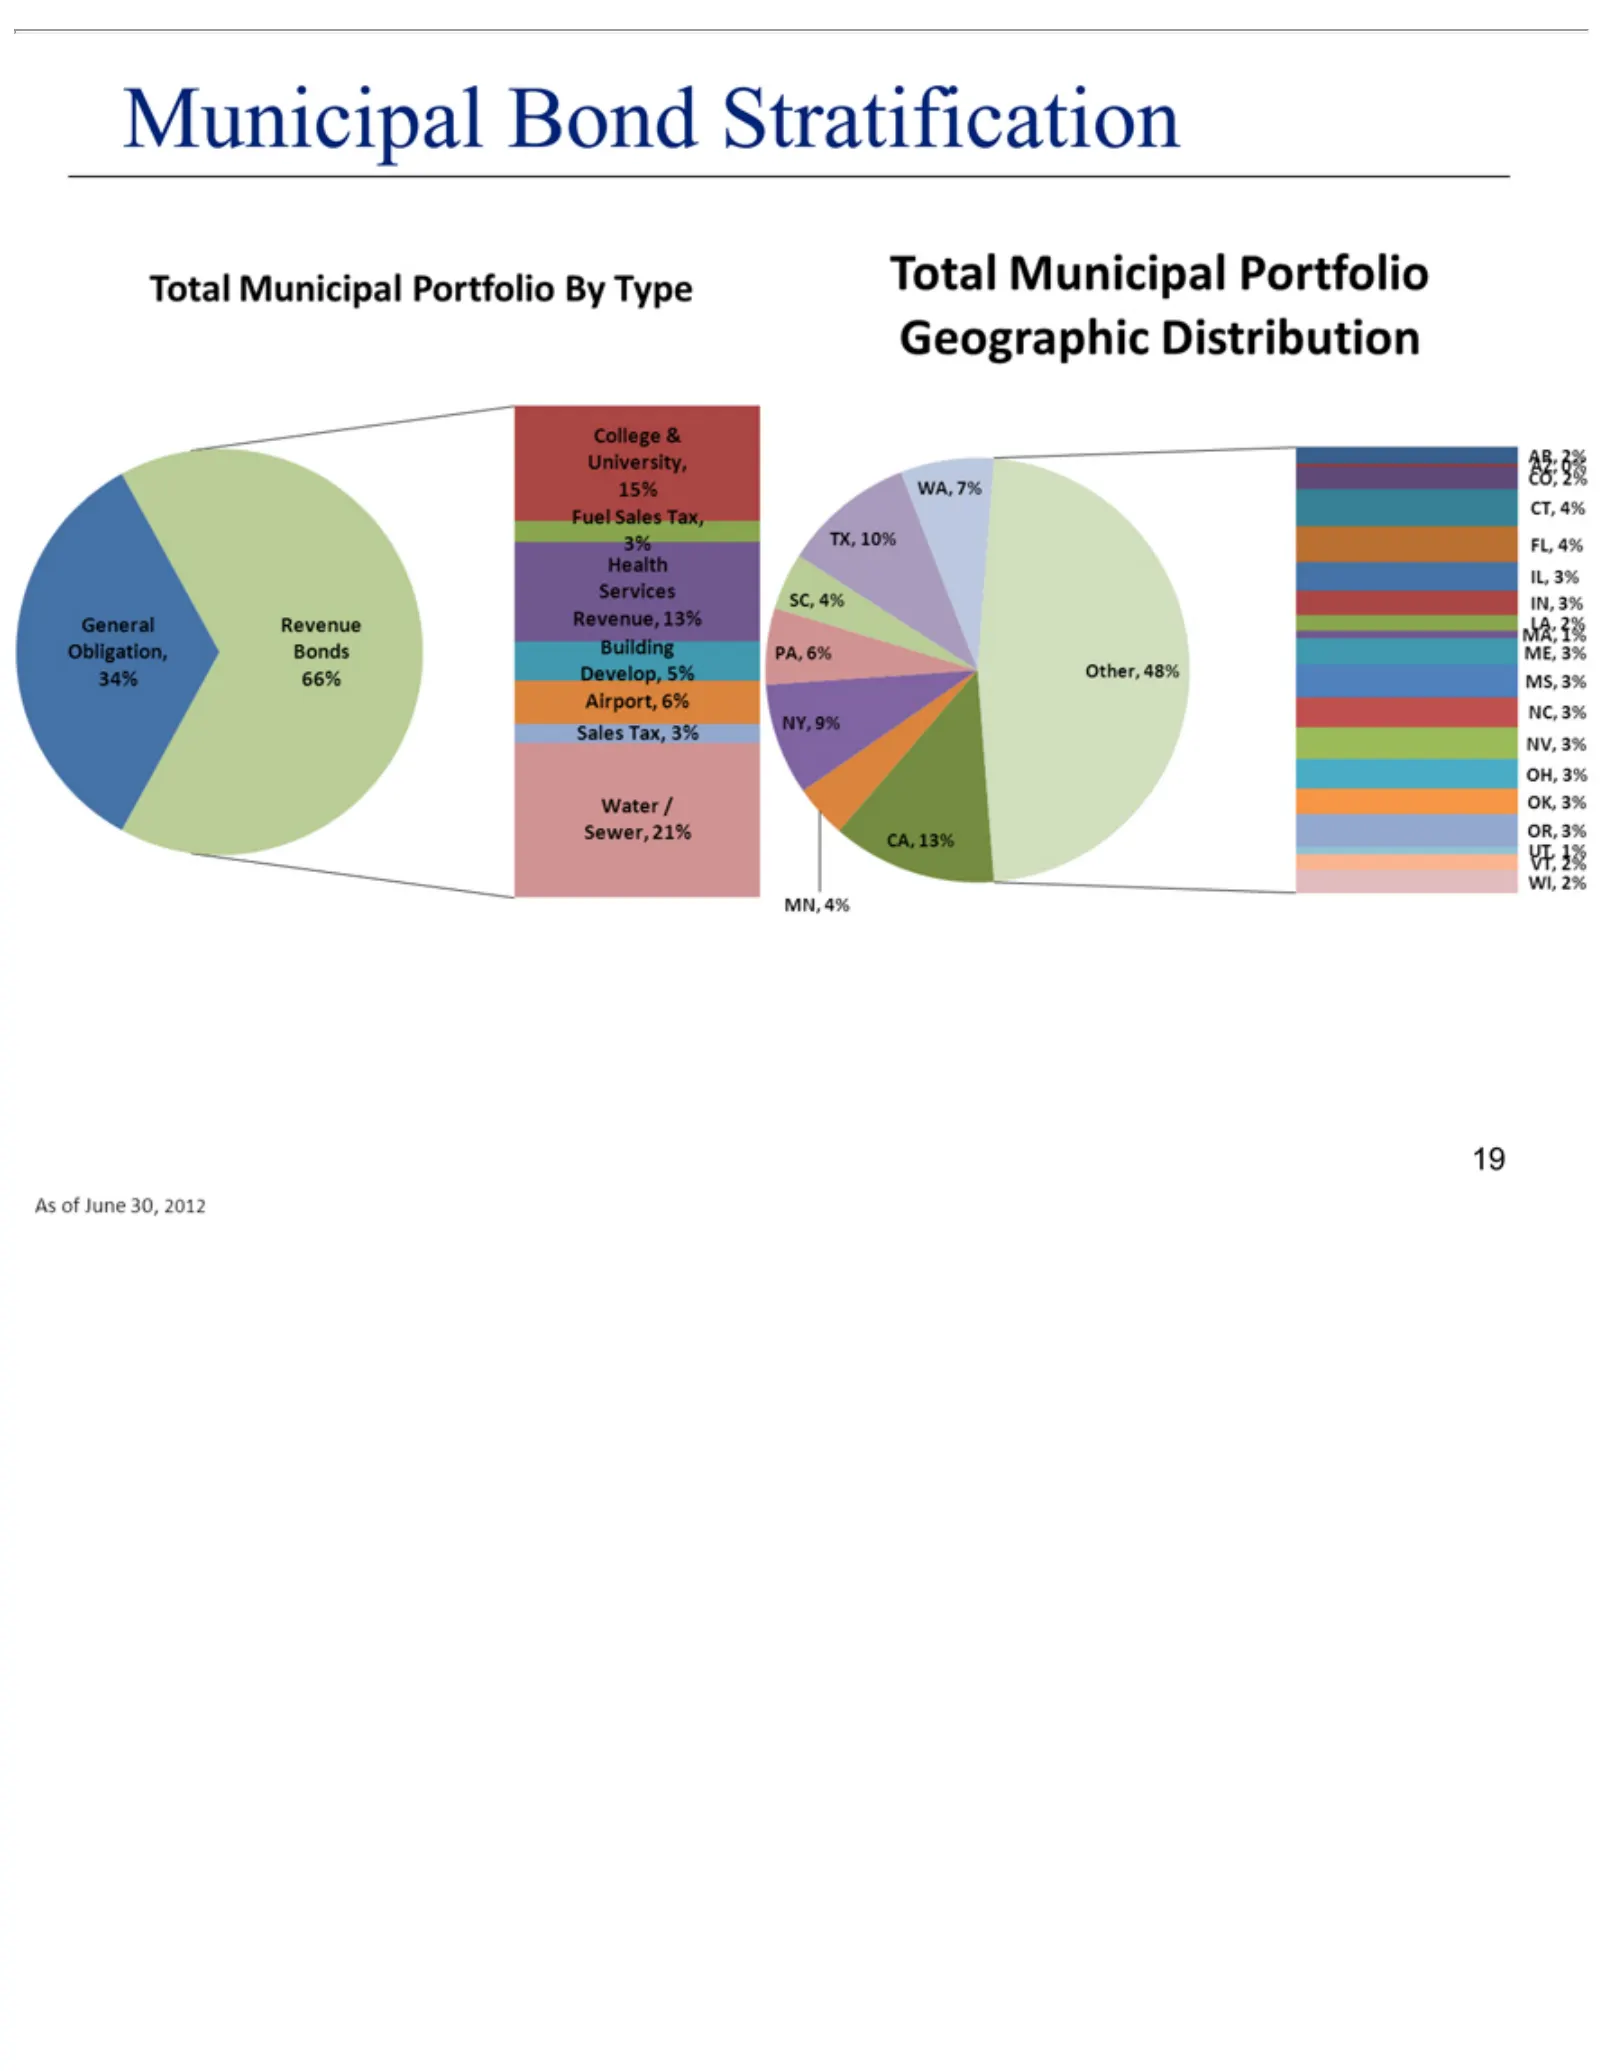
Slide 19: Municipal Bond Portfolio Stratification
Municipal Total As 19 of Municipal June Bond 30, 2012 Portfolio Stratification By Type Geographic Distribution
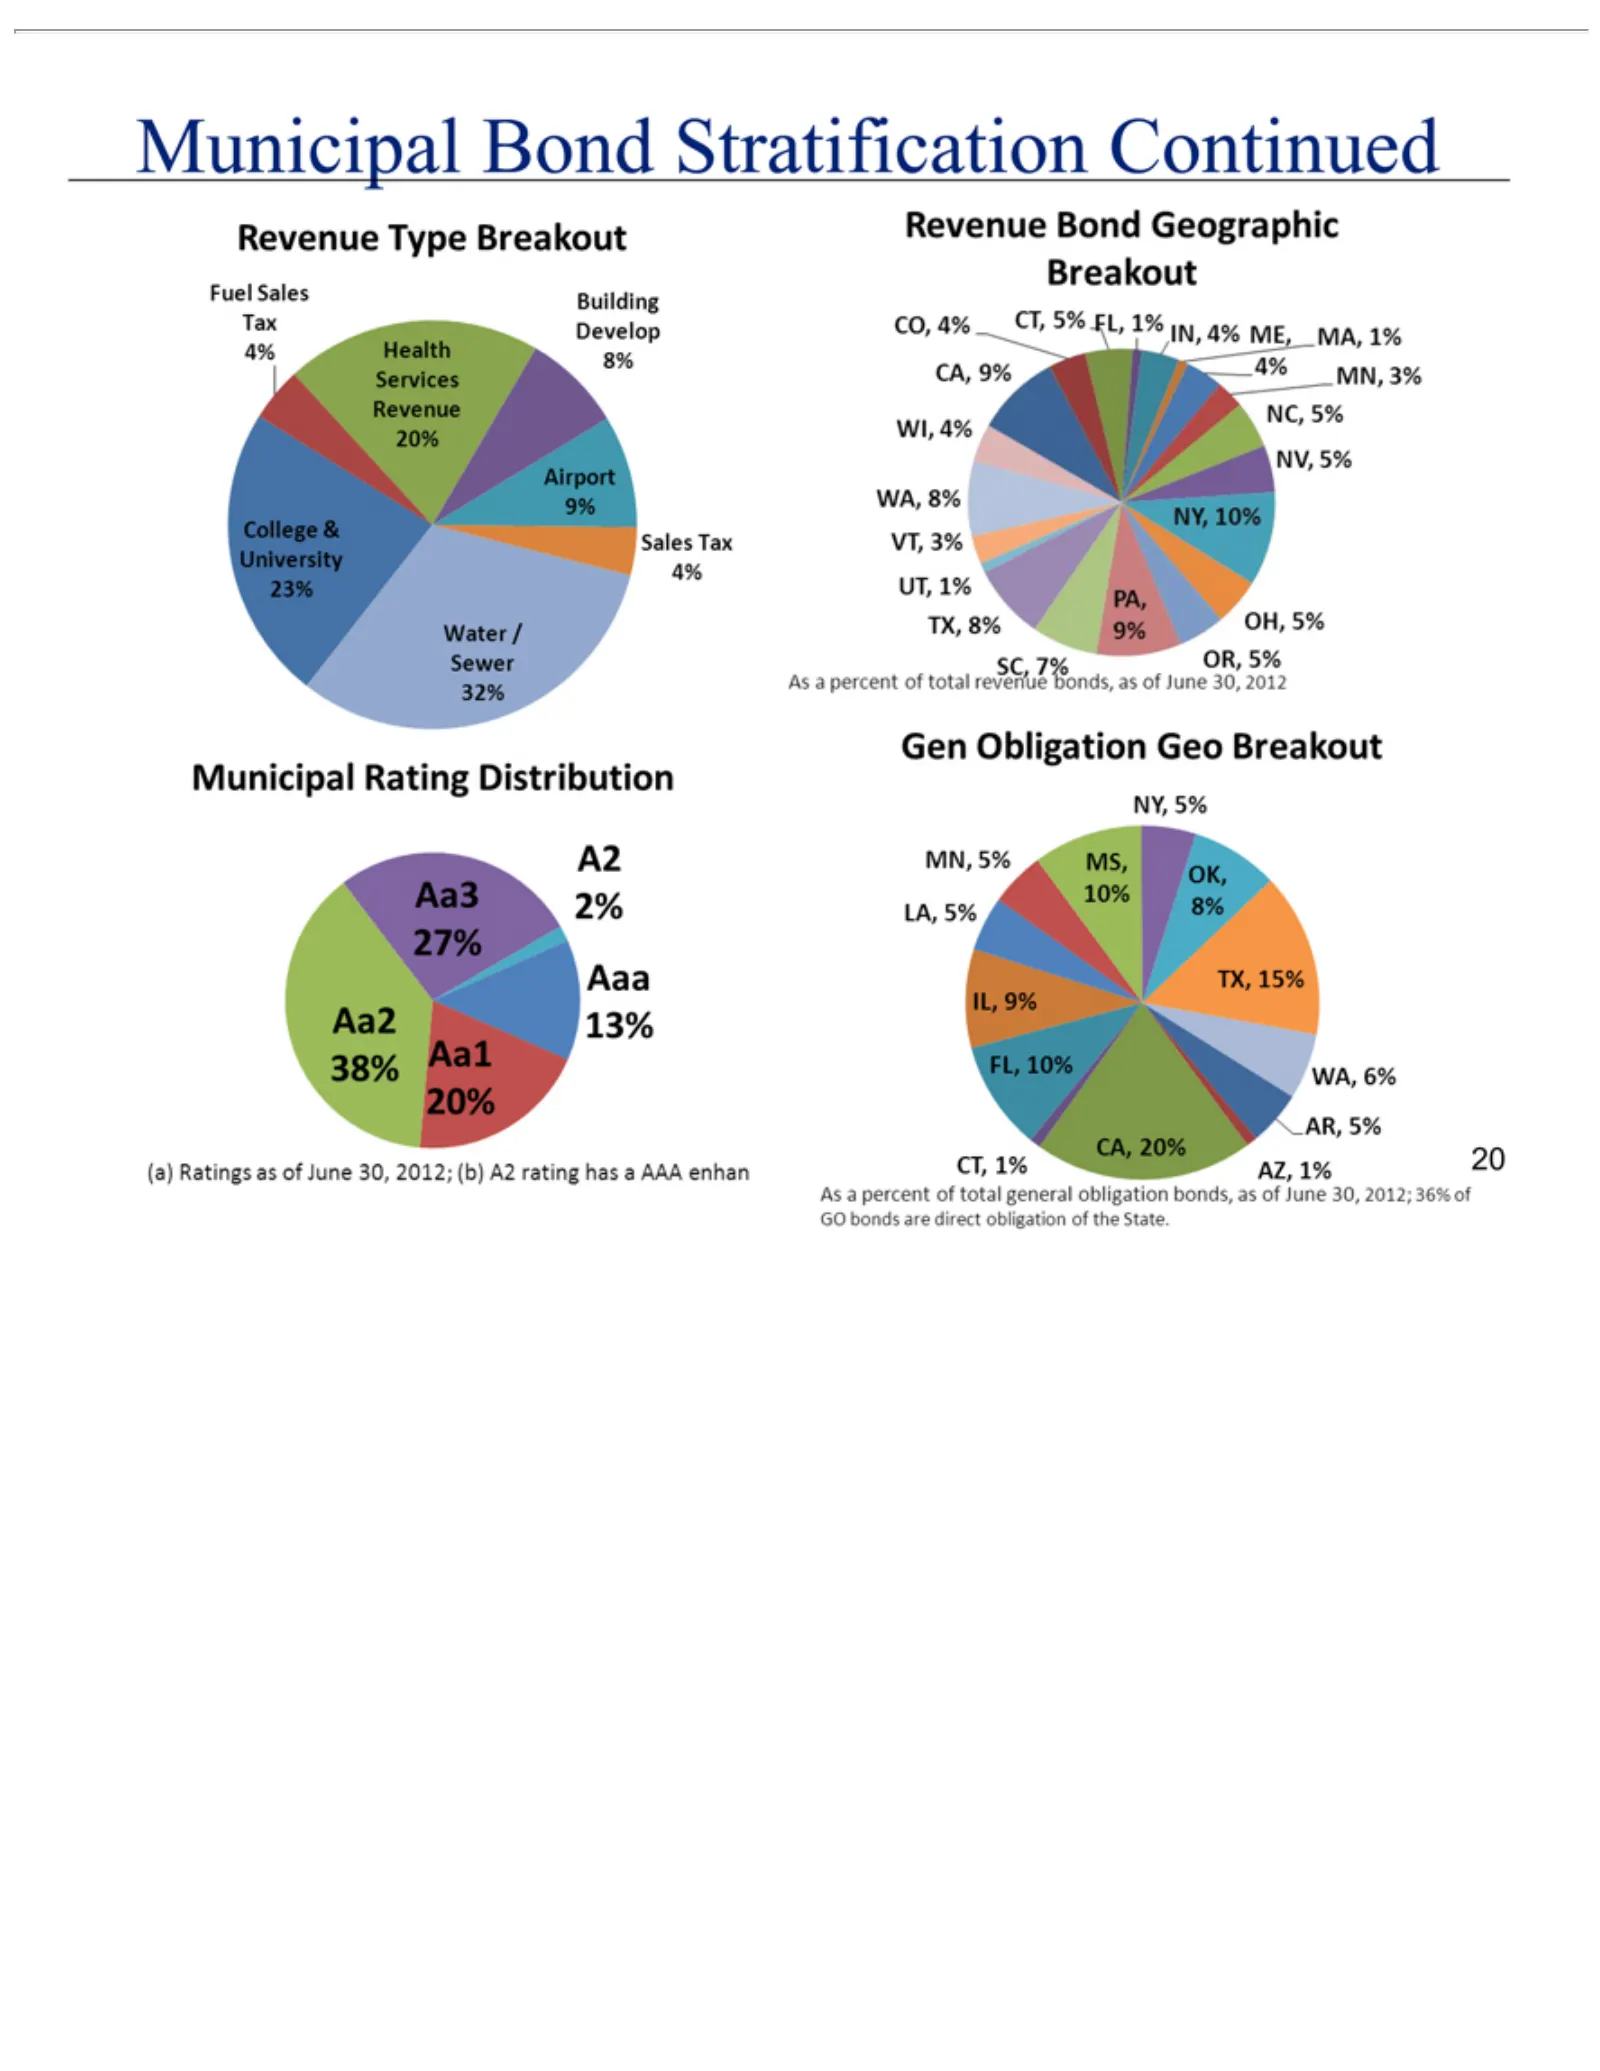
Slide 20: Municipal Bond Portfolio Breakout
Revenue Municipal Gen 20 Obligation Type Bond Bond Rating Breakout Geographic Geo Stratification Distribution BreakoutBreakout Continued
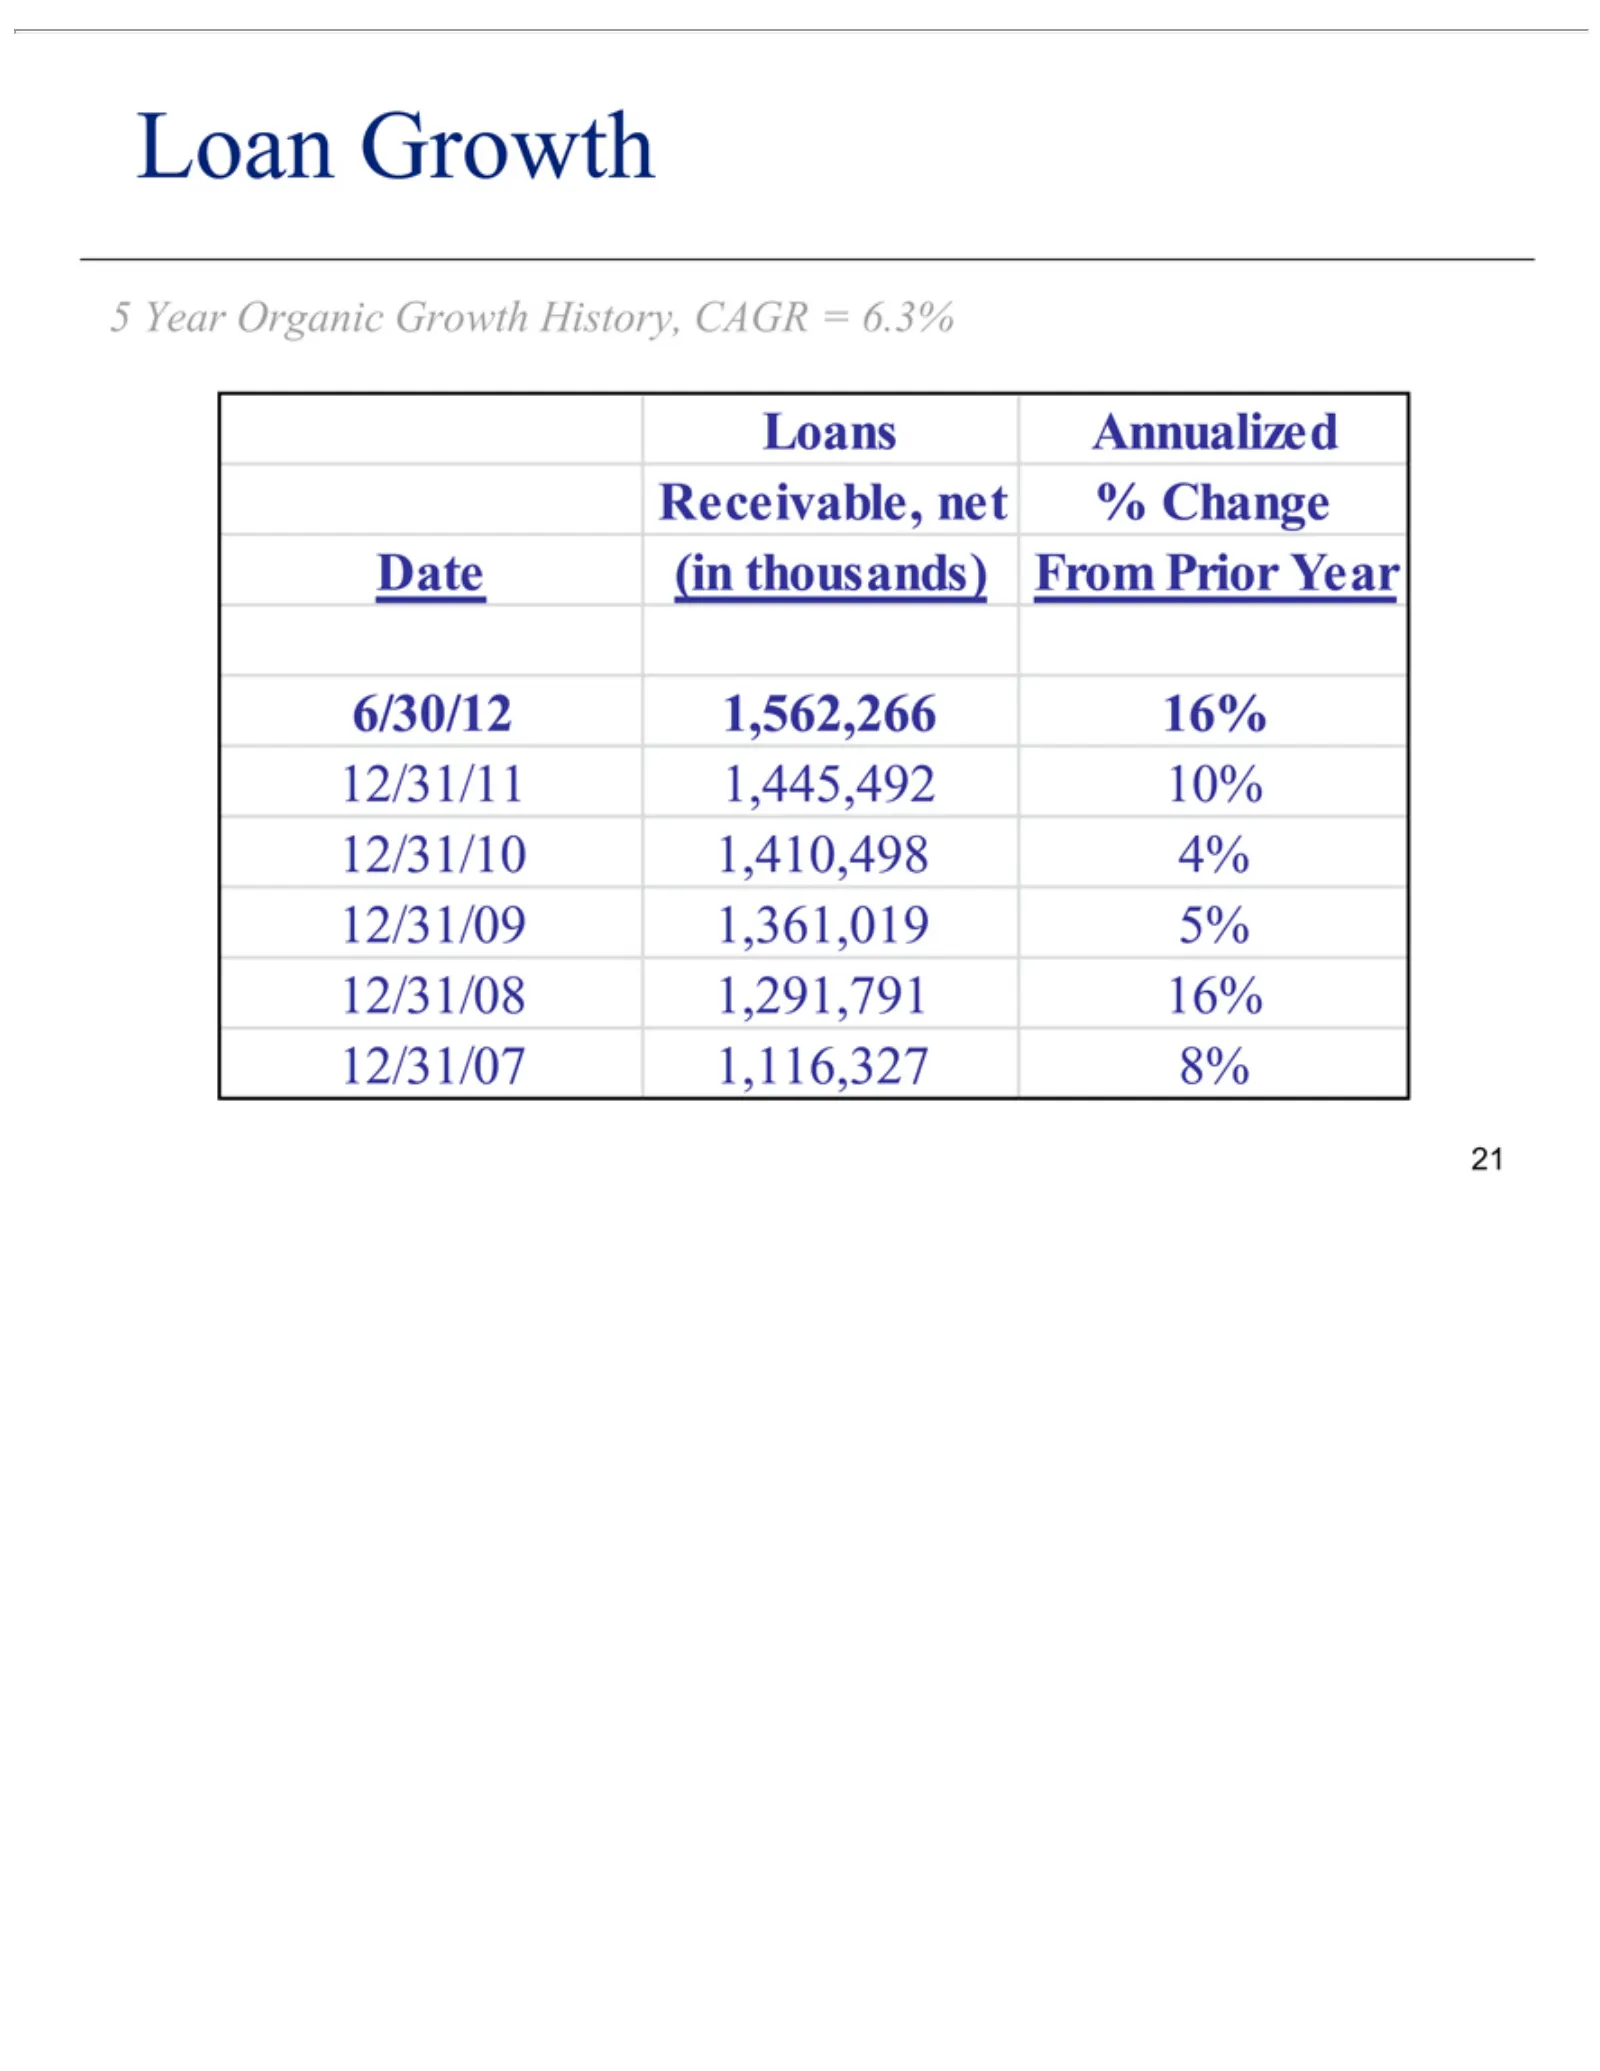
Slide 21: Loan Growth
5Loan Growth Loans(in Year Receivable, Date 6/30/12 12/31/11 12/31/10 12/31/09 12/31/08 12/31/07 21 Organic Annualized 1,562,266 thousands) 1,445,492 1,410,498 1,361,019 1,291,791 1,116,327 net Growth % Change 16% 10% 8% 4% 5% 16% From PriorHistory, Year CAGR = 6.3%
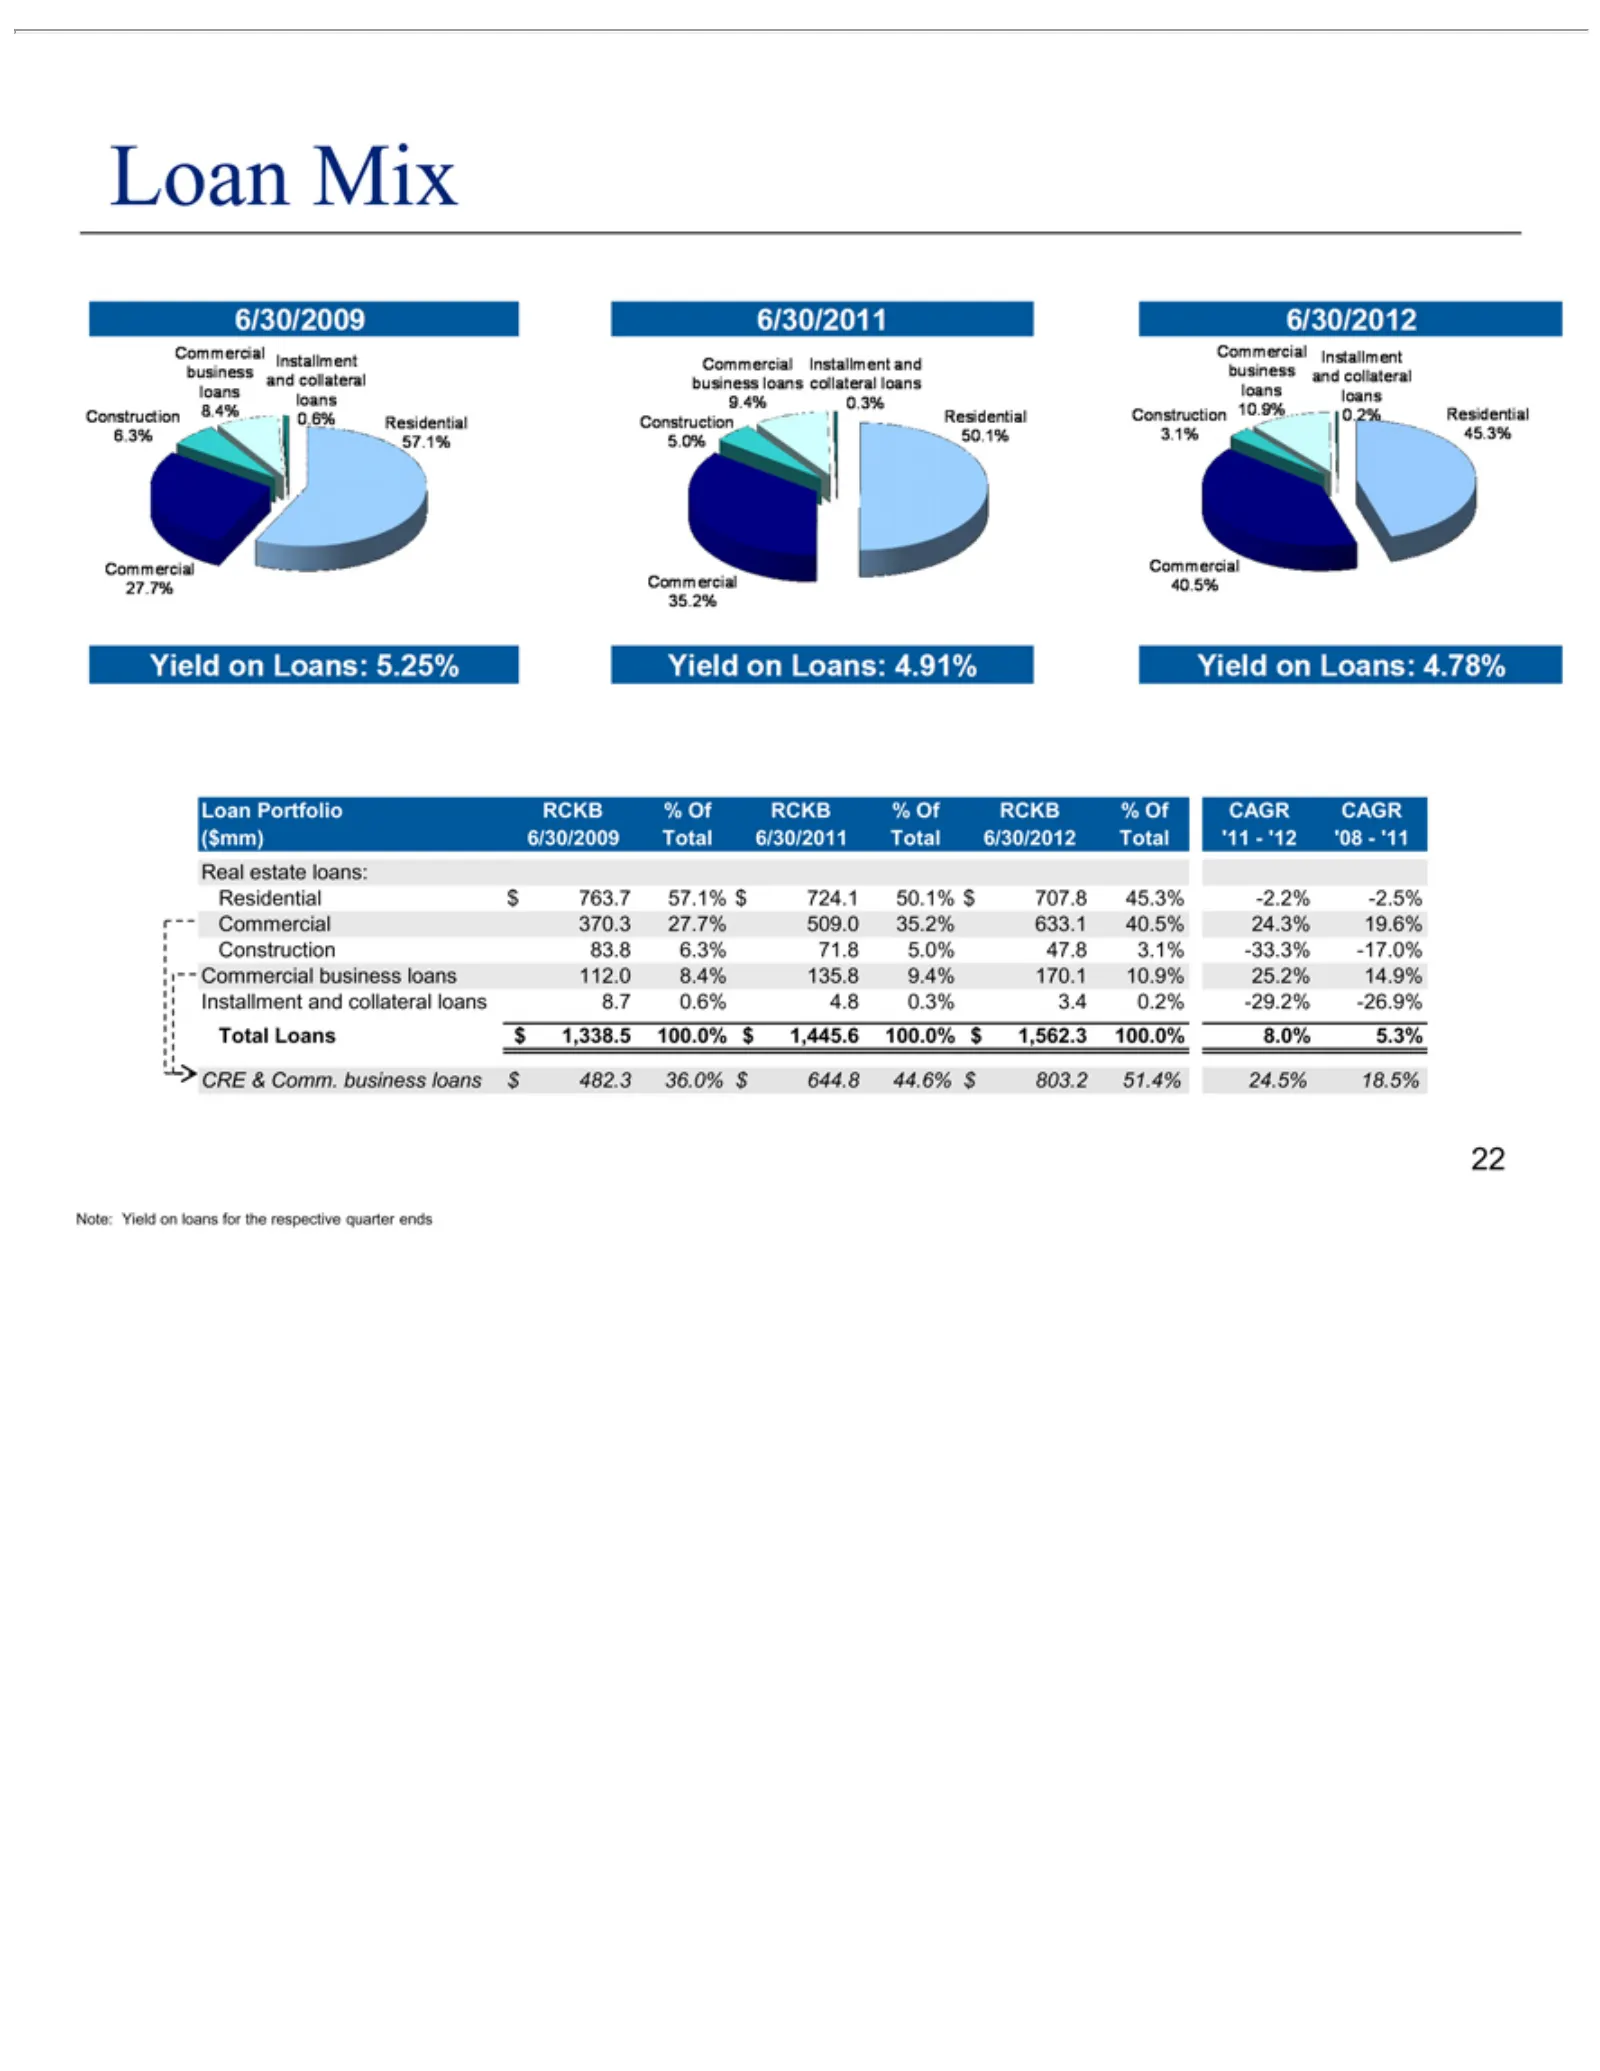
Slide 22: Loan Portfolio Mix and Yield
6/30/2009 6/30/2011 Yield 6/30/2012 Loan ($ Real Residential Construction Commercial Installment Total CRE Note: 22 mm)estate & Loans Mix Portfolio on Yield 6/30/2009 Comm. Loans: loans: and $on $business 370.3 83.8 763.7 1,338.5 loans RCKB collateral business 5.25% 4.91% 4.78% 6.3% Total 27.7% 57.1
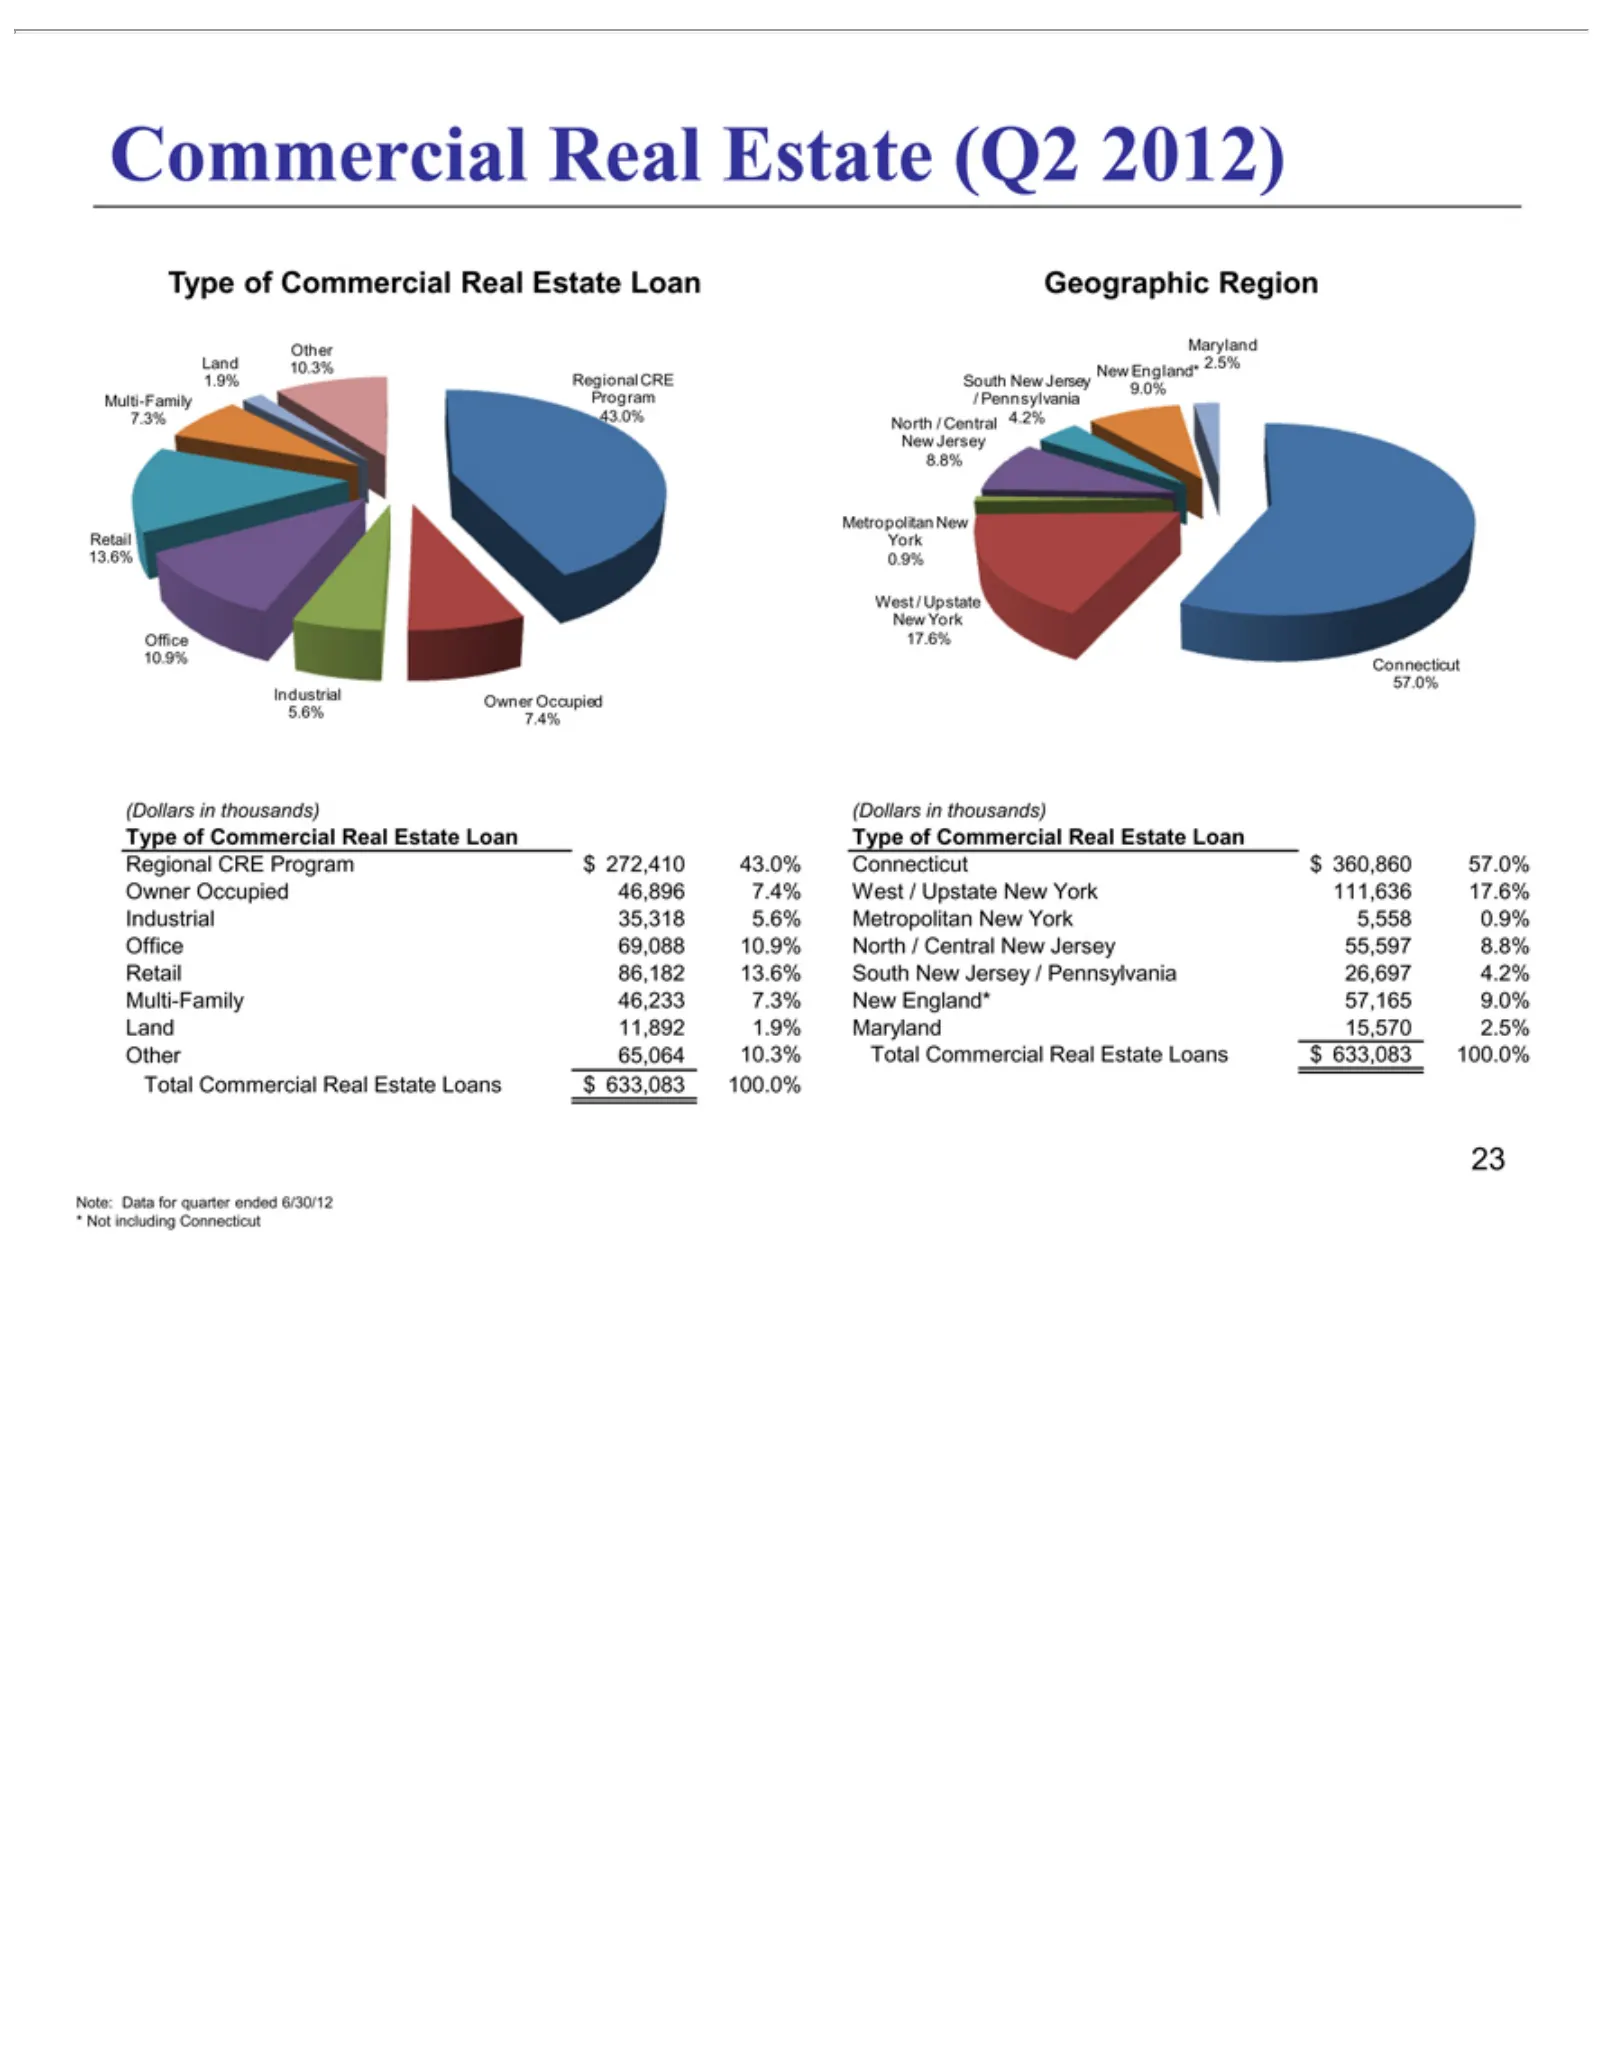
Slide 23: Commercial Real Estate Portfolio
Commercial 1.9% 10.3% 7.3% 10.9% 13.6% 5.6% Geographic /2.5% 9.0% 8.8% 0.9% 57.0% 17.6% Regional Owner Industrial Office Retail Multi-Family Land Other (Dollars Type Connecticut West Metropolitan North South New Maryland Total *Note: Pennsylvania 23 York England* /of Commercial Other 11,892 Regional
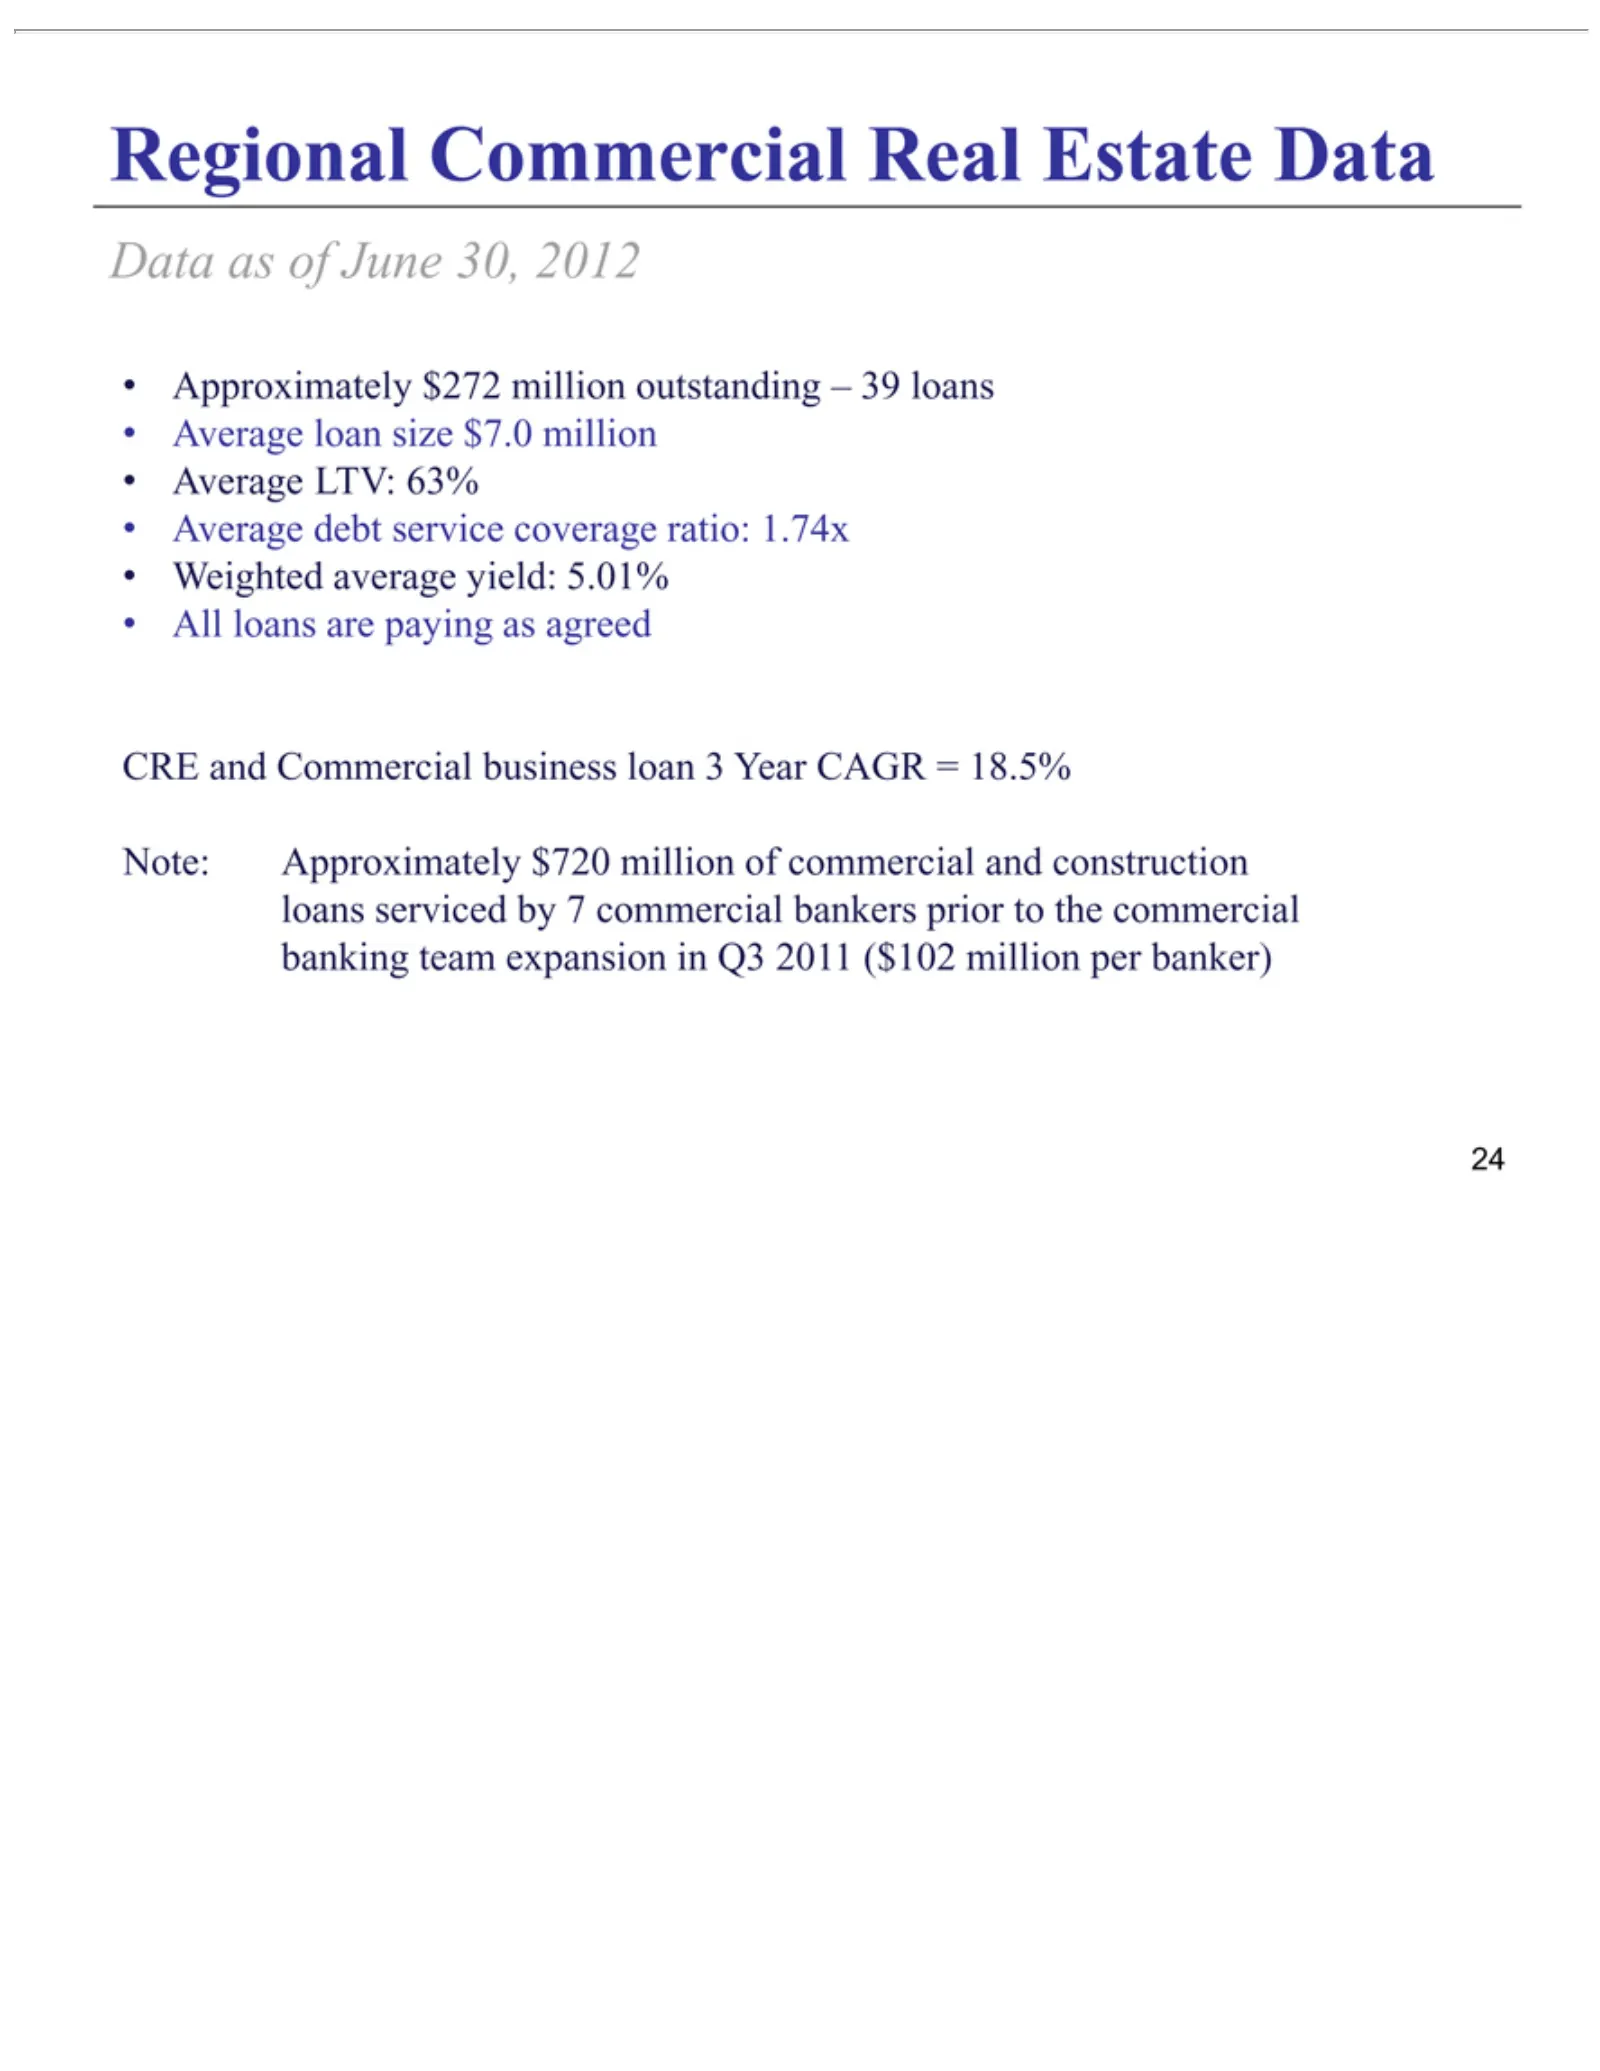
Slide 24: Commercial Real Estate Data
Regional •Data CRE Note: 24 Approximately Average All Weighted loans as and Approximately ofCommercial loan LTV: debt June are average paying size service 30, 63% $272 $7.0 2012 yield: $720 as Real business million coverage million agreed 5.01% million Estate outstanding loan ratio: Data of3commerci
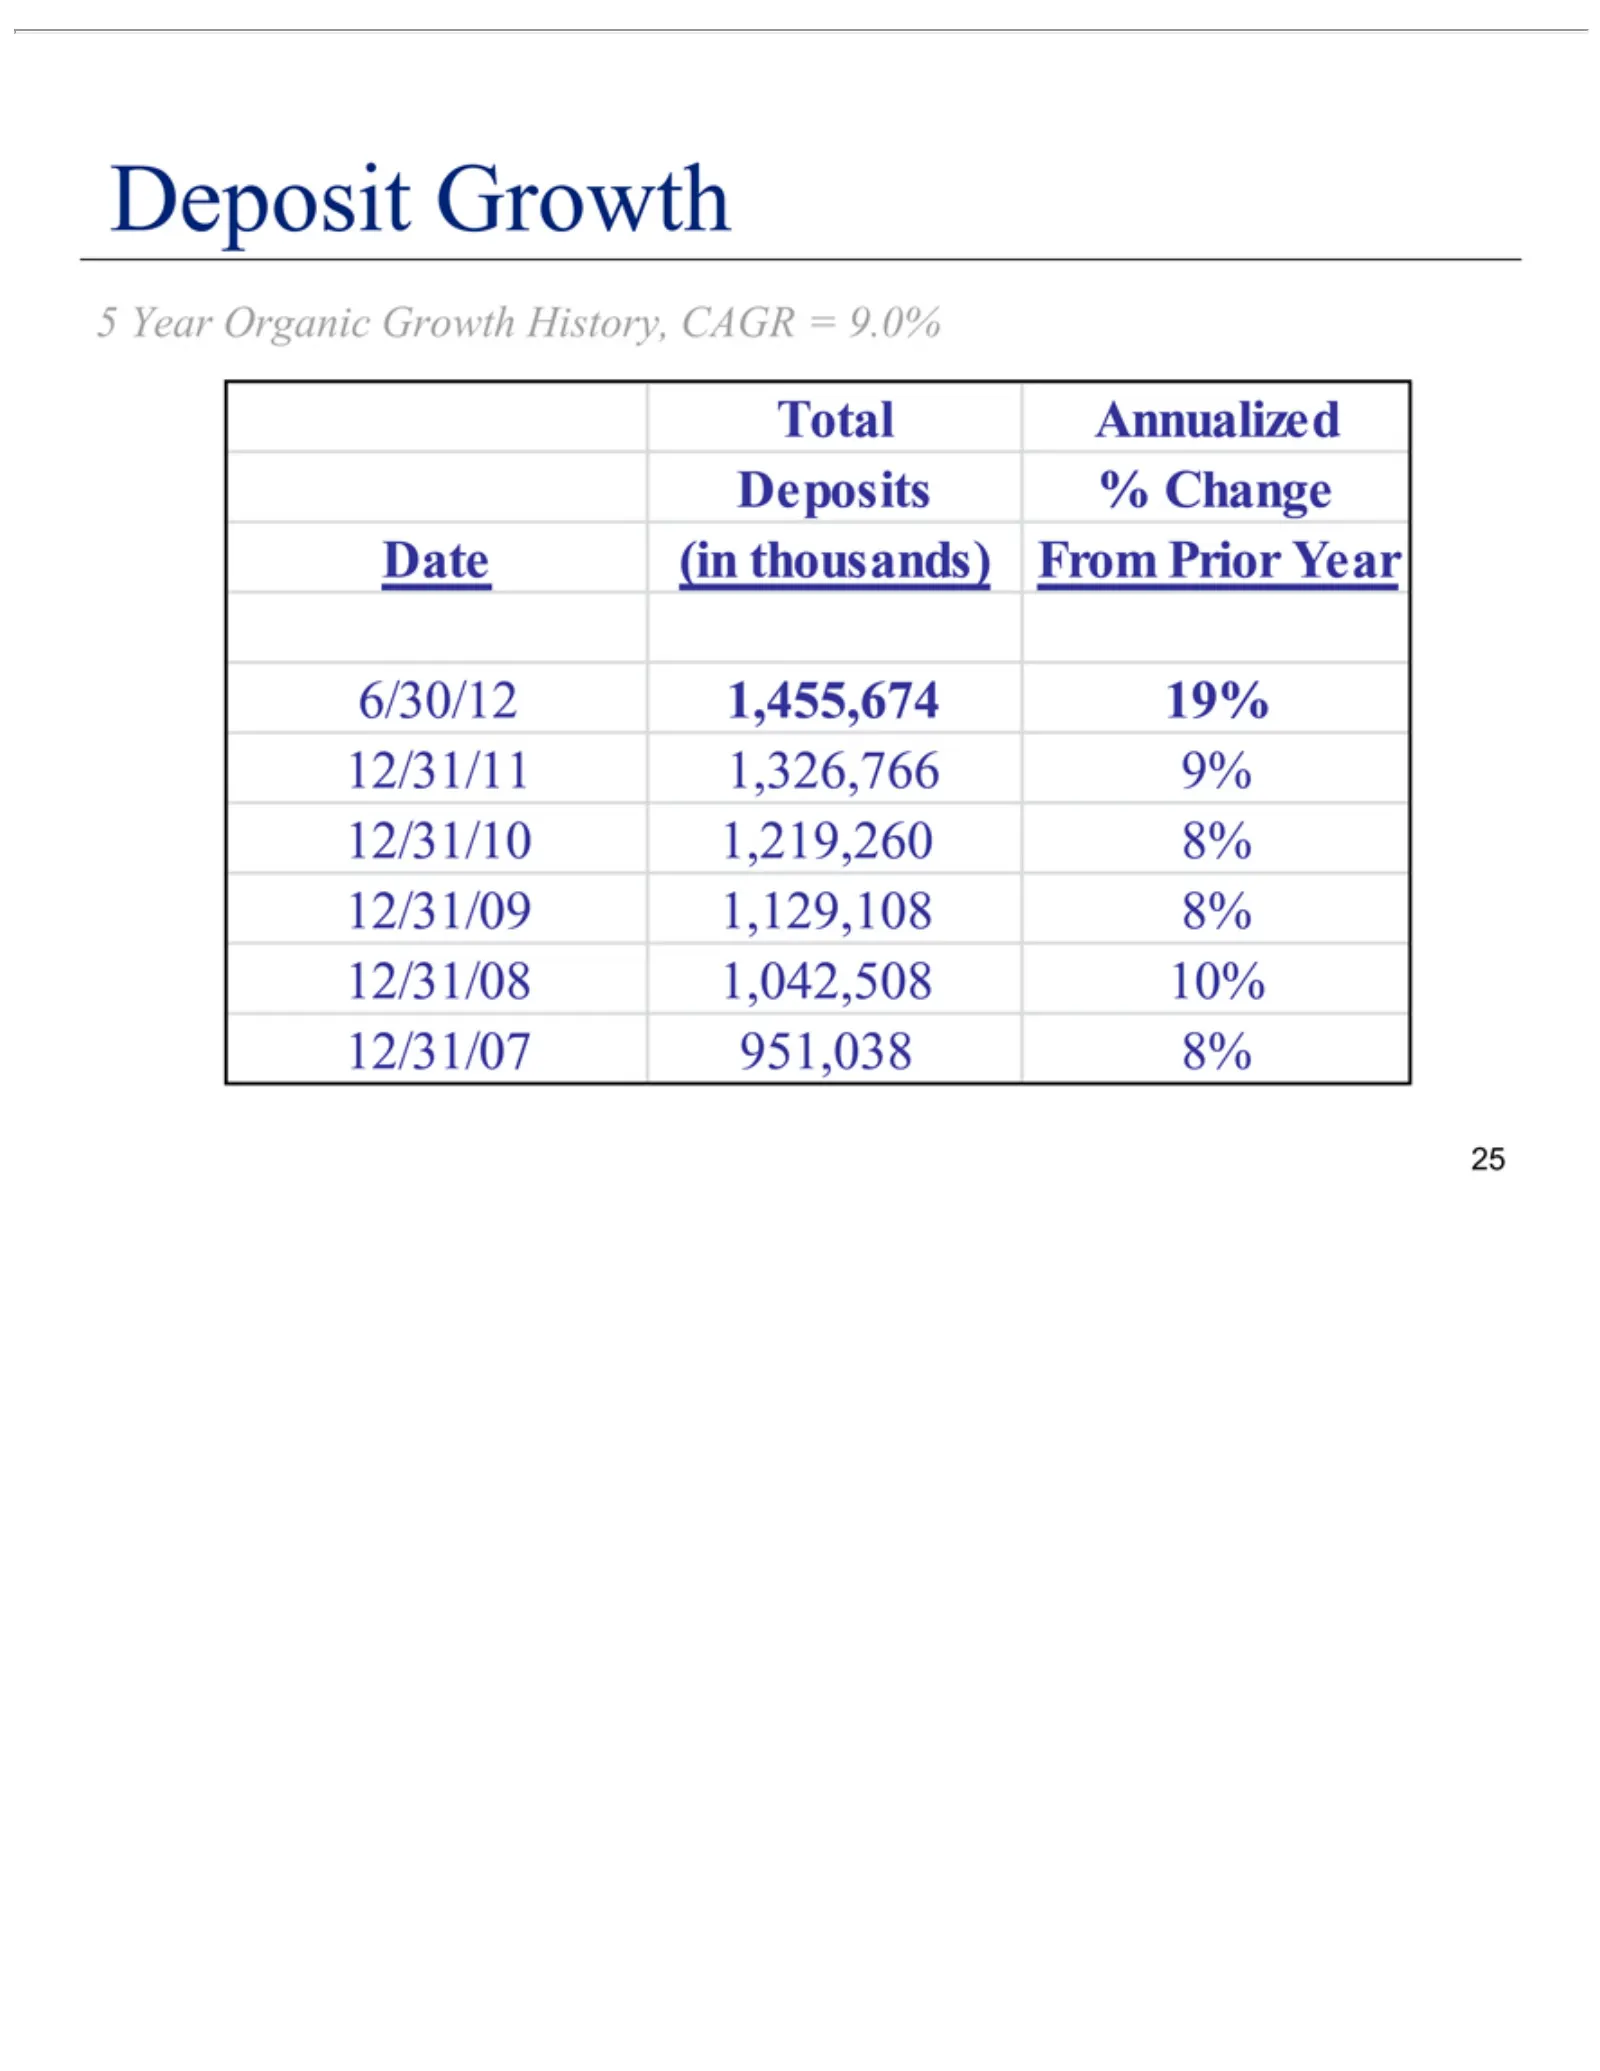
Slide 25: Deposit Growth
5Deposit Total (in Deposits Date 6/30/12 12/31/11 12/31/10 12/31/09 12/31/08 12/31/07 25 Growth Year Organic Annualized 1,455,674 thousands) % 1,326,766 1,219,260 1,129,108 1,042,508 951,038 Change8% 19% 9% 8%Growth 10% From PriorHistory, Year CAGR = 9.0%
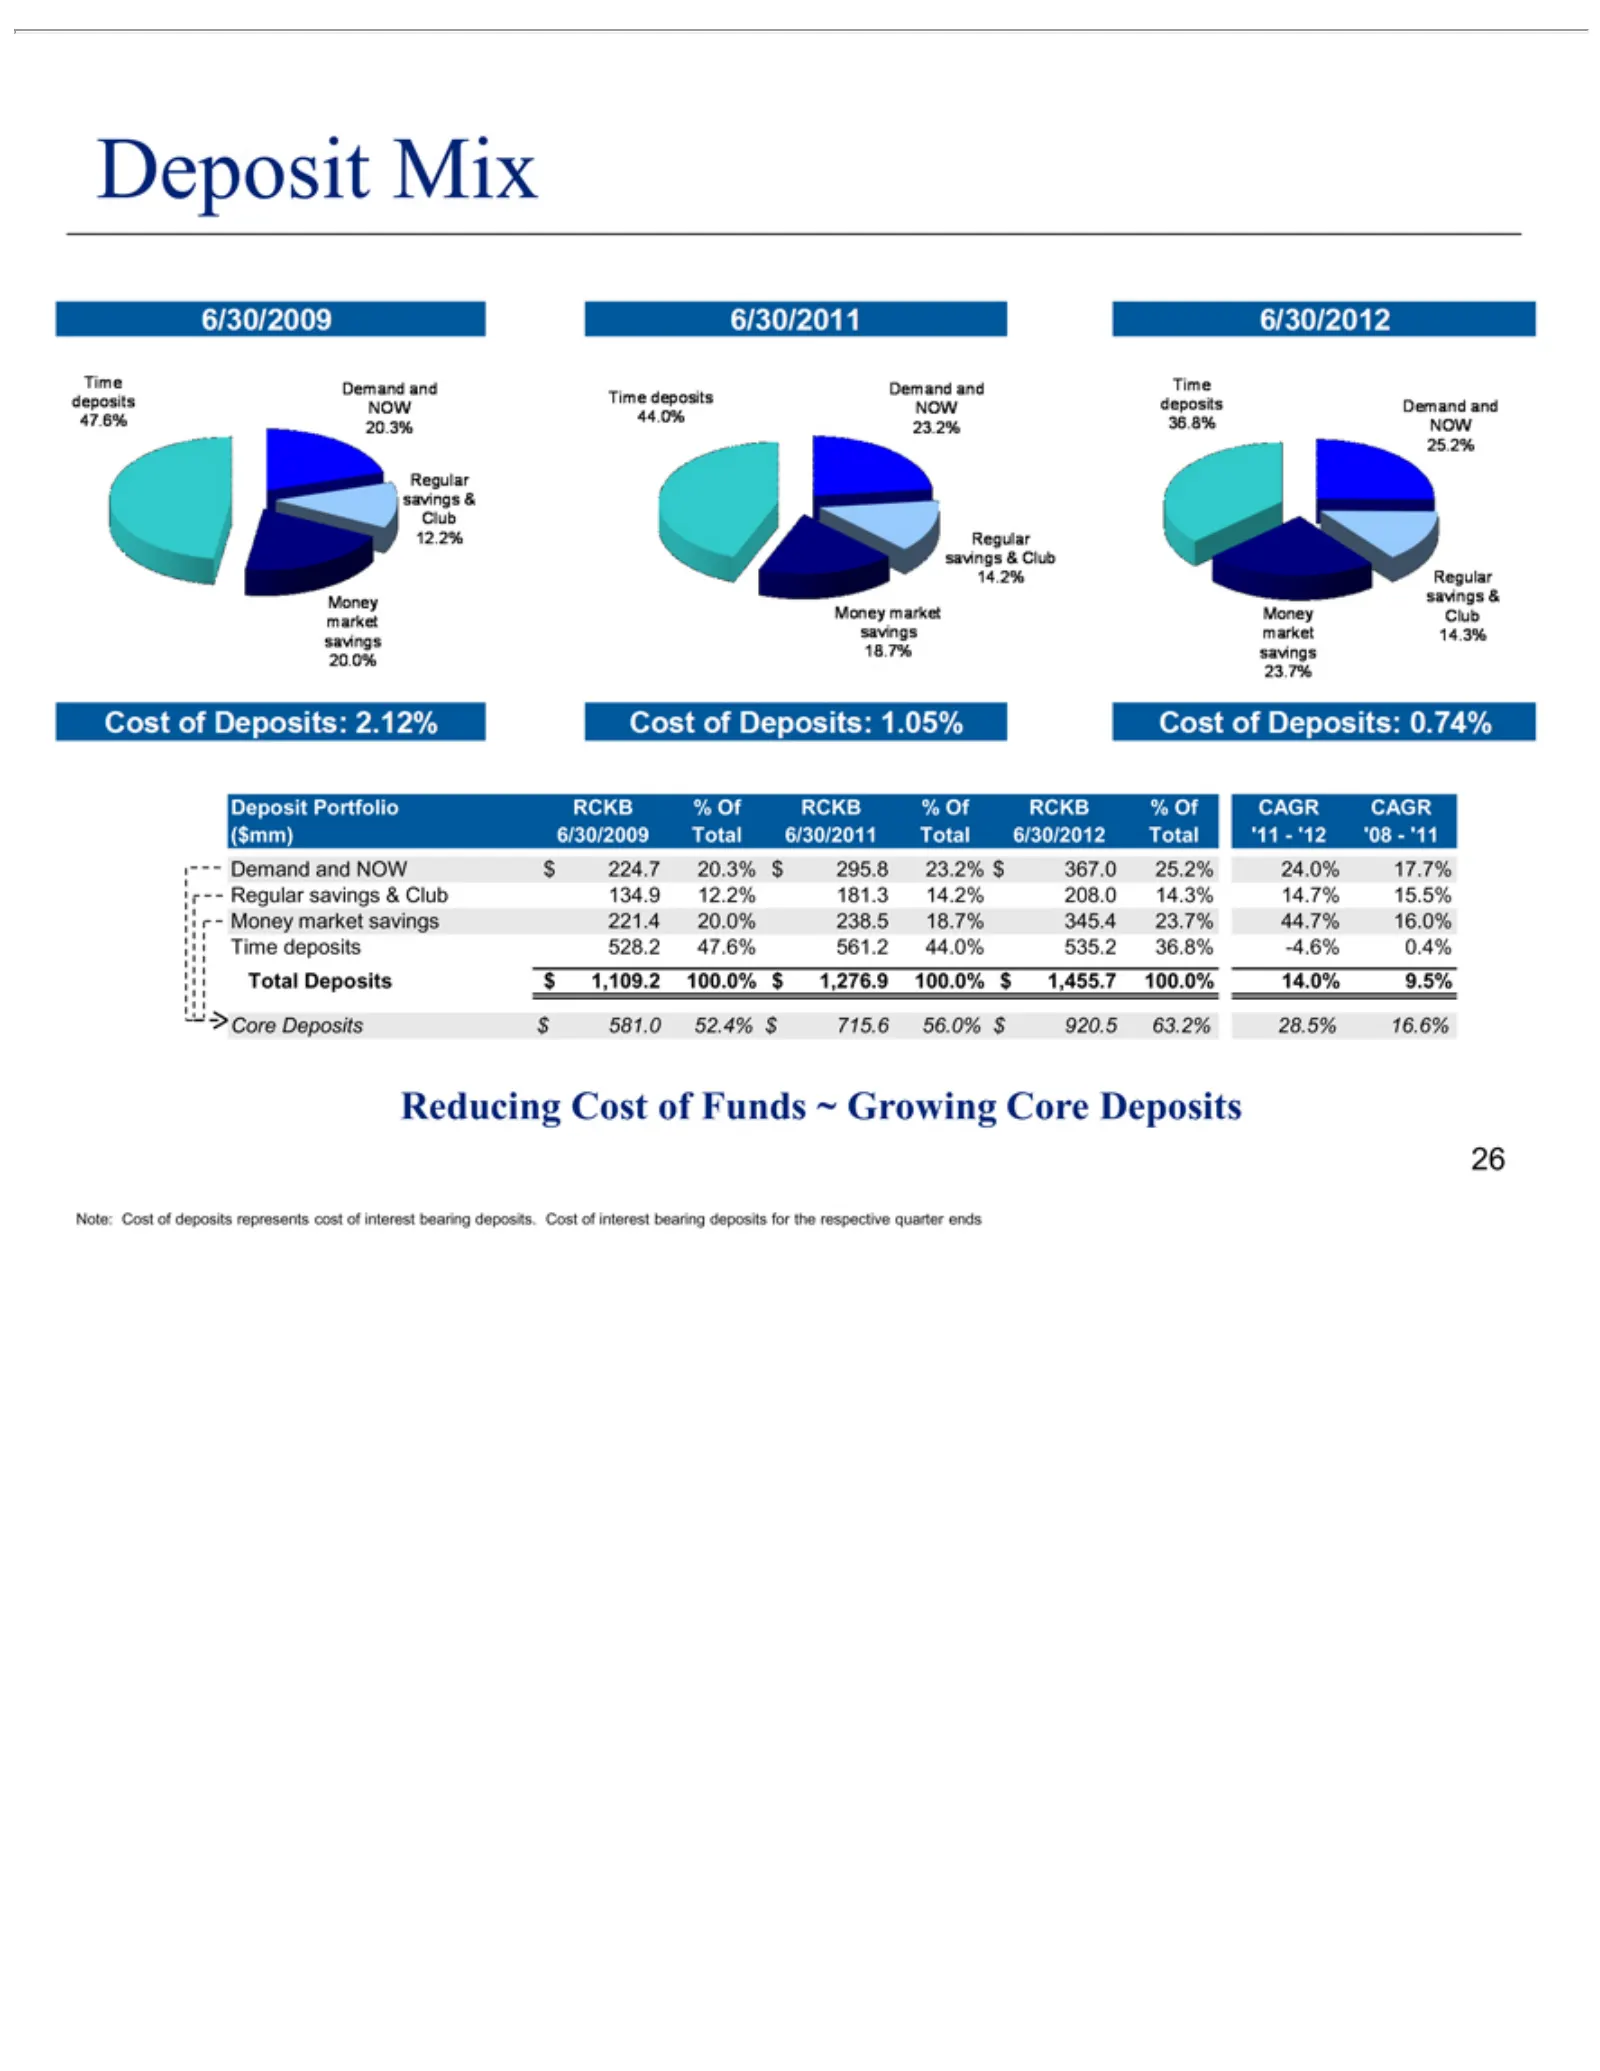
Slide 26: Deposit Mix and Cost of Deposits
6/30/2009 6/30/2011 Cost 6/30/2012 Deposit ($mm) Demand Regular Money Time Total Core Reducing Note: 26 of Deposits deposits Cost 6/30/2009 market Deposits: Mix Portfolio savings and Cost ofNOW deposits 528.2 $savings of& 581.0 1,109.2 RCKB 2.12% 1.05% 0.74% Funds Total Club $47.6% 224.7 represents
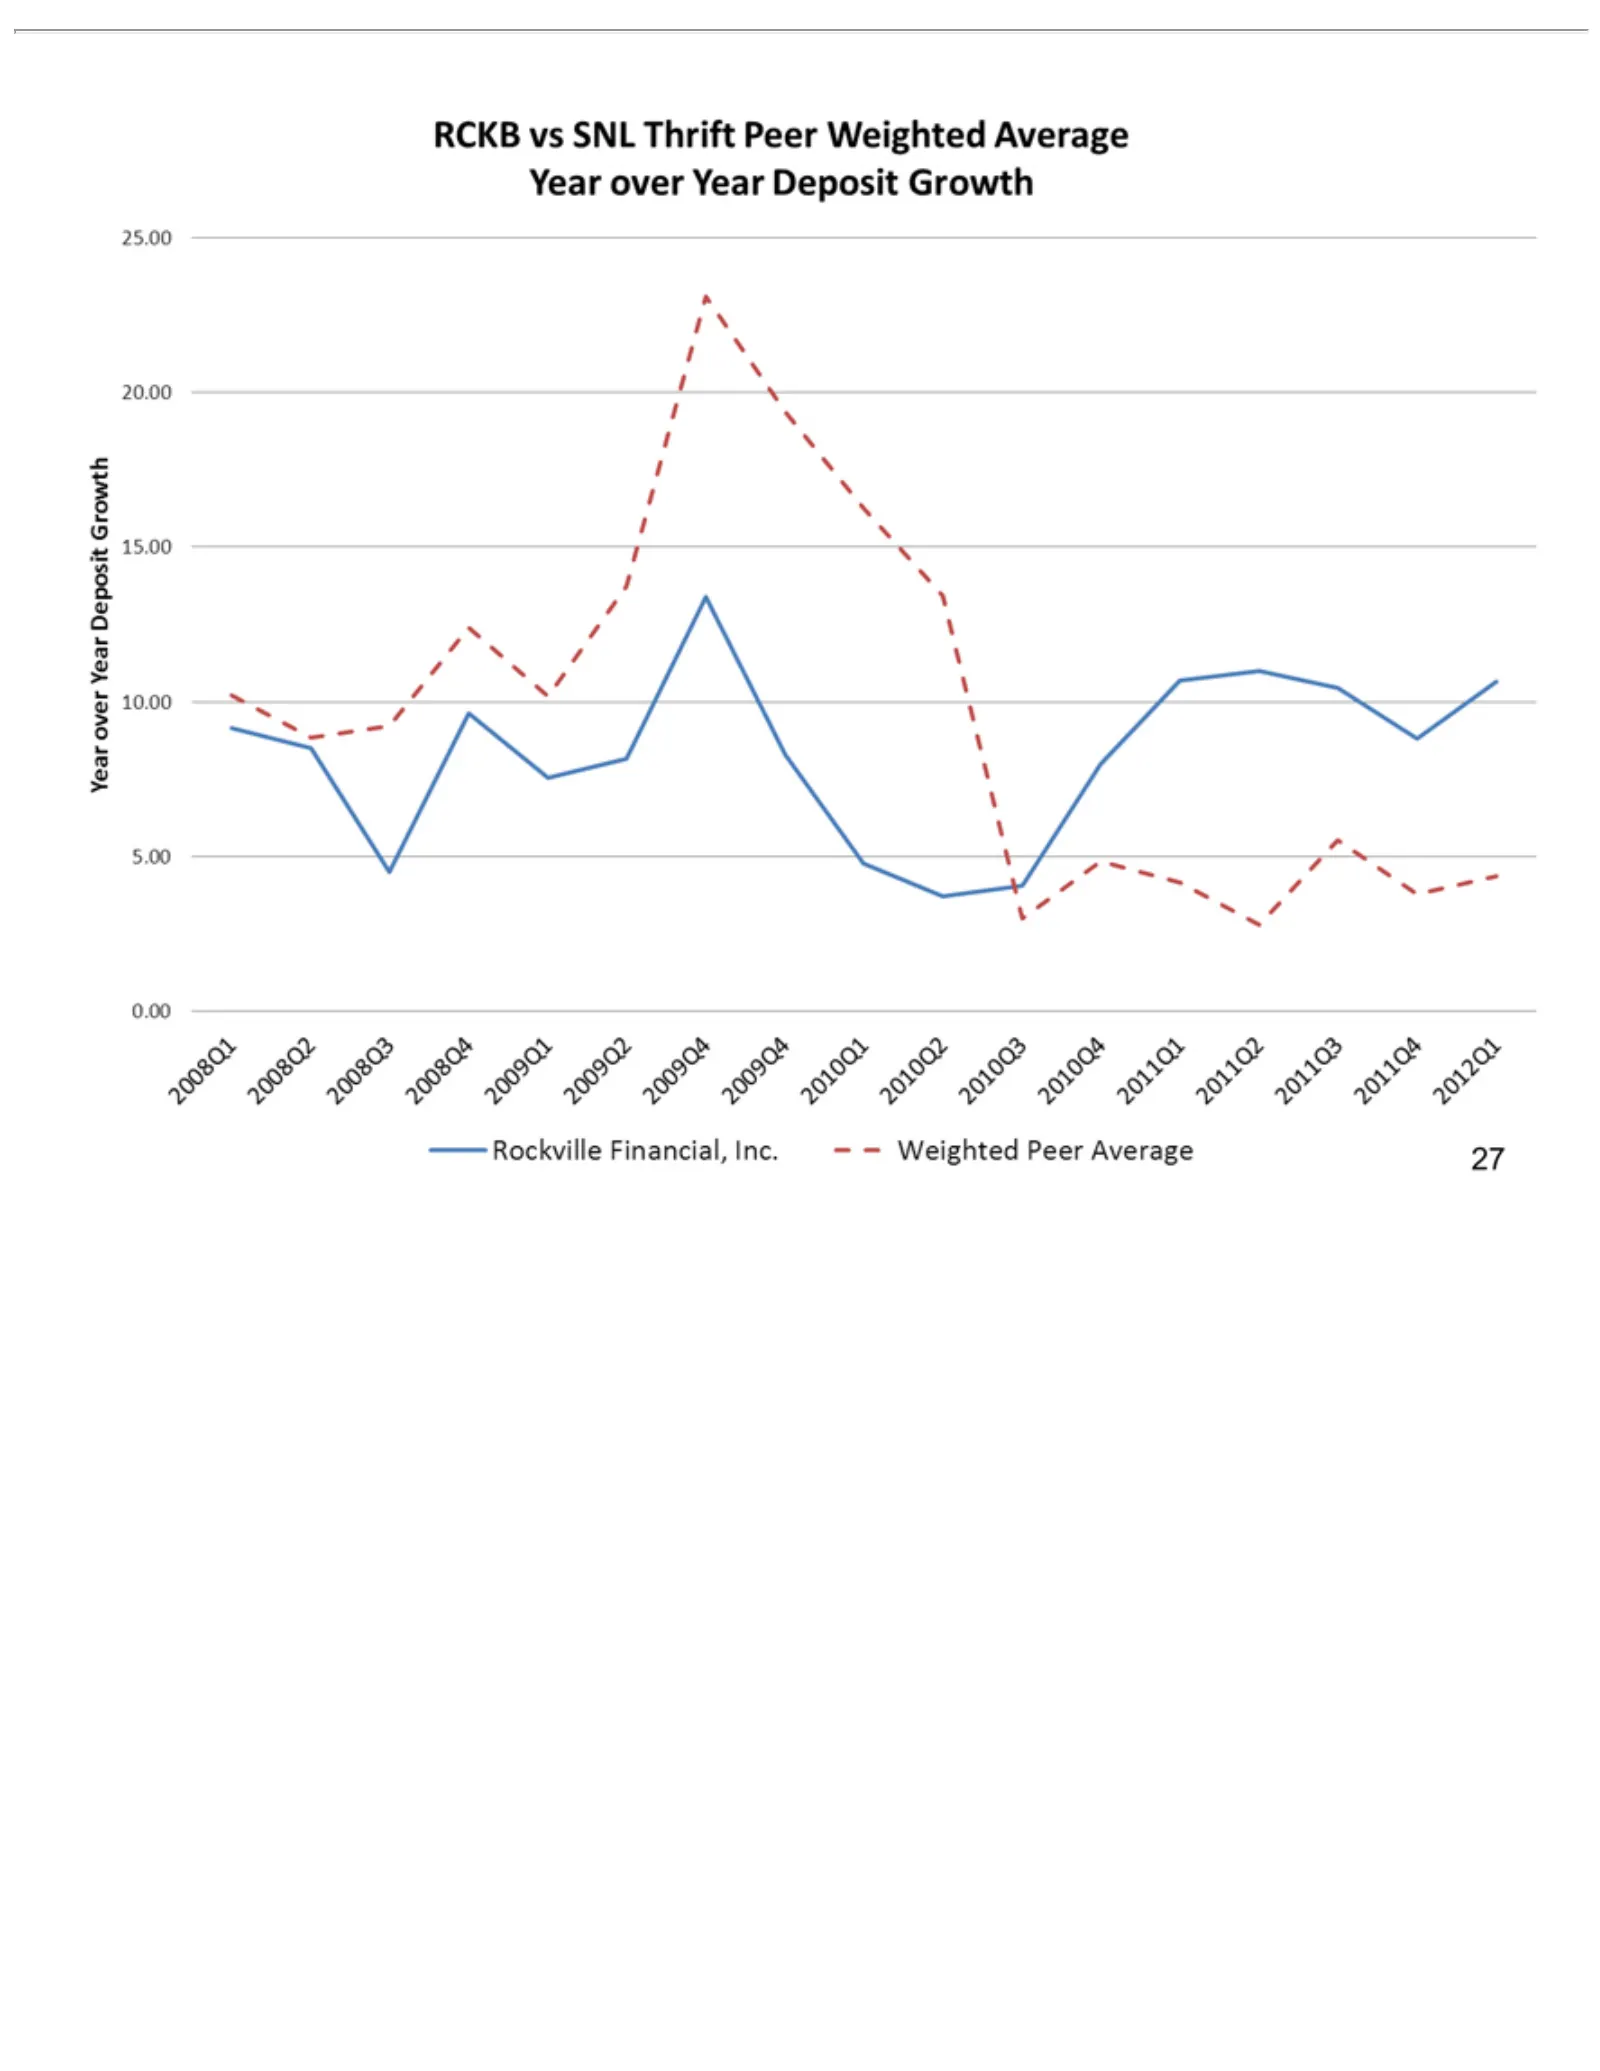
Slide 27: Deposit Growth vs SNL Thrift Peers
RCKB vs SNL Thrift Peer Weighted Average Year over Year Deposit Growth 27
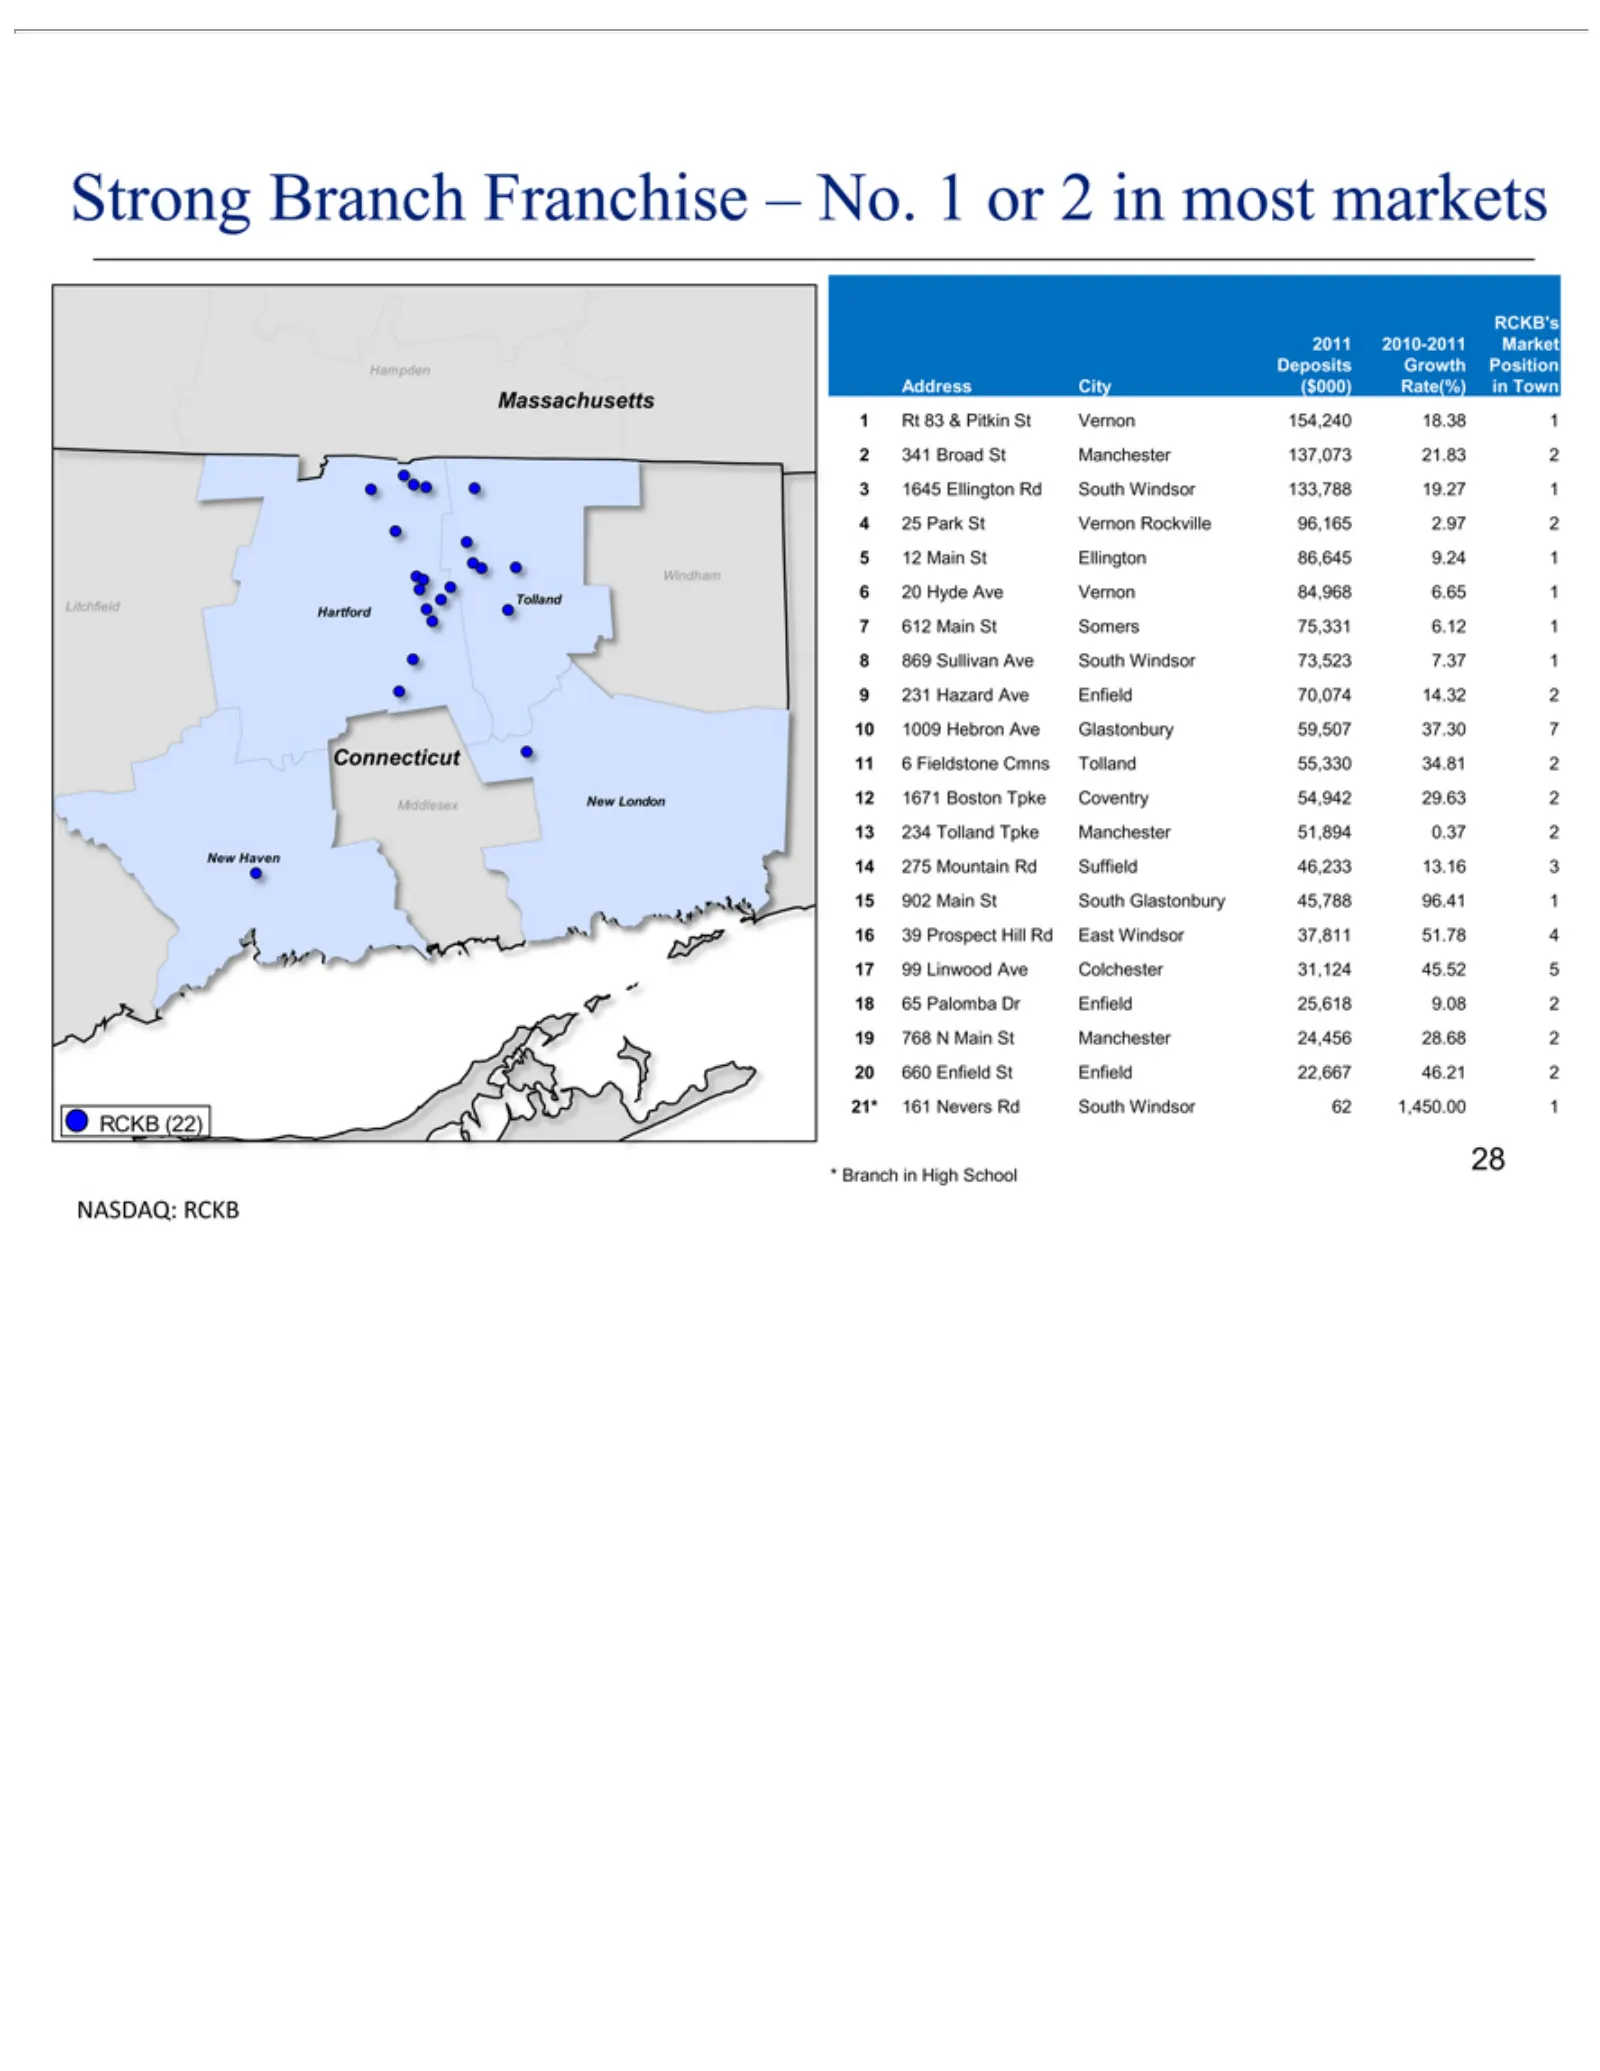
Slide 28: Strong Franchise Position - Branch Network
Strong Franklin Middlesex Hampshire RCKB Connecticut Massachusetts NASDAQ: Suffolk 2011 RCKB’s Deposits 4321Address Plymouth 876Providence5 Kent9 Bristol 10 11 12 13 ashington 14 15 16 17 18 19 20 *21* 28Rt6660 341 1645 25 20 612 869 Branch 1009 1671 234 275 902 39 99 65 768161 83 Fieldstone Park Hy
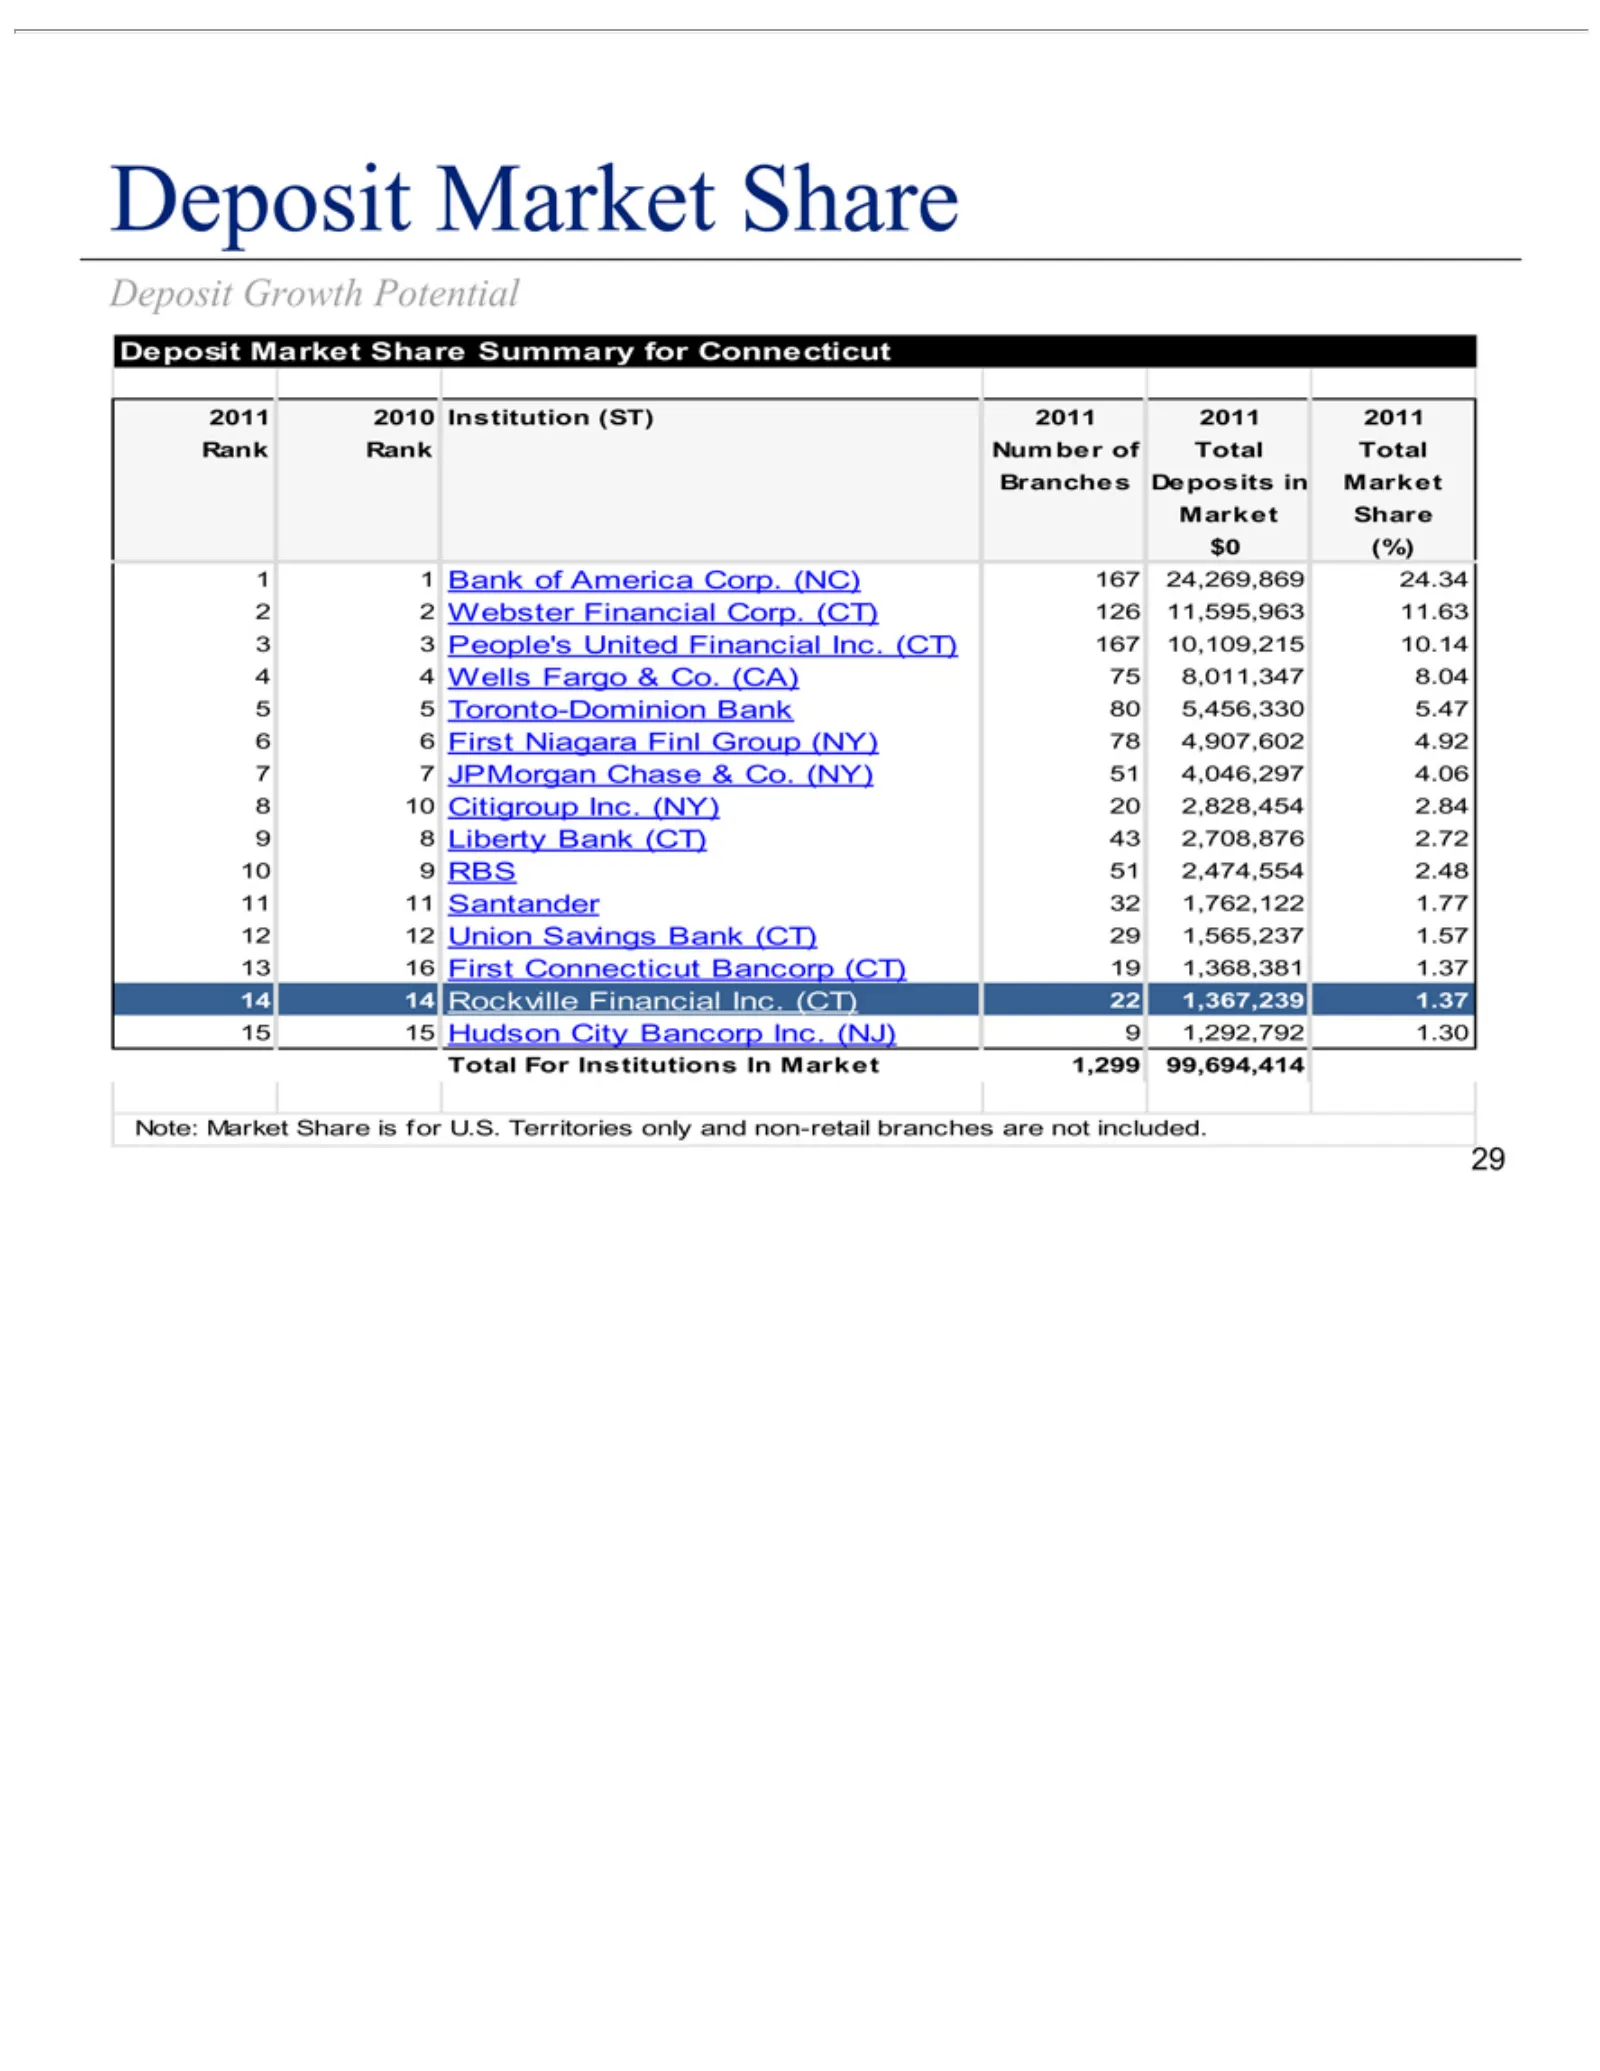
Slide 29: Deposit Market Share Rank
Deposit 2011 Rank Branches Market 987654321$0 10 11 12 13 14 15 Total Note: 29765432111 810 9(%) 12 16 14 15 Webster Wells Toronto-Dominion Bank People’s First JPMorgan Liberty Citigroup RBS 2010 For Rank Santander Market Union First Rockville Hudson Share Growth Market Niagara of Institutions Depos
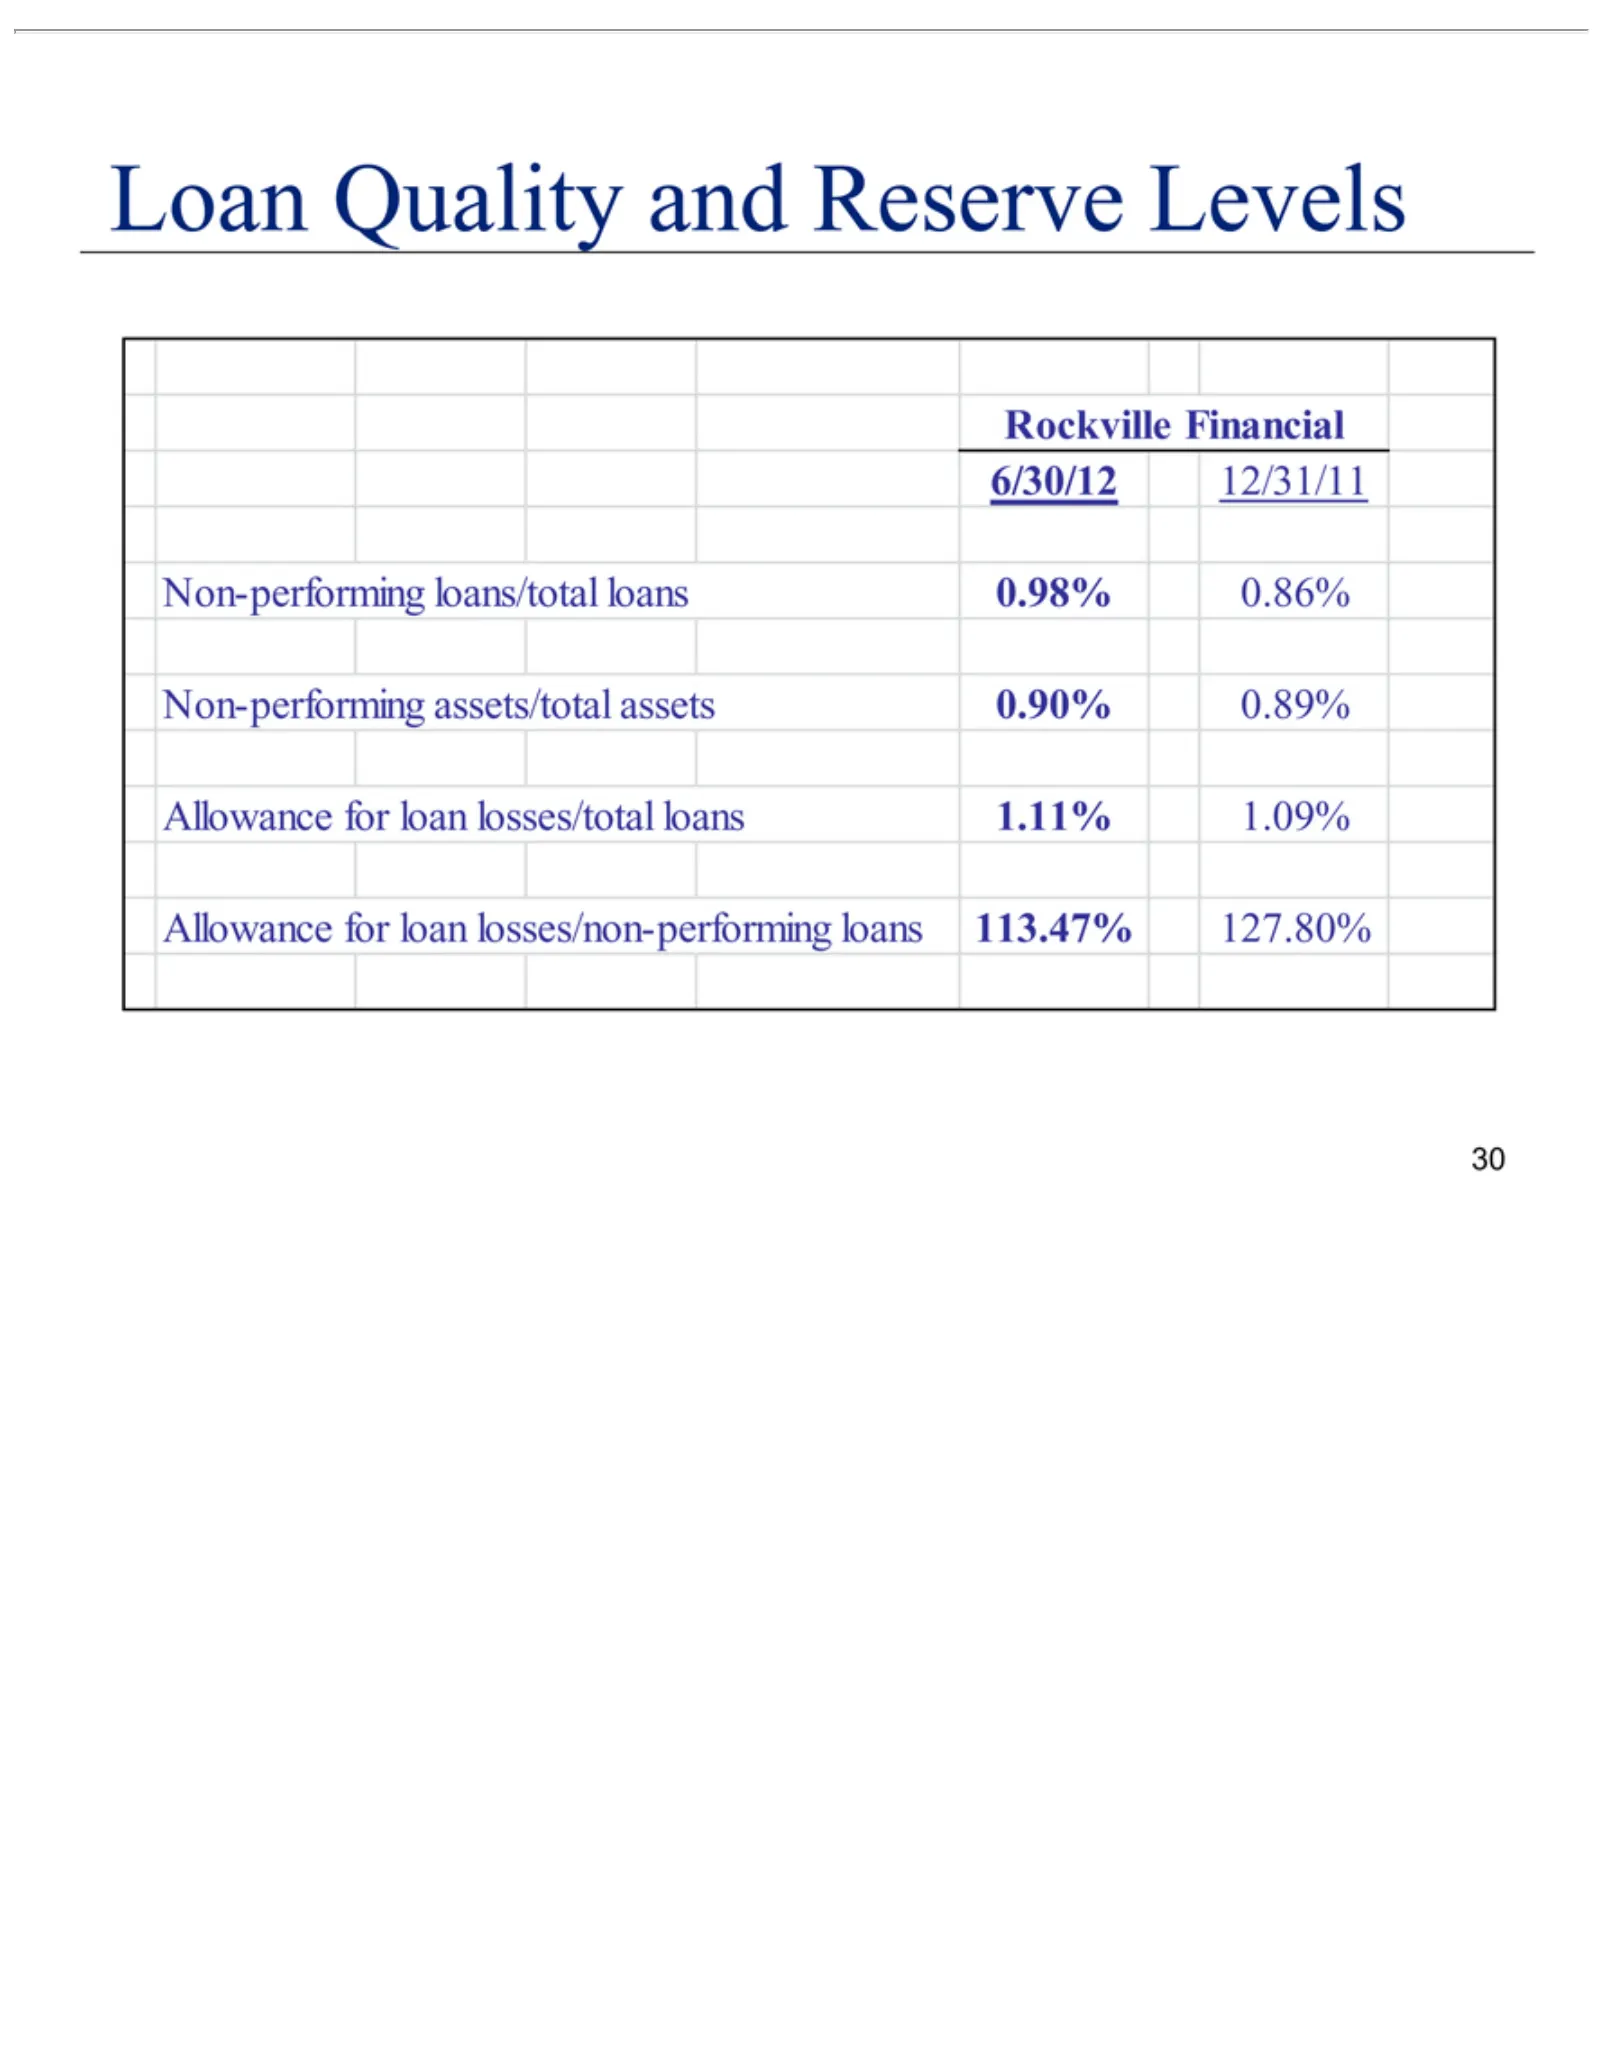
Slide 30: Loan Quality
Loan Quality Rockville 6/30/12 Non- Allowance 30 performing 12/31/11 Financial forand loan loans/total assets/total Reserve losses/total losses/non- Levels loans assets loans performing 0.98% 0.90% 1.11% 0.86% 0.89% loans 1.09%113.47% 127.80%
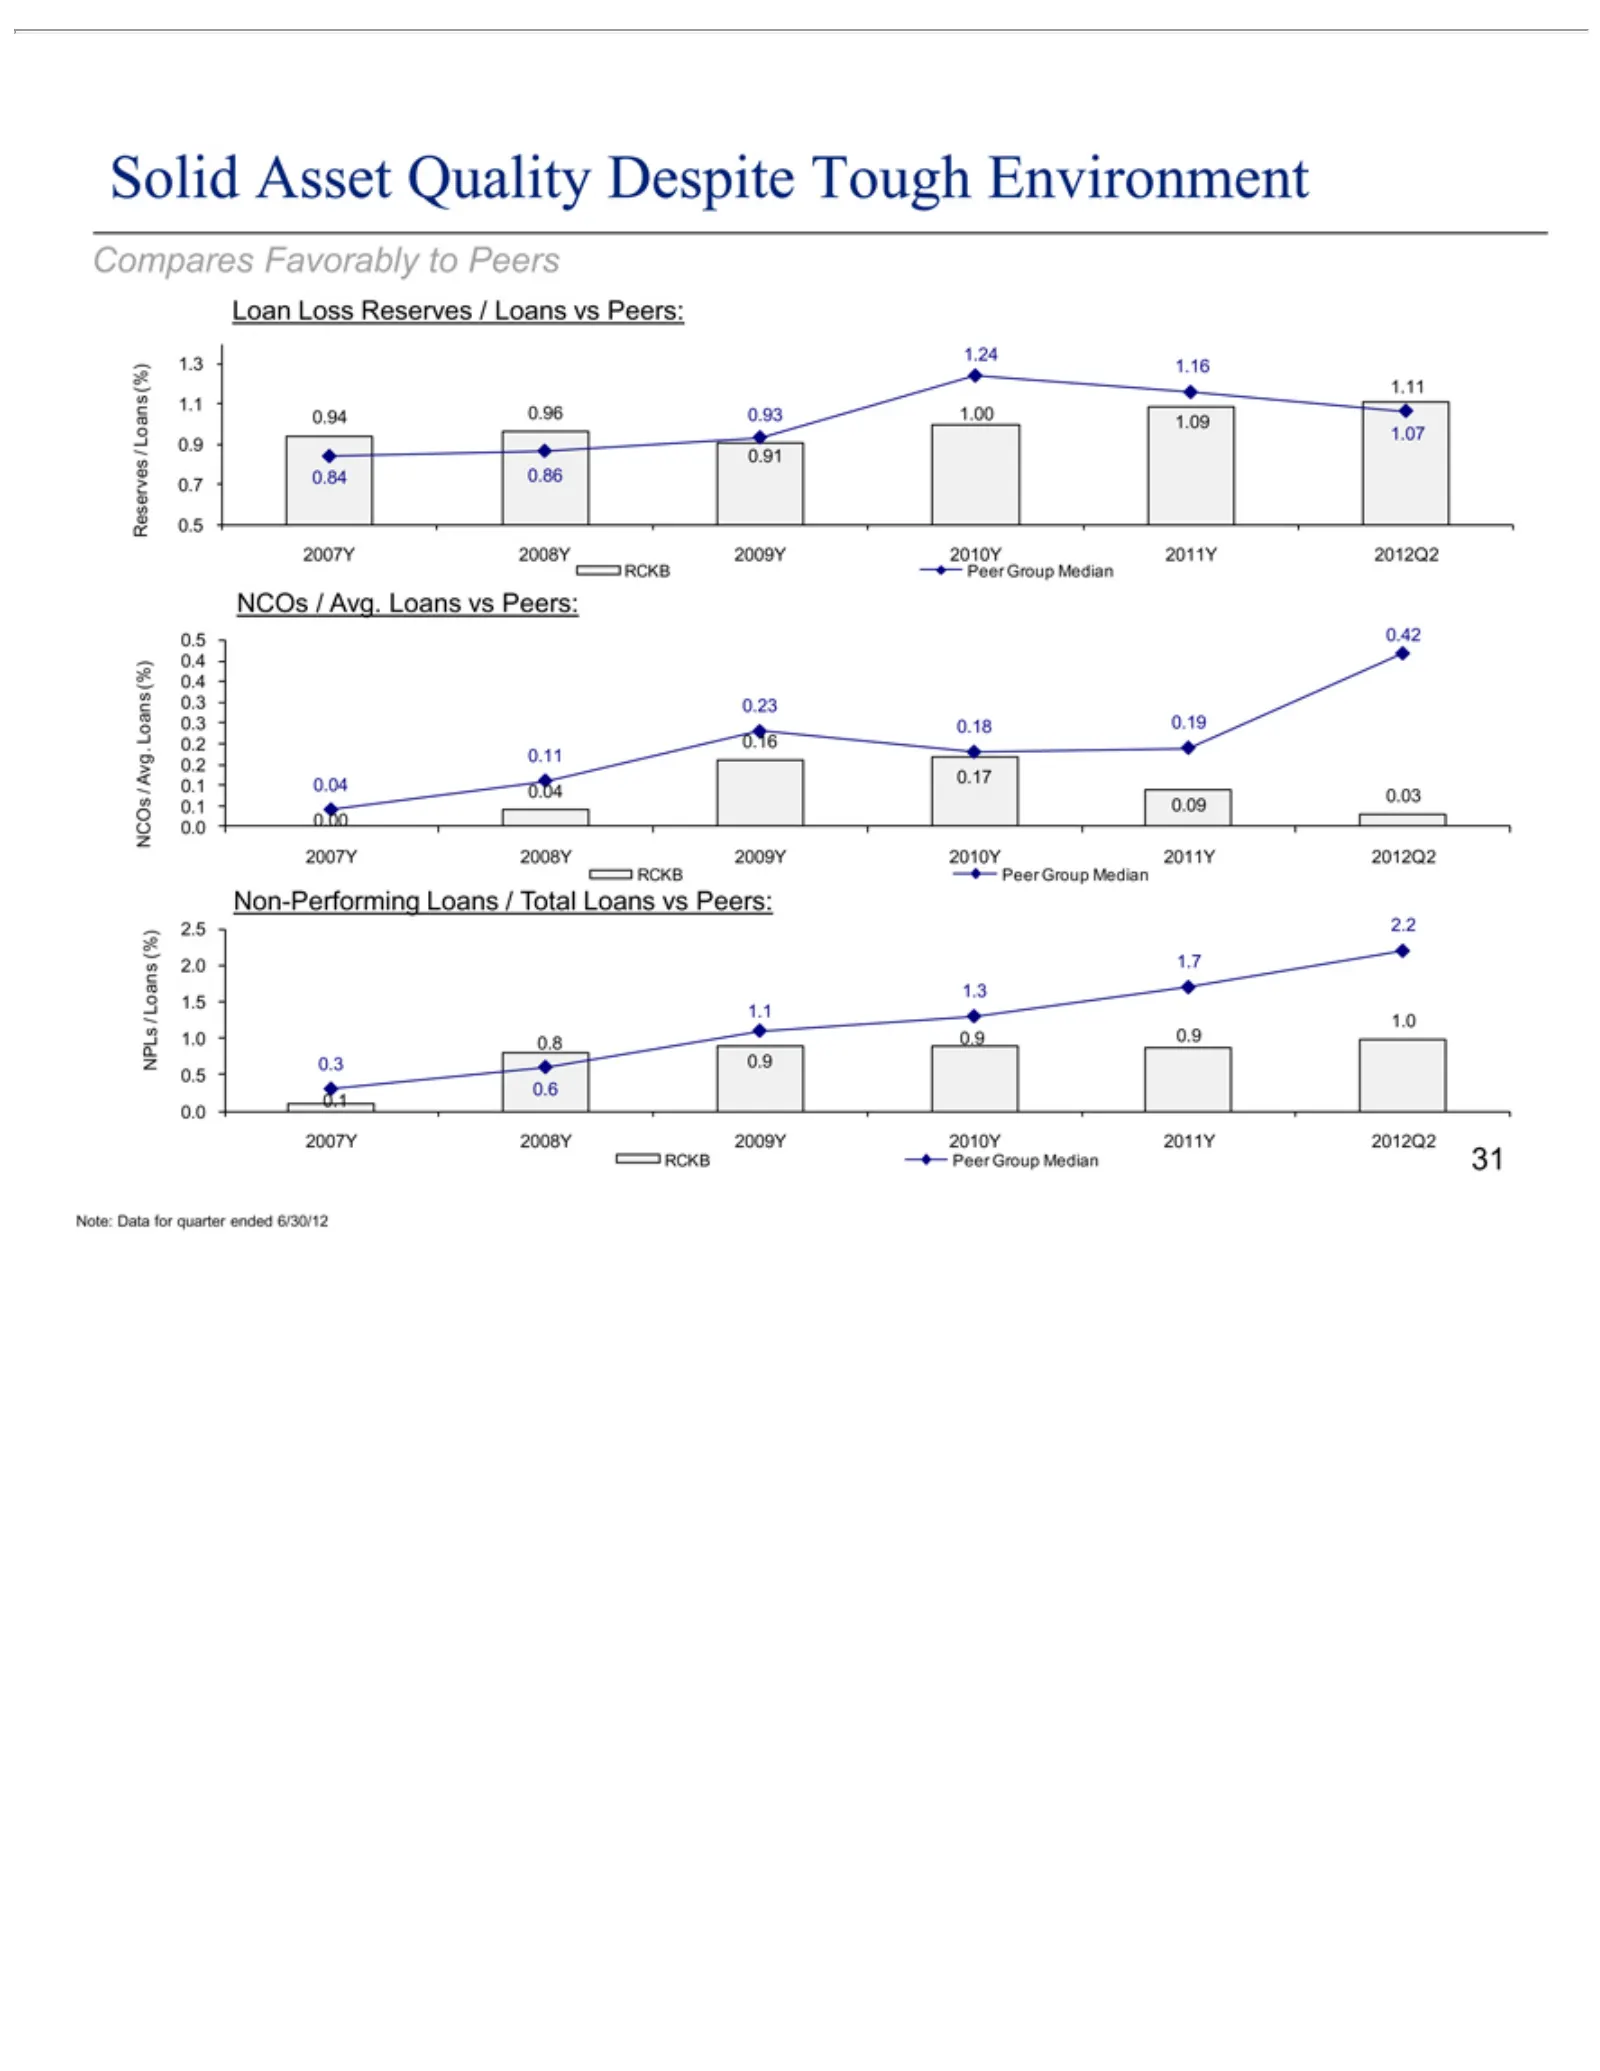
Slide 31: Asset Quality Compares Favorably to Peers
Solid Compares Loan 1.24 0.94 1.11 0.84 0.91 0.9 1.07 1.09 0.7 NCOs 0.4 0.17 0.2 0.11 0.03 Non-Performing 2.5 2.0 1.0 1.1 1.5 1.3 0.3 2007Y 0.0 0.1 0.6 0.5 RCKB Note: 31 1.16 0.42 0.23 0.18 0.16 0.04 0.00 2.2 1.7 0.8 0.9 0.96 0.86 Loss Asset Data /2008Y Peer 0.9 Avg. 0.19 0.04 0.09 0.93 Favorably Re
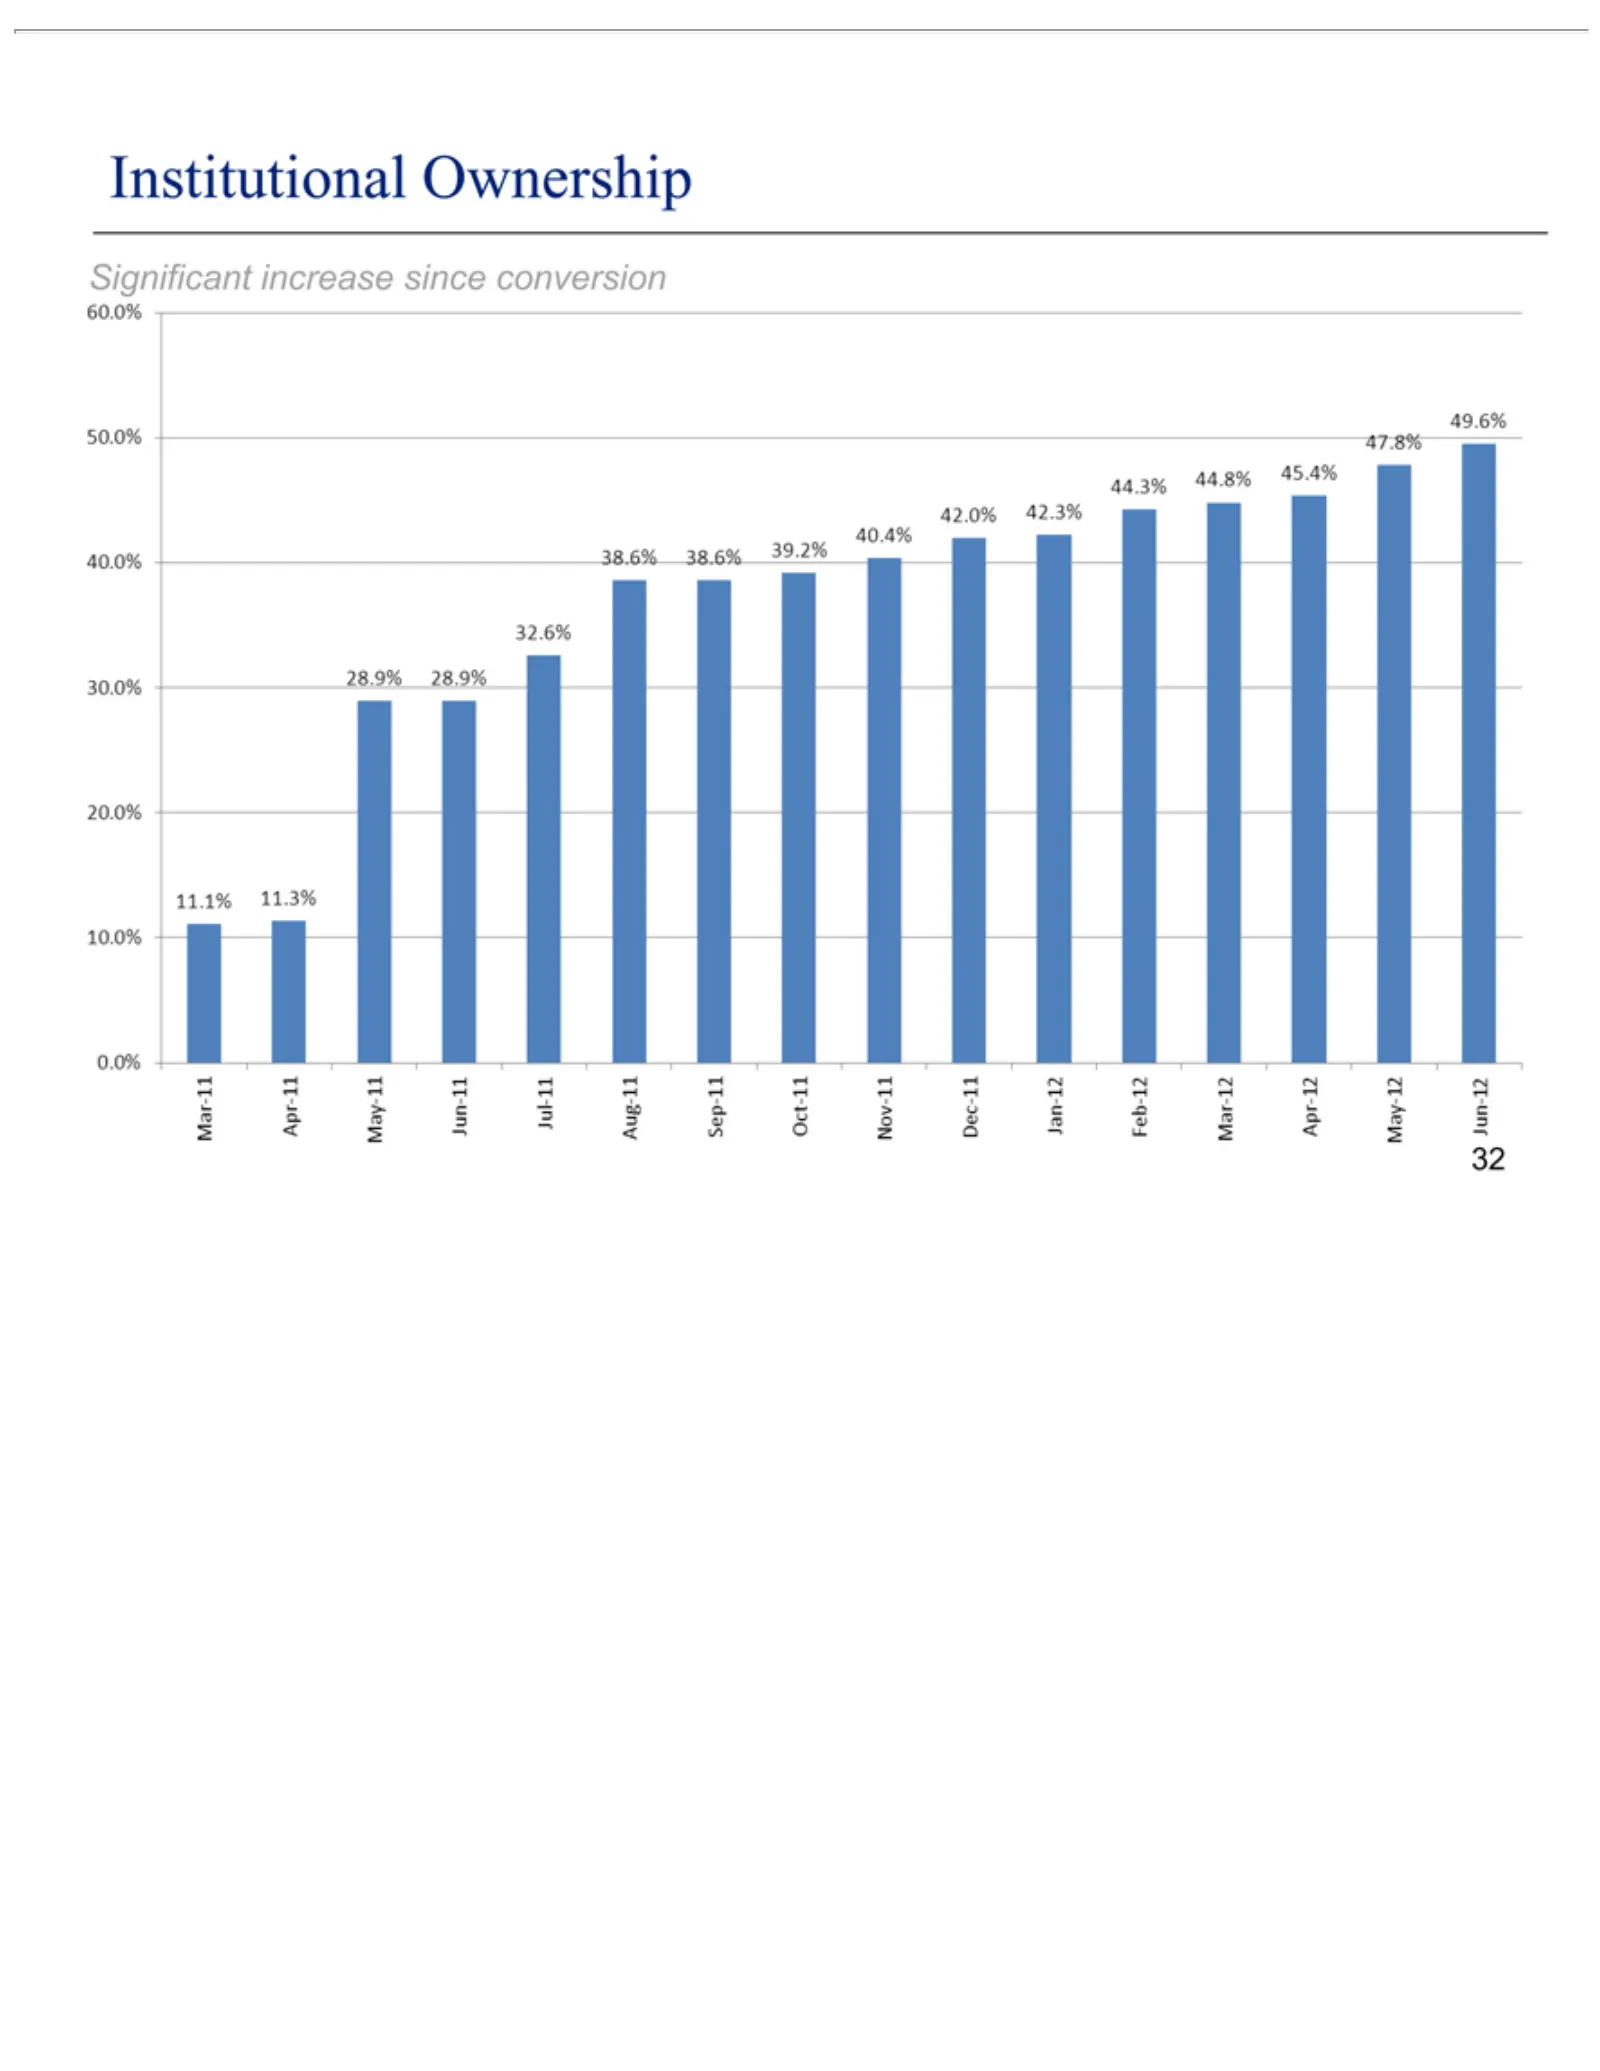
Slide 32: Significant Increase in Institutional Ownership
Institutionalincrease Significant 32 Ownership since conversion
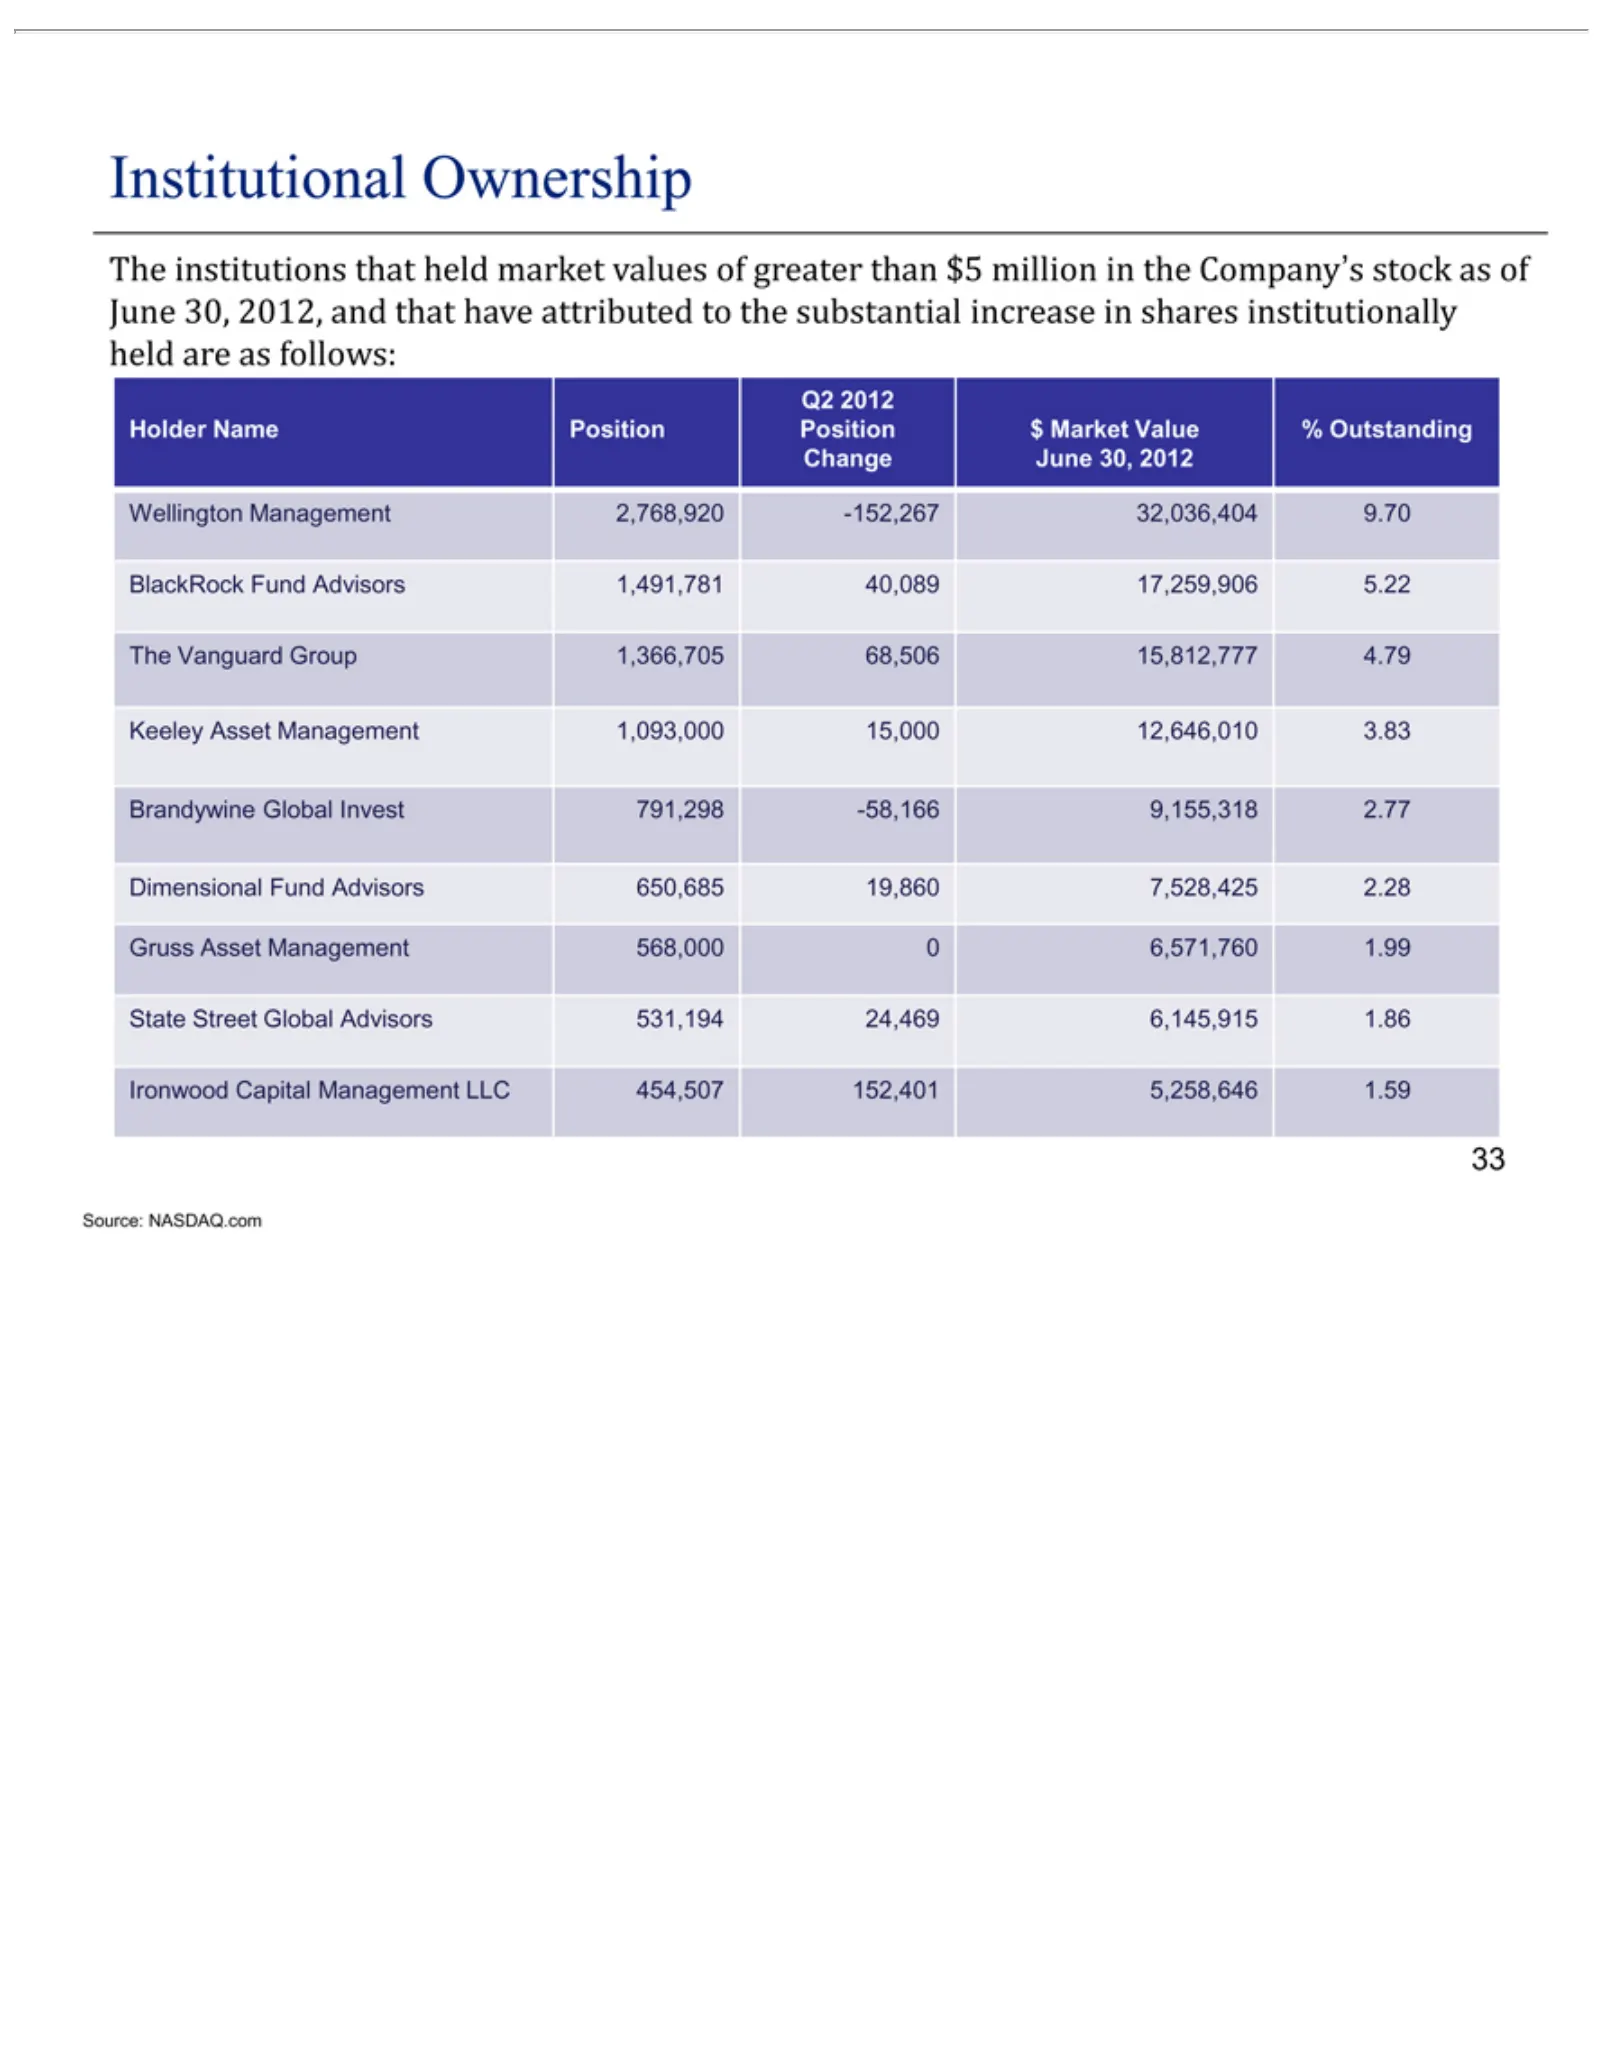
Slide 33: Institutional Ownership
Institutional Q2 Holder Change Wellington BlackRock The Keeley Brandywine Dimensional Gruss State Ironwood Source: 33 2012 Vanguard institutions Street Asset Asset Name NASDAQ.com June Capital Management Fund Global Management Ownership Global Fund 30, Management Position Group that 2012 Advisors Ma
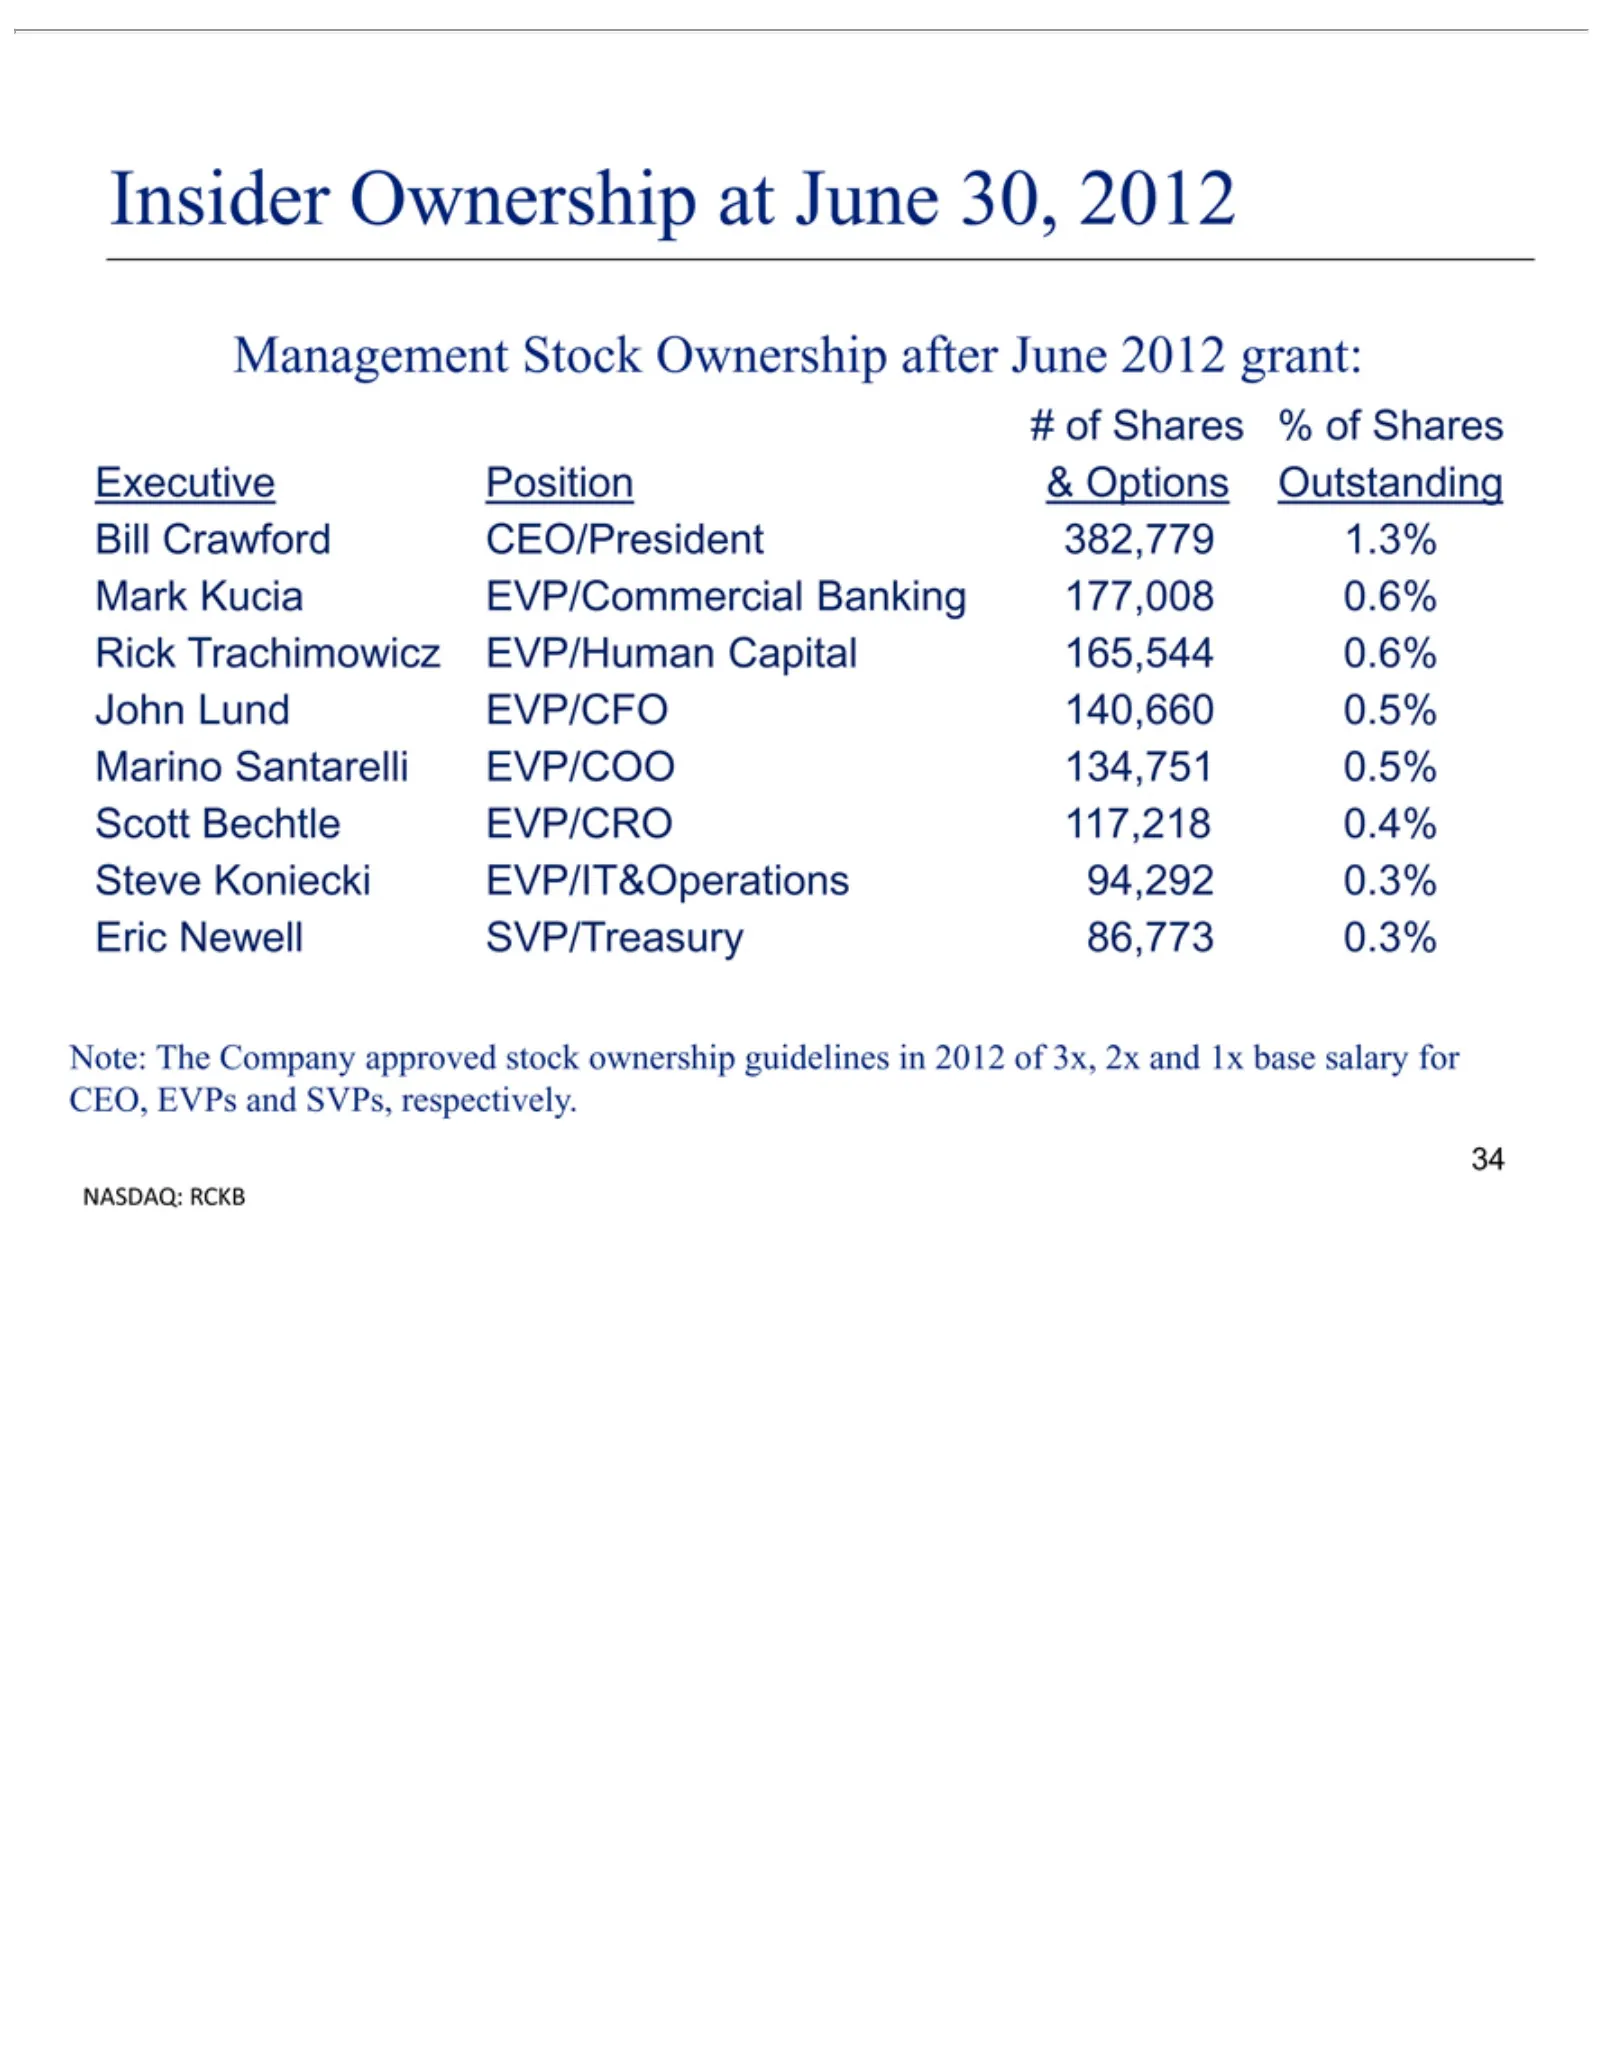
Slide 34: Insider Ownership
Insider #Management Executive Bill Mark Rick John Marino Scott Steve Eric Note: NASDAQ: 34of Crawford Shares Newell Trachimowicz Lund Bechtle Kucia The Koniecki Ownership Santarelli Position Company EVP/CFO RCKB %SVP/Treasury EVP/Commercial Stock EVP/CRO of CEO/President EVP/IT&Operations Shares EVP
Slide 35: Appendix
35 APPENDIX
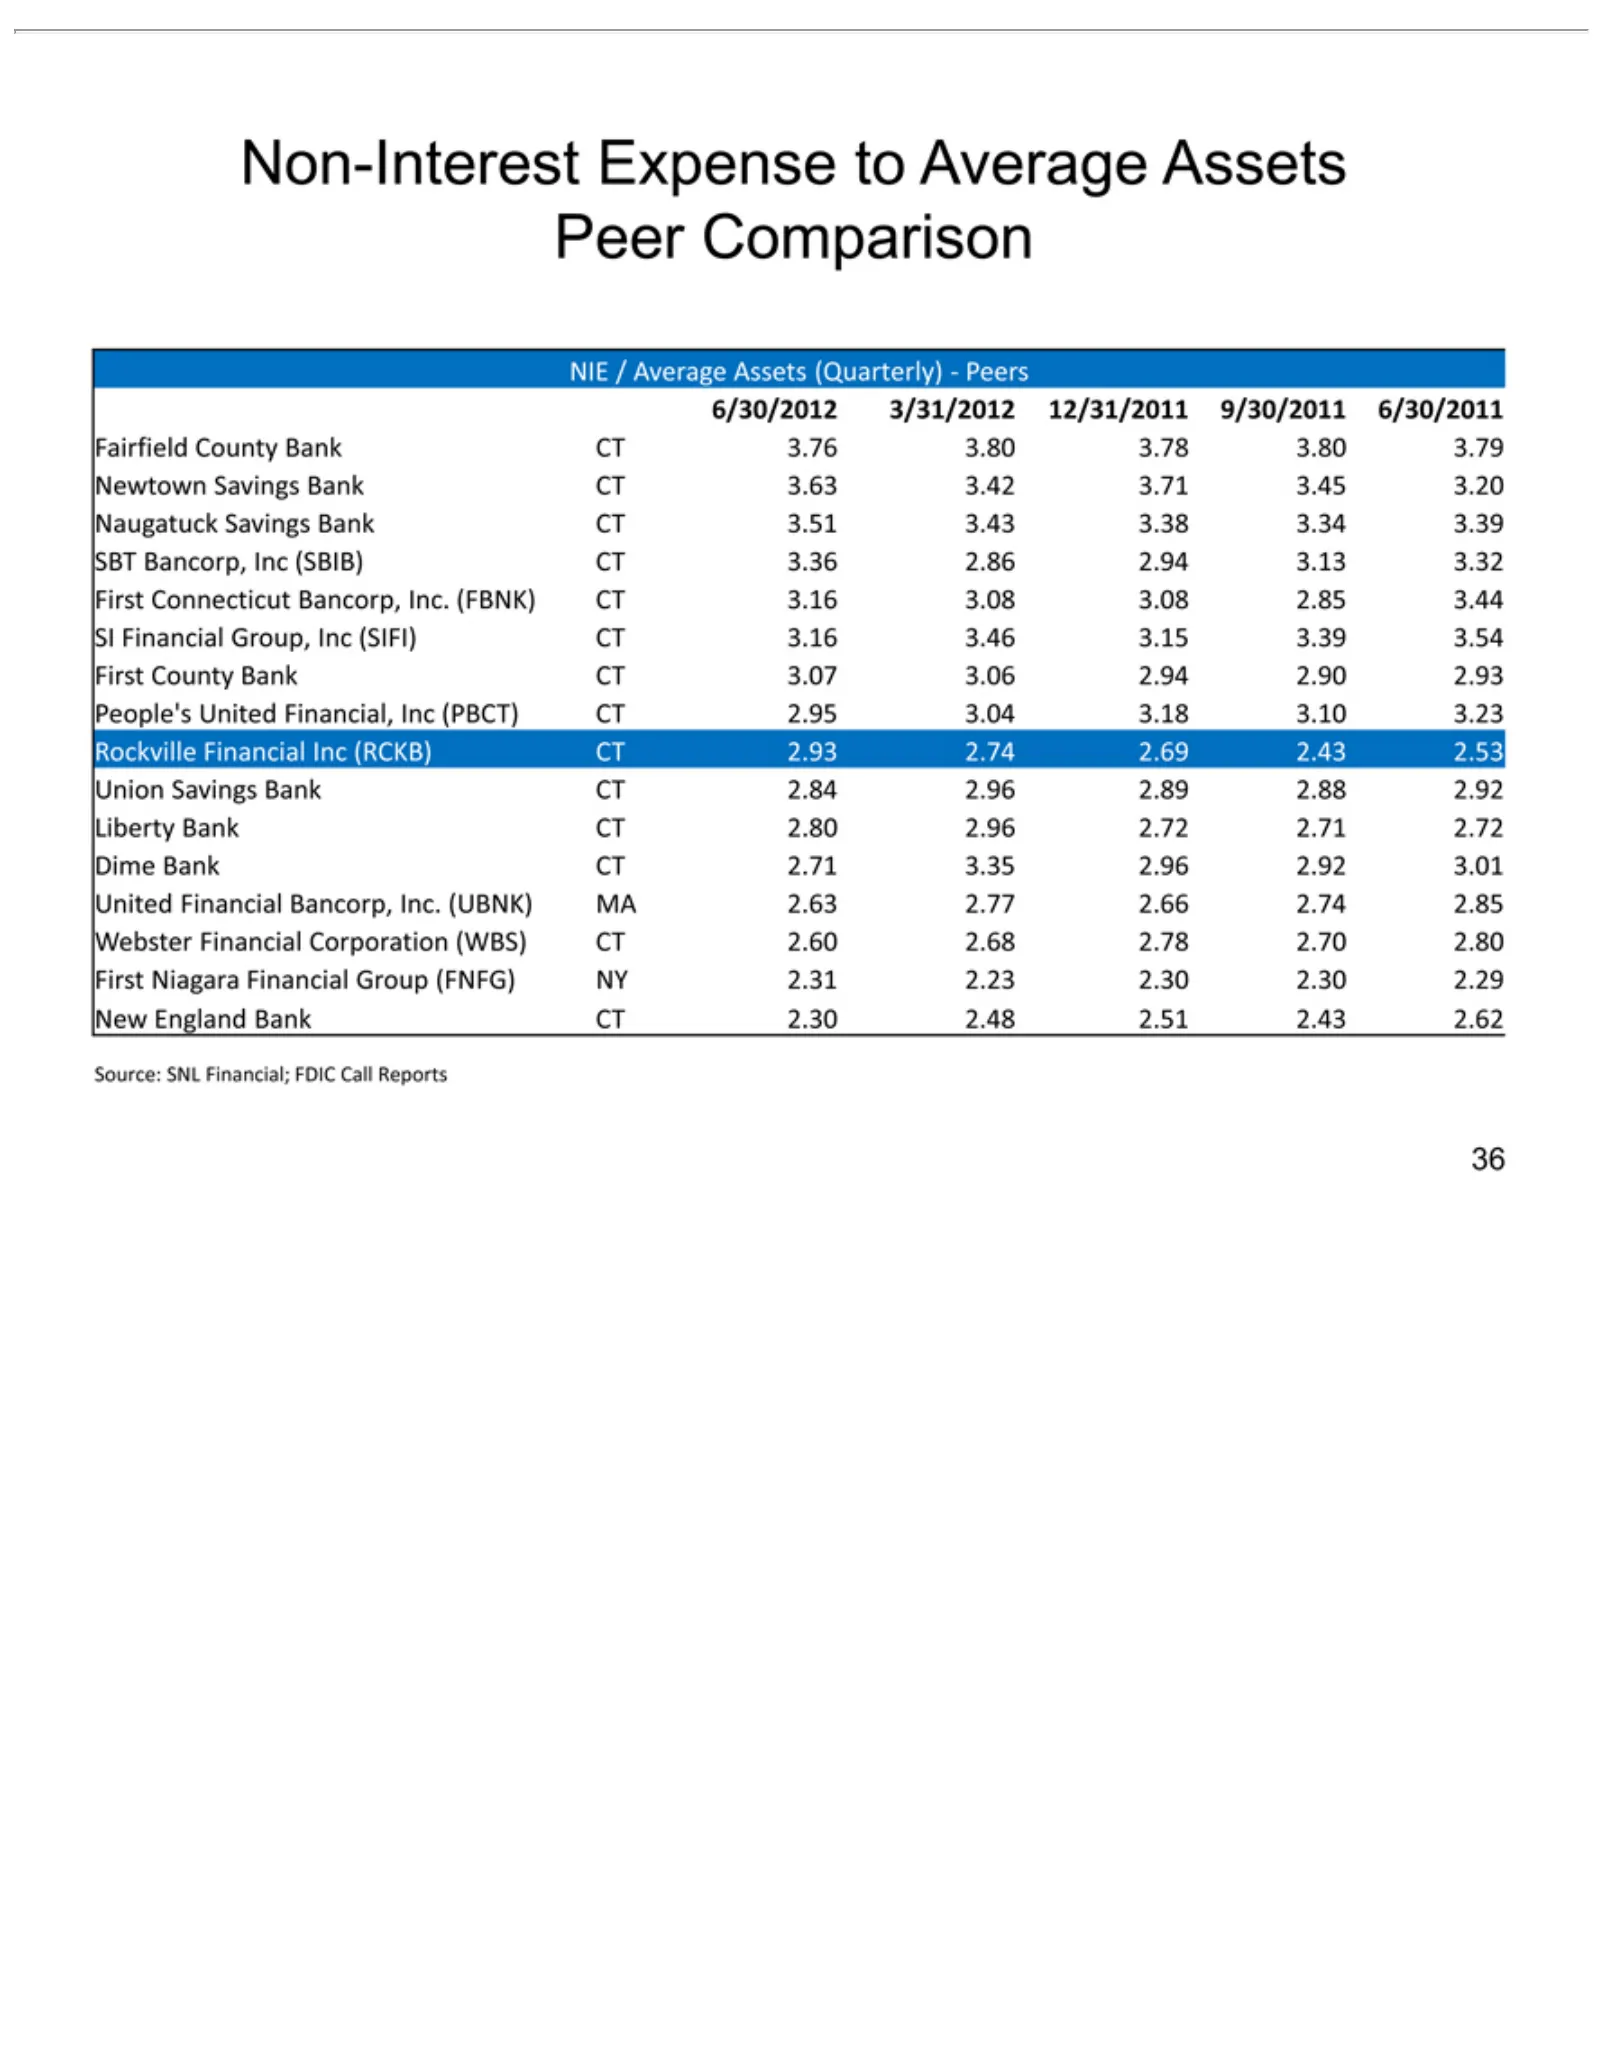
Slide 36: Non-Interest Expense to Assets Peer Comparison
Non-Interest NIE 6/30/2012 Fairfield Newtown Naugatuck SBT SI People’s Rockville Union Liberty Dime United Webster First New Source: 36 Financial /Bancorp, Connecticut County Niagara England Average Bank Savings Financial Bank SNL Financial United County Savings Financial 3/31/2012 Savings CT Group,
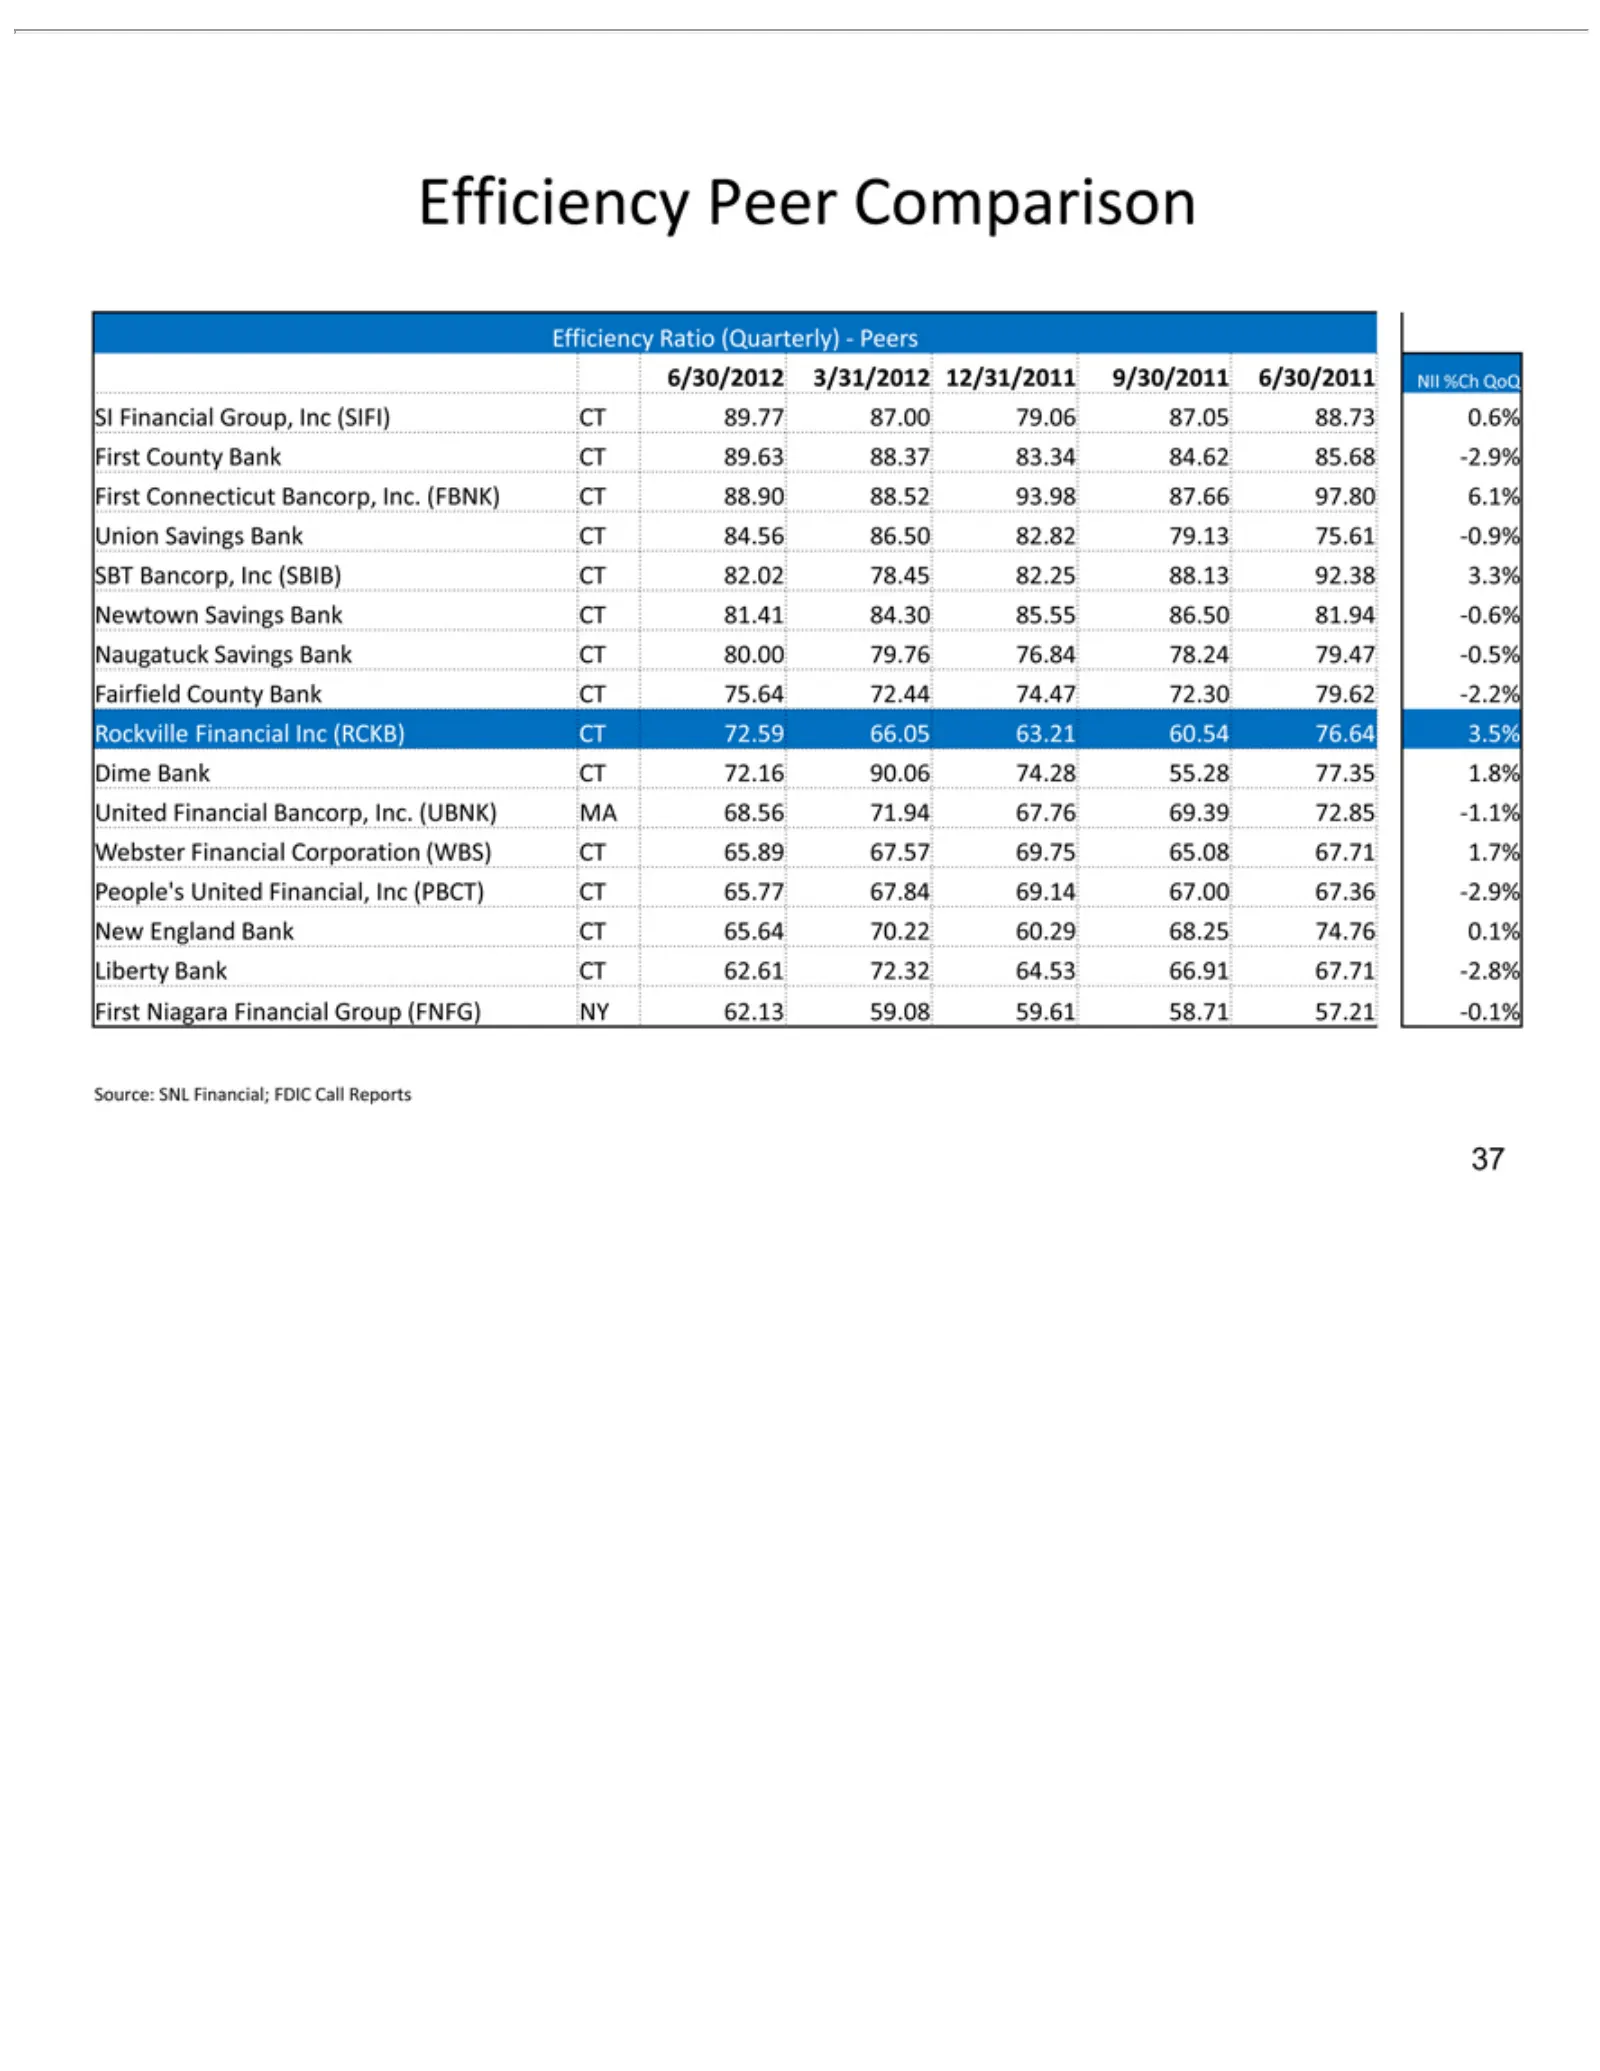
Slide 37: Efficiency Ratio Peer Comparison
Efficiency 6/30/2012 SI Union SBT Newtown Naugatuck Fairfield Rockville Dime United Webster People’s New Liberty First Source: 37 Financial Bancorp, County Connecticut Niagara England Bank Savings Financial Bank SNL Financial United County Savings Financial 3/31/2012 Peer Ratio Savings CT Group, Ban
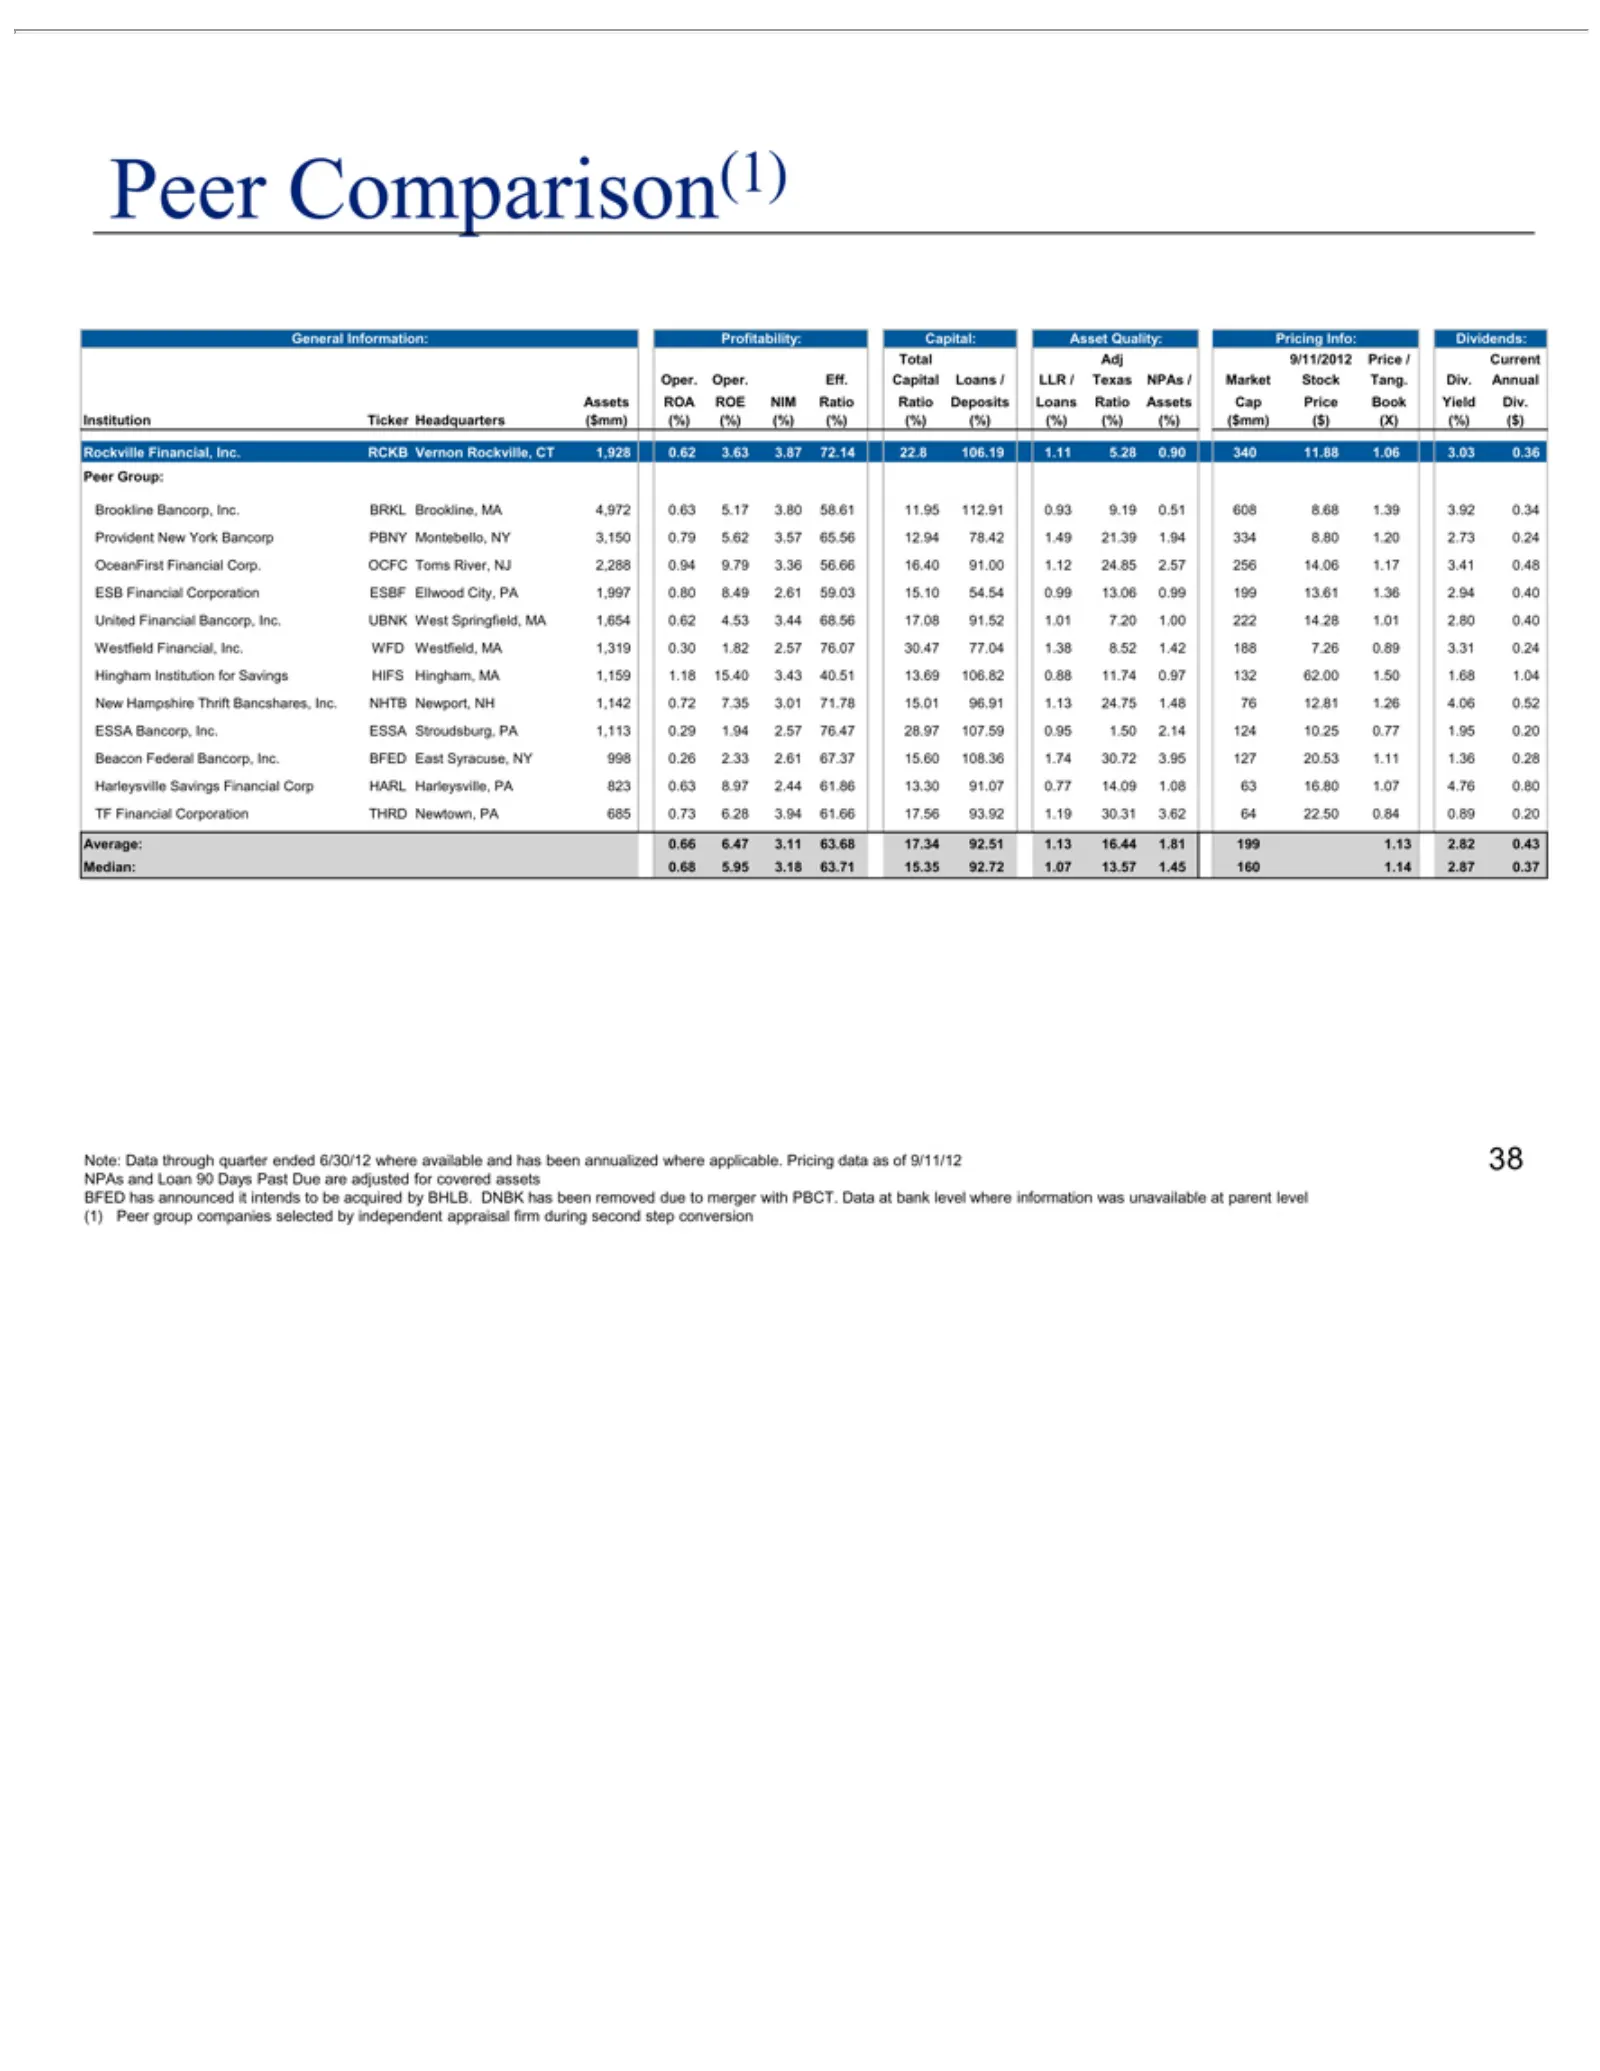
Slide 38: General Information: Peer Group Comparison
General Total Oper. Assets Institution Rockville Peer Brookline Provident OceanFirst ESB United Westfield Hingham New ESSA Beacon Harleysville TF Average: Median: Note: it (1) 38 intends Financial Comparison(1) Group: Financial Hampshire Adj Oper. Data Bancorp, ROA Financial Federal Information: Pee
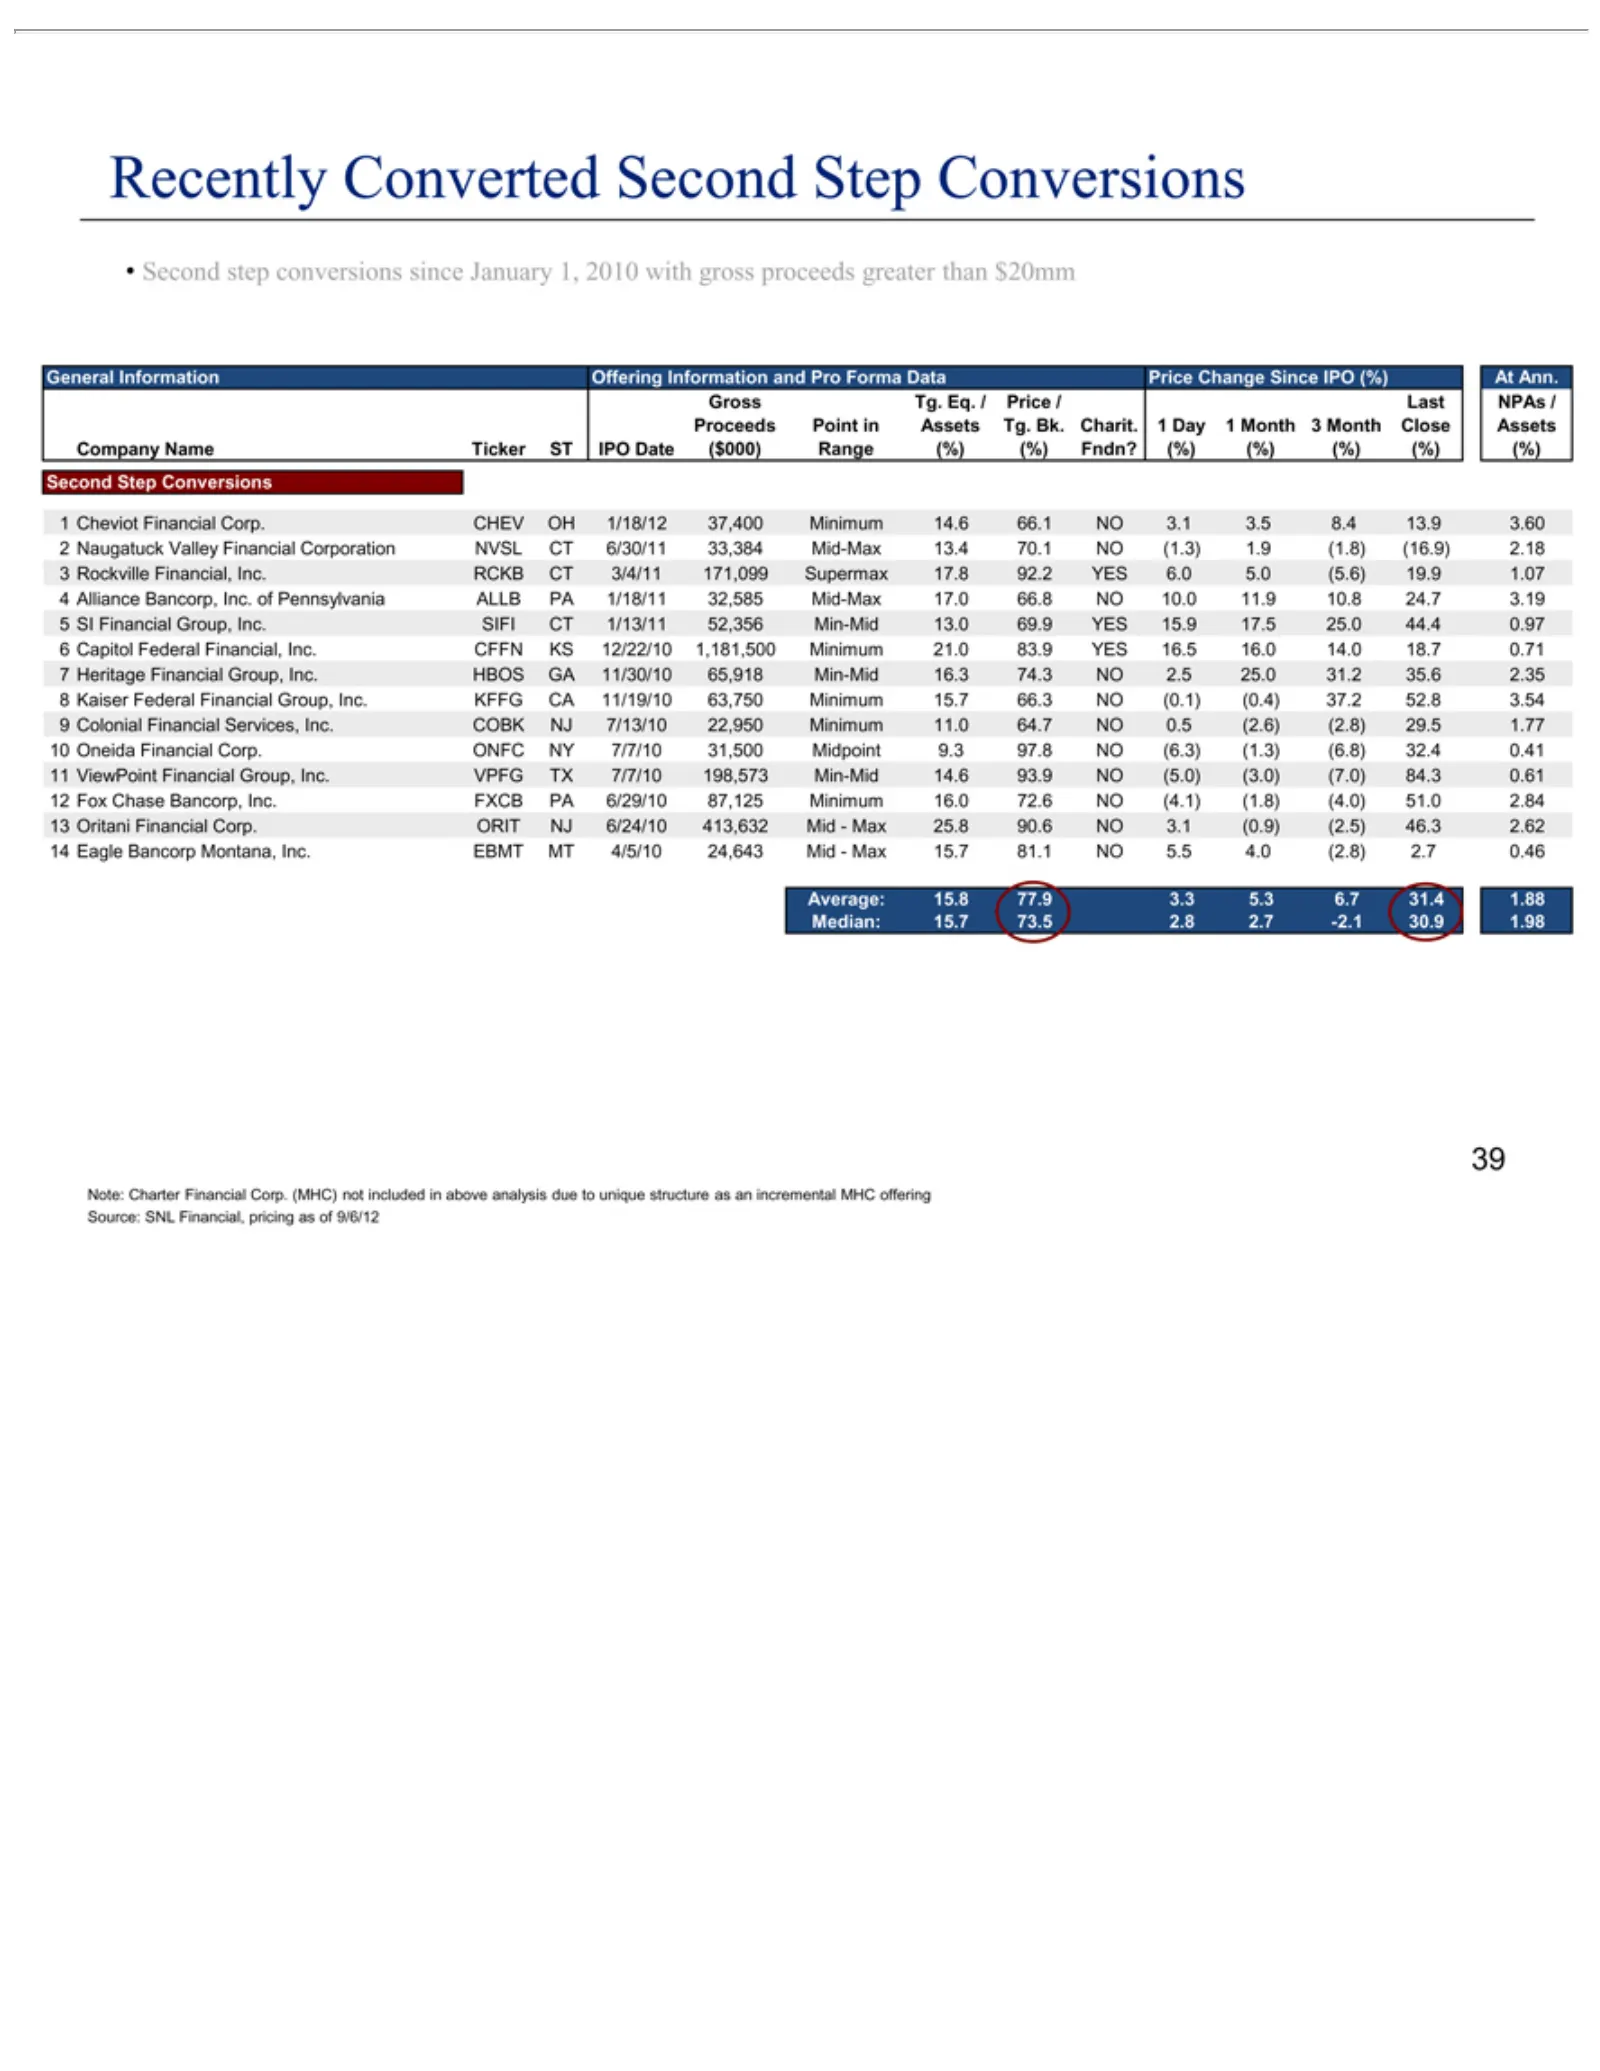
Slide 39: Recently Converted Companies
•Recently General Gross Proceeds Company 231Second 987654 Second 10 11 12 13 14 Tg. Average: Median: Note: 39KaiserStep Information Cheviot Colonialstep Converted Naugatuck Capitol Point ViewPoint Oneida Fox Oritani Eagle Name Eq. Charter Chase 15.7Conversions conversions /77.9 Rockville Alliance SI
Source: SEC EDGAR · 8-K filed Sep 20, 2012
More decks from United Financial Bancorp Inc
 Merger or Acquisition (July 2019)10 slides · Jul 15, 2019
 Shareholder Meeting (May 2019)14 slides · May 13, 2019
 Q1 2019 Earnings Presentation27 slides · Apr 16, 2019
 Q4 2018 Earnings Presentation26 slides · Jan 22, 2019
 Q3 2018 Earnings Presentation25 slides · Oct 16, 2018
 Q2 2018 Earnings Presentation25 slides · Jul 17, 2018