InterMune — J.P. Morgan 2014 Healthcare Conference
29 slides from InterMune's conference presentation, Jan 13, 2014
Slide 1: J.P. Morgan 2014 Healthcare Conference
J.P. Morgan 2014 Healthcare Conference January 13, 2014 Exhibit 99.2
Slide 2: Forward-looking Statements
Forward-looking Statements This presentation contains forward-looking statements made pursuant to the "safe harbor" provisions of the Private Securities Litigation Reform Act of 1995. Investors are cautioned that, without limitation, statements in this presentation regarding InterMune's plans and ex
Slide 3: Our Company: A Fully Integrated Global Biotech Company with Significant Growth Potential
Our Company: A Fully Integrated Global Biotech Company with Significant Growth Potential Demonstrated Research Capability – first in HCV, now delivering in fibrosis Development and Regulatory expertise in Specialty Diseases – Multiple, high-quality, multi-national clinical trials in Phases 1-4 – Esb
Slide 4: Our Franchise: Idiopathic Pulmonary Fibrosis (IPF) A Large, Lethal Orphan Disease
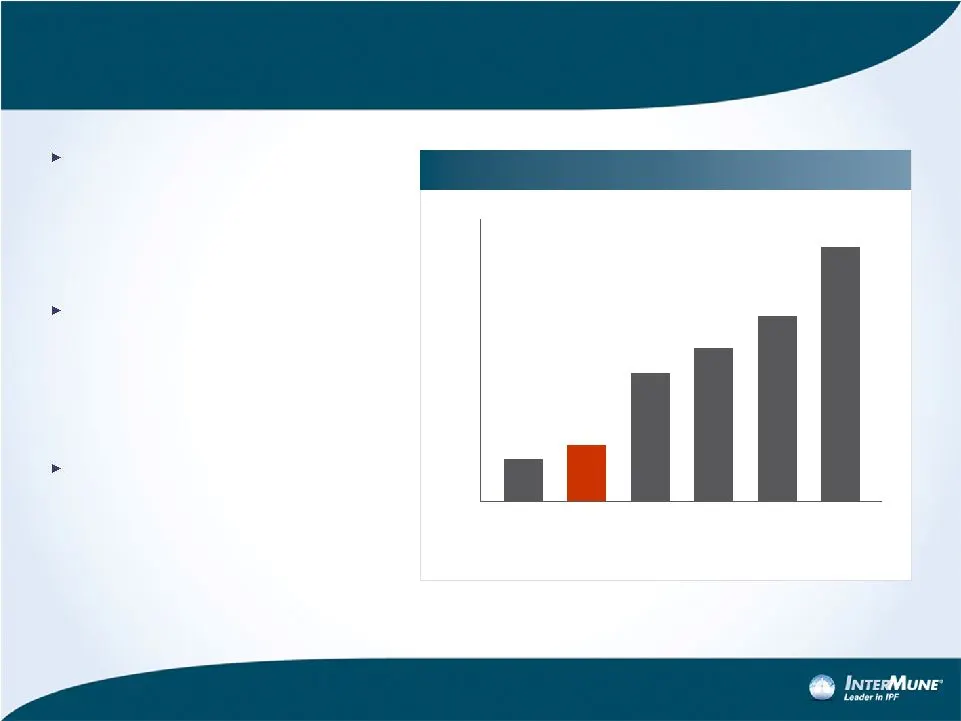
Our Franchise: Idiopathic Pulmonary Fibrosis (IPF) A Large, Lethal Orphan Disease % Patients Surviving at 5 Years Progressive scarring of the lungs with no known cause – Median survival: 2-5 years* Large market in North America + European Top-15: – 118K to 158K prevalence – 28K to 37K incidence Esbr
Slide 5: Our Strategy: Maximize the Value of Esbriet and Grow Beyond Esbriet and IPF
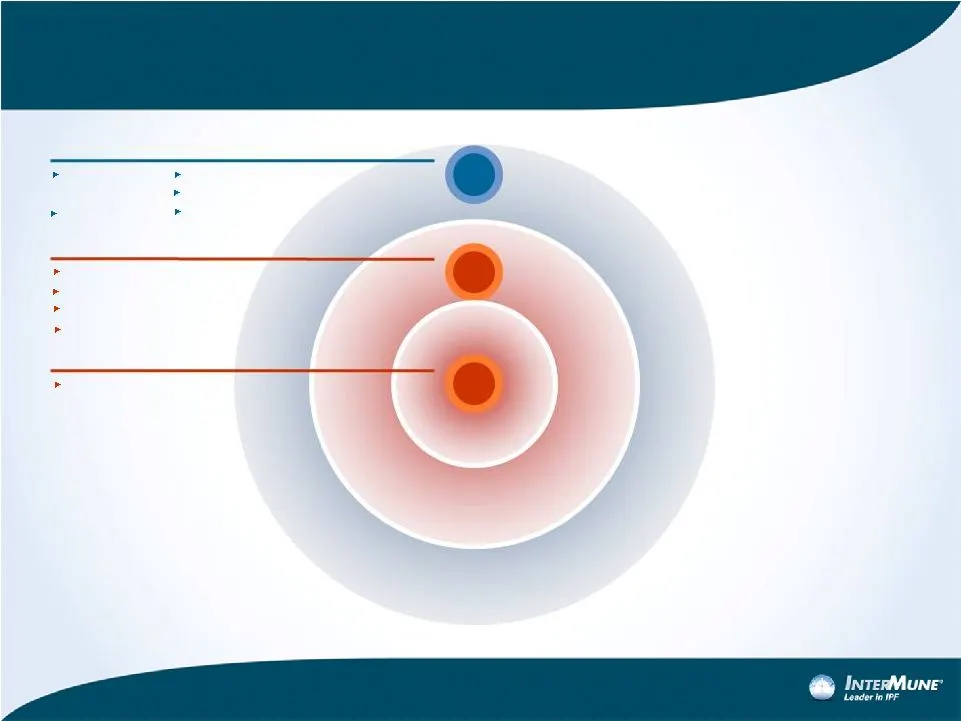
Our Strategy: Maximize the Value of Esbriet and Grow Beyond Esbriet and IPF A B C Grow Beyond Esbriet and IPF Expand Esbriet in IPF New formulations Phase 4 ISTs Registries Leader in IPF: Commercialize Esbriet Key launch and commercialization activities Vision: Leader in Specialty Fibrotic Diseases
Slide 6: InterMune Is a First Mover in an Emerging Growth Area with Significant Unmet Need
InterMune Is a First Mover in an Emerging Growth Area with Significant Unmet Need: Fibrotic Diseases Lung, kidney, liver, bone, heart, GI tract, others ~40M patients in all fibrotic diseases High Unmet Need and Severity Affecting Multiple Organ Systems Fibrotic Diseases ~120 assets in development (5
Slide 7: Commercializing Esbriet (pirfenidone) in IPF
Commercializing Esbriet ® (pirfenidone) in IPF
Slide 8: Successful EU Commercialization Strategy: Focus First on Top 15
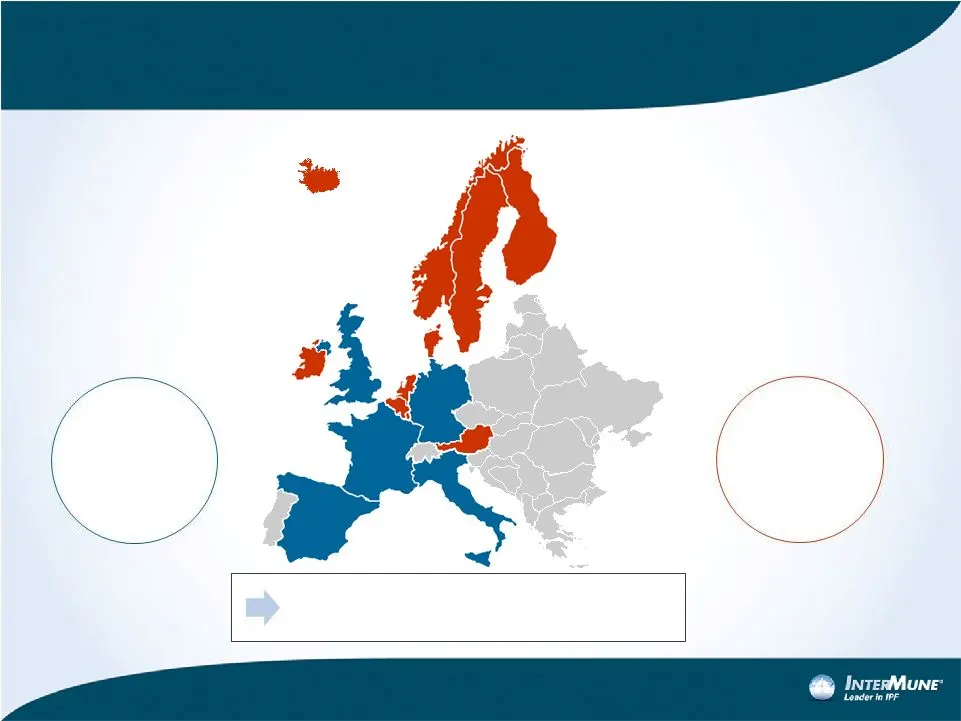
Successful EU Commercialization Strategy: Focus First on Top 15 Esbriet is now available for prescription for 85% of the IPF patients in the Top 15 EU countries Focus First on Top 5 Countries: Germany, France, Italy, UK, Spain Population of 314 million ~ 70-75% of EU market value Esbriet has launche
Slide 9: Esbriet Revenue – EU and Canada Nine Consecutive Quarters of Growth
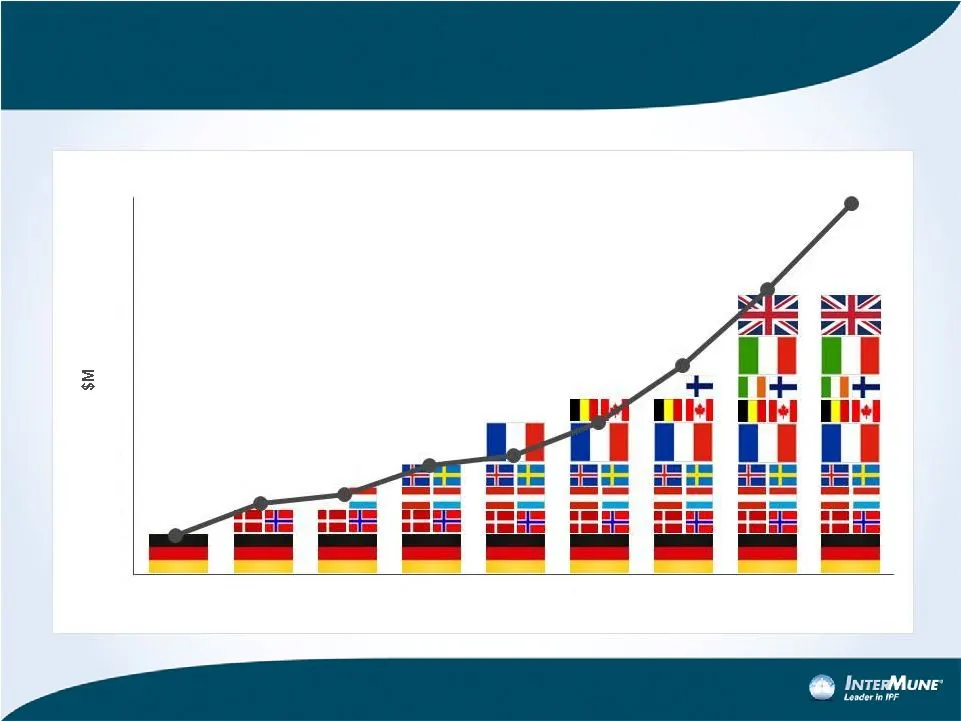
Esbriet Revenue – EU and Canada Nine Consecutive Quarters of Growth 2.7 4.9 5.5 7.5 8.2 10.5 14.4 19.7 25.6 Q4’11 Q1’12 Q2’12 Q3’12 Q4’12 Q1’13 Q2’13 Q3’13 Q4’13
Slide 10: @ Intenvune
@ Intenvune Lender in PE
Slide 11: The U.S. IPF Market Is Very Attractive
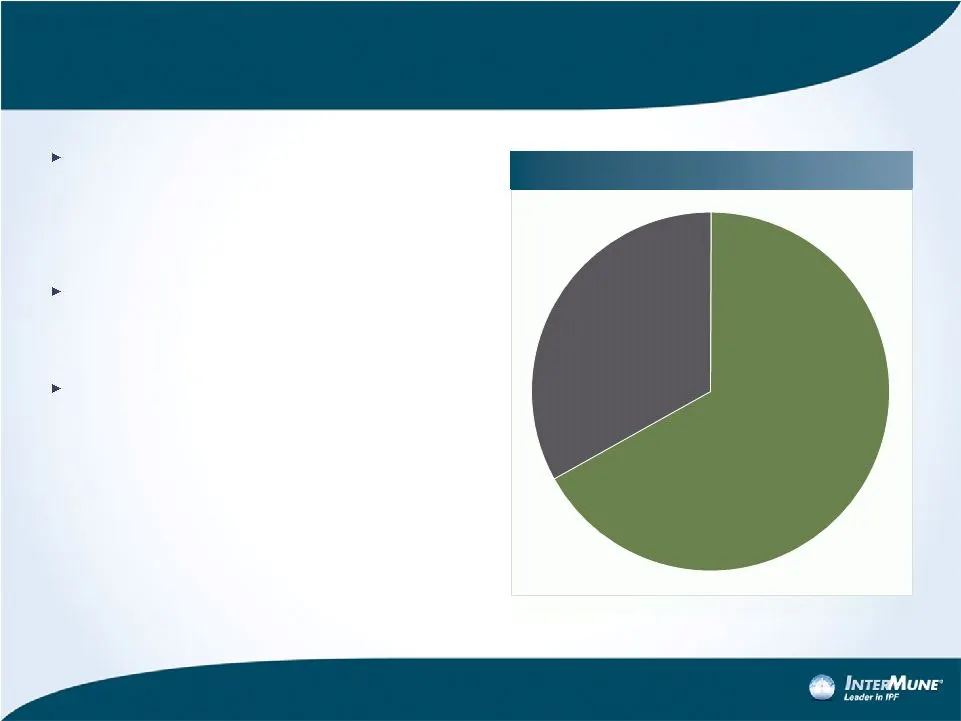
The U.S. IPF Market Is Very Attractive U.S. IPF Prevalence Mild to Moderate (30,000-50,000) Severe (~20,000) Very Large Orphan Disease – Incidence ~ 15-20K/year – Prevalence ~ 30-50K mild/moderate Desperate Unmet Need – No FDA-approved IPF medicines Attractive Business Model – Value based, Orphan Di
Slide 12: Benchmark Products in the U.S. Have a Broad Range of Prices
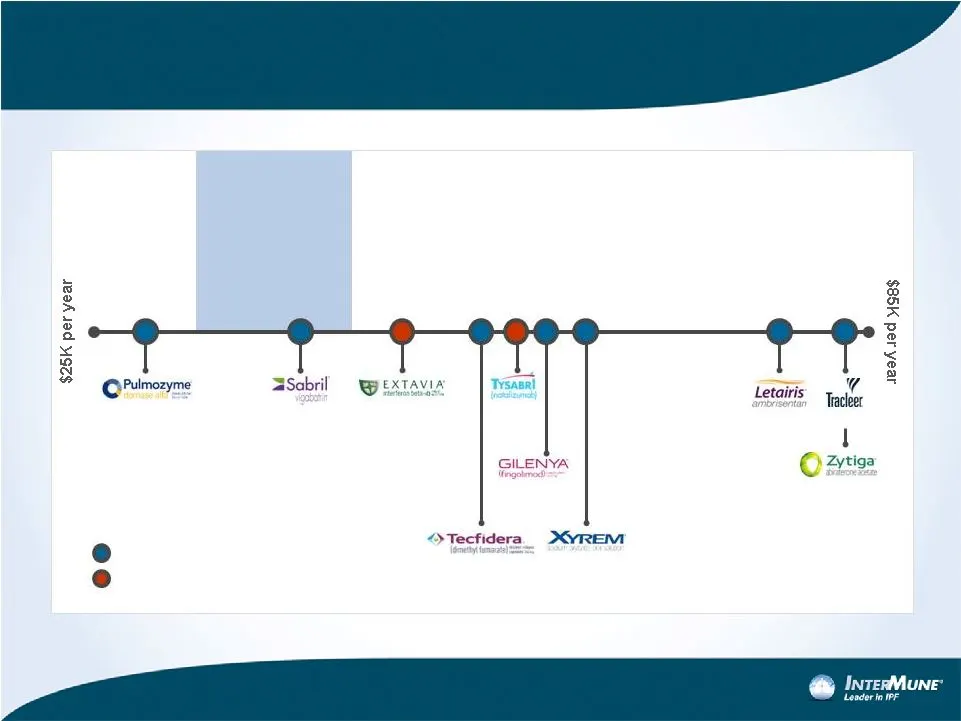
Benchmark Products in the U.S. Have a Broad Range of Prices ($000’s/year)* Esbriet ® EU: $33K to $45K Canada: $42K * Wholesale Acquisition Cost (WAC). Source: AnalySource (12/17/13) (PAH) (PAH) (mCRPC) (cystic fibrosis) (severe epilepsy) (multiple sclerosis) (multiple sclerosis) (multiple sclerosis)
Slide 13: ASCEND Phase Study for U.S. Registration
ASCEND Phase 3 Study for U.S. Registration
Slide 14: Three Phase Trials Support Clinically Meaningful Effect on Lung Function
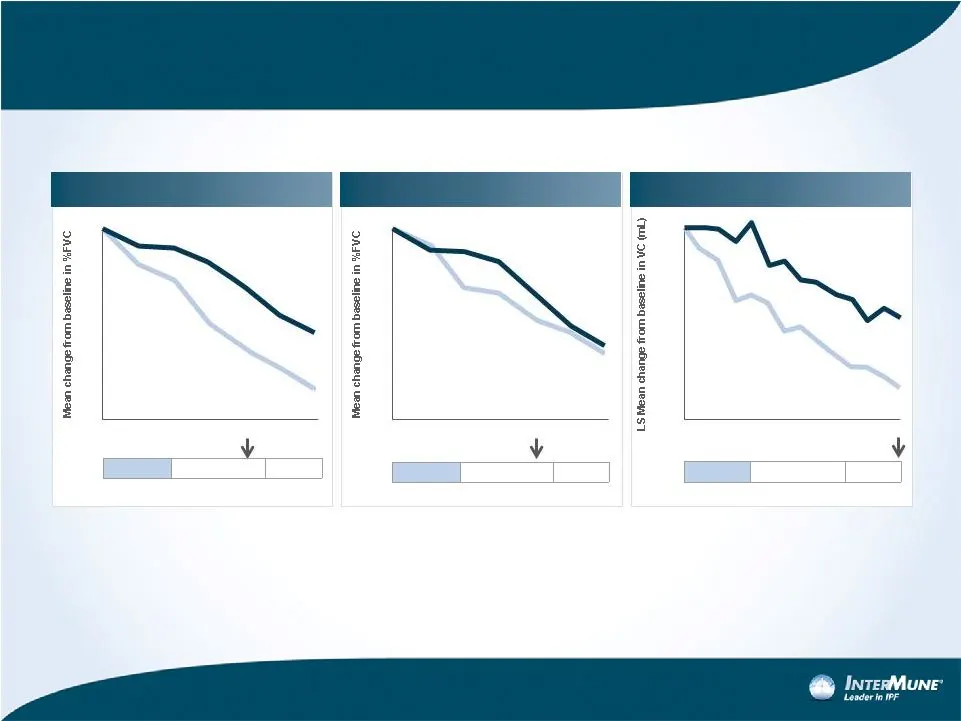
Three Phase 3 Trials Support Clinically Meaningful Effect on Lung Function, with Generally Consistent Results at One Year PIPF-004: FVC Change Week 72* PIPF-006: FVC Change Week 72* SP3: VC Change at Week 52* Weeks -15 -10 -5 Weeks -15 -10 -5 Week 48 52% reduction P<0.001 Week 48 27% reduction P=0.0
Slide 15: ASCEND Design Based on Key Learnings from Prior IPF Trials (1)
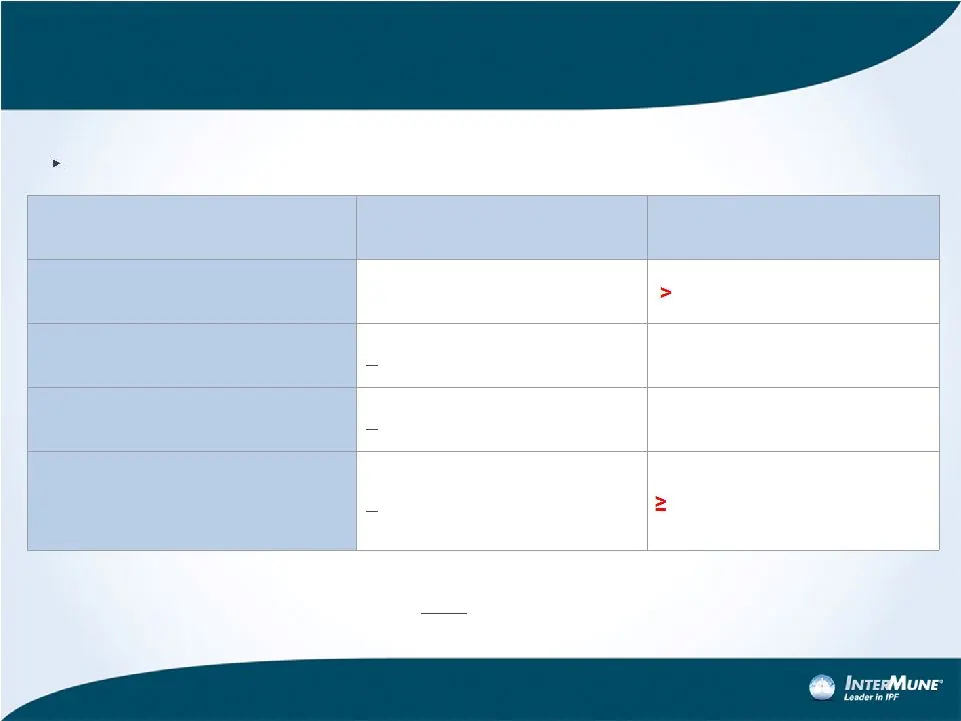
ASCEND Design Based on Key Learnings from Prior IPF Trials to Maximize Probability of Success (1) Rigorously Analyzed our IPF Databases to Determine “Predictors of Progression” Variables* 2 CAPACITY Trials ASCEND Trial Time Since Diagnosis No time limitation 6 to 48 months Baseline % Predicted FVC >
Slide 16: ASCEND Design Based on Key Learnings from Prior IPF Trials (2)
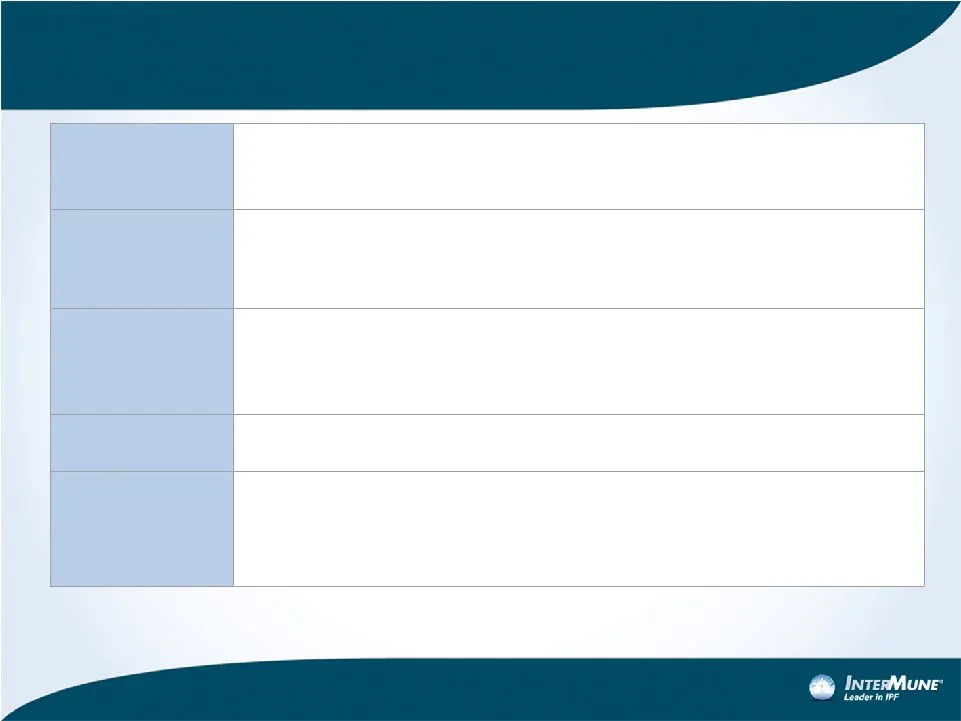
ASCEND Design Based on Key Learnings from Prior IPF Trials to Maximize Probability of Success (2) Duration A 52-Week Study – All three Phase 3 studies of pirfenidone have “won” at 1 year Primary Endpoint FVC Change Versus Placebo (difference versus placebo) Categorical FVC for treatment effect size
Slide 17: Clinically Meaningful Changes in FVC in IPF Studies (1)
Clinically Meaningful Changes in FVC in IPF Studies (1) The Clinical Reality: – ~2/3 of IPF patients have little decline in FVC in clinical studies of ~ one year – ~1/3 of IPF patients have significant decline in FVC – Therefore MEAN decline in FVC of a study population is not the best measure of tr
Slide 18: Clinically Meaningful Changes in FVC in IPF Studies (2)
Clinically Meaningful Changes in FVC in IPF Studies (2) Why is Categorical Change in FVC the best metric of clinical meaningfulness? – Measures changes in an individual patient – Addresses the statistical problem of the population mean – Can be easily tied to the MCID (a population mean cannot) – Re
Slide 19: Categorical FVC Results at One Year From CAPACITY ITT
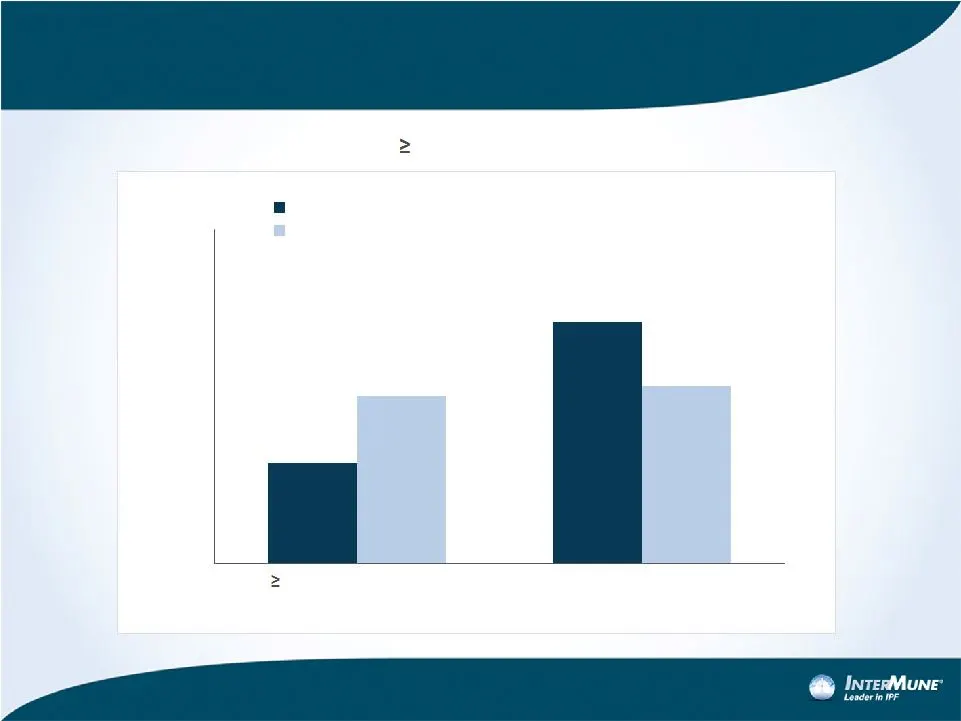
Categorical FVC Results at One Year From CAPACITY ITT *Rank ANCOVA p < 0.001* Pirfenidone Placebo 40% Reduction 36% Increase 10% Decline/Death/LT No Decline (>0%) Patients (%) Categorical FVC: Patients with 10% FVC Decline/Death/Lung Transplant (LT)
Slide 20: CAPACITY ITT Patients Clinically Meaningful Outcome: 10% FVC Decline/Death/LT
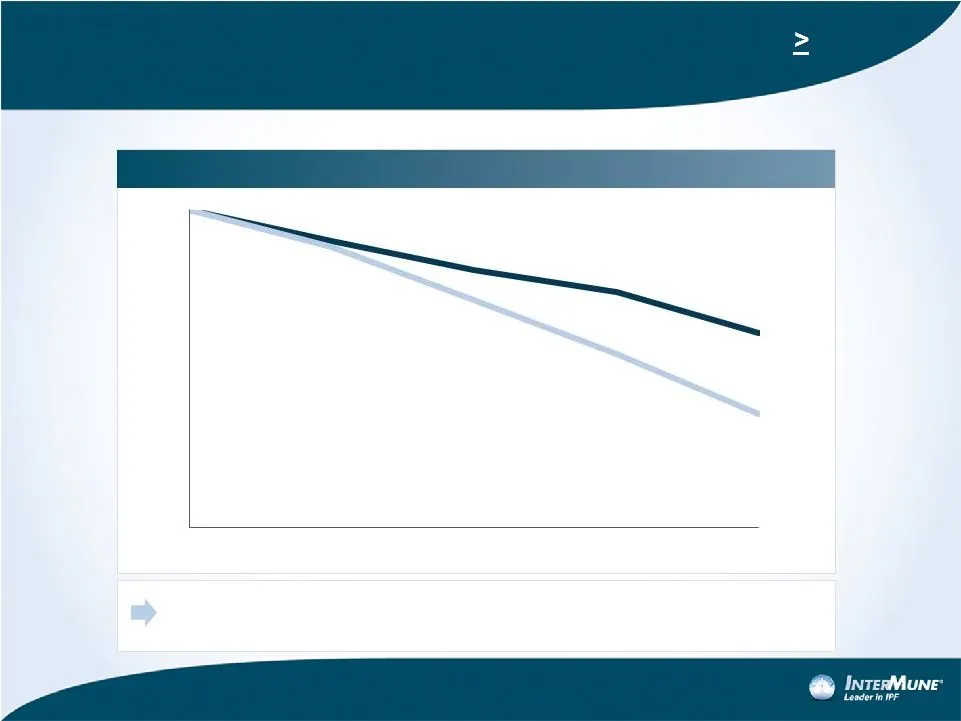
CAPACITY ITT Patients Clinically Meaningful Outcome: Proportion of Patients with 10% FVC Decline/Death/LT Reduced by 40% Relative to Placebo P<0.0001 P=0.0002 P<0.0001 P=0.002 Patients (%) Pirfenidone 2403 mg/d Placebo 40% Reduction Proportion of patients with No FVC decline was 36% greater relative
Slide 21: Two Other Key Secondary Endpoints Showed Clinically Meaningful Change in CAPACITY
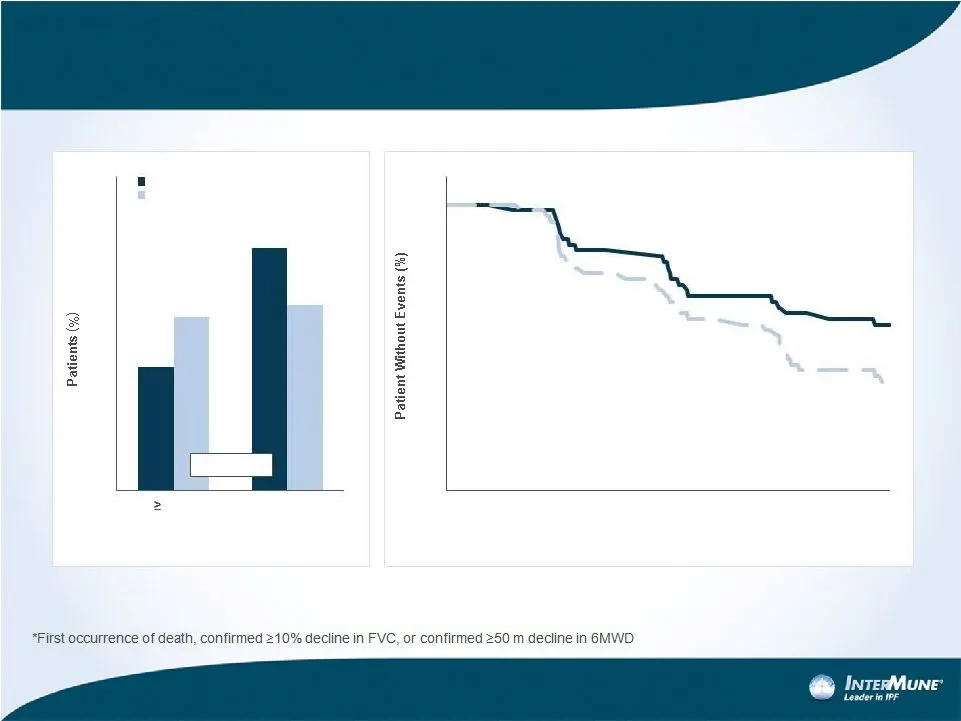
Two Other Key Secondary Endpoints In ASCEND Showed Clinically Meaningful Change in CAPACITY at One Year 29% Reduction 31% Increase HR 0.62 (0.46 – 0.84) P-value = 0.0015 Pirfenidone 2403 mg/d Placebo 50 m Decrement or Death No Decline p = 0.0037 Months Pirfenidone Placebo 6MWD Change Progression-Fre
Slide 22: ASCEND Summary and Timeline
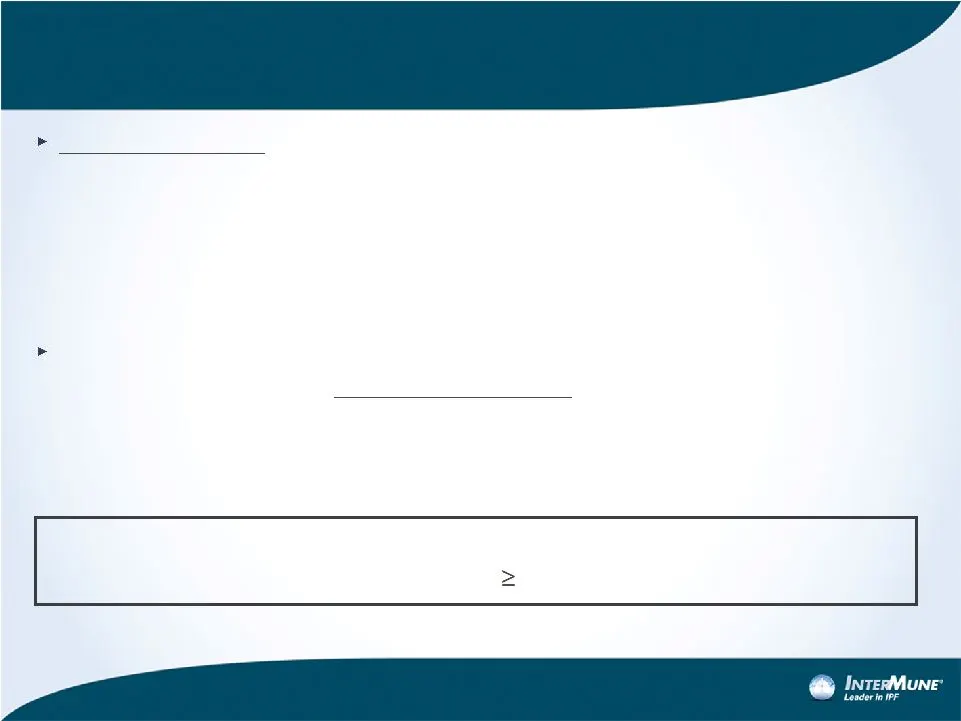
ASCEND Summary and Timeline ASCEND is designed to win — built on our decade of IPF experience – Large, one-year study – Over 95% power using CAPACITY ITT results – Centralized procedures for more homogeneity – Enrichment Strategy for patients with more FVC progression Excellent Study Conduct – High
Slide 23: @ Intenvune
@ Intenvune Lender in PE
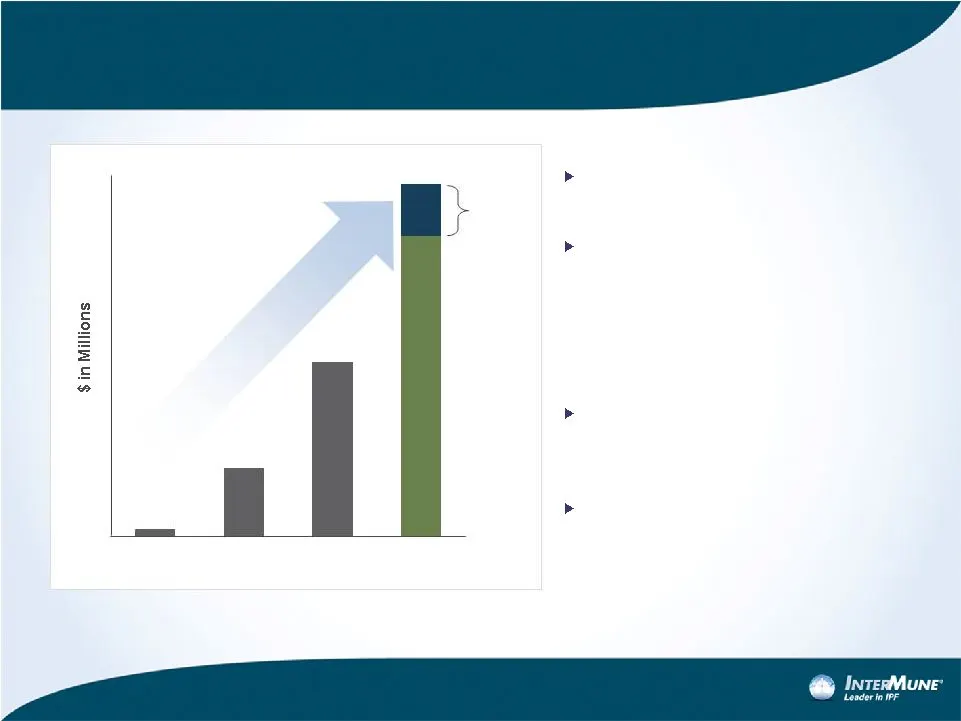
Slide 24: Worldwide Esbriet Revenue
Worldwide Esbriet Revenue Nine consecutive quarters of growth since launch 168% revenue growth in 2013 – New countries – one-time effects due to NPP conversion and pent- up demand – Launched countries – greater penetration and persistence 2014 guidance range of $115 to $135 million represents ~65% t
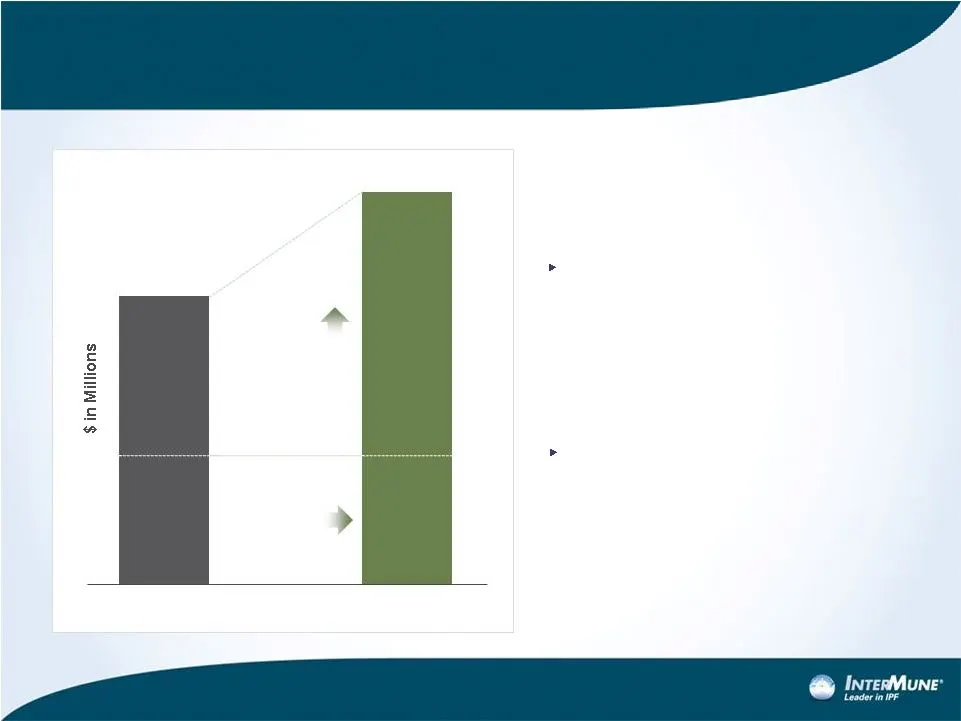
Slide 25: Total Operating Expenses – 2014: Building a Commercial Company with an R&D Pipeline
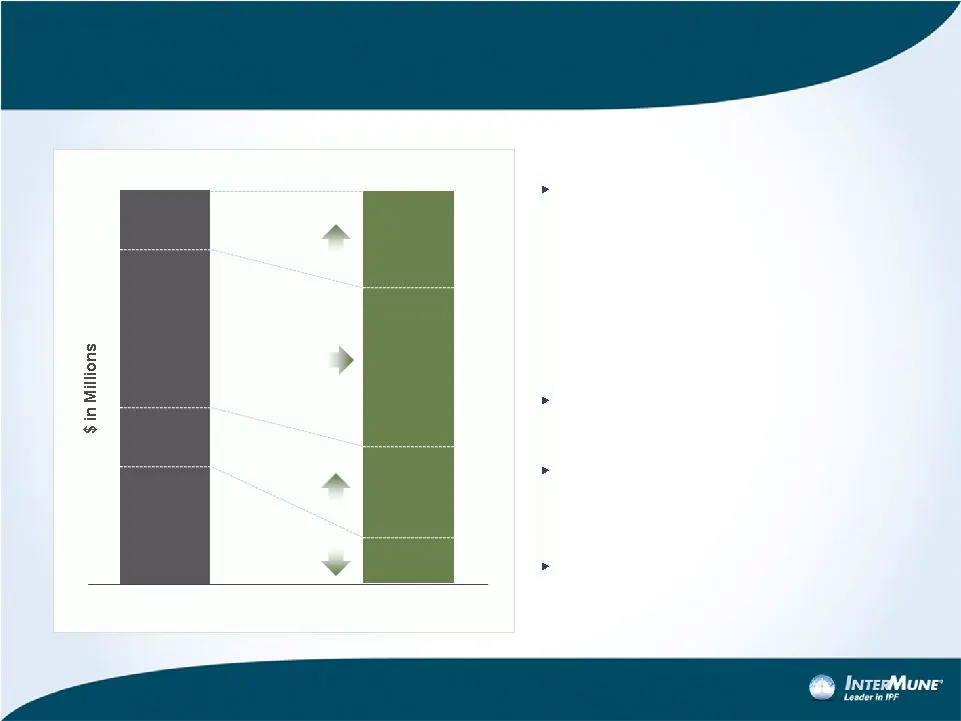
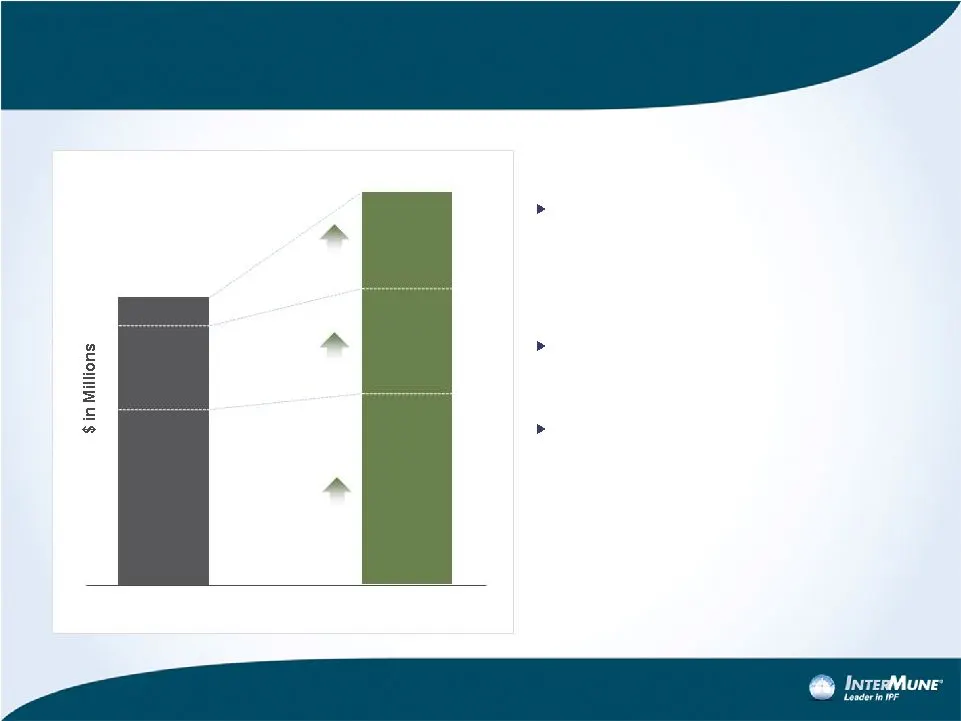
Total Operating Expenses – 2014: Building a Commercial Company with an R&D Pipeline R&D SG&A SG&A R&D $320 - $345 $255 - $265 Guidance Important SG&A increase – U.S. launch preparations to ensure successful launch of Esbriet – Expanding commercial presence in Europe to maximize Esbriet growth Sustai
Slide 26: Research & Development Expenses — 2013 to 2014
Research & Development Expenses — 2013 to 2014 Regulatory, quality and medical affairs support Research and early stage programs Regulatory, quality and medical affairs support Research and early stage programs NDA Prep, RECAP and New Clinical ASCEND ASCEND NDA Prep, RECAP and New Clinical Increased
Slide 27: Selling, General & Administrative Expenses — 2013 to 2014
30% 60% 10% Selling, General & Administrative Expenses — 2013 to 2014 EU/Canada SG&A U.S. Launch Preparation EU/Canada SG&A Corporate/US G&A Corporate/US G&A U.S. Launch Preparation $210 - $225 $145 - $150 Increase driven primarily by U.S. commercial launch preparations (“S”) – Weighted to H2 (post
Slide 28: InterMune Showing Strong Momentum and Poised to Enter the U.S. Market
InterMune Showing Strong Momentum and Poised to Enter the U.S. Market With EU reimbursement now resolved, Esbriet is growing very well – Nine consecutive quarters of revenue growth since first launch – 2013 revenue growth +168% vs. 2012 – 2014 guidance range: $115-$135 million (+65-90%) – Expect cas
Slide 29: InterMune: Leader in IPF
cy INTERMUNE’ Leader in IPF
Source: SEC EDGAR · 8-K filed Jan 13, 2014