Maverick Tube — Investor Presentation (March 2006)
32 slides from Maverick Tube's investor presentation, Mar 13, 2006
Slide 1: Investor Presentation March 2006
Maverick is a leading provider of products and services for the drilling, completion, and production cycles of oil and natural gas. Maverick has demonstrated a history of successful organic and strategic growth, providing a solid foundation for future international expansion and the addition of othe
Slide 2: Forward looking statements
These slides accompany an oral presentation by Maverick Tube Corporation which, except for the historical information, contain forward- looking statements representing our expectations or beliefs about future events and financial performance. Forward-looking statements are subject to known and unkno
Slide 3: Non-GAAP financial matters
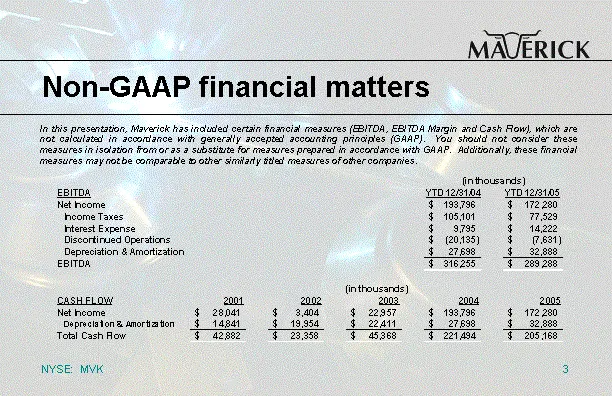
Non-GAAP financial matters In this presentation, Maverick has included certain financial measures (EBITDA, EBITDA Margin and Cash Flow), which are not calculated in accordance with generally accepted accounting principles (GAAP). You should not consider these measures in isolation from or as a subst
Slide 4: Company overview
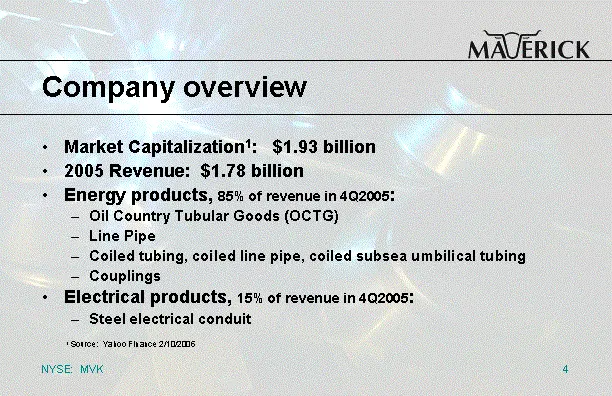
Market Capitalization1: $1.93 billion 2005 Revenue: $1.78 billion Energy products, 85% of revenue in 4Q2005: Oil Country Tubular Goods (OCTG) Line Pipe Coiled tubing, coiled line pipe, coiled subsea umbilical tubing Couplings Electrical products, 15% of revenue in 4Q2005: Steel electrical conduit 1
Slide 5: Strong business climate
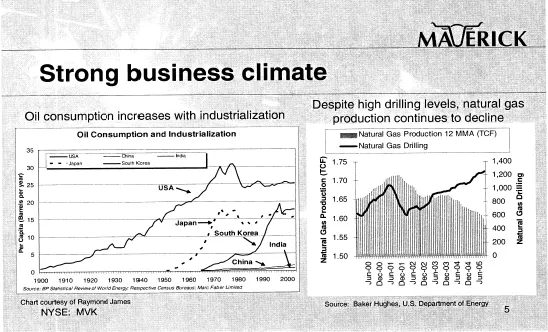
Strong business climate Oil consumption increases with industrialization Despite high drilling levels, natural gas production continues to decline Chart courtesy of Raymond James Source: Baker Hughes, U.S. Department of Energy
Slide 6: Investment highlights
Market leader in key segments of the oil service industry Track record of successfully executing growth initiatives Earnings momentum into '06 Expect substantial cash flow in 2006 2006 initiatives expected to improve margin and earnings for 2007 Focused on achieving superior return on equity Well-po
Slide 7: Market leadership
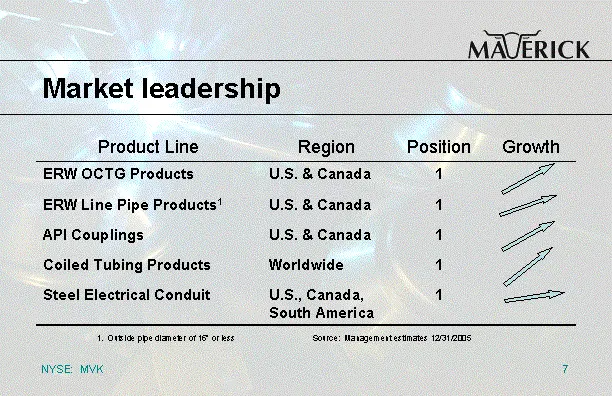
Market leadership Product Line Region Position Growth ERW OCTG Products U.S. & Canada 1 ERW Line Pipe Products1 U.S. & Canada 1 API Couplings U.S. & Canada 1 Coiled Tubing Products Worldwide 1 Steel Electrical Conduit U.S., Canada, South America 1 1. Outside pipe diameter of 16" or less Source: Mana
Slide 8: Global reach
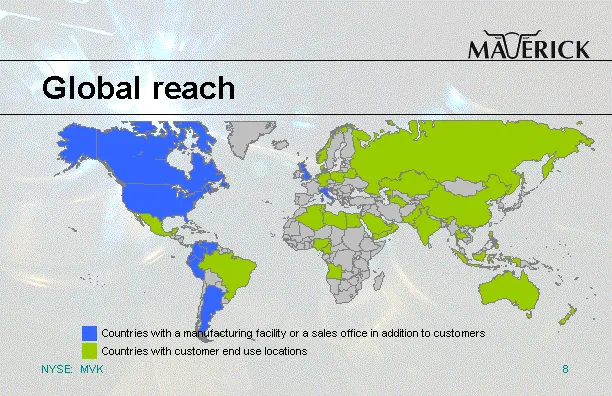
Countries with a manufacturing facility or a sales office in addition to customers Countries with customer end use locations Global reach
Slide 9: International manufacturing operations
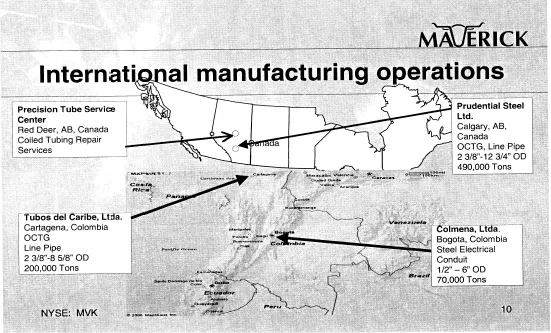
Precision Tube Service Center Red Deer, AB, Canada Coiled Tubing Repair Services Prudential Steel Ltd. Calgary, AB, Canada OCTG, Line Pipe 2 3/8"-12 3/4" OD 490,000 Tons Tubos del Caribe, Ltda. Cartagena, Colombia OCTG Line Pipe 2 3/8"-8 5/8" OD 200,000 Tons Colmena, Ltda. Bogota, Colombia Steel Ele
Slide 10: Operating units - Energy
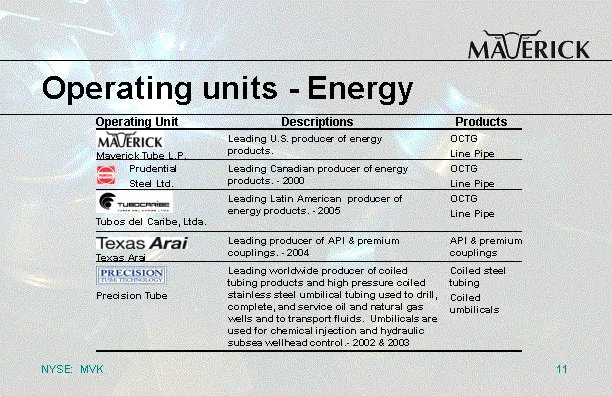
Operating units - Energy Coiled steel tubing Coiled umbilicals API & premium couplings OCTG Line Pipe OCTG Line Pipe OCTG Line Pipe Products Leading worldwide producer of coiled tubing products and high pressure coiled stainless steel umbilical tubing used to drill, complete, and service oil and nat
Slide 11: Maverick Tube L.P.
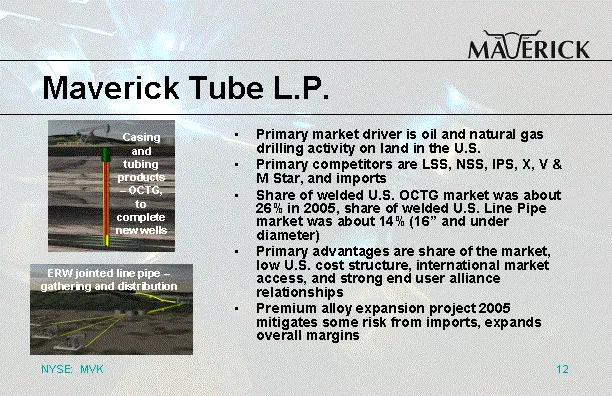
Maverick Tube L.P. Primary market driver is oil and natural gas drilling activity on land in the U.S. Primary competitors are LSS, NSS, IPS, X, V & M Star, and imports Share of welded U.S. OCTG market was about 26% in 2005, share of welded U.S. Line Pipe market was about 14% (16" and under diameter)
Slide 12: Prudential Steel, Ltd.
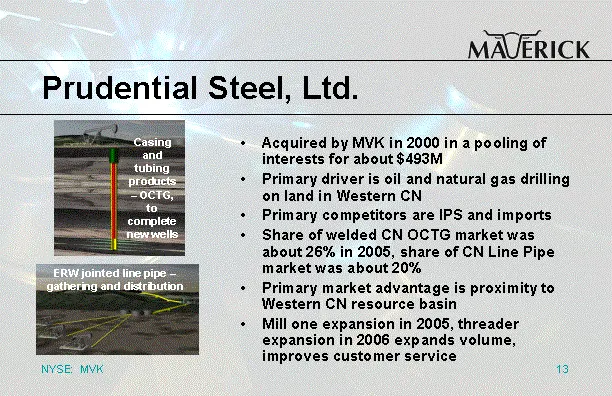
Prudential Steel, Ltd. Acquired by MVK in 2000 in a pooling of interests for about $493M Primary driver is oil and natural gas drilling on land in Western CN Primary competitors are IPS and imports Share of welded CN OCTG market was about 26% in 2005, share of CN Line Pipe market was about 20% Prima
Slide 13: Tubos del Caribe, Ltda.
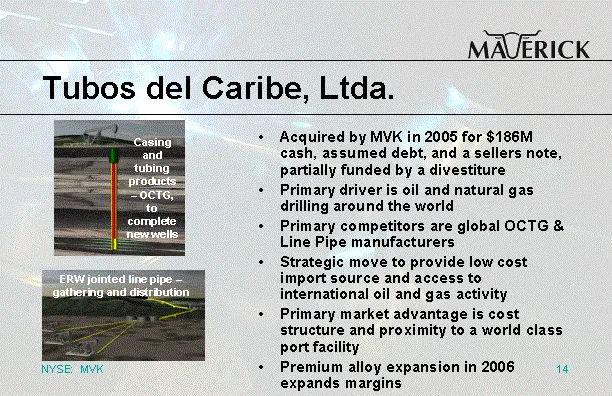
Tubos del Caribe, Ltda. Acquired by MVK in 2005 for $186M cash, assumed debt, and a sellers note, partially funded by a divestiture Primary driver is oil and natural gas drilling around the world Primary competitors are global OCTG & Line Pipe manufacturers Strategic move to provide low cost import
Slide 14: Texas Arai
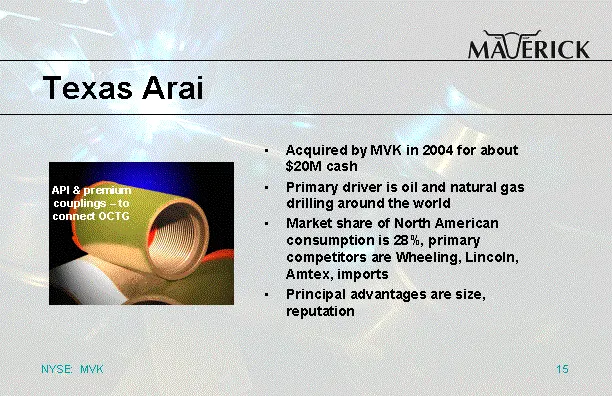
Texas Arai Acquired by MVK in 2004 for about $20M cash Primary driver is oil and natural gas drilling around the world Market share of North American consumption is 28%, primary competitors are Wheeling, Lincoln, Amtex, imports Principal advantages are size, reputation API & premium couplings - to c
Slide 15: Precision Tube Technology
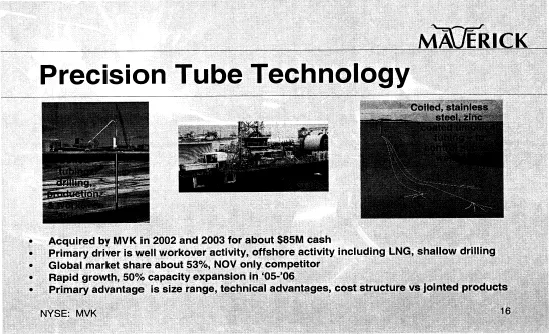
Precision Tube Technology Coiled tubing drilling, production, & workover strings Coiled line pipe - subsea applications Coiled, stainless steel, zinc coated umbilical tubing - to control subsea wellheads Acquired by MVK in 2002 and 2003 for about $85M cash Primary driver is well workover activity, o
Slide 16: Operating units - Electrical
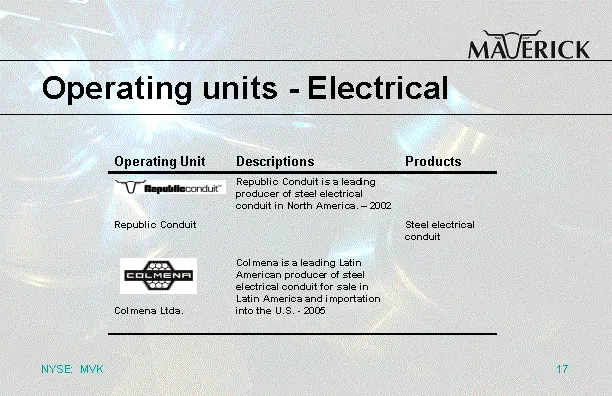
Operating units - Electrical Operating Unit Descriptions Products Republic Conduit Colmena Ltda. Republic Conduit is a leading producer of steel electrical conduit in North America. - 2002 Colmena is a leading Latin American producer of steel electrical conduit for sale in Latin America and importat
Slide 17: Republic and Colmena, Ltda.
Republic and Colmena, Ltda. Acquired by MVK in 2002 for $122M as part of the LTV Pipe Group acquisition for cash, and as part of the Tubo del Caribe, Ltda. acquisition in 2005 Primary driver is non-residential construction Market share is about 35%, two other significant U.S. competitors, Wheatland
Slide 18: Key competitive advantages - Energy
Key competitive advantages - Energy Demonstrated understanding and ability to respond quickly to the cyclical nature of the oil and gas service industry Steel buyer vs steel maker Broad size range, geographic reach and dominant market position Synergies amongst business units Raw mat'l sourcing Manu
Slide 19: Key competitive advantages - Electrical
Key competitive advantages - Electrical Dominant market position Both a domestic manufacturer and an importer Consolidating manufacturing operations into one, low cost facility Synergies amongst business units Stream of earnings and cash flow driven by general economic activity
Slide 20: Aggressive growth strategy
Organic Growth Enhance productivity, cost effectiveness and product technology Expand product lines Alloy OCTG (U.S. and Colombia) Coiled tubing Threading capacity increase in Canada Strategic Growth Expand geographic coverage of existing businesses Tubos del Caribe/Colmena Expand the Company's offe
Slide 21: Financial and Equity Information
Financial and Equity Information
Slide 22: Year to date overview
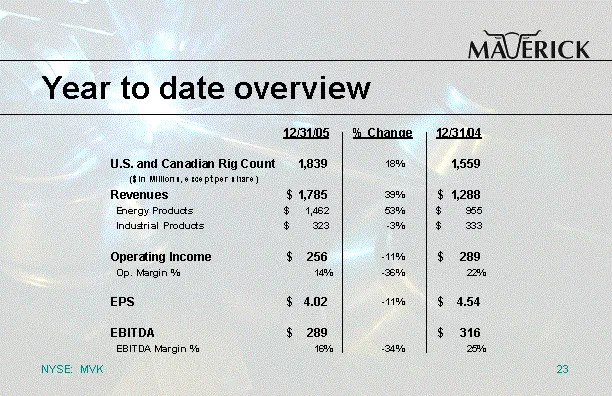
Year to date overview 3Q '04 % Inc. 3Q '03 North American Rig Count 20.4 27.4 90 20.4 West 30.6 38.6 34.6 31.6 North 45.9 46.9 45 43.9
Slide 23: Balance sheet summary
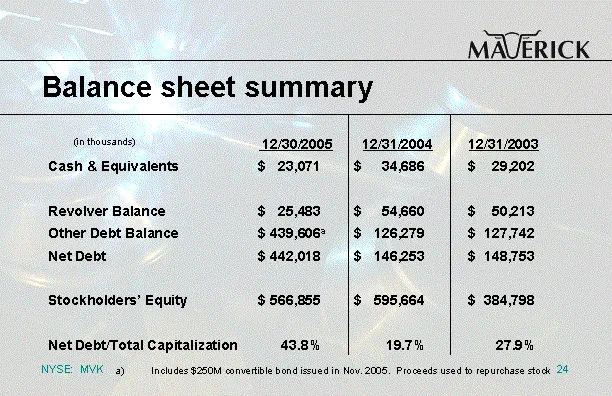
(in thousands) 12/30/2005 12/31/2004 12/31/2003 Cash & Equivalents $ 23,071 $ 34,686 $ 29,202 Revolver Balance $ 25,483 $ 54,660 $ 50,213 Other Debt Balance $ 439,606a $ 126,279 $ 127,742 Net Debt $ 442,018 $ 146,253 $ 148,753 Stockholders' Equity $ 566,855 $ 595,664 $ 384,798 Net Debt/Total Capital
Slide 24: Record historical growth
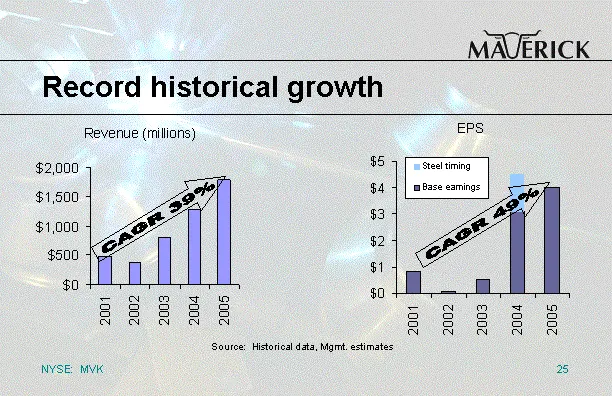
Record historical growth CAGR 39% Source: Historical data, Mgmt. estimates CAGR 49%
Slide 25: Earnings momentum
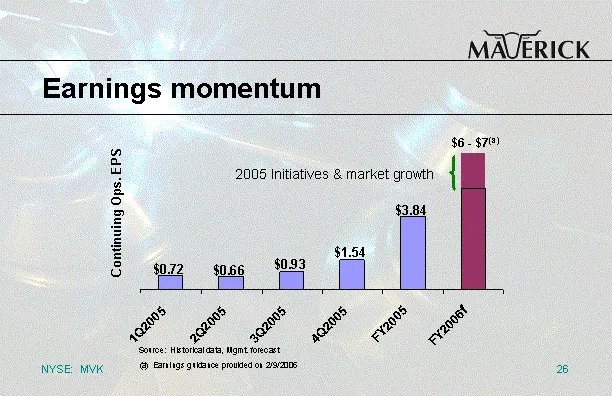
Earnings momentum 2005 Initiatives & market growth Source: Historical data, Mgmt. forecast (a) Earnings guidance provided on 2/9/2006 $6 - $7(a)
Slide 26: Earnings momentum highlights
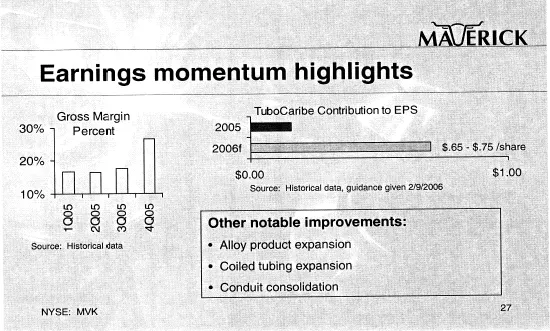
Earnings momentum highlights 1Q05 2Q05 3Q05 4Q05 Gross Margins 0.168 0.166 0.177 0.266 2006f 2005 TuboCaribe Contribution to Earnings 0.7 0.16 Source: Historical data Source: Historical data, guidance given 2/9/2006 $.65 - $.75 /share Other notable improvements: Alloy product expansion Coiled tubing
Slide 27: Strong cash flow
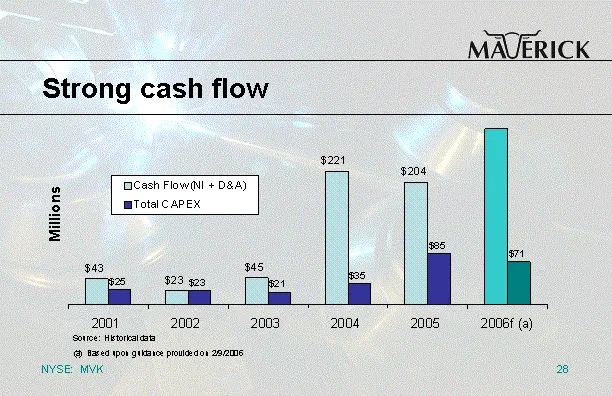
Strong cash flow 2001 2002 2003 2004 2005 2006f (a) Cash Flow (NI + D&A) 42.882 23.358 45.368 221.494 204 292 Total CAPEX 25 23 21 35 85 71 Source: Historical data (a) Based upon guidance provided on 2/9/2006
Slide 28: Raw material strategy
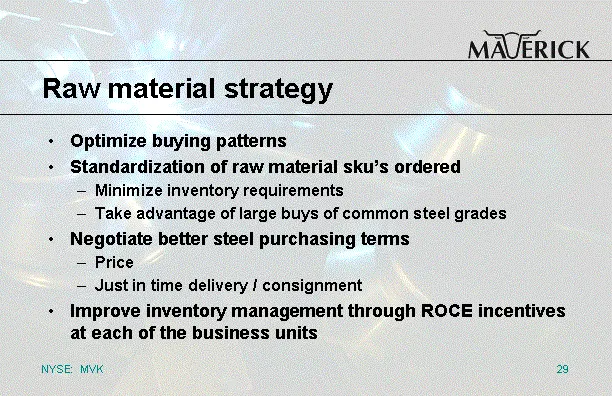
Raw material strategy Optimize buying patterns Standardization of raw material sku's ordered Minimize inventory requirements Take advantage of large buys of common steel grades Negotiate better steel purchasing terms Price Just in time delivery / consignment Improve inventory management through ROCE
Slide 29: Upgraded market profile
Upgraded market profile International access - more stable activity levels "Alliance" customer relationships Increased premium alloy capacity Increased coil tubing capacity Increased threading capacity in Canada Recent successful growth initiatives enhance product and business portfolio
Slide 30: Superior return on equity
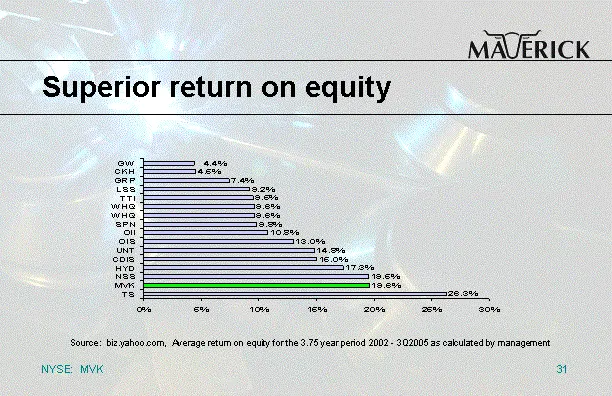
Source: biz.yahoo.com, Average return on equity for the 3.75 year period 2002 - 3Q2005 as calculated by management Superior return on equity
Slide 31: Investment highlights
Market leader in key segments of the oil service industry Track record of successfully executing growth initiatives Earnings momentum into '06 Expect substantial cash flow in 2006 2006 initiatives expected to improve margin and earnings for 2007 Focused on achieving superior return on equity Well-po
Slide 32: Maverick
MAVERICK MAVERICK
Source: SEC EDGAR · 8-K filed Mar 13, 2006
More decks from Maverick Tube Corp
 Investor Presentation (May 2006)28 slides · May 11, 2006
 Investor Presentation (November 2005)29 slides · Nov 16, 2005
 Investor Presentation (November 2005)29 slides · Nov 1, 2005
 Investor Presentation (October 2005)29 slides · Oct 26, 2005
 Investor Presentation (September 2005)28 slides · Sep 1, 2005
 Investor Presentation (May 2005)35 slides · May 31, 2005