Air Transport Services Group Inc
Air Transport Services — Stephens Fall Investment Conference 2014
15 slides from Air Transport Services's conference presentation, Nov 12, 2014
Slide 1: The Global Leader in Midsize Wide-body Freighter Solutions
0 Air Transport Services Group, Inc. The Global Leader in Developing, Deploying and Supporting Midsize Wide-body Freighter Solutions for Expedited Air Networks Stephens Fall Investment Conference New York City November 12, 2014 Joe Hete President & Chief Executive Officer Quint Turner Chief Financia
Slide 2: Safe Harbor Statement
1 Except for historical information contained herein, the matters discussed in this presentation contain forward- looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual results to differ mater
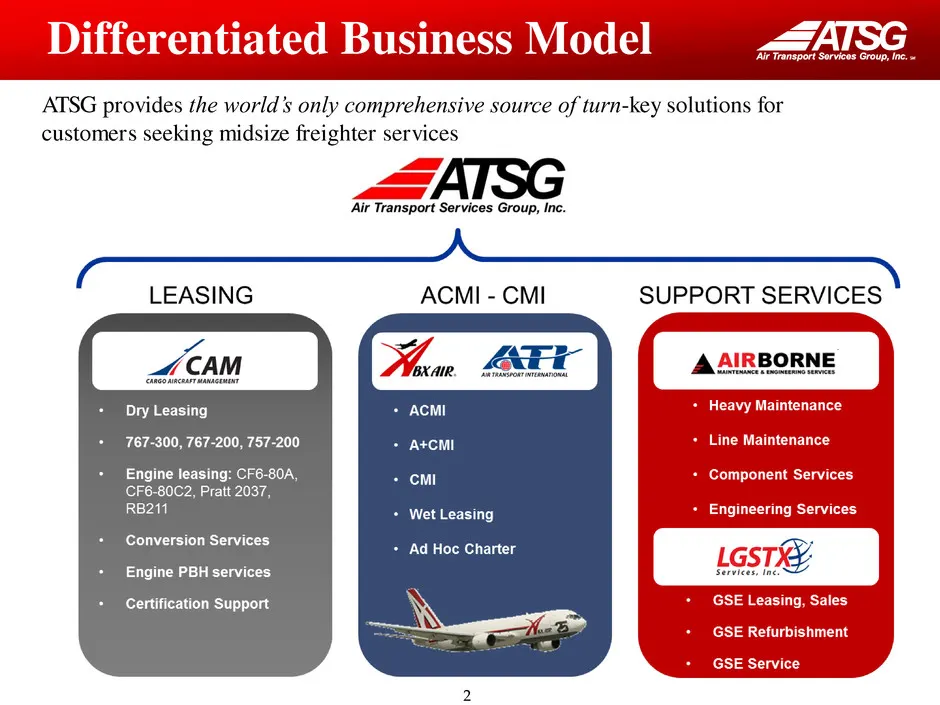
Slide 3: Differentiated Business Model
2 Differentiated Business Model ATSG provides the world’s only comprehensive source of turn-key solutions for customers seeking midsize freighter services
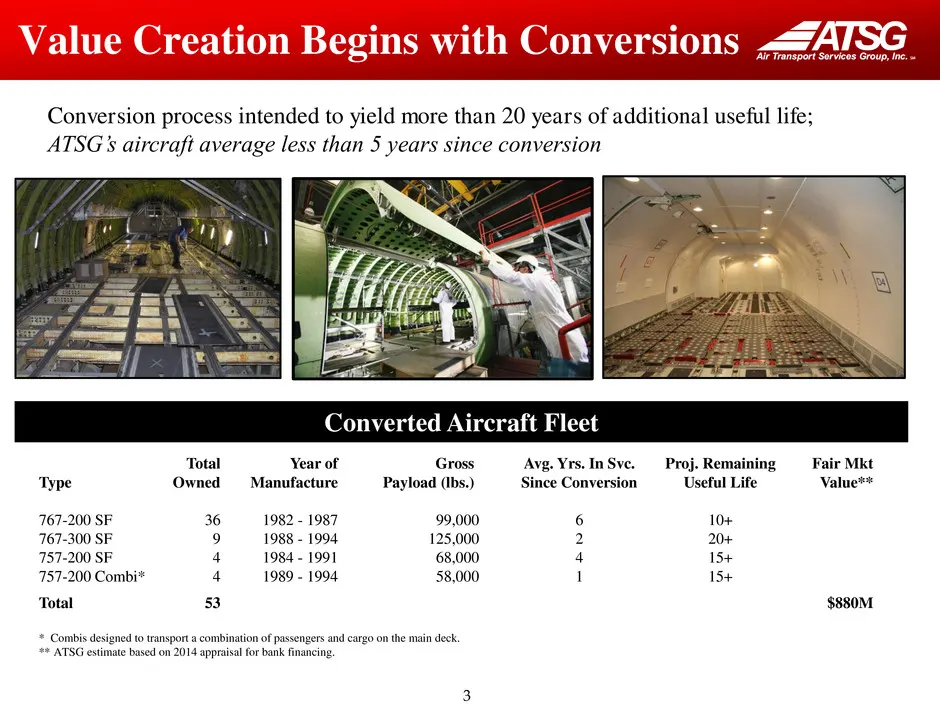
Slide 4: Value Creation Begins with Conversions
3 Value Creation Begins with Conversions Converted Aircraft Fleet Total Year of Gross Avg. Yrs. In Svc. Proj. Remaining Fair Mkt Type Owned Manufacture Payload (lbs.) Since Conversion Useful Life Value** 767-200 SF 36 1982 - 1987 99,000 6 10+ 767-300 SF 9 1988 - 1994 125,000 2 20+ 757-200 SF 4 1984
Slide 5: Improved Market Dynamics
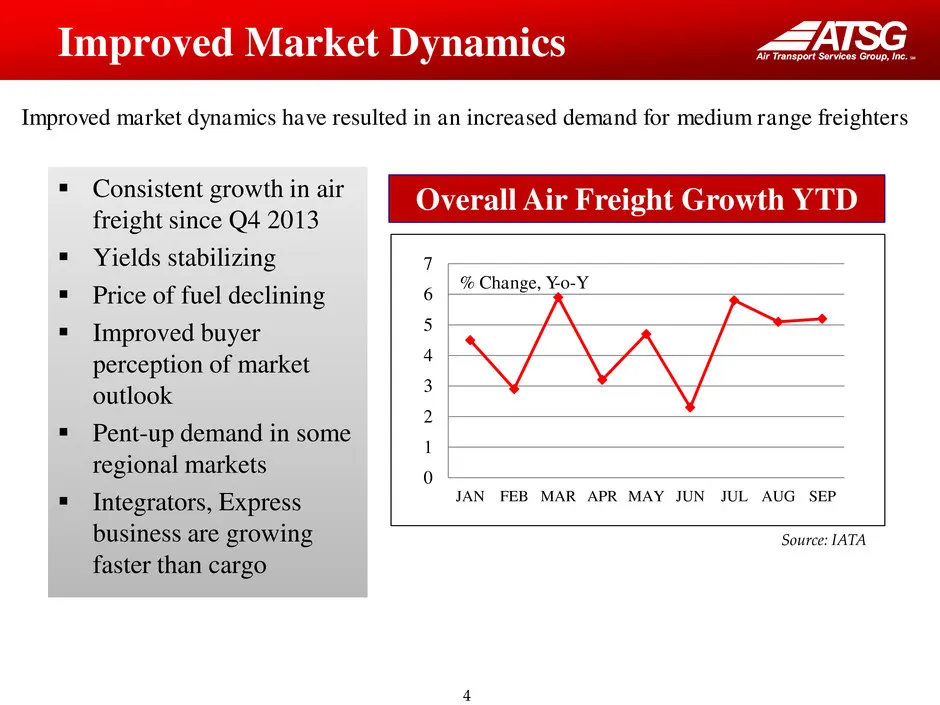
4 Improved Market Dynamics Consistent growth in air freight since Q4 2013 Yields stabilizing Price of fuel declining Improved buyer perception of market outlook Pent-up demand in some regional markets Integrators, Express business are growing faster than cargo Source: IATA Overall Air Fr
Slide 6: Unrivaled Leader in Medium Wide-body
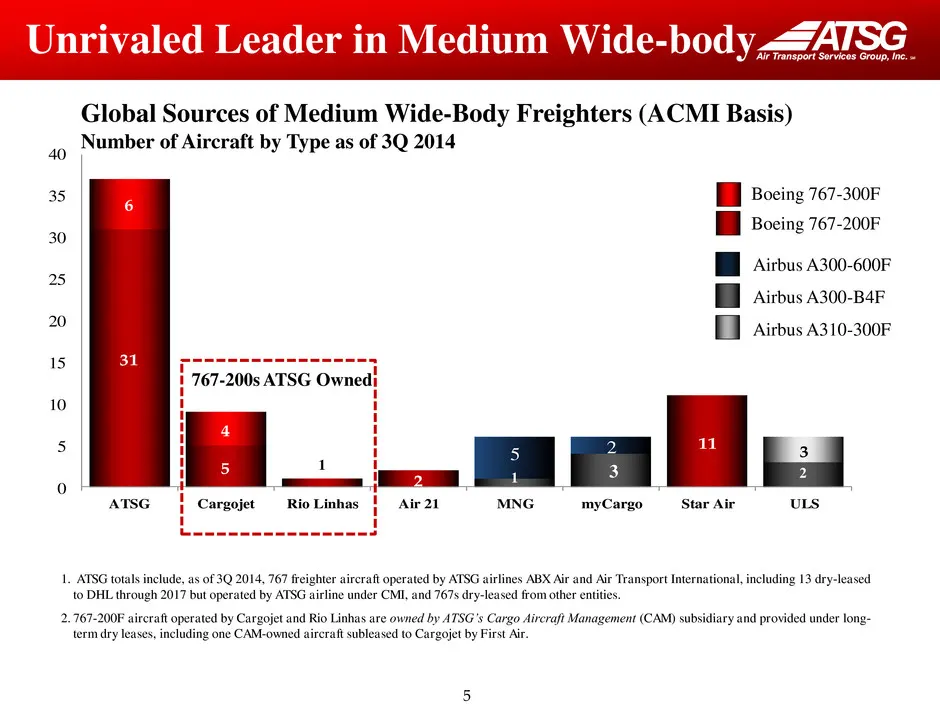
5 31 5 2 11 6 4 5 2 3 0 5 10 15 20 25 30 35 40 ATSG Cargojet Rio Linhas Air 21 MNG myCargo Star Air ULS 1. ATSG totals include, as of 3Q 2014, 767 freighter aircraft operated by ATSG airlines ABX Air and Air Transport International, including 13 dry-leased to DHL through 2017 but operated by ATSG ai
Slide 7: New Leases with Longtime Customers
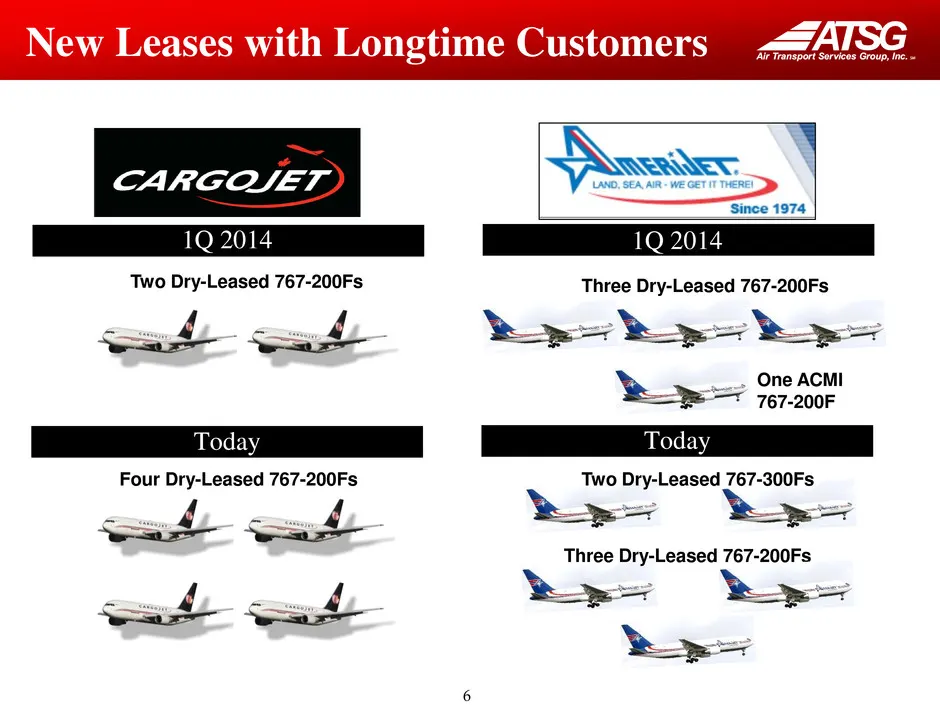
6 New Leases with Longtime Customers 1Q 2014 Today One ACMI 767-200F Three Dry-Leased 767-200Fs Two Dry-Leased 767-300Fs 1Q 2014 Today Two Dry-Leased 767-200Fs Three Dry-Leased 767-200Fs Four Dry-Leased 767-200Fs
Slide 8: Proposed 4-Year DHL Extension
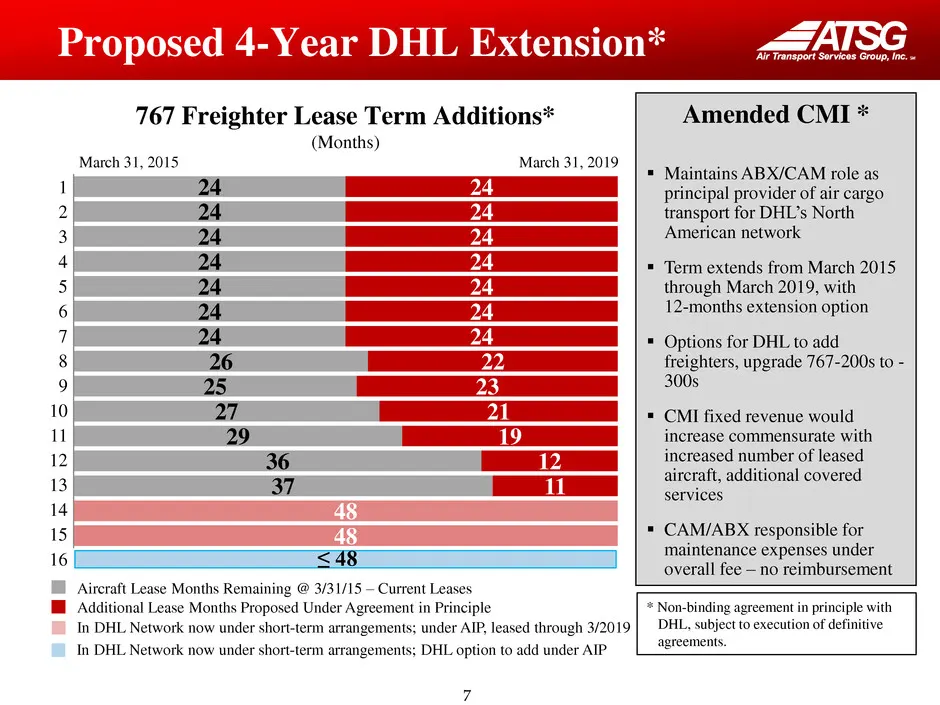
7 37 36 29 27 25 26 24 24 24 24 24 24 24 48 48 11 12 19 21 23 22 24 24 24 24 24 24 24 Proposed 4-Year DHL Extension* 767 Freighter Lease Term Additions* (Months) March 31, 2015 March 31, 2019 In DHL Network now under short-term arrangements; under AIP, leased through 3/2019 ≤ 48 Amended CMI * Main
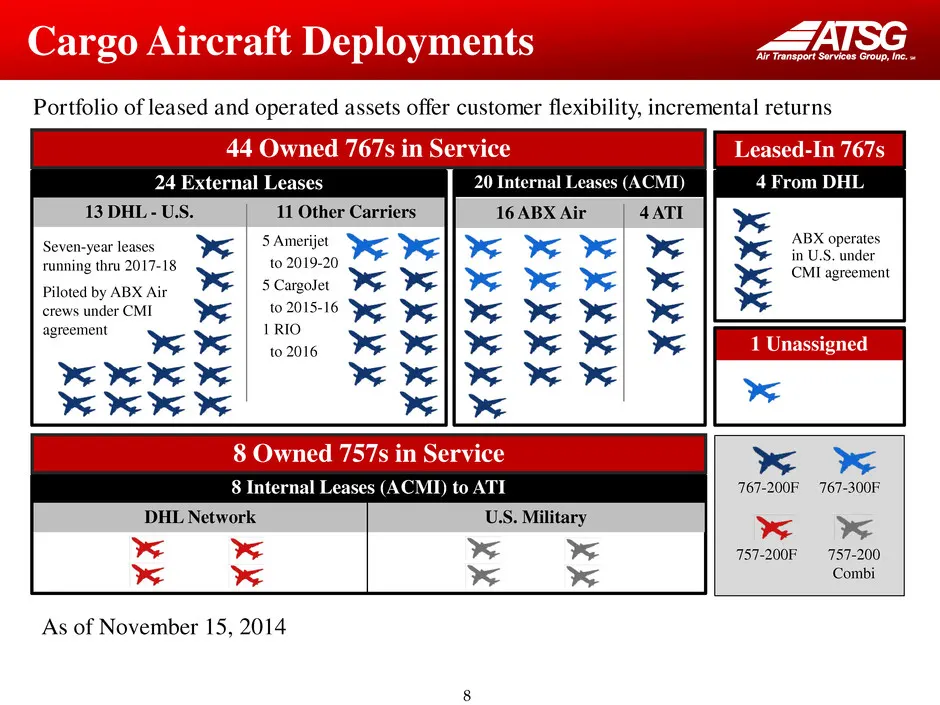
Slide 9: Cargo Aircraft Deployments
8 Cargo Aircraft Deployments 24 External Leases 20 Internal Leases (ACMI) 13 DHL - U.S. 4 ATI 16 ABX Air 11 Other Carriers ABX operates in U.S. under CMI agreement 767-200F 767-300F Leased-In 767s 1 Unassigned Seven-year leases running thru 2017-18 Piloted by ABX Air crews under CMI agreement 44 Own
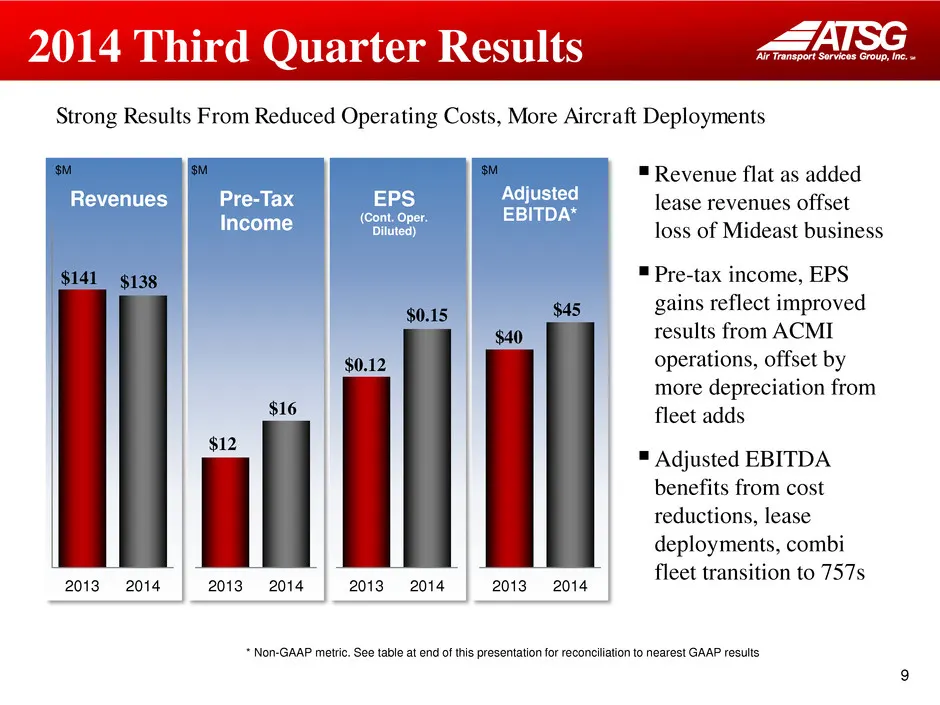
Slide 10: 2014 Third Quarter Results
9 2014 Third Quarter Results Revenue flat as added lease revenues offset loss of Mideast business Pre-tax income, EPS gains reflect improved results from ACMI operations, offset by more depreciation from fleet adds Adjusted EBITDA benefits from cost reductions, lease deployments, combi fleet tr
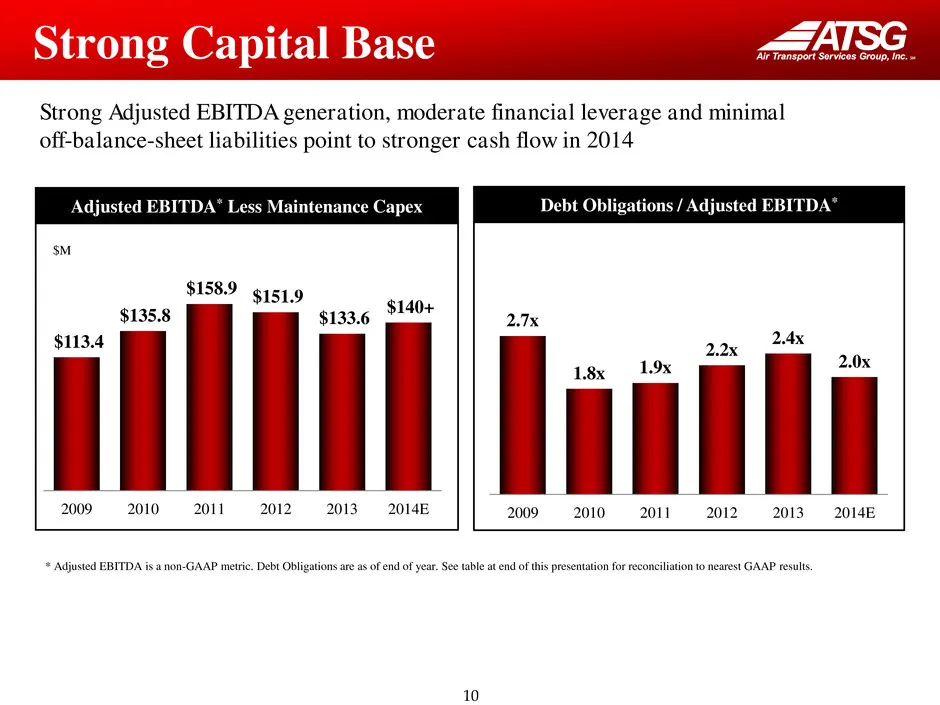
Slide 11: Strong Capital Base
10 $113.4 $135.8 $158.9 $151.9 $133.6 $140+ 2009 2010 2011 2012 2013 2014E 2.7x 1.8x 1.9x 2.2x 2.4x 2.0x 2009 2010 2011 2012 2013 2014E Strong Capital Base Strong Adjusted EBITDA generation, moderate financial leverage and minimal off-balance-sheet liabilities point to stronger cash flow in 2014 Deb
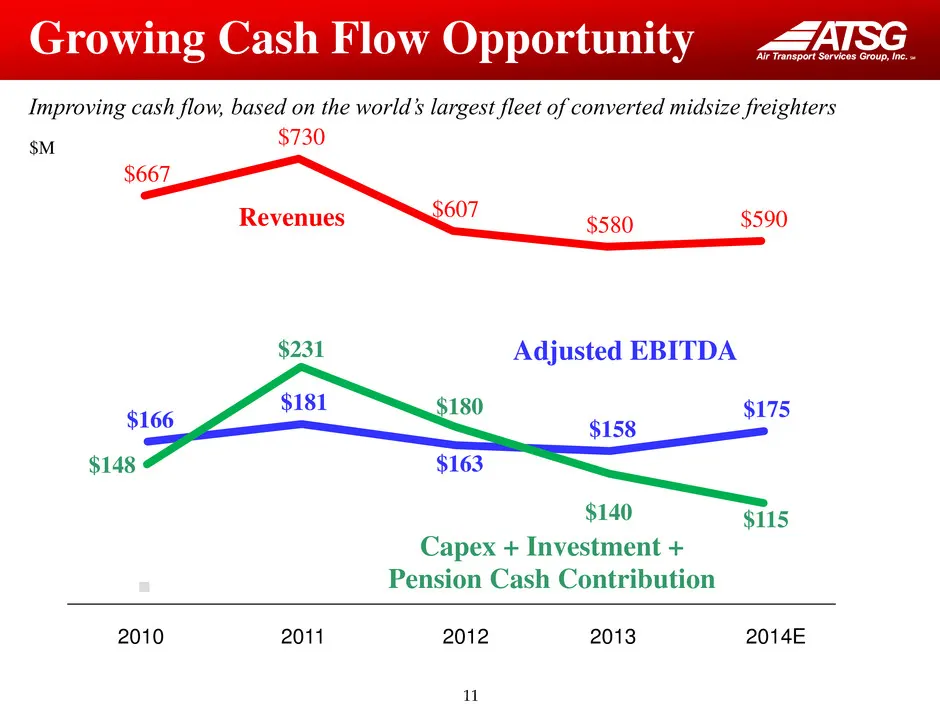
Slide 12: Growing Cash Flow Opportunity
11 $166 $181 $163 $158 $175 Adjusted EBITDA $148 $231 $180 $140 $115 Capex + Investment + Pension Cash Contribution $667 $730 $607 $580 $590 Improving cash flow, based on the world’s largest fleet of converted midsize freighters $M Revenues Growing Cash Flow Opportunity 2010 2011 2012 2013 2014E
Slide 13: Highlights and Outlook
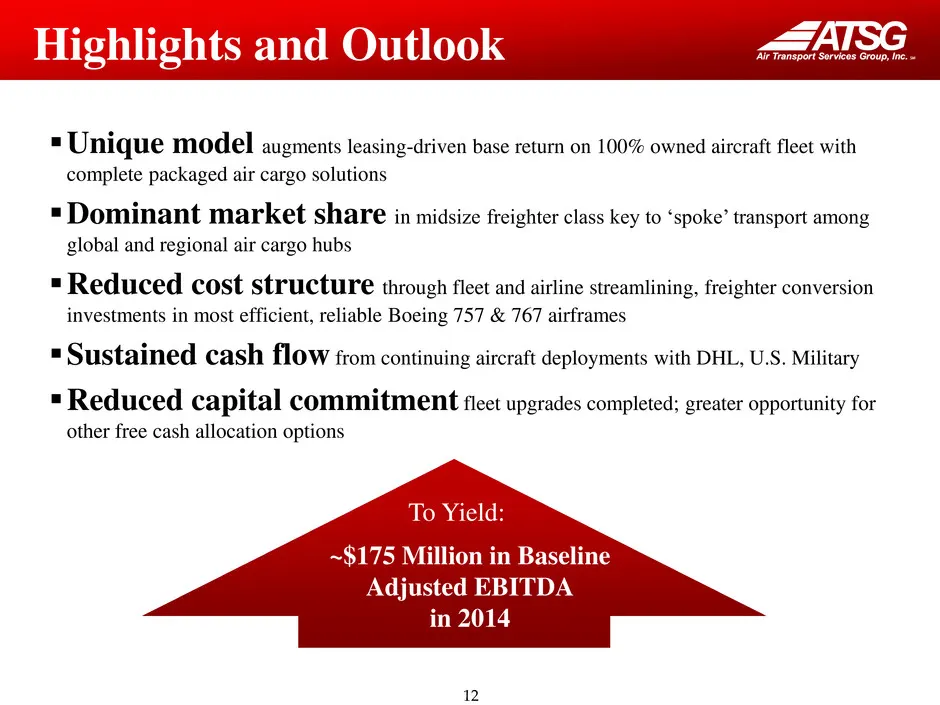
12 Highlights and Outlook Unique model augments leasing-driven base return on 100% owned aircraft fleet with complete packaged air cargo solutions Dominant market share in midsize freighter class key to ‘spoke’ transport among global and regional air cargo hubs Reduced cost structure through flee
Slide 14: Expanding Free Cash Flow Creates Options
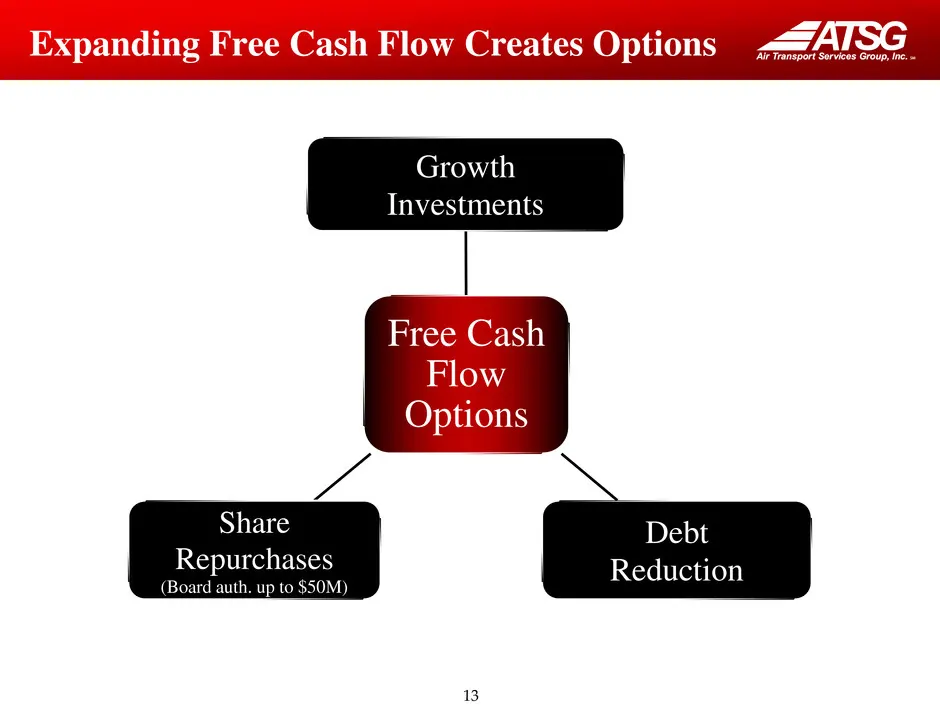
13 Expanding Free Cash Flow Creates Options Free Cash Flow Options Growth Investments Debt Reduction Share Repurchases (Board auth. up to $50M)
Slide 15: Non-GAAP Reconciliation Statement
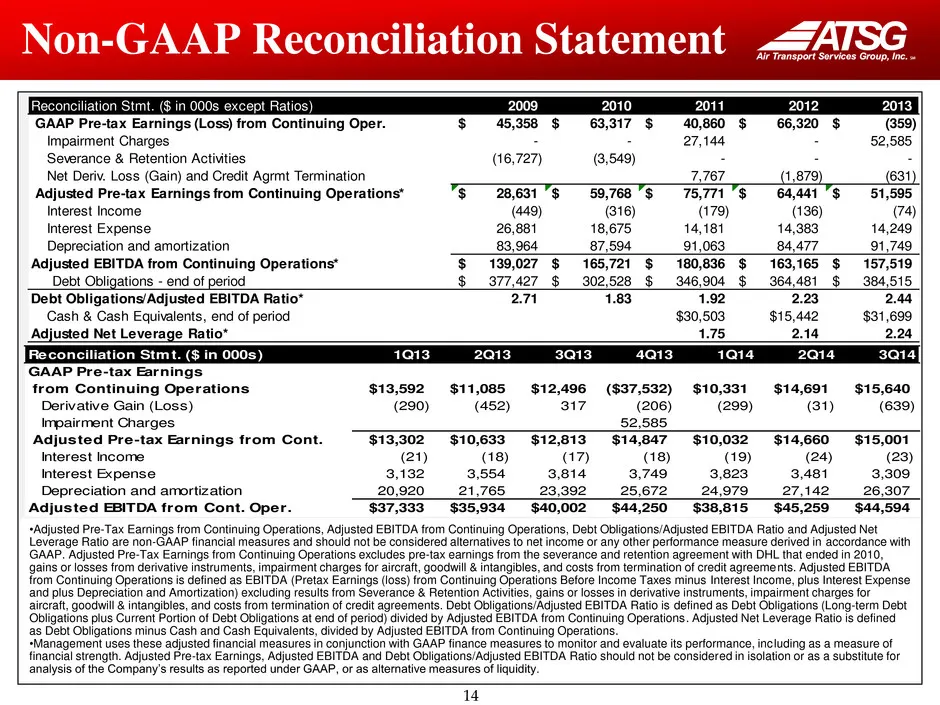
14 Non-GAAP Reconciliation Statement •Adjusted Pre-Tax Earnings from Continuing Operations, Adjusted EBITDA from Continuing Operations, Debt Obligations/Adjusted EBITDA Ratio and Adjusted Net Leverage Ratio are non-GAAP financial measures and should not be considered alternatives to net income or an
Source: SEC EDGAR · 8-K filed Nov 12, 2014
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020