AMAG Pharmaceuticals — JP Morgan Healthcare Conference 2014
25 slides from AMAG Pharmaceuticals's conference presentation, Jan 13, 2014
Slide 1: AMAG Pharmaceuticals JP Morgan Healthcare Conference January 2014
AMAG Pharmaceuticals JP Morgan Healthcare Conference January 2014
Slide 2: Forward Looking Statements
Forward Looking Statements 1 This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other federal securities laws. Any statements contained herein which do not describe historical facts, including but not limited to: state
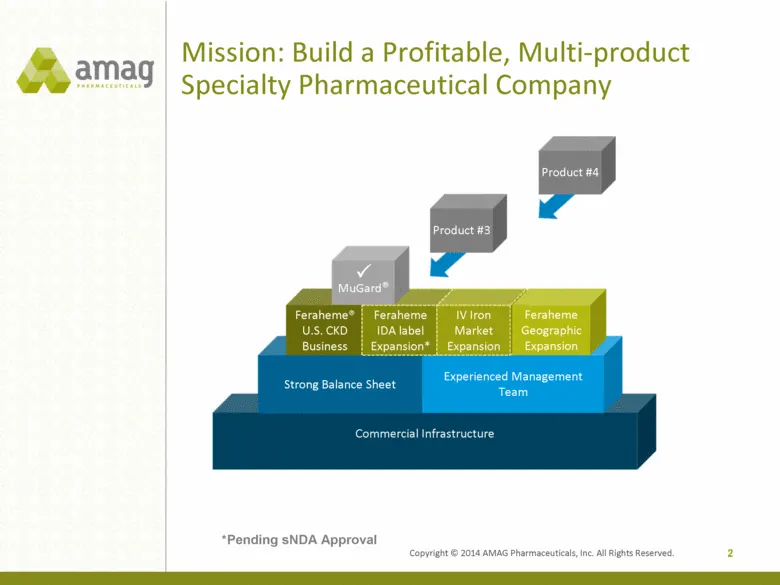
Slide 3: Mission: Build a Profitable, Multi-product Specialty Pharmaceutical Company
Mission: Build a Profitable, Multi-product Specialty Pharmaceutical Company Commercial Infrastructure Focus on Hematology/Oncology, Hospital and Nephrology Strong Balance Sheet Experienced Management Team Feraheme® U.S. CKD Business Feraheme IDA label Expansion* IV Iron Market Expansion Feraheme Geo
Slide 4: 2013 In Review
2013 IN REVIEW
Slide 5: 2013 Performance
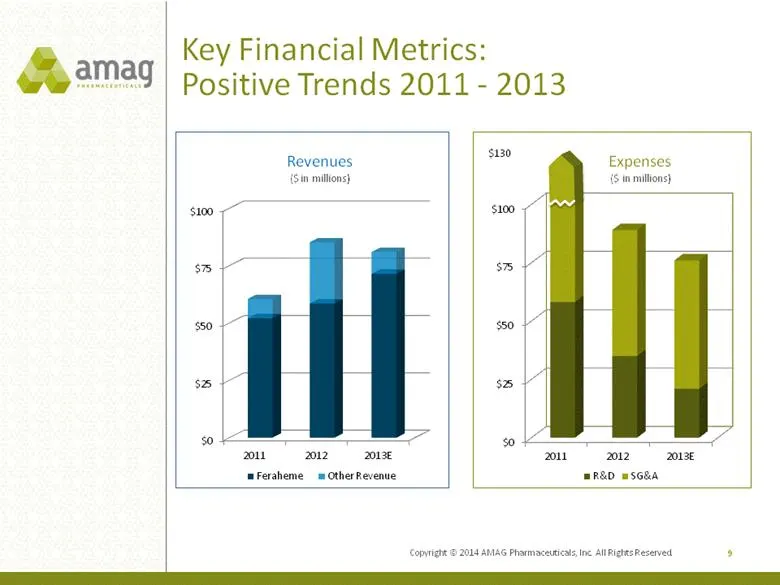
2013 Performance Outstanding 2013 financial performance Feraheme revenue +28% vs. 2012 Operating expenses -7% vs. 2012 First positive cash flow in company history in second half (3Q & 4Q) of 2013 Record-breaking Feraheme performance In-market physician demand +20% vs. 2012 Evolution index of 113, ga
Slide 6: Feraheme Demand Growth by Segment
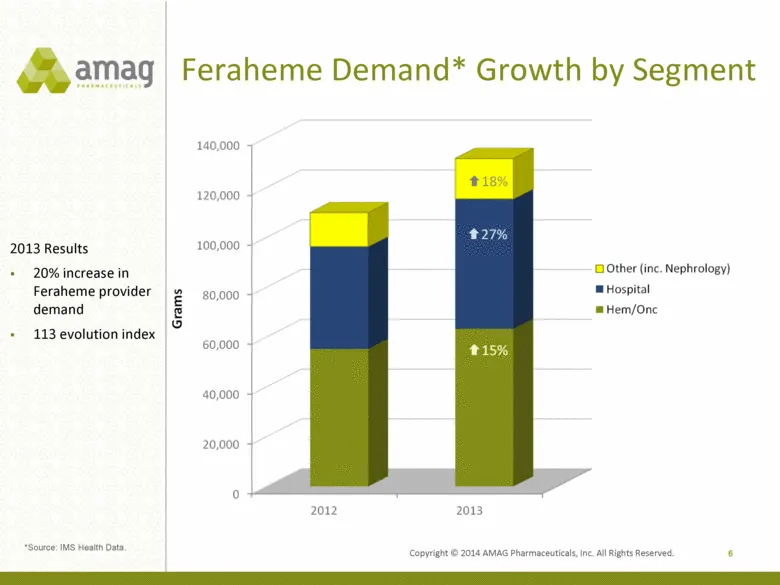
Feraheme Demand* Growth by Segment 6 2013 Results 20% increase in Feraheme provider demand 113 evolution index *Source: IMS Health Data.
Slide 7: Outstanding Preliminary 2013 Results
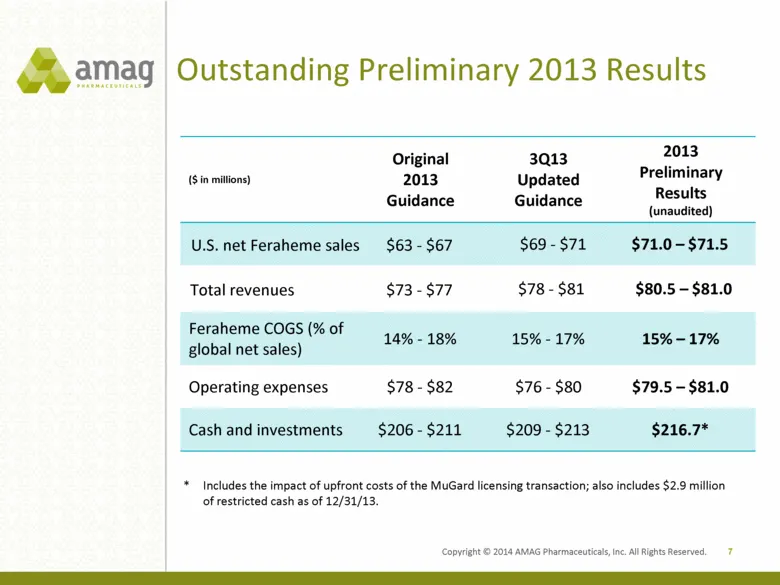
Outstanding Preliminary 2013 Results 7 * Includes the impact of upfront costs of the MuGard licensing transaction; also includes $2.9 million of restricted cash as of 12/31/13. ($ in millions) Original 2013 Guidance 3Q13 Updated Guidance 2013 Preliminary Results (unaudited) U.S. net Feraheme sales $
Slide 8: Recent Improvement in Net Revenue per Gram of Feraheme
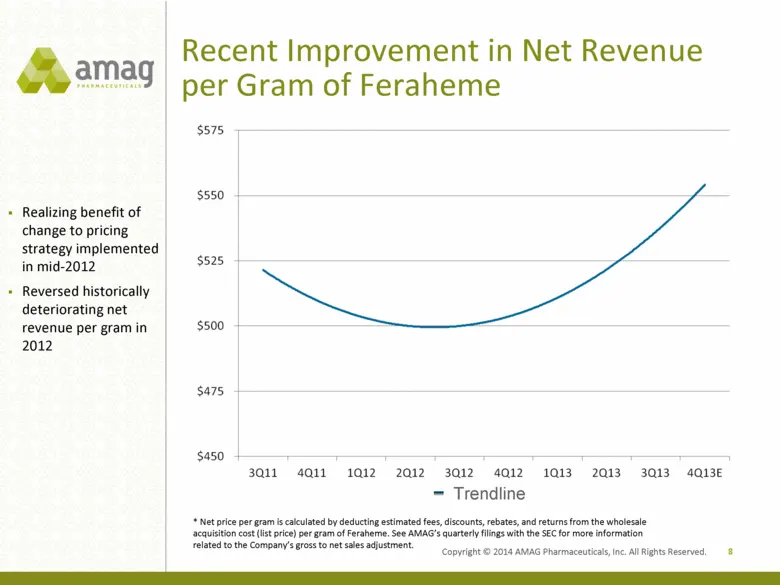
Recent Improvement in Net Revenue per Gram of Feraheme 8 Realizing benefit of change to pricing strategy implemented in mid-2012 Reversed historically deteriorating net revenue per gram in 2012 * Net price per gram is calculated by deducting estimated fees, discounts, rebates, and returns from the w
Slide 9: Key Financial Metrics: Positive Trends 2011 - 2013
Key Financial Metrics: Positive Trends 2011 - 2013 9 Revenues ($ in millions) Expenses ($ in millions) $130
Slide 10: New Strategic Plan
10 New Strategic Plan GROWING Drive revenue growth by optimizing the performance of Feraheme in CKD Enhance label and expand into new markets
Slide 11: Feraheme: 1–2–3
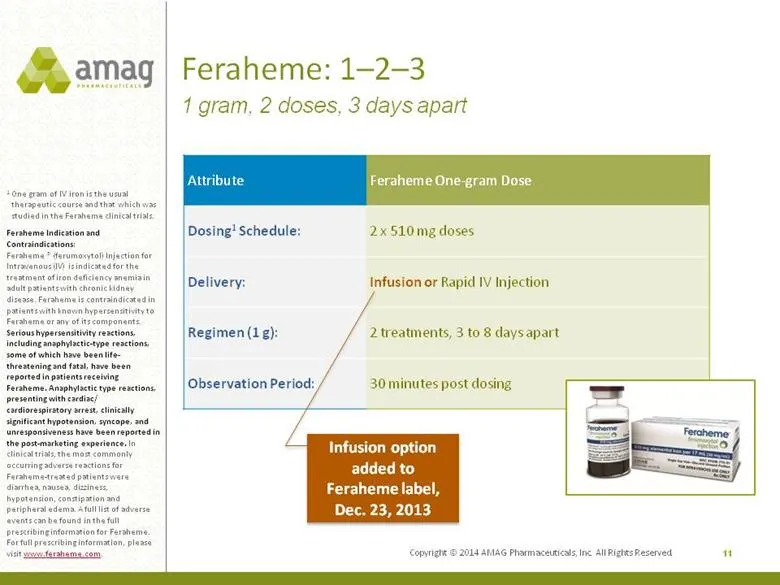
Feraheme: 1–2–3 11 1 One gram of IV iron is the usual therapeutic course and that which was studied in the Feraheme clinical trials. Feraheme Indication and Contraindications: Feraheme ® (ferumoxytol) Injection for Intravenous (IV) is indicated for the treatment of iron deficiency anemia in adult pa
Slide 12: U.S. IV Iron Market: Competitive Landscape
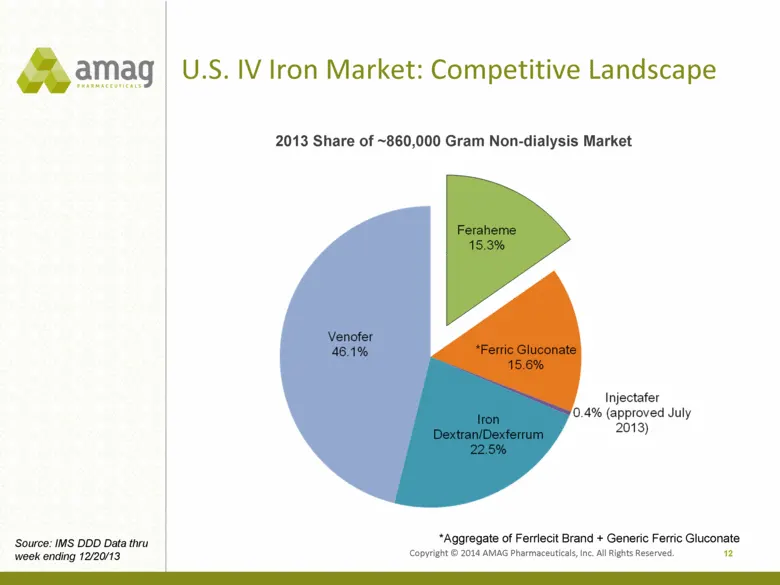
U.S. IV Iron Market: Competitive Landscape 12 *Aggregate of Ferrlecit Brand + Generic Ferric Gluconate Source: IMS DDD Data thru week ending 12/20/13 2013 Share of ~860,000 Gram Non-dialysis Market
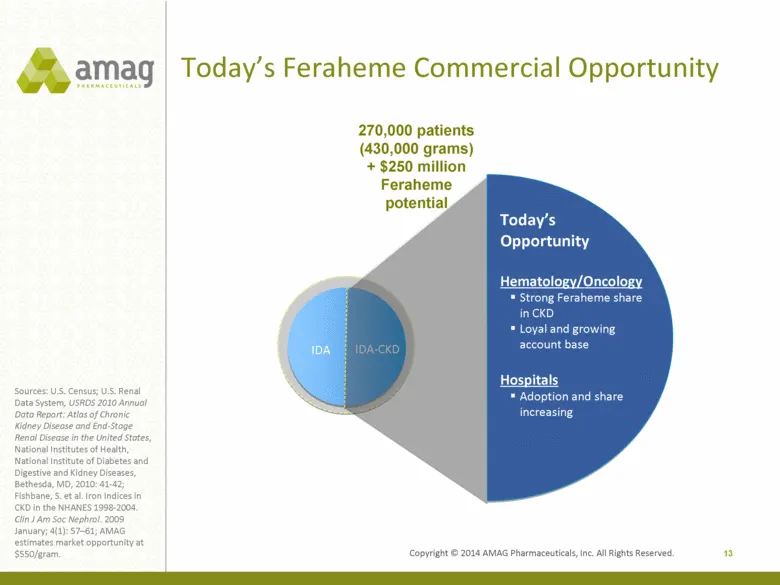
Slide 13: Today's Feraheme Commercial Opportunity
Today’s Feraheme Commercial Opportunity 13 Sources: U.S. Census; U.S. Renal Data System, USRDS 2010 Annual Data Report: Atlas of Chronic Kidney Disease and End-Stage Renal Disease in the United States, National Institutes of Health, National Institute of Diabetes and Digestive and Kidney Diseases, B
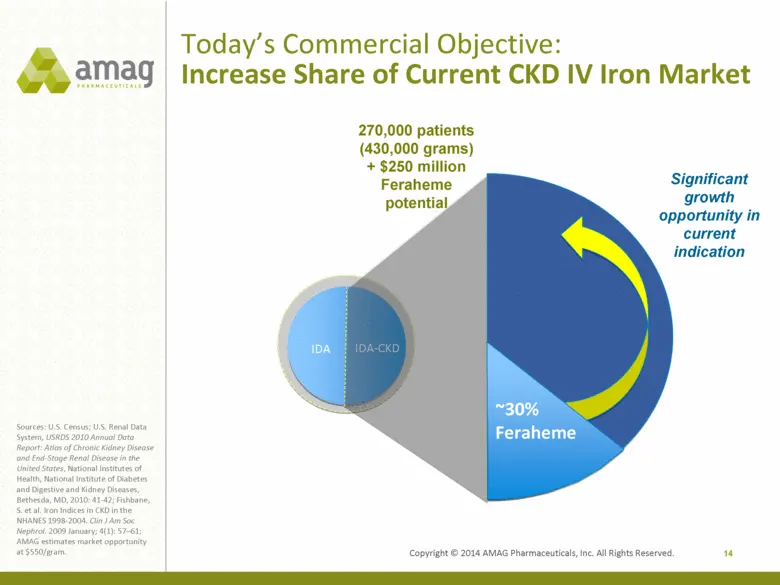
Slide 14: Today's Commercial Objective: Increase Share of Current CKD IV Iron Market
Today’s Commercial Objective: Increase Share of Current CKD IV Iron Market 14 Sources: U.S. Census; U.S. Renal Data System, USRDS 2010 Annual Data Report: Atlas of Chronic Kidney Disease and End-Stage Renal Disease in the United States, National Institutes of Health, National Institute of Diabetes a
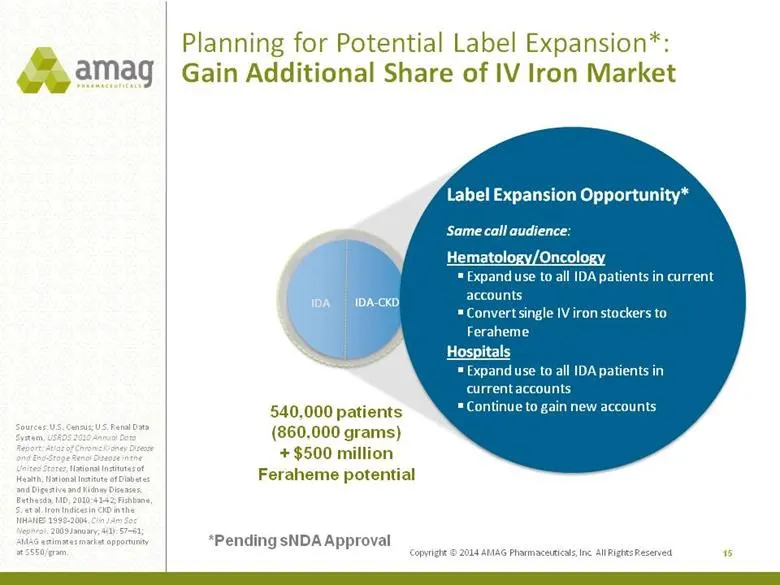
Slide 15: Planning for Potential Label Expansion: Gain Additional Share of IV Iron Market
15 Sources: U.S. Census; U.S. Renal Data System, USRDS 2010 Annual Data Report: Atlas of Chronic Kidney Disease and End-Stage Renal Disease in the United States, National Institutes of Health, National Institute of Diabetes and Digestive and Kidney Diseases, Bethesda, MD, 2010: 41-42; Fishbane, S. e
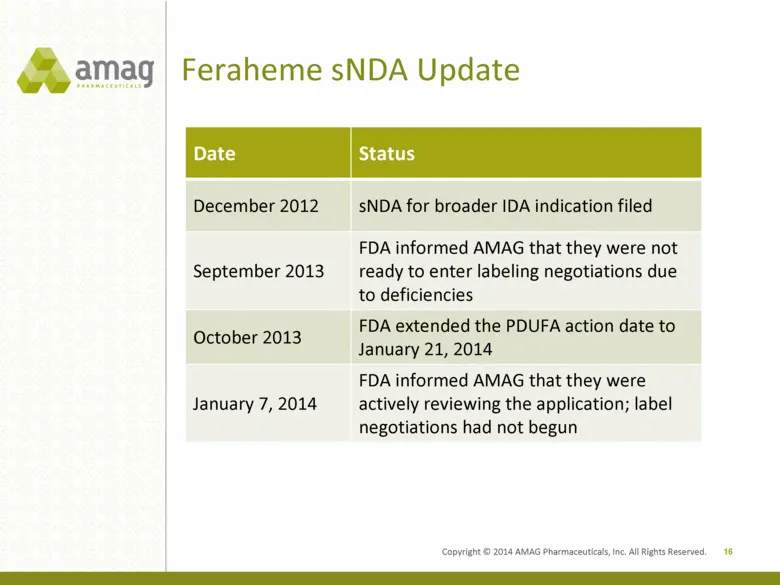
Slide 16: Feraheme sNDA Update
Date Status December 2012 sNDA for broader IDA indication filed September 2013 FDA informed AMAG that they were not ready to enter labeling negotiations due to deficiencies October 2013 FDA extended the PDUFA action date to January 21, 2014 January 7, 2014 FDA informed AMAG that they were actively r
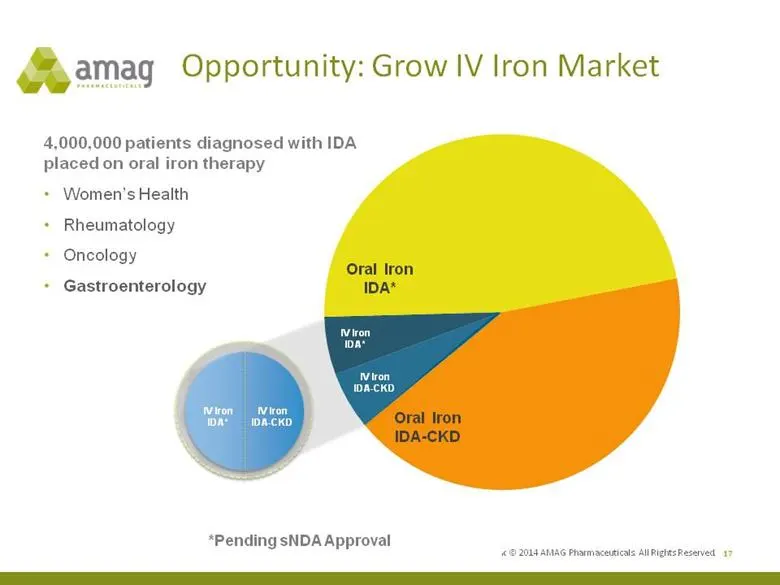
Slide 17: Opportunity: Grow IV Iron Market
Opportunity: Grow IV Iron Market 17 IV Iron IDA* IV Iron IDA-CKD 4,000,000 patients diagnosed with IDA placed on oral iron therapy IV Iron IDA-CKD IV Iron IDA* *Pending sNDA Approval Oral Iron IDA* Oral Iron IDA-CKD 4,000,000 patients diagnosed with IDA placed on oral iron therapy Women’s Health Rhe
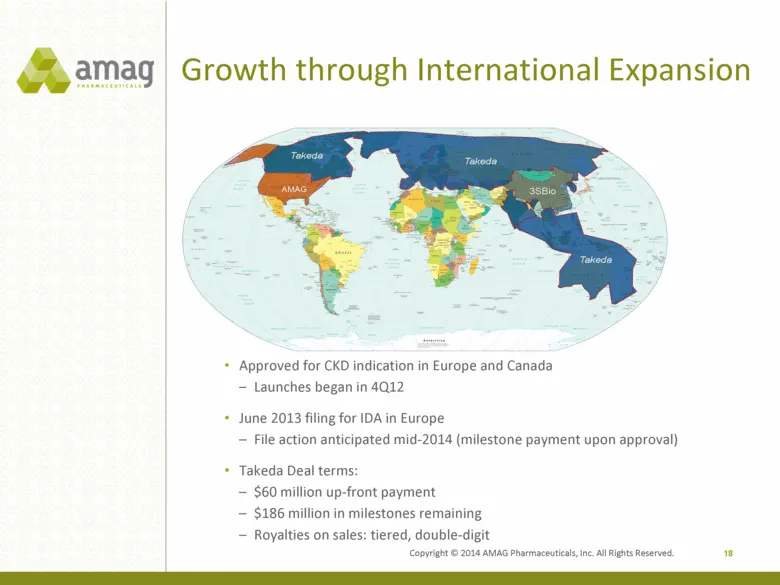
Slide 18: Growth through International Expansion
Growth through International Expansion 18 Approved for CKD indication in Europe and Canada Launches began in 4Q12 June 2013 filing for IDA in Europe File action anticipated mid-2014 (milestone payment upon approval) Takeda Deal terms: $60 million up-front payment $186 million in milestones remaining
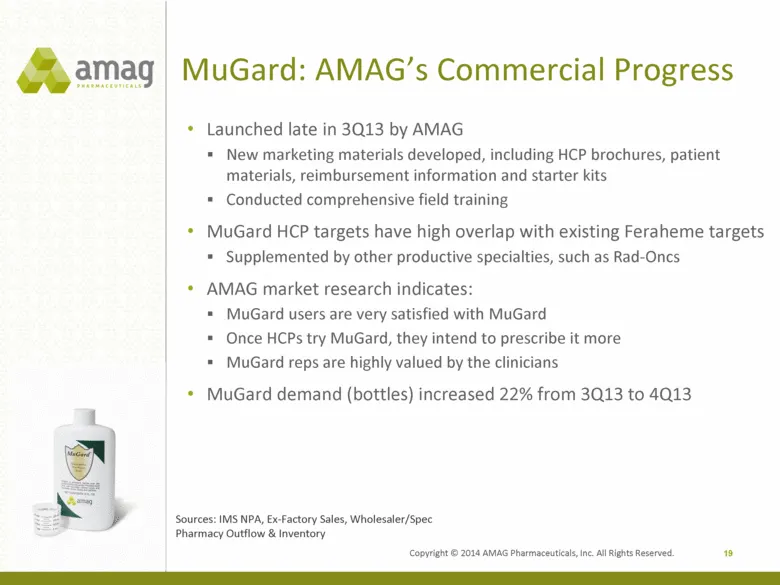
Slide 19: MuGard: AMAG's Commercial Progress
MuGard: AMAG’s Commercial Progress 19 Launched late in 3Q13 by AMAG New marketing materials developed, including HCP brochures, patient materials, reimbursement information and starter kits Conducted comprehensive field training MuGard HCP targets have high overlap with existing Feraheme targets Sup
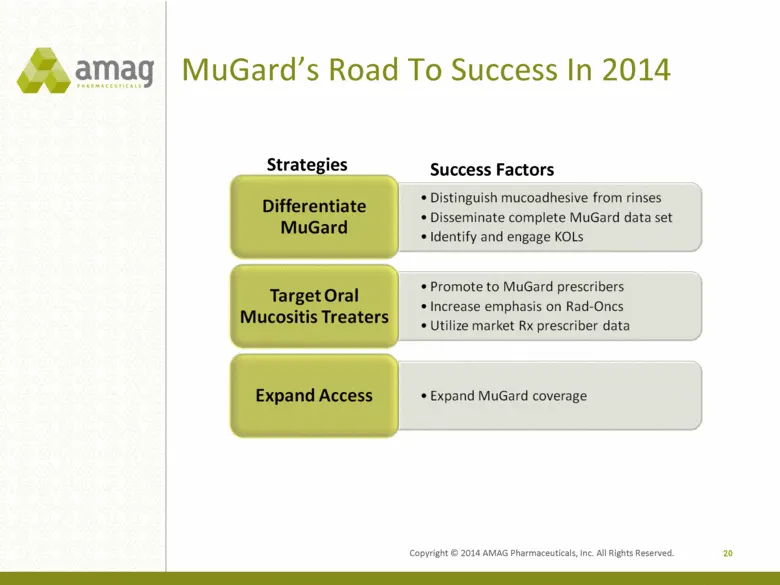
Slide 20: MuGard's Road To Success In 2014
MuGard’s Road To Success In 2014 20 Strategies Success Factors
Slide 21: New Strategic Plan
21 New Strategic Plan GROWING Drive revenue growth by optimizing the performance of Feraheme in CKD Enhance label and expand into new markets BUILDING
Slide 22: Targeted Business Development
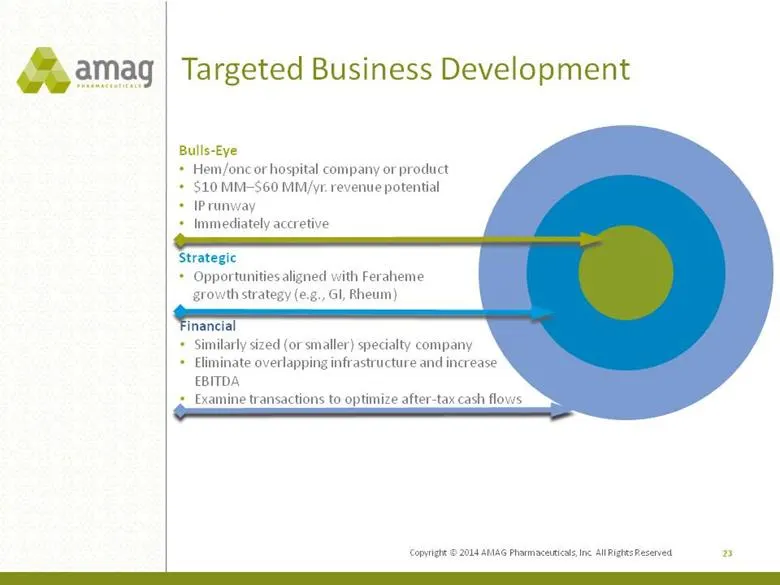
Targeted Business Development 23 Financial Similarly sized (or smaller) specialty company Eliminate overlapping infrastructure and increase EBITDA Examine transactions to optimize after-tax cash flows Bulls-Eye Hem/onc or hospital company or product $10 MM–$60 MM/yr. revenue potential IP runway Imme
Slide 23: New Strategic Plan
24 New Strategic Plan AMAG is a rapidly growing, specialty pharmaceutical company, supported by a talented and passionate workforce. Our primary goal is to bring to market therapies that provide clear benefits and improve patients’ lives. GROWING Drive revenue growth by optimizing the performance of
Slide 24: 2014 Goals
2014 Goals Maximize Feraheme opportunities Drive market share and market growth within current U.S. IDA-CKD indication Optimize net revenue per gram Potential label expansion: IDA (non-CKD) oral iron failures Expected FDA action – January 21, 2014 Expected EU action – mid-2014 Pursue IV iron market
Slide 25: Well positioned for success in 2014... and beyond.
Well positioned for success in 2014. . . and beyond.
Source: SEC EDGAR · 8-K filed Jan 13, 2014
More decks from AMAG Pharmaceuticals Inc
 Q2 2020 Earnings Presentation16 slides · Aug 6, 2020
 Q1 2020 Earnings Presentation14 slides · May 11, 2020
 JP Morgan 38th Healthcare Conference 202033 slides · Jan 9, 2020
 Q3 2019 Earnings Presentation24 slides · Nov 1, 2019
 Proxy Contest (September 2019)48 slides · Sep 4, 2019
 Q2 2019 Earnings Presentation26 slides · Aug 7, 2019