EMCORE — 10th Annual Needham Growth Stock Conference (January 2008)
24 slides from EMCORE's conference presentation, Jan 11, 2008
Slide 1: EMCORE Corporation
January 10 2008 EMCORE Corporation 10th Annual Needham Growth Stock Conf January 11, 2007 New York City Reuben F. Richards, Jr. Chief Executive Officer Chris Larocca, VP and GM, EMCORE Broadband 1 Fiber Optics Division
Slide 2: “Safe Harbor” Statement
“Safe Harbor” Statement The information provided herein may include forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. Such forward-looking statements include, but are not limited to, (a) the Company’s un
Slide 3: EMCORE’s New Business Scope
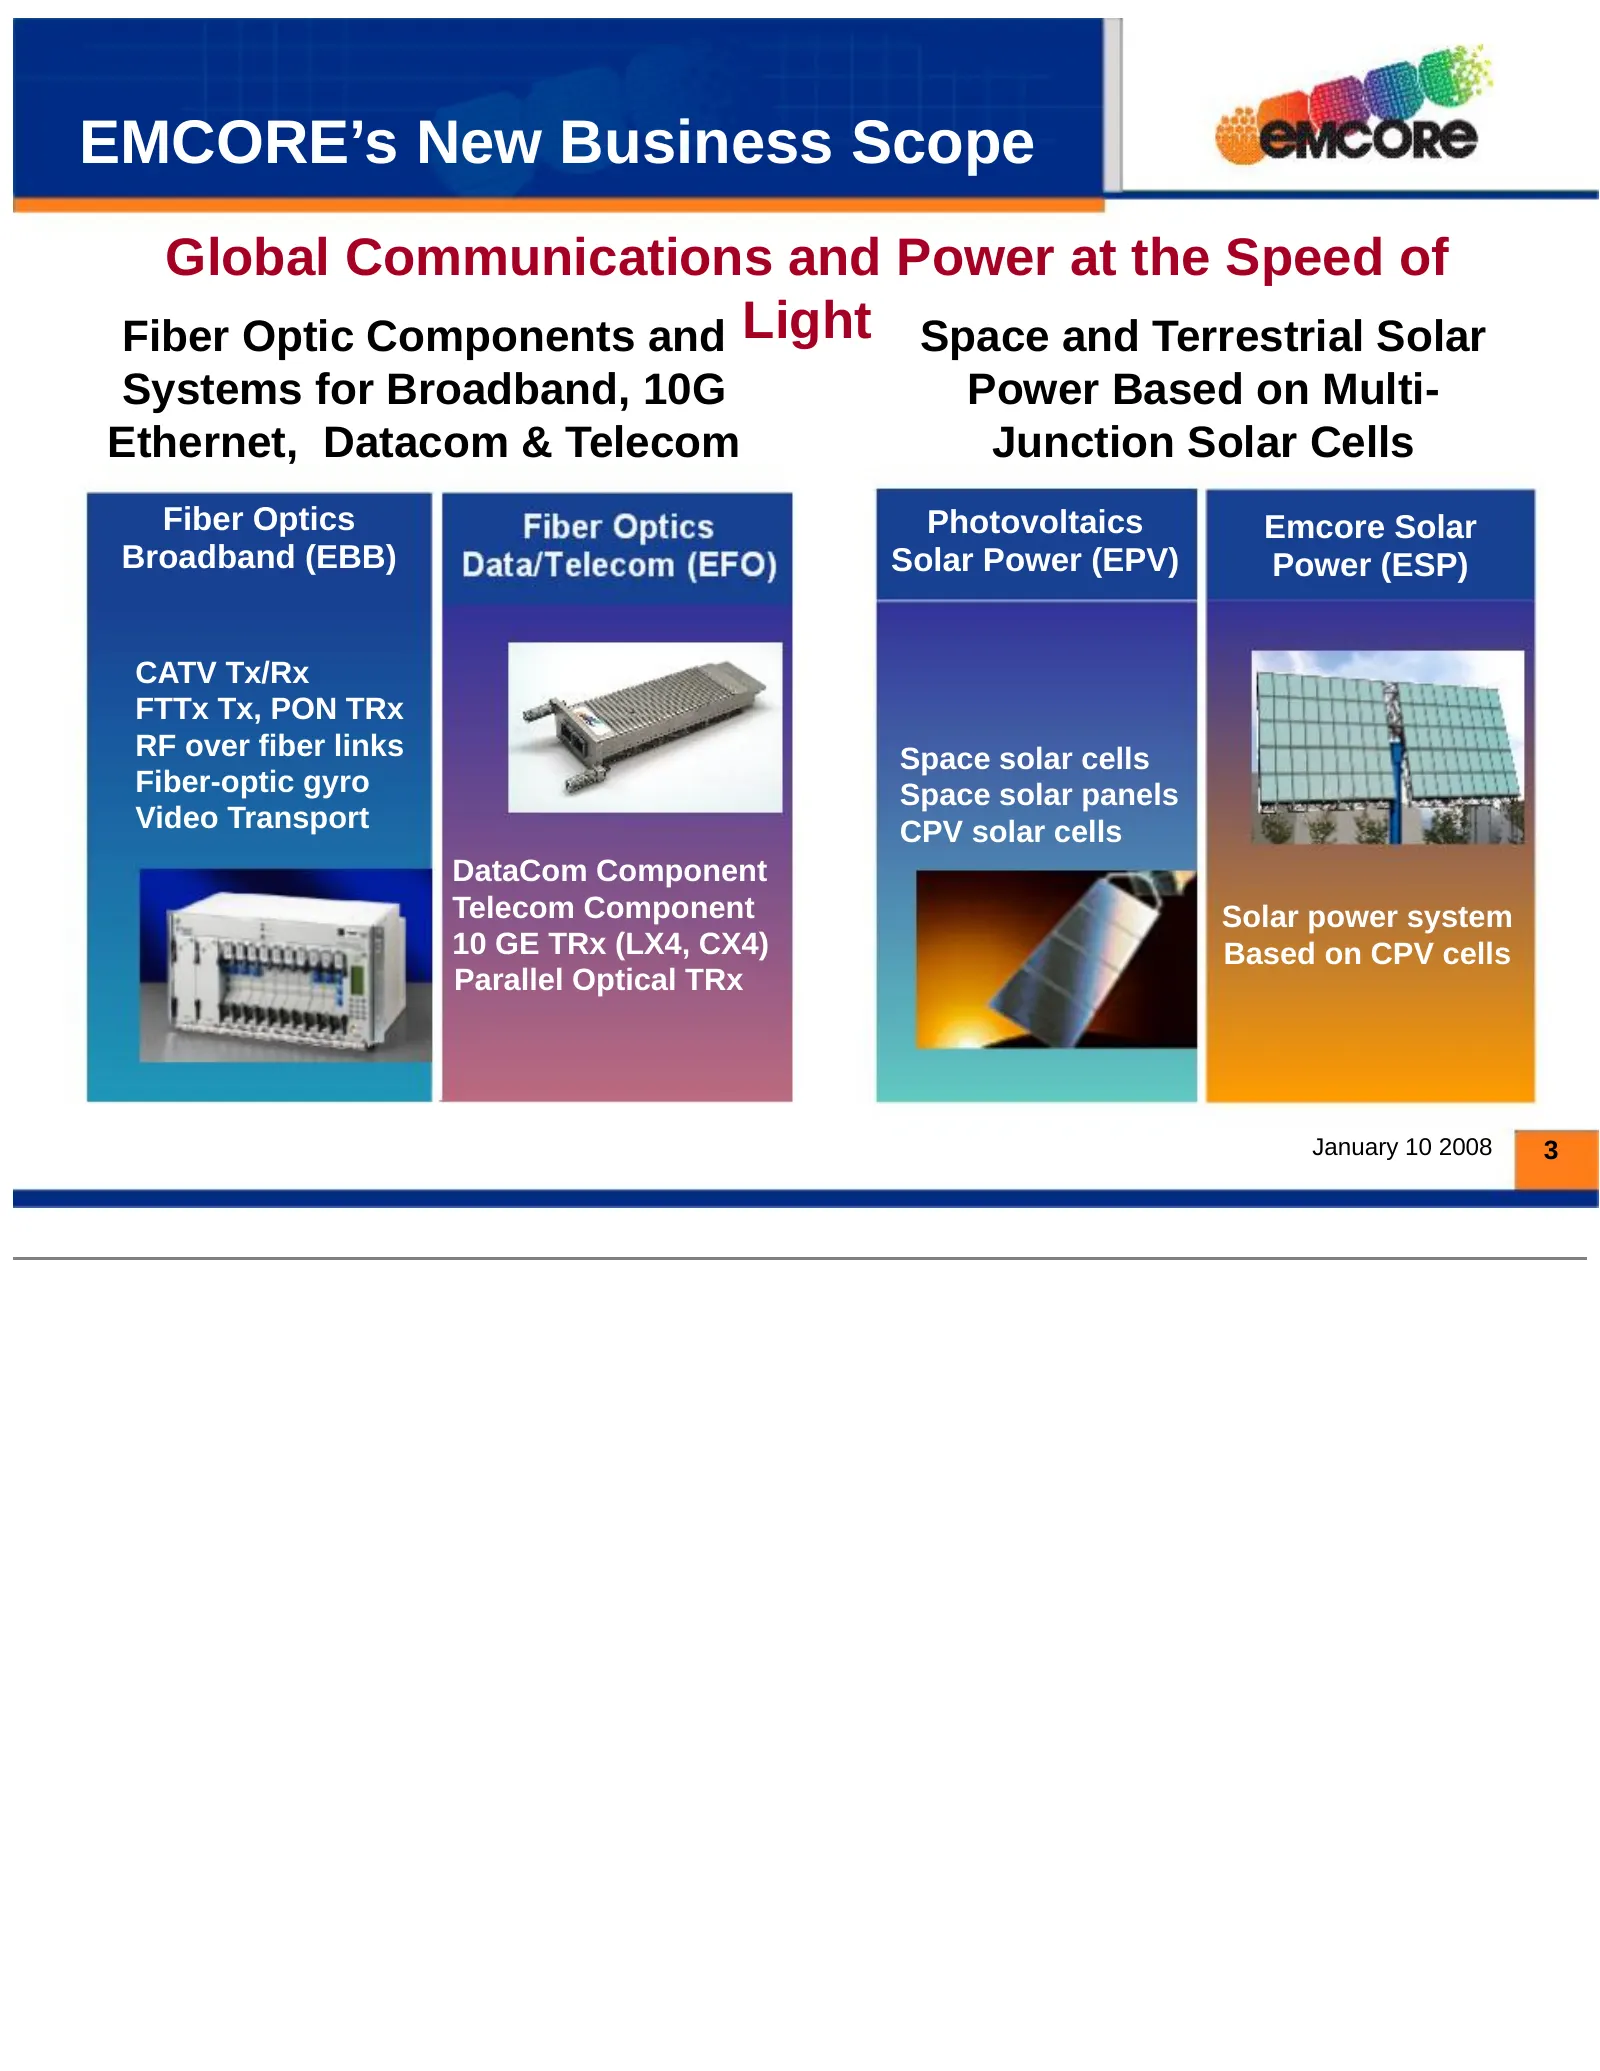
EMCORE’s New Business Scope Global Communications and Power at the Speed of Fiber Optic Components and Light Space and Terrestrial Solar Systems for Broadband, 10G Power Based on Multi- Ethernet, Datacom & Telecom Junction Solar Cells Fiber Optics Photovoltaics Emcore Solar Broadband (EBB) Solar Pow
Slide 4: EMCORE Photovoltaics Division
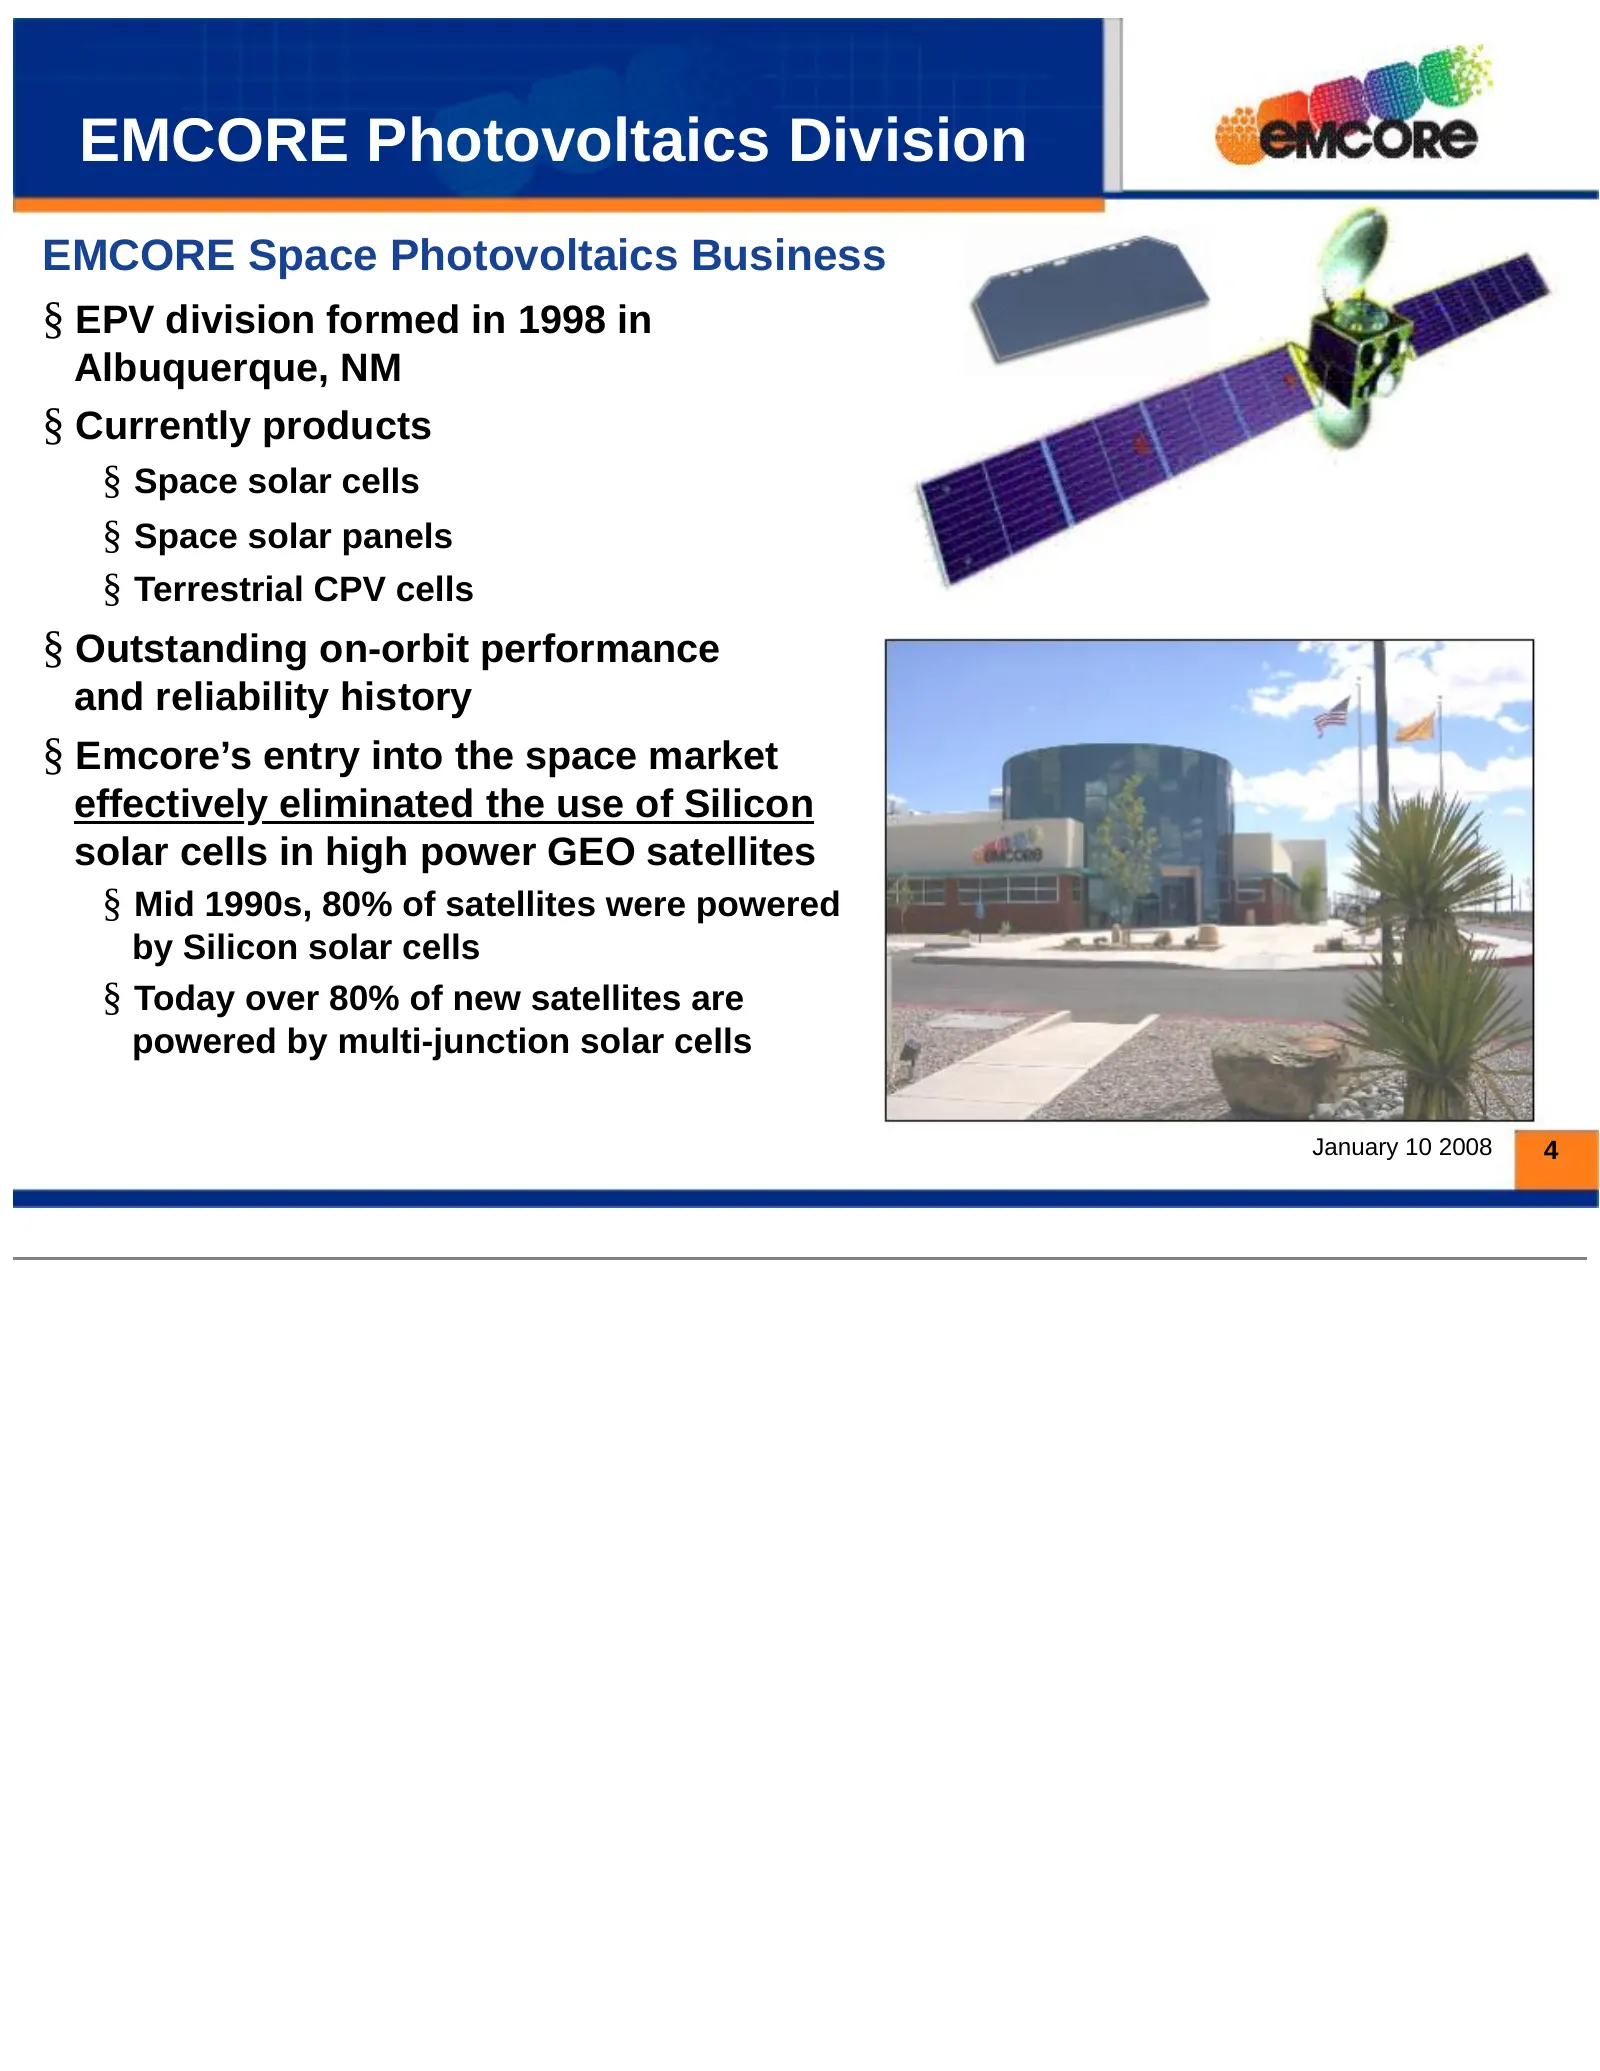
EMCORE Photovoltaics Division EMCORE Space Photovoltaics Business § EPV division formed in 1998 in Albuquerque, NM § Currently products § Space solar cells § Space solar panels § Terrestrial CPV cells § Outstanding on-orbit performance and reliability history § Emcore’s entry into the space market e
Slide 5: Leading III-V Solar Cell Technology Replacing Silicon Based Applications
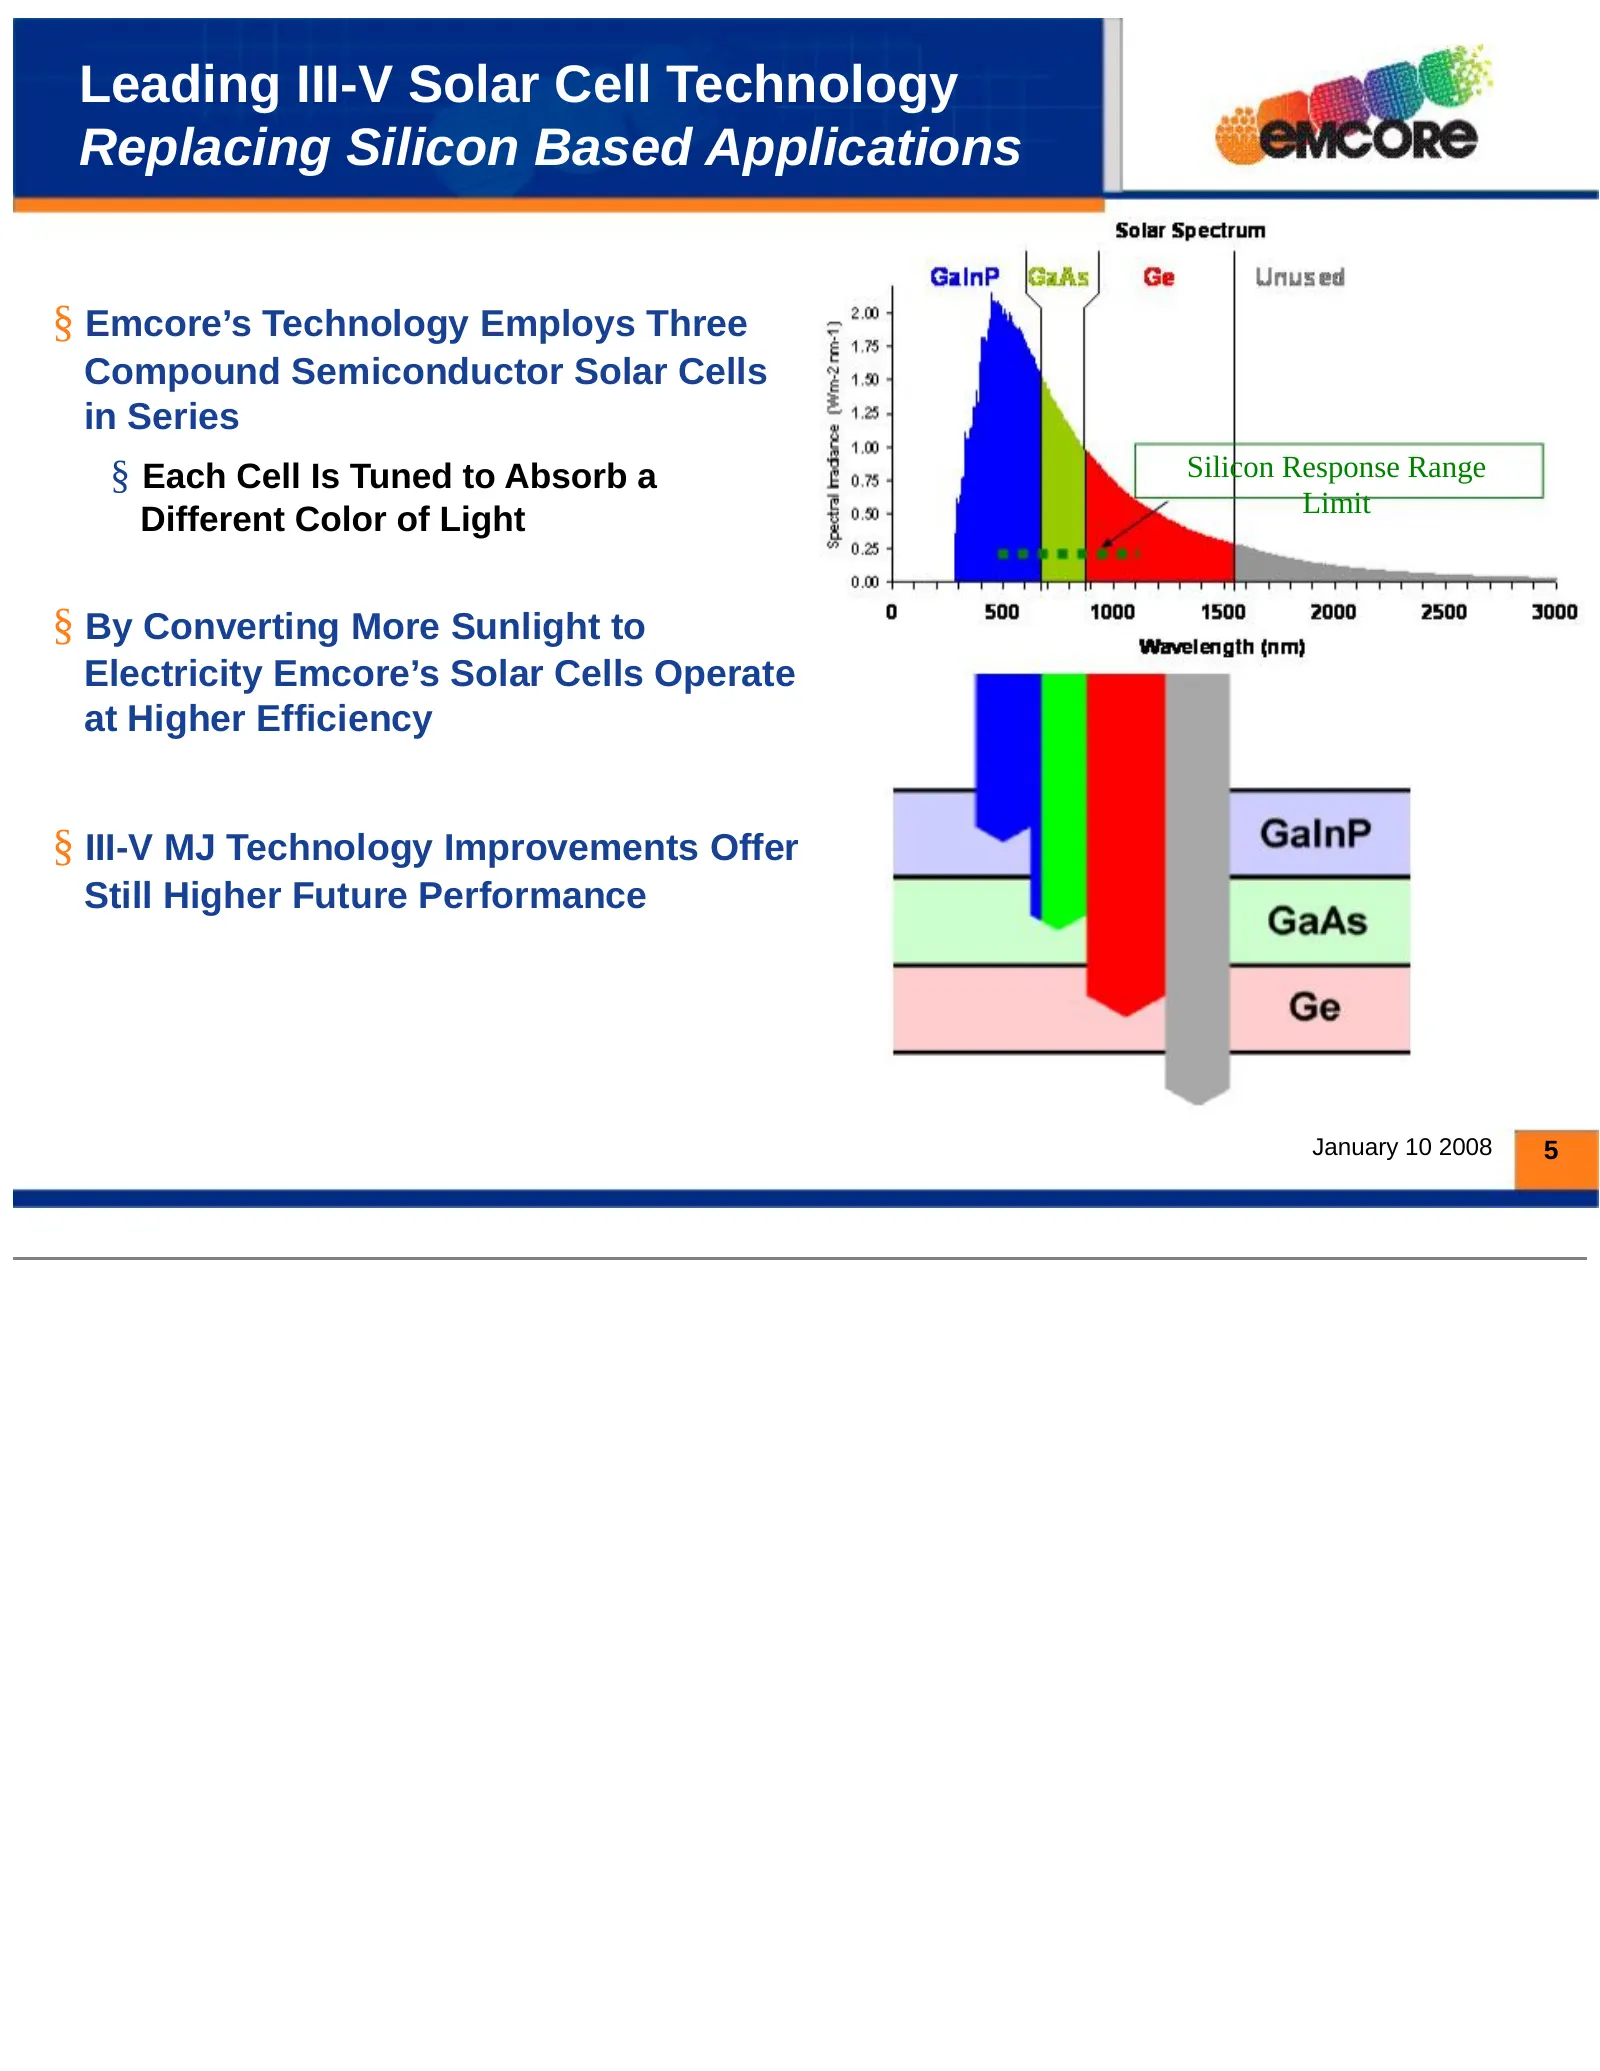
Leading III-V Solar Cell Technology Replacing Silicon Based Applications § Emcore’s Technology Employs Three Compound Semiconductor Solar Cells in Series § Each Cell Is Tuned to Absorb a Silicon Response Range Limit Different Color of Light § By Converting More Sunlight to Electricity Emcore’s Solar
Slide 6: Growth Drivers of Space Solar
Growth Drivers of Space Solar Major Customers § Loral, Lockheed Martin, Northrop-Grumman, Boeing, Astrium, GD, and ATK Market Drivers § Commercial Satellites: 33 GEO awards in 2006, highest since 2001 (6 awards) § Industry is at the leading edge of a replacement cycle as many of the satellites launc
Slide 7: Terrestrial Application of Triple Junction Solar Cell with Concentrator
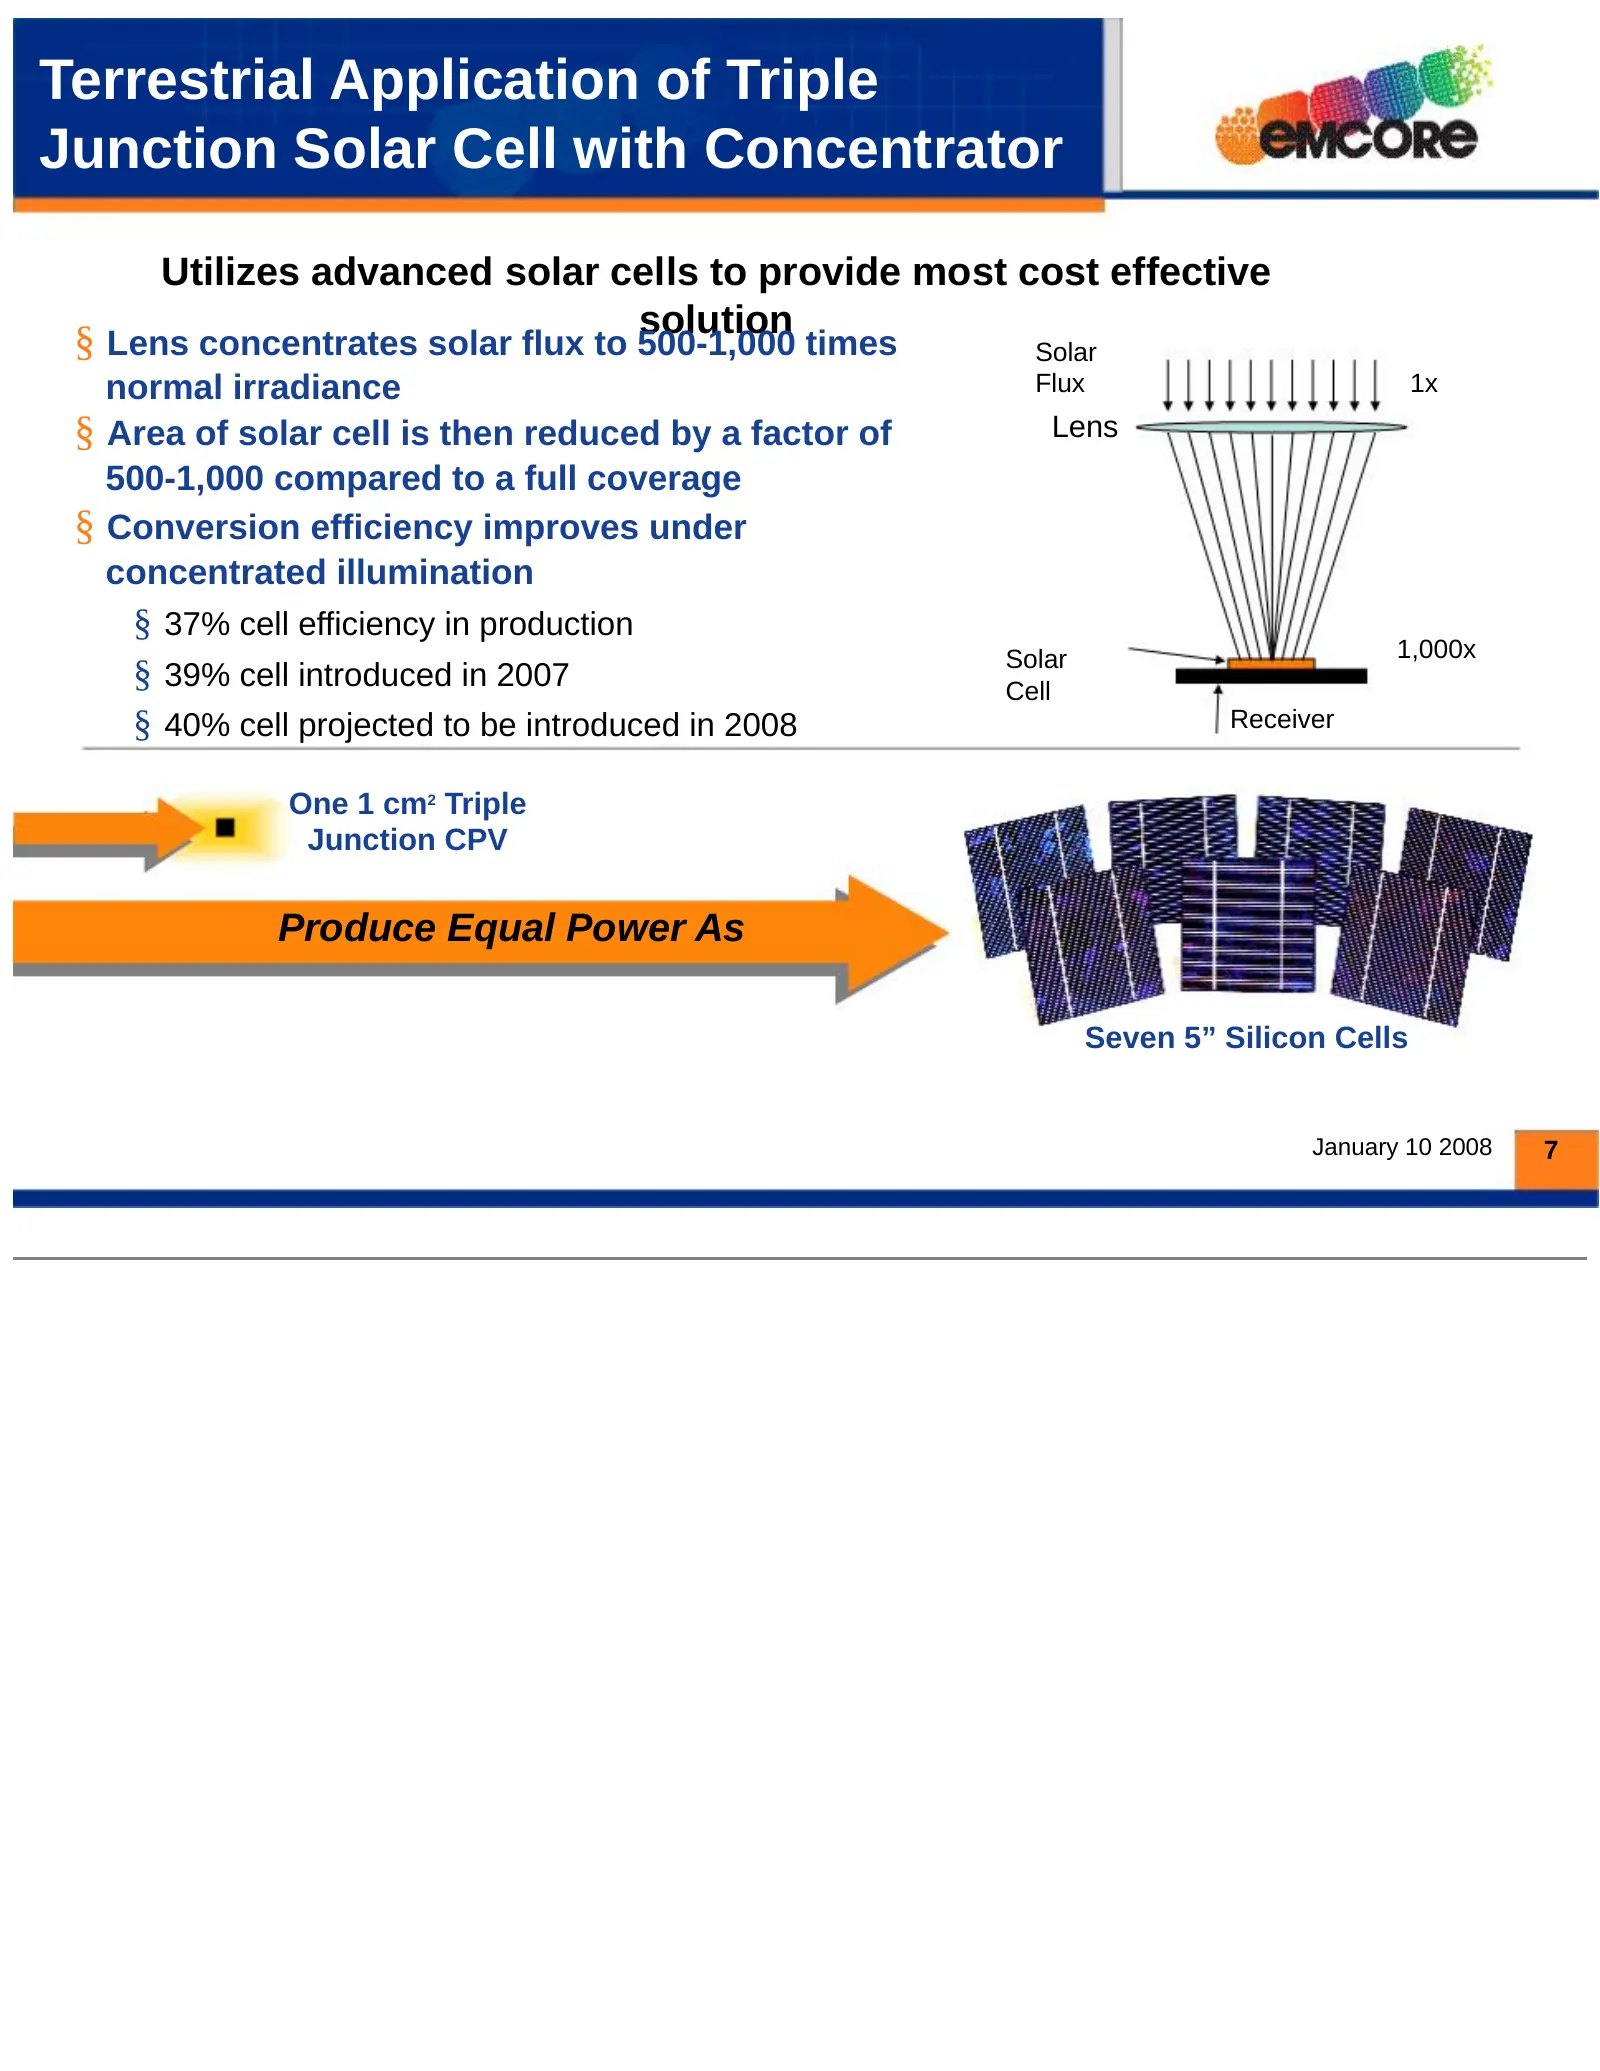
Terrestrial Application of Triple Junction Solar Cell with Concentrator Utilizes advanced solar cells to provide most cost effective solution § Lens concentrates solar flux to 500-1,000 times Solar normal irradiance Flux 1x § Area of solar cell is then reduced by a factor of Lens 500-1,000 compared
Slide 8: Solar Module Technologies
Solar Module Technologies § Crystalline Si: Conversion efficiency of 12-14% at module level § Pros: ♦ Predominant technology ♦ Most versatile for all applications § Cons: ♦ Si shortage (at least until late of 2008) ♦ Relatively high price: ~$3.5-3.8/W § Thin Film: Conversion efficiency of 5-7% at mo
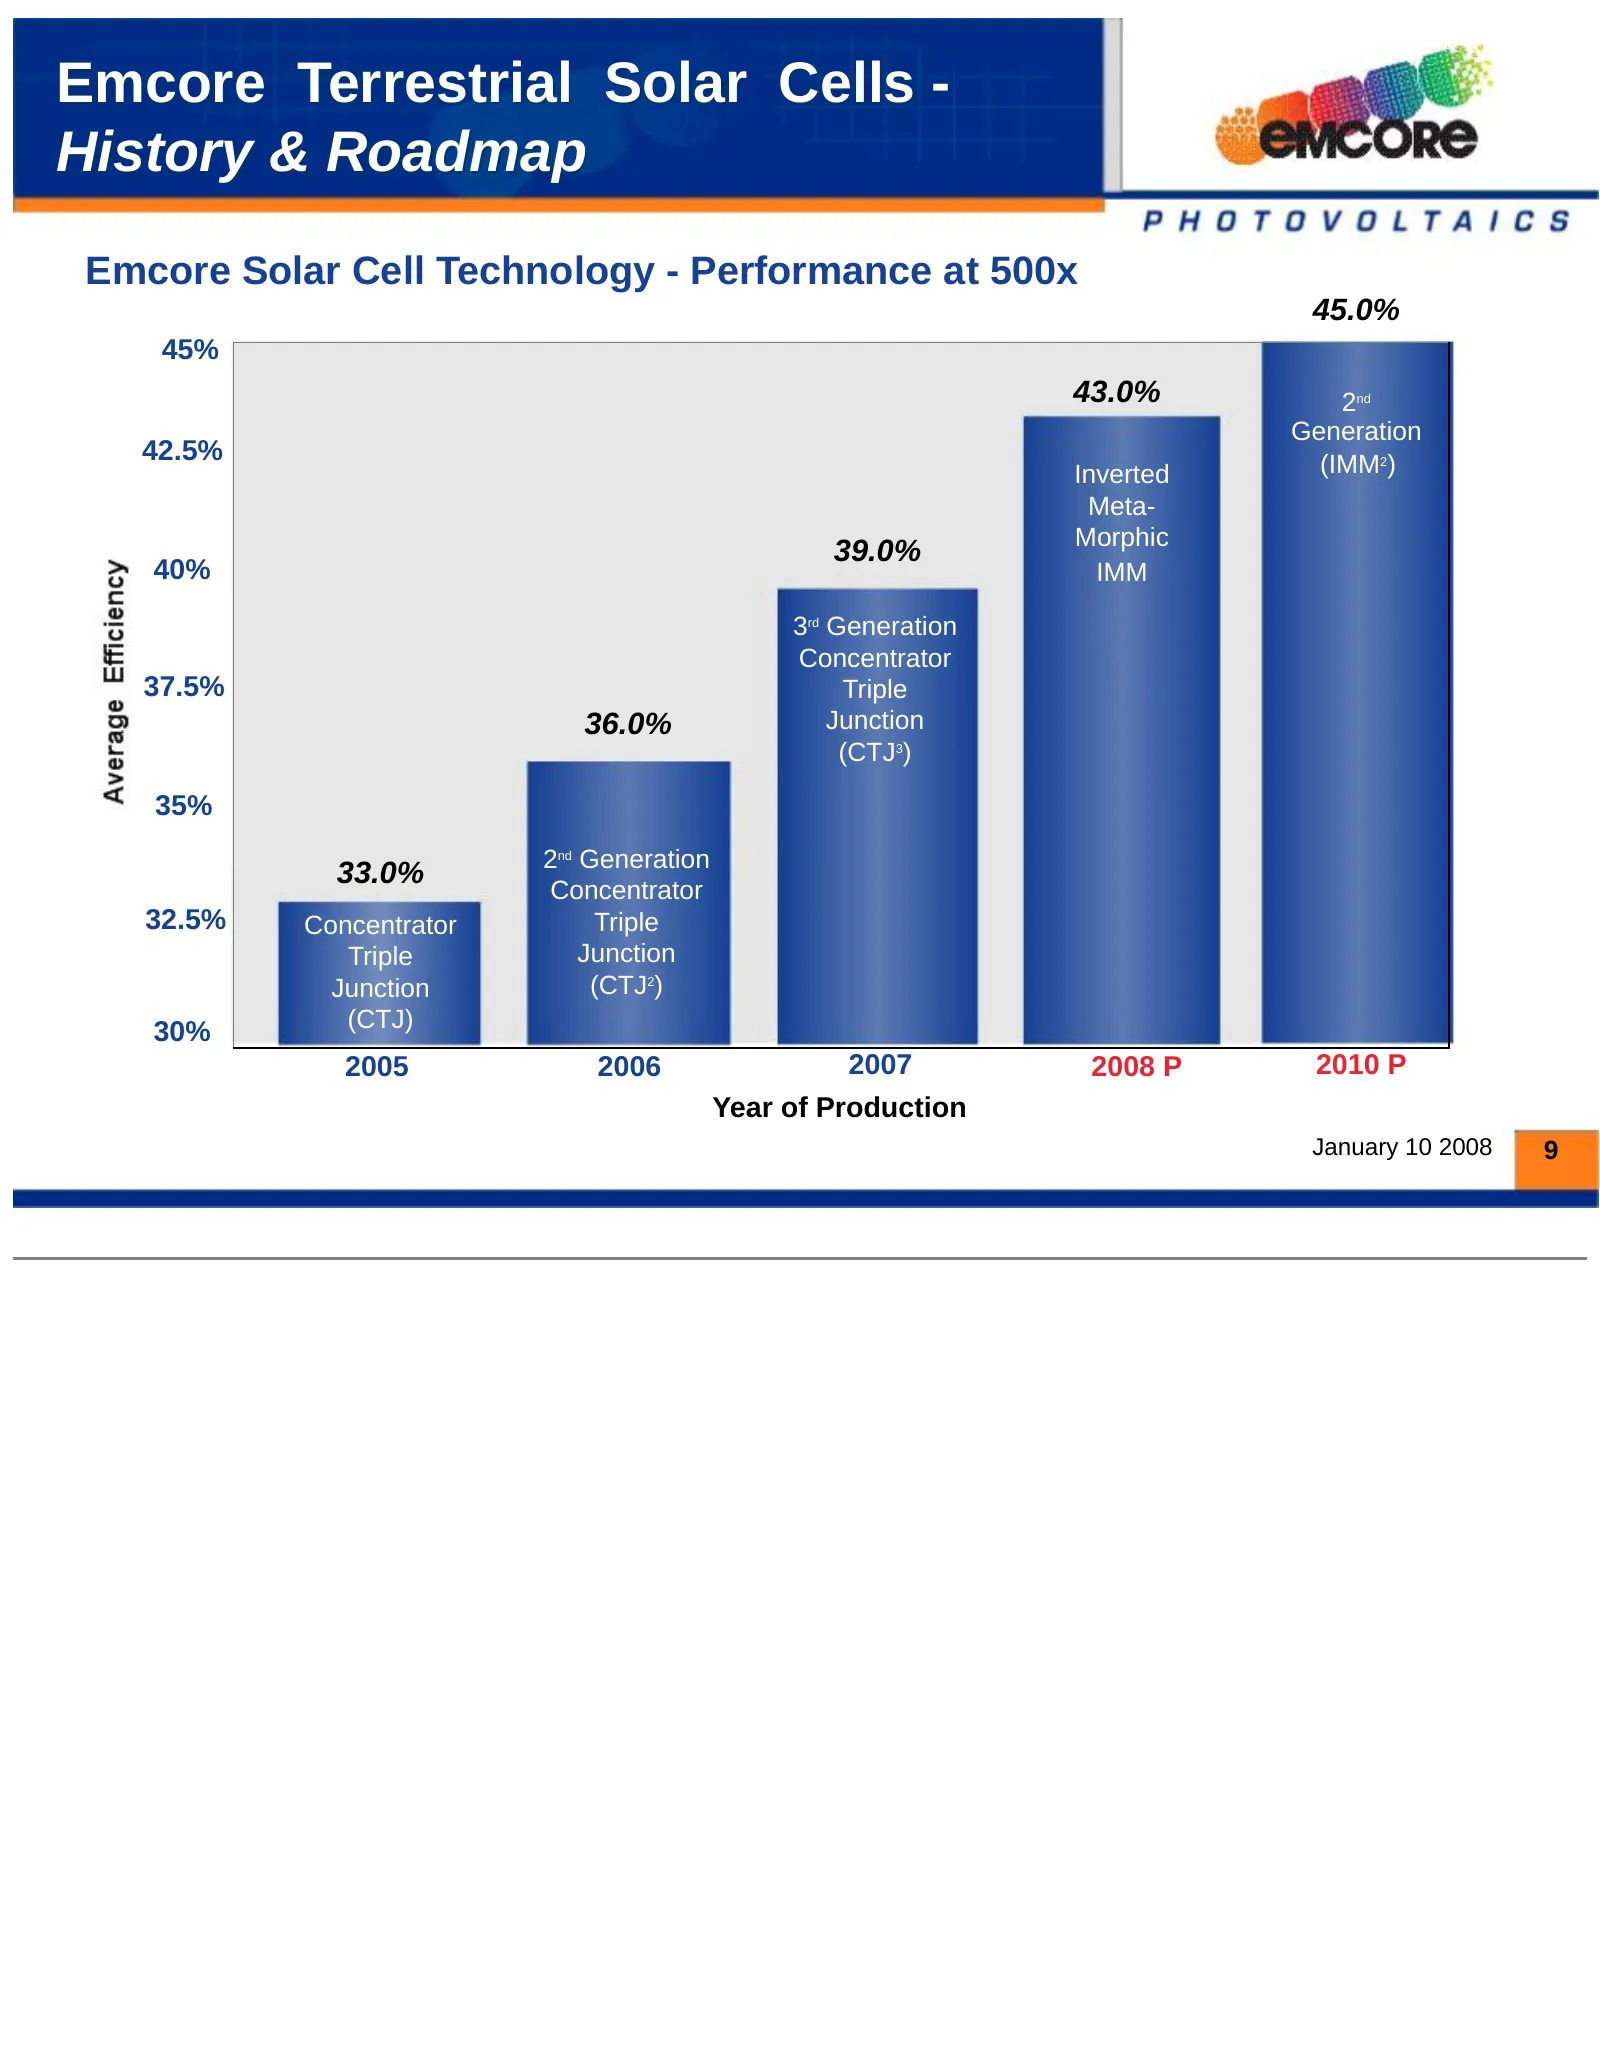
Slide 9: Emcore Terrestrial Solar Cells - History & Roadmap
Emcore Terrestrial Solar Cells - History & Roadmap Emcore Solar Cell Technology - Performance at 500x 45.0% 45% 43.0% 2nd Generation 42.5% (IMM2) Inverted Meta- Morphic 39.0% 40% IMM 3rd Generation Concentrator 37.5% Triple 36.0% Junction (CTJ3) 35% 2nd Generation 33.0% Concentrator 32.5% Concentrat
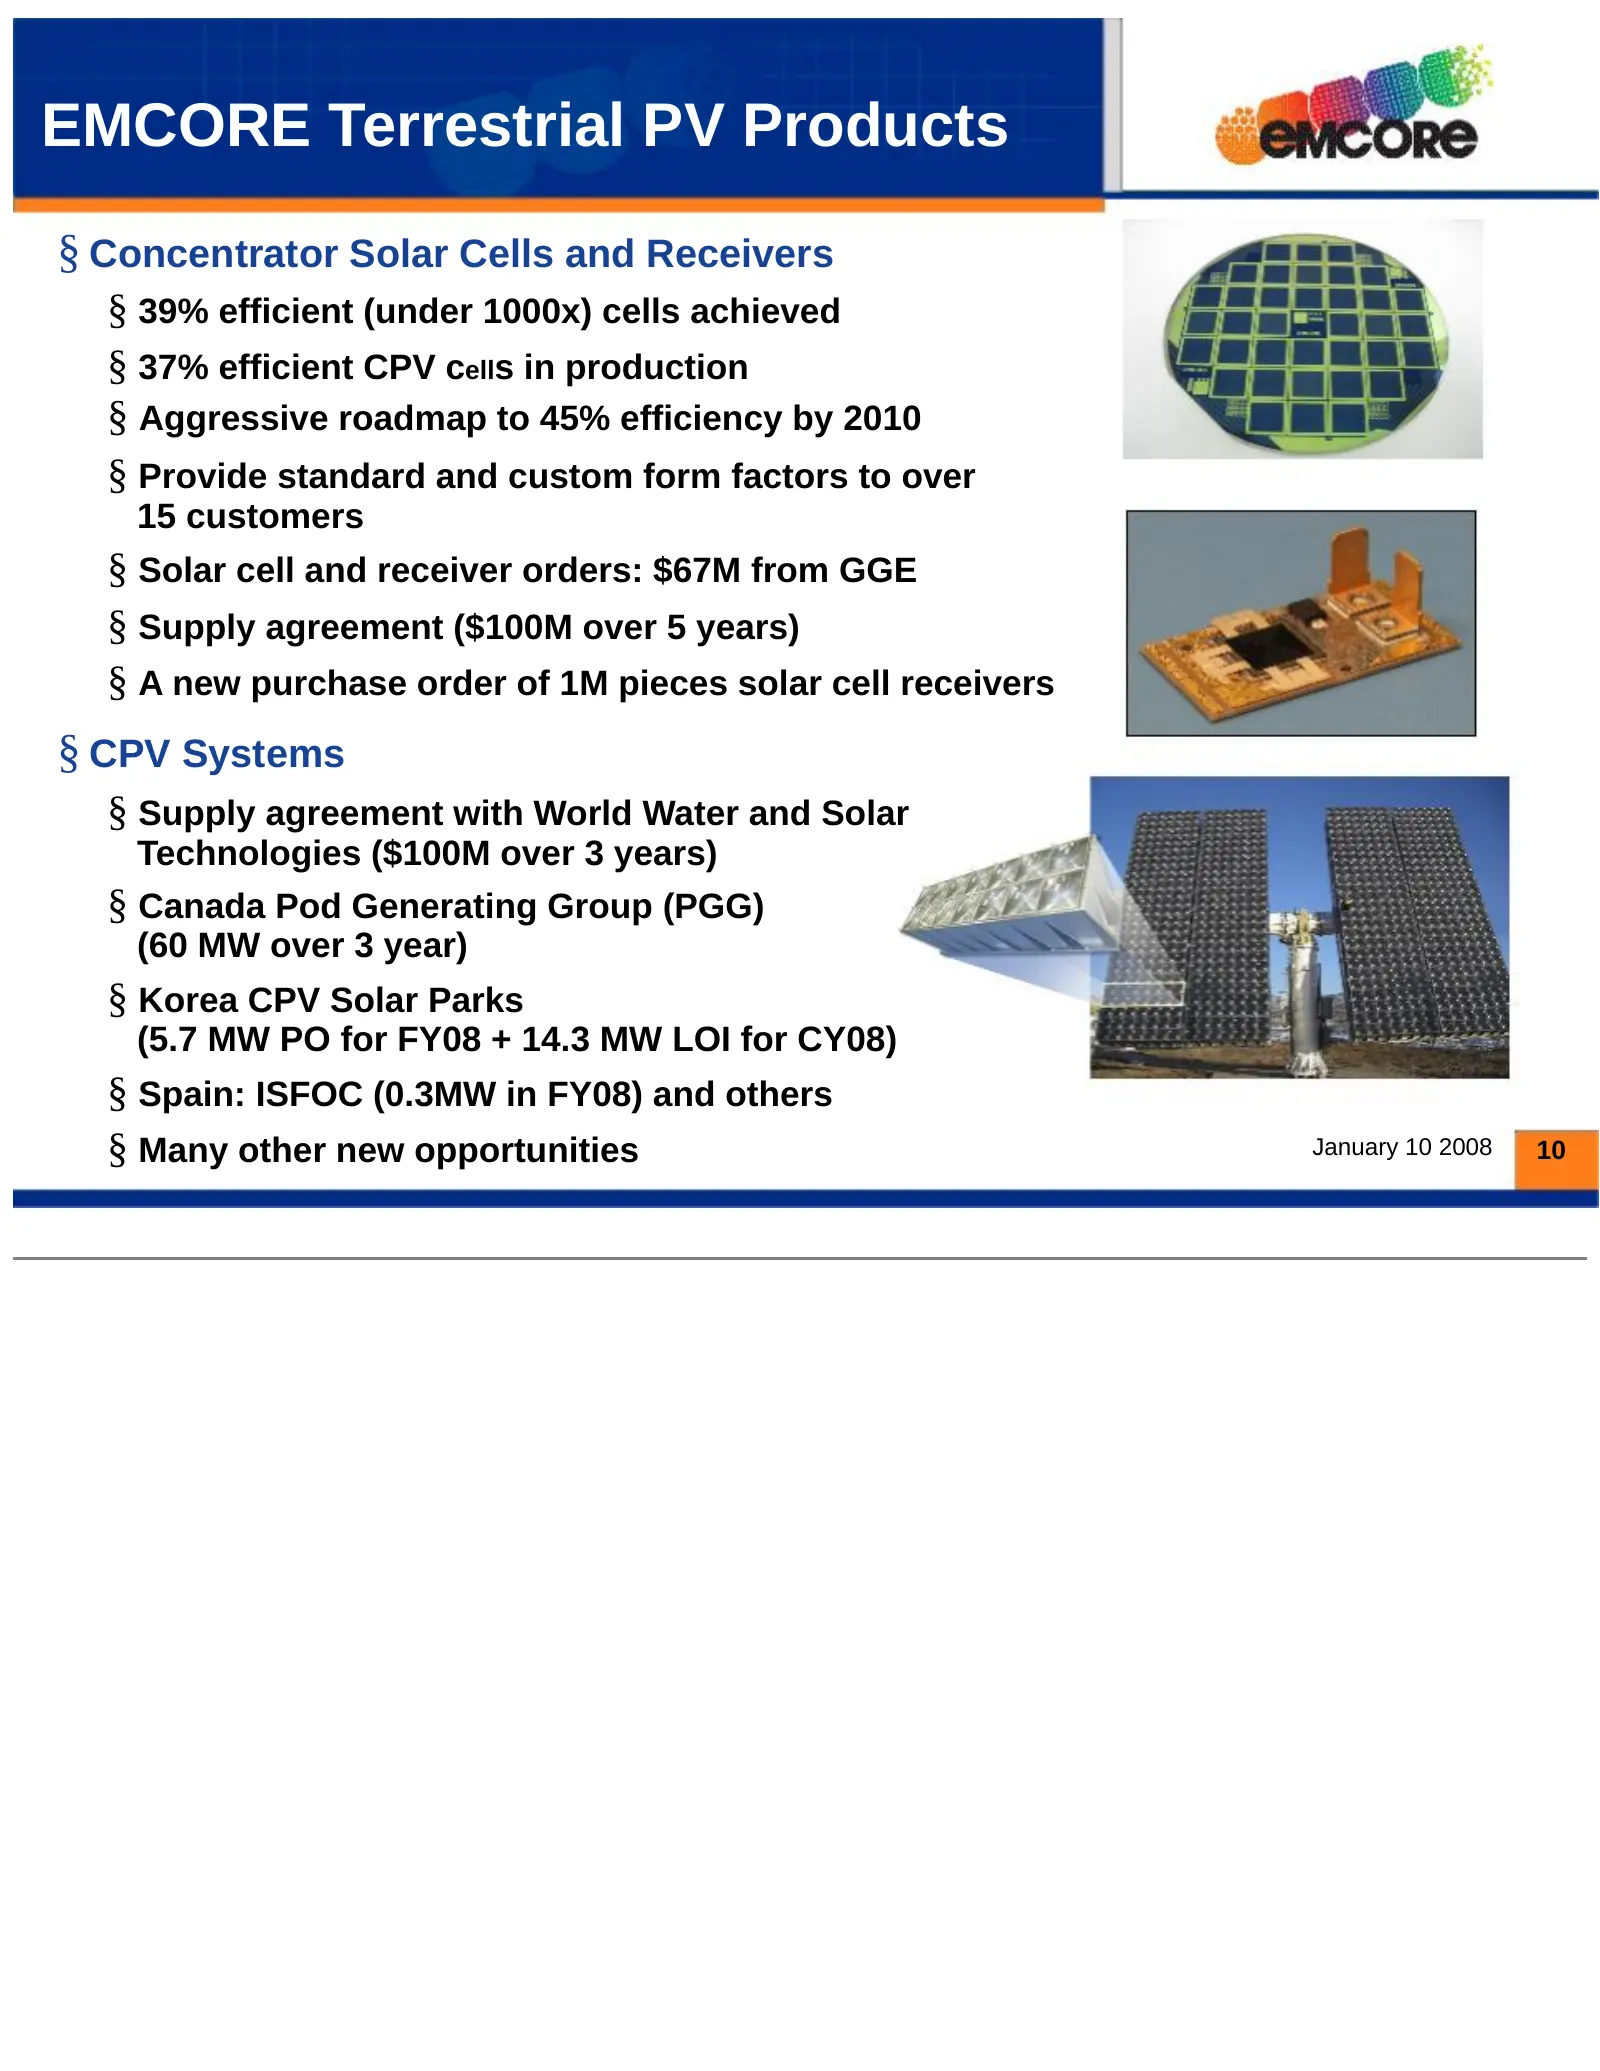
Slide 10: EMCORE Terrestrial PV Products
EMCORE Terrestrial PV Products § Concentrator Solar Cells and Receivers § 39% efficient (under 1000x) cells achieved § 37% efficient CPV cells in production § Aggressive roadmap to 45% efficiency by 2010 § Provide standard and custom form factors to over 15 customers § Solar cell and receiver orders
Slide 11: Growth Drivers of EMCORE Terrestrial PV Business
Growth Drivers of EMCORE Terrestrial PV Business § CPV Components § One of the two major suppliers • Best performance with competitive price • Strong performance roadmap § Support the entire CPV community § Current annual capacity greater than 150MW § CPV Systems § Gen 1 system operating “on sun” fo
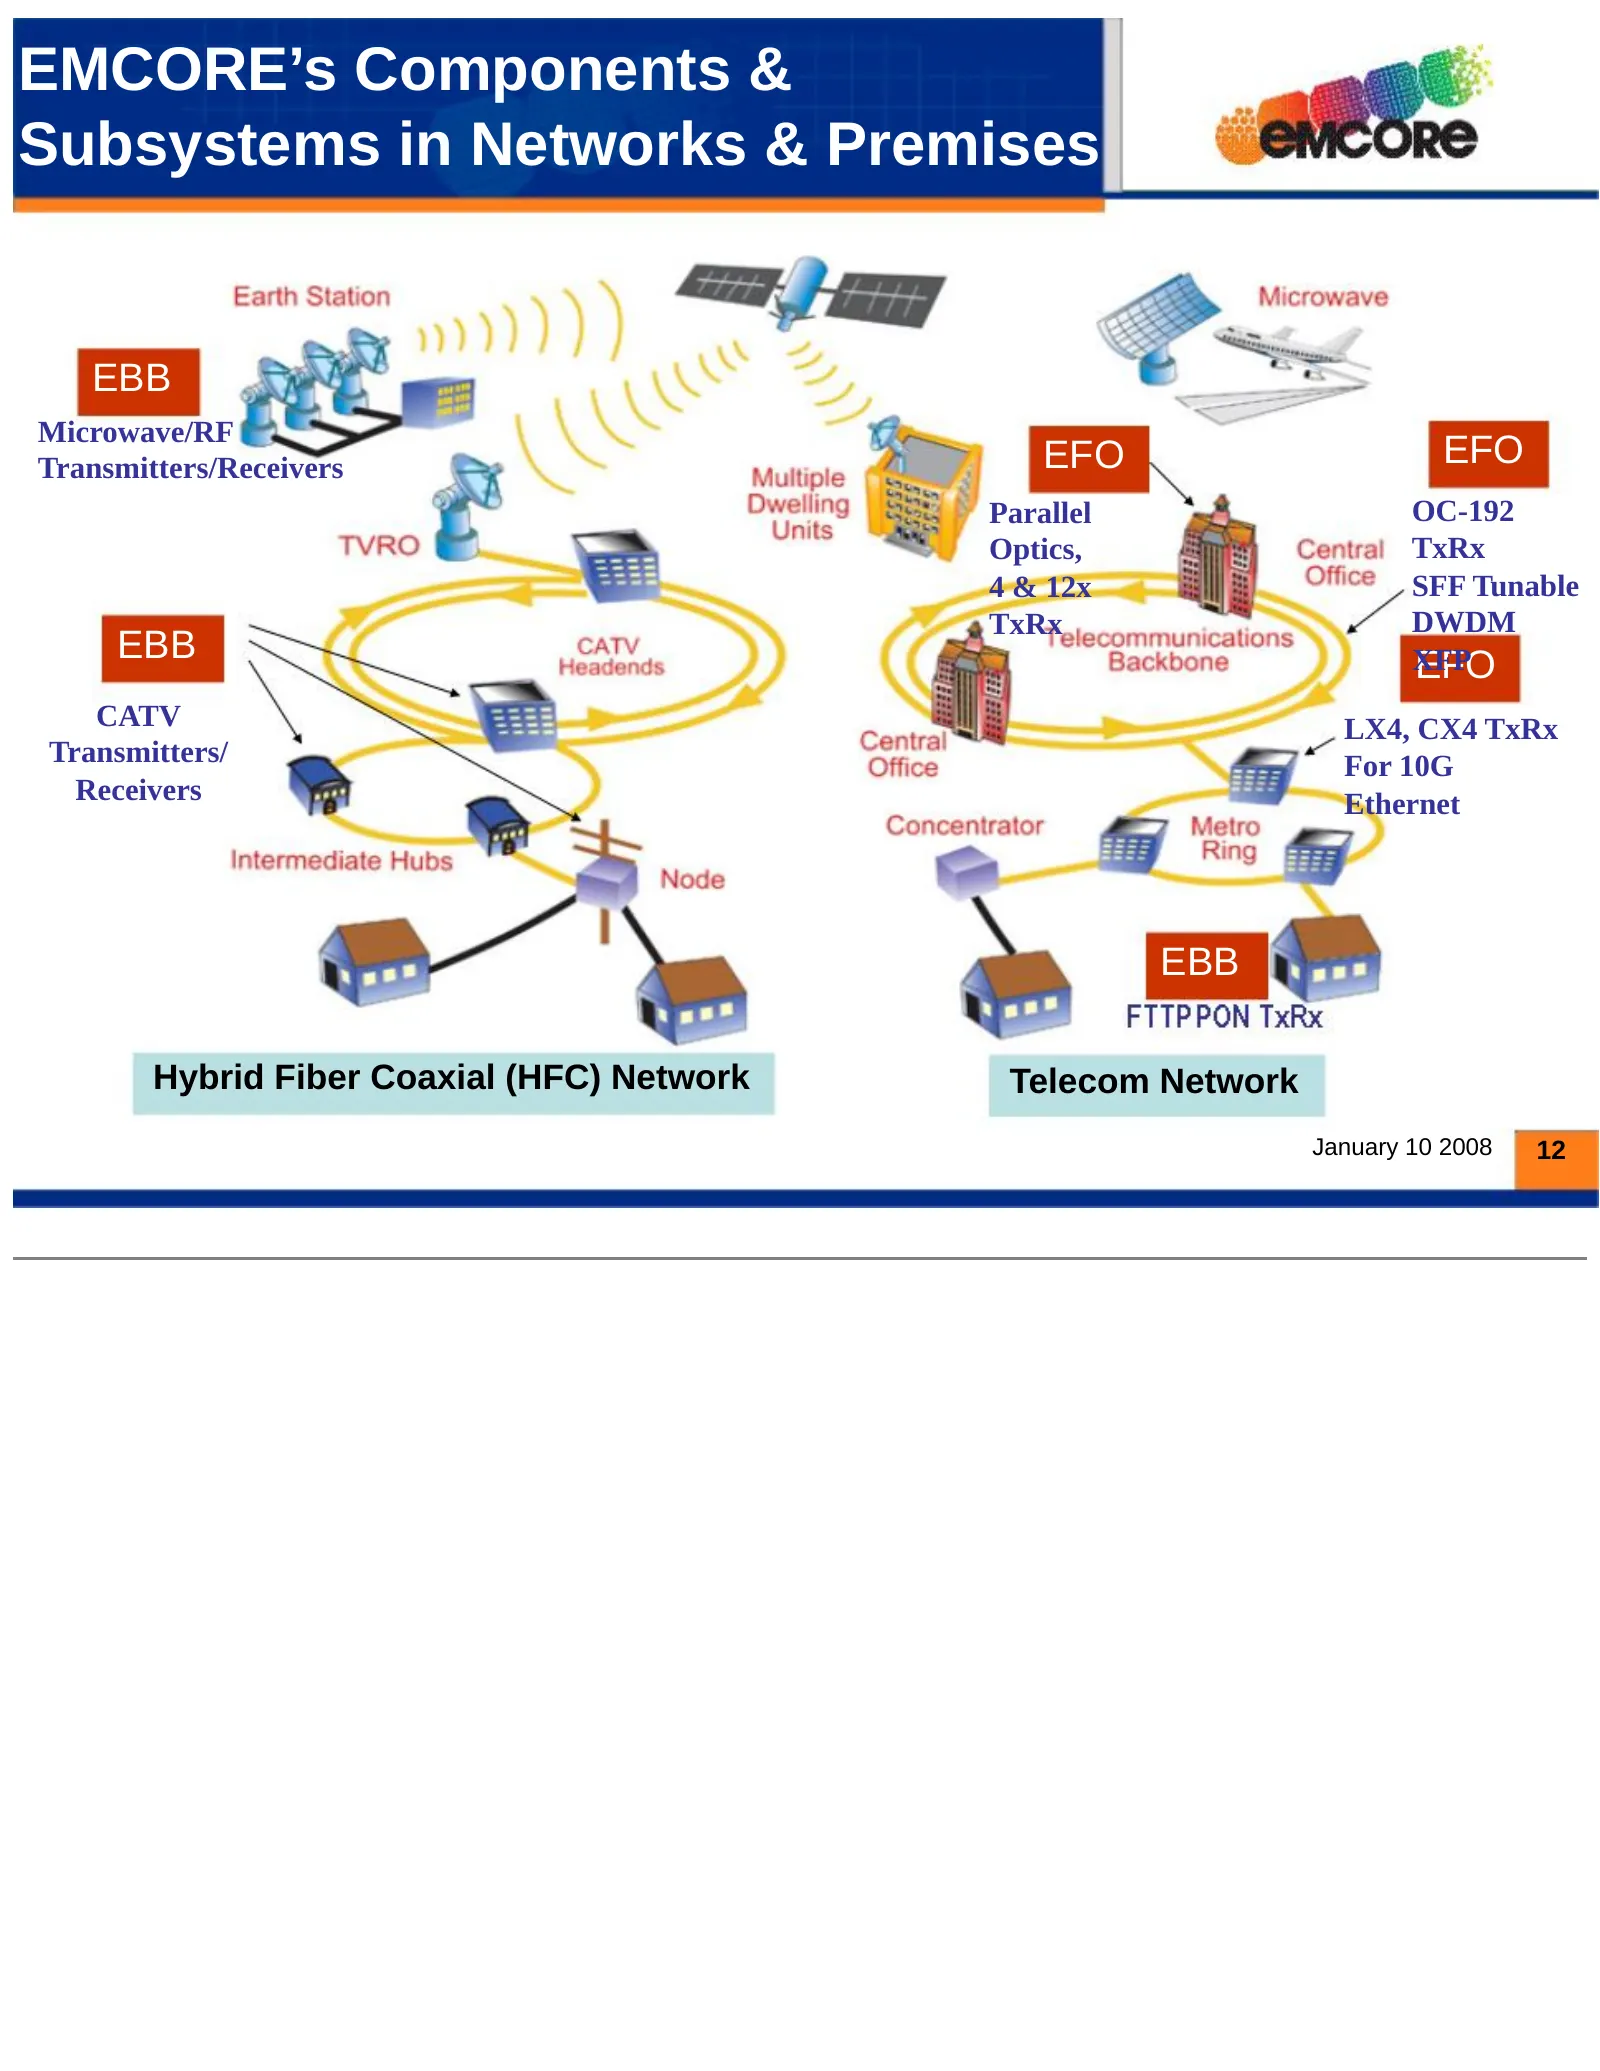
Slide 12: EMCORE’s Components & Subsystems in Networks & Premises
EMCORE’s Components & Subsystems in Networks & Premises EBB Microwave/RF Transmitters/Receivers EFO EFO Parallel OC-192 Optics, TxRx 4 & 12x SFF Tunable TxRx DWDM EBB EFO XFP CATV LX4, CX4 TxRx Transmitters/ For 10G Receivers Ethernet EBB Hybrid Fiber Coaxial (HFC) Network Telecom Network January 10
Slide 13: EMCORE Broadband Product Lines
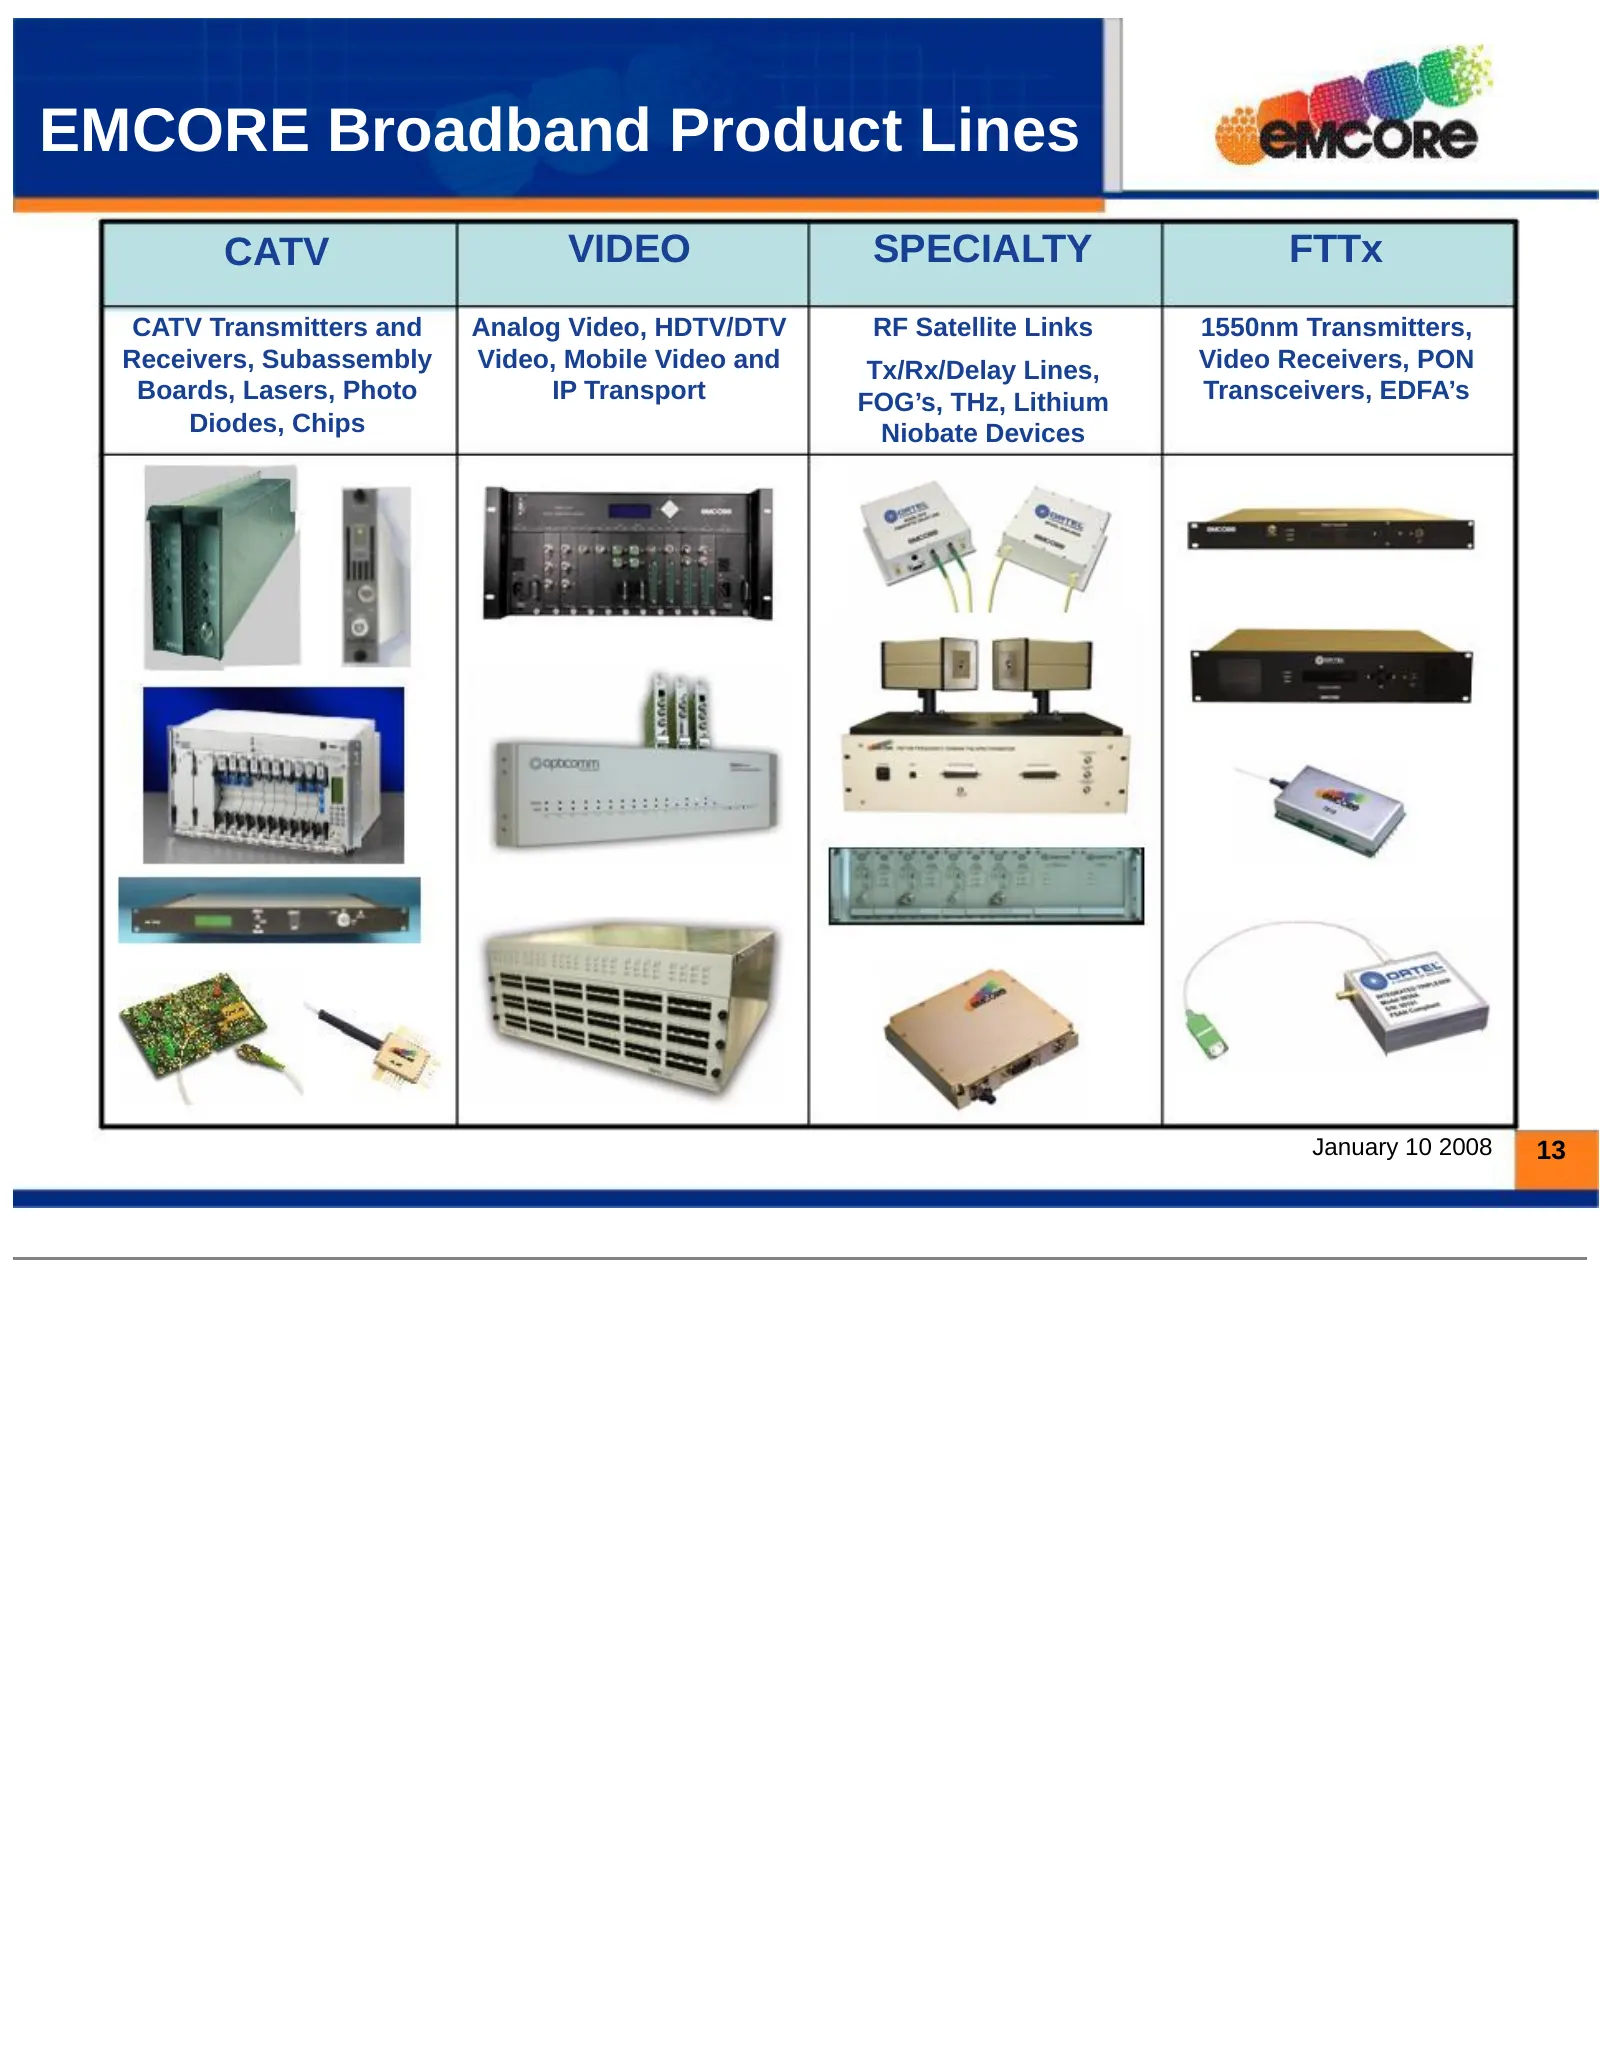
EMCORE Broadband Product Lines CATV VIDEO SPECIALTY FTTx CATV Transmitters and Analog Video, HDTV/DTV RF Satellite Links 1550nm Transmitters, Receivers, Subassembly Video, Mobile Video and Tx/Rx/Delay Lines, Video Receivers, PON Boards, Lasers, Photo IP Transport FOG’s, THz, Lithium Transceivers, ED
Slide 14: Comcast CapEx Budget -- 24% Increase in 07 from 06
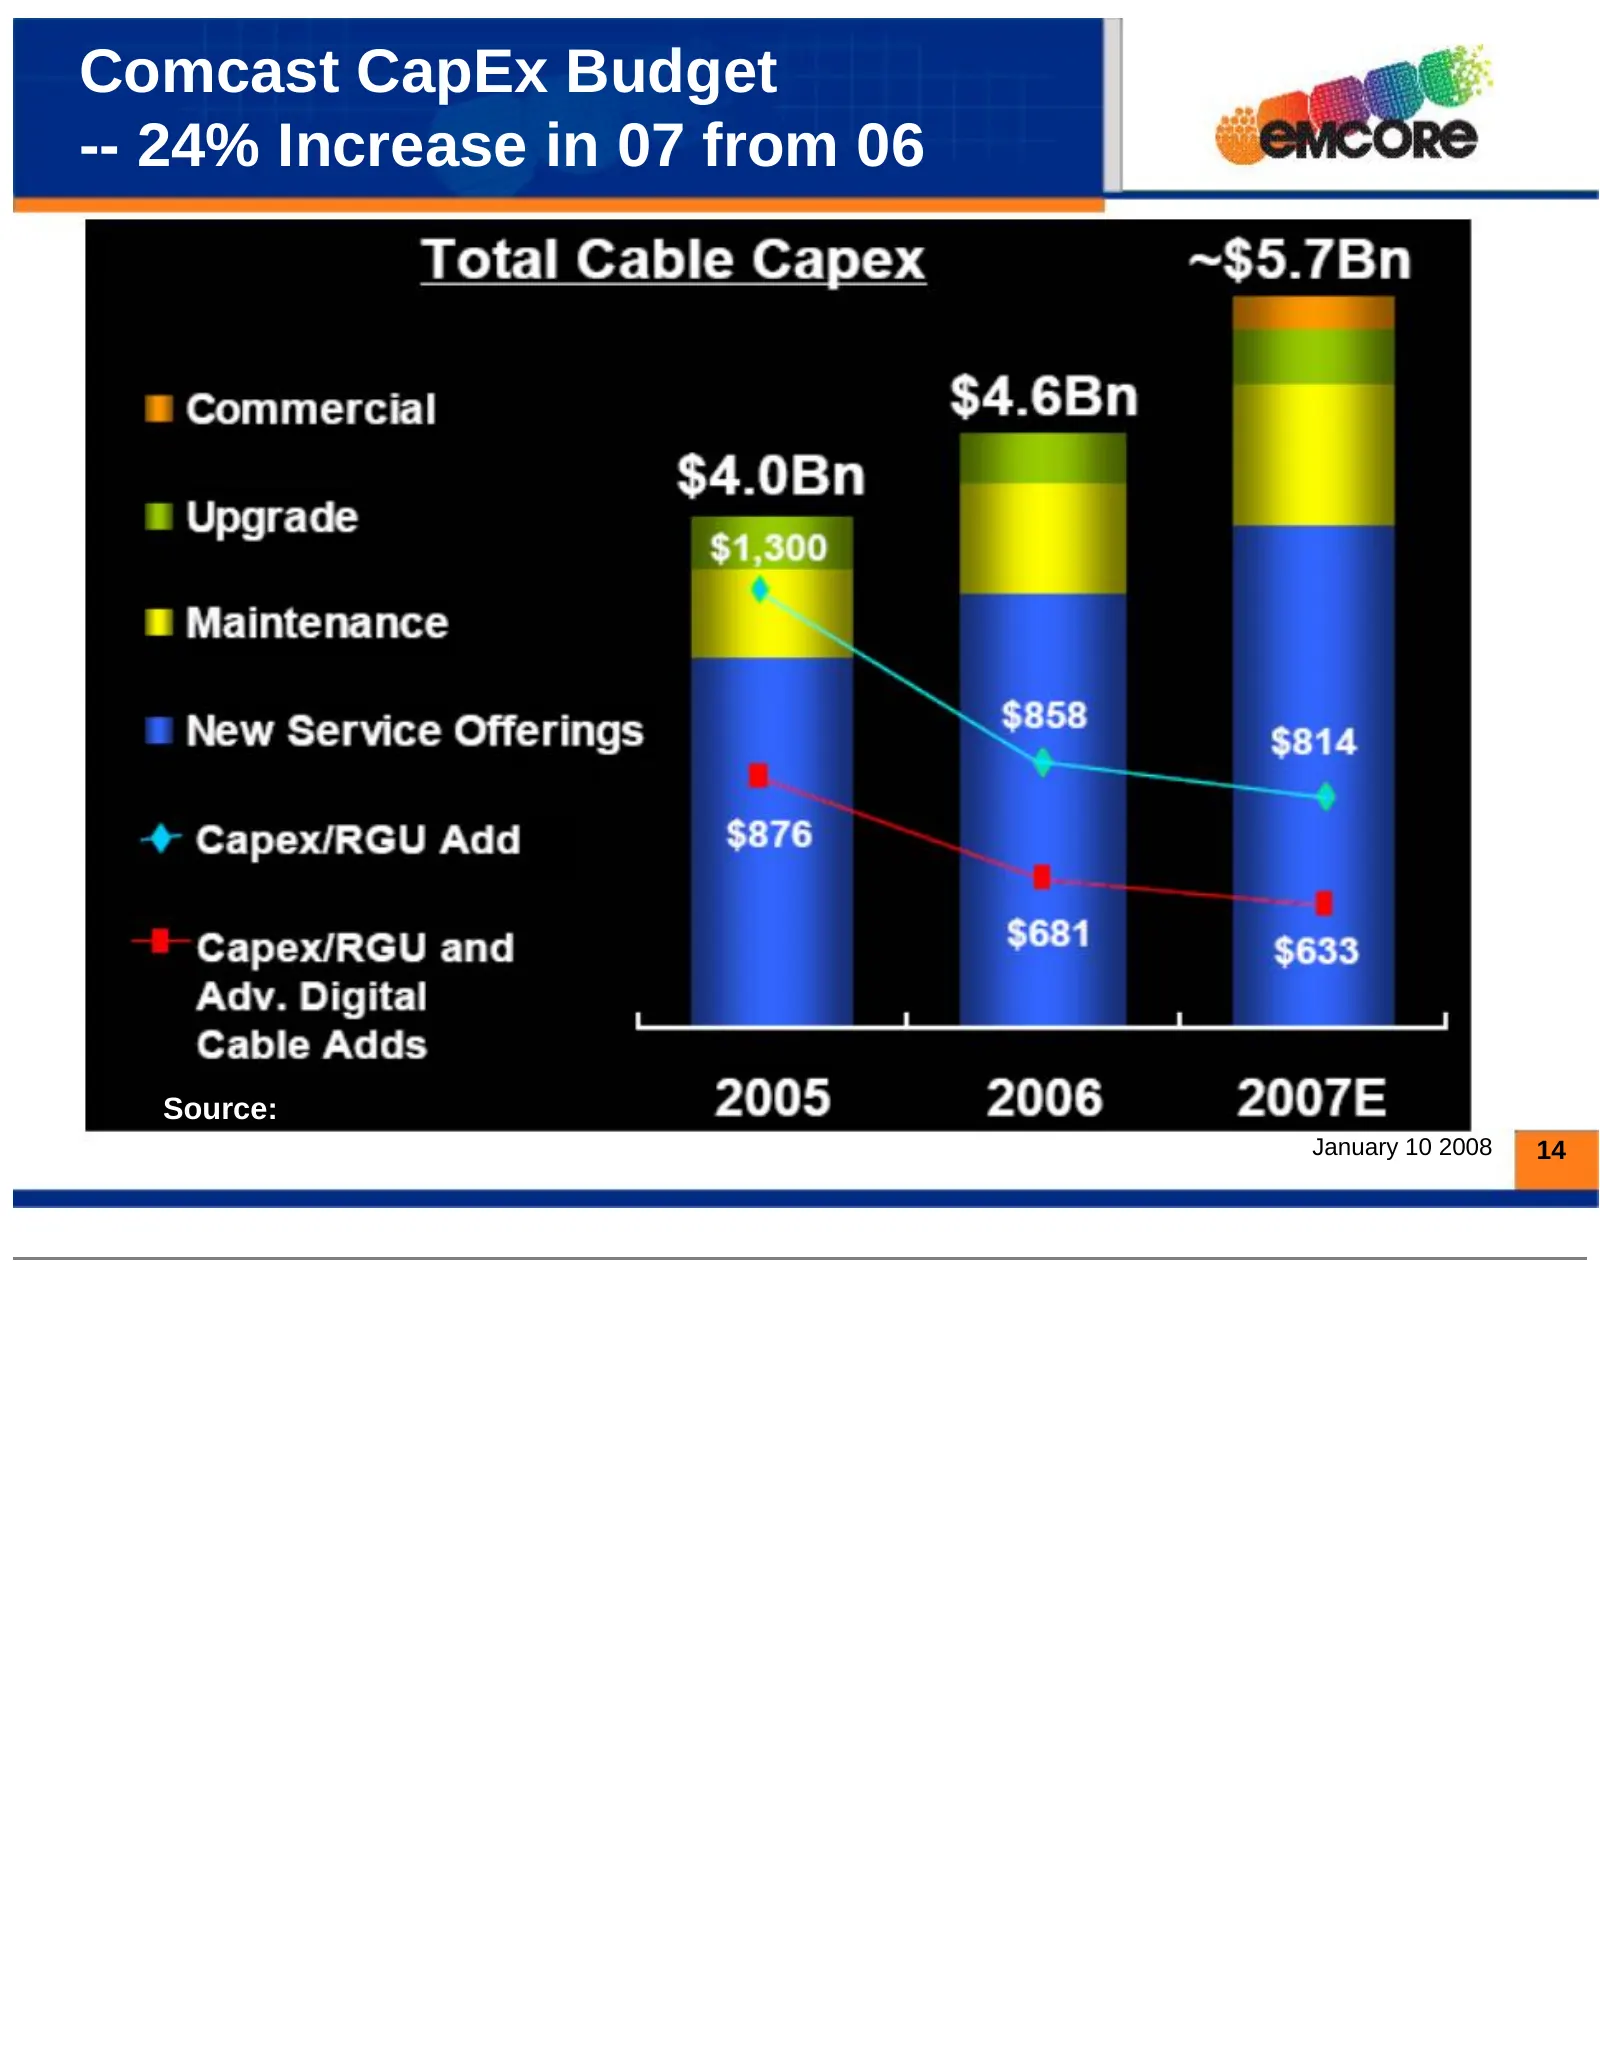
Comcast CapEx Budget -- 24% Increase in 07 from 06 Source: Comcast January 10 2008 14
Slide 15: Broadband (CATV, FTTP, Video Transport) Business Strategy
Broadband (CATV, FTTP, Video Transport) Business Strategy § We are a leading provider of Broadband Components and Systems § Consolidated technology, IP, product portfolio & CATV customer base § Market Drivers of CATV Business § Upgrade HFC network to 1 GHz to offer more value-added premium services
Slide 16: EMCORE Datacom/Telecom Transceiver Product Portfolio
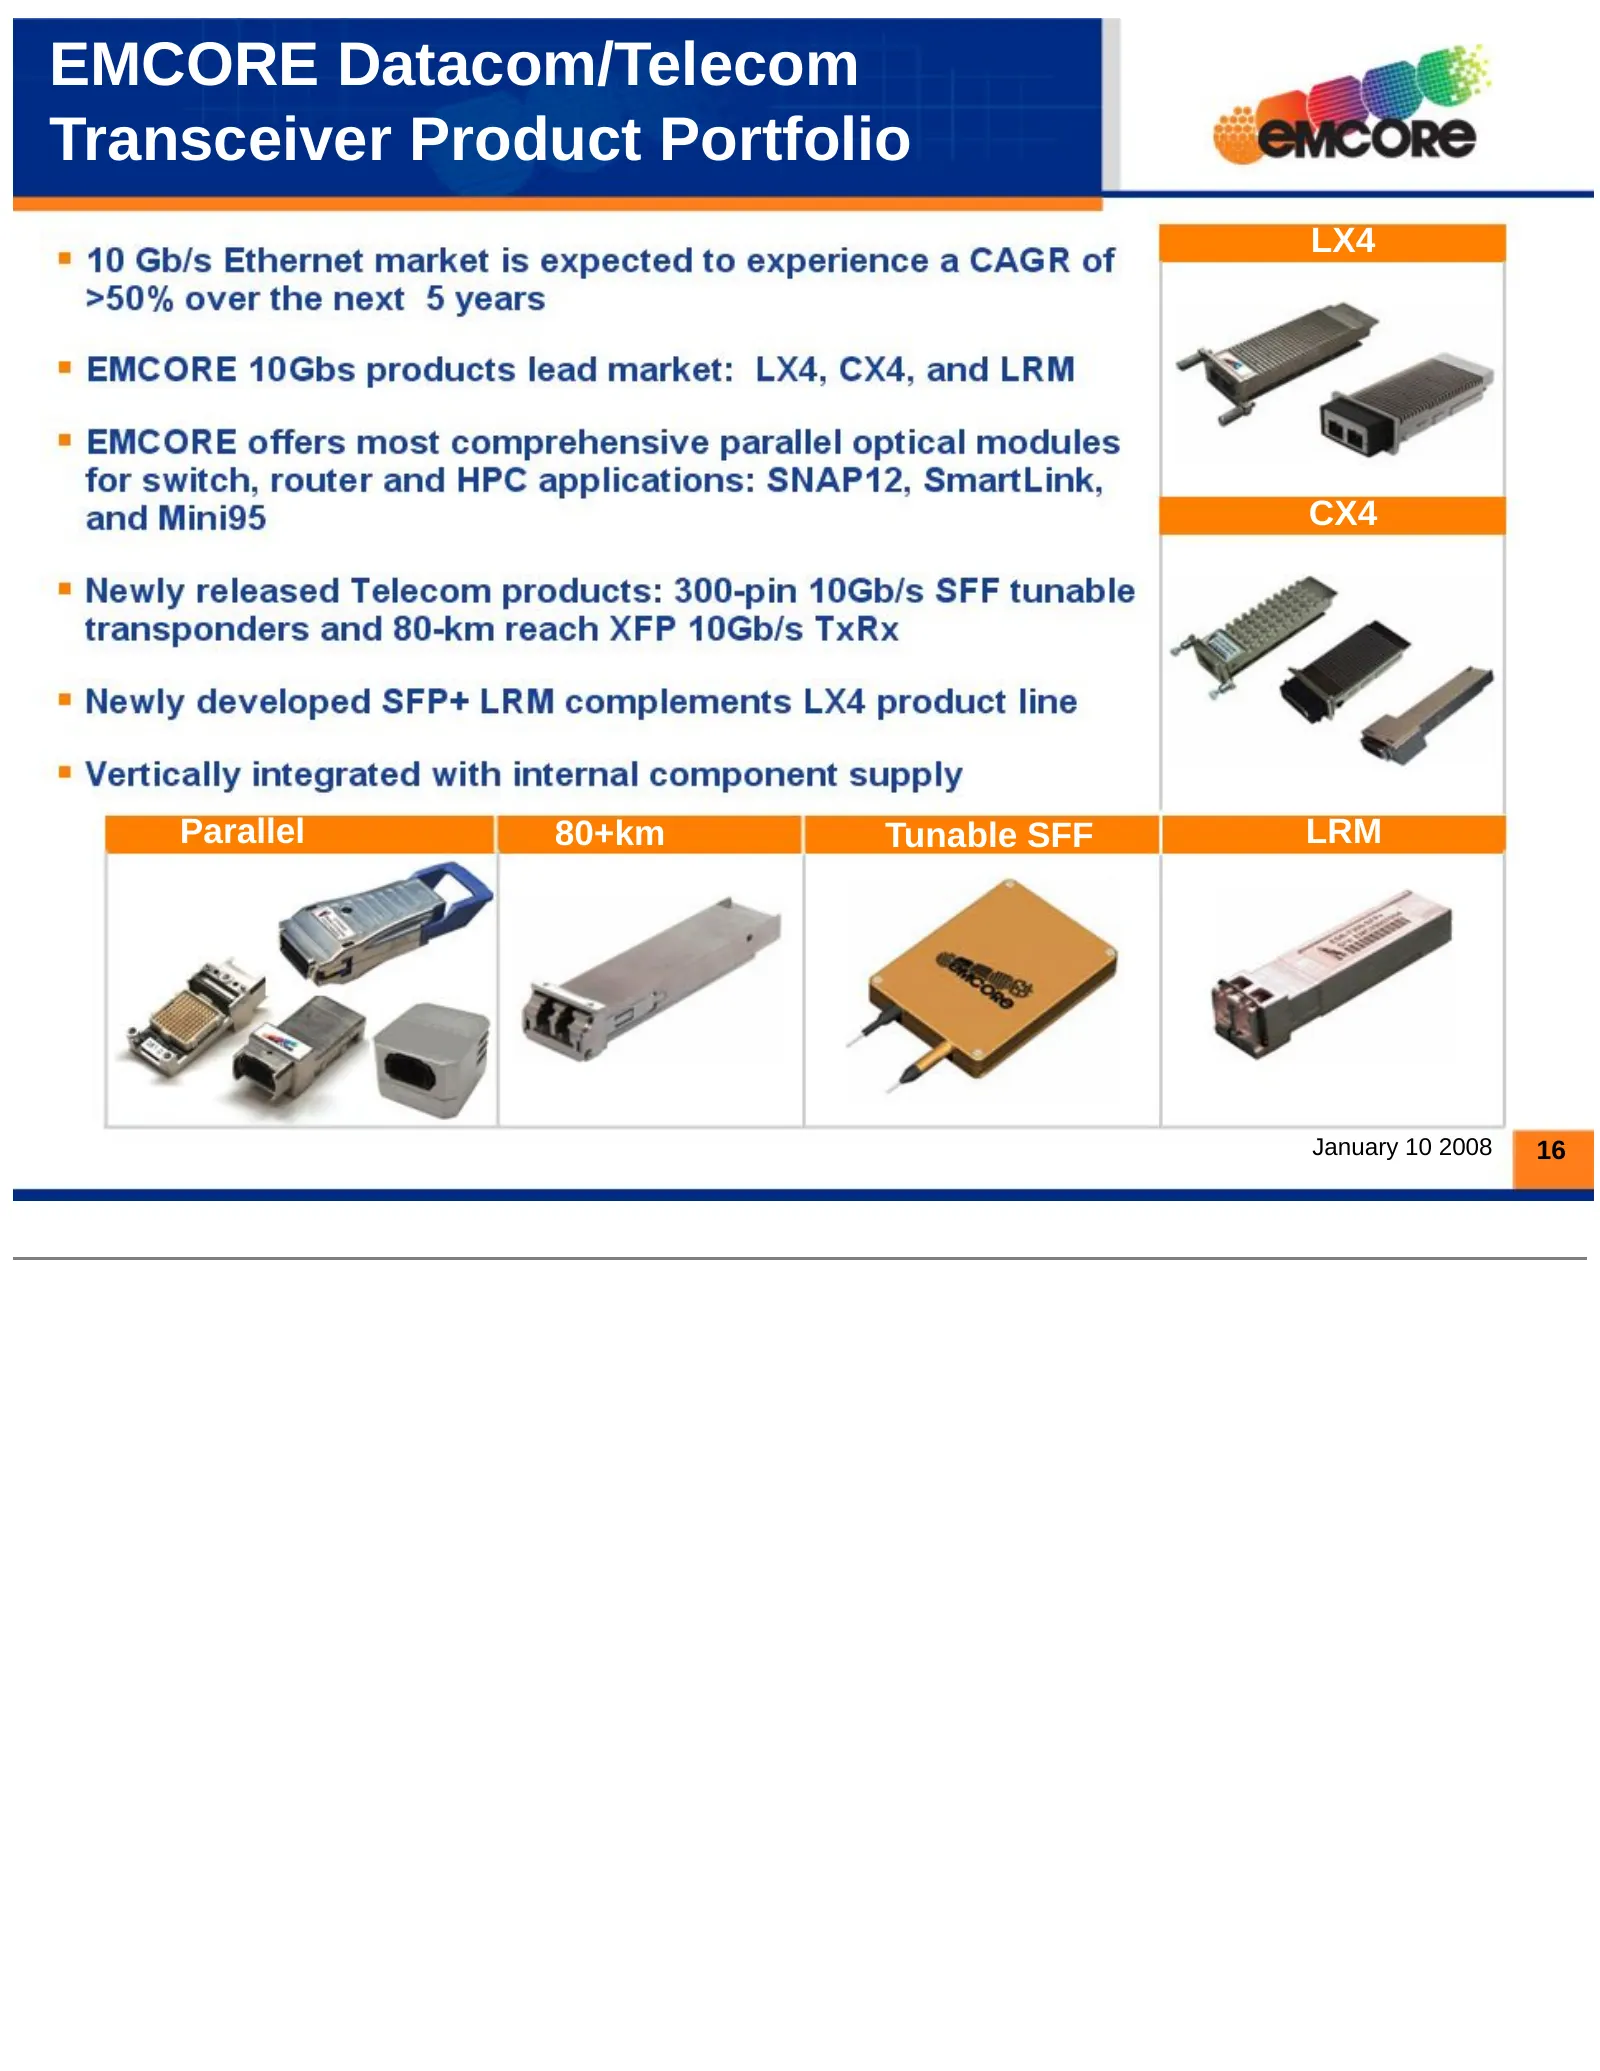
EMCORE Datacom/Telecom Transceiver Product Portfolio LX4 CX4 Parallel 80+km Tunable SFF LRM Optics XFP SFP+ January 10 2008 16
Slide 17
Slide 18: Demand for 10G Ethernet Increases
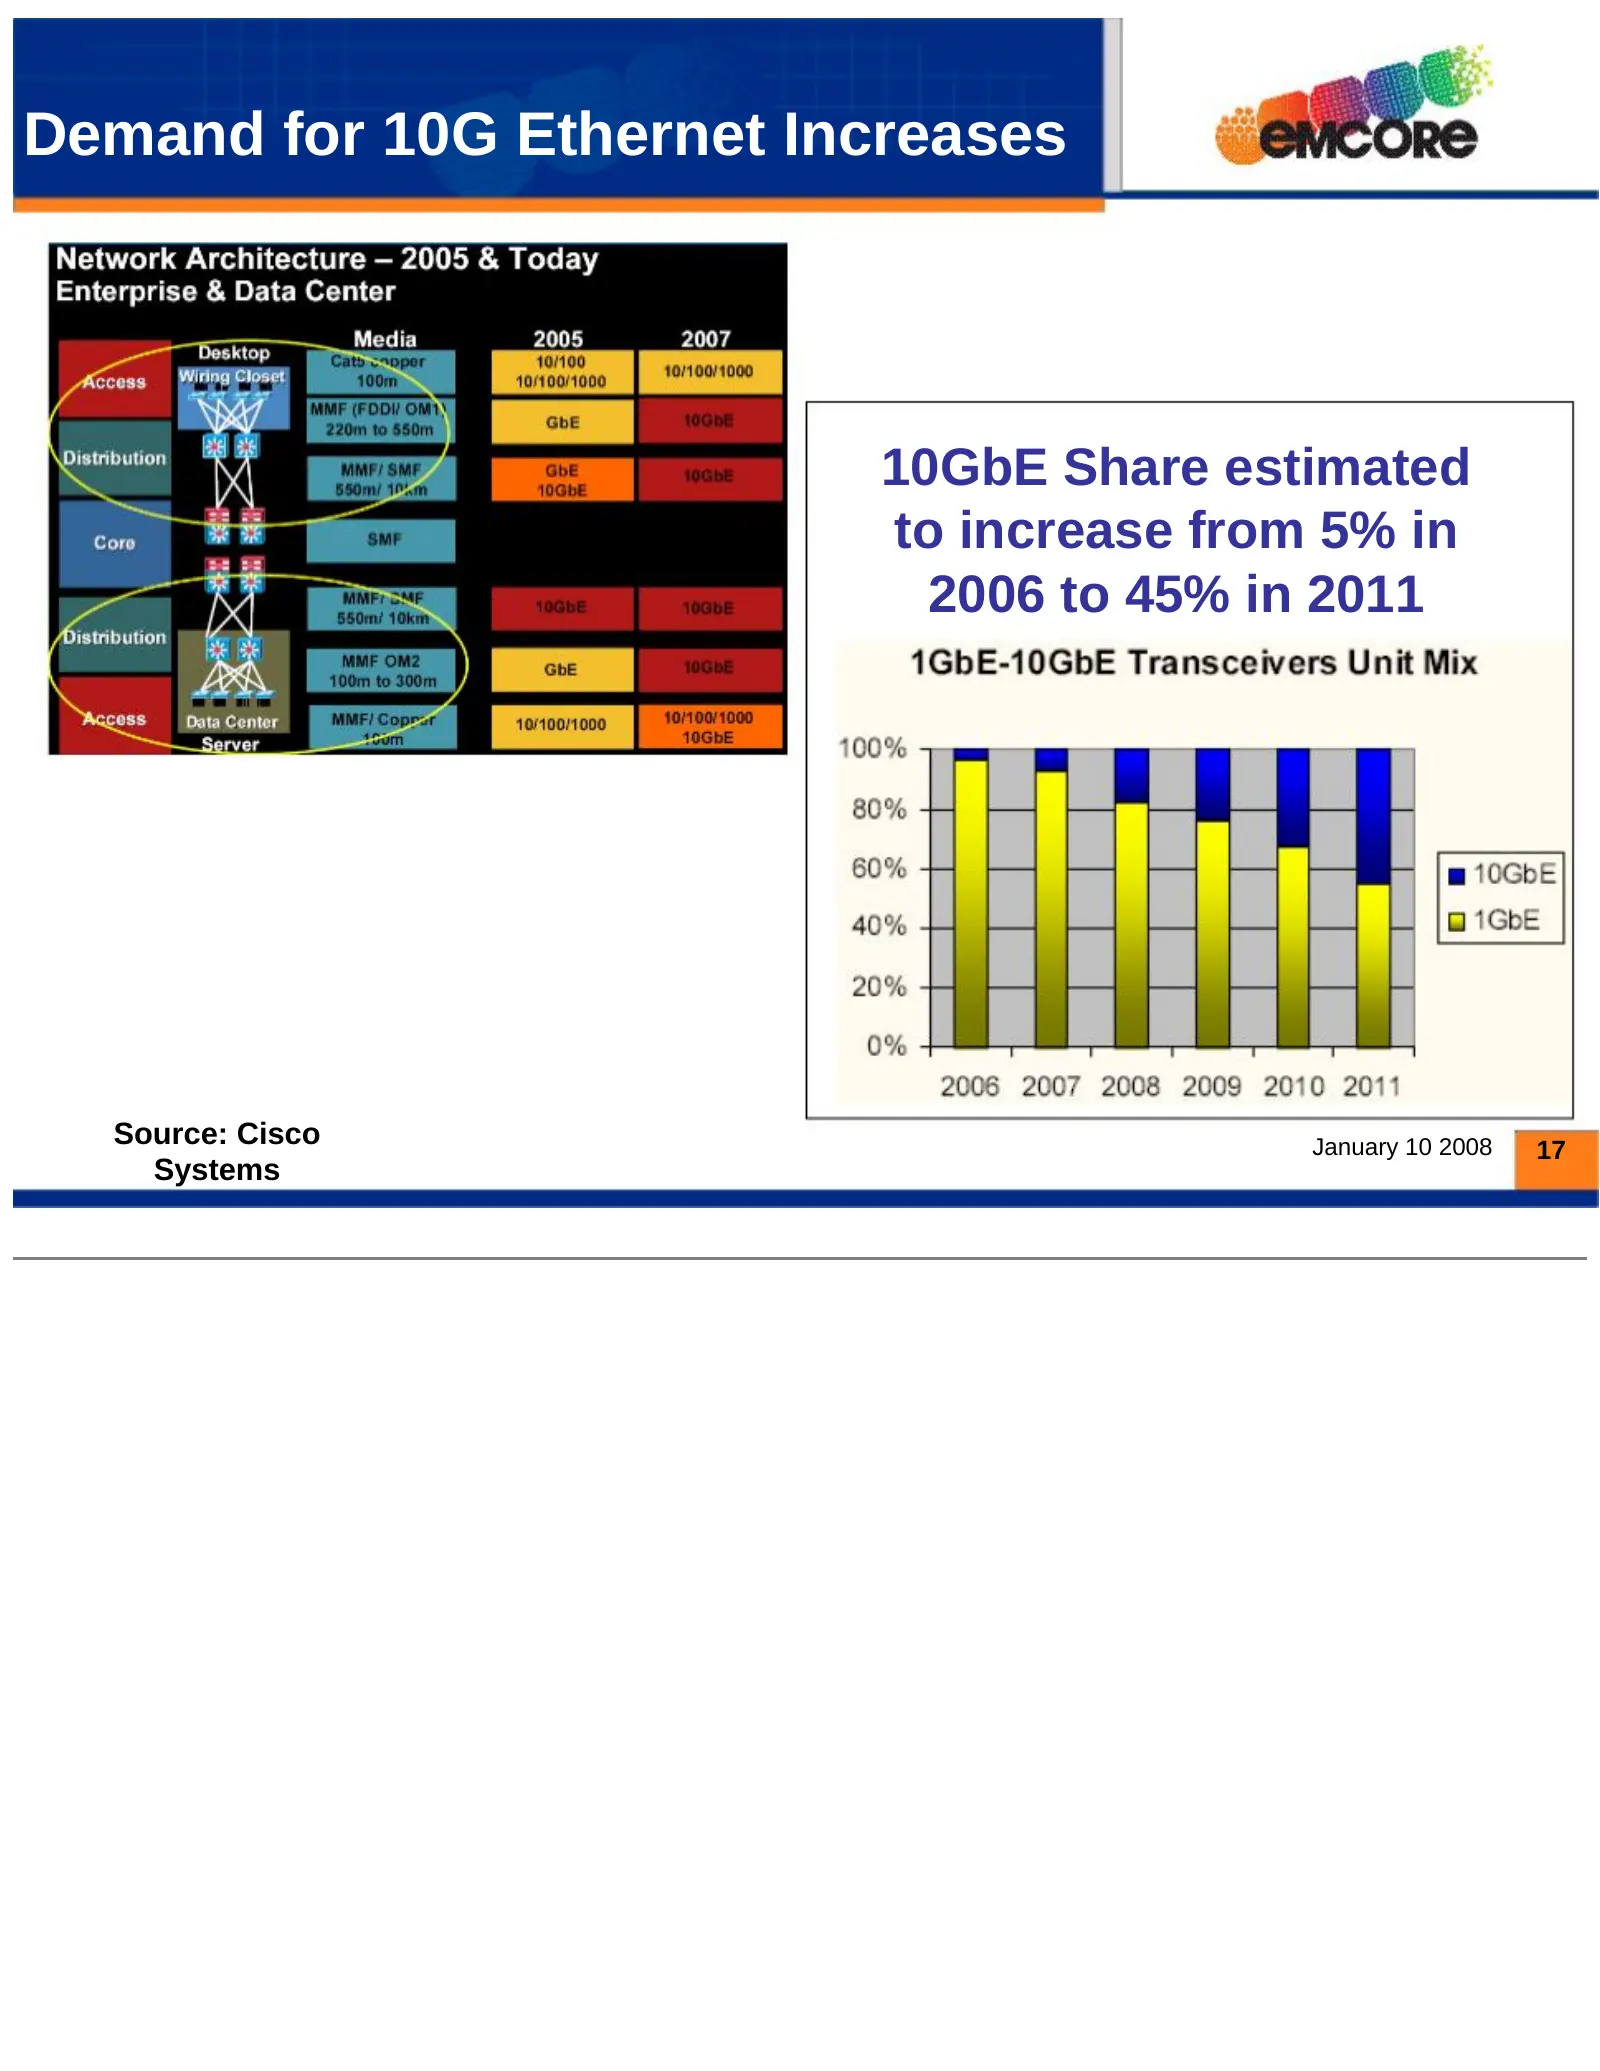
Demand for 10G Ethernet Increases 10GbE Share estimated to increase from 5% in 2006 to 45% in 2011 Source: Cisco January 10 2008 17 Systems
Slide 19: Growth Drivers for EMCORE Datacom/Telecom Business
Growth Drivers for EMCORE Datacom/Telecom Business Product Lines § Leading Supplier of 10Gb/s Ethernet Components and Transceivers § 10Gb/s TOSA/ROSA components for SR § Xenpak LX4/CX4 and X2 CX4, sampling SFP+ SRL, LRM, & LR transceivers § Broadest Portfolio of Parallel Optics Transceivers § 12-lan
Slide 20: Product Lines Acquired from Intel
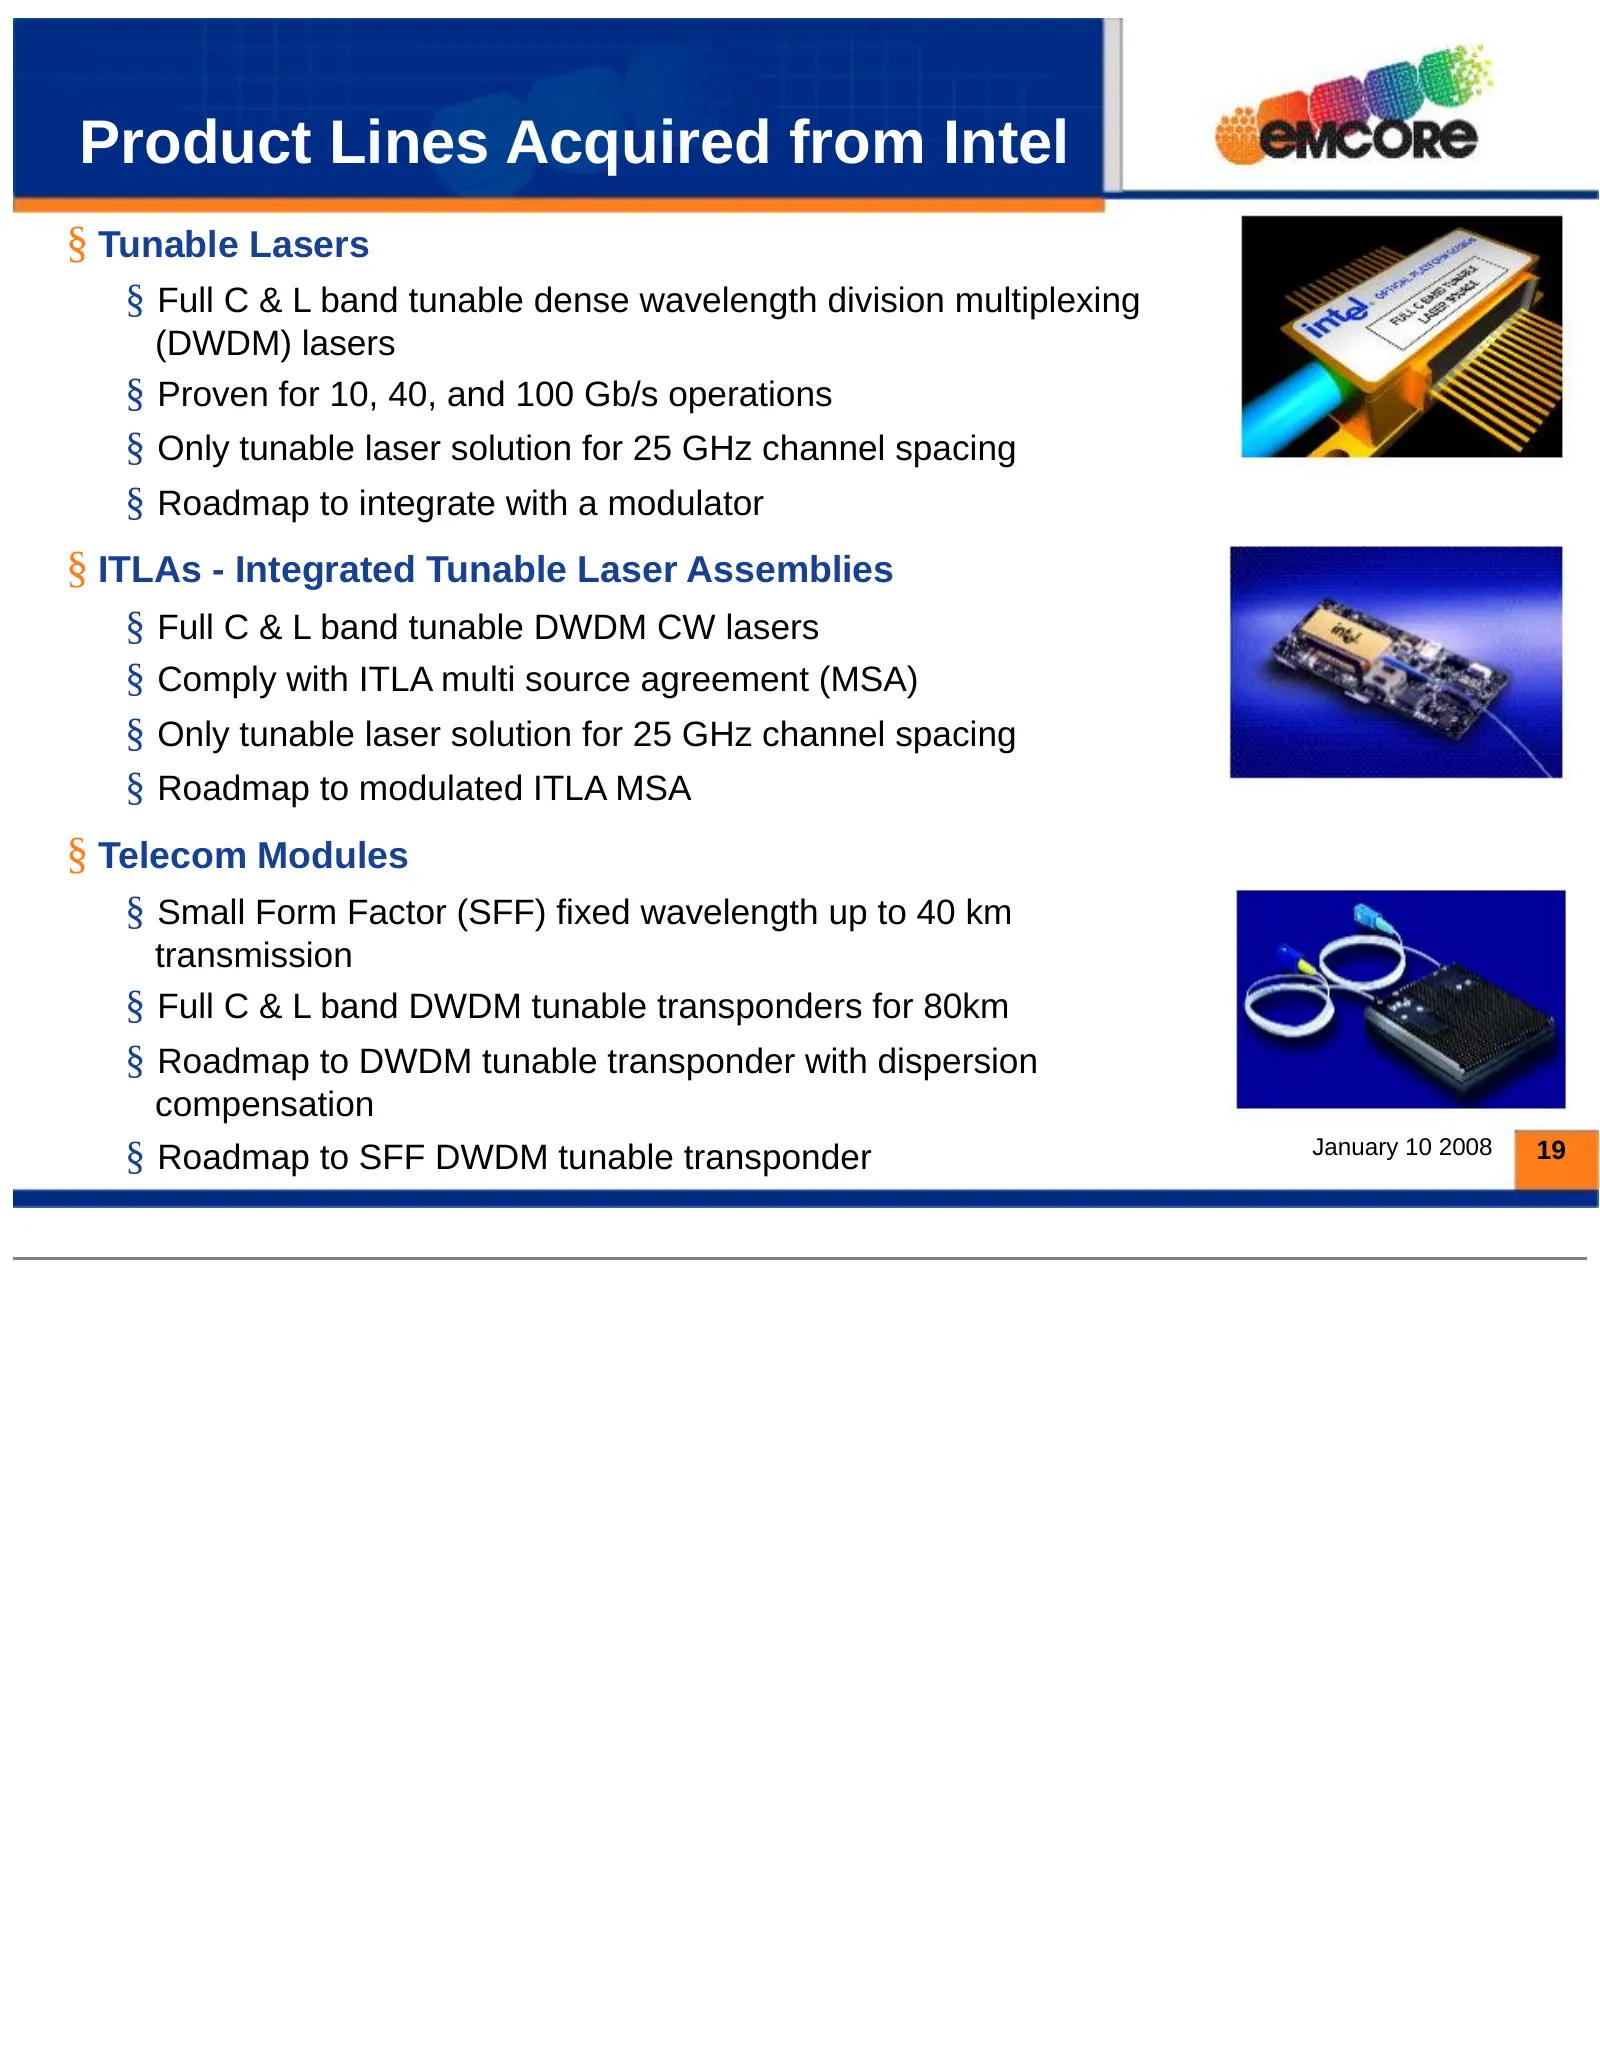
Product Lines Acquired from Intel § Tunable Lasers § Full C & L band tunable dense wavelength division multiplexing (DWDM) lasers § Proven for 10, 40, and 100 Gb/s operations § Only tunable laser solution for 25 GHz channel spacing § Roadmap to integrate with a modulator § ITLAs - Integrated Tunable
Slide 21: Strategic Value and Financial Benefits of Acquiring Intel’s Telecom Optical Asset
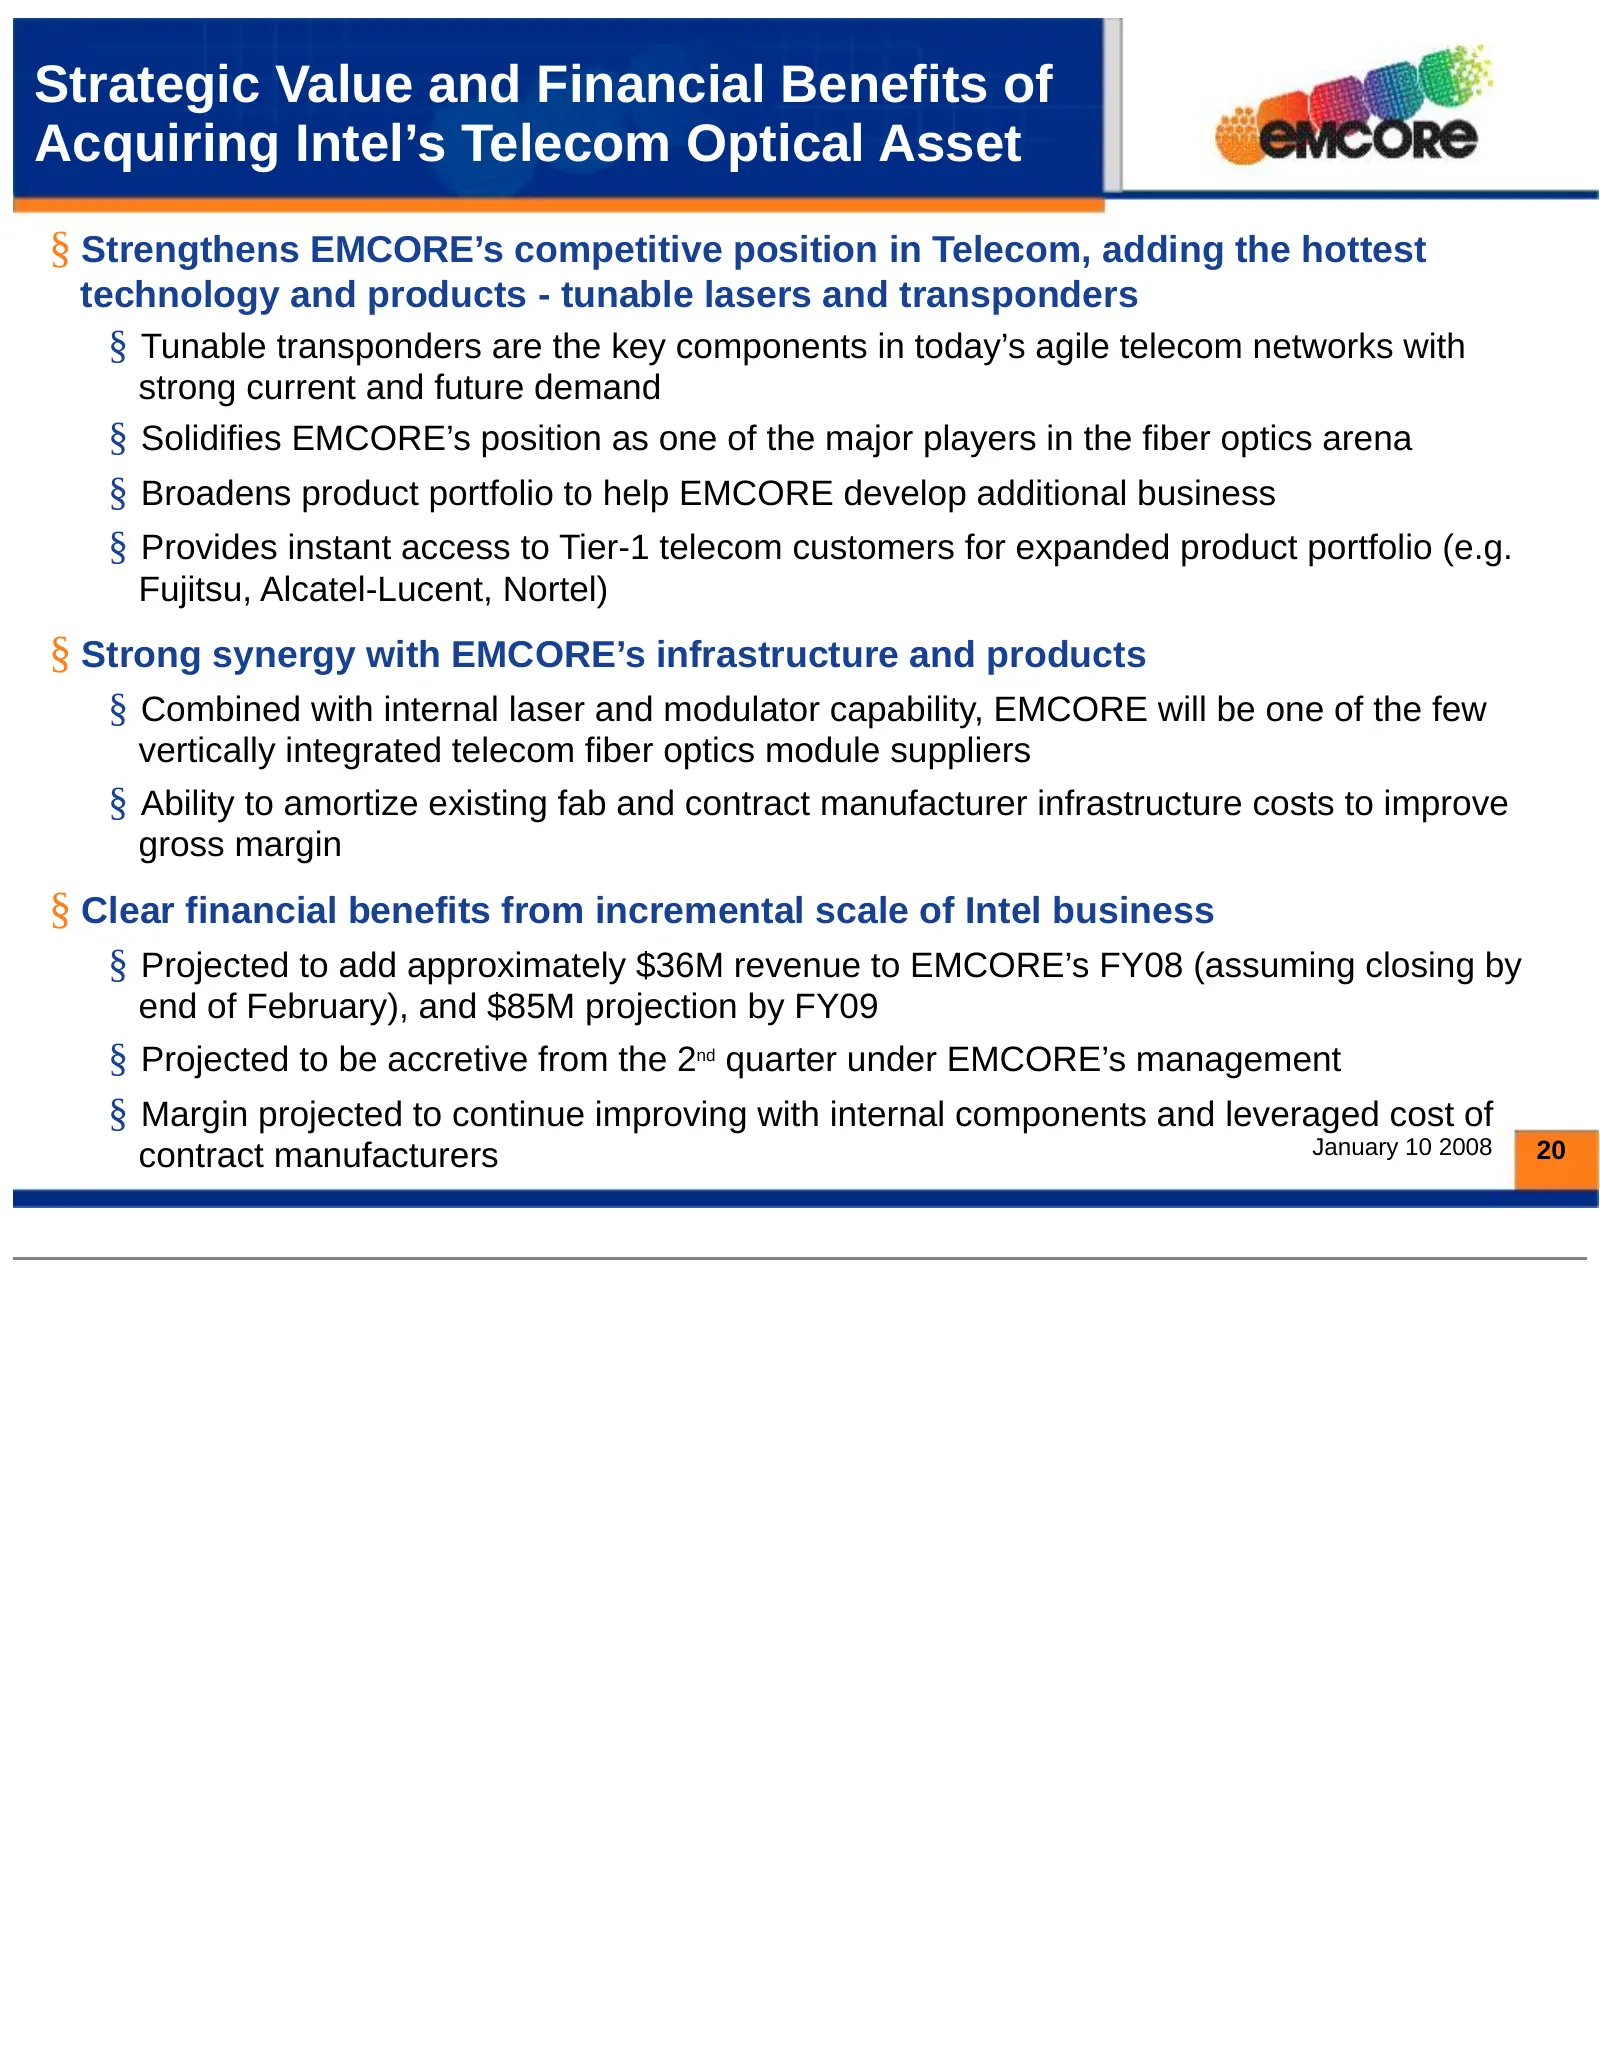
Strategic Value and Financial Benefits of Acquiring Intel’s Telecom Optical Asset § Strengthens EMCORE’s competitive position in Telecom, adding the hottest technology and products - tunable lasers and transponders § Tunable transponders are the key components in today’s agile telecom networks with
Slide 22: Revenue History and Projection from Current Businesses
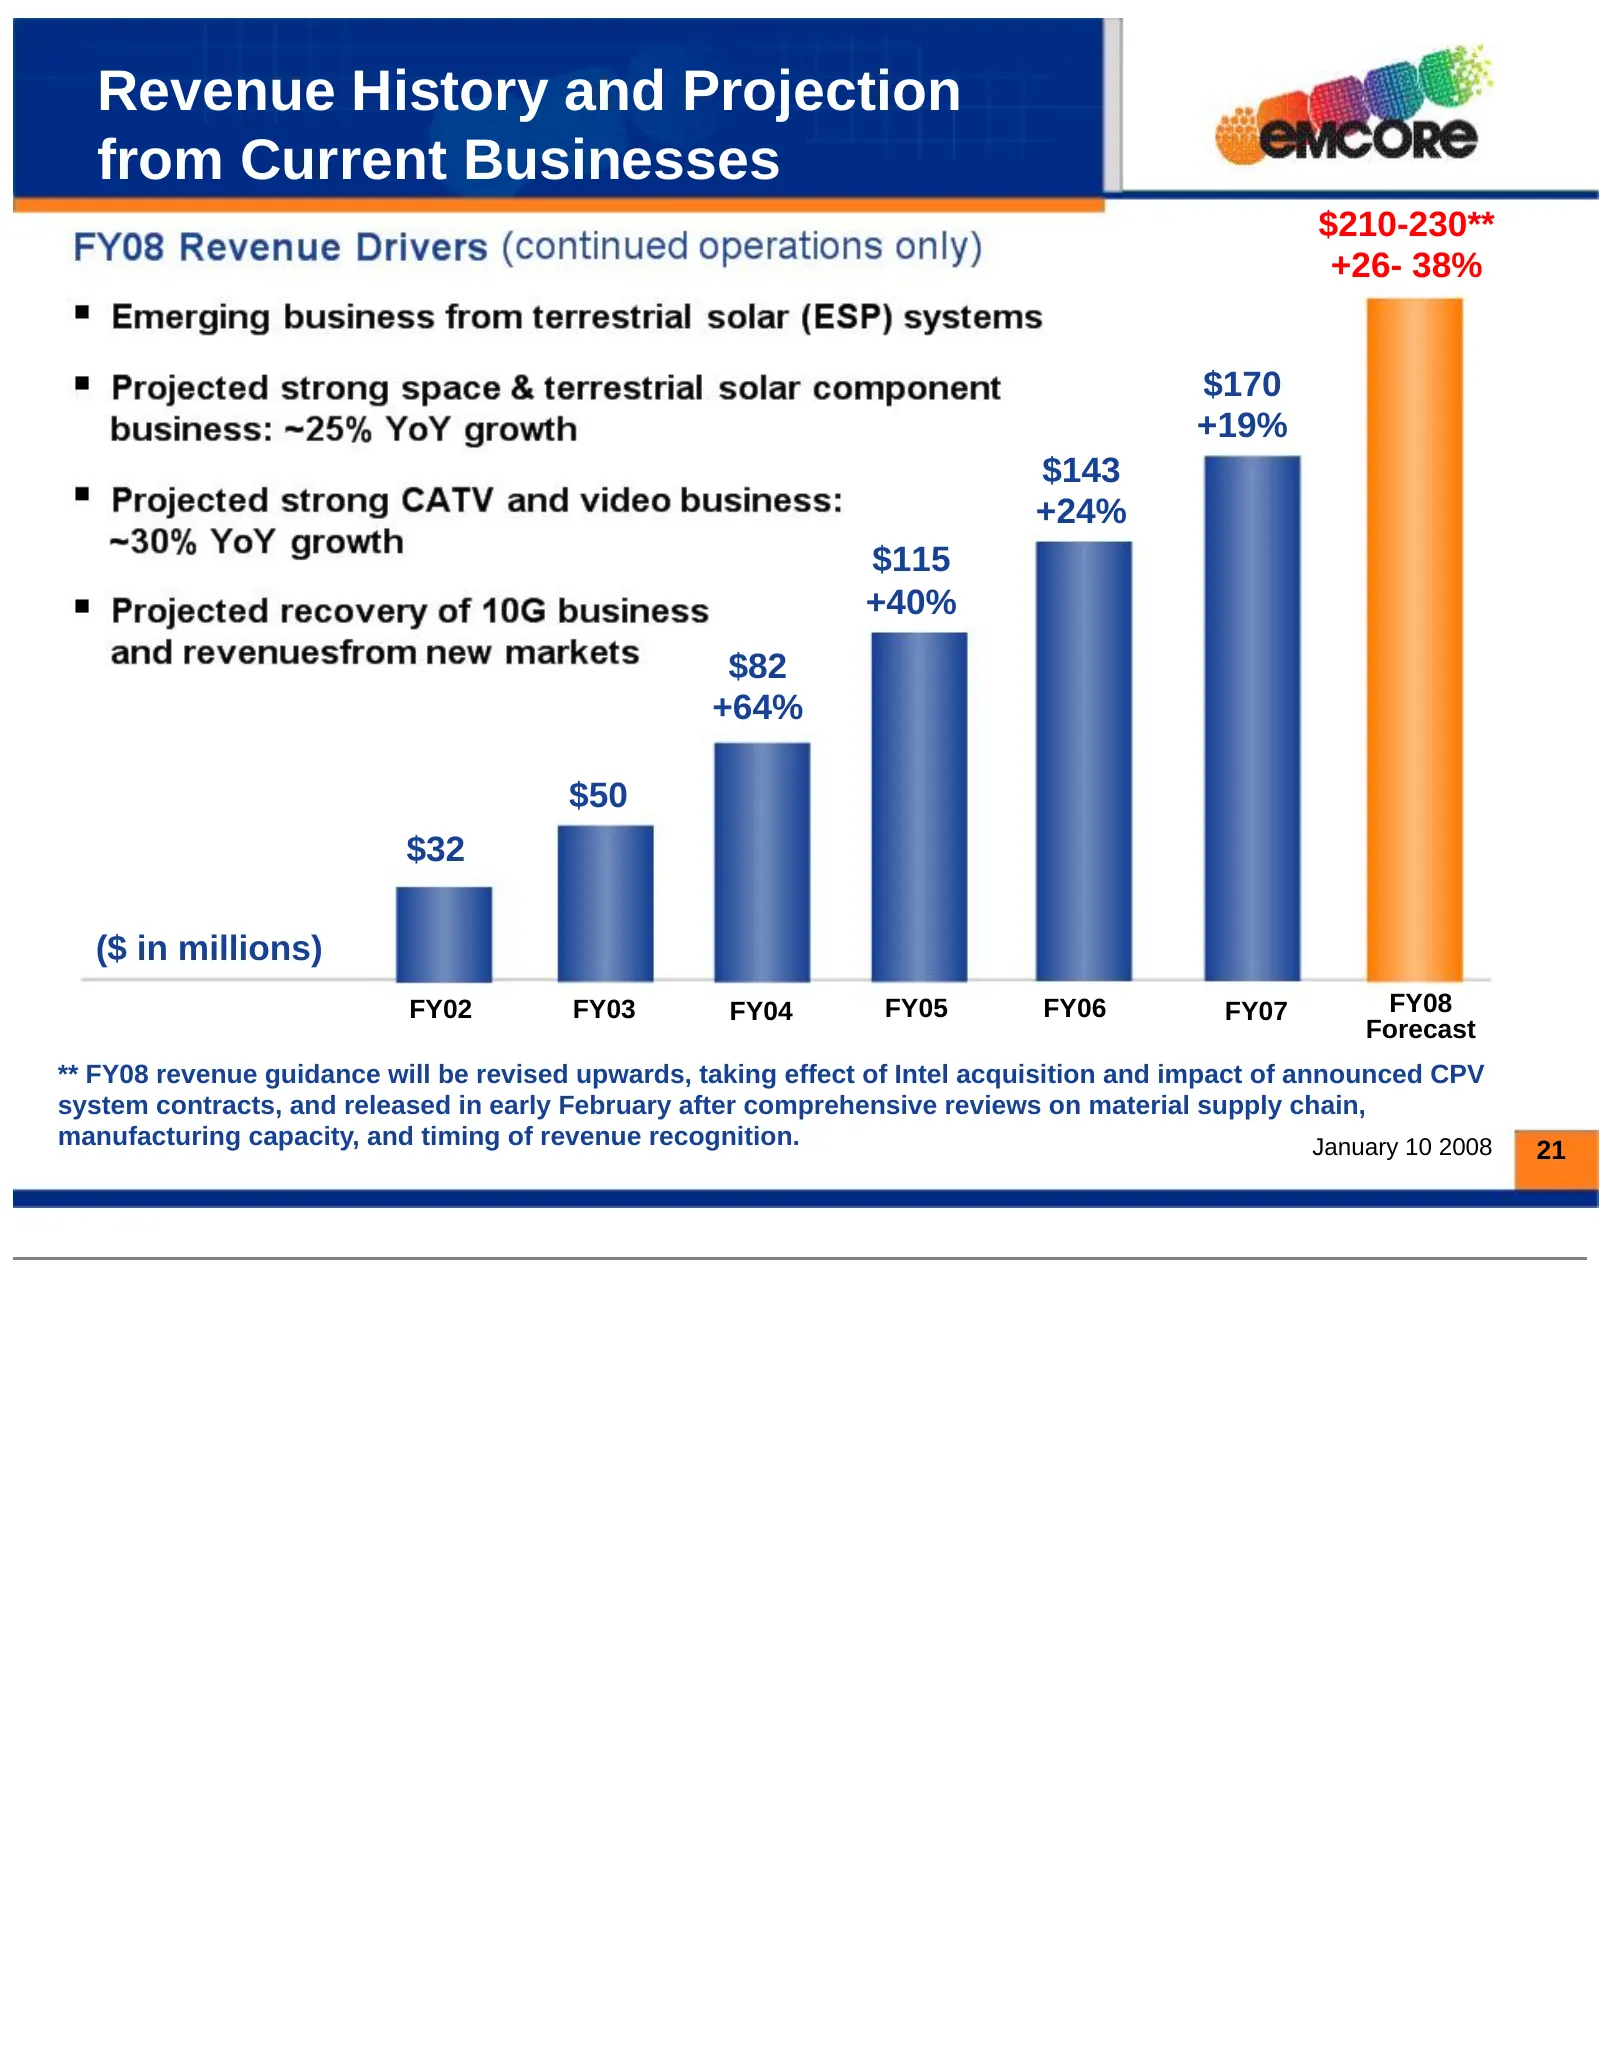
Revenue History and Projection from Current Businesses $210-230** +26- 38% $170 +19% $143 +24% $115 +40% $82 +64% $50 $32 ($ in millions) FY02 FY03 FY04 FY05 FY06 FY07 FY08 Forecast ** FY08 revenue guidance will be revised upwards, taking effect of Intel acquisition and impact of announced CPV syste
Slide 23: EMCORE Corporation
January 10 2008 EMCORE Corporation 10th Annual Needham Growth Stock Conf January 11, 2007 New York City Reuben F. Richards, Jr. Chief Executive Officer Chris Larocca, VP and GM, EMCORE Broadband 22 Fiber Optics Division
Slide 24
Source: SEC EDGAR · 8-K filed Jan 11, 2008
More decks from EMCORE Corporation
 Proxy Contest (February 2018)18 slides · Feb 27, 2018
 13th Annual Needham Growth Conference (January 2011)20 slides · Jan 12, 2011
 2010 SRA Annual Fall Growth Stock Conference15 slides · Oct 26, 2010
 AeA Financial Conference 200822 slides · Nov 3, 2008
 Roth Capital Growth Conference 200725 slides · Sep 6, 2007
 CEUT Emerging Growth Conference (July 2007)24 slides · Jul 11, 2007