Plains Exploration & Production Company
Plains Exploration & Production — Goldman Sachs Global Energy Conference 2011
34 slides from Plains Exploration & Production's conference presentation, Jan 10, 2011
Slide 1: Goldman Sachs Global Energy Conference
Goldman Sachs Global Energy Conference January 2011 Exhibit 99.1
Slide 2: Corporate Information
Corporate Information Corporate Headquarters Contacts Plains Exploration & Production Company 700 Milam, Suite 3100 Houston, Texas 77002 Forward-Looking Statements This presentation is not for reproduction or distribution to others without PXP’s consent. James C. Flores – Chairman, President & CEO W
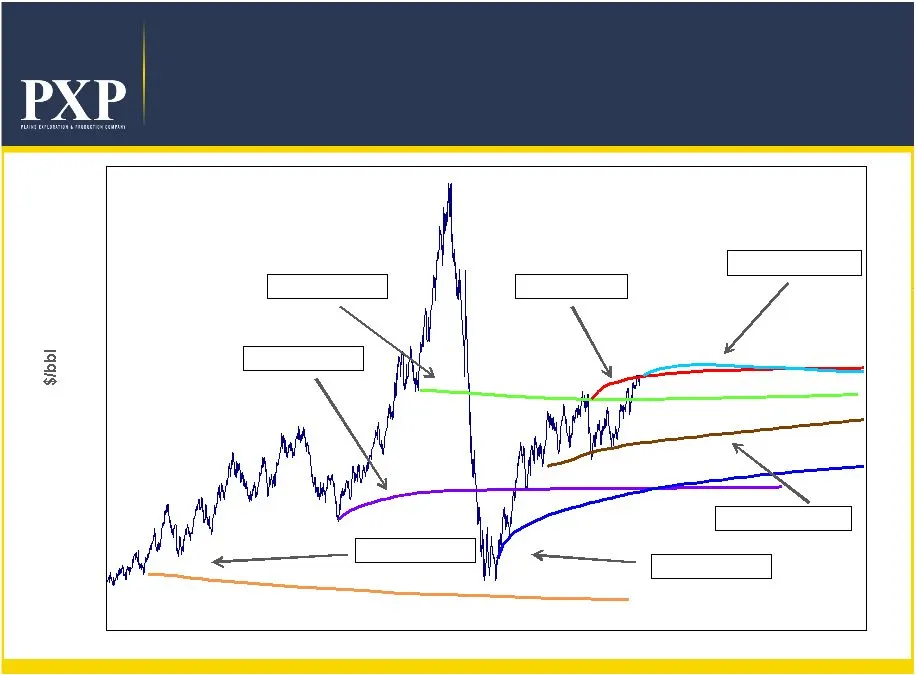
Slide 3: WTI NYMEX Historical Prices and Forward Curves ($/bbl)
WTI NYMEX Historical Prices and Forward Curves ($/bbl) Source: Goldman Sachs, NYMEX June 29, 2004 February 2, 2009 December 31, 2010 April 23, 2010 September 25, 2009 February 6, 2008 January 22, 2007
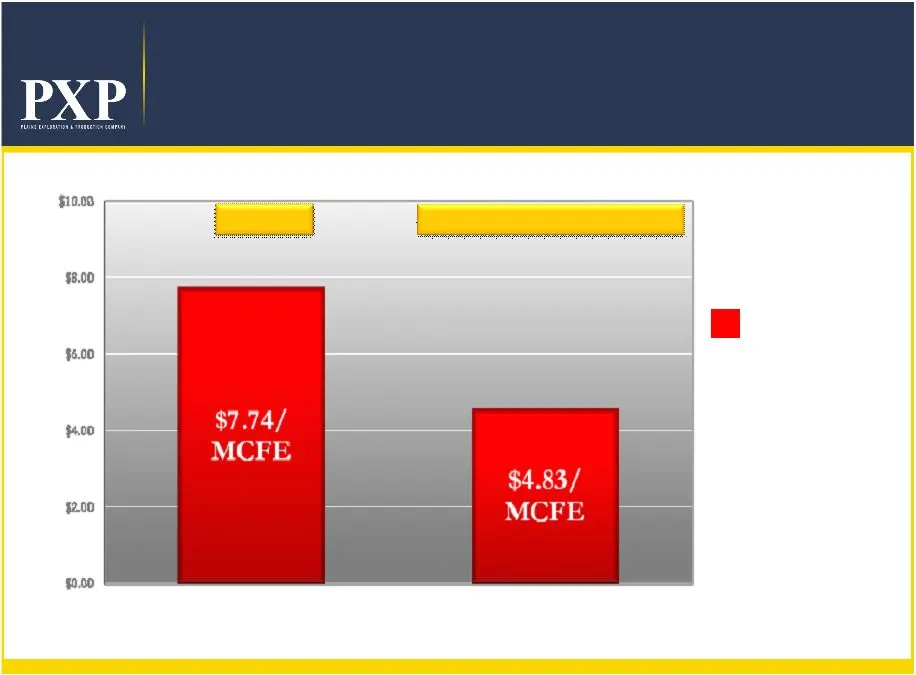
Slide 4: Revenue Per MCFE
Revenue Per MCFE 3Q 2010 Revenue Per MCFE (3) PXP Gas Peer Group Avg. (1)(2) (1) Revenues for non oil and gas producing operations servicing third parties not included. (2) Peer group average includes the following peers: COG, HK, RRC, SD, UPL. Source: Company filings. (3) Excludes the impact of der
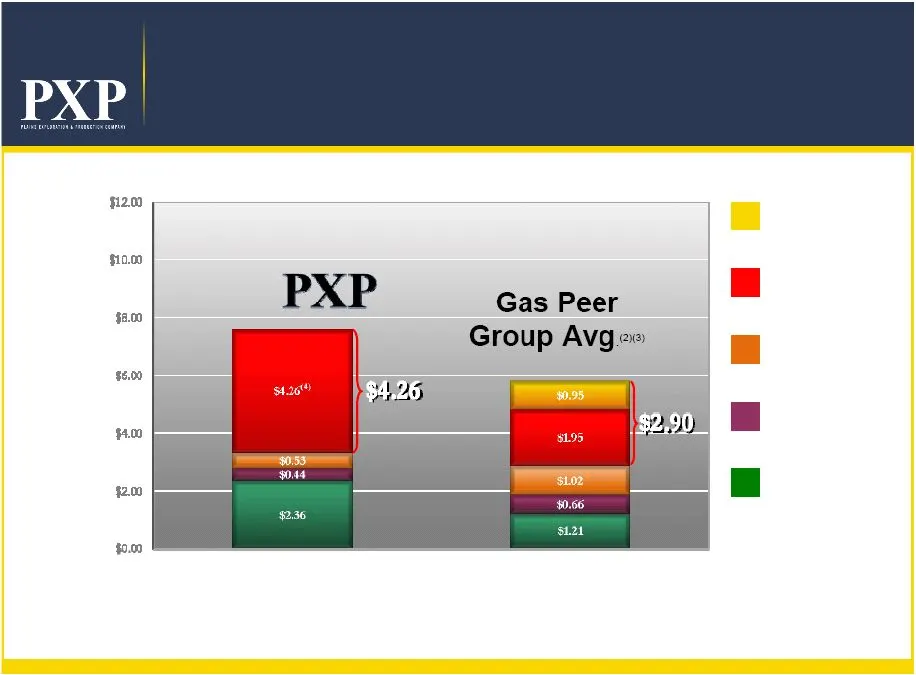
Slide 5: Debt-Adjusted Cash Operating Margin
Debt-Adjusted Cash Operating Margin (1)(8) 3Q 2010 $/Mcfe Derivatives Margin (Excl. Derivatives) Interest (7) G&A (6) Production Costs (5) (1) Debt-Adjusted Cash Operating Margin calculated as revenue (excluding hedging), less production expenses, less cash G&A (excluding capitalized G&A and noncash
Slide 6: Strong Liquidity With No Near Term Debt Maturities
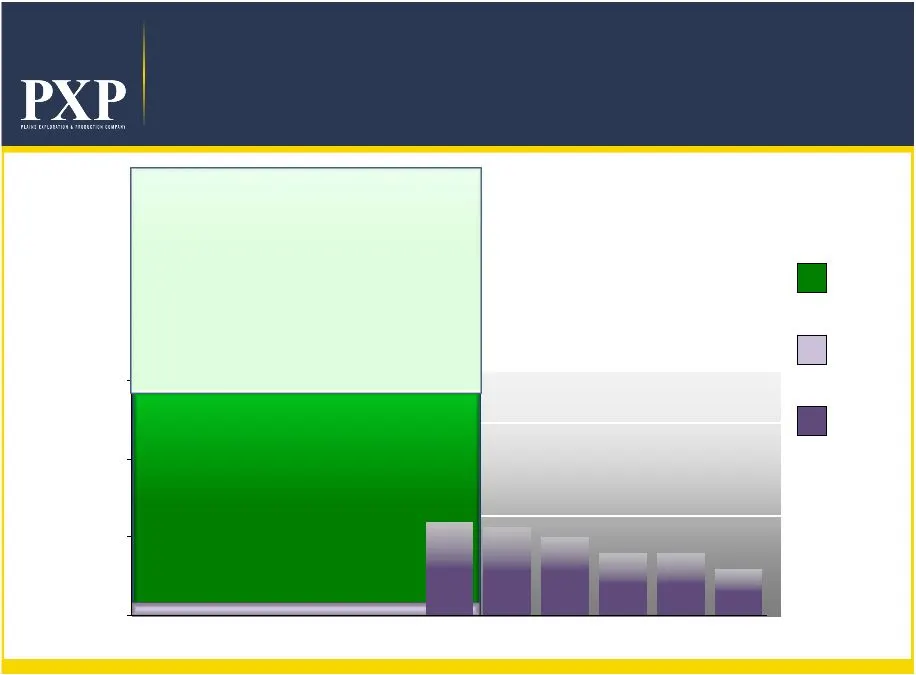
Strong Liquidity With No Near Term Debt Maturities $1.32B (1) Available Liquidity Revolver Availability Senior Notes Revolver Outstanding (1) As of September 30, the revolver had $80 million of borrowings and $1.4 million letters of credit outstanding (prior to Eagle Ford Acquisition). Millions ($)
Slide 7: PXP Today
PXP Today • $6.5 billion enterprise value (1) • 360 MMBOE proved reserves YE 2009 • 90.6 MBOE per day production for 3Q 2010 • +1.6 billion BOE resource potential (2) • 140.1 million shares outstanding (3) • 45% net debt-to-total capitalization (3)(4) (1) Reflects stock price and total debt as of Se
Slide 8: PXP Operational Plan
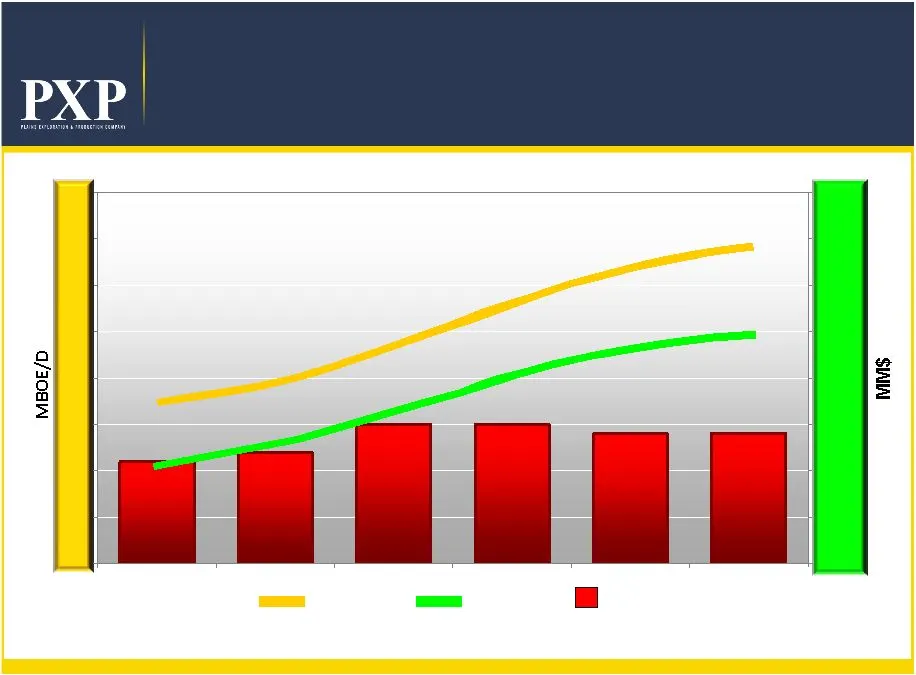
$1400 MM $1400 MM $1100 MM $1500 MM $1200 MM $1500 MM PXP Operational Plan $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 $4,000 PXP Net Production PXP Net Cash Flow (1)(2) Capital Cash Flow Production (1) Net revenue minus net expenses. (2) Assumes Strip pricing in 2010, $85/Bbl of oil and natur
Slide 9: Proved Reserves Target Growth
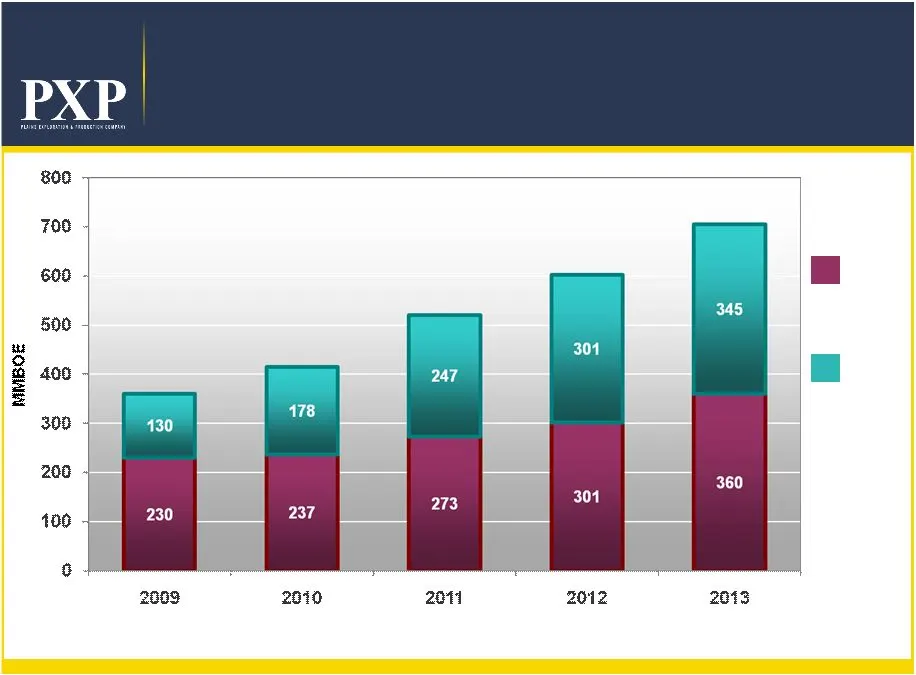
Proved Reserves Target Growth 64% 53% 57% 50% 51% 64% 53% 57% Proved Developed Proved Undeveloped 50% 51% (1) Illustrates estimated reserves using NYMEX pricing. (1) (1) (1) (1)
Slide 10: Capex Profile
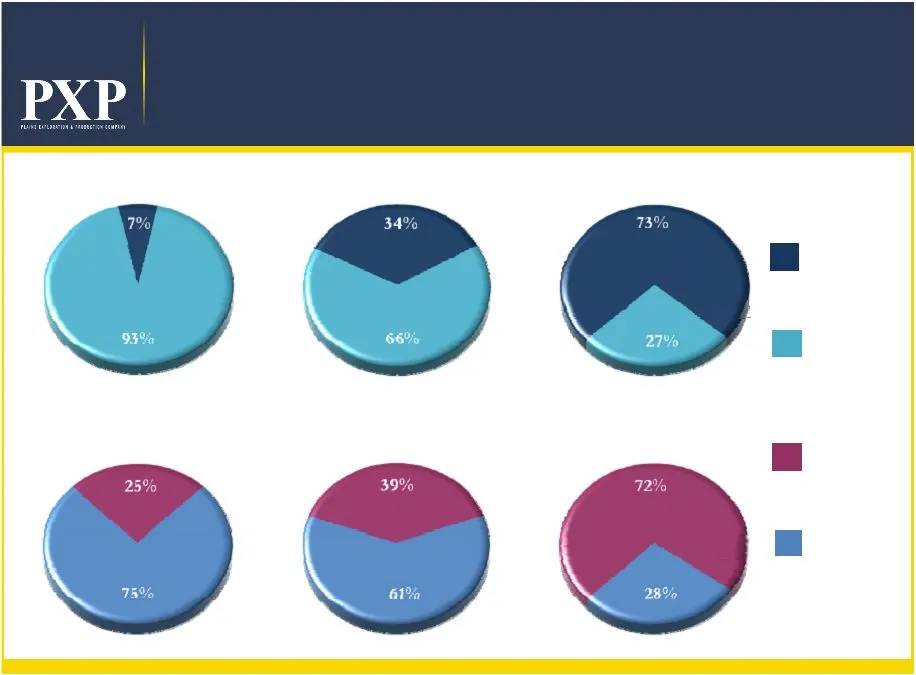
Capex Profile Oil vs. Gas Operated vs. Non-Operated Oil + Liquids Gas + Exploration Operated Non-operated Includes Eagle Ford acquisition and excludes Gulf of Mexico assets, shallow water as of 12/30/2010 and deepwater as of 1/1/2011.
Slide 11: Capital Allocation
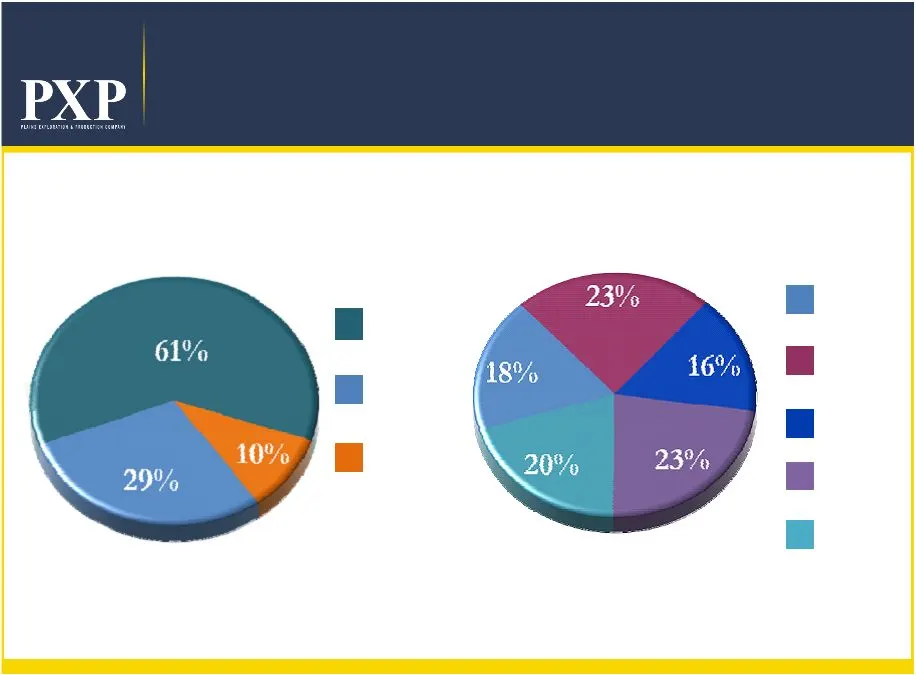
Capital Allocation Development (1) Haynesville California Other Capital (1) Capital Program 2010E $1.1 Billion 2011E $1.2 Billion (1) Includes development, exploitation, real estate, capitalized interest and G&A costs but does not include additional capital for exploratory successes. Exploration cap
Slide 12: Operational Strategy
Operational Strategy Focused Oil Growth Strategy • Operate substantially all oil assets • Maintain total company liquids volumes between 50% and 60% of total production • Hedging strategy protects high oil margins that preserve excellent returns Targeted High Liquids/Natural Gas Strategy • Granite W
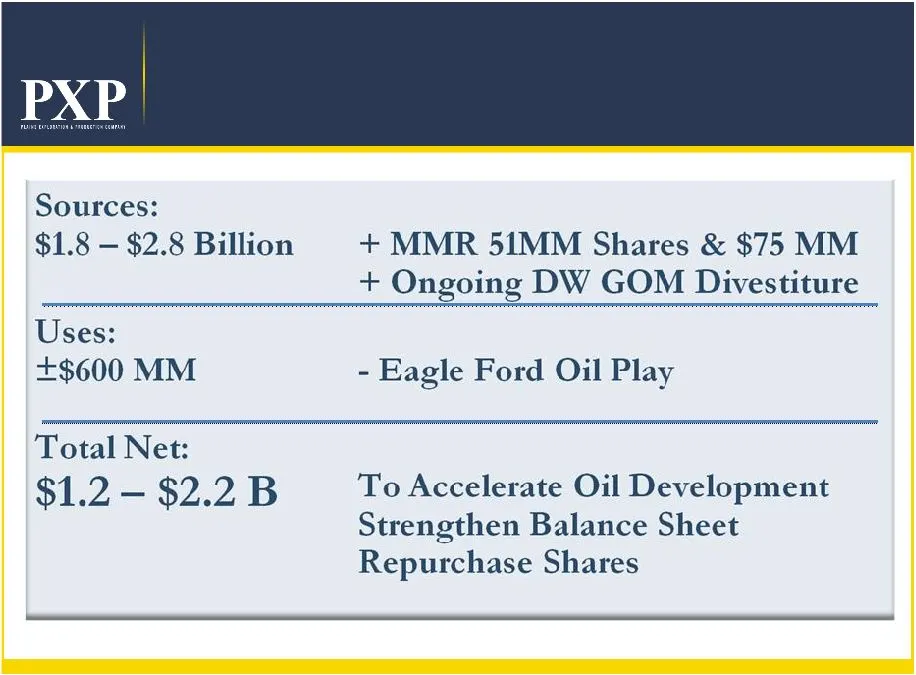
Slide 13: Sources and Uses: $1.8 — $2.8 Billion
Sources: $1.8 — $2.8 Billion Uses: +$600 MM Total Net: $1.2 — $2.2 B + MMR 51MM Shares & $75 MM + Ongoing DW GOM Divestiture - Eagle Ford Oil Play To Accelerate Oil Development Strengthen Balance Sheet Repurchase Shares
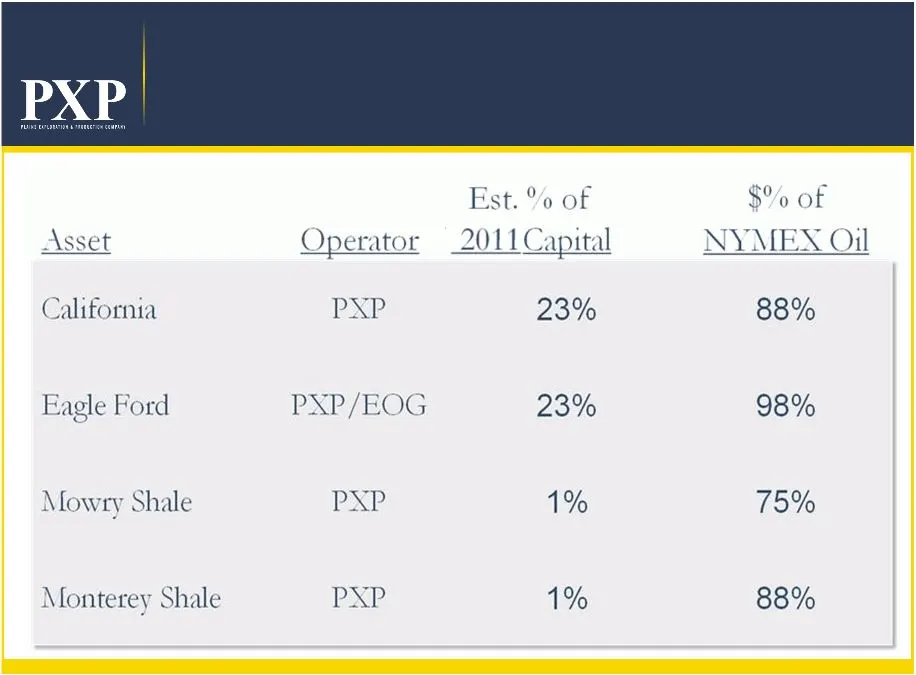
Slide 14: Oil Assets
Asset California Eagle Ford Mowry Shale Monterey Shale Operator Est. % of 2011 Capital $% of NYMEX Oil PX PXP 2/EOG XP XP 23% 23% 1% 1% 88% 98% 75% 88%
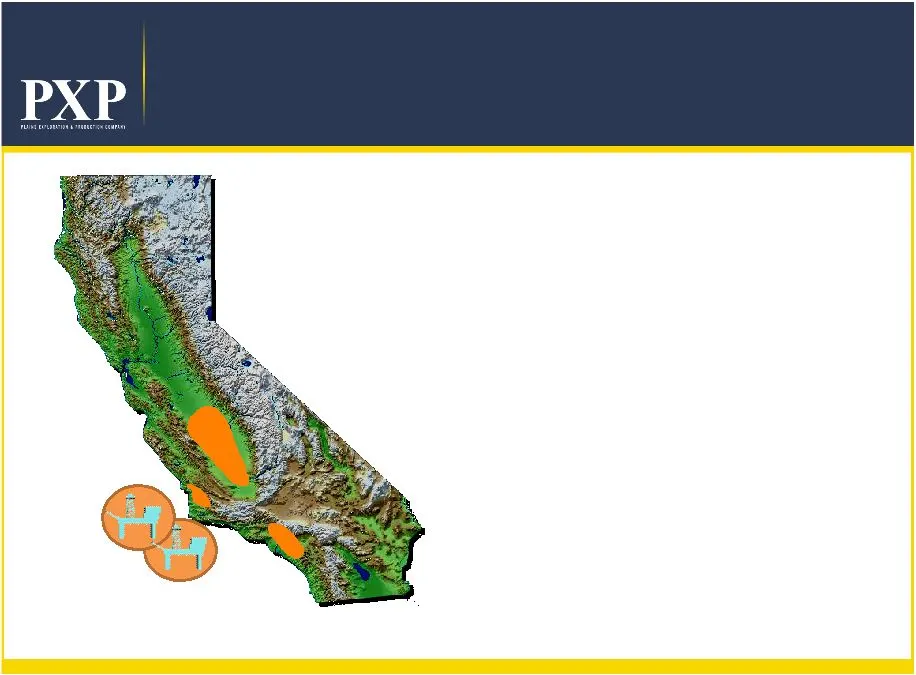
Slide 15: California Onshore/Offshore
California Onshore/Offshore Los Angeles Basin Los Angeles Basin San Joaquin Valley San Joaquin Valley Arroyo Grande Arroyo Grande Pt Pedernales Pt Arguello • 215 MMBOE Net Proved Reserves • 275 MMBOE Net Development Resource Potential • 68% Proved Developed • 2009 Capex $92 MM; 2010E Capex $166 MM •
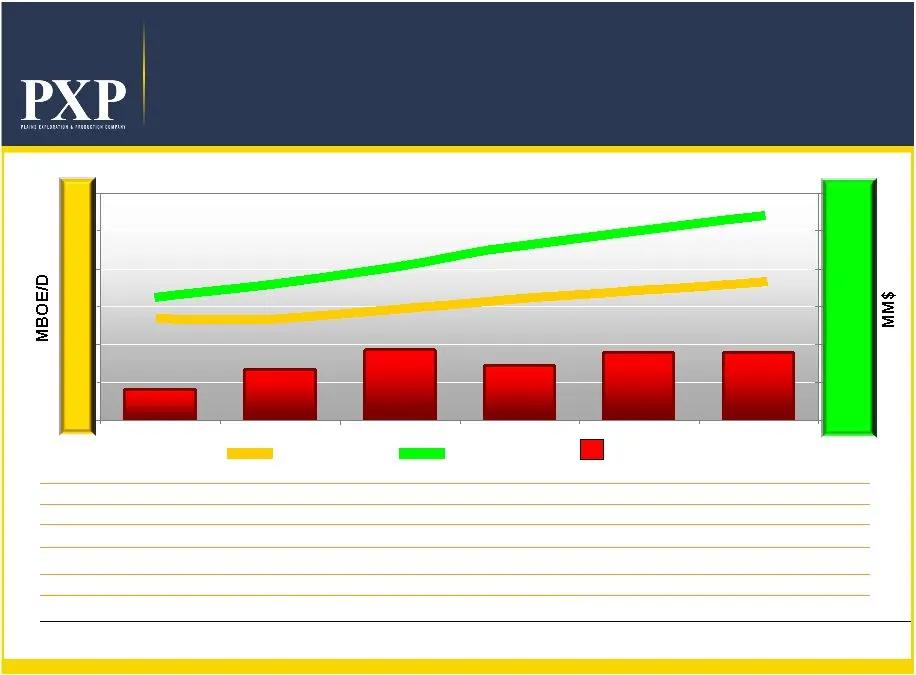
Slide 16: California Operational Plan
California Operational Plan $358 MM $359 MM $166 MM $291 MM $271 MM $371 MM January 1, 2010 Project Cost Forward F&D: $9.87/BOE (2) PXP Interest: 98% WI / 86% NRI Potential Net Locations: 2,500+ Proved Net Reserves: 215 MMBOE Net Development Resource Potential: 275 MMBOE Average Gross Well Cost: $1.
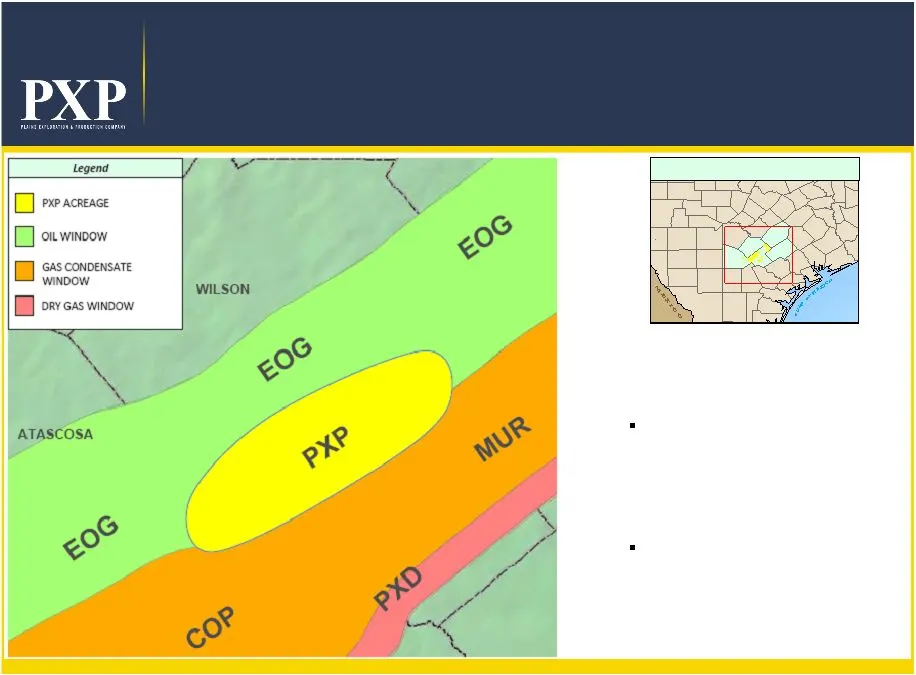
Slide 17: Eagle Ford Horizontal Oil Play
Eagle Ford Horizontal Oil Play Walker Kimble Lee Travis Milam Llano Burnet Mason Gillespie Grimes Matagorda Williamson Fort Bend Brazos Waller Burleson Webb Duval Frio Kerr Edwards Bee Uvalde Bexar Zavala Medina Dimmit La Salle Real Maverick Lavaca Goliad Atascosa Hays Fayette Wharton De Witt Live O
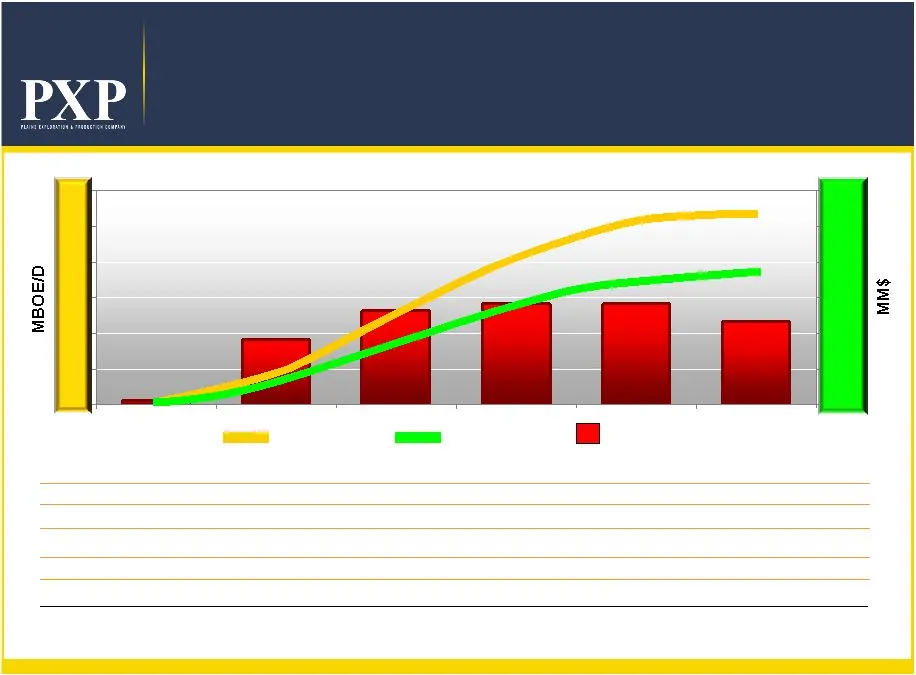
Slide 18: Eagle Ford Operational Plan
$349 MM $424 MM $426 MM $277 MM $396 MM Eagle Ford Operational Plan $17 MM $0 $150 $300 $450 $600 $750 $900 PXP Net Production PXP Net Cash Flow (1)(2) Capital Cash Flow Production (1) Net revenue minus net expenses. (2) Assumes Strip pricing in 2010, $85/Bbl of oil and natural gas pricing of $5.00/
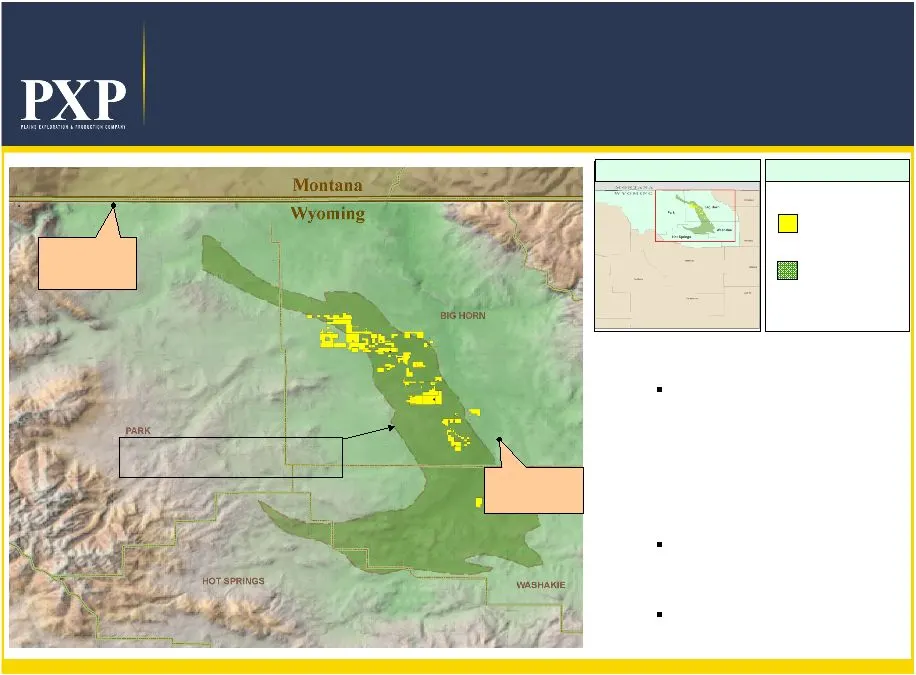
Slide 19: Mowry Shale Horizontal Oil Play Big Horn Basin, Wyoming
Mowry Shale Horizontal Oil Play Big Horn Basin, Wyoming • PXP acreage position 54,000 net acres • Proven Source Rock • Petrophysical characteristics of successful oil shale plays • Depth Range ~6,000' to 10,000' • Shale Thickness Range ~250' to 400' • Currently drilling initial well Legend PXP ACREA
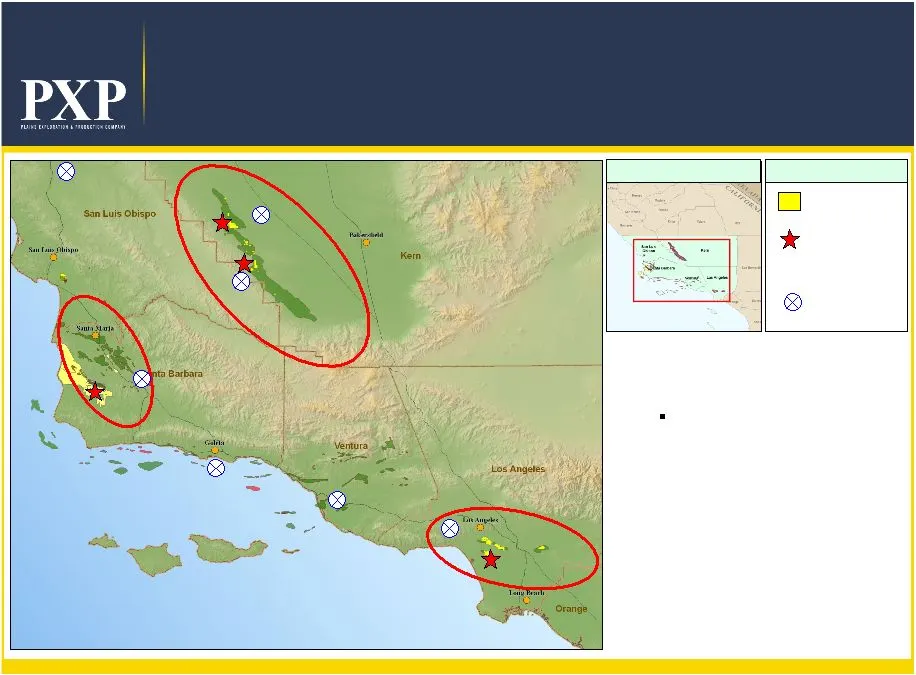
Slide 20: Monterey Shale Oil Play
Monterey Shale Oil Play Legend PXP ACREAGE PXP MONTEREY PRODUCTION OXY DISCOVERY VENOCO ACTIVITY * • PXP acreage position 86,000 net acres • Acquiring 3D seismic data over key assets • Exploratory wells planned in 2011 Location Map Los Angeles Basin Los Angeles Basin Point Pedernales Point Arguello
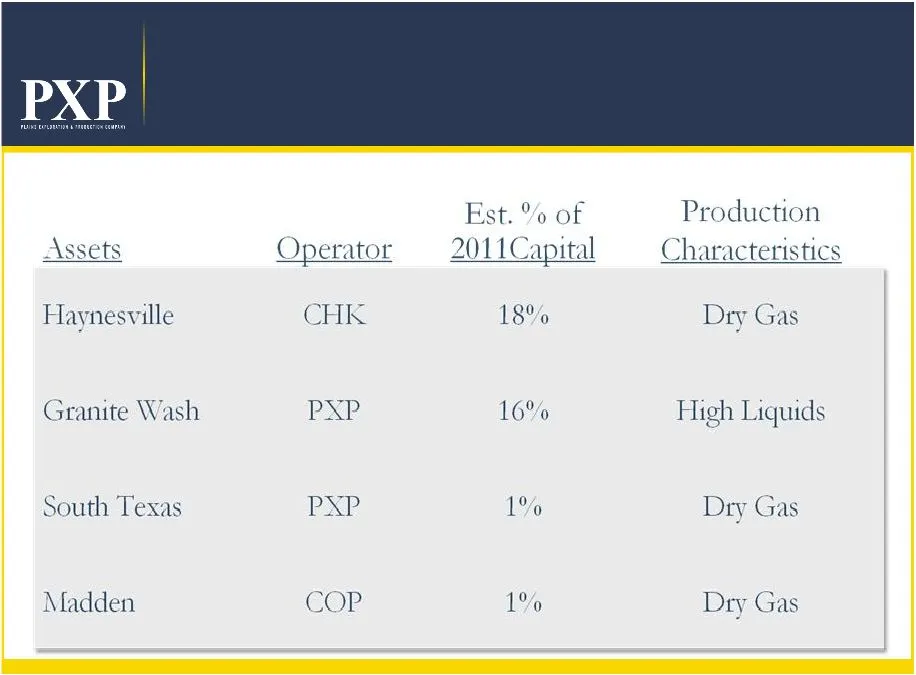
Slide 21: Gas and Liquids Assets
Assets Haynesville Granite Wash South Texas Madden Est. % of Production Operator — 2011. Capital Characteristics CHK 18% Dry Gas PXP 16% High Liquids PXP 1% Dry Gas COP 1% Dry Gas
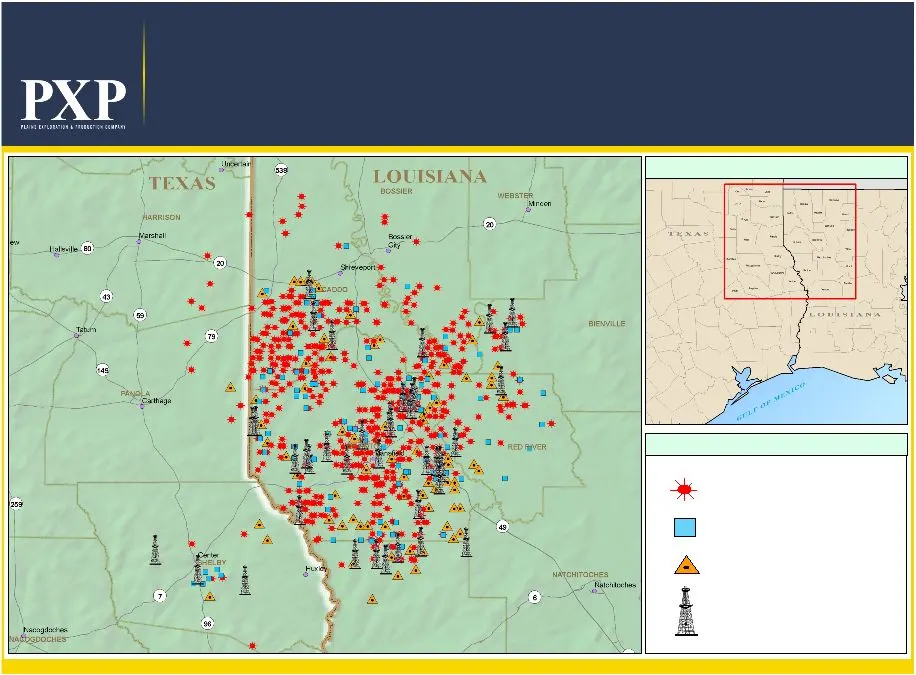
Slide 22: Haynesville Shale Activity Map
Haynesville Shale Activity Map PRODUCING AWAITING COMPLETION 2010 DRILL LOCATIONS ACTIVE DRILLING Location Map Legend
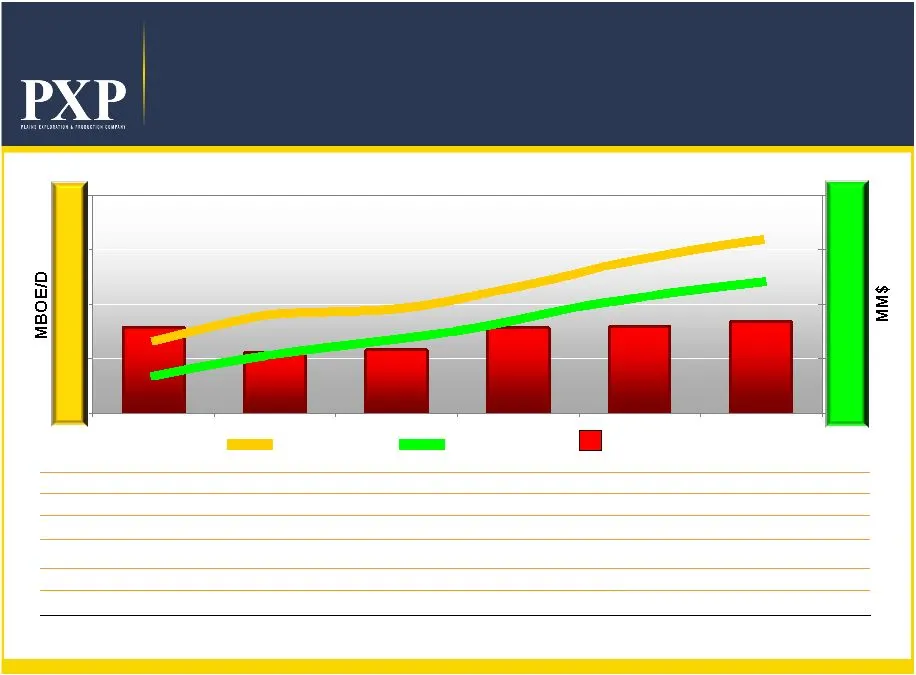
Slide 23: Haynesville Shale Operational Plan
Haynesville Shale Operational Plan $312 MM $319 MM $336 MM $222 MM $232 MM $317 MM PXP Net Production PXP Net Cash Flow (1)(3) $0 $200 $400 $600 $800 January 1, 2010 Project Cost Forward F&D: $8.24/BOE (3) or $1.37/Mcfe (1) Net revenue minus net expenses. (2) Assumes D&C costs for first 4 years = $7
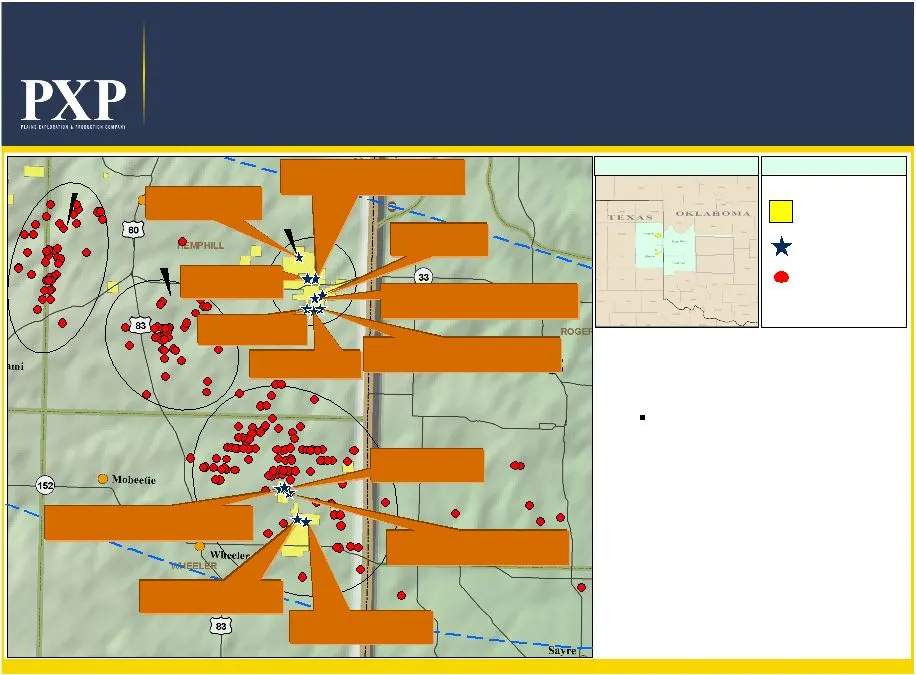
Slide 24: Granite Wash Horizontal Play Recent High-Rate Completions
Granite Wash Horizontal Play Recent High-Rate Completions PXP Hanson #29-2H 19MMCFED PXP Britt #9026H Drilling PXP Thomas #1003H WOC PXP Thomas #903H PXP Sanders #74-1H 15 MMCFED Thomas #1103H WOC JO Well #96-6H WOC PXP Hanson #40-4H PXP Cook #39-2H WOC PXP Hanson #29-3H Drilling Moore #63-6H Drilli
Slide 25: Granite Wash Horizontal Potential Operational Plan
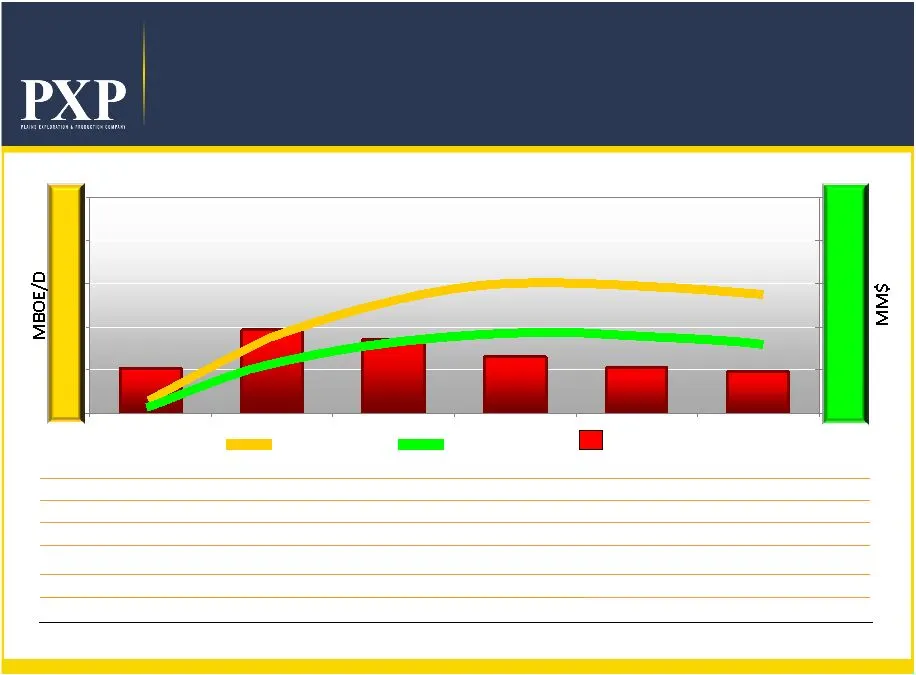
$105MM $106MM $97MM $132MM $193MM $172MM Granite Wash Horizontal Potential Operational Plan $0 $100 $200 $300 $400 $500 PXP Net Production PXP Net Cash Flow (1)(2) (1) Net revenue minus net expenses. (2) Assumes Strip pricing in 2010, $85/Bbl of oil and natural gas pricing of $5.00/MMBtu in 2011, $8
Slide 26: +1.6 Billion BOE Resource Potential
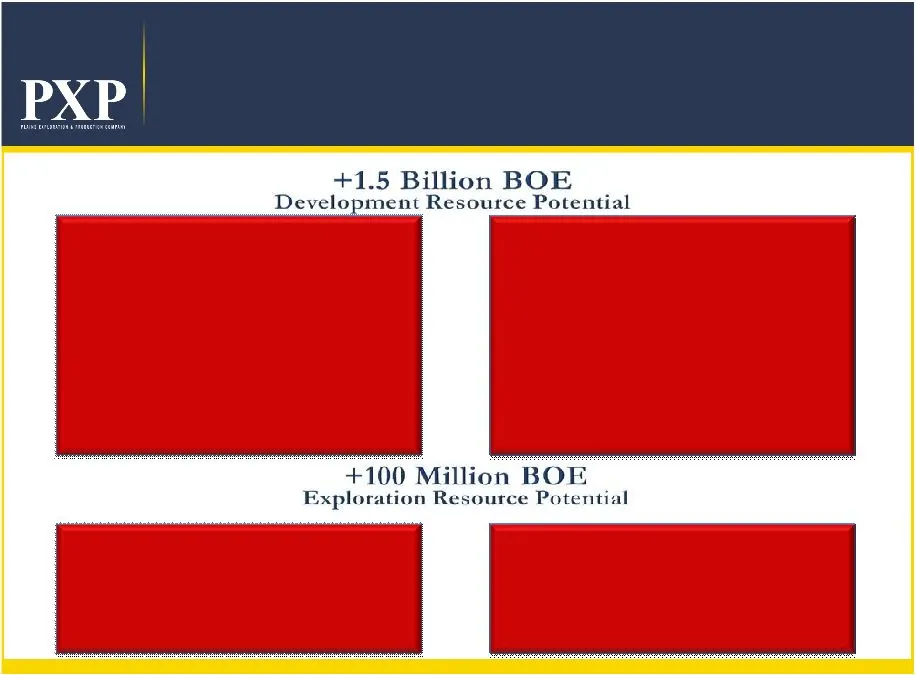
+1.6 Billion BOE Resource Potential 950 MMBOE 275 MMBOE 175 MMBOE 100 MMBOE 10 MMBOE Haynesville California Eagle Ford Granite Wash Rockies 90 MMBOE 30 MMBOE Mowry Shale Monterey Shale Potential Reserves Region Potential Reserves Region
Slide 27: PXP Targets Over Next Years
PXP Targets Over Next 3 Years • Grow reserves 15% to 20% per year over the next 3 years • Grow production 10% to 15% per year over the next 3 years • Efficiently manage business focusing on cost reduction and profitability • Maintain conservative balance sheet with active hedging program • Focus dri
Slide 28: Addendum
Addendum
Slide 29: Full-Year 2011 Operating and Financial Guidance
Full-Year 2011 Operating and Financial Guidance Year Ended December 31, 2011 Production Volumes (MBOE/day) Production volumes sold 95.0 — 100.0 % Oil 50% — 52% % Gas 50% — 48% Price Realization % Index (Unhedged) Oil - NYMEX 84% — 86% Gas - Henry Hub 93% — 95% Production Costs per BOE Lease operatin
Slide 30: Full-Year 2011 Operating and Financial Guidance: Derivative Instruments
Full-Year 2011 Operating and Financial Guidance Derivative Instruments Crude Oil Put options-2011 (6) Bbls / day 31,000 Floor $80.00 Floor Limit $60.00 Option premium and interest ($/Bbl) $5.023 Crude Oil Three-way Collars - (7) Bbls / day 9,000 Ceiling $110.00 Floor $80.00 Floor Limit $60.00 Option
Slide 31: Full-Year 2011 Operating and Financial Guidance
Full-Year 2011 Operating and Financial Guidance (1) Steam gas costs assume a base SoCal Border index price of $4.81 per MMBtu. The purchased volumes are anticipated to be 42,000 - 45,000 MMBtu per day. (2) Production and ad valorem taxes assume base index prices of $85.00 per barrel and $5.00 per MM
Slide 32: Income Statement Summary
Income Statement Summary (Millions) 3 mo. Ended 9/30/10 3 mo. Ended 9/30/09 Revenues $ 387.8 $ 312.2 Production Costs (119.3) (100.1) General & Administrative Expenses (34.3) (36.4) DD&A & Accretion Expense (137.6) (105.3) Other Operating Income 0.5 4.4 Income From Operations $ 97.1 $ 74.8 Income Be
Slide 33: Reconciliation of Debt-Adjusted Cash Operating Margin (Non-GAAP)
Reconciliation of Debt-Adjusted Cash Operating Margin (Non-GAAP) to Net Cash Provided by Operating Activities (GAAP) The following table reconciles the debt-adjusted operating margin (non-GAAP) to the net cash provided by operating activities (GAAP) for the three months ended September 30, 2010. Man
Slide 34: Plains Exploration & Production Company
PLAINS EXPLORATION & PRODUCTION COMPANY
Source: SEC EDGAR · 8-K filed Jan 10, 2011
More decks from Plains Exploration & Production Company
 Global Metals, Mining & Steel Conference 201333 slides · May 14, 2013
 Q1 2013 Earnings Presentation46 slides · Apr 19, 2013
 Merger or Acquisition (February 2013)35 slides · Feb 25, 2013
 2013 Credit Suisse Energy Summit10 slides · Feb 5, 2013
 Merger or Acquisition (January 2013)30 slides · Jan 17, 2013
 Credit Suisse 2012 Energy Summit32 slides · Feb 7, 2012