FGX International Holdings LTD
FGX International — SunTrust Robinson Humphrey Presentation April 2008
25 slides from FGX International's conference presentation, Apr 14, 2008
Slide 1: SunTrust Robinson Humphrey Presentation April 2008
SunTrust Robinson Humphrey Presentation April 2008
Slide 2: Special Note Regarding Forward-Looking Statements
SPECIAL NOTE REGARDING FORWARD-LOOKING STATEMENTS This presentation contains forward-looking statements (as defined in the Private Securities Litigation Reform Act of 1995) that are based on current expectations, estimates, forecasts and projections, as the case may be, and as such involve substanti
Slide 3: The FGX Advantage
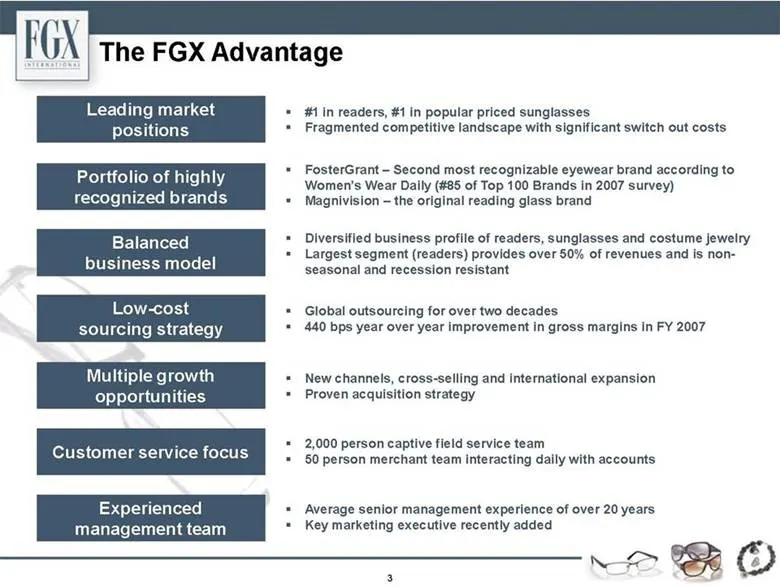
The FGX Advantage #1 in readers, #1 in popular priced sunglasses Fragmented competitive landscape with significant switch out costs FosterGrant – Second most recognizable eyewear brand according to Women’s Wear Daily (#85 of Top 100 Brands in 2007 survey) Magnivision – the original reading glass bra
Slide 4: Leading Market Positions in Key Product Categories
Leading Market Positions in Key Product Categories • FosterGrant + Magnivision creates leading share in a growing market – 50%+ • Magnivision – the original reading glass brand has #1 market share • Foster Grant #1 market share in mass/popular priced sunglasses: estimated to be 20%+ of total market
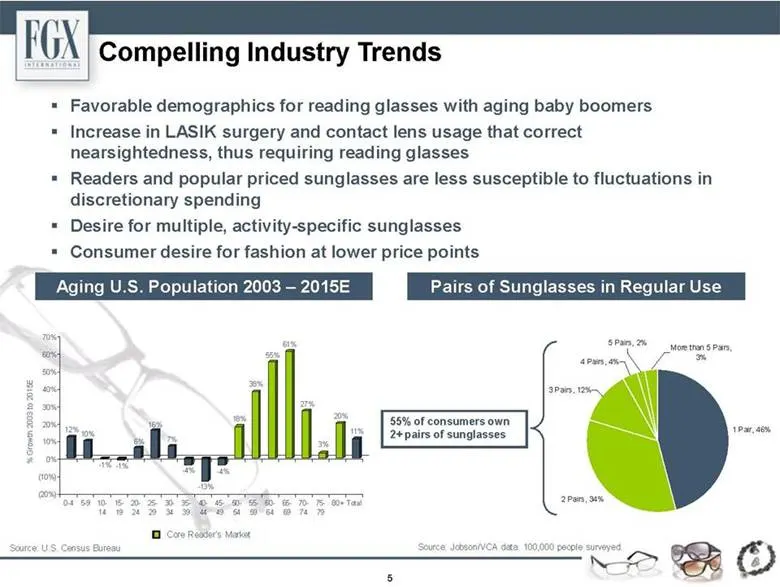
Slide 5: Compelling Industry Trends
• Compelling Industry Trends • Favorable demographics for reading glasses with aging baby boomers • Increase in LASIK surgery and contact lens usage that correct nearsightedness, thus requiring reading glasses • Readers and popular priced sunglasses are less susceptible to fluctuations in discretion
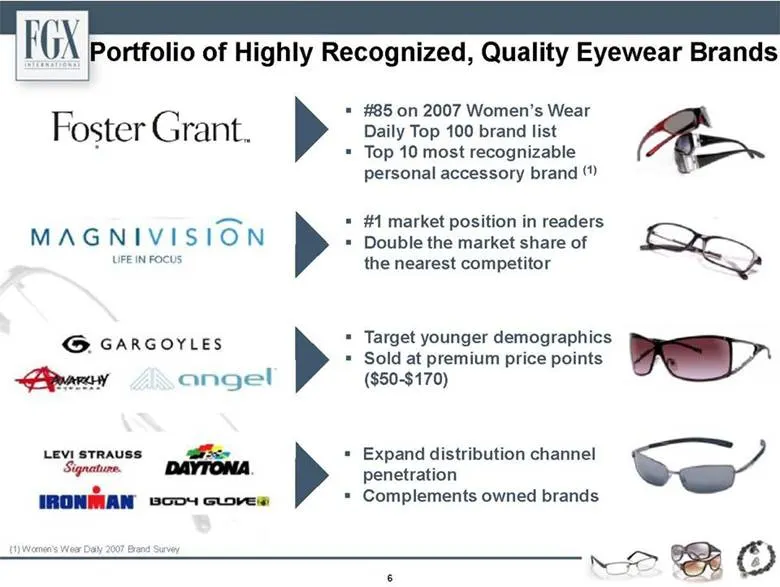
Slide 6: Portfolio of Highly Recognized, Quality Eyewear Brands
Portfolio of Highly Recognized, Quality Eyewear Brands • #85 on 2007 Women’s Wear Daily Top 100 brand list • Top 10 most recognizable personal accessory brand (1) • #1 market position in readers • Double the market share of the nearest competitor • Target younger demographics • Sold at premium price
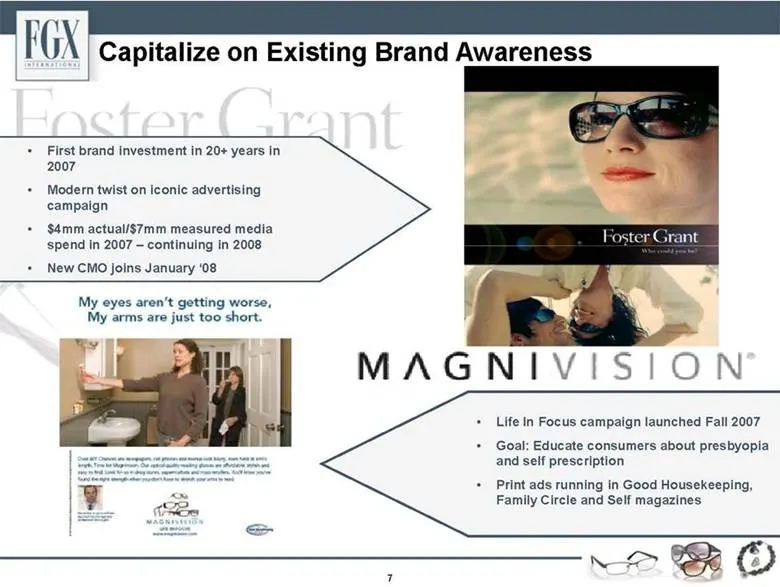
Slide 7: Capitalize on Existing Brand Awareness
Capitalize on Existing Brand Awareness • First brand investment in 20+ years in 2007 • Modern twist on iconic advertising campaign • $4mm actual/$7mm measured media spend in 2007 – continuing in 2008 • New CMO joins January ‘08 • Life In Focus campaign launched Fall 2007 • Goal: Educate consumers ab
Slide 8: Latest TV Advertisement
FOX) Latest TV Advertisement We B&O
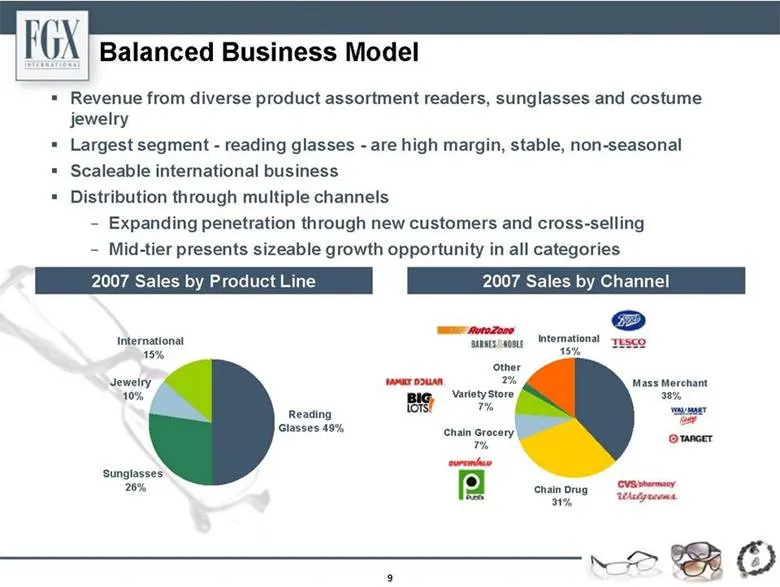
Slide 9: Balanced Business Model
Balanced Business Model • Revenue from diverse product assortment readers, sunglasses and costume jewelry • Largest segment - reading glasses - are high margin, stable, non-seasonal • Scaleable international business • Distribution through multiple channels Expanding penetration through new customer
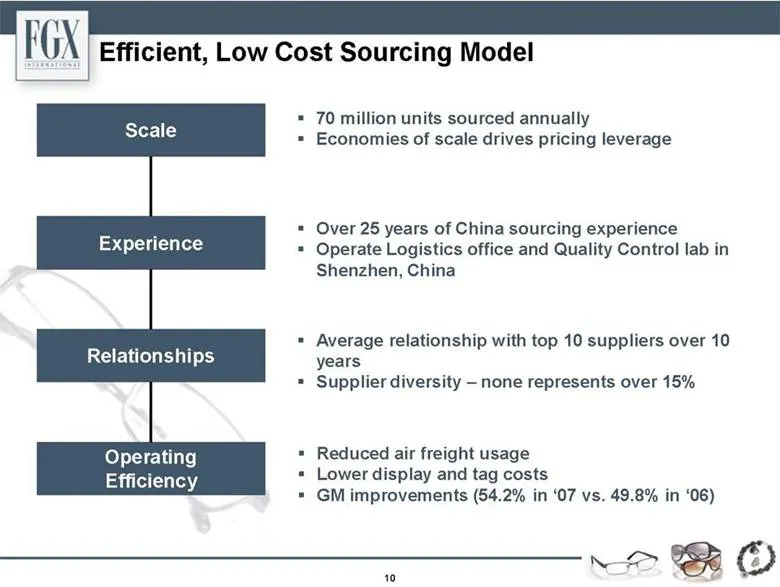
Slide 10: Efficient, Low Cost Sourcing Model
Efficient, Low Cost Sourcing Model • 70 million units sourced annually • Economies of scale drives pricing leverage • Over 25 years of China sourcing experience • Operate Logistics office and Quality Control lab in Shenzhen, China • Average relationship with top 10 suppliers over 10 years • Supplier
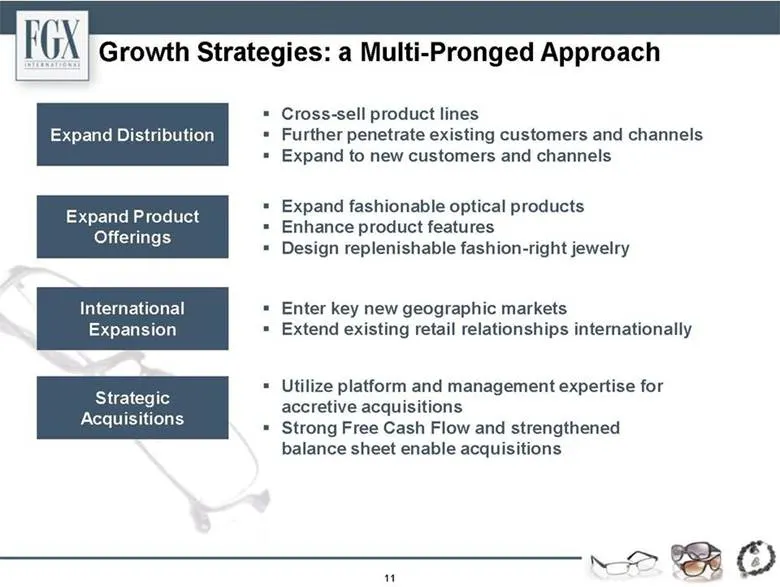
Slide 11: Growth Strategies: a Multi-Pronged Approach
Growth Strategies: a Multi-Pronged Approach Expand Distribution • Cross-sell product lines • Further penetrate existing customers and channels • Expand to new customers and channels Expand Product Offerings • Expand fashionable optical products • Enhance product features • Design replenishable fashi
Slide 12: Jack Flynn, President
Jack Flynn President 12
Slide 13: Significant Barriers to Entry
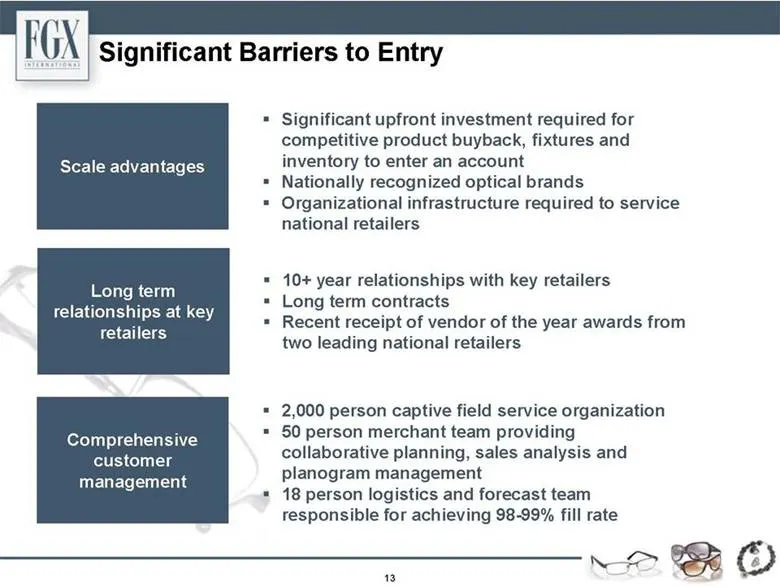
Significant Barriers to Entry Scale advantages • Significant upfront investment required for competitive product buyback, fixtures and inventory to enter an account • Nationally recognized optical brands • Organizational infrastructure required to service national retailers Long term relationships a
Slide 14: Long-Standing Relationships with National Retailers
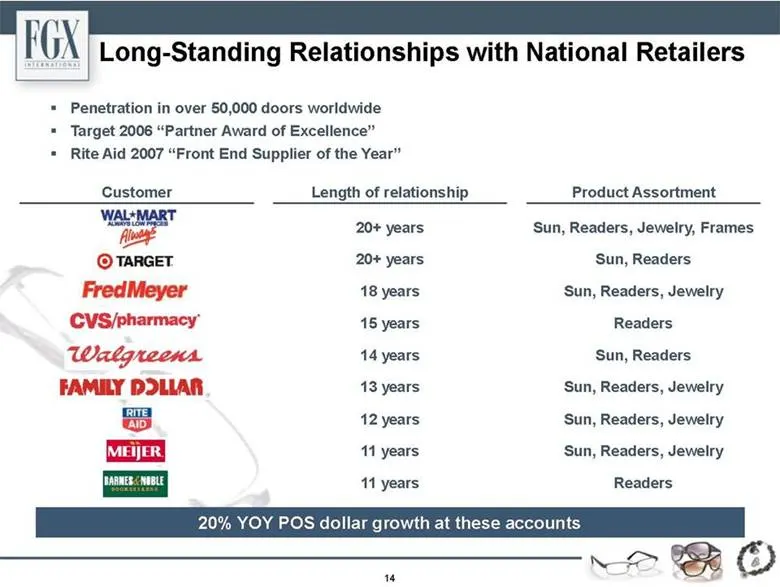
Long-Standing Relationships with National Retailers • Penetration in over 50,000 doors worldwide • Target 2006 “Partner Award of Excellence” • Rite Aid 2007 “Front End Supplier of the Year” Length of relationship Product Assortment Customer 20+ years 20+ years 18 20+ years 15 years 14 years 13 years
Slide 15: Selected Cross-Selling Opportunities by Channel
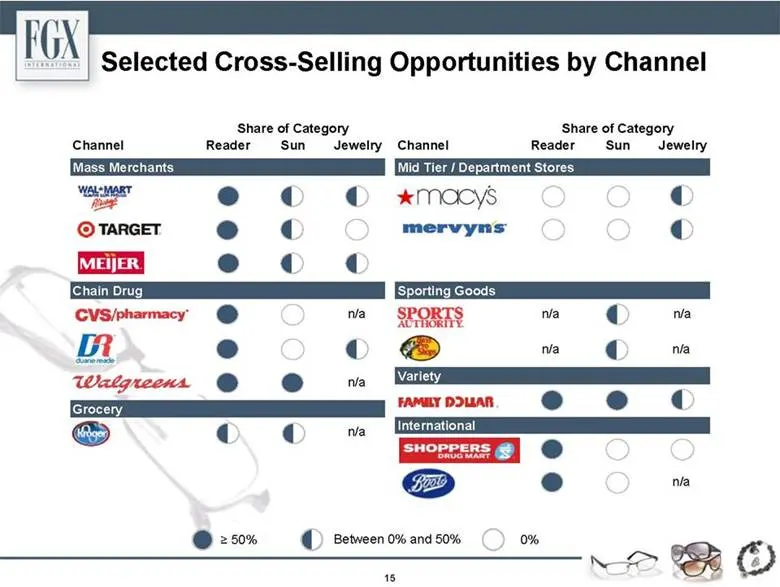
Selected Cross-Selling Opportunities by Channel Share of Category Share of Category Channel Reader Sun Jewelry Channel Reader Sun Jewelry Mass Merchants Mid Tier / Department Stores 15 > 50% Between 0% and 50% 0% Chain Drug Sporting Goods Variety Grocery International n/a n/a n/a n/a n/a n/a n/a n/a
Slide 16: Selected New Business Opportunities by Channel
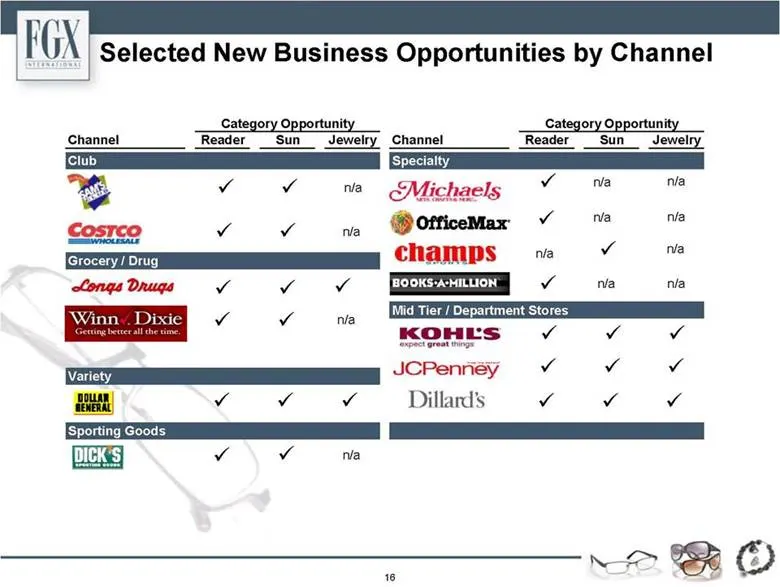
Selected New Business Opportunities by Channel Category Opportunity Category Opportunity Channel Reader Sun Jewelry Channel Reader Sun Jewelry n/a n/a n/a n/a n/a n/a n/a n/a n/a n/a n/a n/a 16
Slide 17: Financial Overview
Financial Overview Anthony DiPaola Executive Vice President Chief Financial Officer 17
Slide 18: Improved Capital Structure During 2007
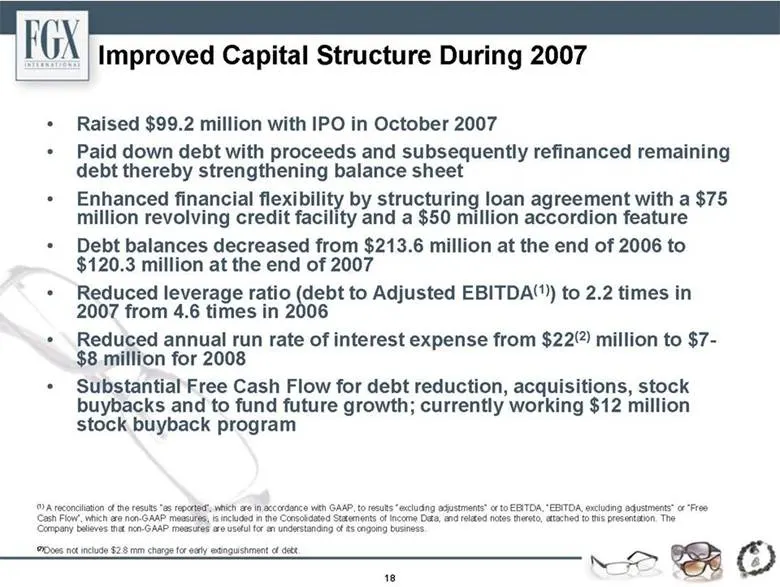
Improved Capital Structure During 2007 • Raised $99.2 million with IPO in October 2007 • Paid down debt with proceeds and subsequently refinanced remaining debt thereby strengthening balance sheet • Enhanced financial flexibility by structuring loan agreement with a $75 million revolving credit faci
Slide 19: Focus on Improving Gross Margin
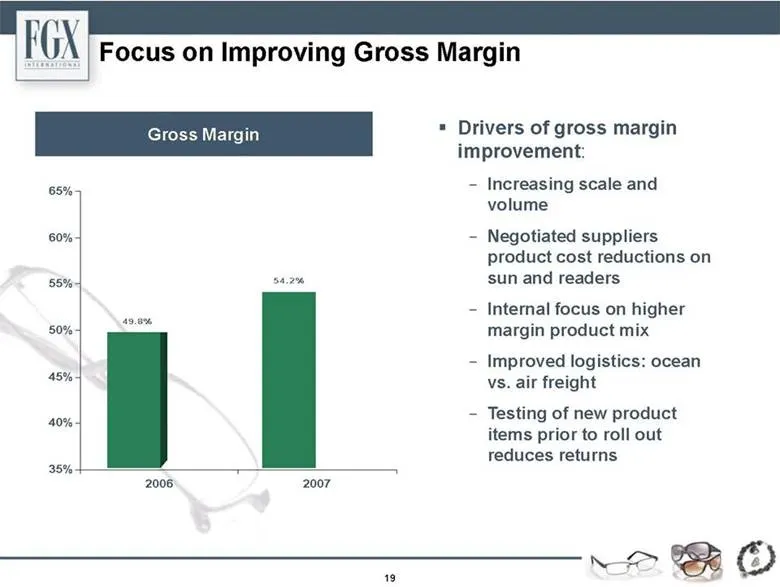
Focus on Improving Gross Margin Gross Margin • Drivers of gross margin improvement: • Increasing scale and volume • Negotiated suppliers product cost reductions on sun and readers • Internal focus on higher margin product mix • Improved logistics: ocean vs. air freight • Testing of new product items
Slide 20: Strong Sales & EBITDA Momentum
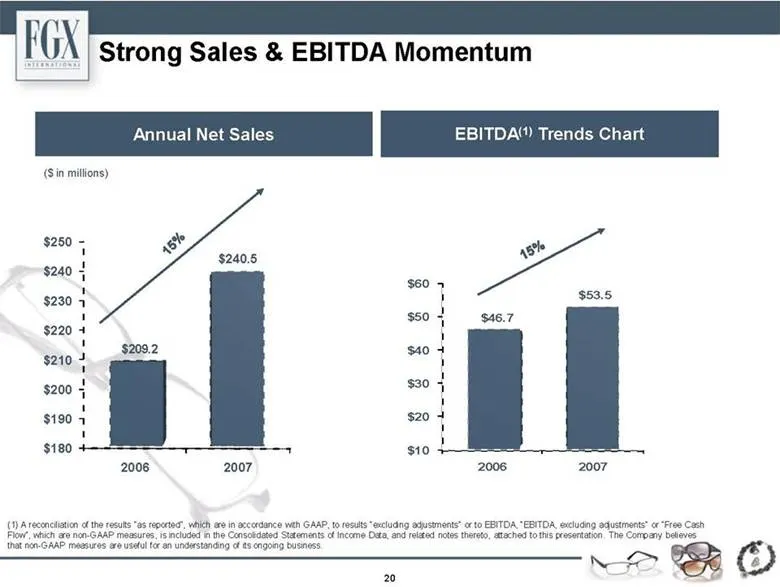
Strong Sales & EBITDA Momentum ($ in millions) $250 $240.5 $240 $60 $230 $53.5 $50 $46.7 $220 $210 $209.2 $40 $200 $30 $190 $20 $180 $10 2006 2007 2006 2007 (1) A reconciliation of the results “as reported”, which are in accordance with GAAP, to results “excluding adjustments” or to EBITDA, “EBITDA,
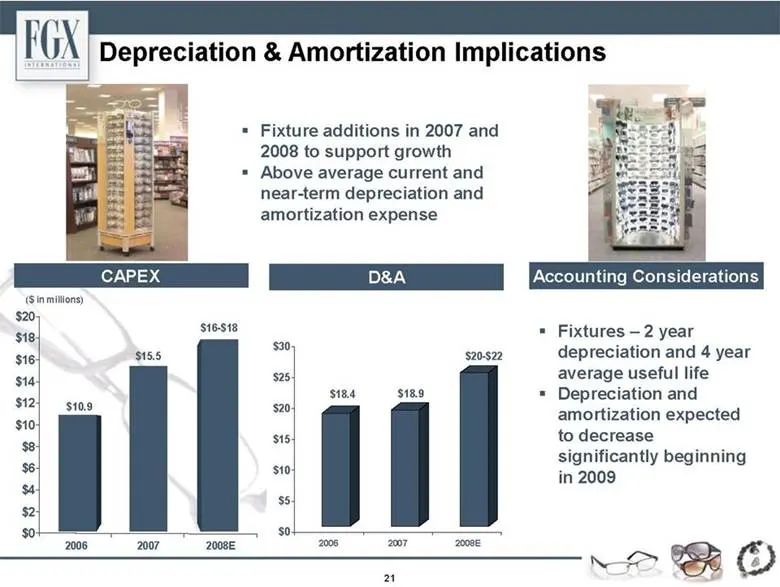
Slide 21: Depreciation & Amortization Implications
Depreciation & Amortization Implications • Fixture additions in 2007 and 2008 to support growth • Above average current and near-term depreciation and amortization expense • Fixtures – 2 year depreciation and 4 year average useful life • Depreciation and amortization expected to decrease significant
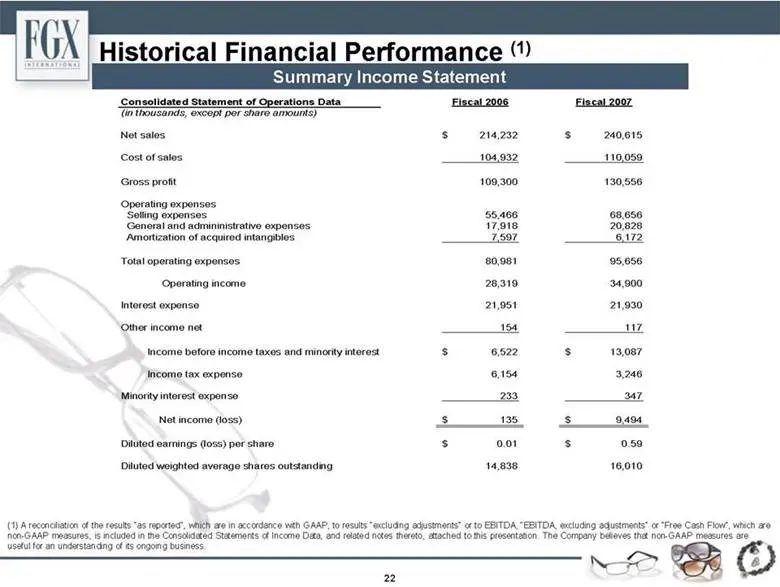
Slide 22: Historical Financial Performance
Historical Financial Performance (1) Summary Income Statement (1) A reconciliation of the results “as reported”, which are in accordance with GAAP, to results “excluding adjustments” or to EBITDA, “EBITDA, excluding adjustments” or “Free Cash Flow”, which are non-GAAP measures, is included in the Co
Slide 23: Summary
Summary Leading market positions Balanced business model Portfolio of highly recognized brands Low-cost sourcing strategy Scale and experience create barriers to entry Multiple growth opportunities Experienced management team Customer service focus 23
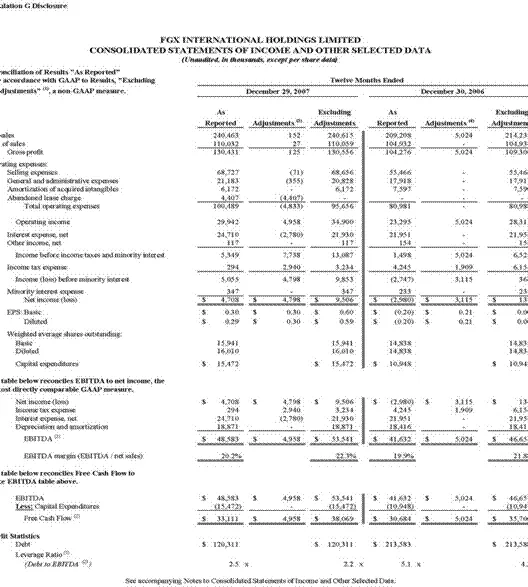
Slide 24: Regulation G Disclosure
Regulation G Disclosure Reconciliation of Results "As Reported" in accordance with GAAP to Results, "Excluding Adjustments" (1), a non-GAAP measure. As Excluding As Excluding Reported Adjustments (3) Adjustments Reported Adjustments (4) Adjustments Net sales 240,463 152 240,615 209,208 5,024 214,232
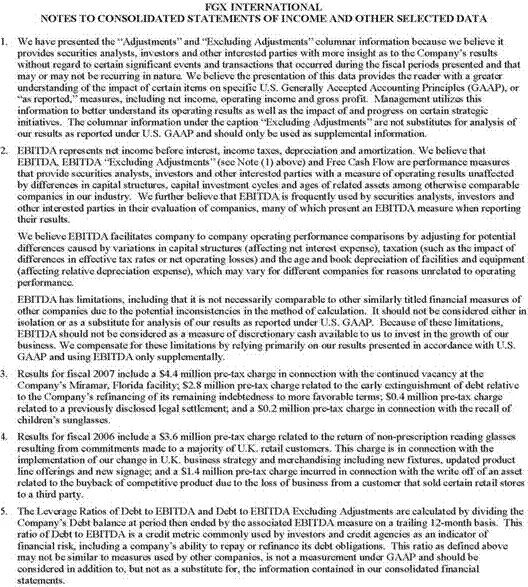
Slide 25: Notes to Consolidated Statements of Income and Other Selected Data
FGX INTERNATIONAL NOTES TO CONSOLIDATED STATEMENTS OF INCOME AND OTHER SELECTED DATA 1. We have presented the “Adjustments” and “Excluding Adjustments” columnar information because we believe it provides securities analysts, investors and other interested parties with more insight as to the Company’
Source: SEC EDGAR · 8-K filed Apr 14, 2008
More decks from FGX International Holdings LTD
 Investor Presentation (November 2009)24 slides · Nov 9, 2009
 Investor Presentation (September 2009)24 slides · Sep 22, 2009
 Oppenheimer Annual Consumer Conference 200930 slides · Jul 13, 2009
 Investor Presentation (June 2009)29 slides · Jun 26, 2009
 Investor Presentation (June 2009)26 slides · Jun 8, 2009
 Investor Presentation (May 2009)25 slides · May 28, 2009