Bancorp Rhode Island — Sandler O'Neill + Partners East Coast Financial Services Conference 2010
24 slides from Bancorp Rhode Island's conference presentation, Nov 10, 2010
Slide 1: Sandler O'Neill + Partners East Coast Financial Services Conference
Sandler O’Neill + Partners, L.P. East Coast Financial Services Conference November 11, 2010
Slide 2: Forward Looking Statements
Certain statements contained in this presentation are “Forward Looking Statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward Looking Statements may be identified by the use of forward looking terminology such as “may,” “believes,” “intends,” “expects,” and “
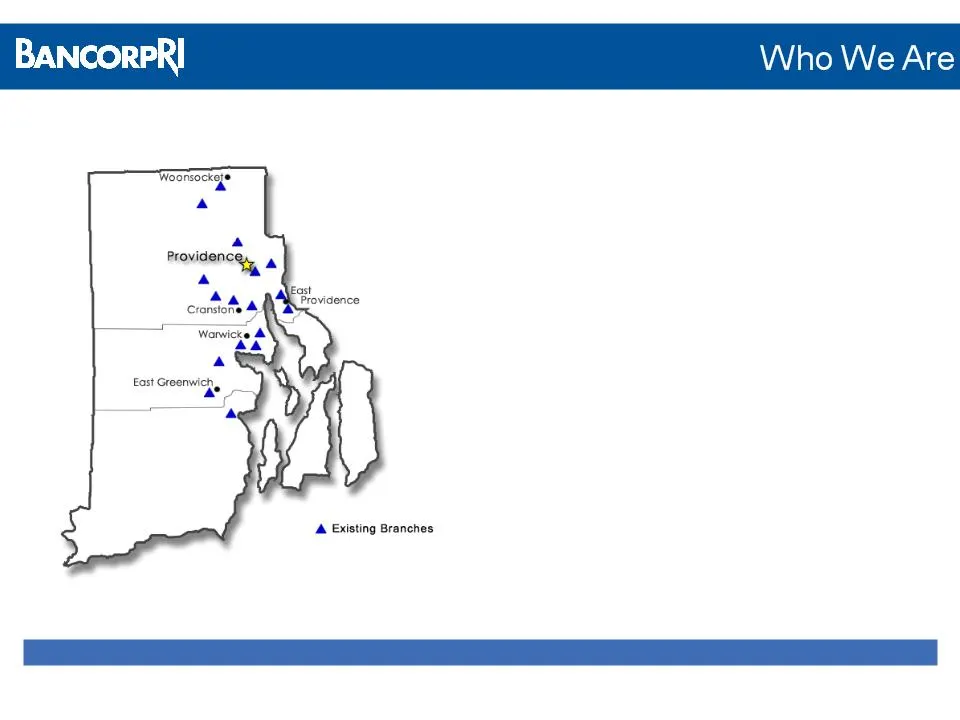
Slide 3: Company Profile
• Cities/Towns Profile: § Formed in March 1996 § $1.6 billion commercial bank § NASDAQ listed: BARI § 17 branches in Greater Providence area § Approximately 75% of RI’s population, jobs and businesses are located in Greater Providence area
Slide 4: Company history and milestones
Oct 1995 Sep 2010 Agreement to purchase RI branches of Shawmut BankRI opened Mar 1996 Jun 2009 May 2005 Nov 2002 Mar 1998 Sep 2009 Secondary offering; NASDAQ listed: BARI Reached $1.0B in assets Acquired Macrolease Listed on Russell 3000 Index #1 SBA lender in RI #1 SBA lender in RI Total Assets Tot
Slide 5: Strong financial performance in a difficult environment
§ Strong financial performance in a difficult environment § Credit quality consistently sound § Capital position well above regulatory thresholds § Experienced management team § Attentive to shareholder returns
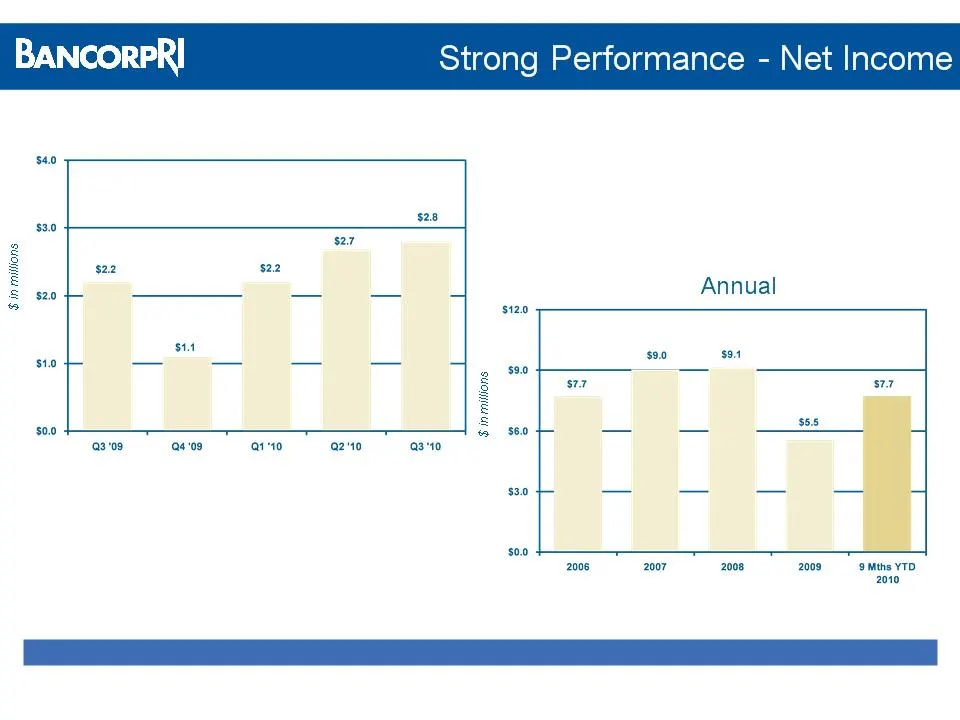
Slide 6: Strong Performance - Net Income
BANCORPRI Strong Performance - Net Income so se sso » 27 2 22 © aaa a Annual = sao sso 808 ae Zz rls = g S77 377 = ! | = sss s00 a! ae att ato a0 ss0 | soo 2008 2007 2008 2008 = 9Mths YTD 2010
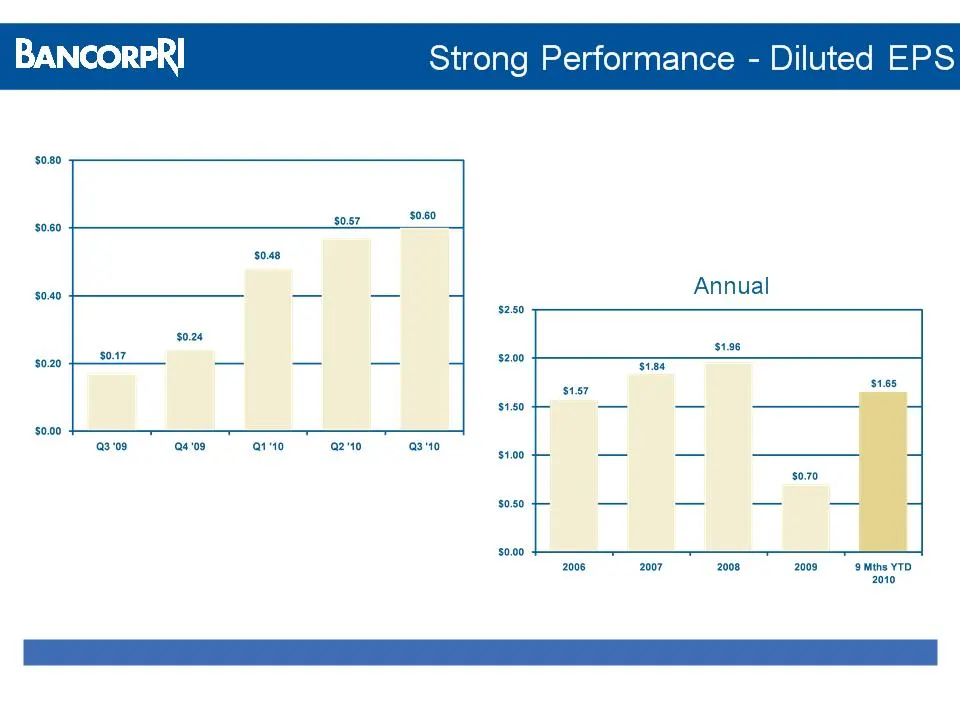
Slide 7: Quarterly Diluted EPS
Quarterly * Diluted EPS after preferred stock dividends and discount accretion related to TARP * * *
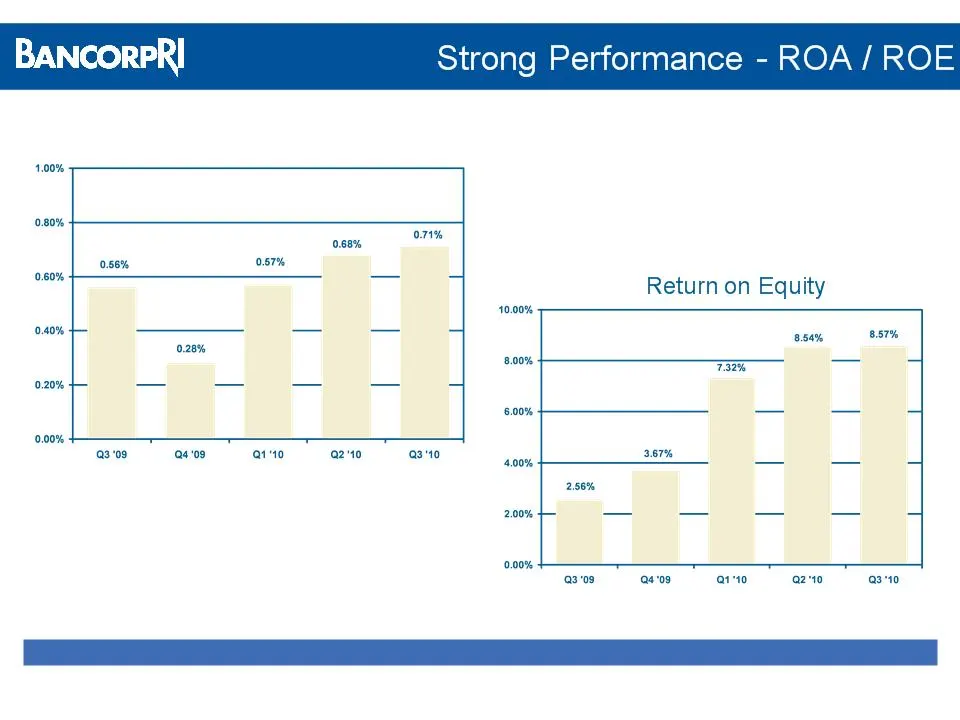
Slide 8: Return on Assets and Equity
Return on Assets * Return on equity after preferred stock dividends and discount accretion related to TARP *
Slide 9: Key drivers of performance
§ Commercial loan growth § Low-cost core deposit growth § Treasury management sophistication § Modest credit costs § Disciplined expense management
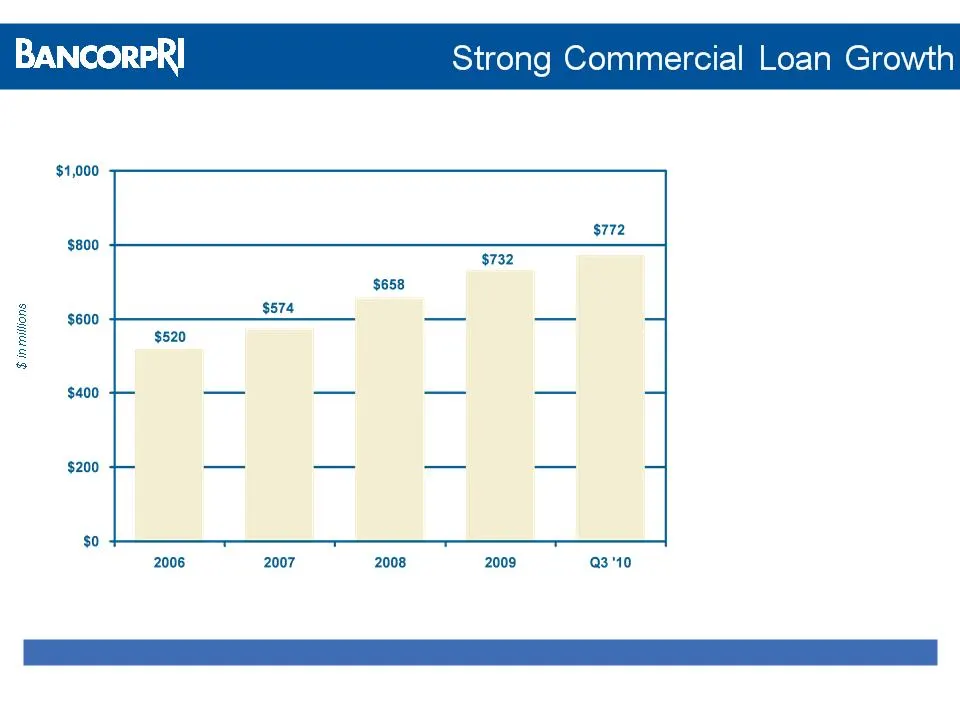
Slide 10: Commercial loan growth
• Double digit growth from 2006 - 2009 • Drives low-cost core deposit growth • Grew from 41% of total loans to 68% over past 10 years
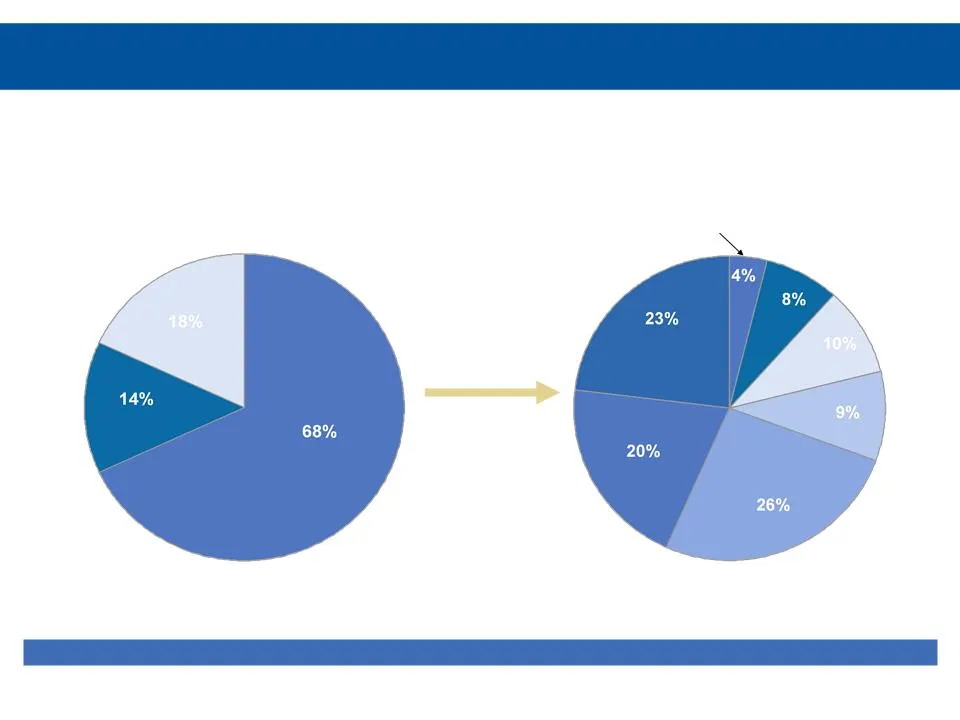
Slide 11: Total Loan Portfolio
Commercial Loans Residential Mortgages Consumer/ Other Total loan portfolio - $1.14 billion as of 9/30/10 Small Business Commercial and Industrial Construction Lease and Other CRE (owner occupied) Multi-Family CRE (non-owner occupied) Breakdown of Commercial Loan Portfolio Total Loan Portfolio
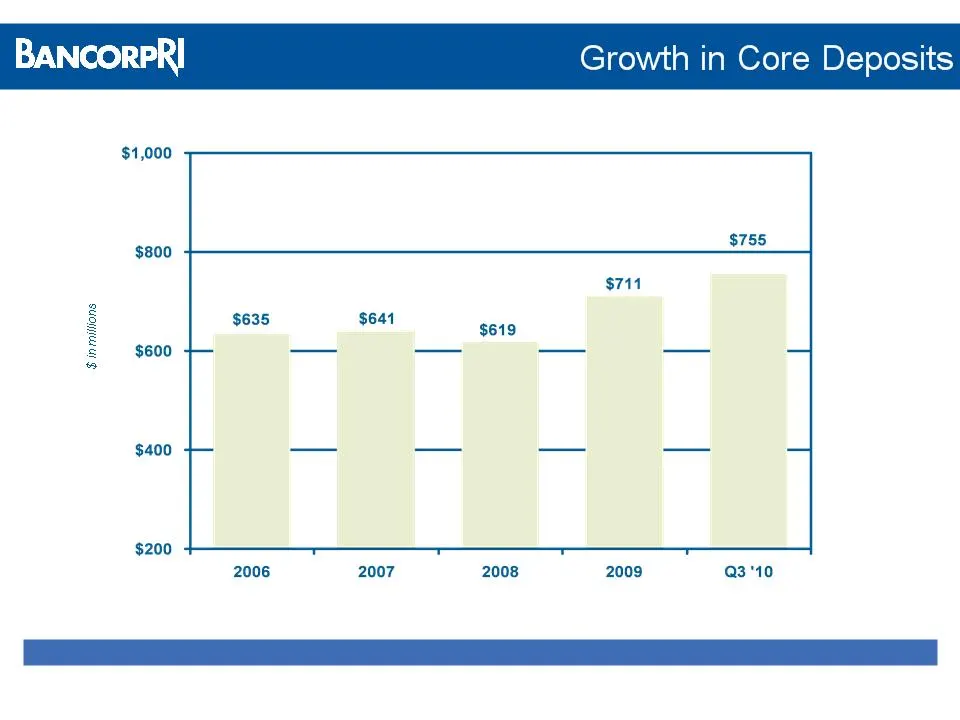
Slide 12: Core deposit growth
Core deposits are defined as DDA, NOW, money market and savings accounts 62% 63% 59% 65% 68% % of total deposits
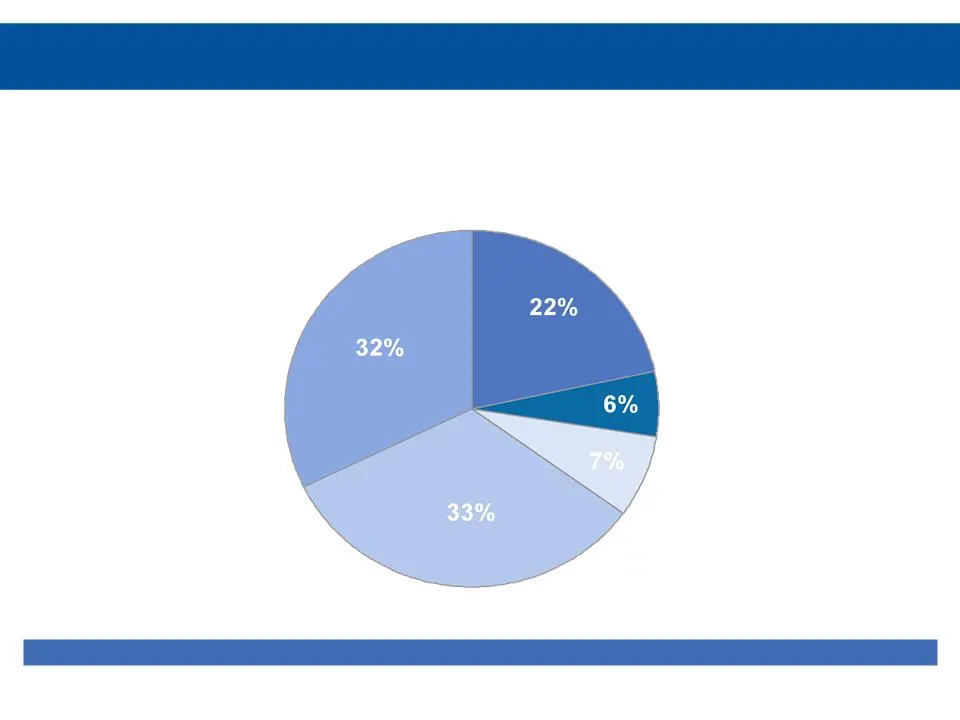
Slide 13: Deposit composition
Money Market Certificate of Deposits Demand Deposits Core Deposits - 68% of total deposits as of 9/30/10 NOW Savings Total deposits - $1.12 billion as of 9/30/10
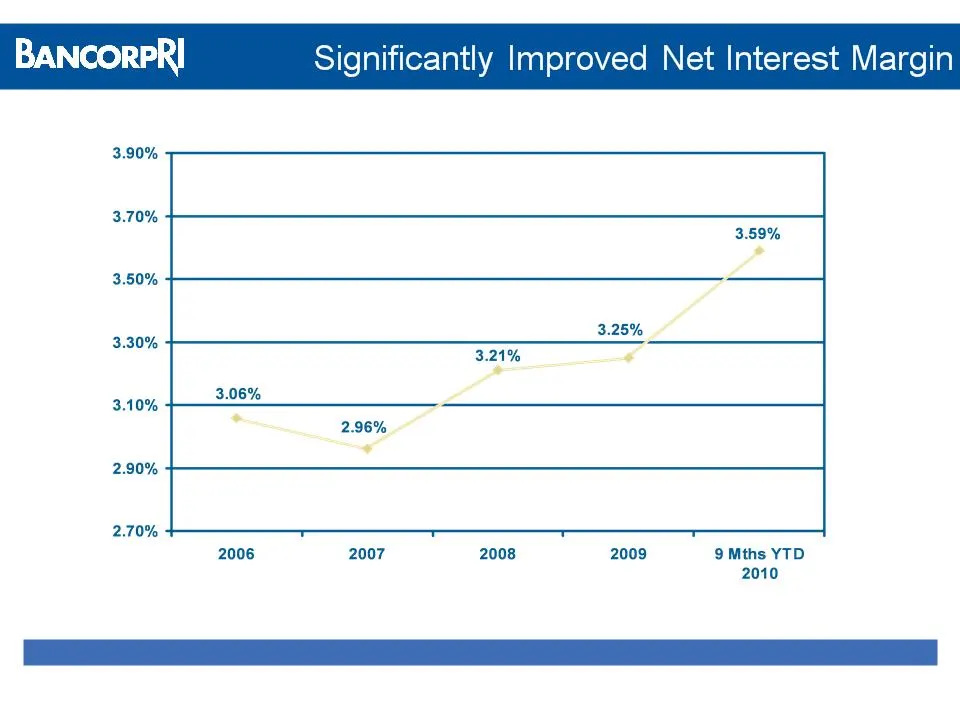
Slide 14: Significantly Improved Net Interest Margin
BANCORPRI Significantly Improved Net Interest Margin 3.90% 3.70% 3.59% 3.50% = 3.30% = i 321% we s0% ane ite ——___ 2.96% ee 2.90% 2.70% 2006 2007 2008 2009 9 Mths YTD 2010
Slide 15: Conservative credit culture
§ Conservative credit culture § Significant credit and credit management expertise § Extensive portfolio monitoring processes § Relatively low level of net charge-offs despite: − Double-digit commercial loan growth − Recessionary environment
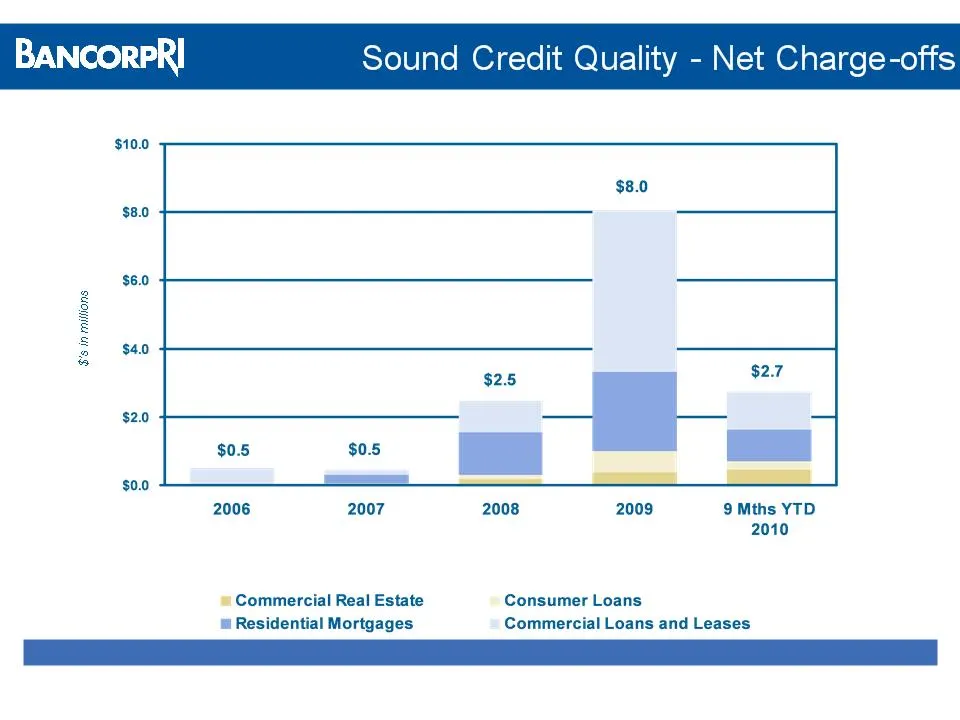
Slide 16: Net charge-offs as % of average loans
0.05% 0.05% 0.24% 0.73% 0.33% % of avg. loans and leases
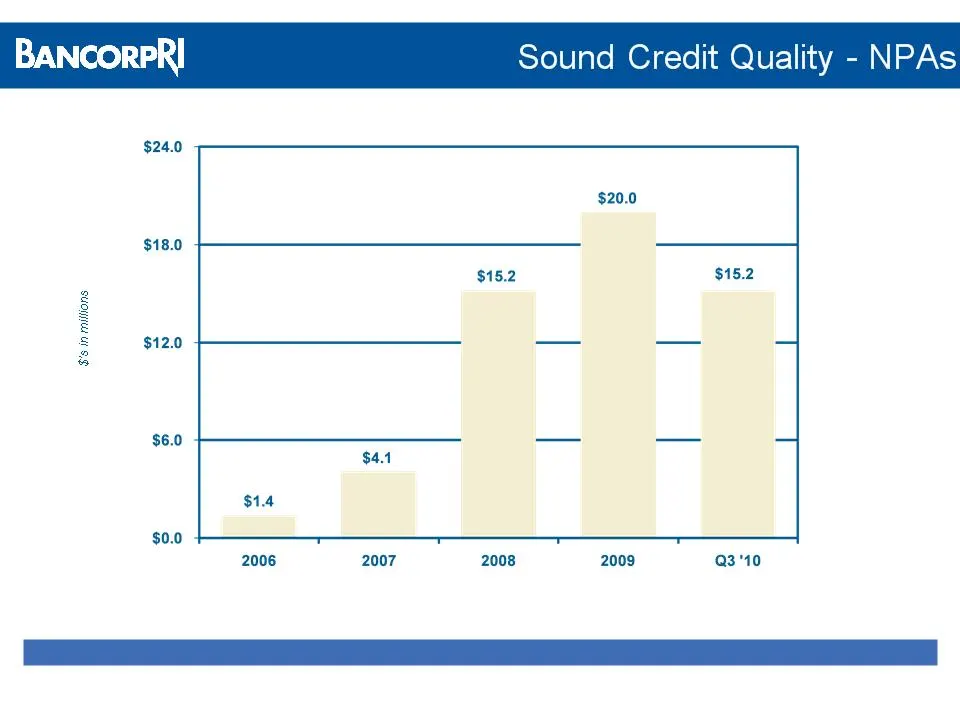
Slide 17: Nonperforming assets
0.10% 0.28% 1.00% 1.26% 0.96% % of total assets
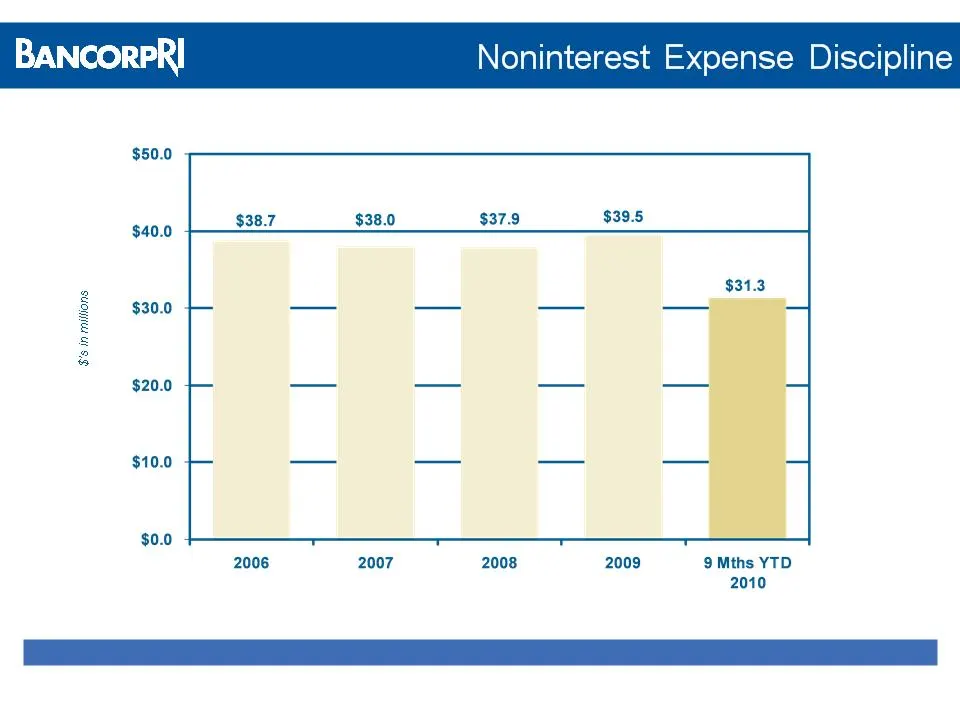
Slide 18: Noninterest Expense Discipline
BANCORPRI Noninterest Expense Discipline $50.0 & 38.0 37.9 $39.5 $40.0 $38.7 $: $ e $31.3 S $30.0 = 2 $20.0 -— rm $10.0 | $0.0 2006 2007 2008 2009 9 Mths YTD 2010
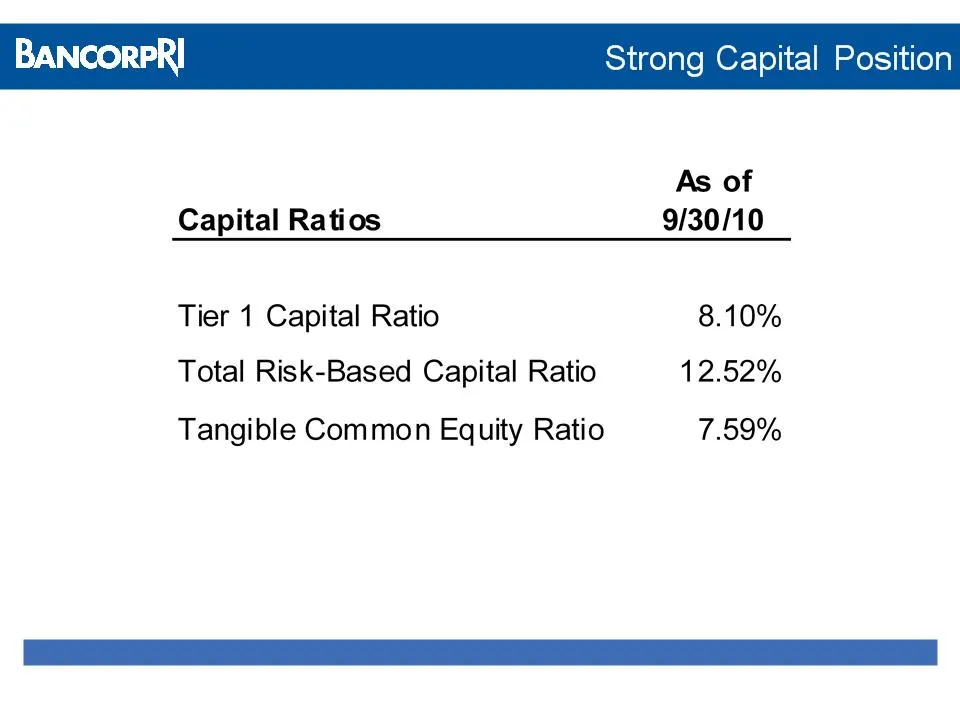
Slide 19: Capital ratios well above regulatory thresholds
Capital ratios well above regulatory thresholds
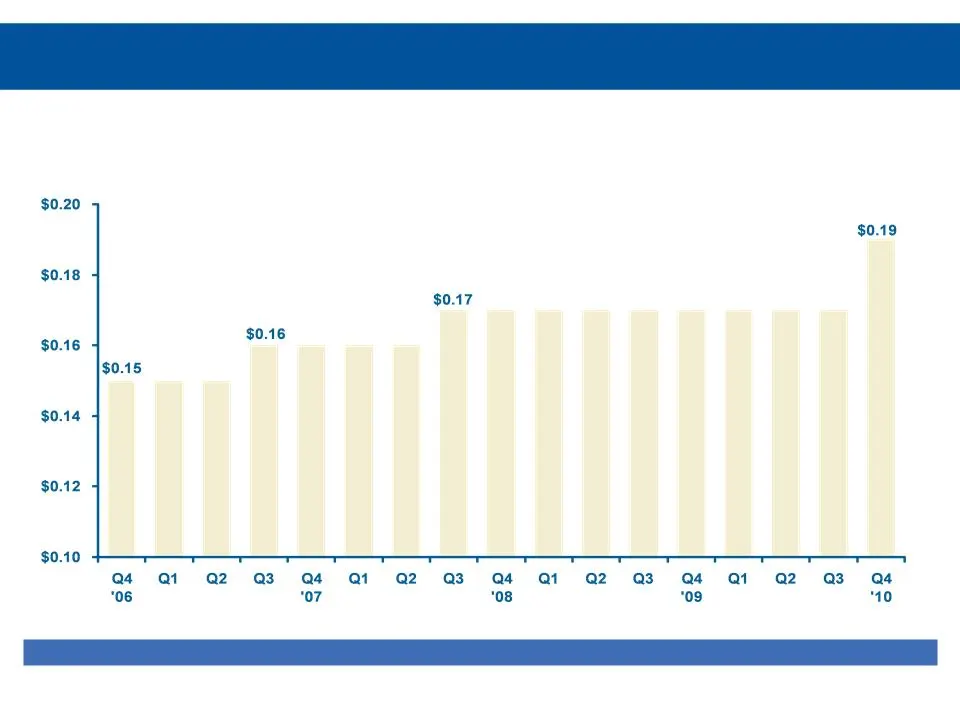
Slide 20: Dividend Track Record
Dividend Track Record 12% increase approved in Q4 ‘10
Slide 21: Recent recognition and achievements
§ Became #1 SBA lender in Rhode Island for 2 nd consecutive year § BankRI named to the Forbes’ list of most “trustworthy” companies § Named to Sandler O’Neill Small All-Stars: Class of 2010
Slide 22: Commercial banking is a sustainable, attractive market niche
§ Commercial banking is a sustainable, attractive market niche for community banks − Ability to differentiate from major competitors • Responsive / accessible • Local decision-making / policy setting • High touch retail network with solid branch footprint − Dense, urban market well-suited for busine
Slide 23: Attractive franchise
§ Attractive franchise − One of the few sizeable independent franchises in New England § Solid credit quality and capital position § Proven track record for delivering results § Strong management team § Positioned to grow franchise § Attentive to shareholder returns § Market Valuations (as of 11/2/1
Slide 24: NASDAQ: BARI
NASDAQ: BARI
Source: SEC EDGAR · 8-K filed Nov 10, 2010
More decks from Bancorp Rhode Island Inc
 Merger or Acquisition (August 2011)14 slides · Aug 9, 2011
 Shareholder Meeting (May 2011)26 slides · May 18, 2011
 Merger or Acquisition (May 2011)6 slides · May 13, 2011
 Merger or Acquisition (April 2011)7 slides · Apr 20, 2011
 Sterne Agee Financial Institutions Investor Conference 201123 slides · Feb 17, 2011
 KBW 11th Annual Community Bank Investor Conference (July 2010)28 slides · Jul 27, 2010