Provident Bankshares — Investor Day (September 2005)
108 slides from Provident Bankshares's investor day presentation, Sep 9, 2005
Slide 1: Provident Bankshares Corporation
PROVIDENT BANKSHARES CORPORATION
Slide 2: Forward-Looking Statements and Risk Factors
FORWARD-LOOKING STATEMENTS AND RISK FACTORS This presentation, as well as other written communications made from time to time by Provident Bankshares Corporation and its subsidiaries (the “Corporation”) (including, without limitation, the Corporation’s 2004 Annual Report to Stockholders) and oral co
Slide 3: Analyst / Investor Day Presentation
ANALYST / INVESTOR DAY PRESENTATION September 9, 2005
Slide 4: Welcome
Welcome Gary N. Geisel Chairman and Chief Executive Officer
Slide 5: Provident Bank History
Introduction Provident Bank History 1886 Founded as a Mutual Thrift 1987 Converted to Commercial Bank 1993 Retail Banking Expansion 1997 Citizen’s Savings Bank Merger 2004 Southern Financial Merger
Slide 6: Provident Bank Mission
Introduction Provident Bank Mission Provident Bank’s mission is to exceed customer expectations by delivering superior service, products and banking convenience. Every employee’s commitment to serve our customers in this fashion will establish Provident Bank as the primary bank of choice of individu
Slide 7: Provident Bank Vision
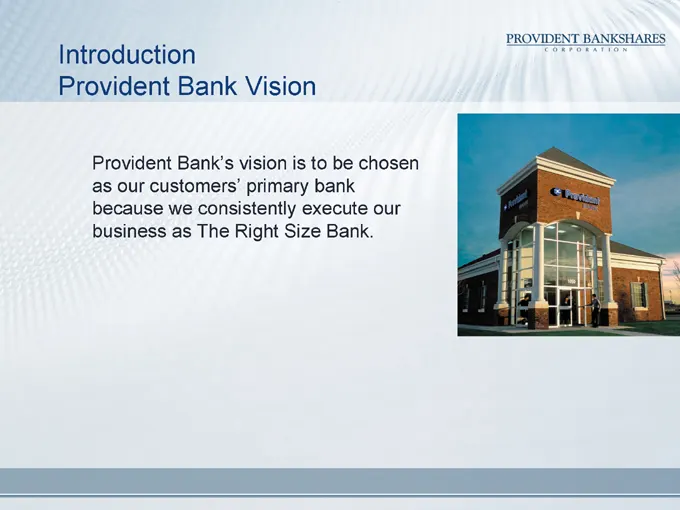
Introduction Provident Bank Vision Provident Bank’s vision is to be chosen as our customers’ primary bank because we consistently execute our business as The Right Size Bank.
Slide 8: Provident Bank Core Values
Introduction Provident Bank Core Values Integrity Excellence Caring Partnership Results Driven
Slide 9: Provident Bank Key Strategies
Introduction Provident Bank Key Strategies Maximize Provident’s Position as the “Right Size” Bank in the Marketplace Grow and Deepen Consumer and Small Business Relationships in Maryland and Virginia Grow and Deepen Commercial and Real Estate Relationships in Maryland and Virginia Move from a Produc
Slide 10: Peer Group
Introduction Peer Group Commerce Bancshares Inc. (MO) First Midwest Bancorp, Inc. Fulton Financial Corporation Mercantile Bankshares Corporation Sky Financial Group, Inc. Susquehanna Bancshares, Inc. TCF Financial Corporation United Bankshares, Inc. Valley National Bancorp
Slide 11: Mid Cap Group
Introduction Mid Cap Group Am South Bancorporation TD Banknorth Inc. Commerce Bancorp Inc. Compass Bancshares, Inc. Comerica Incorporated Colonial BancGroup Inc. First Horizon National Corp. FirstMerit Corporation Fulton Financial Corporation Huntington Bancshares Inc. Hibernia Corporation Mercantil
Slide 12: Investments / Assets
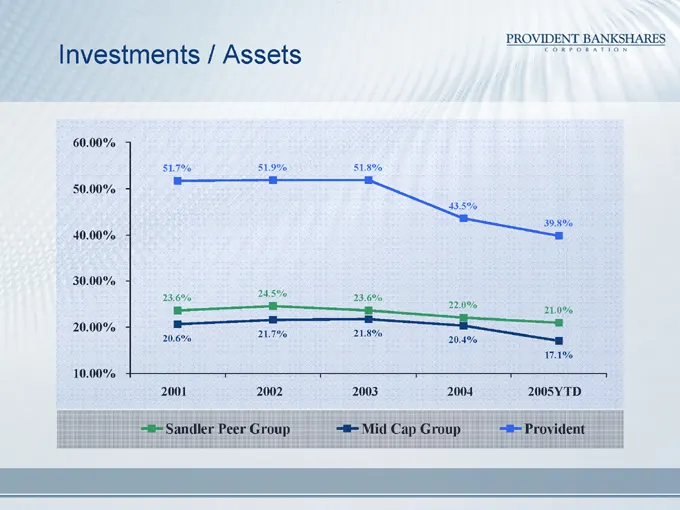
Investments / Assets 60.00% 50.00% 40.00% 30.00% 20.00% 10.00% 2001 2002 2003 2004 2005YTD 51.7% 51.9% 51.8% 43.5% 39.8% 23.6% 24.5% 23.6% 22.0% 21.0% 20.6% 21.7% 21.8% 20.4% 17.1% Sandler Peer Group Mid Cap Group Provident
Slide 13: Core Loans / Assets
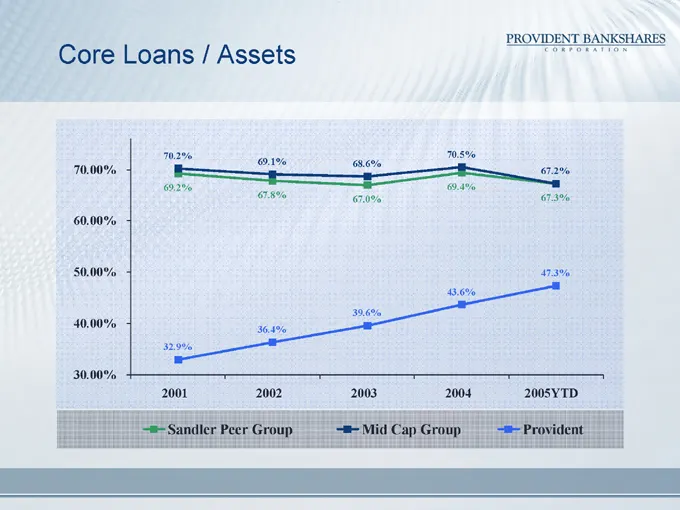
Core Loans / Assets 70.00% 60.00% 50.00% 40.00% 30.00% 2001 2002 2003 2004 2005YTD 70.2% 69.1% 68.6% 70.5% 67.2% 69.2% 67.8% 67.0% 69.4% 67.3% 32.9% 36.4% 39.6% 43.6% 47.3% Sandler Peer Group Mid Cap Group Provident
Slide 14: Core Loan Growth Rate
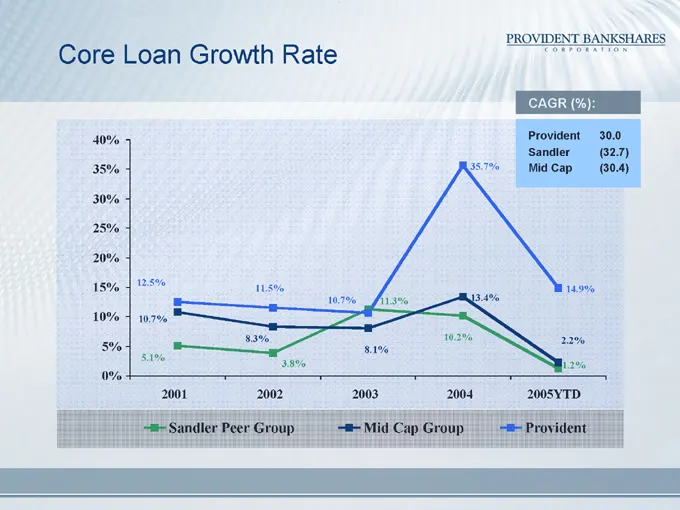
Core Loan Growth Rate 40% 35% 30% 25% 20% 15% 10% 5% 0% 2001 2002 2003 2004 2005YTD 12.5% 11.5% 10.7% 35.7% 14.9% 10.7% 8.3% 8.1% 13.4% 2.2% 5.1% 3.8% 11.3% 10.2% 1.2% Sandler Peer Group Mid Cap Group Provident CAGR (%): Provident 30.0 Sandler (32.7) Mid Cap (30.4)
Slide 15: Net Interest Margin
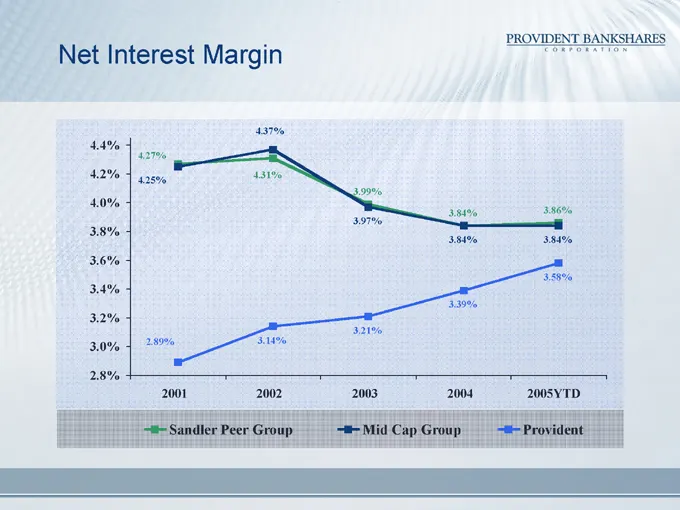
Net Interest Margin 4.4% 4.2% 4.0% 3.8% 3.6% 3.4% 3.2% 3.0% 2.8% 2001 2002 2003 2004 2005YTD 4.27% 4.25% 2.89% 4.37% 4.31% 3.14% 3.99% 3.97% 3.21% 3.84% 3.84% 3.39% 3.86% 3.84% 3.58% Sandler Peer Group Mid Cap Group Provident
Slide 16: Efficiency Ratio
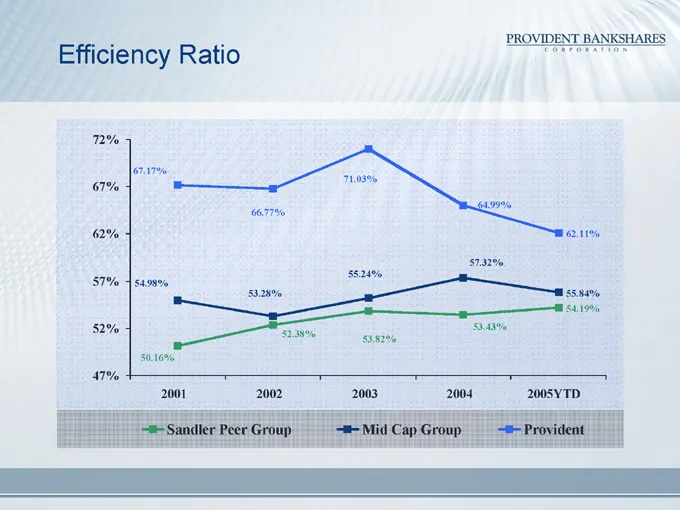
Efficiency Ratio 72% 67% 62% 57% 52% 47% 2001 2002 2003 2004 2005YTD 67.17% 54.98% 50.16% 66.77% 53.28% 52.38% 71.03% 55.24% 53.82% 64.99% 57.32% 53.43% 62.11% 55.84% 54.19% Sandler Peer Group Mid Cap Group Provident
Slide 17: Reserves / Loans
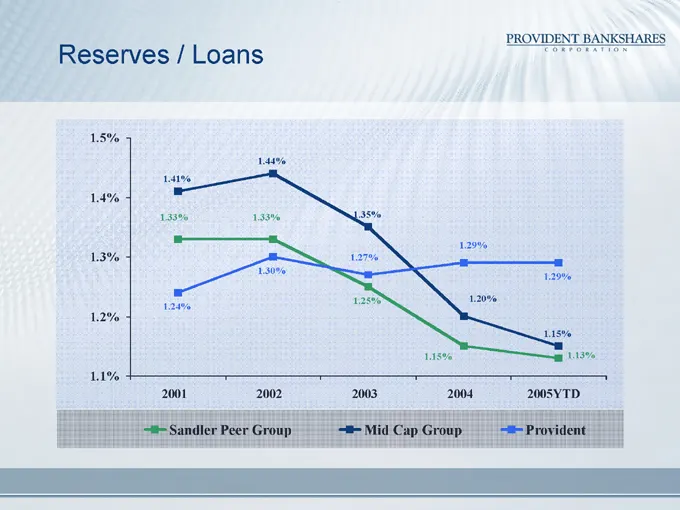
Reserves / Loans 1.5% 1.4% 1.3% 1.2% 1.1% 2001 2002 2003 2004 2005YTD 1.41% 1.33% 1.24% 1.44% 1.33% 1.30% 1.35% 1.27% 1.25% 1.29% 1.20% 1.15% 1.29% 1.15% 1.13% Sandler Peer Group Mid Cap Group Provident
Slide 18: Net Charge-Offs / Average Loans
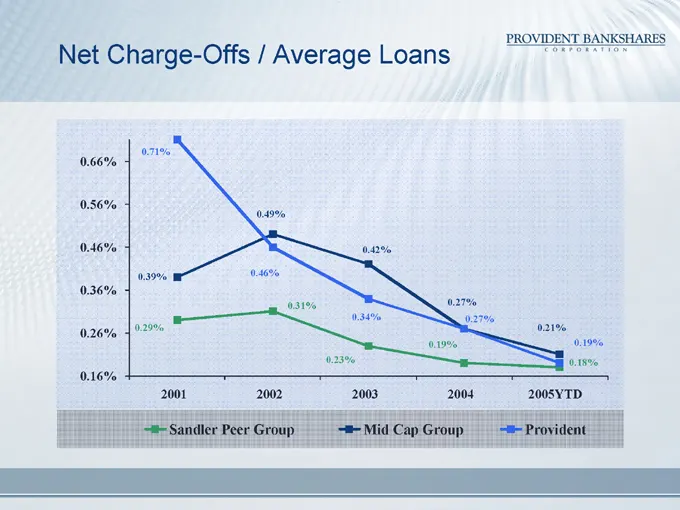
Net Charge-Offs / Average Loans 0.66% 0.56% 0.46% 0.36% 0.26% 0.16% 2001 2002 2003 2004 2005YTD 0.71% 0.39% 0.29% 0.49% 0.46% 0.31% 0.23% 0.42% 0.34% 0.19% 0.27% 0.27% 0.21% 0.19% 0.18% Sandler Peer Group Mid Cap Group Provident
Slide 19: Return on Equity
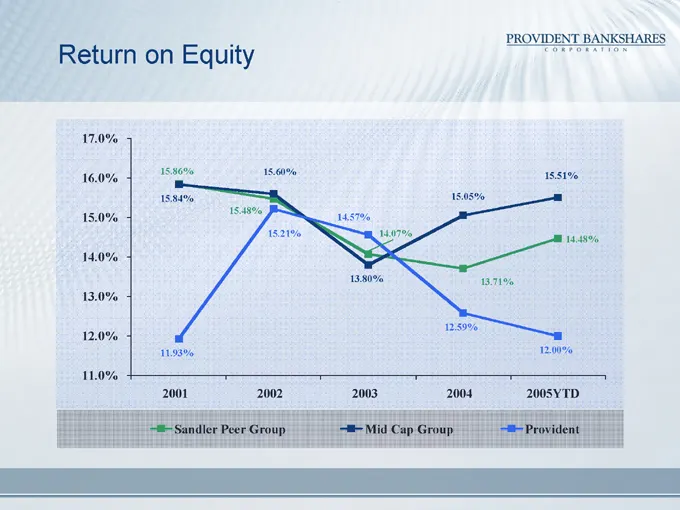
Return on Equity 17.0% 16.0% 15.0% 14.0% 13.0% 12.0% 11.0% 2001 2002 2003 2004 2005YTD 15.86% 15.84% 11.93% 15.60% 15.48% 15.21% 14.57% 14.07% 13.80% 15.05% 13.71% 12.59% 15.51% 14.48% 12.00% Sandler Peer Group Mid Cap Group Provident
Slide 20: Earnings per Share Growth
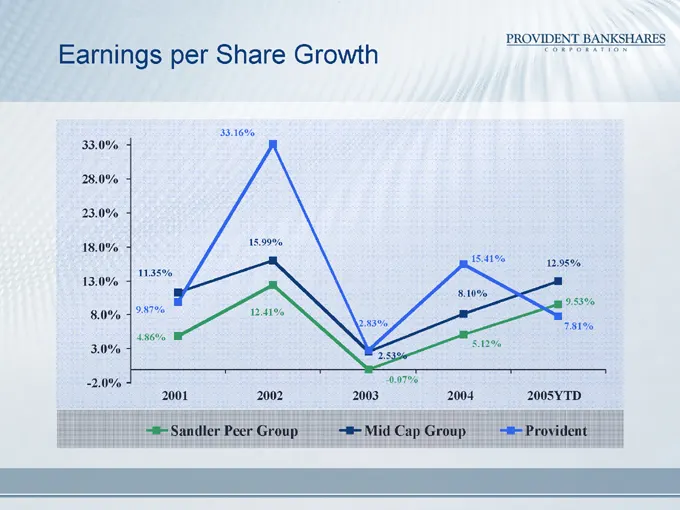
Earnings per Share Growth 33.0% 28.0% 23.0% 18.0% 13.0% 8.0% 3.0% -2.0% 2001 2002 2003 2004 2005YTD 11.35% 9.87% 4.86% 33.16% 15.99% 12.41% 2.83% 2.53% -0.07% 15.41% 8.10% 5.12% 12.95% 9.53% 7.81% Sandler Peer Group Mid Cap Group Provident
Slide 21: Return on Assets
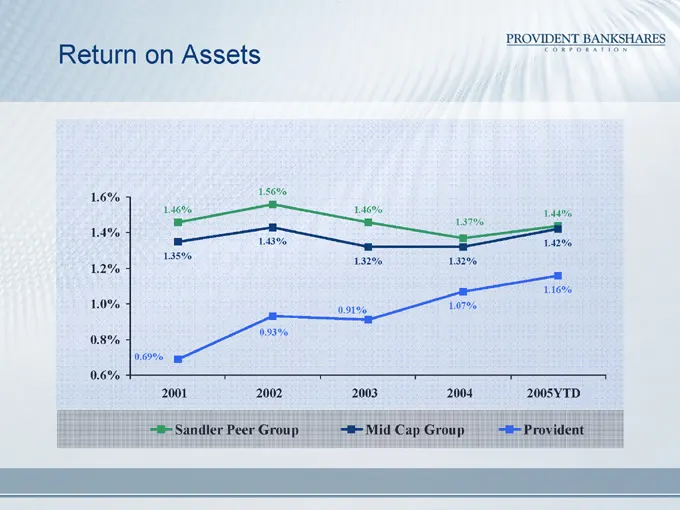
Return on Assets 1.6% 1.4% 1.2% 1.0% 0.8% 0.6% 2001 2002 2003 2004 2005YTD 1.46% 1.35% 0.69% 1.56% 1.43% 0.93% 1.46% 1.32% 0.91% 1.37% 1.32% 1.07% 1.44% 1.42% 1.16% Sandler Peer Group Mid Cap Group Provident
Slide 22: Program Overview
PROGRAM OVERVIEW Kevin Byrnes President and Chief Operating Officer
Slide 23: Convenient Banking
CONVENIENT BANKING Ann Clair Managing Director, Sales Management
Slide 24: Convenient Banking
Convenient Banking Banking Channels In Store Banking Products Future Opportunities
Slide 25: Attractive and Easy to Use Channel Options
Attractive and Easy to Use Channel Options Provident provides more 7-day-a-week banking options than any other bank in Maryland and Virginia. Non-branch banking options provide added convenience Provident Direct opens retail and small business deposit accounts and takes loan applications—all by phon
Slide 26: In Store Network: Why We Are Successful
In Store Network Why We Are Successful We have the right store Partners Our Program supports success We hire and train the right People EDLP Product line
Slide 27: We Have the Right Store Partners
We Have the Right Store Partners Store partnerships primarily with Superfresh, Shoppers Food Warehouse, Wal-Mart and BJ’s Wholesale Club Target similar customer segments Employ complementary pricing methods Select stores where we will be successful
Slide 28: Our Program Supports Success
Our Program Supports Success Independent In-store network structure Value In-store branch contribution Capitalize on 65,000 sq. ft. In-store lobbies Market to 15,000 customers who visit our stores each week Provide attractive variable compensation
Slide 29: We Hire and Train the Right People
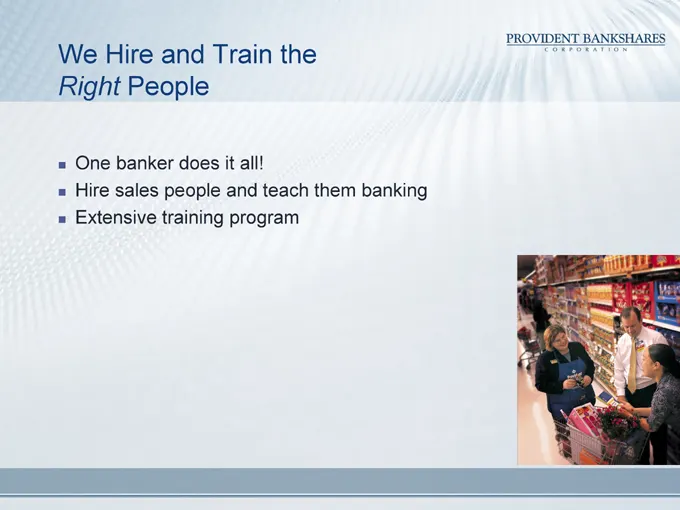
We Hire and Train the Right People One banker does it all! Hire sales people and teach them banking Extensive training program
Slide 30: Competitive Product Line
Competitive Product Line Employ Every Day Low Pricing product pricing methodology Product line appeals to shared customer segments
Slide 31: Products That Meet Customer Financial Needs
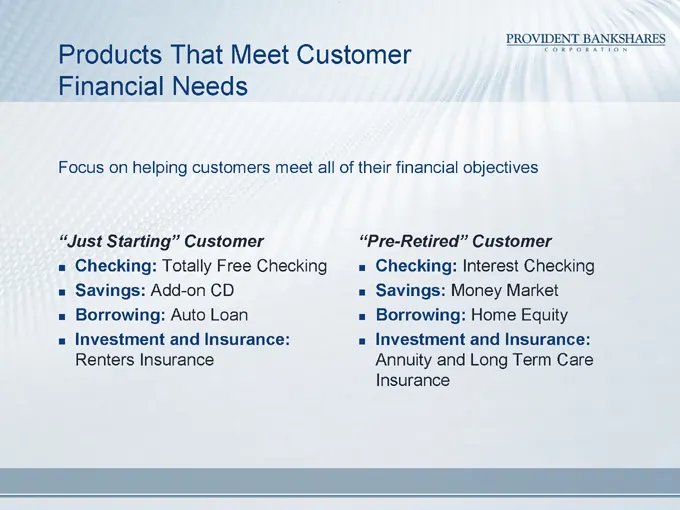
Products That Meet Customer Financial Needs Focus on helping customers meet all of their financial objectives “Just Starting” Customer Checking: Totally Free Checking Savings: Add-on CD Borrowing: Auto Loan Investment and Insurance: Renters Insurance “Pre-Retired” Customer Checking: Interest Checkin
Slide 32: Opportunities
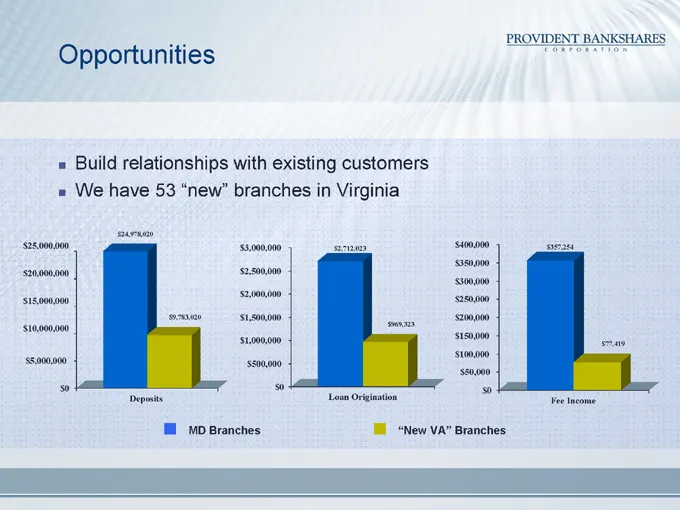
Opportunities Build relationships with existing customers We have 53 “new” branches in Virginia $25,000,000 $20,000,000 $15,000,000 $10,000,000 $5,000,000 $0 $24,978,020 $9,783,020 Deposits $3,000,000 $2,500,000 $2,000,000 $1,500,000 $1,000,000 $500,000 $0 $2,712,023 $969,323 Loan Origination $400,0
Slide 33: Branch Network
Branch Network Our branch network is well positioned in the Greater Baltimore, Suburban Washington and Richmond market areas
Slide 34: Consumer Lending
CONSUMER LENDING Eric Dawes Managing Director, Consumer Lending Division
Slide 35: Core Competency
Core Competency Quality products with very competitive pricing. Streamlined home equity approval to closing process. Effective delivery channels with home equity expertise.
Slide 36: Consumer Loan Work Flow
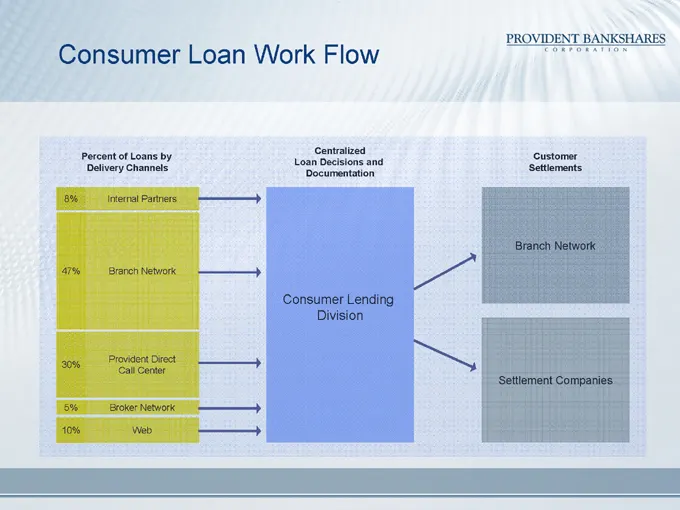
Consumer Loan Work Flow Percent of Loans by Delivery Channels 8% Internal Partners 47% Branch Network Provident Direct 30% Call Center 5% Broker Network 10% Web Centralized Loan Decisions and Documentation Consumer Lending Division Customer Settlements Branch Network Settlement Companies
Slide 37: Core Competency
Core Competency Loan Field Specialist Ability to quickly respond to changing market conditions Real estate market knowledge
Slide 38: Total Consumer Loan Production Compared to Home Equity Production
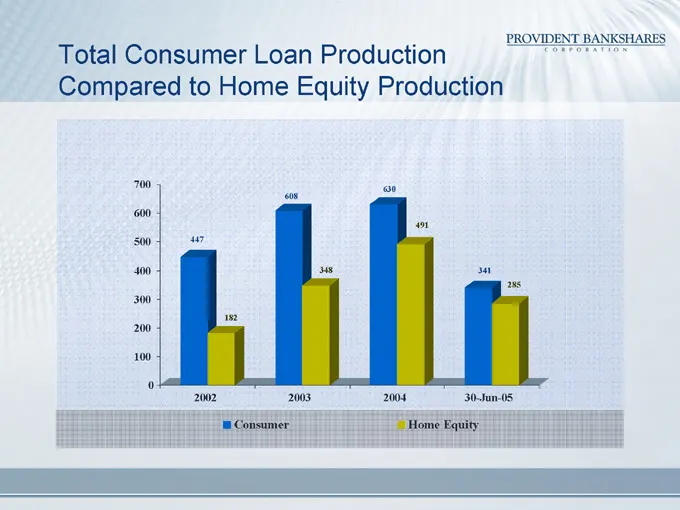
Total Consumer Loan Production Compared to Home Equity Production 700 600 500 400 300 200 100 0 2002 2003 2004 30-Jun-05 Consumer Home Equity
Slide 39: Market Opportunities
Market Opportunities Housing market growth Introduction of new home equity products and services Total Home Equity (fixed line/loan) Home Equity Retention Program
Slide 40: Virginia Market Opportunities
Virginia Market Opportunities Northern VA focus. PNC has entered the D.C. metro market with acquisition of Riggs. Track 10 bank competitors with branch offices that we compete with for home equity loans.
Slide 41: Market Opportunity
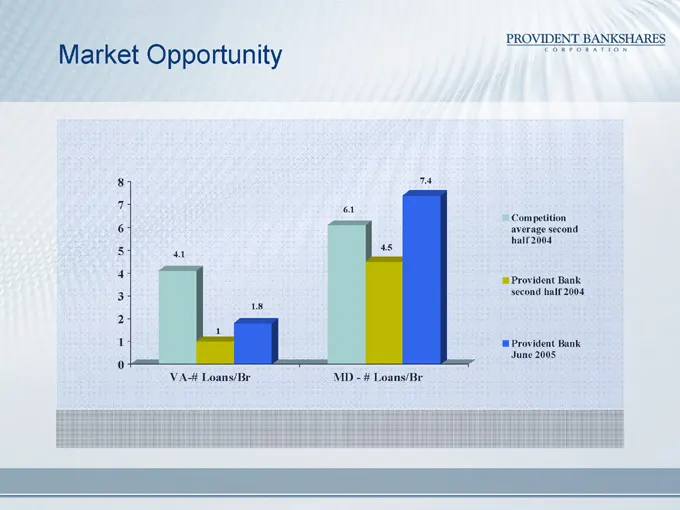
Market Opportunity 8 7 6 5 4 3 2 1 0 4.1 1.8 VA-# Loans/Br 6.1 4.5 7.4 MD - # Loans/Br Competition average second half 2004 Provident Bank second half 2004 Provident Bank June 2005
Slide 42: Home Equity Originations By State
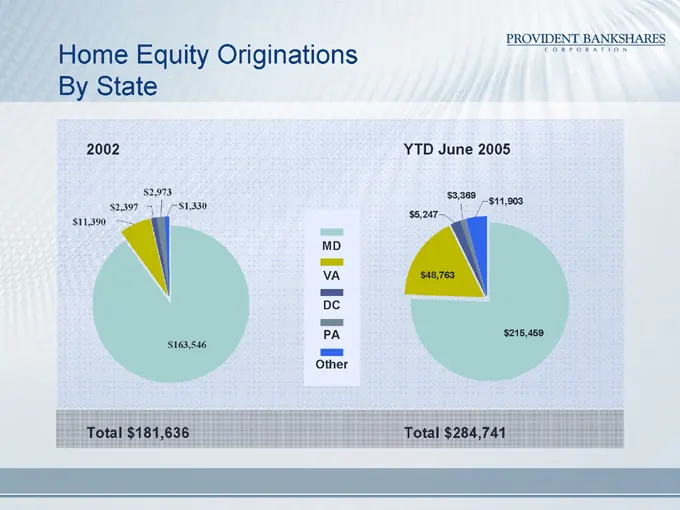
Home Equity Originations By State 2002 $11,390 $2,397 $2,973 $1,330 $163,546 MD VA DC PA Other YTD June 2005 $5,247 $3,369 $11,903 $48,763 $215,459 Total $181,636 Total $284,741
Slide 43: Competitive Advantage
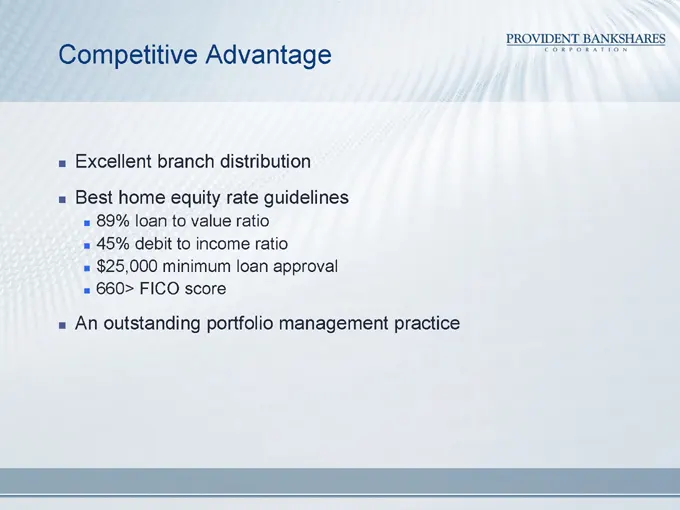
Competitive Advantage Excellent branch distribution Best home equity rate guidelines 89% loan to value ratio 45% debit to income ratio $25,000 minimum loan approval 660> FICO score An outstanding portfolio management practice
Slide 44: Portfolio Highlights
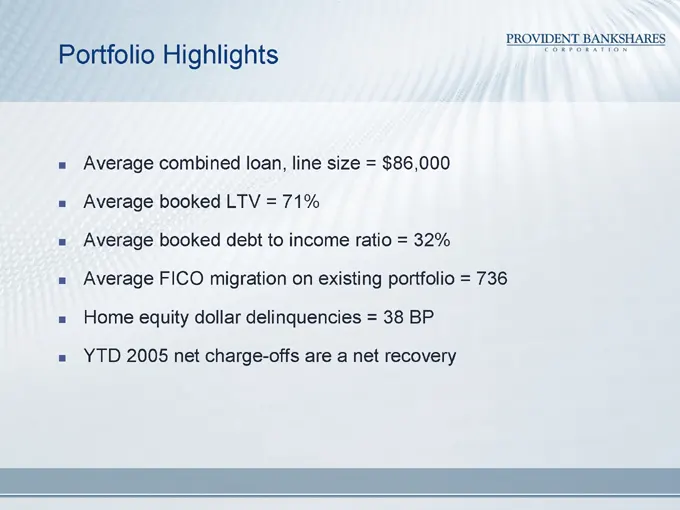
Portfolio Highlights Average combined loan, line size = $86,000 Average booked LTV = 71% Average booked debt to income ratio = 32% Average FICO migration on existing portfolio = 736 Home equity dollar delinquencies = 38 BP YTD 2005 net charge-offs are a net recovery
Slide 45: How We Will Better Execute Our Plan
How We Will Better Execute Our Plan Increase promotional spend Improve technology Increase branch support Implement new product line Second looks at all declined loans
Slide 46: Cash Management
CASH MANAGEMENT John Goedeke Senior Vice President / Division Head Commercial Services Division
Slide 47: Cash Management
Cash Management History Product offerings Outsourcing
Slide 48: Cash Management Strategy
Cash Management Sales Strategy Customer service Time sensitive services Implementation team Product Strategy Reliable products Moderately priced Sweep accounts
Slide 49: Cash Management Target Markets
Cash Management Target Markets Neglected relationships Time sensitive services Success story
Slide 50: Analysis Fees Assessed
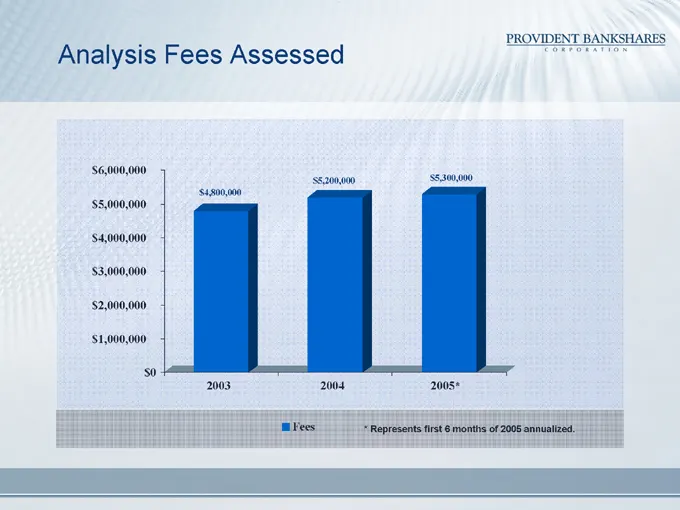
Analysis Fees Assessed $6,000,000 $5,000,000 $4,000,000 $3,000,000 $2,000,000 $1,000,000 $0 2003 2004 2005* $4,800,000 $5,200,000 $5,300,000 Fees * Represents first 6 months of 2005 annualized.
Slide 51: Analysis DDA Average Balance
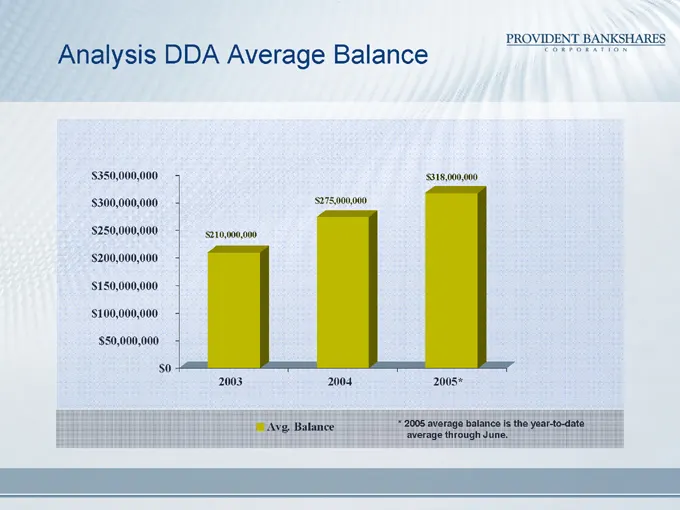
Analysis DDA Average Balance $350,000,000 $300,000,000 $250,000,000 $200,000,000 $150,000,000 $100,000,000 $50,000,000 $0 2003 2004 2005* $210,000,000 $275,000,000 $318,000,000 Avg. Balance * 2005 average balance is the year-to-date average through June.
Slide 52: Cash Management New Initiatives
Cash Management New Initiatives Product management ARTS Payroll processing strategic alliance Rate strategies
Slide 53: Cash Management New Initiatives
Cash Management New Initiatives Sales Management Telephone sales Automated Client Review Sales training and proposal software Virginia market potential
Slide 54: Development of Real Estate Lending into New Markets
DEVELOPMENT OF REAL ESTATE LENDING INTO NEW MARKETS Cecilia Hodges Managing Director George Decker Senior Vice President
Slide 55: Provident Real Estate Centers
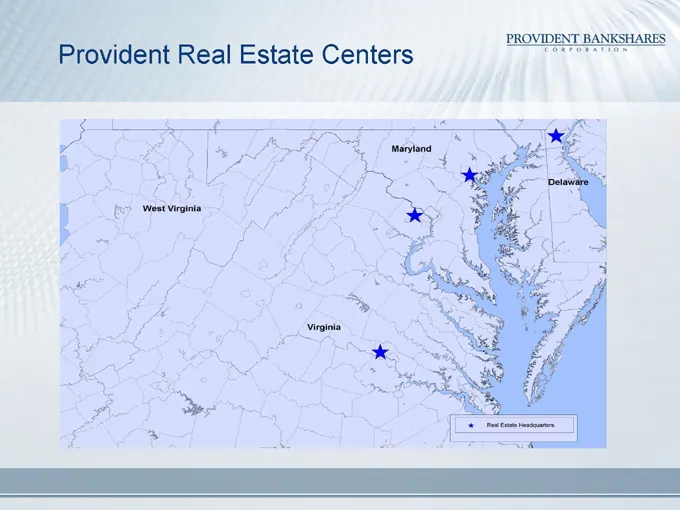
Provident Real Estate Centers
Slide 56: Real Estate Portfolio at Provident Bank
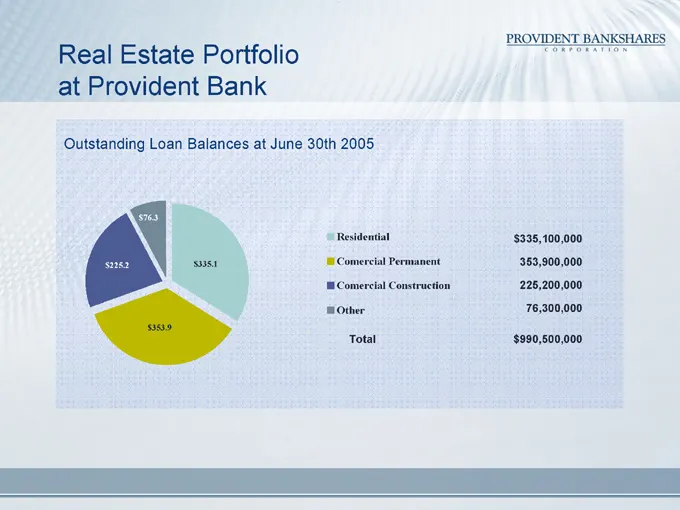
Real Estate Portfolio at Provident Bank Outstanding Loan Balances at June 30th 2005 $225.2 $76.3 $335.1 $353.9 Residential $ 335,100,000 Comercial Permanent 353,900,000 Comercial Construction 225,200,000 Other 76,300,000 Total $ 990,500,000
Slide 57: Loan Outstandings
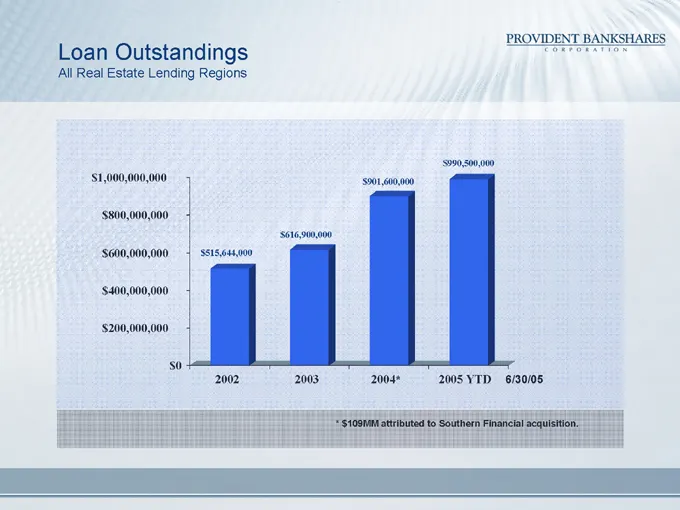
Loan Outstandings All Real Estate Lending Regions $1,000,000,000 $800,000,000 $600,000,000 $400,000,000 $200,000,000 $0 2002 2003 2004* 2005 YTD 6/30/05 $515,644,000 $616,900,000 $901,600,000 $990,500,000 * $ 109MM attributed to Southern Financial acquisition.
Slide 58: Asset Quality
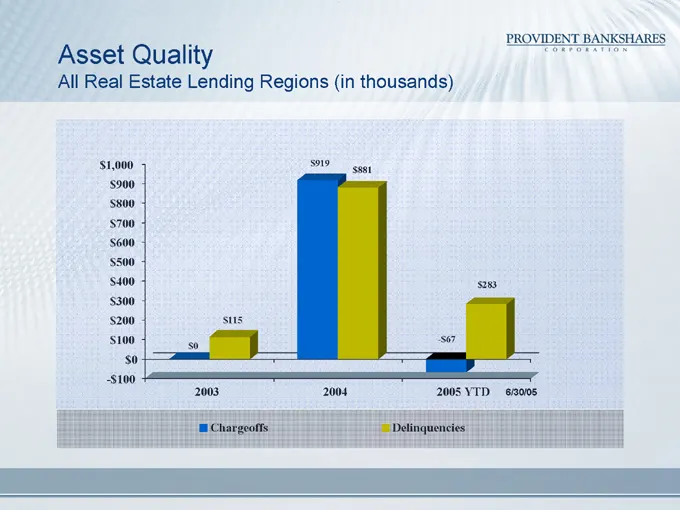
Asset Quality All Real Estate Lending Regions (in thousands) $1,000 $900 $800 $700 $600 $500 $400 $300 $200 $100 $0 -$100 2003 2004 2005 YTD 6/30/05 $0 $115 $919 $881 -$67 $283 Chargeoffs Delinquencies
Slide 59: Growth in Loan Production
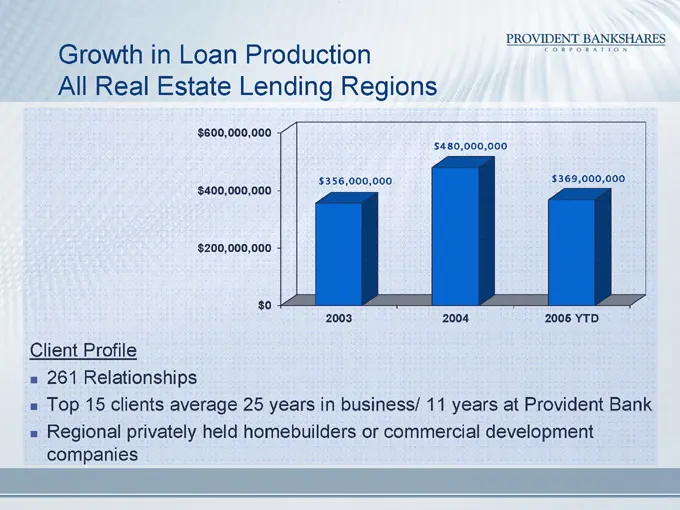
Growth in Loan Production All Real Estate Lending Regions $600,000,000 $400,000,000 $200,000,000 $0 2003 2004 2005 YTD $356,000,000 $480,000,000 $369,000,000 Client Profile 261 Relationships Top 15 clients average 25 years in business/ 11 years at Provident Bank Regional privately held homebuilders
Slide 60: Points of Differentiation and Growth Factors
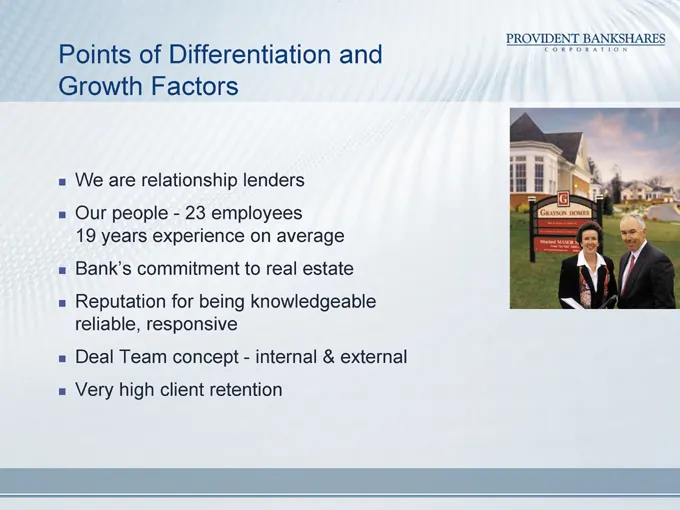
Points of Differentiation and Growth Factors We are relationship lenders Our people - 23 employees 19 years experience on average Bank’s commitment to real estate Reputation for being knowledgeable reliable, responsive Deal Team concept - internal & external Very high client retention
Slide 61: Cross Sell Deposit Growth
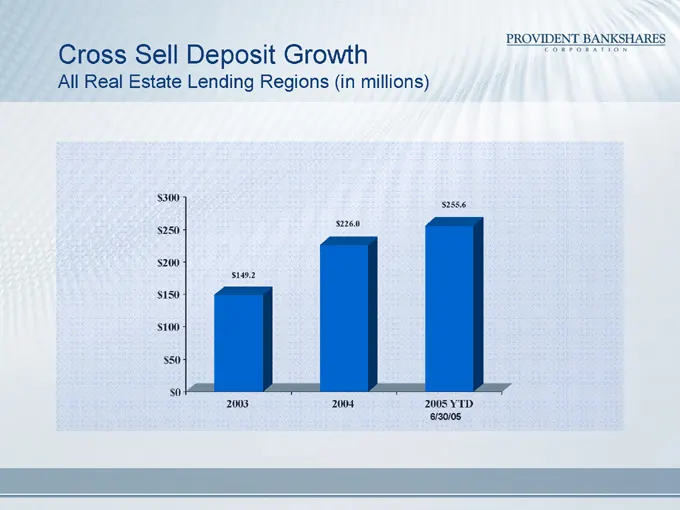
Cross Sell Deposit Growth All Real Estate Lending Regions (in millions) $300 $250 $200 $150 $100 $50 $0 2003 2004 2005 YTD 6/30/05 $149.2 $226.0 $255.6
Slide 62: Virginia Opportunities for Expansion
Virginia Opportunities for Expansion Additional opportunities in Washington Metro/DC Market Central Virginia Custom Homebuilder
Slide 63: Primary Housing Market
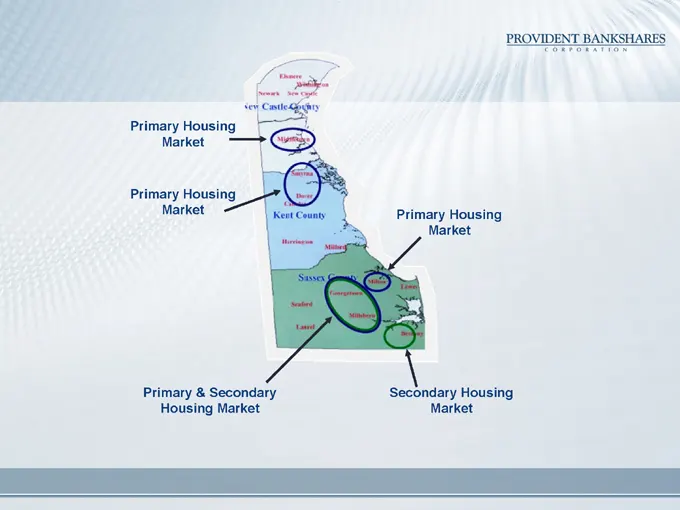
Primary Housing Market Primary Housing Market Primary & Secondary Housing Market Secondary Housing Market Primary Housing Market
Slide 64: Reasons to Lend in Delaware
Reasons to Lend in Delaware Maryland homebuilder clients are active in Delaware Delaware housing market is active Delaware builders meet Provident client profile Provident real estate lending success
Slide 65: Expected Results of Lending in Delaware
Expected Results of Lending in Delaware Ongoing/expansion source of real estate loans Opportunity to increase loans with Maryland builders Opportunity to bring new clients to Provident
Slide 66: Relationship Sales Culture
RELATIONSHIP SALES CULTURE John King Group Manager Consumer Banking
Slide 67: Relationship Sales Culture
Relationship Sales Culture Why the change? What is it? Where are we?
Slide 68: Relationship Sales Culture: 1993 Crossroads
Relationship Sales Culture 1993 Crossroads Stagnant Growth Savings Bank Carry Over
Slide 69: Relationship Sales Culture: 1993 Evolution
Relationship Sales Culture 1993 Evolution HPC In-Store Exception Decisioning
Slide 70: Relationship Sales Culture: 1993 to 2005
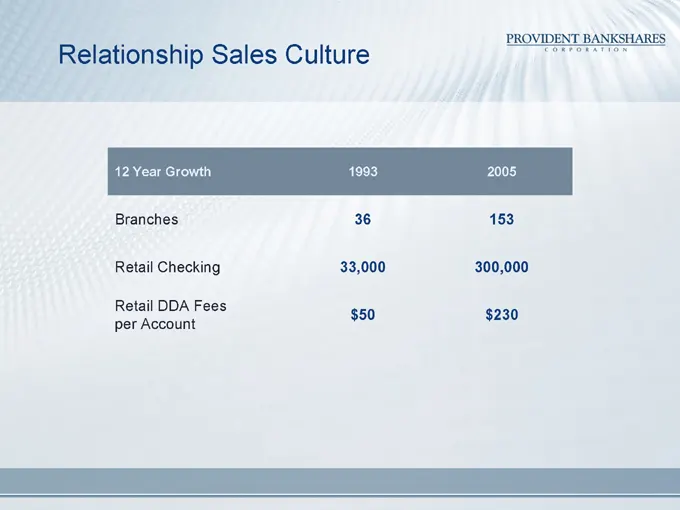
Relationship Sales Culture 12 Year Growth 1993 2005 Branches 36 153 Retail Checking 33,000 300,000 Retail DDA Fees $50 $230 per Account
Slide 71: Today's Crossroads
Relationship Sales Culture Today’s Crossroads Free checking competition Customer behavior changes Efficiency needs Product driven
Slide 72: Households and Cross Sell
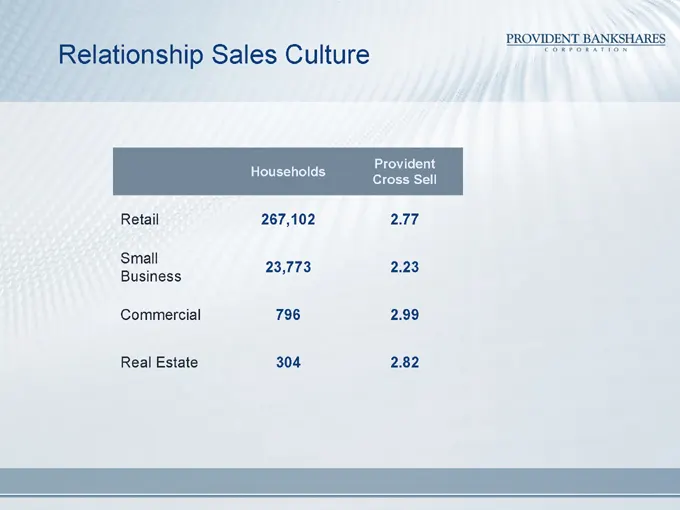
Relationship Sales Culture Households Provident Cross Sell Retail 267,102 2.77 Small Business 23,773 2.23 Commercial 796 2.99 Real Estate 304 2.82
Slide 73: How Do We Get There?
Relationship Sales Culture How Do We Get There? Spring 2004 Hired consultant to assess our environment by seeking employee input on issues Summer 2004 40 Employees - Cross Divisional - 3 day offsite Define how to achieve a Relationship Sales Culture Fall-Winter 2004 6 Project Teams pursued ways to m
Slide 74: How Do We Get There?
Relationship Sales Culture How Do We Get There? Spring 2005 6 new teams were formed to evaluate and implement the recommendations Every area of the bank is represented A member of executive management is assigned to champion each team
Slide 75: Teams
Relationship Sales Culture Teams The Provident Way Technology/Systems/Online Resources Goals and Compensation Staffing and Training Policy and Procedure Employee Resources
Slide 76: Initiatives Completed
Relationship Sales Culture Initiatives Completed Relationship exception decision making Prize patrols Ads/commercials on intranet Branch segmentation on intranet Product representative at orientation Communication/customer/service standards Increased debit card limits Relationship building incentive
Slide 77: Initiatives In Process
Relationship Sales Culture Initiatives In Process Branch greeters One-view screen Sales referral card Cultural training ‘Living the Provident Way’ video Institutionalize success stories Monthly mystery shops
Slide 78: Defining Success
Relationship Sales Culture Defining Success Short Term Interdepartmental referrals Recommendation implementation Early trends on cross-sell, customer retention Long Term Interdepartmental referral goals and performance Cross-sell goals Customer retention goals New customer attrition Provident employ
Slide 79: Success Story
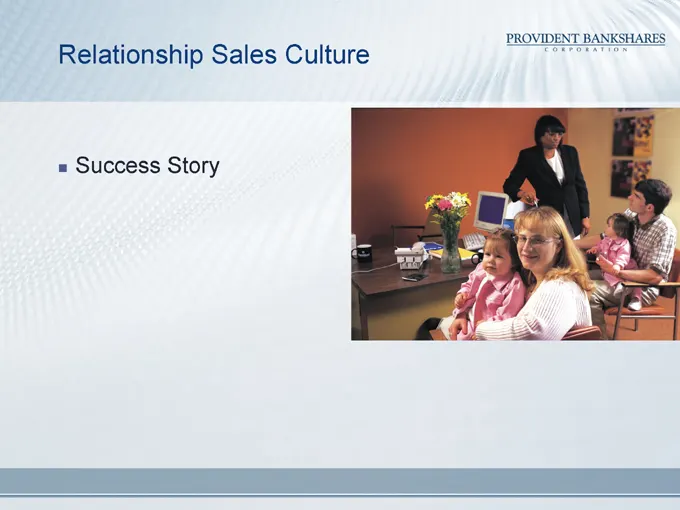
Relationship Sales Culture Success Story
Slide 80: Cross-Sell Raises Retention
Relationship Sales Culture Selling one additional product to a household with 1 product increases their retention from 83% to 92% 1 more to 400,000
Slide 81: Small Business
SMALL BUSINESS Rich Hunt SVP / Division Head, Small Business Jim Prusak SVP, Consumer Banking Division
Slide 82: Strategy
Strategy To be the “Unparalleled Leader” in establishing and maintaining value-added relationships with the small business owners in our footprint, now and in the future Definition of Small Business Provident defines a Small Business as a company with revenues up to $5 million and credit requirement
Slide 83: Opportunity
Opportunity There are over 383,000 Small Businesses located in our Maryland and Virginia marketplace. Currently, Provident has relationships with only 7.8% of these businesses. We have a huge opportunity to exploit.
Slide 84: Challenges
Challenges Focusing on cross sell, not just being a lender Increased competition Establishing effective partnerships both internally and externally Centralized support and continued product enhancement Effective delivery channels
Slide 85: Sales Philosophy
Sales Philosophy A business loan is not enough. Our sales force will go after the company’s entire banking relationship: business, owner and employees. Developing relationships through persistent cross-selling is our standard for excellence.
Slide 86: Delivery Channels
Delivery Channels How it all fits together Relationship Managers Commercial Branch Managers Small Business Financial Consultants (Provident Direct Call Center Team) Branch Managers Right Size Bank - Providing the small business customer with choices
Slide 87: Partnerships
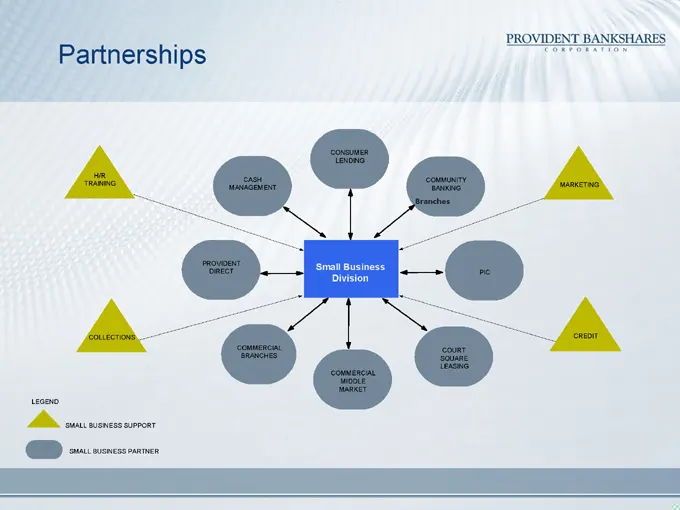
Partnerships Small Business Division H/R TRAINING COLLECTIONS MARKETING CREDIT CASH MANAGEMENT CONSUMER LENDING COMMUNITY BANKING Branches PIC COURT SQUARE LEASING COMMERCIAL MIDDLE MARKET COMMERCIAL BRANCHES PROVIDENT DIRECT LEGEND SMALL BUSINESS SUPPORT SMALL BUSINESS PARTNER
Slide 88: Branch Banking's Small Business Focus
Branch Banking’s Small Business Focus… Why are we having one 30,000 Small Business Customers Importance of deepening these relationships: The average small business customer life span with a bank is 7 years. Increase customer loyalty by focusing on life cycle of business owner (it’s not just about c
Slide 89: Small Business Focus
Small Business Focus Commercial Branches 12 Commercial Branches in the Network What is a Commercial Manager? What is a Commercial Branch?
Slide 90: Small Business 2005 Initiatives
Small Business 2005 InitiativesWhat we have done to date HUGS Phase 1 Commercial Call Training Branch Network Referral Program Business Plus Line
Slide 91: Small Business Initiatives
Small Business Initiatives… What are we going to be doing? HUGS 2 Small Business Outreach Days Additional 12-14 Commercial branches planned for the 4th Qtr Comprehensive Training Program Phase 1: Introductory – Focuses on Sales Phase 2: Intermediate - Focuses on Credit and Sales Phase 3: Advanced –
Slide 92: Results To Date
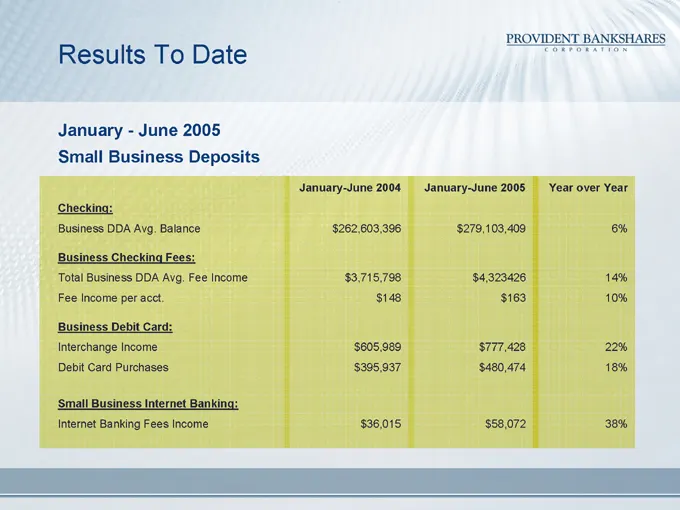
Results To Date January - June 2005 Small Business Deposits January-June 2004 January-June 2005 Year over Year Checking: Business DDA Avg. Balance $262,603,396 $279,103,409 6% Business Checking Fees: Total Business DDA Avg. Fee Income $3,715,798 $4,323426 14% Fee Income per acct. $148 $163 10% Busin
Slide 93: Results To Date
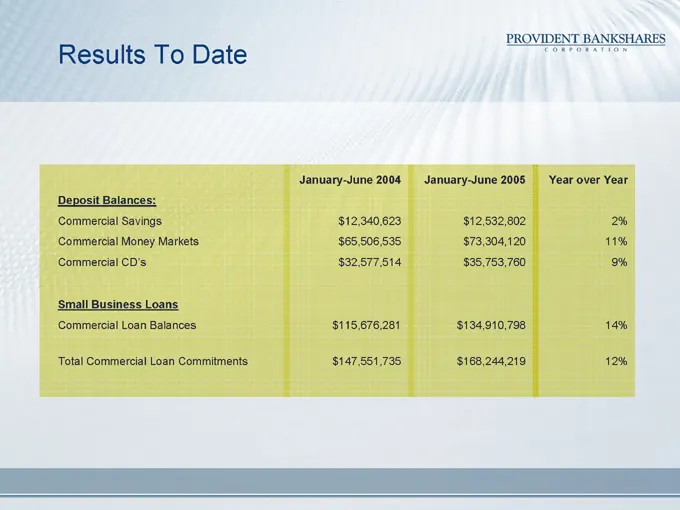
Results To Date January-June 2004 January-June 2005 Year over Year Deposit Balances: Commercial Savings $12,340,623 $12,532,802 2% Commercial Money Markets $65,506,535 $73,304,120 11% Commercial CD’s $32,577,514 $35,753,760 9% Small Business Loans Commercial Loan Balances $115,676,281 $134,910,798 1
Slide 94: New Products/Services and Advertising Strategies
NEW PRODUCTS/SERVICES AND ADVERTISING STRATEGIES Lillian Suffolk Kilroy Chief Marketing Officer & Managing Director, Consumer Products
Slide 95: New Products 2005 / 2006
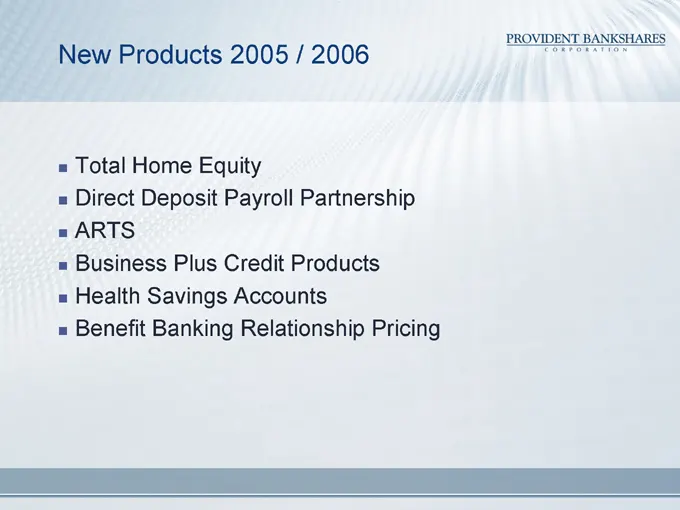
New Products 2005 / 2006 Total Home Equity Direct Deposit Payroll Partnership ARTS Business Plus Credit Products Health Savings Accounts Benefit Banking Relationship Pricing
Slide 96: Health Savings Accounts
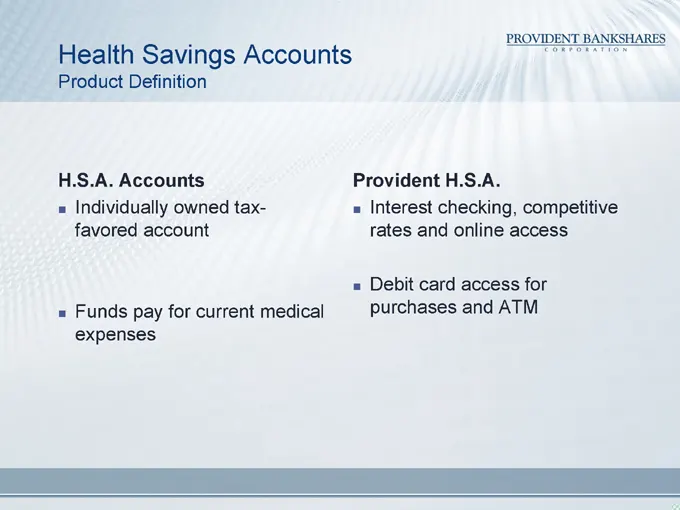
Health Savings Accounts Product Definition H.S.A. Accounts Individually owned tax-favored account Funds pay for current medical expenses Provident H.S.A. Interest checking, competitive rates and online access Debit card access for purchases and ATM
Slide 97: Health Savings Accounts
Health Savings Accounts Product Definition H.S.A. Accounts Provident H.S.A. Funds saved for future qualified expenses Works with High Deductible Health Plan Competitive interest rates, brokerage option Available through Provident Insurance Network
Slide 98: Health Savings Accounts Target Market
Health Savings Accounts Target Market Small businesses <25 employees Professional firms Partnerships Individuals Forrester Research estimates H.S.A. plans will attract 22 million workers — 12% of commercially insured market — by 2008
Slide 99: Health Savings Accounts Market Opportunity
Health Savings Accounts Market Opportunity Direct Sales 30,000 Provident Small Business customers Focused calling program Joint HDHC/H.S.A. sales opportunity Broker Sales Negotiations with Maryland/Virginia TPAs Product line extensions
Slide 100: Benefit Banking Overall Strategy
Benefit Banking Overall Strategy Relationship pricing program that rewards customers who have their primary banking relationship at Provident with the best rates on products and services.
Slide 101: Benefit Banking Program Definition
Benefit Banking Program Definition Customers with direct deposit and a debit card receive: Higher rates on savings, money markets and CDs Lower rates on home equity, auto and boat loans Free Internet Banking with Bill Payment
Slide 102: Benefit Banking Program Objectives
Benefit Banking Program Objectives Make Provident the primary bank for more customers Increase customer profitability Grow customer wallet share Increase customer retention
Slide 103: Benefit Banking Financial Benefits
Benefit Banking Financials Benefits A customer with checking, direct deposit and an active debit card contributes $282 per year 94,000 current customers qualify for Benefit Banking Active promotional programs for acquisition, cross sell and retention in 2006
Slide 104: Just the Right Size for You
Provident Bank Just the Right Size for You Brand Position Conveniently deliver the product/service depth and breath of big banks With personal attention, market expertise and attention to detail provided by only the best community banks
Slide 105: Increasing Awareness in Our Markets
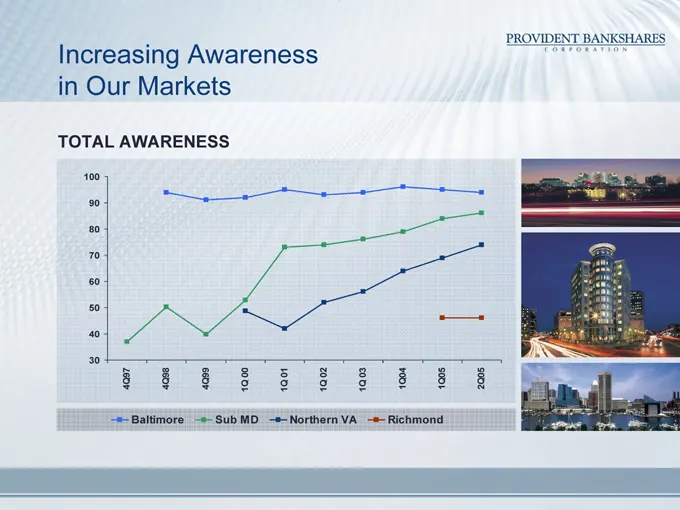
Increasing Awareness in Our Markets TOTAL AWARENESS 100 90 80 70 60 50 40 30 4Q97 4Q98 4Q99 1Q 00 1Q 01 1Q 02 1Q 03 1Q04 1Q05 2Q05 Baltimore Sub MD Northern VA Richmond
Slide 106: Advertisement Placement Strategy
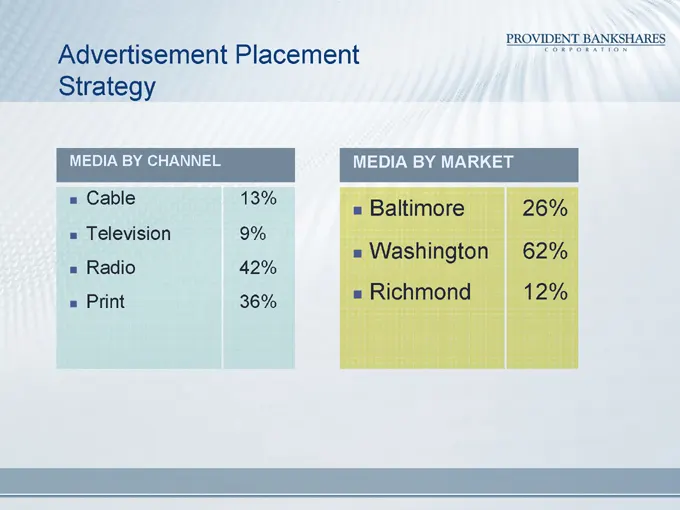
Advertisement Placement Strategy MEDIA BY CHANNEL MEDIA BY MARKET Cable 13% Television 9% Radio 42% Print 36% Baltimore 26% Washington 62% Richmond 12%
Slide 107: It All Works In Concert
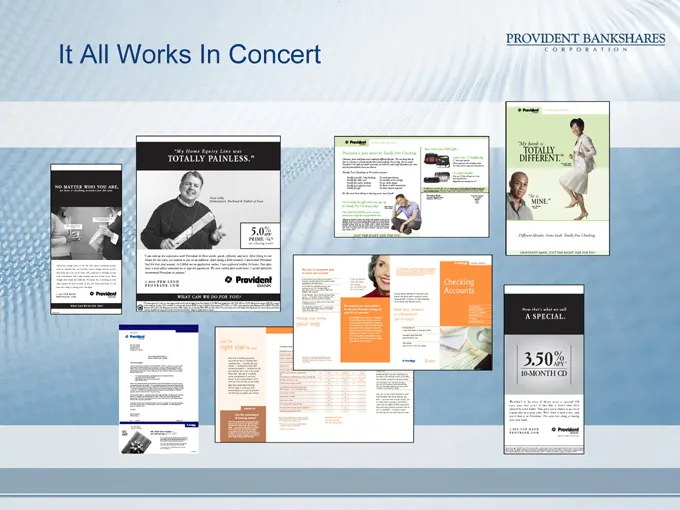
It All Works In Concert
Slide 108: Provident Bankshares Corporation
PROVIDENT BANKSHARES CORPORATION www.provbank.com Contact Media: Lillian Kilroy (410) 277-2833 Investment Community: Melissa Kelly (410) 277-2080
Source: SEC EDGAR · 8-K filed Sep 9, 2005
More decks from Provident Bankshares Corp
 Merger or Acquisition (December 2008)32 slides · Dec 19, 2008
 2007 Stifel Nicolaus Financial Institutions Investor Conference52 slides · Dec 6, 2007
 Investor Presentation (November 2007)49 slides · Nov 8, 2007
 FTN Midwest Small and Mid Cap Bank Conference 200757 slides · Sep 6, 2007
 Investor Presentation (May 2007)51 slides · May 8, 2007
 KBW Regional Bank Conference 200751 slides · Feb 28, 2007