DPL — Merrill Lynch Power & Gas Leaders Conference 2008
32 slides from DPL's conference presentation, Sep 19, 2008
Slide 1: Merrill Lynch Power & Gas Leaders Conference
Merrill Lynch Power & Gas Leaders Conference Paul M. Barbas President and Chief Executive Officer September 23 – 24, 2008
Slide 2: Notice Regarding Forward-Looking Statement
1 Merrill Lynch Power & Gas Leaders Conference Investor Relations Contact Craig Jackson Assistant Treasurer (937) 259-7033 [email protected] Notice Regarding Forward-Looking Statement Certain statements contained in this presentation are “forward-looking statements” within the meaning of the
Slide 3: REG G Disclosure
2 Merrill Lynch Power & Gas Leaders Conference REG G Disclosure Today’s discussion contains certain non-GAAP financial measures as defined under SEC Regulation G. Generally, a non-GAAP financial measure is a numerical measure of a company’s historical or future financial performance, financial posit
Slide 4: Agenda
3 Merrill Lynch Power & Gas Leaders Conference Agenda Topic Page(s) Ohio Energy Bill 4 - 12 Fuel Strategy 13 - 16 Plant Performance 17 - 19 Appendix 20 - 30
Slide 5: Ohio Energy Bill (SB 221)
Ohio Energy Bill (SB 221) September 23 – 24, 2008
Slide 6: Ohio Energy Bill (SB 221) – PUCO published draft rules
5 Merrill Lynch Power & Gas Leaders Conference Ohio Energy Bill (SB 221) – Public Utilities Commission of Ohio published draft rules in July and August – DP&L able to incorporate terms and conditions of its current rate stabilization plan into required filing of electric security plan – Allows us to
Slide 7: Ohio Energy Bill: DPL's Next Steps
6 Merrill Lynch Power & Gas Leaders Conference Ohio Energy Bill DPL’s Next Steps – Currently reviewing AEP, Duke, and First Energy filings – File an Electric Security Plan (ESP) during the 4th quarter 2008 – ESP filing will include: Terms and conditions of existing rate stabilization plan Recovery o
Slide 8: Ohio Energy Bill: Existing Rate Stabilization Plan
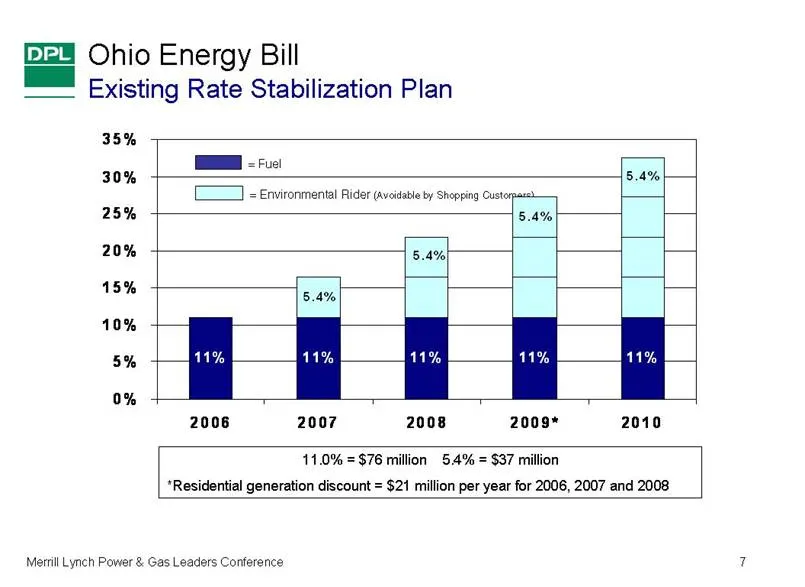
7 Merrill Lynch Power & Gas Leaders Conference 11.0% = $76 million 5.4% = $37 million *Residential generation discount = $21 million per year for 2006, 2007 and 2008 = Fuel = Environmental Rider (Avoidable by Shopping Customers) Ohio Energy Bill Existing Rate Stabilization Plan 11% 11% 11% 11% 11% 5
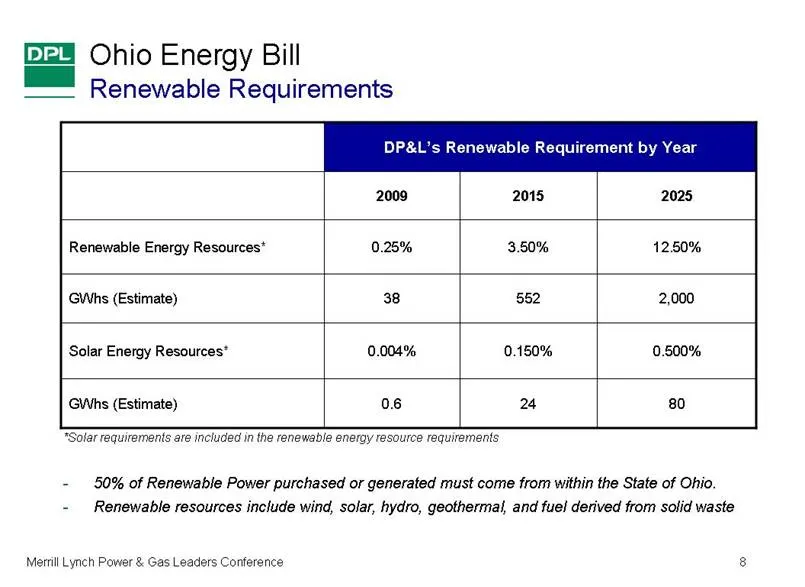
Slide 9: Ohio Energy Bill Renewable Requirements
8 Merrill Lynch Power & Gas Leaders Conference DP&L’s Renewable Requirement by Year 2,000 552 38 GWhs (Estimate) 80 24 0.6 GWhs (Estimate) 0.500% 0.150% 0.004% Solar Energy Resources* 12.50% 3.50% 0.25% Renewable Energy Resources* 2025 2015 2009 Ohio Energy Bill Renewable Requirements *Solar require
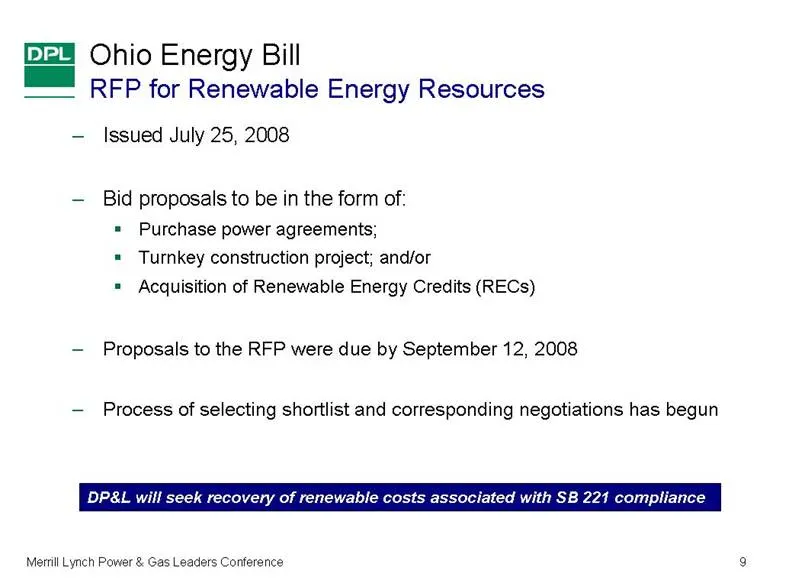
Slide 10: RFP for Renewable Energy Resources
9 Merrill Lynch Power & Gas Leaders Conference Ohio Energy Bill RFP for Renewable Energy Resources – Issued July 25, 2008 – Bid proposals to be in the form of: Purchase power agreements; Turnkey construction project; and/or Acquisition of Renewable Energy Credits (RECs) – Proposals to the RFP were d
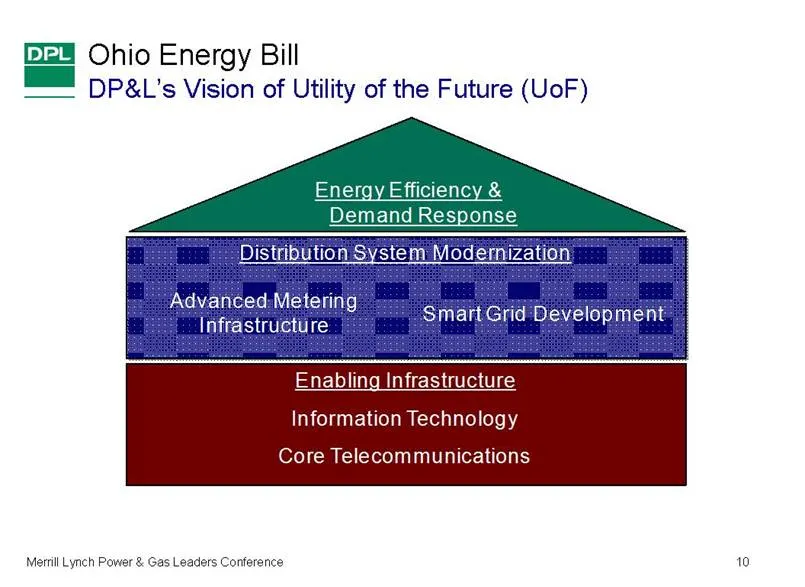
Slide 11: DP&L's Vision of Utility of the Future
10 Merrill Lynch Power & Gas Leaders Conference Distribution System Modernization Energy Efficiency & Demand Response Enabling Infrastructure Information Technology Core Telecommunications Advanced Metering Infrastructure Smart Grid Development Ohio Energy Bill DP&L’s Vision of Utility of the Future
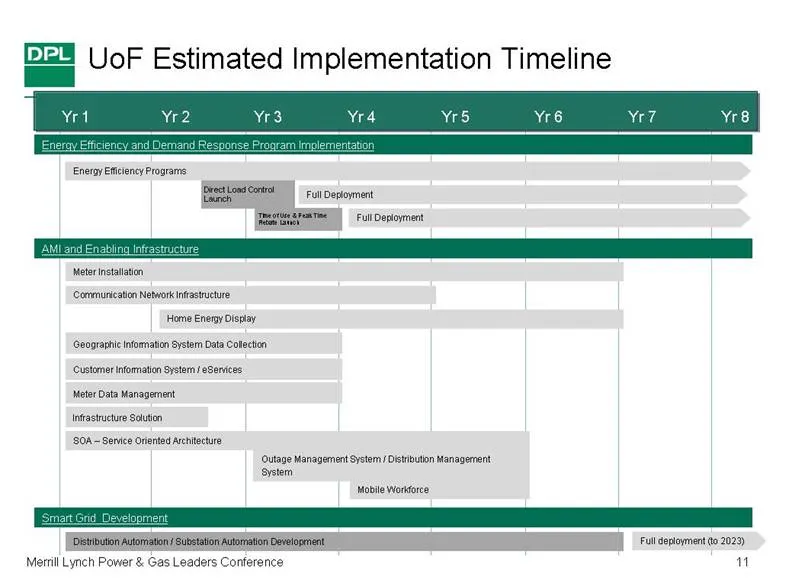
Slide 12: UoF Estimated Implementation Timeline
11 Merrill Lynch Power & Gas Leaders Conference Yr 1 Yr 2 Yr 3 Yr 4 Yr 5 Yr 6 Yr 7 Yr 8 AMI and Enabling Infrastructure Meter Installation Communication Network Infrastructure Home Energy Display Geographic Information System Data Collection Smart Grid Development Customer Information System / eServ
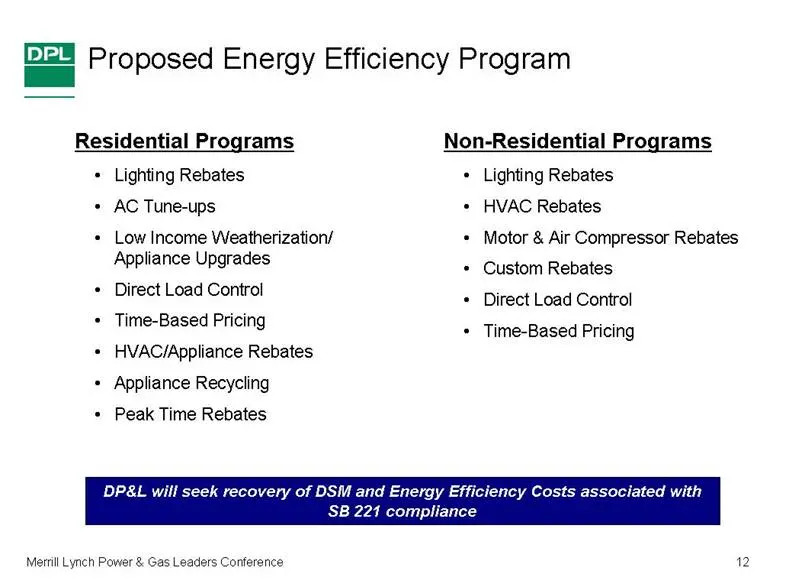
Slide 13: Proposed Energy Efficiency Program
12 Merrill Lynch Power & Gas Leaders Conference Residential Programs • Lighting Rebates • AC Tune-ups • Low Income Weatherization/Appliance Upgrades • Direct Load Control • Time-Based Pricing • HVAC/Appliance Rebates • Appliance Recycling • Peak Time Rebates Non-Residential Programs • Lighting Rebat
Slide 14: Fuel Strategy
Fuel Strategy September 23 – 24, 2008
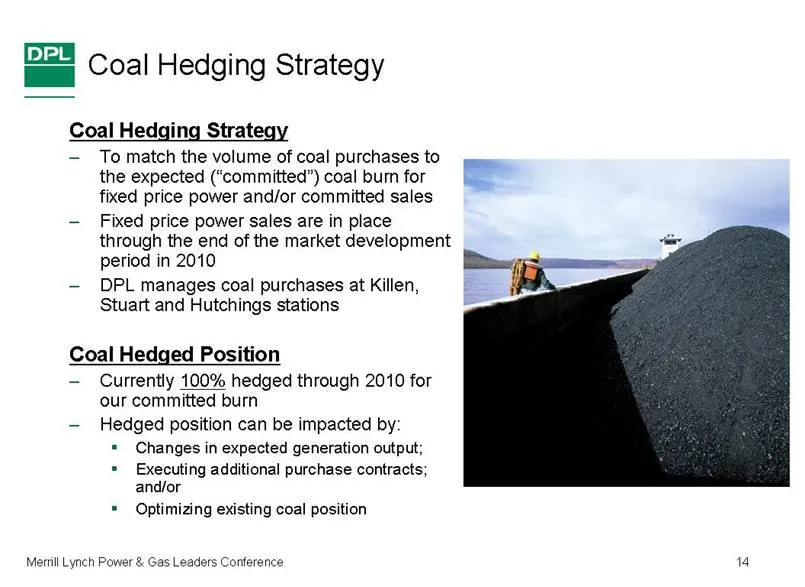
Slide 15: Coal Hedging Strategy
14 Merrill Lynch Power & Gas Leaders Conference Coal Hedging Strategy Coal Hedging Strategy – To match the volume of coal purchases to the expected (“committed”) coal burn for fixed price power and/or committed sales – Fixed price power sales are in place through the end of the market development pe
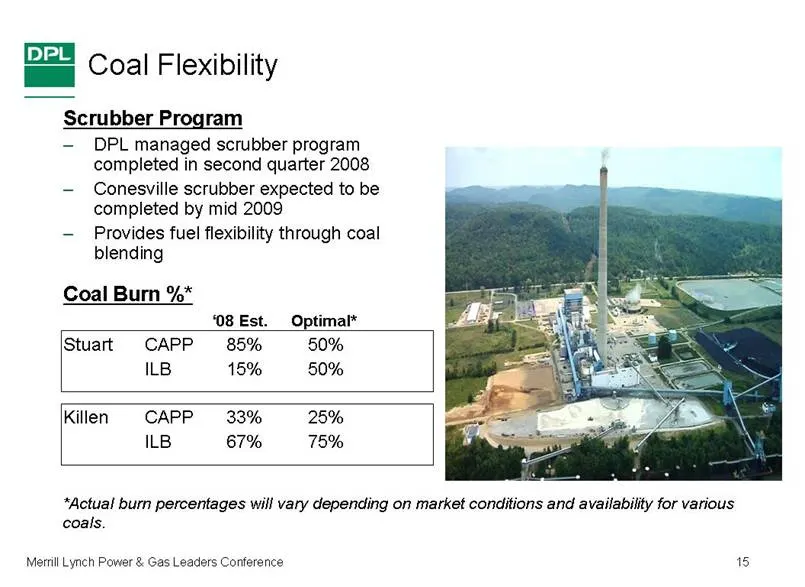
Slide 16: Coal Flexibility
15 Merrill Lynch Power & Gas Leaders Conference Coal Flexibility Scrubber Program – DPL managed scrubber program completed in second quarter 2008 – Conesville scrubber expected to be completed by mid 2009 – Provides fuel flexibility through coal blending Coal Burn %* ‘08 Est. Optimal* Stuart CAPP 85
Slide 17: Hedging Strategy: Coal Transportation Costs
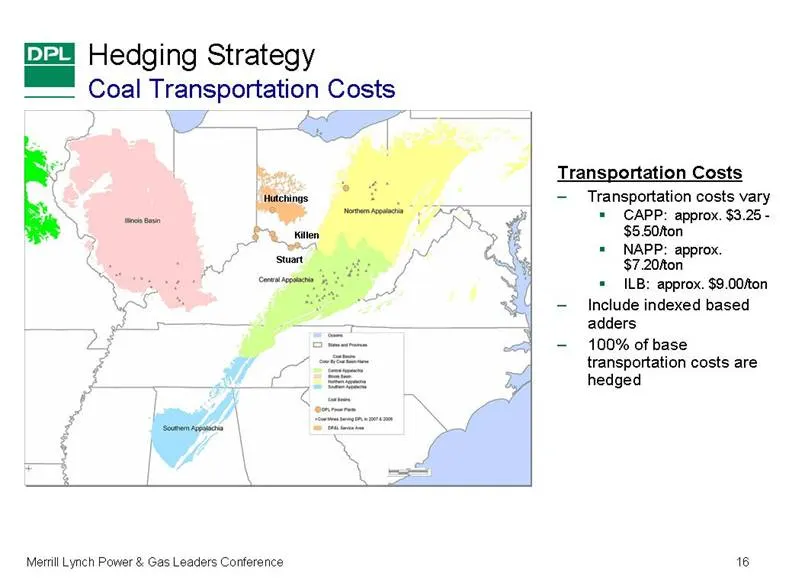
16 Merrill Lynch Power & Gas Leaders Conference Hedging Strategy Coal Transportation Costs Transportation Costs – Transportation costs vary CAPP: approx. $3.25 - $5.50/ton NAPP: approx. $7.20/ton ILB: approx. $9.00/ton – Include indexed based adders – 100% of base transportation costs are hedged Kil
Slide 18: Plant Performance
Plant Performance September 23 – 24, 2008
Slide 19: Plant Performance
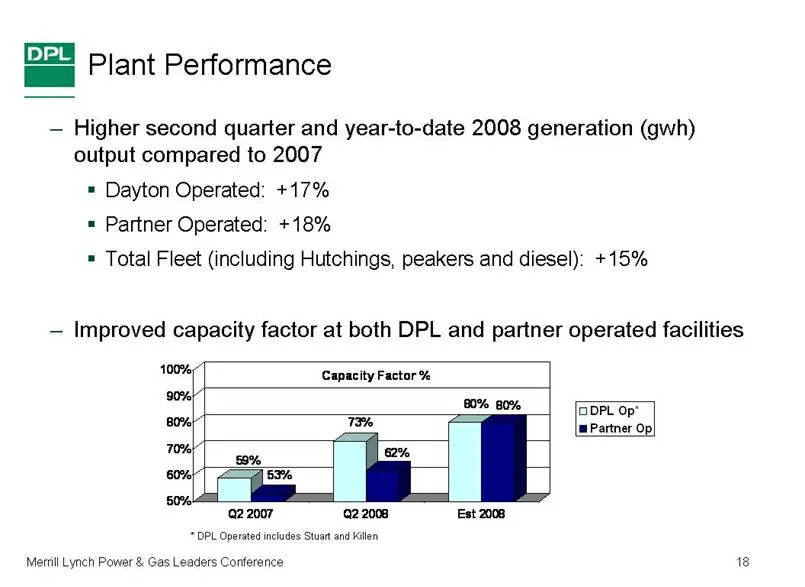
18 Merrill Lynch Power & Gas Leaders Conference Plant Performance – Higher second quarter and year-to-date 2008 generation (gwh) output compared to 2007 Dayton Operated: +17% Partner Operated: +18% Total Fleet (including Hutchings, peakers and diesel): +15% – Improved capacity factor at both DPL and
Slide 20: Plant Performance
19 Merrill Lynch Power & Gas Leaders Conference Plant Performance – Plant performance across DPL’s entire coal generation fleet is critical to DPL’s success – With major construction projects completed, output from coal fired generation is expected to be higher in 2008 and 2009, compared to 2007 – D
Slide 21: Appendix
Appendix September 23 – 24, 2008
Slide 22: Company Overview
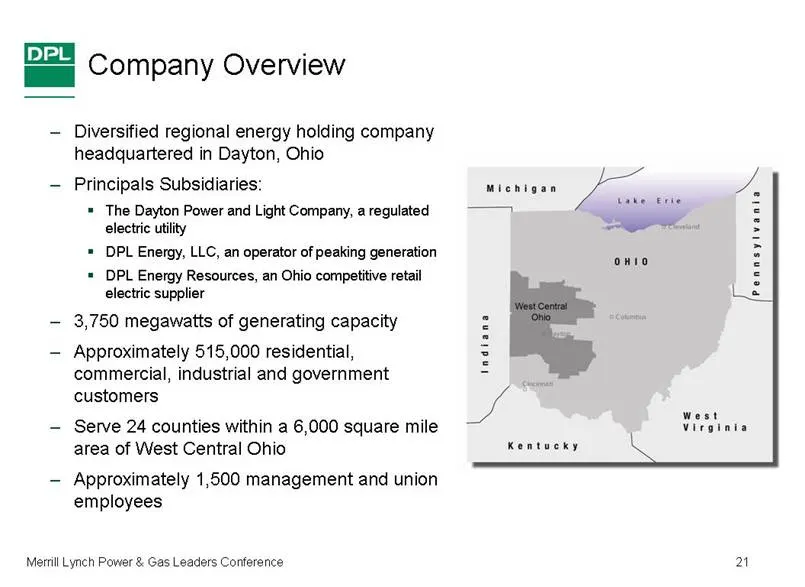
21 Merrill Lynch Power & Gas Leaders Conference Company Overview – Diversified regional energy holding company headquartered in Dayton, Ohio – Principals Subsidiaries: The Dayton Power and Light Company, a regulated electric utility DPL Energy, LLC, an operator of peaking generation DPL Energy Resou
Slide 23: Stable and Diverse Retail Market
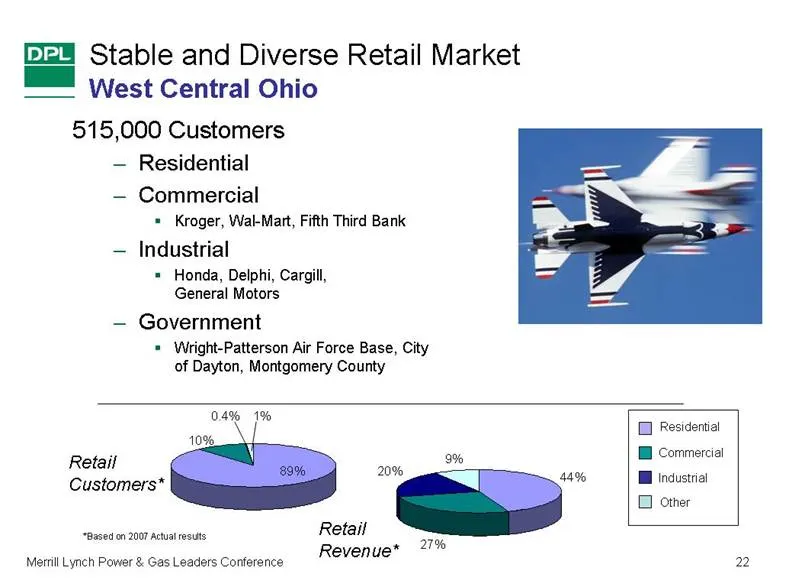
22 Merrill Lynch Power & Gas Leaders Conference Stable and Diverse Retail Market West Central Ohio 515,000 Customers – Residential – Commercial Kroger, Wal-Mart, Fifth Third Bank – Industrial Honda, Delphi, Cargill, General Motors – Government Wright-Patterson Air Force Base, City of Dayton, Montgom
Slide 24: Financial Overview
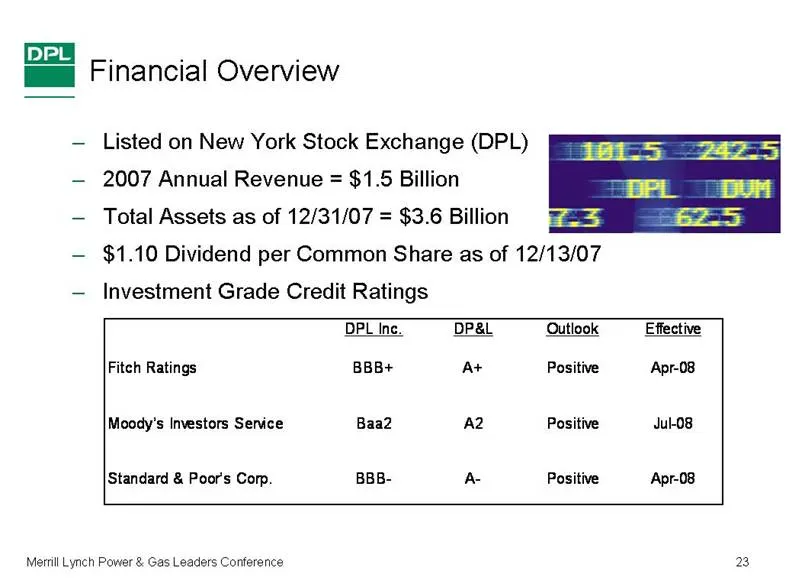
23 Merrill Lynch Power & Gas Leaders Conference Financial Overview – Listed on New York Stock Exchange (DPL) – 2007 Annual Revenue = $1.5 Billion – Total Assets as of 12/31/07 = $3.6 Billion – $1.10 Dividend per Common Share as of 12/13/07 – Investment Grade Credit Ratings DPL Inc. DP&L Outlook Effe
Slide 25: DPL Generation Assets
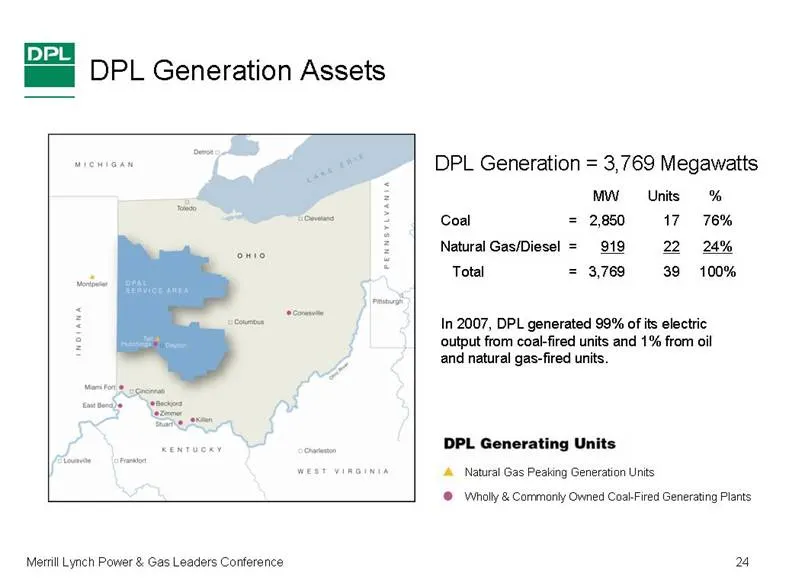
24 Merrill Lynch Power & Gas Leaders Conference DPL Generation Assets Coal = 2,850 17 76% Natural Gas/Diesel = 919 22 24% Total = 3,769 39 100% DPL Generation = 3,769 Megawatts MW Units Natural Gas Peaking Generation Units Wholly & Commonly Owned Coal-Fired Generating Plants In 2007, DPL generated 9
Slide 26: DPL Generation Assets: Coal-Fired Units
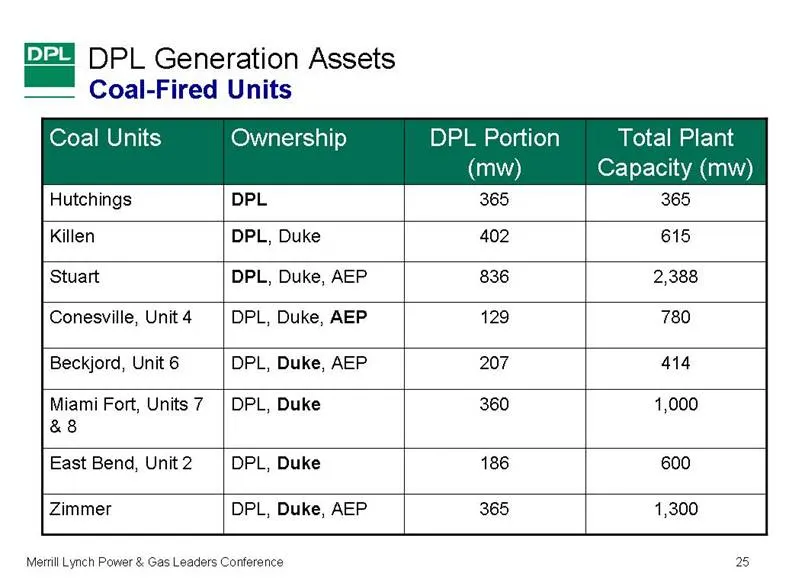
25 Merrill Lynch Power & Gas Leaders Conference 1,300 365 DPL, Duke, AEP Zimmer 600 186 DPL, Duke East Bend, Unit 2 1,000 360 DPL, Duke Miami Fort, Units 7 & 8 414 207 DPL, Duke, AEP Beckjord, Unit 6 780 129 DPL, Duke, AEP Conesville, Unit 4 2,388 836 DPL, Duke, AEP Stuart 615 402 DPL, Duke Killen 3
Slide 27: Regional Transmission Organizations (RTO's)
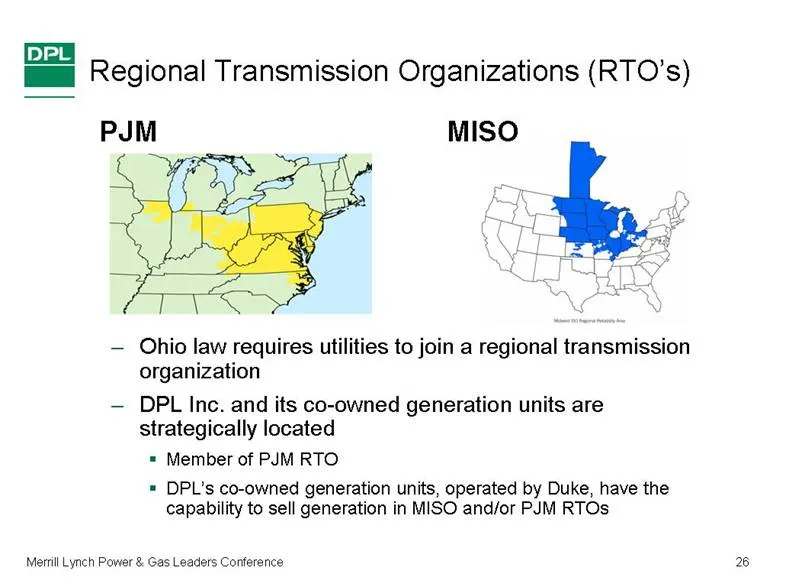
26 Merrill Lynch Power & Gas Leaders Conference Regional Transmission Organizations (RTO’s) – Ohio law requires utilities to join a regional transmission organization – DPL Inc. and its co-owned generation units are strategically located Member of PJM RTO DPL’s co-owned generation units, operated by
Slide 28: Earnings Per Share: Three Months Ended June 30, 2008 and 2007
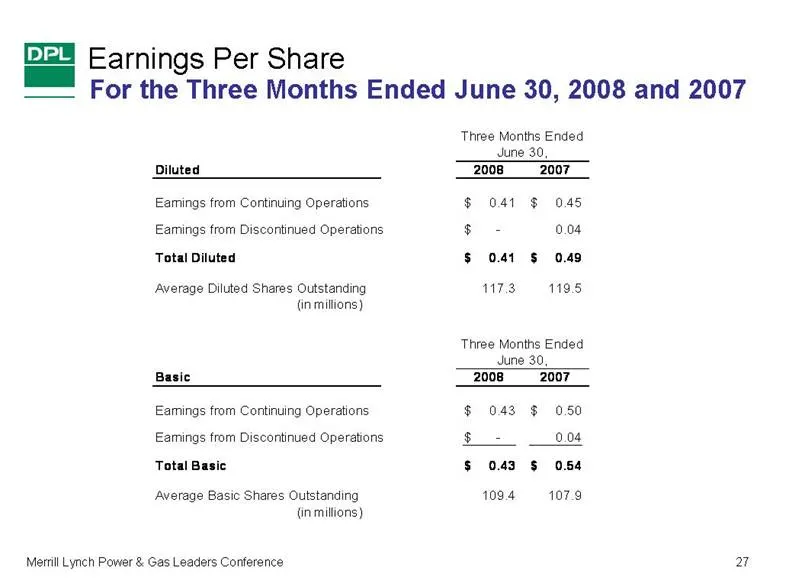
27 Merrill Lynch Power & Gas Leaders Conference For the Three Months Ended June 30, 2008 and 2007 Earnings Per Share Diluted 2008 2007 Earnings from Continuing Operations 0.41 $ 0.45 $ Earnings from Discontinued Operations - $ 0.04 Total Diluted 0.41 $ 0.49 $ Average Diluted Shares Outstanding 117.3
Slide 29: Non-GAAP Earnings Per Share Reconciliation
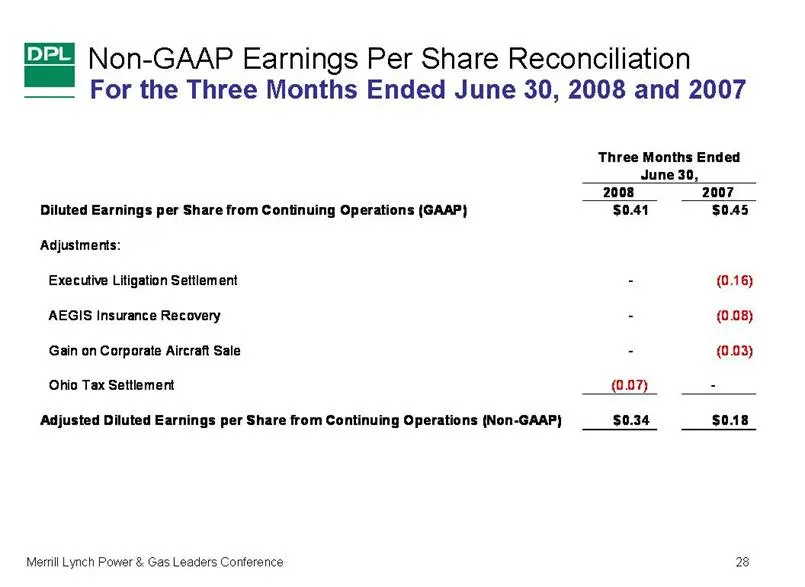
28 Merrill Lynch Power & Gas Leaders Conference For the Three Months Ended June 30, 2008 and 2007 Non-GAAP Earnings Per Share Reconciliation 2008 2007 Diluted Earnings per Share from Continuing Operations (GAAP) $0.41 $0.45 Adjustments: Executive Litigation Settlement - (0.16) AEGIS Insurance Recove
Slide 30: Key Drivers of Non-GAAP Earnings Per Share
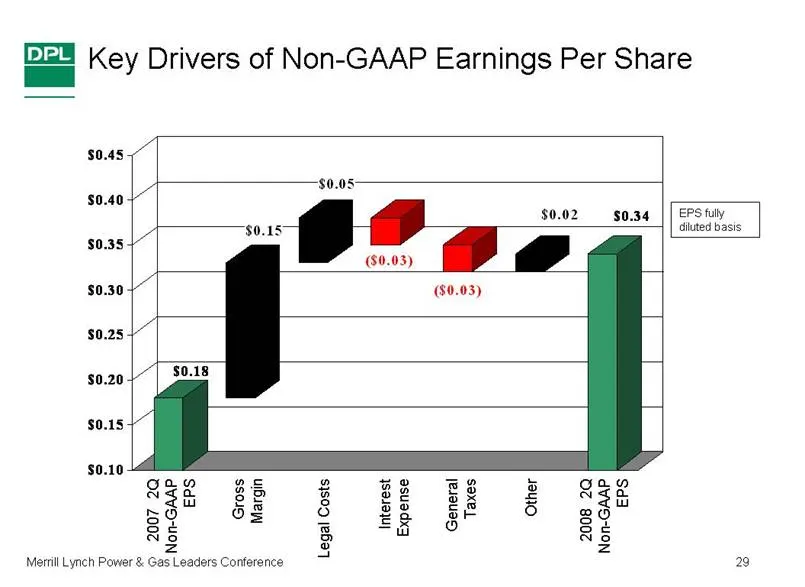
29 Merrill Lynch Power & Gas Leaders Conference $0.18 $0.15 $0.05 ($0.03) ($0.03) $0.02 $0.34 $0.10 $0.15 $0.20 $0.25 $0.30 $0.35 $0.40 $0.45 2007 2Q Non-GAAP EPS Interest Expense General Taxes Other 2008 2Q Non-GAAP EPS Gross Margin Legal Costs EPS fully diluted basis Key Drivers of Non-GAAP Earnin
Slide 31: Liquidity and Cash Flow
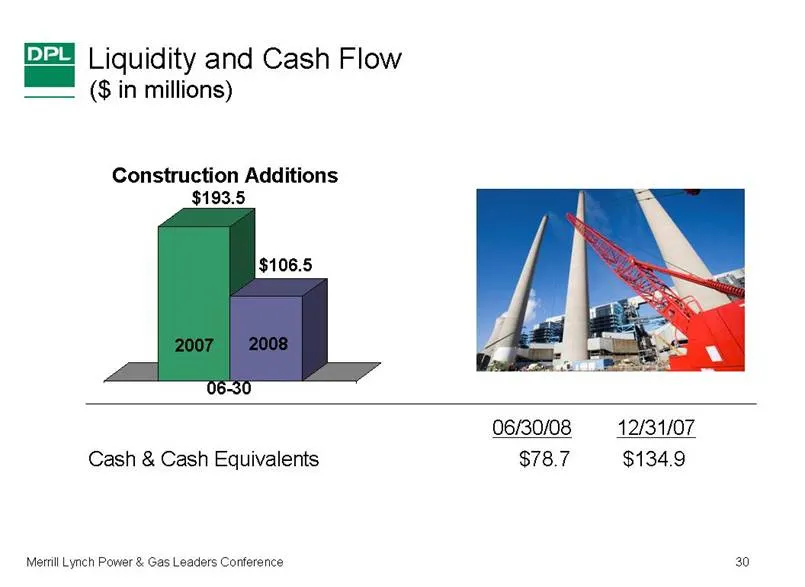
30 Merrill Lynch Power & Gas Leaders Conference Cash & Cash Equivalents $78.7 $134.9 06/30/08 12/31/07 $193.5 2007 2008 06-30 Construction Additions $106.5 Liquidity and Cash Flow ($ in millions)
Slide 32: Paul M. Barbas, President and Chief Executive Officer
Merrill Lynch Power & Gas Leaders Conference Paul M. Barbas President and Chief Executive Officer September 23 – 24, 2008
Source: SEC EDGAR · 8-K filed Sep 19, 2008
More decks from DPL Inc
 Debt Investor Presentation (August 2016)12 slides · Aug 8, 2016
 Q1 2011 Earnings Presentation28 slides · Apr 29, 2011
 FY2010 Earnings Presentation15 slides · Feb 17, 2011
 Non-Deal Roadshow (December 2010)24 slides · Dec 10, 2010
 Q3 2010 Earnings Presentation18 slides · Oct 29, 2010
 Non-Deal Roadshow (September 2010)24 slides · Sep 14, 2010