ClubCorp — Investor Presentation (November 2013)
32 slides from ClubCorp's investor presentation, Nov 4, 2013
Slide 1: Company Overview November 2013
Company Overview November 2013 My Club My Community My World
Slide 2: Cautionary Statement
Cautionary Statement Forward-Looking Statements Certain statements in this presentation may be considered forward-looking statements. Forward-looking statements generally relate to future events or our future financial or operating performance. In some cases, you can identify forward- looking statem
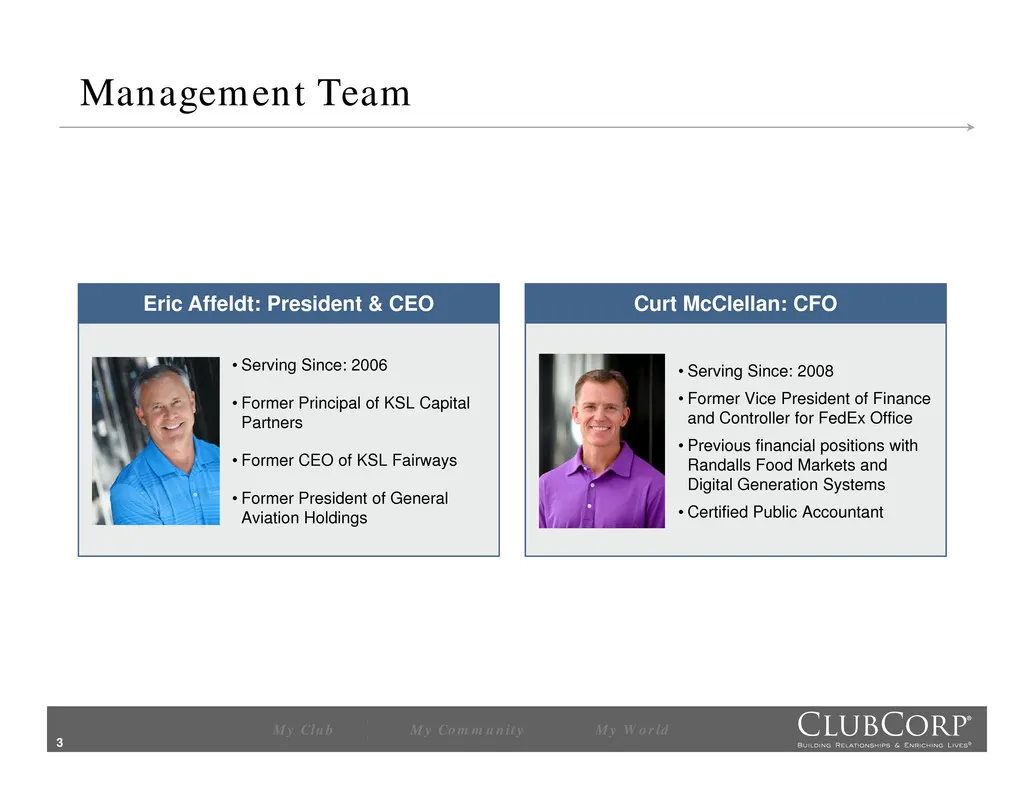
Slide 3: Management Team
Management Team Curt McClellan: CFOEric Affeldt: President & CEO • Serving Since: 2006 • Former Principal of KSL Capital Partners • Serving Since: 2008 • Former Vice President of Finance and Controller for FedEx Office • Previous financial positions with • Former CEO of KSL Fairways • Former Preside
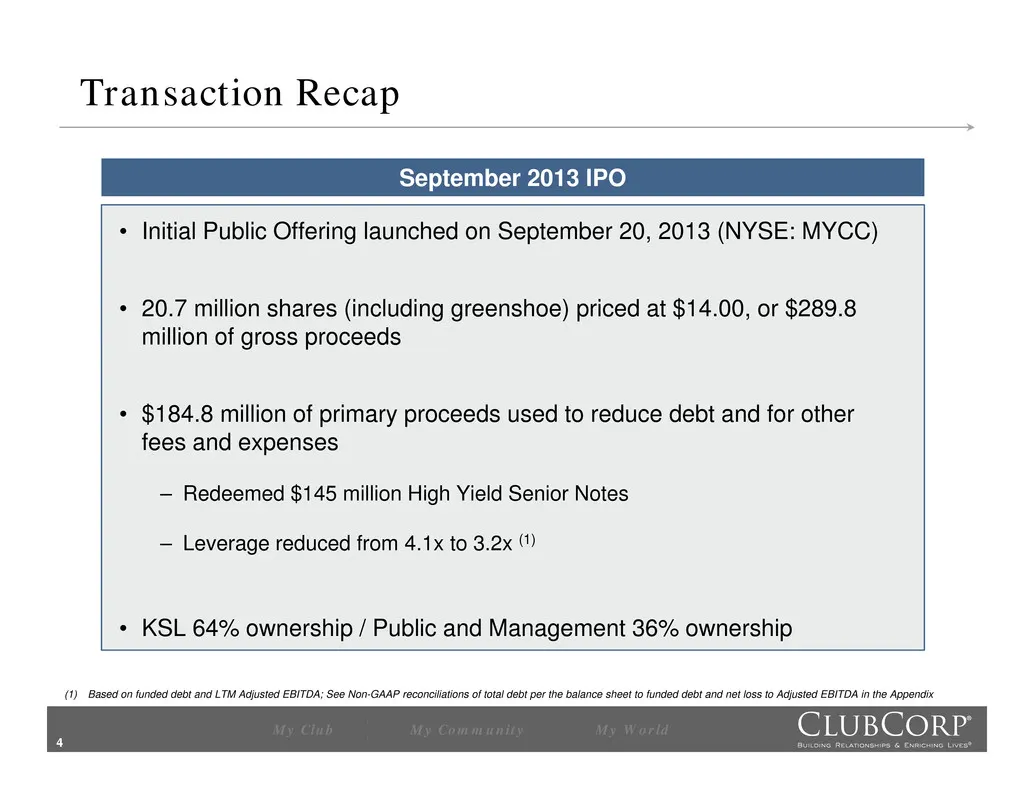
Slide 4: Transaction Recap
Transaction Recap • Initial Public Offering launched on September 20, 2013 (NYSE: MYCC) September 2013 IPO • 20.7 million shares (including greenshoe) priced at $14.00, or $289.8 million of gross proceeds • $184.8 million of primary proceeds used to reduce debt and for other fees and expenses – Rede
Slide 5: Q3 and YTD 2013 Recap
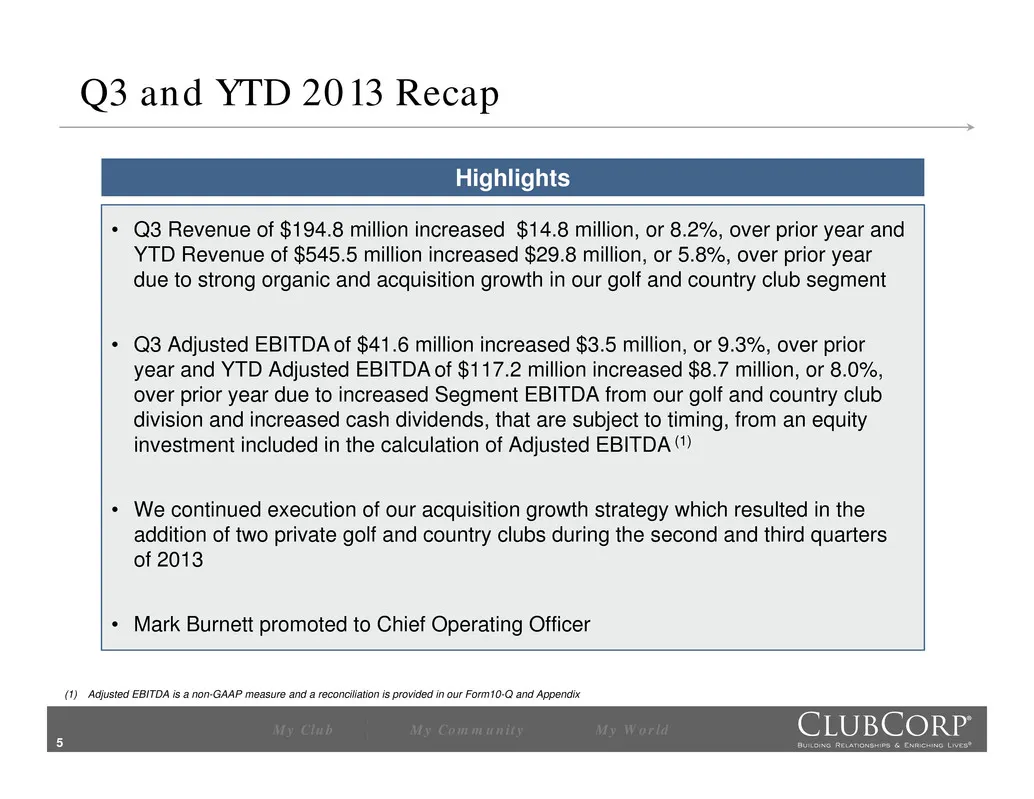
Q3 and YTD 2013 Recap • Q3 Revenue of $194.8 million increased $14.8 million, or 8.2%, over prior year and YTD R f $545 5 illi i d $29 8 illi 5 8% i Highlights evenue o . m on ncrease . m on, or . , over pr or year due to strong organic and acquisition growth in our golf and country club segment • Q
Slide 6: Company Overview
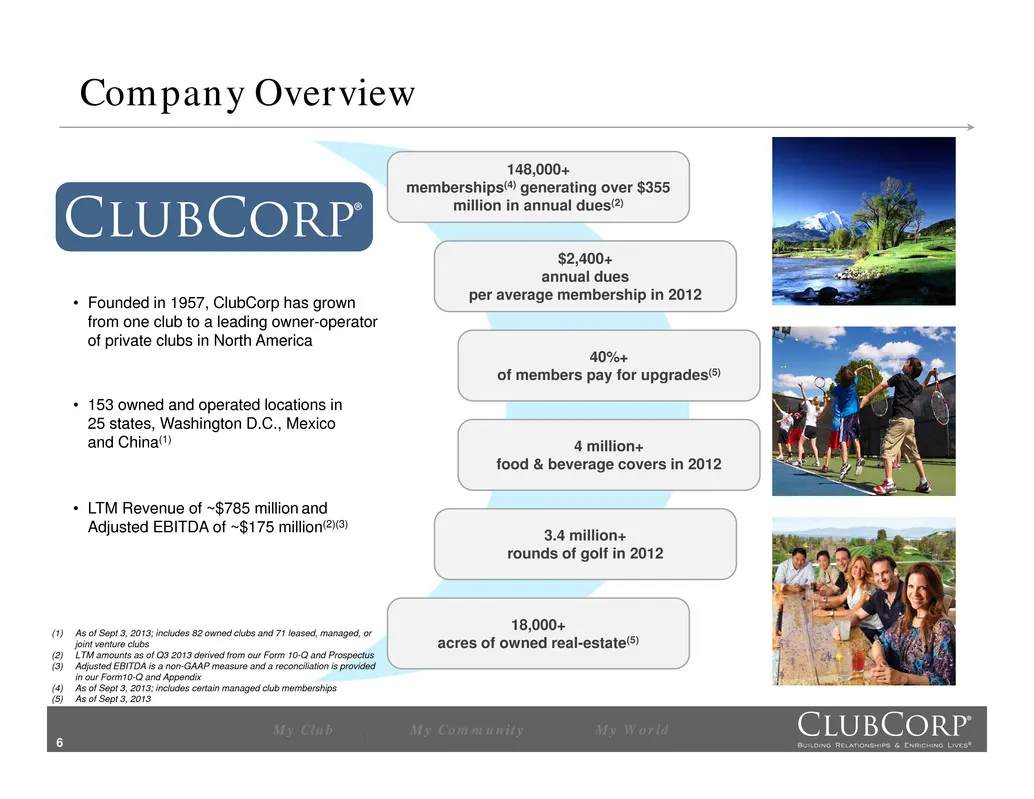
Company Overview 148,000+ memberships(4) generating over $355 million in annual dues(2) $2,400+ annual dues per average membership in 2012• Founded in 1957, ClubCorp has grown from one club to a leading owner-operator of private clubs in North America 4 million+ 40%+ of members pay for upgrades(5) •
Slide 7: ClubCorp At A Glance
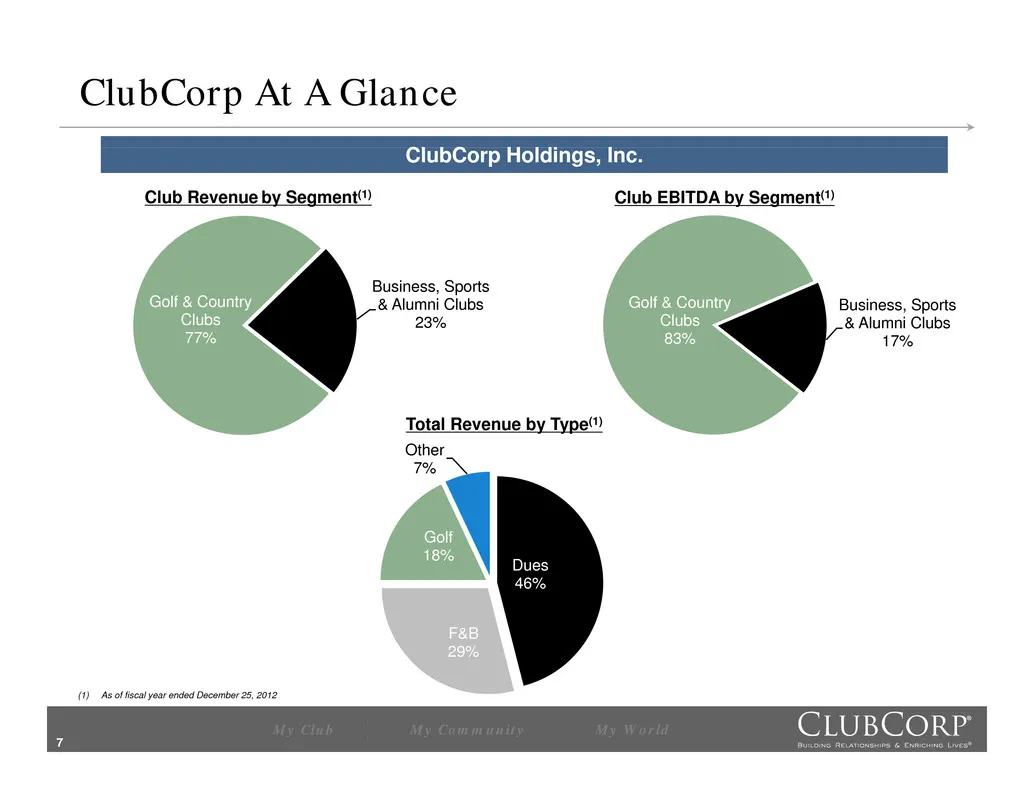
ClubCorp At A Glance Cl bC H ldi Iu orp o ngs, nc. Club Revenue by Segment(1) Club EBITDA by Segment(1) Golf & Country Clubs 83% Business, Sports & Alumni Clubs 17% Golf & Country Clubs 77% Business, Sports & Alumni Clubs 23% Other Total Revenue by Type(1) Golf 18% 7% Dues 46% F&B 29% My Club My Com
Slide 8: Company Highlights
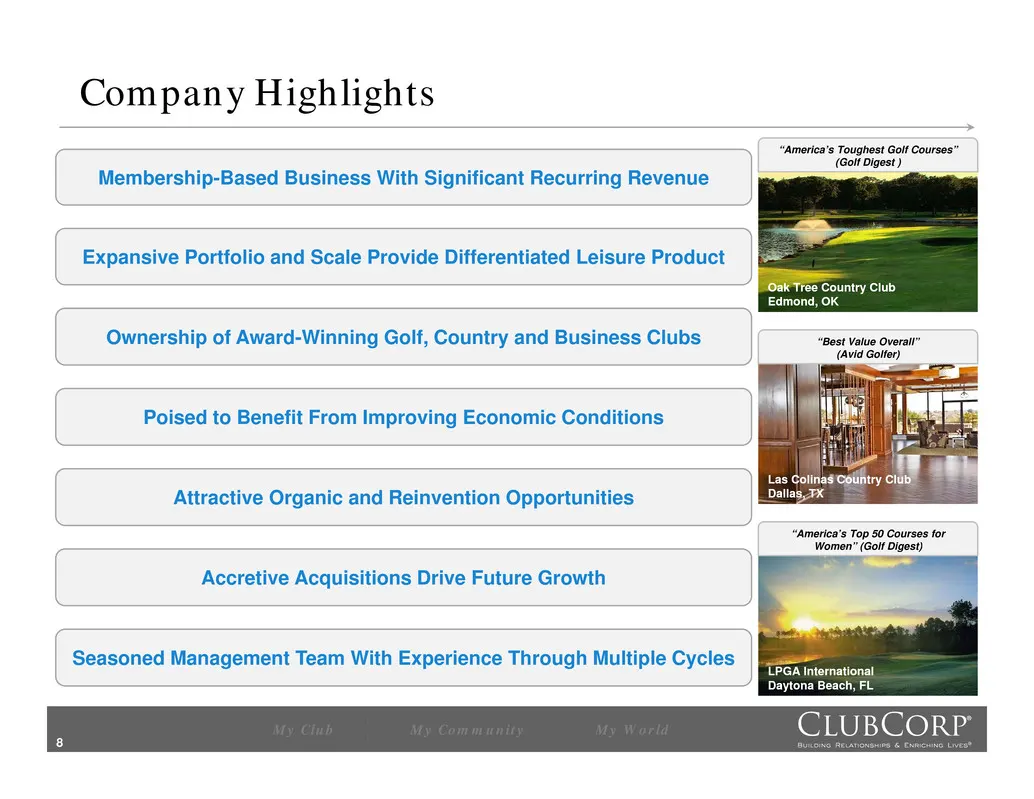
Company Highlights “A i ’ T h t G lf C ” Membership-Based Business With Significant Recurring Revenue mer ca s oug es o ourses (Golf Digest ) Expansive Portfolio and Scale Provide Differentiated Leisure Product Ownership of Award-Winning Golf, Country and Business Clubs Oak Tree Country Club Edmond,
Slide 9: Membership-Based Business With Significant Recurring Revenue
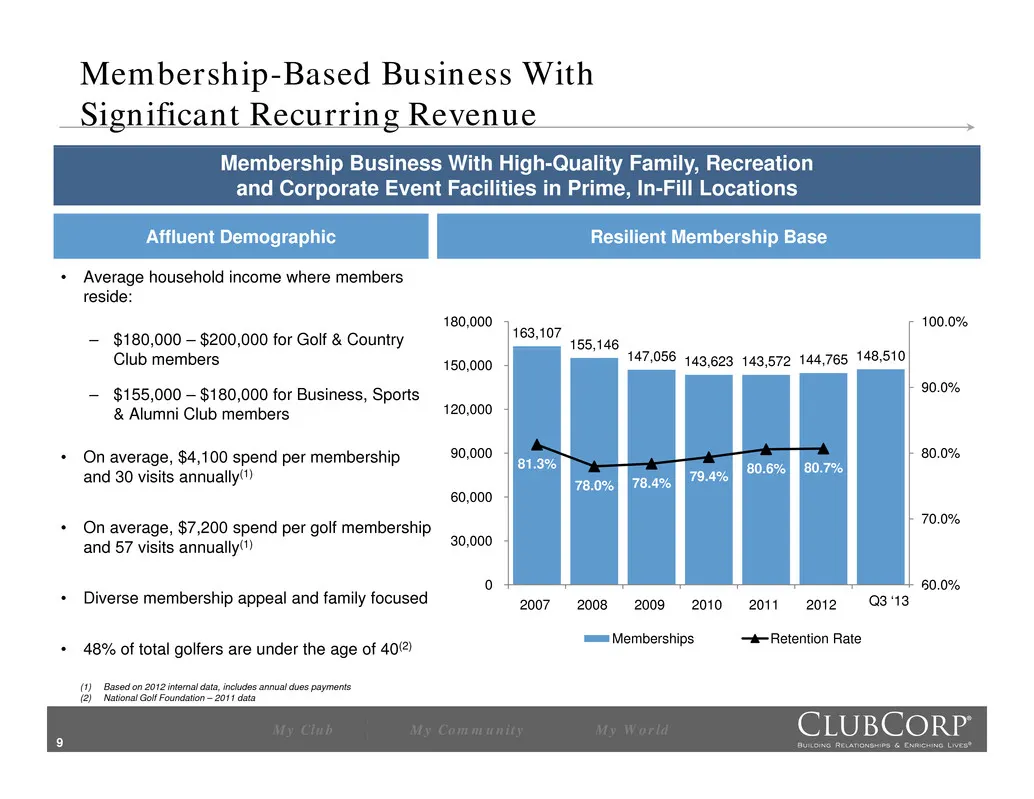
Membership-Based Business With Significant Recurring Revenue Membership Business With High-Quality Family, Recreation and Corporate Event Facilities in Prime, In-Fill Locations Affluent Demographic Resilient Membership Base • Average household income where members reside: – $180,000 – $200,000 for G
Slide 10: Expansive Portfolio and Scale
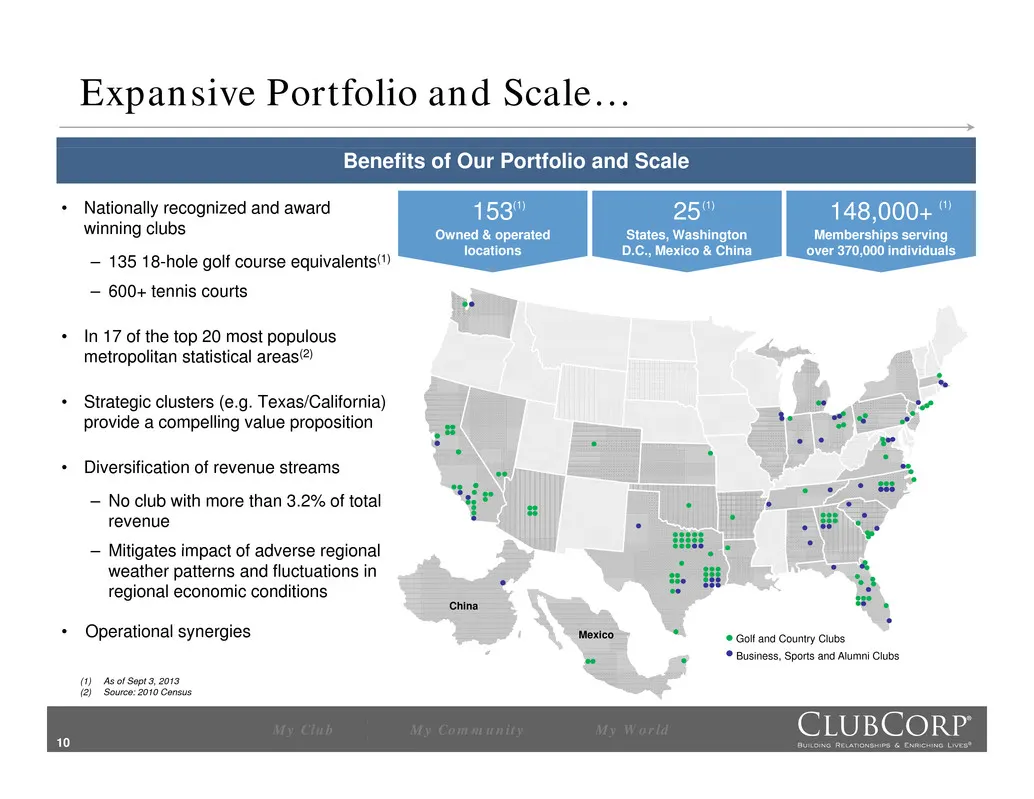
Expansive Portfolio and Scale… Benefits of Our Portfolio and Scale 148,000+ Memberships serving over 370 000 individuals 153 Owned & operated locations (1) 25 States, Washington D C Mexico & China (1)• Nationally recognized and award winning clubs (1) , . ., – 135 18-hole golf course equivalents(1)
Slide 11: Provide Differentiated Leisure Product
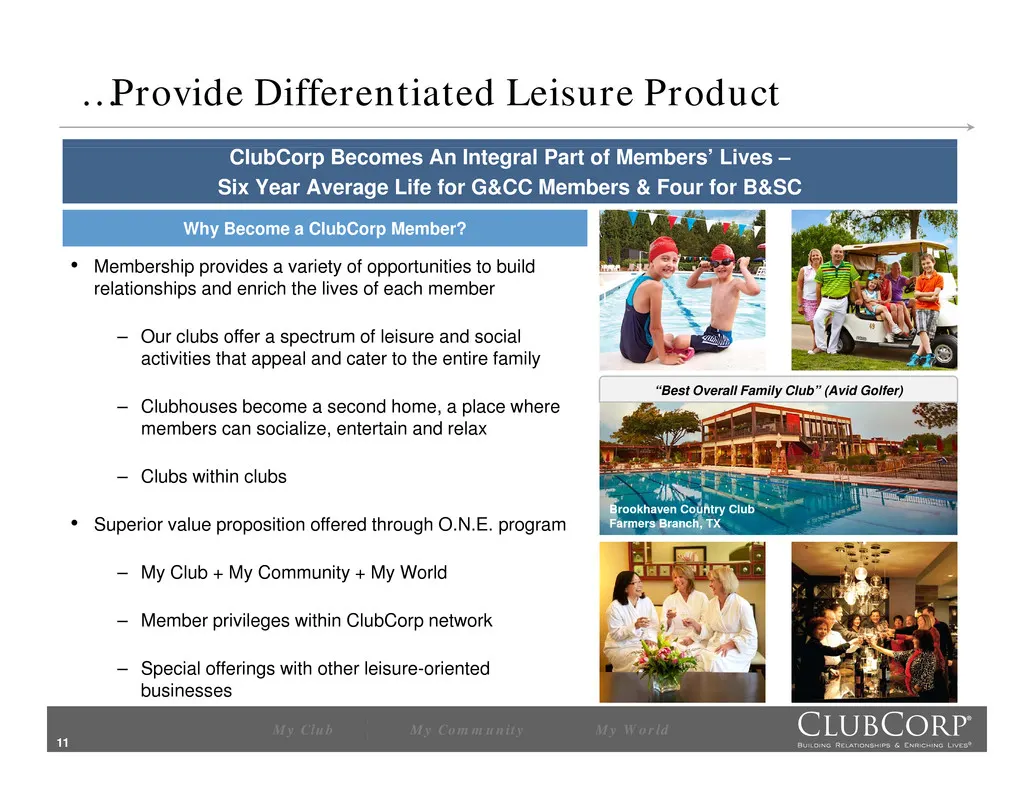
…Provide Differentiated Leisure Product ClubCorp Becomes An Integral Part of Members’ Lives – Six Year Average Life for G&CC Members & Four for B&SC Why Become a ClubCorp Member? • Membership provides a variety of opportunities to build relationships and enrich the lives of each member – Our clubs o
Slide 12: O.N.E. (Optimal Network Experiences)
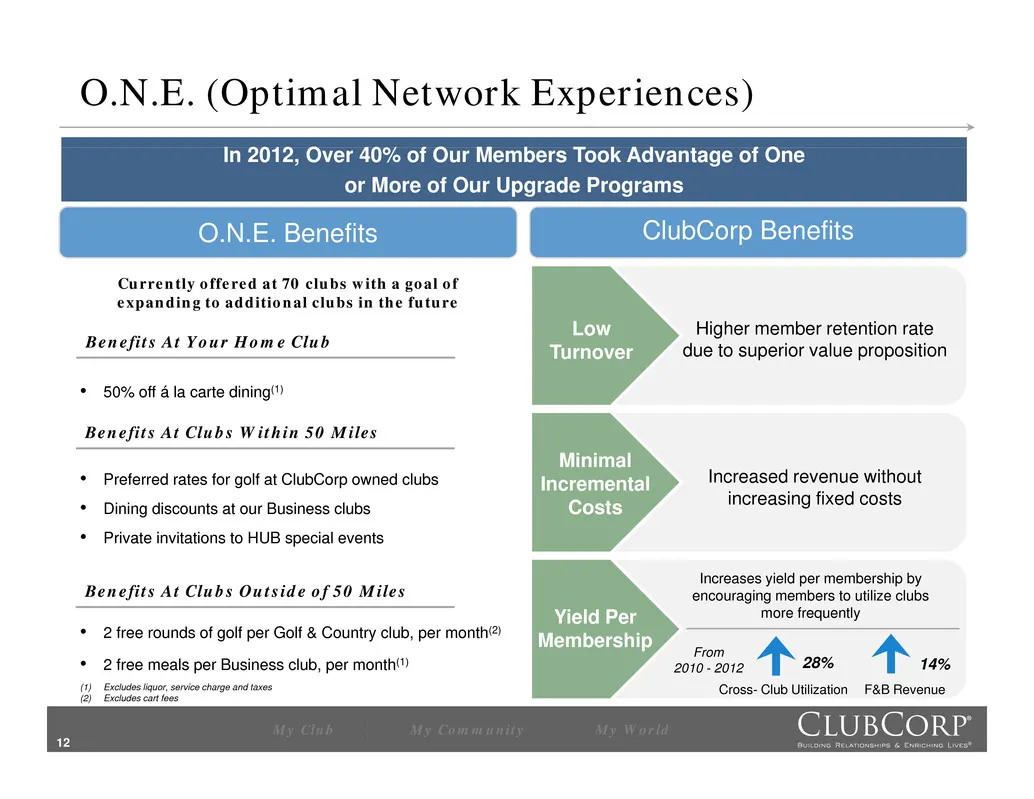
O.N.E. (Optimal Network Experiences) I 2012 O 40% f O M b T k Ad t f O O.N.E. Benefits ClubCorp Benefits n , ver o ur em ers oo van age o ne or More of Our Upgrade Programs Benefits At Your Home Club Currently offered at 70 clubs with a goal of expanding to additional clubs in the future Higher memb
Slide 13: Case Study: Our Dallas Cluster
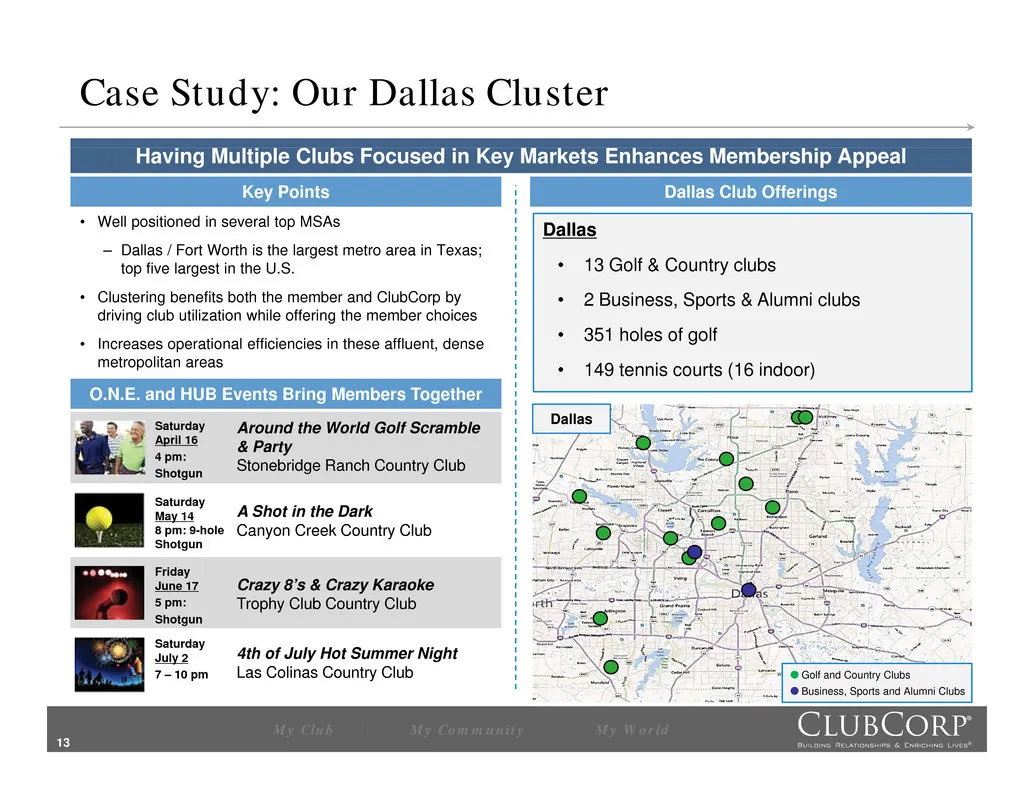
Case Study: Our Dallas Cluster Key Points Having Multiple Clubs Focused in Key Markets Enhances Membership Appeal • Well positioned in several top MSAs Dallas / Fort Worth is the largest metro area in Texas; Dallas Club Offerings Dallas – metr top five largest in the U.S. • Clustering benefits both
Slide 14: Ownership of Award-Winning Clubs / Real Estate
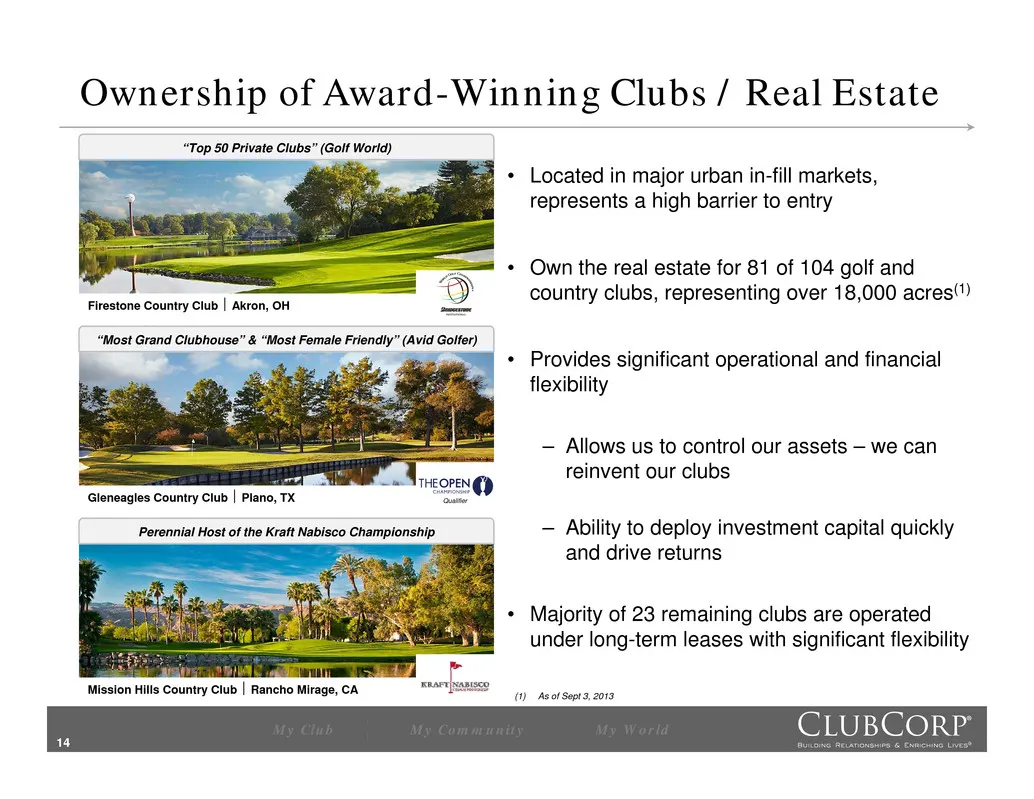
Ownership of Award-Winning Clubs / Real Estate “Top 50 Private Clubs” (Golf World) • Located in major urban in-fill markets, represents a high barrier to entry • Own the real estate for 81 of 104 golf and country clubs, representing over 18,000 acres(1) Firestone Country Club Akron, OH “Most Grand
Slide 15: Poised to Benefit From Improving Economic Conditions
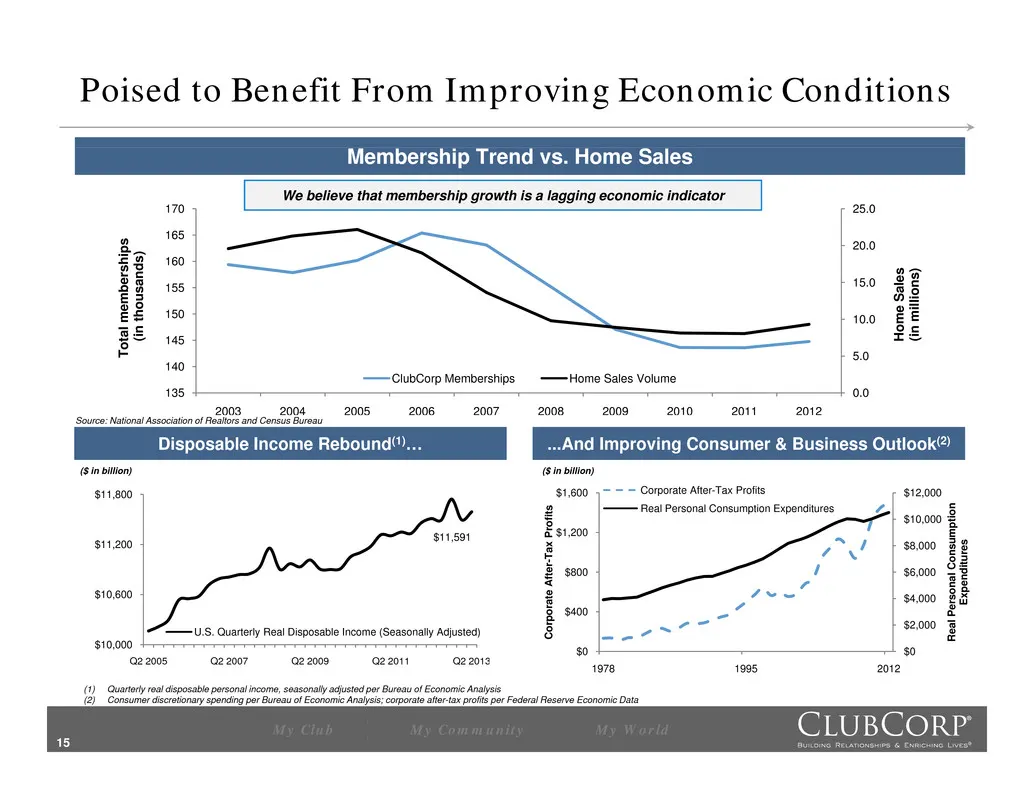
Poised to Benefit From Improving Economic Conditions 20 0 25.0 165 170 p s Membership Trend vs. Home Sales We believe that membership growth is a lagging economic indicator 10.0 15.0 . 145 150 155 160 H o m e S a l e s ( i n m i l l i o n s ) o t a l m e m b e r s h i p ( i n t h o u s a n d s ) 0.0
Slide 16: Strategy for Growth
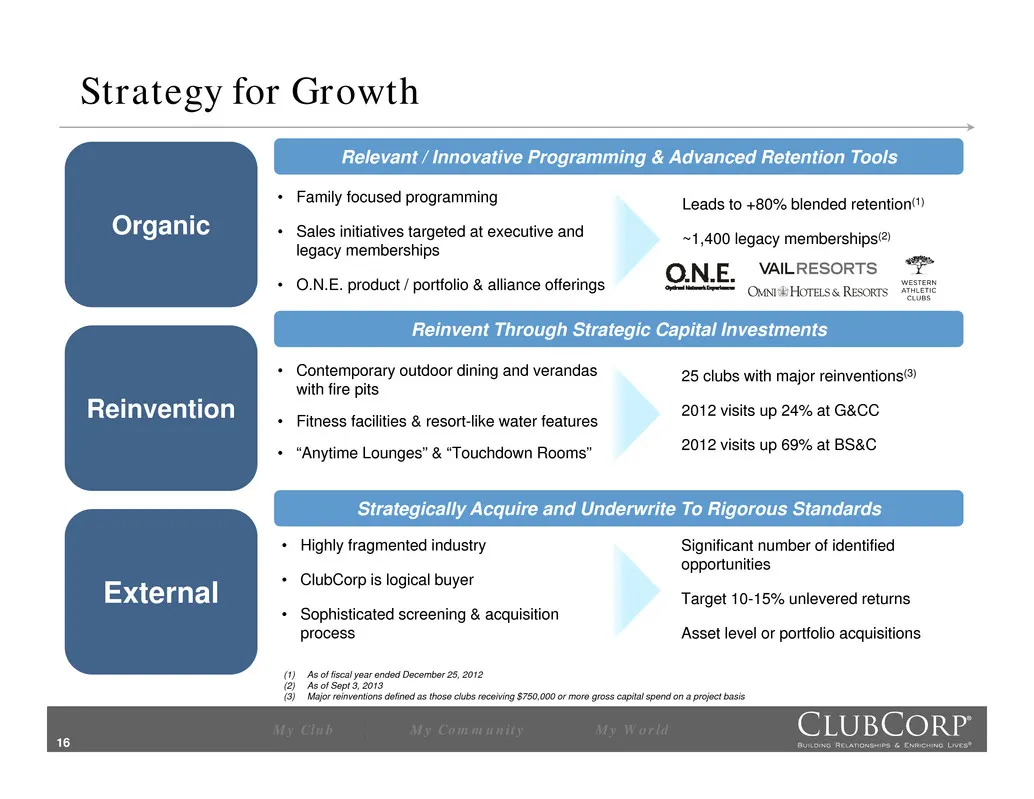
Strategy for Growth Organic Relevant / Innovative Programming & Advanced Retention Tools Leads to +80% blended retention(1) ~1,400 legacy memberships(2) • Family focused programming • Sales initiatives targeted at executive and legacy memberships R levant / Innovative Progra ming & Advanced R tentio
Slide 17: Elements of Reinvention
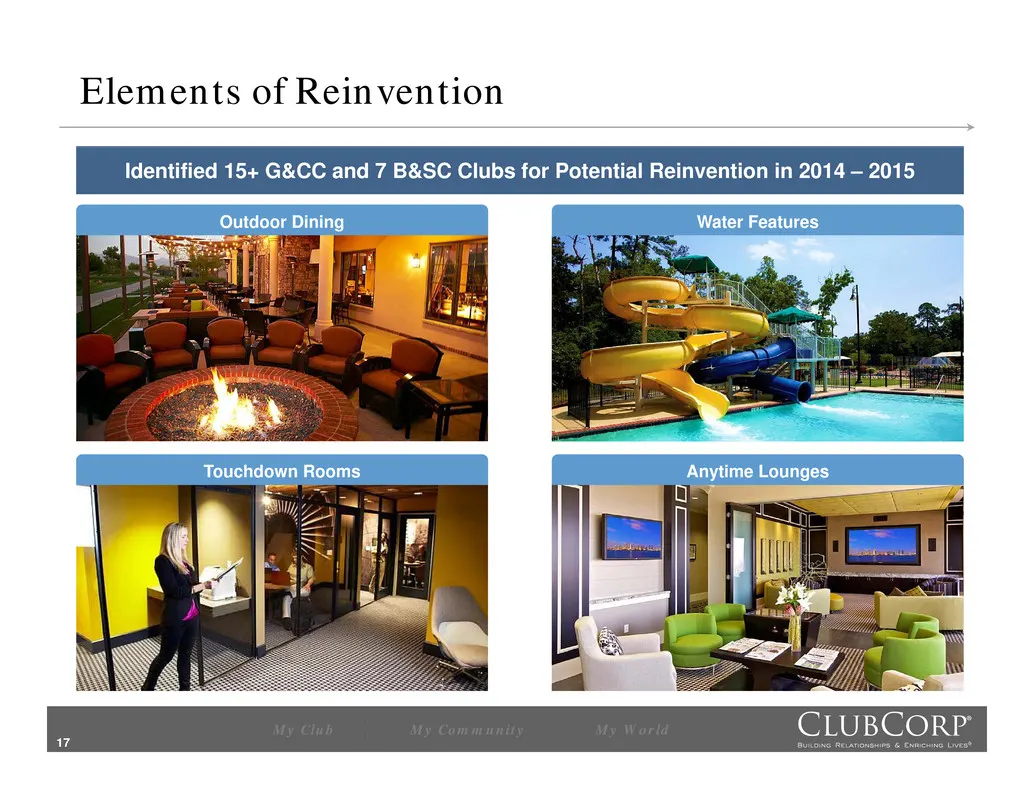
Elements of Reinvention Water FeaturesOutdoor Dining Identified 15+ G&CC and 7 B&SC Clubs for Potential Reinvention in 2014 – 2015 Touchdown Rooms Anytime Lounges My Club My Community My World 17
Slide 18: Case Study: Las Colinas Country Club
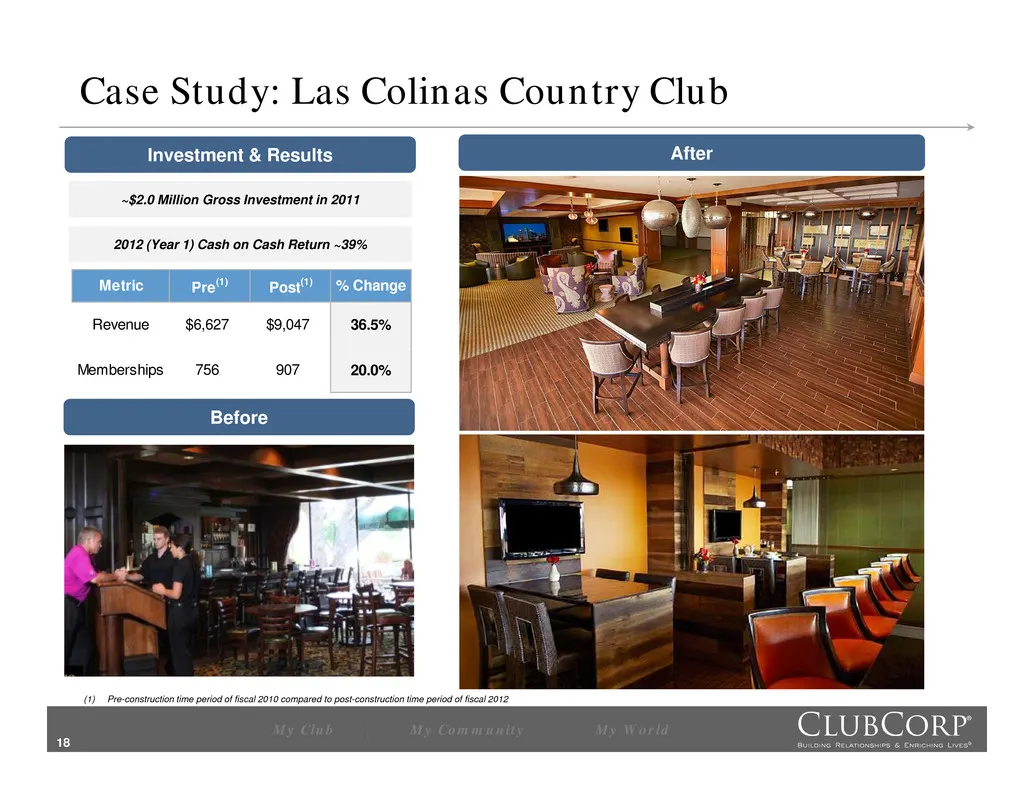
Aft Case Study: Las Colinas Country Club erInvestment & Results ~$2.0 Million Gross Investment in 2011 2012 (Year 1) Cash on Cash Return ~39% Metric Pre(1) Post(1) % Change Revenue $6,627 $9,047 36.5% Before Memberships 756 907 20.0% My Club My Community My World 18 (1) Pre-construction time period
Slide 19: Case Study: University Club San Diego
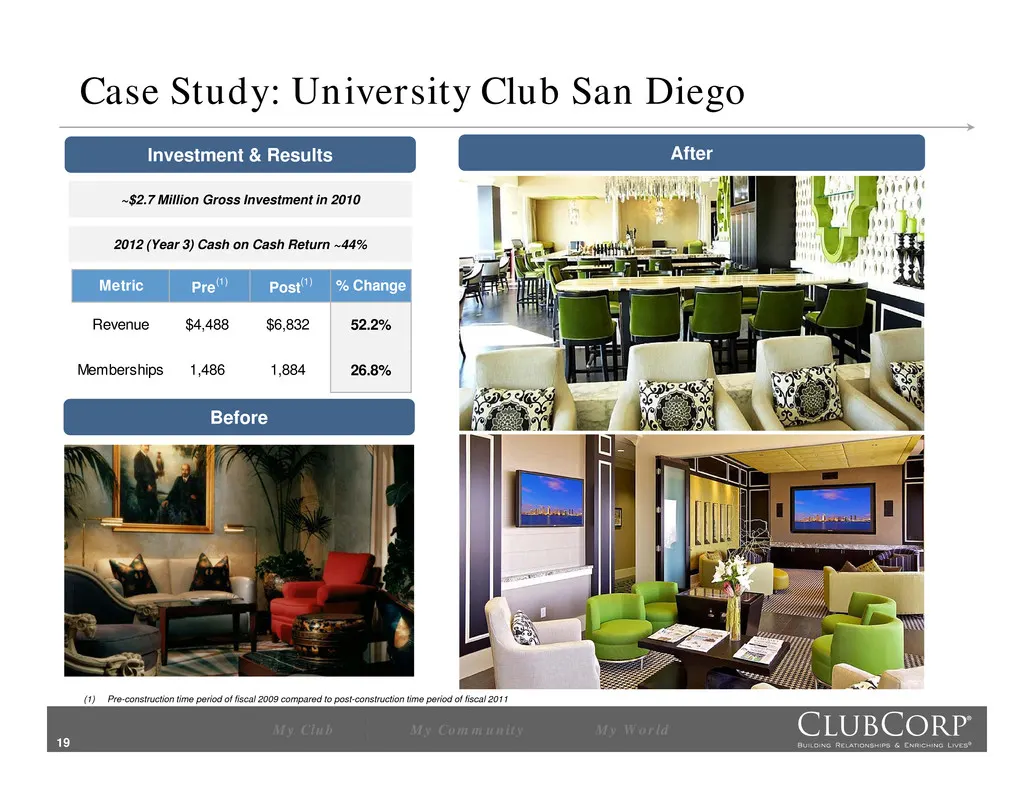
Aft Case Study: University Club San Diego erInvestment & Results ~$2.7 Million Gross Investment in 2010 2012 (Year 3) Cash on Cash Return ~44% Metric Pre(1) Post(1) % Change Revenue $4,488 $6,832 52.2% Before Memberships 1,486 1,884 26.8% My Club My Community My World 19 (1) Pre-construction time pe
Slide 20: External Growth Enhances Returns
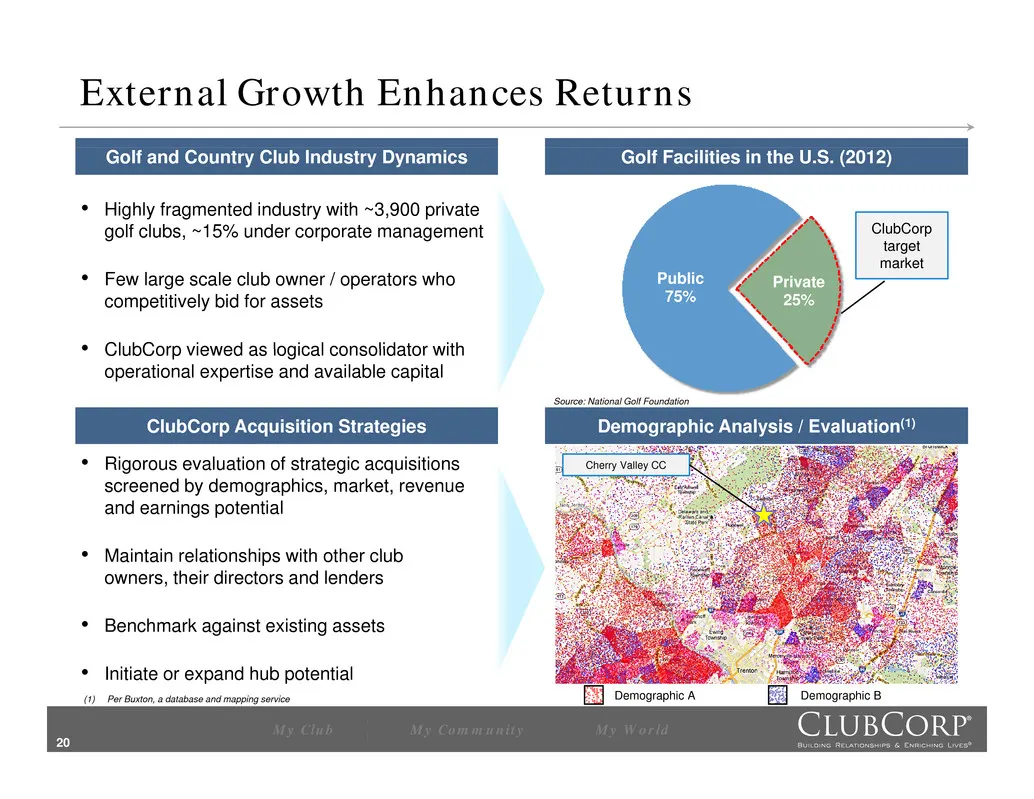
External Growth Enhances Returns Golf and Country Club Industry Dynamics • Highly fragmented industry with ~3,900 private golf clubs, ~15% under corporate management Golf Facilities in the U.S. (2012) ClubCorp target • Few large scale club owner / operators who competitively bid for assets • ClubCor
Slide 21: Recent Acquisitions
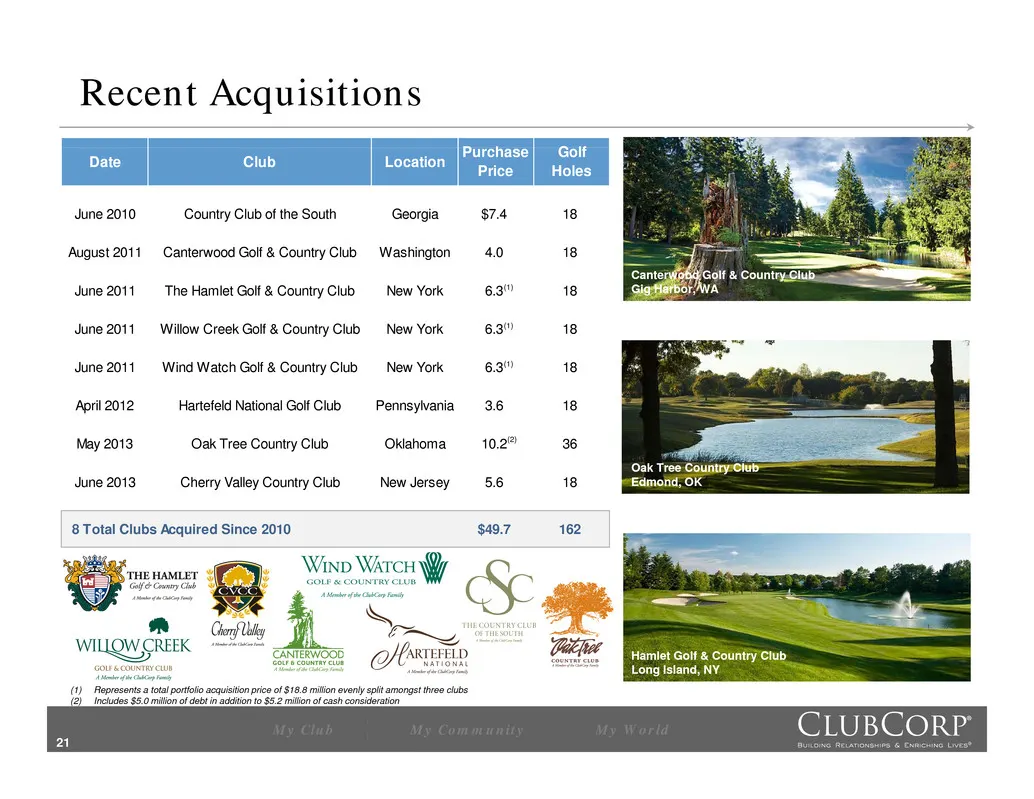
P h G lf Recent Acquisitions Date Club Location urc ase Price o Holes June 2010 Country Club of the South Georgia $7.4 18 A t 2011 C t d G lf & C t Cl b W hi t 4 0 18ugus an erwoo o oun ry u as ng on . June 2011 The Hamlet Golf & Country Club New York 6.3 18 June 2011 Willow Creek Golf & Country Clu
Slide 22: Case Study: Country Club of the South
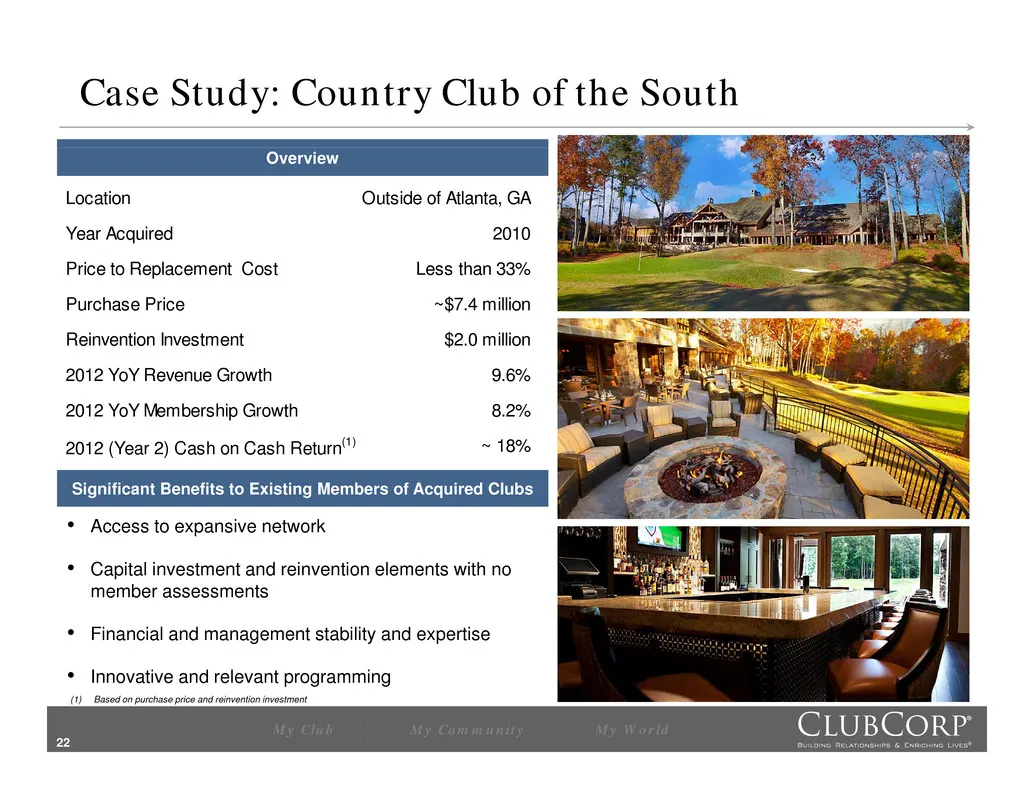
Case Study: Country Club of the South Overview Location Outside of Atlanta, GA Year Acquired 2010 Price to Replacement Cost Less than 33% Purchase Price ~$7.4 million Reinvention Investment $2.0 million 2012 YoY Revenue Growth 9.6% 2012 YoY Membership Growth 8.2% 2012 (Year 2) Cash on Cash Return(1)
Slide 23: Attractive Cash Flow Profile
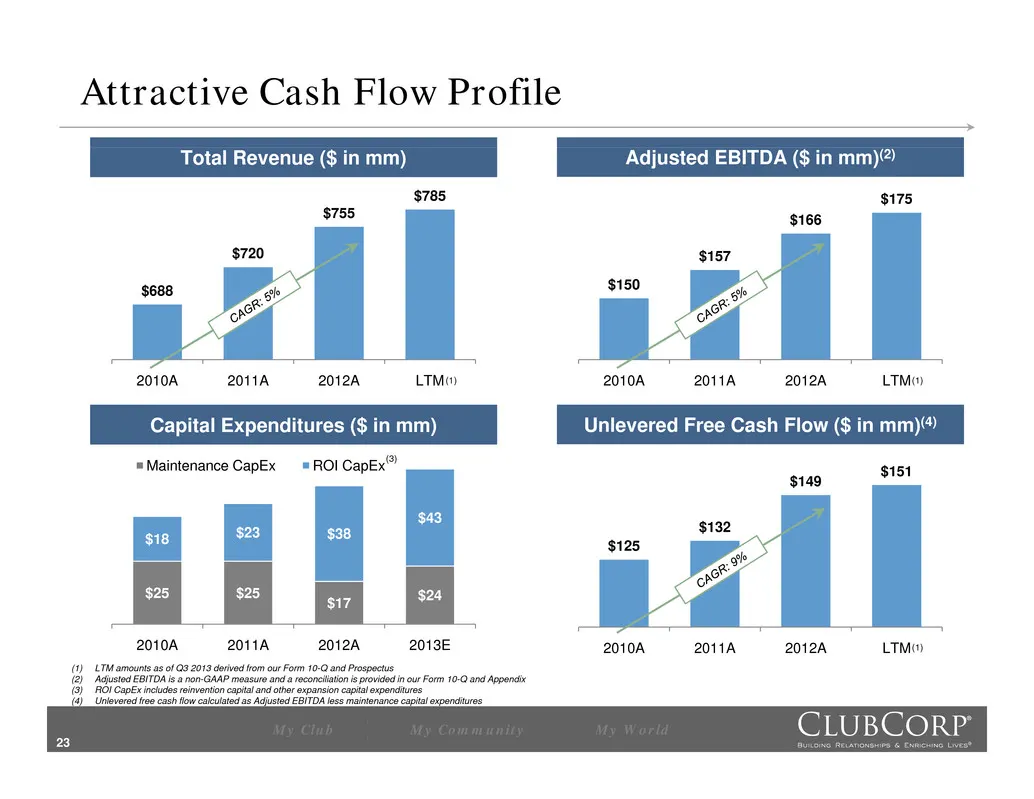
Attractive Cash Flow Profile $720 $755 $785 $166 $175 Total Revenue ($ in mm) Adjusted EBITDA ($ in mm)(2) $688 $150 $157 2010A 2011A 2012A LTM 2010A 2011A 2012A LTM Unlevered Free Cash Flow ($ in mm)(4)Capital Expenditures ($ in mm) (1) (1) $18 $23 $38 $43 Maintenance CapEx ROI CapEx $125 $132 $149
Slide 24: Conservative Capital Structure Positioned for Growth
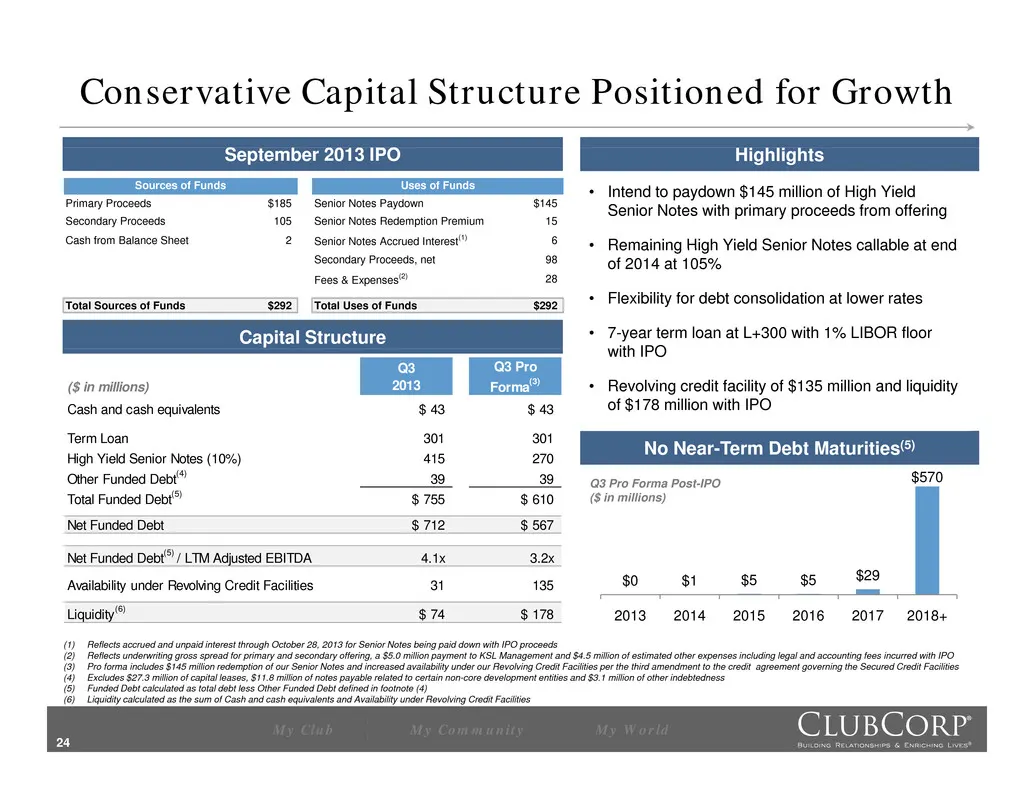
S O Conservative Capital Structure Positioned for Growth eptember 2013 IP • Intend to paydown $145 million of High Yield Senior Notes with primary proceeds from offering • Remaining High Yield Senior Notes callable at end Highlights Primary Proceeds $185 Senior Notes Paydown $145 Secondary Proceeds
Slide 25: Focus on Shareholder Value
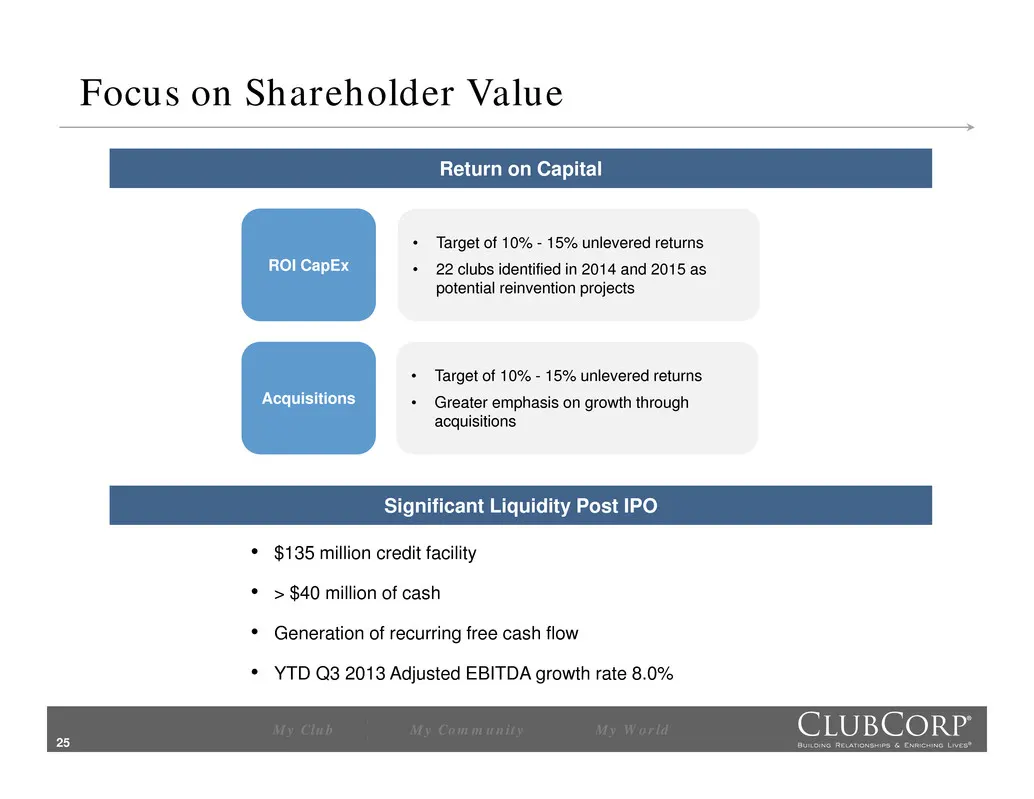
Focus on Shareholder Value Return on Capital • Target of 10% - 15% unlevered returns ROI CapEx • 22 clubs identified in 2014 and 2015 as potential reinvention projects Acquisitions • Target of 10% - 15% unlevered returns • Greater emphasis on growth through acquisitions Significant Liquidity Post IP
Slide 26: Seasoned Management Team
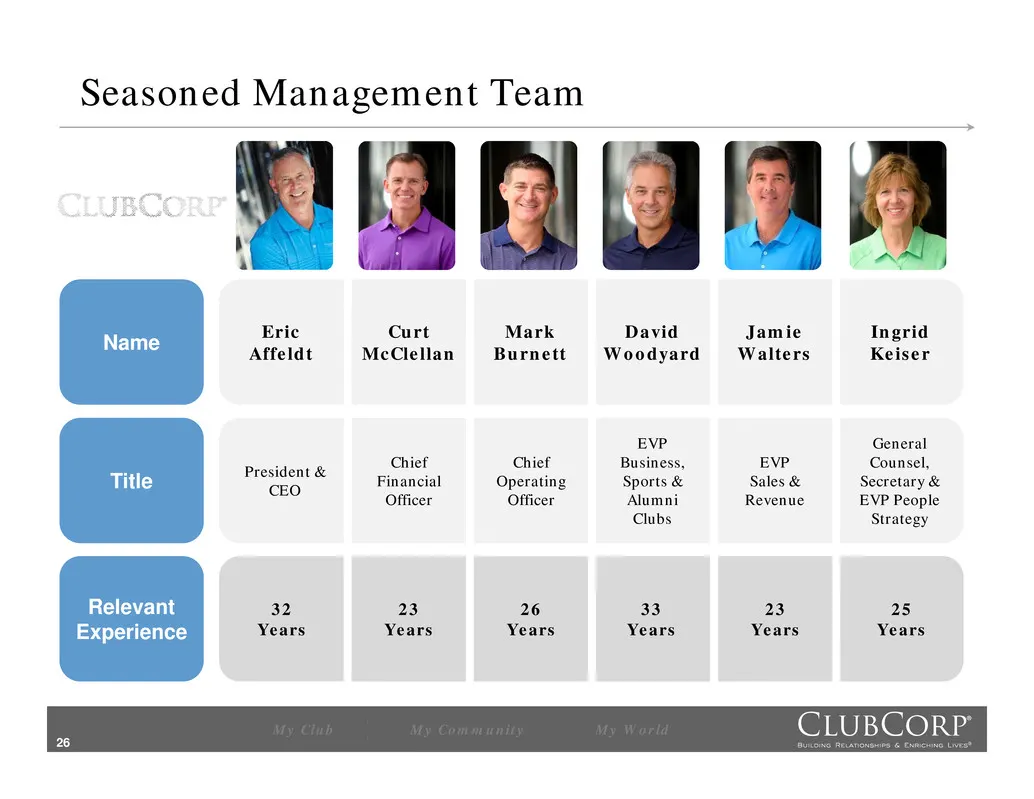
Seasoned Management Team Name EricAff ldt Curt M Cl ll Mark B tt David W d d Jamie W lt Ingrid K ie c e an urne oo yar a ers e ser EVP General Title President &CEO Chief Financial Officer Chief Operating Officer Business, Sports & Alumni Clubs EVP Sales & Revenue Counsel, Secretary & EVP People Stra
Slide 27: Conclusion
Conclusion Membership-Based Business With Significant Recurring Revenue E i P tf li d S l P id Diff ti t d L i P d txpans ve or o o an ca e rov e eren a e e sure ro uc Ownership of Award-Winning Golf, Country and Business Clubs Poised to Benefit From Improving Economic Conditions Attractive Organic
Slide 28: My Club My Community My World 28
My Club My Community My World 28
Slide 29: Appendix
Appendix My Club My Community My World 29
Slide 30: Historical Results
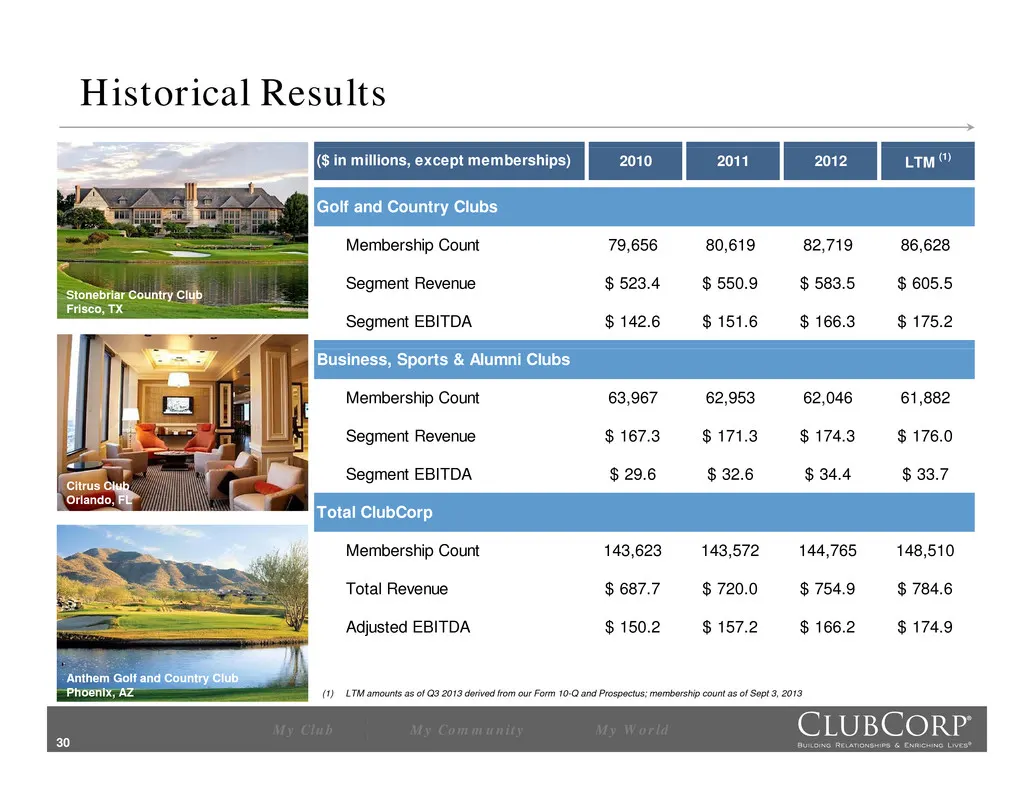
Historical Results (1) (1)2010 2011 2012 LTM (1) Golf and Country Clubs Membership Count 79 656 80 619 82 719 86 628 ($ in millions, except memberships) Stonebriar Country Club Frisco, TX , , , , Segment Revenue $ 523.4 $ 550.9 $ 583.5 $ 605.5 Segment EBITDA $ 142.6 $ 151.6 $ 166.3 $ 175.2 Business,
Slide 31: Adjusted EBITDA Reconciliation
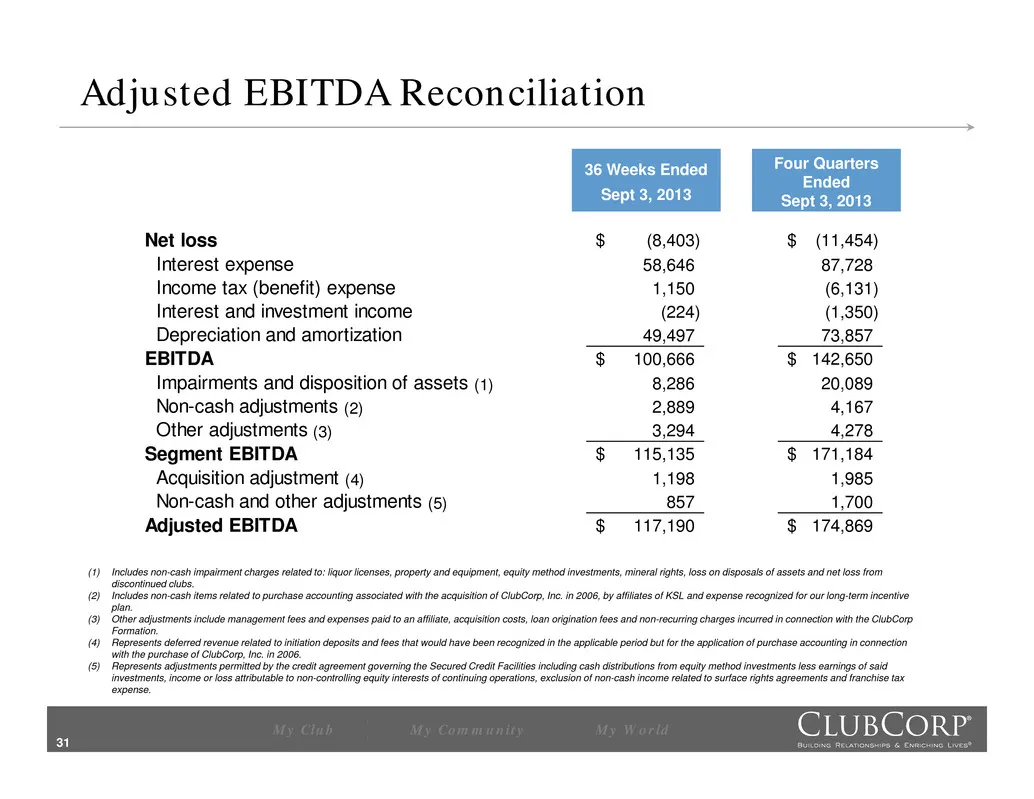
Adjusted EBITDA Reconciliation Net loss (8,403)$ (11,454)$ 36 Weeks Ended Sept 3, 2013 Four Quarters Ended Sept 3, 2013 Interest expense 58,646 87,728 Income tax (benefit) expense 1,150 (6,131) Interest and investment income (224) (1,350) Depreciation and amortization 49,497 73,857 EBITDA 100,666$ 1
Slide 32: Funded Debt Reconciliation
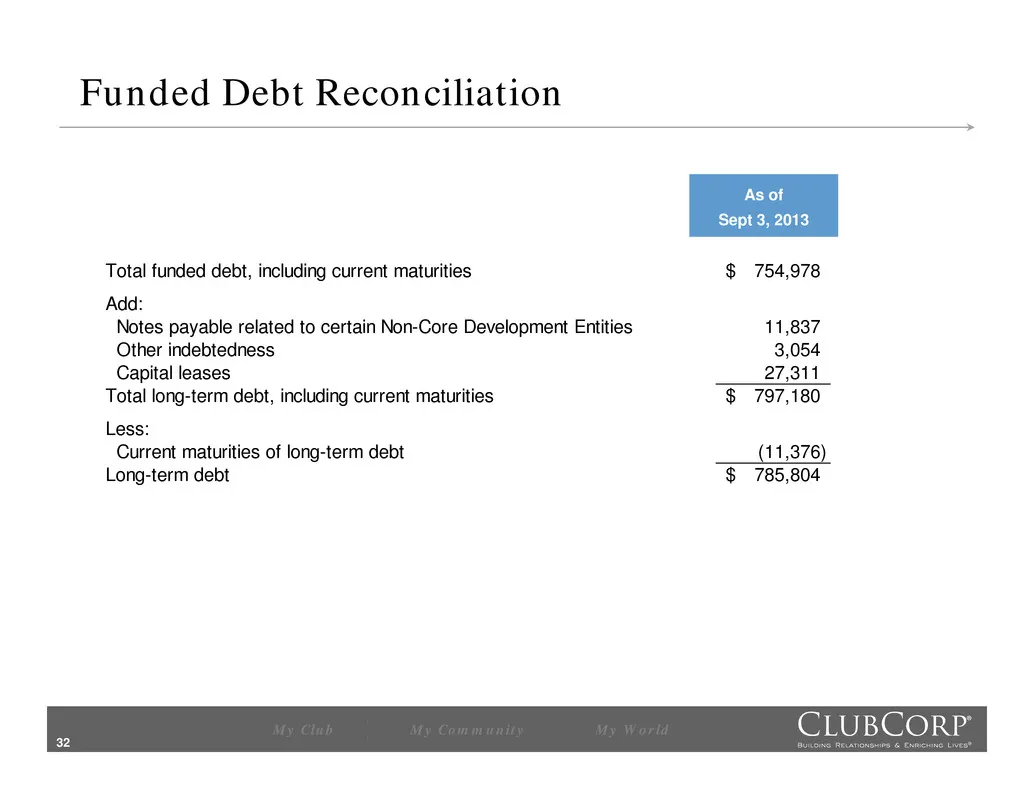
Funded Debt Reconciliation As of Sept 3, 2013 Total funded debt, including current maturities 754,978$ Add: Notes payable related to certain Non-Core Development Entities 11,837 Other indebtedness 3 054 , Capital leases 27,311 Total long-term debt, including current maturities 797,180$ Less: Current
Source: SEC EDGAR · 8-K filed Nov 4, 2013
More decks from ClubCorp Holdings Inc
 Q1 2016 Earnings Presentation38 slides · Apr 27, 2016
 Q4 2015 Earnings Presentation38 slides · Feb 24, 2016
 Q3 2015 Earnings Presentation30 slides · Oct 15, 2015
 Q2 2015 Earnings Presentation31 slides · Jul 23, 2015
 Q1 2015 Earnings Presentation25 slides · Apr 30, 2015
 Q4 2014 Earnings Presentation26 slides · Mar 12, 2015