Blount International — Robert W. Baird & Co. Industrial Conference 2005
27 slides from Blount International's conference presentation, Nov 8, 2005
Slide 1: Robert W. Baird & Co. Industrial Conference
Robert W. Baird & Co. Industrial Conference November 8, 2005
Slide 2: Forward-looking statement
BLOUNT Forward-looking statement Statements in this presentation that are not reported financial results or other historical information are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. They include, for example, statements about our busine
Slide 3: Company Management
BLOUNT Company Management ™@ Cal Jenness Ken Saito @ Jake VanderZanden Senior Vice President and Chief Financial Officer President Oregon Cutting Systems President ICS
Slide 4: LTM Sales and EBITDA by segment
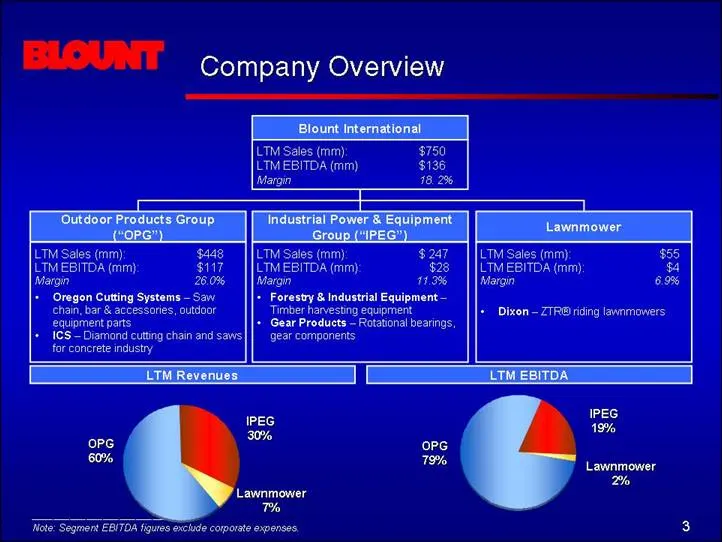
LIM Sales (mm) $750 LIMEBITDA (mm) $136 Margin 18 26 LIM Sales (mm) $448 LTMEBITDA (mm): $17 Margin 26.0% + Oregon Cuting Systems ~Saiv chan, bar & accessories, outdoor equipment parts + 1€S~ Diamond cuting chain and saws forconerete industry LIM Sales (mm) $247 LIMEBITDA (mm): $28 ‘Margin 113% + Fo
Slide 5: Operating From a Strong Position
ELOUNT Operating From a Strong Position Leading Market Positions — Global leader in chainsaw chain & guide bars (estimated market shares of 60% as of 2004) — Leading (#2) distributor of timber harvesting equipment in North America Attractive “Razor-Blade” Business Model of OPG Segment - Replacement
Slide 6: Oregon Cutting Systems (OCS)
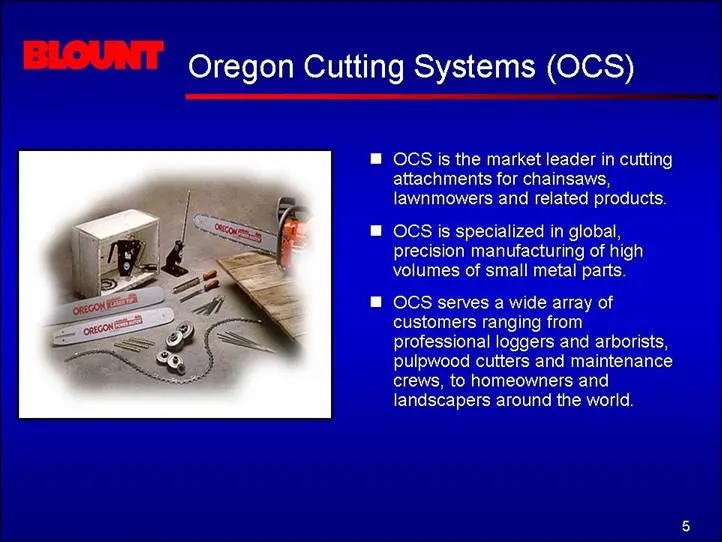
BLOUNT Oregon Cutting Systems (OCS) ™ OCS is the market leader in cutting attachments for chainsaws, lawnmowers and related products. ™ OCS is specialized in global, precision manufacturing of high volumes of small metal parts. ™ OCS serves a wide array of customers ranging from professional loggers
Slide 7: Oregon Cutting Systems: World Class Products and Distribution
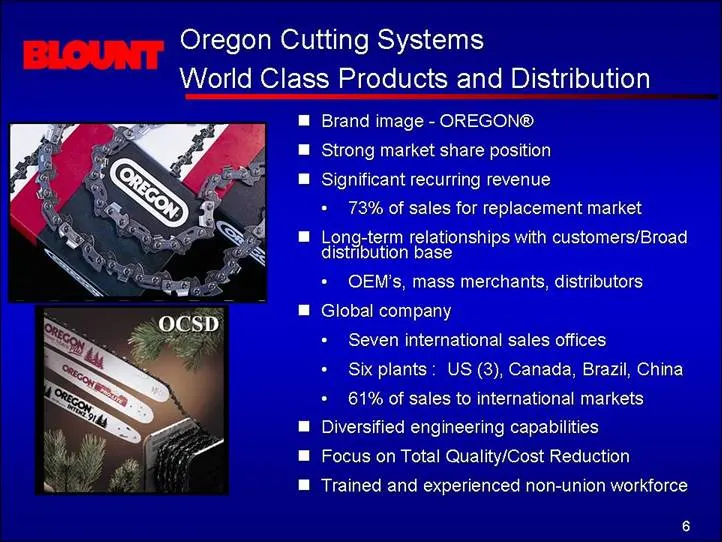
BLOUNT Oregon Cutting Systems World Class Products and Distribution ™ Brand image - OREGON® ™ Strong market share position ™ Significant recurring revenue + 73% of sales for replacement market ™ Long-term relationships with customers/Broad distribution base + OEM's, mass merchants, distributors ™ Gl
Slide 8: Oregon Cutting Systems Business Drivers
Oe Oregon Cutting Systems Business Drivers Residential & industrial construction Repair & remodeling Demand for pulp & paper Natural disasters Energy prices Firewood Disposable income
Slide 9: Oregon Cutting Systems Market Leader
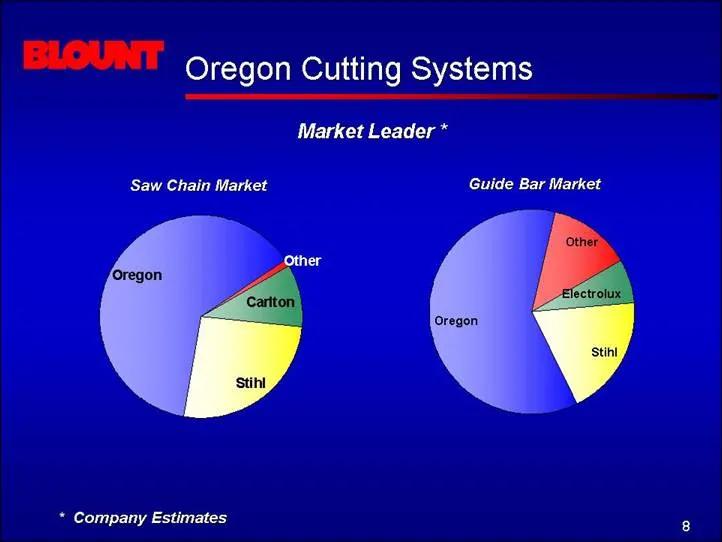
BLOUNT Oregon Cutting Systems Market Leader * Saw Chain Market Guide Bar Market Oregon * Company Estimates
Slide 10: Broad Distribution and Geographical Diversity
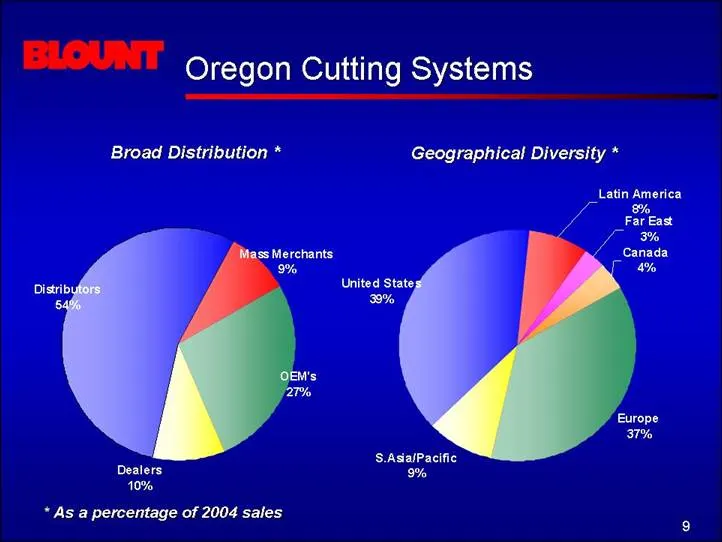
BLOUNT Oregon Cutting Systems Broad Distribution * Geographical Diversity * Latin America EA Far East 3% Canada 4% Dealers 10% * As a percentage of 2004 sales
Slide 11: Significant competitive advantage as low-cost operator in industry
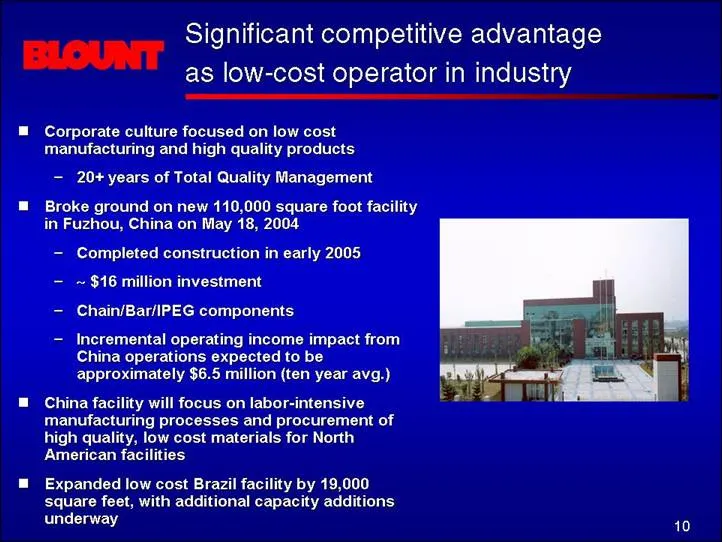
Significant competitive advantage as low-cost operator in industry ™ Corporate culture focused on low cost manufacturing and high quality products = 20+ years of Total Quality Management ™ Broke ground on new 110,000 square foot facility in Fuzhou, China on May 18, 2004 = Completed construction in e
Slide 12: Focus on replacement market
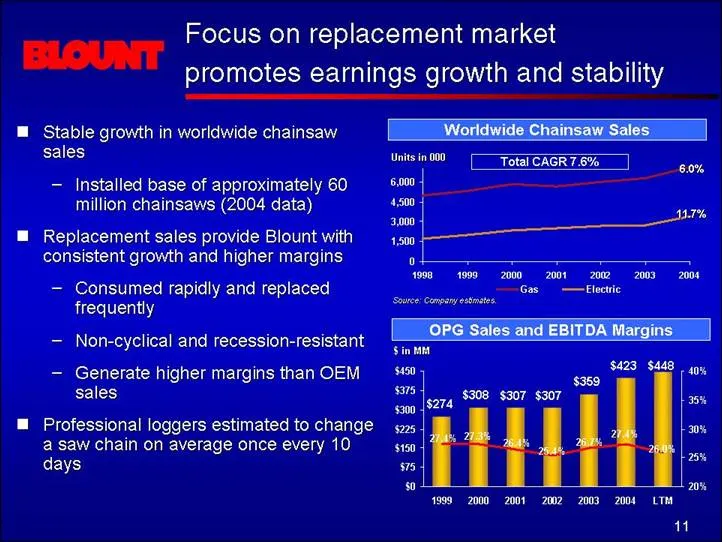
Focus on replacement market BLOUNT promotes earnings growth and stability ™ Stable growth in worldwide chainsaw [Worldwide Chainsaw Sales | sales ts ieee 60% — Installed base of approximately 60 vd eee million chainsaws (2004 data) cai 7% 300 eae ™ Replacement sales provide Blount with 4,500 consist
Slide 13: What is ICS?
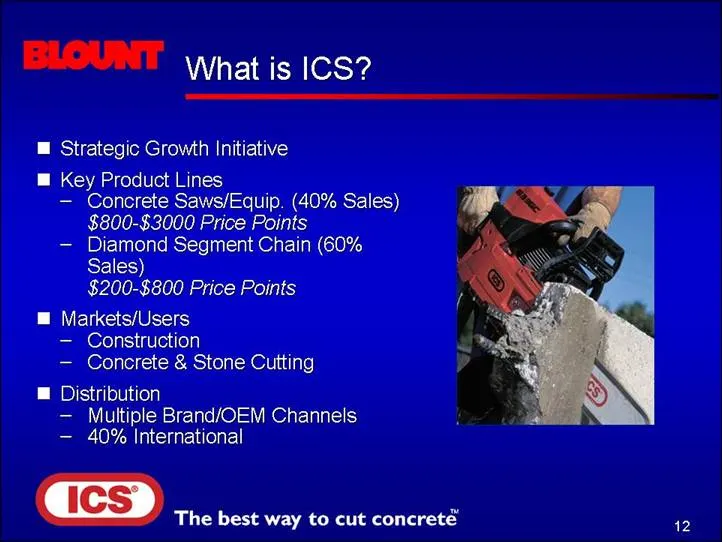
POO" what is Ics? @ Strategic Growth Initiative @ Key Product Lines — Concrete Saws/Equip. (40% Sales) $800-$3000 Price Points — Diamond Segment Chain (60% Sales) $200-$800 Price Points @ Markets/Users — Construction — Concrete & Stone Cutting ™ Distribution — Multiple Brand/OEM Channels — 40% Inter
Slide 14: Searchable text section of graphics shown above
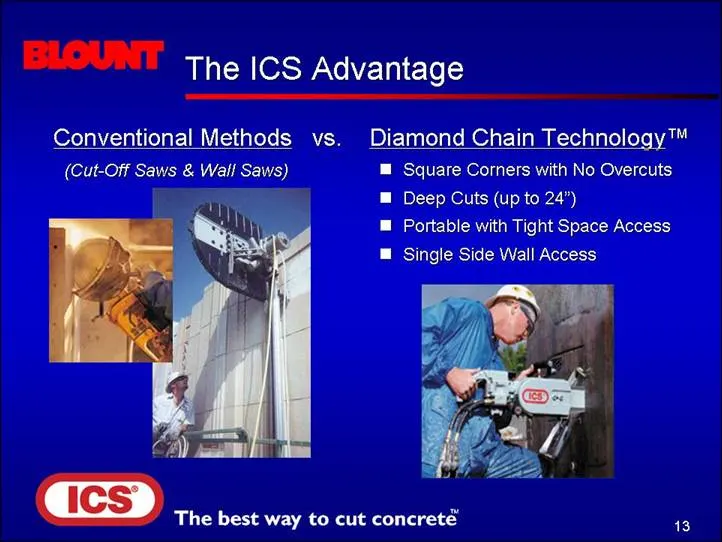
Searchable text section of graphics shown above [L OGO] [GRAPHIC] Robert W. Baird & Co. Industrial Conference November 8, 2005 For ward-looking statement Statements in this presentation that are not reported financial results or other historical information are “forward-looking statements” within th
Slide 15: The Customer Opportunity
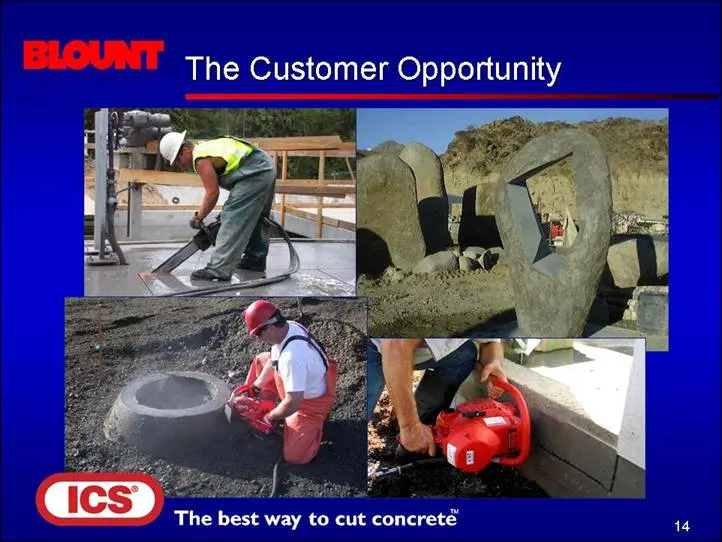
The Customer Opportunity The best way to cut concreté. 14
Slide 16: Innovation is Our Engine
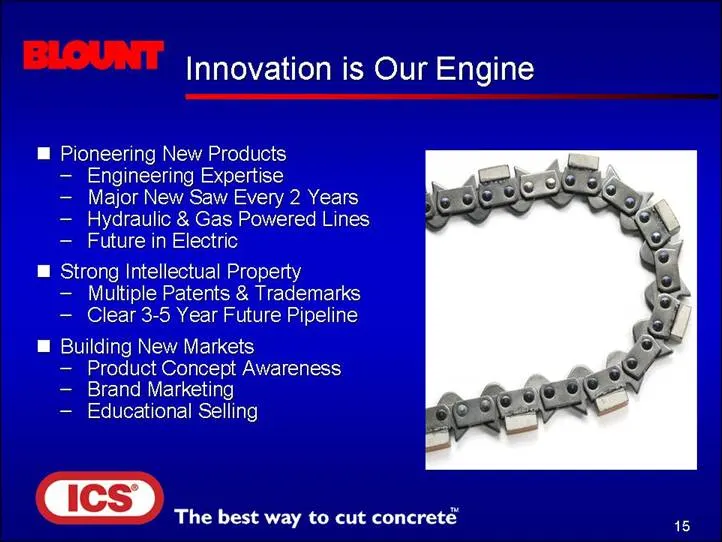
Innovation is Our Engine ™ Pioneering New Products. — Engineering Expertise — Major New Saw Every 2 Years — Hydraulic & Gas Powered Lines — Future in Electric @ Strong Intellectual Property — Multiple Patents & Trademarks — Clear 3-5 Year Future Pipeline @ Building New Markets — Product Concept Awar
Slide 17: The ICS Opportunity
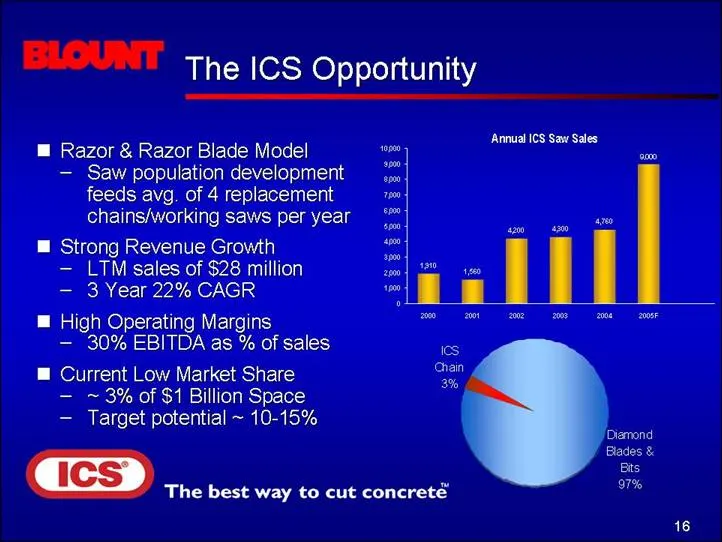
"2°" the Ics Opportunity ™@ Razor & Razor Blade Model pee — Saw population development a feeds avg. of 4 replacement 7980 chains/working saws per year ™@ Strong Revenue Growth Pe — LTM sales of $28 million am] Ea — 3 Year 22% CAGR wy @ High Operating Margins oe — 30% EBITDA as % of sales "eS @ Curre
Slide 18: Industrial & Power Equipment Group
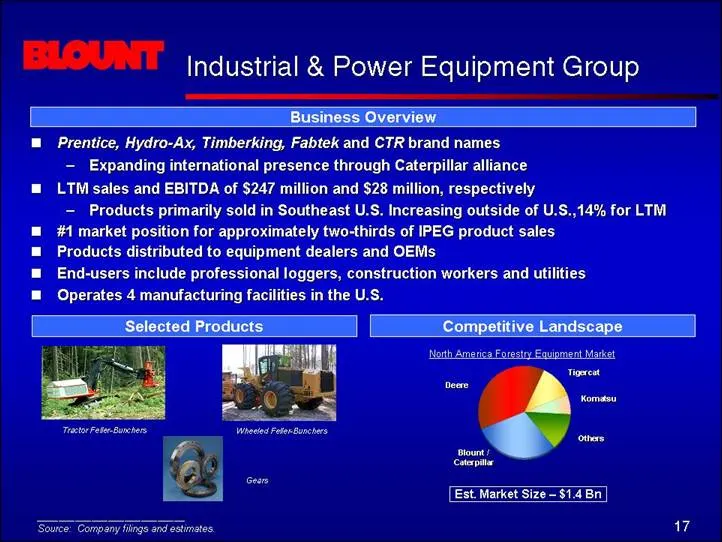
BieUNT Industrial & Power Equipment Group Prentice, Hydro-Ax, Timberking, Fabtek and CTR brand names — Expanding international presence through Caterpillar alliance LTM sales and EBITDA of $247 million and $28 million, respectively — Products primarily sold in Southeast U.S. Increasing outside of U.
Slide 19: Industrial & Power Equipment Group
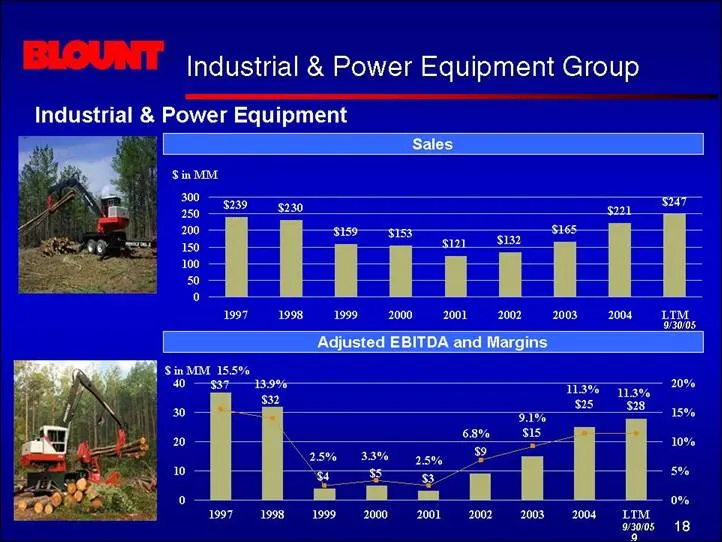
BieUNT Industrial & Power Equipment Group Industrial & Power Equipment 500s m3% nay 7”* S25 "28" 65, 1999 2000 93005 18 =
Slide 20: IPEG has been repositioned
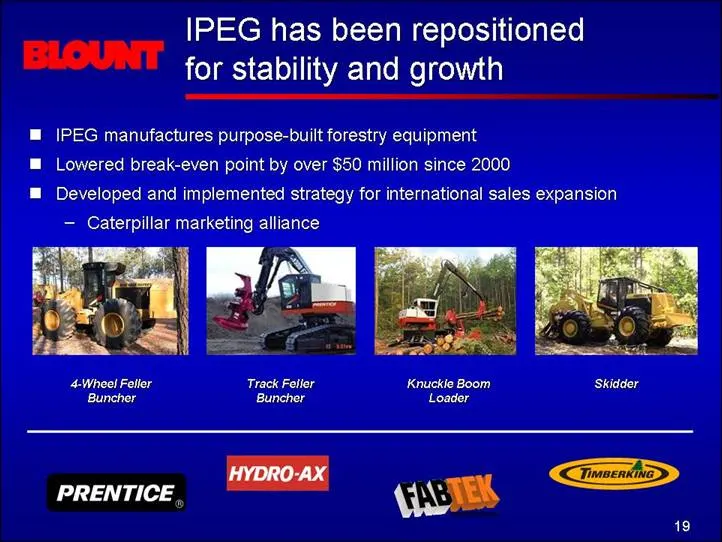
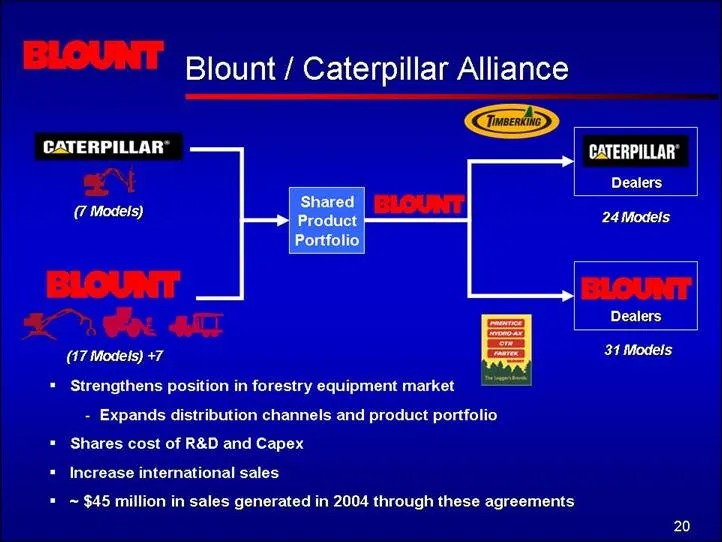
IPEG has been repositioned ‘BlounT for stability and growth m@ IPEG manufactures purpose-built forestry equipment ™ Lowered break-even point by over $50 million since 2000 ™ Developed and implemented strategy for international sales expansion — Caterpillar marketing alliance 4-Wheel Feller Track Fel
Slide 21: Searchable text section of graphics shown above
Searchable text section of graphics shown above The Customer Opportunity [GRAPHIC] Inn ovation is Our Engine • Pioneering New Products • Engineering Expertise • Major New Saw Every 2 Years • Hydraulic & Gas Powered Lines • Future in Electric • Strong Intellectual Property • Multiple Patents & Tradem
Slide 22: Significant expansion opportunity into new markets
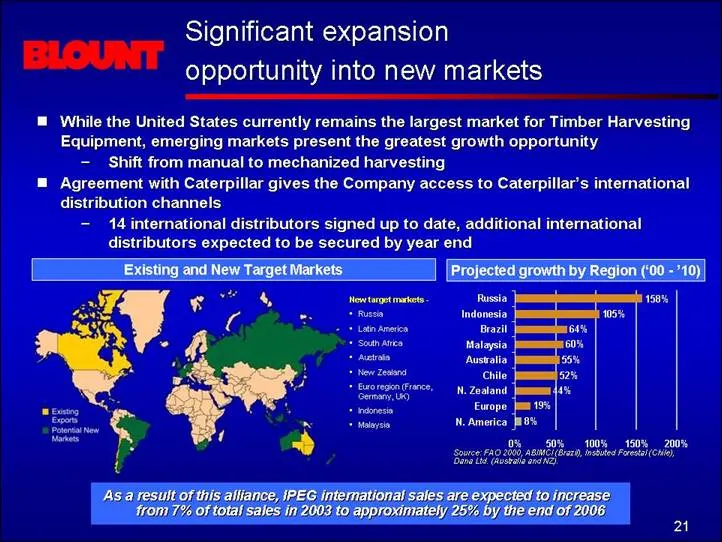
Significant expansion opportunity into new markets ™ While the United States currently remains the largest market for Timber Harvesting Equipment, emerging markets present the greatest growth opportunity = Shift from manual to mechanized harvesting ™ Agreement with Caterpillar gives the Company acce
Slide 23: Financial Strategy
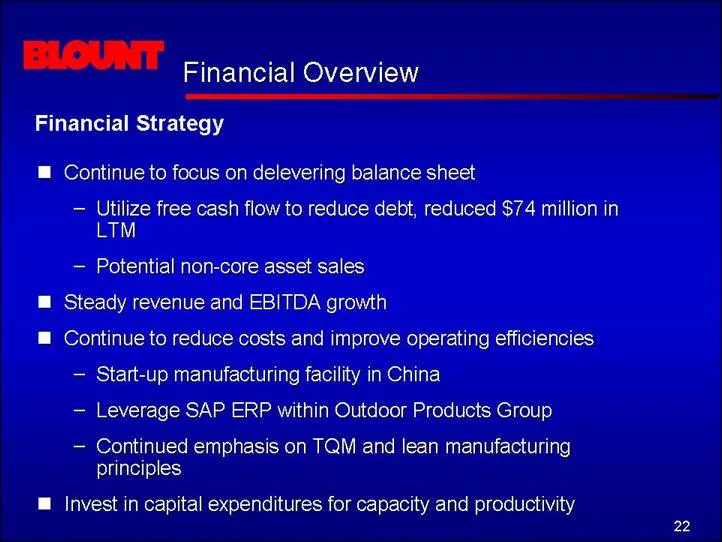
Financial Strategy Financial Overview ™ Continue to focus on delevering balance sheet — Utilize free cash flow to reduce debt, reduced $74 million in LTM — Potential non-core asset sales ™@ Steady revenue and EBITDA growth ™ Continue to reduce costs and improve operating efficiencies — Start-up manu
Slide 24: Solid revenue growth over time
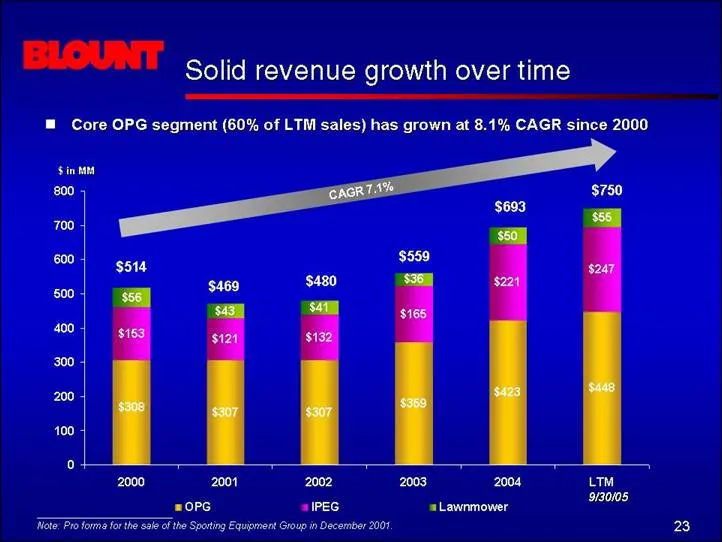
BLOUNT Solid revenue growth over time ™ Core OPG segment (60% of LTM sales) has grown at 8.1% CAGR since 2000 Sine 200 $750 $693 700 600 $514 $559 500 $469 $480 400 300 200 100 0 -— - = = 2000 2001 2002 2003 2008 _ =OPG = IPEG “Lawnmower sions Tita: Pro forma forthe 628 ofthe Spotting Equisment Grou
Slide 25: Strong EBITDA performance
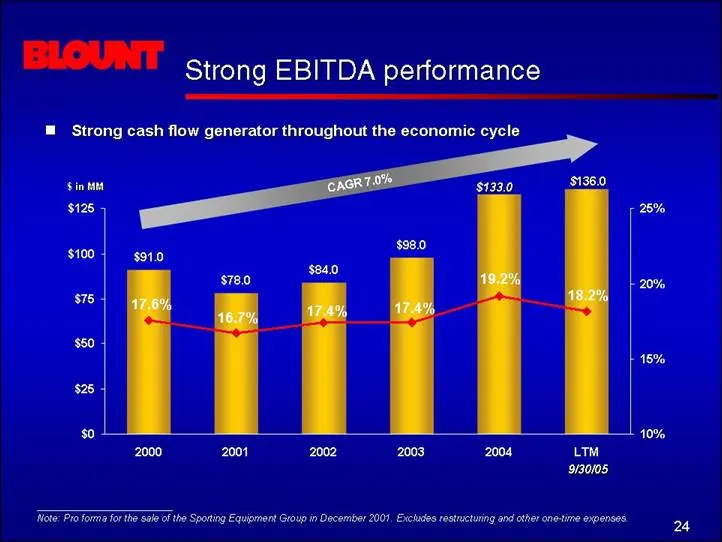
BLOUNT Strong EBITDA performance ™ Strong cash flow generator throughout the economic cycle Sint
Slide 26: Total Debt and Leverage
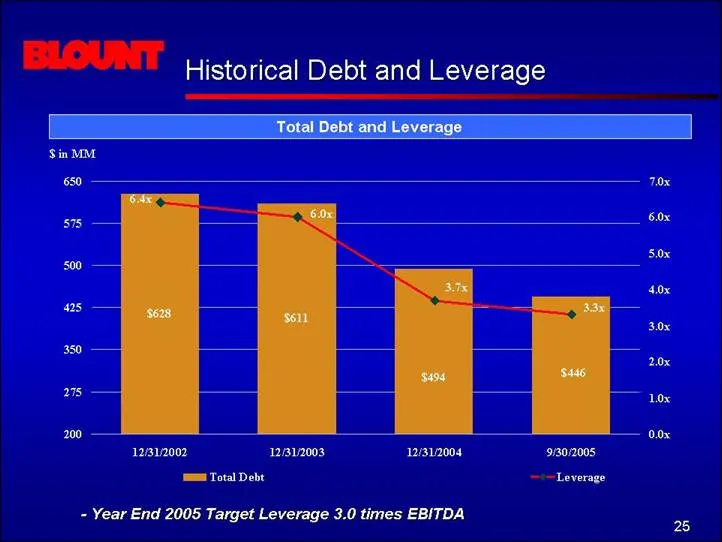
‘Sin MM 650 518 500 05 350 25 200 aag12002 1223172003 12312004 9730/2008 ‘Mim Total Debt ~ Leverage:
Slide 27: Searchable text section of graphics shown above
Searchable text section of graphics shown above Sig nificant expansion opportunity into new markets • While the United States currently remains the largest market for Timber Harvesting Equipment, emerging markets present the greatest growth opportunity • Shift from manual to mechanized harvesting •
Source: SEC EDGAR · 8-K filed Nov 8, 2005
More decks from Blount International Inc
 Merger or Acquisition (March 2016)7 slides · Mar 2, 2016
 Merger or Acquisition (December 2015)10 slides · Dec 15, 2015
 Lehman Brothers High Yield & Syndicated Loan Conference 200525 slides · Mar 16, 2005
 Investor Presentation (November 2004)14 slides · Nov 12, 2004
 Lehman Brothers High Yield & Syndicated Loan Conference (March 2004)37 slides · Mar 22, 2004
 Shareholder Meeting (November 2003)8 slides · Nov 20, 2003