Consolidated Communications — Lehman Brothers 2006 Worldwide Wireless, Wireline, & Media Conference
31 slides from Consolidated Communications's conference presentation, May 23, 2006
Slide 1: Lehman Brothers 2006 Worldwide Wireless, Wireline, & Media Conference
Lehman Brothers 2006 Worldwide Wireless, Wireline, & Media Conference May 23, 2006 Bob Currey - President and CEO Steve Childers - CFO
Slide 2: Regulation G and Safe Harbor
Regulation G and Safe Harbor Regulation G This presentation contains disclosures regarding our "adjusted EBIDTA", cash available to pay dividends and "total net debt to last 12-month adjusted EBITDA", all of which are non-GAAP financial measures as defined by Regulation G of the rules of the Securit
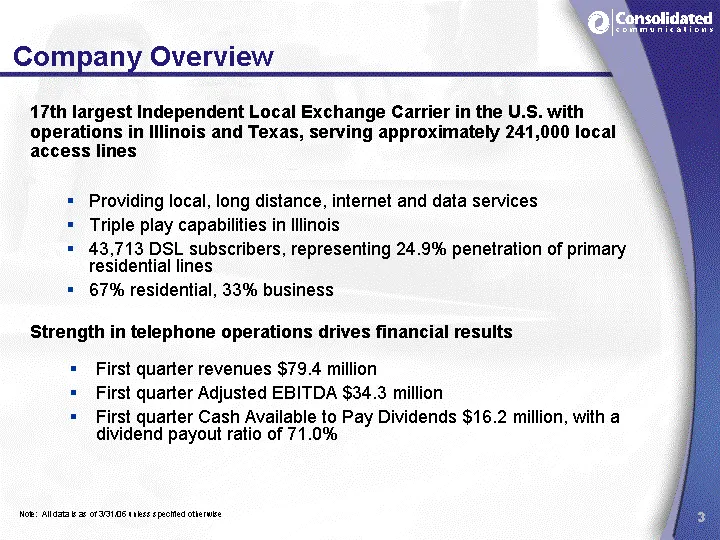
Slide 3: Company Overview
Company Overview 17th largest Independent Local Exchange Carrier in the U.S. with operations in Illinois and Texas, serving approximately 241,000 local access lines Providing local, long distance, internet and data services Triple play capabilities in Illinois 43,713 DSL subscribers, representing 24
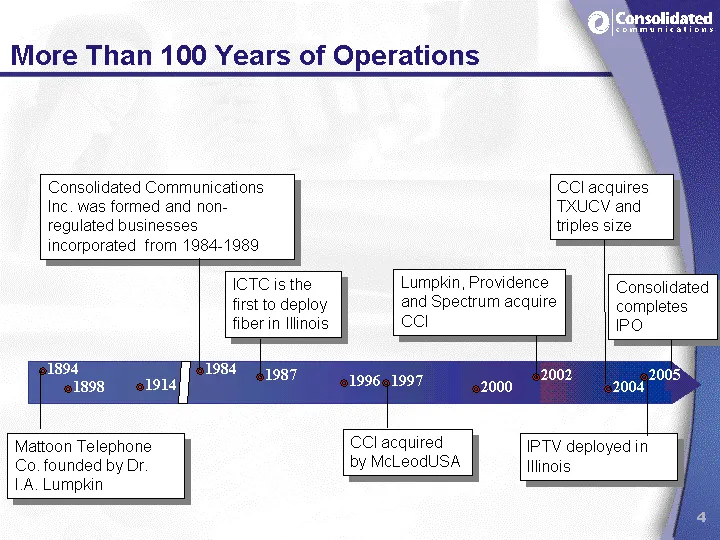
Slide 4: More Than 100 Years of Operations
More Than 100 Years of Operations 1894 1898 Mattoon Telephone Co. founded by Dr. I.A. Lumpkin 1984 1987 2005 1997 2002 2000 1996 2004 Consolidated Communications Inc. was formed and non- regulated businesses incorporated from 1984-1989 ICTC is the first to deploy fiber in Illinois CCI acquired by Mc
Slide 5: Stable Rural Markets in Illinois & Lufkin, Texas
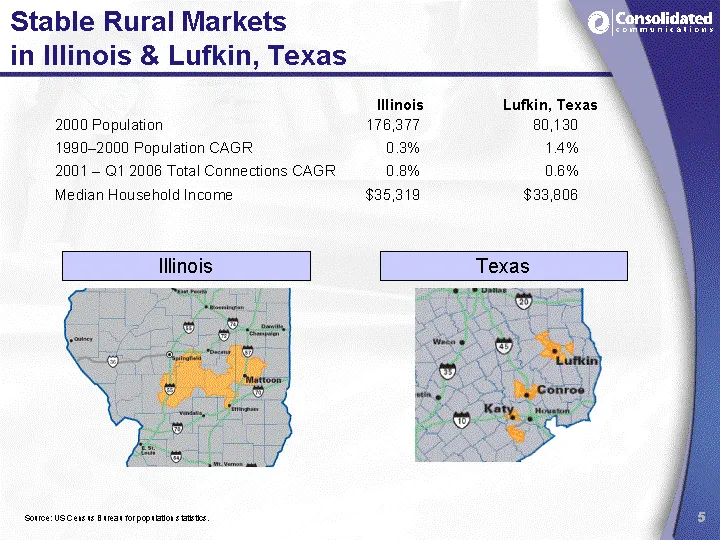
Stable Rural Markets in Illinois & Lufkin, Texas Source: US Census Bureau for population statistics. Illinois Texas
Slide 6: Growing Suburban / Rural Markets in Katy & Conroe, Texas
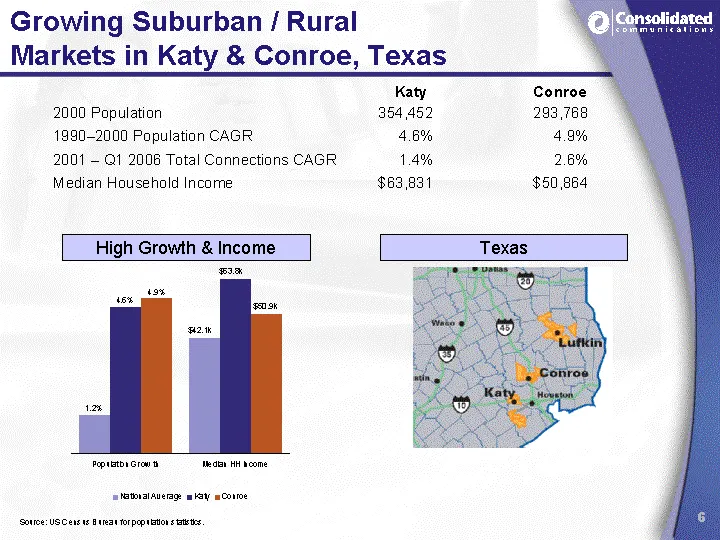
Growing Suburban / Rural Markets in Katy & Conroe, Texas Source: US Census Bureau for population statistics. High Growth & Income Texas
Slide 7: Limited Competition
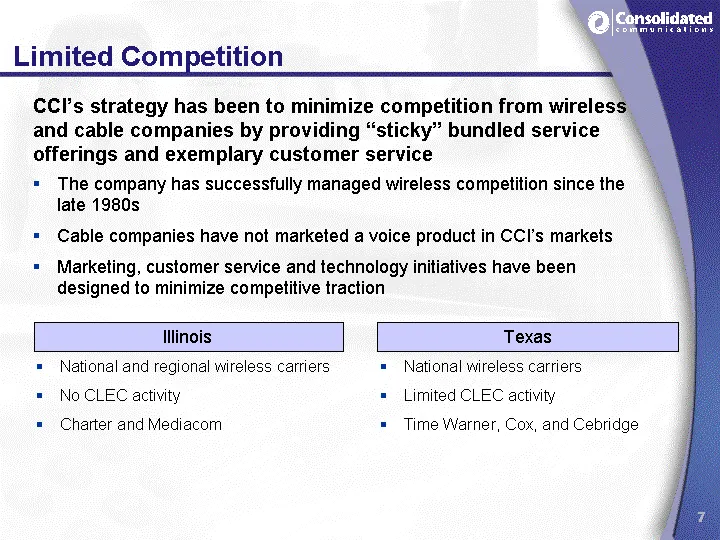
The company has successfully managed wireless competition since the late 1980s Cable companies have not marketed a voice product in CCI's markets Marketing, customer service and technology initiatives have been designed to minimize competitive traction Limited Competition CCI's strategy has been to
Slide 8: Favorable Regulatory Environment
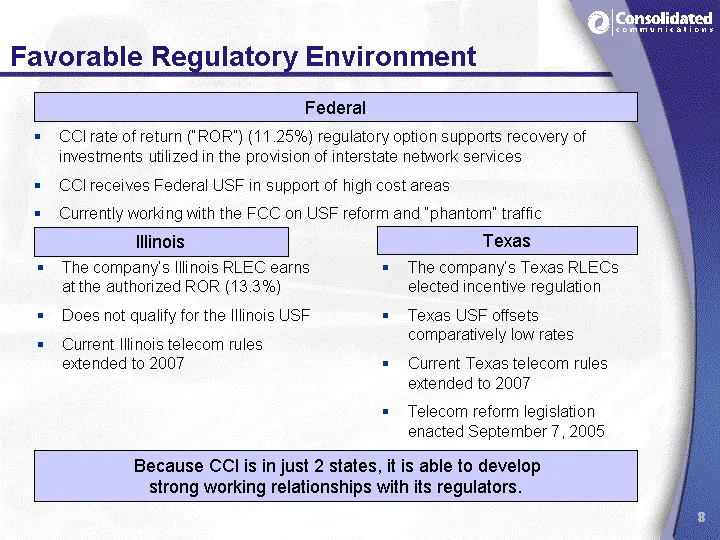
Favorable Regulatory Environment Illinois Texas Federal CCI rate of return ("ROR") (11.25%) regulatory option supports recovery of investments utilized in the provision of interstate network services CCI receives Federal USF in support of high cost areas Currently working with the FCC on USF reform
Slide 9: Experienced & Operations-Focused Management Team
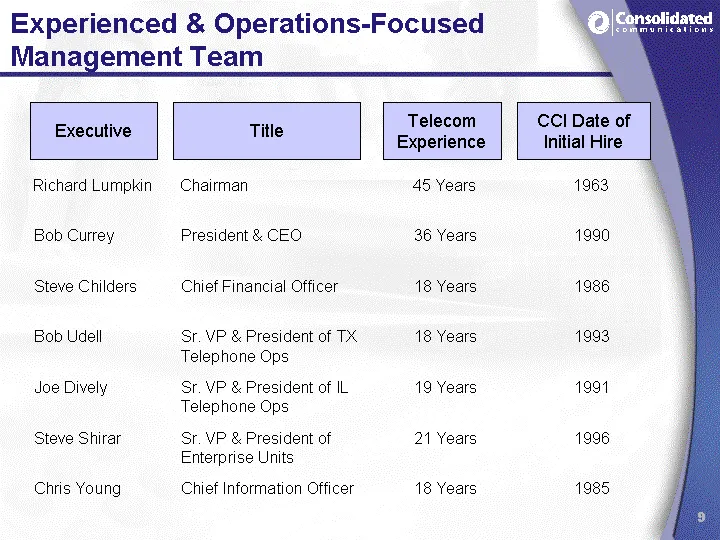
Experienced & Operations-Focused Management Team Executive Title Telecom Experience Bob Currey President & CEO 36 Years Steve Childers Chief Financial Officer 18 Years Joe Dively Sr. VP & President of IL Telephone Ops 19 Years Steve Shirar Sr. VP & President of Enterprise Units 21 Years Bob Udell Sr
Slide 10: Executing on our Strategy
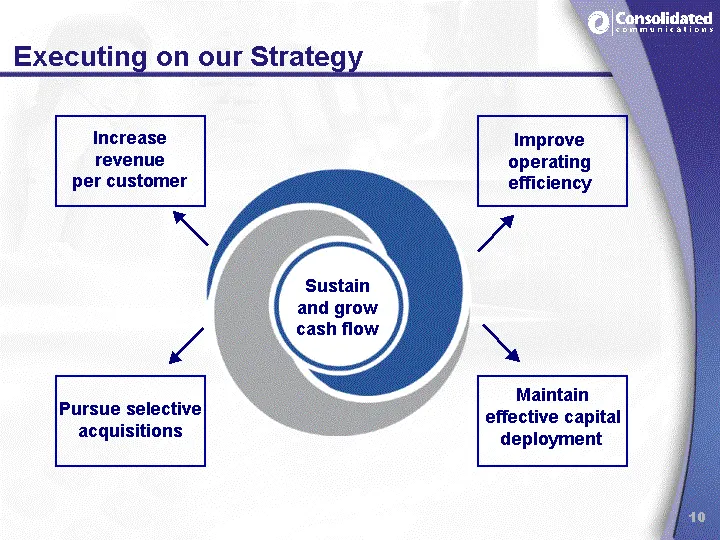
Executing on our Strategy 19 Sustain and grow cash flow Increase revenue per customer Improve operating efficiency Pursue selective acquisitions Maintain effective capital deployment
Slide 11: Increasing Revenue per Customer
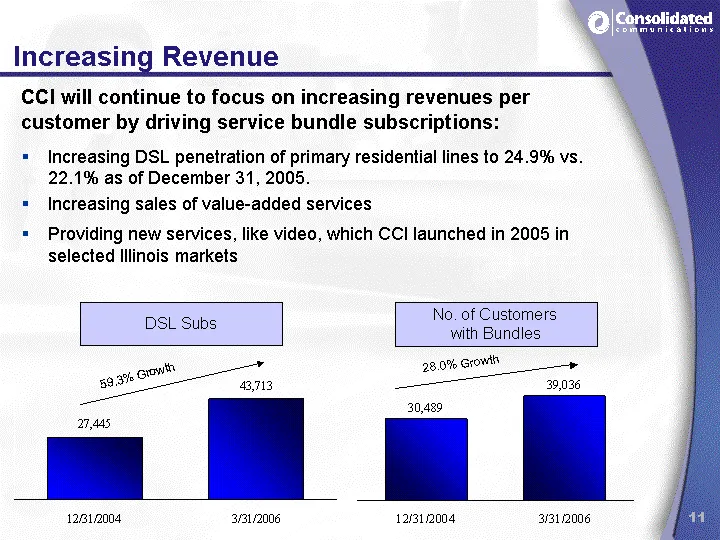
CCI will continue to focus on increasing revenues per customer by driving service bundle subscriptions: Increasing DSL penetration of primary residential lines to 24.9% vs. 22.1% as of December 31, 2005. Increasing sales of value-added services Providing new services, like video, which CCI launched
Slide 12: Increasing Revenue - DSL
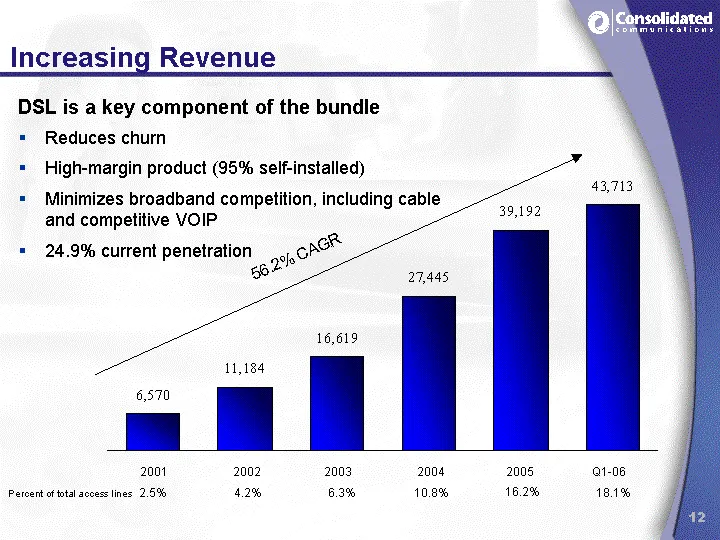
Increasing Revenue 56.2% CAGR DSL is a key component of the bundle Reduces churn High-margin product (95% self-installed) Minimizes broadband competition, including cable and competitive VOIP 24.9% current penetration Percent of total access lines 2.5% 4.2% 6.3% 10.8% 18.1% 2001 2002 2004 2003 Q1-06
Slide 13: Increasing Revenue - New Opportunity Illinois Triple Play
Increasing Revenue - New Opportunity Illinois Triple Play - IPTV Voice, Video & Data Incremental Product Rollout Leverages existing resources and network IP Backbone/ADSL 2+ Future CapEx is success based Gateway set top box is tested and ready for full launch Full marketing launch in August 2005 in
Slide 14: Stable Customer Base
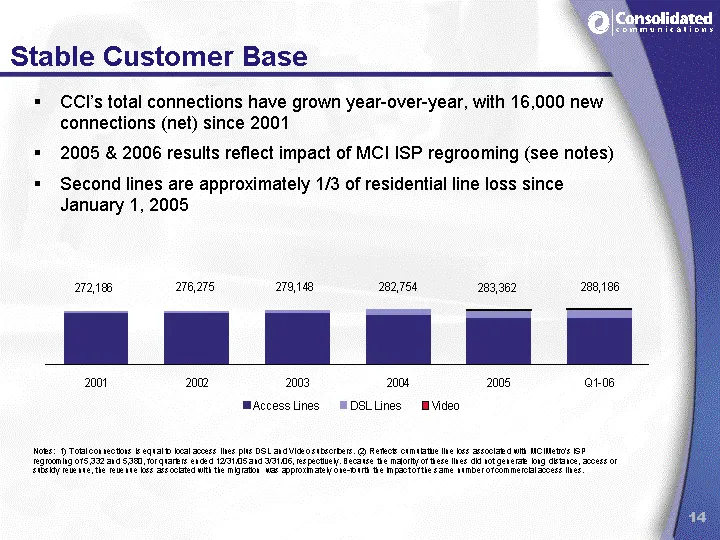
Stable Customer Base Notes: 1) Total connections is equal to local access lines plus DSL and Video subscribers. (2) Reflects cumulative line loss associated with MCIMetro's ISP regrooming of 5,332 and 5,380, for quarters ended 12/31/05 and 3/31/06, respectively. Because the majority of these lines d
Slide 15: Integration Creates Potential for Greater Operating Efficiencies
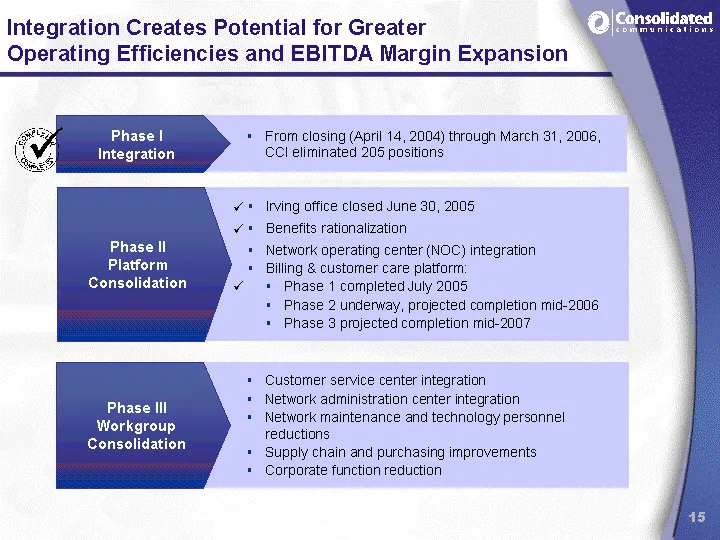
Irving office closed June 30, 2005 Benefits rationalization Network operating center (NOC) integration Billing & customer care platform: Phase 1 completed July 2005 Phase 2 underway, projected completion mid-2006 Phase 3 projected completion mid-2007 Phase II Platform Consolidation Integration Creat
Slide 16: Total Headcount & Adjusted EBITDA per Employee
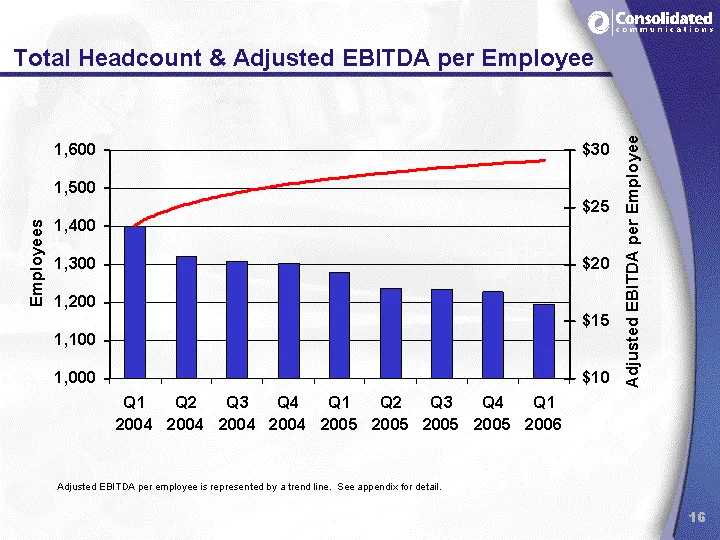
Total Headcount & Adjusted EBITDA per Employee Q1 2004 Q2 2004 Q3 2004 Q4 2004 Q1 2005 Q2 2005 Q3 2005 Q4 2005 Q1 2006 Adjusted EBITDA 22 26 29 27 26 29 27 29 29 Employees 1400 1321 1308 1303 1280 1237 1235 1229 1195 Adjusted EBITDA per employee is represented by a trend line. See appendix for detai
Slide 17: Effective Capital Deployment
Effective Capital Deployment Since Jan. 1, 2003, the company has invested $83.3 million in its network, including its core IP backbone and softswitch technology, which enables video and VOIP Fiber network connects 54 of 56 of the company's exchanges, serving over 99.6% of all access lines 92% of tot
Slide 18: Acquisition Philosophy
Acquisition Philosophy Attractiveness of the markets Quality of the network The company's ability to integrate the acquired company efficiently Potential operating synergies The potential of any proposed transaction to permit increased dividends on the company's common stock CCI has a proven track r
Slide 19: Solid Financial Results
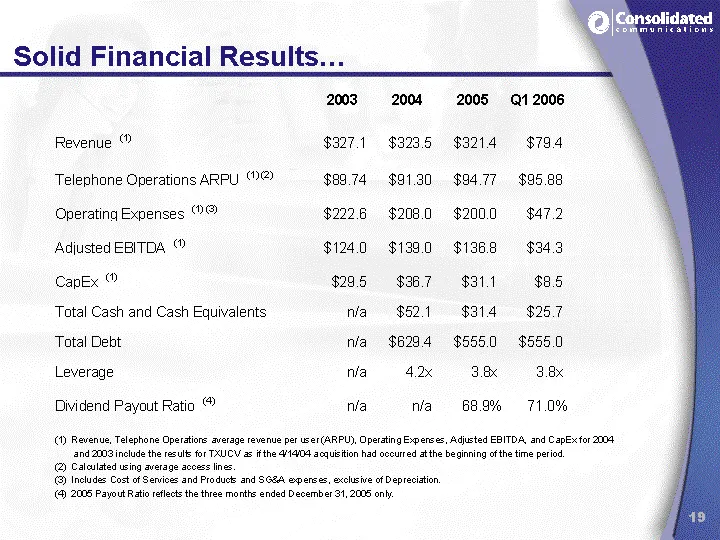
Solid Financial Results. 2004 = 20051 2006 Revenue $327.1 $3235 $3214 $794 Telephone Operations ARPU (? $89.74 $91.30 $94.77 $95.98 Operating Expenses $2226 $2080 $2000 $47.2 Adjusted EBITDA © $124.0 $1390 $1368 $34.3 Capex © $295 $36.7 © $31.1 $8.5 Total Cash and Cash Equivalents na $621 $314 $25.7
Slide 20: Capital Structure Transactions Post IPO
Capital Structure Transactions Post IPO Net increase of $150.0 million in hedge position brings total fixed term debt to $360.0 million, or 85 percent On November 25, 2005, re-priced the term loan D facility to LIBOR + 175 bps, a reduction of 50 bps, which we expect will generate annual interest sav
Slide 21: Investment Highlights
Investment Highlights Attractive Markets and Limited Competition Stable Local Telephone Business Bundled Service Offerings Favorable Regulatory Environment Technologically Advanced Network Experienced Management Team
Slide 22: Appendix
Appendix
Slide 23: GAAP Reconciliation
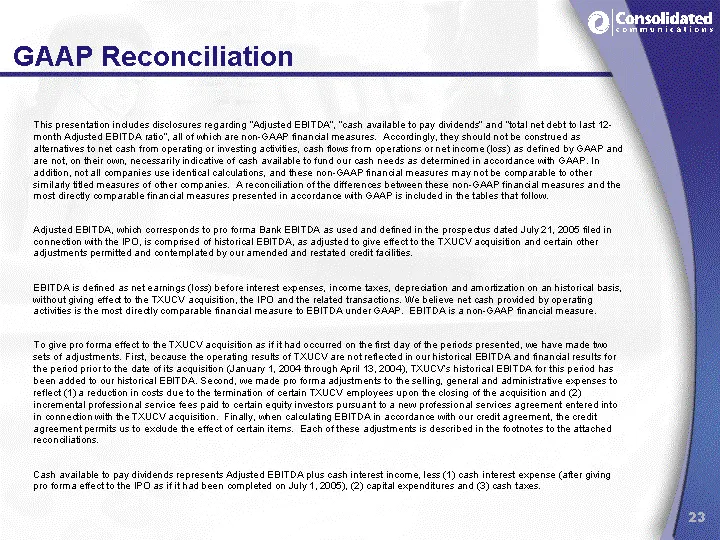
GAAP Reconciliation This presentation includes disclosures regarding "Adjusted EBITDA", "cash available to pay dividends" and "total net debt to last 12- month Adjusted EBITDA ratio", all of which are non-GAAP financial measures. Accordingly, they should not be construed as alternatives to net cash
Slide 24: GAAP Reconciliation
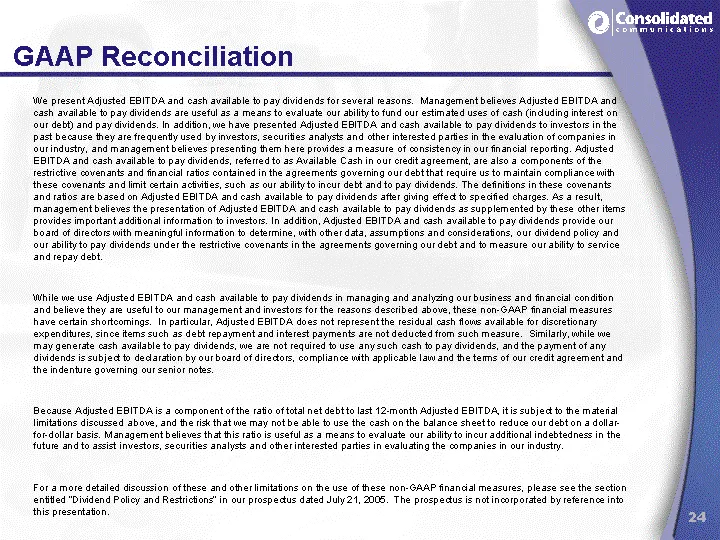
GAAP Reconciliation We present Adjusted EBITDA and cash available to pay dividends for several reasons. Management believes Adjusted EBITDA and cash available to pay dividends are useful as a means to evaluate our ability to fund our estimated uses of cash (including interest on our debt) and pay di
Slide 25: GAAP Reconciliation (Cont'd)
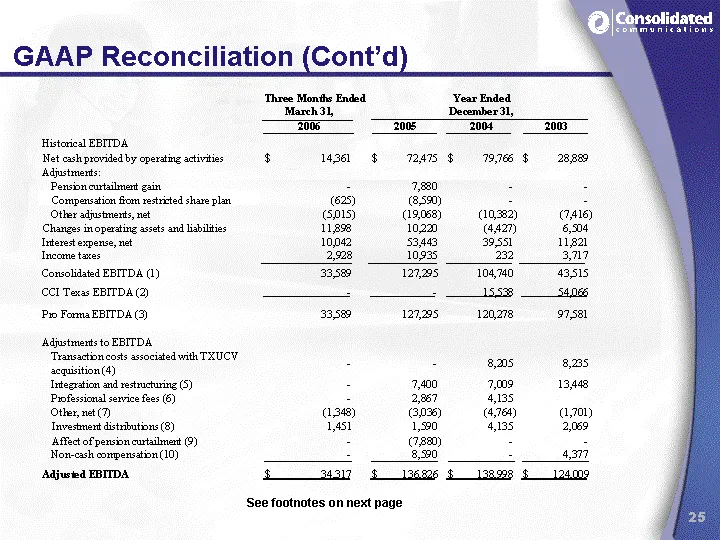
GAAP Reconciliation (Cont'd) See footnotes on next page
Slide 26: GAAP Reconciliation (Cont'd)
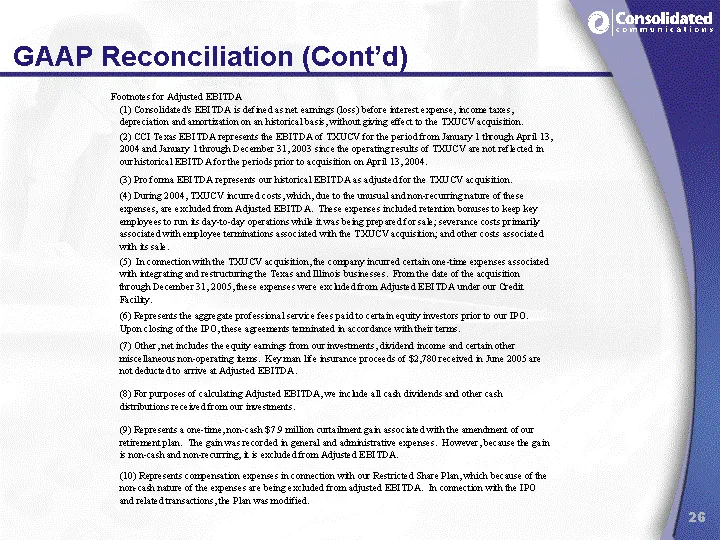
GAAP Reconciliation (Cont'd)
Slide 27: Cash Available to Pay Dividends
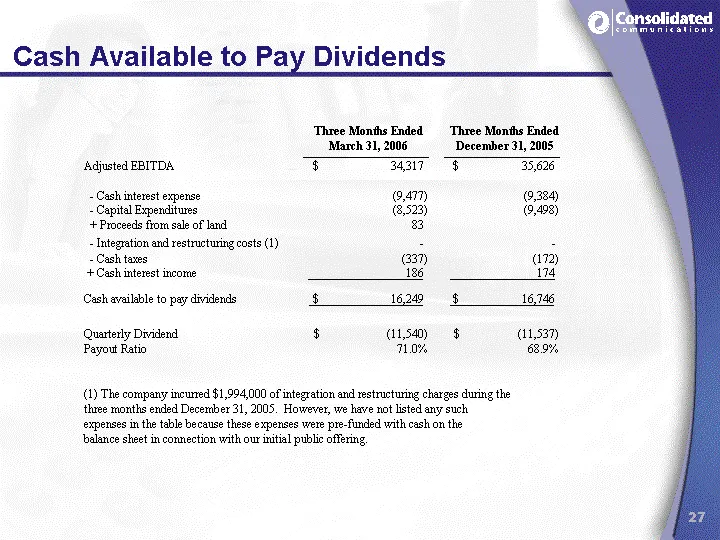
Cash Available to Pay Dividends
Slide 28: Total Net Debt to Adjusted EBITDA Ratio
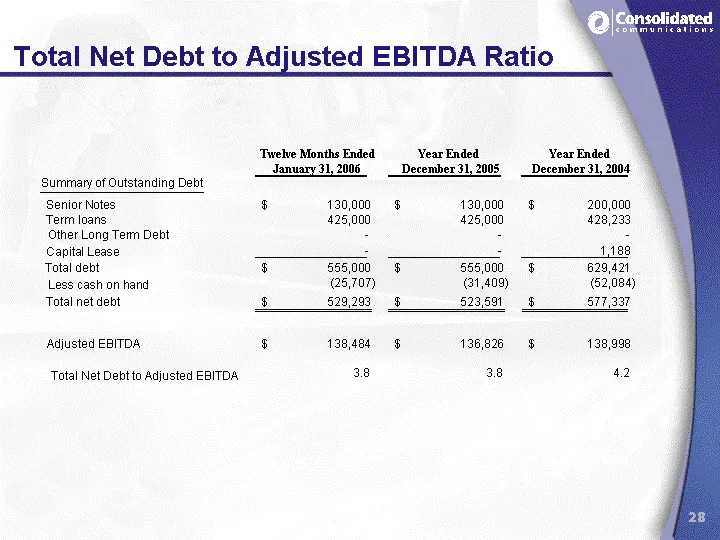
Total Net Debt to Adjusted EBITDA Ratio
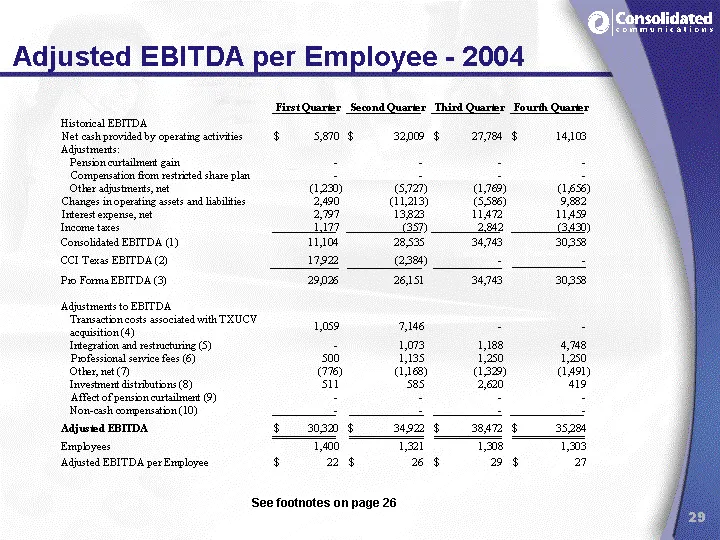
Slide 29: Adjusted EBITDA per Employee - 2004
Adjusted EBITDA per Employee - 2004 See footnotes on page 26
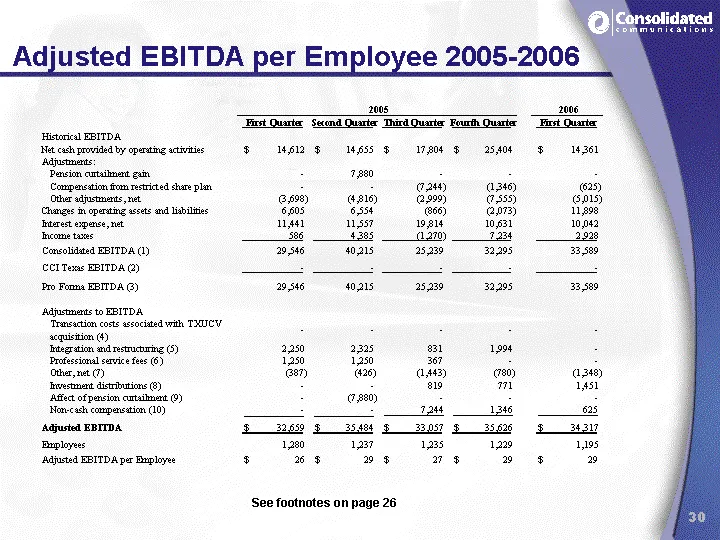
Slide 30: Adjusted EBITDA per Employee 2005-2006
Adjusted EBITDA per Employee 2005-2006 See footnotes on page 26
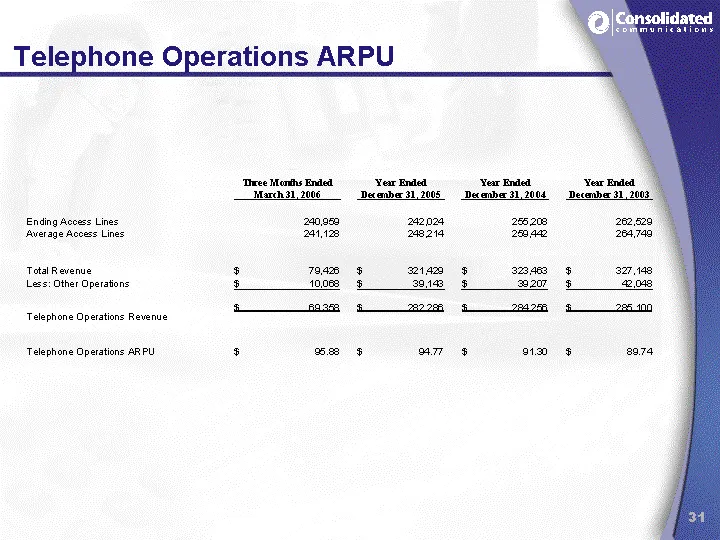
Slide 31: Ending Access Lines and Telephone Operations ARPU
Ending Access Lines ‘Average Access Lines Total Revenue Less: Other Operations Telephone Operations Revenue Telephone Operations ARPU perations ARPU e Consolidated ‘Dee Menthe Ended Yeu Ended Yer Ended Yer Ended ‘Mirch 31,2006 Decenber 31,2005 _Decenber 31,2004, Deconer 31,2002 240.960 params 286208
Source: SEC EDGAR · 8-K filed May 23, 2006
More decks from Consolidated Communications
 Proxy Contest (January 2024)34 slides · Jan 11, 2024
 Merger or Acquisition (October 2023)7 slides · Oct 16, 2023
 Q2 2023 Earnings Presentation27 slides · Aug 8, 2023
 Q1 2023 Earnings Presentation28 slides · May 2, 2023
 Shareholder Meeting (May 2023)15 slides · May 1, 2023
 J.P. Morgan Global High Yield & Leveraged Finance Conference 202317 slides · Mar 7, 2023