Chittenden — Investor Presentation (July 2004)
35 slides from Chittenden's investor presentation, Jul 28, 2004
Slide 1: Chittenden Corporation – As of June 30, 2004
TY y “4 Chittenuln CORPORATION , reaching more customers As of June'20, 2008 by reaching out with more Chittenden
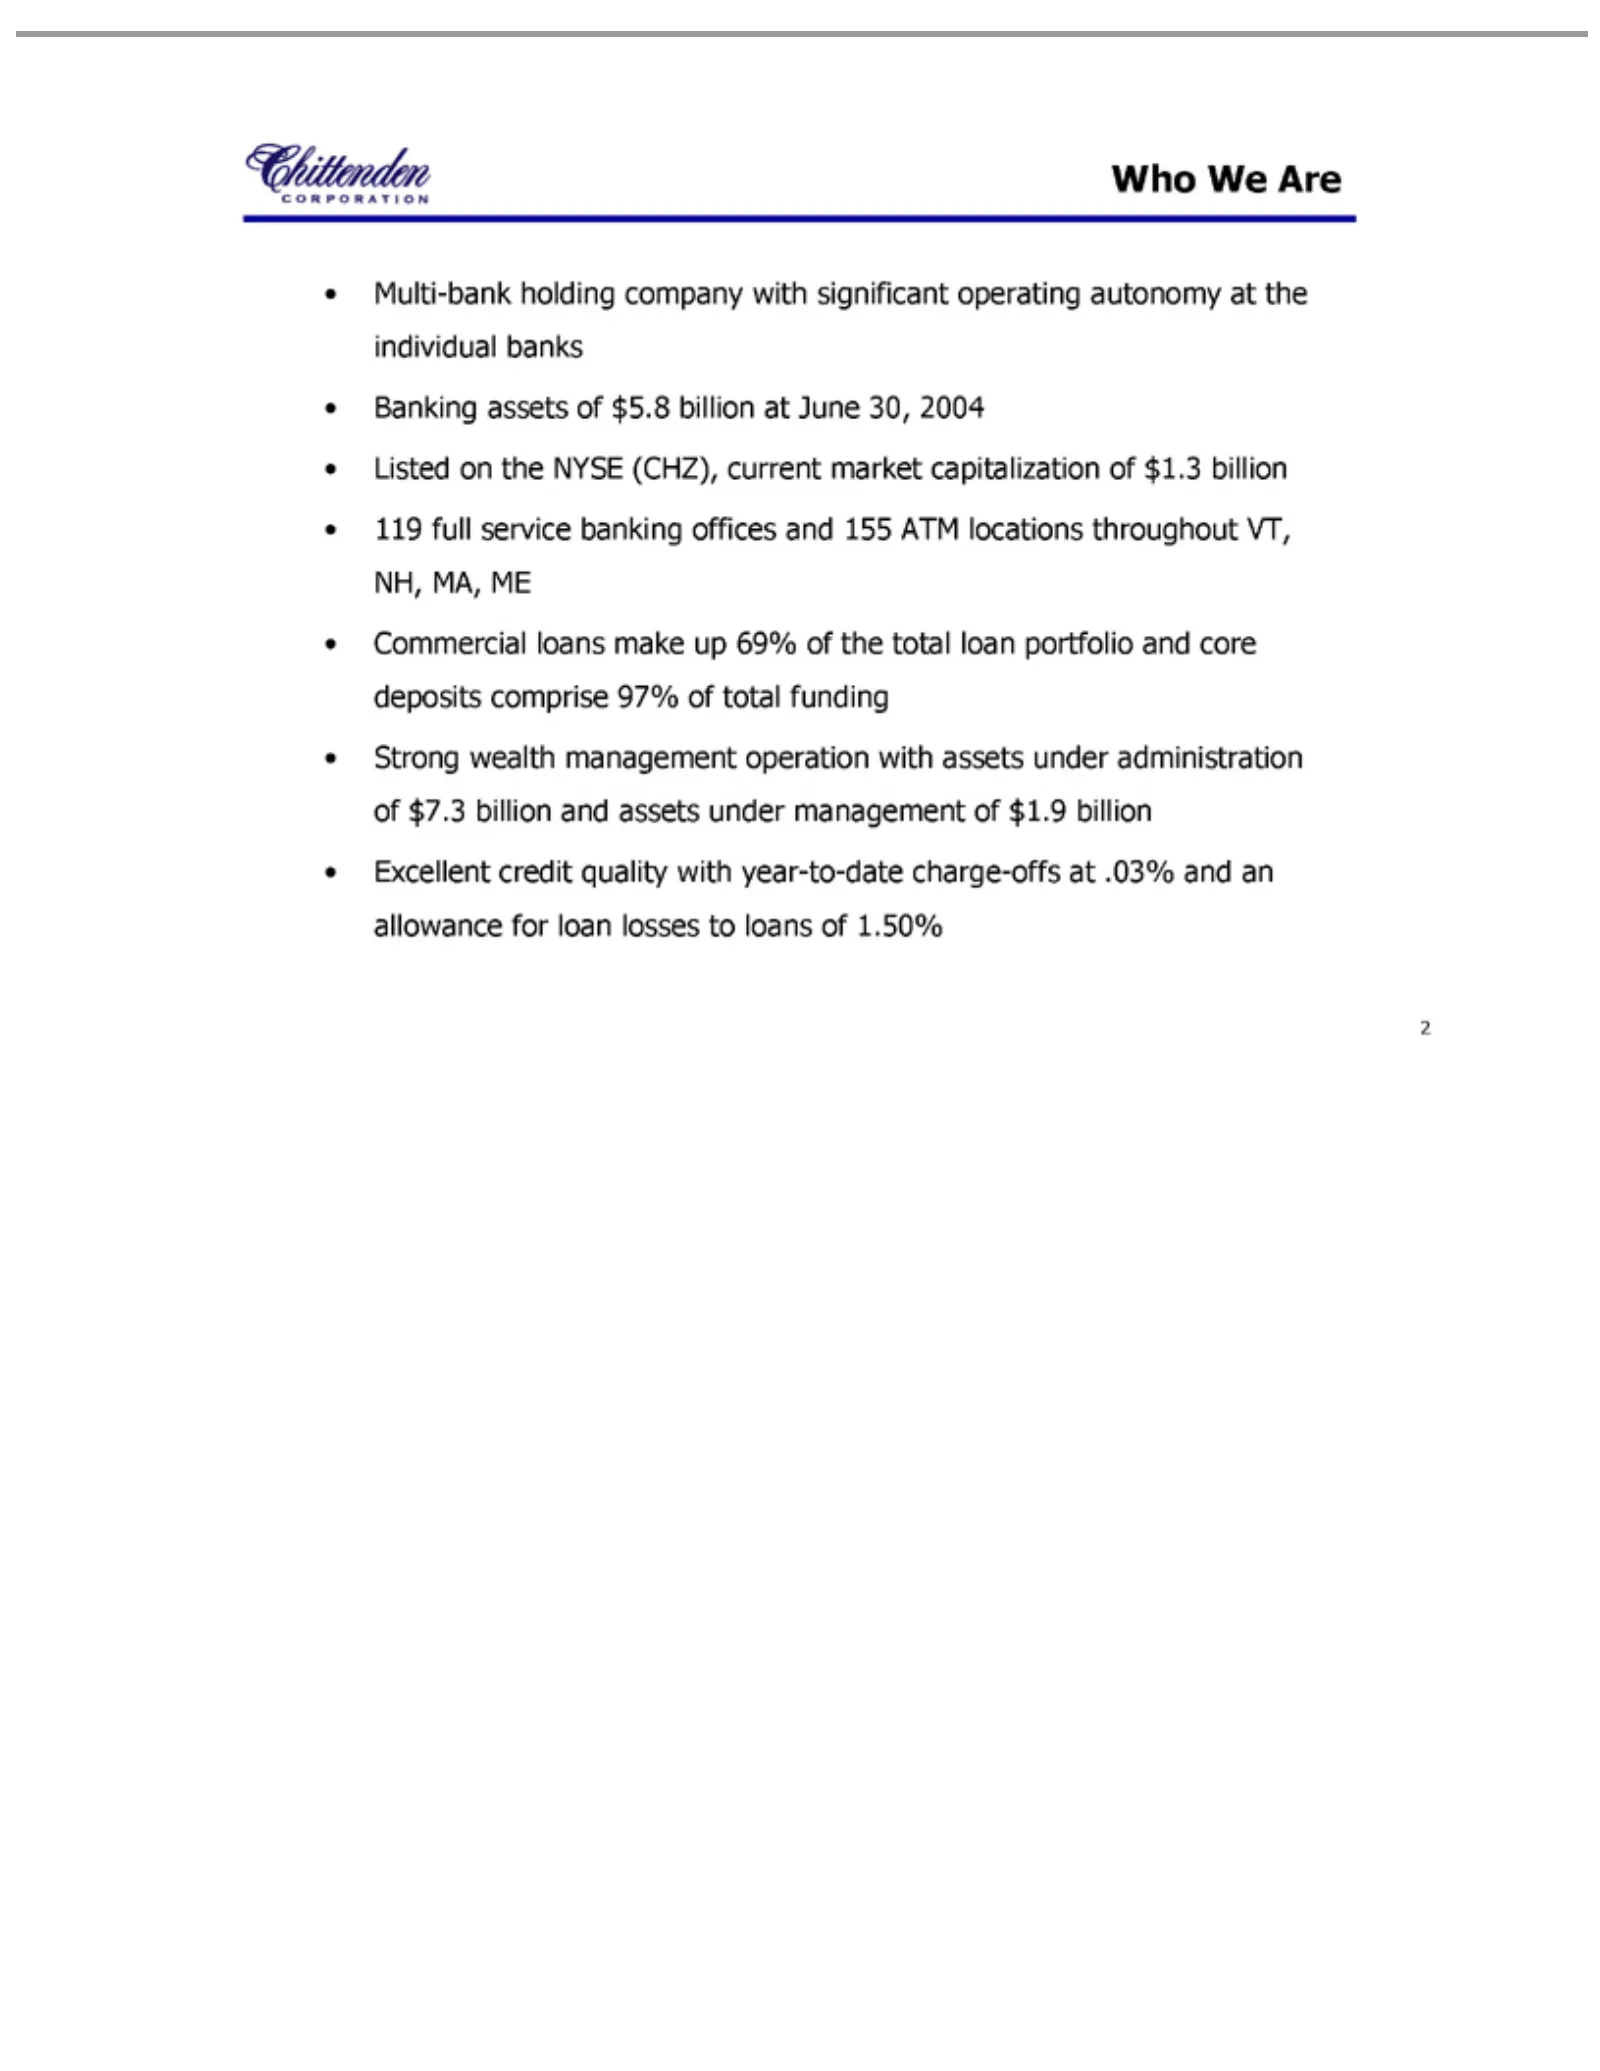
Slide 2: Who We Are
Who billion Multi-bank $1.3 Commercial assets 2 We under Areholding 119 management loans fullmake company service upof69% banking $1.9 withof billion significant the offices total Excellent and loan operating 155 portfolio credit ATMautonomy quality locations and core with atdeposits throughout the
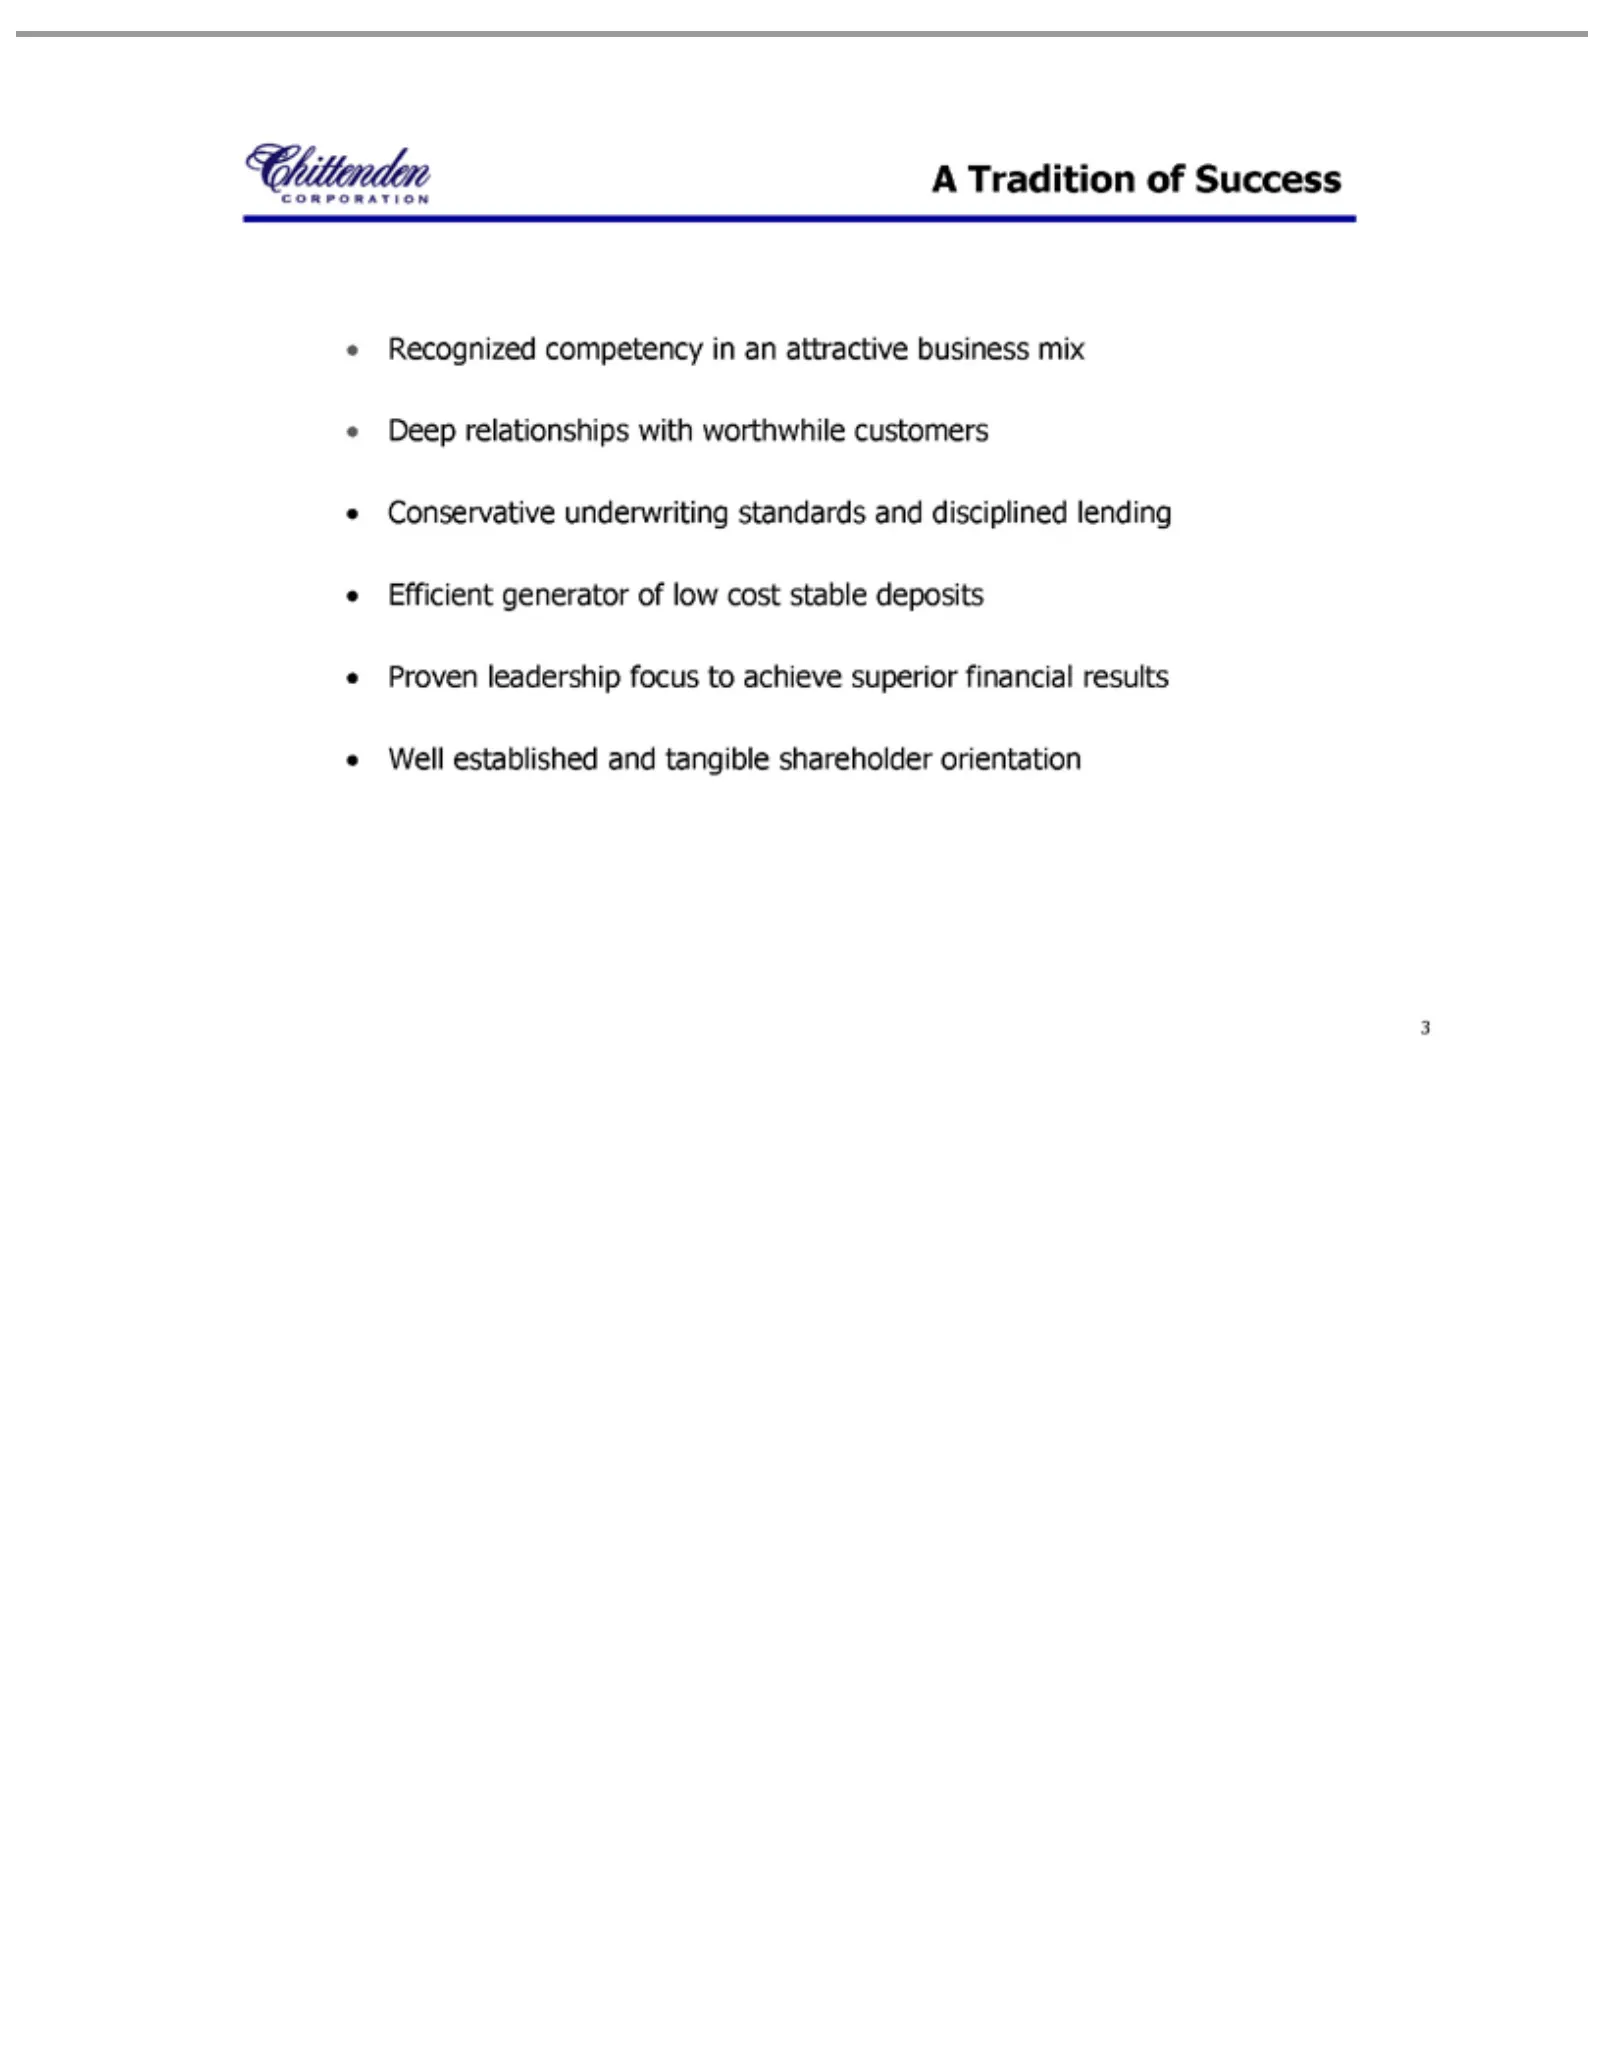
Slide 3: A Tradition of Proven Success
A Tradition Recognized deposits 3 Proven of competency Success leadership in focus an attractive to achieve business superior mixfinancial Deep relationships results Wellwith established worthwhile and customers tangible shareholder Conservative orientation underwriting standards and disciplined len
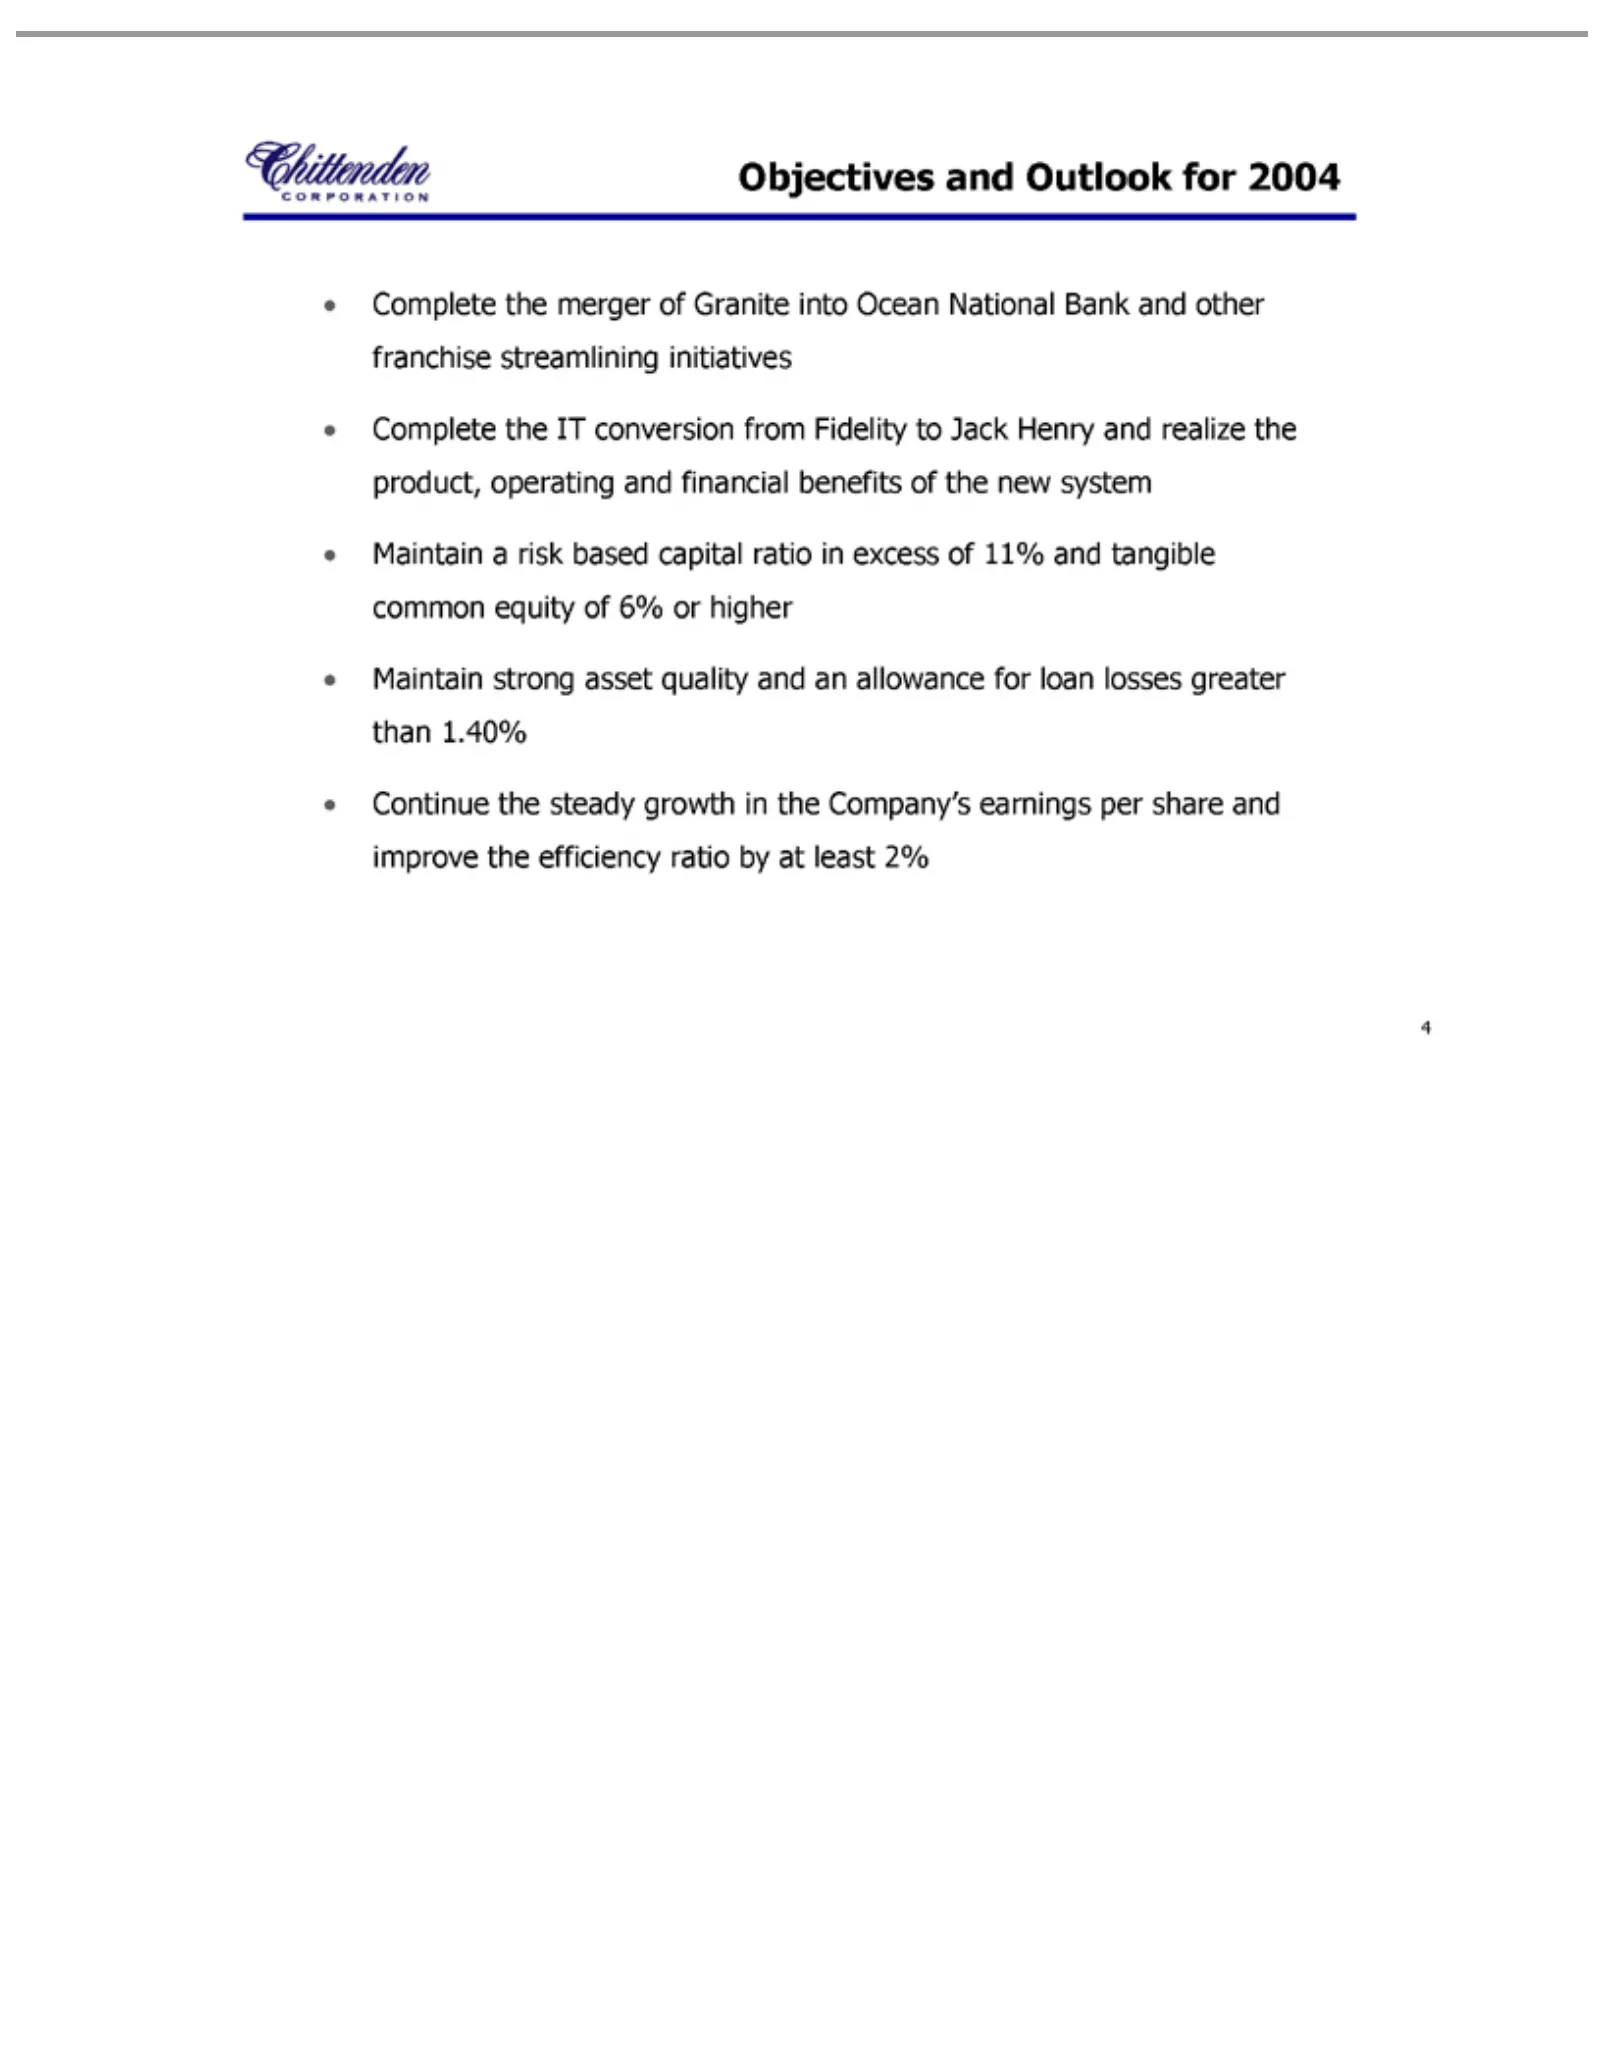
Slide 4: Objectives and Outlook for 2004
Objectivesstrong Complete Maintain Continue 4 athe the and risk steady merger IT Outlook based asset conversion growth of quality capital for Granite 2004 in from ratio and the into an Fidelity Company’s in allowance Ocean excesstoNational of Jack earnings 11% forHenry loan and Bank per losses tangi
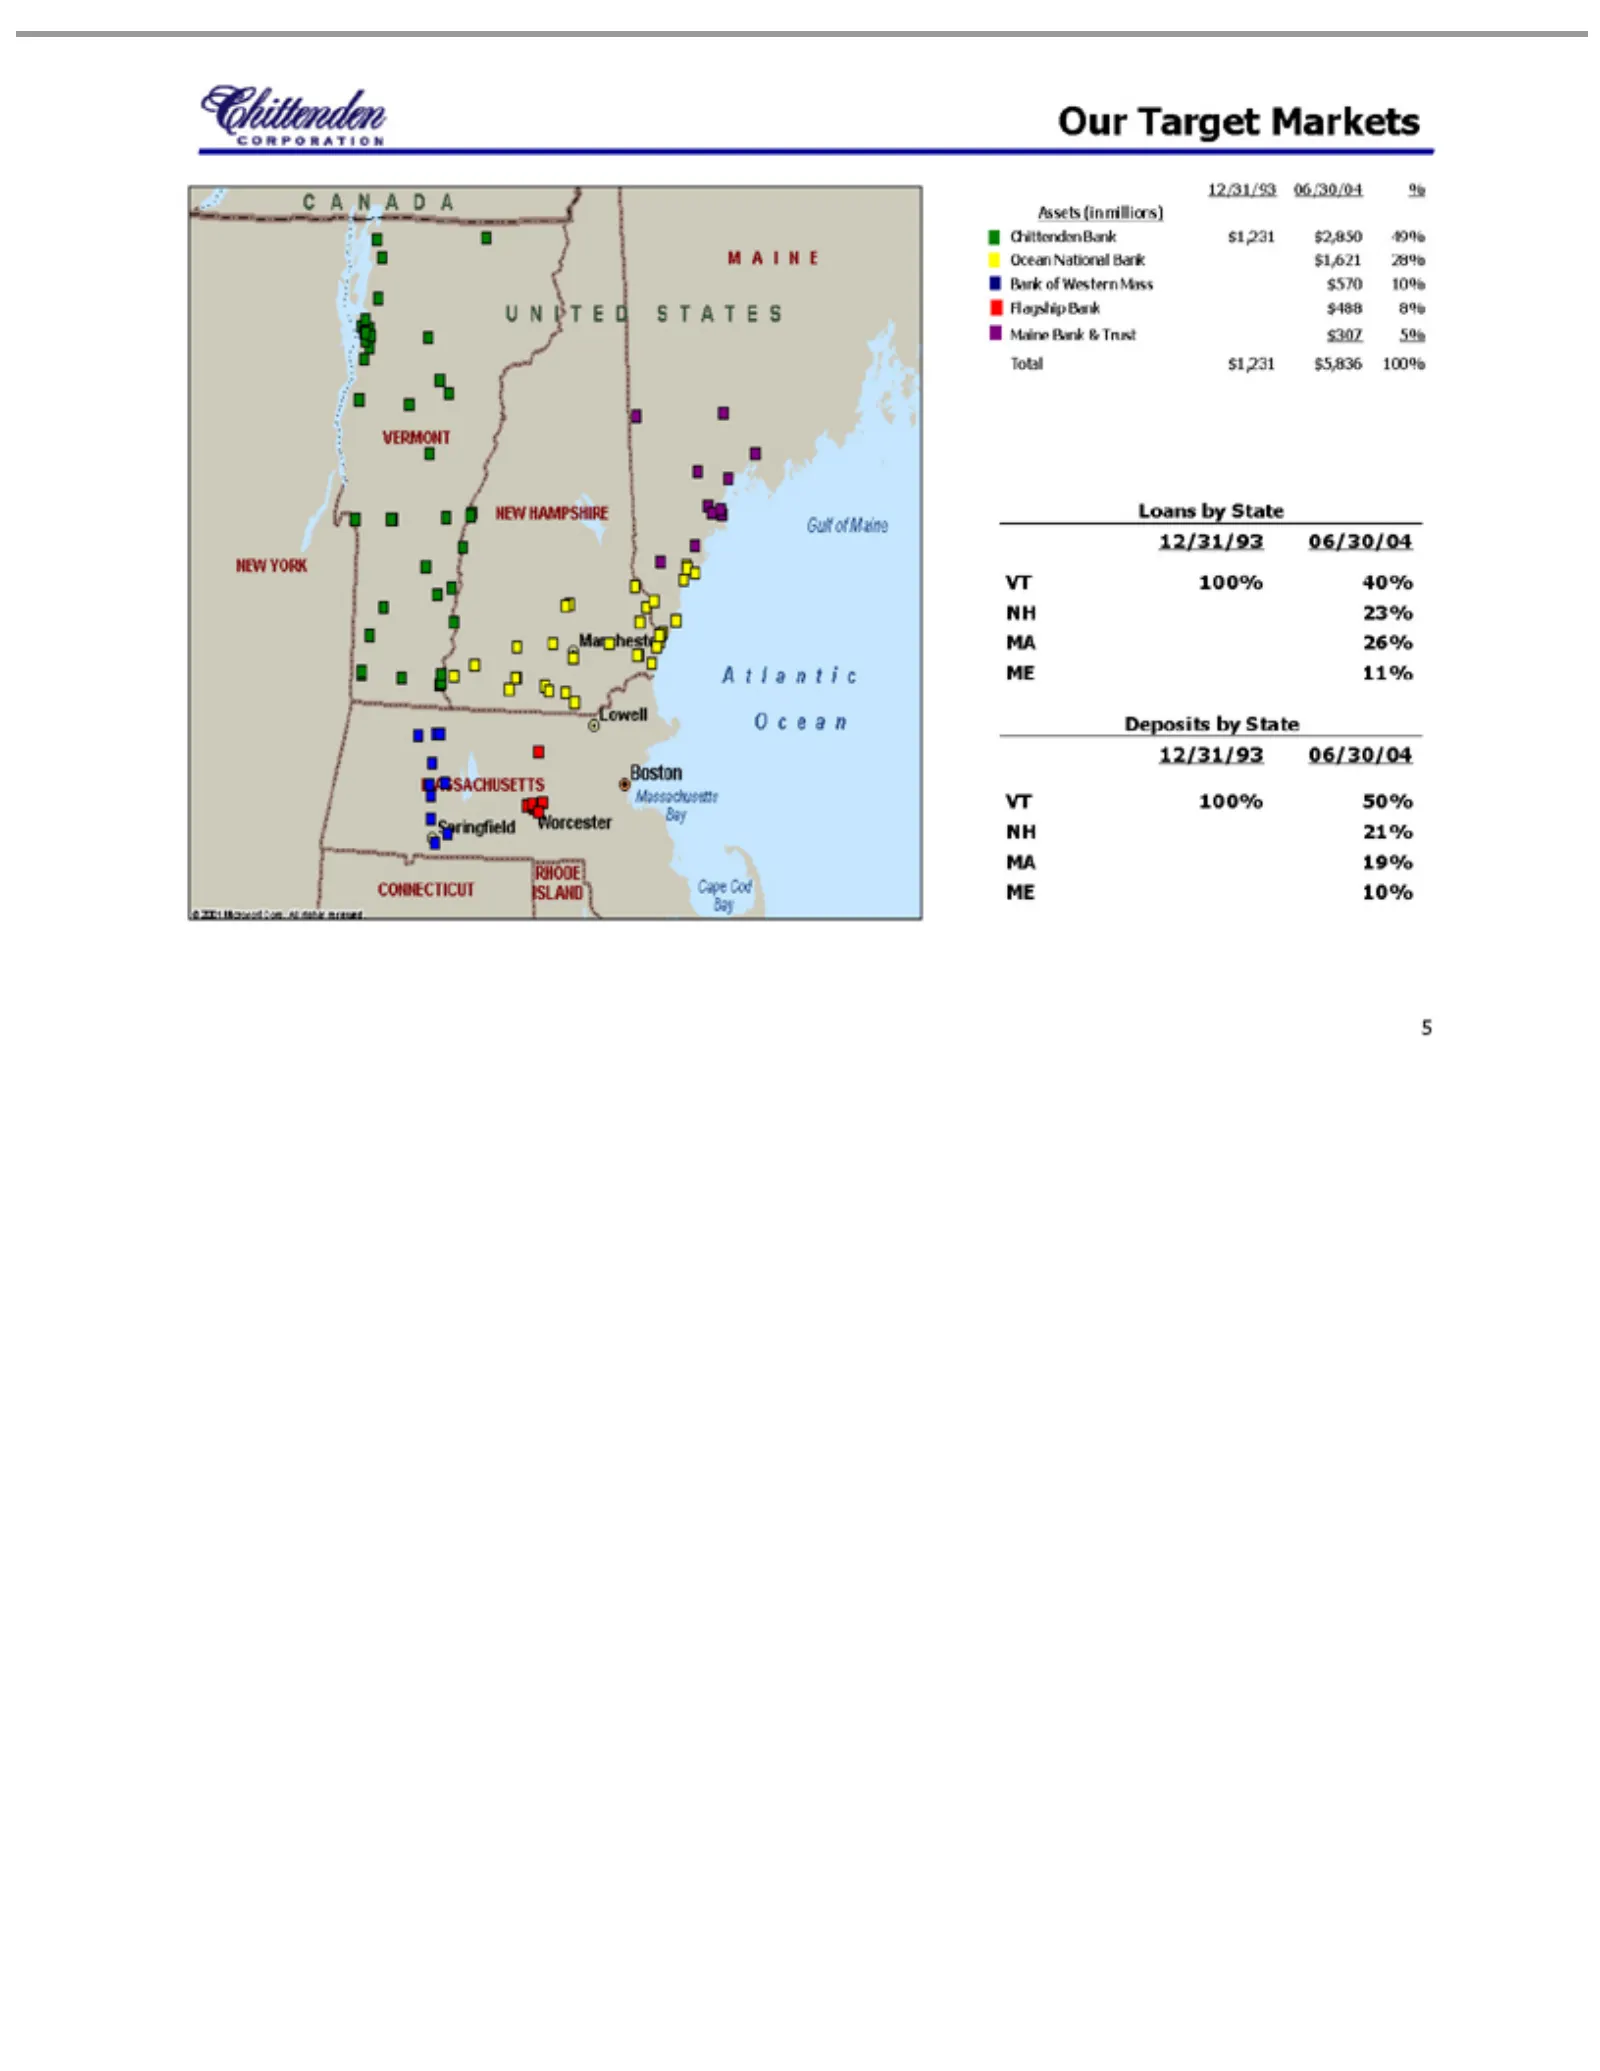
Slide 5: Our Franchise: Affiliate Banks by State
Our100% Assets Chittenden Ocean Bank Flagship Maine Total Loans Deposits 12/31/93 VT NH MA ME 5 23% 21% 11% 10% Target 26% 19% $ofby National Bank (in 1,231 Western Bank by 06/30/04 State 40% 50% millions) Markets Bank State &$$Trust 5,836 Bank 488 Mass $%1,231 $8% 100% $307 $1,621 570 $ 2,850 5%10%
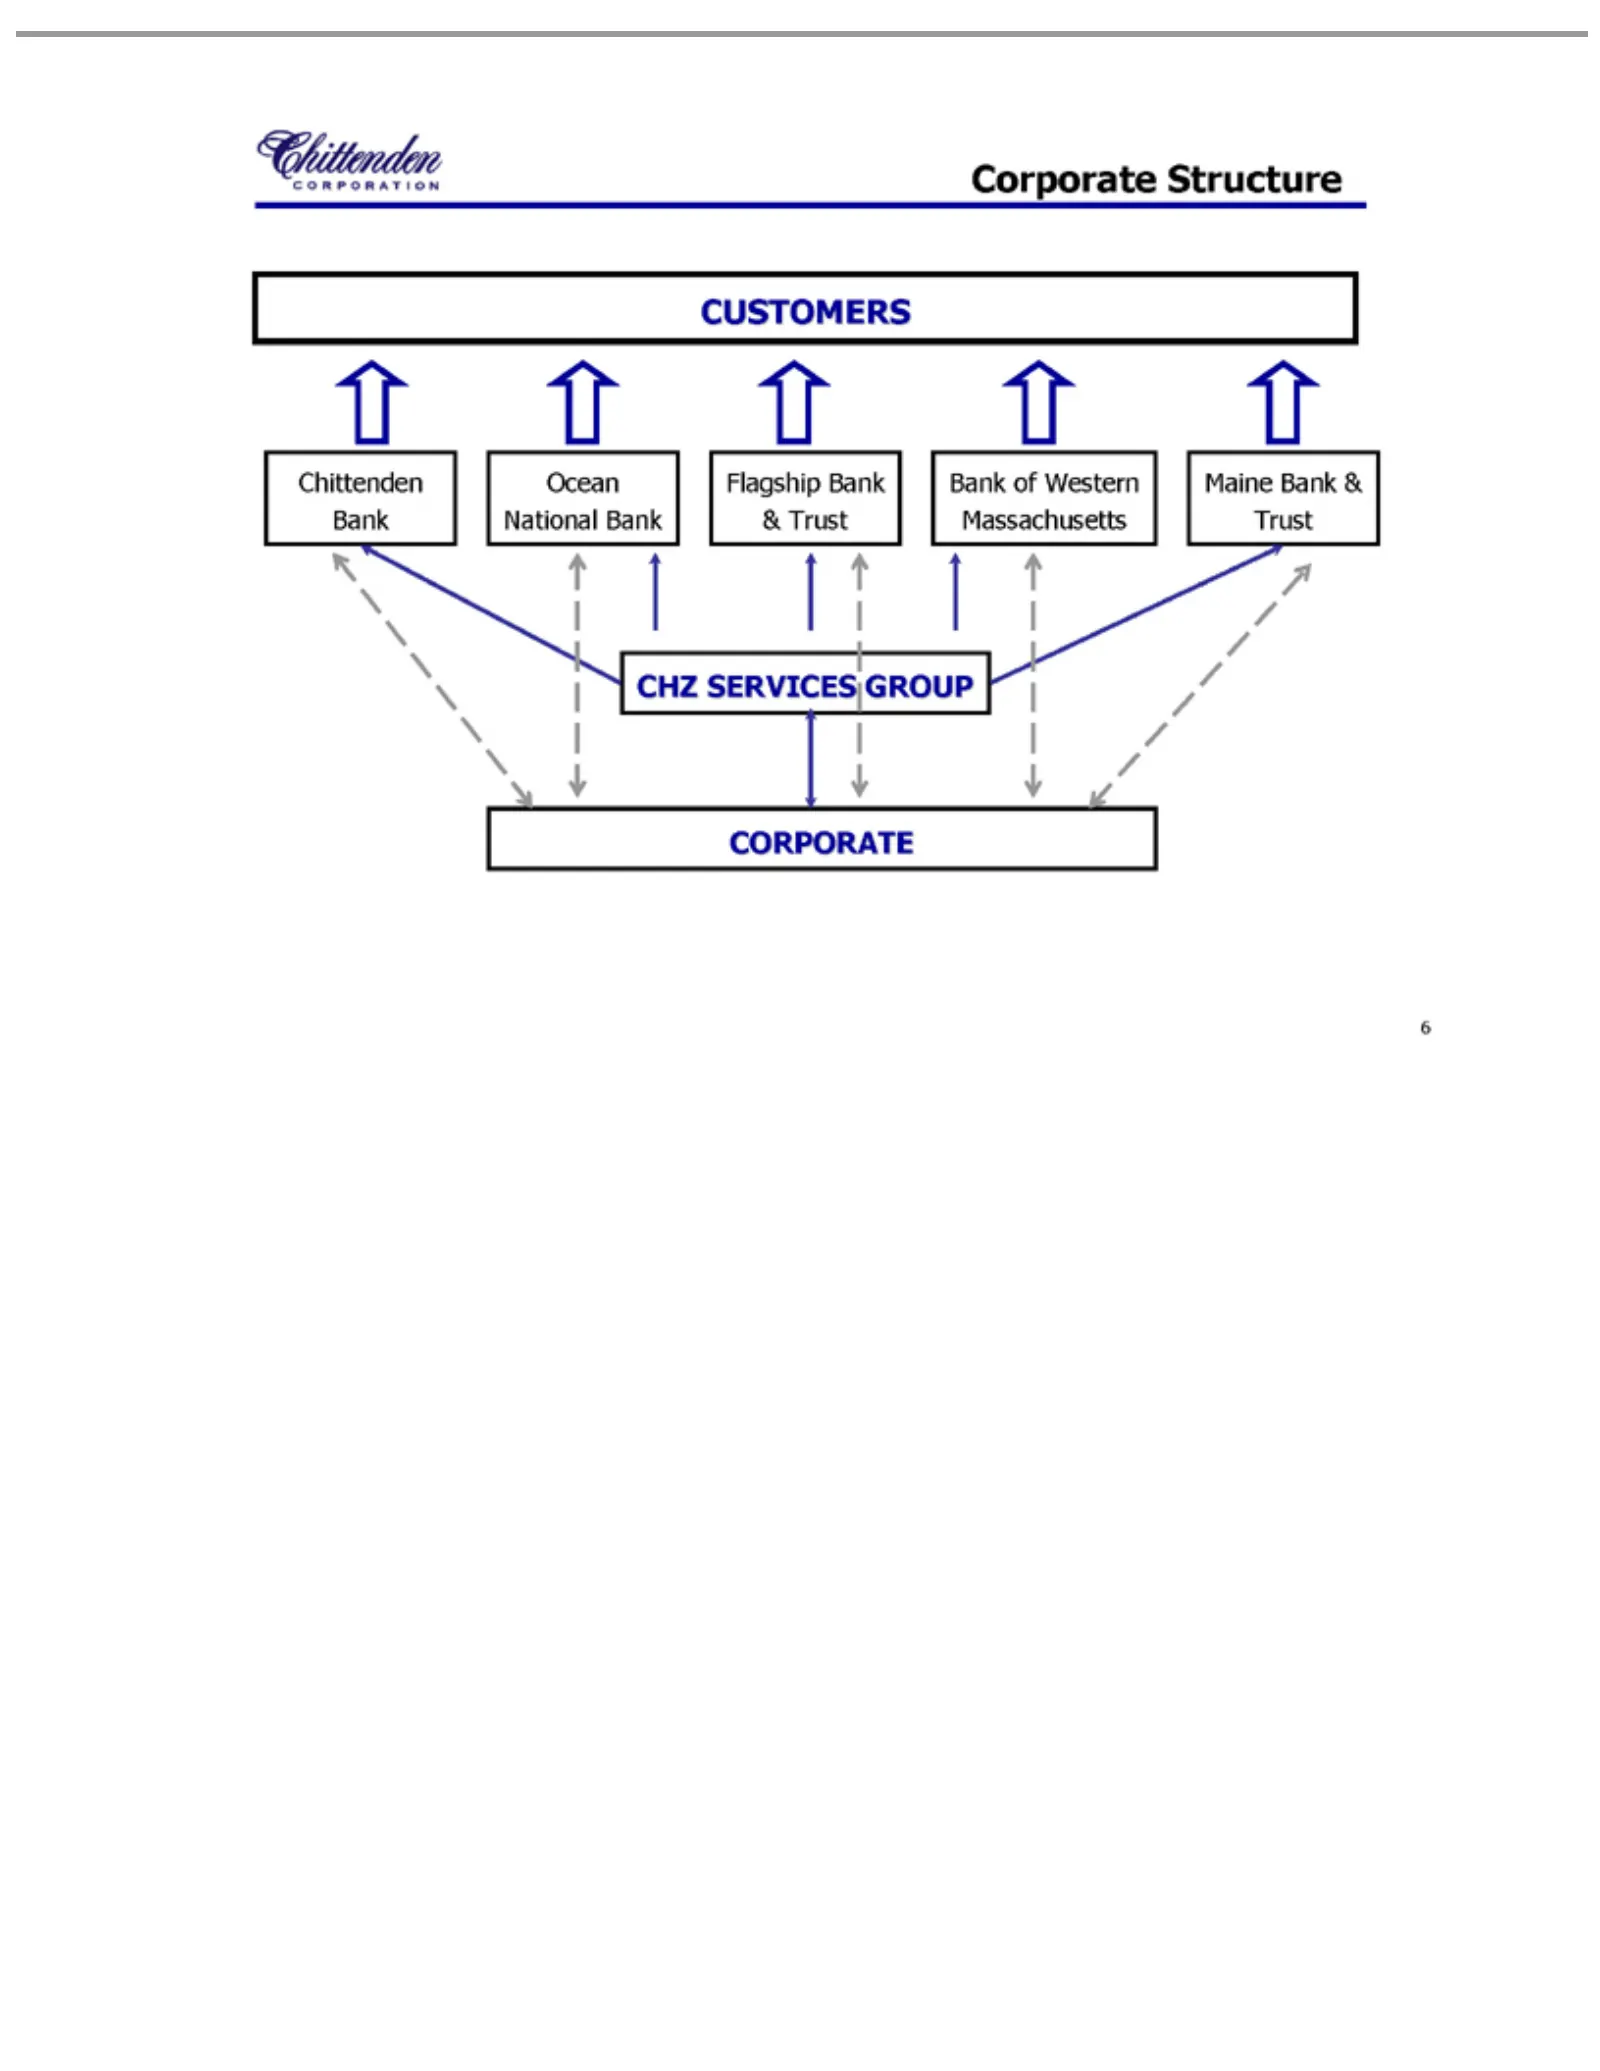
Slide 6: Corporate Structure
Corporate Chittenden CUSTOMERS CHZ 6 CORPORATE SERVICES Structure OceanGROUP Flagship Bank Bank of Western Maine Bank & Bank National Bank & Trust Massachusetts Trust
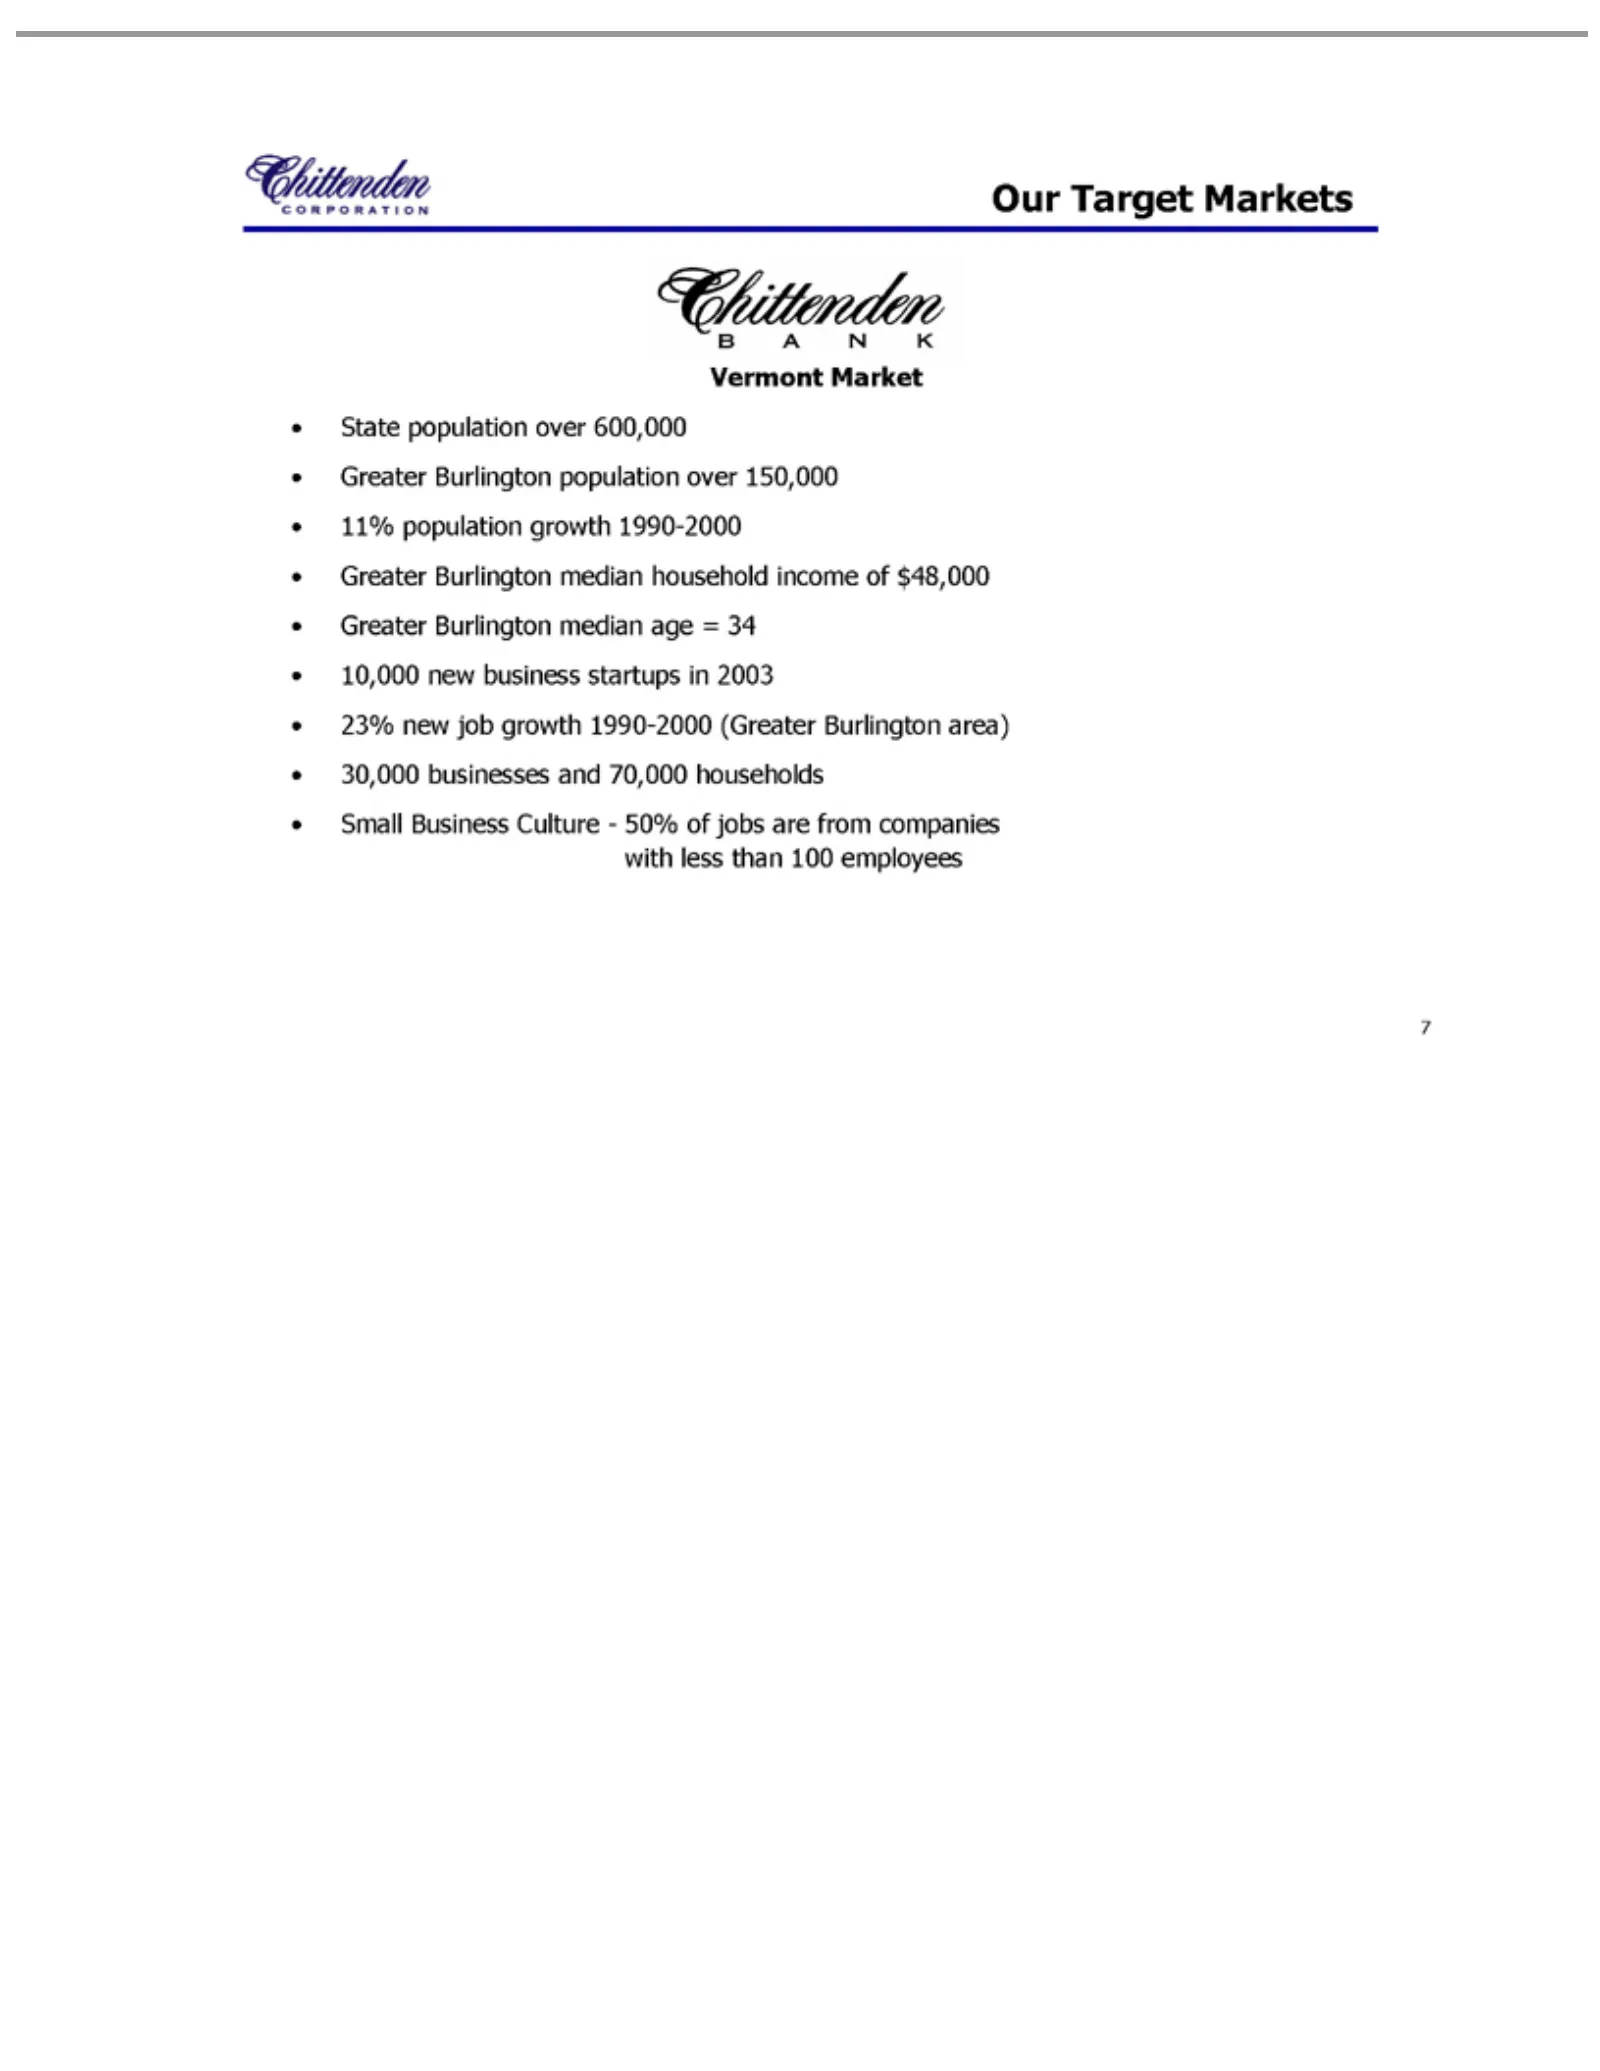
Slide 7: Our Target Markets: Vermont
Our Target Vermont State 11% Greater 10,000 23% 30,000 Small 7 population new population Business new businesses Burlington Market job Markets business growth Culture—50% growth over and population median startups 1990-2000 600,000 70,000 1990-2000 household agein households over of =2003 (Greater 3
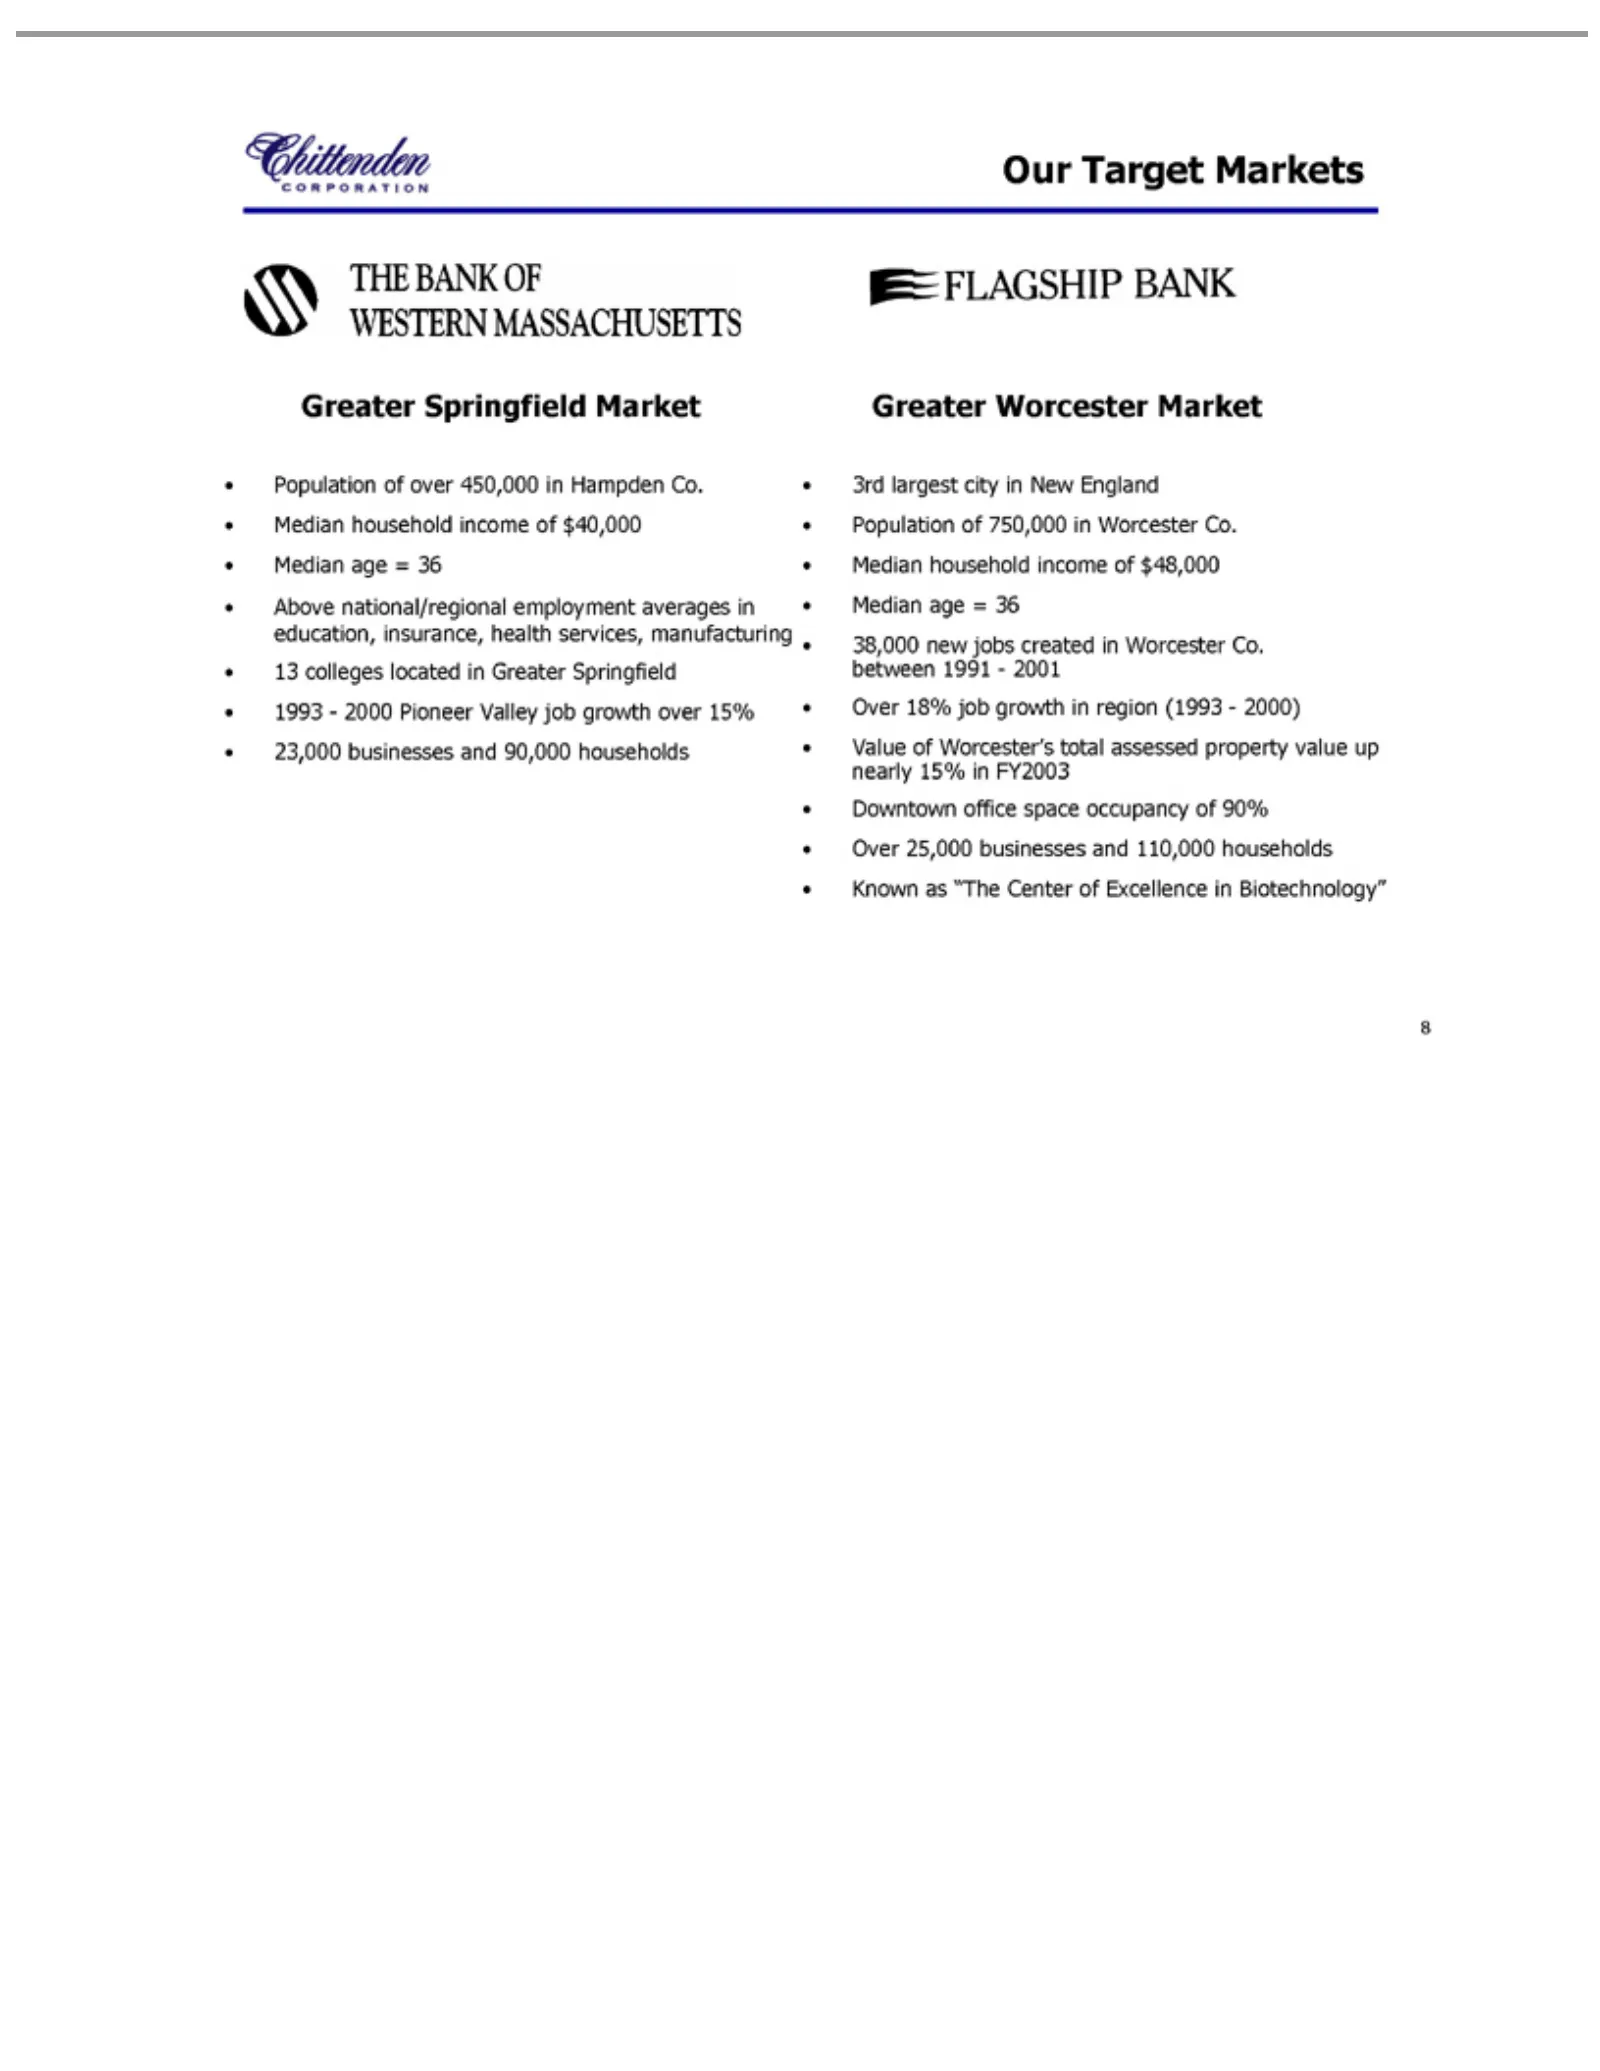
Slide 8: Our Target Markets: Massachusetts
Ourlargest Population manufacturing Greater 3rd 18% Value Excellence 8 Target job ofWorcester Springfield Worcester’s growth city Markets of in Biotechnology” over 13 ininNew colleges Market 450,000 region Market total England (1993—2000) assessed located in Hampden Population in property Greater Co
Slide 9: Our Target Markets: New Hampshire and Maine
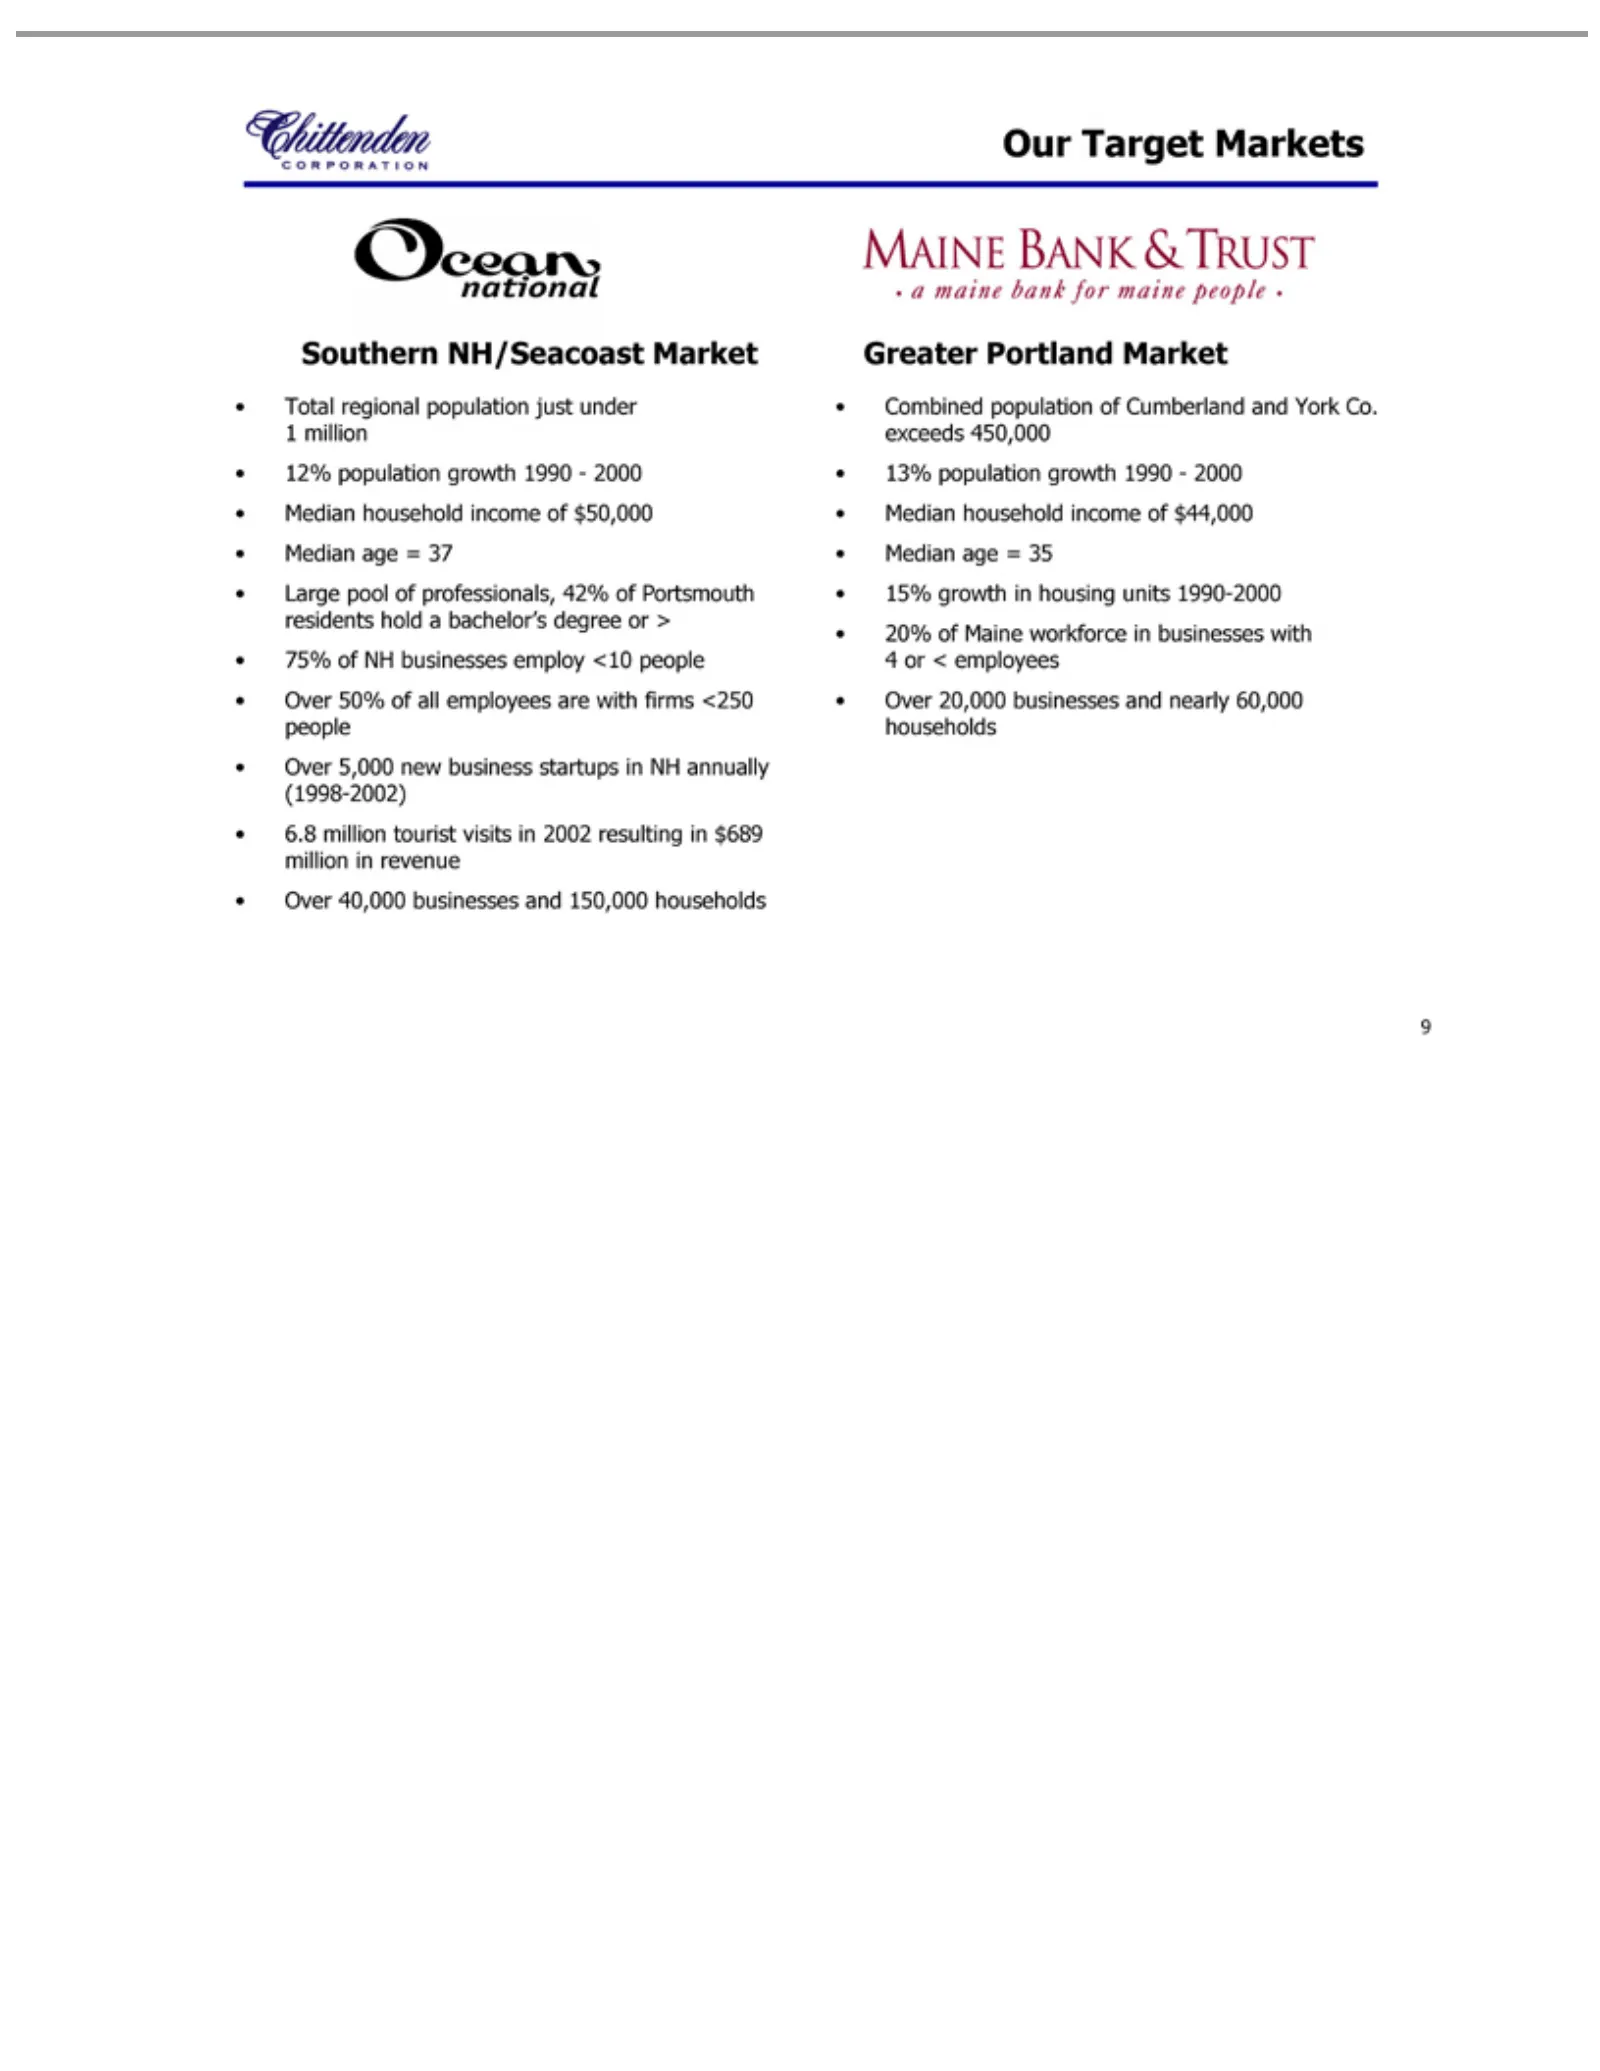
Our Target Southern Total Large new Greater Combined 2000 9 business 20% regional pool Portland NH/Seacoast of population Markets ofMaine startups professionals, population Market workforce in ofMarket NH Cumberland just42% annually under in of businesses 1Portsmouth and million (1998-2002) York wit
Slide 10: Our Target Customers
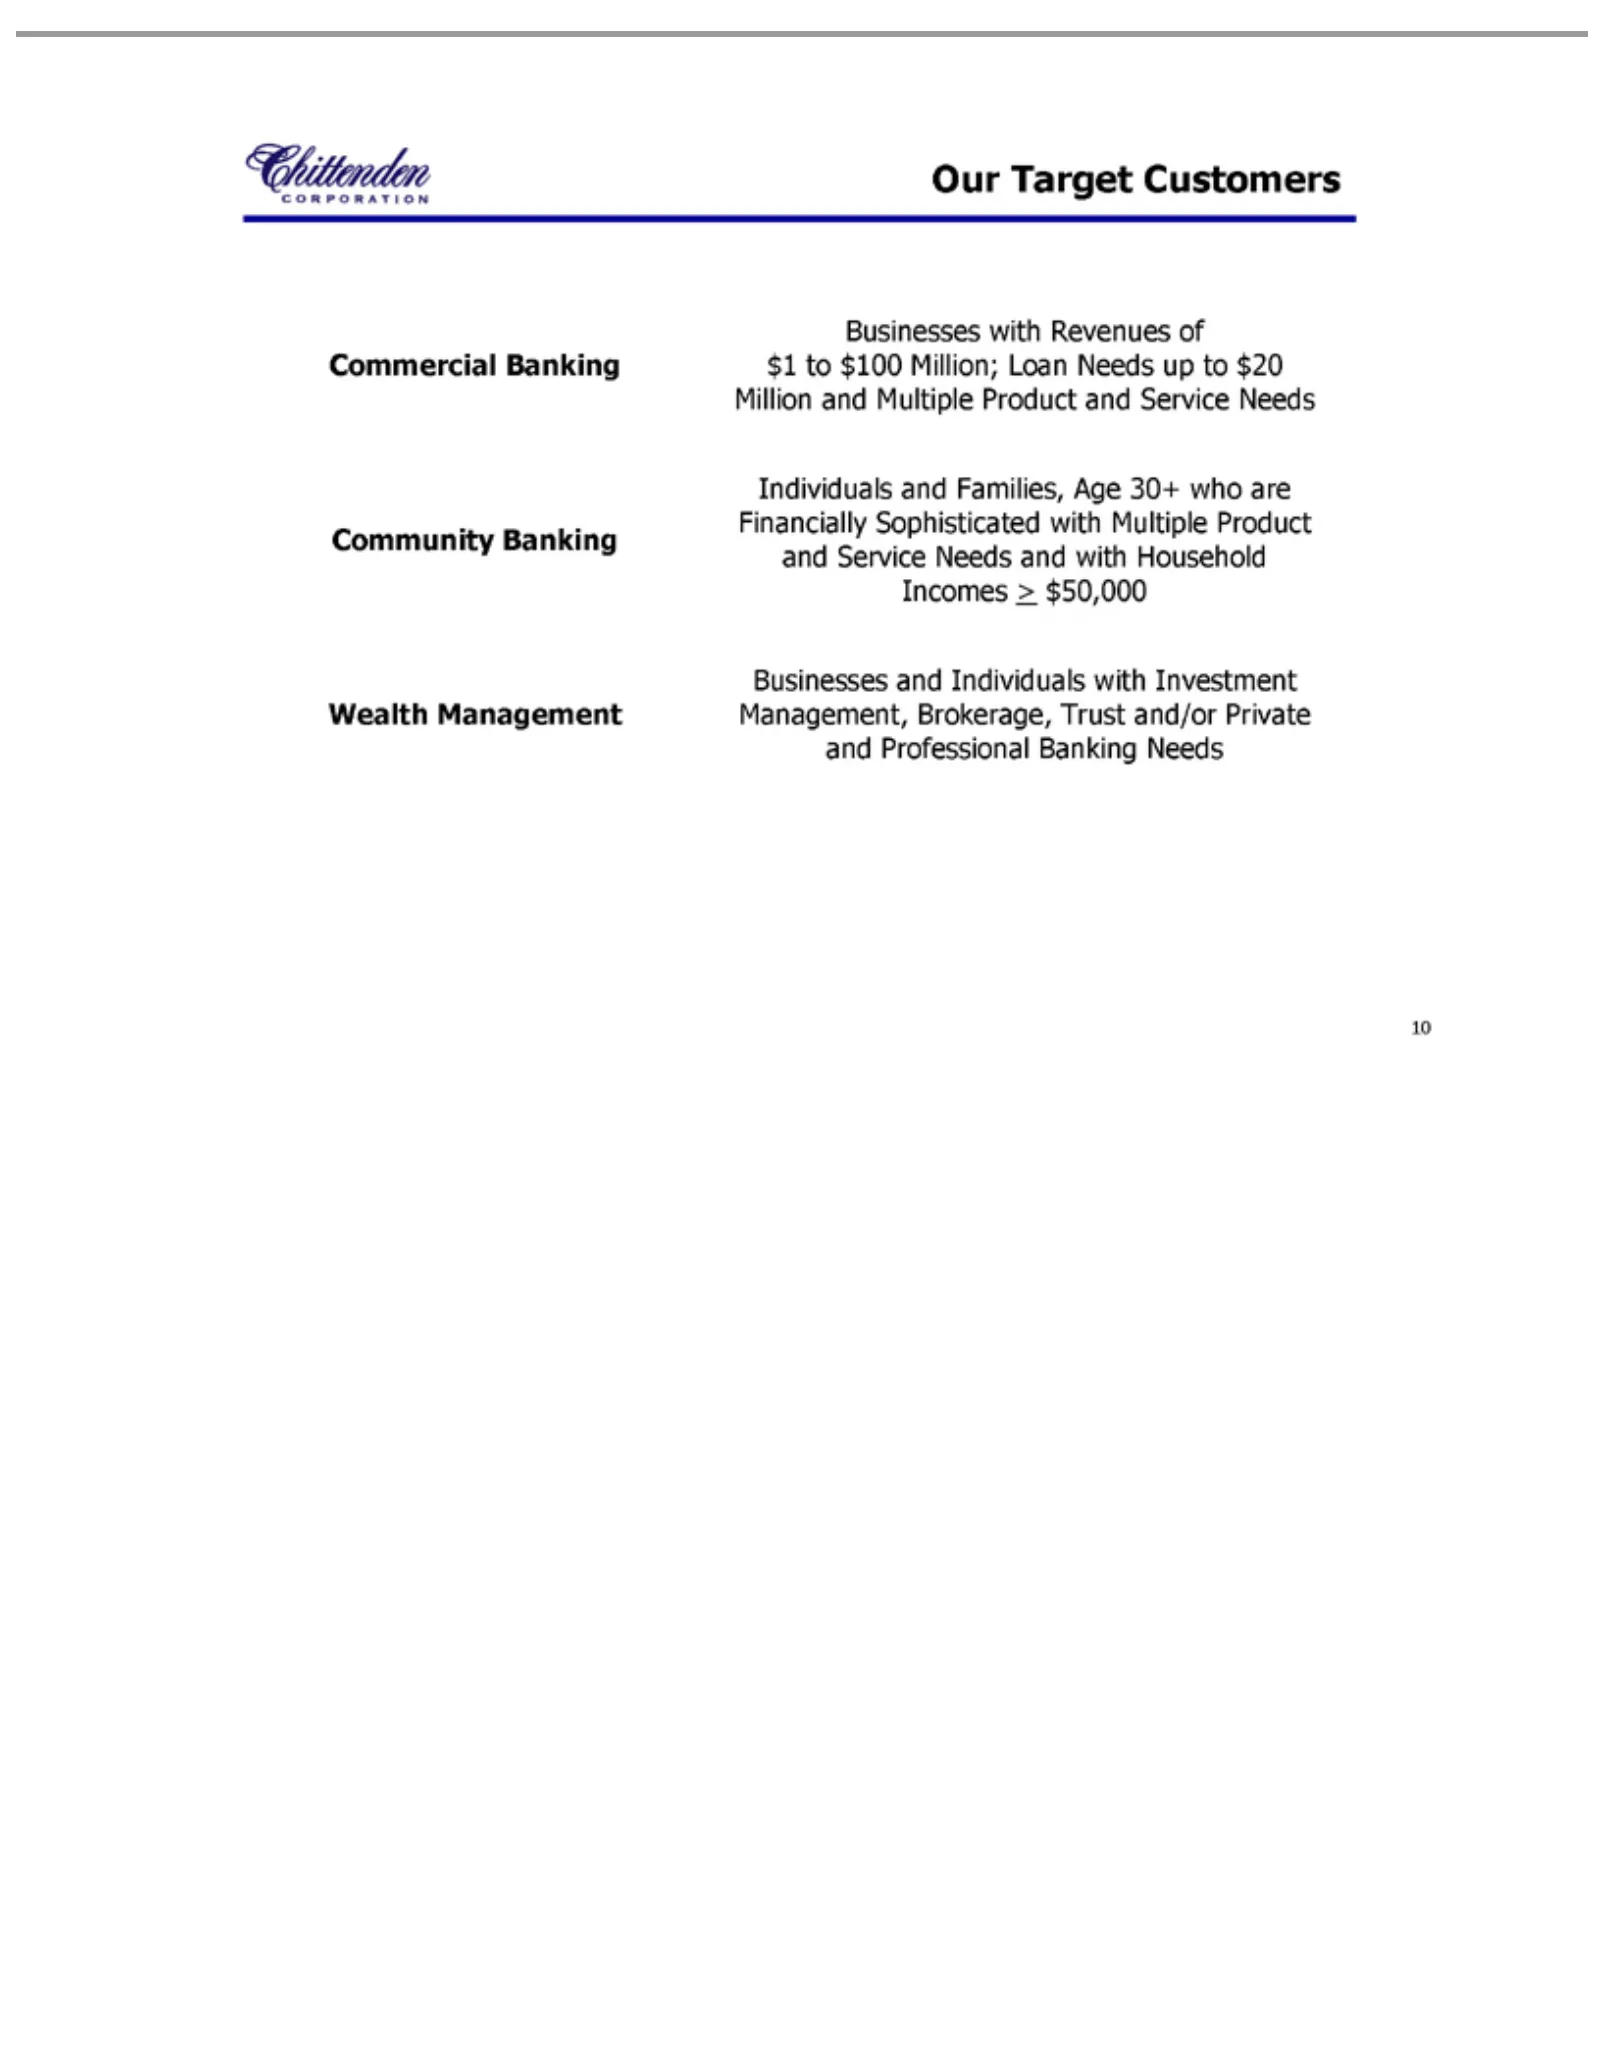
Our Target Customers Individuals Community Businesses 10 with and and Banking Individuals Families, Revenues and Age Service of with Commercial 30+ Investment Needs who are and Banking Financially Wealth with Household $1 Management toSophisticated $100Incomes Million; Management, with ³ Loan $50,00
Slide 11: Commercial & Community Banking
Commercial & Community Banking 11
Slide 12: A Diversified Loan Portfolio
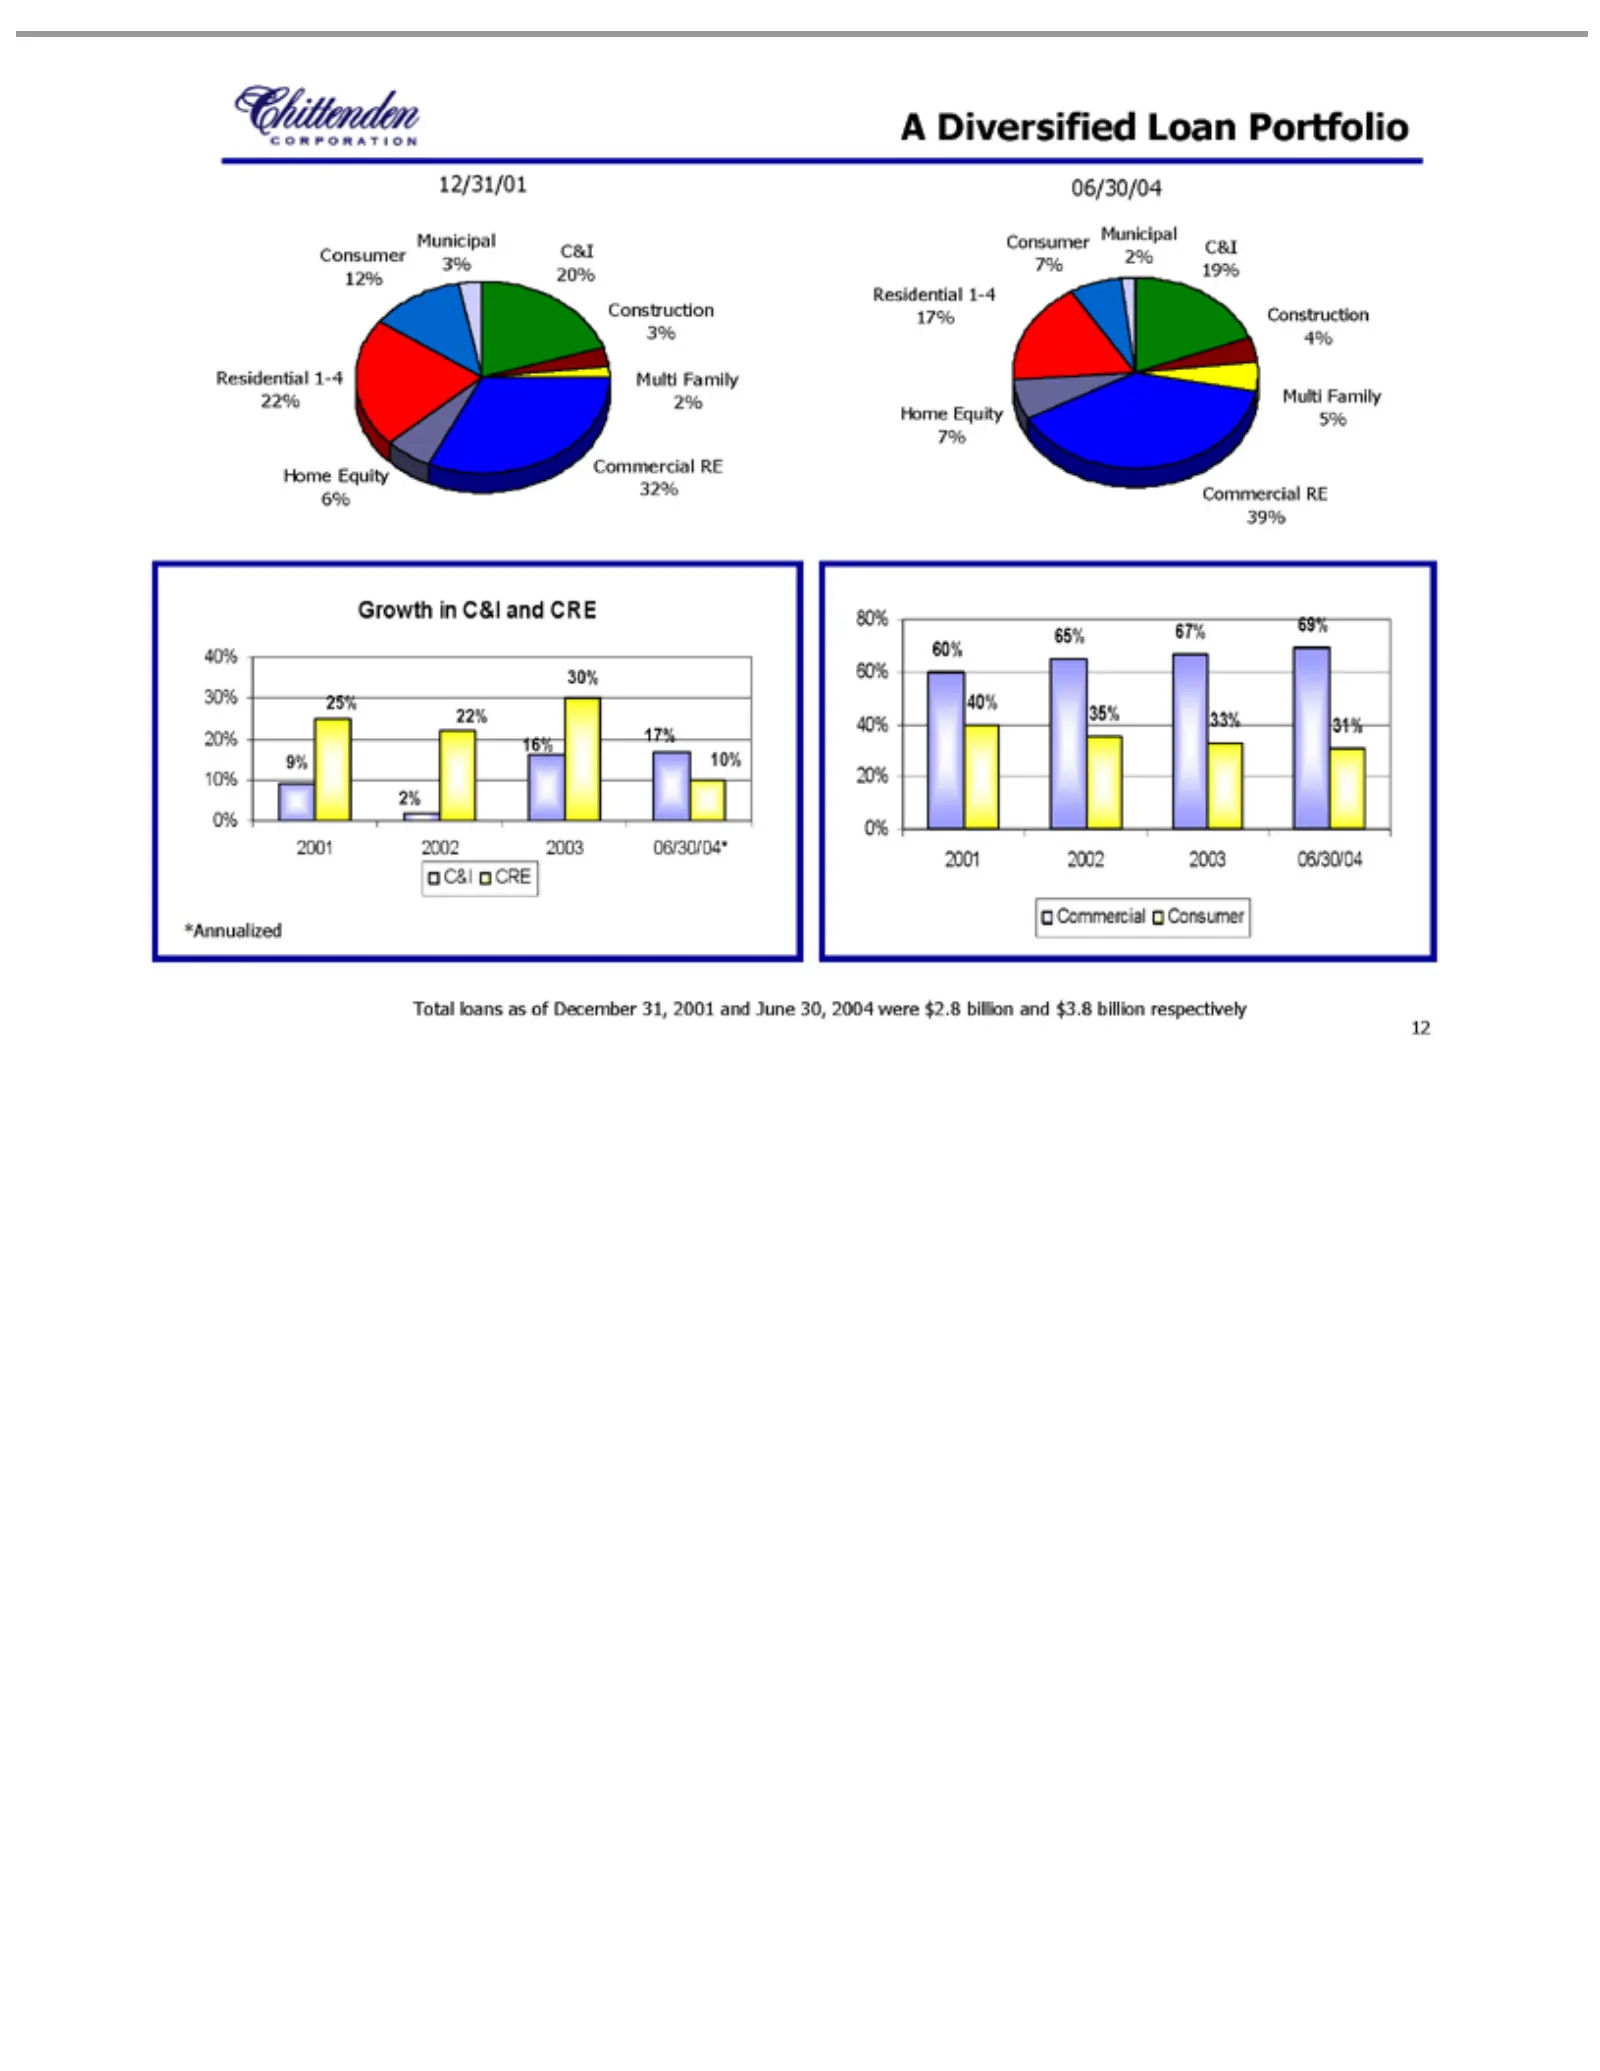
A Diversified 12/31/01 32% Municipal C&I Construction Multi Home 39% Residential Consumer Growth 10% 17% 30% 16% 22% 2% 25% 9% 80% *Annualized 2001 31% 69% 33% 67% 35% 65% 40% 60% Commercial Total 12 20% 19% 30% 60% 2002 loans Family Equity in06/30/04 20% 40% C&I 3% 2% 12% 7% 2003 as 1-4 RE Consumer
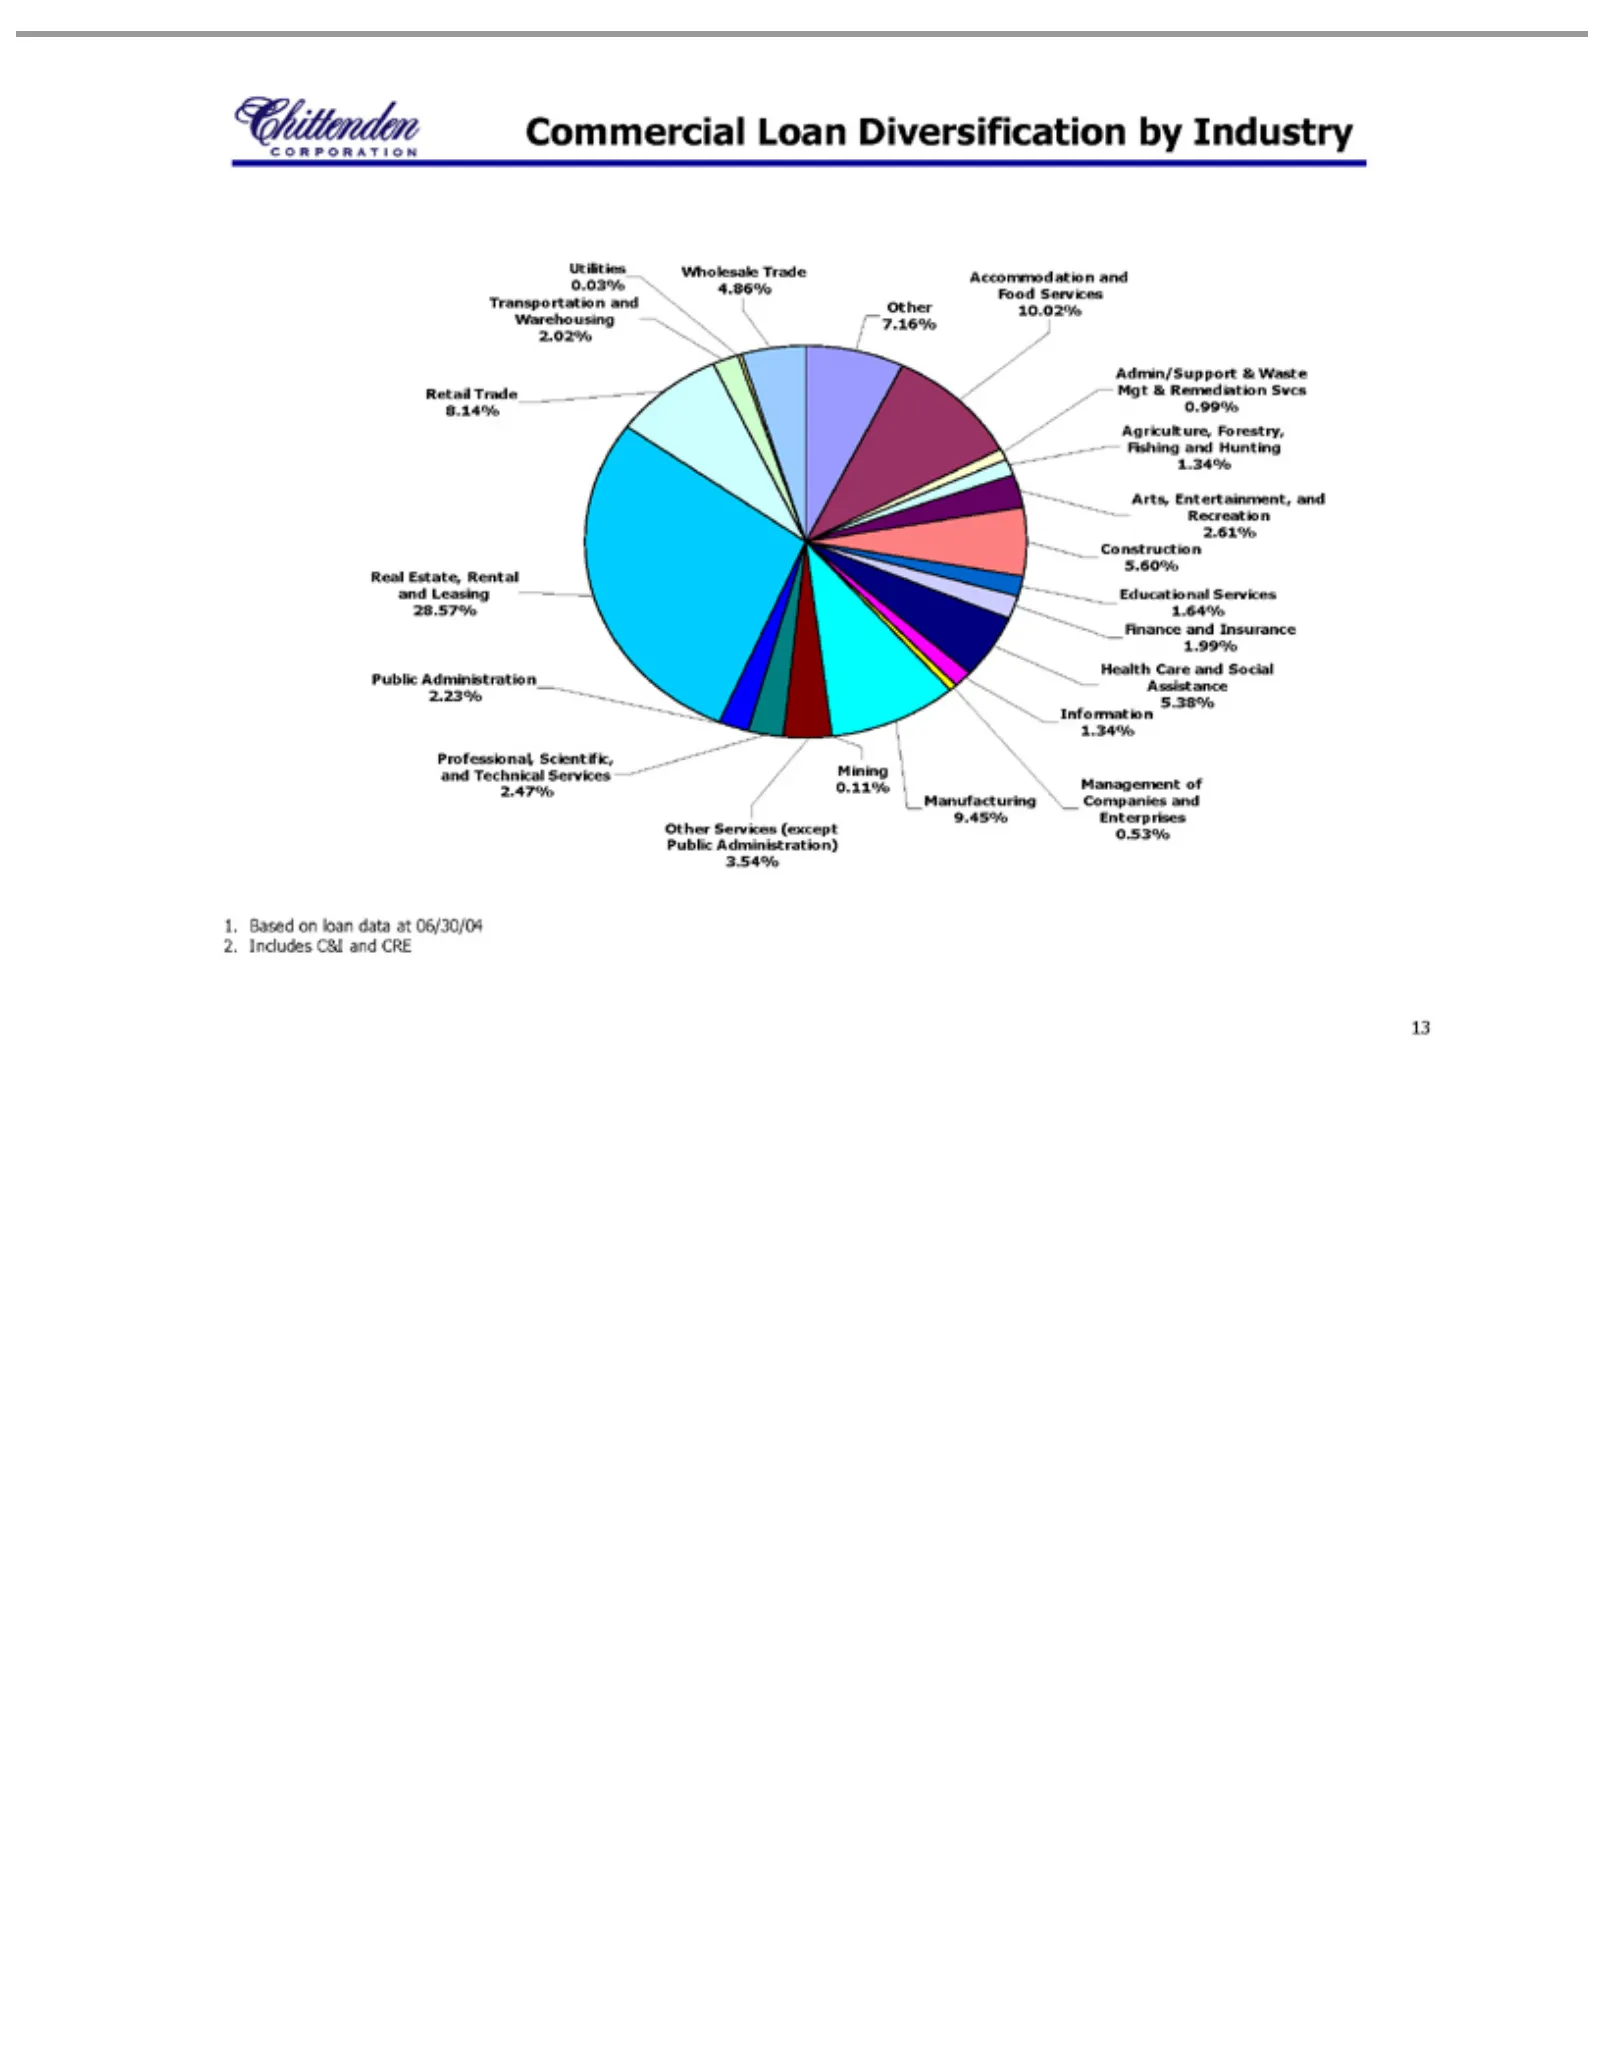
Slide 13: Commercial Loan Diversification by Industry
Commercial Utilities Wholesale Accommodation Admin/Support Arts, Construction Educational Health Management Manufacturing Mining Other Professional, Public Real Retail 1. 2. 13 Based Includes Estate, Entertainment, 7.16% Services Trade Administration Care 0.11% 0.03% onTrade C&I loan Services Rental
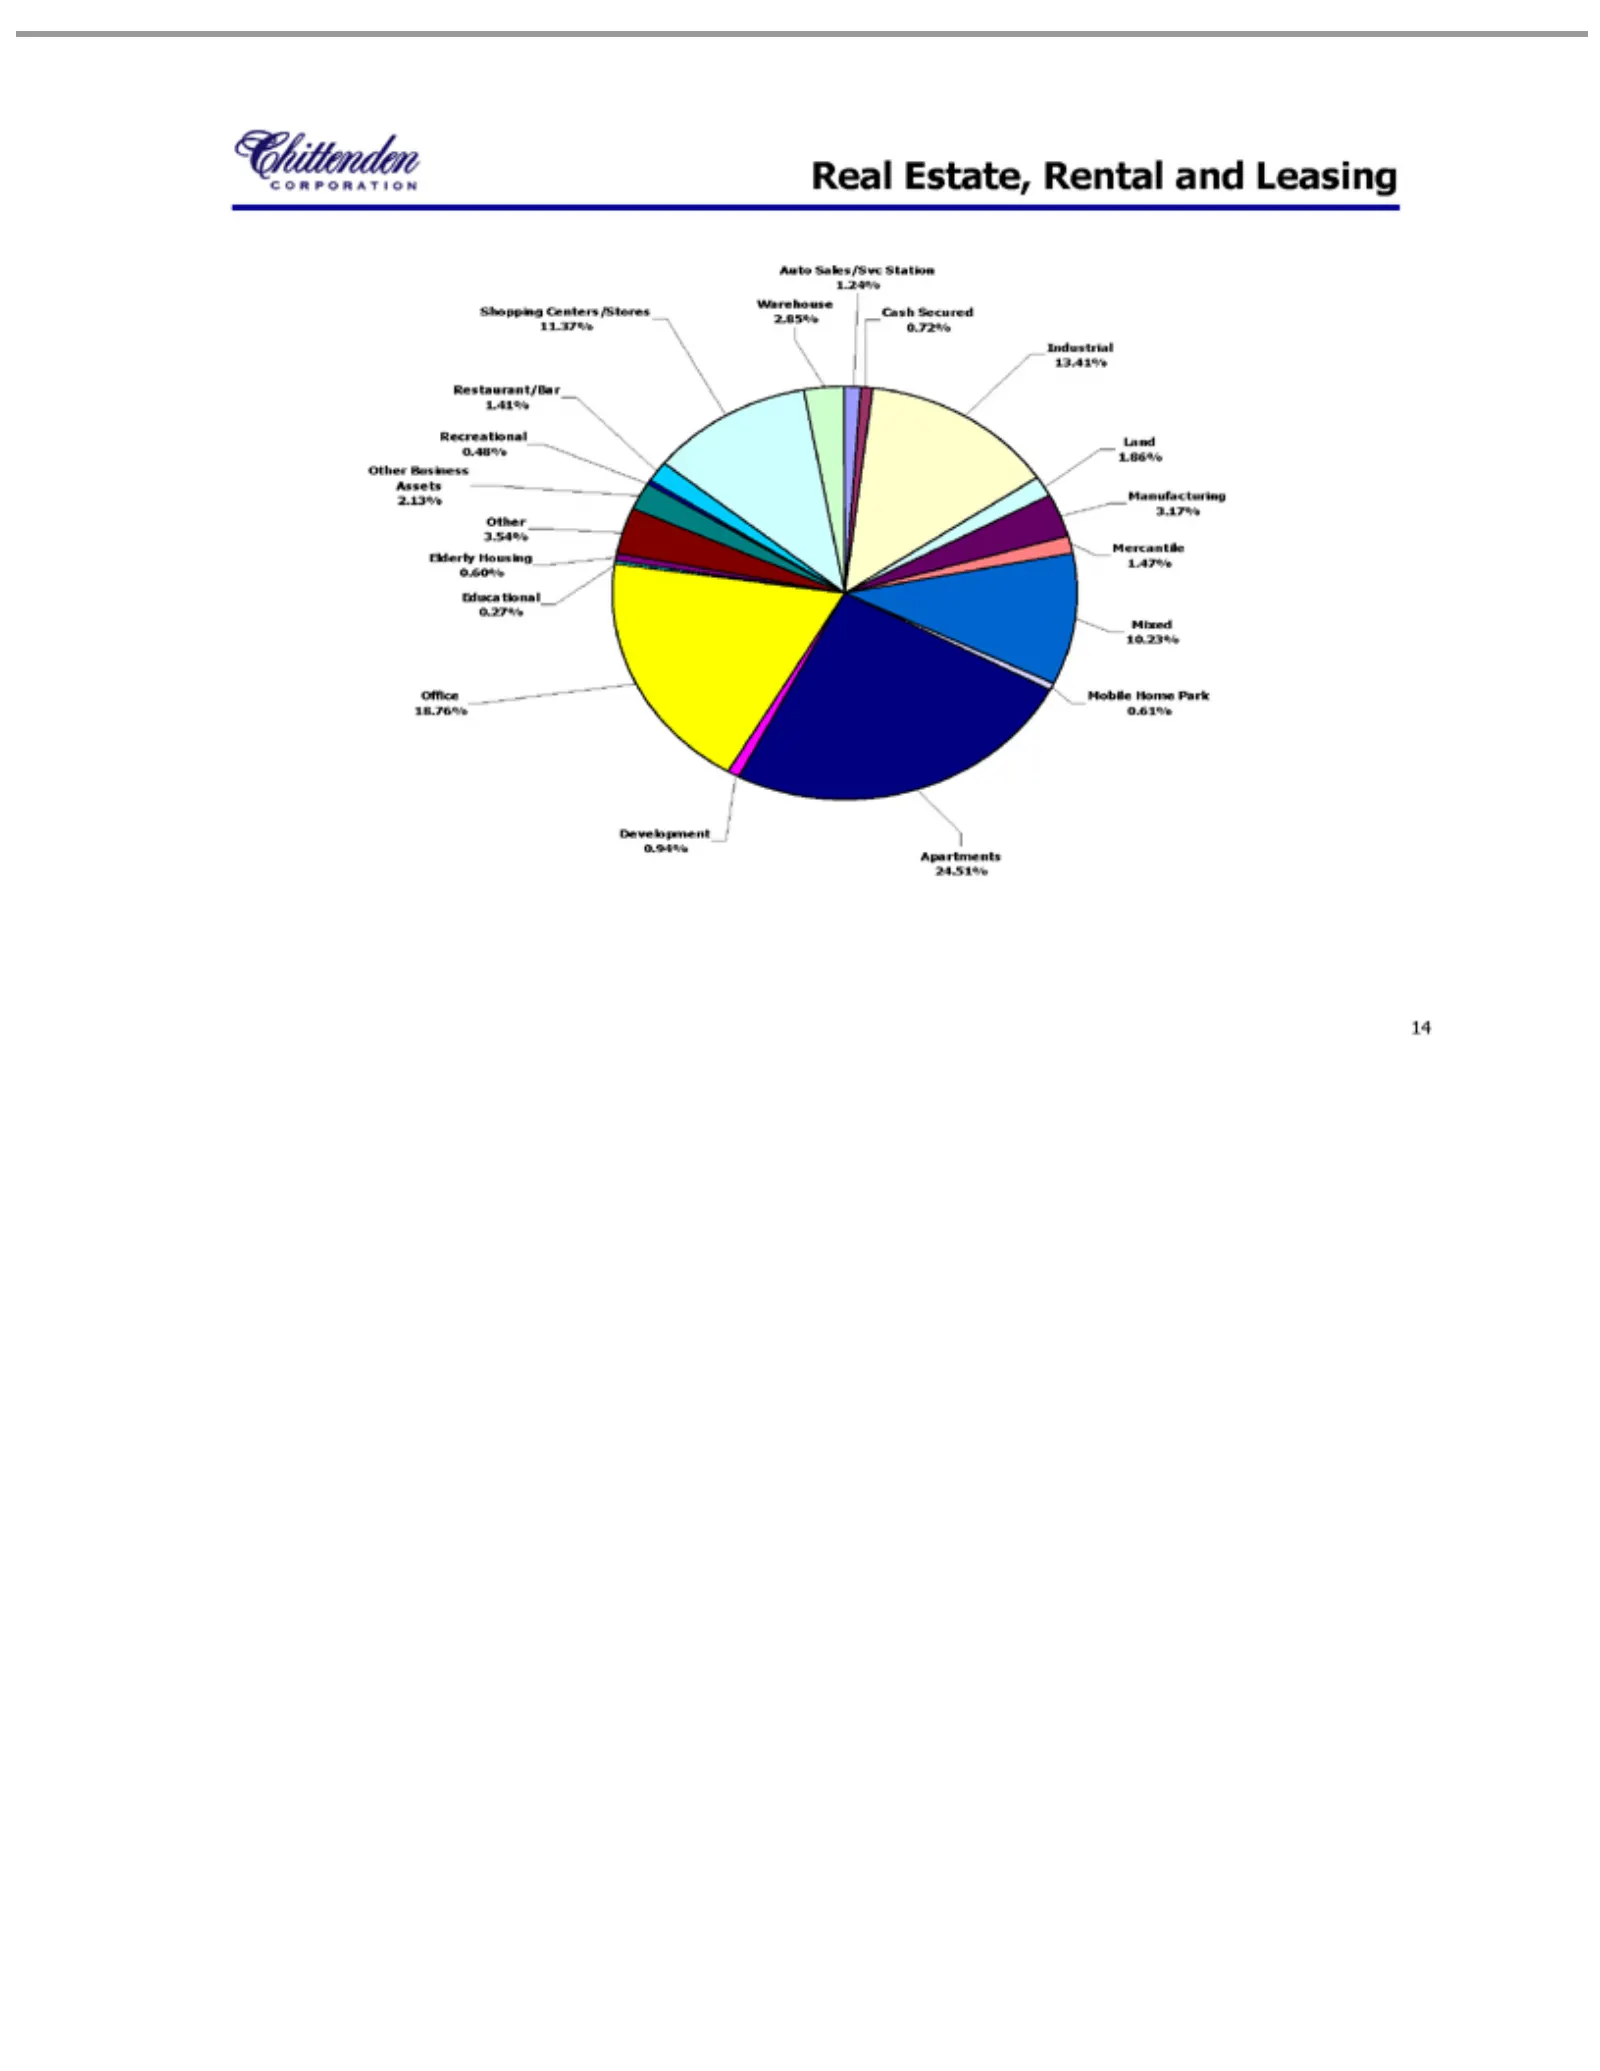
Slide 14: Commercial Real Estate Loan Breakdown
Real Estate, Auto Cash Industrial Land Manufacturing Mercantile Mixed Mobile Apartments Development Office Educational Other Recreational Restaurant/Bar Shopping Warehouse 14 Sales/Svc Secured 1.86% 3.54% Business 18.76% 10.23% Home 13.41% Centers/Stores 1.47% 2.85% 24.51% 0.27% Rental 0.48% Elderly
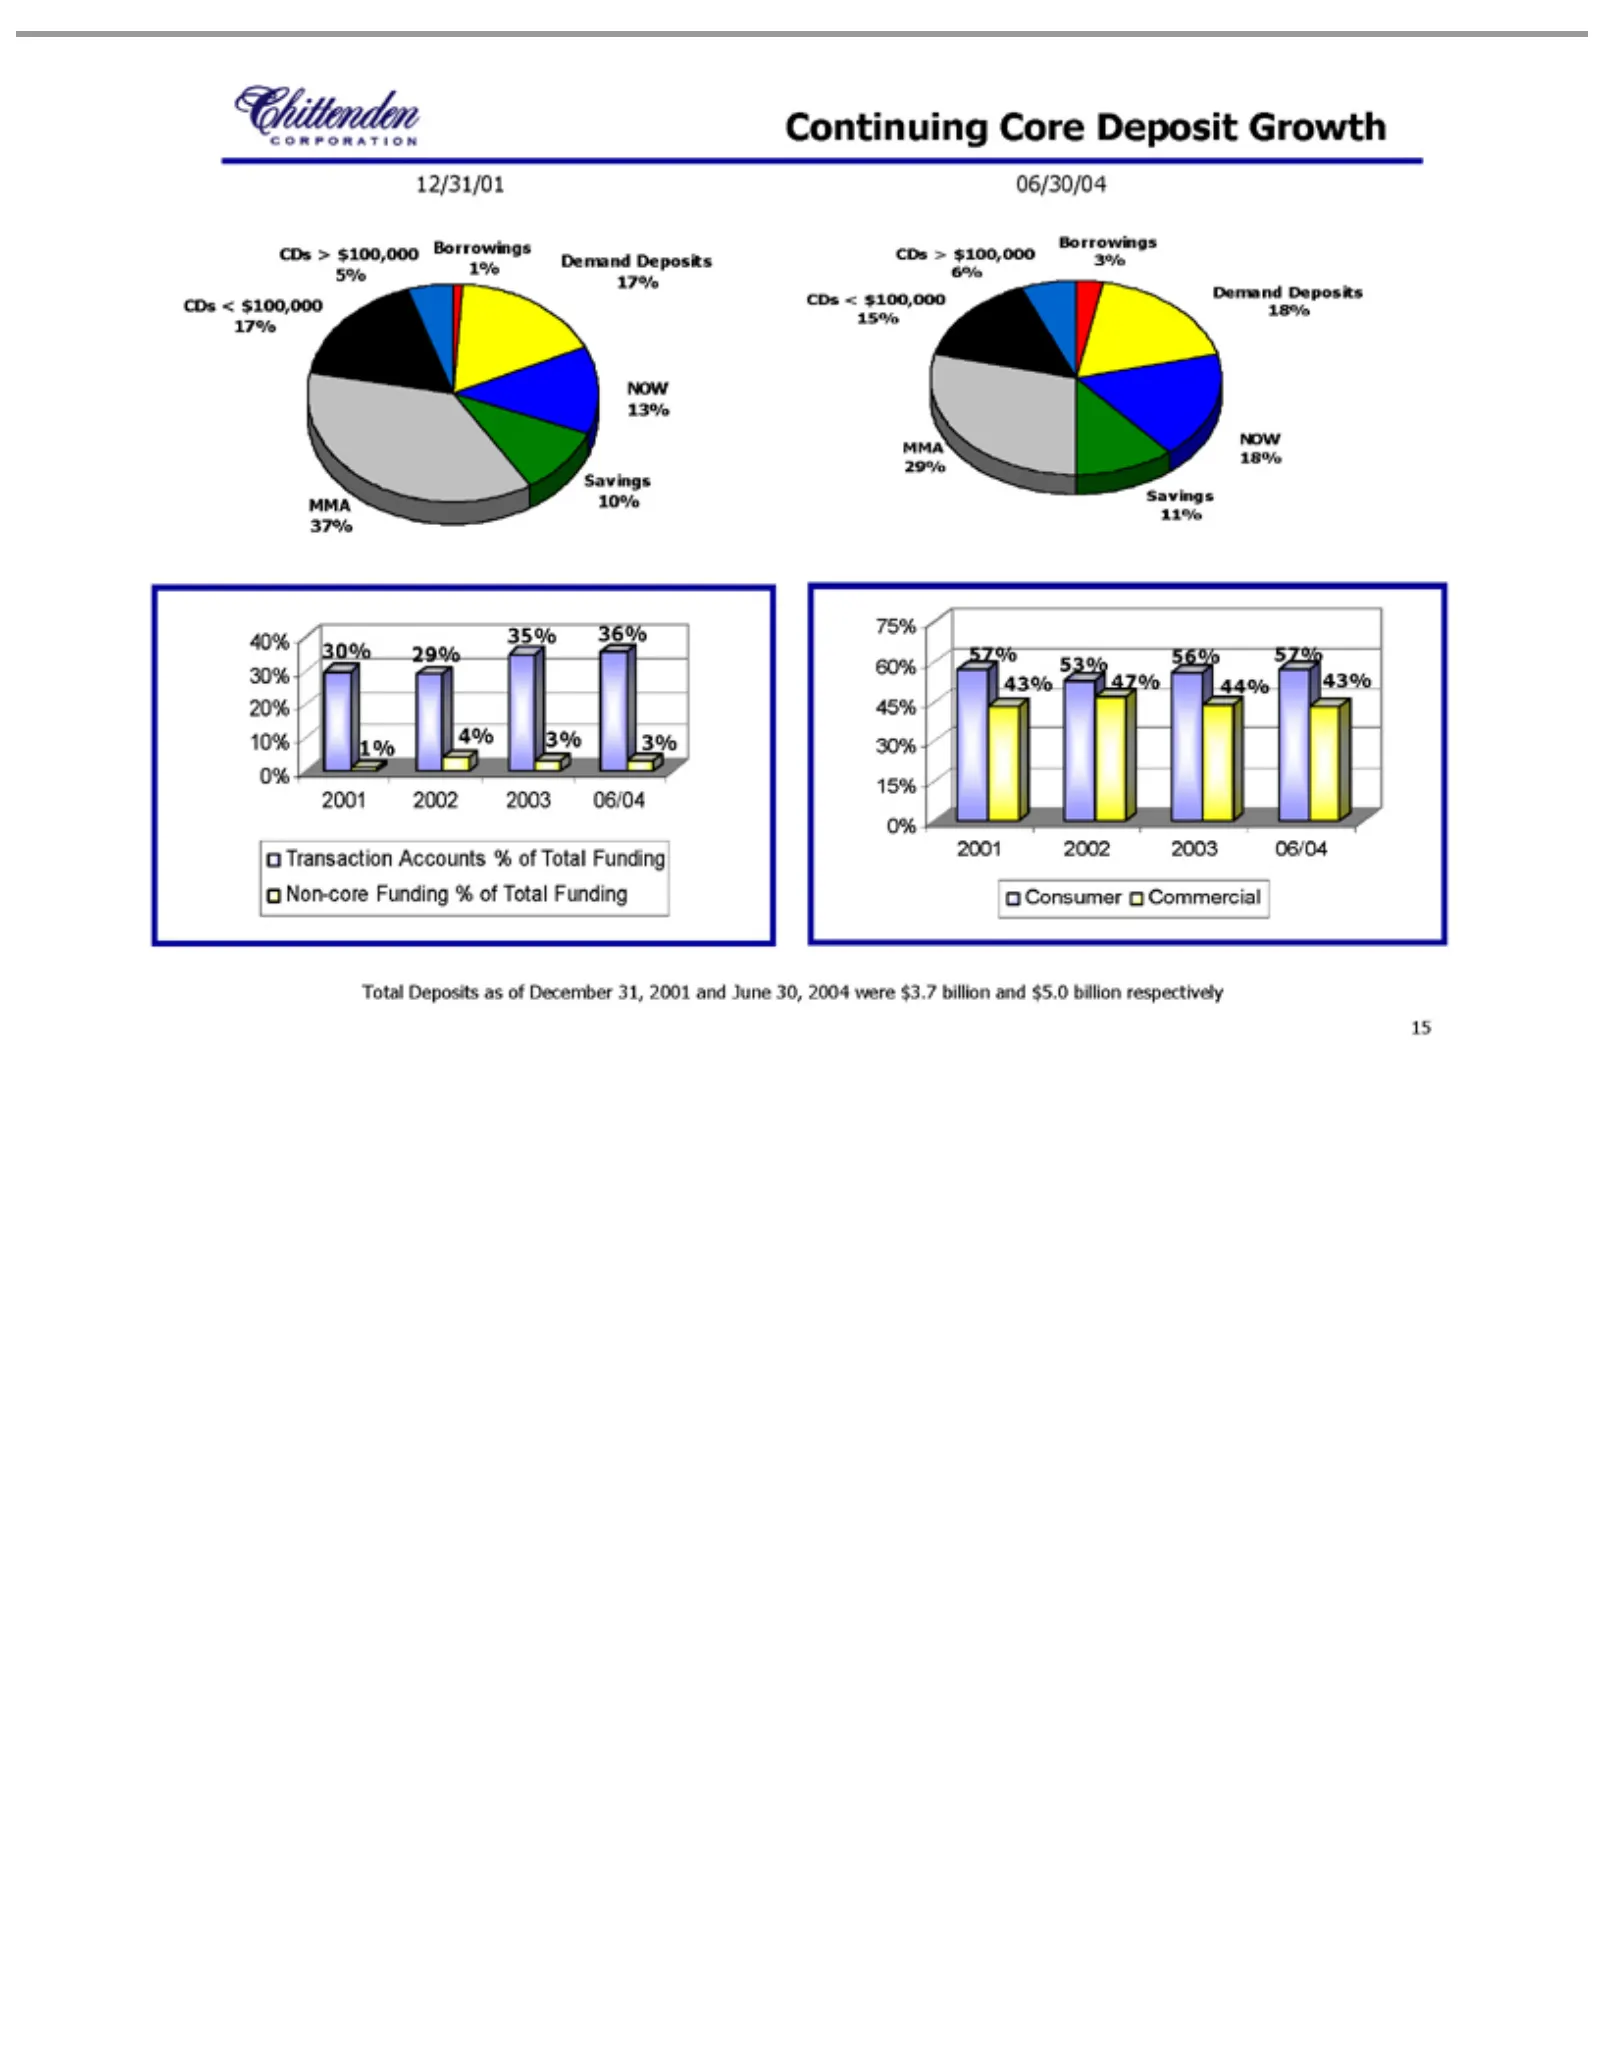
Slide 15: Continuing Deposit Growth
Continuing 12/31/01 Borrowings Demand NOW Savings MMA CDs 40% 36% 3% 35% 4% 29% 1% 30% Transaction 75% 2001 44% 56% 47% 53% 43% 57% Total Commercial Consumer 15 < >30% 60% 2002 Deposits 13% 18% 37% 29% $100,000 10% 11% Deposits 06/30/04 20% 45% 2003 Core Accounts 1%as 3% 10% 30% 06/04 17% 5% 15% 6%
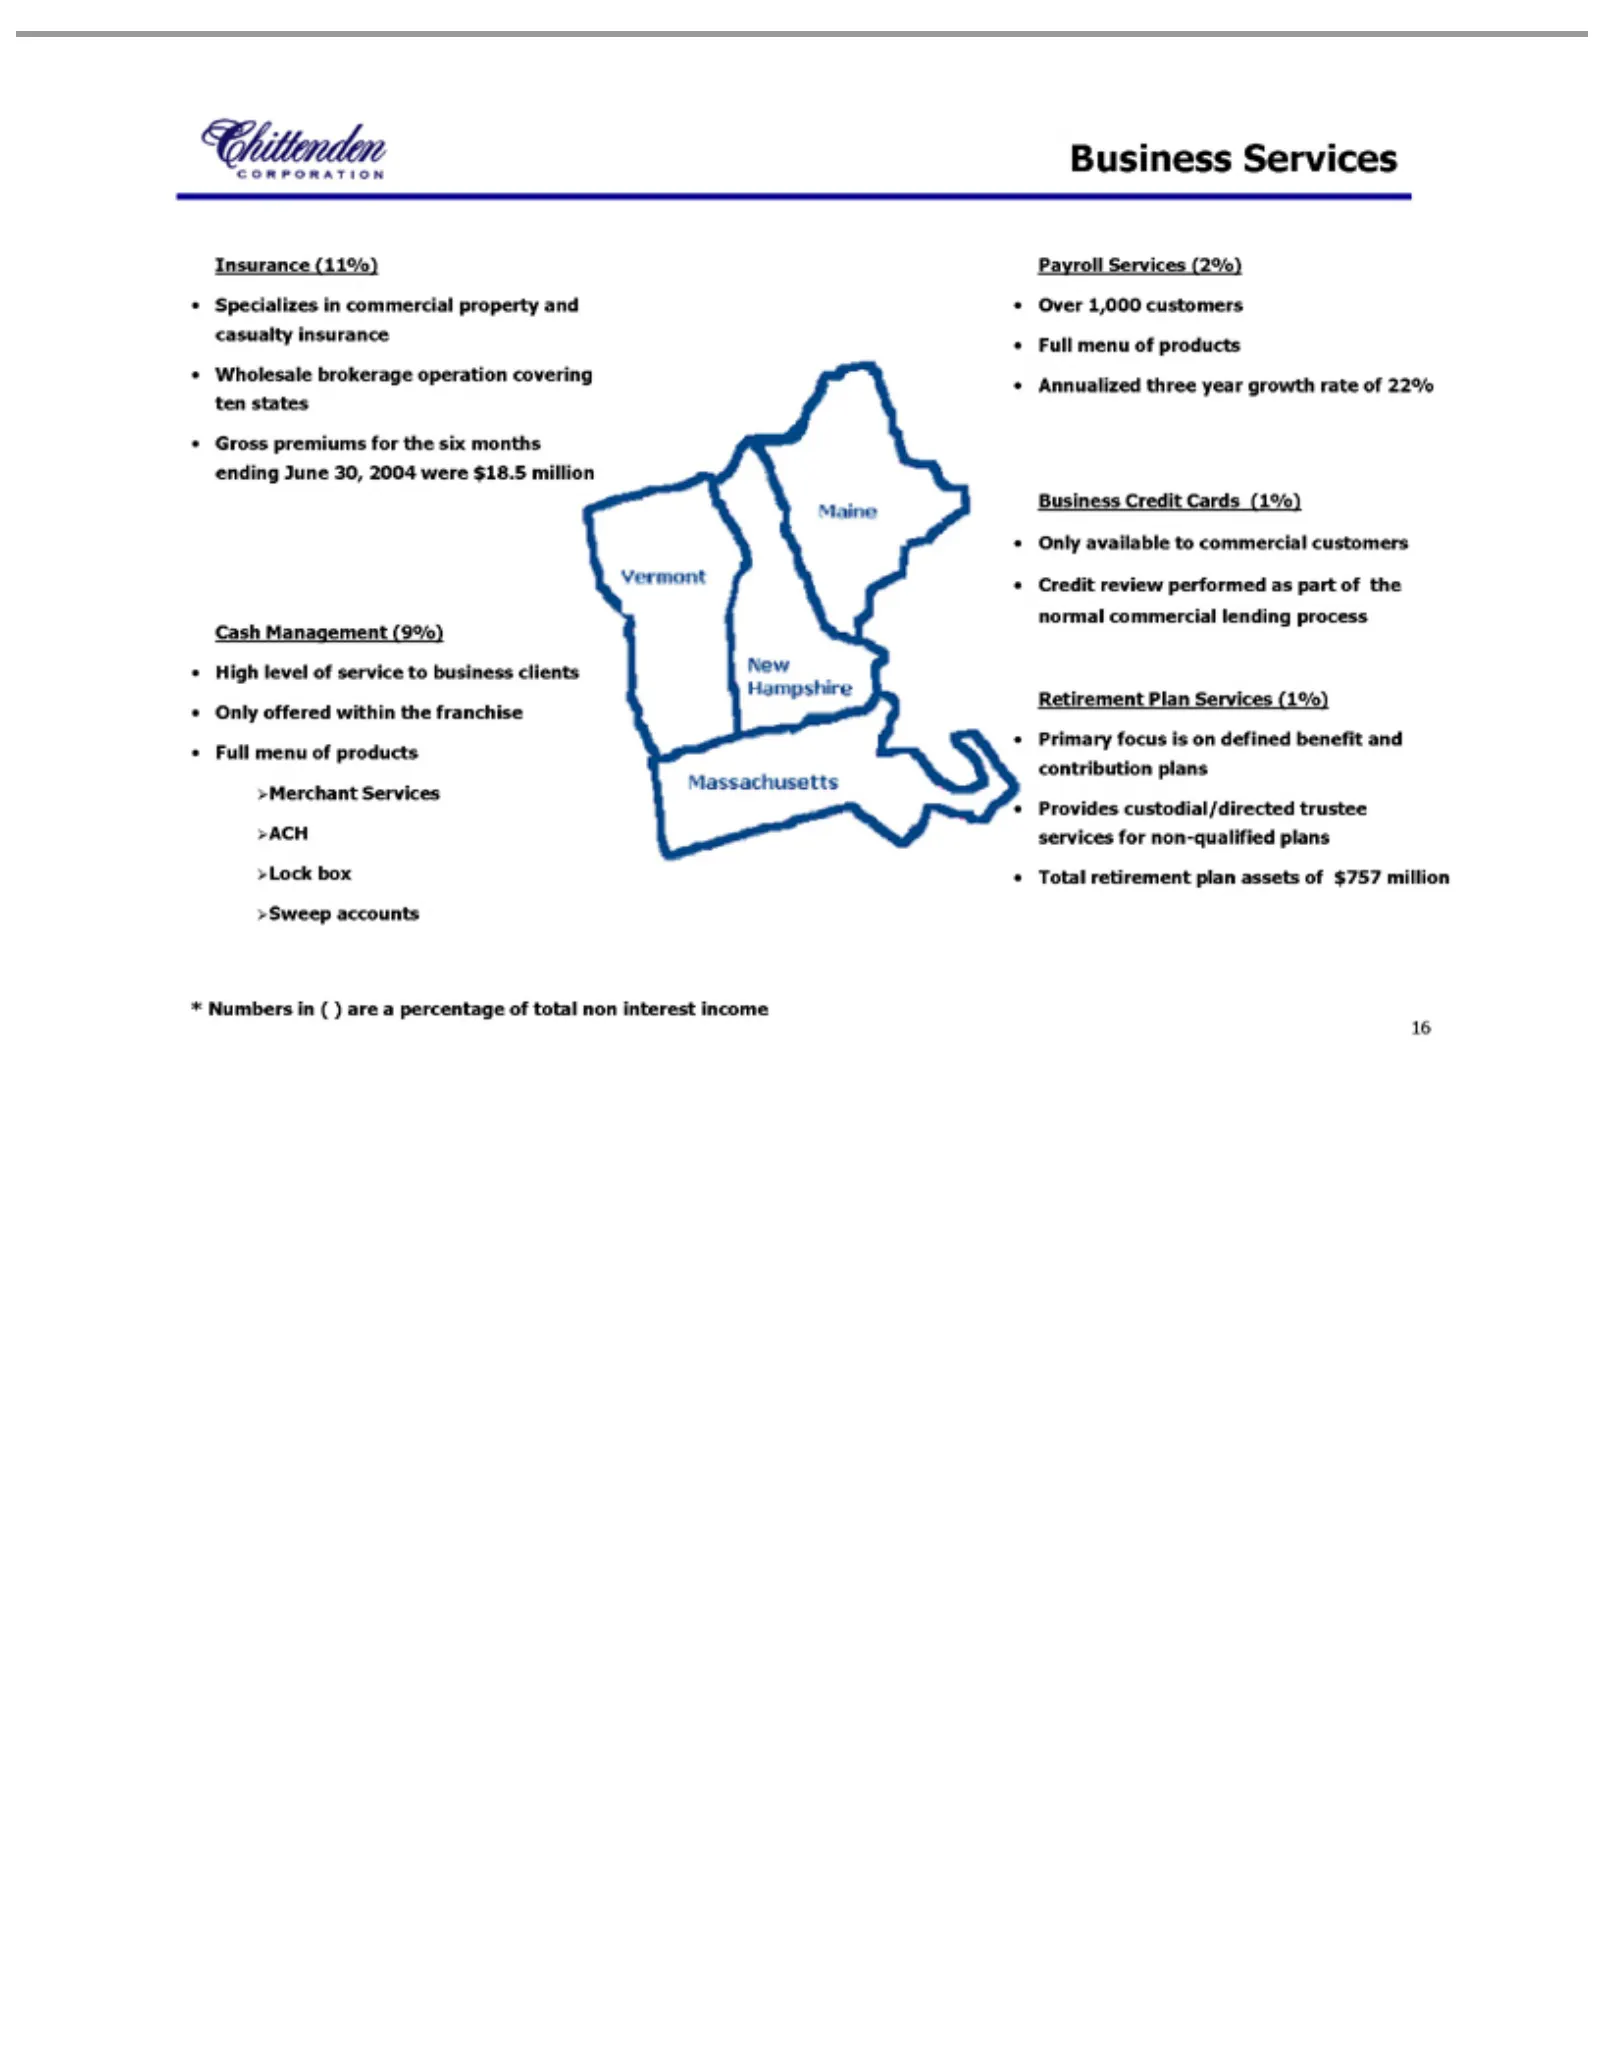
Slide 16: Cash Management and Insurance Services
Insurance Specializes Cash High Merchant Lock ACH Sweep Payroll Annualized Business Only Credit Retirement * million 16Numbers level available Management box review accounts Services Services Credit Services (11%) of in Plan three service (performed commercial toCards Services (2%) year commercial (
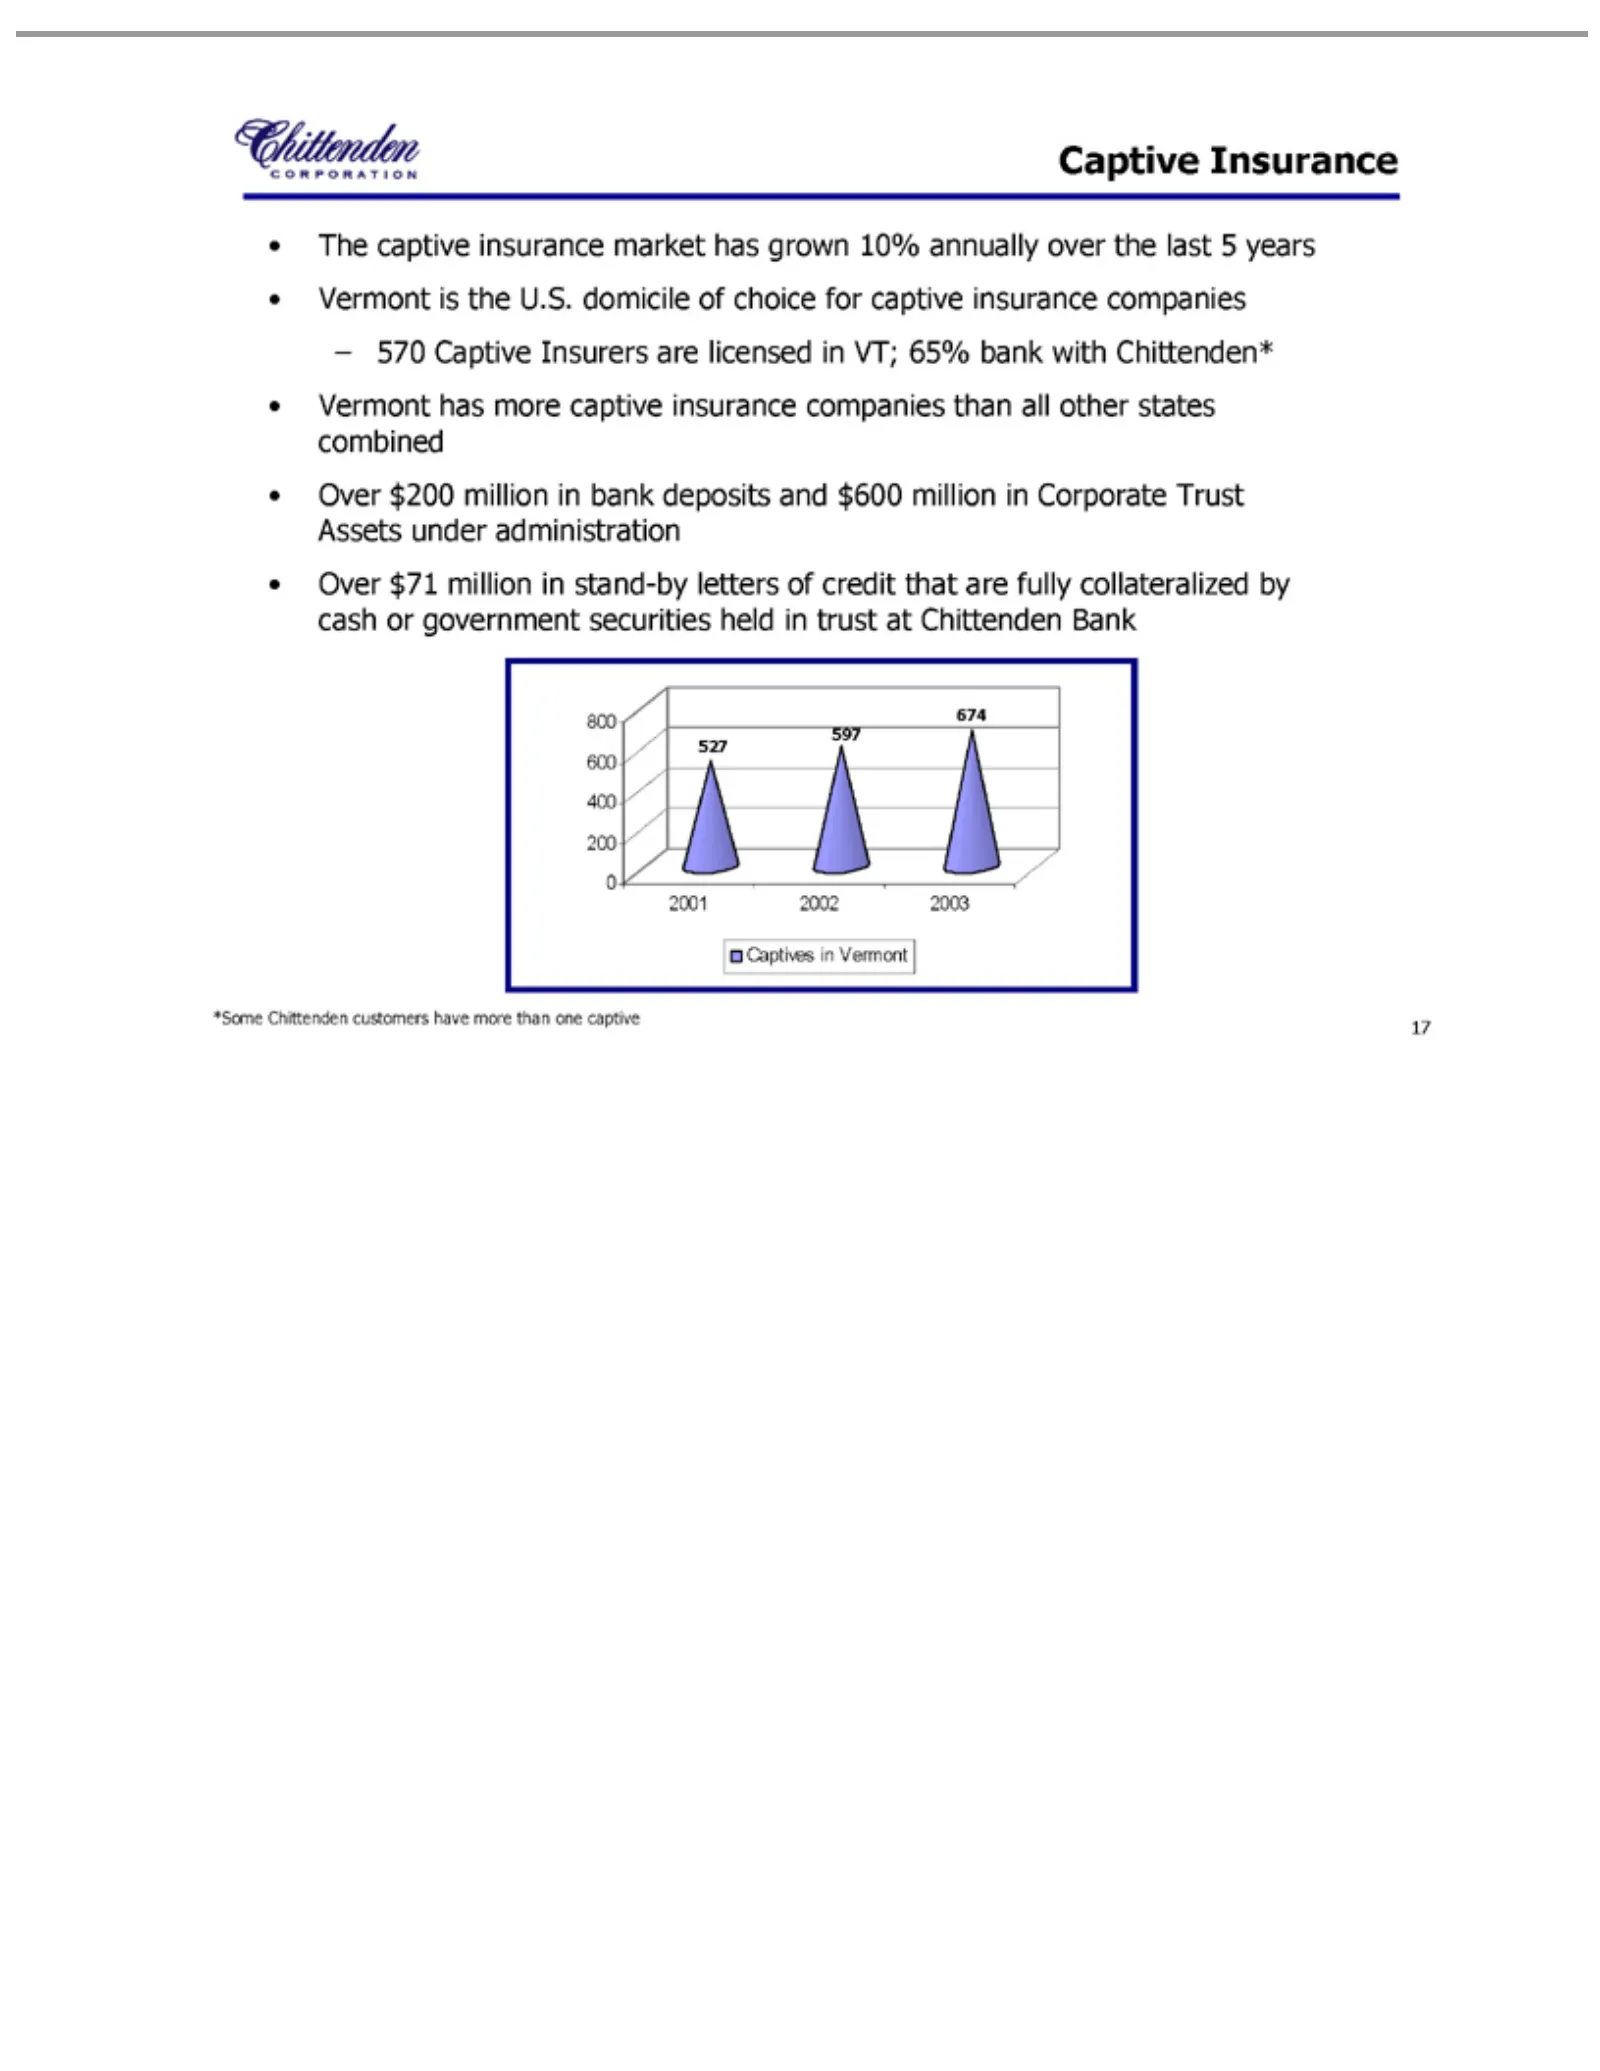
Slide 17: Captive Insurance in Vermont
Captive The 570 Vermont stand-by 800 2001 674 597 527 Captives *Some 17 Captive 600 captive 2002 Chittenden Insurance 400 has letters in2003 Vermont insurance Insurers 200 more of0credit captive customers are market that licensed insurance are have hasfully in grown more VT; companies collateralized
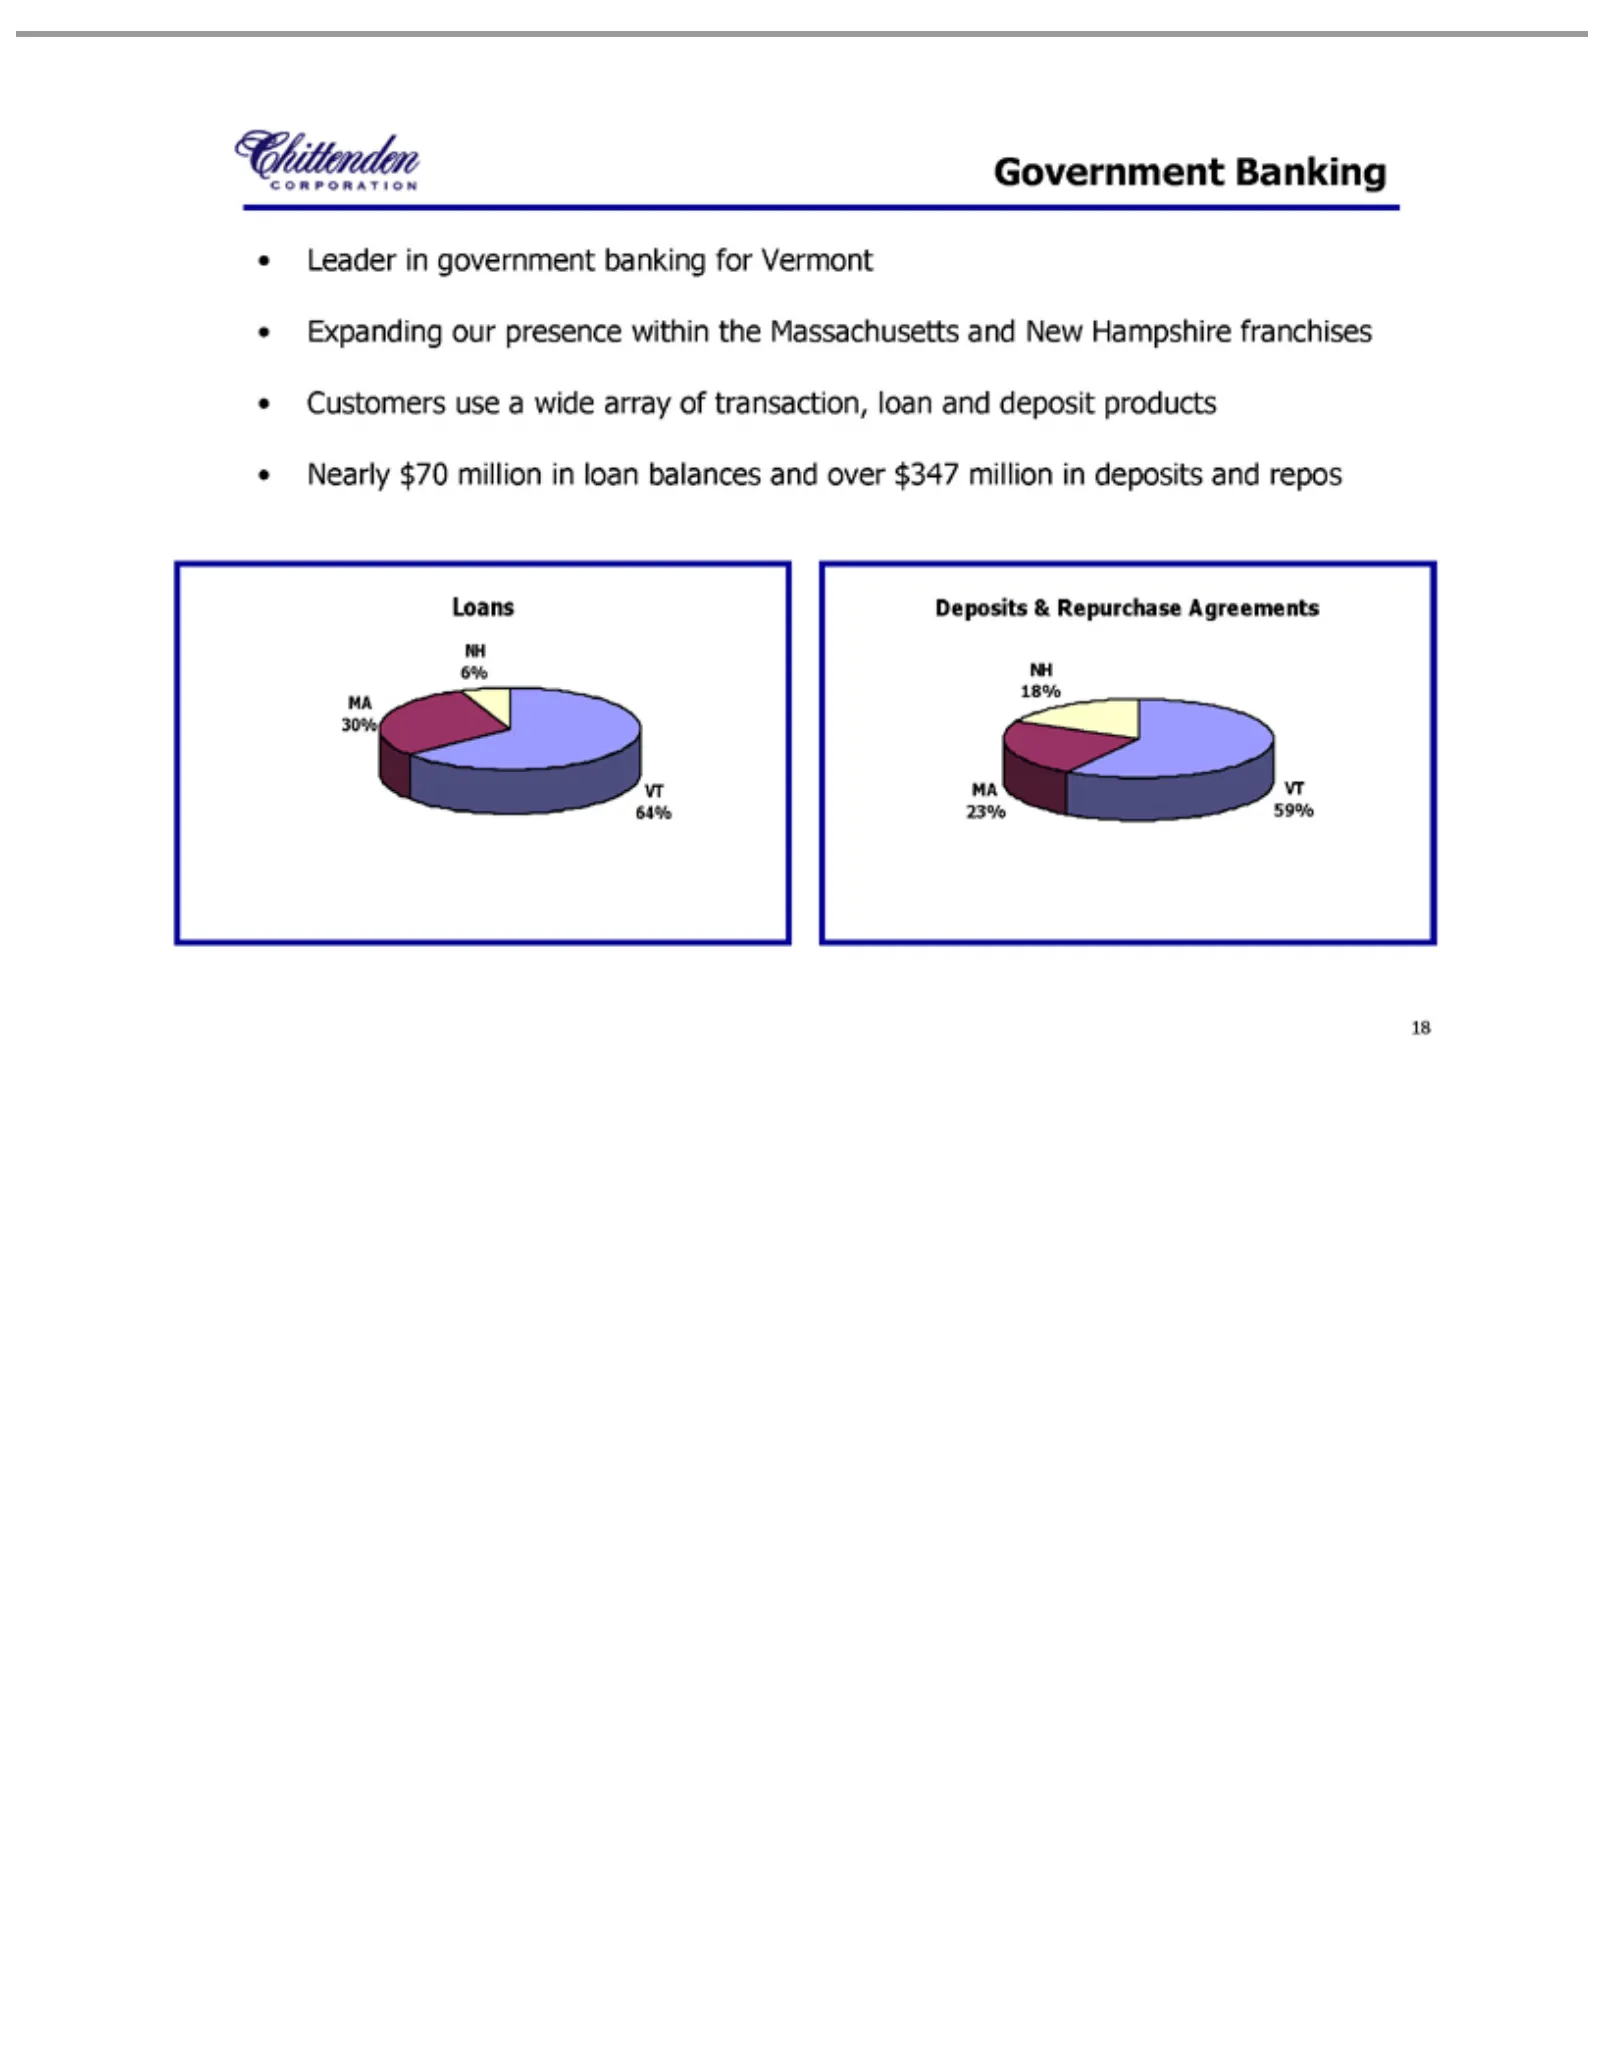
Slide 18: Government Banking Leader Expanding
Government Leader Expanding $347 Loans Deposits NH VT MA 18 64% 59% 6% 18% 30% 23% million in&government our Repurchase Banking inpresence deposits banking Agreements within and repos for theVermont Massachusetts and New Hampshire franchises Customers use a wide array of transaction, loan and deposi
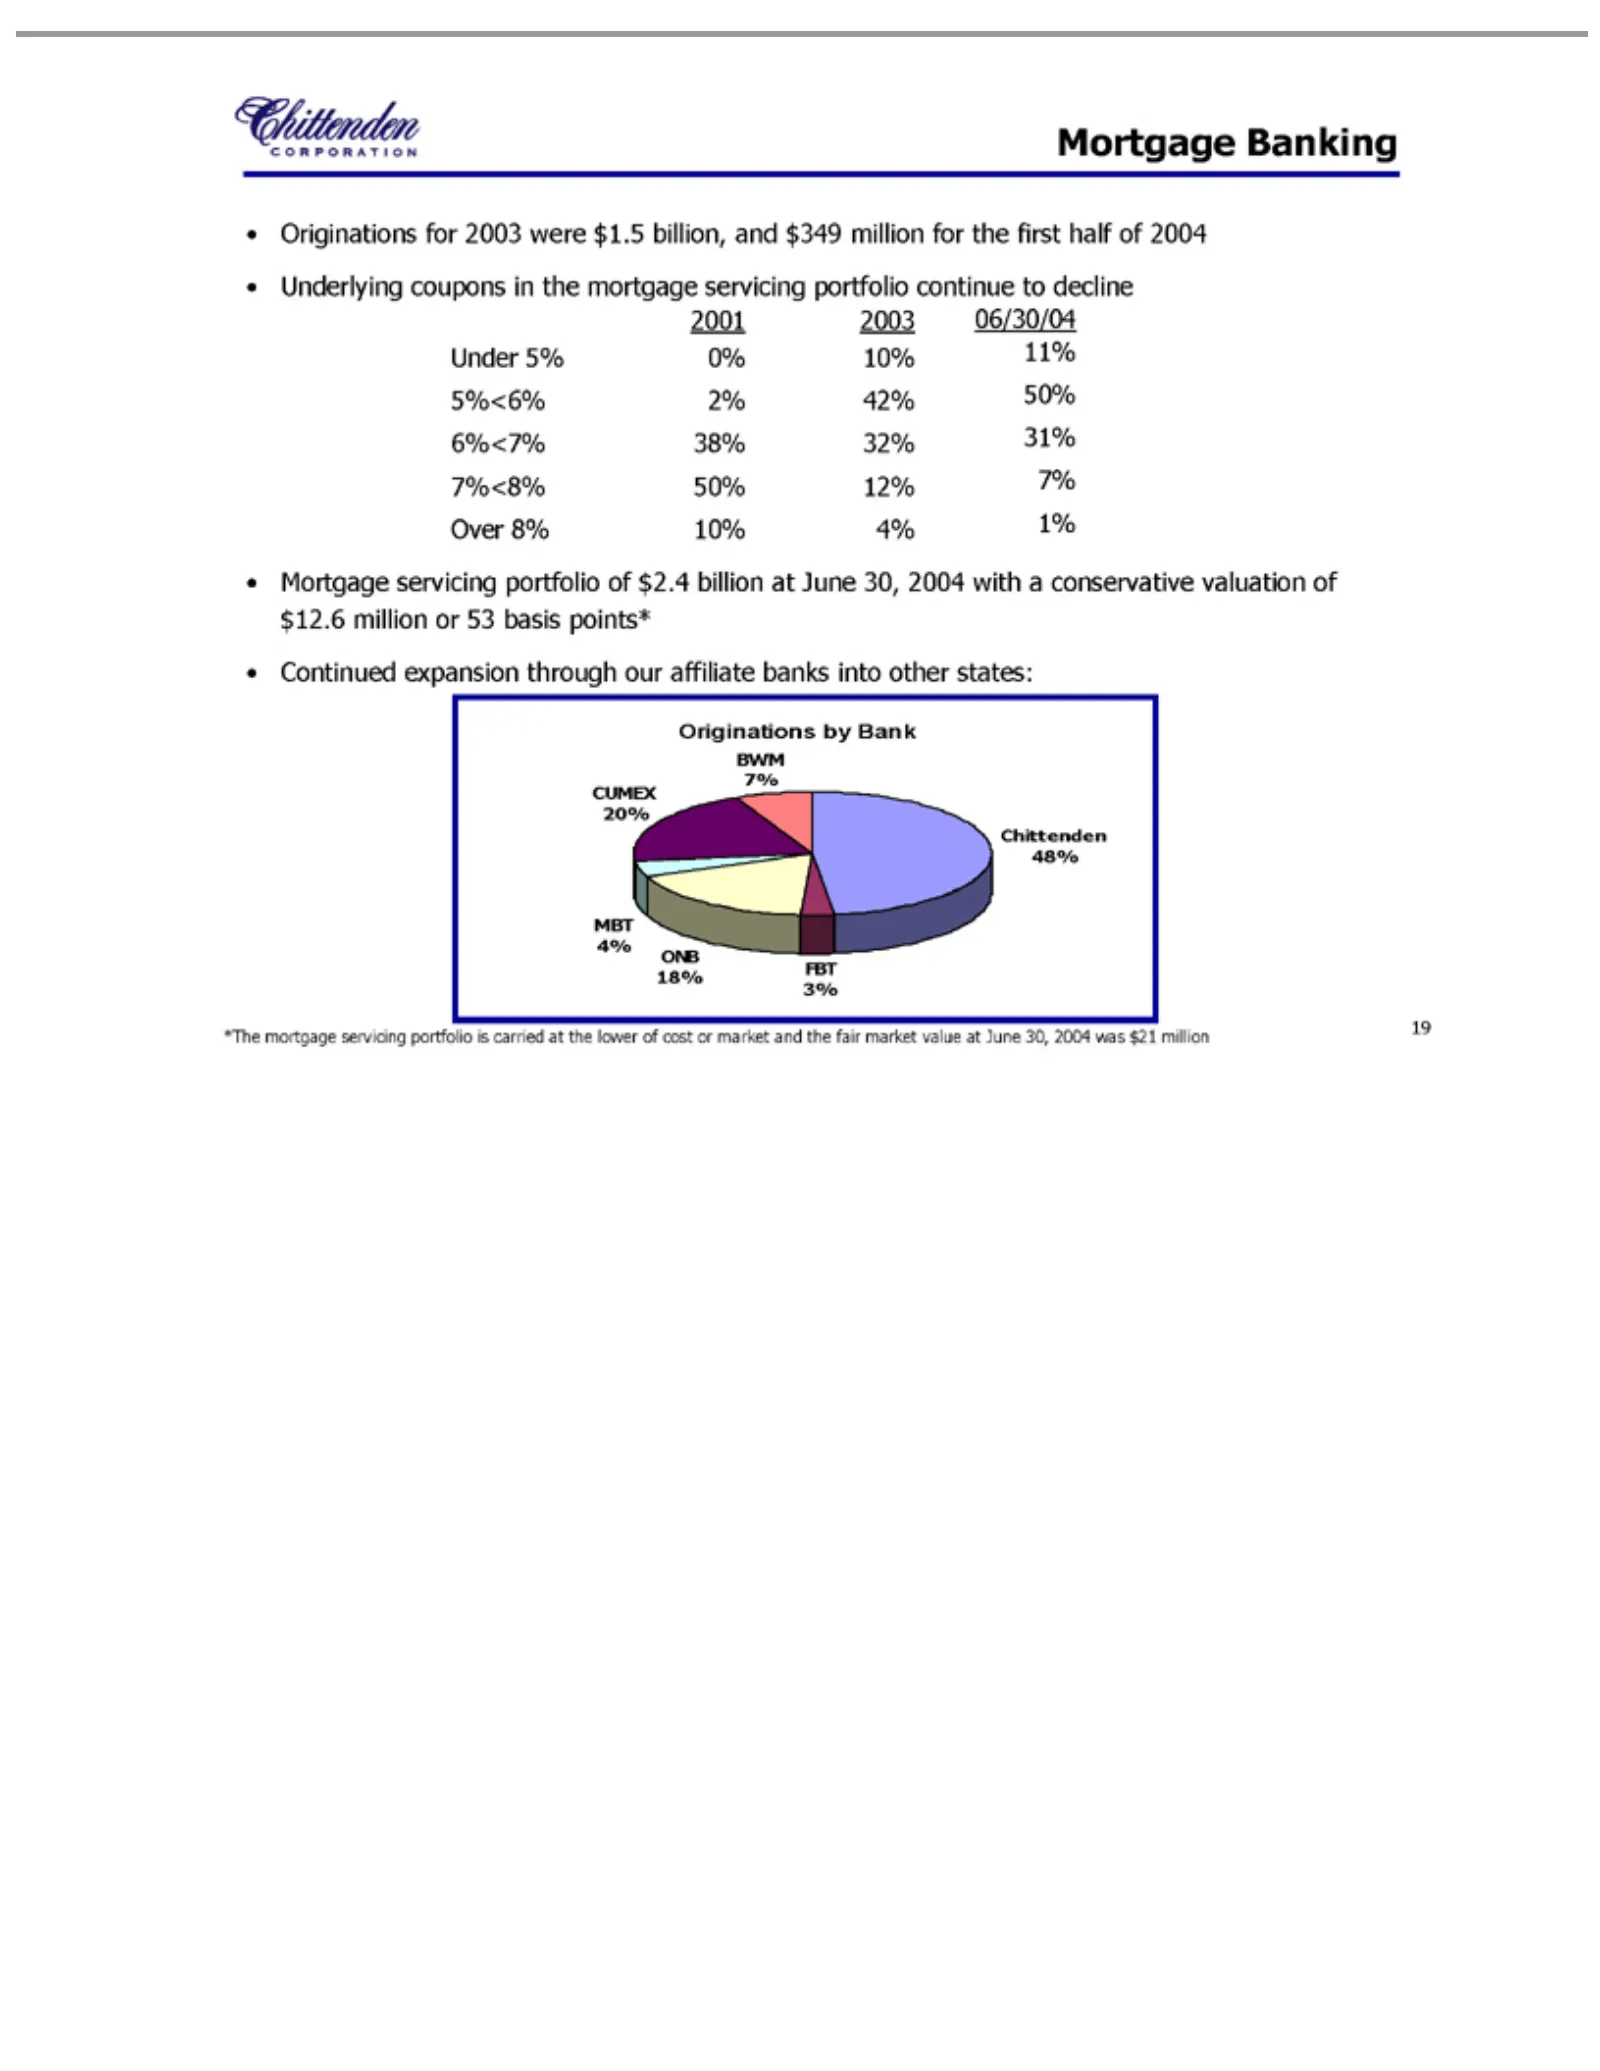
Slide 19: Mortgage Banking
2001 3% Under 5%<6% 6%<7% 7%<8% Over Mortgage Originations BWM Chittenden FBT ONB MBT CUMEX *The 19 8% 2003 mortgage 18% 4% 5% 7%2% 38% 50% 10% 20% Banking servicing 0% 06/30/04 48% 42% for by 32% 12% 10% 4% servicing Bank 2003 50% 1% 31% 7% 11% portfolio were portfolio $1.5 of $2.4 billion, is bill
Slide 20: Wealth Management
Wealth Management 20
Slide 21: Wealth Management Assets
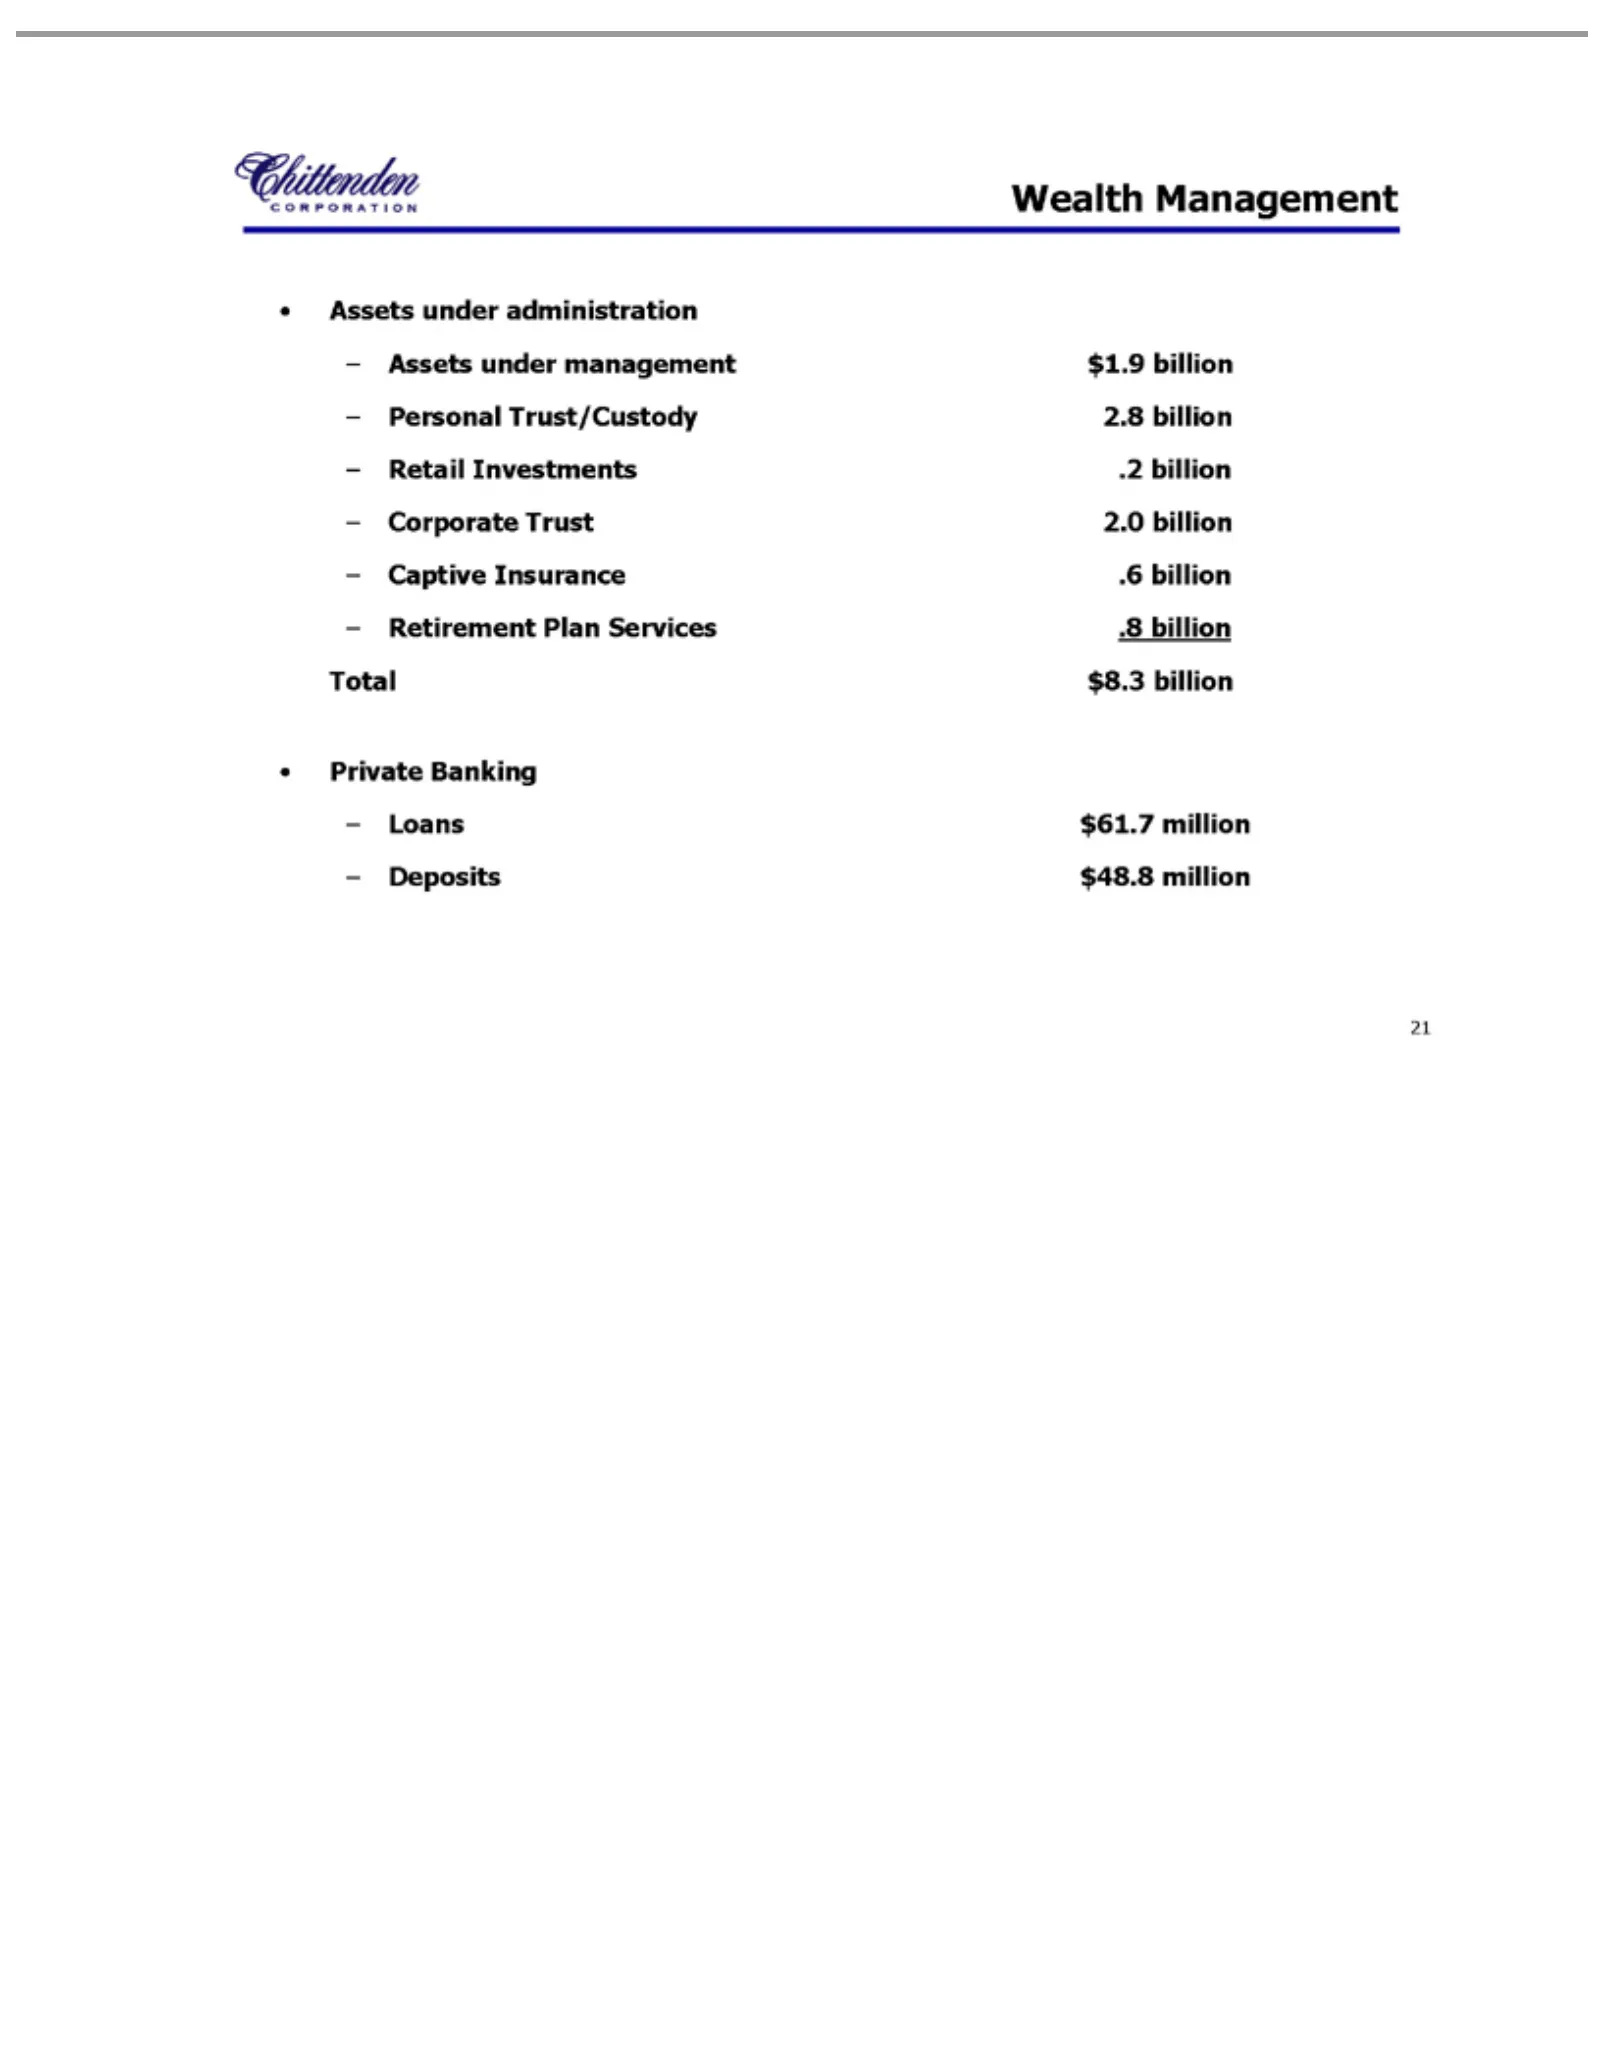
Wealth Assets Personal Retail Corporate Captive Retirement Total Private Loans Deposits 21 $8.3 Investments $under Management Banking Insurance 61.7 Trust/Custody $Trust billion 48.8 Plan administration management million million 2.0 Services .6 .2billion billion billion 2.8 .8$1.9 billion billion b
Slide 22: Asset Management Services
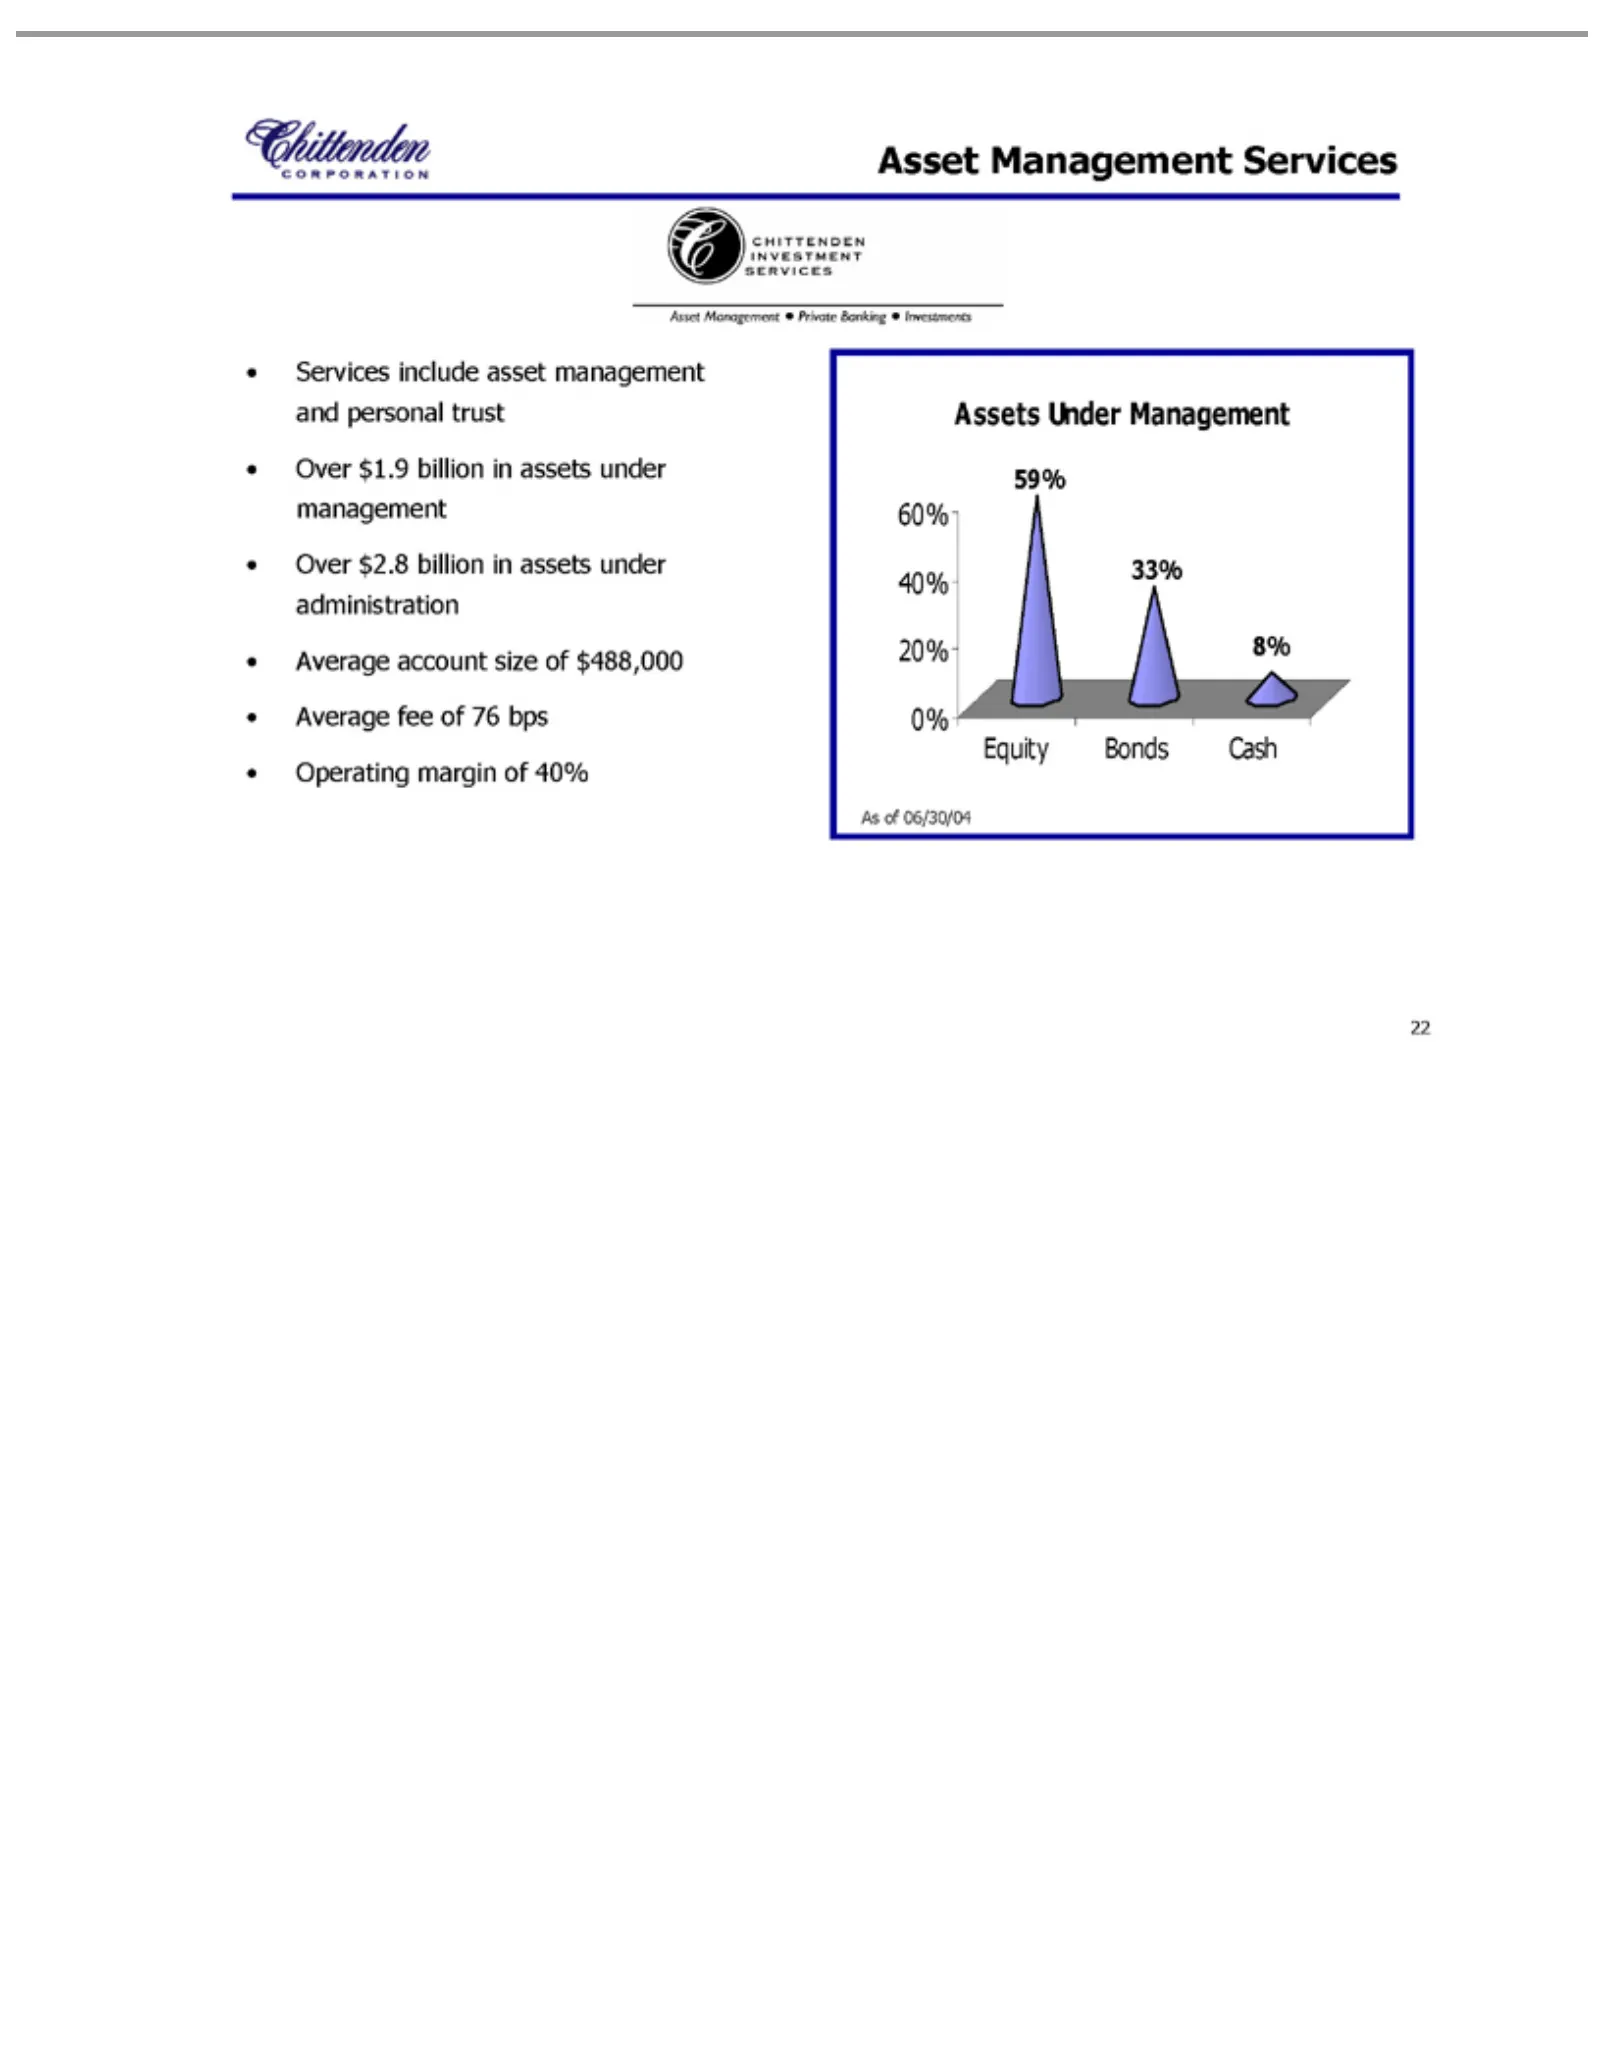
Asset Services 76 Assets 60% Equity 8% 33% 59% As 22 bps of40% 06/30/04 Management Under Operating Bonds include 20%Management Cash 0%asset margin Services management of 40% and personal trust Over $1.9 billion in assets under management Over $2.8 billion in assets under administration Average accou
Slide 23: Retail Investments and Corporate Trust
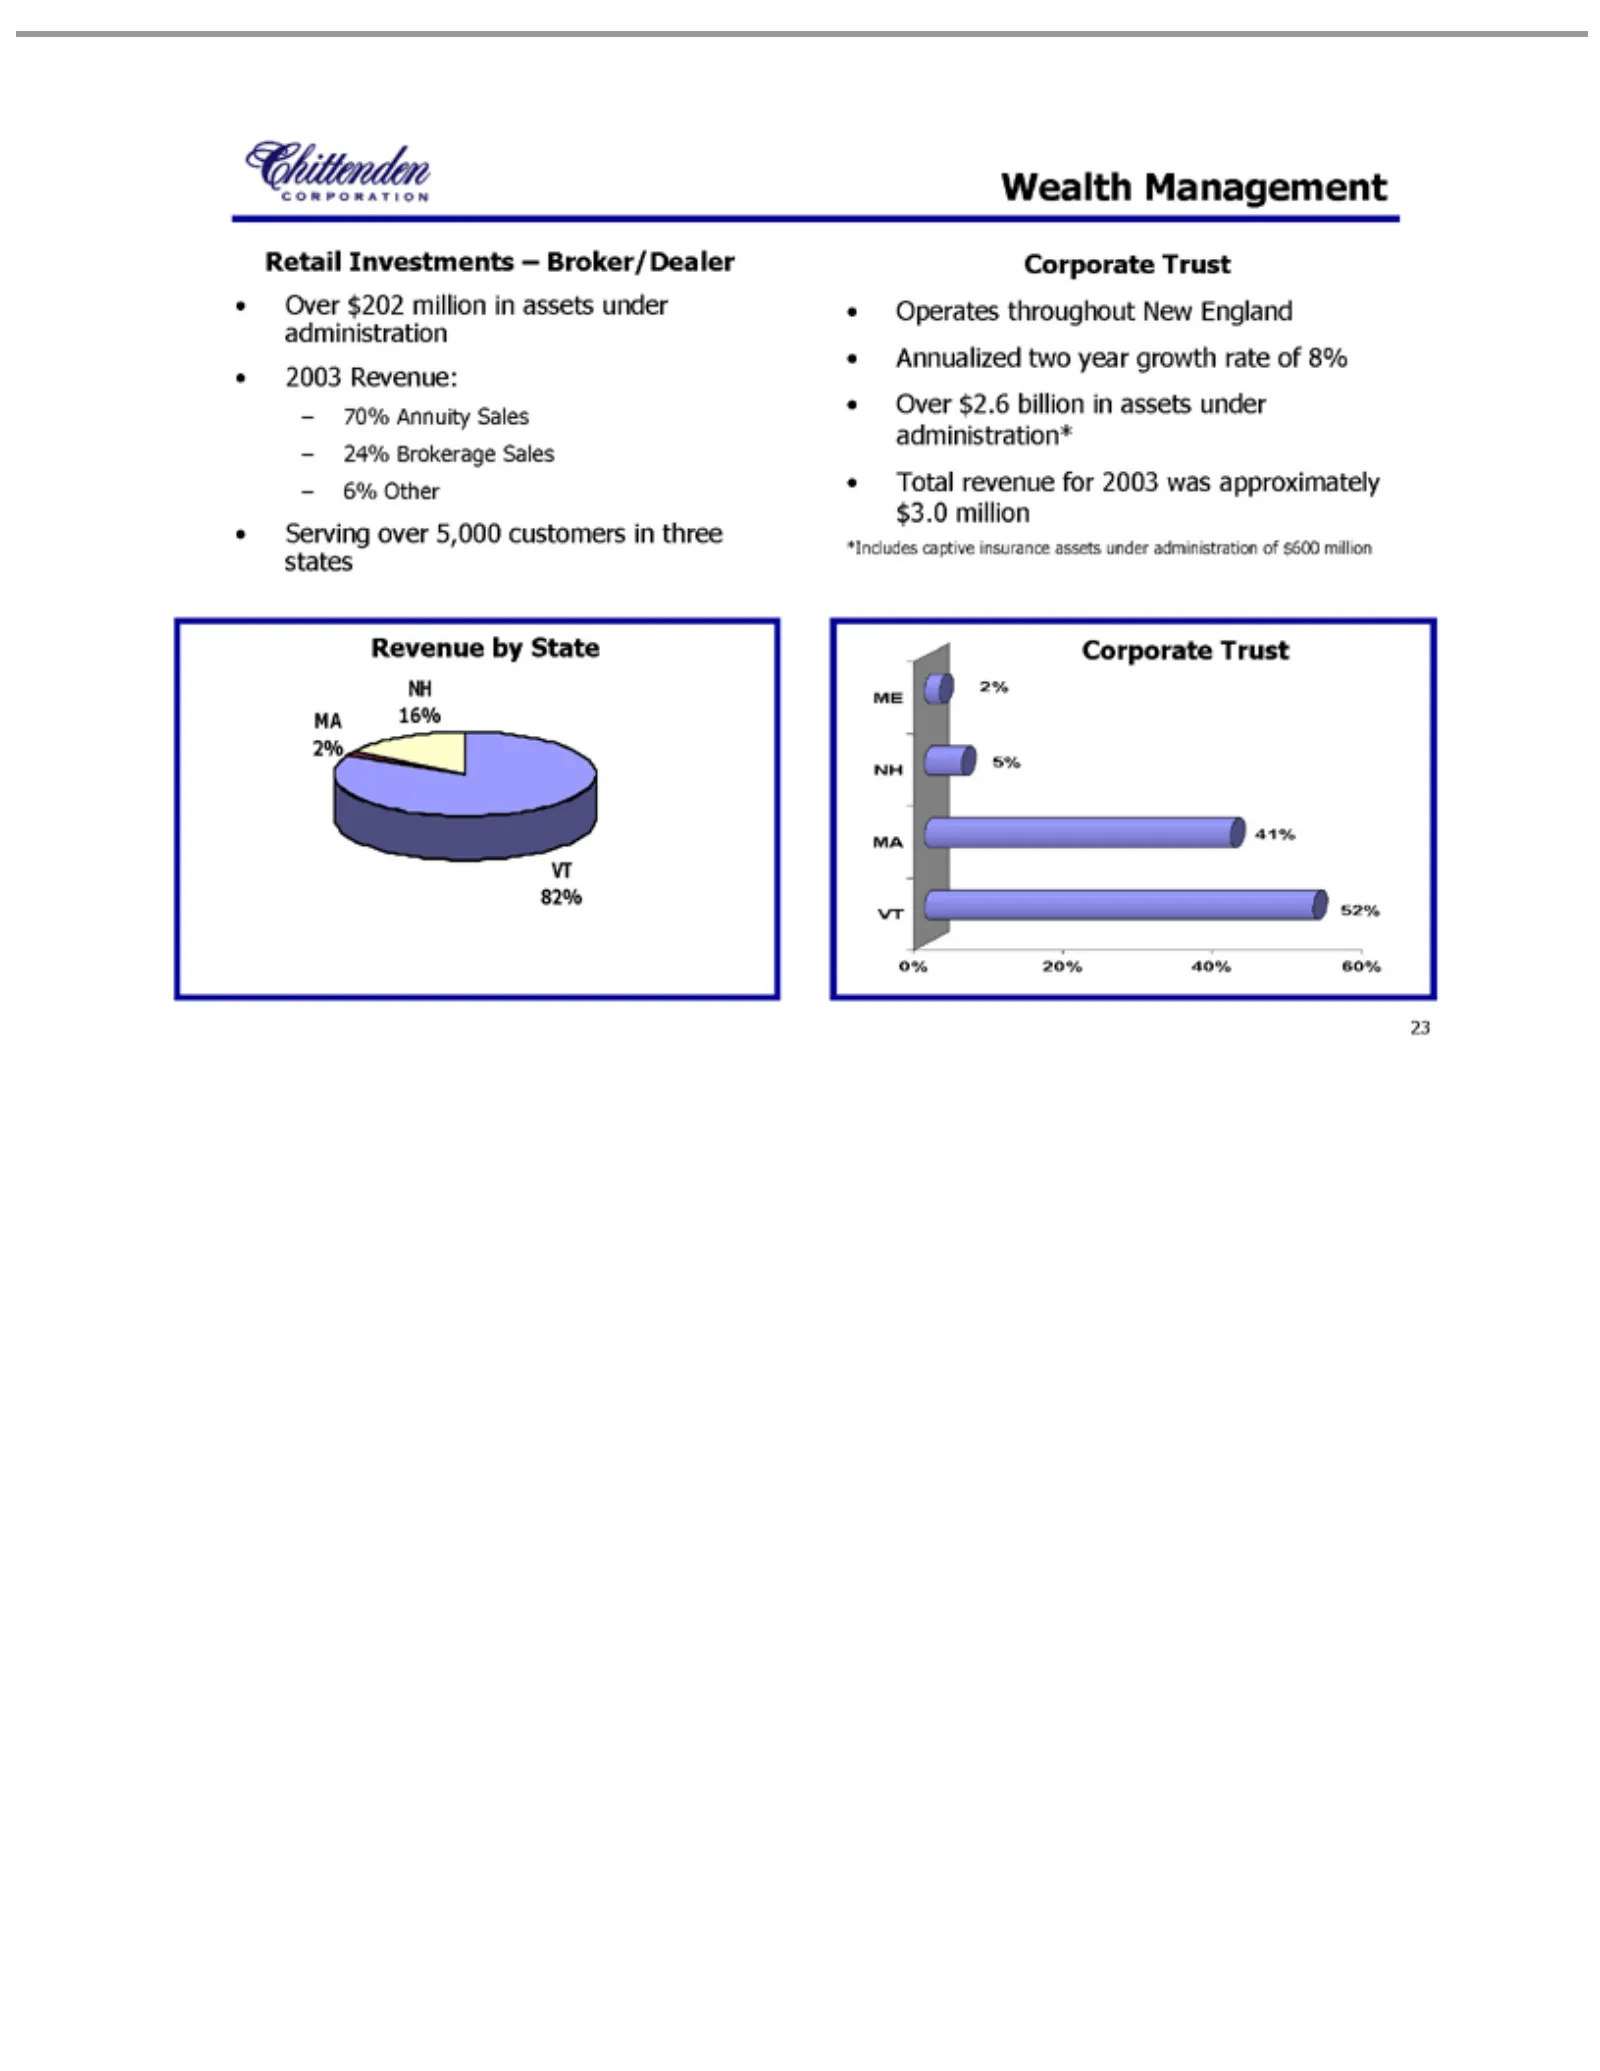
Wealth Retail Over 70% Serving Operates *Includes Revenue NH VT MA Corporate ME 0% 52% 41% 5% 2% 23 82% 20% 16% NH 2% Annuity $202 Investments Management over MA 40% by throughout captive Trust million State VT 5,000 Sales 60%insurance in –customers 24% New Broker/Dealer assets Brokerage England und
Slide 24: Financial Performance
Financial Performance 24
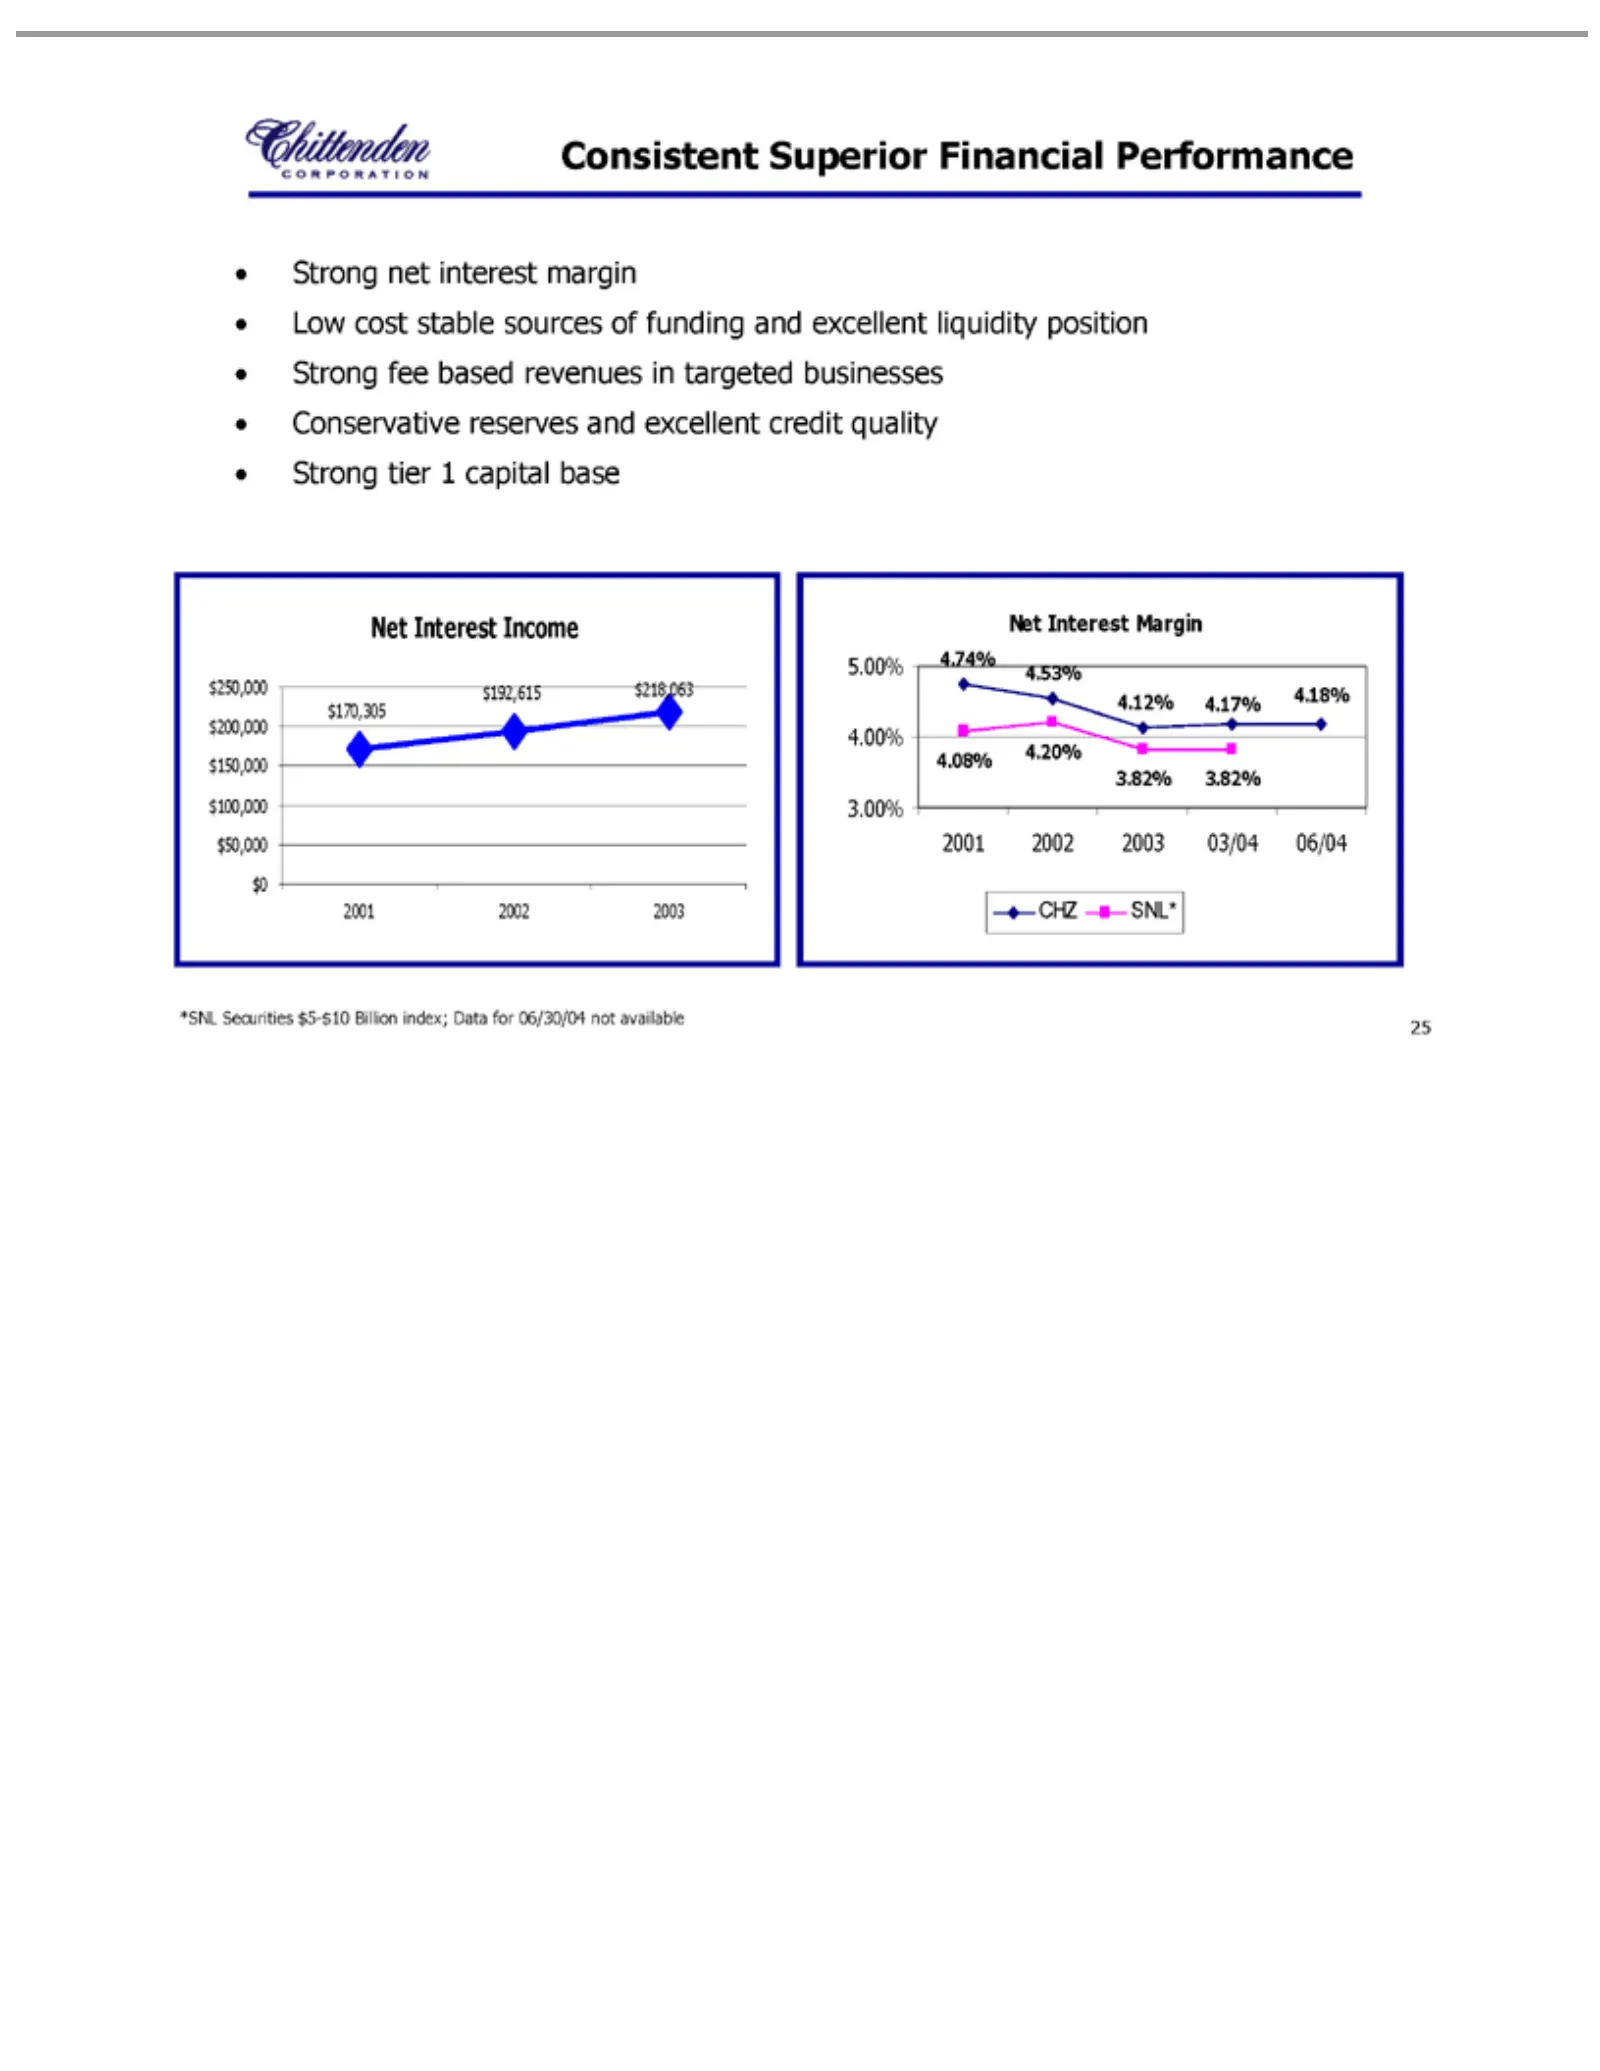
Slide 25: Consistent Net Interest Margin
Consistent Low Conservative Strong Net 2001 3.82% 4.20% 4.08% 4.18% 4.17% 4.12% 4.53% 4.74% 3.00% 4.00% 5.00% *SNL SNL* CHZ 25 Interest cost 2002 Securities netstable fee tier based interest Superior 12003 Income Margin capital reserves sources 03/04 $5-$10 revenues margin base Financial $250,000 an
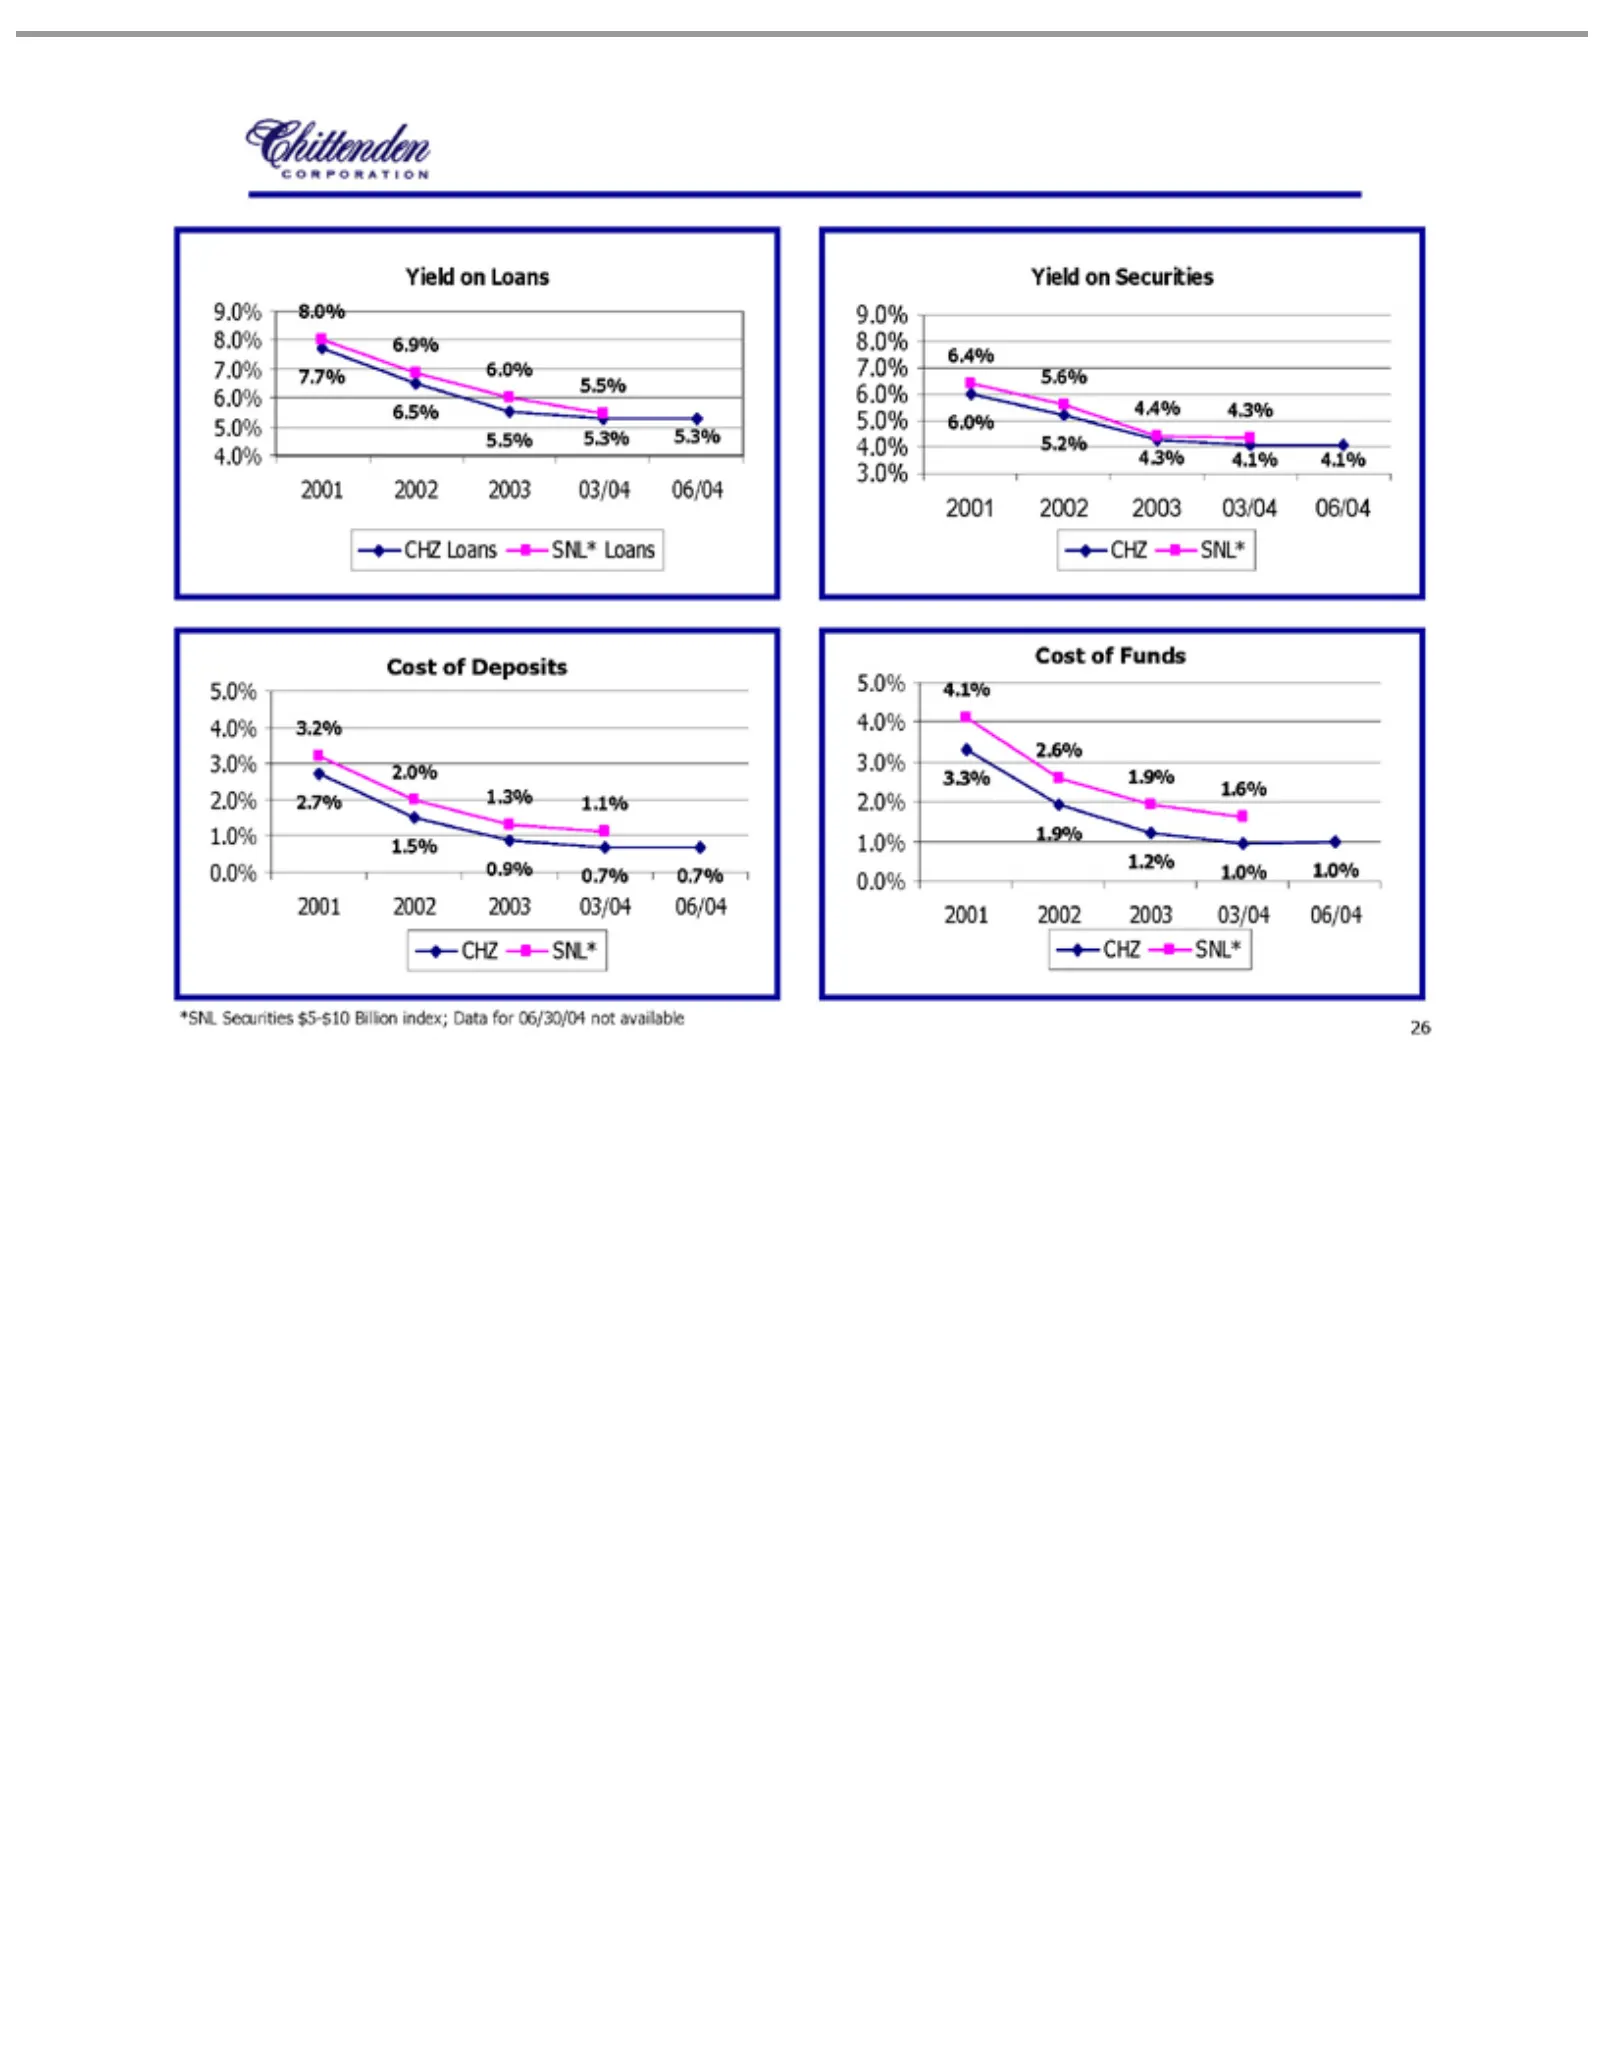
Slide 26: Yield on Loans and Cost of Funds
5.3%of 6.5% 7.7% 5.5% 6.9% 8.0% Yield 9.0% 5.2% 6.0% 4.3% 4.4% 5.6% 6.4% 0.7% 0.9% 1.5% 2.7% 1.1% 1.3% 2.0% 3.2% Cost 5.0% 2001 1.0% 1.2% 3.3% 1.6% 1.9% 2.6% 4.1% *SNL SNL* CHZ 26 Loans 2002 8.0% 4.0% on Securities Loans Deposits Funds Loans Securities 2003 7.0%03/04 3.0% $5-$10 6.0% 06/04 2.0% 5.0%
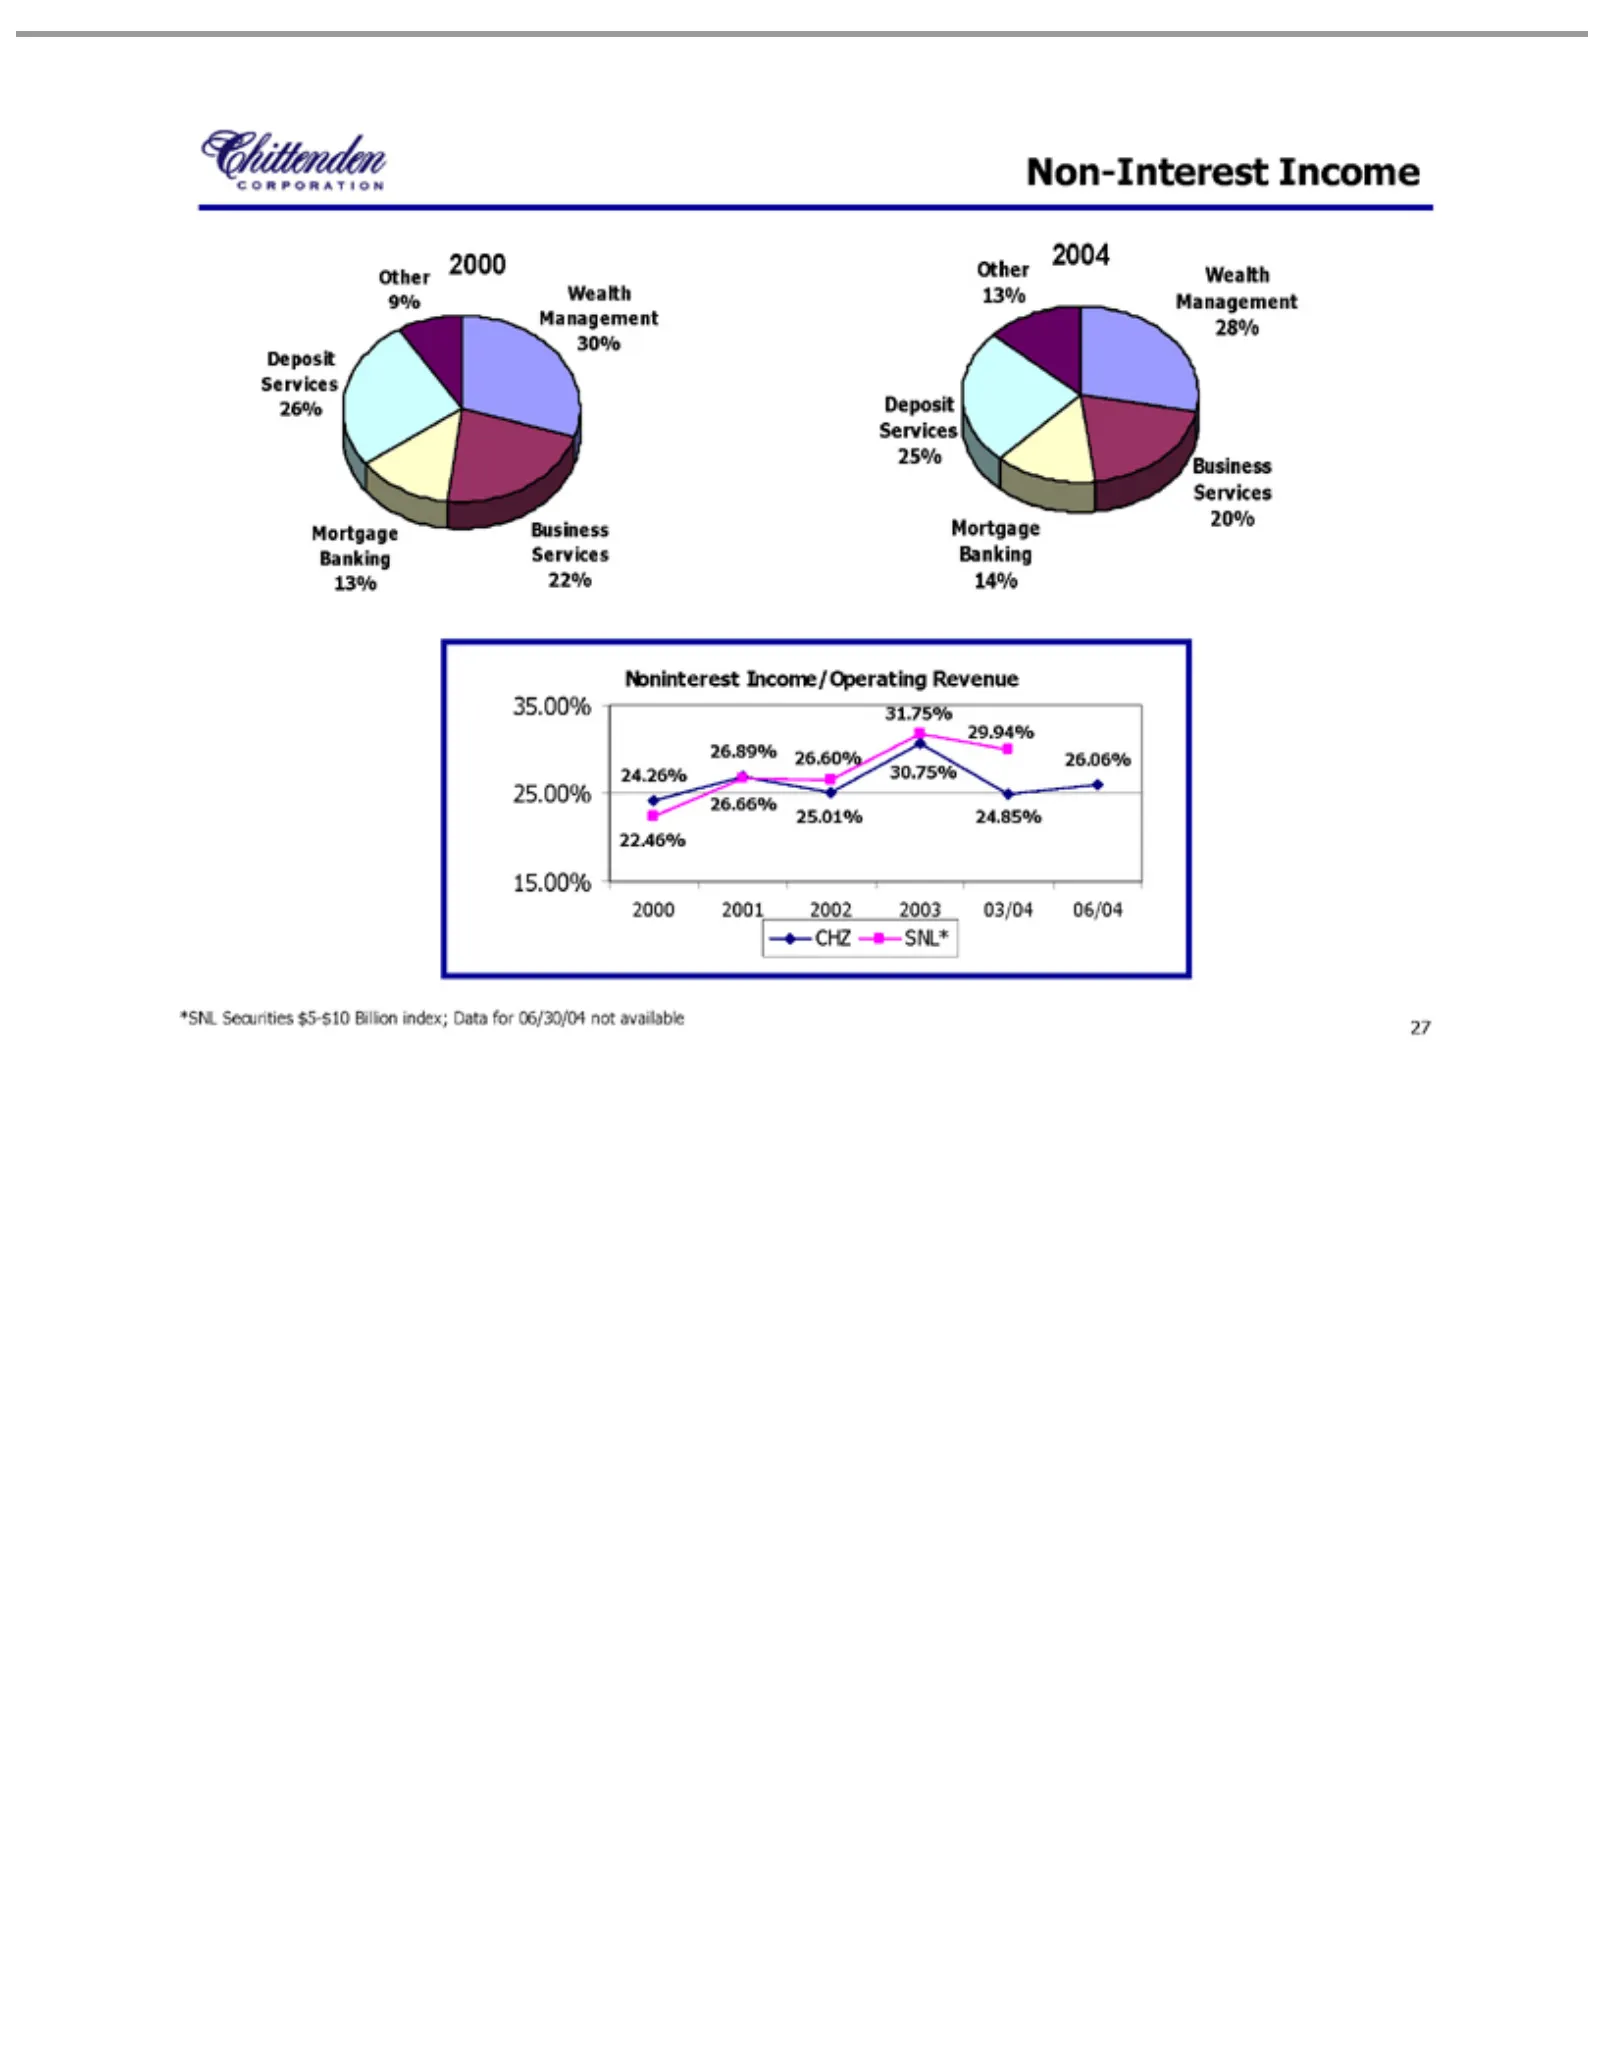
Slide 27: Non-Interest Income and Wealth Business
Non-Interest Wealth 2004 Business Mortgage Deposit Other Noninterest 35.00% 2000 24.85% 30.75% 25.01% 26.66% 22.46% 26.06% 29.94% 31.75% 26.60% 26.89% 24.26% *SNL SNL* CHZ 27 2001 9% 13% Securities Management 25.00% Services Services Banking 2002 Income/Operating Income 15.00% 2003 $5-$10 26% 25% 22
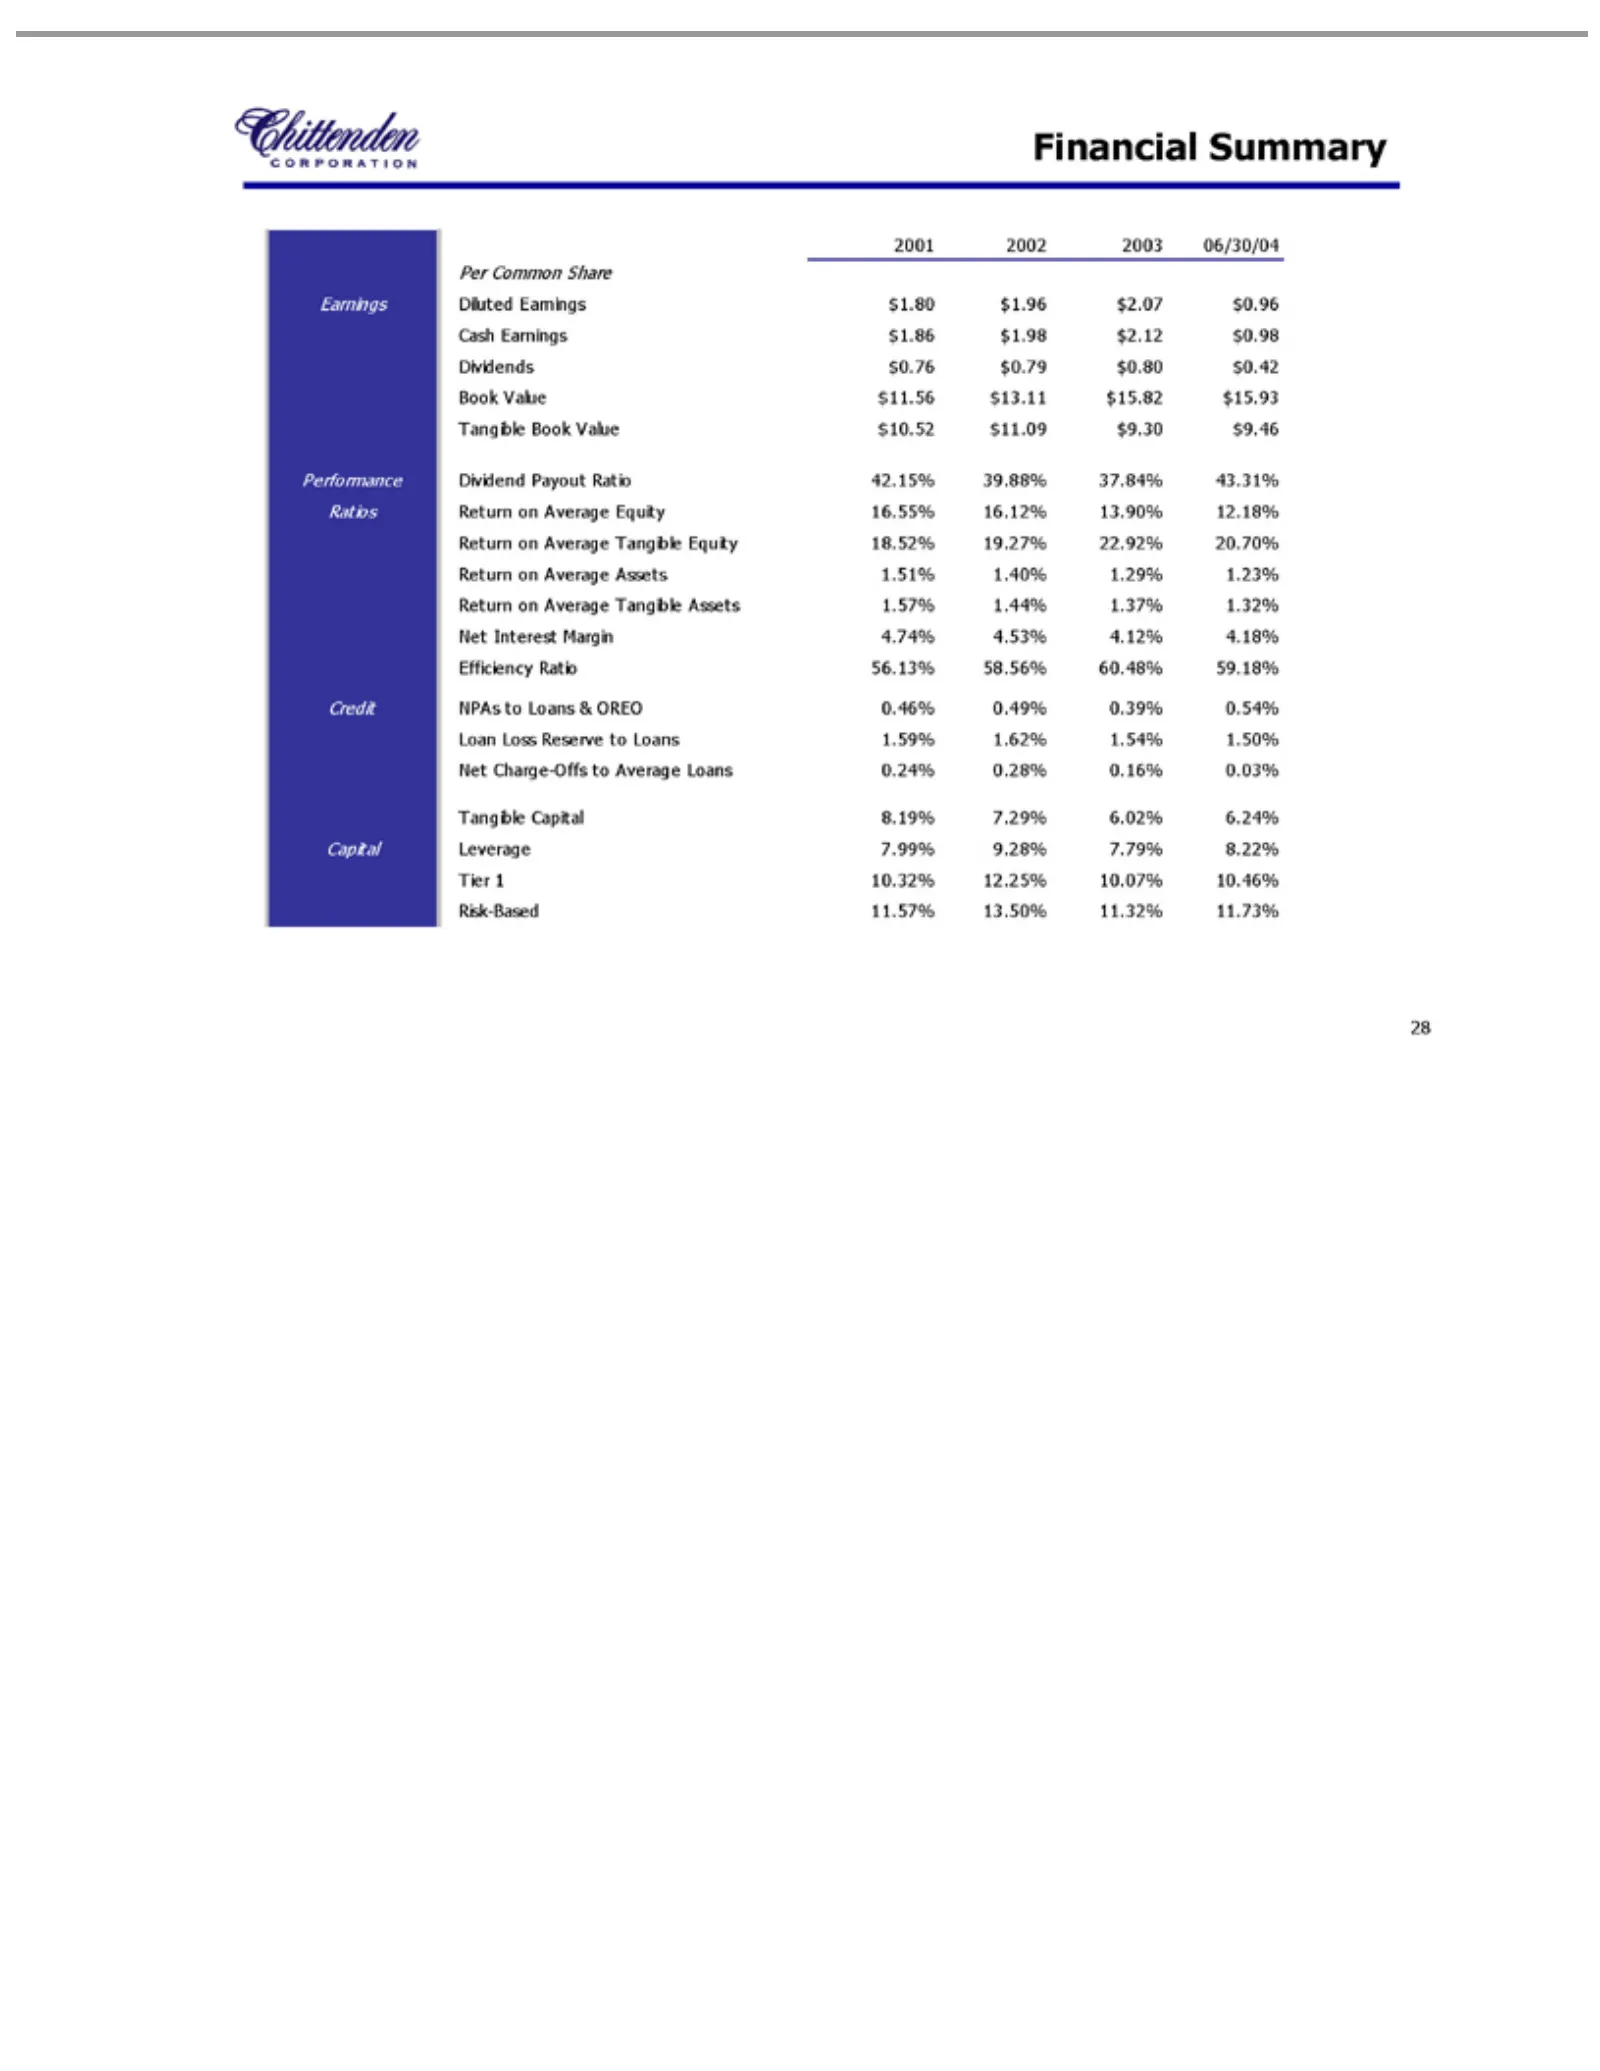
Slide 28: Financial Performance Summary
Financial 2001 Per Earnings Cash Dividends Book Performance Ratios Return Efficiency Credit Loan Net Tangible Capital Tier Risk-Based 28 Common Interest Charge-Offs 12002 Earnings Loss Value 10.32% NPAs Return on Leverage Book Capital Diluted Summary Average $Ratio Reserve 2003 11.57% $Margin 0.76 t
Slide 29: Risk Management
Risk Management 29
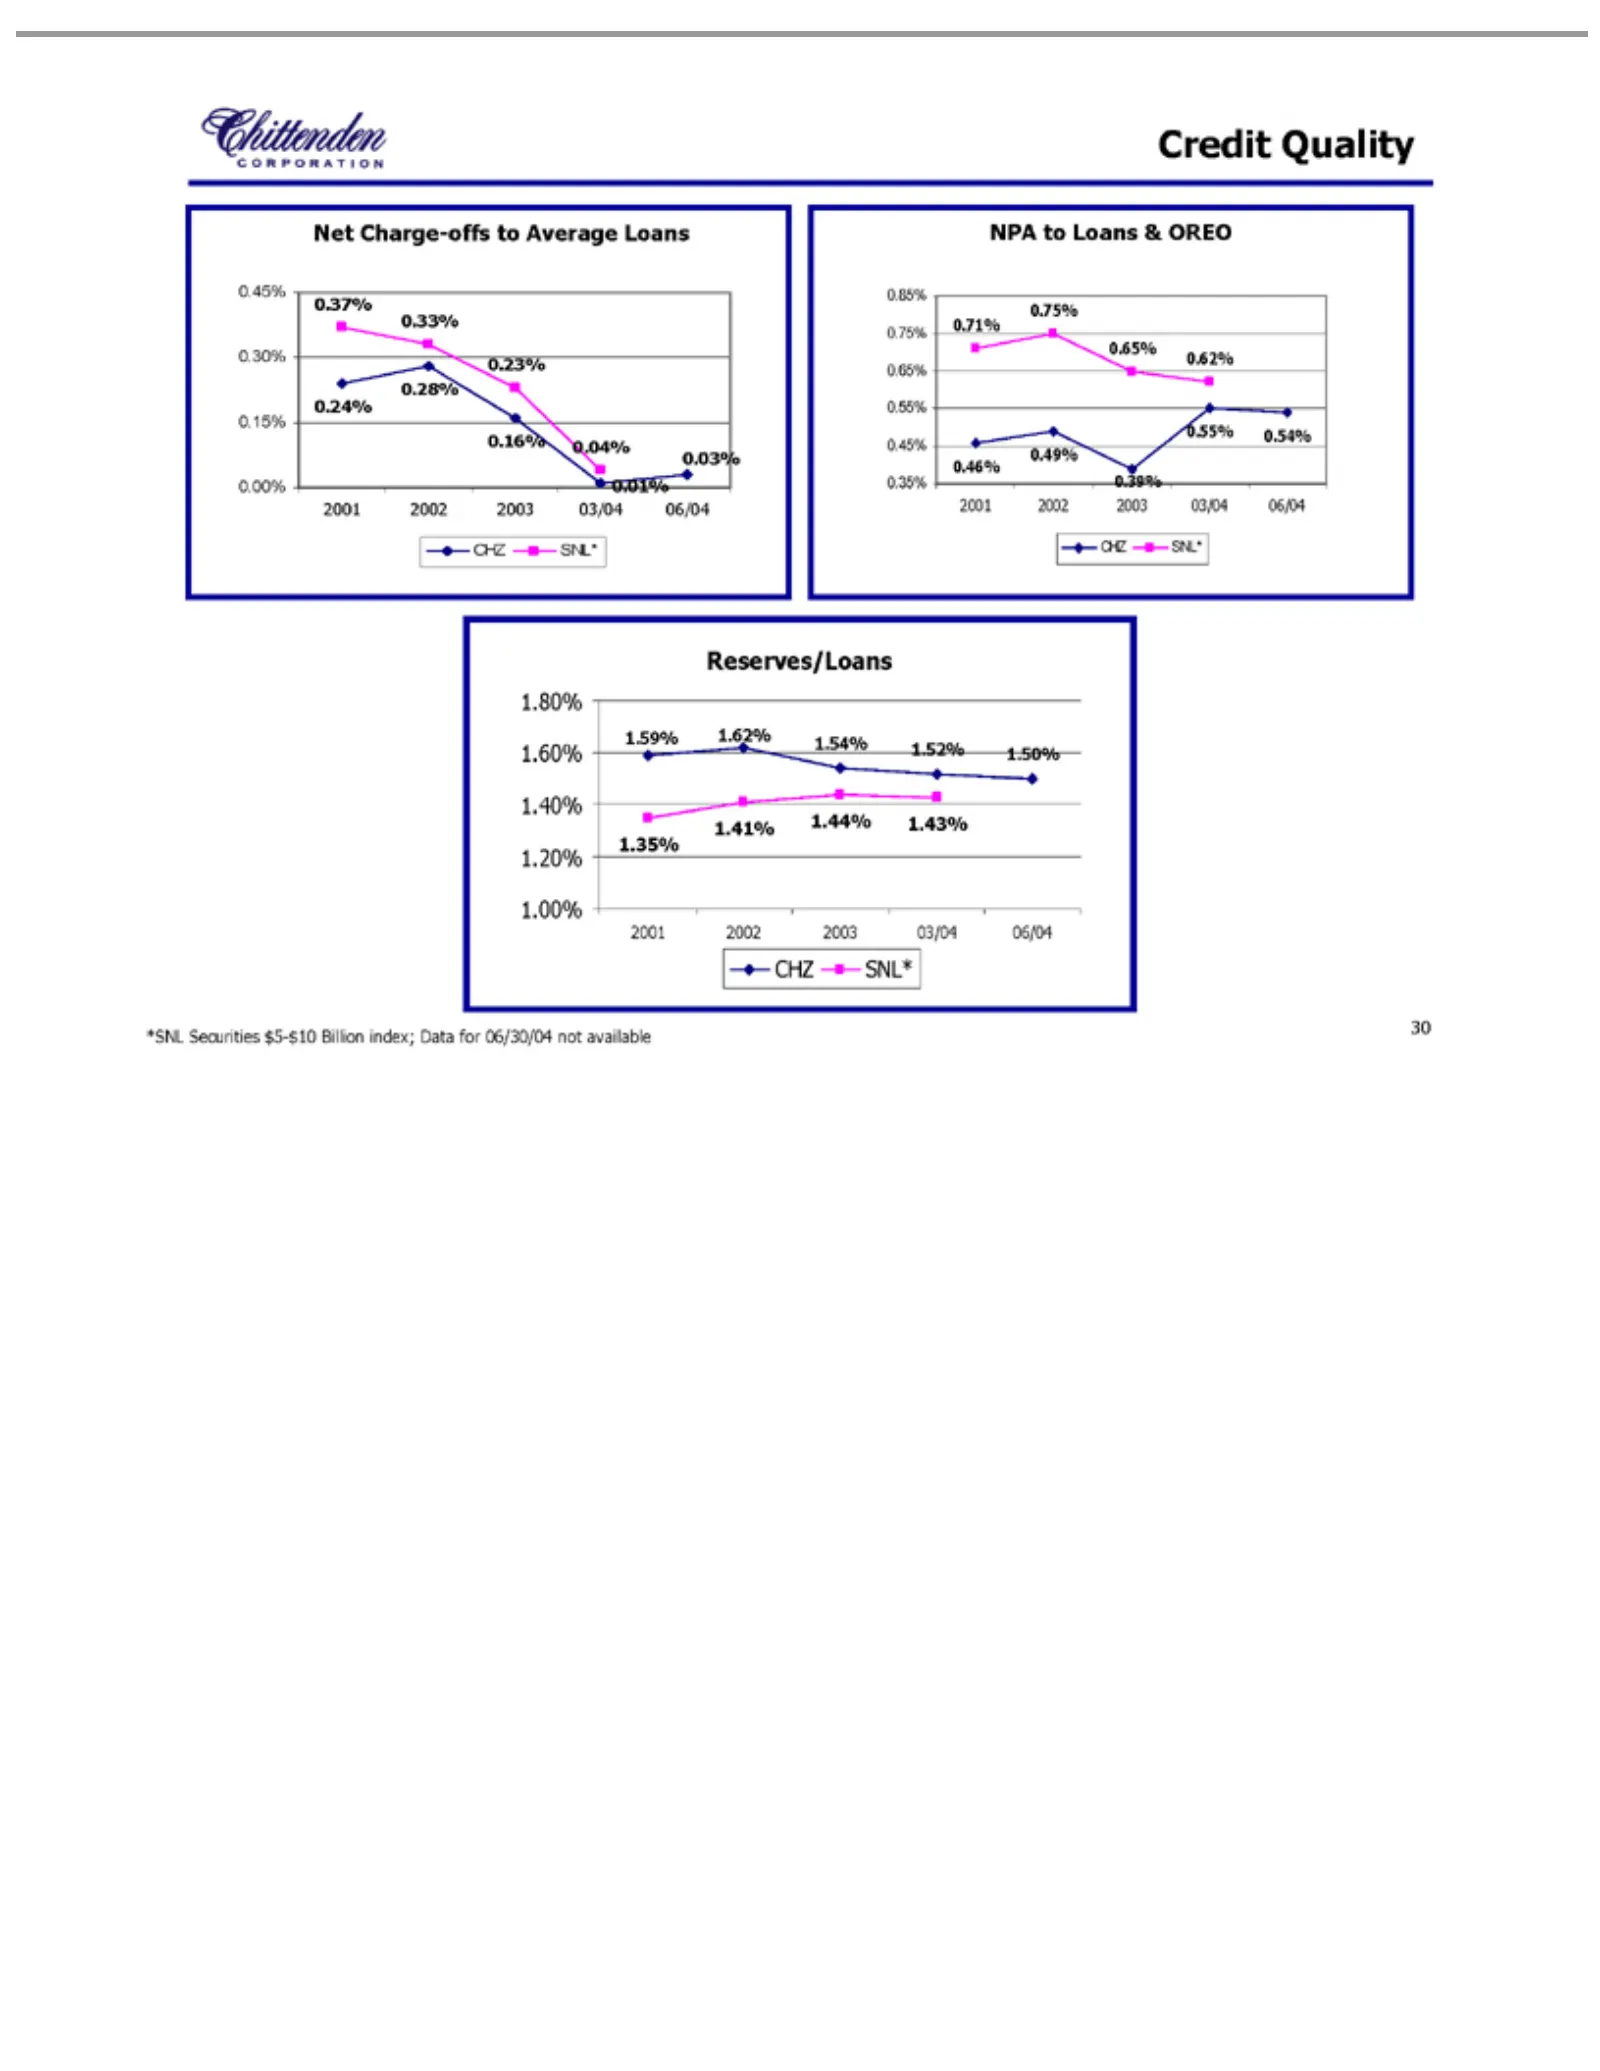
Slide 30: Credit Quality
Credit Net 0.45% 0.03% 0.01% 0.16% 0.28% 0.24% 0.04% 0.23% 0.33% 0.37% NPA 0.85% 0.54% 0.55% 0.39% 0.49% 0.46% 0.62% 0.65% 0.75% 0.71% 1.80% Reserves/Loans 1.20% 1.52% 1.54% 1.62% 1.59% 1.44% 1.41% 1.35% 2001 *SNL SNL* CHZ 30 Charge-offs to 2002 Securities Quality 0.30% 0.75% 1.60% 1.00% 1.50% 1.43%
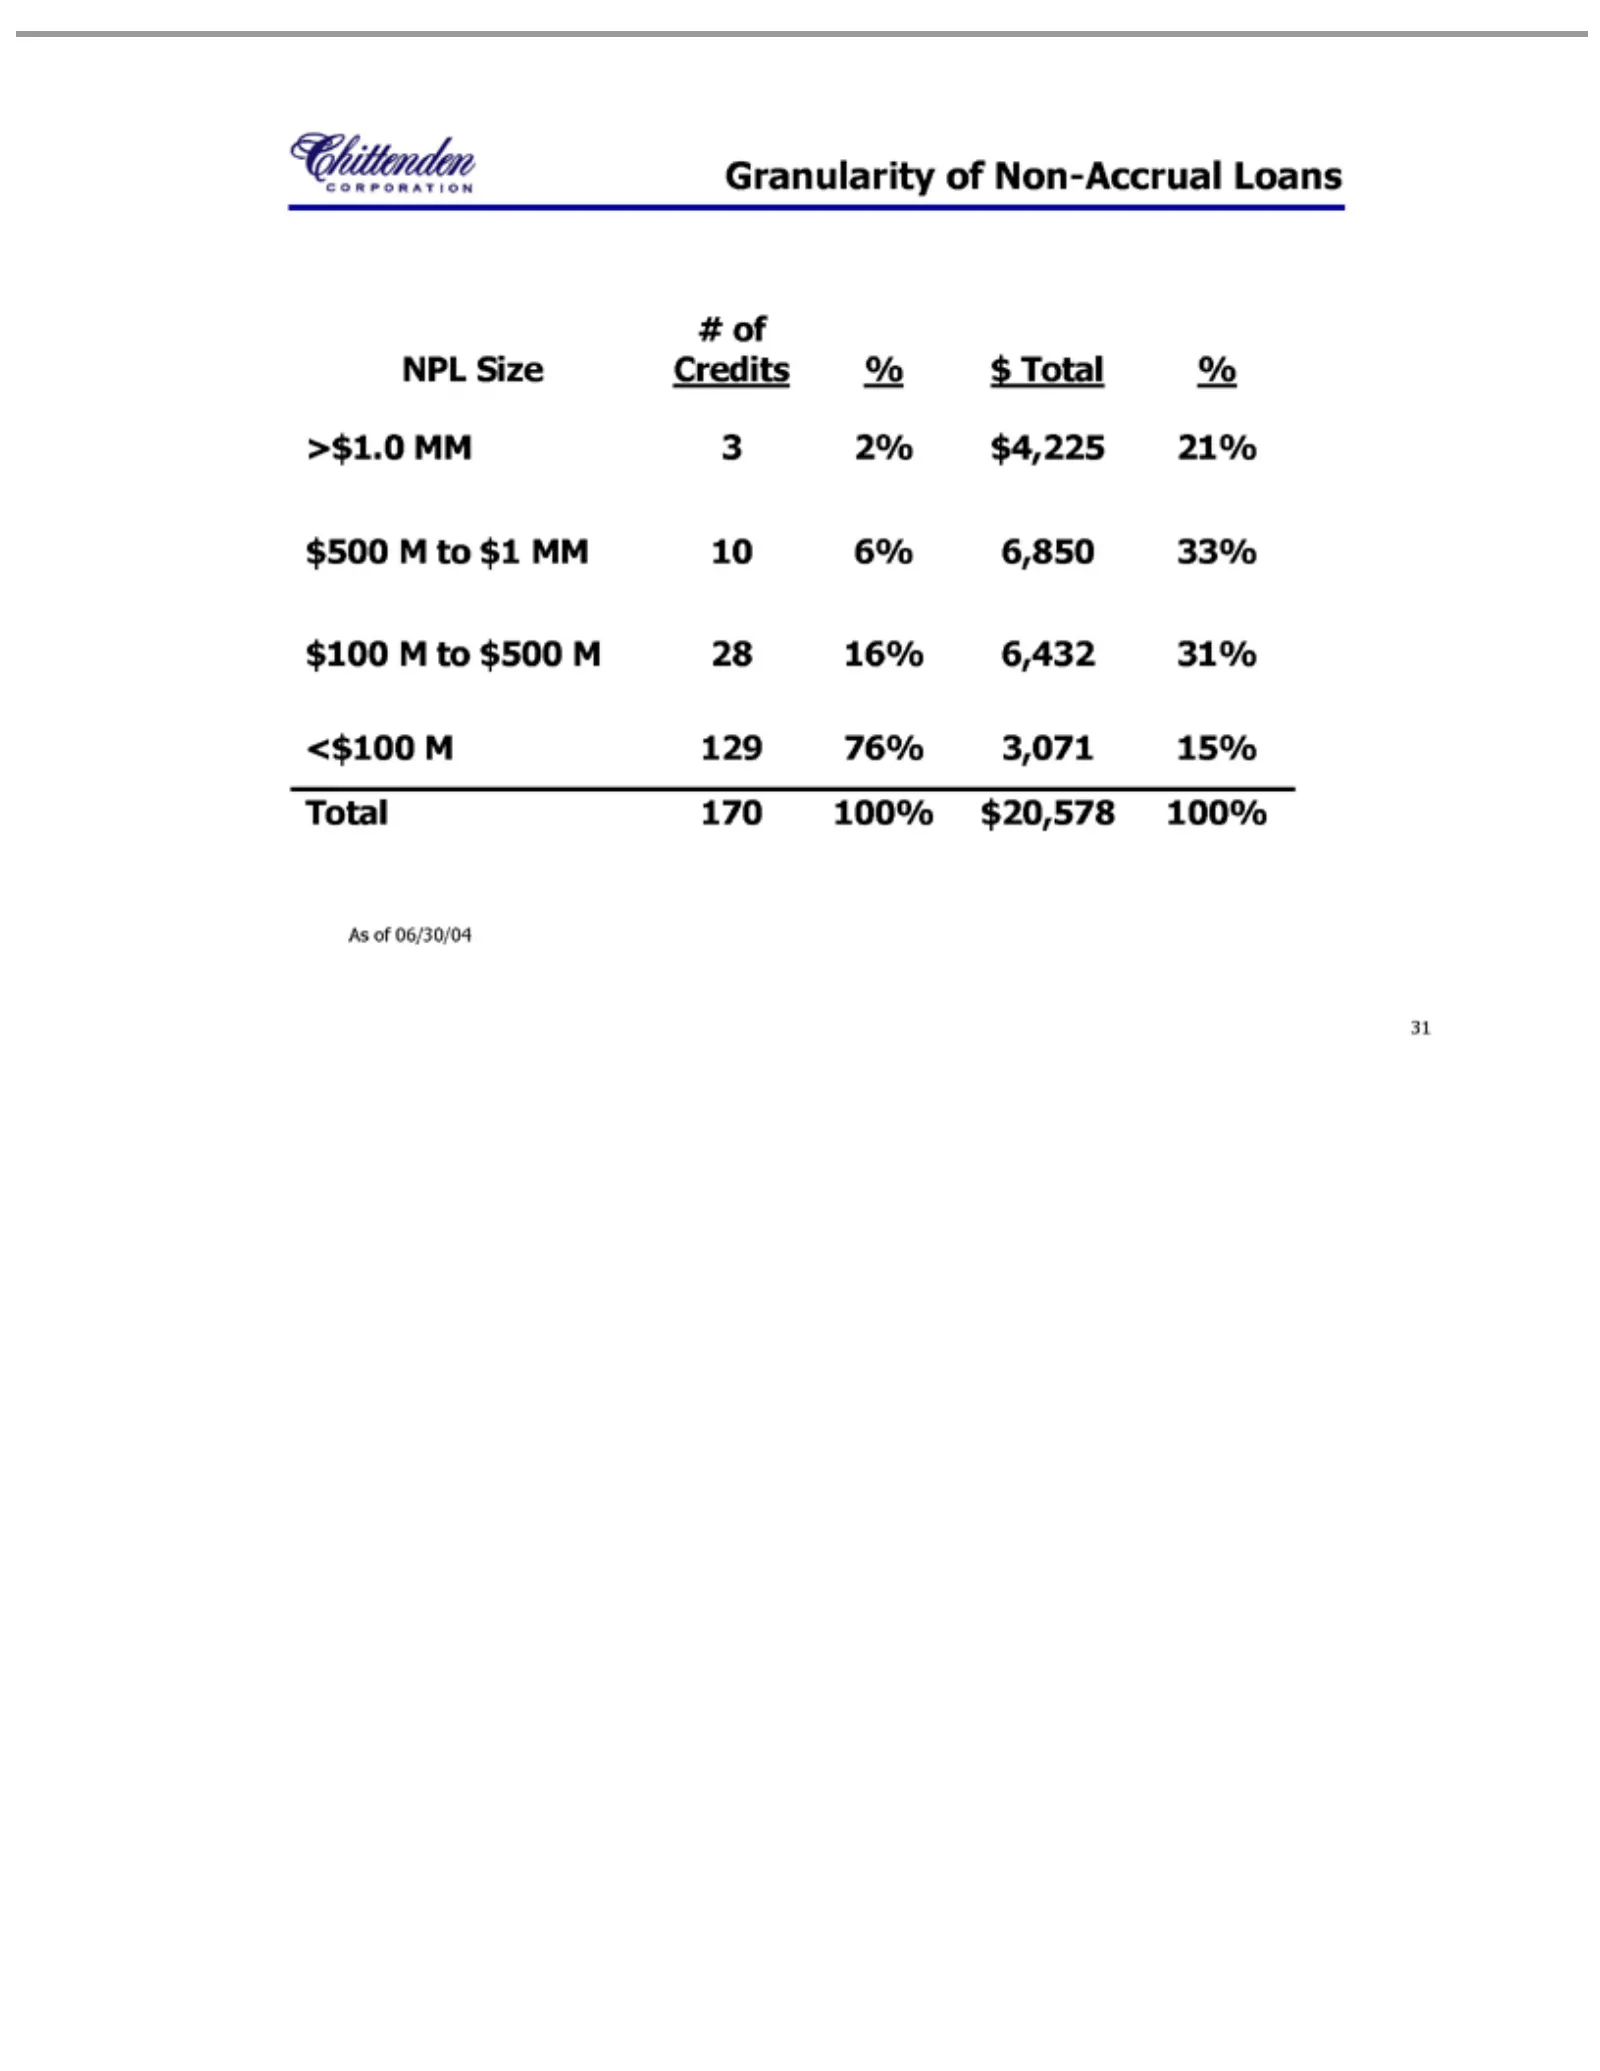
Slide 31: Granularity of Non-Performing Loans
Granularity NPL > $500 $100 < Total As 31$1.0 $100 ofSize M 170 06/30/04 MM M to100% #129 $1 $500 of 3 2% MM Credits Non-Accrual 76% $M$20,578 10 28 4,225 3,071 6% % 16% $100% 21% 6,850 15% 6,432 Loans 33% Total 31% %
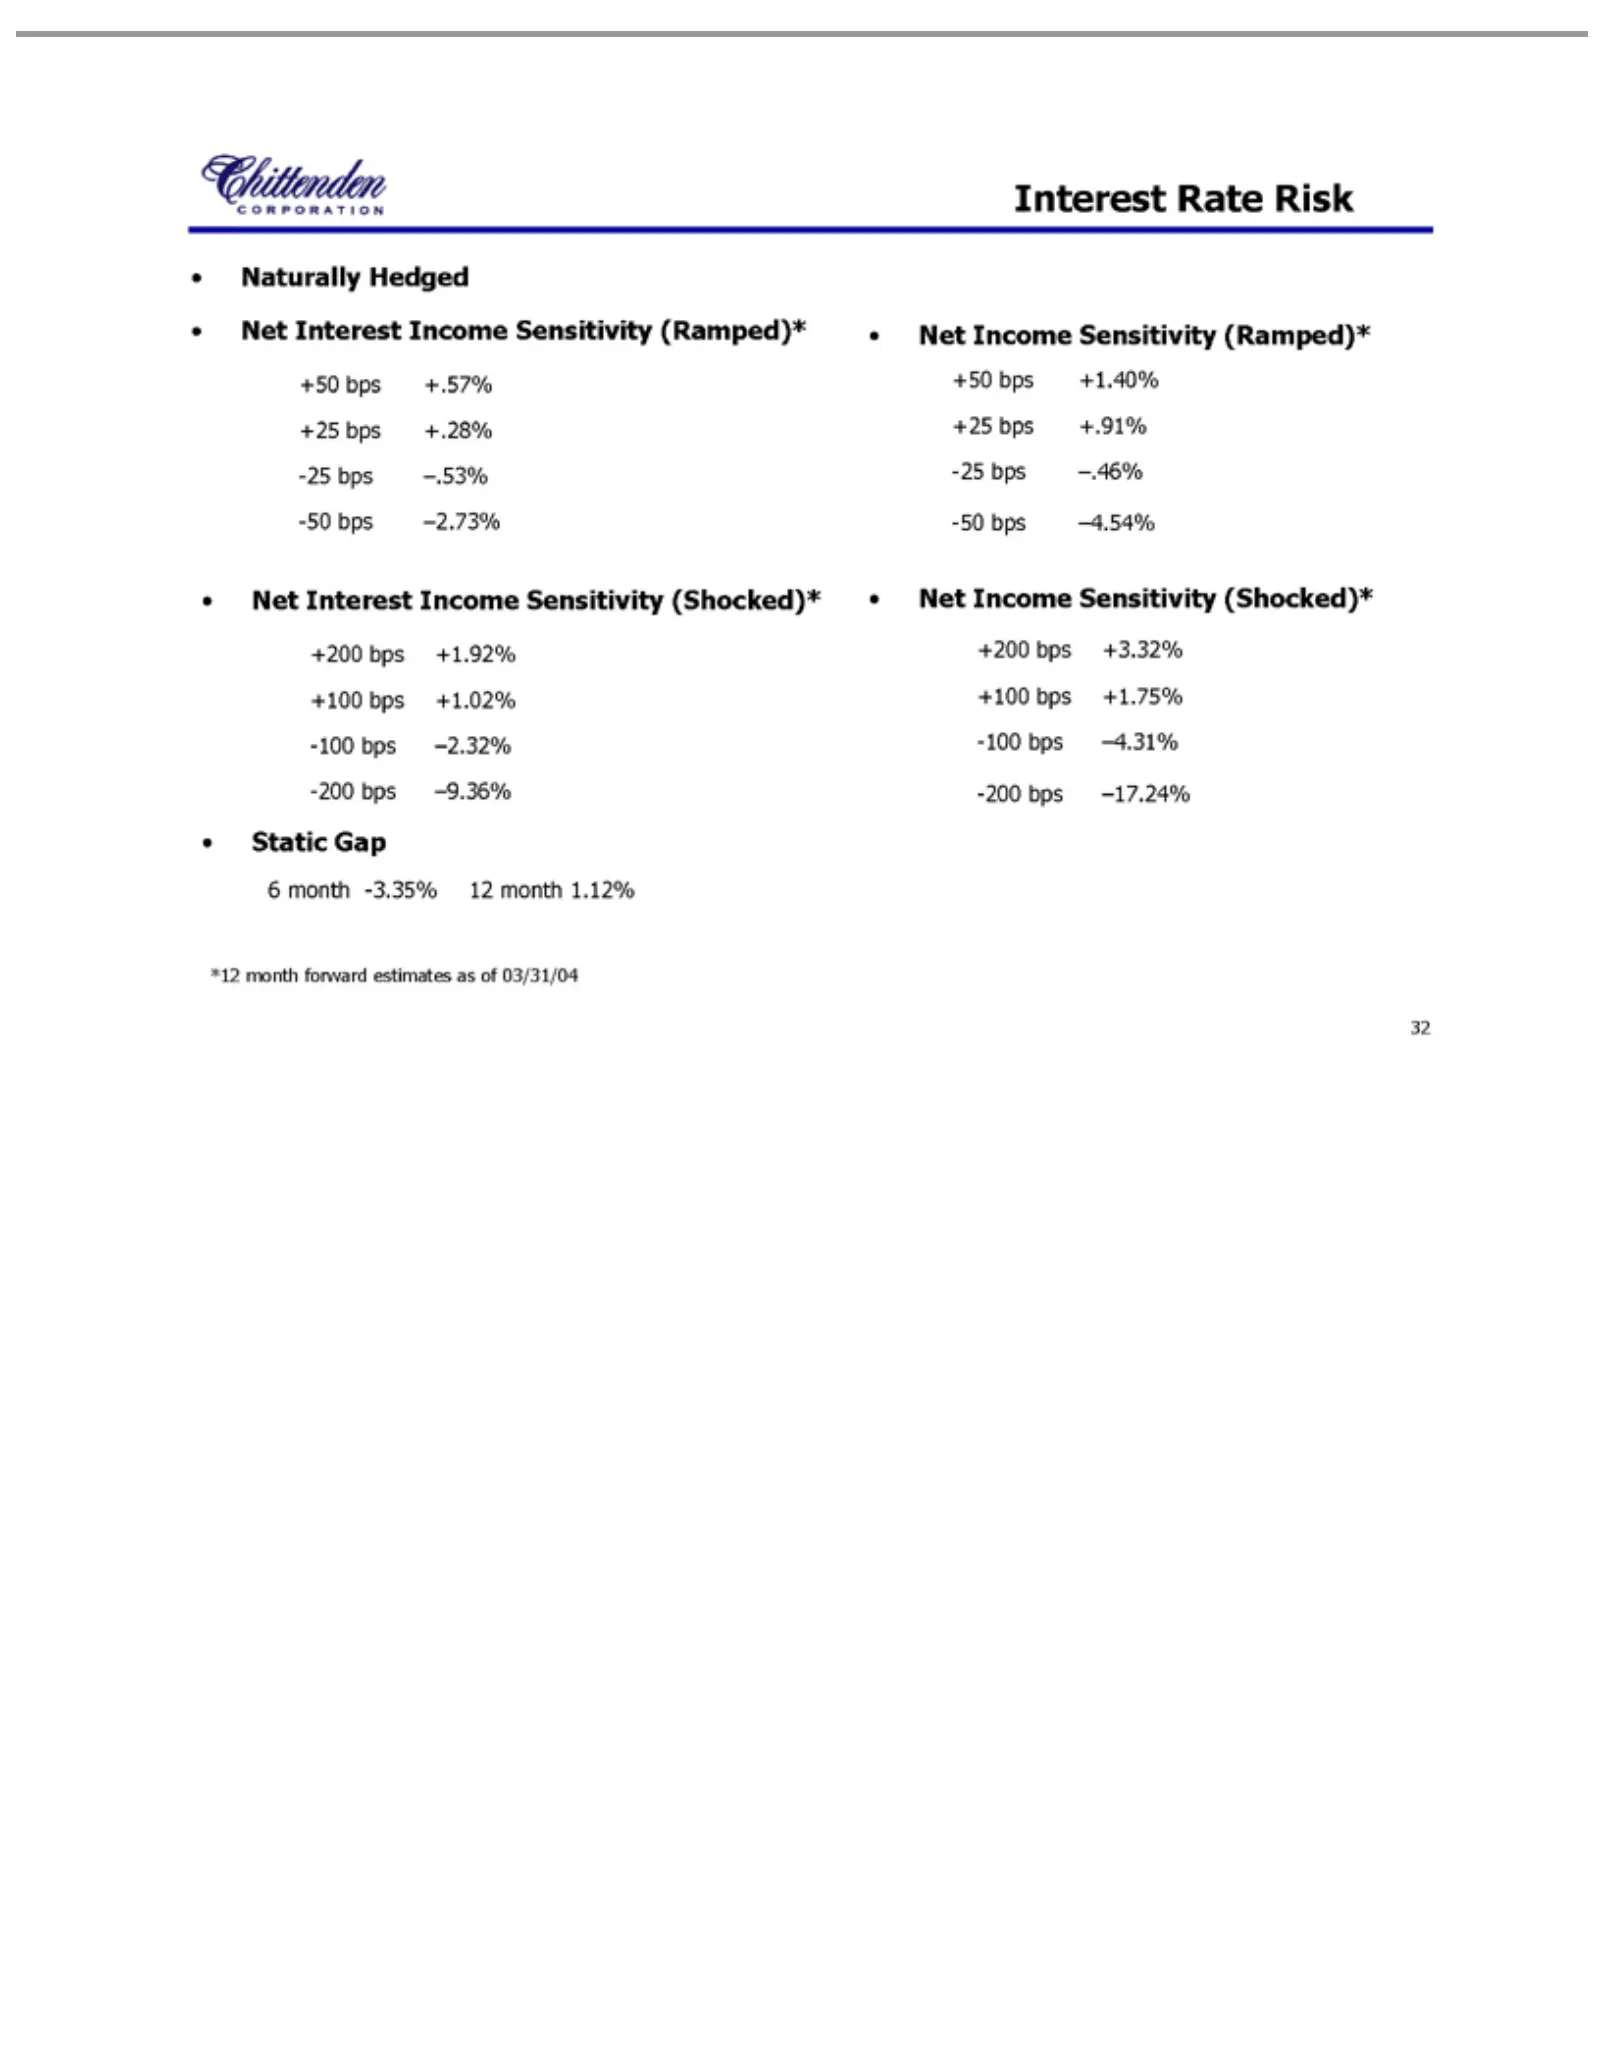
Slide 32: Interest Rate Risk and Sensitivity
Interest Naturally Static 6 +50 +25 -25 -50 Net +200 +100 -100 -200 *12 32month bps Interest Income month bps bps bps Gap –.53% –2.73% –.46% –4.54% Rate +.57% +.28% +1.40% +.91% -3.35% –2.32% –9.36% –4.31% –17.24% +1.92% +1.02% +3.32% +1.75% Hedged forward Income Sensitivity Risk12 estimates month S
Slide 33: In Summary
In Summary 33
Slide 34: A Compelling Story
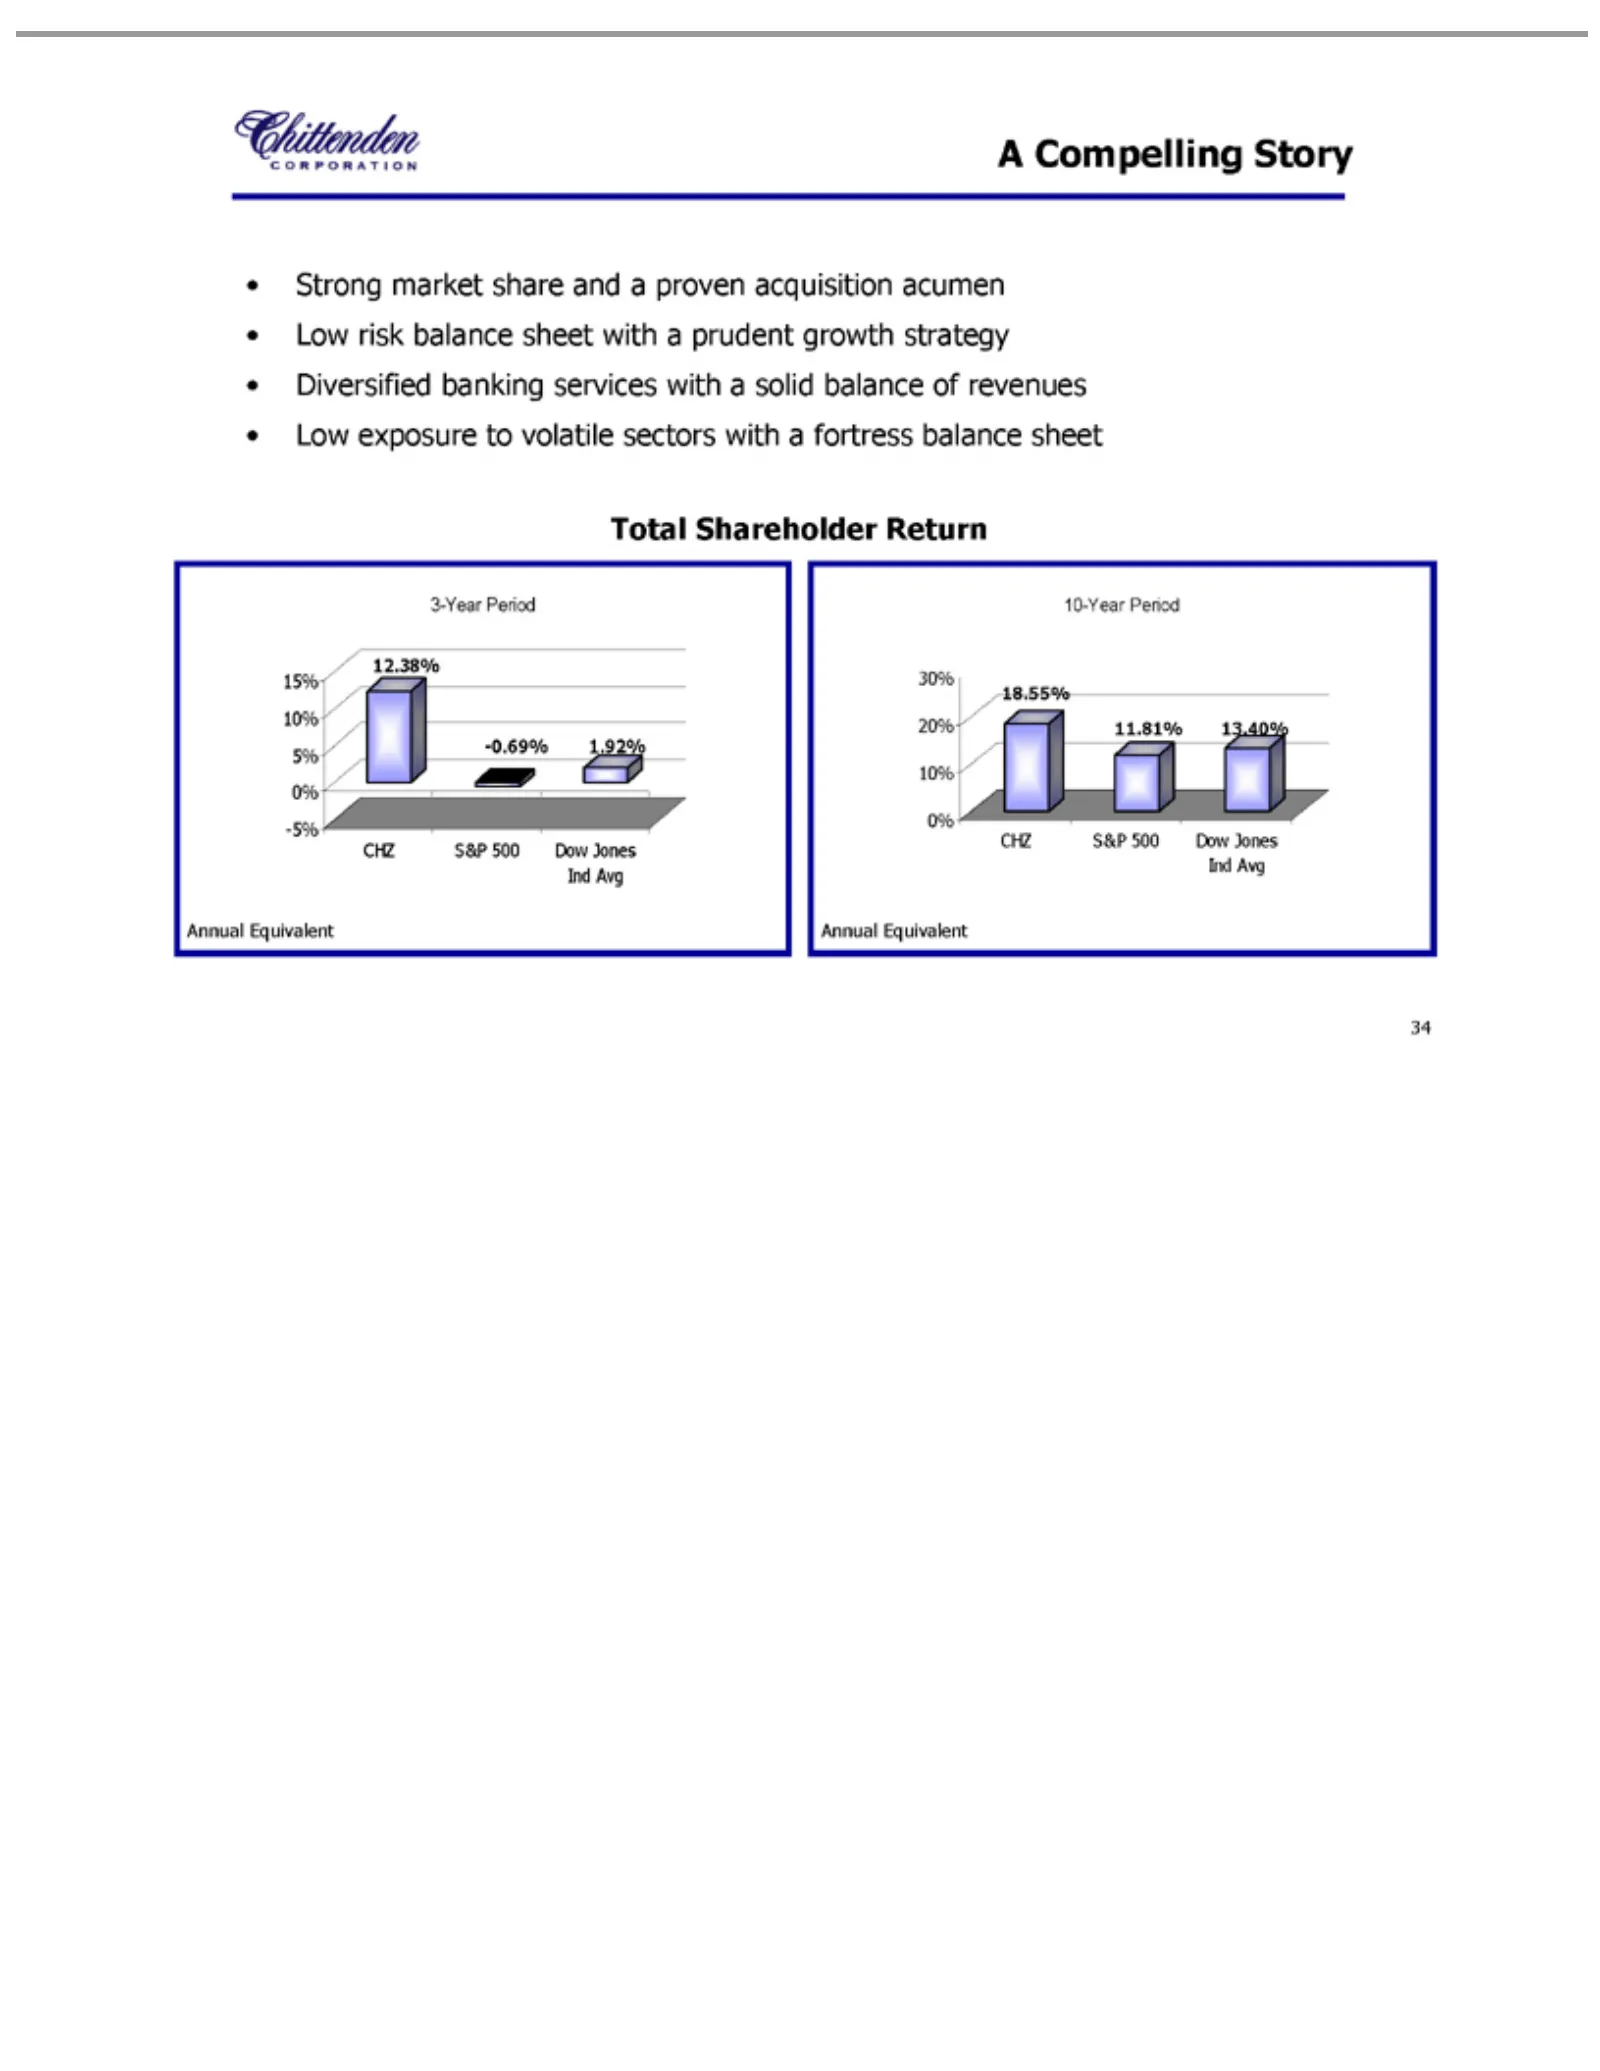
A Compelling Strong sectors Total 3-Year 15% 1.92% -0.69% 12.38% 10-Year 30% CHZ 13.40% 11.81% 18.55% Annual 34 10% 20% S&P Shareholder market Period with Equivalent Period 5% 10% 500 a fortress 0% Story share Dow 0%-5% Return Jones and balance a proven Ind Avg sheet acquisition acumen Low risk bala
Slide 35: Visit our website; forward-looking statements
Visit presentation other This which 35 our interactive arewebsite subjectservices: for contains to aa number wide www.chittendencorp.com “forward-looking range of factors of products, and statements” uncertainties latest financial which that reports could may describe cause and many future future re
Source: SEC EDGAR · 8-K filed Jul 28, 2004
More decks from Chittenden Corp
 Investor Presentation (September 2007)38 slides · Sep 7, 2007
 Merger or Acquisition (June 2007)27 slides · Jun 27, 2007
 Chittenden — Merger or Acquisition (June 2007)25 slides · Jun 27, 2007
 Merger or Acquisition (June 2007)9 slides · Jun 5, 2007
 Investor Presentation (May 2007)36 slides · May 14, 2007
 Investor Presentation (February 2007)37 slides · Feb 16, 2007