IPSCO — CIBC World Markets Institutional Investor Conference 2006
26 slides from IPSCO's conference presentation, Feb 16, 2006
Slide 1: IPSCO Inc. - CIBC World Markets Institutional Investor Conference
IPSCO Inc. CIBC World Markets Institutional Investor Conference February 16, 2006
Slide 2: Forward-looking information
Information contained in this document other than historical information, may be considered forward-looking. Forward-looking statements can be identified by the use of forward-looking words such as “believes,” “expects,” “may,” “will,” “should,” “seeks,” “approximately,” “intends,” “plans,” “estimat
Slide 3: IPSCO At A Glance
IPSCO At A Glance One of North America’s leading steel plate and pipe producers. IPSCO is a $4+ billion market capitalization stock, dual-listed as “IPS” on the NYSE and TSX. Uniquely positioned to capitalize on cyclical trends, employing a “steel short” strategy to optimize pricing, production and
Slide 4: Diverse Production And Geographic Footprint
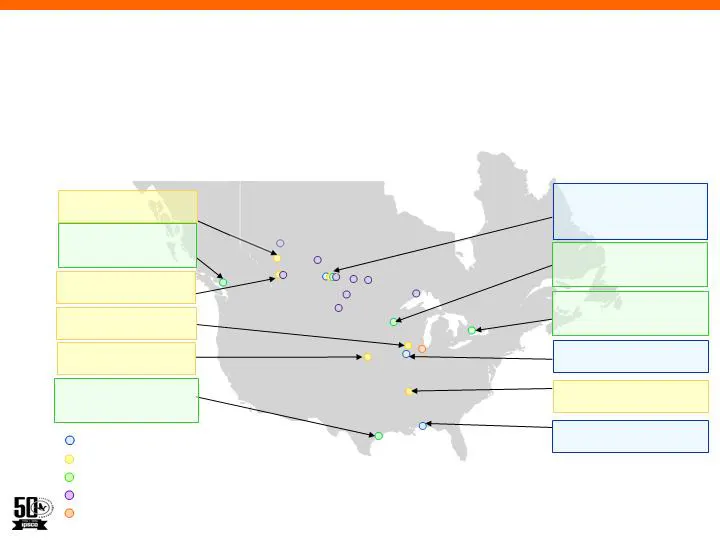
Thunder Bay Minot Dickinson Saskatoon Edmonton Lisle Winnipeg Brandon Surrey Calgary Red Deer Regina Geneva Montpelier Camanche St. Paul Toronto Houston Mobile Blytheville Note: Capacity in Tons Houston, Texas Temper Mill and Cut-to-Length Line 300,000 Geneva, Nebraska Pipe Mill 120,000 Camanche, Io
Slide 5: 2005 Sales Distribution
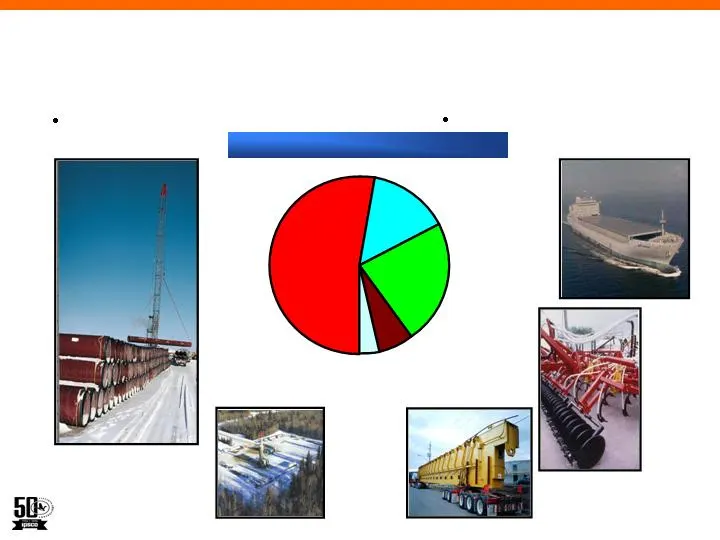
2005 Sales Distribution IPSCO’s Products Tubular Products Steel Mill Products Energy Tubulars 22% Cut-to-Length 15% Discrete Plate Coil 54% Large Diameter Tubulars 2% Non-Energy Tubulars 6%
Slide 6: Sales Distribution by End Markets
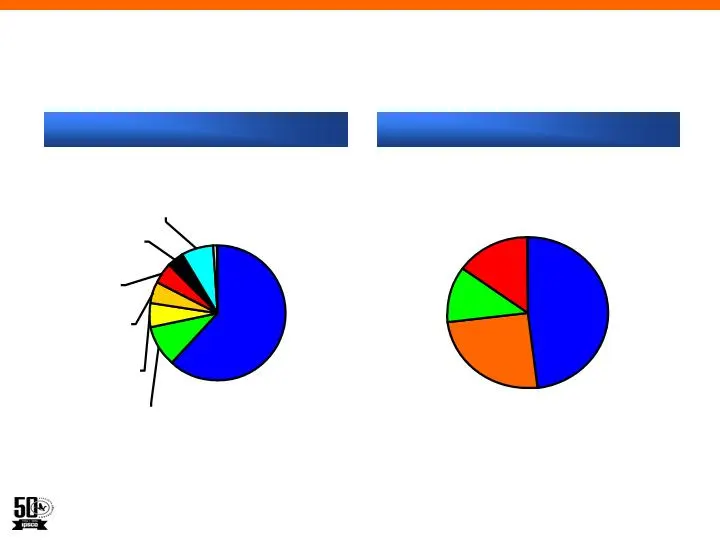
2005 All Products 2005 Steel Mill Products Sales Distribution by End Markets Oil & Gas Industry 5% Construction Products 5% Machinery & Industrial Equipment 6% Pipe & Tube Manufacturing 10% Rail Transportation 4% Shipbuilding/ Marine Equipment 7% Service Centers/ Distributors 62% Other 1% Energy 48%
Slide 7: IPSCO's Energy Exposure
IPSCO’s Energy Exposure IPSCO is leveraged to the energy sector through multiple channels: Direct exposure through pipe business Exploration and development - OCTG Gathering and distribution – line pipe Transmission – large diameter line pipe Direct exposure through plate to energy fabricators Wind
Slide 8: Top Plate Producer in North America
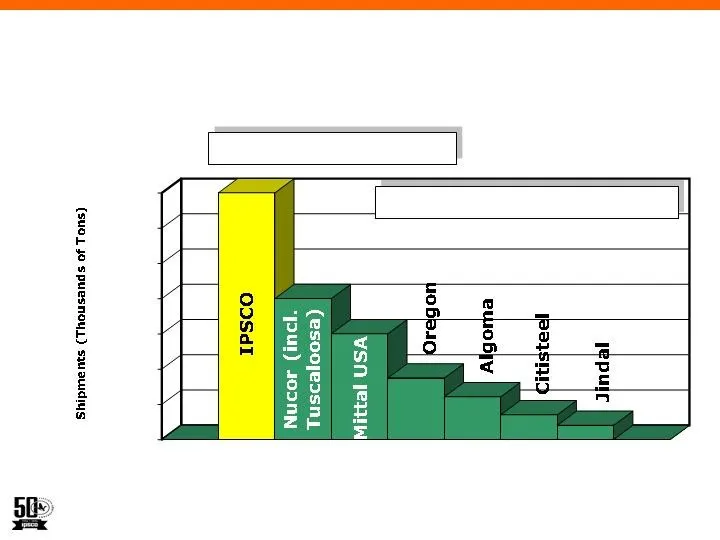
Source: Estimated from Company filings & First River Top Plate Producer in North America Full Year 2004 Oregon/Jindal = No/partial melt Top 3 > 75% of shipments Note: Includes Plate in Coil Form Source: Estimated from Company filings & First River 1,000 1,500 2,000 2,500 3,000 3,500
Slide 9: Plate Consumers – Late-Cycle Performers
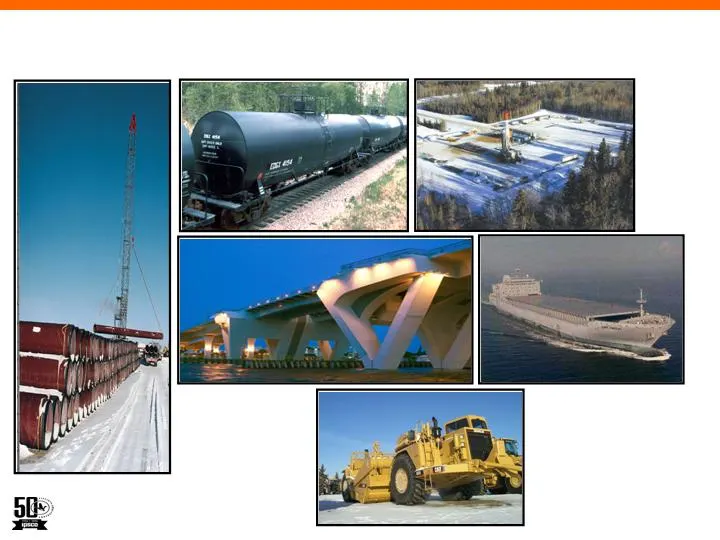
Plate Consumers – Late-Cycle Performers
Slide 10: Plate Production is Cost Competitive Globally
Plate Production is Cost Competitive Globally IPSCO utilizes latest technology North America mills relative to other nations have availability and cost advantage to scrap Man-hours per ton are best-in-class
Slide 11: Growth Driver: Expansion of Value Add Plate Products
Growth Driver: Expansion of Value Add Plate Products Normalized Plate Quench Temper Plate Heavier Gauge Plate Higher Strength As Rolled Plate Blast & Painted Plate
Slide 12: Strong Position in North American Tubes
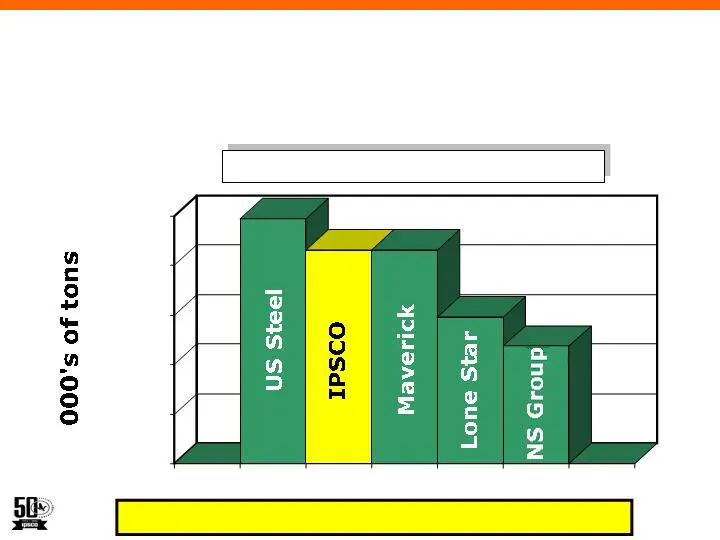
Strong Position in North American Tubes Top 3 > 40% of North American Capacity Energy tubulars represent 80% of tubular shipments 1,000 2004 Energy Tubular Shipments
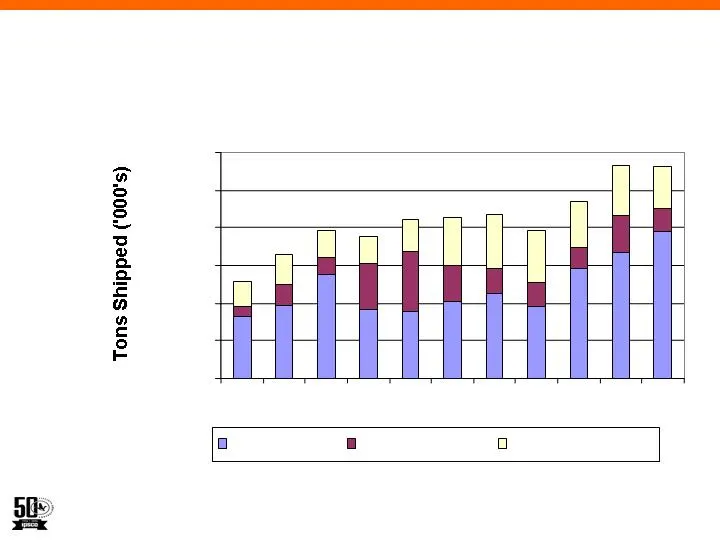
Slide 13: Tubular Shipments
Tubular Shipments - 200.0 400.0 600.0 800.0 1,000.0 1,200.0 Energy Tubulars LD Energy Tubulars Non-Energy Tubulars
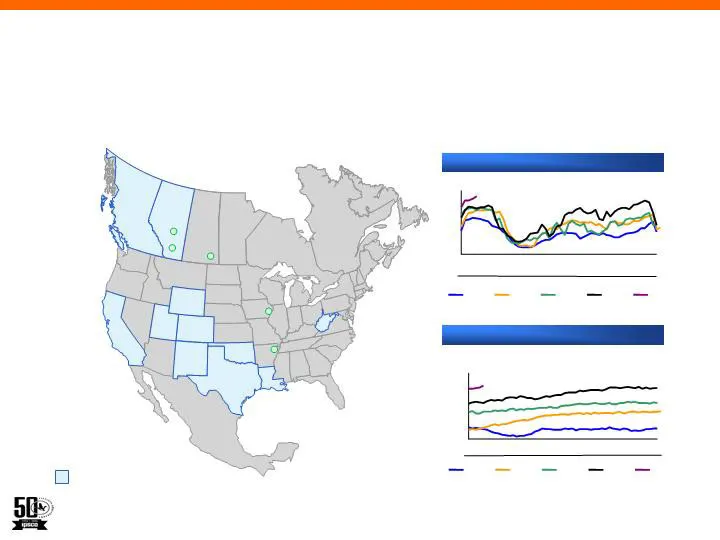
Slide 14: Growth Driver: Energy Tubular
Rig Count – Canada Rig Count – US Growth Driver: Energy Tubular Regina Red Deer Camanche Calgary Blytheville = High drilling activity areas High natural gas prices are expected to drive higher rig counts, which in turn will drive consumption of energy tubulars Source – Baker Hughes 1,100 1,300 1,500
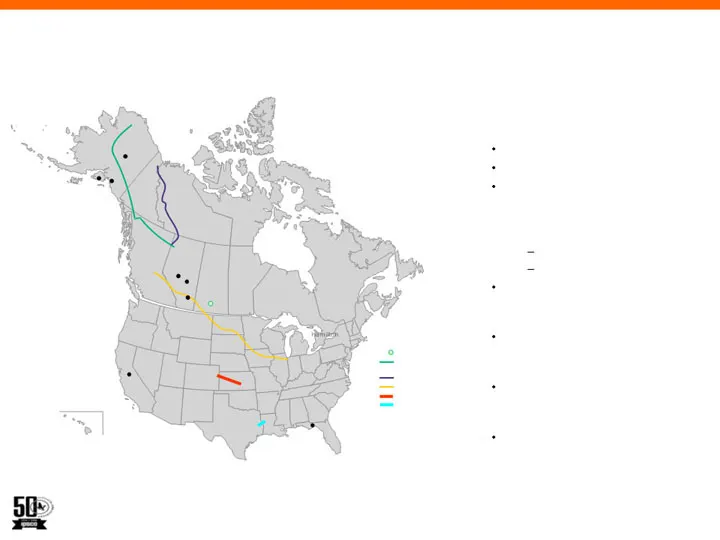
Slide 15: Growth Driver: Large Diameter Pipe
Growth Driver: Large Diameter Pipe Drivers Project-based orders Gaining market share Need for large pipelines to bring natural gas from Alaska and Northern Canada to markets Mackenzie Pipeline Alaska Pipeline Expanding core competency with Frontier Pipe Research Unit Production facilities located to
Slide 16: The Outlook For IPSCO's Pipe Is Strong
The Outlook For IPSCO’s Pipe Is Strong High energy prices driving hydrocarbon exploration, development, transportation together with the development of alternative energy sources Exploration and development drilling (OCTG) is at a high level Steel intensive oil sands development Numerous large diame
Slide 17: Full Year 2005
Full Year 2005 Operating Performance +38 $8.69 $11.96 Diluted EPS +29 Net Income +43 Income Before Tax +36 Operating Income +20 $2,531 $3,033 Sales B/(W) % Chg. Fourth consecutive record year of sales and production Record operating profit per ton of $259 Record full year earnings Record coil and pl
Slide 18: Industry-Leading Profitability
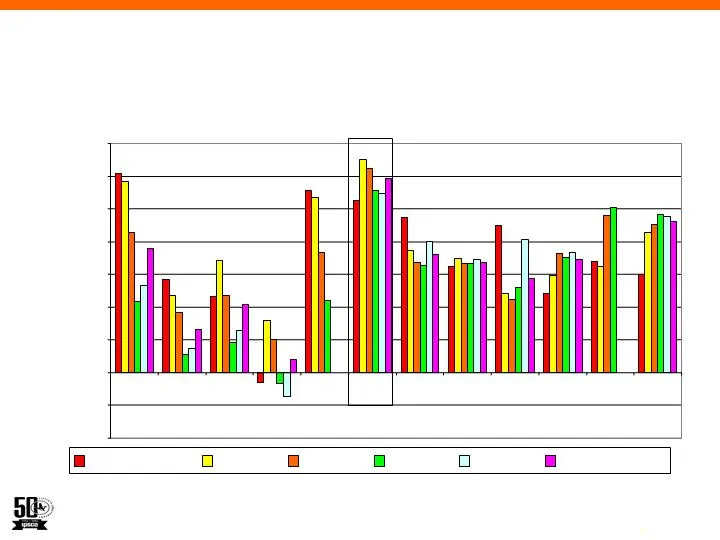
Industry-Leading Profitability * Full Year 2004, Q4 2005 and Full Year 2005 Include Benefit Corridor and other charges Operating Income % to Sales -10.0% -5.0% 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% 30.0% 35.0% Algoma Dofasco U.S. Steel AK Mittal IPSCO Steel Dynamics Nucor Maverick LoneStar NS Group Gran
Slide 19: Industry-Leading Profitability: Operating income per ton
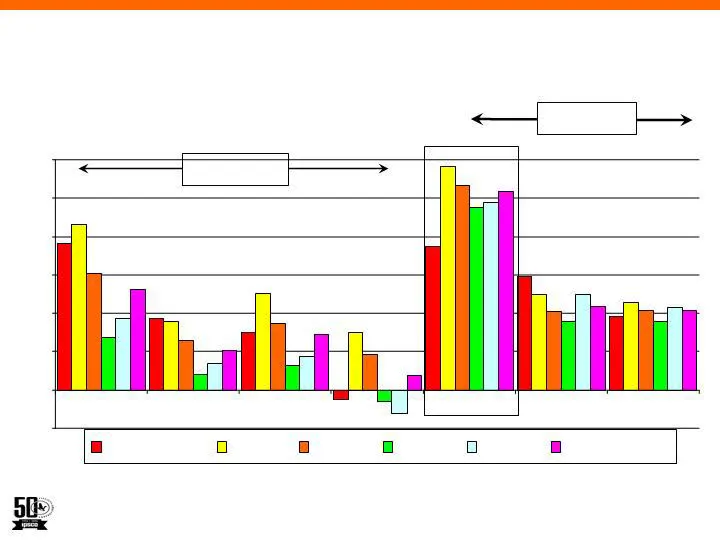
* Full Year 2004, Q4 2005 and Full Year 2005 Include Benefit Corridor and other charges Integrated Mini-mills Industry-Leading Profitability Operating income per ton -$50 $0 $50 $100 $150 $200 $250 $300 Algoma Dofasco U.S. Steel AK * IPSCO Steel Dynamics Nucor Full Year 2004 Q1 2005 Q2 2005 Q3 2005
Slide 20: Employee Incentives Aligned with Shareholder Interest
Employee Incentives Aligned with Shareholder Interest Incentives based on productivity, safety, and/or corporate profitability All Other Employees Rewarded for achieving Budget Goals and Return on Equity Key Managers Rewarded for Return on Capital and Performance Relative to Peers Senior Officers
Slide 21: Growth Strategy: Strategic Capital Expenditures
Growth Strategy: Strategic Capital Expenditures Increase Heat Treating Capabilities – Expanding production capacities in higher value heat treat, quench and tempered pipe in Calgary, Alberta and plate in Mobile, Alabama Eliminate Bottlenecks – Rebalancing processes and executing Six Sigma programs w
Slide 22: Outlook
Outlook Believe end-user demand for steel mill products will remain relatively stable in 2006 Expect high oil and gas prices will continue to drive high rig counts and demand for OCTG products Expect spiral pipe mill will run at near capacity throughout 2006 Anticipate that higher costs of steel mak
Slide 23: Conclusion
Conclusion IPSCO: Is Globally Competitive on cost and quality Has Significant Market Share in the plate and pipe markets it serves with complimentary product lines Leads in New Technologies necessary to make value- added steel and energy pipe for the oil & gas industry Employs a “ Steel Short ” stra
Slide 24: Thank You
Thank You
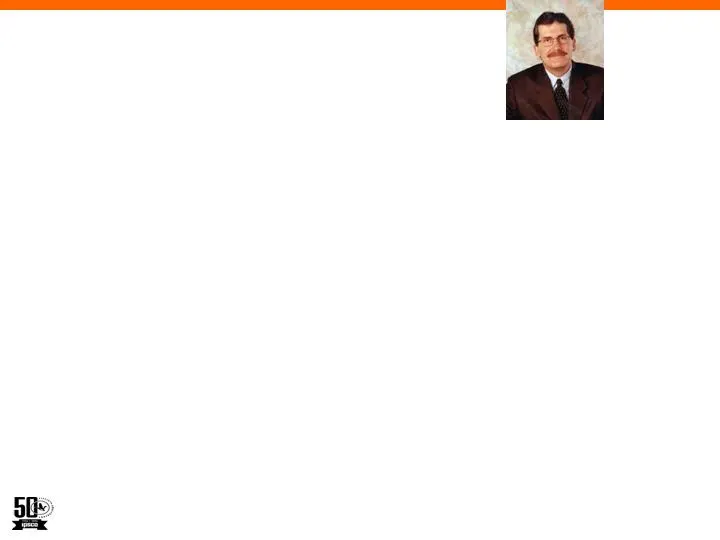
Slide 25: David Sutherland
David Sutherland President and Chief Executive Officer Dave Sutherland has been President and CEO of IPSCO Inc. since January, 2002. He joined IPSCO in 1977. Early in his career he held senior managerial positions in the staff areas of Employee and Industrial Relations in Regina. In April, 2000 Suth
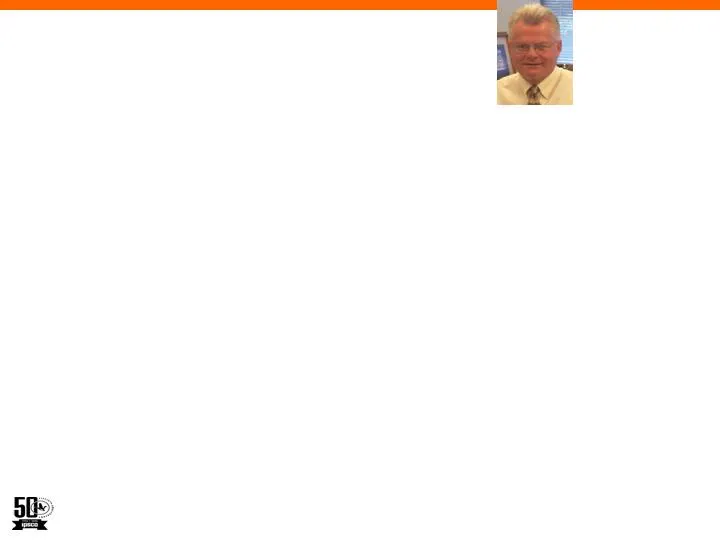
Slide 26: Thomas Filstrup
Thomas Filstrup Director of Investor Relations Mr. Filstrup joined IPSCO in August 2005 after more than 20 years of investor relations and financial experience with Whirlpool Corporation, where he was most recently Director, Investor Relations. Mr. Filstrup joined Whirlpool at its corporate headquar
Source: SEC EDGAR · 8-K filed Feb 16, 2006