Essex Rental — Investor Presentation (December 2008)
29 slides from Essex Rental's investor presentation, Dec 11, 2008
Slide 1: Essex Rental Corp
Essex Rental Corp
Slide 2: ‘This cocumant dows na constitute an ofer'o slr a solitaton ofan afer to buy
‘This cocumant dows na constitute an ofer'o slr a solitaton ofan afer to buy any secures. Ht anti of mates for cussion only. Te lovin orxetton consis sateen, sinatsjrecass and pons wih ape re prema and Foe ee ete eee SOUS ers Sar wih ed sects Assia gale han ta fall care, Bees tte OStprand a ason car
Slide 3: Definitions
Definitions ‘= OLY: Orderly Liquidation Value as assessed by independent specialist equipment appraisers on December 31, 2007 ‘= Replacement Value: The cost required to replicate the current aggregate lifting tonnage of Essex’ fleet vith crawlers being produced today = CAGR: Compound Annual Growth R
Slide 4: Introduction
Introduction STRICTLY CONFIDENTIAL | 4
Slide 5: Essex owns one of the largest rental fleets of heavy lift crawler cranes
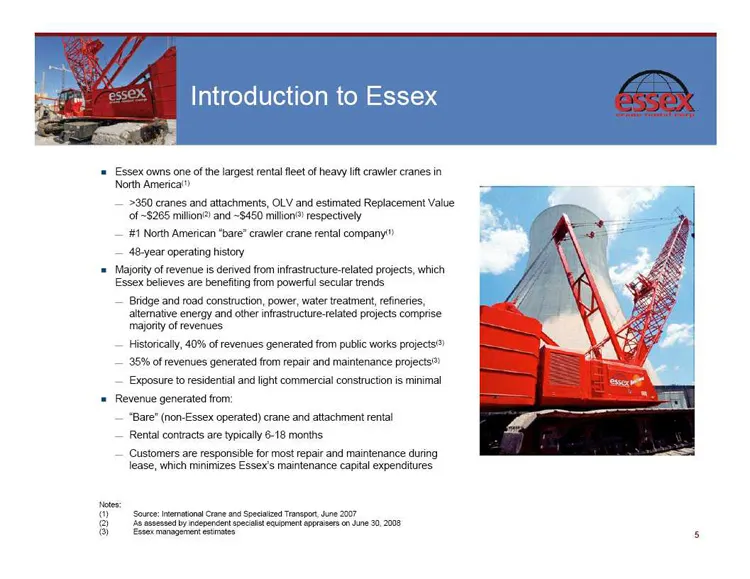
‘= Essex owns one ofthe largest rental fleet of heavy lit crawler cranes in North America >350 cranes and attachments, OLV and estimated Replacement Value of ~$265 milion and ~$450 milion®) respectively #1 North American “bare” crawler erane rental company 48-year operating history ‘= Majonty of rev
Slide 6: Strong long-term secular trend
‘Strong long-term secular trend ‘= Over 90% of revenue generated from infrastructurerelated projects 1 Infrastructure sector demand projected to grow at a 4% CAGR through 2015: ‘= Worldwide infrastructure and industrial investment growth is expected to be an indirect driver affecting crawler availab
Slide 7: Predictable earnings stream with strong free cash flow
Predictable eamings stream with strong free cash flow {As of 6/30/08, sufficient bookings in hand to support full year 2008 rental revenue projections 1 Based on the nine months ended September 30, 2008, management is raising its full year 2008 Rental EBITDA guidance to approximately $411 million 3-
Slide 8: Equipment Rental Revenue and Total EBITDA
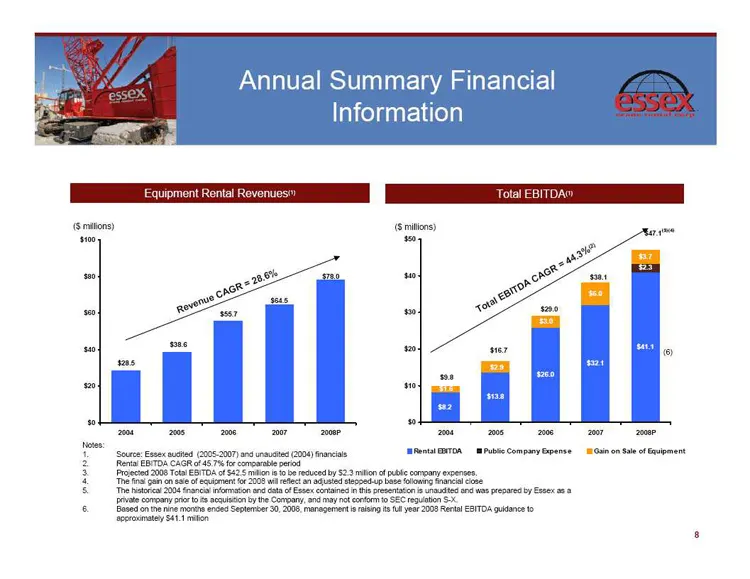
Equipment Rental Revenu Total EBITDA® (Srations) (srniens) 3 Proved 2008 Tota EST be reed by $2 3 mono pb canary expenses. x i oy auaed seca poe ioe real ne Bod on be ne mon ened Septen2 5,08 rarer song ot 208 Reta ESITOS gutaneeo
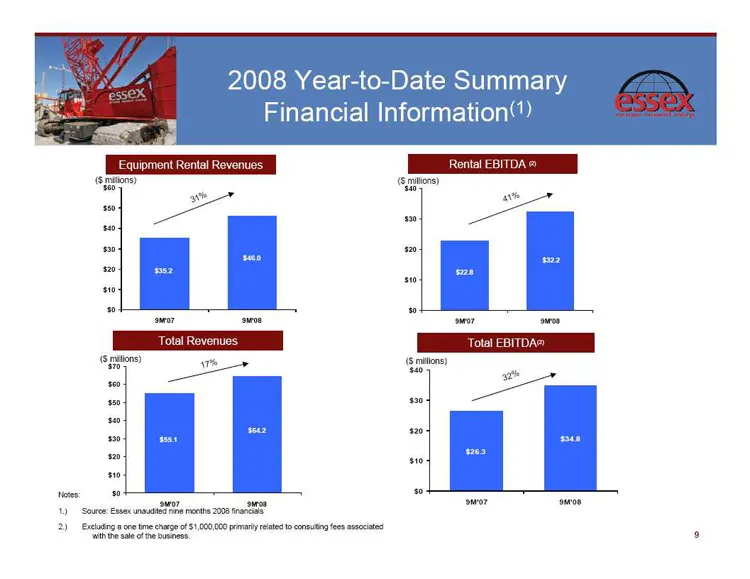
Slide 9: 2008 Year-to-Date Summary Financial Information
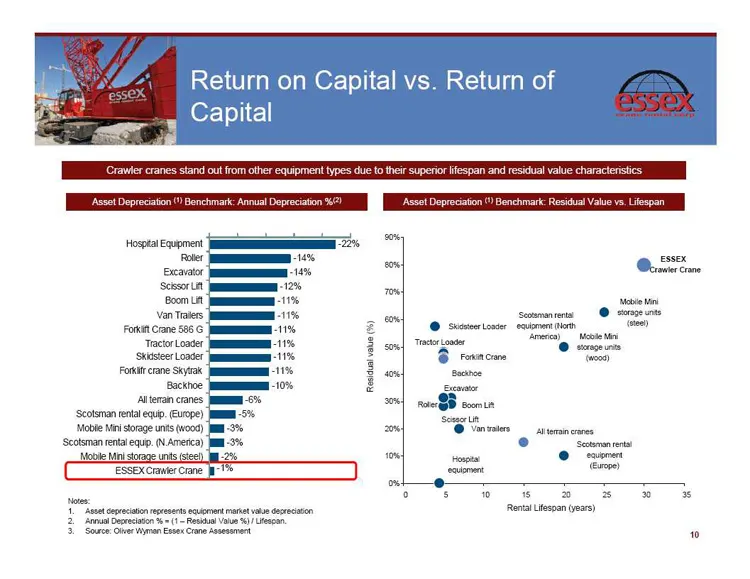
Slide 10: Equipment useful life and value comparison
Hosptal Equpment ober Beavator Seesoruet Boom Let Van Tales Foran Crane 566.6 Tractor Loader sxisteer Loader Far crane Sky ‘ackhoe ‘Atteran cranes ‘Scotsman rental equ. Europe) Mobi Mi strage uns (wood) ‘Scotsman rental equp.(N America) nts sce “aval ceca epeserts equate ae etecnn ental essan (years
Slide 11: Heavy Crane Rental Industry
Heavy Crane Rental Industry STRICTLY CONFIDENTIAL | 11
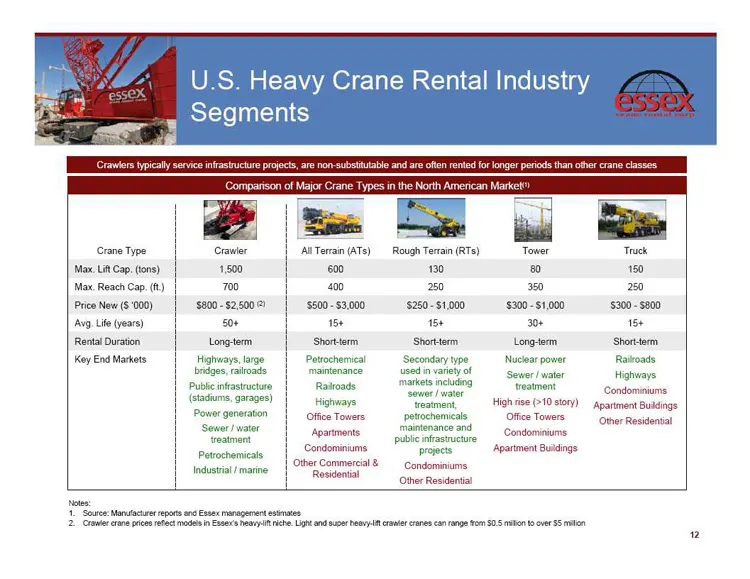
Slide 12: Crane types and end markets
‘See crane Type Craw A Terrain (ATS) Max. Lit Cap. (ons) 1.500 600 Max, Reach Cap. (f) 700 400 Price New ($000) $800 - $2,500 ‘00 - $3,000 ‘Avg. Life (years) 50+ 15+ Renta Duration Key End Markets Highways, age bdges, airoads Ratioads Highways Offce Towers Public inkastveture (stadiums, garages) See
Slide 13: Demand exceeds supply
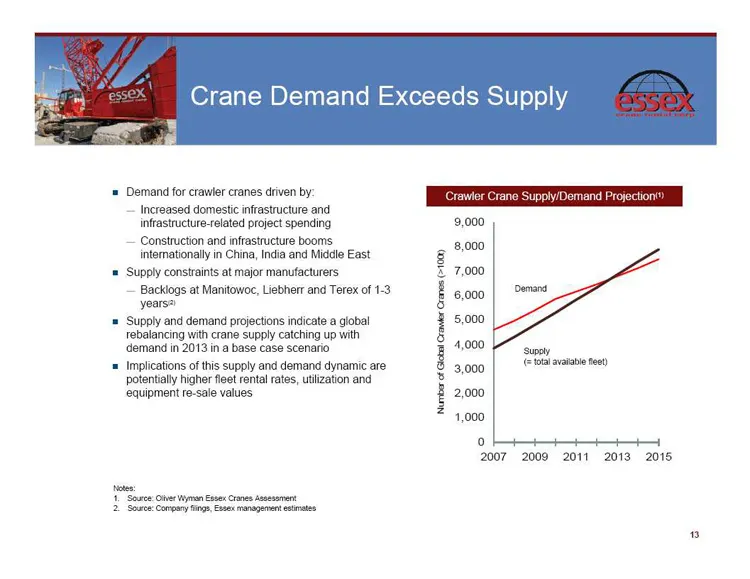
ine Demand Exceeds Supply ‘= Demand for crawler cranes driven by: — Increased domestic infrastructure and infrastructure-related project spending — Construction and infrastructure booms intemationally in China, India and Middle East ‘= Supply constraints at major manufacturers — Backlogs at Manitowo
Slide 14: Essex's end markets benefit from favorable demand drivers
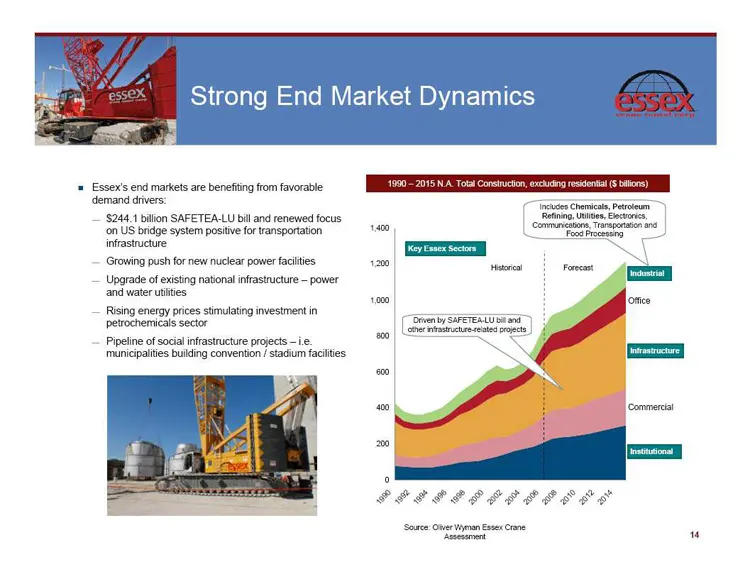
1» Essex’s end markets are benefiting from favorable demand drivers: $244.1 bilion SAFETEA-LU bill and renewed focus ‘on US bridge system positive for transportation infrastructure Growing push for new nuclear power facities Upgrade of existing national infrastructure - power and water utilities Ris
Slide 15: Company Overview
Company Overview STRICTLY CONFIDENTIAL | 15
Slide 16: Simple business model: bare rentals
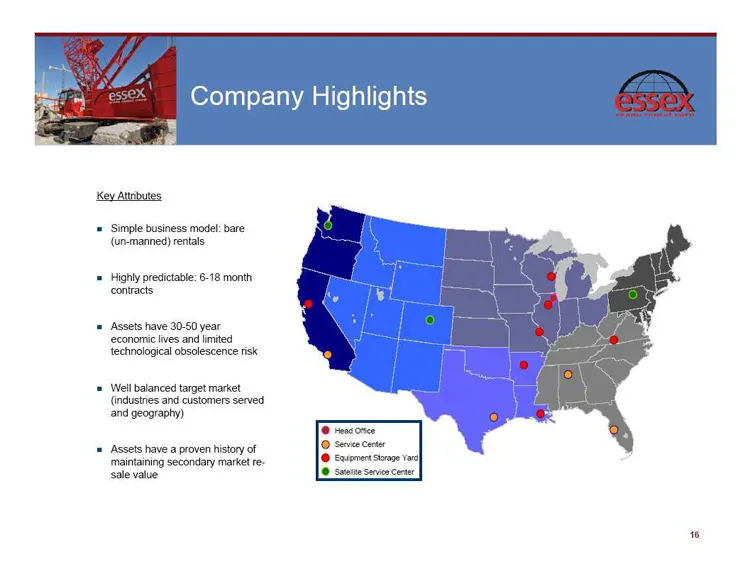
‘Simple business model: bare (unmanned) rentals Highty predictable: 6-18 month contracts ‘Assets have 20-50 year ‘economic lives and limited technological obsolescence risk Wel balanced target market (indusiies and customers served ‘and geography) Assets have a proven history of ‘maintaining seconda
Slide 17: Essex's Competition
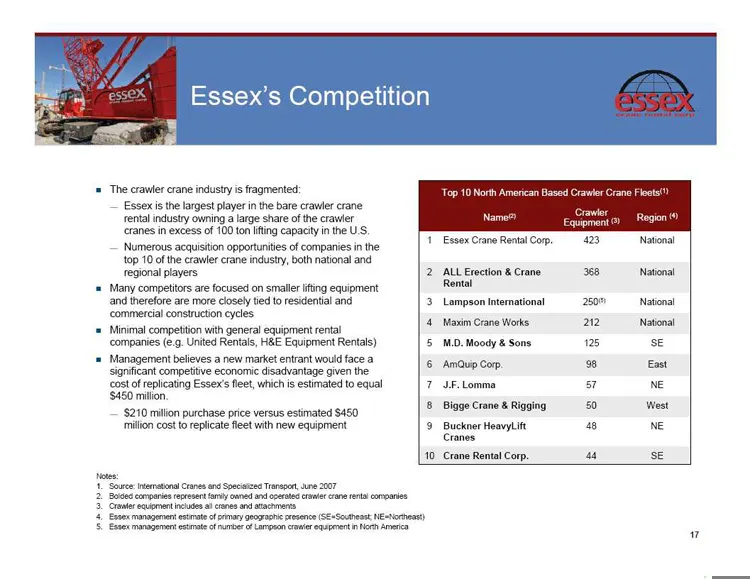
Essex’s Competition 1» The crawler crane industy is fragmented: Top 10 North American Based Crawler Crane Floats! — Essex is the largest player in the bare crawler crane see ‘ental industy owning a large share ofthe craier Name Galt oy Region ‘ranes in excess of 100 ton lifting capac in the US, Nume
Slide 18: Essex Rental Fleet
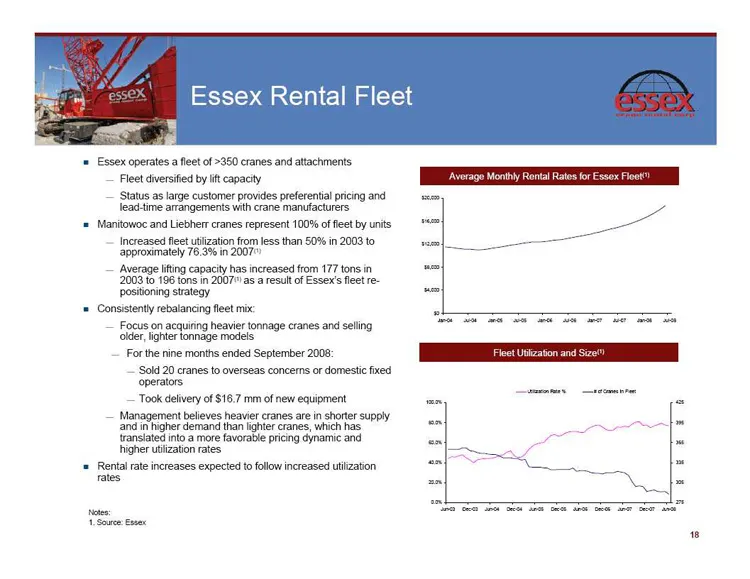
Essex Rental Fleet ‘= Essex operates a fleet of »360 cranes and attachments — Fleet diversified by it capacity — Status as large customer provides preferential pricing and lead-time arrangements with crane manufacturers |= Manitowoc and Liebherr cranes represent 100% of fleet by units Increased flee
Slide 19: Fleet useful life and value
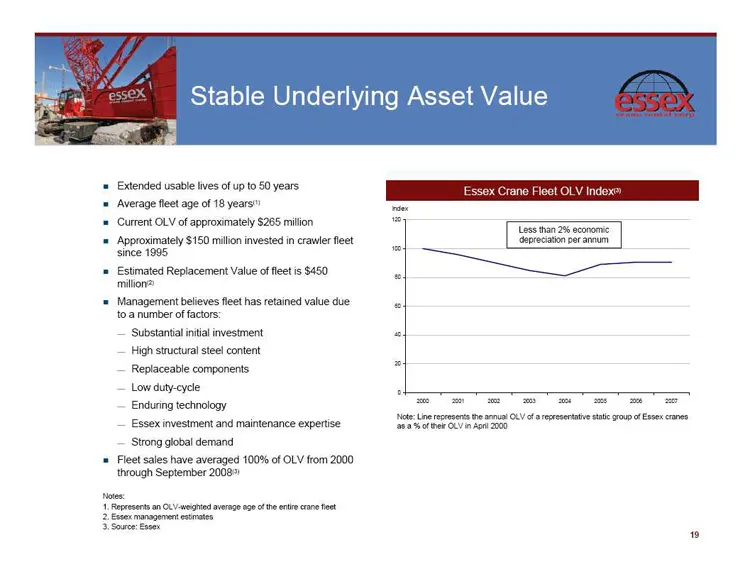
‘+ Extended usable lives of up to 50 years ‘= Average fleet age of 18 years! ‘= Current OLV of approximately $265 milion ‘= Approximately $150 milion invested in crawler fleet ‘since 1995 ‘= Estimated Replacement Value of leet is $450 milion ‘= Management believes fleet has retained value due toa nu
Slide 20: Essex's End Markets
Slide 21: Project lead times and revenue visibility
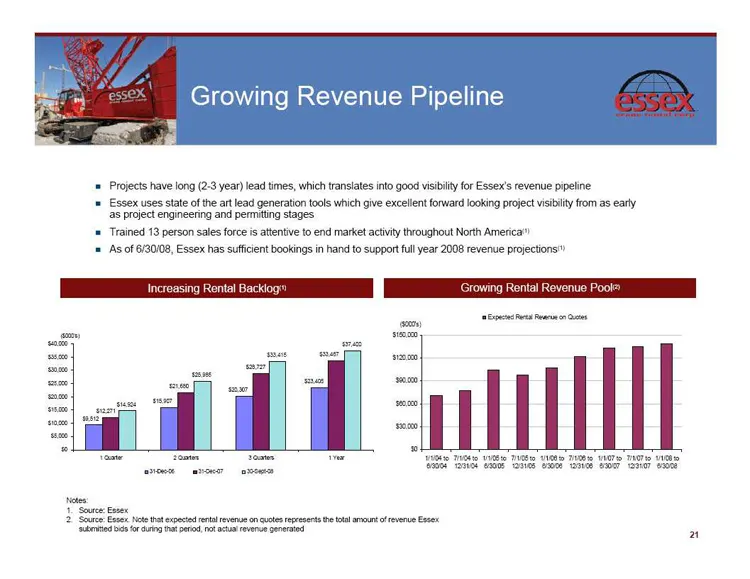
1» Projects have long (2:3 yea) lead times, which translates into good visibly for Essex’s revenue pipeline 1 Essex uses state ofthe art lead generation tools which give excellent forward looking project visibility from as early a project engineering and permiting stages = Trained 13 person sales fo
Slide 22: Organic Growth and Acquisitions
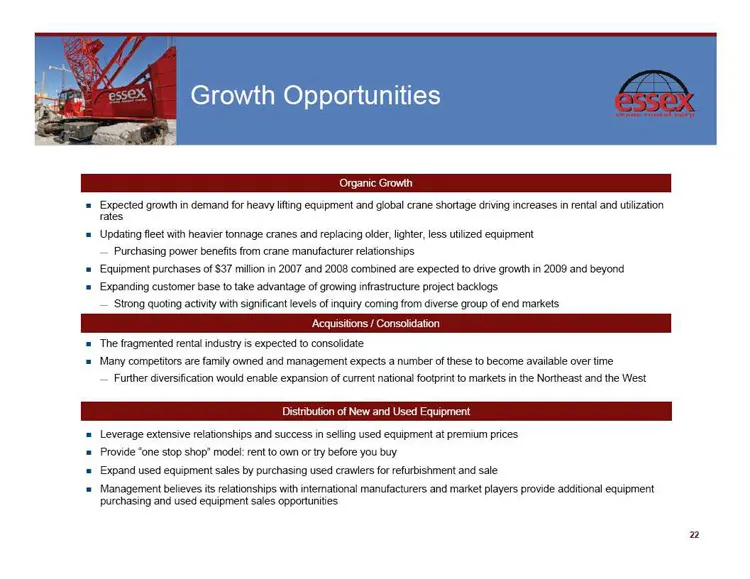
Organic Growth = Expected growth in demand for heavy lifting equipment and global crane shortage driving increases in rental and iiizaton rates. = Updating fleet with heavier tonnage cranes and replacing older, igter, less utilized equipment Purchasing power benefits from crane manufacturer relation
Slide 23: Summary Financial Information and Valuation
Summary Financial Information and Valuation STRICTLY CONFIDENTIAL | 23
Slide 24: Summary financial information
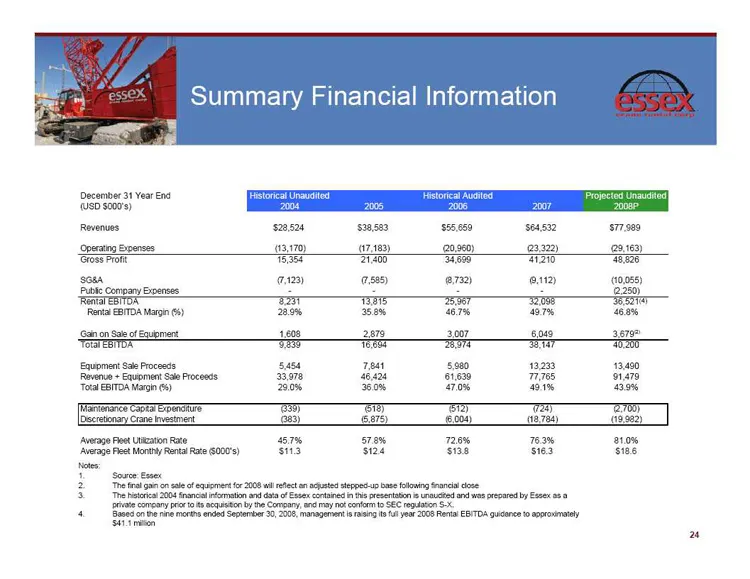
cpectng cess 3.70) 0738) 20 960) 2332) 29.163) ‘Gross Poke Bae 21300 08 ‘120 88 scta 323) 885) e732) 32) 003988) Puble company Excenes - 12250) 7a ug a Sear Renta EBITDA Margin) 239% 3588 ere om 180% (Gan on Sa ot Eauomert s.c08 2879 2.007 019 3670, ToaresTot Tar ieee Ba ar Enupment Soe Proceeds sas
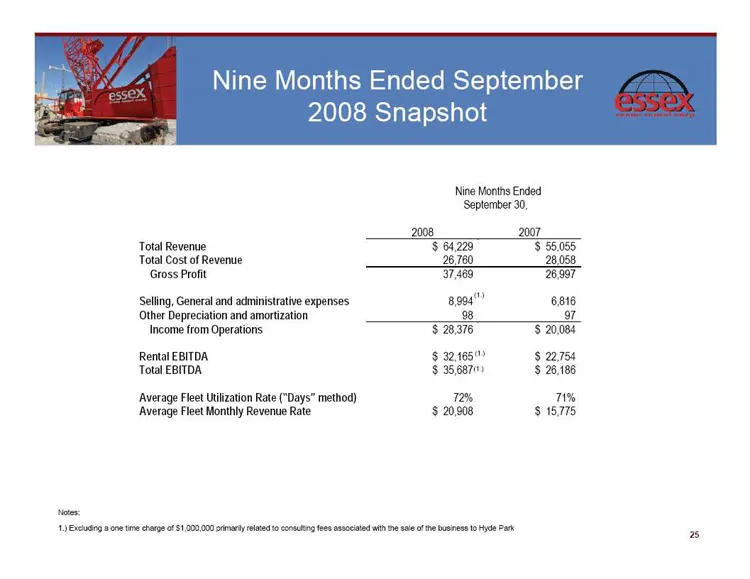
Slide 25: Nine Months Ended September 2008 Snapshot
Nine Months Ended September 2008 Snapshot Nine Months Ended September 30, 2007 Total Revenue ‘S428 $ 55055 Total Cost of Revenue 26,760 28,058 Gross Profit 37 468 26.287 Seling, General and administrative expenses 8904" 6816 ‘Other Depreciation and amortization 98 97 Income from Operations $376 3 20
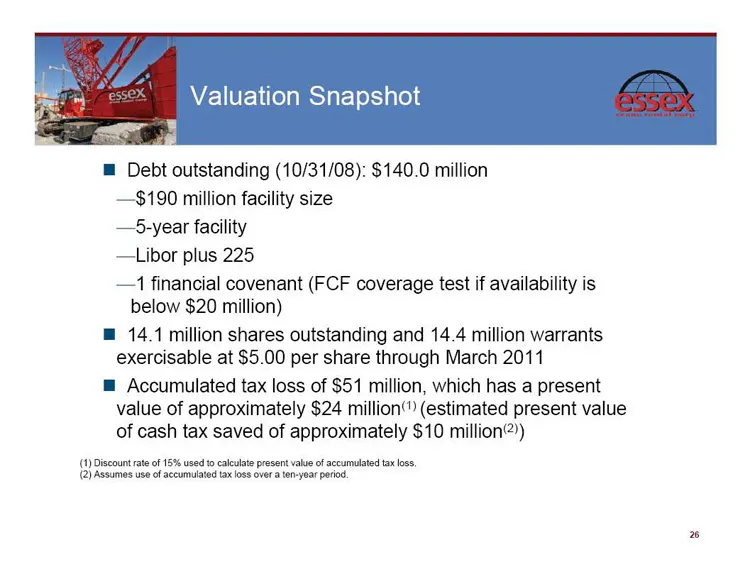
Slide 26: Valuation Snapshot
Valuation Snapshot @ Debt outstanding (10/31/08): $140.0 million —$190 million facility size —5-year facility —Libor plus 225 —1 financial covenant (FCF coverage test if availability is below $20 million) @ 14.1 million shares outstanding and 14.4 million warrants exercisable at $5.00 per share thro
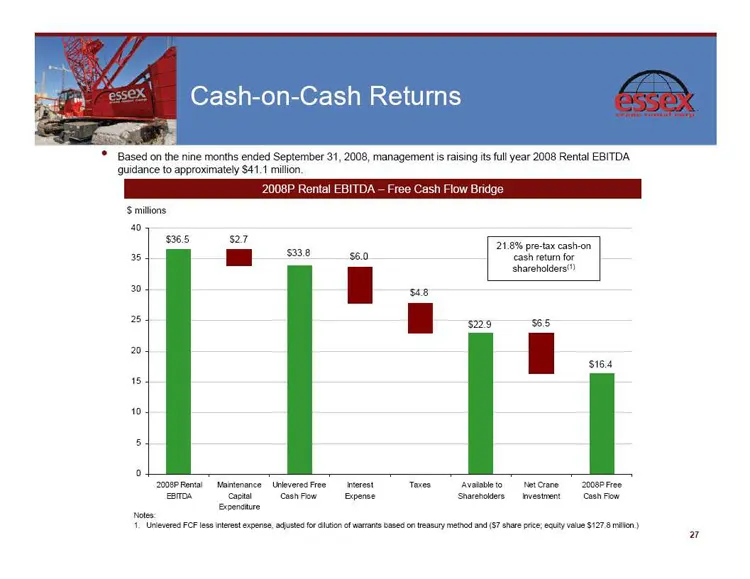
Slide 27: Rental EBITDA guidance
* Based on the nine months ended September 31, 2008, management is raising its full year 2008 Rental EBITDA {guidance to approximately $41.1 millon. 3P Rental EBITD, Smilions 0 21.8% pre-tax cashion cash etn for i si Bs « Dacre FF en wel expense, aut ton aaans bse easy mat and? sve pee ety a $127 Se
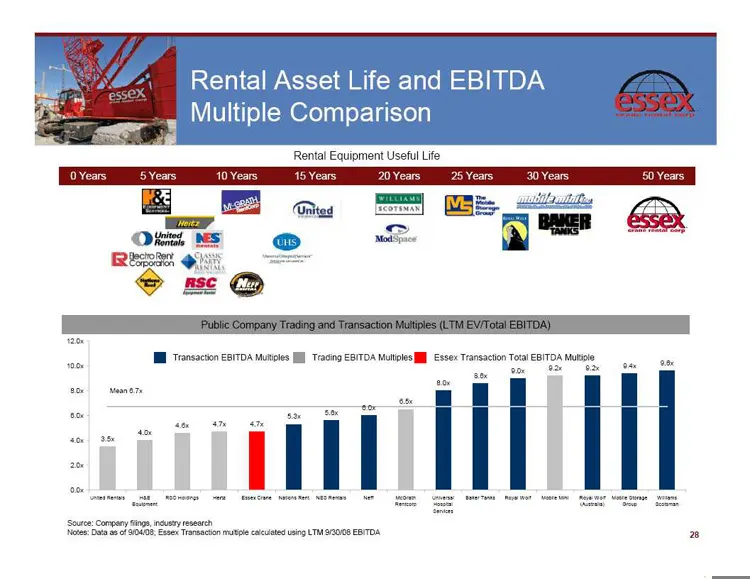
Slide 28: Year
20 Year Sere: Coneeny ns usr reser ies Do of 20008 Eee Trenion mite acl ing LTM 2008 EBTDA ea
Slide 29: Market leader with a long industry heritage able to leverage scale
‘Market leader with a long industry heritage able to leverage scale ‘Committed management team Strong free cash flow generation characteristics Purchasing company ata material discount to leet OLV and replacement cost Good visibility of future project pipeline / rental revenues Exposure to growing i
Source: SEC EDGAR · 8-K filed Dec 11, 2008
More decks from Essex Rental Corp
 Stifel Industrials Conference 201517 slides · Jun 16, 2015
 Proxy Contest (May 2015)14 slides · May 21, 2015
 Investor Presentation (December 2014)18 slides · Dec 3, 2014
 Oppenheimer Presentation (May 2014)20 slides · May 14, 2014
 RBC Industrials Conference 201321 slides · Sep 11, 2013
 Oppenheimer 8th Annual Industrial Growth Summit (May 2013)23 slides · May 14, 2013