MDC — Investor Day (November 2018)
132 slides from MDC's investor day presentation, Nov 8, 2018
Slide 1: MDC Holdings Investor Day Event
MDC HOLDINGS INVESTOR DAY EVENT @MDC p Y HOLDINGS. INC. x
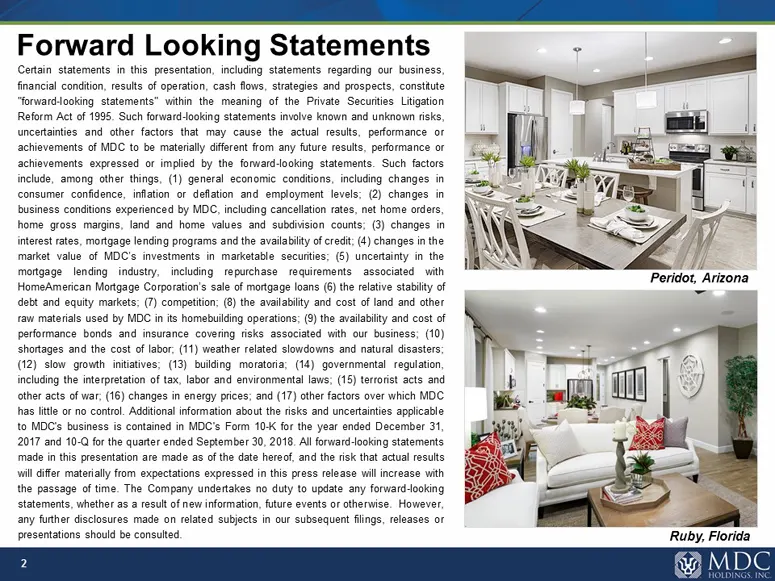
Slide 2: Forward Looking Statements
Forward Looking Statements Certain statements in this presentation, including statements regarding our business, financial condition, results of operation, cash flows, strategies and prospects, consttute forward-looking statements” within the meaning of the Private Securities Litigation Reform Act o
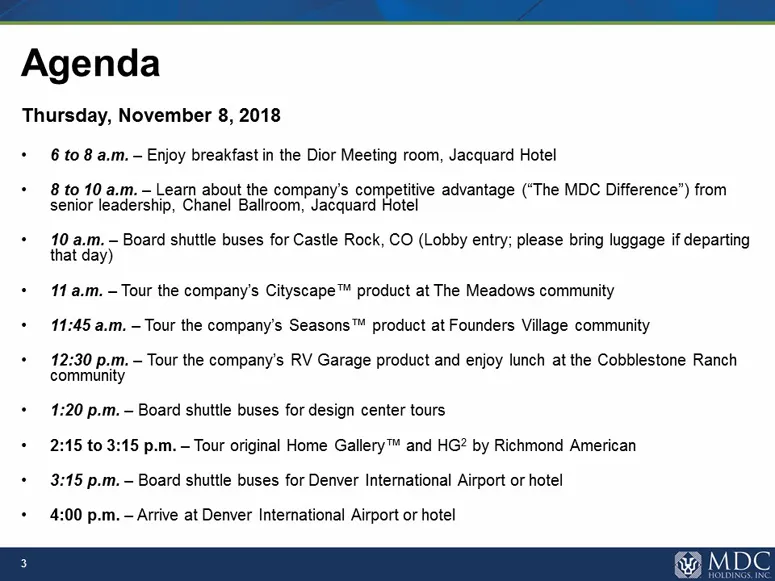
Slide 3: Agenda
a a Agenda Thursday, November 8, 2018 + 6 to 8 a.m. — Enjoy breakfast in the Dior Meeting room, Jacquard Hotel + 8 to 10 a.m. — Lear about the company’s competitive advantage (“The MDC Difference”) from senior leadership, Chanel Ballroom, Jacquard Hotel + 40a.m.~ Board shuttle buses for Castle Rock,
Slide 4: Company Representatives
Company Representatives & MDC HOLDINGS, INC
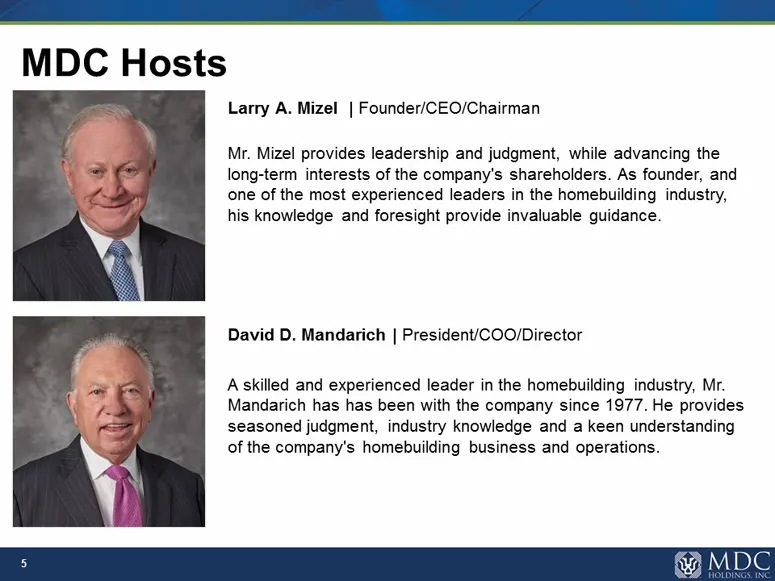
Slide 5: MDC Hosts
7— Sa MDC Hosts Larry A. Mizel | Founder/CEO/Chairman Mr. Mizel provides leadership and judgment, while advancing the long-term interests of the company's shareholders. As founder, and one of the most experienced leaders in the homebuilding industry, his knowledge and foresight provide invaluable gu
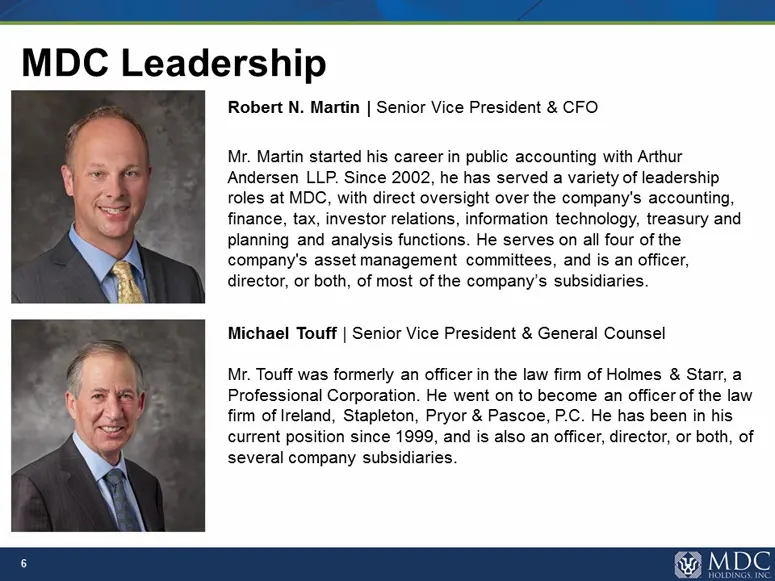
Slide 6: MDC Leadership
ee NE, MDC Leadership Robert N. Martin | Senior Vice President & CFO Mr. Martin started his career in public accounting with Arthur Andersen LLP. Since 2002, he has served a variety of leadership roles at MDC, with direct oversight over the company's accounting, finance, tax, investor relations, inf
Slide 7: Corporate Representatives
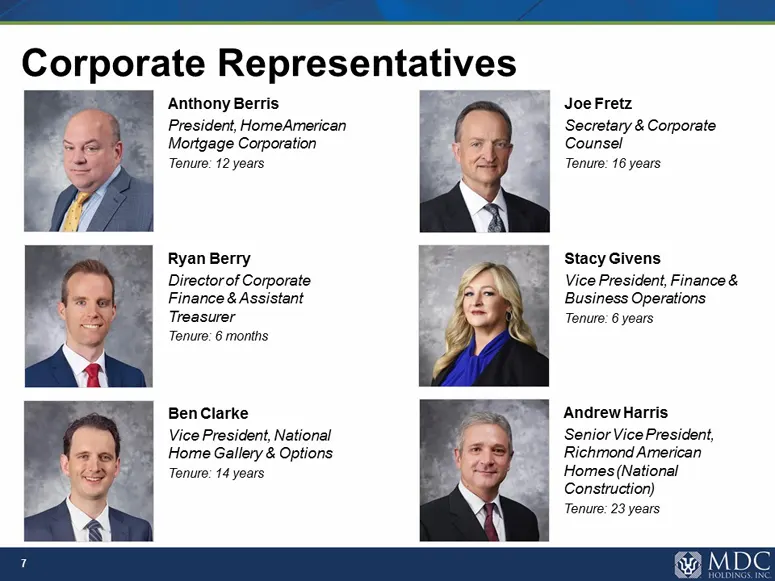
Corporate Representatives Anthony Berris Joe Fretz President, HomeAmerican Secretary & Corporate Mortgage Corporation Counsel Tenure: 12 years Tenure: 16 years Ryan Berry Stacy Givens Director of Corporate Vice President, Finance & Finance & Assistant Business Operations Treasurer Tenure: 6 years Te
Slide 8: Corporate Representatives
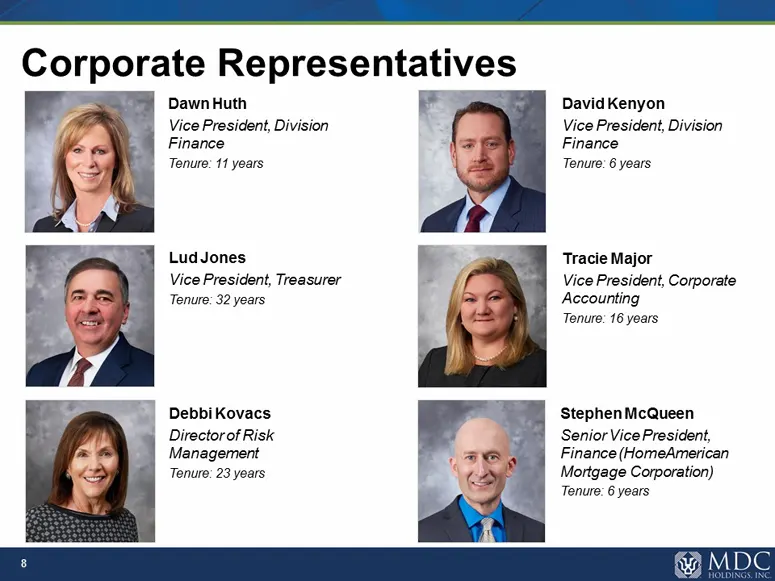
ee NE, Corporate Representatives Dawn Huth David Kenyon Vice President, Division Vice President, Division Finance Finance Tenure: 11 years Tenure: 6 years Lud Jones Vice President, Treasurer Tenure: 32 years Tracie Major Vice President, Corporate Accounting Tenure: 16 years DebbiKovacs Stephen McQue
Slide 9: Corporate Representatives
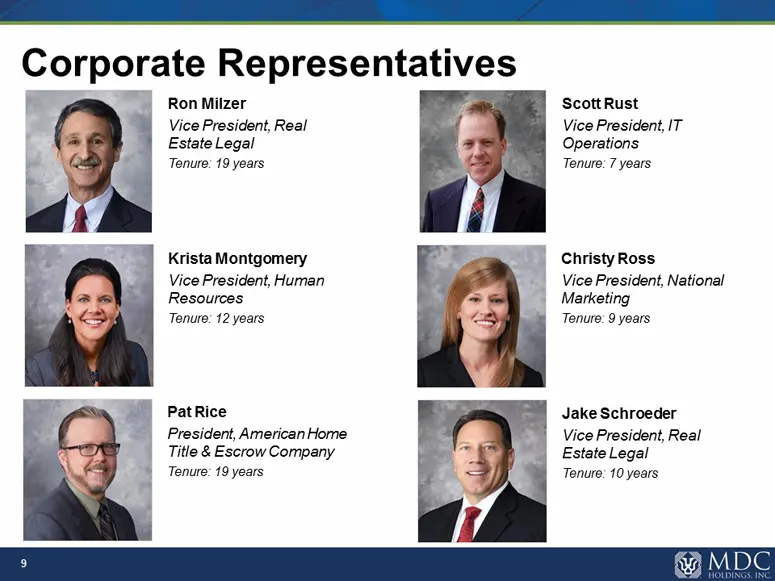
ee NE, Corporate Representatives Ron Milzer Scott Rust Vice President, Real Vice President, IT Estate Legal Operations Tenure: 19 years Tenure: 7 years Krista Montgomery Christy Ross Vice President, Human Vice President, National Resources Marketing Tenure: 12 years Tenure: 9 years PatRice Jake Schr
Slide 10: Corporate Representatives
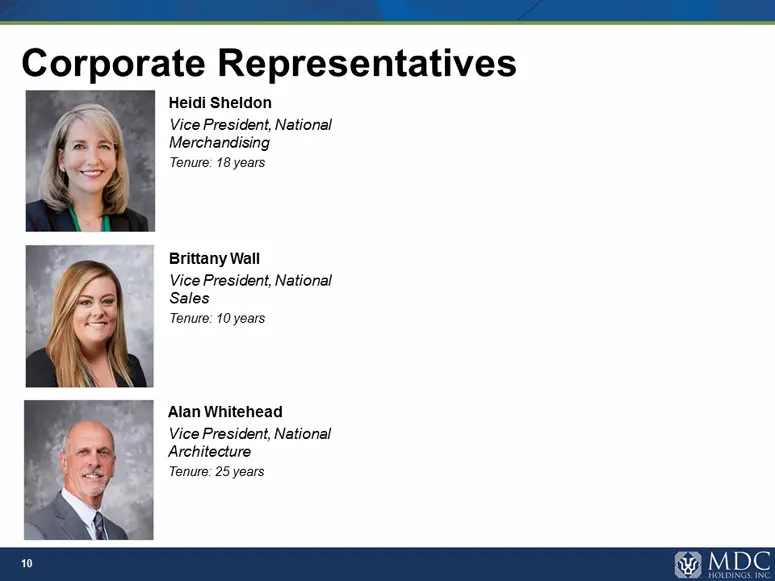
Corporate Representatives Heidi Sheldon Vice President, National ‘Merchandising Tenure: 18 years Brittany Wall Vice President, National Sales Tenure: 10 years Alan Whitehead Vice President, National Architecture Tenure: 25 years
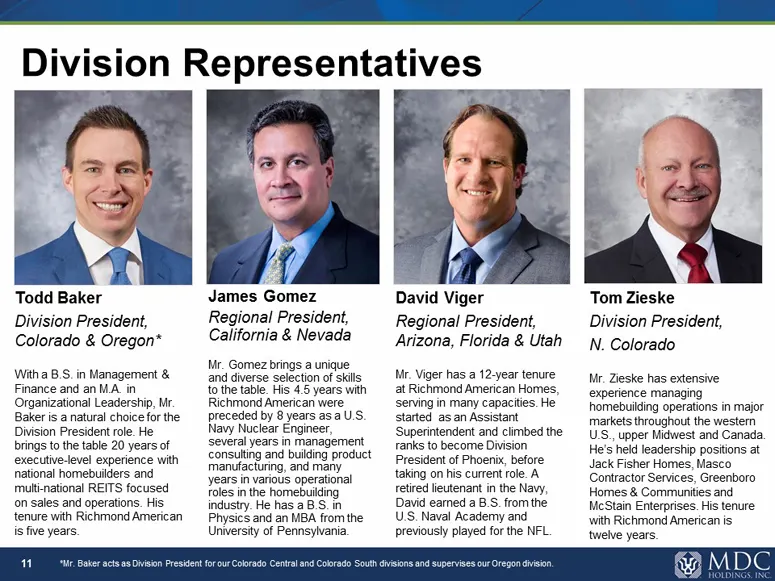
Slide 11: Division Representatives
Division Representatives Todd Baker Division President, Colorado & Oregon* With a B.S. in Management & Finance and an M.A. in Organizational Leadership, Mr. Baker is a natural choice for the Division President role. He brings to the table 20 years of executive-level experience with ‘national homebui
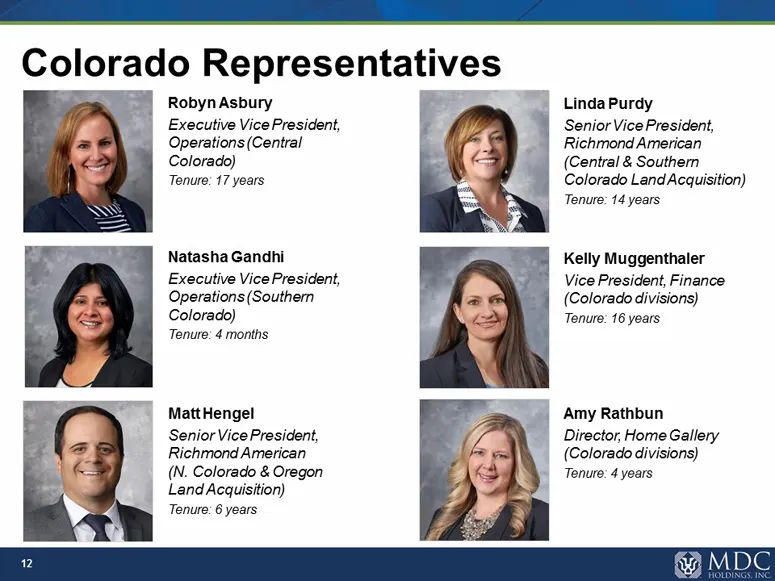
Slide 12: Colorado Representatives
Colorado Representatives Robyn Asbury Linda Purdy Executive Vice President, Senior Vice President, Operations (Central Richmond American Colorado) (Central & Southern Tenure: 17 years Colorado Land Acquisition) Tenure: 14 years Natasha Gandhi Kelly Muggenthaler Executive Vice President, Vice Preside
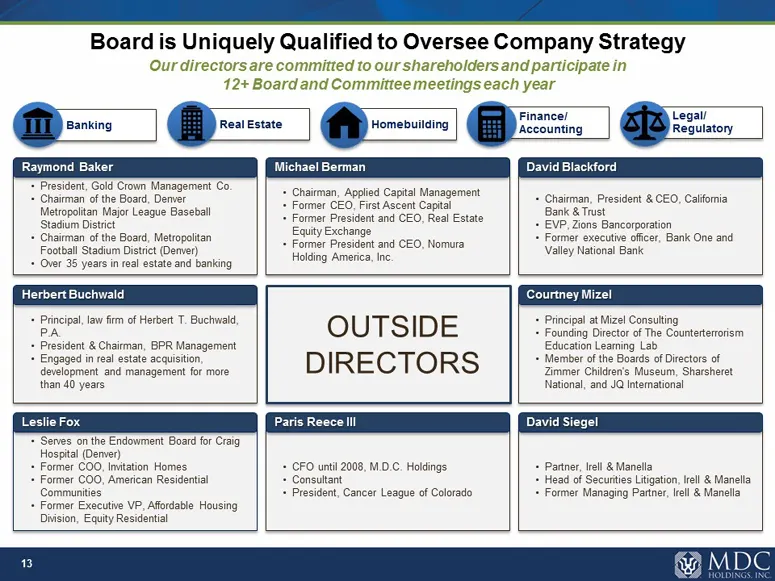
Slide 13: Board is Uniquely Qualified to Oversee Company Strategy
Board is Uniquely Qualified to Oversee Company Strategy Our directors are committed to our shareholders and participate in 12+ Board and Committee meetings each year Raymond Baker * President, Gold Crown Mana‘ + Chairman of the Board, Denver Metropolitan Major League Baseball Stadium Distt * Chairma
Slide 14: Macroeconomic Outlook: Runway Remains for Growth
Macroeconomic Outlook: Runway Remains for Growth @ MDC HOLDINGS, INC
Slide 15: Perspective on the Cycle
a a Perspective on the Cycle “While some might fear that raising interest rates will turn buyers away from purchasing a home, history has shown that consumers will move forward with a home purchase in a rising rate environment, provided they feel confident in their employment status. Additionally, i
Slide 16: Macro Outlook: The Positives
A Macro Outlook: The Positives + Existing home inventory remains low, especially at affordable price points + Matched lowest unemployment rate since 1969 (3.7% in October 2018) * Consumer confidence near a multi-year high * Household formation is strong * Percentage of young adults still living at h
Slide 17: Macro Outlook: The Negatives
Macro Outlook: The Negatives * Home prices have increased significantly since the downturn + Mortgage rates are still low, but rising * Labor availability remains tight « Material costs continue to creep higher
Slide 18: Inventory Levels
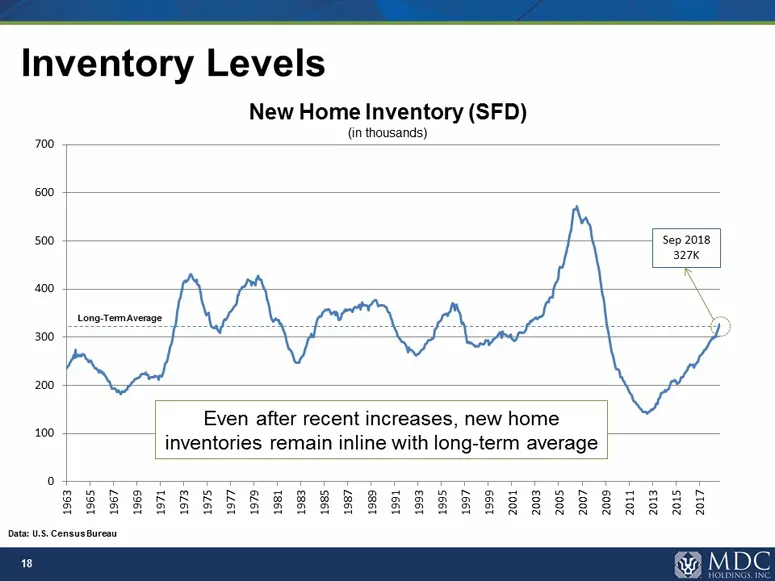
Inventory Levels New Home Inventory (SFD) (in thousands) 700 500 -{-\- Sep 2018 327K Even after recent increases, new home inventories remain inline with long-term average 100 2007 2003 2001 2003 2005 2011 2013 2015 2017 Data: U.S, Census Bureau 8
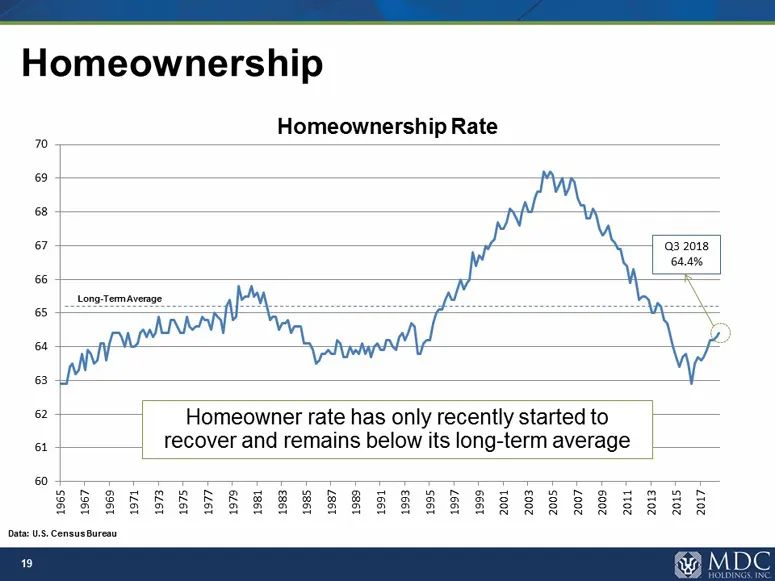
Slide 19: Homeownership
Homeownership » Homeownership Rate a SS a . pusher ce ry \_ 2 Homeowner rate has only recently started to ee ‘et recover and remains below its long-term average = 6 2001 2003 2005 2007 2008 2011 2013 2015 2017 Data: U.S, Census Bureau 19
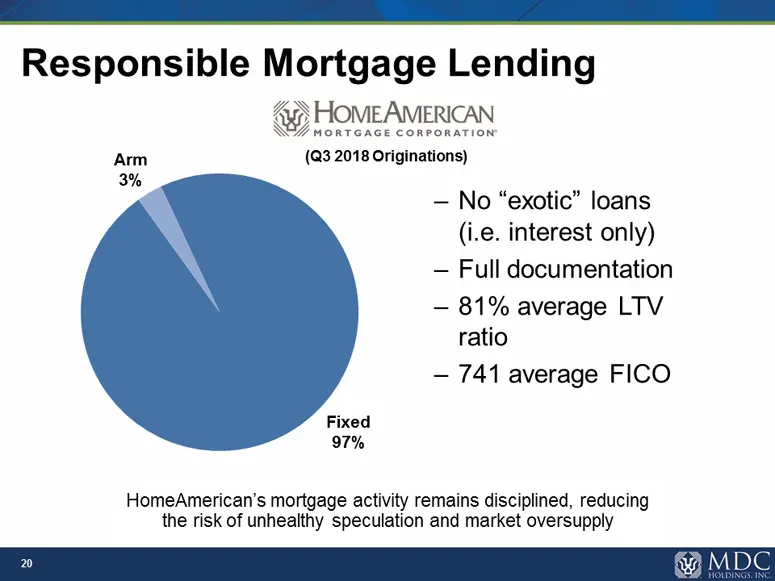
Slide 20: Responsible Mortgage Lending
a a Responsible Mortgage Lending i HOMEAMIERICAN X84 montGace CORPORATION Arm (Q3 2018 Originations) — No “exotic” loans (i.e. interest only) — Full documentation — 81% average LTV ratio — 741 average FICO Fixed 97% HomeAmerican’s mortgage activity remains disciplined, reducing the risk of unhealthy
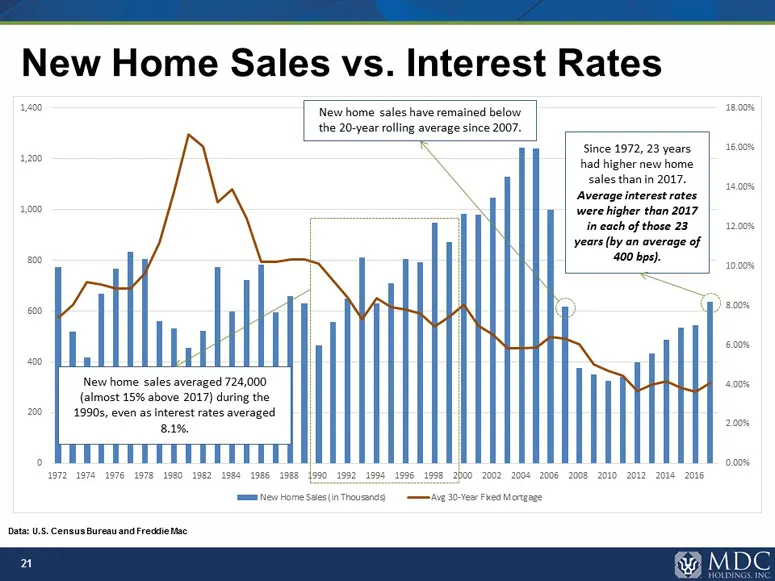
Slide 21: New Home Sales vs. Interest Rates
New Home Sales vs. Interest Rates 1-00 New home sales have remained below a, Since 1972, 23 years | 3500% sal had higher new home salesthanin 2017. |... Average interest rates 3.600 ET were higher than 2017 f in each of those 23. | 1200 years (by an average of 00 400 bps). — eo 00% 600% New home sal
Slide 22: Consumer Strength Accelerating
a a Consumer Strength Accelerating “Hiring accelerated in October and the unemployment rate held at a 49-year low, signs of a strengthening labor market that delivered U.S. workers the best pay raises in nearly a decade. U.S. nonfarm payrolls increased a seasonally adjusted 250,000 in October, the L
Slide 23: The MDC Difference
The MDC Difference & MDC HOLDINGS, INC
Slide 24: MDC builds and finances quality homes at affordable prices
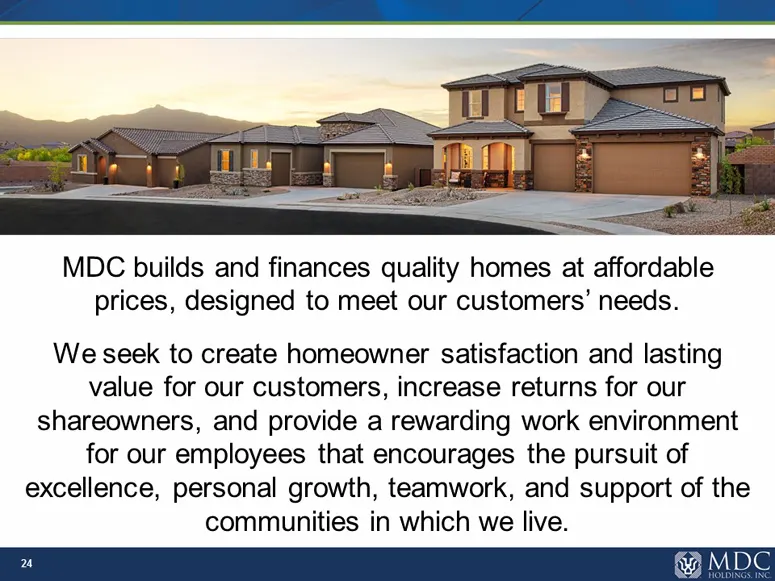
MDC builds and finances quality homes at affordable prices, designed to meet our customers’ needs. We seek to create homeowner satisfaction and lasting value for our customers, increase returns for our shareowners, and provide a rewarding work environment for our employees that encourages the pursui
Slide 25: Timeline 1972 to 1985
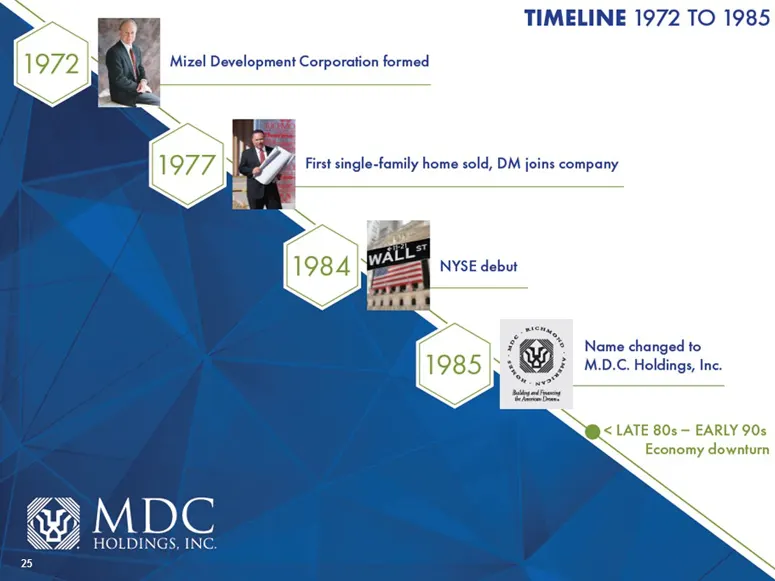
TIMELINE 1972 TO 1985 NYSE debut Name changed to M.D.C. Holdings, Inc. @Me¢ Yy 1OUDINGS. INC
Slide 26: Timeline 1999 to 2004
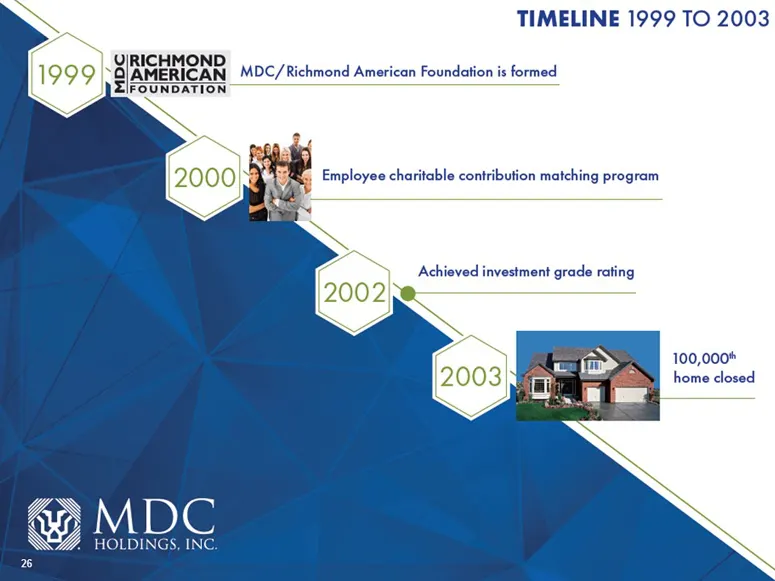
TIMELINE 1999 TO 20 RICHMOND AMEI \N 48) MDC/ Richmond Am in Foundation is formed Employee charitable contribution matching program Achieved investment grade rating 100,000 home closed HOLDINGS, INC. GA &} MDC
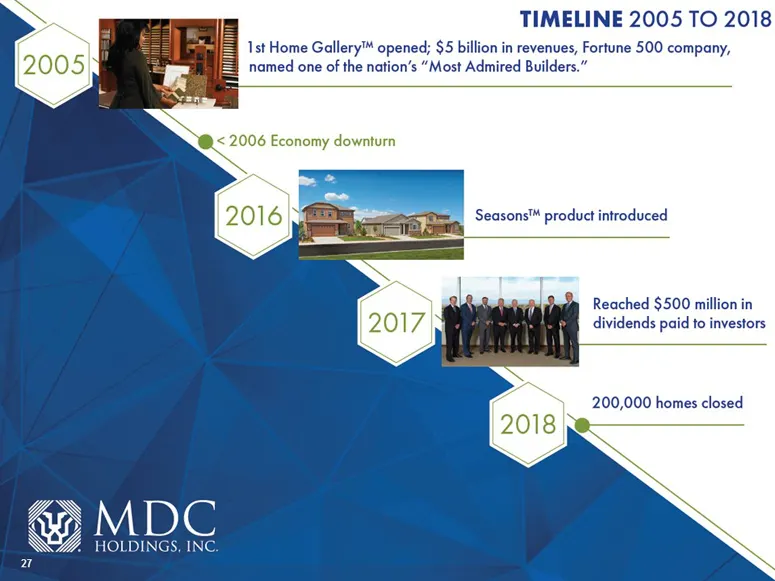
Slide 27: Timeline 2005 to 2018
TIMELINE 2005 TO 2018 Ist Home Gallery opened; $5 billion in revenues, Fortune 500 company, named one of the nation’s “Most Admired Builders.” Reached $500 million in dividends paid to investors 200,000 homes closed HOLDINGS, INC. Gp &Y MDC
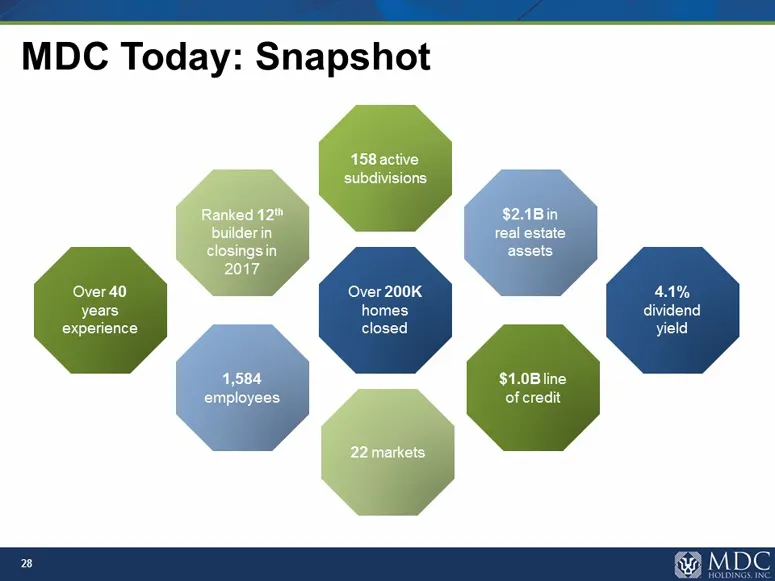
Slide 28: MDC Today: Snapshot
a a MDC Today: Snapshot Over 40 years experience 1,584 employees $2.1B in real estate assets Over 200K 41% homes dividend closed yield $1.0Bline of credit
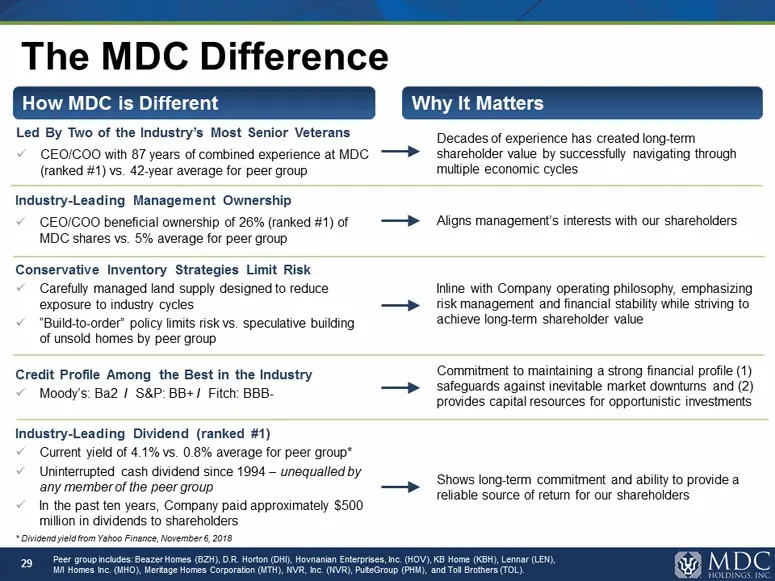
Slide 29: The MDC Difference
7— Sa The MDC Difference How MDC is Different y It Matters Led By Two of the Industry’s Most Senior Veterans ¥ CEOICOO with 87 years of combined experience at MDC. —> (ranked #1) vs. 42-year average for peer group Decades of experience has created long-term shareholder value by successfully navigati
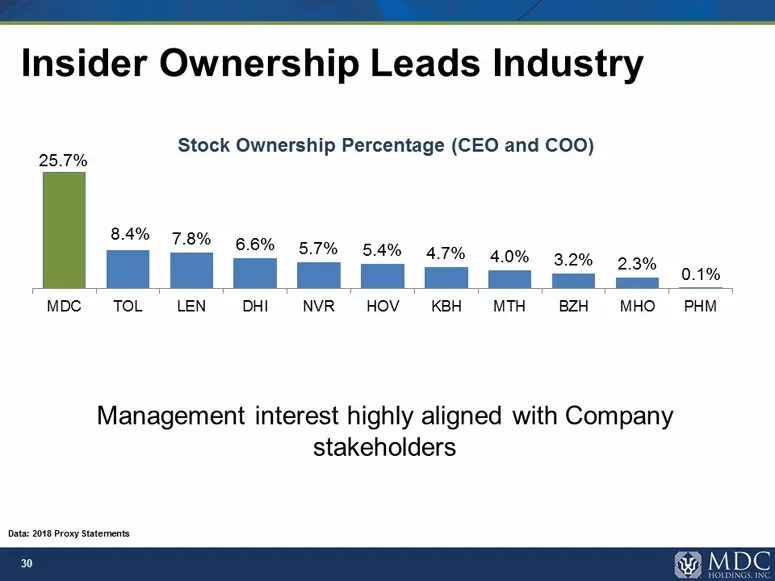
Slide 30: Insider Ownership Leads Industry
ee NE, Insider Ownership Leads Industry Stock Ownership Percentage (CEO and COO) 25.7% 78% 6.6% 5.7% 5.4% 4.7% 4.0% 3.2% 2.3% 0.1% MDC TOL LEN DHI NVR HOV KBH MTH BZH MHO- PHM Management interest highly aligned with Company stakeholders Data: 2018 Prony Statements 20
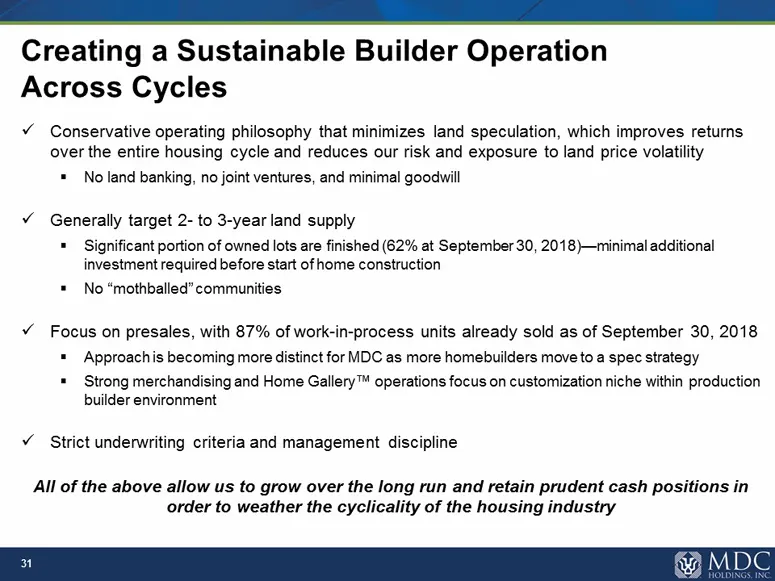
Slide 31: Creating a Sustainable Builder Operation Across Cycles
Creating a Sustainable Builder Opera Across Cycles VY Conservative operating philosophy that minimizes land speculation, which improves returns over the entire housing cycle and reduces our risk and exposure to land price volatility * No land banking, no joint ventures, and minimal goodwill Y Genera
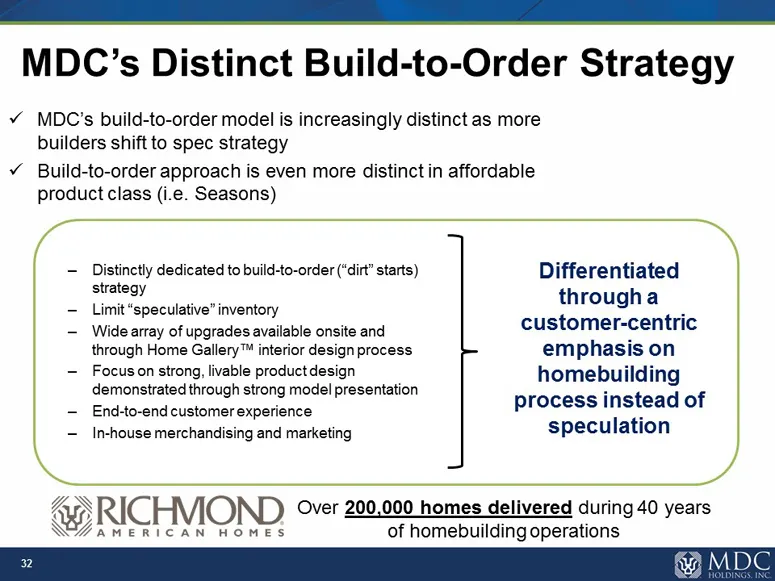
Slide 32: MDC's Distinct Build-to-Order Strategy
a a MDC’s Distinct Build-to-Order Strategy v MDC's build-to-order model is increasingly distinct as more builders shift to spec strategy ¥ Build-to-order approach is even more distinct in affordable product class (i.e. Seasons) Distinctly dedicated to build-to-order (“dirt” starts) Differentiated st
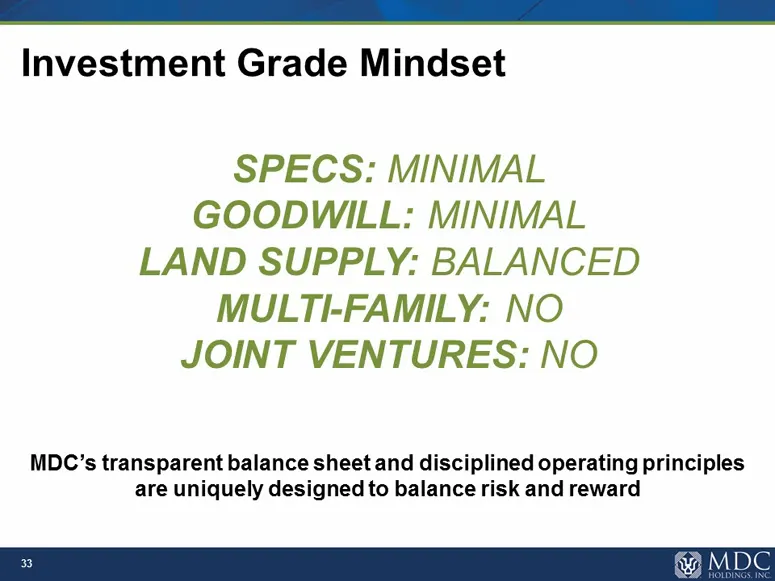
Slide 33: Investment Grade Mindset
7— Sa Investment Grade Mindset SPECS: MINIMAL GOODWILL: MINIMAL LAND SUPPLY: BALANCED MULTI-FAMILY: NO JOINT VENTURES: NO MDC’s transparent balance sheet and disciplined operating principles are uniquely designed to balance risk and reward x2 (MDC
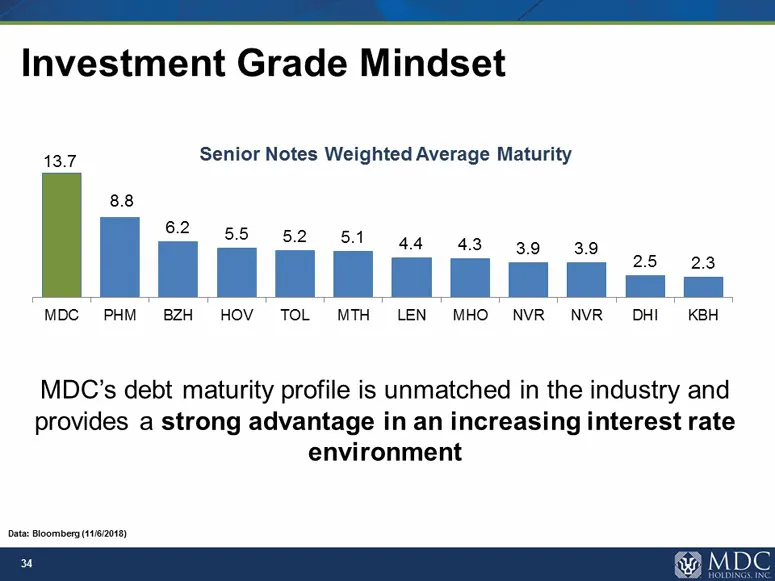
Slide 34: Investment Grade Mindset
7— Sa Investment Grade Mindset 13.7 Senior Notes Weighted Average Maturity MDC PHM BZH HOV TOL MTH LEN MHO NVR NVR- DHI_ KBH MDC’s debt maturity profile is unmatched in the industry and provides a strong advantage in an increasing interest rate environment Data Bloomberg (11182018) u
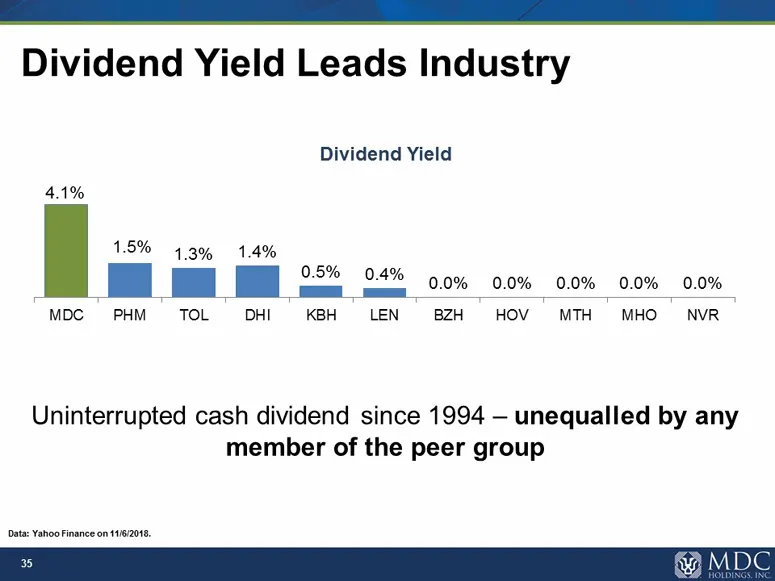
Slide 35: Dividend Yield Leads Industry
ee NE, Dividend Yield Leads Industry Dividend Yield 4.1% 0.0% 0.0% 0.0% 0.0% 0.0% MDC PHM TOL ODHI KBH LEN BZH HOV MTH MHO NVR Uninterrupted cash dividend since 1994 — unequalled by any member of the peer group
Slide 36: Giving Back to Our Communities
Giving Back to Our Communities U|RICHMOND O AMERICAN EZ FOUNDATION
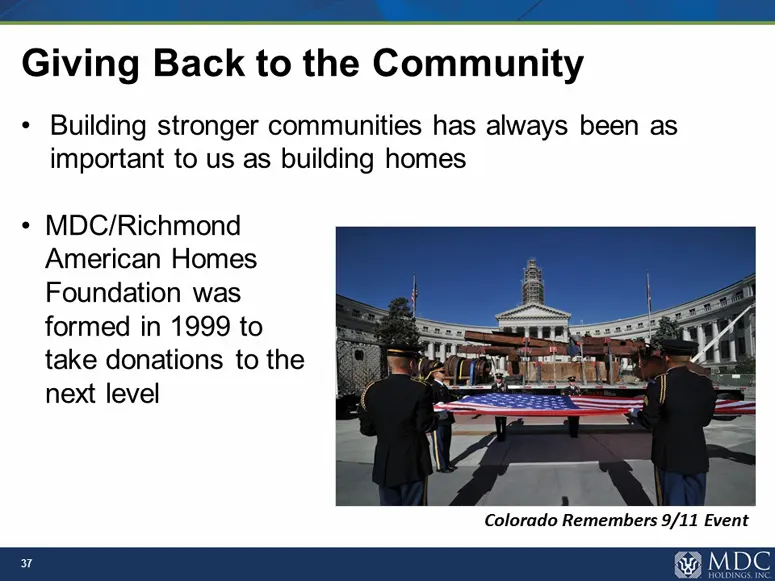
Slide 37: Giving Back to the Community
Giving Back to the Community * Building stronger communities has always been as important to us as building homes * MDC/Richmond American Homes Foundation was formed in 1999 to take donations to the next level
Slide 38: Giving Back to the Community
a a Giving Back to the Community * Since its inception, Foundation donations have exceeded $19 million, supporting 200+ organizations * The Foundation gives to a variety of worthy causes in our own backyard and across the globe 2 National Jewish Health GLOBAL x DOWN SYNDROME U P L f t €@ DENVER HEAL
Slide 39: Product Spotlight
Product Spotlight MPC
Slide 40: The Affordable Product Opportunity
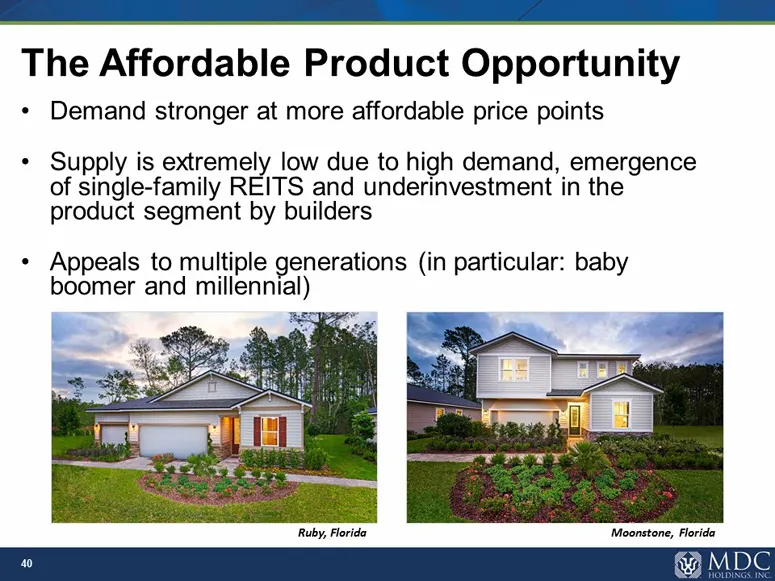
ee NE, The Affordable Product Opportunity + Demand stronger at more affordable price points + Supply is extremely low due to high demand, emergence of single-family REITS and underinvestment in the product segment by builders * Appeals to multiple generations (in particular: baby boomer and millenni
Slide 41: MDC's Affordable Product Approach
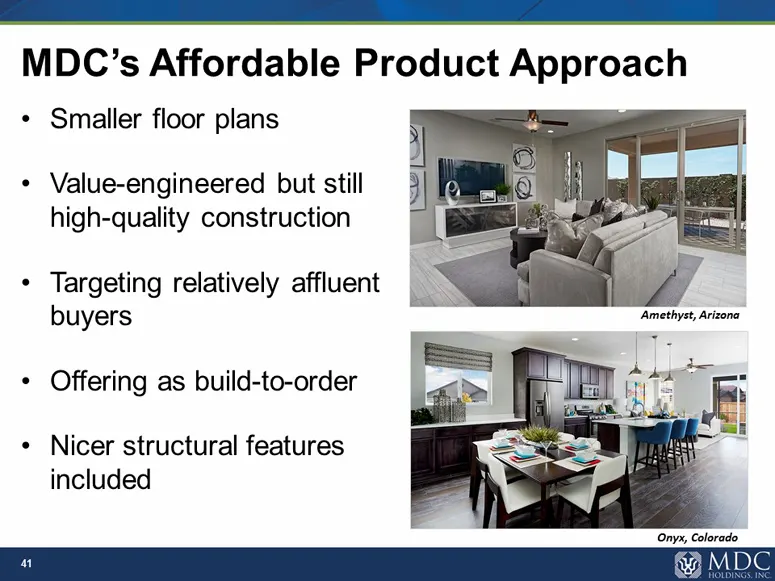
MDC’s Affordable Product Approach * Smaller floor plans + Value-engineered but still high-quality construction * Targeting relatively affluent buyers * Offering as build-to-order * Nicer structural features included
Slide 42: U.S. Population by Generation
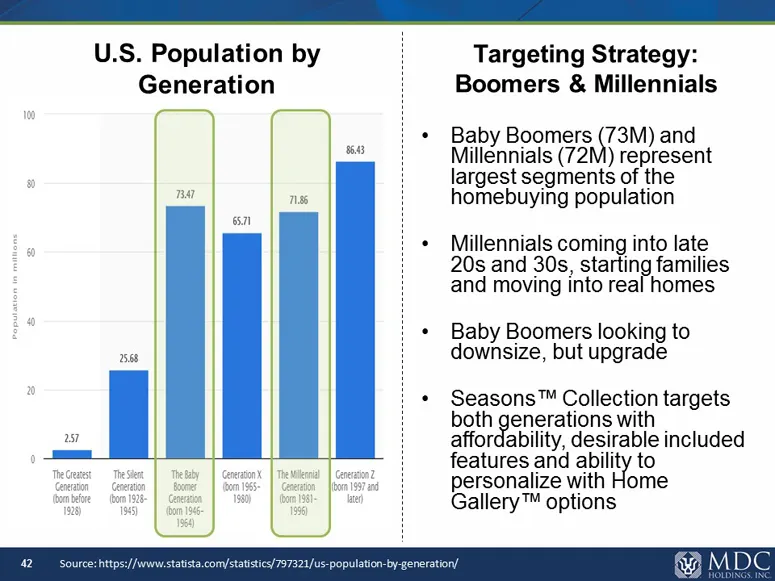
U.S. Population by Generation => $r-) 68 nar ar on Bry ast Targeting Strategy: Boomers & Millennials Baby Boomers (73M) and Millennials (72M) represent largest segments of the homebuying population Millennials coming into late 20s and 30s, starting families and moving into real homes Baby Boomers lo
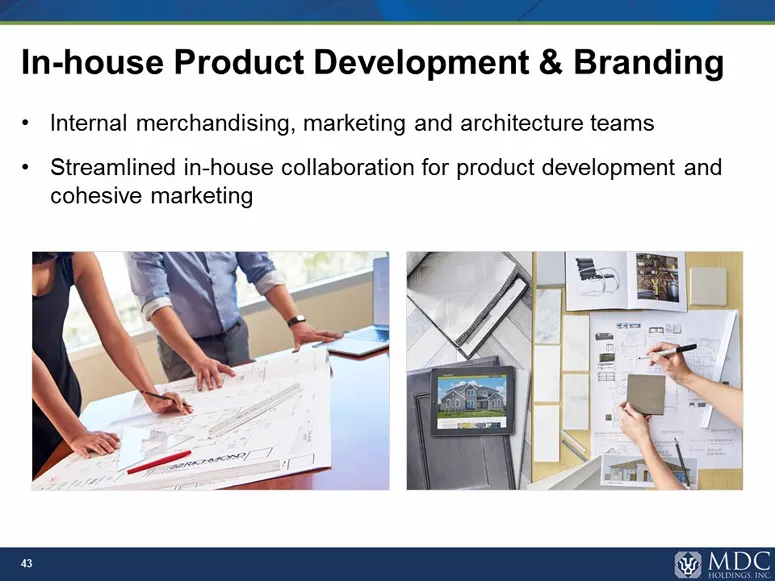
Slide 43: In-house Product Development & Branding
In-house Product Development & Branding + Internal merchandising, marketing and architecture teams + Streamlined in-house collaboration for product development and cohesive marketing
Slide 44: In-house Product Development & Branding
In-house Product Development & Branding Continual emphasis on marketing initiatives focused around data ¢ Shift in funds in 2011 (through today) — Moved away from more traditional tactics, such as print ads, to leverage digital opportunities with better targeting capabilities and conversion reportin
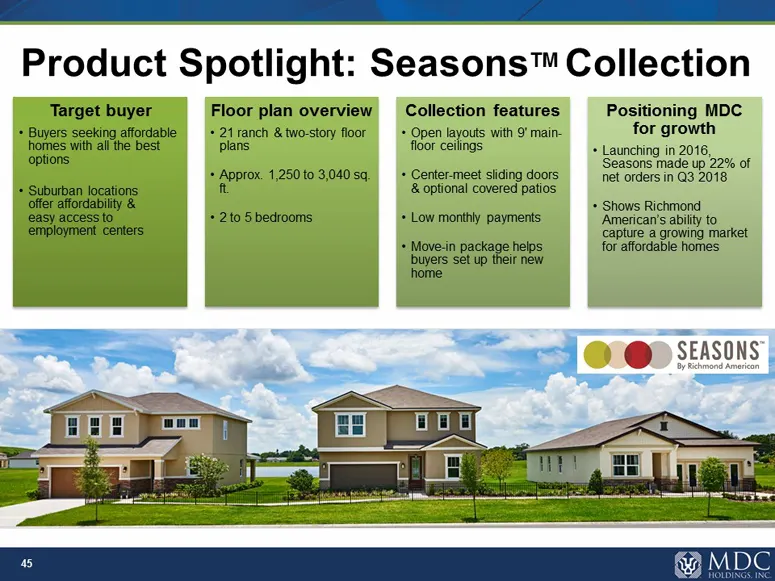
Slide 45: Product Spotlight: Seasons Collection
Product Spotlight: Seasons™ Collection Target buyer Floor plan overview _ Collection features Positioning MDC * Buyers seeking affordable + 21 ranch & two-story floor + Open layouts with 9’ main. for growth homes with all the best plans floor ceilings * Launching in 2016, options ‘Seasons made up 22
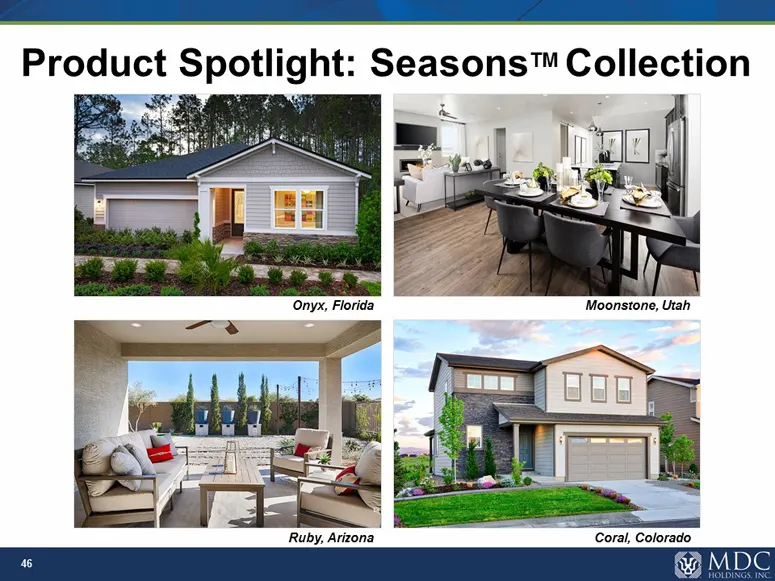
Slide 46: Product Spotlight: Seasons Collection
Product Spotlight: Seasons™ Collection Ss Ruby, Arizona i Coral, Colorad
Slide 47: Seasons Collection: Included Features
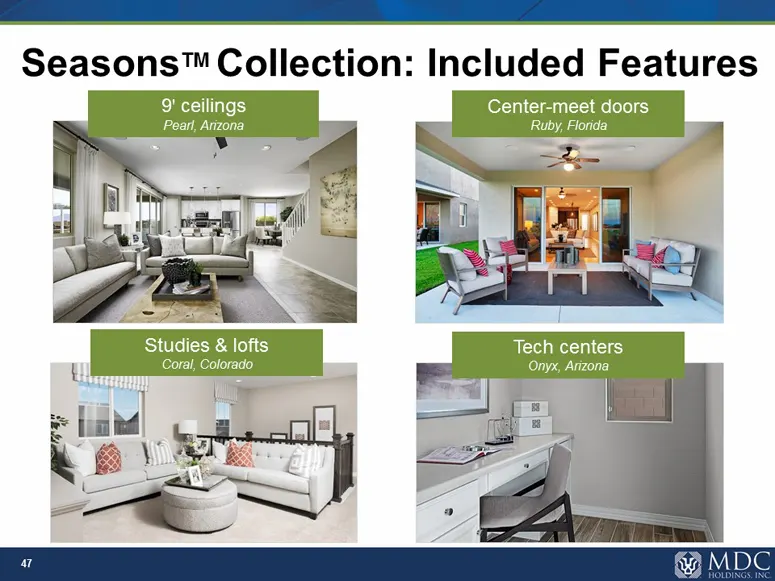
Seasons™ Collection: Included Features 9' ceilings Center-meet doors Pearl, Arizona " Ruby, Florida == 4 yy —_ — ey cee | Studies & lofts Coral, Colorado
Slide 48: Product Spotlight: Seasons Collection
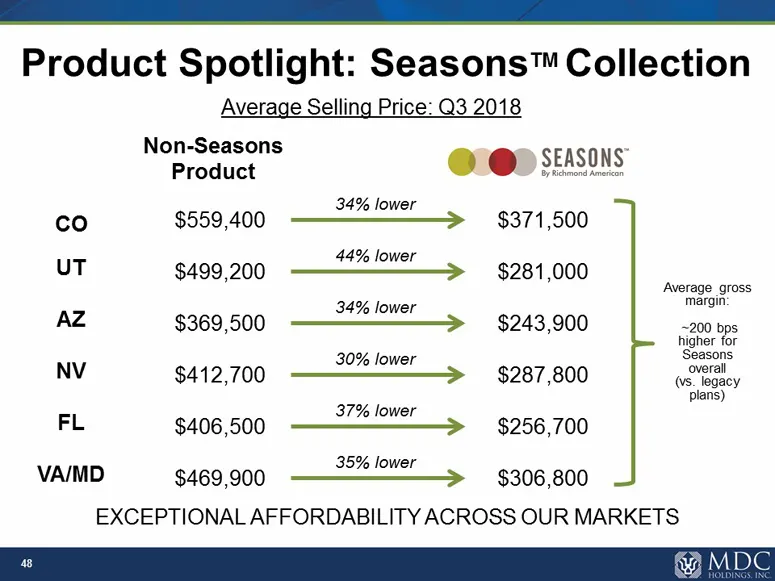
Product Spotlight: Seasons™ Collection Average Selling Price: Q3 2018 UT NV FL VA/MD Non-Seasons Product $559,400 $499,200 $369,500 $412,700 $406,500 $469,900 34% lower 44% lower 34% lower 30% lower 37% lower 35% lower @I@D SEASONS $371,500 $281,000 Average gross margin $243,900 ~200 bps higher for
Slide 49: Product Spotlight: Cityscape Collection
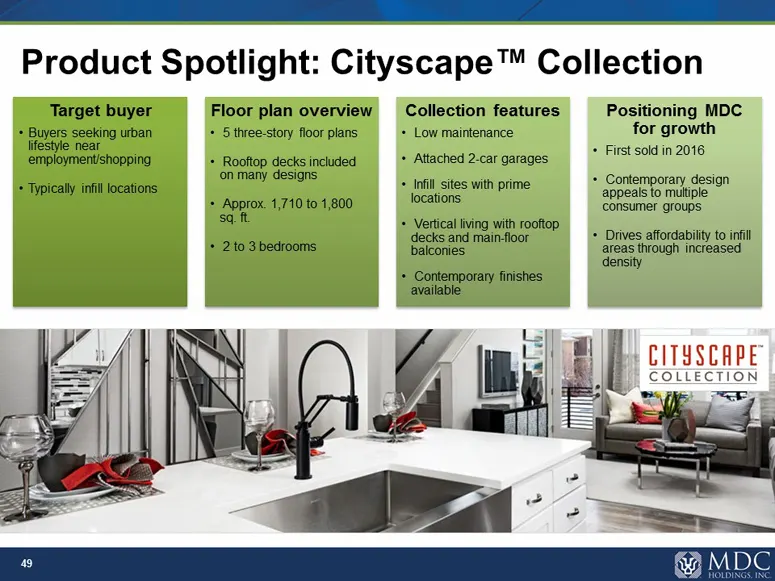
Product Spotlight: Cityscape™ Collection Target buyer Floor plan overview _Collection features Positioning MDC = Buyers seeking urban + 5 three-story floor plans + Low maintenance for growth Westyle near + First sold in 2016 ‘employment/shopping + Rooftop decks included + Attached 2.car garages ‘on
Slide 50: Product Spotlight: Cityscape Collection
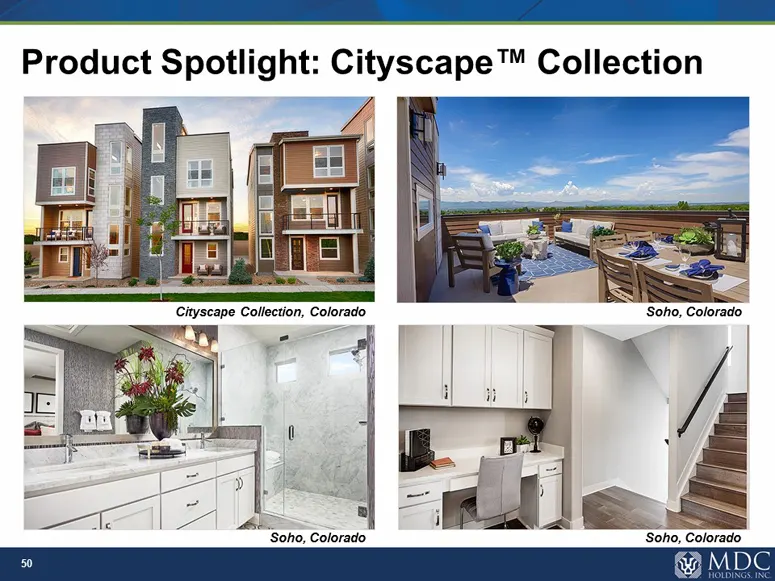
Product Spotlight: Cityscape™ Collection
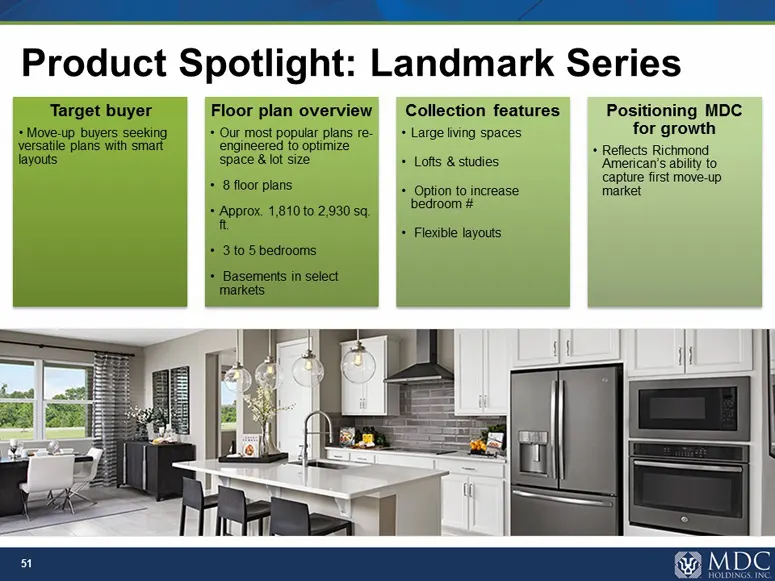
Slide 51: Product Spotlight: Landmark Series
Product Spotlight: Landmark Series Target buyer Floor plan overview + Move-up buyers seeking + Our most popular plans re- versatile plans with smart engineered to optimize layouts space & lot size * 8 floor plans y Bucks 1,810 to 2,930 sq. + 30 5 bedrooms Collection features + Large living spaces Po
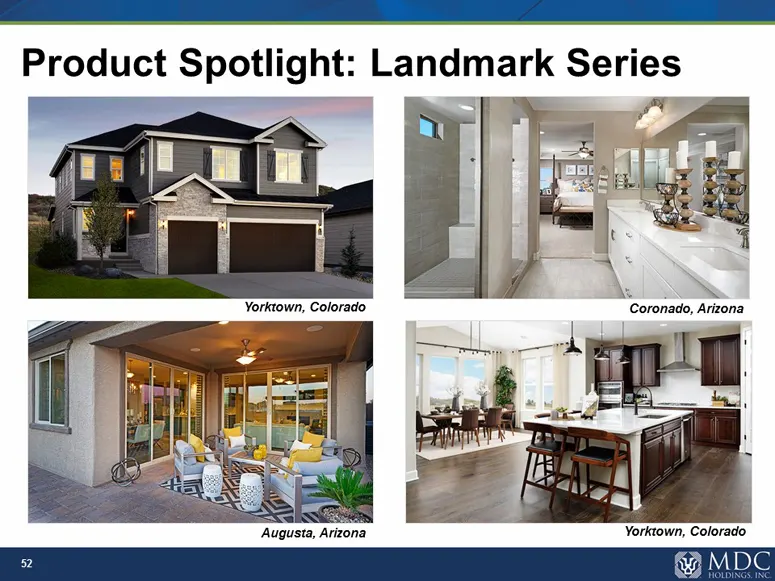
Slide 52: Product Spotlight: Landmark Series
Product Spotlight: Eandmatk Series Augusta, Arizona
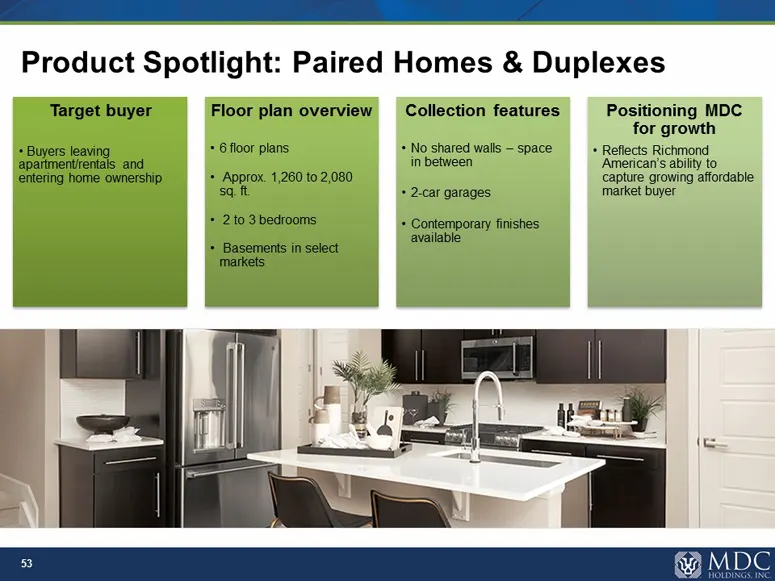
Slide 53: Product Spotlight: Paired Homes & Duplexes
Product Spotlight: Paired Homes & Duplexes Target buyer Floor plan overview = Buyers leavi * 6 floor plans apartment/rental entering home ownership oe ee sq. + 210 3 bedrooms + Basements in select 53 Collection features —_ Positioning MDC. for growth + No shared walls ~ space + Reflects Richmond in
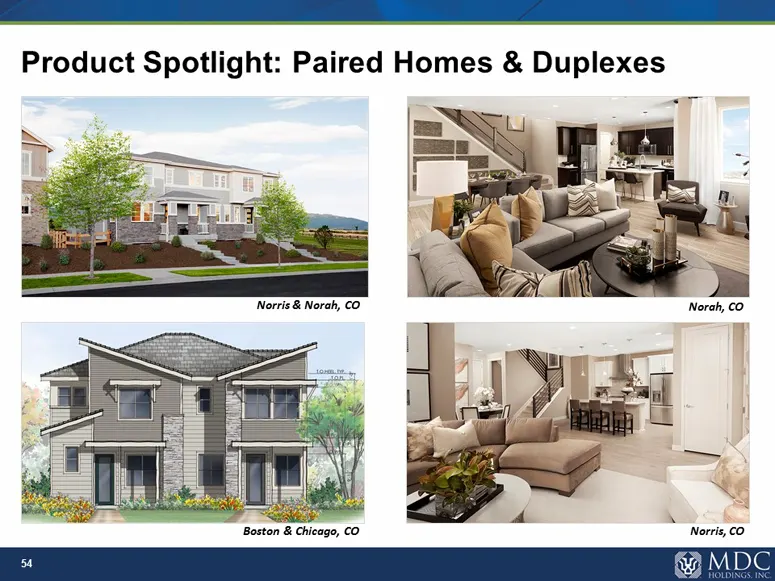
Slide 54: Product Spotlight: Paired Homes & Duplexes
Product Spotlight: Paired Homes & Duplexes
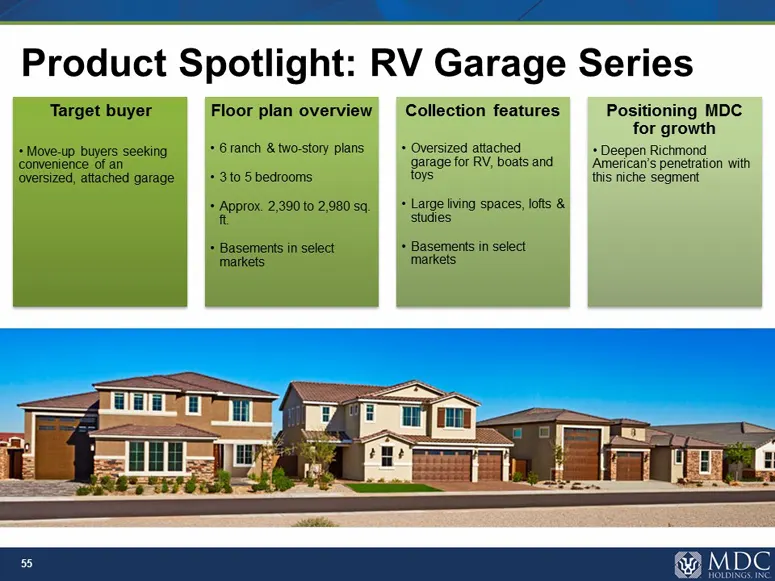
Slide 55: Product Spotlight: RV Garage Series
7— Sa Product Spotlight: RV Garage Series Target buyer Floor plan overview, Collection features — Positioning MDC for growth + Move-up buyers seeking * Granch & two-story plans + Oversized attached = Deepen Richmond convenience of an garage for RV, boats and American’s penetration with oversized, at
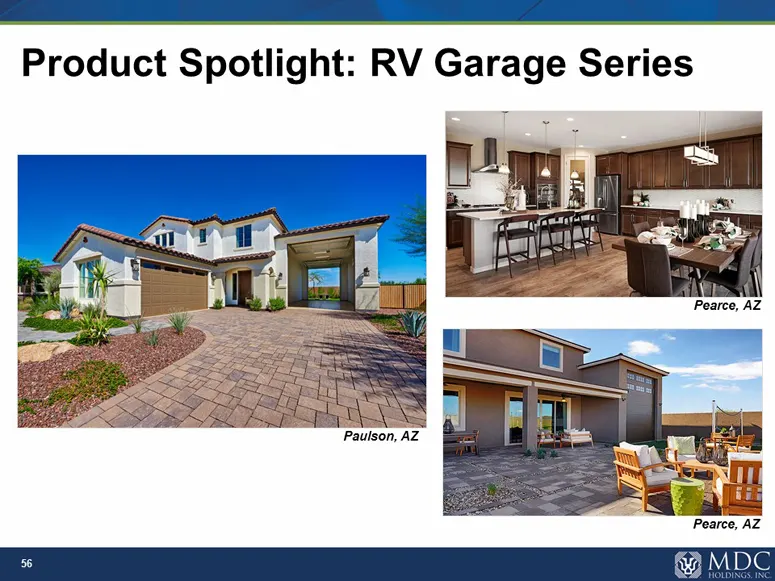
Slide 56: Product Spotlight: RV Garage Series
Product Spotlight: RV Garage Series
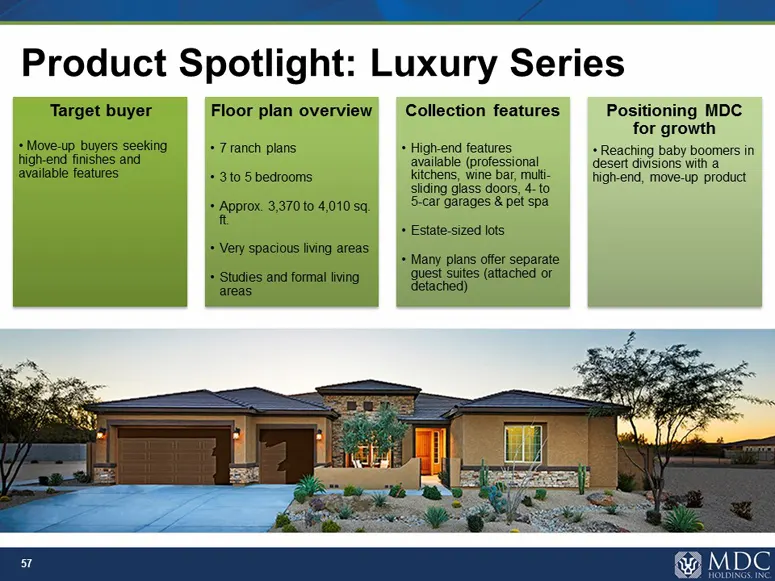
Slide 57: Product Spotlight: Luxury Series
Product Spotlight: Luxury Series Target buyer Floor plan overview + Move-up buyers seeking high-end finishes and available features + 7ranch plans + 3to 5 bedrooms SEER uN ACTED = Very spacious living areas + Studies and formal living areas Collection features + High-end features available (professi
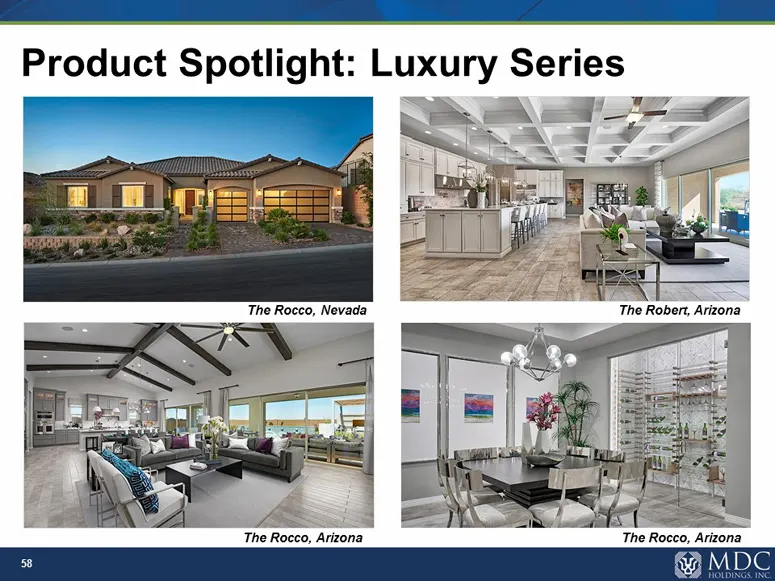
Slide 58: Product Spotlight: Luxury Series
Product Spotlight: Luxury Series Teg Le ee Ce aA The Rocco, Arizona a @ MDC
Slide 59: Committed to Expanding Affordable Product Set
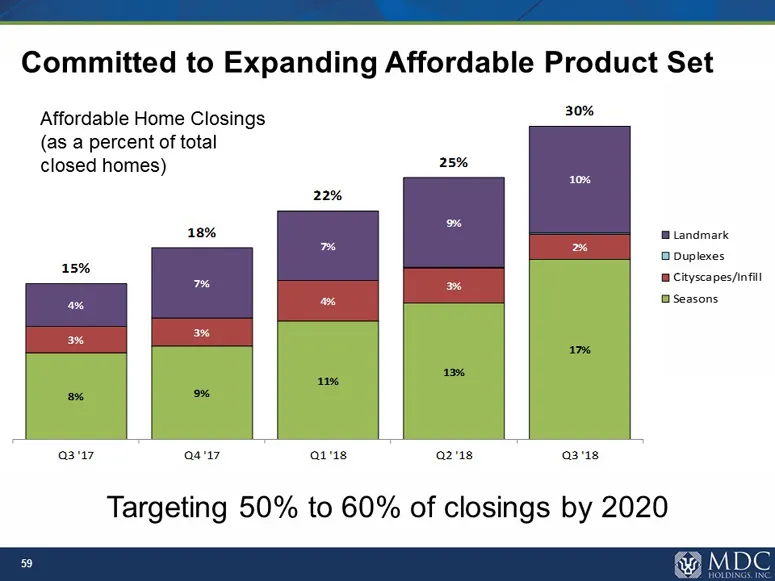
Committed to Expanding Affordable Product Set Affordable Home Closings (as a percent of total closed homes) 30% 25% 22% 18% Landmark 1D Duplexes 15% W Cityscapes/infill Seasons 1% 13% 11% oe o% a3'7 aay ans a218 9318 Targeting 50% to 60% of closings by 2020
Slide 60: Build-to-Order Model
Build-to-Order Model & MDC HOLDINGS, INC
Slide 61: Market Feedback: Buyers Want Personalization
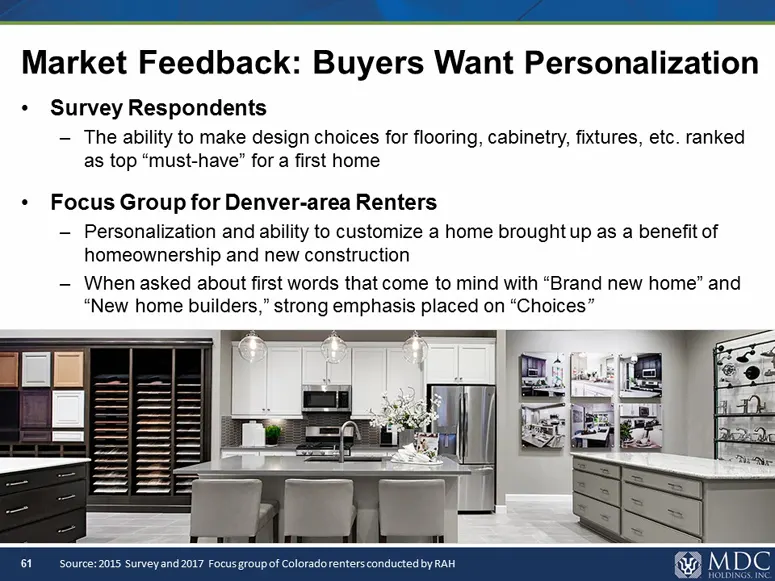
a a Market Feedback: Buyers Want Personalization + Survey Respondents — The ability to make design choices for flooring, cabinetry, fixtures, etc. ranked as top “must-have” for a first home + Focus Group for Denver-area Renters - Personalization and ability to customize a home brought up as a benefi
Slide 62: Build-to-Order Model
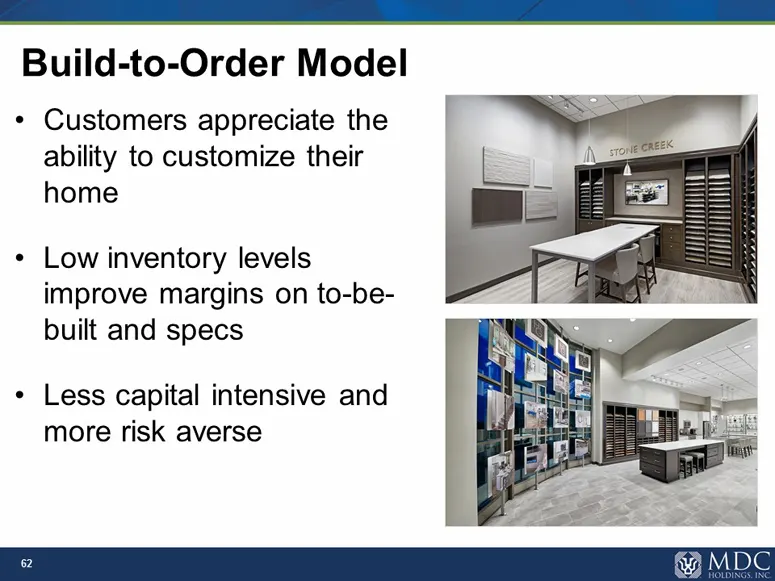
7— Sa Build-to-Order Model * Customers appreciate the ability to customize their home * Low inventory levels improve margins on to-be- built and specs * Less capital intensive and more risk averse
Slide 63: Build-to-Order Model
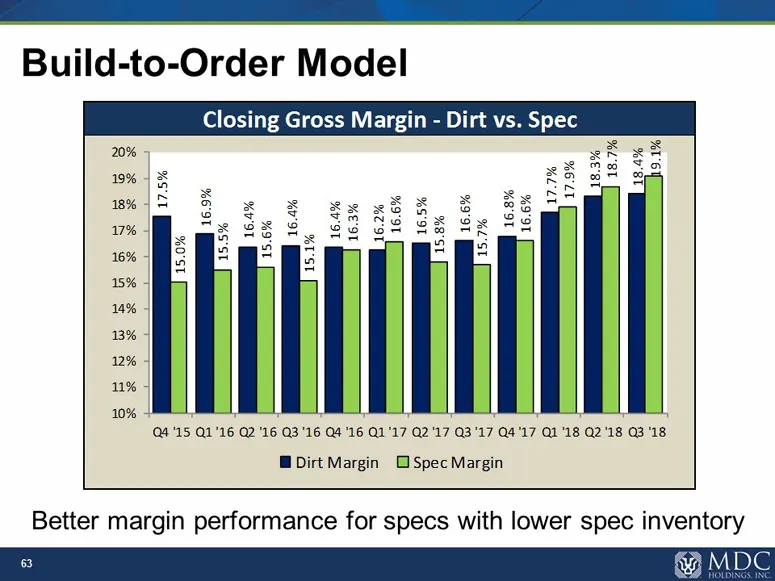
Build-to-Order Model 8 16.4% 16.4% 15.1% Q4'15 Q1'16 Q2 16 Q3'16 Q4 16 Q1'17 Q2‘17 Q3'17 Q4'17 Ql 18 Q2'18 Q3 ‘18 Dirt Margin Gi Spec Margin Better margin performance for specs with lower spec inventory
Slide 64: Build-to-Order Model
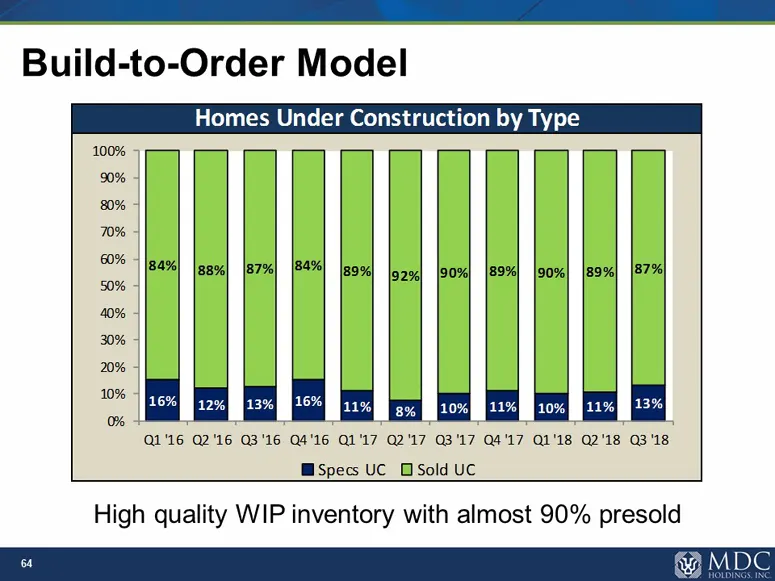
—— SS Build-to-Order Model 100% > *| 84%! |sae6| |87%! 184%) Ig0%| |o>5: |o0% |89%| |a0%| |e9%| |87% 8% Q1'16 Q2'16 Q3'16 Q4'16 QL'17 Q2'17 0317 Q4'17 Q1'18 Q2'18 0318 specs UC_B Sold UC High quality WIP inventory with almost 90% presold
Slide 65: Questions? 15-Minute Break
Questions? 15-Minute Break & MDC HOLDINGS, INC
Slide 66: Market Spotlight
Market Spotlight MPC
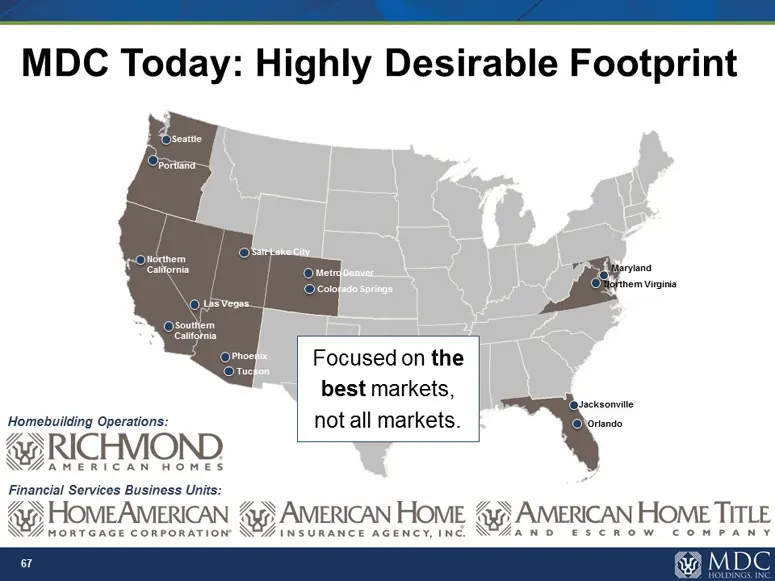
Slide 67: MDC Today: Highly Desirable Footprint
MDC Today: Highly Desirable Footprint Focused on the best markets, Homebuilding Operations: not all markets. aaa aS )RICHVIOND % NOZ aM ERICAN HOMES Financial Services Business Units: @ HOMEAMERICAN @% AMERICAN HOME 4%} AMERICAN HOME TITLE WY montcace corporation \OZinsurance acency, inc. \OZann esc
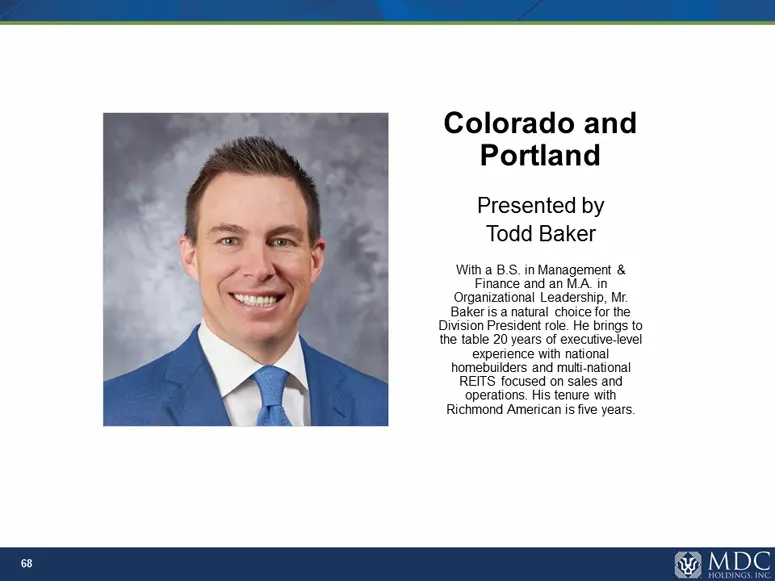
Slide 68: Colorado and Portland
Colorado and Portland Presented by Todd Baker With a B.S. in Management & Finance and an MA in Organizational Leadership, Mr. Baker is a natural choice for the Division President role. He brings to the table 20 years of executive-level experience with national homebuilders and multi-national REITS f
Slide 69: Colorado: Competitive Advantage
a a Colorado: Competitive Advantage 1) Affordability — 30% of our product is Seasons™ + Perfectly placed for affordability-minded buyers + — High margins, low construction times 2) Brand — Historically led market share in Colorado + Respected and recognized + Buying power and local reputation give u
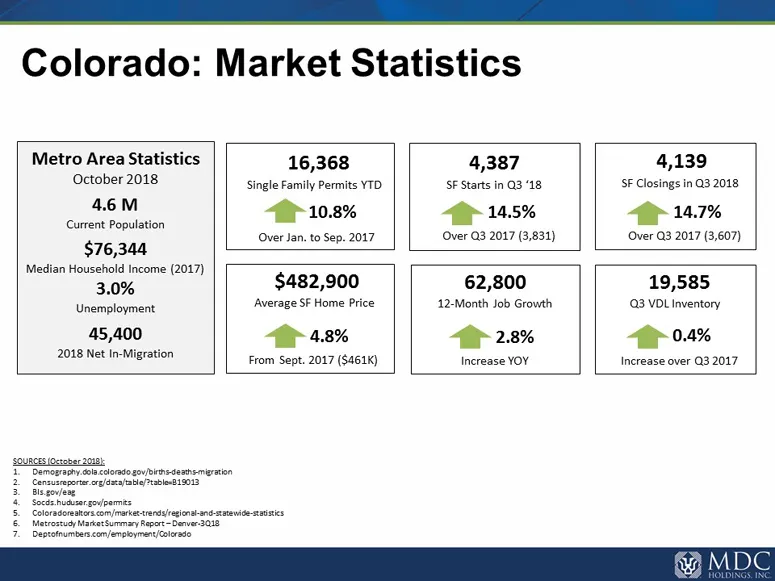
Slide 70: Colorado: Market Statistics
7— Sa Colorado: Market Statistics Metro Area Statistics 16,368 4,387 4,139 October 2018 ‘Single Family Permits YTD SF Starts in Q3 ‘18 SF Closings in Q3 2018, soe “10.8% 14.5% 14.7% coca cases ‘Over Jan. to Sep. 2017 ‘Over Q3 2017 (3,831) Over Q3 2017 (3,607) $76,344 Median Household Income (2017) 3
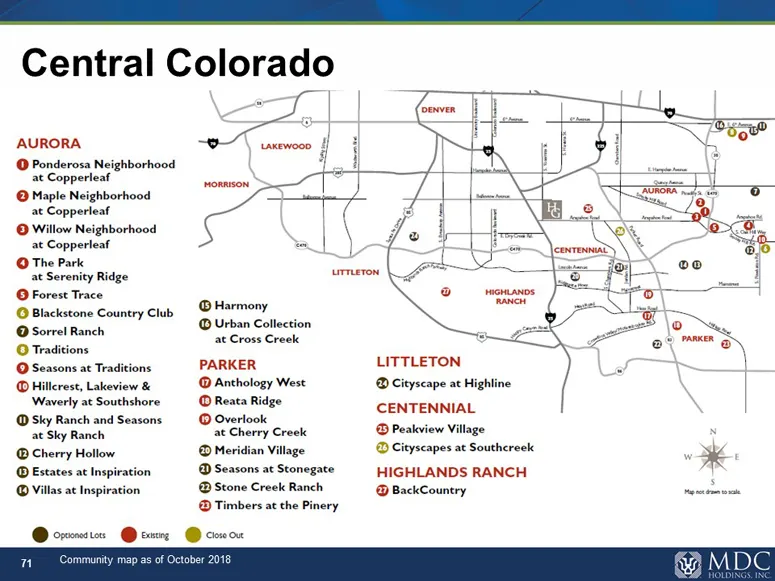
Slide 71: Central Colorado
Central Colorado AURORA © Ponderosa Neighborhood at Copperleaf @ Maple Neighborhood at Copperleaf © Willow Neighborhood at Copperleaf Q The Park at Serenity Ridge © Forest Trace © Blackstone Country Club @ Sorrel Ranch Q Traditions Q Seasons at Traditions Hillerest, Lakeview & Waverly at Southshore
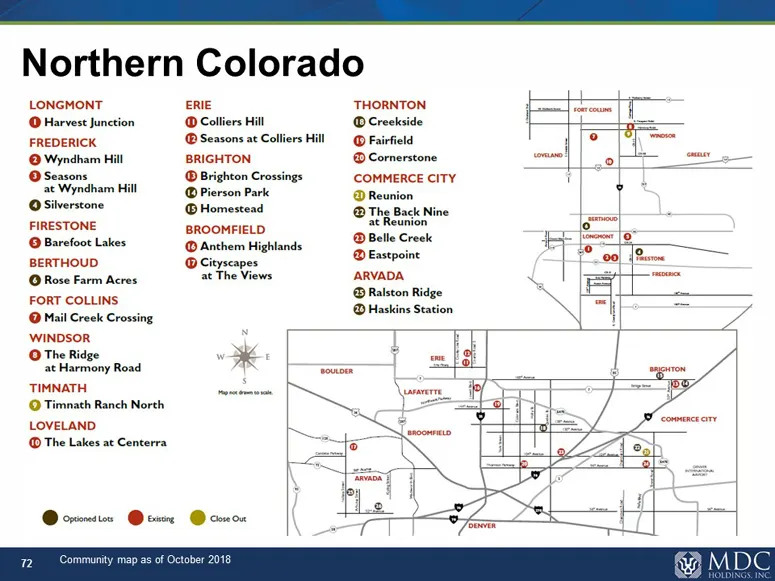
Slide 72: Northern Colorado
7— Sa Northern Colorado \ LONGMONT ERIE THORNTON aad @ Harvest Junction Colliers Hill OCreekside — Pace @Seasons at Colliers Hill @ Fairfield @ Wyndham Hill BRIGHTON @ Cornerstone O Seasons ei @ Brighton Comins COMMERCE CITY at Wyndham Hil Pierson Park @ Reunion OSiverstone Homescead @ The Back Nine
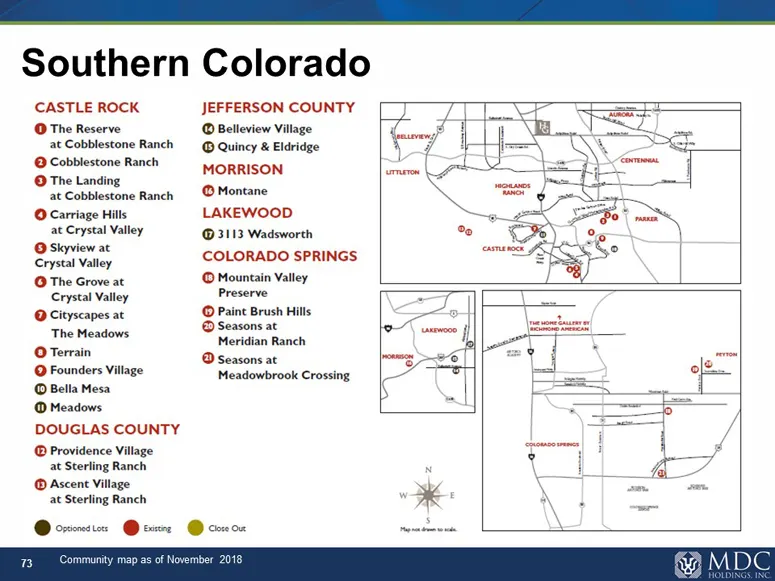
Slide 73: Southern Colorado
Southern Colorado CASTLE ROCK JEFFERSON COUNTY The Reserve © Belleview Village at Cobblestone Ranch @ Quincy & Eldridge (OC cotleseare Ranch MORRISON © The Landing at Cobblestone Ranch © Montane O Carriage Hills LAKEWOOD scoreiNaer ©3113 Wadsworth © Skyview at Crystal Valley COLORADO SPRINGS The Gro
Slide 74: Portland: Competitive Advantage
a a Portland: Competitive Advantage 1) Affordability - 40% of our future product is Seasons™ * Perfectly placed for affordability-minded buyers * High margins, low construction times 2) “With us, it’s personal’ strategy * The ability to personalize the customers’ choice through selecting a lot, plan
Slide 75: Portland Division: Market Statistics
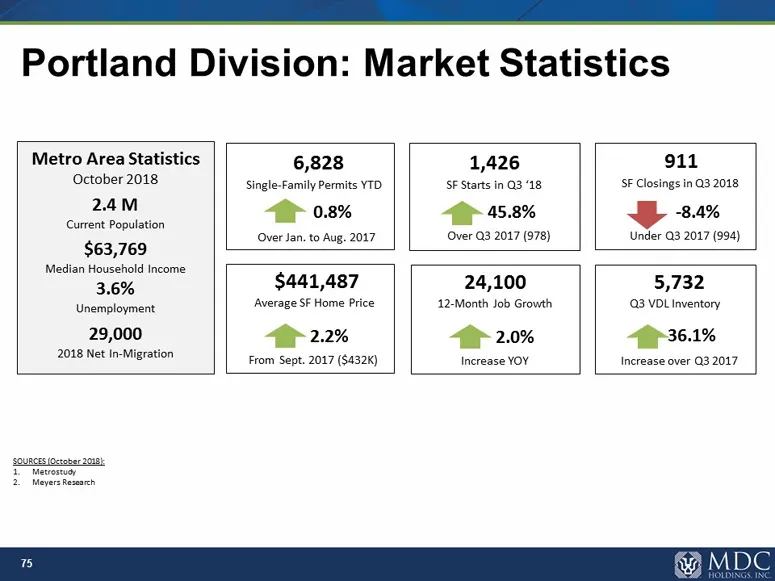
7— Sa Portland Division: Market Statistics Metro Area Statistics 6,828 1,426 911 October 2018 Single-Family Permits YTD SF Starts in Q3 ‘18 SF Closings in Q3 2018 2.4M A sneieattin om Be 5% oo Over Jan, to Aug. 2017 Over 03 2017 (978) Under 03 2017 (994) $63,769 fein ees ee $441,487 24,100 5,732 Ave
Slide 76: Portland
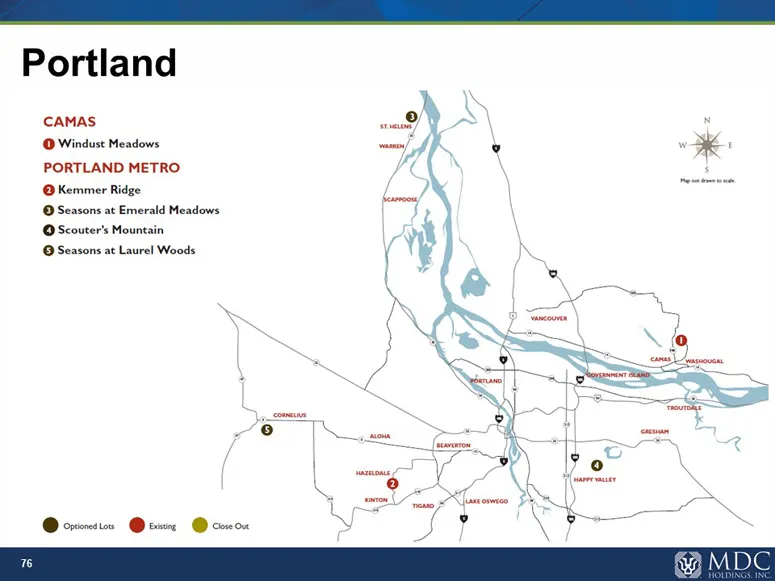
7— Sa Portland ‘CAMAS @ Windust Meadows PORTLAND METRO @ Kemmer Ridge © Seasons at Emerald Meadows O crintion @ tacy @ concn 16
Slide 77: Nevada and Riverside
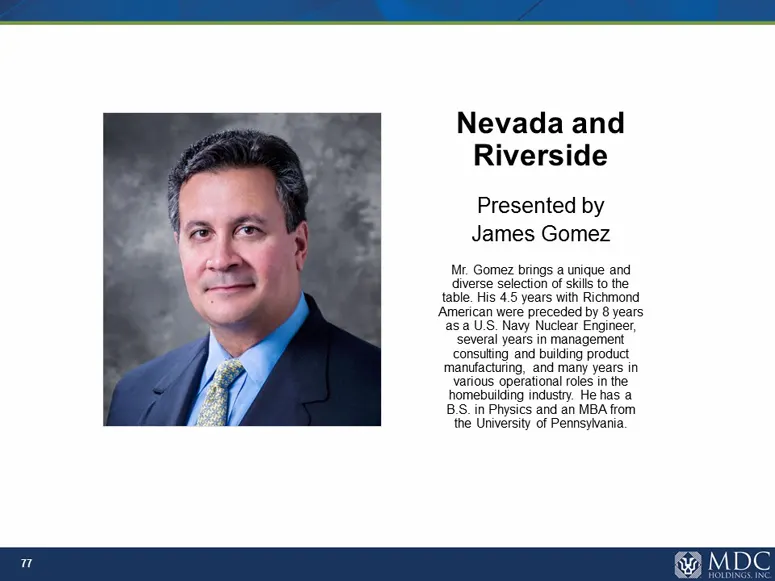
7 Nevada and Riverside Presented by James Gomez Mr. Gomez brings a unique and diverse selection of skills to the table. His 4.5 years with Richmond ‘American were preceded by 8 years asa US. Navy Nuclear Engineer, ‘several years in management consulting and building product manufacturing, and many y
Slide 78: Nevada: Competitive Advantage
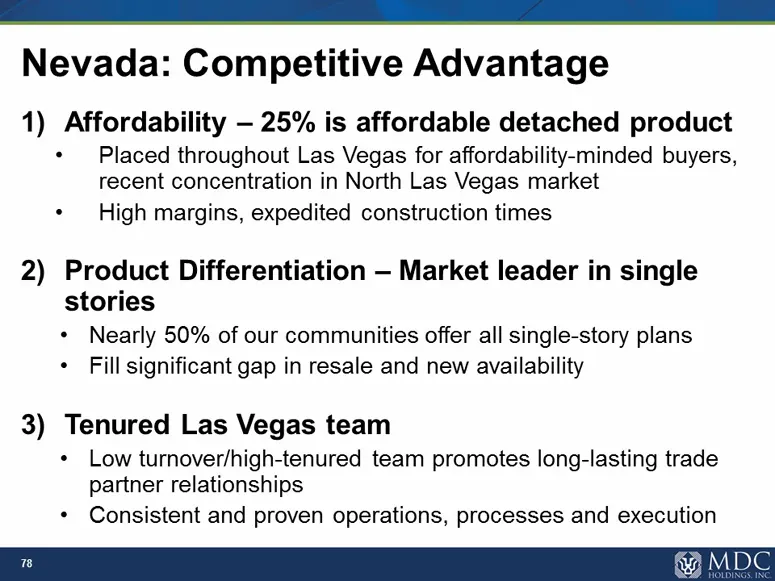
ee NE, Nevada: Competitive Advantage 1) Affordability - 25% is affordable detached product + Placed throughout Las Vegas for affordability-minded buyers, recent concentration in North Las Vegas market + High margins, expedited construction times 2) Product Differentiation — Market leader in single s
Slide 79: Nevada Division: Market Statistics
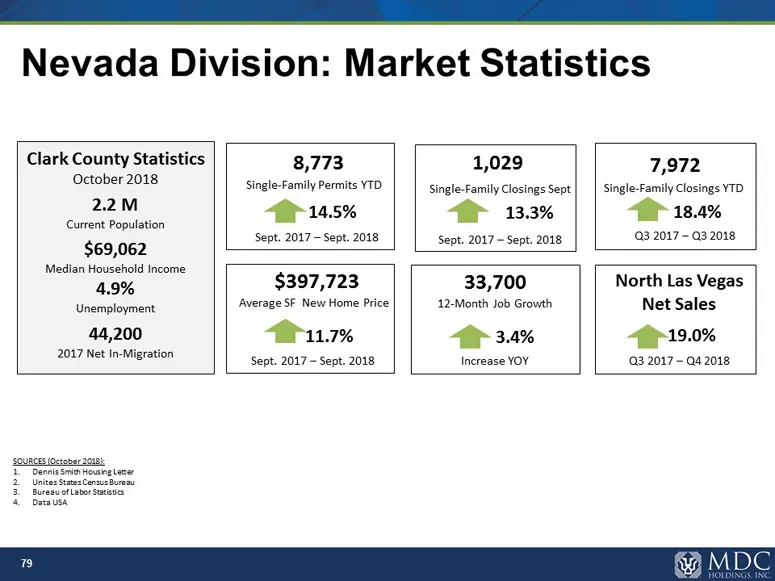
Nevada Division: Market Statistics Clark County Statistics 8,773 1,029 7,972 @arekavas Single-Family Permits YTD. Single-Family Closings Sept ily Closings YTD 2.2M exrmerrn Bass @ vx Cay Sept. 2017 ~ Sept 2018 Sept. 2017 ~ Sept. 2018 03 2017-03 2018 Pree eae told eee 4.9% $397,723 33,700 North Las V
Slide 80: Nevada
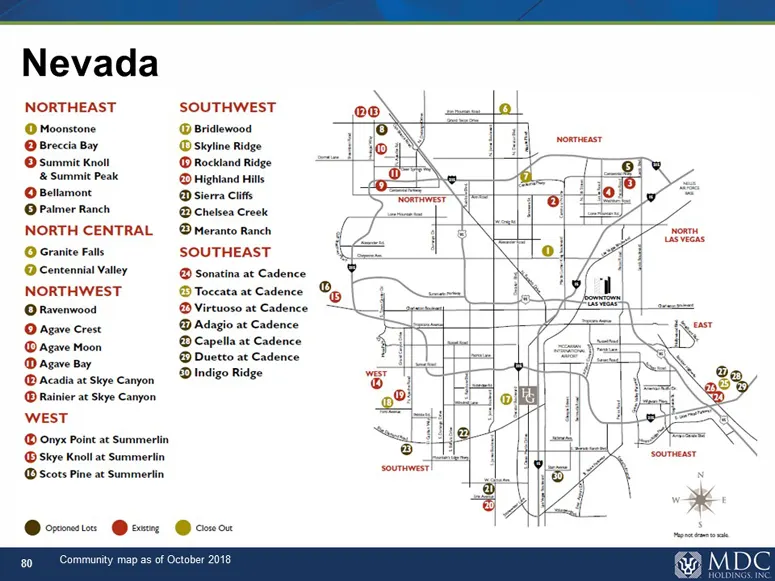
7— Sa Nevada NORTHEAST SOUTHWEST Q Moonstone Bridlewood © Breccia Bay DO skyline Ridge © Summie Knott ‘Rockland Ridge & Summit Peak Highland His OBetlamone D Sierra cits © Paimer Ranch chelsea Creek NORTH CENTRAL — @Meranto Ranch d © Granite Falls SOUTHEAST © Centennial Valley @ Sonatina at Cadence
Slide 81
Slide 82
Slide 83
Slide 84
Slide 85
Slide 86
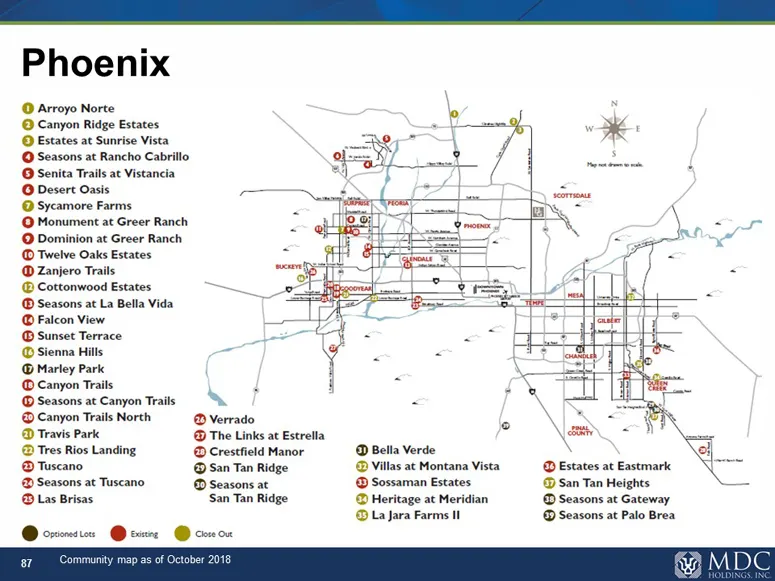
Slide 87
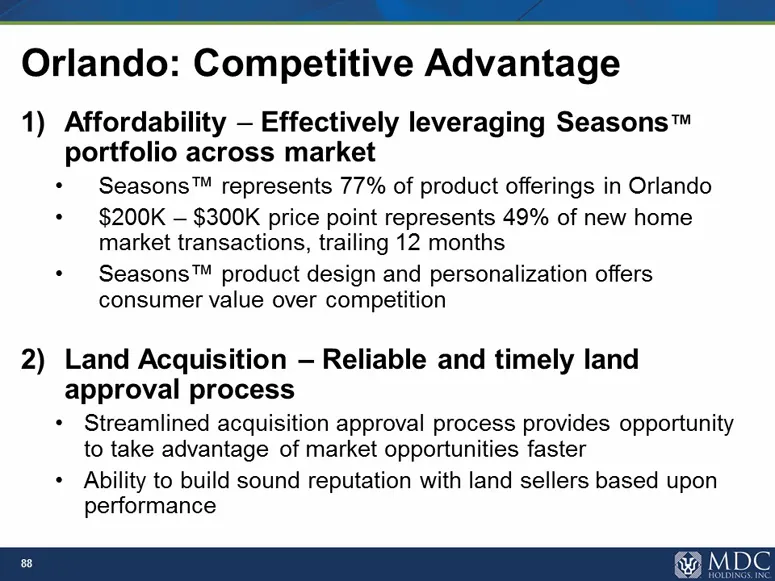
Slide 88
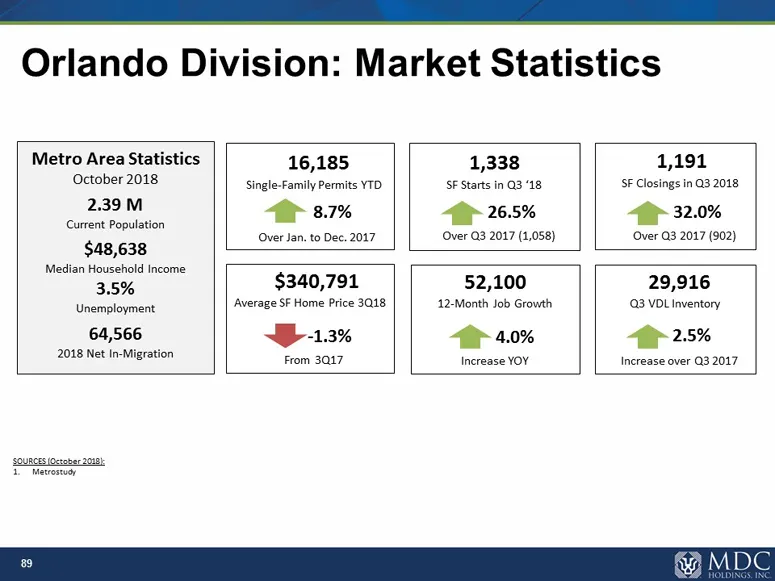
Slide 89
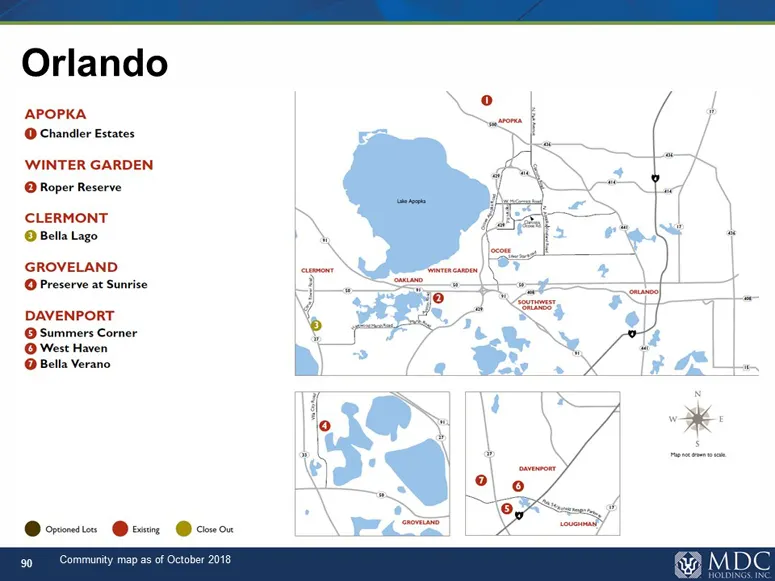
Slide 90
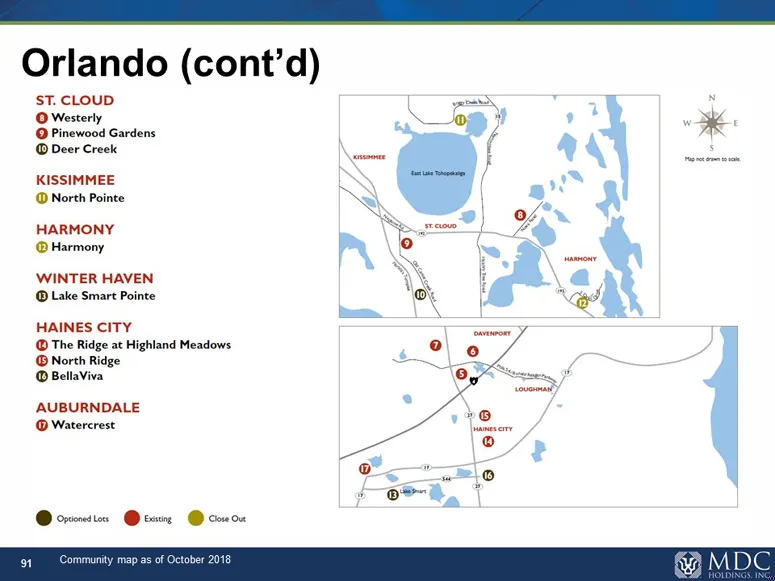
Slide 91
Slide 92
Slide 93
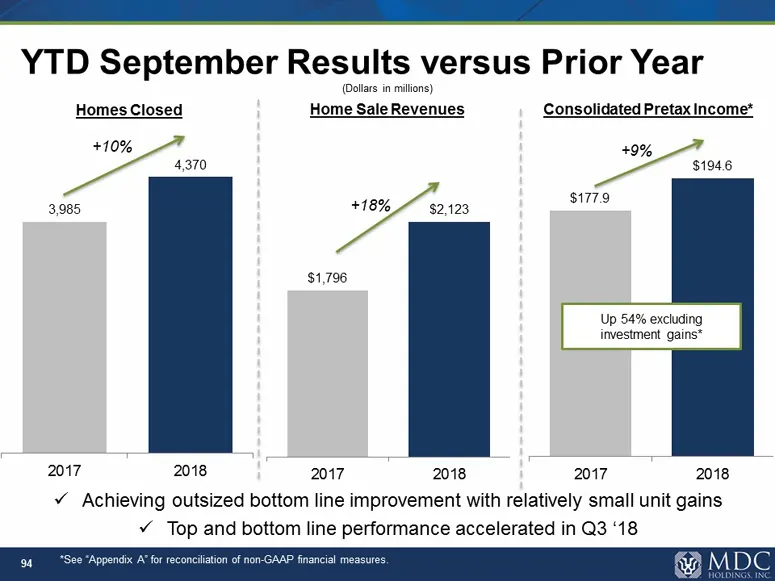
Slide 94
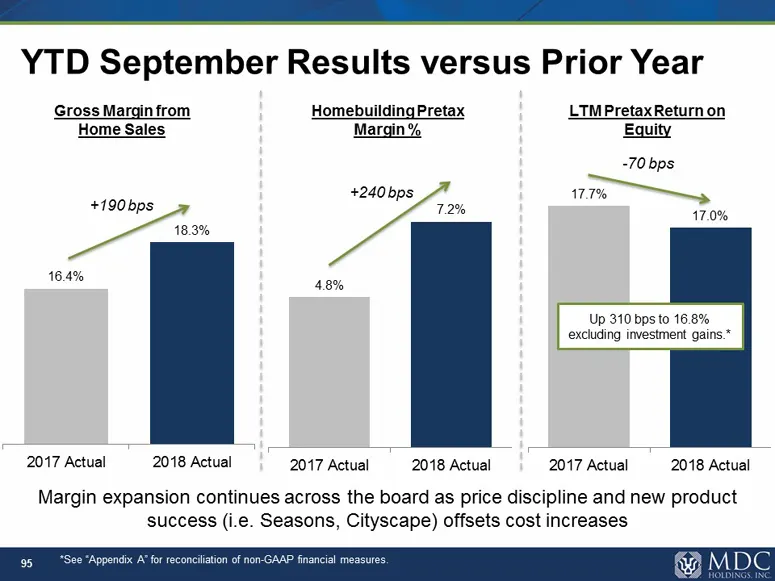
Slide 95
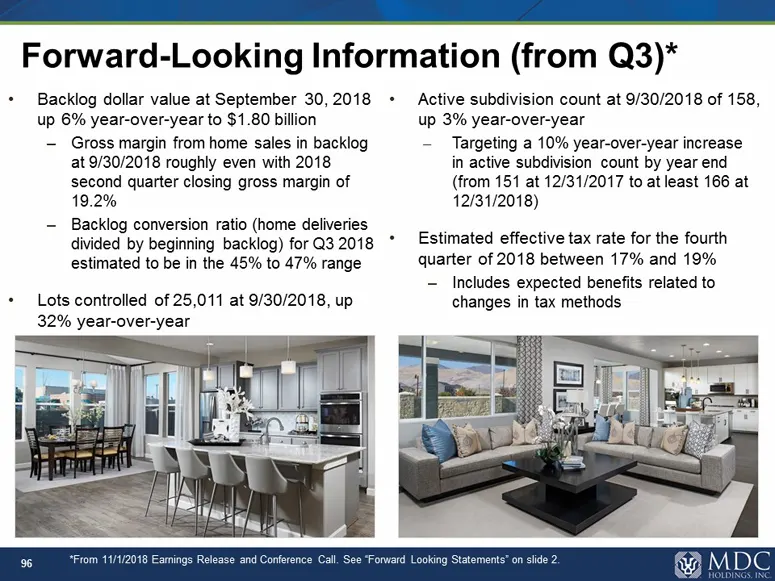
Slide 96
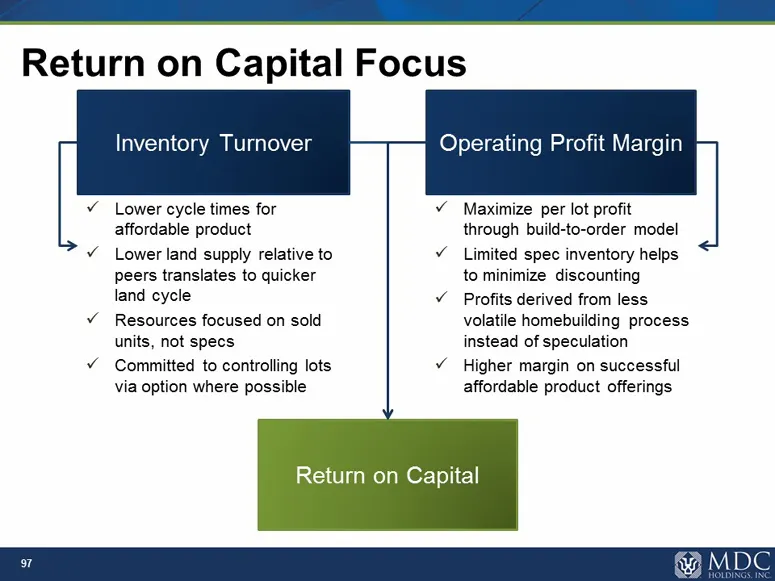
Slide 97
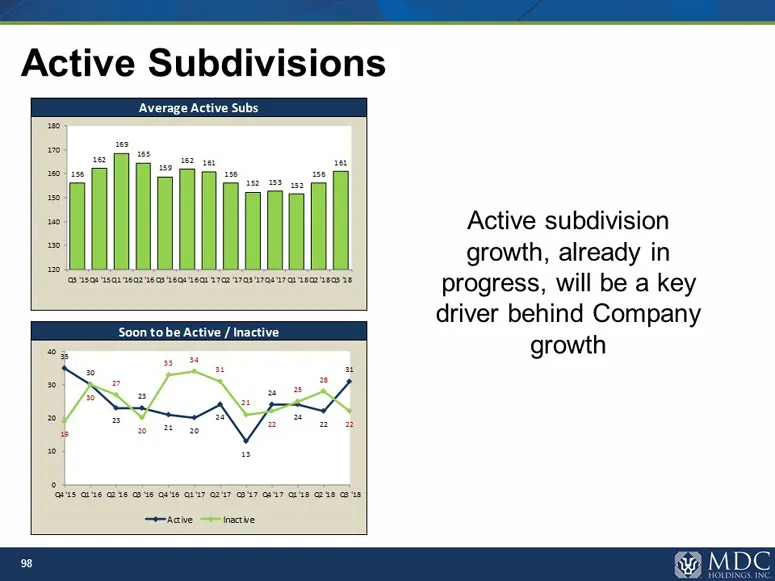
Slide 98
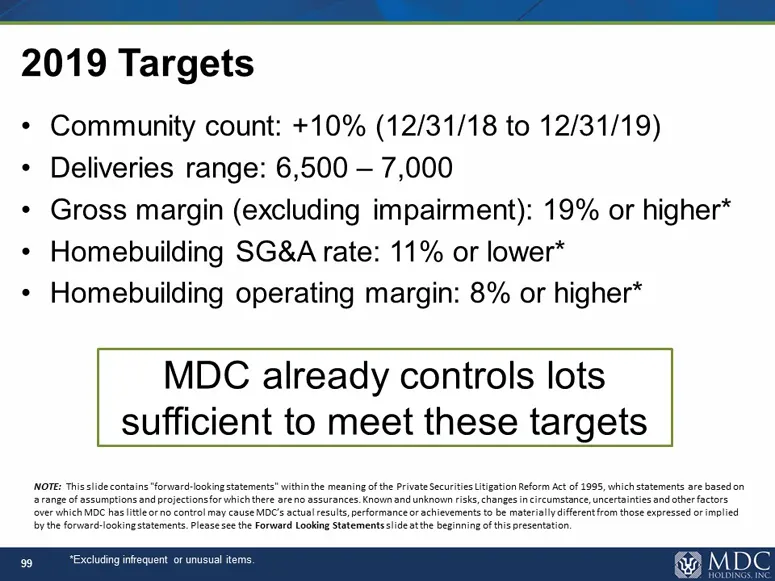
Slide 99
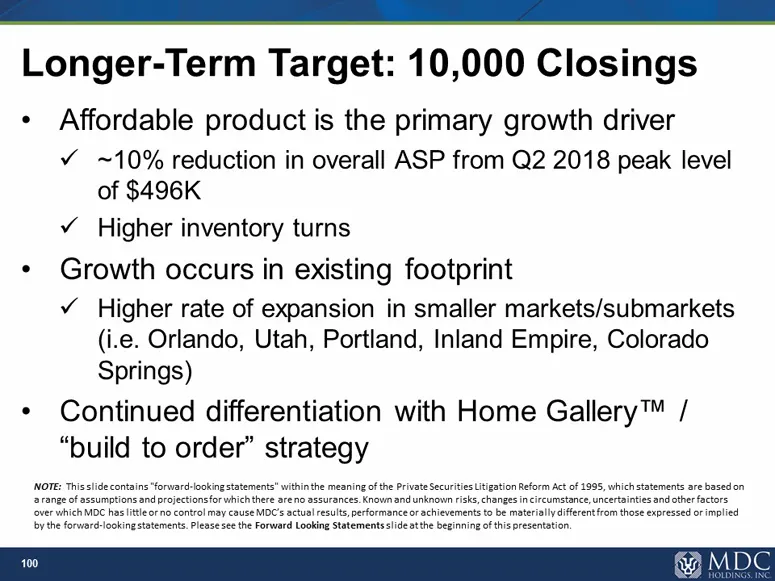
Slide 100
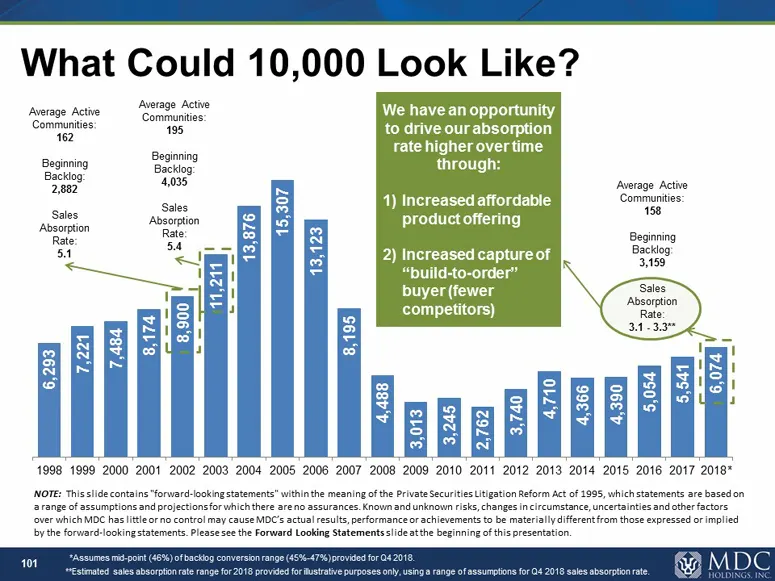
Slide 101
Slide 102
Slide 103
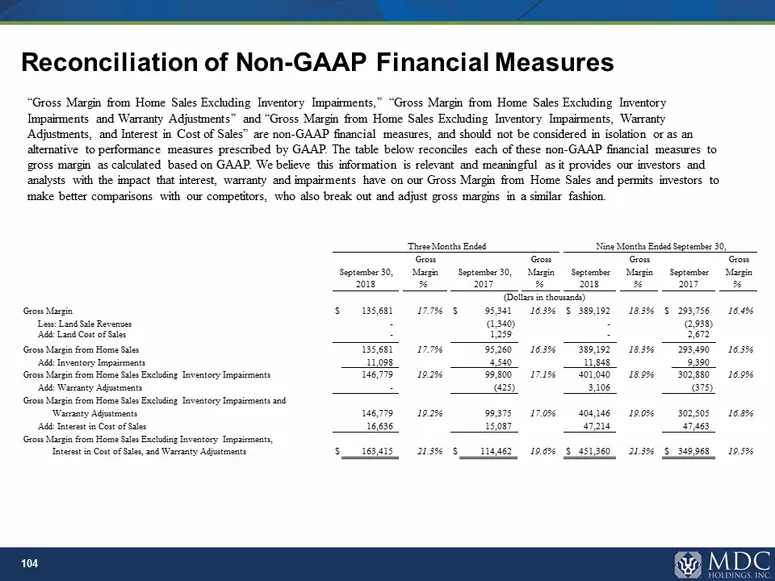
Slide 104
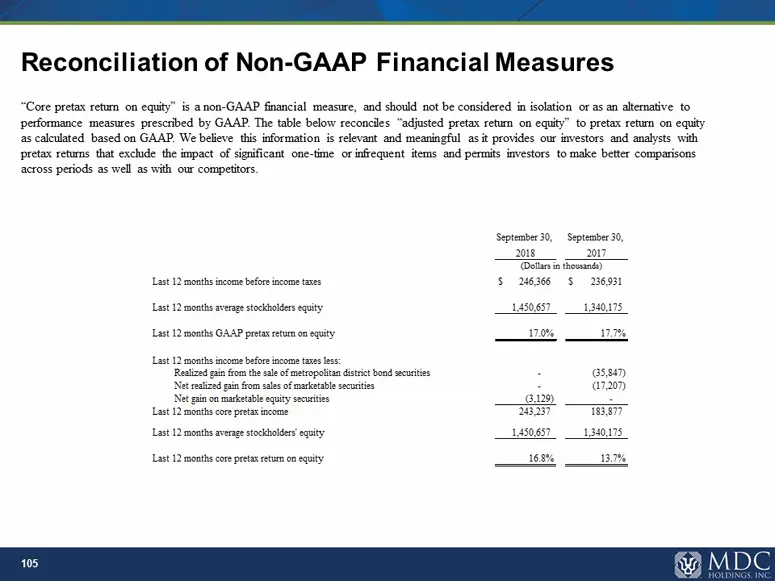
Slide 105
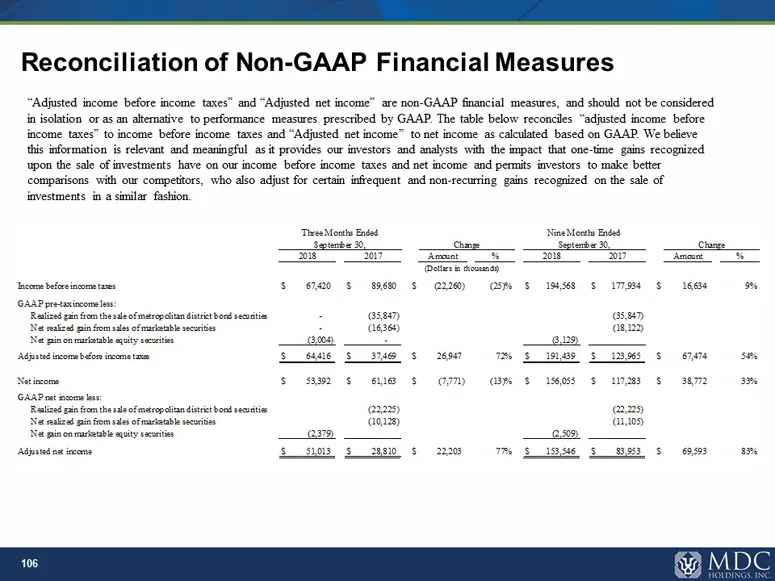
Slide 106
Slide 107
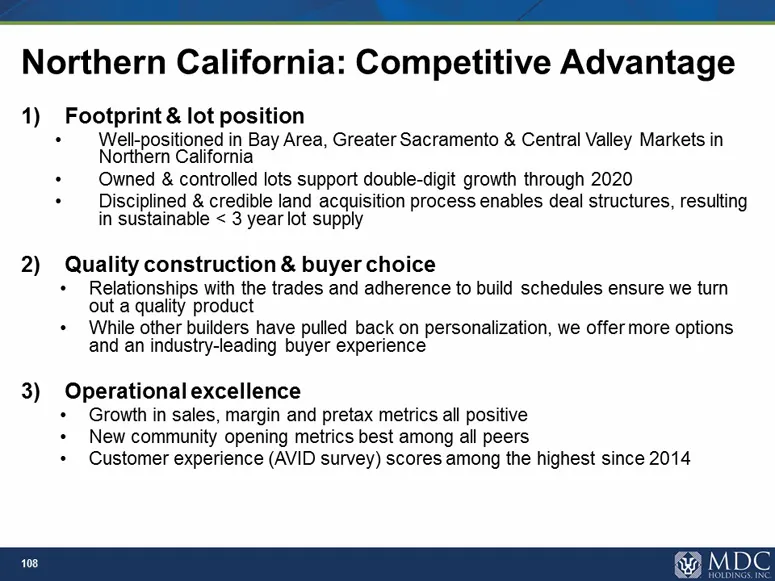
Slide 108
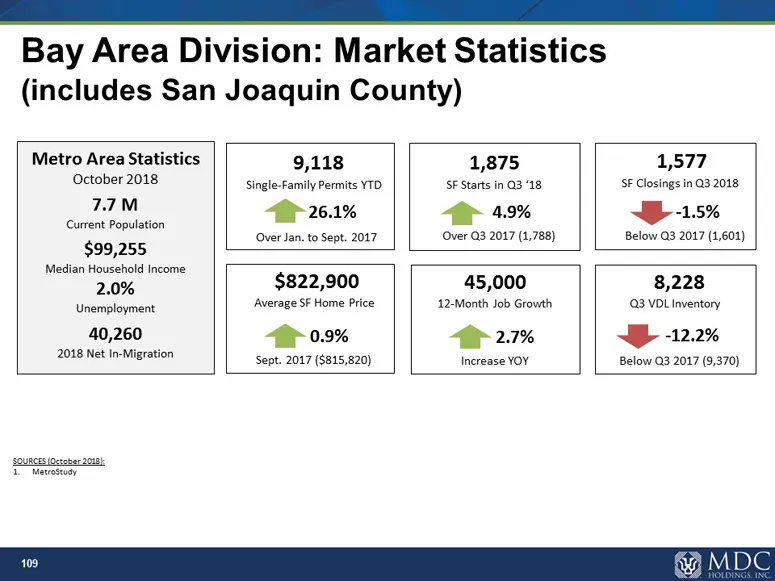
Slide 109
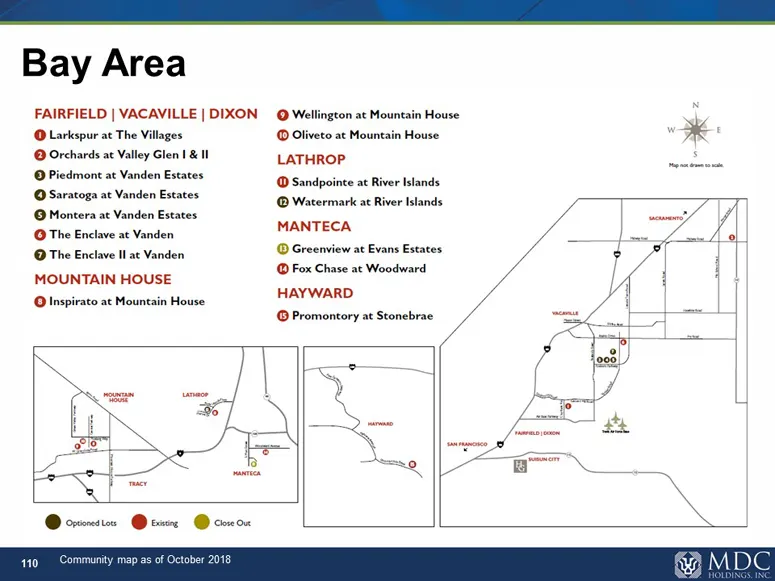
Slide 110
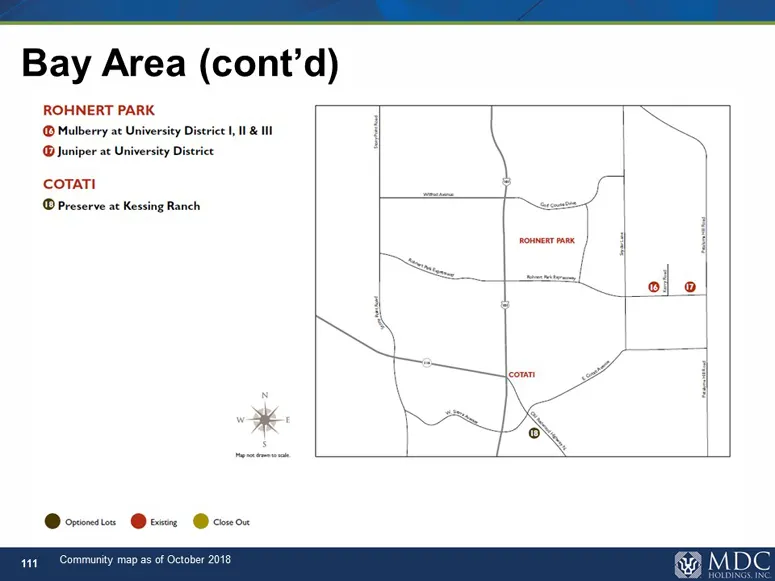
Slide 111
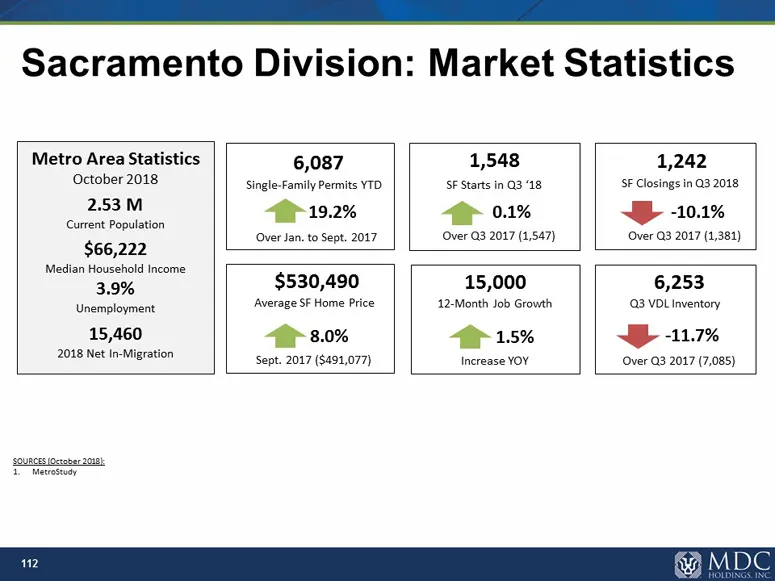
Slide 112
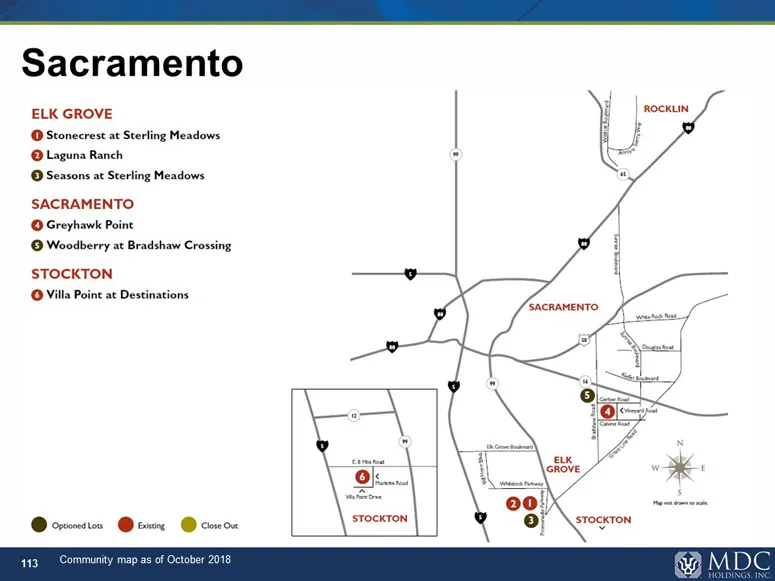
Slide 113
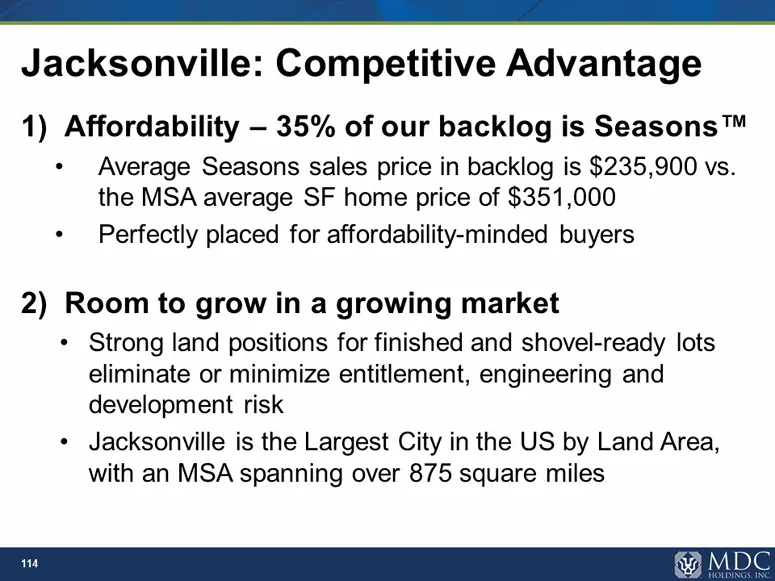
Slide 114
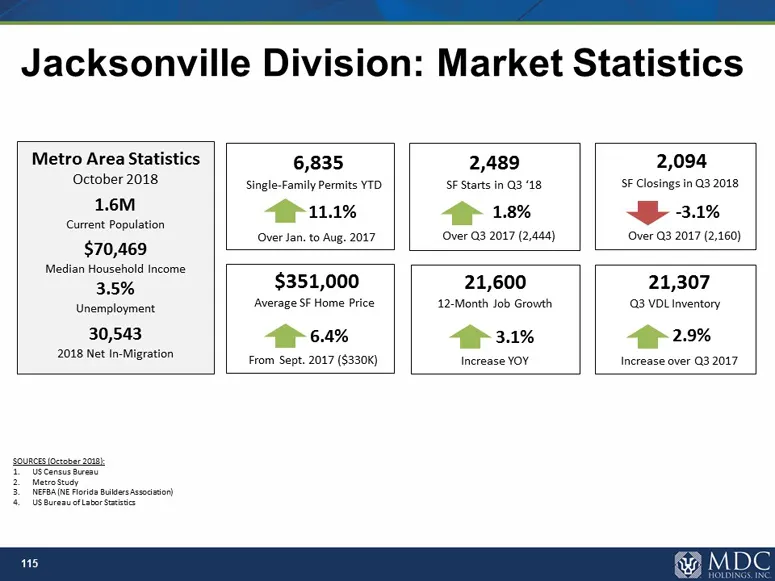
Slide 115
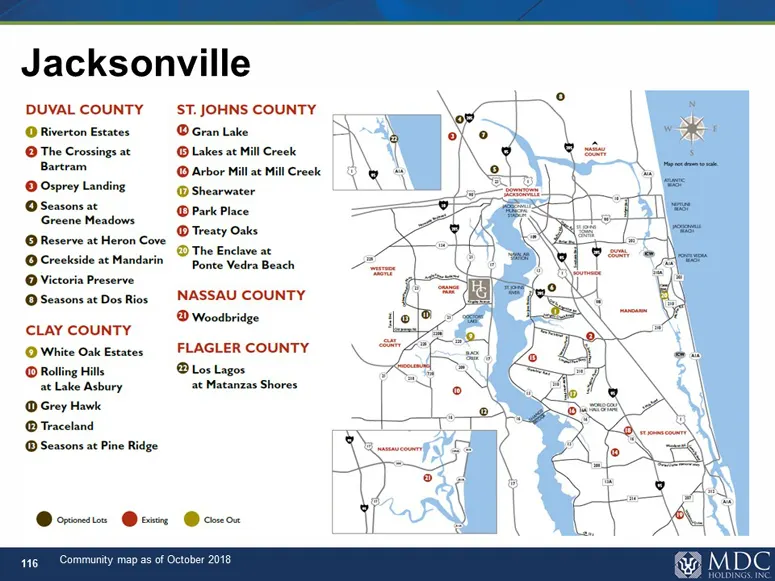
Slide 116
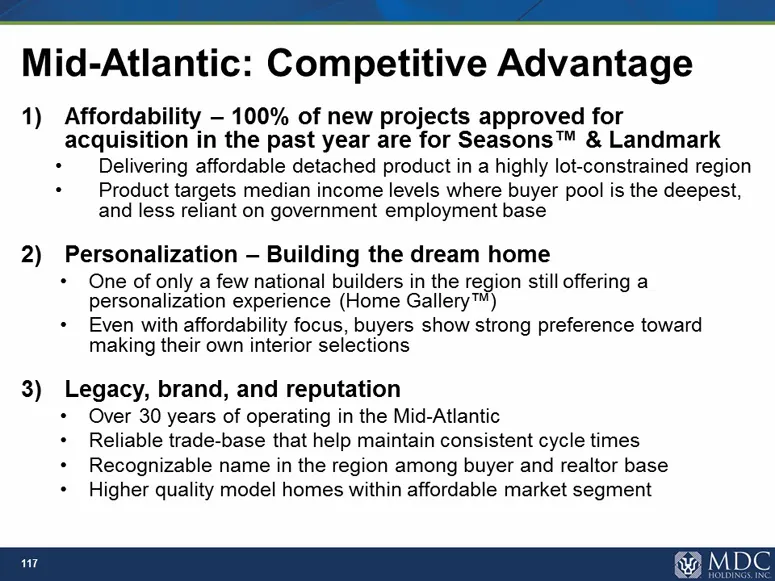
Slide 117
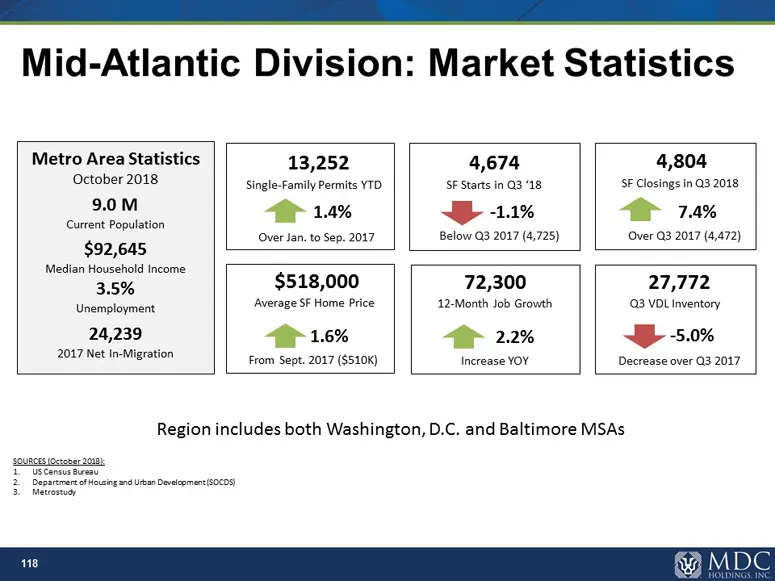
Slide 118
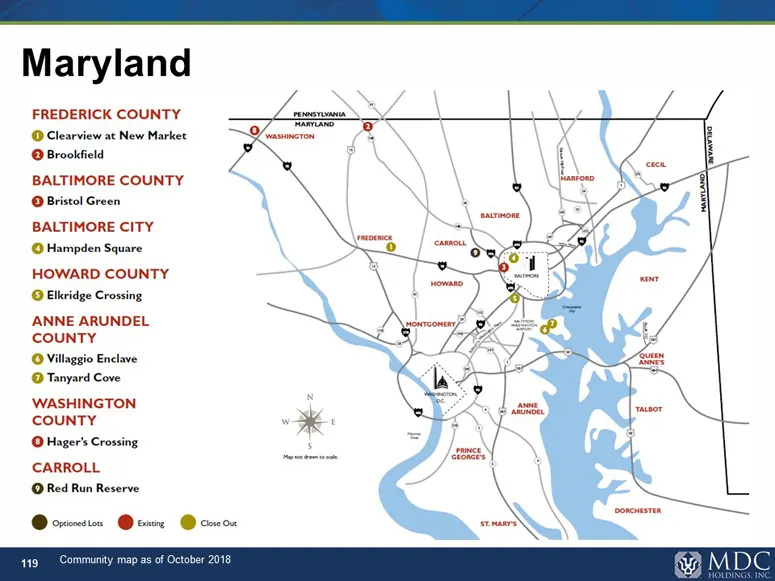
Slide 119
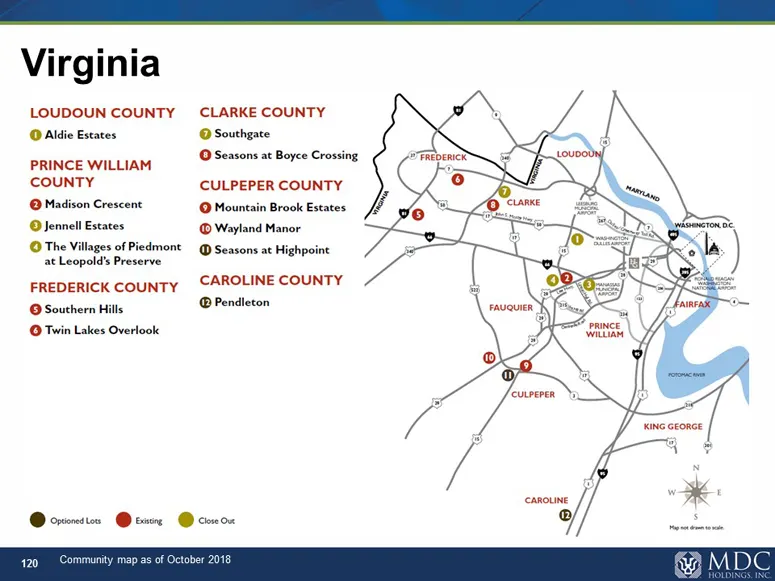
Slide 120
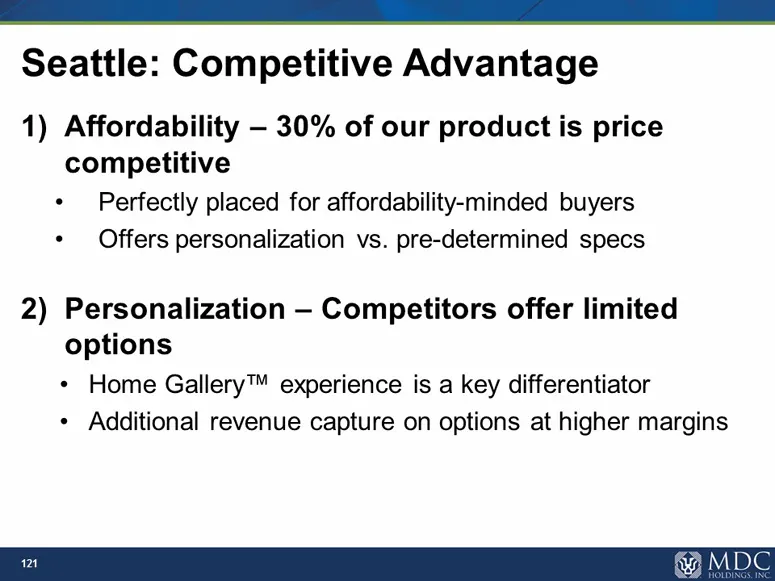
Slide 121
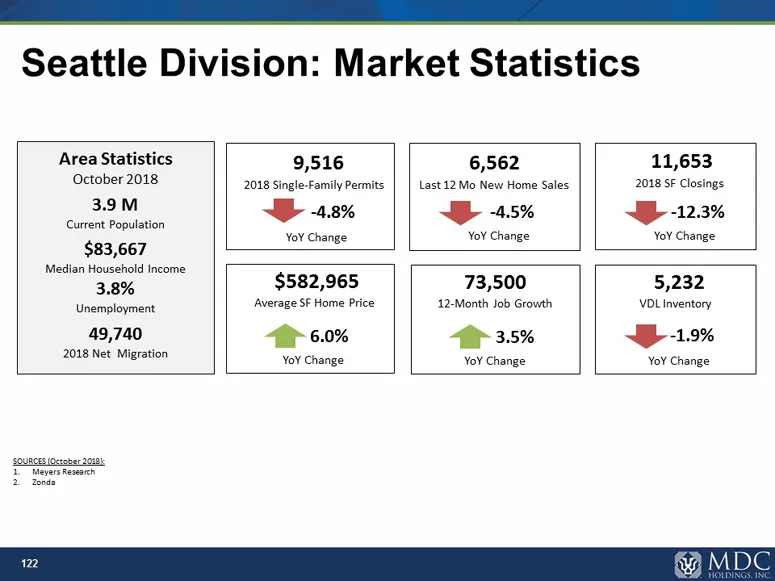
Slide 122
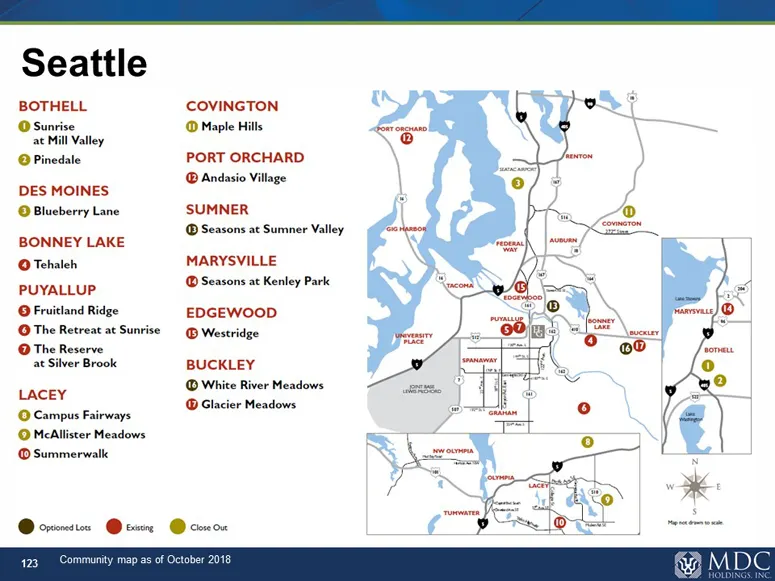
Slide 123
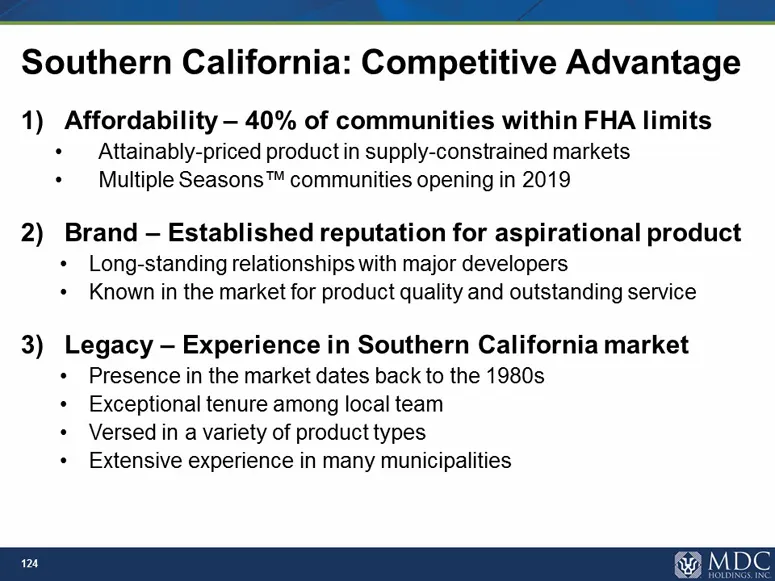
Slide 124
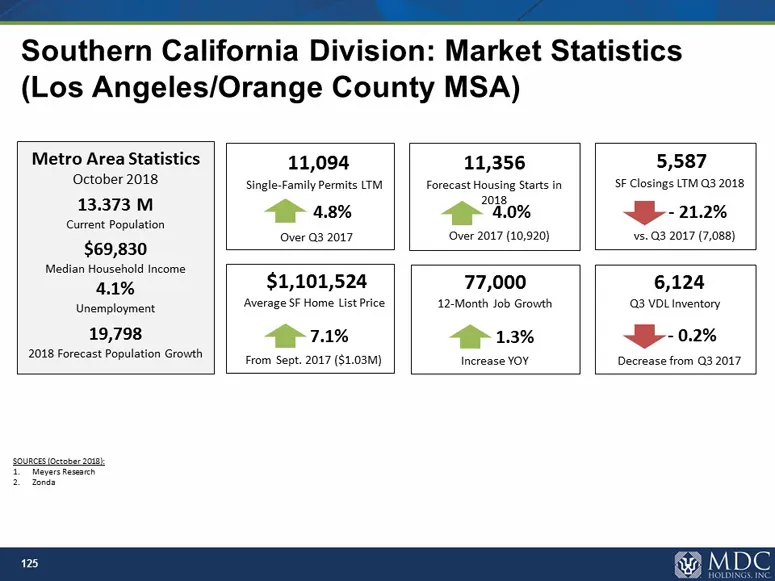
Slide 125
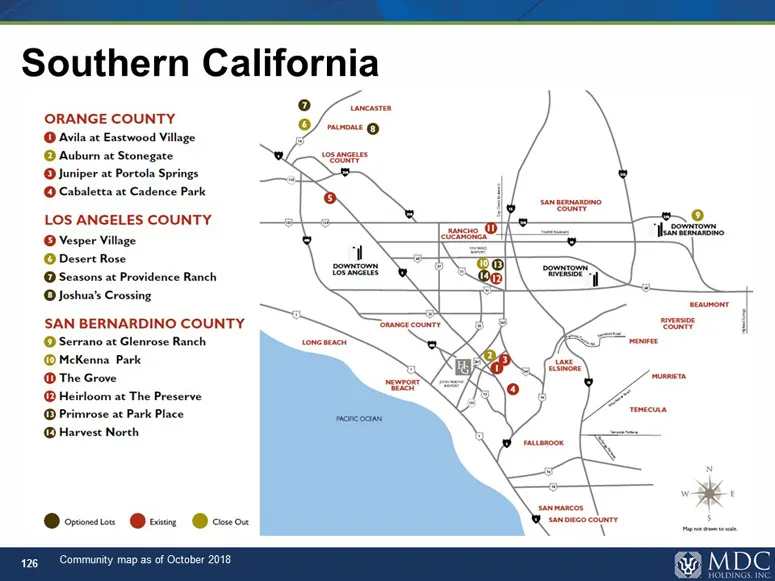
Slide 126
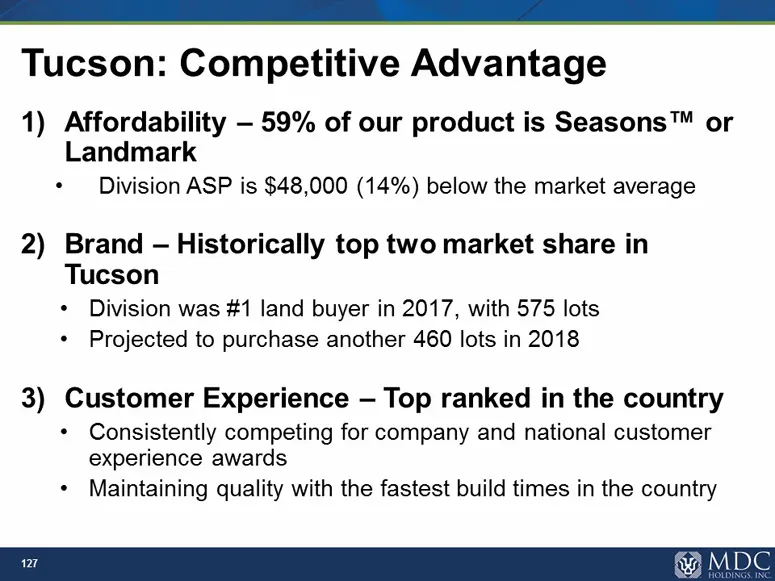
Slide 127
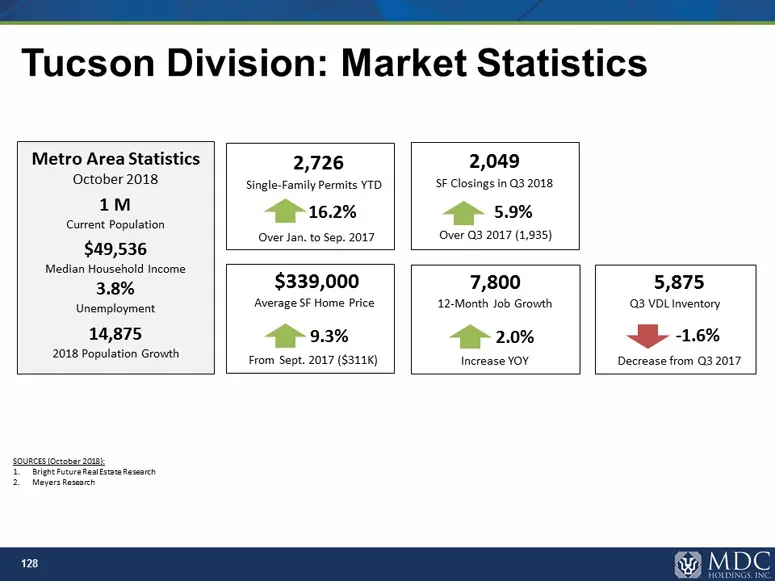
Slide 128
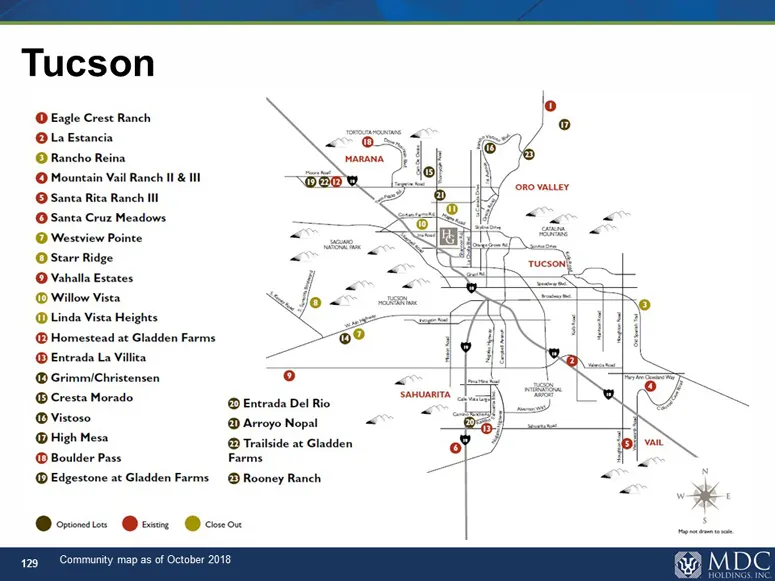
Slide 129
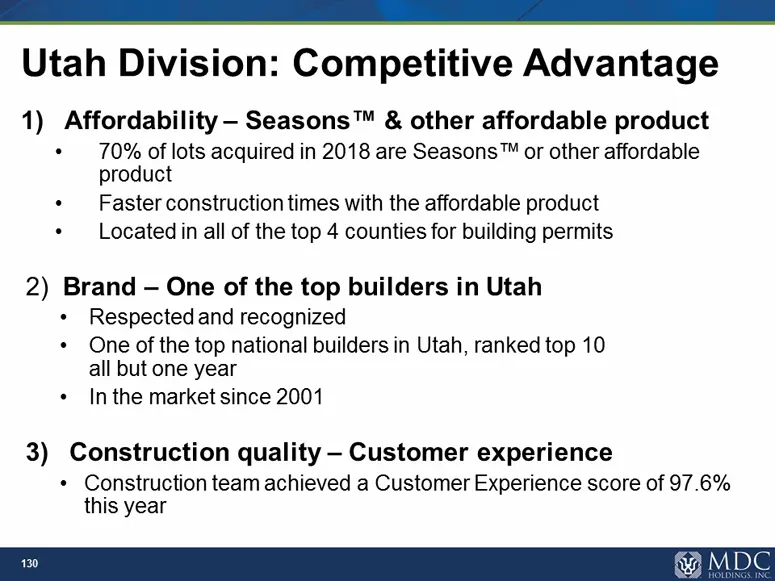
Slide 130
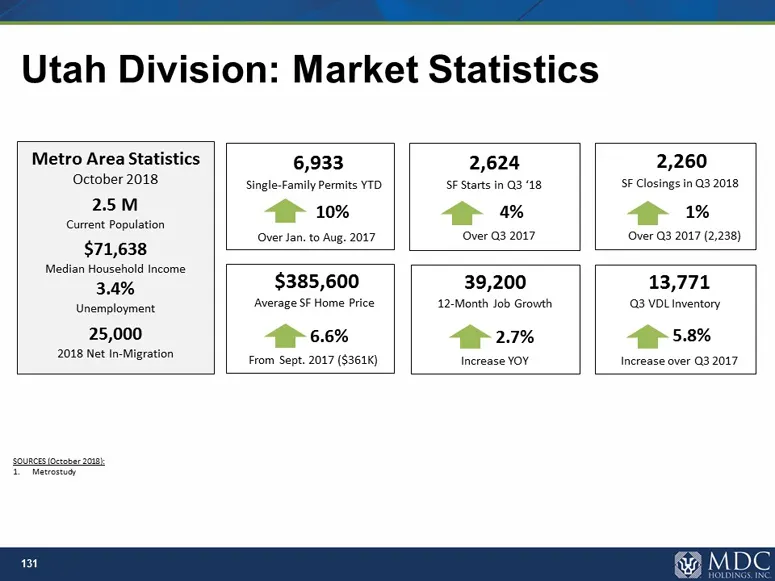
Slide 131
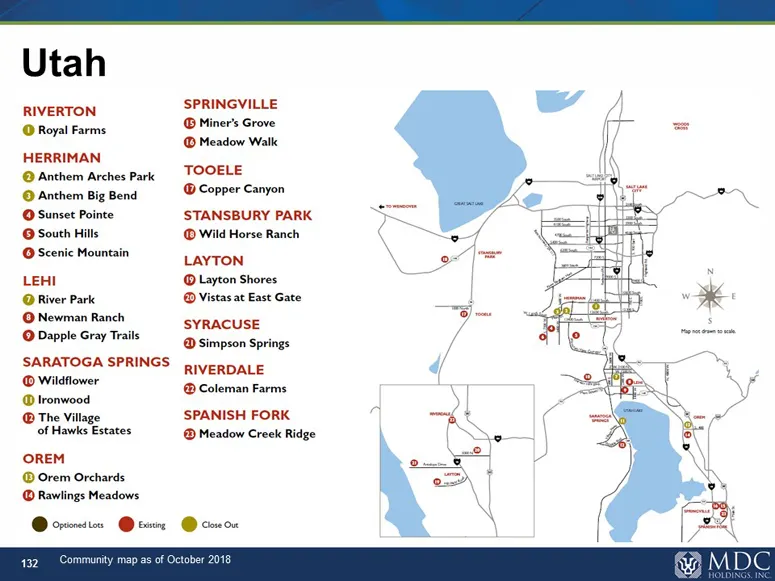
Slide 132
Source: SEC EDGAR · 8-K filed Nov 8, 2018